




Form 424B2 MORGAN STANLEY
 Tweet
 Share
 E-mail
|
Preliminary Pricing Supplement No. 19,636 Filed Pursuant to 424(b)(2) |
Morgan Stanley Finance LLC Trigger Autocallable Contingent Yield Notes
Linked to the VanEck® Gold Miners ETF due October 26, 2029
Fully and Unconditionally Guaranteed by Morgan Stanley
Principal at Risk Securities
|
Investment Description |
These Trigger Autocallable Contingent Yield Notes (the “Securities”) are unsecured and unsubordinated debt obligations of Morgan Stanley Finance LLC (“MSFL”) and are fully and unconditionally guaranteed by Morgan Stanley. The Securities provide returns based on the performance of the VanEck® Gold Miners ETF (the “Underlying Shares”). If the closing price of the Underlying Shares on a quarterly Observation Date (the “Observation Date Closing Price”) is equal to or greater than the Coupon Barrier, MSFL will make a Contingent Coupon payment with respect to that Observation Date. However, if the closing price of the Underlying Shares is less than the Coupon Barrier, no coupon will accrue or be payable with respect to that Observation Date. In addition, MSFL will automatically call the Securities early if the Observation Date Closing Price on any quarterly Observation Date beginning after approximately six months (April 23, 2027) is equal to or greater than the Initial Price. If the Securities are called, MSFL will pay the principal amount plus the Contingent Coupon for that Observation Date, and no further amounts will be owed to you. If the Securities are not called prior to maturity and the Final Price is equal to or greater than the Downside Threshold (which is the same as the Coupon Barrier), MSFL will make a cash payment to you at maturity equal to the principal amount of your Securities, in addition to the Contingent Coupon with respect to the Final Observation Date. However, if the Final Price is less than the Downside Threshold, MSFL will pay you significantly less than the full principal amount, if anything, at maturity, resulting in a loss on your principal amount that is proportionate to the decline in the value of the Underlying Shares from the Trade Date to the Final Observation Date. The Securities may be appropriate for investors who seek an opportunity for potentially enhanced income in exchange for the risk of losing their principal at maturity and the risk of receiving no Contingent Coupons during the term of the Securities. Your return will be solely the Contingent Coupons, if any, and you will not participate in any appreciation in the Underlying Shares. Investing in the Securities involves significant risks. The Issuer will not pay a quarterly Contingent Coupon if the Observation Date Closing Price for the Underlying Shares is below the Coupon Barrier. The Issuer will not automatically call the Securities if the Observation Date Closing Price of the Underlying Shares is below the Initial Price. You will lose a significant portion or all of your principal amount at maturity if the Securities are not called and the Final Price of the Underlying Shares is below the Downside Threshold. Generally, the higher the Contingent Coupon Rate for the Securities, the greater risk of loss on those Securities. If you sell the Securities prior to maturity, you may receive substantially less than the principal amount even if the price of the Underlying Shares is greater than the Downside Threshold at the time of sale.
All payments are subject to our credit risk. If we default on our obligations, you could lose a significant portion or all of your investment. These Securities are not secured obligations and you will not have any security interest in, or otherwise have any access to, any underlying reference asset or assets.
|
Features |
|
Key Dates* |
|
❑Automatically Callable: MSFL will automatically call the Securities and pay you the principal amount plus the Contingent Coupon otherwise due for the quarterly Observation Date only if the Observation Date Closing Price on any quarterly Observation Date beginning April 23, 2027 is equal to or greater than the Initial Price, and no further payments will be made on the Securities. If the Securities are not called, investors will have the potential for downside equity market risk at maturity. ❑Contingent Coupon: If the Observation Date Closing Price on any quarterly Observation Date is equal to or greater than the Coupon Barrier, MSFL will make a Contingent Coupon payment with respect to that Observation Date. However, if the Observation Date Closing Price is below the Coupon Barrier, no coupon will be payable with respect to that Observation Date. ❑Contingent Downside Market Exposure at Maturity: If by maturity the Securities have not been called and the Final Price is greater than or equal to the Downside Threshold (which is the same as the Coupon Barrier) on the Final Observation Date, MSFL will make a cash payment to you at maturity equal to the principal amount of your Securities plus the Contingent Coupon with respect to the Final Observation Date. However, if the Final Price is less than the Downside Threshold, MSFL will repay less than the principal amount, if anything, at maturity, resulting in a significant loss on your principal amount that is proportionate to the decline in the price of the Underlying Shares from the Trade Date to the Final Observation Date. The Downside Threshold is observed only on the Final Observation Date and the contingent downside market exposure applies only at maturity. If you sell the Securities prior to maturity, you may receive substantially less than the principal amount even if the price of the Underlying Shares is greater than the Downside Threshold at the time of sale. Any payment on the Securities is subject to our creditworthiness. |
|
Trade Date October 23, 2026 Settlement Date October 28, 2026 (3 business days after the Trade Date) Observation Dates Quarterly, callable beginning April 23, 2027.
See “Observation Dates and Coupon
Payment Dates” on page 6 for details. Final Observation Date** October 23, 2029 Maturity Date** October 26, 2029
* Expected. In the event that we make any change to the expected Trade Date and Settlement Date, we may change the Observation Dates, the Final Observation Date and/or the Maturity Date so that the stated term of the Securities remains the same. ** Subject to postponement in the event of a Market Disruption Event or for non-Trading Days. See “Postponement of Determination Dates” in the accompanying product supplement. |
NOTICE TO INVESTORS: THE SECURITIES ARE SIGNIFICANTLY RISKIER THAN CONVENTIONAL DEBT INSTRUMENTS. THE SECURITIES DO NOT GUARANTEE THE REPAYMENT OF THE FULL PRINCIPAL AMOUNT AT MATURITY, AND THE SECURITIES CAN HAVE DOWNSIDE MARKET RISK SIMILAR TO THE UNDERLYING. THIS MARKET RISK IS IN ADDITION TO THE CREDIT RISK INHERENT IN PURCHASING OUR DEBT OBLIGATIONS. YOU SHOULD NOT PURCHASE THE SECURITIES IF YOU DO NOT UNDERSTAND OR ARE NOT COMFORTABLE WITH THE SIGNIFICANT RISKS INVOLVED IN INVESTING IN THE SECURITIES. THE SECURITIES WILL NOT BE LISTED ON ANY SECURITIES EXCHANGE.
YOU SHOULD CAREFULLY CONSIDER THE RISKS DESCRIBED UNDER “KEY RISKS” BEGINNING ON PAGE 8 BEFORE PURCHASING ANY SECURITIES. EVENTS RELATING TO ANY OF THOSE RISKS, OR OTHER RISKS AND UNCERTAINTIES, COULD ADVERSELY AFFECT THE MARKET VALUE OF, AND THE RETURN ON, YOUR SECURITIES. YOU MAY LOSE A SIGNIFICANT PORTION OR ALL OF YOUR PRINCIPAL AMOUNT.
|
Security Offering |
This preliminary pricing supplement relates to Trigger Autocallable Contingent Yield Notes linked to the VanEck® Gold Miners ETF. The actual Contingent Coupon Rate and the actual Initial Price, Coupon Barrier and Downside Threshold will be determined on the Trade Date. The Securities are offered at a minimum investment of $1,000 in denominations of $10 and integral multiples thereof.
|
Underlying Shares |
Contingent Coupon Rate* |
Initial Price |
Coupon Barrier/Downside Threshold |
CUSIP |
ISIN |
||||
|
Shares of the VanEck® Gold Miners ETF |
12.25% to 13.00% per annum |
$ |
60% of the Initial Price |
61781P226 |
US61781P2267 |
||||
* The actual Contingent Coupon Rate will be determined on the Trade Date.
See “Additional Information about Morgan Stanley, MSFL and the Securities” on page 2. The Securities will have the terms set forth in the accompanying prospectus, product supplement, index supplement, tax supplement and this preliminary pricing supplement.
Neither the Securities and Exchange Commission nor any other regulatory body has approved or disapproved of these Securities or passed upon the adequacy or accuracy of this preliminary pricing supplement or the accompanying product supplement, index supplement, tax supplement or prospectus. Any representation to the contrary is a criminal offense. The Securities are not deposits or savings accounts and are not insured by the Federal Deposit Insurance Corporation or any other governmental agency or instrumentality, nor are they obligations of, or guaranteed by, a bank.
|
Estimated value on the Trade Date |
Approximately $9.630 per Security, or within $0.30 of that estimate. See “Additional Information about Morgan Stanley, MSFL and the Securities” on page 2. |
||
|
|
Price to Public |
Underwriting Discount(1) |
Proceeds to Us(2) |
|
Per Security |
$10.00 |
$0.20 |
$9.80 |
|
Total |
$ |
$ |
$ |
(1) UBS Financial Services Inc., acting as dealer, will receive from Morgan Stanley & Co. LLC, the agent, a fixed sales commission of $0.20 for each Security it sells. For more information, please see “Supplemental Plan of Distribution; Conflicts of Interest” on page 20 of this preliminary pricing supplement.
(2) See “Use of Proceeds and Hedging” on page 20.
The agent for this offering, Morgan Stanley & Co. LLC, is our affiliate and a wholly owned subsidiary of Morgan Stanley. See “Supplemental Plan of Distribution; Conflicts of Interest” on page 20 of this preliminary pricing supplement.
Morgan Stanley UBS Financial Services Inc.
1
|
Additional Information about Morgan Stanley, MSFL and the Securities |
Morgan Stanley and MSFL have filed a registration statement (including a prospectus, as supplemented by a product supplement, an index supplement and a tax supplement) with the SEC for the offering to which this communication relates. Before you invest, you should read the prospectus in that registration statement, the product supplement, the index supplement, the tax supplement and any other documents relating to this offering that Morgan Stanley and MSFL have filed with the SEC for more complete information about Morgan Stanley, MSFL and this offering. You may get these documents for free by visiting EDGAR on the SEC website at.www.sec.gov. Alternatively, Morgan Stanley, MSFL, any underwriter or any dealer participating in this offering will arrange to send you the prospectus, the index supplement, the product supplement and the tax supplement if you so request by calling toll-free 1-(800)-584-6837.
You may access the accompanying product supplement, index supplement, tax supplement and prospectus on the SEC website at.www.sec.gov as follows:
♦ Product supplement for auto-callable securities dated April 8, 2026:
https://www.sec.gov/Archives/edgar/data/895421/000095010326005464/dp244203_424b2-psautocallsec.htm
♦ Index supplement dated April 8, 2026:
https://www.sec.gov/Archives/edgar/data/895421/000095010326005457/dp244875_424b2-indexsupp.htm
♦ Tax supplement dated April 8, 2026:
https://www.sec.gov/Archives/edgar/data/895421/000095010326005451/dp244874_424b2-sats.htm
♦ Prospectus dated April 8, 2026:
https://www.sec.gov/Archives/edgar/data/895421/000095010326005450/dp244347_424b2-basepro.htm
References to “MSFL” refer only to MSFL, references to “Morgan Stanley” refer only to Morgan Stanley and references to “we,” “our” and “us” refer to MSFL and Morgan Stanley collectively. In this document, the “Securities” refers to the Trigger Autocallable Contingent Yield Notes that are offered hereby. Also, references to the accompanying “prospectus,” “index supplement,” “product supplement” and “tax supplement” mean the prospectus filed by MSFL and Morgan Stanley dated April 8, 2026, the index supplement filed by MSFL and Morgan Stanley dated April 8, 2026, the product supplement for auto-callable securities filed by MSFL and Morgan Stanley dated April 8, 2026 and the tax supplement filed by MSFL and Morgan Stanley dated April 8, 2026, respectively.
You should rely only on the information incorporated by reference or provided in this preliminary pricing supplement or the accompanying product supplement, index supplement, tax supplement and prospectus. We have not authorized anyone to provide you with different information. We are not making an offer of these Securities in any state where the offer is not permitted. You should not assume that the information in this preliminary pricing supplement or the accompanying product supplement, index supplement, tax supplement and prospectus is accurate as of any date other than the date on the front of this document.
The Issue Price of each Security is $10. This price includes costs associated with issuing, selling, structuring and hedging the Securities, which are borne by you, and, consequently, the estimated value of the Securities on the Trade Date will be less than $10. We estimate that the value of each Security on the Trade Date will be approximately $9.630, or within $0.30 of that estimate. Our estimate of the value of the Securities as determined on the Trade Date will be set forth in the final pricing supplement.
What goes into the estimated value on the Trade Date?
In valuing the Securities on the Trade Date, we take into account that the Securities comprise both a debt component and a performance-based component linked to the Underlying Shares. The estimated value of the Securities is determined using our own pricing and valuation models, market inputs and assumptions relating to the Underlying Shares, instruments based on the Underlying Shares, volatility and other factors including current and expected interest rates, as well as an interest rate related to our secondary market credit spread, which is the implied interest rate at which our conventional fixed rate debt trades in the secondary market.
What determines the economic terms of the Securities?
In determining the economic terms of the Securities, including the Contingent Coupon Rate, the Coupon Barrier and the Downside Threshold, we use an internal funding rate, which is likely to be lower than our secondary market credit spreads and therefore advantageous to us. If the issuing, selling, structuring and hedging costs borne by you were lower or if the internal funding rate were higher, one or more of the economic terms of the Securities would be more favorable to you.
What is the relationship between the estimated value on the Trade Date and the secondary market price of the Securities?
The price at which MS & Co. purchases the Securities in the secondary market, absent changes in market conditions, including those related to the Underlying Shares, may vary from, and be lower than, the estimated value on the Trade Date, because the secondary market price takes into account our secondary market credit spread as well as the bid-offer spread that MS & Co. would charge in a secondary market transaction of this type and other factors. However, because the costs associated with issuing, selling, structuring and hedging the Securities are not fully deducted upon issuance, for a period of up to 7 months following the Settlement Date, to the extent that MS & Co. may buy or sell the Securities in the secondary market, absent changes in market conditions, including those related to the Underlying Shares, and to our secondary market credit spreads, it would do so based on values higher than the estimated value. We expect that those higher values will also be reflected in your brokerage account statements.
MS & Co. currently intends, but is not obligated, to make a market in the Securities, and, if it once chooses to make a market, may cease doing so at any time.
2
|
Investor Suitability |
|
|
The Securities may be suitable for you if: |
The Securities may not be suitable for you if: |
|
♦You fully understand the risks inherent in an investment in the Securities, including the risk of loss of your entire initial investment. ♦You can tolerate a loss of all or a substantial portion of your investment and are willing to make an investment that may have the same downside market risk as the Underlying Shares. ♦You understand and accept the risks associated with the Underlying Shares. ♦You accept that you may not receive a Contingent Coupon on some or all of the Coupon Payment Dates. ♦You believe the Underlying Shares will close at or above the Coupon Barrier on the Observation Dates, including above the Downside Threshold on the Final Observation Date. ♦You would be willing to invest in the Securities if the Contingent Coupon Rate were set equal to the bottom of the range indicated on the cover (the actual Contingent Coupon Rate for the Securities will be determined on the Trade Date). ♦You believe the Underlying Shares will close at or above the Initial Price on one of the specified Observation Dates. ♦You understand and accept that you will not participate in any appreciation in the price of the Underlying Shares and that your potential return is limited to the Contingent Coupons, if any. ♦You can tolerate fluctuations in the price of the Securities prior to maturity that may be similar to or exceed the downside price fluctuations of the Underlying Shares. ♦You are willing to invest in the Securities based on the Contingent Coupon Rate specified on the cover hereof. ♦You do not seek guaranteed current income from this investment and are willing to forgo dividends paid on the Underlying Shares. ♦You are willing to invest in securities that may be called early or you are otherwise willing to hold such securities to maturity, as set forth on the cover of this preliminary pricing supplement. ♦You accept that there may be little or no secondary market for the Securities and that any secondary market will depend in large part on the price, if any, at which MS & Co. is willing to trade the Securities. ♦You are willing to assume our credit risk, and understand that if we default on our obligations you may not receive any amounts due to you and could lose your entire investment. |
♦You do not fully understand the risks inherent in an investment in the Securities, including the risk of loss of your entire initial investment. ♦You cannot tolerate a loss of all or a substantial portion of your investment, and are unwilling to make an investment that may have the same downside market risk as the Underlying Shares. ♦You require an investment designed to provide a full return of principal at maturity. ♦You do not understand and accept the risks associated with the Underlying Shares. ♦You do not accept that you may not receive a Contingent Coupon on some or all of the Coupon Payment Dates. ♦You believe that the price of the Underlying Shares will decline during the term of the Securities and is likely to close below the Coupon Barrier on the Observation Dates, including closing below the Downside Threshold on the Final Observation Date. ♦You would be unwilling to invest in the Securities if the Contingent Coupon Rate were set equal to the bottom of the range indicated on the cover (the actual Contingent Coupon Rate for the Securities will be determined on the Trade Date). ♦You seek an investment that participates in the appreciation in the price of the Underlying Shares or that has unlimited return potential. ♦You cannot tolerate fluctuations in the price of the Securities prior to maturity that may be similar to or exceed the downside price fluctuations of the Underlying Shares. ♦You are not willing to invest in the Securities based on the Contingent Coupon Rate specified on the cover hereof. ♦You prefer the lower risk, and therefore accept the potentially lower returns, of fixed income investments with comparable maturities and credit ratings. ♦You seek guaranteed current income from this investment or prefer to receive the dividends paid on the Underlying Shares. ♦You are unable or unwilling to hold securities that may be called early, or you are otherwise unable or unwilling to hold such securities to maturity, as set forth on the cover of this preliminary pricing supplement, or you seek an investment for which there will be an active secondary market. ♦You are not willing to assume our credit risk for all payments under the Securities. |
The investor suitability considerations identified above are not exhaustive. Whether or not the Securities are a suitable investment for you will depend on your individual circumstances, and you should reach an investment decision only after you and your investment, legal, tax, accounting and other advisors have carefully considered the suitability of an investment in the Securities in light of your particular circumstances. You should also review carefully the sections entitled “Key Risks” beginning on page 8 of this preliminary pricing supplement and “Risk Factors” beginning on page 7 of the accompanying prospectus and page S-15 of the accompanying product supplement and “Risk Factors” beginning on page TS-4 of the accompanying tax supplement for risks related to an investment in the Securities. For additional information about the Underlying Shares, see the information set forth under “VanEck® Gold Miners ETF” on page 15.
3
|
Terms |
|
|
Issuer |
Morgan Stanley Finance LLC |
|
Guarantor |
Morgan Stanley |
|
Issue Price |
$10.00 per Security. The Securities are offered at a minimum investment of 100 Securities. |
|
Underlying Shares |
Shares of the VanEck® Gold Miners ETF |
|
Principal Amount |
$10.00 per Security |
|
Term |
Approximately 3 years, unless called earlier |
|
Automatic Call |
Beginning April 23, 2027, the Securities will be called automatically if the Observation Date Closing Price on any Observation Date is equal to or greater than the Initial Price. If the Securities are called, MSFL will pay you the Principal Amount plus the Contingent Coupon otherwise due for that Observation Date on the Coupon Payment Date related to such Observation Date, and no further payments will be made on the Securities. The Securities will not be called if the Observation Date Closing Price of the Underlying Shares is below the Initial Price. |
|
Contingent Coupon |
If the Observation Date Closing Price is equal to or greater than the Coupon Barrier on any Observation Date, we will pay you the Contingent Coupon for that Observation Date on the relevant Coupon Payment Date. If the Observation Date Closing Price is less than the Coupon Barrier on any Observation Date, the Contingent Coupon for that Observation Date will not accrue or be payable and that Contingent Coupon payment will be lost. Each Contingent Coupon will be a fixed amount based on equal quarterly installments at the Contingent Coupon Rate, which is a per-annum rate. The Contingent Coupon amount of $0.30625 to $0.325 (12.25% to 13.00% per annum, to be determined on the Trade Date) would be applicable to each Observation Date on which the closing price of the Underlying Shares is greater than or equal to the Coupon Barrier. Contingent Coupon payments on the Securities are not guaranteed. MSFL will not pay you the Contingent Coupon for any Observation Date on which the closing price of the Underlying Shares is less than the Coupon Barrier. |
|
Contingent Coupon Rate |
The Contingent Coupon Rate will be 12.25% to 13.00% per annum (to be determined on the Trade Date). |
|
Trade Date |
October 23, 2026 |
|
Settlement Date |
October 28, 2026 |
|
Observation Dates |
Quarterly, callable beginning April 23, 2027. See “Observation Dates and Coupon Payment Dates” on page 6 for details. |
|
Final Observation Date |
October 23, 2029* |
|
Coupon Payment Dates |
With respect to each Observation Date, as set forth under “Observation Dates and Coupon Payment Dates” on page 6. |
|
Maturity Date |
October 26, 2029* |
|
Payment at Maturity (per Security) |
MSFL will pay you a cash payment on the Maturity Date linked to the performance of the Underlying Shares during the term of the Securities, as follows: If the Securities are not automatically called and the Final Price is equal to or greater than the Downside Threshold (which is the same as the Coupon Barrier), MSFL will pay you the $10 Principal Amount plus the Contingent Coupon with respect to the Final Observation Date. If the Securities are not automatically called and the Final Price is less than the Downside Threshold, MSFL will pay you an amount calculated as follows: $10 × (1 + Underlying Share Return) In this case, you will lose a significant portion and could lose all of the Principal Amount in an amount proportionate to the decline of the Underlying Shares from the Trade Date to the Final Observation Date. |
|
Observation Date Closing Price |
The closing price of the Underlying Shares on any Observation Date times the Adjustment Factor on such date. |
|
Underlying Share Return |
Final Price – Initial Price |
|
*Subject to postponement in the event of a Market Disruption Event or for non-Trading Days. See “Postponement of Determination Dates” in the accompanying product supplement. |
|
4
|
Initial Price |
The closing price of the Underlying Shares on the Trade Date. |
|
Final Price |
The closing price of the Underlying Shares on the Final Observation Date times the Adjustment Factor on such date. |
|
Adjustment Factor |
1.0, subject to adjustment in the event of certain corporate events affecting the Underlying Shares. |
|
Downside Threshold |
60% of the Initial Price of the Underlying Shares, as specified on the cover of this preliminary pricing supplement. |
|
Coupon Barrier |
60% of the Initial Price of the Underlying Shares, as specified on the cover of this preliminary pricing supplement. |
|
Record Date |
The record date for each Contingent Coupon shall be the date one business day prior to such scheduled Coupon Payment Date; provided, however, that any Contingent Coupon payable at maturity or upon an Automatic Call shall be payable to the person to whom the Payment at Maturity or the payment upon an Automatic Call, as the case may be, shall be payable. |
|
Trustee |
The Bank of New York Mellon |
|
Calculation Agent |
MS & Co. |
5
Observation Dates(1) and Coupon Payment Dates(2)
|
Observation Dates |
Coupon Payment Dates |
|
1/25/2027* |
1/27/2027 |
|
4/23/2027 |
4/27/2027 |
|
7/23/2027 |
7/27/2027 |
|
10/25/2027 |
10/27/2027 |
|
1/24/2028 |
1/26/2028 |
|
4/24/2028 |
4/26/2028 |
|
7/24/2028 |
7/26/2028 |
|
10/23/2028 |
10/25/2028 |
|
1/23/2029 |
1/25/2029 |
|
4/23/2029 |
4/25/2029 |
|
7/23/2029 |
7/25/2029 |
|
10/23/2029 (Final Observation Date) |
10/26/2029 (Maturity Date) |
*The Securities are not subject to an Automatic Call until the second Observation Date, which is April 23, 2027.
(1) Subject to postponement in the event of a Market Disruption Event or for non-Trading Days. See “Postponement of Determination Dates” in the accompanying product supplement.
(2) If, due to a Market Disruption Event or otherwise, any Observation Date is postponed so that it falls less than two business days prior to the scheduled Coupon Payment Date, the Coupon Payment Date will be postponed to the second business day following that Observation Date as postponed, provided that the Coupon Payment Date with respect to the Final Observation Date will be the Maturity Date. No additional coupon will accrue on an account of any such postponement.
6
|
Investment Timeline |
|
|
|
|
|
|
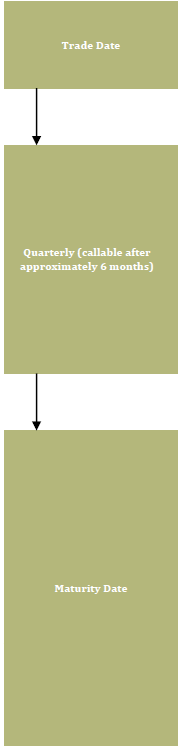
The Initial Price, Downside Threshold and Coupon Barrier are determined. The Contingent Coupon Rate is set.
If the Observation Date Closing Price is equal to or greater than the Coupon Barrier on any Observation Date, MSFL will pay you a Contingent Coupon on the Coupon Payment Date. However, if the Observation Date Closing Price is below the Coupon Barrier, no Coupon will be payable on the related Coupon Payment Date. If the Observation Date Closing Price is equal to or greater than the Initial Price on any Observation Date beginning on April 23, 2027, the Securities will be called and MSFL will pay you a cash payment per Security equal to the principal amount plus the Contingent Coupon otherwise due for the Observation Date, and no further payments will be made on the Securities.
The Final Price is determined as of the Final Observation Date. If the Securities have not been called and the Final Price is equal to or greater than the Coupon Barrier and Downside Threshold, at maturity MSFL will pay you the $10 Principal Amount plus the Contingent Coupon otherwise due on the Maturity Date. If the Securities have not been called and the Final Price is less than the Downside Threshold, MSFL will pay you an amount calculated as follows: $10 × (1 + Underlying Share Return) per Security Under these circumstances, the Payment at Maturity will be significantly less than the $10 Principal Amount by an amount proportionate to the negative Underlying Share Return, and you could lose your entire investment. |
Investing in the Securities involves significant risks. You may lose YOUR ENTIRE principal amount. Any payment on the Securities is subject to OUR creditworthiness. If we were to default on our payment obligations, you may not receive any amounts owed to you under the Securities and you could lose your entire investment.
THE SECURITIES WILL NOT PAY A CONTINGENT COUPON IF THE OBSERVATION DATE CLOSING PRICE OF THE UNDERLYING SHARES IS BELOW THE COUPON BARRIER ON THE APPLICABLE OBSERVATION DATE. THE SECURITIES WILL NOT BE SUBJECT TO AN AUTOMATIC CALL ON ANY OBSERVATION DATE IF THE OBSERVATION DATE CLOSING PRICE OF THE UNDERLYING SHARES ON SUCH OBSERVATION DATE IS BELOW THE INITIAL PRICE. IF THE SECURITIES ARE NOT CALLED, YOU WILL LOSE A SIGNIFICANT PORTION OR ALL OF YOUR INVESTMENT AT MATURITY IF THE FINAL PRICE IS LESS THAN THE DOWNSIDE THRESHOLD.
7
|
Key Risks |
An investment in the Securities involves significant risks. The material risks that apply to the Securities are summarized here, but we urge you to also read the “Risk Factors” section of the accompanying prospectus, product supplement, and tax supplement. You should also consult your investment, legal, tax, accounting and other advisers before you invest in the Securities.
Risks Relating to an Investment in the Securities
♦The Securities do not guarantee the payment of regular interest or the return of any principal. The terms of the Securities differ from those of ordinary debt securities in that the Securities do not guarantee the payment of regular interest or the return of any of the principal amount at maturity. In addition, while the Securities will generally offer the possibility of a higher return if the Securities are automatically called than the potential return payable on our ordinary debt securities with a similar maturity, this higher return potential reflects the risk that you may not receive a positive return on the Securities and may lose a significant portion or all of your investment if the Securities have not been called prior to maturity and if the Final Price is less than the Downside Threshold. In this case, you will be exposed to the decline in the price of the Underlying Shares, as compared to the Initial Price, on a 1-to-1 basis, and the Payment at Maturity will result in a significant loss of your initial investment that is proportionate to the decline of the Underlying Shares over the term of the Securities. You could lose your entire principal amount.
♦You will not receive any Contingent Coupon for any quarterly period where the Observation Date Closing Price is less than the Coupon Barrier. A Contingent Coupon will be made with respect to a quarterly period only if the Observation Date Closing Price is greater than or equal to the Coupon Barrier. If the Observation Date Closing Price remains below the Coupon Barrier on each Observation Date over the term of the Securities, you will not receive any Contingent Coupons.
♦The Contingent Coupon is based solely on the Observation Date Closing Price. Whether the Contingent Coupon will be paid with respect to an Observation Date will be based on the Observation Date Closing Price. As a result, you will not know whether you will receive the Contingent Coupon with respect to any Coupon Payment Date until the applicable Observation Date. Moreover, because the Contingent Coupon is based solely on the Observation Date Closing Price on a specific Observation Date, if such Observation Date Closing Price is less than the Coupon Barrier, you will not receive any Contingent Coupon with respect to such Observation Date, even if the closing price of the Underlying Shares was higher on other days during the term of the Securities.
♦Investors will not participate in any appreciation in the price of the Underlying Shares. Investors will not participate in any appreciation in the price of the Underlying Shares from the Initial Price, and the return on the Securities will be limited to the Contingent Coupon, if any, that is paid with respect to each Observation Date on which the Observation Date Closing Price is greater than or equal to the Coupon Barrier prior to an automatic call or maturity, if any. The return on the Securities will be limited to the Contingent Coupons, if any, regardless of the appreciation of the Underlying Shares, which could be significant. It is possible that the closing price of the Underlying Shares could be below the Coupon Barrier on most or all of the Observation Dates so that you may receive few or no Contingent Coupons. In addition, if the Securities are not called prior to maturity, you may be exposed to the full downside market risk of the Underlying Shares and lose a significant portion or all of your investment despite not being able to participate in any potential appreciation of the Underlying Shares. If you do not earn sufficient Contingent Coupons over the term of the Securities, the overall return on the Securities may be less than the amount that would be paid on a conventional debt security of ours of comparable maturity.
♦You may incur a loss on your investment if you sell your Securities prior to maturity. The Downside Threshold is observed only on the Final Observation Date and the contingent downside market exposure applies only at maturity. If you are able to sell your Securities in the secondary market prior to maturity, you may have to sell them at a loss relative to your initial investment even if the Underlying Shares price is above the Downside Threshold at that time. If you hold the Securities to maturity and the Securities have not been called, MSFL will either repay you the full principal amount per Security plus the Contingent Coupon, or if the price of the Underlying Shares closes below the Downside Threshold on the Final Observation Date, MSFL will repay significantly less than the principal amount, if anything, at maturity, resulting in a loss on your principal amount that is proportionate to the decline in the price of the Underlying Shares from the Trade Date to the Final Observation Date.
♦Early Redemption Risk. The term of your investment in the Securities may be limited to as short as approximately six months by the automatic call feature of the Securities. If the Securities are called prior to maturity, you will not be able to receive any further Contingent Coupon Payments for any future Observation Dates and you may be forced to invest in a lower interest rate environment and may not be able to reinvest at comparable terms or for similar returns. However, under no circumstances will the Securities be redeemed in the first six months of the term of the Securities. Generally, the longer the Securities have been outstanding, the less likely it is that they will be automatically called, because the price of the Underlying Shares will necessarily have declined from the Initial Price if the Securities were not called following an Observation Date, and there will be less time remaining until maturity in which the price of the Underlying Shares can recover.
♦A higher Contingent Coupon Rate and/or a lower Downside Threshold may reflect greater expected volatility of the Underlying Shares, and greater expected volatility generally indicates an increased risk of declines in the price of the Underlying Shares and, potentially, a significant loss at maturity. The economic terms for the Securities, including the Contingent Coupon Rate and the Downside Threshold, are based, in part, on the expected volatility of the Underlying Shares at the time the terms of the Securities are set. “Volatility” refers to the frequency and magnitude of changes in the price of the Underlying Shares. Higher expected volatility with respect to the Underlying Shares as of the Trade Date generally indicates a greater expectation as of that date that the Final Price of the Underlying Shares could ultimately be less than the Downside Threshold on the Final Observation Date, which would result in a loss of a significant portion or all of the Principal Amount. At the time the terms of the Securities are set, higher expected volatility will generally be reflected in a higher Contingent Coupon Rate and/or a lower Downside Threshold, as compared to otherwise comparable securities. Therefore, a relatively higher Contingent Coupon Rate, which would increase the upside return if the Observation Date Closing Price is greater than or equal to the Coupon Barrier on the quarterly Observation Dates, may indicate an increased risk that the price of the Underlying Shares will decrease substantially, which would result in a significant loss at maturity. In addition, and as described above in "The Securities do not guarantee the payment of regular interest or the return of any principal," in general, the higher potential return on the Securities as compared to the return payable on our ordinary debt securities with a comparable maturity indicates the risk that you may not receive a positive return on
8
the Securities and may lose a significant portion or all of your investment. Further, a relatively lower Downside Threshold may not indicate that the Securities have a greater likelihood of a return of principal at maturity. You should be willing to accept the downside market risk of the Underlying Shares and the potential to lose a significant portion or all of your Principal Amount at maturity.
♦The Securities are subject to our credit risk, and any actual or anticipated changes to our credit ratings or our credit spreads may adversely affect the market value of the Securities. You are dependent on our ability to pay all amounts due on the Securities, including Contingent Coupons, if any, and any payments upon an automatic call or at maturity, and therefore you are subject to our credit risk. If we default on our obligations under the Securities, your investment would be at risk and you could lose some or all of your investment. As a result, the market value of the Securities prior to maturity will be affected by changes in the market’s view of our creditworthiness. Any actual or anticipated decline in our credit ratings or increase in the credit spreads charged by the market for taking our credit risk is likely to adversely affect the market value of the Securities.
♦As a finance subsidiary, MSFL has no independent operations and will have no independent assets. As a finance subsidiary, MSFL has no independent operations beyond the issuance and administration of its securities and will have no independent assets available for distributions to holders of MSFL securities if they make claims in respect of such securities in a bankruptcy, resolution or similar proceeding. Accordingly, any recoveries by such holders will be limited to those available under the related guarantee by Morgan Stanley and that guarantee will rank pari passu with all other unsecured, unsubordinated obligations of Morgan Stanley. Holders will have recourse only to a single claim against Morgan Stanley and its assets under the guarantee. Holders of securities issued by MSFL should accordingly assume that in any such proceedings they would not have any priority over and should be treated pari passu with the claims of other unsecured, unsubordinated creditors of Morgan Stanley, including holders of Morgan Stanley-issued securities.
♦The market price of the Securities will be influenced by many unpredictable factors. Several factors, many of which are beyond our control, will influence the value of the Securities in the secondary market and the price at which MS & Co. may be willing to purchase or sell the Securities in the secondary market. Although we expect that generally the closing price of the Underlying Shares on any day will affect the value of the Securities more than any other single factor, other factors that may influence the value of the Securities include:
othe trading price and volatility (frequency and magnitude of changes in value) of the Underlying Shares,
owhether the Observation Date Closing Price has been below the Coupon Barrier on any Observation Date,
ointerest and yield rates in the market,
otime remaining until the Securities mature,
ogeopolitical conditions and economic, financial, political, regulatory or judicial events that affect the Underlying Shares or equities markets generally and which may affect the Final Price,
othe occurrence of certain events affecting the Underlying Shares that may or may not require an adjustment to the Adjustment Factor, and
oany actual or anticipated changes in our credit ratings or credit spreads.
Some or all of these factors will influence the terms of the Securities at the time of issuance and the price that you will receive if you are able to sell your Securities prior to maturity, as the Securities are comprised of both a debt component and a performance-based component linked to the Underlying Shares, and these are the types of factors that also generally affect the values of debt securities and derivatives linked to the Underlying Shares. The price of the Underlying Shares may be, and has recently been, volatile, and we can give you no assurance that the volatility will lessen. See “VanEck® Gold Miners ETF” below. You may receive less, and possibly significantly less, than the Principal Amount per Security if you try to sell your Securities prior to maturity.
♦Investing in the Securities is not equivalent to investing in the Underlying Shares. Investing in the Securities is not equivalent to investing in the Underlying Shares or the component stocks of the Underlying Shares. Investors in the Securities will not have voting rights or rights to receive dividends or other distributions or any other rights with respect to the stocks that constitute the Underlying Shares. Further, you will not participate in any potential appreciation of the Underlying Shares even though you may be exposed to its full decline at maturity.
♦The Securities will not be listed on any securities exchange and secondary trading may be limited. The Securities will not be listed on any securities exchange. Therefore, there may be little or no secondary market for the Securities and, if it once chooses to make a market, may cease doing so at any time. When it does make a market, it will generally do so for transactions of routine secondary market size at prices based on its estimate of the current value of the Securities, taking into account its bid/offer spread, our credit spreads, market volatility, the notional size of the proposed sale, the cost of unwinding any related hedging positions, the time remaining to maturity and the likelihood that it will be able to resell the Securities. MS & Co. currently intends, but is not obligated, to make a market in the Securities. Even if there is a secondary market, it may not provide enough liquidity to allow you to trade or sell the Securities easily. Because we do not expect that other broker-dealers will participate significantly in the secondary market for the Securities, the price at which you may be able to trade your Securities is likely to depend on the price, if any, at which MS & Co. is willing to transact. If, at any time, MS & Co. were to cease making a market in the Securities, it is likely that there would be no secondary market for the Securities. Accordingly, you should be willing to hold your Securities to maturity.
♦The rate we are willing to pay for securities of this type, maturity and issuance size is likely to be lower than the rate implied by our secondary market credit spreads and advantageous to us. Both the lower rate and the inclusion of costs associated with issuing, selling, structuring and hedging the Securities in the Issue Price reduce the economic terms of the Securities, cause the estimated value of the Securities to be less than the Issue Price and will adversely affect secondary market prices. Assuming no change in market conditions or any other relevant factors, the prices, if any, at which dealers, including MS & Co., may be willing to purchase the Securities in secondary market transactions will likely be significantly lower than the Issue Price, because secondary market prices will exclude the issuing, selling, structuring and hedging-related costs that are included in the Issue Price and borne by you and because the
9
secondary market prices will reflect our secondary market credit spreads and the bid-offer spread that any dealer would charge in a secondary market transaction of this type as well as other factors.
The inclusion of the costs of issuing, selling, structuring and hedging the Securities in the Issue Price and the lower rate we are willing to pay as issuer make the economic terms of the Securities less favorable to you than they otherwise would be.
However, because the costs associated with issuing, selling, structuring and hedging the Securities are not fully deducted upon issuance, for a period of up to 7 months following the Settlement Date, to the extent that MS & Co. may buy or sell the Securities in the secondary market, absent changes in market conditions, including those related to the Underlying Shares, and to our secondary market credit spreads, it would do so based on values higher than the estimated value, and we expect that those higher values will also be reflected in your brokerage account statements.
♦The estimated value of the Securities is determined by reference to our pricing and valuation models, which may differ from those of other dealers and is not a maximum or minimum secondary market price. These pricing and valuation models are proprietary and rely in part on subjective views of certain market inputs and certain assumptions about future events, which may prove to be incorrect. As a result, because there is no market-standard way to value these types of securities, our models may yield a higher estimated value of the Securities than those generated by others, including other dealers in the market, if they attempted to value the Securities. In addition, the estimated value on the Trade Date does not represent a minimum or maximum price at which dealers, including MS & Co., would be willing to purchase your Securities in the secondary market (if any exists) at any time. The value of your Securities at any time after the date of this preliminary pricing supplement will vary based on many factors that cannot be predicted with accuracy, including our creditworthiness and changes in market conditions. See also “The market price of the Securities will be influenced by many unpredictable factors” above.
♦Hedging and trading activity by our affiliates could potentially affect the value of the Securities. One or more of our affiliates and/or third-party dealers expect to carry out hedging activities related to the Securities (and to other instruments linked to the Underlying Shares), including trading in the Underlying Shares. As a result, these entities may be unwinding or adjusting hedge positions during the term of the Securities, and the hedging strategy may involve greater and more frequent dynamic adjustments to the hedge as the Final Observation Date approaches. Some of our affiliates also trade the Underlying Shares and other financial instruments related to the Underlying Shares on a regular basis as part of their general broker-dealer and other businesses. Any of these hedging or trading activities on or prior to the Trade Date could potentially increase the Initial Price, and, as a result, the Coupon Barrier and Downside Threshold, which is the price at or above which the Underlying Shares must close on each Observation Date in order for you to earn a Contingent Coupon, or, if the Securities are not called prior to maturity, in order for you to avoid being exposed to the negative price performance of the Underlying Shares at maturity. Additionally, such hedging or trading activities during the term of the Securities could potentially affect the price of the Underlying Shares on the Observation Dates, and, accordingly, whether the Contingent Coupon is payable or whether the Securities are automatically called prior to maturity, and, if the Securities are not called prior to maturity, the payout to you at maturity, if any.
♦The Calculation Agent, which is our affiliate, will make determinations with respect to the Securities. As Calculation Agent, MS & Co. will determine the Initial Price, the Coupon Barrier, the Downside Threshold, the Final Price, whether the Securities will be called following any Observation Date, whether a Contingent Coupon is payable with respect to each Observation Date, whether a market disruption event has occurred, whether to make any adjustments to the Adjustment Factor and the payment that you will receive upon a call, on each Coupon Payment Date, if any, and at maturity, if any. Moreover, certain determinations made by MS & Co., in its capacity as Calculation Agent, may require it to exercise discretion and make subjective judgments, such as with respect to the occurrence or nonoccurrence of market disruption events and certain adjustments to the Adjustment Factor. These potentially subjective determinations may affect the payout to you upon a call, on each Coupon Payment Date, if any, or at maturity, if any. For further information regarding these types of determinations, see “Description of Auto-Callable Securities—Postponement of Determination Dates,” “—Discontinuance of the Underlying Shares of an Exchange-Traded Fund and/or Share Underlying Index; Alteration of Method of Calculation” and “—Calculation Agent and Calculations” in the accompanying product supplement. In addition, MS & Co. has determined the estimated value of the Securities on the Trade Date.
♦Potentially inconsistent research, opinions or recommendations by Morgan Stanley, MSFL, UBS or our or their respective affiliates. Morgan Stanley, MSFL, UBS and our or their respective affiliates may publish research from time to time on financial markets and other matters that may influence the value of the Securities, or express opinions or provide recommendations that are inconsistent with purchasing or holding the Securities. Any research, opinions or recommendations expressed by Morgan Stanley, MSFL, UBS or our or their respective affiliates may not be consistent with each other and may be modified from time to time without notice. Investors should make their own independent investigation of the merits of investing in the Securities and the Underlying Shares to which the Securities are linked.
♦The U.S. federal income tax consequences of an investment in the securities offered by this pricing supplement are uncertain. There is no direct legal authority regarding the proper U.S. federal income tax treatment of the securities, and significant aspects of the tax treatment of the securities are uncertain. Moreover, non-U.S. investors should note that persons having withholding responsibility in respect of the securities are, absent an exception, expected to withhold on any coupon paid to a non-U.S. investor, generally at a rate of 30%. We will not pay any additional amounts in respect of such withholding. You should review carefully the section entitled “United States Federal Income Tax Considerations” herein, in combination with the section entitled “United States Federal Taxation” in the accompanying tax supplement, and consult your tax adviser regarding the U.S. federal income tax consequences of an investment in the securities.
10
Risks Relating to the Underlying Shares
♦The securities are linked to the VanEck® Gold Miners ETF and are subject to risks associated with investments in securities linked to the value of foreign equity securities. As the VanEck® Gold Miners ETF is the Underlying Shares, the securities are linked to the value of foreign equity securities. Investments in securities linked to the value of foreign equity securities involve risks associated with the securities markets in those countries, including risks of volatility in those markets, governmental intervention in those markets and cross-shareholdings in companies in certain countries. Also, there is generally less publicly available information about foreign companies than about U.S. companies that are subject to the reporting requirements of the United States Securities and Exchange Commission, and foreign companies are subject to accounting, auditing and financial reporting standards and requirements different from those applicable to U.S. reporting companies. The prices of securities issued in foreign markets may be affected by political, economic, financial and social factors in those countries, or global regions, including changes in government, economic and fiscal policies and currency exchange laws. In addition, the stocks included in the Share Underlying Index and that are generally tracked by the Underlying Shares have been issued by companies in various emerging markets countries, which pose further risks in addition to the risks associated with investing in foreign equity markets generally. Countries with emerging markets may have relatively unstable governments, may present the risks of nationalization of businesses, restrictions on foreign ownership and prohibitions on the repatriation of assets, and may have less protection of property rights than more-developed countries. The economies of countries with emerging markets may be based on only a few industries, may be highly vulnerable to changes in local or global trade conditions, and may suffer from extreme and volatile debt burdens or inflation rates. Local securities markets may trade a small number of securities and may be unable to respond effectively to increases in trading volume, potentially making prompt liquidation of holdings difficult or impossible at times. Moreover, the economies in such countries may differ favorably or unfavorably from the economy in the United States in such respects as growth of gross national product, rate of inflation, capital reinvestment, resources, self-sufficiency and balance of payment positions.
♦The Underlying Shares may be disproportionately affected by the performance of a small number of stocks. As of September 30, 2026, approximately 53.13% of the weight of the Underlying Share was attributed to just eight stocks: Newmont Corporation, Agnico Eagle Mines Limited, Barrick Gold Corporation, Wheaton Precious Metals Corp., Franco-Nevada Corporation, AngloGold Ashanti plc., Kinross Gold Corporation, and Gold Fields Limited. As a result, a decline in the prices of one or more of these stocks, including as a result of events negatively affecting one or more of these companies, may have the effect of significantly lowering the level of the Underlying Shares even if none of the other constituent stocks of the Underlying Shares are affected by those events. Because of the weighting of the constituents of the Underlying Shares, the amount you receive at maturity could be less than the Cash Settlement Amount you would have received if you had invested in a product linked to an ETF that capped the maximum weight of any one stock to a low amount or that equally weighted all constituents of that ETF.
♦Investing in the Securities exposes investors to risks associated with investments in Securities with a concentration in the gold and silver mining industry. The Securities are subject to certain risks applicable to the gold and silver mining industry. The stocks included in the MarketVector Global Gold Miners Index and that are generally tracked by the Underlying Shares are stocks of companies primarily engaged in the mining of gold or silver. The Underlying Shares may be subject to increased price volatility as they are linked to a single industry, market or sector and may be more susceptible to adverse economic, market, political or regulatory occurrences affecting that industry, market or sector.
Because the Underlying Shares primarily invests in stocks, American Depositary Receipts (“ADRs”) and Global Depositary Receipts (“GDRs”) of companies that are involved in the gold mining industry, the Underlying Shares are subject to certain risks associated with such companies.
Competitive pressures may have a significant effect on the financial condition of companies in the gold mining industry. Also, gold mining companies are highly dependent on the price of gold. Gold prices are subject to volatile price movements over short periods of time and are affected by numerous factors. These include economic factors, including, among other things, the structure of and confidence in the global monetary system, expectations of the future rate of inflation, the relative strength of, and confidence in, the U.S. dollar (the currency in which the price of gold is generally quoted), interest rates and gold borrowing and lending rates, and global or regional economic, financial, political, regulatory, judicial or other events. Gold prices may also be affected by industry factors such as industrial and jewelry demand, lending, sales and purchases of gold by the official sector, including central banks and other governmental agencies and multilateral institutions which hold gold, levels of gold production and production costs, and short-term changes in supply and demand because of trading activities in the gold market.
The Underlying Shares invests to a lesser extent in stocks, ADRs and GDRs of companies involved in the silver mining industry. Silver mining companies are highly dependent on the price of silver. Silver prices can fluctuate widely and may be affected by numerous factors. These include general economic trends, technical developments, substitution issues and regulation, as well as specific factors including industrial and jewelry demand, expectations with respect to the rate of inflation, the relative strength of the U.S. dollar (the currency in which the price of silver is generally quoted) and other currencies, interest rates, central bank sales, forward sales by producers, global or regional political or economic events, and production costs and disruptions in major silver producing countries such as Mexico and Peru. The supply of silver consists of a combination of new mine production and existing stocks of bullion and fabricated silver held by governments, public and private financial institutions, industrial organizations and private individuals. In addition, the price of silver has on occasion been subject to very rapid short-term changes due to speculative activities. From time to time, above-ground inventories of silver may also influence the market. The major end-uses for silver include industrial applications, jewelry, photography and silverware.
♦The Securities are subject to currency exchange rate risk. Because the price of the Underlying Shares tracks the performance of the MarketVector Global Gold Miners Index, holders of the Securities will be exposed to currency exchange rate risk with respect the currencies in which the component Securities trade. Exchange rate movements for a particular currency are volatile and are the result of numerous factors specific to that country including the supply of, and the demand for, those currencies, as well as government policy, intervention or actions, but are also influenced significantly from time to time by political or economic developments, and by macroeconomic factors and
11
speculative actions related to the relevant region. An investor’s net exposure will depend on the extent to which the currencies of the component securities strengthen or weaken against the U.S. dollar and the relative weight of each security. If, taking into account such weighting, the dollar strengthens against the currencies of the component securities represented in the Share Underlying Index, MarketVector Global Gold Miners Index, the price of the Underlying Shares will be adversely affected and the payment at maturity on the Securities may be reduced.
Of particular importance to potential currency exchange risk are:
oexisting and expected rates of inflation;
oexisting and expected interest rate levels;
othe balance of payments; and
othe extent of governmental surpluses or deficits in the relevant countries and the United States.
All of these factors are, in turn, sensitive to the monetary, fiscal and trade policies pursued by the governments of various countries represented in the Share Underlying Index, the United States and other countries important to international trade and finance.
♦VanEck® Gold Miners ETF has recently changed the Share Underlying Index that it tracks. Prior to market close on September 19, 2025, VanEck® Gold Miners ETF’s Share Underlying Index was the NYSE Arca Gold Miners Index. After market close on September 19, 2025, VanEck® Gold Miners ETF’s Share Underlying Index changed to the MarketVector Global Gold Miners Index. The MarketVector Global Gold Miners Index differs from the NYSE Arca Gold Miners Index, including in the use of different market capitalization criteria for inclusion in the index and different weighting schemes. Accordingly, the composition of VanEck® Gold Miners ETF changed as a result of this transition. In connection with this change, VanEck® Gold Miners ETF may have experienced, and may continue to experience, additional portfolio turnover, and VanEck® Gold Miners ETF may have experienced, and may continue to experience, higher tracking error than had been typical for VanEck® Gold Miners ETF. This change could have adversely affected, and may continue to adversely affect, the performance of VanEck® Gold Miners ETF and, in turn, your return on the Securities. In addition, when evaluating the historical performance of VanEck® Gold Miners ETF included below, you should bear in mind that the historical performance of VanEck® Gold Miners ETF might have been meaningfully different had VanEck® Gold Miners ETF tracked the MarketVector Global Gold Miners Index prior to September 19, 2025.
♦Adjustments to the Underlying Shares or to the Share Underlying Index could adversely affect the value of the Securities. As the investment adviser to the Underlying Shares, VanEck Associates Corporation (the “investment adviser”), seeks investment results that correspond generally to the price and yield performance, before fees and expenses, of the Share Underlying Index. Pursuant to its investment strategy or otherwise, the investment adviser may add, delete or substitute the stocks composing the Underlying Shares. Any of these actions could adversely affect the price of the Underlying Shares and, consequently, the value of the Securities. MarketVector Indexes GmbH (“MarketVector”) is responsible for calculating and maintaining the Share Underlying Index. MarketVector may add, delete or substitute the stocks constituting the Share Underlying Index or make other methodological changes that could change the value of the Share Underlying Index. MarketVector may discontinue or suspend calculation or publication of the Share Underlying Index at any time. In these circumstances, the Calculation Agent will have the sole discretion to substitute a successor index that is comparable to the discontinued Share Underlying Index and is permitted to consider indices that are calculated and published by the Calculation Agent or any of its affiliates. Any of these actions could adversely affect the value of the Underlying Shares and, consequently, the value of the Securities.
♦The adjustments to the Adjustment Factor the Calculation Agent is required to make do not cover every corporate event that can affect the shares of the Underlying Shares. MS & Co., as Calculation Agent, will adjust the Adjustment Factor for certain events affecting the Underlying Shares, including stock splits and reverse stock splits. However, the Calculation Agent will not make an adjustment for every event that can affect the Underlying Shares. If an event occurs that does not require the Calculation Agent to adjust the Adjustment Factor, the market price of the Securities may be materially and adversely affected. The determination by the Calculation Agent to adjust, or not to adjust, the Adjustment Factor may materially and adversely affect the market price of the Securities.
♦There are risks associated with the Underlying Shares. Although the Underlying Shares is listed for trading on MarketVector Global, Inc. (the “MarketVector Global”) and a number of similar products have been traded on the MarketVector Global or other securities exchanges for varying periods of time, there is no assurance that an active trading market will continue for the shares of the Underlying Shares or that there will be liquidity in the trading market.
In addition, the Underlying Shares are subject to management risk, which is the risk that the Investment Adviser’s investment strategy, the implementation of which is subject to a number of constraints, may not produce the intended results. For example, the Investment adviser may select up to 20% of the Underlying Shares’ assets to be invested in shares of equity securities that are not included in the Share Underlying Index. The Underlying Shares are also not actively managed and may be affected by a general decline in market segments relating to the Share Underlying Index. The Investment Adviser invests in securities included in, or representative of, the Share Underlying Index regardless of their investment merits. The Investment Adviser does not attempt to take defensive positions in declining markets.
In addition, the Underlying Shares are subject to custody risk, which refers to the risk in the process of clearing and settling trades and to the holding of securities by local banks, agents and depositories. Low trading volumes and volatile prices in less-developed markets make trades harder to complete and settle, and governments or trade groups may compel local agents to hold securities in designated depositories that are not subject to independent evaluation. The less developed a country’s securities market is, the greater the likelihood of custody issues.
Further, under continuous listing standards adopted by the MarketVector Global, the Underlying Shares will be required to confirm on an ongoing basis that the components of the Share Underlying Index satisfy the applicable listing requirements. In the event that its Share Underlying Index does not comply with the applicable listing requirements, the Underlying Shares would be required to rectify such non-compliance by requesting that the Share Underlying Index sponsor modify such Share Underlying Index, adopting a new Share Underlying Index or obtaining relief from the Securities and Exchange Commission. There can be no assurance that the Share Underlying Index sponsor
12
would so modify the Share Underlying Index or that relief would be obtained from the Securities and Exchange Commission and, therefore, non-compliance with the continuous listing standards may result in the Underlying Shares being delisted by the MarketVector Global.
♦The performance and market price of the Underlying Shares, particularly during periods of market volatility, may not correlate with the performance of the Share Underlying Index, the performance of the component securities of the Share Underlying Index or the net asset value per share of the Underlying Shares. The Underlying Shares do not fully replicate the Share Underlying Index and may hold Securities that are different than those included in the Share Underlying Index. In addition, the performance of the Underlying Shares will reflect additional transaction costs and fees that are not included in the calculation of the Share Underlying Index. All of these factors may lead to a lack of correlation between the performance of the Underlying Shares and the Share Underlying Index. In addition, corporate actions (such as mergers and spin-offs) with respect to the equity securities underlying the Underlying Shares may impact the variance between the performances of the Underlying Shares and the Share Underlying Index. Finally, because Underlying Shares are traded on an exchange and are subject to market supply and investor demand, the market price of one share of the Underlying Shares may differ from the net asset value per share of the Underlying Shares.
In particular, during periods of market volatility, or unusual trading activity, trading in the Securities underlying the Underlying Shares may be disrupted or limited, or such Securities may be unavailable in the secondary market. Under these circumstances, the liquidity of the Underlying Shares may be adversely affected, market participants may be unable to calculate accurately the net asset value per share of the Underlying Shares, and their ability to create and redeem shares of the Underlying Shares may be disrupted. Under these circumstances, the market price of the Underlying Shares may vary substantially from the net asset value per share of the Underlying Shares or the level of the Share Underlying Index would affect the Payment at Maturity of the Securities. If the Calculation Agent determines that no Market Disruption Event has taken place, the Payment at Maturity would be based solely on the published closing price per share of the Underlying Shares on the Final Observation Date, even if the Underlying Shares are underperforming the Share Underlying Index or the component securities of the Share Underlying Index and/or trading below the net asset value per share of the Underlying Shares.
For all of the foregoing reasons, the performance of the Underlying Shares may not correlate with the performance of the Share Underlying Index, the performance of the component securities of the Share Underlying Index or the net asset value per share of the Underlying Shares. Any of these events could materially and adversely affect the price of the Underlying Shares and, therefore, the value of the Securities. Additionally, if market volatility or these events were to occur on the Final Observation Date, the Calculation Agent would maintain discretion to determine whether such market volatility or events have caused a Market Disruption Event to occur, and such determination would affect the Payment at Maturity of the Securities. If the Calculation Agent determines that no Market Disruption Event has taken place, the Payment at Maturity would be based solely on the published closing price per share of the Underlying Shares on the Final Observation Date, even if the Underlying Shares are underperforming the Share Underlying Index or the component securities of the Share Underlying Index and/or trading below the net asset value per share of the Underlying Shares.
13
|
Hypothetical Payments on the Securities at Maturity |
The examples below illustrate the payment upon a call, on the Coupon Payment Dates and at maturity for a $10 Security on a hypothetical offering of the Securities, with the following assumptions (the actual terms for the Securities will be determined on the Trade Date; amounts may have been rounded for ease of reference):
♦Principal Amount: $10.00
♦Term: Approximately 3 years
♦Hypothetical Initial Price: $90.00
♦Hypothetical Contingent Coupon Rate: 12.25% per annum
♦Hypothetical Contingent Coupon: $0.30625 per quarter
♦Observation Dates: Quarterly
♦Hypothetical Coupon Barrier and Downside Threshold: $54.00, which is 60% of the hypothetical Initial Price
Example 1 — Securities are Called on the Second Observation Date (the first Observation Date on which MSFL can call the Securities)
|
Date |
Closing Price |
Payment (per Security) |
|
First Observation Date |
$70.00 (at or above Coupon Barrier) |
$0.30625 (Contingent Coupon — Not Callable) |
|
Second Observation Date |
$110.00 (at or above Initial Price) |
$10.30625 (Settlement Amount) |
|
|
Total Payment: |
$10.6125 (6.125% return) |
The Underlying Shares close above the Coupon Barrier on the first Observation Date, and therefore a Contingent Coupon is paid on the related Coupon Payment Date. MSFL calls the Securities on the second Observation Date, which is the first Observation Date on which the Securities can be called. On the call settlement date, MSFL will pay you a total of $10.30625 per Security, reflecting your principal amount plus the Contingent Coupon with respect to the relevant Observation Date. When added to the Contingent Coupon Payment of $0.30625 received in respect of the prior Observation Date, MSFL will have paid you a total of $10.6125 per Security for a 6.125% total return on the Securities over a 6-month term. No further amount will be owed to you under the Securities, and you will not participate in any appreciation of the Underlying Shares.
Example 2 — Securities are Called on the Fourth Observation Date
|
Date |
Closing Price |
Payment (per Security) |
|
First Observation Date |
$75.00 (at or above Coupon Barrier) |
$0.30625 (Contingent Coupon — Not Callable) |
|
Second Observation Date |
$64.00 (at or above Coupon Barrier; below Initial Price) |
$0.30625 (Contingent Coupon — Not Called) |
|
Third Observation Date |
$60.00 (at or above Coupon Barrier; below Initial Price) |
$0.30625 (Contingent Coupon — Not Called) |
|
Fourth Observation Date |
$105.00 (at or above Initial Price) |
$10.30625 (Settlement Amount) |
|
|
Total Payment: |
$11.225 (12.25% return) |
Since the Securities are called on the fourth Observation Date (which is approximately one year after the Trade Date), MSFL will pay you on the call settlement date a total of $10.30625 per Security, reflecting your principal amount plus the Contingent Coupon. When added to the Contingent Coupon payments of $0.91875 received in respect of prior Observation Dates, MSFL will have paid you a total of $11.225 per Security for a 12.25% total return on the Securities over a 1-year term. No further amount will be owed to you under the Securities, and you will not participate in any appreciation of the Underlying Shares.
Example 3 — Securities are NOT Called and the Final Price of the Underlying Shares is at or above the Downside Threshold
|
Date |
Closing Price |
Payment (per Security) |
|
First Observation Date |
$69.00 (at or above Coupon Barrier) |
$0.30625 (Contingent Coupon — Not Callable) |
|
Second Observation Date |
$42.00 (below Coupon Barrier and Initial Price) |
$0.00 (Not Called) |
|
Third to Eleventh Observation Dates |
Various (all below Coupon Barrier and Initial Price) |
$0.00 (Not Called) |
|
Final Observation Date |
$64.00 (at or above Downside Threshold and Coupon Barrier; below Initial Price) |
$10.30625 (Payment at Maturity) |
|
|
Total Payment: |
$10.6125 (6.125% return) |
Since the Securities are not called and the Final Price is greater than or equal to the Downside Threshold, at maturity, MSFL will pay you a total of $10.30625 per Security, reflecting your principal amount plus the Contingent Coupon. When added to the Contingent Coupon payment of $0.30625 received in respect of prior Observation Dates, MSFL will have paid you a total of $10.6125 per Security for a 6.125% total return on the Securities over the 3-year term. You will not participate in any appreciation of the Underlying Shares.
Example 4 — Securities are NOT Called and the Final Price of the Underlying Shares is below the Downside Threshold
|
Date |
Closing Price |
Payment (per Security) |
|
First Observation Date |
$75.00 (at or above Coupon Barrier) |
$0.30625 (Contingent Coupon — Not Callable) |
|
Second Observation Date |
$68.00 (at or above Coupon Barrier; below Initial Price) |
$0.30625 (Contingent Coupon — Not Called) |
|
Third to Eleventh Observation Dates |
Various (all below Coupon Barrier; below Initial Price) |
$0.00 (Not Called) |
|
Final Observation Date |
$27.00 (below Downside Threshold and Coupon Barrier; below Initial Price) |
$10 + [$10 × Underlying Share Return] = |
|
|
Total Payment: |
$3.6125 (-63.875% return) |
14
Since the Securities are not called and the Final Price of the Underlying Shares is below the Downside Threshold, at maturity MSFL will pay you $3.00 per Security. When added to the Contingent Coupon payments of $0.6125 received in respect of prior Observation Dates, MSFL will have paid you $3.6125 per Security over the 3-year term, for a loss on the Securities of 63.875%.
The Securities differ from ordinary debt securities in that, among other features, MSFL is not necessarily obligated to repay the full amount of your initial investment. If the Securities are not called on any Observation Date, you may lose a significant portion or all of your initial investment. Specifically, if the Securities are not called and the Final Price is less than the Downside Threshold, you will lose 1% (or a fraction thereof) of your principal amount for each 1% (or a fraction thereof) that the Underlying Share Return is less than zero. Any payment on the Securities, including any payment upon an automatic call, any Contingent Coupon or the Payment at Maturity, is dependent on our ability to satisfy our obligations when they come due. If we are unable to meet our obligations, you may not receive any amounts due to you under the Securities.
15
|
United States Federal Income Tax Considerations |
You should review carefully the section in the accompanying tax supplement entitled “United States Federal Taxation.” The following discussion, when read in combination with that section, constitutes the full opinion of our counsel, Davis Polk & Wardwell LLP, regarding the material U.S. federal income tax consequences of owning and disposing of the securities offered by this pricing supplement.
Generally, this discussion assumes that you purchased a security for cash in the original issuance at the stated issue price and does not address other circumstances specific to you, including consequences that may arise due to any other investments relating to an underlier. Moreover, as discussed in the section entitled “United States Federal Taxation” in the accompanying tax supplement, we have not attempted to ascertain whether any issuer of any underlier to which the securities relate is a U.S. real property holding corporation or a passive foreign investment company. You should consult your tax adviser regarding these issues, including the effect any circumstances specific to you may have on the U.S. federal income tax consequences of your ownership of a security.
In the opinion of our counsel, which is based on current market conditions, it is reasonable to treat the securities for U.S. federal income tax purposes as prepaid financial contracts with associated coupons, and any coupons as ordinary income, as described in the section entitled “United States Federal Taxation—Tax Consequences to U.S. Holders—Program Securities Treated as Prepaid Financial Contracts with Associated Coupons” in the accompanying tax supplement. There is uncertainty regarding this treatment, and the Internal Revenue Service (the “IRS”) or a court might not agree with it. Moreover, because this treatment of the securities and our counsel’s opinion are based on market conditions as of the date of this preliminary pricing supplement, each is subject to confirmation on the pricing date. A different tax treatment could be adverse to you.
We do not plan to request a ruling from the IRS regarding the treatment of the securities. An alternative characterization of the securities could materially and adversely affect the tax consequences of ownership and disposition of the securities, including the timing and character of income recognized. In particular, due to the terms of the securities and current market conditions, there is a risk that the securities could be characterized as debt instruments for U.S. federal income tax purposes, in which case the timing and character of income recognized in respect of the securities could be different from those described herein and possibly adverse to certain investors. In addition, the U.S. Treasury Department and the IRS have requested comments on various issues regarding the U.S. federal income tax treatment of “prepaid forward contracts” and similar financial instruments and have indicated that such transactions may be the subject of future regulations or other guidance. Furthermore, members of Congress have proposed legislative changes to the tax treatment of derivative contracts. Any legislation, Treasury regulations or other guidance promulgated after consideration of these issues could materially and adversely affect the tax consequences of an investment in the securities, possibly with retroactive effect.
Non-U.S. Holders. If you are a Non-U.S. Holder (as defined in the accompanying tax supplement), please also read the section entitled “United States Federal Taxation—Tax Consequences to Non-U.S. Holders—Program Securities Not Treated as Debt Instruments” in the accompanying tax supplement.
The U.S. federal income tax treatment of the coupons is unclear. To the extent that we have withholding responsibility in respect of the securities, we would expect generally to treat the coupons paid to Non-U.S. Holders as subject to U.S. withholding tax. Moreover, you should expect that, if the applicable withholding agent determines that withholding tax should apply, it will be at a rate of 30% (or lower treaty rate). In order to claim an exemption from, or a reduction in, the 30% withholding under an applicable treaty, you may need to comply with certification requirements to establish that you are not a U.S. person and are eligible for such an exemption or reduction under an applicable tax treaty. You should consult your tax adviser regarding the tax treatment of the coupons.
As discussed under “United States Federal Taxation—Tax Consequences to Non-U.S. Holders—Dividend Equivalents under Section 871(m) of the Code” in the accompanying tax supplement, Section 871(m) of the Internal Revenue Code and Treasury regulations promulgated thereunder (“Section 871(m)”) generally impose a 30% withholding tax on dividend equivalents paid or deemed paid to Non-U.S. Holders with respect to certain financial instruments linked to U.S. equities or indices that include U.S. equities. The Treasury regulations, as modified by an IRS notice, exempt financial instruments issued prior to January 1, 2029 that do not have a “delta” of one. Based on certain determinations made by us, we expect that Section 871(m) will not apply to the securities with regard to Non-U.S. Holders. Our determination is not binding on the IRS, and the IRS may disagree with this determination. If necessary, further information regarding the potential application of Section 871(m) will be provided in the final pricing supplement for the securities.
We will not be required to pay any additional amounts with respect to U.S. federal withholding taxes.
You should consult your tax adviser regarding the U.S. federal income tax consequences of an investment in the securities, including possible alternative treatments, as well as tax consequences arising under the laws of any state, local or non-U.S. taxing jurisdiction.
16
|
VanEck® Gold Miners ETF |
The VanEck® Gold Miners ETF is an exchange-traded fund managed by VanEck, which seeks to provide investment results that correspond generally to the price and yield performance, before fees and expenses, of the MarketVector Global Gold Miners Index. The VanEck® Gold Miners ETF is managed by the VanEck® ETF Trust (the “Trust”), a registered investment company that consists of numerous separate investment portfolios, including the VanEck® Gold Miners ETF. Prior to market close on September 19, 2025, VanEck® Gold Miners ETF’s Share Underlying Index was the NYSE Arca Gold Miners Index. Information provided to or filed with the Securities and Exchange Commission (the “Commission”) by the Trust pursuant to the Securities Act of 1933 and the Investment Company Act of 1940 can be located by reference to Commission file numbers 333-123257 and 811-10325, respectively, through the Commission’s website at www.sec.gov. In addition, information may be obtained from other publicly available sources. Neither the issuer nor the agent makes any representation that any such publicly available information regarding the VanEck® Gold Miners ETF is accurate or complete.
We and/or our affiliates may presently or from time to time engage in business with the Trust. In the course of such business, we and/or our affiliates may acquire non-public information with respect to the Trust, and neither we nor any of our affiliates undertakes to disclose any such information to you. In addition, one or more of our affiliates may publish research reports with respect to the Underlying Shares. The statements in the preceding two sentences are not intended to affect the rights of investors in the Securities under the securities laws. As a prospective purchaser of the Securities, you should undertake an independent investigation of the Trust as in your judgment is appropriate to make an informed decision with respect to an investment linked to the Underlying Shares.
MarketVector℠ is a service mark of Van Eck Associates Corporation (“Van Eck”). The securities are not sponsored, endorsed, sold, or promoted by Van Eck. Van Eck makes no representations or warranties to the owners of the securities or any member of the public regarding the advisability of investing in the Securities. Van Eck has no obligation or liability in connection with the operation, marketing, trading or sale of the Securities.
MarketVector Global Gold Miners Index. The MarketVector Global Gold Miners Index is a float-adjusted market capitalization weighted index comprised of publicly traded companies involved primarily in the mining of gold and silver. The MarketVector Global Gold Miners Index includes common stocks, ADRs or GDRs of selected companies involved in the mining for gold and silver ore and are listed for trading and electronically quoted on a major stock market that is accessible by foreign investors.
|
Historical Information |
The following table sets forth the published high and low closing prices, as well as the end-of-quarter closing prices, of the VanEck® Gold Miners ETF for each quarter in the period from January 1, 2021 through October 21, 2026. The closing price of the VanEck® Gold Miners ETF on October 21, 2026 was $86.72. We obtained the information in the table below from Bloomberg Financial Markets, without independent verification. The historical closing prices of the VanEck® Gold Miners ETF should not be taken as an indication of future performance, and no assurance can be given as to the closing price of the VanEck® Gold Miners ETF on any Observation Date, including the Final Observation Date.
|
Quarter Begin |
Quarter End |
Quarterly High ($) |
Quarterly Low ($) |
Quarterly Close ($) |
|
1/1/2021 |
3/31/2021 |
38.51 |
30.90 |
32.50 |
|
4/1/2021 |
6/30/2021 |
39.68 |
33.60 |
33.98 |
|
7/1/2021 |
9/30/2021 |
35.09 |
28.91 |
29.47 |
|
10/1/2021 |
12/31/2021 |
34.90 |
29.33 |
32.03 |
|
1/1/2022 |
3/31/2022 |
38.91 |
29.30 |
38.35 |
|
4/1/2022 |
6/30/2022 |
40.87 |
27.38 |
27.38 |
|
7/1/2022 |
9/30/2022 |
28.16 |
21.86 |
24.12 |
|
10/1/2022 |
12/31/2022 |
30.04 |
22.68 |
28.66 |
|
1/1/2023 |
3/31/2023 |
33.27 |
26.68 |
32.35 |
|
4/1/2023 |
6/30/2023 |
35.87 |
29.22 |
30.11 |
|
7/1/2023 |
9/30/2023 |
32.63 |
26.91 |
26.91 |
|
10/1/2023 |
12/31/2023 |
31.98 |
25.91 |
31.01 |
|
1/1/2024 |
3/31/2024 |
31.62 |
25.78 |
31.62 |
|
4/1/2024 |
6/30/2024 |
37.24 |
32.03 |
33.93 |
|
7/1/2024 |
9/30/2024 |
41.64 |
33.89 |
39.82 |
|
10/1/2024 |
12/31/2024 |
44.09 |
33.77 |
33.91 |
|
1/1/2025 |
3/31/2025 |
45.97 |
34.58 |
45.97 |
|
4/1/2025 |
6/30/2025 |
54.46 |
41.45 |
52.06 |
|
7/1/2025 |
9/30/2025 |
76.40 |
50.79 |
76.40 |
|
10/1/2025 |
12/31/2025 |
91.29 |
68.28 |
85.77 |
|
1/1/2026 |
3/31/2026 |
115.84 |
80.12 |
91.77 |
|
4/1/2026 |
6/30/2026 |
100.75 |
73.81 |
75.45 |
|
7/1/2026 |
9/30/2026 |
105.52 |
70.74 |
87.80 |
|
10/1/2026 |
10/21/2026* |
89.28 |
83.40 |
86.72 |
* Available information for the indicated period includes data for less than the entire calendar quarter, and accordingly, the “Quarterly High,” “Quarterly Low” and “Quarterly Close” data indicated are for this shortened period.
17
The graph below illustrates the performance of the VanEck® Gold Miners ETF from January 1, 2008 through October 21, 2026, based on information from Bloomberg. Past performance of the VanEck® Gold Miners ETF is not indicative of the future performance of the VanEck® Gold Miners ETF.
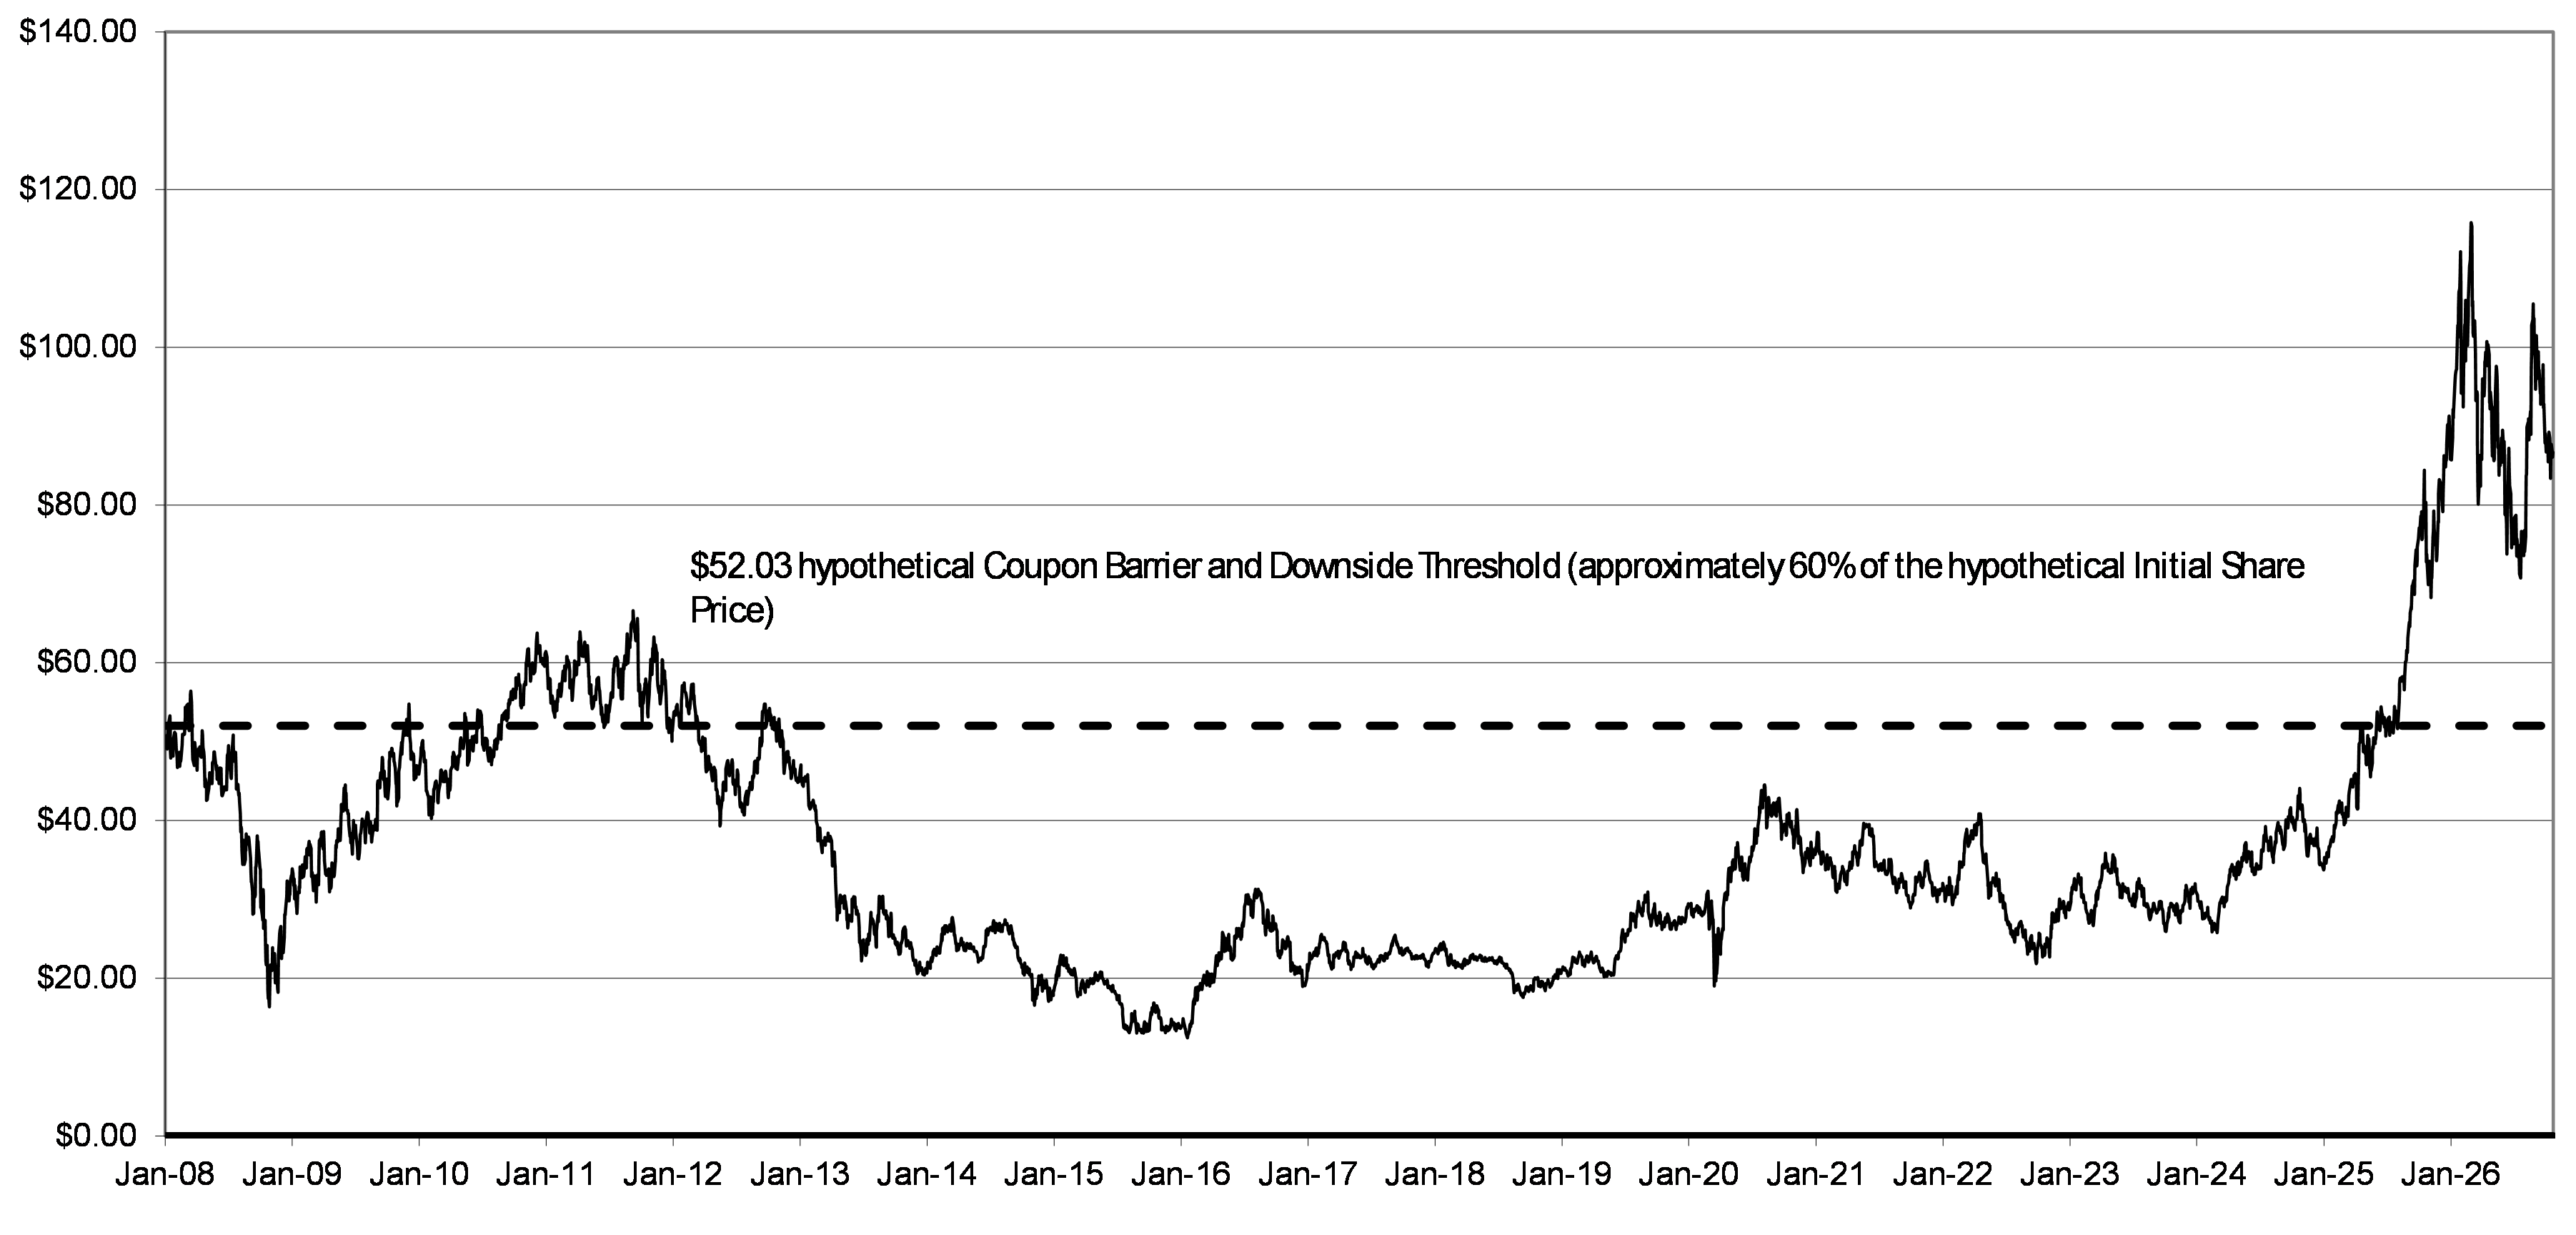
* The dashed line indicates the hypothetical Coupon Barrier and Downside Threshold, assuming the closing price of the VanEck® Gold Miners ETF on October 21, 2026 were the Initial Price.
Past performance is not indicative of future results.
18
|
Additional Terms of the Securities |
If the terms described herein are inconsistent with those described in the accompanying product supplement, index supplement, tax supplement or prospectus, the terms described herein shall control.
The accompanying product supplement refers to the Principal Amount as the “Stated Principal Amount,” the Initial Price as the “Initial Share Price” the Trade Date as the “Pricing Date,” the Observation Dates as the “Determination Dates,” the Final Observation Date as the “Final Determination Date,” the Coupon Barrier/Downside Threshold” as the “Downside Threshold Level” and the day on which any automatic call occurs as the “Early Redemption Date.”
“Share Underlying Index” means the MarketVector Global Gold Miners Index.
“Share Underlying Index Publisher” means MarketVector Indexes GmbH, or any successor thereof.
“Closing Price” means, on any Trading Day for the Underlying Shares, the closing price of one Underlying Share times the Adjustment Factor on such Trading Day (as defined under “—Discontinuance of the Underlying Shares of an Exchange-Traded Fund and/or Share Underlying Index; Alteration of Method of Calculation” in the accompanying product supplement). In certain circumstances, the Closing Price will be based on the alternate calculation of the Underlying Shares or the Share Underlying Index as described under “—Discontinuance of the Underlying Shares of an Exchange-Traded Fund and/or Share Underlying Index; Alteration of Method of Calculation” in the accompanying product supplement.
Day-Count Convention
Interest will be computed on the basis of a 360-day year of twelve 30-day months.
Issuer Notice to Registered Security Holders, the Trustee and the Depositary
In the event that the Maturity Date of the Securities is postponed due to a postponement of the Final Observation Date, the Issuer shall give notice of such postponement and, once it has been determined, of the date to which the Maturity Date has been rescheduled (i) to each registered holder of the Securities by mailing notice of such postponement by first class mail, postage prepaid, to such registered holder’s last address as it shall appear upon the registry books, (ii) to the Trustee by facsimile confirmed by mailing such notice to the Trustee by first class mail, postage prepaid, at its New York office and (iii) to The Depository Trust Company (the “Depositary”) by telephone or facsimile confirmed by mailing such notice to the Depositary by first class mail, postage prepaid. Any notice that is mailed to a registered holder of the Securities in the manner herein provided shall be conclusively presumed to have been duly given to such registered holder, whether or not such registered holder receives the notice. The Issuer shall give such notice as promptly as possible, and in no case later than (i) with respect to notice of postponement of the Maturity Date, the Business Day immediately preceding the scheduled Maturity Date and (ii) with respect to notice of the date to which the Maturity Date has been rescheduled, the Business Day immediately following the Final Observation Date as postponed.
In the event that the Securities are subject to Automatic Call, the Issuer shall, (i) on the Business Day following the applicable Observation Date, give notice of the Automatic Call and the applicable automatic call payment, including specifying the payment date of the applicable amount due upon the Automatic Call, (x) to each registered holder of the Securities by mailing notice of such Automatic Call by first class mail, postage prepaid, to such registered holder’s last address as it shall appear upon the registry books, (y) to the Trustee by facsimile confirmed by mailing such notice to the Trustee by first class mail, postage prepaid, at its New York office and (z) to the Depositary by telephone or facsimile confirmed by mailing such notice to the Depositary by first class mail, postage prepaid and (ii) on or prior to the Automatic Call Date, deliver the aggregate cash amount due with respect to the Securities to the Trustee for delivery to the Depositary, as holder of the securities. Any notice that is mailed to a registered holder of the Securities in the manner herein provided shall be conclusively presumed to have been duly given to such registered holder, whether or not such registered holder receives the notice. This notice shall be given by the Issuer or, at the Issuer’s request, by the Trustee in the name and at the expense of the Issuer, with any such request to be accompanied by a copy of the notice to be given.
The Issuer shall, or shall cause the Calculation Agent to, (i) provide written notice to the Trustee, on which notice the Trustee may conclusively rely, and to the Depositary of the amount of cash to be delivered as Contingent Coupon, if any, with respect to the Securities on or prior to 10:30 a.m. (New York City time) on the Business Day preceding each Coupon Payment Date, and (ii) deliver the aggregate cash amount due, if any, with respect to the Contingent Coupon to the Trustee for delivery to the Depositary, as holder of the Securities, on or prior to the applicable Coupon Payment Date.
The Issuer shall, or shall cause the Calculation Agent to, (i) provide written notice to the Trustee and to the Depositary of the amount of cash, if any, to be delivered with respect to the Securities, on or prior to 10:30 a.m. (New York City time) on the Business Day preceding the Maturity Date, and (ii) deliver the aggregate cash amount due with respect to the Securities, if any, to the Trustee for delivery to the Depositary, as holder of the Securities, on or prior to the Maturity Date.
19
|
Additional Information About the Securities |
Use of Proceeds and Hedging
The proceeds from the sale of the Securities will be used by us for general corporate purposes. We will receive, in aggregate, $10 per Security issued, because, when we enter into hedging transactions in order to meet our obligations under the Securities, our hedging counterparty will reimburse the cost of the Agent’s commissions. The costs of the Securities borne by you and described on page 2 above comprise the Agent’s commissions and the cost of issuing, structuring and hedging the Securities. See also “Use of Proceeds” in the accompanying prospectus.
On or prior to the Trade Date, we will hedge our anticipated exposure in connection with the Securities, by entering into hedging transactions with our affiliates and/or third-party dealers. We expect our hedging counterparties to take positions in the Underlying Shares, in futures or options contracts on the Underlying Shares, or positions in any other securities or instruments related to the Underlying Shares that they may wish to use in connection with such hedging. Any of these hedging or trading activities on or prior to the Trade Date could potentially increase the Initial Price, and, as a result, the Coupon Barrier and Downside Threshold of the Underlying Shares, which is the price at or above which such Underlying Shares must close on each Observation Date in order for you to earn a Contingent Coupon, or, if the Securities are not called prior to maturity, is the price at or above which the Underlying Shares must close on the Final Observation Date so that you do not suffer a significant loss on your initial investment in the Securities. In addition, through our affiliates, we are likely to modify our hedge position throughout the term of the Securities, including on the Final Observation Date, by purchasing and selling the Underlying Shares, futures or options contracts on the Underlying Shares, or any other securities or instruments that we may wish to use in connection with such hedging activities, including by purchasing or selling any such securities or instruments on the Final Observation Date. As a result, these entities may be unwinding or adjusting hedge positions during the term of the Securities, and the hedging strategy may involve greater and more frequent dynamic adjustments to the hedge as the Final Observation Date approaches. We cannot give any assurance that our hedging activities will not affect the value of the Underlying Shares on the Observation Dates, and, therefore, adversely affect the value of the Securities, whether the Contingent Coupon is payable or whether the Securities are called prior to maturity and, if not, the payment you will receive at maturity, if any.
Supplemental Plan of Distribution; Conflicts of Interest
MS & Co. will act as the agent for this offering. We will agree to sell to MS & Co., and MS & Co. will agree to purchase, all of the Securities at the issue price less the underwriting discount indicated on the cover of this document. UBS Financial Services Inc., acting as dealer, will receive from MS & Co. a fixed a sales commission of $0.20 for each Security it sells.
MS & Co. is our affiliate and a wholly owned subsidiary of Morgan Stanley, and it and other affiliates of ours expect to make a profit by selling, structuring and, when applicable, hedging the Securities. When MS & Co. prices this offering of Securities, it will determine the economic terms of the Securities, including the Contingent Coupon Rate, such that for each Security the estimated value on the Trade Date will be no lower than the minimum level described in “Additional Information about Morgan Stanley, MSFL and the Securities” on page 2.
MS & Co. will conduct this offering in compliance with the requirements of Rule 5121 of the Financial Industry Regulatory Authority, Inc. (“FINRA”), regarding a FINRA member firm’s distribution of the securities of an affiliate and related conflicts of interest. MS & Co. or any of our other affiliates may not make sales in this offering to any discretionary account.
In order to facilitate the offering of the Securities, the agent may engage in transactions that stabilize, maintain or otherwise affect the price of the Securities. Specifically, the agent may sell more Securities than it is obligated to purchase in connection with the offering, creating a naked short position in the Securities, for its own account. The agent must close out any naked short position by purchasing the Securities in the open market. A naked short position is more likely to be created if the agent is concerned that there may be downward pressure on the price of the Securities in the open market after pricing that could adversely affect investors who purchase in the offering. As an additional means of facilitating the offering, the agent may bid for, and purchase, the Securities or the Underlying Shares in the open market to stabilize the price of the Securities. Any of these activities may raise or maintain the market price of the Securities above independent market levels or prevent or retard a decline in the market price of the Securities. The agent is not required to engage in these activities, and may end any of these activities at any time. An affiliate of the agent has entered into a hedging transaction with us in connection with this offering of Securities. See “—Use of Proceeds and Hedging” above.
20

FREE Breaking News Alerts from StreetInsider.com!
StreetInsider.com Top Tickers, 10/23/2026
- Wall Street futures edge lower after AI selloff, telecom slide
- Meta's capital-raising plans expose a major weakness in the AI boom
- Brent crude hits more than five-month high on concern over Middle East escalation
- BofA flags further downside risk for stocks, yields and dollar
- SpaceX cell-site ambitions lift tower stocks and weigh on carriers
Serious News for Serious Traders! Try StreetInsider.com Premium Free!
You May Also Be Interested In
- Pinnacle Financial Partners (PNFP) PT Raised to $140 at Morgan Stanley, New Top Pick
- Spotify (SPOT) PT Raised to $700 at Morgan Stanley
- Medical Care Technologies Inc. (OTCID:MDCE) Engages Task-Based Software Technicians and External Platforms to Accelerate Technology and Enterprise Expansion
Create E-mail Alert Related Categories
SEC FilingsRelated Entities
Morgan StanleySign up for StreetInsider Free!
Receive full access to all new and archived articles, unlimited portfolio tracking, e-mail alerts, custom newswires and RSS feeds - and more!
