




Form 424B2 MORGAN STANLEY
 Tweet
 Share
 E-mail
October 2026
Preliminary Pricing Supplement No. 19,303
Registration Statement Nos. 333-293641; 333-293641-01
Dated October 5, 2026
Filed pursuant to Rule 424(b)(2)
Morgan Stanley Finance LLC
Structured Investments
Opportunities in U.S. Assets
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Fully and Unconditionally Guaranteed by Morgan Stanley
Principal at Risk Securities
The securities offered are unsecured obligations of Morgan Stanley Finance LLC (“MSFL”) and are fully and unconditionally guaranteed by Morgan Stanley. The securities have the terms described in the accompanying product supplement, tax supplement and prospectus, as supplemented or modified by this document. The securities do not provide for the regular payment of interest and do not guarantee the return of any principal at maturity. Instead, the securities will pay a contingent monthly coupon (plus any previously unpaid contingent monthly coupons from prior observation dates pursuant to the memory coupon feature) but only if the determination closing price of the underlying shares is at or above 80% of the initial share price, which we refer to as the coupon barrier level, on the related observation date. If, however, the determination closing price of the underlying shares is less than the coupon barrier level on any observation date, we will pay no interest for the related monthly period. The securities will be automatically redeemed if the determination closing price of the underlying shares is greater than or equal to the initial share price on any redemption determination date for the early redemption payment equal to the sum of the stated principal amount plus the related contingent monthly coupon and any previously unpaid contingent monthly coupons from prior observation dates pursuant to the memory coupon feature. No further payments will be made on the securities once they have been redeemed. At maturity, if the securities have not previously been redeemed and the final share price of the underlying shares is greater than or equal to 80% of the initial share price, meaning that the underlying shares have not declined by an amount greater than the buffer amount of 20%, the payment at maturity will be the stated principal amount and the related contingent monthly coupon and any previously unpaid contingent monthly coupons from prior observation dates pursuant to the memory coupon feature. However, if the final share price of the underlying shares is less than 80% of the initial share price, meaning that the underlying shares have declined by an amount greater than the buffer amount of 20%, investors will lose 1.25% for every 1% decline in the final share price of the underlying shares from the initial share price beyond the buffer amount of 20%. Accordingly, investors in the securities must be willing to accept the risk of losing their entire initial investment and also the risk of not receiving any contingent monthly coupons throughout the 1-year term of the securities. The securities are for investors who are willing to risk their principal and seek an opportunity to earn interest at a potentially above-market rate in exchange for the risk of receiving no interest over the entire 1-year term and in exchange for the possibility of an automatic early redemption prior to maturity. Investors will not participate in any appreciation of the underlying shares. The securities are notes issued as part of MSFL’s Series A Global Medium-Term Notes program.
Investors should be knowledgeable about the risks associated with cryptocurrencies and digital assets because the underlying shares seek to reflect generally the performance of the price of bitcoin and therefore the securities involve significant risks in investments tracking cryptocurrencies. Bitcoin has historically exhibited high price volatility relative to more traditional asset classes and has experienced extreme volatility in recent periods and may continue to do so.
All payments are subject to our credit risk. If we default on our obligations, you could lose some or all of your investment. These securities are not secured obligations and you will not have any security interest in, or otherwise have any access to, any underlying reference asset or assets.
|
SUMMARY TERMS |
||||
|
Issuer: |
Morgan Stanley Finance LLC |
|||
|
Guarantor: |
Morgan Stanley |
|||
|
Underlying shares: |
iShares® Bitcoin Trust ETF (the “IBIT Shares”) |
|||
|
Aggregate principal amount: |
$ |
|||
|
Stated principal amount: |
$1,000 per security |
|||
|
Issue price: |
$1,000 per security |
|||
|
Pricing date: |
October 5, 2026 |
|||
|
Original issue date: |
October 8, 2026 (3 business days after the pricing date) |
|||
|
Maturity date: |
October 8, 2027 |
|||
|
Early redemption: |
If, on any redemption determination date, beginning on November 5, 2026, the determination closing price of the underlying shares is greater than or equal to the initial share price, the securities will be automatically redeemed for an early redemption payment on the related early redemption date. No further payments will be made on the securities once they have been redeemed. The securities will not be redeemed early on any early redemption date if the determination closing price of the underlying shares is below the initial share price on the related redemption determination date. |
|||
|
Early redemption payment: |
The early redemption payment will be an amount equal to (i) the stated principal amount for each security you hold plus (ii) the contingent monthly coupon with respect to the related observation date and any previously unpaid contingent monthly coupons from prior observation dates pursuant to the memory coupon feature. |
|||
|
Determination closing price: |
The closing price of the underlying shares on any redemption determination date or observation date (other than the final observation date) times the adjustment factor on such redemption determination date or observation date, as applicable |
|||
|
Redemption determination dates: |
Monthly, as set forth under “Observation Dates, Redemption Determination Dates, Coupon Payment Dates and Early Redemption Dates” below, subject to postponement for non-trading days and certain market disruption events. |
|||
|
Early redemption dates: |
Monthly. See “Observation Dates, Redemption Determination Dates, Coupon Payment Dates and Early Redemption Dates” below. If any such day is not a business day, that early redemption payment, if payable, will be made on the next succeeding business day and no adjustment will be made to any early redemption payment made on that succeeding business day. |
|||
|
Contingent monthly coupon: |
We will pay a contingent monthly coupon at an annual rate of 15.96% (corresponding to approximately $13.30 per month per security) on each coupon payment date but only if the determination closing price of the underlying shares is at or above the coupon barrier level on the related observation date. If, on any observation date, the determination closing price of the underlying shares is less than the coupon barrier level, no contingent monthly coupon will be paid with respect to that observation date. It is possible that the underlying shares will remain below the coupon barrier level for extended periods of time or even throughout the entire 1-year term of the securities so that you will receive few or no contingent monthly coupons. |
|||
|
Memory coupon feature: |
If the contingent monthly coupon is not paid on any coupon payment date (because the determination closing price of the underlying shares on any observation date is less than the coupon barrier level), such unpaid contingent monthly coupon will be paid on a later coupon payment date but only if the determination closing price of the underlying shares on such later observation date is greater than or equal to the coupon barrier level; provided, however, in the case of any such payment of a previously unpaid contingent monthly coupon, that no additional interest shall accrue or be payable in respect of such unpaid contingent monthly coupon from and after the end of the original interest period for such unpaid contingent monthly coupon. You will not receive such unpaid contingent monthly coupons if the determination closing price of the underlying shares is less than the coupon barrier level on each subsequent observation date. |
|||
|
Coupon barrier level: |
$38.184, which is equal to 80% of the initial share price |
|||
|
Buffer amount: |
20% |
|||
|
Payment at maturity: |
If the securities are not redeemed prior to maturity, investors will receive a payment at maturity determined as follows: ●If the final share price of the underlying shares is greater than or equal to 80% of the initial share price, meaning that the underlying shares have not decreased by an amount greater than the buffer amount of 20% from the initial share price: the stated principal amount and the contingent monthly coupon with respect to the final monthly period and any previously unpaid contingent monthly coupons with respect to the prior observation dates pursuant to the memory coupon feature ●If the final share price of the underlying shares is less than 80% of the initial share price, meaning that the underlying shares have decreased by an amount greater than the buffer amount of 20% from the initial share price: $1,000 + [$1,000 × (share percent change + 20%) × downside factor] Under these circumstances, the payment at maturity will be less than the stated principal amount of $1,000 and could be zero. |
|||
|
|
Terms continued on the following page |
|||
|
Agent: |
Morgan Stanley & Co. LLC (“MS & Co.”), an affiliate of MSFL and a wholly owned subsidiary of Morgan Stanley. See “Supplemental information regarding plan of distribution; conflicts of interest.” |
|||
|
Estimated value on the pricing date: |
Approximately $990.60 per security, or within $25.00 of that estimate. See “Investment Summary” beginning on page 3. |
|||
|
Commissions and issue price: |
Price to public |
Agent’s commissions and fees |
Proceeds to us(3) |
|
|
Per security |
$1,000 |
$5(1) |
|
|
|
|
|
$5(2) |
$990 |
|
|
Total |
$ |
$ |
$ |
|
(1)Selected dealers, including Morgan Stanley Wealth Management (an affiliate of the agent), and their financial advisors will collectively receive from the agent, MS & Co., a fixed sales commission of $5 for each security they sell. See “Supplemental information regarding plan of distribution; conflicts of interest.” For additional information, see “Plan of Distribution (Conflicts of Interest)” in the accompanying product supplement.
(2)Reflects a structuring fee payable to Morgan Stanley Wealth Management by the agent or its affiliates of $5 for each security.
(3)See “Use of proceeds and hedging” on page 21.
The securities involve risks not associated with an investment in ordinary debt securities. See “Risk Factors” beginning on page 10.
The Securities and Exchange Commission and state securities regulators have not approved or disapproved these securities, or determined if this document or the accompanying product supplement, tax supplement and prospectus is truthful or complete. Any representation to the contrary is a criminal offense.
The securities are not deposits or savings accounts and are not insured by the Federal Deposit Insurance Corporation or any other governmental agency or instrumentality, nor are they obligations of, or guaranteed by, a bank.
You should read this document together with the related product supplement, tax supplement and prospectus, each of which can be accessed via the hyperlinks below. Please also see “Additional Terms of the Securities” and “Additional Information About the Securities” at the end of this document.
As used in this document, “we,” “us” and “our” refer to Morgan Stanley or MSFL, or Morgan Stanley and MSFL collectively, as the context requires.
Product Supplement for Auto-Callable Securities dated April 8, 2026 Tax Supplement dated April 8, 2026 Prospectus dated April 8, 2026
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
|
Terms continued from previous page: |
|
|
Initial share price: |
$47.73, which is the closing price on October 2, 2026 |
|
Coupon payment dates: |
Monthly, as set forth under “Observation Dates, Redemption Determination Dates, Coupon Payment Dates and Early Redemption Dates” below. If any such day is not a business day, that coupon payment will be made on the next succeeding business day and no adjustment will be made to any coupon payment made on that succeeding business day; provided that the contingent monthly coupon, if any, with respect to the final observation date shall be paid on the maturity date. |
|
Observation dates: |
Monthly, as set forth under “Observation Dates, Redemption Determination Dates, Coupon Payment Dates and Early Redemption Dates” below, subject to postponement for non-trading days and certain market disruption events. We also refer to October 5, 2027, which is the third scheduled business day preceding the scheduled maturity date, as the final observation date |
|
Final share price: |
The closing price of the underlying shares on the final observation date times the adjustment factor on such date |
|
Downside factor: |
1.25 |
|
Adjustment factor: |
1.0, subject to adjustment in the event of certain events affecting such underlying shares |
|
Share percent change: |
(final share price – initial share price) / initial share price |
|
CUSIP / ISIN: |
61781LM80 / US61781LM805 |
|
Listing: |
The securities will not be listed on any securities exchange. |
Observation Dates, Redemption Determination Dates, Coupon Payment Dates and Early Redemption Dates
|
Observation Dates / Redemption Determination Dates |
Coupon Payment Dates / Early Redemption Dates |
|
November 5, 2026 |
November 10, 2026 |
|
December 7, 2026 |
December 10, 2026 |
|
January 5, 2027 |
January 8, 2027 |
|
February 5, 2027 |
February 10, 2027 |
|
March 5, 2027 |
March 10, 2027 |
|
April 5, 2027 |
April 8, 2027 |
|
May 5, 2027 |
May 10, 2027 |
|
June 7, 2027 |
June 10, 2027 |
|
July 6, 2027 |
July 9, 2027 |
|
August 5, 2027 |
August 10, 2027 |
|
September 7, 2027 |
September 10, 2027 |
|
October 5, 2027 (final observation date) |
October 8, 2027 (maturity date) |
October 2026 Page 2
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
Investment Summary
Contingent Income Buffered Auto-Callable Securities with Memory Coupon
Principal at Risk Securities
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027 All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF (the “securities”) do not provide for the regular payment of interest. Instead, the securities will pay a contingent monthly coupon (plus any previously unpaid contingent monthly coupons from prior observation dates pursuant to the memory coupon feature) but only if the determination closing price of the iShares® Bitcoin Trust ETF which we refer to as the underlying shares, is at or above 80% of the initial share price, which we refer to as the coupon barrier level, on the related observation date. If, however, the determination closing price of the underlying shares is less than the coupon barrier level on any observation date, we will pay no interest for the related monthly period. The securities will be automatically redeemed if the determination closing price of the underlying shares is greater than or equal to the initial share price on any redemption determination date for the early redemption payment equal to the sum of the stated principal amount plus the related contingent monthly coupon and any previously unpaid contingent monthly coupons from prior observation dates pursuant to the memory coupon feature. No further payments will be made on the securities once they have been redeemed. At maturity, if the securities have not previously been redeemed and the final share price of the underlying shares is greater than or equal to 80% of the initial share price, meaning that the underlying shares have not declined by an amount greater than the buffer amount of 20%, the payment at maturity will be the stated principal amount and the related contingent monthly coupon and any previously unpaid contingent monthly coupons from prior observation dates pursuant to the memory coupon feature. However, if the final share price of the underlying shares is less than 80% of the initial share price, meaning that the underlying shares have declined by an amount greater than the buffer amount of 20%, investors will lose 1.25% for every 1% decline in the final share price of the underlying shares from the initial share price beyond the buffer amount of 20%. Accordingly, investors in the securities must be willing to accept the risk of losing their entire initial investment and also the risk of not receiving any contingent monthly coupons throughout the 1-year term of the securities. Investors will not participate in any appreciation in the price of the underlying shares.
|
Maturity: |
1 year |
|
Contingent monthly coupon: |
We will pay a contingent monthly coupon at an annual rate of 15.96% (corresponding to approximately $13.30 per month per security) on each coupon payment date but only if the determination closing price of the underlying shares is at or above the coupon barrier level on the related observation date. If the contingent monthly coupon is not paid on any coupon payment date (because the determination closing price of the underlying shares on any observation date is less than the coupon barrier level), such unpaid contingent monthly coupon will be paid on a later coupon payment date but only if the determination closing price of the underlying shares on such later observation date is greater than or equal to the coupon barrier level; provided, however, in the case of any such payment of a previously unpaid contingent monthly coupon, that no additional interest shall accrue or be payable in respect of such unpaid contingent monthly coupon from and after the end of the original interest period for such unpaid contingent monthly coupon. You will not receive such unpaid contingent monthly coupons if the determination closing price of the underlying shares is less than the coupon barrier level on each subsequent observation date. If, on any observation date, the determination closing price of the underlying shares is less than the coupon barrier level, no contingent monthly coupon will be paid with respect to that observation date. It is possible that the underlying shares will remain below the coupon barrier level for extended periods of time or even throughout the entire 1-year term of the securities so that you will receive few or no contingent monthly coupons. |
|
Automatic early redemption: |
If the determination closing price of the underlying shares is greater than or equal to the initial share price on any redemption determination date, beginning on November 5, 2026, the securities will be automatically redeemed for an early redemption payment equal to the stated principal amount plus the contingent monthly coupon with respect to the related observation date and any previously unpaid contingent monthly coupons from prior observation dates pursuant to the memory coupon feature. No further payments will be |
October 2026 Page 3
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
|
made on the securities once they have been redeemed. |
|
|
Payment at maturity: |
If the securities have not previously been redeemed and the final share price of the underlying shares is greater than or equal to 80% of the initial share price, meaning that the underlying shares have not declined by an amount greater than the buffer amount of 20%, the payment at maturity will be the stated principal amount and the related contingent monthly coupon with respect to the final monthly period and any previously unpaid contingent monthly coupons from prior observation dates pursuant to the memory coupon feature. If the final share price of the underlying shares is less than 80% of the initial share price, meaning that the underlying shares have declined by an amount greater than the buffer amount of 20%, investors will lose 1.25% for every 1% decline in the final share price of the underlying shares from the initial share price beyond the buffer amount of 20%. Under these circumstances, the payment at maturity will be less than the stated principal amount of the securities and could be zero. Accordingly, investors in the securities must be willing to accept the risk of losing their entire initial investment. |
October 2026 Page 4
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
The original issue price of each security is $1,000. This price includes costs associated with issuing, selling, structuring and hedging the securities, which are borne by you, and, consequently, the estimated value of the securities on the pricing date will be less than $1,000. We estimate that the value of each security on the pricing date will be approximately $990.60, or within $25.00 of that estimate. Our estimate of the value of the securities as determined on the pricing date will be set forth in the final pricing supplement.
What goes into the estimated value on the pricing date?
In valuing the securities on the pricing date, we take into account that the securities comprise both a debt component and a performance-based component linked to the underlying shares. The estimated value of the securities is determined using our own pricing and valuation models, market inputs and assumptions relating to the underlying shares, instruments based on the underlying shares, volatility and other factors including current and expected interest rates, as well as an interest rate related to our secondary market credit spread, which is the implied interest rate at which our conventional fixed rate debt trades in the secondary market.
What determines the economic terms of the securities?
In determining the economic terms of the securities, including the contingent monthly coupon rate, the coupon barrier level, the buffer amount and the downside factor, we use an internal funding rate, which is likely to be lower than our secondary market credit spreads and therefore advantageous to us. If the issuing, selling, structuring and hedging costs borne by you were lower or if the internal funding rate were higher, one or more terms of the securities would be more favorable to you.
What is the relationship between the estimated value on the pricing date and the secondary market price of the securities?
The price at which MS & Co. purchases the securities in the secondary market, absent changes in market conditions, including those related to the underlying shares, may vary from, and be lower than, the estimated value on the pricing date, because the secondary market price takes into account our secondary market credit spread as well as the bid-offer spread that MS & Co. would charge in a secondary market transaction of this type and other factors. However, because the costs associated with issuing, selling, structuring and hedging the securities are not fully deducted upon issuance, for a period of up to 2 months following the issue date, to the extent that MS & Co. may buy or sell the securities in the secondary market, absent changes in market conditions, including those related to the underlying shares, and to our secondary market credit spreads, it would do so based on values higher than the estimated value. We expect that those higher values will also be reflected in your brokerage account statements.
MS & Co. may, but is not obligated to, make a market in the securities and, if it once chooses to make a market, may cease doing so at any time.
October 2026 Page 5
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
Key Investment Rationale
The securities do not provide for the regular payment of interest. Instead, the securities will pay a contingent monthly coupon (plus any previously unpaid contingent monthly coupons from prior observation dates pursuant to the memory coupon feature) but only if the determination closing price of the underlying shares is at or above the coupon barrier level on the related observation date. The securities have been designed for investors who are willing to forgo market floating interest rates and risk the loss of principal and accept the risk of receiving few or no coupon payments for the entire 1-year term of the securities in exchange for an opportunity to earn interest at a potentially above-market rate if the underlying shares close at or above the coupon barrier level on each observation date, unless the securities are redeemed early. The following scenarios are for illustration purposes only to demonstrate how the coupon and the payment at maturity (if the securities have not previously been redeemed) are calculated, and do not attempt to demonstrate every situation that may occur. Accordingly, the securities may or may not be redeemed, the contingent monthly coupon may be payable in none of, or some but not all of, the periods during the 1-year term of the securities, and the payment at maturity may be less than the stated principal amount of the securities and may be zero.
|
Scenario 1: The securities are redeemed prior to maturity |
Prior to early redemption, investors receive the contingent monthly coupon for the periods for which the determination closing price of the underlying shares is at or above the coupon barrier level on the related observation date, but not for the periods for which the determination closing price of the underlying shares is below the coupon barrier level on the related observation date. When the underlying shares close at or above the initial share price on a redemption determination date, the securities will be automatically redeemed for the stated principal amount plus the contingent monthly coupon with respect to the related observation date and any previously unpaid contingent monthly coupons with respect to any prior observation dates pursuant to the memory coupon feature. |
|
Scenario 2: The securities are not redeemed prior to maturity, and investors receive principal back at maturity |
This scenario assumes that the underlying shares close at or above the coupon barrier level on some observation dates, but the underlying shares close below the coupon barrier level on the others, and the underlying shares close below the initial share price on every redemption determination date. Consequently, the securities are not redeemed early, and investors receive the contingent monthly coupon (plus any previously unpaid contingent monthly coupons from prior observation dates pursuant to the memory coupon feature) for the periods for which the determination closing price of the underlying shares is at or above the coupon barrier level on the related observation date, but not for the periods for which the determination closing price of the underlying shares is below the coupon barrier level on the related observation date. On the final observation date, the underlying shares close at or above 80% of the initial share price, meaning that the underlying shares have not declined by an amount greater than the buffer amount of 20%. At maturity, investors will receive the stated principal amount and the related contingent monthly coupon and any previously unpaid contingent monthly coupons with respect to any prior observation dates pursuant to the memory coupon feature. |
October 2026 Page 6
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
|
Scenario 3: The securities are not redeemed prior to maturity, and investors suffer a loss of principal at maturity |
This scenario assumes that the underlying shares close at or above the coupon barrier level on some observation dates, but the underlying shares close below the coupon barrier level on the others, and the underlying shares close below the initial share price on every redemption determination date. Consequently, the securities are not redeemed early, and investors receive the contingent monthly coupon (plus any previously unpaid contingent monthly coupons from prior observation dates pursuant to the memory coupon feature) for the periods for which the determination closing price of the underlying shares is greater than or equal to the coupon barrier level on the related observation date, but not for the periods for which the determination closing price of the underlying shares is below the coupon barrier level on the related observation date. On the final observation date, the underlying shares close below 80% of the initial share price, meaning that the underlying shares have declined by an amount greater than the buffer amount of 20%. At maturity, investors will lose 1.25% for every 1% decline in the final share price of the underlying shares from the initial share price beyond the buffer amount of 20%. Under these circumstances, the payment at maturity will be less than the stated principal amount and could be zero. No coupon will be paid at maturity in this scenario and investors will not receive payment for any previously unpaid contingent monthly coupons. |
October 2026 Page 7
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
Hypothetical Examples
The following hypothetical examples illustrate how to determine whether a contingent monthly coupon is paid with respect to an observation date and how to calculate the payment at maturity, if any, assuming the securities are not redeemed prior to maturity. The following examples are for illustrative purposes only. Whether you receive a contingent monthly coupon will be determined by reference to the determination closing price of the underlying shares on each observation date, and the amount you will receive at maturity, if any, will be determined by reference to the final share price of the underlying shares on the final observation date. The actual initial share price and coupon barrier level are set forth on the cover of this document. All payments on the securities, if any, are subject to our credit risk. The below examples are based on the following terms:
|
Contingent Coupon: |
15.96% per annum (corresponding to approximately $13.30 per month per security) With respect to each coupon payment date, a contingent monthly coupon plus any previously unpaid contingent monthly coupons with respect to any prior observation dates pursuant to the memory coupon feature is paid but only if the determination closing price of the underlying shares is at or above the coupon barrier level on the related observation date. |
|
Payment at Maturity (if the securities are not redeemed prior to maturity): |
If the final share price of the underlying shares is greater than or equal to 80% of the initial share price: the stated principal amount and the contingent monthly coupon with respect to the final monthly period and any previously unpaid contingent monthly coupons with respect to the prior observation dates pursuant to the memory coupon feature.
If the final share price of the underlying shares is less than 80% of the initial share price: $1,000 + [$1,000 × (share percent change + 20%) × downside factor] |
|
Stated Principal Amount: |
$1,000 |
|
Downside Factor: |
1.25 |
|
Hypothetical Initial Share Price: |
$60.00 |
|
Hypothetical Coupon Barrier Level: |
$48.00, which is 80% of the hypothetical initial share price |
|
Buffer Amount: |
20% |
How to determine whether a contingent monthly coupon is payable with respect to an observation date:
|
|
Determination Closing Price |
Contingent Coupon |
|
Hypothetical Observation Date 1 |
$55.00 (at or above the coupon barrier level) |
$13.30 |
|
Hypothetical Observation Date 2 |
$40.00 (below the coupon barrier level) |
$0 |
|
Hypothetical Observation Date 3 |
$70.00 (at or above the coupon barrier level) |
$13.30 + $13.30 = $26.60 |
On hypothetical observation date 1, the underlying shares close at or above the coupon barrier level. Therefore, a contingent monthly coupon of $13.30 is paid on the relevant coupon payment date.
On hypothetical observation date 2, the underlying shares close below the coupon barrier level and accordingly no contingent monthly coupon is paid on the relevant coupon payment date.
On hypothetical observation date 3, the underlying shares close at or above the coupon barrier level. Therefore, investors receive the hypothetical contingent monthly coupon with respect to the third observation date as well as the previously unpaid contingent monthly coupon with respect to the second observation date.
You will not receive a contingent monthly coupon on any coupon payment date if the determination closing price of the underlying shares is below the coupon barrier level on the related observation date.
October 2026 Page 8
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
How to calculate the payment at maturity:
In the following examples, the underlying shares close below the initial share price on each redemption determination date, and, consequently, the securities are not automatically redeemed prior to, and remain outstanding until, maturity.
|
|
Final Share Price |
Payment at Maturity |
|
Example 1: |
$75.00 (at or above 80% of initial share price) |
The stated principal amount and the contingent monthly coupon with respect to the final monthly period and any previously unpaid contingent monthly coupons from prior observation dates pursuant to the memory coupon feature |
|
Example 2: |
$6.00 (below 80% of initial share price) |
$1,000 + [$1,000 × (share percent change + 20%) × downside factor] |
In example 1, the final share price of the underlying shares is at or above 80% of the initial share price. Therefore, investors receive at maturity the stated principal amount of the securities and the contingent monthly coupon with respect to the final monthly period and any previously unpaid contingent monthly coupons from prior observation dates pursuant to the memory coupon feature. However, investors do not participate in any appreciation of the underlying shares.
In example 2, the final share price of the underlying shares is below 80% of the initial share price. Therefore, investors are exposed to the downside performance of the underlying shares and investors lose 1.25% of principal for every 1% decline in the final share price of the underlying shares from the initial share price beyond the buffer amount of 20%. The payment at maturity in this example is equal to $125.00 per security. Investors do not receive the contingent monthly coupon for the final observation date.
If the final share price of the underlying shares is below 80% of the initial share price, you will be exposed to the downside performance of the underlying shares at maturity, and your payment at maturity will be less than the stated principal amount per security and could be zero.
October 2026 Page 9
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
Risk Factors
This section describes the material risks relating to the securities. For further discussion of these and other risks, you should read the section entitled “Risk Factors” in the accompanying product supplement, tax supplement and prospectus. We also urge you to consult with your investment, legal, tax, accounting and other advisers in connection with your investment in the securities.
Risks Relating to an Investment in the Securities
■The securities do not guarantee the return of any principal. The terms of the securities differ from those of ordinary debt securities in that they do not guarantee the return of any of the principal amount at maturity. If the securities have not been automatically redeemed prior to maturity and if the final share price of the underlying shares is less than 80% of the initial share price, meaning that the underlying shares have declined by an amount greater than the buffer amount of 20%, you will lose 1.25% for every 1% decline in the final share price of the underlying shares from the initial share price beyond the buffer amount of 20%. In this case, the payment at maturity will be less than the stated principal amount and could be zero. You could lose your entire investment in the securities.
■The securities do not provide for the regular payment of interest and may pay no interest over the entire term of the securities. The terms of the securities differ from those of ordinary debt securities in that they do not provide for the regular payment of interest. Instead, the securities will pay a contingent monthly coupon but only if the determination closing price of the underlying shares is at or above 80% of the initial share price, which we refer to as the coupon barrier level, on the related observation date. If, on the other hand, the determination closing price of the underlying shares is lower than the coupon barrier level on the relevant observation date for any interest period, we will pay no coupon on the applicable coupon payment date. However, if the contingent monthly coupon is not paid on any coupon payment date because the determination closing price of the underlying shares is less than the coupon barrier level on the related observation date, such unpaid contingent monthly coupon will be paid pursuant to the memory coupon feature on a later coupon payment date but only if the determination closing price of the underlying shares on such later observation date is greater than or equal to the coupon barrier level. Therefore, you will not receive such unpaid contingent monthly coupon pursuant to the memory coupon feature if the determination closing price of the underlying shares is less than the coupon barrier level on each subsequent observation date. It is possible that the determination closing price of the underlying shares could remain below the coupon barrier level for extended periods of time or even throughout the entire 1-year term of the securities so that you will receive few or no contingent monthly coupons. If you do not earn sufficient contingent monthly coupons over the term of the securities, the overall return on the securities may be less than the amount that would be paid on a conventional debt security of ours of comparable maturity.
■The contingent monthly coupon, if any, is based only on the determination closing price of the underlying shares on the related observation date at the end of the related interest period. Whether the contingent monthly coupon will be paid on any coupon payment date will be determined at the end of the relevant interest period based on the determination closing price of the underlying shares on the relevant observation date. As a result, you will not know whether you will receive the contingent monthly coupon on any coupon payment date until near the end of the relevant interest period. Moreover, because the contingent monthly coupon is based solely on the price of the underlying shares on observation dates, if the determination closing price of the underlying shares on any observation date is below the coupon barrier level, you will receive no coupon for the related interest period even if the price of the underlying shares was higher on other days during that interest period.
■Investors will not participate in any appreciation in the price of the underlying shares. Investors will not participate in any appreciation in the price of the underlying shares from the initial share price, and the return on the securities will be limited to the contingent monthly coupon that is paid with respect to each observation date on which each determination closing price is greater than or equal to the coupon barrier level, if any.
■The market price will be influenced by many unpredictable factors. Several factors, many of which are beyond our control, will influence the value of the securities in the secondary market and the price at which MS & Co. may be willing to purchase or sell the securities in the secondary market. We expect that generally the level of interest rates available in the market and the price of the underlying shares on any day, including in relation to the coupon barrier level, will affect the value of the securities more than any other factors. Other factors that may influence the value of the securities include:
othe trading price and volatility (frequency and magnitude of changes in value) of the underlying shares,
October 2026 Page 10
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
owhether the determination closing price of the underlying shares has been below the coupon barrier level on any observation date,
ogeopolitical conditions and economic, financial, political, regulatory or judicial events that affect the underlying shares or markets generally and which may affect the price of the underlying shares,
othe time remaining until the securities mature,
ointerest and yield rates in the market,
othe occurrence of certain events affecting the underlying shares that may or may not require an adjustment to the adjustment factor, and
oany actual or anticipated changes in our credit ratings or credit spreads.
Generally, the longer the time remaining to maturity, the more the market price of the securities will be affected by the other factors described above. Some or all of these factors will influence the price that you will receive if you sell your securities prior to maturity. For example, you may have to sell your securities at a substantial discount from the stated principal amount of $1,000 per security if the price of the underlying shares at the time of sale is near or below the coupon barrier level or if market interest rates rise.
The price of the underlying shares may be, and has recently been, volatile, and we can give you no assurance that the volatility will lessen. The price of the underlying shares may decrease and be below the coupon barrier level on each observation date so that you will receive no return on your investment, and the underlying shares may decline by an amount greater than the buffer amount as of the final observation date so that you lose some or all of your initial investment in the securities. There can be no assurance that the closing price of the underlying shares will be at or above the coupon barrier level on any observation date so that you will receive a coupon payment on the securities for the applicable interest period, or that the underlying shares will not decline by an amount greater than the buffer amount of 20% as of the final observation date so that you do not suffer a loss on your initial investment in the securities. The IBIT Shares began trading on January 11, 2024 and therefore have limited historical performance. See “iShares® Bitcoin Trust ETF Overview” below.
■The securities may be accelerated at our option if a discontinuance or liquidation event occurs. If the calculation agent determines that trading in the underlying shares on the relevant exchange is permanently discontinued or the underlying shares are liquidated or otherwise terminated and there is no successor underlier, we will be permitted to accelerate the payment on the securities at our option and pay you an amount determined in good faith and in a commercially reasonable manner by the calculation agent. If we accelerate the payment on the securities at our option, your investment may result in a loss and you may not be able to reinvest your money at a comparable return for a similar level of risk. For more information, see “Additional Terms of the Securities—Acceleration upon a discontinuance or liquidation event” below.
■The securities are subject to our credit risk, and any actual or anticipated changes to our credit ratings or credit spreads may adversely affect the market value of the securities. You are dependent on our ability to pay all amounts due on the securities on each coupon payment date, upon automatic redemption and at maturity and therefore you are subject to our credit risk. The securities are not guaranteed by any other entity. If we default on our obligations under the securities, your investment would be at risk and you could lose some or all of your investment. As a result, the market value of the securities prior to maturity will be affected by changes in the market’s view of our creditworthiness. Any actual or anticipated decline in our credit ratings or increase in the credit spreads charged by the market for taking our credit risk is likely to adversely affect the market value of the securities.
■As a finance subsidiary, MSFL has no independent operations and will have no independent assets. As a finance subsidiary, MSFL has no independent operations beyond the issuance and administration of its securities and will have no independent assets available for distributions to holders of MSFL securities if they make claims in respect of such securities in a bankruptcy, resolution or similar proceeding. Accordingly, any recoveries by such holders will be limited to those available under the related guarantee by Morgan Stanley and that guarantee will rank pari passu with all other unsecured, unsubordinated obligations of Morgan Stanley. Holders will have recourse only to a single claim against Morgan Stanley and its assets under the guarantee. Holders of securities issued by MSFL should accordingly assume that in any such proceedings they would not have any priority over and should be treated pari passu with the claims of other unsecured, unsubordinated creditors of Morgan Stanley, including holders of Morgan Stanley-issued securities.
October 2026 Page 11
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
■Reinvestment risk. The term of your investment in the securities may be shortened due to the automatic early redemption feature of the securities. If the securities are redeemed prior to maturity, you will receive no more contingent monthly coupons and may be forced to invest in a lower interest rate environment and may not be able to reinvest at comparable terms or returns.
■The securities will not be listed on any securities exchange and secondary trading may be limited, and accordingly, you should be willing to hold your securities for the entire 1-year term of the securities. The securities will not be listed on any securities exchange. Therefore, there may be little or no secondary market for the securities. MS & Co. may, but is not obligated to, make a market in the securities and, if it once chooses to make a market, may cease doing so at any time. When it does make a market, it will generally do so for transactions of routine secondary market size at prices based on its estimate of the current value of the securities, taking into account its bid/offer spread, our credit spreads, market volatility, the notional size of the proposed sale, the cost of unwinding any related hedging positions, the time remaining to maturity and the likelihood that it will be able to resell the securities. Even if there is a secondary market, it may not provide enough liquidity to allow you to trade or sell the securities easily. Since other broker-dealers may not participate significantly in the secondary market for the securities, the price at which you may be able to trade your securities is likely to depend on the price, if any, at which MS & Co. is willing to transact. If, at any time, MS & Co. were to cease making a market in the securities, it is likely that there would be no secondary market for the securities. Accordingly, you should be willing to hold your securities to maturity.
■The rate we are willing to pay for securities of this type, maturity and issuance size is likely to be lower than the rate implied by our secondary market credit spreads and advantageous to us. Both the lower rate and the inclusion of costs associated with issuing, selling, structuring and hedging the securities in the original issue price reduce the economic terms of the securities, cause the estimated value of the securities to be less than the original issue price and will adversely affect secondary market prices. Assuming no change in market conditions or any other relevant factors, the prices, if any, at which dealers, including MS & Co., may be willing to purchase the securities in secondary market transactions will likely be significantly lower than the original issue price, because secondary market prices will exclude the issuing, selling, structuring and hedging-related costs that are included in the original issue price and borne by you and because the secondary market prices will reflect our secondary market credit spreads and the bid-offer spread that any dealer would charge in a secondary market transaction of this type as well as other factors.
The inclusion of the costs of issuing, selling, structuring and hedging the securities in the original issue price and the lower rate we are willing to pay as issuer make the economic terms of the securities less favorable to you than they otherwise would be.
However, because the costs associated with issuing, selling, structuring and hedging the securities are not fully deducted upon issuance, for a period of up to 2 months following the issue date, to the extent that MS & Co. may buy or sell the securities in the secondary market, absent changes in market conditions, including those related to the underlying shares, and to our secondary market credit spreads, it would do so based on values higher than the estimated value, and we expect that those higher values will also be reflected in your brokerage account statements.
■The estimated value of the securities is determined by reference to our pricing and valuation models, which may differ from those of other dealers, and is not a maximum or minimum secondary market price. These pricing and valuation models are proprietary and rely in part on subjective views of certain market inputs and certain assumptions about future events, which may prove to be incorrect. As a result, because there is no market-standard way to value these types of securities, our models may yield a higher estimated value of the securities than those generated by others, including other dealers in the market, if they attempted to value the securities. In addition, the estimated value on the pricing date does not represent a minimum or maximum price at which dealers, including MS & Co., would be willing to purchase your securities in the secondary market (if any exists) at any time. The value of your securities at any time after the date of this document will vary based on many factors that cannot be predicted with accuracy, including our creditworthiness and changes in market conditions. See also “The market price will be influenced by many unpredictable factors” above.
■Not equivalent to investing in the underlying shares or their underlying asset. Investing in the securities is not equivalent to investing in the underlying shares or their underlying asset. Investors in the securities will not have voting rights or any other rights with respect to the underlying shares or the underlying asset. As a result, the return will not reflect the return investors would realize if they actually owned and held the underlying shares or the underlying asset for a period similar to the term of the investment, because the investors will not receive any dividend payments, distributions or any other payments made on such shares or asset, as applicable.
October 2026 Page 12
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
■Hedging and trading activity by our affiliates could potentially affect the value of the securities. One or more of our affiliates and/or third-party dealers expect to carry out hedging activities related to the securities (and to other instruments linked to the underlying shares or the underlying asset), including trading in the underlying shares and in other instruments related to the underlying shares or the underlying asset. As a result, these entities may be unwinding or adjusting hedge positions during the term of the securities, and the hedging strategy may involve greater and more frequent dynamic adjustments to the hedge as the final observation date approaches. Some of our affiliates also trade the underlying shares, the underlying asset and other financial instruments related to the underlying shares or the underlying asset on a regular basis as part of their general broker-dealer and other businesses. Any of these hedging or trading activities on or prior to October 2, 2026 could potentially increase the initial share price of the underlying shares and, therefore, could increase (i) the value at or above which the underlying shares must close on the redemption determination dates so that the securities are redeemed prior to maturity for the early redemption payment, (ii) the coupon barrier level, which is the value at or above which the underlying shares must close on the observation dates so that you receive a contingent monthly coupon on the securities, and (iii) the value at or above which the underlying shares must close on the final observation date so that you are not exposed to the negative performance of the underlying shares at maturity. Additionally, such hedging or trading activities during the term of the securities could potentially affect the value of the underlying shares on the redemption determination dates and the observation dates and, accordingly, whether we redeem the securities prior to maturity, whether we pay a contingent monthly coupon on the securities and the amount of cash you will receive at maturity, if any.
■The calculation agent, which is a subsidiary of Morgan Stanley and an affiliate of MSFL, will make determinations with respect to the securities. As calculation agent, MS & Co. will determine the initial share price, the coupon barrier level, the final share price, the payment at maturity, if any, whether you receive a contingent monthly coupon on each coupon payment date and/or at maturity, whether you will receive any previously unpaid contingent monthly coupons pursuant to the memory coupon feature, whether the securities will be redeemed on any early redemption date, whether a market disruption event has occurred and whether to make any adjustments to the adjustment factor. Moreover, certain determinations made by MS & Co., in its capacity as calculation agent, may require it to exercise discretion and make subjective judgments, such as with respect to the occurrence or non-occurrence of market disruption events or calculation of the determination closing price in the event of a market disruption event. These potentially subjective determinations may affect the payout to you upon an automatic early redemption or at maturity, if any. For further information regarding these types of determinations, see “Description of Auto-Callable Securities—Auto-Callable Securities Linked to Underlying Shares” and “—Calculation Agent and Calculations” in the accompanying product supplement and “Additional Terms of the Securities—Acceleration upon discontinuance or liquidation event” below. In addition, MS & Co. has determined the estimated value of the securities on the pricing date.
■The U.S. federal income tax consequences of an investment in the securities offered by this pricing supplement are uncertain. There is no direct legal authority regarding the proper U.S. federal income tax treatment of the securities, and significant aspects of the tax treatment of the securities are uncertain. Moreover, non-U.S. investors should note that persons having withholding responsibility in respect of the securities are, absent an exception, expected to withhold on any coupon paid to a non-U.S. investor, generally at a rate of 30%. We will not pay any additional amounts in respect of such withholding. You should review carefully the section entitled “United States Federal Income Tax Considerations” herein, in combination with the section entitled “United States Federal Taxation” in the accompanying tax supplement, and consult your tax adviser regarding the U.S. federal income tax consequences of an investment in the securities.
Risks Relating to the Underlying Shares
■Governmental regulatory actions, such as sanctions, could adversely affect your investment in the securities. Governmental regulatory actions, including, without limitation, sanctions-related actions by the U.S. or a foreign government, could prohibit or otherwise restrict persons from holding the securities or the underlying asset, or engaging in transactions therein, and any such action could adversely affect the value of the underlying asset or the securities. These regulatory actions could result in restrictions on the securities and could result in the loss of a significant portion or all of your initial investment in the securities, including if you are forced to divest the securities due to the government mandates, especially if such divestment must be made at a time when the value of the securities has declined.
■The securities are subject to risks associated with bitcoin and digital assets. The investment objective of the iShares® Bitcoin Trust ETF is to reflect generally the performance of the price of bitcoin, less the iShares® Bitcoin Trust ETF’s expenses. Bitcoin is a digital asset, and use of bitcoin in the retail and commercial marketplace is relatively limited. Bitcoin generally operates without central authority or banks and is not backed by any government or organized governing
October 2026 Page 13
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
body. Digital assets such as bitcoin represent new, novel and rapidly evolving products, and their value is influenced by a wide variety of factors that are uncertain and difficult to evaluate. The trading prices of many digital assets, including bitcoin, have experienced extreme volatility in recent periods and may continue to do so. Digital asset markets in the United States exist in a state of regulatory uncertainty and the exchanges on which bitcoin trades globally, including in the United States, are relatively new and, in most cases, largely unregulated. Legislative or regulatory developments could significantly affect the value of bitcoin, as could competition from other digital assets. Political or economic crises may motivate large-scale sales of bitcoin, resulting in a reduction in the price of bitcoin. The value of bitcoin could be adversely affected by the actions of bitcoin miners and changes in the block rewards and transaction fees miners earn. Bitcoin is susceptible to theft, loss and fraud. The Bitcoin Network, bitcoin custodians and trading platforms are subject to risks relating to operational problems, technical glitches, internet disruptions, shutdowns, hackers and malware, all of which may also affect the price of bitcoin. Over the past several years, some digital asset platforms have been closed, been subject to criminal and civil litigation and have entered into bankruptcy proceedings due to fraud and manipulative activity, business failure and/or security breaches. Negative perception, a lack of stability and standardized regulation in the digital asset markets and/or the closure or temporary shutdown of digital asset trading platforms due to fraud, business failure, security breaches or government mandated regulation, and associated losses by customers, may reduce confidence in digital asset networks and result in greater volatility in the prices of digital assets, including bitcoin. These and other factors could have an adverse effect on the price of bitcoin and, therefore, the value of the securities.
■Investments linked to bitcoin are subject to specific risks relating to security threats. Security breaches, computer malware and computer hacking attacks have been a prevalent concern in relation to digital assets, including bitcoin. The sponsor of the Underlier has stated that it believes that the bitcoins held in the Underlier’s account at its bitcoin custodian or trading balance held with its prime execution agent will be an appealing target to hackers or malware distributors seeking to steal the Underlier’s bitcoins and will only become more appealing as the amount or value of the Underlier’s assets grow. To the extent that the Underlier is unable to identify and mitigate or stop new security threats or otherwise adapt to technological changes in the digital asset industry, the Underlier’s bitcoins may be subject to theft, loss or other attack.
■Investments linked to bitcoin are subject to specific risks relating to fraud and manipulation. Many digital asset platforms, both in the United States and abroad, are unlicensed, not subject to, or not in compliance with, regulation in relevant jurisdictions, or operate without extensive supervision by governmental authorities, and therefore may be more susceptible to fraudulent or manipulative acts and practices. In particular, those located outside the United States may be subject to significantly less stringent regulatory and compliance requirements in their local jurisdictions and may take the position that they are not subject to laws and regulations that would apply to a regulated financial market in the United States, or may, as a practical matter, be beyond the ambit of U.S. regulators. Furthermore, many bitcoin trading venues lack certain safeguards put in place by exchanges for more traditional assets to enhance the stability of trading on the exchanges, such as circuit breakers. Tools to detect and deter fraudulent or manipulative trading activities such as market manipulation, front-running of trades, and wash-trading may not be available to or employed by digital asset platforms, or may not exist at all. Sources of fraud and manipulation in the bitcoin market generally include, among others (1) wash trading; (2) persons with a dominant position in bitcoin manipulating bitcoin pricing; (3) hacking of the bitcoin network and trading platforms; (4) malicious control of the bitcoin network; (5) trading based on material, non-public information (for example, plans of market participants to significantly increase or decrease their holdings in bitcoin, new sources of demand for bitcoin) or based on the dissemination of false and misleading information; (6) manipulative activity involving purported “stablecoins,” and (7) fraud and manipulation at bitcoin trading platforms. The effect of potential market manipulation, front-running, wash-trading, and other fraudulent or manipulative trading practices may inflate the volumes actually present in crypto market and/or cause distortions in price, which could adversely impact the Underlier’s creation and redemption arbitrage mechanism and affect the value of the Underlier and, consequently, the securities.
■The underlying shares have very limited historical performance. The underlying shares began trading on January 11, 2024 and therefore have very limited historical performance. Past performance should not be considered indicative of future performance.
■The performance and market price of the underlying shares, particularly during periods of market volatility, may not correlate with the performance of their underlying asset or the net asset value per share of the underlying shares. The underlying shares do not fully replicate the performance of their underlying asset due to the fees and expenses charged by the underlying shares or by restrictions on access to their underlying asset due to other circumstances. The underlying shares do not generate any income, and as the underlying shares regularly sell their underlying asset to pay for ongoing expenses, the amount of the underlying asset represented by each share of the
October 2026 Page 14
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
underlying shares gradually declines over time. The underlying shares sell their underlying asset to pay expenses on an ongoing basis irrespective of whether the trading price of shares of the underlying shares rises or falls in response to changes in the price of their underlying asset. The sale by the underlying shares of underlying asset to pay expenses at a time of relatively low prices for such underlying asset could adversely affect the value of the securities. Additionally, there is a risk that part or all of the holdings of the underlying shares in their underlying asset could be lost, damaged or stolen due to war, terrorism, theft, natural disaster or otherwise. Finally, because the shares of the underlying shares are traded on an exchange and are subject to market supply and investor demand, the market price of one share of the underlying shares may differ from the net asset value per share of the underlying shares.
In particular, during periods of market volatility or unusual trading activity, trading in the underlying shares' underlying asset may be disrupted or limited, or such underlying asset may be unavailable in the secondary market. Under these circumstances, the liquidity of the underlying shares may be adversely affected, market participants may be unable to calculate accurately the net asset value per share of the underlying shares, and their ability to create and redeem shares of the underlying shares may be disrupted. Under these circumstances, the market price of the underlying shares may vary substantially from the net asset value per share of the underlying shares or the performance of their underlying asset.
For all of the foregoing reasons, the performance of the underlying shares may not correlate with the performance of their underlying asset or the net asset value per share of the underlying shares. Any of these events could materially and adversely affect the price of the underlying shares and, therefore, the value of the securities. Additionally, if market volatility or these events were to occur on the valuation date, the calculation agent would maintain discretion to determine whether such market volatility or events have caused a market disruption event to occur, and such determination would affect the payment at maturity on the securities. If the calculation agent determines that no market disruption event has taken place, the payment at maturity would be based on the published closing price per share of the underlying shares on the valuation date, even if the underlying shares are underperforming their underlying asset and/or trading below the net asset value per share of the underlying shares.
■The antidilution adjustments the calculation agent is required to make do not cover every event that could affect the underlying shares. MS & Co., as calculation agent, will adjust the adjustment factor for certain events affecting the underlying shares. However, the calculation agent will not make an adjustment for every event that could affect the underlying shares. If an event occurs that does not require the calculation agent to adjust the adjustment factor, the market price of the securities may be materially and adversely affected.
October 2026 Page 15
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
iShares® Bitcoin Trust ETF Overview
The iShares® Bitcoin Trust ETF (“the Trust”) is a Delaware statutory trust sponsored by iShares® Delaware Trust Sponsor LLC that seeks to reflect generally the performance of the price of bitcoin, which is its underlying asset, less the Trust’s expenses and liabilities. The assets of the Trust consist primarily of bitcoin held by a custodian on behalf of the Trust. Information provided to or filed with the Securities and Exchange Commission (the “Commission”) pursuant to the Securities Act of 1933 can be located by reference to Commission file number 001- 41914 through the Commission’s website at www.sec.gov. In addition, information may be obtained from other publicly available sources. Neither the issuer nor the agent makes any representation that any such publicly available information regarding the iShares® Bitcoin Trust ETF is accurate or complete.
We have derived all information regarding the Trust, including its composition and method of calculation, from publicly available information, without independent verification. This information reflects the policies of, and is subject to change by, iShares® Delaware Trust Sponsor LLC, a indirect subsidiary of BlackRock, Inc. BlackRock Fund Advisors is the trustee of the Trust; Coinbase Custody Trust Company, LLC is the custodian of the Trust’s bitcoin holdings; Coinbase, Inc., an affiliate of Coinbase Custody Trust Company, LLC, is the prime exchange agent; the Bank of New York Mellon is the custodian for the Trust’s cash holdings and the administrator of the trust; and Wilmington Trust Company, a Delaware trust company, serves as the trustee of the Trust.
The Trust issues (in blocks of 40,000 shares, each of which is referred to as a “basket”) shares representing fractional undivided beneficial interests in its net assets. The assets of the Trust consist primarily of bitcoin held by a custodian on behalf of the Trust. The shares of the Trust are intended to constitute a simple and cost-effective means of making an investment similar to an investment in bitcoin rather than by acquiring, holding and trading bitcoin directly on a peer-to-peer or other basis or via a digital asset platform. The trustee of the Trust sells bitcoin held by the Trust to pay the Trust’s expenses on an as-needed basis irrespective of then-current bitcoin prices.
The Trust is not actively managed and will not take any actions to take advantage, or mitigate the impacts, of volatility in the price of bitcoin. The Trust pays the sponsor’s fee, which accrues daily at an annualized rate equal to 0.25% of the net asset value of the Trust, at least quarterly in arrears. The trustee of the Trust will, when directed by the sponsor of the Trust, and, in the absence of such direction, may in its discretion, sell bitcoin in such quantity and at such times as may be necessary to permit payment of the Trust sponsor’s fee and Trust expenses or liabilities not assumed by the sponsor. As a result of the recurring sales of bitcoin necessary to pay the Trust sponsor’s fee and Trust expenses or liabilities not assumed by the Trust sponsor, the net asset value of the Trust will decrease over the life of the trust. New purchases of bitcoin utilizing cash proceeds from new shares issued by the Trust do not reverse this trend. A decrease in the amount of bitcoin represented by each share is expected to result in a decrease in the price of the shares, even if the price of bitcoin has not changed. To retain the share’s original price, the price of bitcoin would likely have to increase. Without that increase, the lesser amount of bitcoin represented by the share would be expected to cause the shares to have a correspondingly lower price. If these increases do not occur, or are not sufficient to counter the lesser amount of bitcoin represented by each share, the price of the shares will likely decrease.
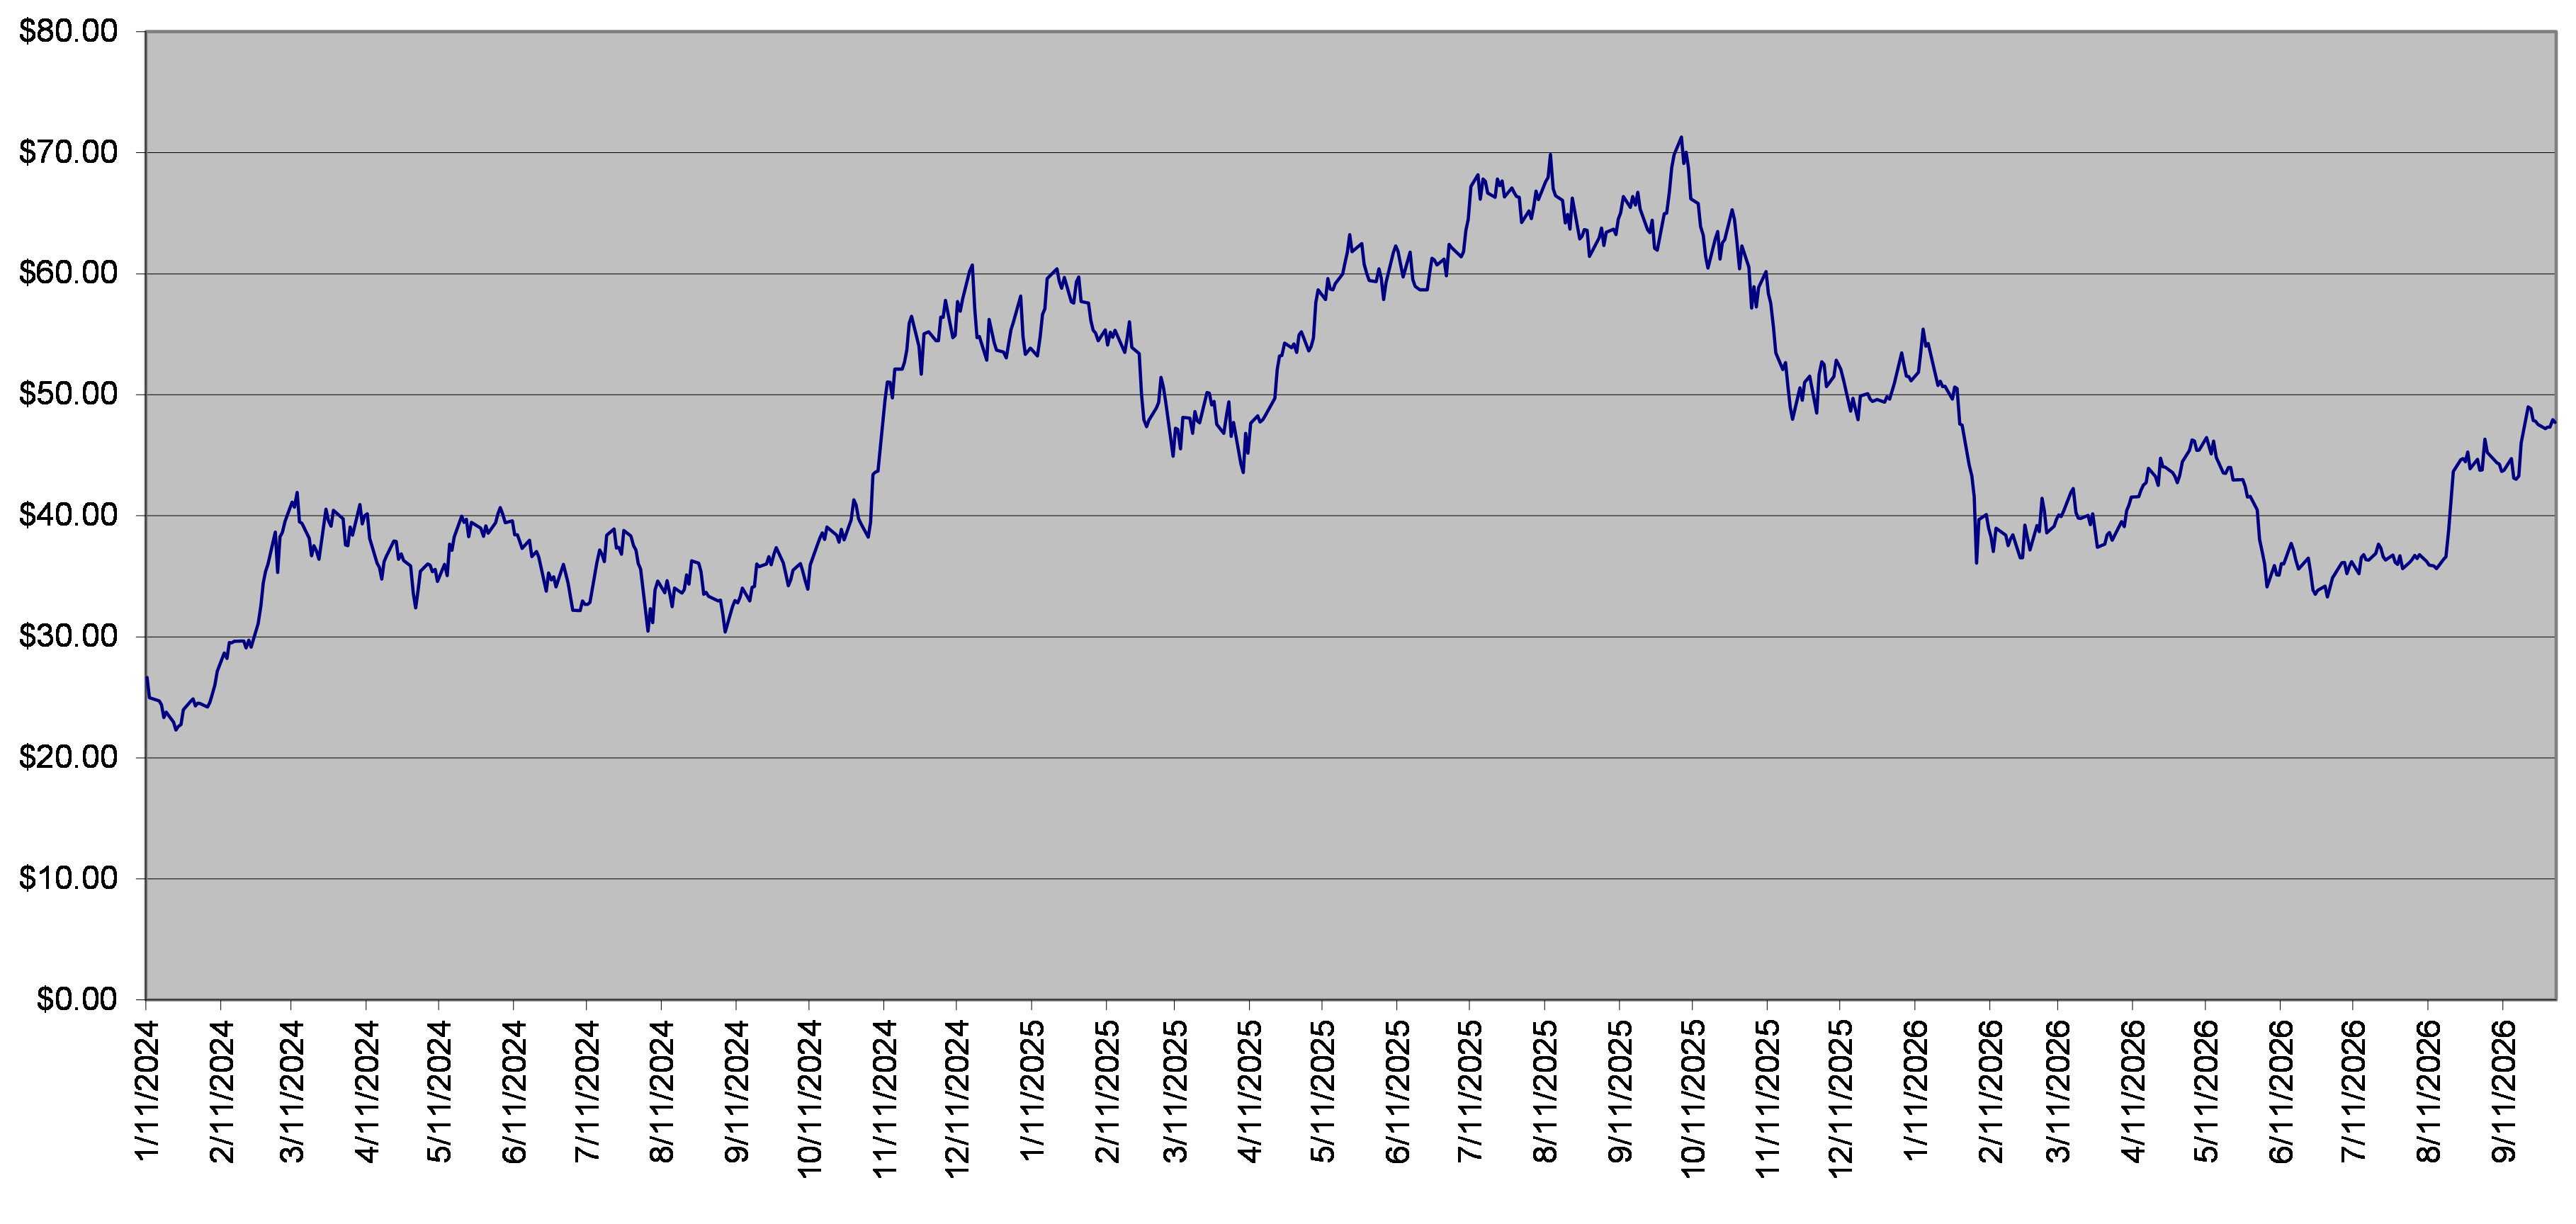
The closing price of the underlying shares on October 2, 2026 was $47.73. The underlying fund began trading on January 11, 2024 and therefore has limited historical performance. The associated graph shows the closing prices of the underlying shares for each day from January 11, 2024 through October 2, 2026. We obtained the information in the graph below from Bloomberg Financial Markets, without independent verification. The historical performance of the underlying shares should not be taken as an indication of future performance, and no assurance can be given as to the price of the underlying shares at any time, including on the redemption determination dates or the observation dates.
October 2026 Page 16
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
|
IBIT Shares – Daily Closing Prices |
|
|
|
*The IBIT Shares began trading on January 11, 2024 and therefore has limited historical performance.
|
This document relates only to the securities offered hereby and does not relate to the IBIT Shares. We have derived all disclosures contained in this document regarding the Trust from the publicly available documents described above. In connection with the offering of the securities, neither we nor the agent has participated in the preparation of such documents or made any due diligence inquiry with respect to the Trust. Neither we nor the agent makes any representation that such publicly available documents or any other publicly available information regarding the Trust is accurate or complete. Furthermore, we cannot give any assurance that all events occurring prior to the date hereof (including events that would affect the accuracy or completeness of the publicly available documents described above) that would affect the trading price of the IBIT Shares (and therefore the price of the IBIT Shares at the time we price the securities) have been publicly disclosed. Subsequent disclosure of any such events or the disclosure of or failure to disclose material future events concerning the Trust could affect the value received with respect to the securities and therefore the value of the securities.
Neither we nor any of our affiliates makes any representation to you as to the performance of the IBIT Shares.
We and/or our affiliates may presently or from time to time engage in business with the Trust. In the course of such business, we and/or our affiliates may acquire non-public information with respect to the Trust, and neither we nor any of our affiliates undertakes to disclose any such information to you. In addition, one or more of our affiliates may publish research reports with respect to the IBIT Shares. The statements in the preceding two sentences are not intended to affect the rights of investors in the securities under the securities laws. As a prospective purchaser of the securities, you should undertake an independent investigation of the Trust as in your judgment is appropriate to make an informed decision with respect to an investment linked to the IBIT Shares.
Bitcoin. Bitcoin is a digital asset, the ownership and behavior of which are determined by participants in an online, peer-to-peer network that connects computers that run publicly accessible, or “open source,” software that follows the rules and procedures governing the Bitcoin Network, commonly referred to as the Bitcoin Protocol. The value of bitcoin, like the value of other digital assets, is not backed by any government, corporation or other identified body. Ownership and the ability to transfer or take other actions with respect to bitcoin are protected through public-key cryptography. The supply of bitcoin is constrained or formulated by its protocol instead of being explicitly delegated to an identified body (e.g., a central bank) to control. Units of bitcoin, called tokens, are treated as fungible. Bitcoin and certain other types of digital assets are often referred to as digital currencies or cryptocurrencies. No single entity owns or operates the Bitcoin Network, the infrastructure of which is collectively maintained by (1) a decentralized group of participants who run computer software that results in the recording and validation of transactions (commonly referred to as “miners”), (2) developers who propose improvements to the Bitcoin Protocol and the software that enforces the protocol and (3) users who choose what bitcoin software to run.
Bitcoin was released in 2009 and, as a result, there is little data on its long-term investment potential. Bitcoin is not backed by a government-issued legal tender or any other currency or asset. Bitcoin is “stored” or reflected on a digital transaction ledger commonly known as a “blockchain.” A blockchain is a type of shared and continually reconciled database, stored in a decentralized manner on the computers of certain users of the digital asset. Bitcoin is created by “mining.” Mining involves miners using a sophisticated computer program to repeatedly solve very complex mathematical problems on specialized computer hardware. Miners can range from bitcoin enthusiasts to professional mining operations that design and build dedicated machines and data centers.
October 2026 Page 17
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
Additional Terms of the Securities
Please read this information in conjunction with the summary terms on the front cover of this document.
|
Additional Terms: |
|
|
If the terms described herein are inconsistent with those described in the accompanying product supplement, tax supplement or prospectus, the terms described herein shall control. |
|
|
Interest period: |
The period from and including the original issue date (in the case of the first interest period) or the previous scheduled coupon payment date, as applicable, to but excluding the following scheduled coupon payment date, with no adjustment for any postponement thereof. |
|
Record date: |
The record date for each coupon payment date shall be the date one business day prior to such scheduled coupon payment date; provided, however, that any coupon payable at maturity (or upon early redemption) shall be payable to the person to whom the payment at maturity or early redemption payment, as the case may be, shall be payable. |
|
Share underlying asset: |
Bitcoin (“underlying asset”) |
|
Postponement of coupon payment dates and early redemption dates: |
If any observation date or redemption determination date is postponed due to a non-trading day or certain market disruption events with respect to the underlying shares so that it falls less than two business days prior to the relevant scheduled coupon payment date or early redemption date, as applicable, the coupon payment date or the early redemption date will be postponed to the second business day following that observation date or redemption determination date as postponed, and no adjustment will be made to any coupon payment or early redemption payment made on that postponed date. |
|
Acceleration upon a discontinuance or liquidation event: |
Notwithstanding anything to the contrary in this pricing supplement, the accompanying product supplement, tax supplement and prospectus, if trading in the underlying shares on the relevant exchange is permanently discontinued or the underlying shares are liquidated or otherwise terminated a “discontinuance or liquidation event”) and the calculation agent determines, in its sole discretion, that no exchange-traded fund that is comparable to the underlying shares (a “successor fund”) is available, we will have the right, but not the obligation, to accelerate the payment on the securities. If we choose to exercise this right, (a) we will provide, or cause the calculation agent to provide, written notice of our election to exercise this right, (b) the amount due and payable per security upon early acceleration will be determined by the calculation agent in good faith and in a commercially reasonable manner on the date on which we (or the calculation agent) deliver notice of acceleration and (c) that amount will be payable on the fifth business day following the date on which we (or the calculation agent) deliver notice of acceleration, and the maturity date will be accelerated to that fifth business day. In determining the amount due and payable upon the occurrence of a discontinuance or liquidation event, the calculation agent will consider the last price published by the relevant exchange before such discontinuance or liquidation event. If we accelerate the payment on your securities at our (or the calculation agent’s) option, your investment may result in a loss and you may not be able to reinvest your money at a comparable return for a similar level of risk. |
|
Postponement of maturity date: |
If due to a market disruption event or otherwise, the final observation date is postponed so that it falls less than two business days prior to the scheduled maturity date, the maturity date of the securities will be postponed to the second business day following the final observation date as postponed. |
|
Trustee: |
The Bank of New York Mellon |
|
Calculation agent: |
MS & Co. |
|
Issuer notices to registered security holders, the trustee and the depositary: |
In the event that the maturity date is postponed due to postponement of the final observation date, the issuer shall give notice of such postponement and, once it has been determined, of the date to which the maturity date has been rescheduled (i) to each registered holder of the securities by mailing notice of such postponement by first class mail, postage prepaid, to such registered holder’s last address as it shall appear upon the registry books, (ii) to the trustee by facsimile, confirmed by mailing such notice to the trustee by first class mail, postage prepaid, at its New York office and (iii) to The Depository Trust Company (the “depositary”) by telephone or facsimile confirmed by mailing such notice to the depositary by first class mail, postage prepaid. Any notice that is mailed to a registered holder of the securities in the manner herein provided shall be conclusively presumed to have been duly given to such registered holder, whether or not such registered holder receives the notice. The issuer shall give such notice as promptly as possible, and in no case later than (i) with respect to notice of postponement of the maturity date, the business day immediately preceding the scheduled maturity date and (ii) with respect to notice of the date to which the maturity date has been rescheduled, the business day immediately following the final observation date as postponed.
In the event that the securities are subject to early redemption, the issuer shall, (i) on the business day following the applicable redemption determination date, give notice of the early |
October 2026 Page 18
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
|
redemption and the early redemption payment, including specifying the payment date of the amount due upon the early redemption, (x) to each registered holder of the securities by mailing notice of such early redemption by first class mail, postage prepaid, to such registered holder’s last address as it shall appear upon the registry books, (y) to the trustee by facsimile confirmed by mailing such notice to the trustee by first class mail, postage prepaid, at its New York office and (z) to the depositary by telephone or facsimile confirmed by mailing such notice to the depositary by first class mail, postage prepaid, and (ii) on or prior to the early redemption date, deliver the aggregate cash amount due with respect to the securities to the trustee for delivery to the depositary, as holder of the securities. Any notice that is mailed to a registered holder of the securities in the manner herein provided shall be conclusively presumed to have been duly given to such registered holder, whether or not such registered holder receives the notice. This notice shall be given by the issuer or, at the issuer’s request, by the trustee in the name and at the expense of the issuer, with any such request to be accompanied by a copy of the notice to be given.
The issuer shall, or shall cause the calculation agent to, (i) provide written notice to the trustee, on which notice the trustee may conclusively rely, and to the depositary of the amount of cash to be delivered as contingent monthly coupon, if any, with respect to each security on or prior to 10:30 a.m. (New York City time) on the business day preceding each coupon payment date, and (ii) deliver the aggregate cash amount due, if any, with respect to the contingent monthly coupon to the trustee for delivery to the depositary, as holder of the securities, on the applicable coupon payment date. The issuer shall, or shall cause the calculation agent to, (i) provide written notice to the trustee, on which notice the trustee may conclusively rely, and to the depositary of the amount of cash, if any to be delivered with respect to each stated principal amount of the securities, on or prior to 10:30 a.m. (New York City time) on the business day preceding the maturity date, and (ii) deliver the aggregate cash amount due with respect to the securities to the trustee for delivery to the depositary, as holder of the securities, on the maturity date. |
October 2026 Page 19
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
Additional Information About the Securities
|
Additional Information: |
|
|
Minimum ticketing size: |
$1,000 / 1 security |
|
Tax considerations: |
You should review carefully the section in the accompanying tax supplement entitled “United States Federal Taxation.” The following discussion, when read in combination with that section, constitutes the full opinion of our counsel, Davis Polk & Wardwell LLP, regarding the material U.S. federal income tax consequences of owning and disposing of the securities offered by this pricing supplement. Generally, this discussion assumes that you purchased a security for cash in the original issuance at the stated issue price and does not address other circumstances specific to you, including consequences that may arise due to any other investments relating to an underlier. Moreover, as discussed in the section entitled “United States Federal Taxation” in the accompanying tax supplement, we have not attempted to ascertain whether any issuer of any underlier to which the securities relate is a U.S. real property holding corporation or a passive foreign investment company. You should consult your tax adviser regarding these issues, including the effect any circumstances specific to you may have on the U.S. federal income tax consequences of your ownership of a security. In the opinion of our counsel, which is based on current market conditions, it is reasonable to treat the securities for U.S. federal income tax purposes as prepaid financial contracts with associated coupons, and any coupons as ordinary income, as described in the section entitled “United States Federal Taxation—Tax Consequences to U.S. Holders—Program Securities Treated as Prepaid Financial Contracts with Associated Coupons” in the accompanying tax supplement. There is uncertainty regarding this treatment, and the Internal Revenue Service (the “IRS”) or a court might not agree with it. Moreover, because this treatment of the securities and our counsel’s opinion are based on market conditions as of the date of this preliminary pricing supplement, each is subject to confirmation on the pricing date. A different tax treatment could be adverse to you. We do not plan to request a ruling from the IRS regarding the treatment of the securities. An alternative characterization of the securities could materially and adversely affect the tax consequences of ownership and disposition of the securities, including the timing and character of income recognized. In particular, due to the terms of the securities and current market conditions, there is a risk that the securities could be characterized as debt instruments for U.S. federal income tax purposes, in which case the timing and character of income recognized in respect of the securities could be different from those described herein and possibly adverse to certain investors. In addition, the U.S. Treasury Department and the IRS have requested comments on various issues regarding the U.S. federal income tax treatment of “prepaid forward contracts” and similar financial instruments and have indicated that such transactions may be the subject of future regulations or other guidance. Furthermore, members of Congress have proposed legislative changes to the tax treatment of derivative contracts. Any legislation, Treasury regulations or other guidance promulgated after consideration of these issues could materially and adversely affect the tax consequences of an investment in the securities, possibly with retroactive effect. Non-U.S. Holders. If you are a Non-U.S. Holder (as defined in the accompanying tax supplement), please also read the section entitled “United States Federal Taxation—Tax Consequences to Non-U.S. Holders—Program Securities Not Treated as Debt Instruments” in the accompanying tax supplement. The U.S. federal income tax treatment of the coupons is unclear. To the extent that we have withholding responsibility in respect of the securities, we would expect generally to treat the coupons paid to Non-U.S. Holders as subject to U.S. withholding tax. Moreover, you should expect that, if the applicable withholding agent determines that withholding tax should apply, it will be at a rate of 30% (or lower treaty rate). In order to claim an exemption from, or a reduction in, the 30% withholding under an applicable treaty, you may need to comply with certification requirements to establish that you are not a U.S. person and are eligible for such an exemption or reduction under an applicable tax treaty. You should consult your tax adviser regarding the tax treatment of the coupons. As discussed under “United States Federal Taxation—Tax Consequences to Non-U.S. Holders—Dividend Equivalents under Section 871(m) of the Code” in the accompanying tax supplement, Section 871(m) of the Internal Revenue Code and Treasury regulations promulgated thereunder (“Section 871(m)”) generally impose a 30% withholding tax on dividend |
October 2026 Page 20
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
|
equivalents paid or deemed paid to Non-U.S. Holders with respect to certain financial instruments linked to U.S. equities or indices that include U.S. equities. The Treasury regulations, as modified by an IRS notice, exempt financial instruments issued prior to January 1, 2029 that do not have a “delta” of one. Based on certain determinations made by us, we expect that Section 871(m) will not apply to the securities with regard to Non-U.S. Holders. Our determination is not binding on the IRS, and the IRS may disagree with this determination. If necessary, further information regarding the potential application of Section 871(m) will be provided in the final pricing supplement for the securities. We will not be required to pay any additional amounts with respect to U.S. federal withholding taxes. You should consult your tax adviser regarding the U.S. federal income tax consequences of an investment in the securities, including possible alternative treatments, as well as tax consequences arising under the laws of any state, local or non-U.S. taxing jurisdiction. |
|
|
Use of proceeds and hedging: |
The proceeds from the sale of the securities will be used by us for general corporate purposes. We will receive, in aggregate, $1,000 per security issued, because, when we enter into hedging transactions in order to meet our obligations under the securities, our hedging counterparty will reimburse the cost of the agent’s commissions. The costs of the securities borne by you and described beginning on page 5 above comprise the agent’s commissions and the cost of issuing, structuring and hedging the securities. On or prior to October 2, 2026, we will hedge our anticipated exposure in connection with the securities by entering into hedging transactions with our affiliates and/or third-party dealers. We expect our hedging counterparties to take positions in the underlying shares or the underlying asset, in futures and/or options contracts on the underlying shares or in the underlying asset, or positions in any other available securities or instruments that they may wish to use in connection with such hedging. Such purchase activity could potentially increase the initial share price of the underlying shares and, therefore, could increase (i) the value at or above which the underlying shares must close on the redemption determination dates so that the securities are redeemed prior to maturity for the early redemption payment, (ii) the coupon barrier level, which is the value at or above which the underlying shares must close on the observation dates so that you receive a contingent monthly coupon on the securities, and (iii) the value at or above which the underlying shares must close on the final observation date so that you are not exposed to the negative performance of the underlying shares at maturity. These entities may be unwinding or adjusting hedge positions during the term of the securities, and the hedging strategy may involve greater and more frequent dynamic adjustments to the hedge as the final observation date approaches. Additionally, our hedging activities, as well as our other trading activities, during the term of the securities could potentially affect the value of the underlying shares on the redemption determination dates and other observation dates and, accordingly, whether we redeem the securities prior to maturity, whether we pay a contingent monthly coupon on the securities and the amount of cash you will receive at maturity, if any. For further information on our use of proceeds and hedging, see “Use of Proceeds and Hedging” in the accompanying product supplement. |
|
Additional considerations: |
Client accounts over which Morgan Stanley, Morgan Stanley Wealth Management or any of their respective subsidiaries have investment discretion are not permitted to purchase the securities, either directly or indirectly. |
|
Supplemental information regarding plan of distribution; conflicts of interest: |
The agent may distribute the securities through Morgan Stanley Smith Barney LLC (“Morgan Stanley Wealth Management”), as selected dealer, or other dealers, which may include Morgan Stanley & Co. International plc (“MSIP”) and Bank Morgan Stanley AG. Morgan Stanley Wealth Management, MSIP and Bank Morgan Stanley AG are affiliates of ours. Selected dealers, including Morgan Stanley Wealth Management, and their financial advisors will collectively receive from the agent, Morgan Stanley & Co. LLC, a fixed sales commission of $5 for each security they sell. In addition, Morgan Stanley Wealth Management will receive a structuring fee of $5 for each security. The costs included in the original issue price of the securities will include a fee paid by MS & Co. to LFT Securities, LLC, an entity in which an affiliate of Morgan Stanley Wealth Management has an ownership interest, for providing certain electronic platform services with respect to this offering. MS & Co. is an affiliate of MSFL and a wholly owned subsidiary of Morgan Stanley, and it and other affiliates of ours expect to make a profit by selling, structuring and, when applicable, hedging the securities. When MS & Co. prices this offering of securities, it will determine the economic terms of the securities such that for each security the estimated value on the pricing date will be no lower than the minimum level described in “Investment Summary” beginning on page 3. MS & Co. will conduct this offering in compliance with the requirements of FINRA Rule 5121 of the Financial Industry Regulatory Authority, Inc., which is commonly referred to as FINRA, |
October 2026 Page 21
Morgan Stanley Finance LLC
Contingent Income Buffered Auto-Callable Securities with Memory Coupon due October 8, 2027
All Payments on the Securities Based on the Performance of the iShares® Bitcoin Trust ETF
Principal at Risk Securities
|
regarding a FINRA member firm’s distribution of the securities of an affiliate and related conflicts of interest. MS & Co. or any of our other affiliates may not make sales in this offering to any discretionary account. See “Plan of Distribution (Conflicts of Interest)” and “Use of Proceeds and Hedging” in the accompanying product supplement for auto-callable securities. |
|
|
Where you can find more information: |
Morgan Stanley and MSFL have filed a registration statement (including a prospectus, as supplemented by the product supplement for auto-callable securities and the tax supplement) with the Securities and Exchange Commission, or SEC, for the offering to which this communication relates. You should read the prospectus in that registration statement, the product supplement for auto-callable securities, the tax supplement and any other documents relating to this offering that MSFL and Morgan Stanley have filed with the SEC for more complete information about Morgan Stanley and this offering. You may get these documents without cost by visiting EDGAR on the SEC web site at.www.sec.gov. Alternatively, MSFL, Morgan Stanley, any underwriter or any dealer participating in the offering will arrange to send you the product supplement for auto-callable securities, tax supplement and prospectus if you so request by calling toll-free 1-(800)-584-6837. You may access these documents on the SEC web site at.www.sec.gov as follows: Product Supplement for Auto-Callable Securities dated April 8, 2026 Tax Supplement dated April 8, 2026 Prospectus dated April 8, 2026 Terms used but not defined in this document are defined in the product supplement for auto-callable securities, in the tax supplement or in the prospectus. |
October 2026 Page 22

FREE Breaking News Alerts from StreetInsider.com!
StreetInsider.com Top Tickers, 10/5/2026
- Nasdaq hits record high as investors focus on earnings
- Oil slips on rising Mideast crude exports, G7 stocks release
- Intel stock slides as TSMC explores Terafab tie-up, analyst flags share losses
- Schneider Electric to acquire PTC for $22.6 billion in all-cash deal
- Five things to watch in markets in the week ahead
Serious News for Serious Traders! Try StreetInsider.com Premium Free!
You May Also Be Interested In
- RXO shares soar as C.H. Robinson announces $5.8B cash and stock buyout
- C.H. Robinson to acquire RXO in $5.8 billion deal
- Shionogi to acquire IntraBio for $2 billion in rare disease push
Create E-mail Alert Related Categories
SEC FilingsRelated Entities
Morgan StanleySign up for StreetInsider Free!
Receive full access to all new and archived articles, unlimited portfolio tracking, e-mail alerts, custom newswires and RSS feeds - and more!
