


Form DEFA14A Empery Digital Inc.
 Tweet
 Share
 E-mail
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, DC 20549
SCHEDULE 14A
Proxy Statement Pursuant to Section 14(a) of the
Securities Exchange Act of 1934
(Amendment No. )
| Filed by the Registrant ☒ |
| Filed by a Party other than the Registrant ☐ |
| Check the appropriate box: |
| ☐ Preliminary Proxy Statement |
| ☐ Confidential, For Use of the Commission Only (as permitted by Rule 14a-6(e)(2)) |
| ☐ Definitive Proxy Statement |
| ☒ Definitive Additional Materials |
| ☐ Soliciting Material Pursuant to §240.14a-12 |
|
Empery Digital Inc. (Name of Registrant as Specified in its Charter)
(Name of Person(s) Filing Proxy Statement, if other than the Registrant)
|
| Payment of Filing Fee (Check the appropriate box): |
| ☒ No fee required. |
| ☐ Fee paid previously with preliminary materials. |
| ☐ Fee computed on table in exhibit required by Item 25(b) per Exchange Act Rules 14a-6(i)(1) and 0-11 |

SEPTEMBER 2026

2 Forward - Looking Statements This investor presentation includes forward - looking statements. These forward - looking statements generally can be identified by the use of words such as “anticipate,” “believe,” “could,” “expect,” “focus,” “leverage,” “may,” “pathway,” “plan,” “proposes,” “seek,” “starting,” “strategy,” “will” and other words of similar meaning. These forward - looking statements address various matters, which include, without limitation, statements regarding our strategy, future operations, future financial position, including, but not limited to, statements relating to: the Company’s expectatio ns regarding financial metrics and trends for the remainder of fiscal year 2026, the Company’s digital asset - treasury strategy, the Company’s ability to efficiently manage its BTC portfolio, the Company’s ability to increase Bitcoin p er share to drive stockholder value, the Company’s ability to generate income through derivatives on BTC through the use of short - term put and call contracts, repurchases under the Company’s share repurchase program and financing arrangement s related thereto; the Company’s strategic partnership with Cardinal Power LLC (“Cardinal”), the ability of the Company and Cardinal to execute on its shared vision for AI infrastructure and to identify, fund and execute o n f uture opportunities, and the timing and realization of the expected benefits therefrom; closing under the definitive agreement by EMHU, LLC, a Delaware limited liability company (“EMHU” or the “Partnership”) to purchase 100% of the eq uity interests of the current holder of a fee simple title to a property in the Midwest and the timing thereof; the proposed conversion of the Midwest property into an AI data center and the potential to increase its power capac ity and timing thereof; EMHU or its affiliate executing a definitive lease agreement with respect to the Midwest property and the terms and timing thereof, including the expected total net lease payments that may be realized in connection th erewith; the Company’s plans for future data center - related opportunities; the Company’s plans for future capital allocation; Cardinal Data Power Inc.’s (“CDP”) proposed data center campus in West Texas and the letter of intent ass oci ated therewith; the expected outcome or impact of pending or threatened litigation and the anticipated insurance recoveries associated therewith; the status of and ability to resolve the matter with ATG and the continued defense an d against litigation brought by ATG and the ability of the Company to generate positive net interest income from financing of inventory purchases. Each forward - looking statement is subject to risks and uncertainties that could cause actual results to differ materially from t hose expressed or implied in such statements. Applicable risks and uncertainties include the risks and uncertainties regarding, among other things: our ability to keep pace with new technology and changing market needs; changes in business, market, financial, political and regulatory conditions; reduced demand for data centers or decreases in information technology spending; increased competition or available supply of data center capacity; delays or di sru ptions in connectivity or availability of power; deterioration in the relationship between the Company and Cardinal or CDP, or between EMHU or CDP and their potential data center tenants; the Company’s operations and business, inclu din g the highly volatile nature of the price of Bitcoin and other cryptocurrencies; the Company’s stock price may be highly correlated to the price of the digital assets that it holds; increased competition in the industries in w hic h the Company operates; significant legal, commercial, regulatory and technical uncertainty regarding digital assets generally; the treatment of crypto assets for U.S. and foreign tax purpose; the Company’s ability to generate revenues fr om sales and generate cash from financing of inventory, sale of its products and Bitcoin derivatives; significant decrease in the market value of the Company’s Bitcoin holdings; the Company’s ability to obtain additional financ ing through equity or debt offerings, obtain borrowings from financing arrangements or generate cash from the sale of Bitcoin and the competitive environment of our business. Other risks and uncertainties include those identified under th e heading “Risk Factors” contained in our Annual Report on Form 10 - K for the year ended December 31, 2025, (as amended by Form 10 - K/A filed with the SEC on April 21, 2026), and in our Quarterly Report on Form 10 - Q for the three m onths ended June 30, 2026, and any subsequent filings with the SEC. As a result of these and other factors, we may not achieve the plans, intentions or expectations disclosed in our forward - lookin g statements, and you should not place undue reliance on our forward - looking statements. The forward - looking statements reflect our views as of the date hereof. We do not assume and specifically disclaim any obligation to upda te any forward - looking statements, whether as a result of new information, future events or otherwise, except as required by law. Our business is subject to substantial risks and uncertainties, including those referenced above. Investo rs, potential investors, and others should give careful consideration to these risks and uncertainties. Important Additional Information The Company has filed a definitive proxy statement on Schedule 14A and an accompanying white proxy card. THE COMPANY’S STOCKH OLD ERS ARE STRONGLY ENCOURAGED TO READ THE COMPANY’S PROXY STATEMENT (INCLUDING ANY AMENDMENTS OR SUPPLEMENTS THERETO), THE ACCOMPANYING WHITE PROXY CARD AND ANY OTHER DOCUMENTS FILED WITH THE S EC IN CONNECTION WITH THE 2026 ANNUAL MEETING CAREFULLY AND IN THEIR ENTIRETY AS THEY CONTAIN IMPORTANT INFORMATION ABOUT THE 2026 ANNUAL MEETING. Stockholders will be able to obtain a fre e c opy of the Company’s definitive proxy statement, accompanying white proxy card, any amendments or supplements to the proxy statement and other documents that the Company files with the SEC at no charge from th e S EC’s website at www.sec.gov. Copies will also be available at no charge on the Company’s website at https://ir.emperydigital.com/sec - filings. The Company, its directors and certain of its officers and employees are participants in the solicitation of proxies from sha reh olders in connection with the 2026 Annual Meeting. Information regarding the identity of the participants and their direct or indirect interests, by security holdings or otherwise, is set forth in the Company’s definitive proxy stateme nt.

3 Sources: Company press releases; Company Proxy; Trial Transcript; Post - Trial Memorandum Opinion, Aug. 28, 2026; Supplemental Let ter Opinion, Sept. 2, 2026; ATG Press release; ATG Proxy. A new team has been rebuilding for 15 months In July 2025, Empery Asset Management led a $500 million PIPE into Volcon, a company whose stock price languished in the years following its 2021 IPO. Four new directors joined the Board and new executives joined management. Within a month the Company held over 4,000 BTC and was operating a low - cost, transparent bitcoin treasury with a mission to grow bitcoin per share. When the DAT sector broke and the discount to NAV persisted, EMPD repurchased 26.2 million shares below NAV. When the gap still would not close, the Board and management evaluated a range of options, including continued buybacks and a liquidation, before making a well thought - out decision to allocate capital to AI data center investments alongside the Hunt family. Cash flow is expected to begin in early 2027. ATG concealed a liquidation play with Woodmont, then reversed itself ATG launched a new vehicle just weeks after identifying Empery Digital as a “discount” trade that it could hedge by shorting bitcoin. Its confidential offering materials touted to investors ATG’s “willingness to use litigation and pursue liquidations.” After forming, ATG invested nearly all of its assets to purchase a 12% stake in Empery Digital in less than a month while shorting bitcoin ETFs against 100% of it. Woodmont's Tice Brown, a 9.7% holder, publicly demanded a full liquidation. He and Gliksberg spoke eight to ten times in three days while dramatically increasing their positions, then moved to auto - deleting apps. Both denied working together. ATG destroyed every message with Brown and most with its nominees. The Court found ATG "furtive in its coordination with Tice Brown." Now ATG says it merely wants "oversight." Sanctioned and retreating, ATG still targets the CEO and wants its fees paid The Court sanctioned ATG for destroying evidence and ordered it to pay the Company's fees from its spoliation. Two days later ATG cut its slate from nine to four. It still targets the Chairman and Co - CEO, the independent Nominating Committee chair, the Board's digital asset operator and an independent director. ATG has articulated no plan and no relevant experience for its nominees. Its proxy lists steps they "could" consider. Every step is already done or underway. ATG's stated priority is reimbursement of an estimated $9.15 million in expenses, including its litigation fees, if it wins. We are asking for your support of EMPERY DIGITAL'S NINE NOMINEES on the WHITE proxy card so the Board can continue the work it started.

4 The Board is qualified and the team is executing our strategy • We are executing a strategic plan that we believe will set Empery Digital up for a future of sustained success. Our director candidates are the right team for shareholders to keep in place, as Empery Digital's team has only been on the job for a litt le over one year. We are excited about what the future holds for the Company and our shareholders through continued execution of the plan . • Nine nominees combine a complementary set of skills that align with our long - term strategy: capital markets, digital asset, energy and public company governance experience. Directors include the former CEO of Pfizer, two Gemini alumni and the general counsel of Cardinal Data Power (a Hunt Entity focused on AI data centers). We are pursuing the most compelling value creation opportunity of our time • The Board and management evaluated a range of options including continued buybacks below NAV, a liquidation, and numerous strategic opportunities reviewed and negotiated under NDA. • After months of conducting diligence and deliberating a range of potential transactions , the Board and management concluded that the AI data center investment offered the most potential for stockholders. It chose to partner with Hunt to allocate capital to AI data center investments. • The strategy expands a discounted bitcoin balance sheet into AI data center investments. Assets that generate near - term cash flow with limited to no incremental capital requirements, and a mandate shareholders were told about from the start: raise above N AV, buy back below it, and deploy the balance sheet where it creates the most value. The Board and management are aligned with shareholders • Directors and officers own 21.2% of the Company. The Chairman beneficially owns 17.5% and bought 1.9 million more shares in the open market in August and September 2026. • Cash compensation is very low and options pay when the shares perform. $225,000 co - CEO salaries, no annual bonus, no management fee, and options struck at $10, more than three times the current share price. Directors are paid $40,000 a year. • We recognize the underperformance. Board and management do not believe the current share price adequately values EMPD and are focused each day on making decisions that create value. Sources: Company Proxy; Company press releases; Trial Transcript.
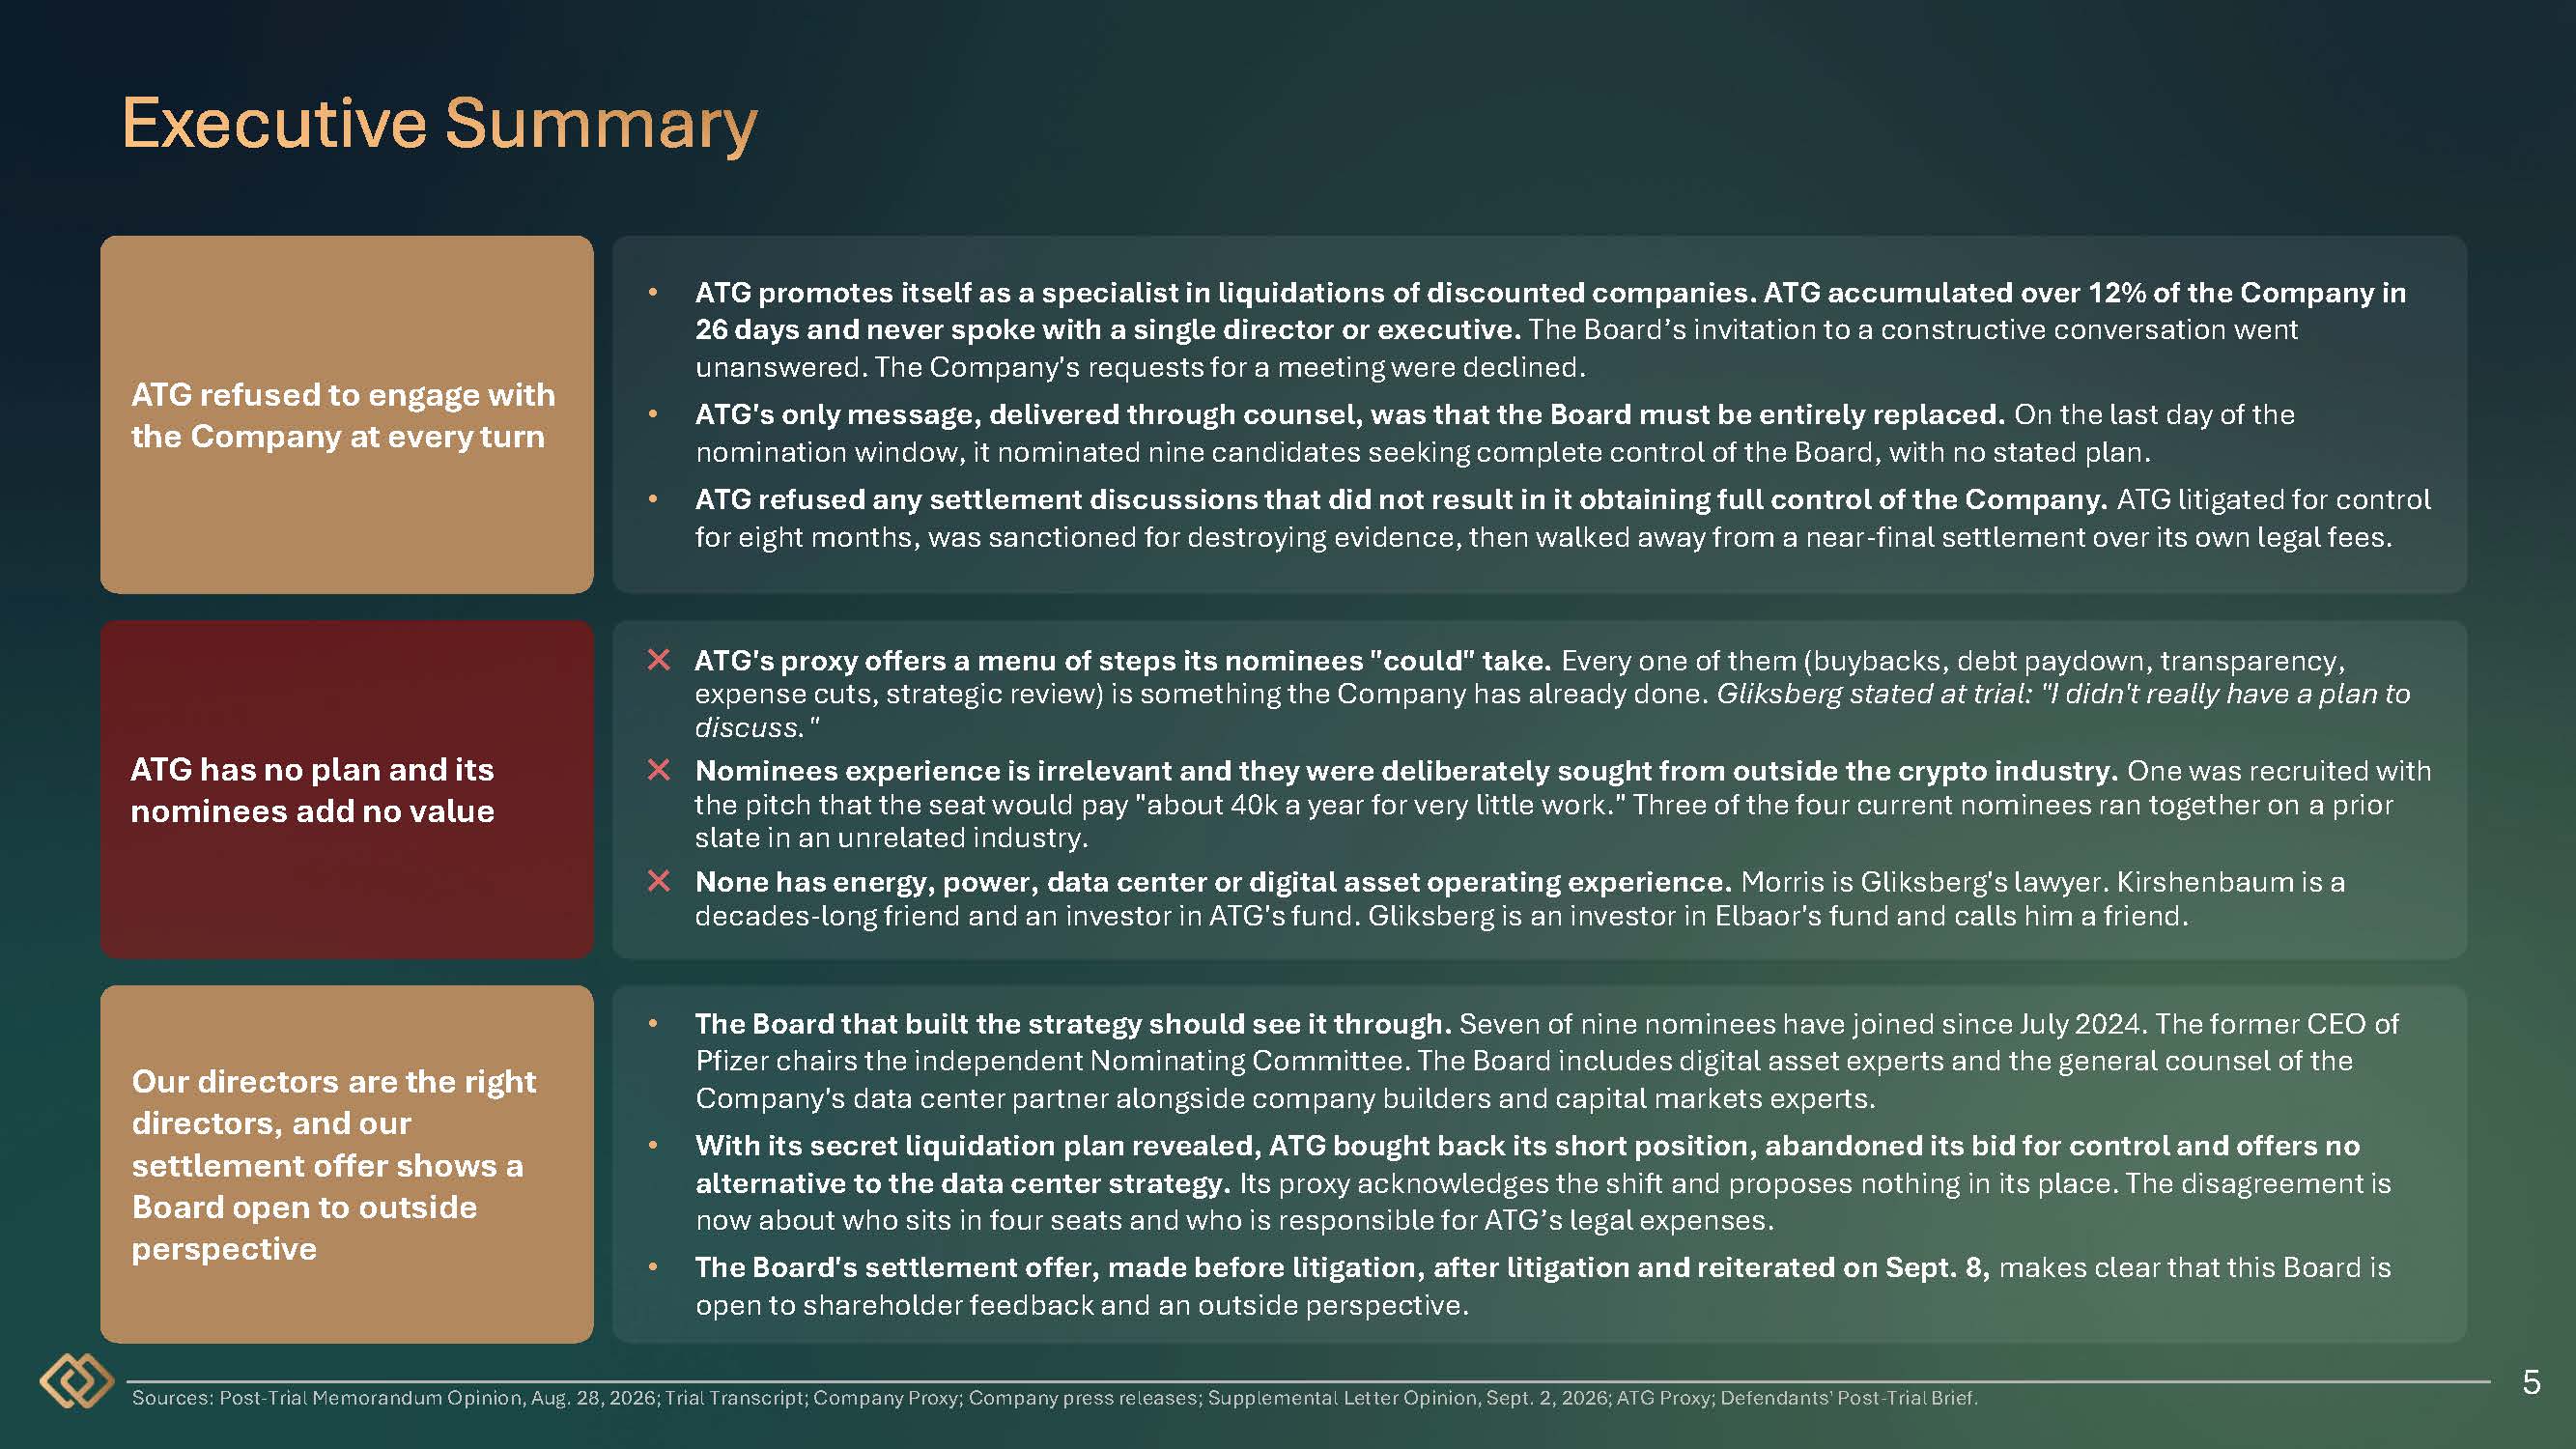
5 ATG refused to engage with the Company at every turn • ATG promotes itself as a specialist in liquidations of discounted companies. ATG accumulated over 12% of the Company in 26 days and never spoke with a single director or executive. The Board’s invitation to a constructive conversation went unanswered. The Company's requests for a meeting were declined. • ATG's only message, delivered through counsel, was that the Board must be entirely replaced. On the last day of the nomination window, it nominated nine candidates seeking complete control of the Board, with no stated plan. • ATG refused any settlement discussions that did not result in it obtaining full control of the Company. ATG litigated for control for eight months, was sanctioned for destroying evidence, then walked away from a near - final settlement over its own legal fees. ATG has no plan and its nominees add no value ✖ ATG's proxy offers a menu of steps its nominees "could" take. Every one of them (buybacks, debt paydown, transparency, expense cuts, strategic review) is something the Company has already done. Gliksberg stated at trial: "I didn't really have a plan to discuss." ✖ Nominees experience is irrelevant and they were deliberately sought from outside the crypto industry. One was recruited with the pitch that the seat would pay "about 40k a year for very little work." Three of the four current nominees ran together on a prior slate in an unrelated industry. ✖ None has energy, power, data center or digital asset operating experience. Morris is Gliksberg's lawyer. Kirshenbaum is a decades - long friend and an investor in ATG's fund. Gliksberg is an investor in Elbaor's fund and calls him a friend. Our directors are the right directors, and our settlement offer shows a Board open to outside perspective • The Board that built the strategy should see it through. Seven of nine nominees have joined since July 2024. The former CEO of Pfizer chairs the independent Nominating Committee. The Board includes digital asset experts and the general counsel of the Company's data center partner alongside company builders and capital markets experts. • With its secret liquidation plan revealed, ATG bought back its short position, abandoned its bid for control and offers no alternative to the data center strategy. Its proxy acknowledges the shift and proposes nothing in its place. The disagreement is now about who sits in four seats and who is responsible for ATG’s legal expenses. • The Board's settlement offer, made before litigation, after litigation and reiterated on Sept. 8, makes clear that this Board is open to shareholder feedback and an outside perspective. Sources: Post - Trial Memorandum Opinion, Aug. 28, 2026; Trial Transcript; Company Proxy; Company press releases; Supplemental Let ter Opinion, Sept. 2, 2026; ATG Proxy; Defendants' Post - Trial Brief.

6 Note: Shares Outstanding includes common shares and pre - funded warrants. All numbers in millions other than per share metrics. U naudited figures as of September 15, 2026. BTC price of $75,874. Source: Sources: Forms 10 - K / 10 - Q; Company internal data; Company press releases; Bloomberg. Business Overview A bitcoin treasury company expanding into AI infrastructure alongside operators with decades of energy development experience. The legacy vehicle business never generated cash; the data center investments are expected to from early 2027. Capitalization Net Asset Value Per Share Aggregate ($M) 1,143.7 Bitcoin Count $2.91 $86.8 BTC NAV $2.22 $66.1 Cash $0.67 $20.0 CDP Investment (Cost) $0.10 $2.9 Midwest Data Center Investment (Cost) ($1.17) ($35.0) Debt $4.72 $140.7 Net Asset Value AI Data Center Investments • Midwest AI Data Center Facility • Upon closing, $65 million investment for a 25% interest • Currently negotiating definitive lease based on non - binding LOI in place Cardinal Data Power • $20 million preferred equity investment for ~8% ownership • Backed by value of deposit on reciprocating generator sets 1 2 29.8 Shares Outstanding $2.88 Share Price $85.9 Market Capitalization $66.1 Cash $86.8 BTC Value $35.0 Debt 0.4 4.5 3.3 4.0 1.0 0.3 24.2 33.6 29.6 16.0 17.8 10.4 2021 2022 2023 2024 2025 H1 26 Revenue ($M) Cash used in operations ($M)

7 OCT. 2021 Volcon IPOs on Nasdaq at $5.50 per share 1 , raising about $17 million to build electric off - road vehicles. 2021 TO 2025 Volcon's stock price languished in the years following its IPO. Five reverse splits totaled 1 - for - 1,440,000. Cumulative net losses of $165 million on $12 million of revenue from 2021 through 2024. MAY 2025 Nasdaq notifies Volcon that its bid price has been below $1.00 for 30 days; delisting risk. JULY 17, 2025 New team, new strategy. Empery Asset Management leads a $500 million - plus PIPE at $10 per share. Ryan Lane, Ian Read, Rohan Chauhan and Matthew Homer join the Board. JULY 21 TO 31, 2025 PIPE closes. Volcon becomes Empery Digital; $1 billion ATM capacity and a share repurchase plan put in place to sell above NAV and repurchase below it. AUG. 11, 2025 4,018 BTC acquired at an average $117,552, with no debt. Treasury dashboard launched. $500M+ raised in the July 2025 PIPE 4,018 BTC acquired in 25 days $225K Co - CEO salary, no annual bonus, no annual option grants $40K annual director fee Built to be aligned with shareholders • Low management salaries. Co - CEO salaries of $225,000 with no annual bonus, and no management fee like other DATs. • Significant skin in the game. Many directors and executives bought PIPE shares at $10 alongside investors. • Options struck at $10, more than three times the current share price. They are worth nothing unless shareholders more than triple their money first. • Real - time, third - party verified treasury dashboard from launch; disciplined derivatives trading program generated $2.0 million of realized proceeds by February 2026. • A board built for credibility: Pfizer's former CEO, a Gemini strategy executive, a Gemini Trust director and former NYDFS regulator. 1. IPO price as issued. Adjusted for the five reverse splits since the IPO (1 - for - 1,440,000 cumulative), $5.50 equals $7,920,000 per share of today's stock. Sources: Forms 10 - K / 10 - Q; July 17, 2025 8 - K; Company press releases; Company Proxy.

8 Bitcoin fell ~30% over the same period Discounts to NAV became the norm across the sector ~40% of bitcoin treasuries traded below 1.0x NAV by early January 2026; at least 37 of the 100 largest were underwater. Repurchases below NAV lifted bitcoin per share ~39% and cut the NAV gap ~40% in one month The Board responded with the sector's largest buyback Sources: Bloomberg market data; Company press releases; Bitcointreasuries.net. $109.4K $84.1K $68.8K $70.5K $77.1K Oct 31, 2025 Jan 30, 2026 Feb 10, 2026 Mar 20, 2026 Apr 17, 2026 Bitcoin price ($000) 10.2M 14.0M 15.9M 22.4M 26.2M Oct 31, 2025 Jan 30, 2026 Feb 10, 2026 Mar 20, 2026 Apr 17, 2026 Cumulative shares repurchased (M)

9 Sources: Trial Transcript; Company press releases; Post - Trial Memorandum Opinion, Aug. 28, 2026. FALL 2025 Bitcoin falls from its ~$126,000 peak and DATs flip from premiums to discounts. Investment banks begin showing strategic opportunities consistently. The Company signs numerous NDAs and "evaluate[s] everything that came our way." OCT. 2025 TO APR. 2026 The sector's largest buyback: 26.2 million shares repurchased below NAV, bitcoin per share up 39%. The discount narrows, then persists. The Board concludes buybacks alone will not close it. JAN. 28, 2026 Woodmont demands an immediate liquidation of the bitcoin. Board and management determined the math didn’t support that demand. Buybacks below NAV and strategic opportunities that could deliver more than NAV are the better path. EARLY 2026 Board instructed management to negotiate and conduct due diligence on two opportunities in parallel. Management conducts three months of diligence, including a site visit with a senior executive of a global energy infrastructure company brought in to assess the power, the property and the seller. MAY 2026 Board instructs management to advance the Midwest transaction and receives its financial advisor's valuation analysis, showing investment could generate substantial value for shareholders. JUNE 30 AND JULY 23, 2026 The Board approves. $65 million for 25% of a 150 MW powered site under LOI and $20 million in Cardinal Data Power, both alongside the Hunt family. Cash flow to EMPD expected from early 2027. What the Board weighed Keep buying back stock. Executed: 26.2 million shares below NAV. But the discount persisted, so buybacks alone would not close the gap. Liquidate the bitcoin and return the cash. Evaluated and rejected. Board and management determined the math didn’t support that demand. The Company's expert: selling the coins is "like killing the golden goose"; hedged arbitrageurs gain, long - term holders lose. Redeploy into cash - generating assets. Chosen. Assets that pay lease income "the most accretive way to buy bitcoin," and create long - term value for shareholders. The Board thoroughly evaluated its options, including continued buybacks and a liquidation, before deciding to pursue the AI dat a center investment opportunity.

Capitalizing on the Largest Infrastructure Build - out of 10 Deploying Capital to Maximize Value

11 2.7x global data center demand by 2030 +22% CAGR for global data center demand from 2025 – 2030 $660B hyperscaler capex 2026E, up from $118B in 2021 5 to 10 yrs U.S. grid interconnection queues Global data center capacity demand (GW), McKinsey 44 62 83 102 124 156 38 40 45 50 56 64 82 102 128 152 180 220 2025 2026 2027 2028 2029 2030 AI workload Non-AI workload Why this matters for Empery Digital • Energized, grid - connected sites are the bottleneck. Interconnection queues run five to ten years in most U.S. regions, so a 150 MW facility with power in hand and a utility contract for ~150 MW more is extremely scarce. • Behind - the - meter generation skips the queue. Cardinal Data Power pairs reserved reciprocating engines, natural gas supply and pipeline capacity on 3,500 - plus acres to deliver first power in 2027. Empery Digital shareholders will benefit from the value creation associated with the unique behind - the - meter skill set. • Capturing the opportunity takes both capital markets skill and energy operating experience. That is the premise of the Hunt partnership. Sources: McKinsey Data Center Demand Model; Bloomberg; JLL 2026 Global Data Center Outlook; FERC interconnection data; Compan y p ress releases.

12 $85M committed across two investments $440M+ expected cash flow to EMPD over the 15 - year lease from the first deal Early 2027 first lease payments expected $0 build - out, power or operating cost borne by EMPD Near - term cash flow: $65M for 25% of a 150 MW Midwest facility • Powered facility with an owned substation, 150 MW available today under an existing utility agreement and a utility contract in hand for ~150 MW more. • Non - binding LOI for a 15 - year triple net lease with high investment grade counterparties; ~$1 billion of payments on the first 150 MW, with the opportunity to roughly double after the capacity upgrade. • EMPD's 25% share expected to exceed $440 million, with payments beginning in early 2027. Lease execution expected in September 2026 Behind - the - meter buildouts: $20M for ~8% of Cardinal Data Power • Signed and closed July 20, 2026 as part of an approximately $70 million Series A led by Hood River Capital Management. • West Texas campus: 1.3 GW Phase I under LOI on more than 3,500 acres, first power in 2027, ~1 GW by 2029 and a path to 5 GW. • Investment backed by the deposit paid for ~950 MW of reciprocating engines reserved from a leading OEM. The first of several projects in CDP's pipeline. We believe there is a clear path to sustainable cash flow after the legacy business lost $165 million on $12 million of revenue from 2021 through 2024 Sources: Company press releases; Forms 10 - K / 10 - Q. Lease terms reflect a non - binding LOI and are subject to definitive documentation and closing conditions. Hunt Allred, Chairman, Cardinal Power and Cardinal Data Power 10 - plus years investing across industrial, energy, utility and venture sectors through hedge funds and family office; 8 - plus years directing investments for Petro - Hunt family entities; public equity analysis at Citadel and Vollero Beach; board and governance leadership across multiple portfolio companies. Anthony McKieran, CEO, Cardinal Data Power As CEO of Ionic Digital, led the company's conversion from bitcoin mining to AI data centers, including negotiating the lease with Nscale, Microsoft and Nvidia that is the core of that company today; 25 - plus years of financial services leadership with public company C - suite experience, including 5 - plus years as CFO of MBIA Inc.; restructured $120 billion - plus of transactions across RMBS and structured finance markets. The People Behind the Execution

The Board sought engagement. ATG refused, litigated for control, flip - flopped on its plan and now recouping its legal fees is its priority. 13 What we Uncovered in our Efforts to Protect the Interests of all Shareholders

14 ATG has a history of engaging in litigation and liquidation strategies of companies trading below their NAV 1 In January 2026, when EMPD was trading at its largest discount to NAV, ATG Capital a “NAV Gap” activist, rapidly acquired a 12% stake and hedged its position “dollar for dollar” by shorting Bitcoin ETFs. 2 ATG refused to engage in any dialogue with the Company despite becoming its largest shareholder. 3 ATG then called for the replacement of the entire Board and nominated nine candidates. 4 The Board correctly suspected that ATG was concealing a voting arrangement with Woodmont Investing to take control of the Company and liquidate its bitcoin. Mr. Brown had publicly pushed for a full liquidation. 5 The Board determined ATG's nomination notice was deficient for failing to disclose ATG’s arrangement with Woodmont and its short position against bitcoin and rejected ATG’s submission. 6 After ATG sued, it was forced to reveal that it had conducted virtually the entirety of its campaign on ephemeral messaging applications that destroyed communications between Gliksberg , his nominees and Woodmont. 7 Upon learning of the Company’s data center investments, ATG sought to prevent the Company from closing (and thereby destroy the transaction). 8 The court ruled that the Company’s bylaws lacked the specific language required to uphold the Board’s rejection. Nonetheless, the Court held that the Board was reasonable in its suspicions of ATG’s concealed plans. 10 With its previously concealed plans for the Company revealed, ATG bought back its short positions, dropped its campaign for control and is claiming that it invested nearly all of its assets in buying shares of Empery Digital because it wanted additional “oversight.” 11 ATG has articulated no plan for the Company, no relevant experience or expertise of its nominees, and instead focused on its desire to demand that the Company agree to pay its legal fees in connection with the Delaware litigation. ATG sought control of all nine seats Without a premium to shareholders. Without a plan. Without a single conversation with a director. And while concealing an ~100% hedge against the very asset the Company held and its coordination with a shareholder publicly demanding liquidation. We believe ATG's priority is ATG's legal fees ATG has dropped its bid for control and has stated that if it is successful in this campaign it intends to seek reimbursement of over $9 million in legal expenses, ignoring court sanctions stating that it owes Empery Digital shareholders the costs its own conduct imposed. The offer of a seat for Mr. Morris remains open. Sources: Post - Trial Memorandum Opinion, Aug. 28, 2026; Supplemental Letter Opinion, Sept. 2, 2026; Company Proxy; Company press releases; Defendants' Post - Trial Brief; ATG Proxy; ATG Press release; Trial Transcript. 9 The Court then sanctioned ATG for its destruction of communications.

15 Jan. 13 Brown texts an activist investor: "Come do empd .“ The activist responds: “Not a group!” and rejects Brown’s advances. Jan. 15, 1:36 p.m. The same activist introduced Gliksberg to Brown, writing: "You both called me on the same topic today." Within one minute of this email, Brown asks for Gliksberg's number. Jan. 15, afternoon Gliksberg and Brown have five phone calls together totalling over an hour. Gliksberg places an order for 400,000 shares immediately after getting off the phone with Brown, and Brown makes arrangements to free up capital to take his Empery Digital position to “9.9%.” Jan. 15, 4:58 p.m. Gliksberg moves 1,000 shares into record name. Gliksberg calls Brown after he takes this action. Brown moves 1,000 shares the next morning. Jan. 16 Gliksberg texts a future nominee he "might have a proxy fight coming up." Brown presses his broker on cash. The two speak on the phone three more times. Jan. 20 Brown buys 813,779 shares. Gliksberg and Brown move their communications to Signal with auto - delate enabled. They explain to the Court that they used Signal due to poor cell reception from their homes in Manhattan and Miami. Jan. 23 to 26 Brown files a 13G at 9.7%. Three days later ATG files a 13D at 5.6%, saying it "may in the future" hedge. It already had fully hedged its position. Jan. 28 Brown meets with EMPD management and demands liquidation, telling management that other holders are "fully hedged," while naming only "Gabi.” Feb. 3 to 4 Brown demands the Board's resignation and pitches the ATG liquidation story to Bloomberg. Gliksberg sends the published article to a nominee: "Read it now! And then don't text me about it.“ Gliksberg explained under oath that he was “concern[ed] about a friend making an inappropriate joke in response.” ATG knew it had Brown’s vote all along ATG told the Court the two were competitors running competing slates. Its own spreadsheet, withheld as "business strategy" until the last day of trial, listed Brown among the stockholders expected to vote for ATG. The Court: "It is more likely than not that Brown and Gliksberg's multiple communications in mid - January went beyond sharing pleasantries and focused on their plans for Empery." Sources: Post - Trial Memorandum Opinion, Aug. 28, 2026; Trial Transcript; Defendants' Post - Trial Brief; Company Proxy; Plaintiff' s Post - Trial Brief. After being introduced through a mutual activist, Gliksberg and Tice Brown spoke for hours on the phone before both making immediate arrangements to purchase millions of collective shares, then they both explained under oath that they were talking about fami ly and religion

16 What the Court decided (Aug. 28 and Sept. 2, 2026) • The bylaws did not specifically require ATG to disclose a bitcoin hedge or its coordination with Tice Brown, so the Board lacked contractual grounds to reject the notice. The rejection was therefore inequitable. • ATG's nine nominees may stand for election. ATG's request to reopen the nomination window after the data center announcement was denied. • ATG was sanctioned for failing to preserve evidence and ordered to pay the Company's fees and expenses in connection with ATG’s misconduct. • The Company believes the notice was deficient, respectfully disagrees with the ruling and has submitted for an interlocutory appeal. What the Court found about ATG The Court’s ruling supported the Board’s concerns regarding ATG, stating that ATG lacked credibility. A sample of quotes from the opinions are below: "evidence came to light that lends credence to the board's beliefs." Mem. Op. p. 1 "the Board had reason to be suspicious." Mem. Op. p. 20 "It is more likely than not that Brown and Gliksberg's multiple communications in mid - January went beyond sharing pleasantries and focused on their plans for Empery." Mem. Op. p. 21 Gliksberg's testimony that he had no plans to liquidate the Company's bitcoin "is difficult to credit." Mem. Op. pp. 41 - 42 "the timing and context of the message suggest an intent to conceal coordination." Mem. Op. p. 42 n.190 ATG was "furtive in its coordination with Tice Brown." Supp. Op. p. 3 Why the Board acted In bringing ATG’s conduct to light, the Board prevented an undisclosed attempt to liquidate the Company. • ATG accumulated over 12% of the Company in 26 days, declined every invitation to talk, and sought control of all nine seats without offering shareholders a premium or a plan. • The Board believed the nomination notice was deficient and was entitled to act on that belief. It did so unanimously, on the recommendation of its independent Nominating Committee, with the advice of three law firms. • The information available to the Board at the time strongly suggested that ATG had an undisclosed liquidation plan and was coordinating with Mr. Brown of Woodmont Investing, who publicly called for liquidation. • We believe any rational board focused on the best interests of all shareholders would have acted to protect them from an undisclosed, hedged bid for control. Sources: Post - Trial Memorandum Opinion, Aug. 28, 2026; Supplemental Letter Opinion, Sept. 2, 2026; Company Proxy; Company press releases; Trial Transcript; Defendants' Post - Trial Brief.

17 ~100% of ATG's position hedged by shorting bitcoin ETFs Jan. 13 hedge opened, before ATG crossed 5% and before Gliksberg met Brown No Disclosure of the hedge or coordination in ATG's 13D or nomination notice What ATG did • A "dollar for dollar" hedge. For every dollar long EMPD, roughly a dollar short a bitcoin ETF, leaving ATG with "virtually no material interest in bitcoin." • The only diligence Gliksberg did on EMPD was on the hedge. Gliksberg asked ChatGPT "what would it look like to hedge the trade with shorting gbtc dollar for dollar to the long position." • On valuing the Company. "I multiply the two, that's the value. It's easy to understand. I'm comfortable going big." • A Feb. 4 margin call on the short. Covered with $20 million of new investor money. Gliksberg had testified he never had a margin issue. • ATG closed the short only after the Company’s strategic data center investment. Only disclosed the short once discovery forced the issue. Why it matters to every other shareholder • Self - serving motivations that were not disclosed to shareholders . Shareholders deserve all of the facts. • Divergent incentives. A hedged arbitrageur is "incentivized to seek liquidation of the bitcoin. But the longer - term shareholders might want to ride out the market downturn." Selling the coins is "like killing the golden goose." • Divergent time horizon. The arbitrageur "faces short - term pressures ... but also the risk of margin calls." Long - only holders do not. • Misleading disclosure. ATG's 13D said it "may in the future" hedge. It already had, on ~100% of its position. A securities law expert called the statement misleading. • The Court's view of the omission. The Board "had reason to be suspicious," and the Court declined to fault the Board's concern, only the bylaw route it used. Sources: Post - Trial Memorandum Opinion, Aug. 28, 2026; Trial Transcript; Defendants' Post - Trial Brief; ATG Proxy.
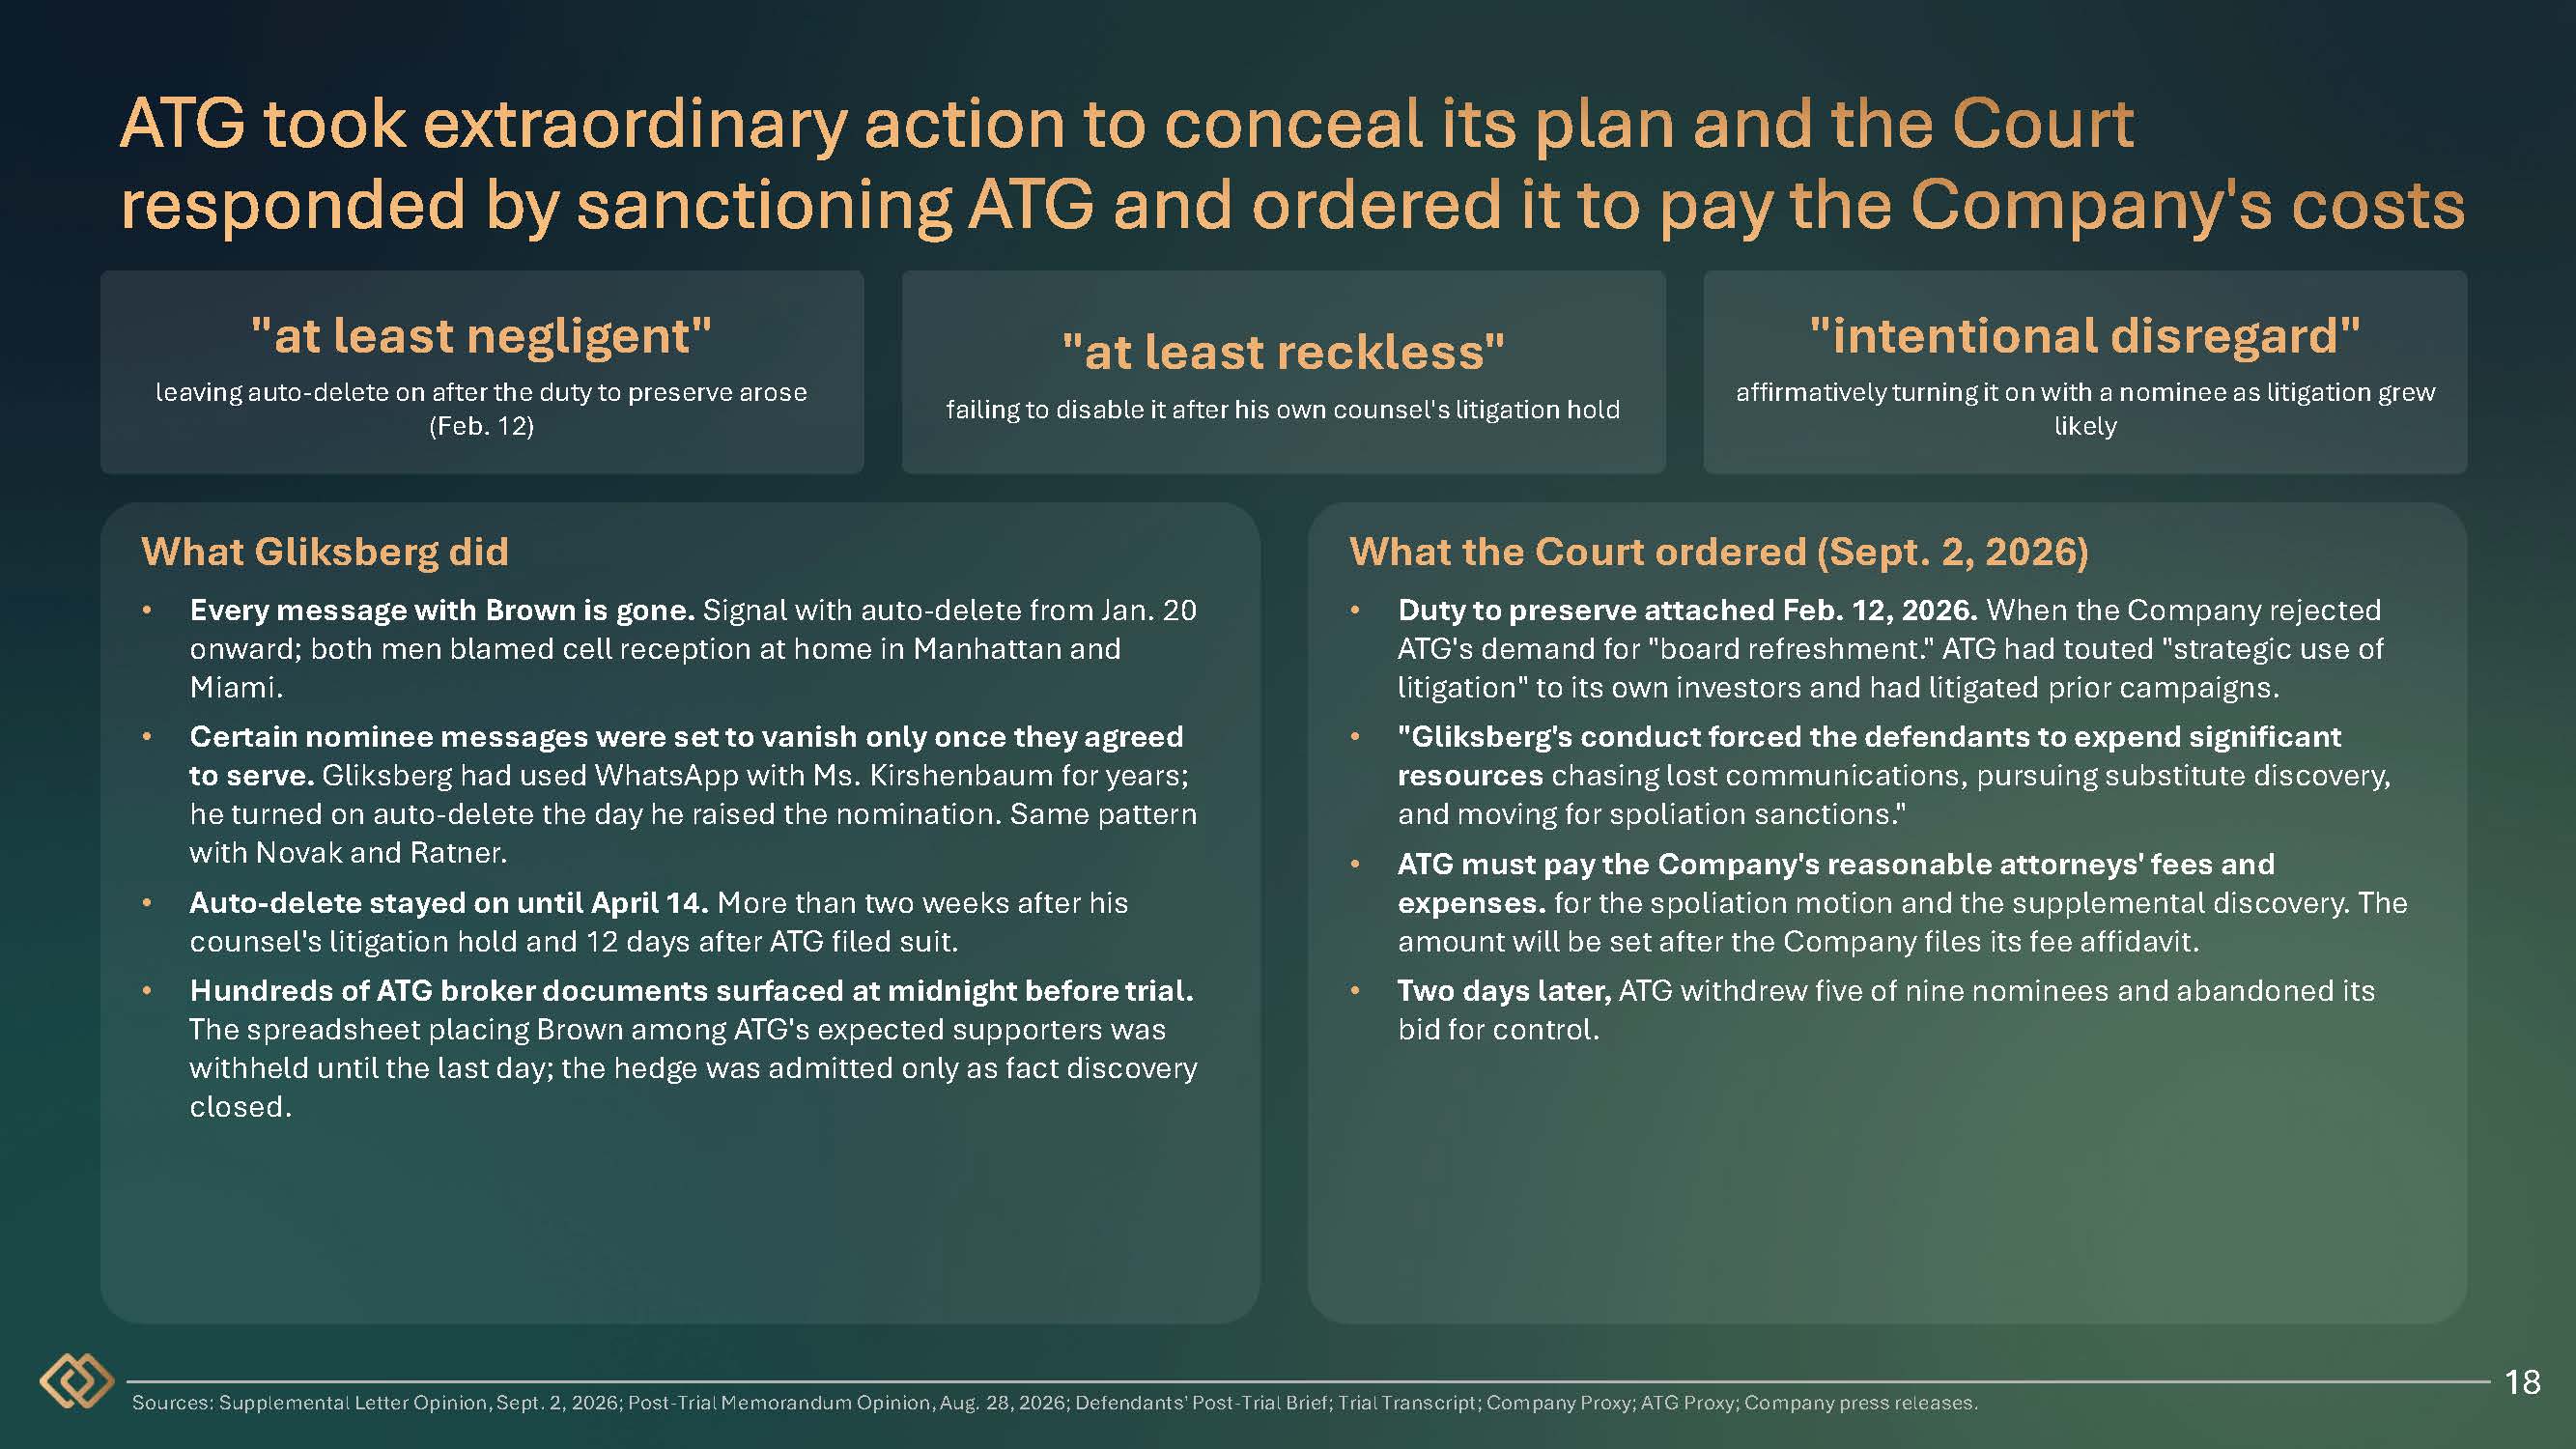
18 "at least negligent" leaving auto - delete on after the duty to preserve arose (Feb. 12) "at least reckless" failing to disable it after his own counsel's litigation hold "intentional disregard" affirmatively turning it on with a nominee as litigation grew likely What Gliksberg did • Every message with Brown is gone. Signal with auto - delete from Jan. 20 onward; both men blamed cell reception at home in Manhattan and Miami. • Certain nominee messages were set to vanish only once they agreed to serve. Gliksberg had used WhatsApp with Ms. Kirshenbaum for years; he turned on auto - delete the day he raised the nomination. Same pattern with Novak and Ratner. • Auto - delete stayed on until April 14. More than two weeks after his counsel's litigation hold and 12 days after ATG filed suit. • Hundreds of ATG broker documents surfaced at midnight before trial. The spreadsheet placing Brown among ATG's expected supporters was withheld until the last day; the hedge was admitted only as fact discovery closed. What the Court ordered (Sept. 2, 2026) • Duty to preserve attached Feb. 12, 2026. When the Company rejected ATG's demand for "board refreshment." ATG had touted "strategic use of litigation" to its own investors and had litigated prior campaigns. • "Gliksberg's conduct forced the defendants to expend significant resources chasing lost communications, pursuing substitute discovery, and moving for spoliation sanctions." • ATG must pay the Company's reasonable attorneys' fees and expenses. for the spoliation motion and the supplemental discovery. The amount will be set after the Company files its fee affidavit. • Two days later, ATG withdrew five of nine nominees and abandoned its bid for control. Sources: Supplemental Letter Opinion, Sept. 2, 2026; Post - Trial Memorandum Opinion, Aug. 28, 2026; Defendants' Post - Trial Brief; Trial Transcript; Company Proxy; ATG Proxy; Company press releases.

ATG's nominees lack the experience the strategy requires, and ATG has put forward no plan. They are the wrong people for the job. 19 ATG’s Nominees are the Wrong People for the Job

20 Three of four ran on a prior slate together. Three of four own no stock. None have relevant experience. Qualifications are irrelevant or unneeded Questionable independence and other concerns James C. Elbaor Age 40 ✖ Closed - end fund investor at Marlton LLC. Prior board work: ATRM Holdings, an OTC modular housing maker (2017 - 19), and the Intuit Art Museum. ✖ No identified experience in energy infrastructure, power procurement, hyperscaler relationships or digital assets. ✖ Gliksberg is an investor in Elbaor's fund and calls him a friend; they "go out with our wives." Ran with Gliksberg and Morris on the Marlton slate at 180 Degree Capital. ✖ Communicated with Gliksberg on WhatsApp set to auto - delete; the timer was shortened to 24 hours in late March 2026, during the litigation. Gabriel D. Gliksberg Age 39 ✖ Runs a fund with ~$63mm raised, 85 to 90% of it in one stock. Four months on the Tortoise Energy Independence Fund board before it merged. Safe Auto Insurance, a private company founded by his father - in - law, 2016 - 21. ✖ Chair of Edinburgh Worldwide since April 2026 after a Saba - backed campaign. ✖ No operating, energy or data center experience. ✖ Sanctioned for spoliation; testimony "difficult to credit"; "furtive" coordination with Tice Brown; ~100% hedged while calling ATG the largest shareholder. ✖ Holds a power of attorney from every other nominee, pre - approves and pays all their expenses and indemnifies them. "I don't mind the little work." Meredith S. Kirshenbaum Age 39 ✖ Labor and employment lawyer representing employers before the NLRB and advising charter schools. No public company board experience; nonprofit boards only. ✖ No identified experience in capital allocation, digital assets, energy or data center development. ✖ A limited partner in ATG Fund. Has known Gliksberg for decades as a personal friend. Owns no Empery Digital shares. ✖ Gliksberg turned on WhatsApp auto - delete with her on Feb. 16, 2026, the day she agreed to serve, after years of messaging without it. Aaron T. Morris Age 39 ✖ Plaintiffs' securities litigator whose firm solicits investors for class actions after stock declines. Skadden associate 2012 - 19. First public board seat June 2026 (a U.K. investment trust). ✖ No identified experience in energy infrastructure, power, digital assets or financing large - scale sites. ✖ His firm represents Gliksberg and ATG and has an ongoing attorney - client relationship with them. Gliksberg called Morris between his first calls with Brown on Jan. 15. ✖ Ran with Gliksberg on the Marlton slate. Owns no Empery Digital shares. ✖ Communicated with Gliksberg on WhatsApp set to auto - delete. The withdrawn slate tells the same story: Ron Davies was Safe Auto's CEO while Gliksberg sat on its board, and Arati Batta wa s r ecruited by Gliksberg's father - in - law with the promise of "about 40k a year for very little work." Sources: ATG Proxy; ATG Supp. Notice 9/10/26; Trial Transcript; Post - Trial Memorandum Opinion, Aug. 28, 2026; Supplemental Lette r Opinion, Sept. 2, 2026; Defendants' Post - Trial Brief.

21 ATG recruited its nominees for a seat, not for the work, and kept them in the dark on purpose "Hi. My son - in - law Gabi asked me to reach out to you. I recommended you for a potential seat on a public board ... It'll pay about 40k a year for very little work." Message recruiting nominee Arati Batta, sent by Gliksberg's father - in - law at his request (JX 155). Gliksberg: "I have no idea. I didn't write this." "You don't necessarily want people that are currently into the industry ... people that previously were in the industry but are no longer are sort of the ideal candidates." Gliksberg on why he screened out active crypto professionals, agreeing that a bitcoin bull might not want the "bad rep" of taking "a more capitalist stand" against a bitcoin company. "Did you discuss your plans for Empery with any of the candidates?" "No." ... "I didn't really have a plan to discuss." Gliksberg at trial. He also described his 13D plans as "boilerplate" and said that when he bought the shares he did "not exactly" have a plan. "As far as the company we're after, better to not share that with anyone at this stage." Gliksberg to a contact helping source nominees. Candidates were approached on a "no - name" basis; none was told what company they were being recruited to oversee. "Read it now! And then don't text me about it." Gliksberg to nominee Evan Ratner, forwarding the Bloomberg column laying out a DAT liquidation playbook that Brown had pitched to the columnist. "I don't mind the little work." Gliksberg, asked about his criticism that Empery's directors were paid for doing little. The Court: "The candidates he selected lacked cryptocurrency experience." Gliksberg enabled auto - deleting messages "when discuss ing the proxy contest with several of his nominees." Sources: Trial Transcript; Post - Trial Memorandum Opinion, Aug. 28, 2026.

22 ATG's proxy lists actions its nominees "could" consider. Each is already done or underway What ATG says its nominees "could" do What the Board has already done Repurchasing shares $150 million allocated to repurchase 26.2 million shares at an average of $5.71, all below NAV. Program raised from $150 mill ion to $200 million. 29.8 million shares remain outstanding. Bitcoin per share up 39% from Aug. 27, 2025 to March 2, 2026. Paying down debt Term loan repaid in full on April 1, 2026, releasing about 1,800 bitcoin from collateral. Debt cut from $105 million in Janua ry 2026 to $35 million today. A tender offer at or close to NAV The Board repurchased $150 million of its stock below NAV instead, which is more accretive per share than an immediate return of capital. Enhancing investor transparency Operated with real - time treasury dashboard prior to pursuit of AI data center strategy, when reporting NAV based on bitcoin holdings no longer reflected the true value of the company. Reducing the burdensome expense structure Co - CEO salaries cut to $225,000, no annual bonus since July 2025, no management fee to Empery Asset Management. Headcount 15 at year - end 2025. Four - wheel business divested, lease expense reduced. Evaluating structural or strategic alternatives Numerous NDAs signed and weekly conversations with banks since fall 2025. Three months of diligence produced the Hunt partnership: $65 million for 25% of a 150 MW site and $20 million in Cardinal Data Power. Cash flow to the Company expected from early 2027. Sell some or all assets and return capital The Company sold $80.1 million of bitcoin in the first half of 2026 to fund $54.0 million of repurchases below NAV and repay deb t. The only thing that ATG says its nominees “could” do that the Board has not done is liquidate all of the Company’s assets Sources: ATG Proxy; Company press releases; Forms 10 - K / 10 - Q; Company Proxy; Trial Transcript. Lease terms reflect a non - binding LOI and are subject to definitive documentation and closing conditions. Shares Outstanding inc ludes common shares and pre - funded warrants.

Highly relevant skills and experience, and 21% beneficial ownership, ensuring long - term alignment with shareholders and oversight of management 23 Our Directors are the Right People for the Job
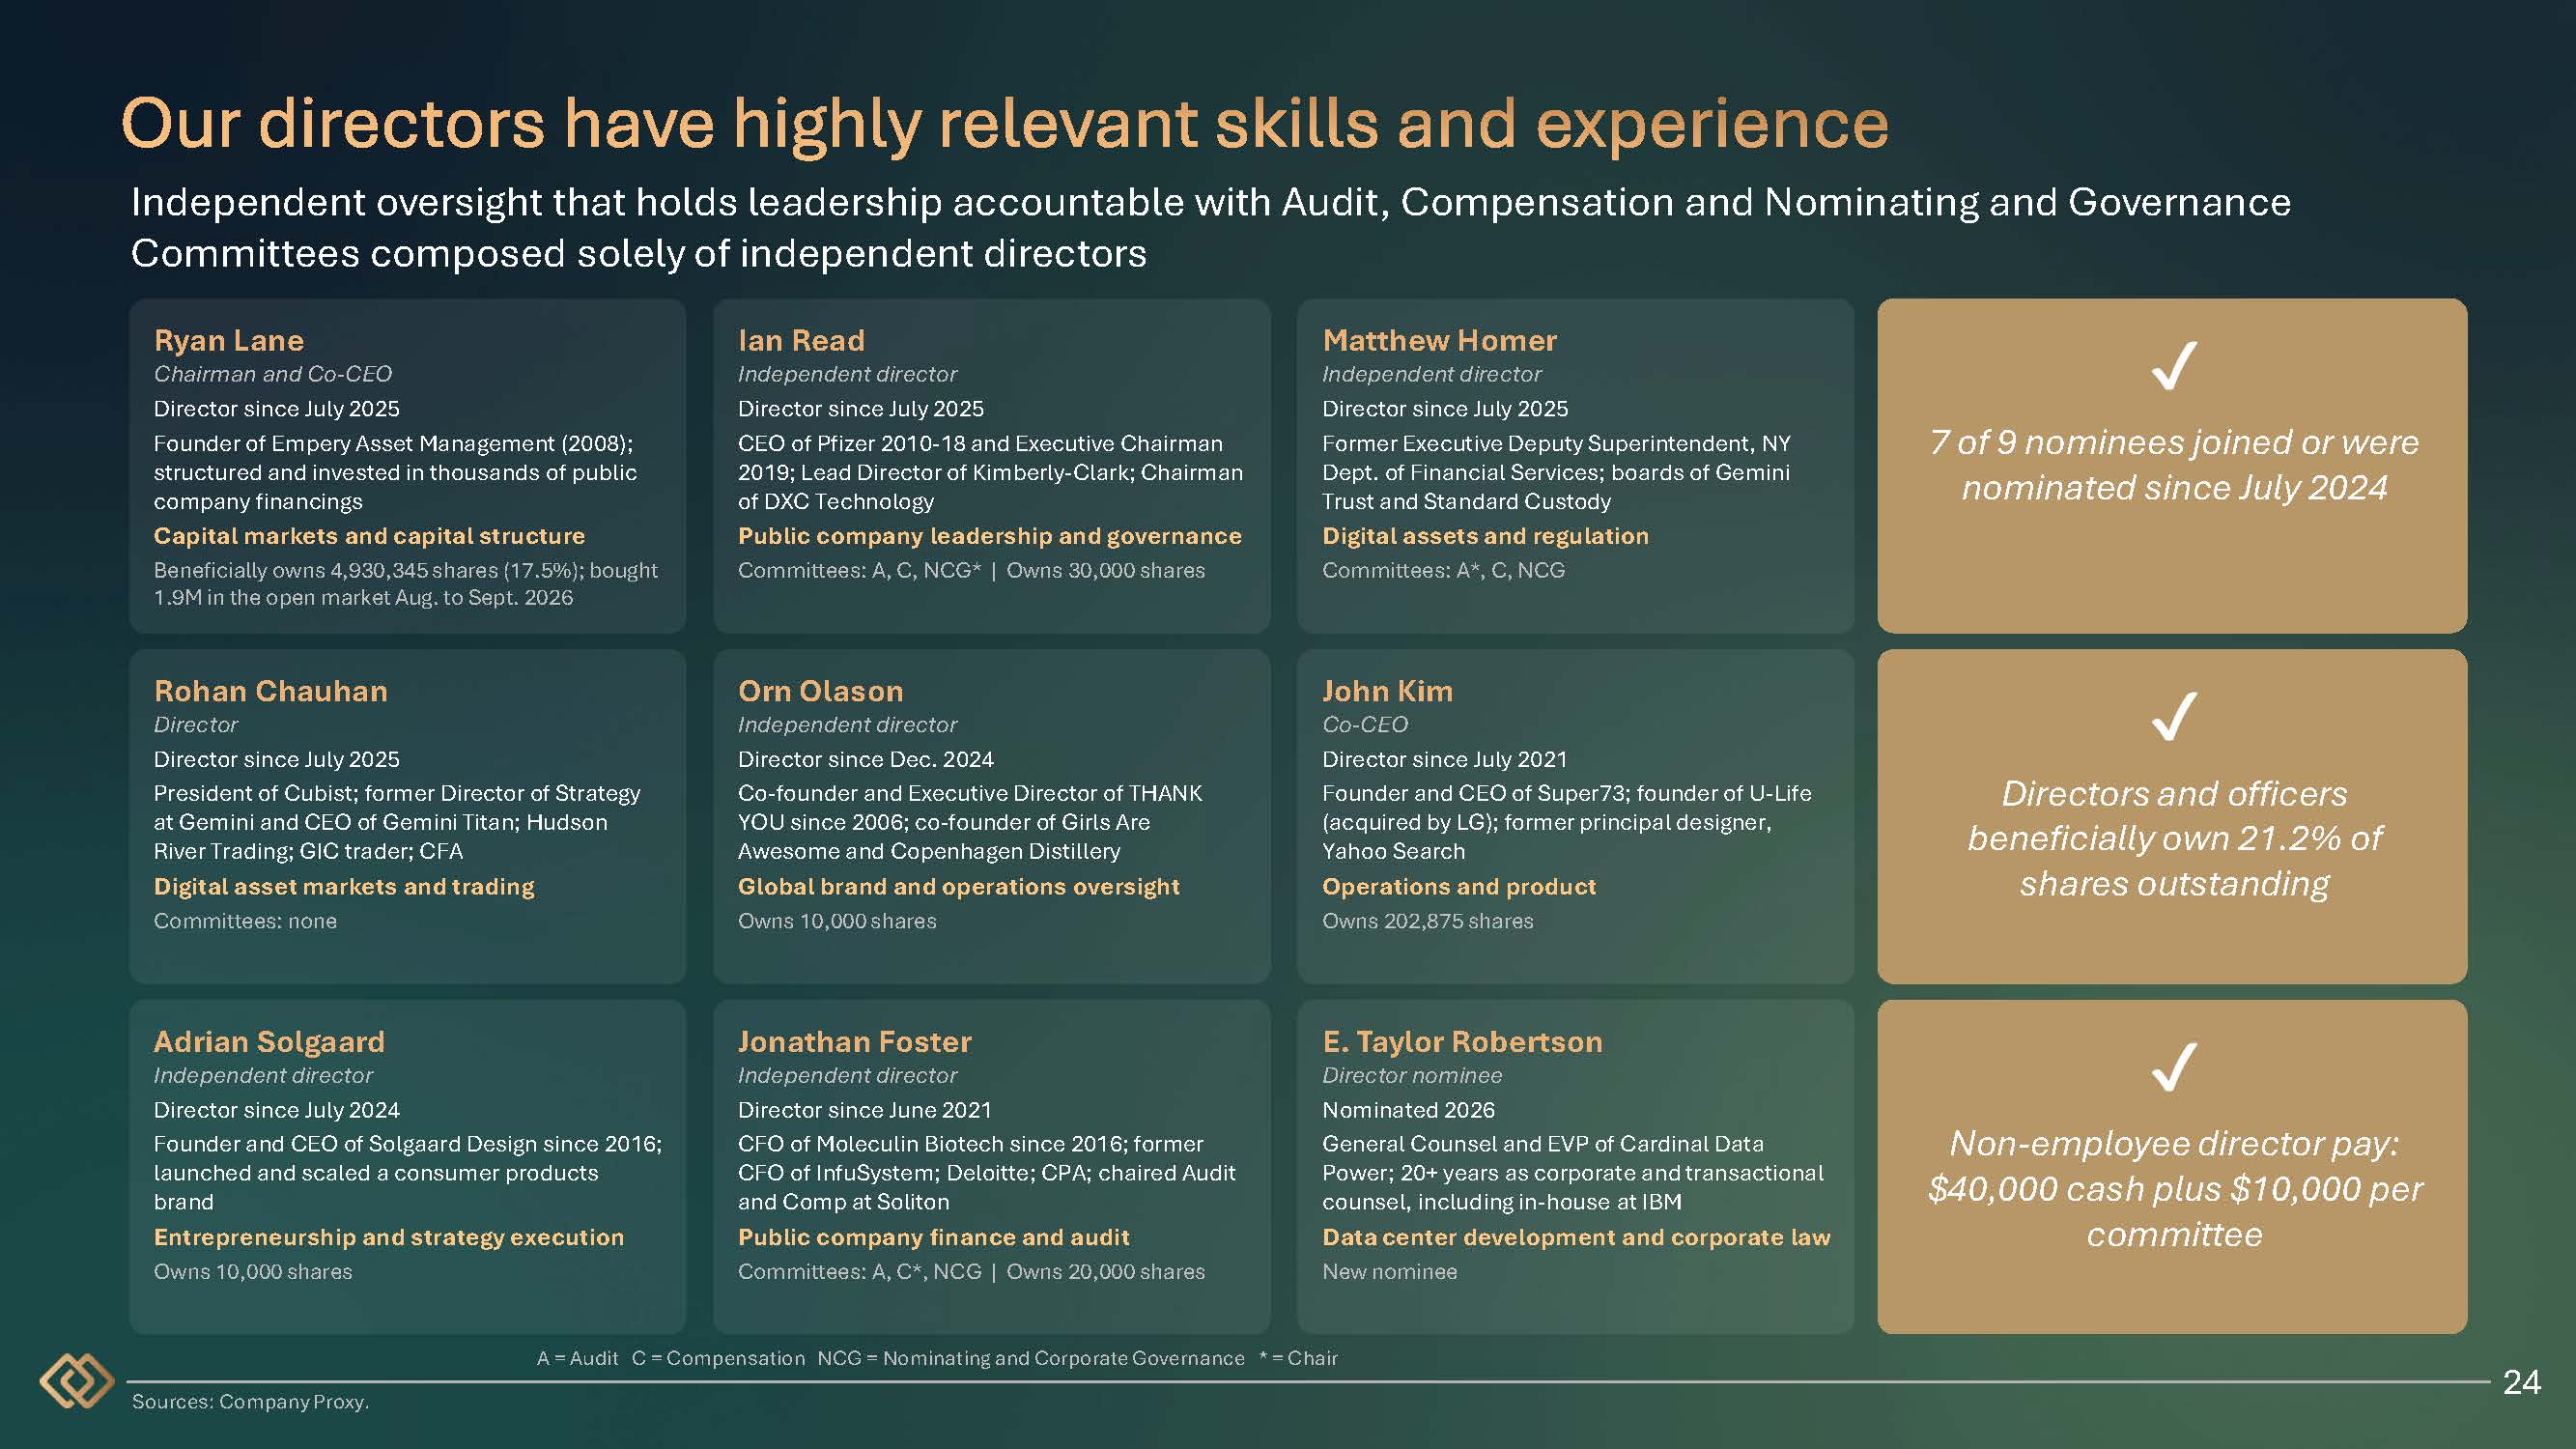
24 Ryan Lane Chairman and Co - CEO Director since July 2025 Founder of Empery Asset Management (2008); structured and invested in thousands of public company financings Capital markets and capital structure Beneficially owns 4,930,345 shares (17.5%); bought 1.9M in the open market Aug. to Sept. 2026 Ian Read Independent director Director since July 2025 CEO of Pfizer 2010 - 18 and Executive Chairman 2019; Lead Director of Kimberly - Clark; Chairman of DXC Technology Public company leadership and governance Committees: A, C, NCG* | Owns 30,000 shares Matthew Homer Independent director Director since July 2025 Former Executive Deputy Superintendent, NY Dept. of Financial Services; boards of Gemini Trust and Standard Custody Digital assets and regulation Committees: A*, C, NCG Rohan Chauhan Director Director since July 2025 President of Cubist; former Director of Strategy at Gemini and CEO of Gemini Titan; Hudson River Trading; GIC trader; CFA Digital asset markets and trading Committees: none Jonathan Foster Independent director Director since June 2021 CFO of Moleculin Biotech since 2016; former CFO of InfuSystem; Deloitte; CPA; chaired Audit and Comp at Soliton Public company finance and audit Committees: A, C*, NCG | Owns 20,000 shares John Kim Co - CEO Director since July 2021 Founder and CEO of Super73; founder of U - Life (acquired by LG); former principal designer, Yahoo Search Operations and product Owns 202,875 shares Adrian Solgaard Independent director Director since July 2024 Founder and CEO of Solgaard Design since 2016; launched and scaled a consumer products brand Entrepreneurship and strategy execution Owns 10,000 shares Orn Olason Independent director Director since Dec. 2024 Co - founder and Executive Director of THANK YOU since 2006; co - founder of Girls Are Awesome and Copenhagen Distillery Global brand and operations oversight Owns 10,000 shares E. Taylor Robertson Director nominee Nominated 2026 General Counsel and EVP of Cardinal Data Power; 20+ years as corporate and transactional counsel, including in - house at IBM Data center development and corporate law New nominee A = Audit C = Compensation NCG = Nominating and Corporate Governance * = Chair Sources: Company Proxy. Independent oversight that holds leadership accountable with Audit, Compensation and Nominating and Governance Committees composed solely of independent directors 7 of 9 nominees joined or were nominated since July 2024 Non - employee director pay: $40,000 cash plus $10,000 per committee Directors and officers beneficially own 21.2% of shares outstanding

25 Mr. Lane brought the capital and the plan. Mr. Read brings Fortune 100 governance experience. Ryan Lane Chairman and Co - Chief Executive Officer Director since July 2025 Founder, Empery Asset Management (2008) Beneficially owns 4,930,345 shares (17.51%) Salary $225,000, no annual bonus, no management fee ✔ Led the $500 million July 2025 PIPE and led the transition from a struggling vehicle maker to a bitcoin treasury and then to AI infrastructure. ✔ Has negotiated and invested in thousands of public company financings since 2008, the skill set behind the $500 million July 2025 PIPE and a $25 million raise at 103% of NAV. ✔ Bought 1.9 million shares in the open market in August and September 2026 at $2.82 to $3.59, after the Court ruling and during the contest. ✔ Compensation is tied to the share price: his options are struck at $10, more than three times the current $2.88 share price and are worth nothing unless the stock more than triples. ✔ Sourced and is the linchpin of the Hunt Properties relationship that produced the Midwest site and Cardinal Data Power investment. Ian Read Independent director; Chair, Nominating and Governance Director since July 2025 CEO of Pfizer 2010 - 18; Executive Chairman 2019 Lead Director, Kimberly - Clark; Chairman, DXC Technology Owns 30,000 shares ✔ Led one of the world's largest public companies for eight years and chaired two others. More than 40 years of senior management and governance experience. ✔ Chairs the independent committee that reviewed ATG's nomination notice with three law firms and recommended, unanimously, that the Board reject it. ✔ Sits on all three standing committees and has served as Lead Director and Chairman, the roles that matter most when a board is under pressure. ✔ Senior operating executive, Carlyle Global Healthcare since 2020; brings large - cap investor and board discipline to a small - cap company. Mr. Lane's incentives are the shareholders' incentives He beneficially owns 17.5% of the Company, took no management fee, is paid $225,000 with no annual bonus and holds options that pay nothing unless the stock at least triples. He bought more stock last month. Mr. Read brings Fortune 100 governance experience Eight years as CEO of Pfizer, a Fortune 100 company, and Executive Chairman in 2019. Five years as Lead Director of Kimberly - Clark and four as Chairman of DXC Technology. He brings that boardroom discipline to the independent committee that oversees this Board's nominations and governance. Sources: Company Proxy; July 17, 2025 8 - K; Company press releases; Trial Transcript; Post - Trial Memorandum Opinion, Aug. 28, 202 6.

26 Mr. Chauhan has the crypto expertise ATG screened out. Mr. Olason is independent and predates the pivot. Rohan Chauhan Director Director since July 2025 President, Cubist, Inc. (since Jan. 2026) Director of Strategy, Gemini; CEO, Gemini Titan (2024 - 25) Hudson River Trading; GIC trader CFA charterholder ✔ Runs a digital asset infrastructure company building cross - chain systems for tokenized assets and on - chain finance. ✔ Director of Strategy at Gemini and CEO and Chairman of Gemini Titan . ✔ Traded and scaled businesses at two of the most sophisticated capital allocators in the world, Hudson River Trading and Singapore's sovereign wealth fund. ✔ Exactly the profile ATG avoided: Gliksberg testified he did not want nominees "currently in the industry." The Court: ATG's candidates "lacked cryptocurrency experience." Orn Olason Independent director Director since December 2024 Co - founder and Executive Director, THANK YOU (since 2006) Co - founder, Girls Are Awesome and Copenhagen Distillery Owns 10,000 shares ✔ Twenty years running a creative studio with global clients, overseeing complex operations across geographic regions. ✔ Joined the Board before the July 2025 recapitalization and voted for the treasury strategy and the data center strategic investments as an independent director. ✔ Served on the Nominating and Governance and Audit Committees through the 2025 transition. ✔ One of two independent directors who bridge the legacy Volcon board and the current one, giving shareholders continuity of oversight ATG's slate cannot offer. ATG wants to remove the crypto expertise it says the Company lacks ATG's proxy calls for "fresh perspectives." Its slate has no one who has run a digital asset business. Mr. Chauhan has. Removing him and Mr. Olason would leave a board with less market expertise and less institutional memory during the most important execution period in the Company's history. Sources: Company Proxy; Trial Transcript; Post - Trial Memorandum Opinion, Aug. 28, 2026; ATG Proxy.

27 What our Board would lose What ATG's nominees would "add" Ryan Lane ✔ Capital markets expertise behind the $500M PIPE, the buyback and the Hunt partnership ✔ 17.5% beneficial owner who bought 1.9M more shares in Aug. and Sept. 2026 ✔ Architect of the data center strategy James Elbaor ✖ Closed - end fund investor; board experience limited to an OTC housing maker and an art museum ✖ Gliksberg's friend and fund investor ✖ Owns no shares Ian Read ✔ Former CEO of Pfizer; chaired DXC; Lead Director of Kimberly - Clark ✔ Chairs the independent Nominating and Governance Committee ✔ Four decades of public company governance Gabriel Gliksberg ✖ Sanctioned for destroying evidence; testimony "difficult to credit" ✖ No credible public company board experience ✖ No plan Rohan Chauhan ✔ Runs a digital asset infrastructure company ✔ Former Director of Strategy at Gemini; Hudson River Trading; GIC ✔ The Board's hands - on crypto market expertise Meredith Kirshenbaum ✖ Labor and employment lawyer; no public board experience ✖ Limited partner in ATG Fund; decades - long friend of Gliksberg ✖ Owns no shares Orn Olason ✔ Independent director since Dec. 2024, before the recapitalization ✔ Twenty years overseeing global operations ✔ Continuity from the legacy Board Aaron Morris ✖ Plaintiffs' class action lawyer ✖ His firm represents Gliksberg and ATG ✖ Owns no shares Experience aligned with a strategy already delivering No relevant experience, questionable independence, no plan Sources: Company Proxy; ATG Proxy; Post - Trial Memorandum Opinion, Aug. 28, 2026; Supplemental Letter Opinion, Sept. 2, 2026; Tri al Transcript; Defendants' Post - Trial Brief.

28 A nominee whose day job is building the behind - the - meter data centers the Company is now invested in E. Taylor Robertson Director nominee, age 48 General Counsel and Executive Vice President, Cardinal Data Power, Inc. (since Aug. 2026) Founding Partner, Robertson & Robertson Law Group (2016 - 2026) Former in - house counsel, IBM B.A. International Trade & Finance and J.D., Louisiana State University ✔ Executive at the Company's data center partner. CDP is developing the 1.3 GW Phase I West Texas campus in which the Company invested $20 million. Mr. Robertson brings that project's legal, power and land work into the boardroom. ✔ More than 20 years as a corporate and transactional lawyer, advising technology, financial services, oil and gas, energy and manufacturing businesses, the sectors the new strategy spans. ✔ Nominated by the independent Nominating and Governance Committee, chaired by Ian Read, as part of a refreshment that has added seven of nine nominees since July 2024. ✔ Related - party interests are disclosed in full in the proxy statement. The Audit, Compensation and Nominating Committees remain composed entirely of independent directors. Board refreshment July 2024 Adrian Solgaard joins Dec. 2024 Orn Olason joins July 2025 Ryan Lane, Ian Read, Matthew Homer and Rohan Chauhan join with the recapitalization Aug. 2025 Re - constituted Audit, Compensation and Nominating Committees; full independence maintained Sept. 2026 E. Taylor Robertson nominated Seven of nine nominees are new since July 2024. The two longest - serving directors, Mr. Kim and Mr. Foster, are not opposed by ATG. Sources: Company Proxy; Company press releases; ATG Proxy.

29 The Board converted a discounted bitcoin balance sheet into stakes in AI infrastructure, with cash flow to the Company expected to begin in early 2027. Shareholders are better served by the team that built this plan than by nominees who have none. >$440M expected cash flow to the Company over the Midwest lease, from 2027 $4.72 NAV per share vs. a $2.88 share price 21.2% of shares beneficially owned by directors and officers Oct. 14 2026 Annual Meeting. Vote the WHITE proxy card Vote FOR ONLY the Board's nine nominees on the WHITE universal proxy card. Because directors are elected by plurality, only FOR votes for the Board's nominees help elect them. Sources: Company press releases; Company Proxy; Company internal data. Based on Bitcoin price of $75,874 as of September 15, 2026. Lease terms reflect a non - binding LOI and are subject to definitive documentation and closing conditions.

30 • We are executing with urgency. In 14 months the Board raised $500 million, bought back 26.2 million shares below NAV, repaid its term loan and redeployed capital into two data center investments with cash flow expected from early 2027. • The strategy is taking hold. A $65 million commitment for 25% of a 150 MW powered site under LOI with an investment grade tenant; $20 million in Cardinal Data Power's 1.3 GW West Texas campus and partnered with real estate and energy development experts. • Shareholder alignment is real. Directors and officers beneficially own 21.2% of the Company. The Chairman bought 1.9 million shares in the open market during this contest. Management has low salaries, out of the money options, no bonuses and no additional options available. • ATG offers no plan and no relevant expertise. It sought control without a premium, hedged its exposure, destroyed evidence, was sanctioned, and walked away from a near - final settlement over its own legal fees. It owes the Company's shareholders money and it is seeking over $9 million in legal fees from the Company. • Electing ATG's nominees would remove the directors who built the plan at the moment it begins to pay. The Board asks shareholders to protect it. Vote the WHITE proxy card The Board unanimously recommends a vote "FOR ONLY" each of its nine nominees: Ryan Lane John Kim Ian Read Matthew Homer Jonathan Foster Adrian Solgaard Orn Olason Rohan Chauhan E. Taylor Robertson Mark only nine names. A card marked FOR more than nine nominees is invalid. Sources: Company press releases; Company Proxy; Post - Trial Memorandum Opinion, Aug. 28, 2026; Supplemental Letter Opinion, Sept. 2, 2026; ATG Proxy.

31 Vote FOR ONLY the Board's nine nominees on the WHITE universal proxy card By internet Go to www.proxyvote.com with the control number on your WHITE proxy card or voting instruction form. Votes accepted until 11:59 p.m. ET on Oct. 13, 2026. By telephone Stockholders of record call 1 - 800 - 690 - 6903 (toll - free in the U.S., U.S. territories and Canada) with your card in hand, until 11:59 p.m. ET on Oct. 13, 2026. Street - name holders: follow your broker's instructions. By mail Mark FOR only the nine Board nominees, sign, date and return the WHITE proxy card in the envelope provided. A card marked FOR more than nine nominees is invalid. At the virtual meeting Pre - register at www.proxyvote.com by 10 a.m. CT on Oct. 13, 2026. The meeting begins at 10 a.m. CT on Oct. 14, 2026 at www.virtualshareholdermeeting.com/E MPD2026. Questions or help voting Okapi Partners LLC, the Company's proxy solicitor 1212 Avenue of the Americas, 17th Floor, New York, NY 10036 Shareholders and all others, toll - free: (877) 839 - 1065 Banks and brokerage firms: (212) 297 - 0720 Email: [email protected] Discard any gold card Do not sign or return any gold proxy card from ATG Capital. If you already have, you can revoke it by voting a later - dated WHITE proxy card. Only your latest - dated proxy counts.
32 Appendix

33 The raise benefited all shareholders. Voting with management was neither required nor discussed $25M proceeds raised +3% unit price premium to NAV 25% unit price premium to the prior day trading price 20% warrant strike price premium to NAV ATG CLAIM WHAT ACTUALLY HAPPENED Transaction was undervalued Priced above NAV (103%) and at a 25% premium to the prior day trading price. Goal was to frustrate ATG Goal was to raise capital accretively, above NAV, to repay debt and fund share repurchases below NAV. There was no valuation of the warrants Management valued the warrants with the same inputs it uses at its fund. The Board's decision rested on selling stock above NAV; a formal warrant appraisal was not what drove it. Deal came together too fast Highbridge first raised the deal with management on March 17, six days before the March 23 announcement. Highbridge portfolio manager: "We have never once had a conversation with Empery's management or anyone else about how we wou ld vote." Sources: Company press releases; Trial Transcript; Plaintiff's Post - Trial Brief; Defendants' Post - Trial Arg. Slides.

EMPD and Bitcoin price severely declined intraday on February 5, 2026 34 An unsolicited block sale negotiated before the open at that morning's price. No premium was paid ATG CLAIM "Lane agreed to repurchase Cable Car's shares at $4.35 per share, an approximately 33% premium to the market price, to remove Ma - Weaver from the stockholder base." ATG Post - Trial Brief WHAT ACTUALLY HAPPENED Ma - Weaver to Brown the same day: "4.35, you can see the print posted AH ... Negotiated premkt ." Sources: Plaintiff's Post - Trial Brief; Trial Transcript; Defendants' Post - Trial Brief; Defendants' Post - Trial Arg. Slides; Bloom berg market data. $4.40 $3.26 - 25.5% $70,064 $63,083 - 9.2% 9:00 10:00 11:00 12:00 1:00 2:00 3:00 4:00 EMPD Bitcoin Ma - Weaver (Cable Car) approached the Company to sell pre - market. No premium. The price was agreed before the open at the market price. Bitcoin and EMPD prices declined dramatically on that day. ATG is comparing the $4.35 trade price to the $3.26 closing price and claiming the trade was at a premium.

35 The largest share repurchase program in the industry Sources: Bloomberg market data; Company press releases; Company internal records; Chart goes through June 29, 2026 when we announced the AI Data Center investment, at which point we believe the value of our sha res are not best reflected by NAV. 0k 100k 200k 300k 400k 500k 0.6x 0.7x 0.8x 0.9x 1.0x 1.1x 1.2x Aug ’25 Sep Oct Nov Dec Jan ’26 Feb Mar Apr May Jun Shares repurchased (000s) mNAV (x) Shares repurchased (daily) mNAV Share repurchases increased NAV per share while successfully driving the share price closer to NAV $150 Million Returned to shareholders through share repurchases 26.2 Million Shares repurchased ~0.9x Increased mNAV from ~0.7x ~50% Of shares outstanding since the Aug. 2025 PIPE repurchased
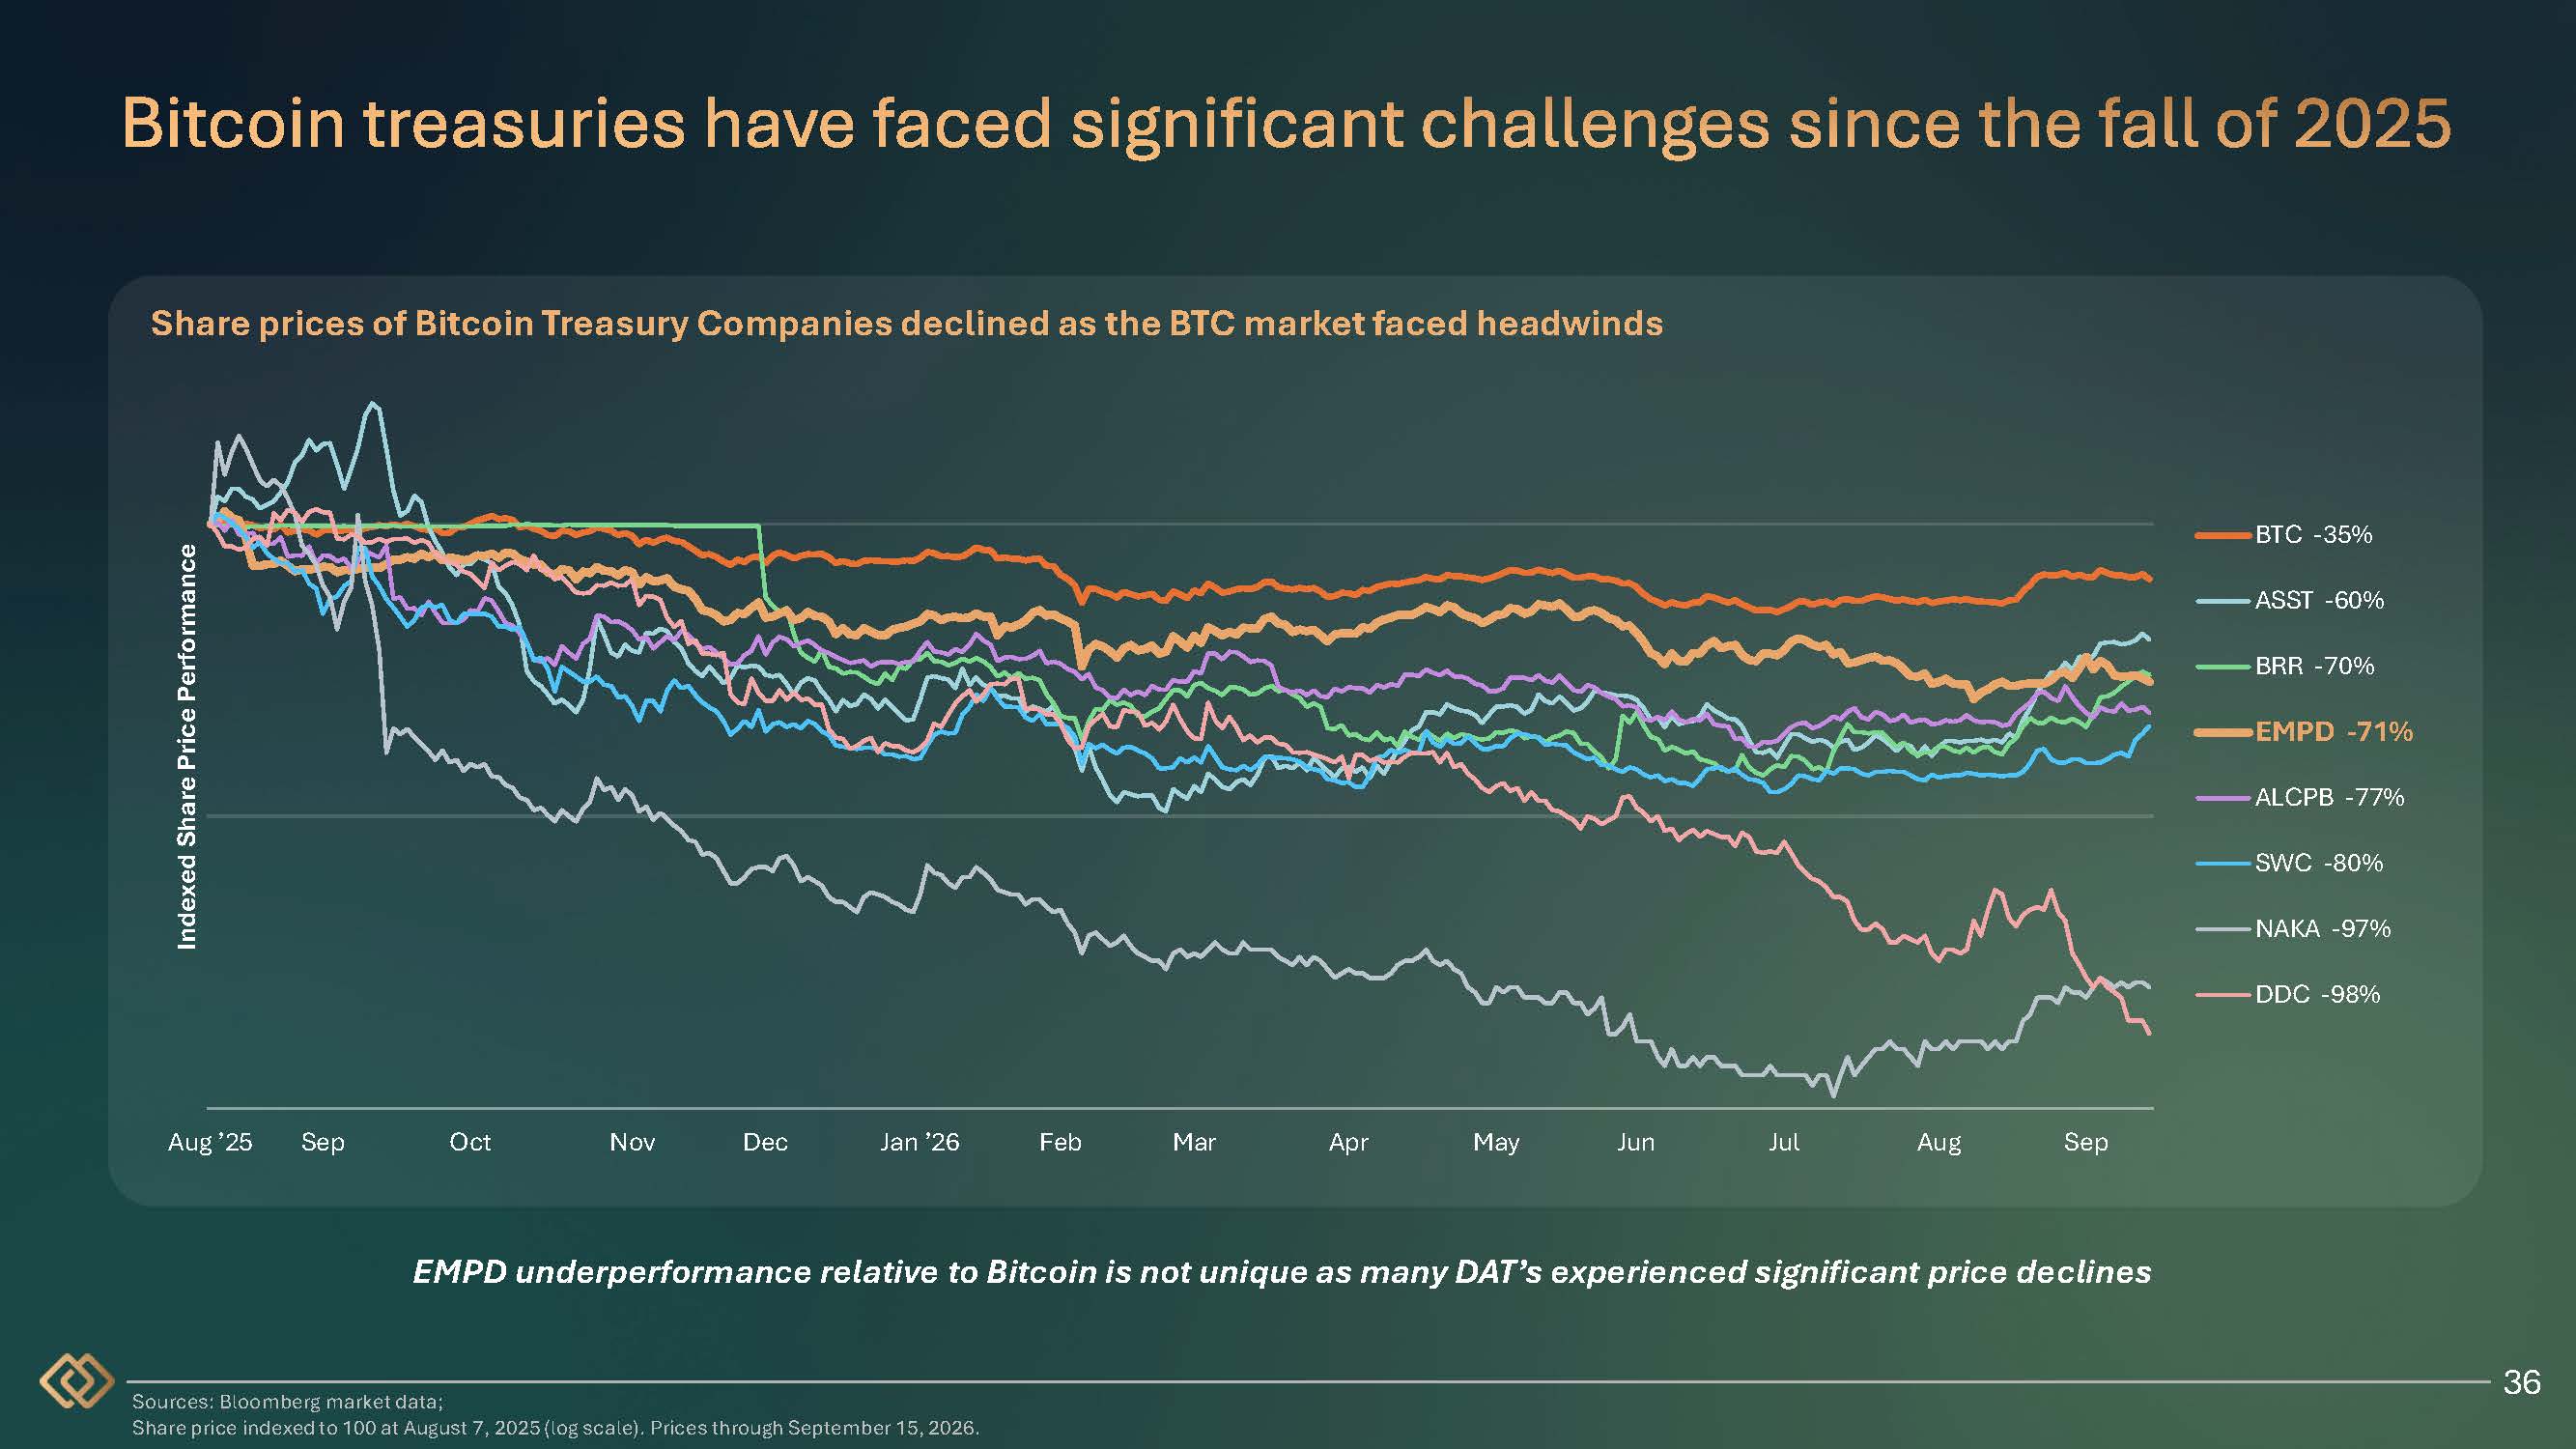
36 Share prices of Bitcoin Treasury Companies declined as the BTC market faced headwinds Sources: Bloomberg market data; Share price indexed to 100 at August 7, 2025 (log scale). Prices through September 15, 2026. Aug ’25 Sep Oct Nov Dec Jan ’26 Feb Mar Apr May Jun Jul Aug Sep Indexed Share Price Performance BTC -35% ASST -60% BRR -70% EMPD -71% ALCPB -77% SWC -80% NAKA -97% DDC -98% EMPD underperformance relative to Bitcoin is not unique as many DAT’s experienced significant price declines

37 EMPD partnered with Hunt Properties to acquire a Midwest data center property with an LOI in place for a triple net lease $65M Investment for a 25% stake 150 MW Power today; clear path to ~300 MW ~$1B Potential net - lease payments on 150 MW Q3 2026 Expected lease execution The Asset • Powered Midwest facility with an owned substation and existing infrastructure that has operated as a power - intensive industrial facility for the past three years • 150 MW available today under an existing utility power agreement with the local utility • Load study confirms a path to nearly double capacity to ~300 MW for AI workloads – Utility contract in hand for the additional power The Investment Structure • $65M for a 25% interest in a newly formed acquiring entity • Hunt Properties serves as managing member and operating partner • Currently negotiating lease based on non - binding LOI for a triple - net lease with a high investment grade counterparties detailing a 15 - year lease with payments of ~$1 billion for the first 150 MW and plans for use of the additional power capacity upgrades to ~300 MW • Contract in hand from utility for incremental ~150 MW • Upon closing, total expected cash flow expected to exceed $440 million to EMPD over the proposed 15 - year term, beginning in early 2027 1 Note: Sources: Company press releases. Lease terms reflect a non - binding LOI. Reflects potential outcomes under a non - binding LOI; subject to customary closing conditions.

38 $20mm preferred equity investment in Cardinal Data Power, a Hunt Properties - affiliated developer $20M Preferred equity investment ~8% Ownership stake in CDP 1.3 GW Phase I campus under LOI >5 GW Long - term site capacity Behind - the - Meter Capability • Reciprocating - engine generation capacity reserved from a leading OEM through an agreement with an experienced independent power producer • Advantaged natural gas supply, proprietary pipeline capacity and electrical infrastructure on large contiguous land • Delivers large - scale, reliable power on accelerated timelines without waiting on grid interconnections The Investment • $20mm preferred equity signed and closed July 20, 2026 for an approximately 8% stake in CDP • Part of an approximately $70mm Series A led by Hood River Capital Management • Backed by value of deposit paid for ~950MW of reciprocating motors from large OEM • Inaugural West Texas campus: 1.3 GW Phase I LOI on more than 3,500 acres, first power in 2027 and approximately 1 GW by 2029 • Deepens the Hunt Properties partnership across West Texas and West Virginia 2 Sources: Company press releases. Note: Reflects potential outcomes under a non - binding LOI; subject to customary closing conditions.
Serious News for Serious Traders! Try StreetInsider.com Premium Free!
You May Also Be Interested In
- ATG Capital pushes for board seats at Empery Digital ahead of vote
- ASUS and Poesis Team Up on Autonomous Trading Agents Powered by NVIDIA Technologies
- TUK Group Advances 35 Toronto Rental Homes, Launches TUK Partner Portal
Create E-mail Alert Related Categories
SEC FilingsSign up for StreetInsider Free!
Receive full access to all new and archived articles, unlimited portfolio tracking, e-mail alerts, custom newswires and RSS feeds - and more!
