




Form 486BPOS Bluerock Total Income
 Tweet
 Share
 E-mail
As filed with the Securities and Exchange Commission on January 27, 2025
Securities Act Registration No.
Investment Company Act Registration No.
SECURITIES AND EXCHANGE COMMISSION
Washington, D. C. 20549
FORM
REGISTRATION STATEMENT UNDER THE SECURITIES ACT OF 1933
| Pre-Effective Amendment No._ |
| Post-Effective Amendment No. |
and/or
REGISTRATION STATEMENT UNDER THE INVESTMENT COMPANY ACT OF 1940
| Amendment No. |
(Check appropriate box or boxes.)
BLUEROCK TOTAL INCOME+ REAL ESTATE FUND
(Exact Name of Registrant as Specified in Charter)
(Address of Principal Executive Offices) (Zip Code)
Registrant’s Telephone Number, including
Area Code: 1-
(Name and Address of Agent for Service)
With copy to:
| JoAnn M. Strasser, Esq. | Jason Emala, Esq. |
| Thompson Hine LLP | Bluerock Asset Management, LLC |
| 41 South High Street, 17th Floor | 919 Third Avenue, 40th Floor |
| Columbus, OH 43215 | New York, NY 10022 |
| (614) 469-3265 | (212) 843-1601 |
| Check box if the only securities being registered on this Form are being offered pursuant to dividend or interest reinvestment plans. |
| Check box if any securities being registered on this Form will be offered on a delayed or continuous basis in reliance on Rule 415 under the Securities Act of 1933 (“Securities Act”), other than securities offered in connection with a dividend reinvestment plan. |
| Check box if this Form is a registration statement pursuant to General Instruction A.2 or a post-effective amendment thereto. |
| Check box if this Form is a registration statement pursuant to General Instruction B or a post-effective amendment thereto that will become effective upon filing with the Commission pursuant to Rule 462(e) under the Securities Act. |
| Check box if this Form is a post-effective amendment to a registration statement filed pursuant to General Instruction B to register additional securities or additional classes of securities pursuant to Rule 413(b) under the Securities Act. |
It is proposed that this filing will become effective (check appropriate box)
| when declared effective pursuant to Section 8(c) of the Securities Act |
The following boxes should only be included and completed if the registrant is making this filing in accordance with Rule 486 under the Securities Act.
| immediately upon filing pursuant to paragraph (b) |
| on |
| 60 days after filing pursuant to paragraph (a) |
| on (date) pursuant to paragraph (a) |
If appropriate, check the following box:
| This [post-effective] amendment designates a new effective date for a previously filed [post-effective amendment] [registration statement]. |
| This Form is filed to register additional securities for an offering pursuant to Rule 462(b) under the Securities Act, and the Securities Act registration statement number of the earlier effective registration statement for the same offering is: |
| This Form is a post-effective amendment filed pursuant to Rule 462(c) under the Securities Act, and the Securities Act registration statement number of the earlier effective registration statement for the same offering is: |
| This Form is a post-effective amendment filed pursuant to Rule 462(d) under the Securities Act, and the Securities Act registration statement number of the earlier effective registration statement for the same offering is: |
Check each box that appropriately characterizes the Registrant:
| Registered Closed-End Fund (closed-end company that is registered under the Investment Company Act of 1940 (“Investment Company Act”)). |
| Business Development Company (closed-end company that intends or has elected to be regulated as a business development company under the Investment Company Act). |
| Interval Fund (Registered Closed-End Fund or a Business Development Company that makes periodic repurchase offers under Rule 23c-3 under the Investment Company Act). |
| A.2 Qualified (qualified to register securities pursuant to General Instruction A.2 of this Form). |
| Well-Known Seasoned Issuer (as defined by Rule 405 under the Securities Act). |
| Emerging Growth Company (as defined by Rule 12b-2 under the Securities Exchange Act of 1934 (“Exchange Act”). |
| [ ] | If an Emerging Growth Company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 7(a)(2)(B) of Securities Act. |
| New Registrant (registered or regulated under the Investment Company Act for less than 12 calendar months preceding this filing). |

Bluerock Total Income+ Real Estate Fund (the “Fund”) is a continuously offered, non-diversified, closed-end management investment company that is operated as an interval fund.
The Securities and Exchange Commission has not approved or disapproved these securities or determined if this Prospectus is truthful or complete. Any representation to the contrary is a criminal offense.
This prospectus is intended to concisely provide you, a prospective investor, with information about the Fund that you should know before investing in the shares of the Fund that are being offered through this prospectus. You are advised to thoroughly and carefully read this prospectus and retain it for future reference. Additional information about the Fund is also available on the Securities and Exchange Commission’s (“SEC”) website at http://www.sec.gov, including the Fund’s Statement of Additional Information dated February 1, 2025 (the “SAI”). The address of the SEC’s website is provided solely for the information of prospective shareholders and is not intended to be an active link. The table of contents of the SAI appears on page 34 of this prospectus. The SAI is incorporated by reference into this prospectus (legally made a part of this prospectus). The SAI, Fund annual and semi-annual reports and other information and shareholder inquiries regarding the Fund may be requested free of charge by writing the Fund at c/o SS&C Global Investor & Distribution Solutions, Inc., PO Box 219445, Kansas City, MO 64121-9445 (the “Transfer Agent” or “SS&C GIDS”), by calling the Transfer Agent toll-free at 1-844-819-8287, or by visiting the Fund’s website at http://www.bluerockfunds.com.
Investment Objectives. The Fund’s primary investment objective is to generate current income while secondarily seeking long-term capital appreciation with low to moderate volatility and low correlation to the broader markets.
Summary of Investment Strategy. The Fund pursues its investment objectives using a comprehensive multi-strategy, multi-manager, multi-sector approach, primarily investing in a strategic combination of what the Fund’s advisor believes are global ‘best in class’ institutional private real estate funds and public real estate securities.
The Advisor. The Fund’s investment advisor is Bluerock Fund Advisor, LLC (the “Advisor”), a registered advisor under the Investment Advisers Act of 1940, as amended (the “Advisers Act”). The Advisor has engaged Mercer Investments LLC (“Mercer” or a “Sub-Advisor”), a registered advisor under the Advisers Act, to provide ongoing research, opinions and recommendations of institutional asset managers and their investment funds for consideration by the Advisor on behalf of the Fund. Mercer, together with its affiliated investment businesses, have over 5,600 delegated and advisory clients globally with over $547 billion in assets under management as of September 30, 2024 and over $17.5 trillion in assets under advisement as of June 30, 2024. The Advisor has also engaged RREEF America L.L.C. (“RREEF” or a “Sub-Advisor”), a registered adviser under the Advisers Act, to provide investment management for a portion, generally less than 20%, of the Fund’s portfolio. RREEF, together with its affiliates in Europe and Asia, comprise the global real estate investment business of DWS Group GmbH & Co. KGaA (“DWS”), an indirect majority owned subsidiary of Deutsche Bank A.G. DWS’s real estate investment business, is one of the largest real estate investment managers globally with more than 330 professionals and staff located in 23 cities worldwide and approximately $78.9 billion in real estate and real estate-related assets under management as of September 30, 2024.
See “The Fund” and “Investment Objectives, Strategies and Investment Features.”
Securities Offered. The Fund engages in a continuous offering of classes of shares of beneficial interest of the Fund. Class A shares are offered by this prospectus. The Fund offers Class C, Class I, Class L and Class M shares by different prospectuses. The Fund is authorized as a Delaware statutory trust to issue an unlimited number of shares. The Fund is offering to sell, through its principal underwriter, ALPS Distributors, Inc., (the “Distributor”) on a continual basis under the terms of this prospectus, shares of beneficial interest at net asset value (“NAV”) per share of the relevant share class, plus any applicable sales load. As of January 3, 2025, the Fund’s NAV per share was $26.03 for Class A shares. The maximum sales load is 5.75% of the amount invested for Class A shares. The minimum initial investment by a shareholder for Class A shares is $2,500 for regular accounts and $1,000 for retirement plan accounts. Subsequent investments may be made with at least $100 for regular accounts and $50 for retirement plan accounts. The Distributor is not required to sell any specific number or dollar amount of the Fund’s shares, but will use reasonable efforts to sell the shares. No termination date of the Fund’s continuous offering has been established. Monies received will be invested promptly and no arrangements have been made to place such monies in an escrow, trust or similar account.
The Fund’s shares have no history of public trading, nor is it intended that they will be listed on a public exchange at this time. No secondary market is expected to develop for the Fund’s shares, liquidity for the Fund’s shares will be provided only through quarterly repurchase offers for no less than 5% of the Fund’s shares and there is no guarantee that an investor will be able to sell all the shares that the investor desires to sell in the repurchase offer. Investing in the Fund’s shares involves substantial risks, including the risks set forth in the “Risk Factors” section of this prospectus.
|
Investment Advisor | Bluerock Fund Advisor, LLC |
TABLE OF CONTENTS
PROSPECTUS SUMMARY |
1 |
SUMMARY OF FUND EXPENSES |
7 |
FINANCIAL HIGHLIGHTS |
8 |
THE FUND |
9 |
USE OF PROCEEDS |
9 |
INVESTMENT OBJECTIVE, POLICIES AND STRATEGIES |
10 |
RISK FACTORS |
14 |
MANAGEMENT OF THE FUND |
19 |
DETERMINATION OF NET ASSET VALUE |
23 |
CONFLICTS OF INTEREST |
24 |
QUARTERLY REPURCHASES OF SHARES |
25 |
DISTRIBUTION POLICY |
26 |
DIVIDEND REINVESTMENT POLICY |
27 |
U.S. FEDERAL INCOME TAX MATTERS |
28 |
DESCRIPTION OF CAPITAL STRUCTURE AND SHARES |
28 |
ANTI-TAKEOVER PROVISIONS IN THE DECLARATION OF TRUST |
29 |
PLAN OF DISTRIBUTION |
29 |
LEGAL MATTERS |
33 |
REPORTS TO SHAREHOLDERS |
33 |
INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM |
34 |
ADDITIONAL INFORMATION |
34 |
TABLE OF CONTENTS OF THE STATEMENT OF ADDITIONAL INFORMATION |
34 |
PRIVACY POLICY & PRACTICES |
35 |
PROSPECTUS SUMMARY
This summary does not contain all of the information that you should consider before investing in the shares. You should review the more detailed information contained or incorporated by reference in this prospectus and in the Statement of Additional Information, particularly the information set forth below under the heading “Risk Factors.”
The Fund
Bluerock Total Income+ Real Estate Fund (the “Fund”) is a continuously offered, non-diversified, closed-end management investment company. See “The Fund.” The Fund is an interval fund that provides investor liquidity by offering to make quarterly repurchases of each class of shares at that class of shares’ net asset value, which will be calculated on a daily basis. See “Quarterly Repurchases of Shares,” and “Determination of Net Asset Value.”
Investment Objectives and Policies
The Fund’s primary investment objective is to generate current income while secondarily seeking long-term capital appreciation with low to moderate volatility and low correlation to the broader markets.
The Fund pursues its investment objectives by investing, under normal circumstances, at least 80% of net assets, plus the amount of any borrowings for investment purposes, in “real estate industry securities,” primarily in income producing equity and debt securities. The Fund invests in debt securities of any duration or maturity.
The Fund concentrates investments in the real estate industry, meaning that under normal circumstances, it invests over 25% of its assets in real estate industry securities. The Fund’s investments may be targeted in any one or more of the many sectors of the real estate market, including but not limited to the retail, office, multifamily, hospitality, industrial, residential, healthcare, life sciences, and self-storage sectors. The Fund defines real estate industry securities to include the common stock, partnership or similar interests, asset-backed securities, preferred stock, and secured or unsecured debt. Real estate industry securities may be issued by a wide variety of entities including: private real estate investment funds managed by institutional investment managers (“Institutional Investment Funds”); non-traded unregistered real estate investment trusts (“Private REITs”); publicly traded real estate investment trusts or other similar companies (“Public REITs”); Government Sponsored Entities (“GSEs”) such as Federal Home Loan Mortgage Corporation Structured Pass-Through Certificates (“K-Notes”); exchange traded funds, index mutual funds, and other investment vehicles such as closed-end funds and mutual funds that invest principally, directly or indirectly, in real estate (collectively, “Other Public Investment Vehicles”) and unregistered funds that invest principally in real estate. In certain circumstances or market environments, the Fund may reduce its investment in real estate industry securities and hold a larger position in cash or cash equivalents. The Fund will not invest in any issuer that is an affiliate of the Fund, or affiliate of a Fund affiliate (as defined by the Investment Company Act of 1940, as amended (the “1940 Act”)).
The Fund’s real estate industry investment policy is fundamental and may not be changed without shareholder approval. The Fund’s Statement of Additional Information (“SAI”) contains a list of all of the fundamental and non-fundamental investment policies of the Fund, under the heading “Investment Objectives and Policies.”
Investment Strategy
The Fund pursues its investment objectives using a comprehensive multi-strategy, multi-manager, multi-sector approach, primarily investing in a strategic combination of global ‘best in class’ institutional private real estate investment funds and public real estate securities.
The term ‘best in class’ refers to Institutional Investment Funds the Advisor has identified as offering above average prospects using information provided by Mercer and its proprietary screening process. Mercer’s screening process applies multiple factors including quantitative and qualitative assessment (as described more fully below) of the management team and track record, and is not generally available to the individual investor through financial filings or published reports. Mercer is one of the leading advisors to endowments, pension funds, sovereign wealth funds, and family offices globally.
The Fund executes a portion of its investment strategy, generally less than 20%, by seeking to invest in publicly traded real estate securities selected by RREEF, an indirect subsidiary of DWS. RREEF seeks to maximize risk-adjusted returns by managing volatility and identifying securities that are priced inefficiently relative to its assessment of intrinsic value and the public real estate securities may be of any credit quality; including fixed-income and preferred securities rated less than investment grade that are sometimes referred to as high yield or “junk bonds.” The Advisor or RREEF will sell a security when other securities are available that offer higher expected current income, long-term capital appreciation, lower volatility or lower correlation to broader securities markets or a combination of the preceding.
The Fund may utilize leverage through borrowing for investment purposes or to satisfy repurchase requests. The Fund currently borrows money under two credit facilities.
Many of the Institutional Investment Funds have a large minimum investment size and stringent investor qualification criteria that are intended to limit their direct investors to mainly institutions such as endowments and pension funds. As such, the Fund enables investors to invest with institutional investment managers that may not be otherwise permitted or available to them.
In addition, the Fund enables investors to execute a comprehensive multi-strategy, multi-manager, multi-sector strategy by making a single investment in the Fund, whereas due to the large minimums of many of the Institutional Investment Funds, such a strategy may not otherwise be permitted or available to the investor.
1 |
The Advisor also believes that the Fund may be able to provide an additional benefit in terms of lower fees from the Institutional Investment Funds as a result of volume discounts that may not otherwise be permitted or available to them.
Investment Advisor
Bluerock Fund Advisor, LLC was formed on May 11, 2012 and is registered with the SEC as an investment adviser. The Advisor is a subsidiary of Bluerock Asset Management, LLC (“BAM”); BAM, together with its affiliates (“Bluerock”), is a leading institutional alternative asset manager with more than $19.2 billion in acquired and managed assets based in New York with regional offices across the United States. Bluerock principals have a collective 100+ years of investing experience with more than $120 billion of real estate and capital markets experience and manage multiple well-recognized real estate private and public company platforms.
Sub-Advisors
The Advisor may, from time to time, engage one or more investment sub-advisors. Any sub-advisor chosen by the Advisor will be paid by the Advisor on only the portion of Fund assets allocated to any such sub-advisor. Shareholders do not pay any sub-advisor directly.
The Advisor has engaged Mercer, a registered investment adviser under the Advisers Act, to provide both ongoing research and opinions of institutional asset managers and their investment funds for consideration by the Advisor on behalf of the Fund as well as recommendations for the selection of investment funds for approval by the Advisor. The Advisor has engaged RREEF, a registered investment adviser under the Advisers Act, to invest a portion of the Fund’s portfolio in publicly traded real estate securities and to provide the Advisor with research and information with respect to non-publicly traded real estate related debt securities.
Advisor Fees and Expenses
The Advisor is entitled to receive a monthly fee at the annual rate of 1.50% of the Fund’s daily net assets. The Advisor and the Fund have entered into an expense limitation and reimbursement agreement (the “Expense Limitation Agreement”) under which the Advisor has contractually agreed to waive its fees and to pay or absorb the ordinary operating expenses of the Fund (excluding any taxes, interest, brokerage commissions, acquired fund fees and expenses, and extraordinary expenses, such as litigation or reorganization costs, but including organizational costs and offering costs), to the extent that such expenses exceed 1.95% per annum of the Fund’s average daily net assets (the “Expense Limitation”) attributable to Class A shares. In consideration of the Advisor’s agreement to limit the Fund’s expenses, the Fund has agreed to repay the Advisor in the amount of any fees the Advisor previously waived or Fund expenses reimbursed, subject to the limitations that: (1) the reimbursement will be made if payable not more than three years from the date incurred; (2) the reimbursement may not be made if it would cause the expense limitation then in effect or in effect at the time of the waiver to be exceeded; and (3) the reimbursement is approved by the Fund’s Board of Trustees (the “Board”). The Expense Limitation Agreement will remain in effect at least until January 31, 2026 unless and until the Board approves its modification or termination. After January 31, 2026, the Expense Limitation Agreement may be renewed at the Advisor’s and Board’s discretion. See “Management of the Fund.”
Administrator, Accounting Agent and Transfer Agent
ALPS Fund Services, Inc. (the “Administrator”) serves as the Fund’s administrator and accounting agent. SS&C Global Investor & Distribution Solutions, Inc. (the “Transfer Agent” or “SS&C GIDS”) serves as the transfer agent of the Fund. See “Management of the Fund.”
Distribution Fees
Class A shares are not subject to a Distribution Fee. See “Plan of Distribution.”
Closed-End Fund Structure
Generally, closed-end funds differ from mutual funds in that closed-end funds do not typically redeem their shares at the option of the shareholder. Closed-end fund shares typically trade in the secondary market via a stock exchange. Unlike many closed-end funds, however, the Fund’s shares will not be listed on a stock exchange. Instead, the Fund will provide limited liquidity to shareholders by offering to repurchase a limited amount of the Fund’s shares (at least 5%) quarterly, which is discussed in more detail below. The Fund, similar to a mutual fund, is subject to continuous asset in-flows, although not subject to continuous out-flows.
Share Classes
The Fund offers Class A shares by this prospectus. The Fund began continuously offering its common shares on October 22, 2012. As of February 18, 2014, the Fund simultaneously redesignated its issued and outstanding common shares as Class A shares and created its Class C shares and Class I shares, each offered by a separate prospectus. As of May 30, 2017, the Fund created its Class L shares. As of February 1, 2020, the Fund created its Class M shares. An investment in any share class of the Fund represents an investment in the same assets of the Fund. However, the sales loads and ongoing fees and expenses for each share class are different. The loads, fees and expenses for the Fund are set forth in “Summary of Fund Expenses.” If an investor has hired an intermediary and is eligible to invest in more than one class of shares, the intermediary may help determine which share class is appropriate for that investor. When selecting a share class, you should consider which share classes are available to you, how much you intend to invest, the investment minimum, how long you expect to own shares, and the total costs and expenses associated with a particular share class.
2 |
Each investor’s financial considerations are different. You should speak with your financial advisor to help you decide which share class is best for you. Not all financial intermediaries offer all classes of shares and all share classes may not be available in every state. If your financial intermediary offers more than one class of shares, you should carefully consider which class of shares to purchase.
Investor Suitability
An investment in the Fund involves a considerable amount of risk. It is possible that you will lose some or all of your money. An investment in the Fund is suitable only for investors who can bear the risks associated with the limited liquidity of the shares and should be viewed as a medium to long-term investment. Before making your investment decision, you should (i) consider the suitability of this investment with respect to your investment objectives and personal financial situation and (ii) consider factors such as your personal net worth, income, age, risk tolerance and liquidity needs.
Repurchases of Shares
The Fund is an interval fund and, as such, has adopted a fundamental policy to make quarterly repurchase offers, at net asset value, of no less than 5% of the Fund’s outstanding shares. There is no guarantee that shareholders will be able to sell all of the shares they desire to sell in a quarterly repurchase offer. Liquidity will be provided to shareholders only through the Fund’s quarterly repurchases. See “Quarterly Repurchases of Shares.”
Summary of Risks
Investing in the Fund involves risks, including the risk that you may receive little or no return on your investment or that you may lose part or all of your investment. Before investing you should consider carefully the risks that you assume when you invest in the Fund’s shares. See “Risk Factors.”
Real Estate Industry Concentration Risk. The Fund will concentrate its investments in real estate related securities, and it may invest in real estate directly. As such, its portfolio will be significantly impacted by the performance of the real estate market and may experience more volatility and be exposed to greater risk than a more diversified portfolio. The value of companies engaged in the real estate industry is affected by: (i) changes in general economic and market conditions; (ii) changes in the value of real estate properties; (iii) risks related to local economic conditions, overbuilding and increased competition; (iv) increases in property taxes and operating expenses; (v) changes in zoning laws; (vi) casualty and condemnation losses; (vii) variations in rental income, neighborhood values or the appeal of property to tenants; (viii) the availability of financing; (ix) climate change and (x) changes in interest rates and leverage. There are also special risks associated with particular sectors, or real estate operations, including, but not limited to, those risks described below:
Retail Properties. Retail properties are affected by shifts in consumer demand due to demographic changes, changes in spending patterns and lease terminations.
Office Properties. Office properties are affected by a downturn in the businesses operated by their tenants.
Hospitality Properties. Hotel properties and other properties in the hospitality real estate sector, such as motels and extended-stay properties, are affected by declines in business and leisure travel.
Healthcare and Life Sciences Properties. Healthcare and life sciences properties are affected by potential federal, state and local laws governing licenses, certification, adequacy of care, pharmaceutical distribution, rates, equipment, personnel and other factors regarding operations, funding for biotech companies and the continued availability of revenue from government reimbursement programs.
Industrial Properties. Industrial properties are affected by downturns in the manufacturing, processing and shipping of goods.
Multifamily Properties. Multifamily properties are affected by adverse economic conditions in the locale, oversupply and rent control laws.
Residential Properties. Residential properties can be significantly affected by the national, regional and local real estate markets. This segment of the real estate industry also is sensitive to interest rate fluctuations which can cause changes in the availability of mortgage capital and directly affect the purchasing power of potential homebuyers. Thus, residential properties can be significantly affected by changes in government spending, consumer confidence, demographic patterns and the level of new and existing home sales.
Shopping Centers. Shopping center properties are affected by changes in the local markets where their properties are located and dependent upon the successful operations and financial condition of their major tenants.
Self-Storage Properties. Self-storage properties are affected by changes to competing local properties, consumer and small business demand for storage space, and the ability of the management team.
3 |
Other factors may contribute to the risk of real estate investments:
Development Issues. Real estate development companies in which the Underlying Funds (defined below) or the Fund may invest are affected by construction delays and insufficient tenant demand to occupy newly developed properties.
Lack of Insurance. Certain of the companies in the Fund’s portfolio may fail to carry comprehensive liability, fire, flood, wind or earthquake extended coverage and rental loss insurance, or insurance and may be subject to various policy specifications, limits and deductibles. Due to the prevalence of catastrophic events, the cost of insurance may increase materially.
Dependence on Tenants. The ability of companies in the real estate industry in which the Fund may invest to make distributions to shareholders depends upon the ability of the tenants at their properties to generate enough income in excess of tenant operating expenses to make their lease payments.
Financial Leverage. Companies in the real estate industry in which the Fund may invest may be highly leveraged and financial covenants may affect their ability to operate effectively. The use of floating rate loans may also negatively impact returns in a rising interest rate environment.
Environmental Issues. Owners of properties that may contain hazardous or toxic substances may be responsible for removal or remediation costs. Environmental risk from high winds, hurricanes, fires, flood and extreme heat may also materially affect a property’s value.
Credit Market Conditions. Instability in credit markets can potentially make it more difficult for borrowers to obtain financing or refinancing on attractive terms or at all. Conditions in the credit markets may expose borrowers to increased interest expenses for borrowed money and tightening underwriting standards. There is also a risk that a general lack of liquidity or other events in the credit markets may adversely affect the ability of issuers in whose securities the Fund invests to finance real estate developments and projects or refinance completed projects.
Market Risk. An investment in shares is subject to investment risk, including the possible loss of the entire principal amount invested. An investment in shares represents an indirect investment in the securities owned by the Fund. The value of these securities, like other market investments, may move up or down, sometimes rapidly and unpredictably. In addition, the Fund is subject to the risk that geopolitical and other similar events will disrupt the economy on a national or global level. For instance, war, terrorism, market manipulation, government defaults, government shutdowns, political changes or diplomatic developments, public health emergencies (such as the spread of infectious diseases, pandemics and epidemics) and natural/environmental disasters can all negatively impact the securities markets.
Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. The foregoing could impair the Fund’s ability to maintain operational standards, disrupt the operations of the Fund and its service providers, adversely affect the performance, value and liquidity of the Fund’s investments, and negatively impact the Fund’s performance and your investment in the Fund. The value of your shares at any point in time may be worth less than the value of your original investment, even after taking into account any reinvestment of dividends and distributions.
Liquidity Risk. There currently is no secondary market for the Fund’s shares and the Advisor does not expect that a secondary market will develop. Limited liquidity is provided to shareholders only through the Fund’s quarterly repurchase offers for no less than 5% of the Fund’s shares outstanding at net asset value. There is no guarantee that shareholders will be able to sell all of the shares they desire in a quarterly repurchase offer. The Fund’s investments also are subject to liquidity risk. Liquidity risk exists when particular investments of the Fund would be difficult to purchase or sell, possibly preventing the Fund from selling such illiquid securities at an advantageous time or price, or possibly requiring the Fund to dispose of other investments at unfavorable times or prices in order to satisfy its obligations.
Allocation Risk. The ability of the Fund to achieve its investment objective depends, in part, on the ability of the Advisor to allocate effectively the Fund’s assets among the various Institutional Investment Funds, Private REITs, Public REITs and Other Public Investment Vehicles in which the Fund invests and, with respect to each such asset class, among equity and fixed income securities. There can be no assurance that the actual allocations will be effective in achieving the Fund’s investment objective or delivering positive returns.
Correlation Risk. The Fund seeks to produce returns that are not correlated to the broader financial markets. Although the prices of equity securities and fixed-income securities, as well as other asset classes, often rise and fall at different times so that a fall in the price of one may be offset by a rise in the price of the other, in down markets the prices of these securities and asset classes can also fall in tandem. Because the Fund allocates its investments among different real estate asset classes, the Fund is subject to correlation risk.
Credit Risk. It is possible that issuers of debt securities may not make scheduled interest and principal payments, resulting in losses to the Fund. In addition, the credit quality of securities held may be lowered if an issuer’s financial condition changes and this also may negatively impact the Fund’s returns on investment in such securities.
Distribution Policy Risk. The Fund’s distribution policy is expected to result in distributions that equal a fixed percentage of the Fund’s current net asset value per share. All or a portion of a distribution may consist of a return of capital (i.e. from your original investment). Shareholders should not assume that the source of a distribution from the Fund is net profit. Shareholders should note that return of capital will reduce the tax basis of their shares and potentially increase the taxable gain, if any, upon disposition of their shares.
4 |
Fixed Income Risk. Typically, a rise in interest rates causes a decline in the value of fixed income securities. Recently, interest rates have risen sharply after maintaining historically low levels for a significant period of time. Current conditions may result in an increase in interest rate volatility, which in turn may result in a decline in the value of the fixed income investments held by the Fund. As a result, for the present, interest rate risk may be heightened. Fixed income securities are also subject to default risk.
Institutional Investment Fund Risk. The Fund’s investment in Institutional Investment Funds will require it to bear a pro rata share of the vehicles’ expenses, including management and performance fees. The fees the Fund pays to invest in an Institutional Investment Fund may be higher than if the manager of the Institutional Investment Fund managed the Fund’s assets directly. The performance fees charged by certain Institutional Investment Funds may create an incentive for its manager to make investments that are riskier and/or more speculative than those it might have made in the absence of a performance fee. Furthermore, Institutional Investment Funds, like the other “Underlying Funds” in which the Fund may invest, are subject to specific risks, depending on the nature of the vehicle, and also may employ leverage such that their returns are more than one times that of their benchmark which could amplify losses suffered by the Fund when compared to unleveraged investments. Shareholders of the Institutional Investment Funds are not entitled to the protections of the 1940 Act. For example, these funds need not have independent boards, shareholder approval of advisory contracts may not be required, may leverage to an unlimited extent, and may engage in joint transactions with affiliates. These characteristics present additional risks for shareholders.
Issuer and Non-Diversification Risk. The value of a specific security can perform differently from the market as a whole for reasons related to the investment manager or issuer, such as management performance, financial leverage and reduced demand for the respective properties and services. The Fund’s performance may be more sensitive to any single economic, business, political or regulatory occurrence than the value of shares of a diversified investment company because as a non-diversified fund, the Fund may invest more than 5% of its total assets in the securities of one or more issuers.
Lack of Control Over Institutional Investment Funds and Other Portfolio Investments. Once the Advisor or RREEF has selected an Institutional Investment Fund, Private REIT, Public REIT, or Other Public Investment Vehicle (each, an “Underlying Fund” and together, the “Underlying Funds”) for investment by the Fund, the Advisor and RREEF will have no control over the investment decisions made by any such Underlying Fund. Although the Fund and the Advisor or RREEF will evaluate regularly each Underlying Fund and its manager to determine whether their respective investment programs are consistent with the Fund’s investment objective, the Advisor and RREEF will not have any control over the investments made by any Underlying Fund. Even though the Underlying Funds are subject to certain constraints, the managers may change aspects of their investment strategies. The managers may do so at any time (for example, such change may occur immediately after providing the Advisor with the quarterly unaudited financial information for an Institutional Investment Fund). The Advisor or RREEF may reallocate the Fund’s investments among the Underlying Funds, but the Advisor’s ability to do so may be constrained by the withdrawal limitations imposed by certain of the Underlying Funds, which may prevent the Fund from reacting rapidly to market changes should an Underlying Fund fail to effect portfolio changes consistent with such market changes and the demands of the Advisor. Such withdrawal limitations may also restrict the Advisor’s ability to terminate investments in Underlying Funds that are poorly performing or have otherwise had adverse changes. The Advisor and RREEF will be dependent on information provided by the Underlying Fund, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s or RREEF’s ability to manage the Fund’s investment portfolio in accordance with its investment objectives.
Leveraging Risk. The use of leverage, such as borrowing money to purchase securities or otherwise invest the Fund’s assets, will cause the Fund to incur additional expenses and may significantly magnify the Fund’s losses in the event of adverse performance of the Fund’s underlying investments. In addition to any borrowing utilized by the Fund, the Underlying Funds in which the Fund invests may utilize leverage, subject to the limitations of their charters and operative documents. Leverage by Underlying Funds and/or the Fund has the effect of potentially increasing losses. In addition, interest rates (including benchmarks like Secured Overnight Financing Rate (“SOFR”) and the spreads to such benchmarks charged by lenders) are highly sensitive to external factors outside a borrower’s control, including general and local economic conditions (such as inflation, recession, money supply and unemployment) and the monetary and fiscal policies of various governmental agencies such as the Federal Reserve Board. During periods of increased interest rates, borrowing costs of the Fund will likely increase and may adversely affect the Fund’s performance.
Management Risk. The judgments of the Advisor or a Sub-Advisor about the attractiveness, value and potential appreciation of particular real estate segment and securities in which the Fund invests may prove to be incorrect and may not produce the desired results.
Possible Competition Between Underlying Funds and Between the Fund and the Underlying Funds. The Underlying Funds trade independently of each other and may pursue investment strategies that “compete” with each other for execution or that cause the Fund to participate in positions that offset each other (in which case the Fund would bear its pro rata share of commissions and fees without the potential for a profit). Also, the Fund’s investments in any particular Underlying Fund could increase the level of competition for the same trades that other Underlying Funds might otherwise make, including the priorities of order entry. This could make it difficult or impossible to take or liquidate a position in a particular security at a price consistent with the Advisor’s strategy.
Preferred Securities Risk. Preferred securities are subject to credit risk and interest rate risk. Interest rate risk is, in general, that the price of a debt security falls when interest rates rise. Securities with longer maturities tend to be more sensitive to interest rate changes. Credit risk is the risk that an issuer of a security may not be able to make principal and interest or dividend payments on the security as they become. Holders of preferred securities may not receive dividends, or the payment can be deferred for some period of time. In bankruptcy, creditors are generally paid before the holders of preferred securities.
REIT Risk. The value of investments in REIT shares may decline because of adverse developments affecting the real estate industry and real property values. In general, real estate values can be affected by a variety of factors, including supply and demand for properties, the economic health of the country or of different regions, and the strength of specific industries that rent properties. Also, qualification as a REIT under the Internal Revenue Code of 1986, as amended (the “Code”) in any particular year is a complex
5 |
analysis that depends on a number of factors. There can be no assurance that an entity in which the Fund invests with the expectation that it will be taxed as a REIT will, in fact, qualify as a REIT. An entity that fails to qualify as a REIT would be subject to a corporate level tax, would not be entitled to a deduction for dividends paid to its shareholders and would not pass through to its shareholders the character of income earned by the entity.
Repurchase Policy Risks. Quarterly repurchases by the Fund of its shares typically will be funded from available cash or sales of portfolio securities. The sale of securities to fund repurchases could reduce the market price of those securities, which in turn would reduce the Fund’s net asset value.
Underlying Funds Risk. Investments in real estate index funds (“Index Funds”), real estate exchange traded funds (“ETFs”), and Other Public Investment Vehicles are subject to investment advisory and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in such Other Public Investment Vehicles, and also may be higher than other funds that invest directly in securities. Further, Other Public Investment Vehicles are subject to specific risks, depending on the nature of the fund.
Valuation of Institutional Investment Funds. Institutional Investment Funds are not publicly traded and the Fund may consider information provided by the institutional asset manager to determine the value of the Fund’s investment therein. The valuation provided by an institutional asset manager as of a specific date may vary from the actual sale price that may be obtained if such investment were sold to a third party. To determine the value of the Fund’s investment in Institutional Investment Funds, the Advisor considers, among other things, information provided by the Institutional Investment Funds, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s ability to value accurately the Fund’s shares. Institutional Investment Funds that invest primarily in publicly traded securities are more easily valued.
U.S. Federal Income Tax Matters
The Fund intends to elect to be treated and to qualify each year for taxation as a regulated investment company under Subchapter M of the Code. In order for the Fund to so qualify, it must meet an income and asset diversification test each year. If the Fund so qualifies and satisfies the applicable distribution requirements, the Fund (but not its shareholders) will not be subject to federal income tax to the extent it distributes its investment company taxable income and net capital gains (the excess of net long-term capital gains over net short-term capital loss) in a timely manner to its shareholders in the form of dividends or capital gain distributions. The Code imposes a 4% nondeductible excise tax on regulated investment companies, such as the Fund, to the extent they do not meet certain distribution requirements by the end of each calendar year. The Fund anticipates meeting these distribution requirements. See “U.S. Federal Income Tax Matters.”
Distribution Policy
The Fund’s distribution policy is to make quarterly distributions to shareholders. The level of distributions (including any return of capital) is not fixed, but is expected to represent an annual rate of approximately 5.25% of the Fund’s current net asset value per share. However, this distribution policy is subject to change. Unless a shareholder elects otherwise, the shareholder’s distributions will be reinvested in additional shares of the same class under the Fund’s dividend reinvestment policy. Shareholders who elect not to participate in the Fund’s dividend reinvestment policy will receive all distributions in cash paid to the shareholder of record (or, if the shares are held in street or other nominee name, then to such nominee). See “Dividend Reinvestment Policy.”
Custodian
UMB Bank, N.A. (“UMB Bank”) serves as the custodian for the Fund. See “Management of the Fund.”
6 |
SUMMARY OF FUND EXPENSES
Shareholder Transaction Expenses |
Class A |
Maximum
Sales Load |
|
Maximum Early Withdrawal Charge (as a percent of original purchase price)1 |
Annual Expenses (as a percentage of net assets attributable to shares) |
|
Management Fees |
|
Other Expenses |
|
Shareholder Servicing Fee |
|
Distribution Fee |
|
Remaining Other Expenses |
|
Interest Payments on Borrowed Funds2 |
|
Acquired Fund Fees and Expenses |
|
Total Annual Expenses |
|
|
1. |
|
|
2. |
|
The above Summary of Fund Expenses table describes the fees and expenses that you may pay if you buy and hold shares of the Fund. You may qualify for sales charge discounts on purchases of Class A shares if you and your family invest, or agree to invest in the future, at least $100,000 in the Fund. More information about these and other discounts is available from your financial professional and in Purchasing Shares starting on page 30 of this prospectus. More information about management fees, fee waivers and other expenses is available in Management of the Fund starting on page 19 of this prospectus.
The following example illustrates the hypothetical expenses that you would pay on a $1,000 investment assuming annual expenses attributable to shares remain unchanged and shares earn a 5% annual return:
Share Class |
1 Year |
3 Years |
5 Years |
10 Years |
Class A Shares |
$ |
$ |
$ |
$ |
Shareholders who choose to participate in repurchase offers by the Fund will not incur an early withdrawal charge, unless the repurchase is less than 365 days after purchase by a shareholder who purchased in amounts of $1,000,000 or more. However, if shareholders request repurchase proceeds be paid by wire transfer, such shareholders will be assessed an outgoing wire transfer fee at prevailing rates charged by the Transfer Agent, currently $10. The purpose of the above table is to help a holder of shares understand the fees and expenses that such holder would bear directly or indirectly. The example should not be considered a representation of actual future expenses. Actual expenses may be higher or lower than those shown.
7 |
FINANCIAL HIGHLIGHTS
Class A Shares
The financial highlights table below is intended to help you understand the Fund’s financial performance since its inception. Certain information reflects financial results for a single Share. The total returns in the table represent the rate that an investor would have earned (or lost) on an investment in the Fund (assuming reinvestment of all dividends and other distributions). This information has been derived from the Fund’s financial statements, which have been audited by Cohen & Company, Ltd., the Fund’s independent registered public accounting firm, whose report, along with the Fund’s financial statements, is included in the Fund’s Annual Report for the fiscal year ended September 30, 2024, which is available upon request.
|
For the |
For the |
For the |
For the |
For the |
For the |
For the |
For the |
For the |
For the |
||||||||||||||||||||||||||||||
Net asset value, beginning of year |
$ | 30.74 | $ | 37.10 | $ | 32.66 | $ | 29.26 | $ | 30.43 | $ | 30.00 | $ | 29.37 | $ | 29.13 | $ | 28.68 | $ | 27.98 | ||||||||||||||||||||
INCOME FROM INVESTMENT OPERATIONS: |
||||||||||||||||||||||||||||||||||||||||
Net investment income/(loss)(a) |
(0.33 | ) | (0.14 | ) | 0.38 | 0.50 | 0.46 | 0.33 | 0.21 | 0.23 | 0.23 | 0.39 | ||||||||||||||||||||||||||||
Net realized and unrealized gain/(loss) |
(2.40 | ) | (4.45 | ) | 5.97 | 4.50 | (0.05 | ) | 1.69 | 2.00 | 1.56 | 1.75 | 1.81 | |||||||||||||||||||||||||||
Total from investment operations |
(2.73 | ) | (4.59 | ) | 6.35 | 5.00 | 0.41 | 2.02 | 2.21 | 1.79 | 1.98 | 2.20 | ||||||||||||||||||||||||||||
|
||||||||||||||||||||||||||||||||||||||||
DISTRIBUTIONS: |
||||||||||||||||||||||||||||||||||||||||
From net investment income |
— | — | — | — | (0.06 | ) | — | — | — | — | (0.09 | ) | ||||||||||||||||||||||||||||
From net realized gain on investments |
(0.14 | ) | (0.19 | ) | (0.42 | ) | (0.63 | ) | (1.02 | ) | (0.32 | ) | (0.54 | ) | (0.37 | ) | (0.16 | ) | (0.29 | ) | ||||||||||||||||||||
Return of capital |
(1.36 | ) | (1.58 | ) | (1.49 | ) | (0.97 | ) | (0.50 | ) | (1.27 | ) | (1.04 | ) | (1.18 | ) | (1.37 | ) | (1.12 | ) | ||||||||||||||||||||
Total distributions |
(1.50 | ) | (1.77 | ) | (1.91 | ) | (1.60 | ) | (1.58 | ) | (1.59 | ) | (1.58 | ) | (1.55 | ) | (1.53 | ) | (1.50 | ) | ||||||||||||||||||||
Net asset value, end of year |
$ | 26.51 | $ | 30.74 | $ | 37.10 | $ | 32.66 | $ | 29.26 | $ | 30.43 | $ | 30.00 | $ | 29.37 | $ | 29.13 | $ | 28.68 | ||||||||||||||||||||
TOTAL RETURN(b)(c) |
(9.08 | )% | (12.64 | )% | 19.76 | % | 17.68 | % | 1.38 | % | 6.94 | % | 7.69 | % | 6.29 | % | 7.08 | % | 8.06 | % | ||||||||||||||||||||
|
||||||||||||||||||||||||||||||||||||||||
RATIOS/SUPPLEMENTAL DATA: |
||||||||||||||||||||||||||||||||||||||||
Net assets, end of year (000s) |
$ | 654,361 | $ | 815,193 | $ | 921,035 | $ | 573,540 | $ | 525,950 | $ | 536,913 | $ | 373,488 | $ | 291,772 | $ | 226,712 | $ | 129,287 | ||||||||||||||||||||
Ratios to Average Net Assets (including interest expense) |
||||||||||||||||||||||||||||||||||||||||
Ratio of expenses to average net assets excluding fee waivers and reimbursements (d)(e) |
3.82 | % | 3.14 | % | 2.01 | % | 2.09 | % | 2.15 | % | 2.20 | % | 2.43 | % | 2.37 | % | 2.19 | % | 2.25 | % | ||||||||||||||||||||
8 |
|
For the |
For the |
For the |
For the |
For the |
For the |
For the |
For the |
For the |
For the |
||||||||||||||||||||||||||||||
Ratio of expenses to average net assets including fee waivers and reimbursements (e) |
3.82 | % | 3.14 | % | 2.04 | % | 2.06 | % | 2.17 | % | 2.21 | % | 2.37 | % | 2.21 | % | 1.82 | % | 1.79 | % | ||||||||||||||||||||
Ratio of net investment income/(loss) to average net assets(e) |
(1.15 | )% | (0.42 | )% | 1.06 | % | 1.65 | % | 1.53 | % | 1.10 | % | 0.71 | % | 0.80 | % | 0.79 | % | 1.36 | % | ||||||||||||||||||||
|
||||||||||||||||||||||||||||||||||||||||
Ratios to Average Net Assets (excluding interest expense) |
||||||||||||||||||||||||||||||||||||||||
Ratio of expenses to average net assets excluding fee waivers and reimbursements (d)(e) |
1.95 | % | 1.94 | % | 1.92 | % | 1.98 | % | 1.91 | % | 1.94 | % | 1.99 | % | 2.04 | % | 2.19 | % | 2.24 | % | ||||||||||||||||||||
Ratio of expenses to average net assets including fee waivers and reimbursements (e) |
1.95 | % | 1.94 | % | 1.95 | % | 1.95 | % | 1.93 | % | 1.95 | % | 1.93 | % | 1.89 | % | 1.82 | % | 1.78 | % | ||||||||||||||||||||
Portfolio turnover rate |
14 | % | 13 | % | 4 | % | 26 | % | 27 | % | 8 | % | 13 | % | 16 | % | 18 | % | 35 | % | ||||||||||||||||||||
|
(a) |
Per share amounts are calculated using the average shares method. |
|
(b) |
Includes adjustments in accordance with accounting principles generally accepted in the United States and, consequently, the net asset value for financial reporting purposes and the returns based upon those net asset values may differ from the net asset values and returns for shareholder transactions. |
|
(c) |
Total returns are historical in nature and assumes changes in net asset value per share, reinvestment of dividends and capital gains distributions, if any, and do not reflect the impact of sales charges. Had the Advisor not absorbed a portion of the Fund expenses, total returns would have been lower. |
|
(d) |
Represents the ratio of expenses to average net assets absent fee waivers expense reimbursement and/or recoupment by the Advisor. |
|
(e) |
The ratios of expenses to average net assets and net investment income to average net assets do not directly reflect the expenses of the underlying institutional private real estate investments in which the Fund invests. The Fund invests in each underlying institutional private real estate investment based upon its net asset value, inclusive of management fees, which typically range from 0.50% to 1.30% on an annualized basis. The Fund’s Total Return is reported net of all fees and expenses. |
THE FUND
The Fund is a continuously offered, non-diversified, closed-end management investment company that is operated as an interval fund. The Fund was organized as a Delaware statutory trust on May 25, 2012. The Fund’s principal office is located at 919 Third Avenue, 40th Floor, New York, NY 10022, and its telephone number is 1-844-819-8287.
USE OF PROCEEDS
The net proceeds of the Fund’s continuous offering of shares, after payment of the sales load (if applicable) and other associated expenses, will be invested in accordance with the Fund’s investment objective and policies (as stated below) as soon as practicable after receipt. The Fund pays organizational costs and its offering expenses incurred with respect to its initial and continuous offering. Pending investment of the net proceeds in accordance with the Fund’s investment objective and policies, the Fund will invest in money market or short-term fixed-income mutual funds. Investors should expect, therefore, that before the Fund has fully invested the proceeds of the offering in accordance with its investment objective and policies, the Fund’s assets would earn interest income at a modest rate.
9 |
INVESTMENT OBJECTIVE, POLICIES AND STRATEGIES
Investment Objective and Policies
The Fund seeks primarily to generate current income while secondarily seeking long-term capital appreciation with low to moderate volatility and low correlation to the broader markets.
The Fund pursues its investment objectives by investing, under normal circumstances, at least 80% of its net assets, plus the amount of any borrowings for investment purposes, in real estate industry securities, primarily in income producing equity and debt securities. The Fund’s investments may be targeted in any one or more of the many sectors of the real estate market, including but not limited to the retail, office, multifamily, hospitality, industrial, residential, healthcare, life sciences, and self-storage sectors. The Fund concentrates investments in the real estate industry, meaning that under normal circumstances, it invests over 25% of its assets in real estate industry securities. The Fund may utilize leverage through borrowing for investment purposes or to satisfy repurchase requests. The Fund currently borrows money under two credit facilities.
The Fund defines real estate industry securities to include the common stock, partnership or similar interests, asset-backed securities, preferred stock, and secured or unsecured debt. Real estate industry securities may be issued by a wide variety of entities including: private real estate investment funds managed by institutional investment managers (“Institutional Investment Funds”); non-traded unregistered real estate investment trusts (“Private REITs”); publicly traded real estate investment trusts or other similar companies (“Public REITs”); Government Sponsored Entities (“GSEs”) such as Federal Home Loan Mortgage Corporation Structured Pass-Through Certificates (“K-Notes”), exchange traded funds, index mutual funds, and other investment vehicles such as closed-end funds and mutual funds that invest principally, directly or indirectly, in real estate (collectively, “Other Public Investment Vehicles”) and unregistered funds that invest principally in real estate.
The Fund may invest in issuers of real estate industry securities of any credit quality; including fixed-income and preferred securities rated less than investment grade that are sometimes referred to as high yield or “junk bonds.” The Fund may invest in debt securities of any duration or maturity. The Fund may also, to a limited extent, make real estate-related investments other than through real estate industry securities. The Advisor or RREEF will sell a security when other securities are available that offer higher expected current income, higher expected long-term capital appreciation, lower volatility or lower correlation to broader securities markets or a combination of the preceding.
The Fund’s SAI contains a list of the fundamental (those that may not be changed without a shareholder vote) and non-fundamental (if any) investment policies of the Fund under the heading “Investment Objective and Policies.”
Fund’s Target Investment Portfolio
The Advisor executes the Fund’s real estate investment strategy primarily through a strategic combination of global ‘best in class’ Institutional Investment Funds, publicly traded real estate securities, and real estate related debt investments. The Fund will not invest more than 10% of the Fund’s assets in private funds employing hedging strategies (commonly known as “hedge funds”, i.e., investment funds that would be investment companies but for the exemptions under Rule 3(c)(1) or 3(c)(7) under the 1940 Act).
The Advisor has retained Mercer to provide ongoing research and investment opinions of and/or recommendations of institutional investment managers using the Mercer’s proprietary screening process, which applies multiple factors based on quantitative and qualitative assessment of the management team and track record. The Advisor has engaged RREEF to invest a portion of the Fund’s portfolio, generally less than 20%, in publicly traded real estate securities (Public REITs and Other Public Investment Vehicles). RREEF selects securities to seek to maximize risk-adjusted returns by managing volatility and identifying securities that are priced inefficiently relative to its assessment of intrinsic value.
Institutional Investment Funds. Institutional Investment Funds are real estate investment funds managed by institutional investment managers with expertise in managing portfolios of real estate and real estate-related securities. Many Institutional Investment Funds have large minimum investment requirements and stringent investor qualification criteria intended to limit their direct investors to mainly institutions such as endowments and pension funds. It is the intent of the Fund to provide an element of the endowment model of investing to individual investors by permitting access to a portfolio of Institutional Investment Funds with diversification across multiple strategies, managers and sectors.
The Advisor also believes that the Fund may provide an additional benefit in terms of better fee pricing from the Institutional Investment Funds as a result of volume discounts, which pricing benefits may not otherwise be permitted or available to other investors. In addition, the Fund’s investments in Institutional Investment Funds are intended to deliver returns that have a low correlation to the broader markets.
The Fund’s typical investments in Institutional Investment Funds will be made through the purchase of common stock, limited liability company units, or limited partnership interests (or similar interests). Investment criteria will include evaluating a combination of strength of the sponsor and management; prior investment performance of the target fund as well as the performance of other funds managed by the sponsor; the attractiveness of the property sectors and geographical allocations of the fund; expected stability of income; expected capital appreciation, and target leverage levels.
REITs. The Fund may invest, directly or indirectly, in Real Estate Investment Trusts (“REITs”). REITs are investment vehicles that invest primarily in income-producing real estate or mortgages and other real estate-related loans or interests. Public REITs are listed on major stock exchanges such as the New York Stock Exchange (“NYSE”) or the National Association of Securities Dealers Automated Quotation System (“NASDAQ”), and invest directly in real estate, typically through either properties or mortgages.
10 |
Other Public Investment Vehicles. The Fund anticipates making limited investments in Other Public Investment Vehicles, including ETFs and Index Funds that invest primarily in real estate related assets, principally to temporarily invest the Fund’s capital pending its deployment into other higher-returning investment opportunities, or for temporary defensive purposes under adverse market conditions.
Exchange Traded Funds (“ETFs”). ETFs are typically managed by professionals and provide investors with diversification, cost and tax efficiency, liquidity, marginability, are useful for hedging, have the ability to go long and short, and some provide quarterly dividends. An ETF typically holds a portfolio of securities or contracts designed to track a particular market segment or index. ETFs are listed on major stock exchanges and are traded like stocks.
Index Funds. An Index Fund is a mutual fund with an investment objective of seeking to replicate the performance of a specific securities index, such as the National Association of Real Estate Investment Trusts (NAREIT) Index or the MSCI REIT Index. Most Index Funds are not actively managed and generally provide broad market exposure, low operating expenses and low portfolio turnover.
Other. In addition to ETFs and Index Funds, and subject to the Fund’s investment restrictions, the Fund may invest in investment companies that invest primarily in what the Advisor considers real estate industry securities, including closed-end funds and mutual funds. Shares of Closed-end Funds are typically listed for trading on major stock exchanges and, in some cases, may be traded in other over-the-counter markets.
Real Estate Related Debt Investments. The Fund may invest in real estate related direct debt including first and second mortgage loans, mezzanine loans and other structured debt investments.
Investment Strategy, and Criteria Used by the Advisor and Mercer in Selecting Investments
The Fund’s investment strategy focuses primarily on identifying Institutional Investment Funds that have:
|
● |
attractive risk-adjusted returns; |
|
● |
with low to moderate volatility; |
|
● |
low correlation to the broader markets; and |
|
● |
an emphasis on income generation. |
The Fund utilizes a comprehensive multi-manager, multi-sector, and multi-strategy approach. The Advisor primarily selects funds with the highest expected risk-adjusted returns from a real estate sector peer group of issuers with similar market capitalization and/or credit quality. Secondarily, the Advisor considers potential for capital appreciation. When constructing and balancing the Fund’s portfolio, the Advisor selects funds from real estate sectors that it believes have relatively low volatility and will not be highly correlated to each other or to the equity or fixed income markets, generally.
The Advisor, working closely with Mercer and in consideration of its recommendations, uses both a quantitative screening process and a qualitative selection process when selecting investments for the Fund to implement its real estate investment strategy. The Advisor and Mercer conduct research on various real estate investment managers and investment options in order to establish a selection of investments to fulfill the Fund’s investment objectives. Mercer’s assistance and recommendations for selection of investment funds are made according to asset allocation, return expectations and other guidelines set by the Advisor with oversight of the Board. No assurance can be given that any or all investment strategies, or the Fund’s investment program, will be successful.
Investment Strategy – Mercer Process
Mercer’s process begins with a proprietary database created and continuously maintained by its professionals - the Global Investment Manager Database (GIMD™) which gives Mercer access to up-to-date information and insights on a worldwide matrix of investment managers and strategies. GIMD™ contains information on numerous investment types across all asset classes, including real estate. This information ranges from access to and analysis of performance data to qualitative forward-looking research on investment managers supported by screening functionality. In the twelve months leading up to September 30, 2024, over 2,700 formal manager meetings were held and over 3,600 Research Reports were produced globally. As of September 30, 2024, GIMD™ contained information on over 6,800 investment managers and over 32,300 investment strategies.
Mercer, together with its global investment management affiliates, have over 3,300 delegated clients globally.
The Advisor has entered into a Sub-Advisory Agreement with Mercer Investments LLC (“Mercer” or a “Sub-Advisor”), 99 High Street, Boston, MA 02110.
11 |

The Advisor, in conjunction with Mercer, employs a regimen of quantitative and qualitative criteria to arrive at a universe of investments which are considered to be ‘best in class.’ By combining historical quantitative analysis with a sound knowledge of key qualitative attributes, the Advisor will evaluate a prospective investment’s potential for generating sustainable, positive, risk-adjusted returns under a wide variety of market conditions. Mercer’s investment selection and due diligence process are outlined in the chart below.
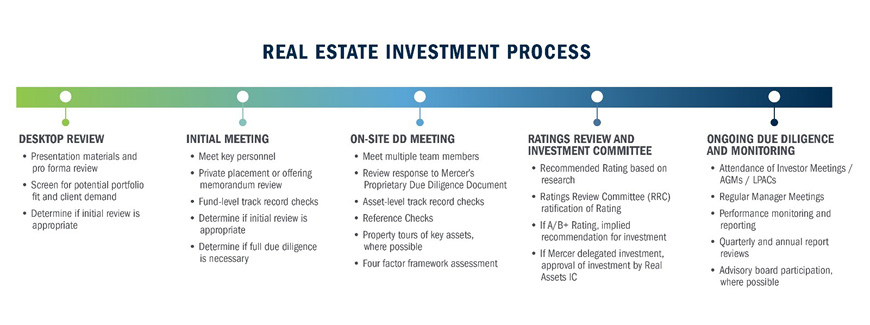
On-going monitoring of the Fund’s investments will be utilized to assist the Advisor in maintaining portfolio allocations and managing cash in-flows and outflows. The Advisor may strategically rebalance its investment strategies according to the current market conditions, but will remain true to its fundamental analysis with respect to real estate asset class and sector risk over time. The
12 |
Advisor manages investments over a long-term time horizon while being mindful of the historical context of the markets. Mercer will provide to the Advisor investment performance reporting and analysis, including discussions on investment strategy, portfolio construction, and market update reports. The illustration below further outlines this monitoring process.

Investment Strategy - Multi-Manager Diversification
The Fund intends to employ a Multi-Manager approach by identifying and investing with ‘best in class’ institutional asset managers with expertise in managing portfolios of real estate and real estate-related securities. The term ‘best in class’ refers to Institutional Investment Funds that the Advisor and Mercer have identified through Mercer’s proprietary screening process as having above average prospects.
Many of the Institutional Investment Funds have large minimum investment size and stringent investor qualification criteria intended to limit their direct investors to mainly institutions such as endowments and pension funds. As such, the Fund enables investors to invest with institutional investment managers that may not be otherwise permitted or available to them.
The Fund also enables investors to execute a comprehensive multi-strategy, multi-manager, multi-sector strategy by making a single investment in its shares, whereas due to the large minimums of many of the Institutional Investment Funds, such a strategy may not otherwise be permitted or available to the investor.
The sponsor believes that the Fund may provide an additional benefit in terms of lower fees from the Institutional Investment Funds as a result of volume discounts, which pricing benefits may not otherwise be permitted or available to them.
Investment Strategy - Multi-Strategy Diversification
The Fund intends to employ a Multi-Strategy approach to diversify the risk-reward profiles and the underlying types of real estate in which it invests, with the strategies noted below. Because each real estate strategy performs differently throughout the overall real estate and economic cycle, investment strategies that include multiple strategies generally have lower volatility than single strategy funds. Thus, a multi-strategy approach should assist the Fund in achieving its objective of lower portfolio volatility as well as lower correlation with the broader markets.
|
● |
Core. The Fund’s ‘core’ strategy targets high-quality portfolios with real estate assets that provide relatively lower and more stable returns. Such investments are typically located in primary markets and in the main property types (retail, office, industrial and multi-family). Properties are stable, well-maintained, well-leased and often of the Class A variety. For example, office properties, including life sciences, tend to be Class A buildings with investment grade tenants. Multifamily properties are usually in major metropolitan cities with higher rental rates. Retail would typically be more traditional neighborhood and community strip-mall centers, as well as regional and super regional malls. The Advisor believes that warehouse and research and development properties in strong distribution centers typically offer better chances for predictable cash flow within the industrial sector. As an example, a Class A office property may broadly be defined as 100,000 square feet or larger (five or more floors), concrete and steel construction, recently built and/or very well maintained (excellent condition), with business/support amenities and in a strong identifiable location with good access to a primary metropolitan market. Class A properties are the most prestigious buildings competing for premier tenants with rents above average for the area. |
|
● |
Core Plus. The Fund’s ‘core plus’ strategy seeks moderate risk portfolios with real estate that provides moderate returns. Such investments are predominantly core but with an emphasis on a modest value add management approach. A core plus portfolio requires slightly more complex financial structuring and management intensive focus than a core portfolio of investments. Focus is on the main property types, in both primary and secondary markets, in Class A or lower quality buildings that require some form of enhancement (i.e. repositioning, redevelopment and/or releasing). In comparison to the Class A example above, a Class B property may be renovated and/or in good condition, potentially smaller in size, in a good location in a primary or secondary metropolitan market. Class B properties compete for a wide range of users with rents in the average range for the area. |
13 |
|
● |
Value Add. The Fund’s ‘value add’ strategy typically focuses on more aggressive active asset management and often employs more leverage. Such investments typically are lower quality buildings, in both primary and secondary markets in the main property types or development projects. Properties are considered value add when they exhibit management or operational problems, require physical improvement, and/or suffer from capital constraints. Buildings often require enhancement to upgrade them to higher quality properties (i.e., redevelopment/repositioning/re-tenanting). |
Investment Strategy - Multi-Sector Diversification
The Fund intends to employ a Multi-Sector approach to diversify its investments by property type or sector - for example, across retail, office, multifamily, hospitality, industrial, residential, healthcare, life sciences and/or self-storage sectors. Because each real estate sector has its own investment cycle, correlations across property types are generally low. Thus, employing a multi-sector approach should assist the Fund in achieving its objective of low to moderate volatility as well as low correlation to the broader markets.
Additional Information Regarding Investment Strategy
The Fund may, from time to time, in attempting to respond to adverse market, economic, political or other similar conditions, take temporary defensive positions that are inconsistent with the Fund’s principal investment strategy. During such times, the Advisor may determine that the Fund should invest up to 100% of its assets in cash or cash equivalents, including money market instruments, prime commercial paper, repurchase agreements, Treasury bills and other short-term obligations of the U.S. Government, its agencies or instrumentalities. In addition to the foregoing, the Fund may utilize Other Public Investment Vehicles as temporary investments as the Fund raises capital or pending deployment of capital to other investment opportunities selected by the Advisor. In these and in other cases, the Fund may not achieve its investment objective. The Advisor may invest the Fund’s cash balances in any investments it deems appropriate. The Advisor expects that such investments will be made, without limitation and as permitted under the 1940 Act, in money market mutual funds, repurchase agreements, U.S. Treasury and U.S. agency securities, municipal bonds and bank accounts. Any income earned from such investments is ordinarily reinvested by the Fund in accordance with its investment program. Many of the considerations entering into recommendations and decisions of the Advisor and the Fund’s Portfolio Managers are subjective.
The frequency and amount of portfolio purchases and sales (known as the “portfolio turnover rate”) will vary from year to year. The portfolio turnover rate is not expected to exceed 100%, but may vary greatly from year to year and will not be a limiting factor if the Advisor determines that portfolio changes are appropriate. Although the Fund generally does not intend to trade for short-term profits, the Fund may engage in short-term trading strategies, and securities may be sold without regard to the length of time held when, in the opinion of the Advisor, investment considerations warrant such action. These policies may have the effect of increasing the annual rate of portfolio turnover of the Fund. Higher rates of portfolio turnover would likely result in higher brokerage commissions and may generate short-term capital gains taxable as ordinary income. If securities are not held for the applicable holding periods, dividends paid on them will not qualify for the advantageous federal tax rates. See “Tax Status” in the Fund’s SAI.
There is no assurance what portion, if any, of the Fund’s investments will qualify for the reduced federal income tax rates applicable to qualified dividends under the Code. As a result, there can be no assurance as to what portion of the Fund’s distributions will be designated as qualified dividend income. See “U.S. Federal Income Tax Matters.”
Investment Strategy and Criteria Used by RREEF in Selecting Public Real Estate Securities
The Advisor with RREEF has developed an investment strategy intended to maximize risk-adjusted returns by managing volatility and identifying securities that are priced inefficiently relative to RREEF’s assessment of intrinsic value. RREEF believes that real estate security performance is reflective of the underlying real estate portfolio and, therefore, over time will be driven by the pricing and fundamentals of their assets. The risk management process is highly focused on quantitative risk factors as well as fundamental portfolio risk factors. RREEF’s investment universe encompasses over 100 property companies in the United States with a total market capitalization of over $800 billion. RREEF is focused on companies that derive the majority of their operating income or asset base from commercial real estate (apartments, office, industrial, storage, hotels, retail, net lease). Operating and capital efficiency are critically important to a successful real estate company and hence RREEF typically focuses on companies with large, high quality asset bases. If there are securities outside of this group that meet these criteria, RREEF will include these as part of the investable universe. The investment universe is generally defined as all REITs and REOCs (real estate operating companies) with an equity market capitalization of at least $200 million that derive the majority of revenue or net asset value (NAV) from an equity interest in real estate activities. The U.S. real estate securities portion of the Fund’s portfolio managed by RREEF typically holds between 35-50 securities. Under normal circumstances, such securities will generally comprise between 5% and 20% of the Fund’s portfolio. With respect to any investments in non-publicly traded real estate related debt securities, the Advisor makes all investment decisions.
RISK FACTORS
An investment in the Fund’s shares is subject to risks. The value of the Fund’s investments will increase or decrease based on changes in the prices of the investments it holds. This will cause the value of the Fund’s shares to increase or decrease. You could lose money by investing in the Fund. By itself, the Fund does not constitute a balanced investment program. Before investing in the Fund you should consider carefully the following risks. There may be additional risks that the Fund does not currently foresee or consider material. You may wish to consult with your legal or tax advisors before deciding whether to invest in the Fund.
Real Estate Industry Concentration Risk. Because the Fund will concentrate its investments in real estate related securities, its portfolio will be significantly impacted by the performance of the real estate market and may experience more volatility and be exposed to greater risk than a more diversified portfolio. In addition, the Fund may invest in real estate equity or debt and therefore may be subject to risks similar to those associated with direct investment in real property. The value of the Fund’s shares will be affected by factors affecting the value of real estate and the earnings of companies engaged in the real estate industry. These factors
14 |
include, among others: (i) changes in general economic and market conditions; (ii) changes in the value of real estate properties; (iii) risks related to local economic conditions, overbuilding and increased competition; (iv) increases in property taxes and operating expenses; (v) changes in zoning laws; (vi) casualty and condemnation losses; (vii) variations in rental income, neighborhood values or the appeal of property to tenants; (viii) the availability of financing; (ix) climate change and (x) changes in interest rates. Many real estate companies utilize leverage, which increases investment risk and could adversely affect a company’s operations and market value in periods of rising interest rates. The value of securities of companies in the real estate industry may go through cycles of relative under-performance and over-performance in comparison to equity securities markets in general.
There are also special risks associated with particular sectors, or real estate operations, including, but not limited to, those risks described below:
Retail Properties. Retail properties are affected by the overall health of the economy and may be adversely affected by, among other things, the growth of alternative forms of retailing, bankruptcy, departure or cessation of operations of a tenant, a shift in consumer demand due to demographic changes, changes in spending patterns and lease terminations.
Office Properties. Office properties are affected by the overall health of the economy, and other factors such as a downturn in the businesses operated by their tenants, obsolescence and non-competitiveness.
Industrial Properties. Industrial properties are affected by the overall health of the economy and other factors such as downturns in the manufacturing, processing and shipping of goods.
Hospitality Properties. The risks of hotel, motel and similar hospitality properties include, among other things, the necessity of a high level of continuing capital expenditures, competition, increases in operating costs which may not be offset by increases in revenues, dependence on business and commercial travelers and tourism, increases in fuel costs and other expenses of travel, and adverse effects of general and local economic conditions. Hotel properties tend to be more sensitive to adverse economic conditions and competition than many other commercial properties.
Healthcare and Life Sciences Properties. Healthcare and life sciences properties and healthcare providers are affected by several significant factors, including federal, state and local laws governing licenses, certification, adequacy of care, pharmaceutical distribution, rates, equipment, personnel and other factors regarding operations, funding for biotech companies, continued availability of revenue from government reimbursement programs and competition on a local and regional basis. The failure of any healthcare operator to comply with governmental laws and regulations may affect its ability to operate its facility or receive government reimbursements.
Multifamily Properties. The value and successful operation of a multifamily property may be affected by a number of factors such as the location of the property, the ability of the management team, the level of mortgage interest rates, the presence of competing properties, adverse economic conditions in the locale, oversupply and rent control laws or other laws affecting such properties.
Residential Properties. Residential properties can be significantly affected by the national, regional and local real estate markets. This segment of the real estate industry also is sensitive to interest rate fluctuations which can cause changes in the availability of mortgage capital and directly affect the purchasing power of potential homebuyers. Thus, residential properties can be significantly affected by changes in government spending, consumer confidence, demographic patterns and the level of new and existing home sales.
Shopping Centers. Shopping center properties are dependent upon the successful operations and financial condition of their tenants, particularly certain of their major tenants, and could be adversely affected by bankruptcy of those tenants. In some cases, a tenant may lease a significant portion of the space in one center, and the filing of bankruptcy could cause significant revenue loss, including the loss of revenue from smaller tenants with co-tenancy rights. Like others in the commercial real estate industry, community centers are subject to environmental risks and interest rate risk. They also face the need to enter into new leases or renew leases on favorable terms to generate rental revenues. Community center properties could be adversely affected by changes in the local markets where their properties are located, as well as by adverse changes in national economic and market conditions.
Self-Storage Properties. The value and successful operation of a self-storage property may be affected by a number of factors, such as the ability of the management team, the location of the property, the presence of competing properties, changes in traffic patterns and effects of general and local economic conditions with respect to rental rates and occupancy levels.
Other factors may contribute to the risk of real estate investments:
Development Issues. Certain real estate companies in which the Fund directly or indirectly invests (“portfolio companies”) may engage in the development or construction of real estate properties. Portfolio companies are exposed to a variety of risks inherent in real estate development and construction, such as the risk that there will be insufficient tenant demand to occupy newly developed properties, and the risk that prices of construction materials or construction labor may rise materially during the development.
Lack of Insurance. Certain of the portfolio companies in the Fund’s portfolio may fail to carry comprehensive liability, fire, flood, earthquake extended coverage and rental loss insurance, or insurance in place may be subject to various policy specifications, limits and deductibles. Due to the prevalence of catastrophic events, the cost of insurance may increase materially. Should any type of uninsured loss occur, the portfolio company could lose its investment in, and anticipated profits and cash flows from, a number of properties and, as a result, adversely affect the Fund’s investment performance.
15 |
Dependence on Tenants. The value of the Fund’s portfolio companies’ properties and the ability of these companies to make distributions to their shareholders depends upon the ability of the tenants at the properties to generate enough income in excess of their tenant operating expenses to make their lease payments. Changes beyond the control of our portfolio companies may adversely affect their tenants’ ability to make their lease payments and, in such event, would substantially reduce both their income from operations and ability to make distributions to our portfolio companies and, consequently, the Fund.
Financial Leverage. Companies in the real estate industry may be highly leveraged and financial covenants may affect their ability to operate effectively. The use of floating rate loans may also negatively impact returns in a rising interest rate environment.
Environmental Issues. In connection with the ownership (direct or indirect), operation, management and development of real properties that may contain hazardous or toxic substances, a portfolio company may be considered an owner, operator or responsible party of such properties and, therefore, may be potentially liable for removal or remediation costs, as well as certain other costs, including governmental fines and liabilities for injuries to persons and property. The existence of any such material environmental liability could have a material adverse effect on the results of operations and cash flow of any such portfolio company and, as a result, the amount available to make distributions on shares of the Fund could be reduced. Environmental risk from high winds, hurricanes, fires, flood and extreme heat may also materially affect a property’s value.
Credit Market Conditions. Instability in credit markets can potentially make it more difficult for borrowers to obtain financing or refinancing on attractive terms or at all. Conditions in the credit markets may expose borrowers to increased interest expenses for borrowed money and tightening underwriting standards. There is also a risk that a general lack of liquidity or other events in the credit markets may adversely affect the ability of issuers in whose securities the Fund invests to finance real estate developments and projects or refinance completed projects.
This may also adversely affect the price at which portfolio companies can sell real estate, because purchasers may not be able to obtain financing on attractive terms or at all. These developments may potentially adversely affect the broader economy, which in turn may adversely affect the real estate markets. Additionally, such developments could reduce the Fund’s investment opportunities.
Market Risk. An investment in shares is subject to investment risk, including the possible loss of the entire principal amount invested. An investment in shares represents an indirect investment in the securities owned by the Fund. The value of these securities, like other market investments, may move up or down, sometimes rapidly and unpredictably. In addition, the Fund is subject to the risk that geopolitical and other similar events will disrupt the economy on a national or global level. For instance, war, terrorism, market manipulation, government defaults, government shutdowns, political changes or diplomatic developments, public health emergencies (such as the spread of infectious diseases, pandemics and epidemics) and natural/environmental disasters can all negatively impact the securities markets.
Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. The foregoing could impair the Fund’s ability to maintain operational standards, disrupt the operations of the Fund and its service providers, adversely affect the performance, value and liquidity of the Fund’s investments, and negatively impact the Fund’s performance and your investment in the Fund. The value of your shares at any point in time may be worth less than the value of your original investment, even after taking into account any reinvestment of dividends and distributions.
Liquidity Risk. The Fund is a closed-end investment company structured as an “interval fund” and is designed for medium to long-term investors. Unlike many closed-end investment companies, the Fund’s shares are not listed on any securities exchange and are not publicly traded. There currently is no secondary market for the shares and the Advisor does not expect that a secondary market will develop. Limited liquidity is provided to shareholders only through the Fund’s quarterly repurchase offers for no less than 5% of the Fund’s shares outstanding at per-class net asset value. There is no guarantee that shareholders will be able to sell all of the shares they desire in a quarterly repurchase offer. Since inception, the Fund has made 44 repurchase offers, 37 have resulted in the repurchase of all shares, seven have resulted in the repurchase of less than all shares tendered. The Fund’s investments are also subject to liquidity risk. Liquidity risk exists when particular investments of the Fund would be difficult to purchase or sell, possibly preventing the Fund from selling such illiquid securities at an advantageous time or price, or possibly requiring the Fund to dispose of other investments at unfavorable times or prices in order to satisfy its obligations. Funds with principal investment strategies that involve securities of companies with smaller market capitalizations, derivatives or securities with substantial market and/or credit risk tend to have the greatest exposure to liquidity risk.
Allocation Risk. The ability of the Fund to achieve its investment objective depends, in part, on the ability of the Advisor or RREEF to allocate effectively the Fund’s assets among the various Institutional Investment Funds, Private REITs, Public REITs and Other Public Investment Vehicles in which the Fund invests and, with respect to each such asset class, among equities and fixed income securities. There can be no assurance that the actual allocations will be effective in achieving the Fund’s investment objectives or delivering positive returns.
Correlation Risk. The Fund seeks to produce returns that are not correlated to the broader financial markets. Although the prices of equity securities and fixed-income securities, as well as other asset classes, often rise and fall at different times so that a fall in the price of one may be offset by a rise in the price of the other, in down markets the prices of these securities and asset classes can also fall in tandem. Because the Fund allocates its investments among different asset classes, the fund is subject to correlation risk.
Credit Risk. There is a risk that debt issuers will not make payments, resulting in losses to the Fund. In addition, the credit quality of securities may be lowered if an issuer’s financial condition changes. Lower credit quality may lead to greater volatility in the price of a security and in shares of the Fund. Lower credit quality also may affect liquidity and make it difficult to sell the security. Default,
16 |
or the market’s perception that an issuer is likely to default, could reduce the value and liquidity of securities, thereby reducing the value of your investment in Fund shares. In addition, default may cause the Fund to incur expenses in seeking recovery of principal or interest on its portfolio holdings.
Distribution Policy Risk. The Fund’s distribution policy is expected to result in distributions that equal a fixed percentage of the Fund’s current net asset value per share. Shareholders receiving periodic payments from the Fund may be under the impression that they are receiving net profits. However, all or a portion of a distribution may consist of a return of capital. Return of capital is the portion of a distribution that is a return of your original investment dollars in the Fund. Shareholders should not assume that the source of a distribution from the Fund is net profit. Shareholders should note that return of capital will reduce the tax basis of their shares and potentially increase the taxable gain, if any, upon disposition of their shares.
Fixed Income Risk. When the Fund invests in fixed income securities, the value of your investment in the Fund will fluctuate with changes in interest rates. Typically, a rise in interest rates causes a decline in the value of fixed income securities. In general, the market price of debt securities with longer maturities will increase or decrease more in response to changes in interest rates than shorter-term securities. Recently, interest rates have risen sharply after maintaining historically low levels for a significant period of time. Current conditions may result in an increase in interest rate volatility, which in turn may result in a decline in the value of the fixed income investments held by the Fund. As a result, for the present, interest rate risk may be heightened. Other risk factors include credit risk (the debtor may default) and prepayment risk (the debtor may pay its obligation early, reducing the amount of interest payments). These risks could affect the value of a particular investment, possibly causing the Fund’s share price and total return to be reduced and fluctuate more than other types of investments.
Institutional Investment Fund Risk. The Fund’s investment in Institutional Investment Funds will require it to bear a pro rata share of the vehicles’ expenses, including management and performance fees. The fees the Fund pays to invest in an Institutional Investment Fund may be higher than if the manager of the Institutional Investment Fund, managed the Fund’s assets directly. The incentive fees charged by certain Institutional Investment Funds may create an incentive for its manager to make investments that are riskier and/or more speculative than those it might have made in the absence of an incentive fee. The Funds are not publicly traded and therefore may not be as liquid as other types of investments. Furthermore, Institutional Investment Funds, like the other Underlying Funds in which the Fund may invest, are subject to specific risks, depending on the nature of the vehicle and also may employ leverage such that their returns are more than one times that of their benchmark which will amplify losses suffered by the Fund when compared to unleveraged investments. For example, these Funds need not have independent boards, shareholder approval of advisory contracts may not be required, may leverage to an unlimited extent, and may engage in joint transactions with affiliates.
Issuer and Non-Diversification Risk. The value of a specific security can be more volatile than the market as a whole and can perform differently from the value of the market as a whole. As a non-diversified fund, the Fund may invest more than 5% of its total assets in the securities of one or more issuers. The Fund’s performance may be more sensitive to any single economic, business, political or regulatory occurrence than the value of shares of a diversified investment company. The value of an issuer’s securities that are held in the Fund’s portfolio may decline for a number of reasons which directly relate to the issuer, such as management performance, financial leverage and reduced demand for the respective properties and services.
Lack of Control Over Institutional Investment Funds and Other Portfolio Investments. Once the Advisor or RREEF has selected an Underlying Fund for investment by the Fund, the Advisor and RREEF will have no control over the investment decisions made by any such Underlying Fund. Although the Advisor or RREEF will evaluate regularly each Underlying Fund and its manager to determine whether their respective investment programs are consistent with the Fund’s investment objective, the Advisor and RREEF will not have any control over the investments made by any Underlying Fund. Even though the Underlying Funds are subject to certain constraints, the managers may change aspects of their investment strategies. The managers may do so at any time (for example, such change may occur immediately after providing the Advisor with the quarterly unaudited financial information for an Institutional Investment Fund). The Advisor or RREEF may reallocate the Fund’s investments among the Underlying Funds, but the Advisor’s ability to do so may be constrained by the withdrawal limitations imposed by certain Underlying Funds, which may prevent the Fund from reacting rapidly to market changes should an Underlying Fund fail to effect portfolio changes consistent with such market changes and the demands of the Advisor. Such withdrawal limitations may also restrict the Advisor’s ability to terminate investments in Underlying Funds that are poorly performing or have otherwise had adverse changes. The Advisor and RREEF will be dependent on information provided by the Underlying Fund, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s or RREEF’s ability to manage the Fund’s investment portfolio in accordance with its investment objectives.
Leveraging Risk. The use of leverage, such as borrowing money to purchase securities or otherwise invest the Fund’s assets, will cause the Fund to incur additional expenses and may significantly magnify the Fund’s losses in the event of adverse performance of the Fund’s underlying investments. In addition to any borrowing utilized by the Fund, the Underlying Funds in which the Fund invests may utilize leverage, subject to the limitations of their charters and operative documents. Leverage by Underlying Funds and/or the Fund has the effect of potentially increasing losses. In addition, interest rates (including benchmarks like SOFR and the spreads to such benchmarks charged by lenders) are highly sensitive to external factors outside a borrower’s control, including general and local economic conditions (such as inflation, recession, money supply and unemployment) and the monetary and fiscal policies of various governmental agencies such as the Federal Reserve Board. During periods of increased interest rates, borrowing costs of the Fund will likely increase and may adversely affect the Fund’s performance.
Management Risk. The net asset value of the Fund changes daily based on the performance of the securities in which it invests. The Advisor’s or a Sub-Advisor’s judgments about the attractiveness, value and potential appreciation of particular real estate segment and securities in which the Fund invests may prove to be incorrect and may not produce the desired results.
17 |
Possible Competition Between Underlying Funds and Between the Fund and the Underlying Funds. The Underlying Funds trade independently of each other and may pursue investment strategies that “compete” with each other for execution or that cause the Fund to participate in positions that offset each other (in which case the Fund would bear its pro rata share of commissions and fees without the potential for a profit). Also, the Fund’s investments in any particular Underlying Fund could increase the level of competition for the same trades that other Underlying Funds might otherwise make, including the priorities of order entry. This could make it difficult or impossible to take or liquidate a position in a particular security at a price consistent with the Advisor’s or a Sub-Advisor’s strategy.
Preferred Securities Risk. There are various risks associated with investing in preferred securities, including credit risk, interest rate risk, deferral and omission of distributions, subordination to bonds and other debt securities in a company’s capital structure, limited liquidity, limited voting rights and special redemption rights. Interest rate risk is, in general, that the price of a debt security falls when interest rates rise. Securities with longer maturities tend to be more sensitive to interest rate changes. Credit risk is the risk that an issuer of a security may not be able to make principal and interest or dividend payments on the security as they become. Holders or preferred securities may not receive dividends, or the payment can be deferred for some period of time. In bankruptcy, creditors are generally paid before the holders of preferred securities.
REIT Risk. Investments (directly or indirectly) in REITs will subject the Fund to various risks. REIT share prices may decline because of adverse developments affecting the real estate industry and real property values. In general, real estate values can be affected by a variety of factors, including supply and demand for properties, the economic health of the country or of different regions, and the strength of specific industries that rent properties. REITs often invest in highly leveraged properties. Returns from REITs, which typically are small or medium capitalization stocks, may trail returns from the overall stock market. In addition, changes in interest rates may hurt real estate values or make REIT shares less attractive than other income-producing investments. REITs are also subject to heavy cash flow dependency, defaults by borrowers and self-liquidation.
Qualification as a REIT under the Internal Revenue Code of 1986, as amended, in any particular year is a complex analysis that depends on a number of factors. There can be no assurance that an entity in which the Fund invests with the expectation that it will be taxed as a REIT will, in fact, qualify as a REIT. An entity that fails to qualify as a REIT would be subject to a corporate level tax, would not be entitled to a deduction for dividends paid to its shareholders and would not pass through to its shareholders the character of income earned by the entity. If the Fund were to invest in an entity that failed to qualify as a REIT, such failure could significantly reduce the Fund’s yield on that investment. REITs can be classified as equity REITs, mortgage REITs and hybrid REITs. Equity REITs invest primarily in real property and earn rental income from leasing those properties. They may also realize gains or losses from the sale of properties. Equity REITs will be affected by conditions in the real estate rental market and by changes in the value of the properties they own. Mortgage REITs invest primarily in mortgages and similar real estate interests and receive interest payments from the owners of the mortgaged properties. Mortgage REITs will be affected by changes in creditworthiness of borrowers and changes in interest rates. Hybrid REITs invest both in real property and in mortgages. Equity and mortgage REITs are dependent upon management skills, may not be diversified and are subject to the risks of financing projects.
Dividends paid by REITs will not generally qualify for the reduced U.S. federal income tax rates applicable to qualified dividends under the Code. See “U.S. Federal Income Tax Matters.” The Fund’s investments in REITs may include an additional risk to shareholders. Some or all of a REIT’s annual distributions to its investors may constitute a non-taxable return of capital. Any such return of capital will generally reduce the Fund’s basis in the REIT investment, but not below zero. To the extent the distributions from a particular REIT exceed the Fund’s basis in such REIT, the Fund will generally recognize gain. In part because REIT distributions often include a nontaxable return of capital, Fund distributions to shareholders may also include a nontaxable return of capital. Shareholders that receive such a distribution will also reduce their tax basis in their shares of the Fund, but not below zero. To the extent the distribution exceeds a shareholder’s basis in the Fund’s shares, such shareholder will generally recognize a capital gain. The Fund does not have any investment restrictions with respect to investments in REITs.
Repurchase Policy Risks. Quarterly repurchases by the Fund of its shares typically will be funded from available cash or sales of portfolio securities. However, payment for repurchased shares may require the Fund to liquidate portfolio holdings earlier than the Advisor otherwise would liquidate such holdings, potentially resulting in losses, and may increase the Fund’s portfolio turnover. The Advisor may take measures to attempt to avoid or minimize such potential losses and turnover, and instead of liquidating portfolio holdings, may borrow money to finance repurchases of shares. If the Fund borrows to finance repurchases, interest on any such borrowing will negatively affect shareholders who do not tender their shares in a repurchase offer by increasing the Fund’s expenses and reducing any net investment income. To the extent the Fund finances repurchase proceeds by selling investments, the Fund may hold a larger proportion of its net assets in less liquid securities. Also, the sale of securities to fund repurchases could reduce the market price of those securities, which in turn would reduce the Fund’s net asset value.
Repurchase of shares will tend to reduce the number of outstanding shares and, depending upon the Fund’s investment performance, its net assets. A reduction in the Fund’s net assets may increase the Fund’s expense ratio, to the extent that additional shares are not sold. In addition, the repurchase of shares by the Fund may be a taxable event to shareholders.
Underlying Funds Risk. Other Public Investment Vehicles such as ETFs, Index Funds, closed-end funds, and mutual funds in which the Fund may invest are subject to investment advisory fees and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in such Underlying Funds and also may be higher than other funds that invest directly in securities. Underlying Funds are subject to specific risks, depending on the nature of the fund. The Fund’s performance depends in part upon the performance of the Underlying Fund managers and selected strategies, the adherence by such Underlying Fund managers to such selected strategies, the instruments used by such Underlying Fund managers and the Advisor’s or a Sub-Advisor’s ability to select Underlying Fund managers and strategies and effectively allocate Fund assets among them. Additionally, the market value of shares of Underlying Funds that are closed-end funds typically trade at a discount relative to their net asset value. This difference in price may be due to the fact that the supply and demand in the market for fund shares at any point in time is not always identical to the supply and demand in the market for the underlying basket of securities.
18 |
ETF shares may trade at a discount or a premium in market price if there is a limited market in such shares. Transactions in shares of closed-end funds and ETFs are also subject to brokerage and other trading costs, which could result in greater expenses to the Fund. Investments in pooled investment vehicles also may be illiquid, making it difficult for the Advisor to redeem the interest of the Fund in such vehicles in a reasonable amount of time.
Valuation of Institutional Investment Funds. While the valuations of the Fund’s investments in publicly-traded securities are more readily ascertainable, the Fund’s ownership interests in Institutional Investment Funds are not publicly traded and the Fund will depend on the institutional asset manager to a Private Investment Fund to provide a valuation of the Fund’s investment. Moreover, the valuation of the Fund’s investment in an Institutional Investment Fund, as provided by an institutional asset manager as of a specific date, may vary from the fair value of the investment that may be obtained if such investment were sold to a third party. For information about the value of the Fund’s investment in Institutional Investment Funds, the Advisor will be dependent on information provided by the Institutional Investment Funds, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s ability to accurately value the Fund’s shares.
MANAGEMENT OF THE FUND
Trustees and Officers
The Board is responsible for the overall management of the Fund, including supervision of the duties performed by the Advisor. The Board is comprised of five trustees. The Trustees are responsible for the Fund’s overall management, including adopting the investment and other policies of the Fund, electing and replacing officers and selecting and supervising the Fund’s investment advisor. The name and business address of the Trustees and officers of the Fund and their principal occupations and other affiliations during the past five years, as well as a description of committees of the Board, are set forth under “Management” in the Statement of Additional Information.
Investment Advisor
Bluerock Fund Advisors, LLC, located at 919 Third Avenue, 40th Floor, New York, NY 10022, serves as the Fund’s investment advisor. The Advisor is registered with the SEC as an investment advisor under the Advisers Act. The Advisor is a Delaware limited liability company formed on May 11, 2012.
Under the general supervision of the Fund’s Board, and pursuant to the terms of an Investment Management Agreement with the Fund, the Advisor will carry out the investment and reinvestment of the net assets of the Fund, will furnish continuously an investment program with respect to the Fund, and determine which securities should be purchased, sold or exchanged. In addition, the Advisor will supervise and provide oversight of the Fund’s service providers. The Advisor will furnish to the Fund office facilities, equipment and personnel for servicing the management of the Fund. The Advisor will compensate all Advisor personnel who provide services to the Fund. In return for these services, facilities and payments, the Fund has agreed to pay the Advisor, as compensation under the Investment Management Agreement, a monthly management fee computed at the annual rate of 1.50% of the daily net assets of the Fund. The Advisor may employ research services and service providers to assist in the Advisor’s market analysis and investment selection.
The Advisor and the Fund have entered into an expense limitation and reimbursement agreement (the “Expense Limitation Agreement”) under which the Advisor has agreed contractually to waive its fees and to pay or absorb the ordinary operating expenses (excluding any taxes, interest, brokerage commissions, acquired fund fees and expenses, and extraordinary expenses, such as litigation or reorganization costs, but including organizational costs and offering costs), to the extent that such expenses exceed 1.95% per annum of the Fund’s average daily net assets attributable to Class A shares (the “Expense Limitation”). In consideration of the Advisor’s agreement to limit the Fund’s expenses, the Fund has agreed to repay the Advisor in the amount of any fees the Advisor previously waived or Fund expenses reimbursed, subject to the limitations that: (1) the reimbursement will be made if payable not more than three years from the date incurred; (2) the reimbursement may not be made if it would cause the Expense Limitation then in effect or in effect at the time of the waiver to be exceeded; and (3) the reimbursement is approved by the Board. The Expense Limitation Agreement will remain in effect, at least until January 31, 2026, unless and until the Board approves its modification or termination. This agreement may be terminated only by the Board on 60 days written notice to the Advisor. After January 31, 2026, the Expense Limitation Agreement may be renewed at the Advisor’s and Board’s discretion.
A discussion regarding the basis for the Board’s approval of each of the Fund’s Investment Management Agreement with the Advisor and Sub-Advisory Agreements with Mercer and RREEF is available annually in the Fund’s March 31 semi-annual report to shareholders.
Affiliated Brokerage
Bluerock Capital Markets, LLC (“BCM”), a registered broker-dealer and an affiliate of the Advisor, is paid a portion of the sales load, up to 0.75% of the offering price, charged on the sale of Class A shares.
Advisor’s Investment Committee
The Advisor has established an Investment Committee comprised of five persons (the “Committee”) responsible for: setting overall investment policies and strategies of the Advisor; approval of Institutional Investment Funds being considered for investment by the Fund; establishing allocation targets for the investment portfolio of the Fund among the Institutional Investment Funds, Other Public Investment Vehicles and other entities in which the Fund intends to invest; and generally overseeing the activities of the Advisor’s Portfolio Managers (see below).
19 |
The members of the Committee, and their professional background and experience, are as follows:
R. Ramin Kamfar — Mr. Kamfar has served as a member of the Investment Committee and as Chairman of the Advisor since the inception of the Advisor in 2012. In addition, Mr. Kamfar is the founder of and serves as the Chairman and Chief Executive Officer of Bluerock Real Estate, LLC (“BRRE”), since its founding in October 2002. Mr. Kamfar served as Chairman and CEO of Bluerock Residential Growth REIT, a publicly traded REIT listed on the NYSE American (“BRG”), from its founding in 2009 until its sale in 2022. Mr. Kamfar currently serves as Chairman and CEO of Bluerock Homes Trust, a publicly traded REIT listed on the NYSE American (“BHM”) since its spin-off from BRG in 2022, as well as Chairman of Bluerock Asset Management, LLC since 2018. Mr. Kamfar started his career as an investment banker at Lehman Brothers Inc. in 1988, and has 30 years of experience in various aspects of real estate, mergers and acquisitions, private equity investing, investment banking, and public and private financings. Mr. Kamfar received an M.B.A. degree with distinction in Finance in 1988 from The Wharton School of the University of Pennsylvania and a B.S. degree with distinction in Finance in 1985 from the University of Maryland, College Park.
James G. Babb, III — Mr. Babb has served as a member of the Investment Committee since the inception of the Advisor in 2012. In addition, Mr. Babb has served in a variety of senior capacities, including his current role as Chief Strategy Officer, at BRRE, which he joined in 2007. Mr. Babb served as Chief Investment Officer of BRG from its founding in 2009 to 2020, as Chief Strategy Officer from 2020 until its sale in 2022 and as a Director of BRG from 2009 to 2014. Mr. Babb currently serves as Chief Strategy Officer of BHM. Mr. Babb was a founding principal of Starwood Capital Group (“Starwood”), a leading institutional real estate investment manager, where he helped lead the residential and office acquisitions initiatives from 1992 to 2003. During Mr. Babb’s tenure Starwood raised and invested funds on behalf of institutional investors through seven private real estate funds, and which in the aggregate ultimately invested approximately $8 billion in approximately 250 separate transactions. Mr. Babb also led Starwood’s efforts to expand its platform to invest in England and France. Mr. Babb received a B.A. degree in Economics in 1987 from the University of North Carolina, Chapel Hill.
Jordan B. Ruddy — Mr. Ruddy currently serves as Co-CIO of the Advisor and Portfolio Manager of the Fund. Mr. Ruddy has served as a member of the Investment Committee and as President of the Advisor since the inception of the Advisor in 2012. Mr. Ruddy also serves as president of Bluerock Asset Management, LLC. Mr. Ruddy served in several senior capacities of BRG from its founding in 2009 until its sale in 2022 and currently serves as President of BHM. Mr. Ruddy brings approximately 30 years of institutional real estate investment experience working with some of leading public and private firms in the industry. Prior to joining Bluerock, Mr. Ruddy served as a real estate investment banker at Banc of America Securities LLC, and at Smith Barney Inc. and at JP Morgan Chase (previously the Chase Manhattan Bank), and as Vice President of Amerimar Enterprises, a real estate company specializing in value-added investments nationwide. Mr. Ruddy received an M.B.A. degree in Finance and Real Estate in 1995 from The Wharton School of the University of Pennsylvania, and a B.S. degree with high honors in Economics in 1986 from the London School of Economics.
Ryan MacDonald — Mr. MacDonald has served as a member of the Investment Committee of the Advisor since January 2018. Mr. MacDonald currently serves as Chief Investment Officer for BHM and of BRRE and certain of its affiliates. Mr. MacDonald served in a variety of senior capacities for BRG, including Chief Investment Officer from 2020 until its sale. Since joining Bluerock in 2008, Mr. MacDonald is responsible for sourcing, underwriting, structuring, financing and closing of all of Bluerock’s real estate investments and dispositions. To date with Bluerock, Mr. MacDonald has been involved with real estate transactions with an aggregate value of approximately $11 billion. Prior to joining Bluerock, Mr. MacDonald was an Investment Analyst for PNC Realty Investors. Mr. MacDonald received a B.A. in Economics from the University of Maryland, College Park.
Adam Lotterman — Mr. Lotterman is co-founder of the Advisor and has been a key member of the Fund’s investment team since its inception in 2012. Mr. Lotterman currently serves as the Fund’s Senior Portfolio Manager, as well as the Advisor’s Co-Chief Investment Officer and Lead Economist. Prior to joining Bluerock, Mr. Lotterman was Vice President of Forman Capital, a private commercial real estate lender from 2011 to 2012. Mr. Lotterman was also an Adjunct Professor at Nova Southeastern University from 2010 to 2012, where he taught a master’s level course in Real Estate Market Analysis. Prior to that, Mr. Lotterman worked as a Senior Valuation Analyst at Bayview Asset Management (former hedge fund affiliate of The Blackstone Group) from 2010 to 2011, and from 2005 to 2010 Mr. Lotterman was the Senior Analyst for Goodkin Consulting, the former real estate consulting arm of PricewaterhouseCoopers. Mr. Lotterman received an M.S. in International Real Estate in 2006 from Florida International University, where he graduated first in class, and a B.S. Degree in microbiology with a minor in chemistry in 1997 from the University of Florida.
Advisor Portfolio Managers
Subject to the Committee’s oversight, Jordan B. Ruddy, a member of the Committee, and Adam Lotterman serve as the Fund’s Portfolio Managers and oversee the day-to-day investment operations of the Fund. Each has served as a Portfolio Manager to the Fund since October 2013.
Jordan B. Ruddy — Mr. Ruddy’s biographical information is presented above.
Adam Lotterman — Mr. Lotterman’s biographical information is presented above.
Tim Thran, CFA — Mr. Thran currently serves as Associate Portfolio Manager and Assistant Treasurer of the Fund. Mr. Thran joined Bluerock in 2017 and currently serves as a Managing Director of the Advisor. Mr. Thran works directly with the Fund’s Senior Portfolio Managers and is responsible for overseeing day-to-day investment operations and execution of the Fund’s strategy, including portfolio valuation, investment analysis, liquidity management and performance evaluation. Previously, Mr. Thran served at JPMorgan Asset Management from 2014 to 2016, directing daily oversight and controls on over $200 billion in retail mutual fund assets. From 2008 to 2014, Mr. Thran held multiple management roles at State Street Corporation, with a focus on accounting and compliance on the
20 |
company’s premier ETFs and mutual fund clients. Mr. Thran received an M.B.A. degree with a concentration in Investments from the D’Amore-McKim School of Business at Northeastern University and B.A. degrees in both Mathematics and Economics from the College of the Holy Cross. Mr. Thran is a CFA charterholder, CFA Institute.
Investment Sub-Advisor – Mercer
The Advisor has engaged Mercer Investments LLC, a registered adviser under the Advisers Act, to act as an investment sub-advisor. For more than 50 years, Mercer and its affiliates have provided global leadership in investment consulting and multi-manager fiduciary management, and is a leading advisor to sovereign wealth funds, pension plans, banks, family offices, insurance companies, endowments and foundations. Mercer, together with its affiliated investment businesses, have over 5,600 delegated and advisory clients globally with over $547 billion in assets under management as of September 30, 2024 and over $17.5 trillion in assets under advisement as of June 30, 2024. Asset under management reported here includes include aggregated assets for which Mercer Investments LLC (Mercer Investments) and their global affiliates providing discretionary investment management services as of the dates indicated. Assets under management is calculated differently from regulatory assets under management, which is reported in Form ADV and filed with the Securities and Exchange Commission.
Mercer is an affiliate of Mercer (US), LLC, a human resource and financial consulting company. Mercer (US), LLC has approximately 25,000+ employees as of September 30, 2024 based in more than 40 countries and serves over 36,000 clients worldwide and is a wholly owned subsidiary of Marsh & McLennan Companies (NYSE: MMC).
Investment Sub-Advisor – RREEF
The Advisor has engaged RREEF America L.L.C., a registered advisor under the Advisers Act, to provide investment management for a portion of the Fund’s portfolio, generally less than 20%. In addition, RREEF provides the Advisor with research and information that the Advisor uses to make investment decisions with respect to non-publicly traded real estate related debt securities. RREEF together with its affiliates in Europe and Asia, comprise the global real estate investment business of DWS, an indirect majority owned subsidiary of Deutsche Bank A.G. DWS’s real estate investment business, is one of the largest real estate investment managers globally with more than 330 professionals and staff located in 23 cities worldwide and approximately $78.9 billion in real estate and real estate-related assets under management as of September 30, 2024.
RREEF Portfolio Managers
Subject to the Advisor’s oversight, David W. Zonavetch, Bob Thomas, and John W. Vojticek serve as the Fund’s RREEF Portfolio Managers and oversee a portion of investment portfolio of the Fund. Mr. Zonavetch and Mr. Vojticek have served as a Portfolio Managers to the Fund since May 2016. Mr. Thomas has served as a Portfolio Manager to the Fund since January 2018.
David W. Zonavetch — Mr. Zonavetch has served as a Director and Co-Lead Portfolio Manager for RREEF since September 2013 and as Co-Lead Portfolio Manager - Real Estate Securities since February 2012. Previously, he served as Vice President and Portfolio Manager from February 2007 to February 2012. From February 2007 to February 2012, Mr. Zonavetch was a Vice President and Securities Analyst at RREEF Real Estate. He has nine years of experience in accounting and finance. From 1998 to 2001, Mr. Zonavetch served as a Senior Accountant in Corporate Finance of RREEF Real Estate, and from 2001 to 2003, he served as Securities Accounting Coordinator with RREEF Real Estate’s Securities Group, covering the office and self- storage sectors. From 1995 until joining RREEF Real Estate in 1998, Mr. Zonavetch worked as an analyst for Cendant Mobility Services Corp., a corporate employee relocation company. Mr. Zonavetch holds a B.S. in Finance from the University of Illinois at Urbana-Champaign and is a certified public accountant.
Bob Thomas — Mr. Thomas has served as a Managing Director and Co-Head of Americas Real Estate Securities, Alternatives for RREEF since 2017. He has 15 years of industry experience serving as lead portfolio manager of North America for global listed property funds at Henderson Global Investors from 2015 to 2016, he was co-lead portfolio manager of North America for global listed property funds at AMP Capital from 2012 to 2015, and as an analyst at Nuveen Asset Management from 2011 to 2012, at BNP Paribas Asset Management from 2005 to 2011 and at Security Capital Research & Management from 20014 to 2005. Mr. Thomas started his career as an investment banking analyst in the Real Estate group at KeyBanc Capital Markets in 2002. Mr. Thomas holds a B.A. in Economics from Duke University and an MBA in Finance, Management & Strategy from Kellogg School of Management, Northwestern University.
John W. Vojticek — Mr. Vojticek has served as a Managing Director and Chief Investment Officer of Real Estate & Infrastructure Securities and Global Portfolio Manager for RREEF since July 2011 and was Co-Head of Americas Real Estate Securities from 2006 to July 2011. Mr. Vojticek was responsible for launching the firm’s first listed infrastructure securities strategy in June 2008 and served as Head of the Listed Infrastructure Securities business from June 2008 until his appointment as Chief Information Officer in July 2011. Mr. Vojticek is an associate member of the National Association of Real Estate Investment Trusts. Mr. Vojticek holds a B.S. in Business Administration from the University of Southern California.
The Statement of Additional Information provides additional information about each Portfolio Manager’s compensation, other accounts managed and ownership of Fund shares.
21 |
Administrator, Accounting Agent and Transfer Agent
ALPS Fund Services, Inc. (“ALPS” or the “Administrator”), located at 1290 Broadway, Suite 1000, Denver, CO 80203, serves as Administrator and Accounting Agent for the Fund. For the services rendered to the Fund by ALPS, the Fund pays ALPS the greater of an annual minimum fee or an asset-based fee, which scales downward based upon net assets for fund administration and fund accounting services. SS&C GIDS, located at PO Box 219445, Kansas City, MO 64121-9445, serves as the Fund’s Transfer Agent and for such services the Fund pays the Transfer Agent separate fees.
Custodian
UMB Bank, N.A (“UMB Bank” or the “Custodian”), with principal offices at 1010 Grand Boulevard, Kansas City, Missouri 64106, serves as custodian for the securities and cash of the Fund’s portfolio. Under a Custody Agreement, UMB Bank holds the Fund’s assets in safekeeping and keeps all necessary records and documents relating to its duties.
Fund Expenses
The Advisor is obligated to pay expenses associated with providing the services stated in the Investment Management Agreement, including compensation of and office space for its officers and employees connected with investment and economic research, trading and investment management and administration of the Fund. The Advisor is obligated to pay the fees of any Trustee of the Fund who is affiliated with it.
The Administrator is obligated to pay expenses associated with providing the services contemplated by a Fund Services Administration Agreement (administration and accounting services), including compensation of and office space for its officers and employees employed in providing these services to the Fund.
The Fund pays all other expenses incurred in the operation of the Fund including, among other things, (i) expenses for legal and independent accountants’ services, (ii) costs of printing proxies, share certificates, if any, and reports to shareholders, (iii) charges of the custodian and transfer agent in connection with the Fund’s dividend reinvestment policy, (iv) fees and expenses of independent Trustees, (v) printing costs, (vi) membership fees in trade association, (vii) fidelity bond coverage for the Fund’s officers and Trustees, (viii) errors and omissions insurance for the Fund’s officers and Trustees, (ix) brokerage costs, (x) taxes, (xi) costs associated with the Fund’s quarterly repurchase offers, (xii) servicing fees and (xiii) other extraordinary or non-recurring expenses and other expenses properly payable by the Fund. The expenses incident to the offering and issuance of shares to be issued by the Fund will be recorded as a reduction of capital of the Fund attributable to the shares.
Class A shares are subject to a monthly shareholder servicing fee at an annual rate of up to 0.25% of the average daily net assets of the Fund attributable to the respective share class.
The Board has authorized the Advisor and RREEF to select brokers or dealers (including affiliates) to arrange for the purchase and sale of Fund securities, including principal transactions. Any commission, fee or other remuneration paid to an affiliated broker or dealer is paid in compliance with the Fund’s procedures adopted in accordance with Rule 17e-1 under the 1940 Act.
Control Persons and Principal Shareholders
A principal shareholder is any person who owns (either of record or beneficially) 5% or more of the outstanding shares of a fund. A control person is one who owns, either directly or indirectly, more than 25% of the voting securities of a company or acknowledges the existence of control. The Fund’s principal shareholders as of January 3, 2025 are listed in the chart below. Each shareholder listed below is a record shareholder, holding shares for the benefit of others.
Class A Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
6,523,152.52 |
26.75% |
EQUITABLE ADVISORS LLC LPL FINANCIAL SERVICES FBO LPL BIN 66920980 1055 LPL WAY FORT MILL SC, 29715-8101 |
4,721,545.33 |
19.36% |
CHARLES SCHWAB & CO INC SPECIAL CUSTODY A/C FBO CUSTOMERS 211 MAIN STREET SAN FRANCISCO, CA 94105-1905 |
3,107,371.03 |
12.74% |
NATIONAL FINANCIAL SERVICES LLC BIN #B9F699887 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
3,082,068.56 |
12.64% |
22 |
Class C Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
5,923,943.31 |
38.47% |
LPL FINANCIAL LLC FBO CUSTOMER ACCOUNTS 4707 EXECUTIVE DR. SAN DIEGO CA, 92121-3091 |
2,299,101.93 |
14.93% |
CHARLES SCHWAB AND CO INC SPECIAL CUSTODY A/C FBO CUSTOMERS 211 MAIN STREET SAN FRANCISCO, CA 94105-1905 |
2,076,778.96 |
13.49% |
NATIONAL FINANCIAL SERVICES LLC 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
895,604.35 |
5.82% |
Class I Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
CHARLES SCHWAB & CO INC SPECIAL CUSTODY A/C FBO CUSTOMERS 211 MAIN STREET SAN FRANCISCO, CA 92121 |
42,258,021.47 |
36.65% |
NATIONAL FINANCIAL SERVICES LLC 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
21,116,400.89 |
18.31% |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
21,101,606.20 |
18.30% |
LPL FINANCIAL SERVICES FBO LPL BIN 66920980 1055 LPL WAY FORT MILL SC 29715-8101 |
14,367,372.68 |
12.46% |
ROBERT W BAIRD & CO. INC. A/C 47100819 777 EAST WISCONSIN AVENUE MILWAUKEE, WI 53202 |
6,642,155.04 |
5.76% |
Class L Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
1,652,278.67 |
53.11% |
NATIONAL FINANCIAL SERVICES LLC 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
535,807.56 |
17.22% |
LPL FINANCIAL LLC FBO CUSTOMER ACCOUNTS 4707 EXECUTIVE DR. SAN DIEGO CA, 92121-3091 |
247,909.67 |
7.97% |
Class M Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
MORGAN STANLEY SMITH BARNEY LLC 1 NEW YORK PLAZA NEW YORK, NY 10004 |
4,313,743.14 |
98.46% |
As of January 3, 2025, the Trustees and officers, as a group, owned less than 1.00% of the shares of the Fund.
DETERMINATION OF NET ASSET VALUE
The net asset value of shares of the Fund is determined daily, as of the close of regular trading on the NYSE (normally, 4:00 p.m., Eastern Time). The NYSE is closed on weekends and New Year’s Day, Martin Luther King, Jr. Day, Presidents’ Day, Good Friday,
23 |
Memorial Day, Juneteenth Day, Independence Day, Labor Day, Thanksgiving Day, and Christmas Day. Each Class A share will be offered at the Class A net asset value plus the applicable sales load. During the continuous offering, the price of the shares will increase or decrease on a daily basis according to the net asset value of the shares.
In computing net asset value, portfolio securities of the Fund are valued at their current market values determined on the basis of market quotations as of the last quoted sales price on the security’s primary exchange. If market quotations are not readily available, as in the case of Institutional Investment Funds investing in private real estate, securities are valued at fair value as determined in good faith by the Advisor, in its capacity as the Board’s valuation designee, pursuant to Rule 2a-5 under the 1940 Act or with respect to securities traded or dealt in upon one or more securities exchanges (whether domestic or foreign), as described below. As a general matter, fair value represents the amount that the Fund could reasonably expect to receive if the Fund’s investment in the security were sold at the time of valuation, based on information reasonably available at the time the valuation is made and that the Advisor believes to be reliable. As the valuation designee, the Advisor acts under the Board’s oversight. The Board and the Advisor may enlist third party service providers, such as pricing services, broker-dealers or valuation firms, on an as-needed basis to assist in determining a security-specific fair value. The Board reviews the execution of this process and the resultant fair value prices at least quarterly to assure the process produces reliable results.
Fair valuation involves subjective judgments, and it is possible that the fair value determined for a security may differ materially from the value that could be realized upon the sale of the security. Like all investments that are valued at fair value, the Institutional Investment Funds will be difficult to value. There is no single standard for determining fair value of a security. Rather, in determining the fair value of a security for which there are no readily available market quotations, the Advisor, using information including that provided by a Sub-Advisor, may consider several factors, including fundamental analytical data relating to the investment in the security, the nature and duration of any restriction on the disposition of the security, the cost of the security at the date of purchase, the liquidity of the market for the security and the recommendation of the Fund’s Portfolio Managers. The Advisor may also consider periodic financial statements (audited and unaudited) or other information provided by the issuer. The Advisor will attempt to obtain current information to value all fair valued securities, but it is anticipated that portfolio holdings of the Institutional Investment Funds could be available on no more than a quarterly basis. Institutional Investment Funds that invest primarily in publicly traded securities are more easily valued.
The Advisor, with the assistance of other parties, will provide the Board with periodic reports, no less frequently than quarterly, that discuss the functioning of the valuation process, if applicable to that period, and that identify issues and valuations problems that have arisen, if any. To the extent deemed necessary by the Advisor, the fair value team or committee of the Board will review any securities valued by the Advisor in accordance with the Fund’s valuation policies.
Non-dollar-denominated securities, if any, are valued as of the close of the NYSE at the closing price of such securities in their principal trading market, but may be valued at fair value if subsequent events occurring before the computation of net asset value materially have affected the value of the securities. Trading may take place in foreign issues held by the Fund, if any, at times when the Fund is not open for business. As a result, the Fund’s net asset value may change at times when it is not possible to purchase or sell shares of the Fund. The Fund may use a third-party pricing service to assist it in determining the market value of securities in the Fund’s portfolio. The Fund’s net asset value per share is calculated, on a class-specific basis, by dividing the value of the Fund’s total assets (the value of the securities the Fund holds plus cash or other assets, including interest accrued but not yet received), less accrued expenses of the Fund, less the Fund’s other liabilities by the total number of shares outstanding.
For purposes of determining the net asset value of the Fund, readily marketable portfolio securities listed on the NYSE are valued, except as indicated below, at the last sale price reflected on the consolidated tape at the close of the NYSE on the business day as of which such value is being determined. If there has been no sale on such day, the securities are valued at the mean of the closing bid and asked prices on such day. If no bid or asked prices are quoted on such day or if market prices may be unreliable because of events occurring after the close of trading, then the security is valued by such method as the Advisor, as valuation designee, shall determine in good faith to reflect its fair market value. Readily marketable securities not listed on the NYSE but listed on other domestic or foreign securities exchanges are valued in a like manner. Portfolio securities traded on more than one securities exchange are valued at the last sale price on the business day as of which such value is being determined as reflected on the consolidated tape at the close of the exchange representing the principal market for such securities. Securities trading on the NASDAQ are valued at the NASDAQ official closing price.
Readily marketable securities traded in the over-the-counter market, including listed securities whose primary market is believed by the Advisor to be over-the-counter, are valued at the mean of the current bid and asked prices as reported by the NASDAQ or, in the case of securities not reported by the NASDAQ or a comparable source, as the Advisor deems appropriate to reflect their fair market value. Where securities are traded on more than one exchange and also over-the-counter, the securities will generally be valued using the quotations the Advisor believes reflect most closely the value of such securities.
CONFLICTS OF INTEREST
As a general matter, certain conflicts of interest may arise in connection with a portfolio manager’s management of a fund’s investments, on the one hand, and the investments of other accounts for which the portfolio manager is responsible, on the other. For example, it is possible that the various accounts managed could have different investment strategies that, at times, might conflict with one another to the possible detriment of the Fund. Alternatively, to the extent that the same investment opportunities might be desirable for more than one account, possible conflicts could arise in determining how to allocate them. Other potential conflicts might include conflicts created by specific portfolio manager compensation arrangements, and conflicts relating to selection of brokers or dealers to execute Fund portfolio trades and/or specific uses of commissions from Fund portfolio trades (for example, research, or “soft dollars”, if any). The Advisor, and Sub-Advisor, to the extent applicable, have adopted policies and procedures and have structured their Portfolio Managers’ compensation in a manner reasonably designed to safeguard the Fund from being negatively affected as a result of any such potential conflicts.
24 |
QUARTERLY REPURCHASES OF SHARES
Once each quarter, the Fund will offer to repurchase, at per-class net asset value no less than 5% of the outstanding shares of the Fund, unless such offer is suspended or postponed in accordance with regulatory requirements (as discussed below). The offer to purchase shares is a fundamental policy that may not be changed without the vote of the holders of a majority of the Fund’s outstanding voting securities (as defined in the 1940 Act). Shareholders will be notified in writing of each quarterly repurchase offer and the date the repurchase offer ends (the “Repurchase Request Deadline”). Shares will be repurchased at the per-class NAV per share determined as of the close of regular trading on the NYSE no later than the 14th day after the Repurchase Request Deadline, or the next business day if the 14th day is not a business day (each a “Repurchase Pricing Date”).
Shareholders will be notified in writing about each quarterly repurchase offer, how they may request that the Fund repurchase their shares and the “Repurchase Request Deadline,” which is the date the repurchase offer ends. Shares tendered for repurchase by shareholders prior to any Repurchase Request Deadline will be repurchased subject to the aggregate repurchase amounts established for that Repurchase Request Deadline. The time between the notification to shareholders and the Repurchase Request Deadline may vary from no more than 42 days to no less than 21 days. Payment pursuant to the repurchase will be made by checks to the shareholder’s address of record, or credited directly to a predetermined bank account on the Purchase Payment Date, which will be no more than seven days after the Repurchase Pricing Date. The Board may establish other policies for repurchases of shares that are consistent with the 1940 Act, regulations thereunder and other pertinent laws. Shareholders have no right to redeem Fund shares outside the regular quarterly repurchases, regardless of shareholder circumstances, and the Fund may not honor any such requests.
Determination of Repurchase Offer Amount
The Board, or a committee thereof, in its sole discretion, will determine the number of shares for each share class that the Fund will offer to repurchase (the “Repurchase Offer Amount”) for a given Repurchase Request Deadline. The Repurchase Offer Amount, however, will be no less than 5% and no more than 25% of the total number of shares outstanding on the Repurchase Request Deadline.
If shareholders tender for repurchase more than the Repurchase Offer Amount for a given repurchase offer, the Fund will repurchase the shares on a pro rata basis. However, the Fund may accept all shares tendered for repurchase by shareholders who own less than one hundred shares and who tender all of their shares, before prorating other amounts tendered.
Notice to Shareholders
No less than 21 days and more than 42 days before each Repurchase Request Deadline, the Fund shall send to each shareholder of record and to each beneficial owner of the shares that are the subject of the repurchase offer a notification (“Shareholder Notification”). The Shareholder Notification will contain information shareholders should consider in deciding whether to tender their shares for repurchase. The notice also will include detailed instructions on how to tender shares for repurchase, state the Repurchase Offer Amount and identify the dates of the Repurchase Request Deadline, the scheduled Repurchase Pricing Date, and the date the repurchase proceeds are scheduled for payment (the “Repurchase Payment Deadline”). The notice also will set forth the NAV that has been computed no more than seven days before the date of notification, and how shareholders may ascertain the NAV after the notification date.
Repurchase Price
The repurchase price of the shares will be the NAV of the share class as of the close of regular trading on the NYSE on the Repurchase Pricing Date. The notice of the repurchase offer also will provide information concerning the NAV, such as the NAV as of a recent date or a sampling of recent NAVs, and a toll-free number for information regarding the repurchase offer. You may call 1-844-819-8287 to learn the NAV.
Early Withdrawal Charge
Selling brokers, or other financial intermediaries that have entered into distribution agreements with the Distributor may receive a commission of up to 1.00% of the purchase price of Class A shares (for purchases of $1,000,000 or more).
Class A shareholders who tender for repurchase of Class A shares that were purchased in amounts of $1,000,000 or more that have been held, as of the time of repurchase, less than 365 days from the purchase date will be subject to an early withdrawal charge of 1.00% of the original purchase price. The Distributor may waive the imposition of the early withdrawal charge in the following situations: (1) shareholder death or (2) shareholder disability. Any such waiver does not imply that the early withdrawal charge will be waived at any time in the future or that such early withdrawal charge will be waived for any other shareholder. Class A share purchases of less than $1,000,000 are not be subject to an early withdrawal charge.
Repurchase Amounts and Payment of Proceeds
Shares tendered for repurchase by shareholders prior to any Repurchase Request Deadline will be repurchased subject to the aggregate Repurchase Offer Amount established for that Repurchase Request Deadline. Payment pursuant to the repurchase offer will be made by check to the shareholder’s address of record, or credited directly to a predetermined bank account on the Purchase Payment Date, which will be no more than seven days after the Repurchase Pricing Date. The Board may establish other policies for repurchases of shares that are consistent with the 1940 Act, regulations thereunder and other pertinent laws.
25 |
If shareholders tender for repurchase more than the Repurchase Offer Amount for a given repurchase offer, the Fund will repurchase the shares on a pro rata basis. Notwithstanding the foregoing, the Fund may in its sole discretion and for administrative convenience accept all shares tendered for repurchase by shareholders who own less than one hundred shares and who tender all of their shares, before prorating other amounts tendered.
Suspension or Postponement of Repurchase Offer
The Fund may suspend or postpone a repurchase offer only: (a) if making or effecting the repurchase offer would cause the Fund to lose its status as a regulated investment company under the Code; (b) for any period during which the NYSE or any market on which the securities owned by the Fund are principally traded is closed, other than customary weekend and holiday closings, or during which trading in such market is restricted; (c) for any period during which an emergency exists as a result of which disposal by the Fund of securities owned by it is not reasonably practicable, or during which it is not reasonably practicable for the Fund fairly to determine the value of its net assets; or (d) for such other periods as the Commission may by order permit for the protection of shareholders of the Fund.
Liquidity Requirements
The Fund must maintain liquid assets equal to the Repurchase Offer Amount from the time that the notice is sent to shareholders until the Repurchase Pricing Date. The Fund will ensure that either a percentage of its net assets equal to at least 100% of the Repurchase Offer Amount consists of cash or assets that can be sold or disposed of in the ordinary course of business at approximately the price at which the Fund has valued the investment within the time period between the Repurchase Request Deadline and the Repurchase Payment Deadline, and/or a line of credit is available to satisfy the Repurchase Offer Amount. The Board has adopted procedures that are reasonably designed to ensure that the Fund’s assets are sufficiently liquid so that the Fund can comply with the repurchase offer and the liquidity requirements described in the previous paragraphs. If, at any time, the Fund falls out of compliance with these liquidity requirements, the Board will take whatever action it deems appropriate to ensure compliance.
Consequences of Repurchase Offers
Repurchase offers will typically be funded from available cash or sales of portfolio securities. Payment for repurchased shares, however, may require the Fund to liquidate portfolio holdings earlier than the Advisor otherwise would, thus increasing the Fund’s portfolio turnover and potentially causing the Fund to realize losses. The Advisor intends to take measures to attempt to avoid or minimize such potential losses and turnover, and instead of liquidating portfolio holdings, may borrow money to finance repurchases of shares. If the Fund borrows to finance repurchases, interest on that borrowing will negatively affect shareholders who do not tender their shares in a repurchase offer by increasing the Fund’s expenses and reducing any net investment income. To the extent the Fund finances repurchase amounts by selling Fund investments, the Fund may hold a larger proportion of its assets in less liquid securities. The sale of portfolio securities to fund repurchases also could reduce the market price of those underlying securities, which in turn would reduce the Fund’s net asset value.
Repurchase of the Fund’s shares will tend to reduce the number of outstanding shares and, depending upon the Fund’s investment performance, its net assets. A reduction in the Fund’s net assets would increase the Fund’s expense ratio, to the extent that additional shares are not sold and expenses otherwise remain the same (or increase). In addition, the repurchase of shares by the Fund will be a taxable event to shareholders.
The Fund is intended as a medium to long-term investment. The Fund’s quarterly repurchase offers are a shareholder’s only means of liquidity with respect to his or her shares. Shareholders have no right to redeem Fund shares outside the regular quarterly repurchases, regardless of shareholder circumstances, and the Fund may not honor any such requests. The shares are not traded on a national securities exchange and no secondary market exists for the shares, nor does the Fund expect a secondary market for its shares to exist in the future.
DISTRIBUTION POLICY
Quarterly Distribution Policy
The Fund’s distribution policy is to make quarterly distributions to shareholders. The level of quarterly distributions (including any return of capital) is not fixed, but is expected to represent an annual rate of approximately 5.25% of the Fund’s current net asset value per share. However, this distribution policy is subject to change. Shareholders receiving periodic payments from the Fund may be under the impression that they are receiving net profits. However, all or a portion of a distribution may consist of a return of capital. Shareholders should not assume that the source of a distribution from the Fund is net profit. A return of capital is not taxable to a shareholder unless it exceeds a shareholder’s tax basis in the shares. Returns of capital reduce a shareholder’s tax cost (or “tax basis”). Once a shareholder’s tax basis is reduced to zero, any further return of capital would be taxable. Shareholders should note that return of capital will reduce the tax basis of their shares and potentially increase the taxable gain, if any, upon disposition of their shares. As required under the Investment Company Act of 1940, the Fund will provide a notice to shareholders at the time of distribution when such distribution does not consist solely of net income. Additionally, each distribution payment will be accompanied by a written statement which discloses the source or sources of each distribution. The IRS requires you to report these amounts, excluding returns of capital, on your income tax return for the year declared. The Fund will provide disclosures, with each distribution, that estimate the percentages of the current and year-to-date distributions that represent (1) net investment income, (2) capital gains and (3) return of capital. At the end of the year, the Fund may be required under applicable law to re-characterize distributions made previously during that year among (1) ordinary income, (2) capital gains and (3) return of capital for tax purposes. An additional distribution may be made in December, and other additional distributions may be made with respect to a particular fiscal year in order to comply with applicable law. Distributions declared in December, if paid to shareholders by the end of January, are treated for federal income tax purposes as if received in December.
26 |
The distribution rate may be modified by the Board from time to time. If, for any quarterly distribution, investment company taxable income (which term includes net short-term capital gain), if any, and net tax-exempt income, if any, is less than the amount of the distribution, then the difference will generally be a tax-free return of capital distributed from the Fund’s assets. The Fund’s final distribution for each calendar year will include any remaining investment company taxable income and net tax-exempt income undistributed during the year, as well as all net capital gain realized during the year. If the total distributions made in any calendar year exceed investment company taxable income, net tax-exempt income and net capital gain, such excess distributed amount would be treated as ordinary dividend income to the extent of the Fund’s current and accumulated earnings and profits. Distributions in excess of the earnings and profits would first be a tax-free return of capital to the extent of the adjusted tax basis in the shares. After such adjusted tax basis is reduced to zero, the distribution would constitute capital gain (assuming the shares are held as capital assets). This distribution policy may, under certain circumstances, have certain adverse consequences to the Fund and its shareholders because it may result in a return of capital resulting in less of a shareholder’s assets being invested in the Fund and, over time, increase the Fund’s expense ratio. The distribution policy also may cause the Fund to sell a security at a time it would not otherwise do so in order to manage the distribution of income and gain.
Unless the registered owner of shares elects to receive cash, all dividends declared on shares will be automatically reinvested in additional shares of the Fund. See “Dividend Reinvestment Policy.”
The dividend distribution described above may result in the payment of approximately the same amount or percentage to the Fund’s shareholders each quarter. Section 19(a) of the 1940 Act and Rule 19a-1 thereunder require the Fund to provide a written statement accompanying any such payment that adequately discloses its source or sources. Thus, if the source of the dividend or other distribution were the original capital contribution of the shareholder, and the payment amounted to a return of capital, the Fund would be required to provide written disclosure to that effect. Nevertheless, persons who periodically receive the payment of a dividend or other distribution may be under the impression that they are receiving net profits when they are not. Shareholders should read any written disclosure provided pursuant to Section 19(a) and Rule 19a-1 carefully and should not assume that the source of any distribution from the Fund is net profit.
The Board reserves the right to change the quarterly distribution policy from time to time.
DIVIDEND REINVESTMENT POLICY
The Fund will operate under a dividend reinvestment policy administered by the Transfer Agent. Pursuant to the policy, the Fund’s income dividends or capital gains or other distributions (each, a “Distribution” and collectively, “Distributions”), net of any applicable U.S. withholding tax, are reinvested in the same class of shares of the Fund.
Shareholders automatically participate in the dividend reinvestment policy, unless and until an election is made to withdraw from the policy on behalf of such participating shareholder. Shareholders who do not wish to have Distributions automatically reinvested should so notify the Transfer Agent in writing at Bluerock Total Income+ Real Estate Fund, c/o SS&C GIDS, PO Box 219445, Kansas City, MO 64121-9445. Such written notice must be received by the Transfer Agent 30 days prior to the record date of the Distribution or the shareholder will receive such Distribution in shares through the dividend reinvestment policy. Under the dividend reinvestment policy, the Fund’s Distributions to shareholders are reinvested in full and fractional shares as described below.
When the Fund declares a Distribution, the Transfer Agent, on the shareholder’s behalf, will receive additional authorized shares from the Fund either newly issued or repurchased from shareholders by the Fund and held as treasury stock. The number of shares to be received when Distributions are reinvested will be determined by dividing the amount of the Distribution by the Fund’s net asset value per share.
The Transfer Agent will maintain all shareholder accounts and furnish written confirmations of all transactions in the accounts, including information needed by shareholders for personal and tax records. The Transfer Agent will hold shares in the account of the shareholders in non-certificated form in the name of the participant, and each shareholder’s proxy, if any, will include those shares purchased pursuant to the dividend reinvestment policy. Each participant, nevertheless, has the right to request certificates for whole and fractional shares owned. The Fund will issue certificates in its sole discretion. The Administrator will distribute all proxy solicitation materials, if any, to participating shareholders.
In the case of shareholders, such as banks, brokers or nominees, that hold shares for others who are beneficial owners participating under the dividend reinvestment policy, the Transfer Agent will administer the dividend reinvestment policy on the basis of the number of shares certified from time to time by the record shareholder as representing the total amount of shares registered in the shareholder’s name and held for the account of beneficial owners participating under the dividend reinvestment policy.
Neither the Transfer Agent nor the Fund shall have any responsibility or liability beyond the exercise of ordinary care for any action taken or omitted pursuant to the dividend reinvestment policy, nor shall they have any duties, responsibilities or liabilities except such as expressly set forth herein. Neither shall they be liable hereunder for any act done in good faith or for any good faith omissions to act, including, without limitation, failure to terminate a participant’s account prior to receipt of written notice of his or her death or with respect to prices at which shares are purchased or sold for the participants account and the terms on which such purchases and sales are made, subject to applicable provisions of the federal securities laws.
The automatic reinvestment of dividends will not relieve participants of any federal, state or local income tax that may be payable (or required to be withheld) on such dividends. See “U.S. Federal Income Tax Matters.”
The Fund reserves the right to amend or terminate the dividend reinvestment policy. There is no direct service charge to participants with regard to purchases under the dividend reinvestment policy; however, the Fund reserves the right to amend the dividend reinvestment policy to include a service charge payable by the participants.
27 |
All correspondence concerning the dividend reinvestment policy should be directed to the Transfer Agent at Bluerock Total Income+ Real Estate Fund, c/o SS&C GIDS, PO Box 219445, Kansas City, MO 64121-9445. Certain transactions can be performed by calling the toll-free number 1-844-819-8287.
U.S. FEDERAL INCOME TAX MATTERS
The following briefly summarizes some of the important federal income tax consequences to shareholders of investing in the Fund’s shares, reflects the federal tax law as of the date of this prospectus, and does not address special tax rules applicable to certain types of investors, such as corporate, tax-exempt and foreign investors. Investors should consult their tax advisors regarding other federal, state or local tax considerations that may be applicable in their particular circumstances, as well as any proposed tax law changes.
The following is a summary discussion of certain U.S. federal income tax consequences that may be relevant to a shareholder of the Fund that acquires, holds and/or disposes of shares of the Fund, and reflects provisions of the Internal Revenue Code of 1986, as amended, existing Treasury regulations, rulings published by the IRS, and other applicable authority, as of the date of this prospectus. These authorities are subject to change by legislative or administrative action, possibly with retroactive effect. The following discussion is only a summary of some of the important tax considerations generally applicable to investments in the Fund and the discussion set forth herein does not constitute tax advice. For more detailed information regarding tax considerations, see the Statement of Additional Information. There may be other tax considerations applicable to particular investors such as those holding shares in a tax deferred account such as an IRA or 401(k) plan. In addition, income earned through an investment in the Fund may be subject to state, local and foreign taxes.
The Fund intends to elect to be treated and to qualify each year for taxation as a regulated investment company under Subchapter M of the Code. In order for the Fund to qualify as a regulated investment company, it must meet an income and asset diversification test each year. If the Fund so qualifies and satisfies certain distribution requirements, the Fund (but not its shareholders) will not be subject to federal income tax to the extent it distributes its investment company taxable income and net capital gains (the excess of net long-term capital gains over net short-term capital loss) in a timely manner to its shareholders in the form of dividends or capital gain distributions. The Code imposes a 4% nondeductible excise tax on regulated investment companies, such as the Fund, to the extent they do not meet certain distribution requirements by the end of each calendar year. The Fund anticipates meeting these distribution requirements. Shareholders will not be subject to the alternative minimum tax.
The Fund intends to make distributions of investment company taxable income after payment of the Fund’s operating expenses no less frequently than annually. Unless a shareholder is ineligible to participate or elects otherwise, all distributions will be automatically reinvested in additional shares of the Fund pursuant to the dividend reinvestment policy. For U.S. federal income tax purposes, all dividends are generally taxable whether a shareholder takes them in cash or they are reinvested pursuant to the policy in additional shares of the Fund. Distributions of the Fund’s investment company taxable income (including short-term capital gains) will generally be treated as ordinary income to the extent of the Fund’s current and accumulated earnings and profits. Distributions of the Fund’s net capital gains (“capital gain dividends”), if any, are taxable to shareholders as capital gains, regardless of the length of time shares have been held by shareholders. Distributions, if any, in excess of the Fund’s earnings and profits will first reduce the adjusted tax basis of a holder’s shares and, after that basis has been reduced to zero, will constitute capital gains to the shareholder of the Fund (assuming the shares are held as a capital asset). A corporation that owns Fund shares generally will not be entitled to the dividends received deduction with respect to all of the dividends it receives from the Fund. Fund dividend payments that are attributable to qualifying dividends received by the Fund from certain domestic corporations may be designated by the Fund as being eligible for the dividends received deduction. There can be no assurance as to what portion of Fund dividend payments may be classified as qualifying dividends. The determination of the character for U.S. federal income tax purposes of any distribution from the Fund (i.e. ordinary income dividends, capital gains dividends, qualified dividends or return of capital distributions) will be made as of the end of the Fund’s taxable year. Generally, no later than 60 days after the close of its taxable year, the Fund will provide shareholders with a written notice designating the amount of any capital gain distributions and any other distributions.
The Fund will inform its shareholders of the source and tax status of all distributions promptly after the close of each calendar year.
DESCRIPTION OF CAPITAL STRUCTURE AND SHARES
The Fund is an unincorporated statutory trust established under the laws of the State of Delaware upon the filing of a Certificate of Trust with the Secretary of State of Delaware on May 25, 2012. The Trustees are authorized to issue an unlimited number of shares. The Fund does not intend to hold annual meetings of its shareholders.
The Declaration of Trust, which has been filed with the SEC, permits the Fund to issue an unlimited number of full and fractional shares of beneficial interest, no par value. The Fund offers five different classes of shares: Class A, Class C, Class I, Class L and Class M shares. The Class C, Class I, Class L and Class M shares are each offered by a different prospectus. The Fund began continuously offering its common shares on October 22, 2012. As of February 18, 2014, the Fund simultaneously redesignated its issued and outstanding common shares as Class A shares and created its Class C and Class I shares, which commenced offering April 1, 2014. As of May 30, 2017, the Fund created its Class L shares. As of February 1, 2020, the Fund created its Class M shares. An investment in any share class of the Fund represents an investment in the same assets of the Fund. However, the minimum investment amounts, sales loads, and ongoing fees and expenses for each share class may be different. The fees and expenses for the Fund are set forth in “Summary of Fund Expenses”. The details of each share class are set forth in “Plan of Distribution”.
28 |
The following table shows the amounts of the Fund’s shares that have been authorized and are outstanding as of January 3, 2025, of which none were owned by the Fund:
Title of Class |
Amount Authorized |
Amount Outstanding |
Unlimited |
shares NAV $26.03 per share |
|
Class C |
Unlimited |
15,397,873.19 shares NAV $24.05 per share |
Class I |
Unlimited |
115,282,227.36 shares NAV $26.80 per share |
Class L |
Unlimited |
3,111,066.77 shares NAV $25.54 per share |
Class M |
Unlimited |
4,381,277.79 shares NAV $24.24 per share |
Holders of shares will be entitled to the payment of dividends when, as and if declared by the Board. The Fund currently intends to make dividend distributions to its shareholders no less frequently than quarterly. Unless the registered owner of shares elects to receive cash, all dividends declared on shares will be automatically reinvested for shareholders in additional shares of the same class of the Fund. See “Dividend Reinvestment Policy.” The 1940 Act may limit the payment of dividends to the holders of shares. Each whole share shall be entitled to one vote as to matters on which it is entitled to vote pursuant to the terms of the Declaration of Trust on file with the SEC. Upon liquidation of the Fund, after paying or adequately providing for the payment of all liabilities of the Fund, and upon receipt of such releases, indemnities and refunding agreements as they deem necessary for their protection, the Trustees may distribute the remaining assets of the Fund among its shareholders. The shares are not liable to further calls or to assessment by the Fund. There are no pre-emptive rights associated with the shares. The Declaration of Trust provides that the Fund’s shareholders are not liable for any liabilities of the Fund. Although shareholders of an unincorporated statutory trust established under Delaware law, in certain limited circumstances, may be held personally liable for the obligations of the Fund as though they were general partners, the provisions of the Declaration of Trust described in the foregoing sentence make the likelihood of such personal liability remote.
The Fund generally will not issue share certificates. However, upon written request to the Fund’s Transfer Agent, a share certificate may be issued at the Fund’s discretion for any or all of the full shares credited to an investor’s account. Share certificates that have been issued to an investor may be returned at any time. The Fund’s Transfer Agent will maintain an account for each shareholder upon which the registration of shares are recorded, and transfers, permitted only in rare circumstances, such as death or bona fide gift, will be reflected by bookkeeping entry, without physical delivery. The Fund’s Transfer Agent will require that a shareholder provide requests in writing, accompanied by a valid signature guarantee form, when changing certain information in an account such as wiring instructions or telephone privileges.
Other Classes of Shares. The Fund offers Class C, Class I, Class L and Class M shares by a different prospectus. The other share classes are subject to different investment minimums, sales charges, and shareholder servicing fees and/or distribution servicing fees.
ANTI-TAKEOVER PROVISIONS IN THE DECLARATION OF TRUST
The Amended and Restated Declaration of Trust includes provisions that could have the effect of limiting the ability of other entities or persons to acquire control of the Fund or to change the composition of the Board, and could have the effect of depriving the Fund’s shareholders of an opportunity to sell their shares at a premium over prevailing market prices, if any, by discouraging a third party from seeking to obtain control of the Fund. These provisions may have the effect of discouraging attempts to acquire control of the Fund, which attempts could have the effect of increasing the expenses of the Fund and interfering with the normal operation of the Fund. The Trustees are elected for indefinite terms and do not stand for reelection. A Trustee may be removed from office without cause only by a written instrument signed or adopted by a majority of the remaining Trustees or by a vote of the holders of at least two-thirds of the shares of the Fund that are entitled to elect a Trustee and that are entitled to vote on the matter. The Declaration of Trust does not contain any other specific inhibiting provisions that would operate only with respect to an extraordinary transaction such as a merger, reorganization, tender offer, sale or transfer of substantially all of the Fund’s asset, or liquidation. Reference should be made to the Declaration of Trust on file with the SEC for the full text of these provisions.
PLAN OF DISTRIBUTION
ALPS Distributors, Inc. (the “Distributor”), located at 1290 Broadway, Suite 1000, Denver, Colorado 80203, serves as the Fund’s principal underwriter and acts as the distributor of the Fund’s shares on a best efforts basis, subject to various conditions. The Fund’s shares are offered for sale through the Distributor at net asset value plus the applicable sales load. The Distributor also may enter into selected dealer agreements with other broker dealers for the sale and distribution of the Fund’s shares, including with affiliates of the Advisor. In reliance on Rule 415, the Fund intends to offer to sell its shares, on a continual basis, through the Distributor. No arrangement has been made to place funds received in an escrow, trust or similar account. The Distributor is not required to sell any specific number or dollar amount of the Fund’s shares. Shares of the Fund will not be listed on any national securities exchange and the Distributor will not act as a market marker in Fund shares. Class A shares are not currently subject to a Distribution Fee.
29 |
The Distributor has entered into a “wholesaling” agreement with Bluerock Capital Markets, LLC (“BCM”), a registered broker-dealer and an affiliate of the Advisor. Pursuant to the terms of the wholesaling agreement, BCM will seek to market and otherwise promote the Fund through various “wholesale” distribution channels, including regional and independent retail broker-dealers. BCM is paid a portion of the sales load, up to 0.75% of the offering price, charged on the sale of Class A shares (the “Dealer Manager Fee”) for the services it provides under the wholesaling agreement.
The Advisor or its affiliates, in the Advisor’s discretion and from their own resources, may pay additional compensation to brokers or dealers in connection with the sale and distribution of Fund shares (the “Additional Compensation”). In return for the Additional Compensation, the Fund may receive certain marketing advantages including access to a broker’s or dealer’s registered representatives, placement on a list of investment options offered by a broker or dealer, or the ability to assist in training and educating the broker’s or dealer’s registered representatives. The Additional Compensation may differ among brokers or dealers in amount or in the manner of calculation: payments of Additional Compensation may be fixed dollar amounts, or based on the aggregate value of outstanding shares held by shareholders introduced by the broker or dealer, or determined in some other manner. The receipt of Additional Compensation by a selling broker or dealer may create potential conflicts of interest between an investor and its broker or dealer who is recommending the Fund over other potential investments. Additionally, the Fund may pay a servicing fee to intermediaries and other financial industry professionals for providing ongoing services in respect of shareholders of the Fund. Such services may include electronic processing of client orders, electronic fund transfers between clients and the Fund, account reconciliations with the Fund’s Transfer Agent, facilitation of electronic delivery to clients of Fund documentation, monitoring client accounts for back-up withholding and any other special tax reporting obligations, maintenance of books and records with respect to the foregoing, and such other information and liaison services as the Fund or the Advisor may reasonably request.
The Fund and the Advisor have agreed to indemnify the Distributor against certain liabilities, including liabilities under the Securities Act of 1933, or to contribute to payments the Distributor may be required to make because of any of those liabilities. Such agreement does not include indemnification of the Distributor against liability resulting from willful misfeasance, bad faith or negligence on the part of the Distributor in the performance of its duties or from reckless disregard by the Distributor of its obligations and duties under the Distribution Agreement. The Distributor may, from time to time, engage in transactions with or perform services for the Advisor and its affiliates in the ordinary course of business.
Purchasing Shares
Investors may purchase shares directly from the Fund in accordance with the instructions below. Investors will be assessed fees for returned checks and stop payment orders at prevailing rates charged by SS&C GIDS, the Fund’s Transfer Agent. The returned check and stop payment fee is currently $25. Investors may buy and sell shares of the Fund through financial intermediaries and their agents that have made arrangements with the Fund and are authorized to buy and sell shares of the Fund (collectively, “Financial Intermediaries”). Such Financial Intermediaries are authorized to designate other intermediaries to receive purchase orders on the Fund’s behalf. The Fund will be deemed to have received a purchase order when a Financial Intermediary or, if applicable, its authorized designee, receives the order. Orders will be priced at the appropriate price next computed after it is received by a Financial Intermediary or their authorized designee and accepted by the Fund. A Financial Intermediary may hold shares in an omnibus account in the Financial Intermediary’s name or the Financial Intermediary or their authorized designee may maintain individual ownership records. The Fund may pay the Financial Intermediary for maintaining individual ownership records as well as providing other shareholder services. Financial intermediaries may charge fees for the services they provide in connection with processing your transaction order or maintaining an investor’s account with them. Investors should check with their Financial Intermediary to determine if it is subject to these arrangements. Financial Intermediaries are responsible for placing orders correctly and promptly with the Fund, forwarding payment promptly. Orders transmitted with a Financial Intermediary before the close of regular trading (generally 4:00 p.m., Eastern Time) on a day that the NYSE is open for business, will be priced based on the Fund’s NAV next computed after it is received by the Financial Intermediary.
The Fund reserves the right to reject or restrict purchase requests for any reason, particularly when the shareholder’s trading activity suggests that the shareholder may be engaged in disruptive trading activities. Neither the Fund nor the Advisor will be liable for any losses resulting from rejected purchase orders.
By Mail
To make an initial purchase by mail, complete an account application and mail the application, together with a check made payable to Bluerock Total Income+ Real Estate Fund to:
Bluerock Total Income+ Real Estate Fund
c/o SS&C GIDS
P.O. Box 219445
Kansas City, MO 64121-9445
All checks must be in U.S. Dollars drawn on a domestic bank. The Fund will not accept payment in cash or money orders. The Fund also does not accept cashier’s checks in amounts of less than $10,000. To prevent check fraud, the Fund will neither accept third party checks, Treasury checks, credit card checks, traveler’s checks or starter checks for the purchase of shares, nor post-dated checks, post-dated on-line bill pay checks, or any conditional purchase order or payment.
The Transfer Agent will charge a $25 fee against an investor’s account, in addition to any loss sustained by the Fund, for any payment that is returned. It is the policy of the Fund not to accept applications under certain circumstances or in amounts considered disadvantageous to shareholders. The Fund reserves the right to reject any application.
30 |
By Wire — Initial Investment
To make an initial investment in the Fund, the Transfer Agent must receive a completed account application before an investor wires funds. Investors may mail or overnight deliver an account application to the Transfer Agent. Upon receipt of the completed account application, the Transfer Agent will establish an account. The account number assigned will be required as part of the instruction that should be provided to an investor’s bank to send the wire. An investor’s bank must include both the name of the Fund, the account number, and the investor’s name so that monies can be correctly applied. If you wish to wire money to make an investment in the Fund, please call the Fund at 1-844-819-8287 for wiring instructions and to notify the Fund that a wire transfer is coming. Any commercial bank can transfer same-day funds via wire. The Fund will normally accept wired funds for investment on the day received if they are received by the Fund’s designated bank before the close of regular trading on the NYSE. Your bank may charge you a fee for wiring same-day funds. The bank should transmit funds by wire to:
ABA #: (number provided by calling toll-free number above)
Credit: SS&C GIDS
Account #: (number provided by calling toll-free number above)
Further Credit:
Bluerock Total Income+ Real Estate Fund
(shareholder registration)
(shareholder account number)
By Wire — Subsequent Investments
Before sending a wire, investors must contact the Transfer Agent to advise them of the intent to wire funds. This will ensure prompt and accurate credit upon receipt of the wire. Wired funds must be received prior to 4:00 p.m. Eastern Time to be eligible for same day pricing. The Fund, and its agents, including the transfer agent and custodian, are not responsible for the consequences of delays resulting from the banking or Federal Reserve wire system, or from incomplete wiring instructions.
Automatic Investment Plan — Subsequent Investments
You may participate in the Fund’s Automatic Investment Plan, an investment plan that automatically moves money from your bank account and invests it in the Fund through the use of electronic funds transfers or automatic bank drafts. You may elect to make subsequent investments by transfers of a minimum of $100 on specified days of each month into your established Fund account. Please contact the Fund at 1-844-819-8287 for more information about the Fund’s Automatic Investment Plan.
By Telephone
Investors may purchase additional shares of the Fund by calling 1-844-819-8287. If an investor elected this option on the account application, and the account has been open for at least 15 days, telephone orders will be accepted via electronic funds transfer from your bank account through the Automated Clearing House (ACH) network. Banking information must be established on the account prior to making a purchase. Orders for shares received prior to 4:00 p.m. Eastern Time will be purchased at the appropriate price calculated on that day.
Telephone trades must be received by or prior to market close. During periods of high market activity, shareholders may encounter higher than usual call waits. Please allow sufficient time to place your telephone transaction.
In compliance with the USA Patriot Act of 2001, the Transfer Agent will verify certain information on each account application as part of the Fund’s Anti-Money Laundering Program. As requested on the application, investors must supply full name, date of birth, social security number and permanent street address. Mailing addresses containing only a P.O. Box will not be accepted. Investors may call the Transfer Agent (SS&C GIDS) at 1-844-819-8287 for additional assistance when completing an application.
If the Transfer Agent does not have a reasonable belief of the identity of a customer, the account will be rejected or the customer will not be allowed to perform a transaction on the account until such information is received. The Fund also may reserve the right to close the account within 5 business days if clarifying information/documentation is not received.
Share Class Considerations
When selecting a share class, you should consider the following:
|
● |
which share classes are available to you; |
|
● |
the amount you intend to invest; |
|
● |
how long you expect to own the shares; and |
|
● |
total costs and expenses associated with a particular share class. |
Each investor’s financial considerations are different. You should speak with your financial advisor to help you decide which share class is best for you. Not all financial intermediaries offer all classes of shares. If your financial intermediary offers more than one class of shares, you should carefully consider which class of shares to purchase.
31 |
Class A Shares
Class A shares are sold at the prevailing net asset value per Class A share plus the applicable sales load (which may be reduced as described below); however, the following are additional features that should be taken into account when purchasing Class A shares:
|
● |
a minimum initial investment of $2,500 for regular accounts and $1,000 for retirement plan accounts, and a minimum subsequent investment of at least $100 for regular accounts and $50 for retirement plan accounts; |
|
● |
a monthly shareholder servicing fee at an annual rate of up to 0.25% of the average daily net assets of the Fund attributable to Class A shares; and |
|
● |
Investors in Class A shares may pay a sales load based on the amount of their investment up to 5.75%, as set forth in the table below. A reallowance will be made by the Distributor from the sales load paid by each investor. There are no sales loads on reinvested distributions. The Fund reserves the right to waive sales loads. The following sales loads apply to your purchases of Class A shares of the Fund: |
Amount |
Broker Commission / |
Dealer Manager Fee |
Sales Load as % of |
Sales Load as % of |
Under $100,000 |
5.00% |
0.75% |
5.75% |
6.10% |
$100,000-$249,999 |
4.00% |
0.75% |
4.75% |
4.99% |
$250,000-$499,999 |
3.00% |
0.75% |
3.75% |
3.90% |
$500,000-$999,999 |
2.00% |
0.50% |
2.50% |
2.56% |
$1,000,000 and Above |
0.00%* |
0.00% |
0.00% |
0.00% |
|
* |
Selling brokers, or other financial intermediaries that have entered into distribution agreements with the Distributor may receive a commission of up to 1.00% of the purchase price of Class A shares. |
You may be able to buy Class A shares without a sales charge (i.e. “load-waived”) when you are:
|
● |
reinvesting dividends or distributions; |
|
● |
participating in an investment advisory or agency commission program under which you pay a fee to an investment advisor or other firm for portfolio management or brokerage services; |
|
● |
exchanging an investment in Class A (or equivalent type) shares of another fund for an investment in the Fund; |
|
● |
a current or former director or Trustee of the Fund; |
|
● |
an employee (including the employee’s spouse, domestic partner, children, grandchildren, parents, grandparents, siblings, and any dependent of the employee, as defined in section 152 of the Internal Revenue Code) of the Advisor or its affiliates or of a broker-dealer authorized to sell shares of the Fund; or |
|
● |
a client of the Advisor; or |
|
● |
purchasing shares through a financial services firm (such as a broker-dealer, investment advisor or financial institution) that has a special arrangement with the Fund. |
In addition, concurrent purchases of Class A shares by related accounts may be combined to determine the application of the sales load. The Fund will combine purchases made by an investor, the investor’s spouse or domestic partner, and dependent children when it calculates the sales load.
It is the investor’s responsibility to determine whether a reduced sales load would apply. The Fund is not responsible for making such determination. To receive a reduced sales load, notification must be provided at the time of the purchase order. If you purchase Class A shares directly from the Fund, you must notify the Fund in writing. Otherwise, notice should be provided to the Financial Intermediary through whom the purchase is made so they can notify the Fund.
Right of Accumulation
For the purposes of determining the applicable reduced sales charge, the right of accumulation allows you to include prior purchases of Class A shares of the Fund as part of your current investment as well as reinvested dividends. To qualify for this option, you must be either:
|
● |
an individual; |
|
● |
an individual and spouse purchasing shares for your own account or trust or custodial accounts for your minor children; or |
|
● |
a fiduciary purchasing for any one trust, estate or fiduciary account, including employee benefit plans created under Sections 401, 403 or 457 of the Internal Revenue Code, including related plans of the same employer. |
For example, the following illustrates the operation of the right of accumulation:
If a shareholder owned Class A shares of the Fund through an investment of $99,999 (including sales charge) and wished to purchase additional Class A shares of the Fund through an investment of $50,000 (including sales charge), the sales charge applicable on the $50,000 purchase would be at the 4.75% rate, rather than the 5.75% rate that would otherwise apply to a $50,000 purchase. The discount will be applied to the current purchase (i.e., the $50,000 purchase), not to any previous transaction.
32 |
You may add the current value of all of your existing investments in the Fund and certain other funds advised by the Advisor or its affiliates (collectively, “Bluerock Family Funds”) to determine the front-end sales charge to be applied to your current Class A purchase. Only balances currently held entirely at the Bluerock Family Funds or, if held in an account through a financial services firm, at the same firm through whom you are making your current purchase, will be eligible to be added to your current purchase for purposes of determining your Class A sales charge. You may include the value of Bluerock Family Funds’ investments held by the members of your immediately family, including the value of Bluerock Family Funds’ investments held by you or them in individual retirement plans, such as individual retirement accounts, or IRAs, provided such balances are also currently held entirely at the Bluerock Family Funds or, if held in an account through a financial services firm, at the same financial services firm through whom you are making your current purchase. The value of shares eligible for a cumulative quantity discount equals the cumulative cost of the shares purchased (not including reinvested dividends) or the current account market value; whichever is greater. The current market value of the shares is determined by multiplying the number of shares by the previous day’s NAV. If you believe there are cumulative quantity discount eligible shares that can be combined with your current purchase to achieve a sales charge breakpoint, you must, at the time of your purchase (including at the time of any future purchase) specifically identify those shares to your current purchase broker-dealer.
If you plan to rely on this right of accumulation, you must notify the Fund’s distributor at the time of your purchase. You will need to give the Distributor your account numbers. Existing holdings of family members or other related accounts of a shareholder may be combined for purposes of determining eligibility. If applicable, you will need to provide the account numbers of your spouse and your minor children as well as the ages of your minor children.
Letter of Intent
The letter of intent allows you to count all investments within a 13-month period in Class A shares of the Fund as if you were making them all at once for the purposes of calculating the applicable reduced sales charges. The minimum initial investment under a letter of intent is 5% of the total letter of intent amount. The letter of intent does not preclude the Fund from discontinuing sales of its shares. You may include a purchase not originally made pursuant to a letter of intent under a letter of intent entered into within 90 days of the original purchase. To determine the applicable sales charge reduction, you also may include (1) the cost of Class A shares of the Fund which were previously purchased at a price including a front end sales charge during the 90-day period prior to the Distributor receiving the letter of intent, and (2) the historical cost of shares of other Funds you currently own acquired in exchange for Class A shares the Fund purchased during that period at a price including a front-end sales charge. You may combine purchases and exchanges by family members (limited to spouse and children, under the age of 21, living in the same household). You should retain any records necessary to substantiate historical costs because the Fund, the transfer agent and any financial intermediaries may not maintain this information. Shares acquired through reinvestment of dividends are not aggregated to achieve the stated investment goal.
Share Conversion
For investors currently owning Class A, Class C, Class L and/or Class M shares, these shares may be convertible into Class I shares if (i) the broker/dealer or other financial intermediary responsible for the shareholder relationship requests such conversion, (ii) Class I shares are available to the broker dealer or financial intermediary, and (iii) the account would have been eligible to purchase Class I shares. More detailed information on Class I shares and the related investment minimums and other restrictions is available in the Fund’s Class I prospectus.
Shareholder Service Plan
The Fund has adopted a “Shareholder Services Plan” with respect to its Class A shares under which the Fund may compensate financial industry organizations for providing ongoing shareholder servicing of client accounts with whom they have distributed shares of the Fund. Such services may include electronic processing of client orders, electronic fund transfers between clients and the Fund, account reconciliations with the Fund’s transfer agent, facilitation of electronic delivery to clients of Fund documentation, monitoring client accounts for back-up withholding and any other special tax reporting obligations, maintenance of books and records with respect to the foregoing, and such other information and liaison services as the Fund or the Advisor may reasonably request. Under the Shareholder Services Plan, the Fund, with respect to its Class A shares, may incur expenses on an annual basis equal up to 0.25% of its average net assets attributable to Class A shares. Because these fees are paid from the Fund’s assets on an ongoing basis they will increase your costs over time and may cost you more than paying other types of sales charges.
LEGAL MATTERS
Certain legal matters in connection with the shares will be passed upon for the Fund by Thompson Hine LLP, 41 South High Street, Suite 1700, Columbus, Ohio 43215.
REPORTS TO SHAREHOLDERS
The Fund makes available to its shareholders unaudited semi-annual and audited annual reports, including a list of investments held.
Householding
If you have elected to receive paper copies of the Fund’s annual and semi-annual reports, in an effort to decrease costs, the Fund intends to send only one copy of each to those addresses shared by two or more accounts and to shareholders reasonably believed to be from the same family or household. A shareholder must call 1-844-819-8287 to discontinue householding and request individual copies of these documents. Once the Fund receives notice to stop householding, individual copies will be sent beginning thirty days after receiving your request. This policy does not apply to account statements.
33 |
INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
Cohen & Company, Ltd. is the independent registered public accounting firm for the Fund and audits the Fund’s financial statements. Cohen & Company, Ltd. is located at 1835 Market St., Suite 310, Philadelphia, PA 19103.
ADDITIONAL INFORMATION
The Prospectus and the Statement of Additional Information do not contain all of the information set forth in the Registration Statement that the Fund has filed with the SEC (file No. 811-22710). The complete Registration Statement may be obtained from the SEC at www.sec.gov. See the cover page of this prospectus for information about how to obtain a paper copy of the Registration Statement or Statement of Additional Information without charge.
TABLE OF CONTENTS OF THE STATEMENT OF ADDITIONAL INFORMATION
[To Be Updated]
General Information and History |
1 |
Investment Objectives and Policies |
2 |
Repurchases and Transfers of Shares |
9 |
Management of the Fund |
15 |
Codes of Ethics |
22 |
Proxy Voting Policies and Procedures |
22 |
Control Persons and Principal Holders |
22 |
Investment Advisory and Other Services |
23 |
Portfolio Managers |
27 |
Allocation of Brokerage |
31 |
Tax Status |
31 |
Other Information |
34 |
Independent Registered Public Accounting Firm |
35 |
Financial Statements |
35 |
Appendix A |
A-1 |
Appendix B |
B-1 |
34 |
PRIVACY POLICY & PRACTICES
Rev. January 2019
PRIVACY NOTICE
FACTS |
WHAT DOES THE BLUEROCK TOTAL INCOME+ REAL ESTATE FUND DO WITH YOUR PERSONAL INFORMATION? |
|
Why? |
Financial companies choose how they share your personal information. Federal law gives consumers the right to limit some but not all sharing. Federal law also requires us to tell you how we collect, share, and protect your personal information. Please read this notice carefully to understand what we do. |
|
What? |
The types of personal information we collect and share depend on the product or service you have with us. This information can include: |
|
● Social Security number
● Assets
● Retirement Assets
● Transaction History
● Checking Account Information |
● Purchase History
● Account Balances
● Account Transactions
● Wire Transfer Instructions |
|
When you are no longer our customer, we may continue to share your personal information as described in this notice. |
||
How? |
All financial companies need to share customers’ personal information to run their everyday business. In the section below, we list the reasons financial companies can share their customers’ personal information; the reasons the Bluerock Total Income+ Real Estate Fund chooses to share; and whether you can limit this sharing. |
|
Reasons we can share your personal information |
Does Bluerock Total Income+ Real Estate Fund share? |
Can you limit this sharing? |
For our everyday business purposes – such as to process your transactions, maintain your account(s), respond to court orders and legal investigations, or report to credit bureaus |
Yes |
No |
For our marketing purposes – to offer our products and services to you |
No |
We don’t share |
For joint marketing with other financial companies |
No |
We don’t share |
For our affiliates’ everyday business purposes – information about your transactions and experiences |
No |
We don’t share |
For our affiliates’ everyday business purposes – information about your creditworthiness |
No |
We don’t share |
For nonaffiliates to market to you |
No |
We don’t share |
Questions? |
Call 1-844-819-8287 |
35 |
Who we are |
|
Who is providing this notice? |
Bluerock Total Income+ Real Estate Fund |
What we do |
|
How does Bluerock Total Income+ Real Estate Fund protect my personal information? |
To protect your personal information from unauthorized access and use, we use security measures that comply with federal law. These measures include computer safeguards and secured files and buildings.
Our service providers are held accountable for adhering to strict policies and procedures to prevent any misuse of your nonpublic personal information. |
How does Bluerock Total Income+ Real Estate Fund collect my personal information? |
We collect your personal information, for example, when you
● Open an account
● Provide account information
● Give us your contact information
● Make deposits or withdrawals from your account
● Make a wire transfer
● Tell us where to send the money
● Tells us who receives the money
● Show your government-issued ID
● Show your driver’s license
We also collect your personal information from other companies. |
Why can’t I limit all sharing? |
Federal law gives you the right to limit only
● Sharing for affiliates’ everyday business purposes – information about your creditworthiness
● Affiliates from using your information to market to you
● Sharing for nonaffiliates to market to you
State laws and individual companies may give you additional rights to limit sharing. |
Definitions |
|
Affiliates |
Companies related by common ownership or control. They can be financial and nonfinancial companies.
● Bluerock Total Income+ Real Estate Fund does not share with our affiliates. |
Nonaffiliates |
Companies not related by common ownership or control. They can be financial and nonfinancial companies
● Bluerock Total Income+ Real Estate Fund does not share with nonaffiliates so they can market to you. |
Joint marketing |
A formal agreement between nonaffiliated financial companies that together market financial products or services to you.
● Bluerock Total Income+ Real Estate Fund doesn’t jointly market. |
36 |
Page Intentionally Left Blank
BLUEROCK TOTAL INCOME+ REAL ESTATE FUND
Class A Shares (TIPRX) of Beneficial Interest
PROSPECTUS
February 1, 2025
Investment Advisor
Bluerock Fund Advisor, LLC
All dealers that buy, sell or trade the Fund’s shares, whether or not participating in this offering, may be required to deliver a prospectus when acting on behalf of the Fund’s Distributor.
You should rely only on the information contained in or incorporated by reference into this prospectus. The Fund has not authorized any other person to provide you with different information. If anyone provides you with different or inconsistent information, you should not rely on it. The Fund is not making an offer to sell these securities in any jurisdiction where the offer or sale is not permitted.

Bluerock Total Income+ Real Estate Fund (the “Fund”) is a continuously offered, non-diversified, closed-end management investment company that is operated as an interval fund.
The Securities and Exchange Commission has not approved or disapproved these securities or determined if this Prospectus is truthful or complete. Any representation to the contrary is a criminal offense.
This prospectus is intended to concisely provide you, a prospective investor, with information about the Fund that you should know before investing in the shares of the Fund that are being offered through this prospectus. You are advised to thoroughly and carefully read this prospectus and retain it for future reference. Additional information about the Fund is also available on the Securities and Exchange Commission’s (“SEC”) website at http://www.sec.gov, including the Fund’s Statement of Additional Information dated February 1, 2025 (the “SAI”). The address of the SEC’s website is provided solely for the information of prospective shareholders and is not intended to be an active link. The table of contents of the SAI appears on page 32 of this prospectus. The SAI is incorporated by reference into this prospectus (legally made a part of this prospectus). The SAI, Fund annual and semi-annual reports and other information and shareholder inquiries regarding the Fund may be requested free of charge by writing the Fund at c/o SS&C Global Investor & Distribution Solutions, Inc. PO Box 219445, Kansas City, MO 64121-9445 (the “Transfer Agent” or “SS&C GIDS”), by calling the Transfer Agent toll-free at 1-844-819-8287, or by visiting the Fund’s website at http://www.bluerockfunds.com.
Investment Objectives. The Fund’s primary investment objective is to generate current income while secondarily seeking long-term capital appreciation with low to moderate volatility and low correlation to the broader markets.
Summary of Investment Strategy. The Fund pursues its investment objectives using a comprehensive multi-strategy, multi-manager, multi-sector approach, primarily investing in a strategic combination of what the Fund’s advisor believes are global ‘best in class’ institutional private real estate funds and public real estate securities.
The Advisor. The Fund’s investment advisor is Bluerock Fund Advisor, LLC (the “Advisor”), a registered advisor under the Investment Advisers Act of 1940, as amended (the “Advisers Act”). The Advisor has engaged Mercer Investments, LLC (“Mercer” or a “Sub-Advisor”), a registered advisor under the Advisers Act, to provide ongoing research, opinions and recommendations of institutional asset managers and their investment funds for consideration by the Advisor on behalf of the Fund. Mercer, together with its affiliated investment businesses, have over 5,600 delegated and advisory clients globally with over $547 billion in assets under management as of September 30, 2024 and over $17.5 trillion in assets under advisement as of June 30, 2024. The Advisor has also engaged RREEF America L.L.C. (“RREEF” or a “Sub-Advisor”), a registered adviser under the Advisers Act, to provide investment management for a portion, generally less than 20%, of the Fund’s portfolio. RREEF, together with its affiliates in Europe and Asia, comprise the global real estate investment business of DWS Group GmbH & Co. KGaA (“DWS”), an indirect majority owned subsidiary of Deutsche Bank A.G. DWS’s real estate investment business, is one of the largest real estate investment managers globally with more than 330 professionals and staff located in 23 cities worldwide and approximately $78.9 billion in real estate and real estate-related assets under management as of September 30, 2024.
See “The Fund” and “Investment Objectives, Strategies and Investment Features.”
Securities Offered. The Fund engages in a continuous offering of classes of shares of beneficial interest of the Fund. Class C shares are offered by this prospectus. The Fund offers Class A, Class I, Class L and Class M shares by different prospectuses. The Fund is authorized as a Delaware statutory trust to issue an unlimited number of shares. The Fund is offering to sell, through its principal underwriter, ALPS Distributors, Inc., (the “Distributor”) on a continual basis under the terms of this prospectus, shares of beneficial interest at net asset value (“NAV”) per share of the relevant share class, plus any applicable sales load. As of January 3, 2025, the Fund’s NAV per share was $ 24.05 for Class C shares. The Class C shares are not subject to sales charges. The minimum initial investment by a shareholder for Class C shares is $2,500 for regular accounts and $1,000 for retirement plan accounts. Subsequent investments may be made with at least $100 for regular accounts and for retirement plan accounts. The Distributor is not required to sell any specific number or dollar amount of the Fund’s shares, but will use reasonable efforts to sell the shares. No termination date of the Fund’s continuous offering has been established. Monies received will be invested promptly and no arrangements have been made to place such monies in an escrow, trust or similar account.
The Fund’s shares have no history of public trading, nor is it intended that they will be listed on a public exchange at this time. No secondary market is expected to develop for the Fund’s shares, liquidity for the Fund’s shares will be provided only through quarterly repurchase offers for no less than 5% of the Fund’s shares and there is no guarantee that an investor will be able to sell all the shares that the investor desires to sell in the repurchase offer. Investing in the Fund’s shares involves substantial risks, including the risks set forth in the “Risk Factors” section of this prospectus.
|
Investment Advisor | Bluerock Fund Advisor, LLC |

TABLE OF CONTENTS
PROSPECTUS SUMMARY |
1 |
SUMMARY OF FUND EXPENSES |
7 |
FINANCIAL HIGHLIGHTS |
8 |
THE FUND |
9 |
USE OF PROCEEDS |
9 |
INVESTMENT OBJECTIVE, POLICIES AND STRATEGIES |
9 |
RISK FACTORS |
13 |
MANAGEMENT OF THE FUND |
18 |
DETERMINATION OF NET ASSET VALUE |
23 |
CONFLICTS OF INTEREST |
24 |
QUARTERLY REPURCHASES OF SHARES |
24 |
DISTRIBUTION POLICY |
26 |
DIVIDEND REINVESTMENT POLICY |
26 |
U.S. FEDERAL INCOME TAX MATTERS |
27 |
DESCRIPTION OF CAPITAL STRUCTURE AND SHARES |
28 |
ANTI-TAKEOVER PROVISIONS IN THE DECLARATION OF TRUST |
28 |
PLAN OF DISTRIBUTION |
29 |
LEGAL MATTERS |
31 |
REPORTS TO SHAREHOLDERS |
32 |
INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM |
32 |
ADDITIONAL INFORMATION |
32 |
TABLE OF CONTENTS OF THE STATEMENT OF ADDITIONAL INFORMATION |
32 |
PRIVACY POLICY & PRACTICES |
33 |
PROSPECTUS SUMMARY
This summary does not contain all of the information that you should consider before investing in the shares. You should review the more detailed information contained or incorporated by reference in this prospectus and in the Statement of Additional Information, particularly the information set forth below under the heading “Risk Factors.”
The Fund
Bluerock Total Income+ Real Estate Fund (the “Fund”) is a continuously offered, non-diversified, closed-end management investment company. See “The Fund.” The Fund is an interval fund that provides investor liquidity by offering to make quarterly repurchases of each class of shares at that class of shares’ net asset value, which will be calculated on a daily basis. See “Quarterly Repurchases of Shares,” and “Determination of Net Asset Value.”
Investment Objectives and Policies
The Fund’s primary investment objective is to generate current income while secondarily seeking long-term capital appreciation with low to moderate volatility and low correlation to the broader markets.
The Fund pursues its investment objectives by investing, under normal circumstances, at least 80% of net assets, plus the amount of any borrowings for investment purposes, in “real estate industry securities,” primarily in income producing equity and debt securities. The Fund invests in debt securities of any duration or maturity.
The Fund concentrates investments in the real estate industry, meaning that under normal circumstances, it invests over 25% of its assets in real estate industry securities. The Fund’s investments may be targeted in any one or more of the many sectors of the real estate market, including but not limited to the retail, office, multifamily, hospitality, industrial, residential, healthcare, life sciences and self-storage sectors. The Fund defines real estate industry securities to include the common stock, partnership or similar interests, asset-backed securities, preferred stock, and secured or unsecured debt. Real estate industry securities may be issued by a wide variety of entities including: private real estate investment funds managed by institutional investment managers (“Institutional Investment Funds”); non-traded unregistered real estate investment trusts (“Private REITs”); publicly traded real estate investment trusts or other similar companies (“Public REITs”); Government Sponsored Entities (“GSEs”) such as Federal Home Loan Mortgage Corporation Structured Pass-Through Certificates (“K-Notes”); exchange traded funds, index mutual funds, and other investment vehicles such as closed-end funds and mutual funds that invest principally, directly or indirectly, in real estate (collectively, “Other Public Investment Vehicles”) and unregistered funds that invest principally in real estate. In certain circumstances or market environments, the Fund may reduce its investment in real estate industry securities and hold a larger position in cash or cash equivalents. The Fund will not invest in any issuer that is an affiliate of the Fund, or affiliate of a Fund affiliate (as defined by the Investment Company Act of 1940, as amended (the “1940 Act”)).
The Fund’s real estate industry investment policy is fundamental and may not be changed without shareholder approval. The Fund’s Statement of Additional Information (“SAI”) contains a list of all of the fundamental and non-fundamental investment policies of the Fund, under the heading “Investment Objectives and Policies.”
Investment Strategy
The Fund pursues its investment objectives using a comprehensive multi-strategy, multi-manager, multi-sector approach, primarily investing in a strategic combination of global ‘best in class’ institutional private real estate investment funds and public real estate securities.
The term ‘best in class’ refers to Institutional Investment Funds the Advisor has identified as offering above average prospects using information provided by Mercer and its proprietary screening process. Mercer’s screening process applies multiple factors including quantitative and qualitative assessment (as described more fully below) of the management team and track record, and is not generally available to the individual investor through financial filings or published reports. Mercer is one of the leading advisors to endowments, pension funds, sovereign wealth funds, and family offices globally.
The Fund executes a portion of its investment strategy, generally less than 20%, by seeking to invest in publicly traded real estate securities selected by RREEF, an indirect subsidiary of DWS. RREEF seeks to maximize risk-adjusted returns by managing volatility and identifying securities that are priced inefficiently relative to its assessment of intrinsic value and the public real estate securities may be of any credit quality; including fixed-income and preferred securities rated less than investment grade that are sometimes referred to as high yield or “junk bonds.” The Advisor or RREEF will sell a security when other securities are available that offer higher expected current income, long-term capital appreciation, lower volatility or lower correlation to broader securities markets or a combination of the preceding.
The Fund may utilize leverage through borrowing for investment purposes or to satisfy repurchase requests. The Fund currently borrows money under two credit facilities.
Many of the Institutional Investment Funds have a large minimum investment size and stringent investor qualification criteria that are intended to limit their direct investors to mainly institutions such as endowments and pension funds. As such, the Fund enables investors to invest with institutional investment managers that may not be otherwise permitted or available to them.
In addition, the Fund enables investors to execute a comprehensive multi-strategy, multi-manager, multi-sector strategy by making a single investment in the Fund, whereas due to the large minimums of many of the Institutional Investment Funds, such a strategy may not otherwise be permitted or available to the investor.
1 |
The Advisor also believes that the Fund may be able to provide an additional benefit in terms of lower fees from the Institutional Investment Funds as a result of volume discounts that may not otherwise be permitted or available to them.
Investment Advisor
Bluerock Fund Advisor, LLC was formed on May 11, 2012 and is registered with the SEC as an investment adviser. The Advisor is a subsidiary of Bluerock Asset Management, LLC (“BAM”); BAM together with its affiliates (“Bluerock”), is a leading institutional alternative asset manager with more than $19.2 billion in acquired and managed assets based in New York with regional offices across the United States. Bluerock principals have a collective 100+ years of investing experience with more than $120 billion of real estate and capital markets experience and manage multiple well-recognized real estate private and public company platforms.
Sub-Advisors
The Advisor may, from time to time, engage one or more investment sub-advisors. Any sub-advisor chosen by the Advisor will be paid by the Advisor on only the portion of Fund assets allocated to any such sub-advisor. Shareholders do not pay any sub-advisor directly.
The Advisor has engaged Mercer, a registered investment adviser under the Advisers Act, to provide both ongoing research and opinions of institutional asset managers and their investment funds for consideration by the Advisor on behalf of the Fund as well as recommendations for the selection of investment funds for approval by the Advisor. The Advisor has engaged RREEF, a registered investment adviser under the Advisers Act, to invest a portion of the Fund’s portfolio in publicly traded real estate securities and to provide the Advisor with research and information with respect to non-publicly traded real estate related debt securities.
Advisor Fees and Expenses
The Advisor is entitled to receive a monthly fee at the annual rate of 1.50% of the Fund’s daily net assets. The Advisor and the Fund have entered into an expense limitation and reimbursement agreement (the “Expense Limitation Agreement”) under which the Advisor has contractually agreed to waive its fees and to pay or absorb the ordinary operating expenses of the Fund (excluding any taxes, interest, brokerage commissions, acquired fund fees and expenses, and extraordinary expenses, such as litigation or reorganization costs, but including organizational costs and offering costs), to the extent that such expenses exceed 2.70% per annum of the Fund’s average daily net assets (the “Expense Limitation”) attributable to Class C shares. In consideration of the Advisor’s agreement to limit the Fund’s expenses, the Fund has agreed to repay the Advisor in the amount of any fees the Advisor previously waived or Fund expenses reimbursed, subject to the limitations that: (1) the reimbursement will be made if payable not more than three years from the date incurred; (2) the reimbursement may not be made if it would cause the expense limitation then in effect or in effect at the time of the waiver to be exceeded; and (3) the reimbursement is approved by the Fund’s Board of Trustees (the “Board”). The Expense Limitation Agreement will remain in effect at least until January 31, 2026, unless and until the Board approves its modification or termination. After January 31, 2026, the Expense Limitation Agreement may be renewed at the Advisor’s and Board’s discretion. See “Management of the Fund.”
Administrator, Accounting Agent and Transfer Agent
ALPS Fund Services, Inc. (the “Administrator”) serves as the Fund’s administrator and accounting agent. SS&C Global Investor & Distribution Solutions, Inc. (the “Transfer Agent” or “SS&C GIDS”) serves as the transfer agent of the Fund. See “Management of the Fund.”
Distribution Fees
Class C shares will pay to the Distributor a distribution fee (the “Distribution Fee”) that will accrue at an annual rate equal to 0.75% of the Fund’s average daily net assets attributable to Class C shares and is payable on a monthly basis. See “Plan of Distribution.”
Closed-End Fund Structure
Generally, closed-end funds differ from mutual funds in that closed-end funds do not typically redeem their shares at the option of the shareholder. Closed-end fund shares typically trade in the secondary market via a stock exchange. Unlike many closed-end funds, however, the Fund’s shares will not be listed on a stock exchange. Instead, the Fund will provide limited liquidity to shareholders by offering to repurchase a limited amount of the Fund’s shares (at least 5%) quarterly, which is discussed in more detail below. The Fund, similar to a mutual fund, is subject to continuous asset in-flows, although not subject to continuous out-flows.
Share Classes
The Fund offers Class C shares by this prospectus. The Fund began continuously offering its common shares on October 22, 2012. As of February 18, 2014, the Fund simultaneously redesignated its issued and outstanding common shares as Class A shares and created its Class C shares and Class I shares, each offered by a separate prospectus. As of May 30, 2017, the Fund created its Class L shares. As of February 1, 2020, the Fund created its Class M shares. An investment in any share class of the Fund represents an investment in the same assets of the Fund. However, the sales loads and ongoing fees and expenses for each share class are different. The loads, fees and expenses for the Fund are set forth in “Summary of Fund Expenses.” If an investor has hired an intermediary and is eligible to invest in more than one class of shares, the intermediary may help determine which share class is appropriate for that investor. When selecting a share class, you should consider which share classes are available to you, how much you intend to invest, the investment minimum, how long you expect to own shares, and the total costs and expenses associated with a particular share class.
2 |
Each investor’s financial considerations are different. You should speak with your financial advisor to help you decide which share class is best for you. Not all financial intermediaries offer all classes of shares and all share classes may not be available in every state. If your financial intermediary offers more than one class of shares, you should carefully consider which class of shares to purchase.
Investor Suitability
An investment in the Fund involves a considerable amount of risk. It is possible that you will lose some or all of your money. An investment in the Fund is suitable only for investors who can bear the risks associated with the limited liquidity of the shares and should be viewed as a medium to long-term investment. Before making your investment decision, you should (i) consider the suitability of this investment with respect to your investment objectives and personal financial situation and (ii) consider factors such as your personal net worth, income, age, risk tolerance and liquidity needs.
Repurchases of Shares
The Fund is an interval fund and, as such, has adopted a fundamental policy to make quarterly repurchase offers, at net asset value, of no less than 5% of the Fund’s outstanding shares. There is no guarantee that shareholders will be able to sell all of the shares they desire to sell in a quarterly repurchase offer. Liquidity will be provided to shareholders only through the Fund’s quarterly repurchases. See “Quarterly Repurchases of Shares.”
Summary of Risks
Investing in the Fund involves risks, including the risk that you may receive little or no return on your investment or that you may lose part or all of your investment. Before investing you should consider carefully the risks that you assume when you invest in the Fund’s shares. See “Risk Factors.”
Real Estate Industry Concentration Risk. The Fund will concentrate its investments in securities real estate industry issuers, and it may invest in real estate directly. As such, its portfolio will be significantly impacted by the performance of the real estate market and may experience more volatility and be exposed to greater risk than a more diversified portfolio. The value of companies engaged in the real estate industry is affected by: (i) changes in general economic and market conditions; (ii) changes in the value of real estate properties; (iii) risks related to local economic conditions, overbuilding and increased competition; (iv) increases in property taxes and operating expenses; (v) changes in zoning laws; (vi) casualty and condemnation losses; (vii) variations in rental income, neighborhood values or the appeal of property to tenants; (viii) the availability of financing; (ix) climate change and (x) changes in interest rates and leverage. There are also special risks associated with particular sectors, or real estate operations, including, but not limited to, those risks described below:
Retail Properties. Retail properties are affected by shifts in consumer demand due to demographic changes, changes in spending patterns and lease terminations.
Office Properties. Office properties are affected by a downturn in the businesses operated by their tenants.
Hospitality Properties. Hotel properties and other properties in the hospitality real estate sector, such as motels and extended-stay properties, are affected by declines in business and leisure travel.
Healthcare and Life Sciences Properties. Healthcare and life sciences properties are affected by potential federal, state and local laws governing licenses, certification, adequacy of care, pharmaceutical distribution, rates, equipment, personnel and other factors regarding operations, funding for biotech companies and the continued availability of revenue from government reimbursement programs.
Industrial Properties. Industrial properties are affected by downturns in the manufacturing, processing and shipping of goods.
Multifamily Properties. Multifamily properties are affected by adverse economic conditions in the locale, oversupply and rent control laws.
Residential Properties. Residential properties can be significantly affected by the national, regional and local real estate markets. This segment of the real estate industry also is sensitive to interest rate fluctuations which can cause changes in the availability of mortgage capital and directly affect the purchasing power of potential homebuyers. Thus, residential properties can be significantly affected by changes in government spending, consumer confidence, demographic patterns and the level of new and existing home sales.
Shopping Centers. Shopping center properties are affected by changes in the local markets where their properties are located and dependent upon the successful operations and financial condition of their major tenants.
Self-Storage Properties. Self-storage properties are affected by changes to competing local properties, consumer and small business demand for storage space, and the ability of the management team.
3 |
Other factors may contribute to the risk of real estate investments:
Development Issues. Real estate development companies in which the Underlying Funds (defined below) or the Fund may invest are affected by construction delays and insufficient tenant demand to occupy newly developed properties.
Lack of Insurance. Certain of the companies in the Fund’s portfolio may fail to carry comprehensive liability, fire, flood, wind or earthquake extended coverage and rental loss insurance, or insurance and may be subject to various policy specifications, limits and deductibles. Due to the prevalence of catastrophic events, the cost of insurance may increase materially.
Dependence on Tenants. The ability of companies in the real estate industry in which the Fund may invest to make distributions to shareholders depends upon the ability of the tenants at their properties to generate enough income in excess of tenant operating expenses to make their lease payments.
Financial Leverage. Companies in the real estate industry in which the Fund may invest may be highly leveraged and financial covenants may affect their ability to operate effectively. The use of floating rate loans may also negatively impact returns in a rising interest rate environment.
Environmental Issues. Owners of properties that may contain hazardous or toxic substances may be responsible for removal or remediation costs. Environmental risk from high winds, hurricanes, fires, flood and extreme heat may also materially affect a property’s value.
Credit Market Conditions. Instability in credit markets can potentially make it more difficult for borrowers to obtain financing or refinancing on attractive terms or at all. Conditions in the credit markets may expose borrowers to increased interest expenses for borrowed money and tightening underwriting standards. There is also a risk that a general lack of liquidity or other events in the credit markets may adversely affect the ability of issuers in whose securities the Fund invests to finance real estate developments and projects or refinance completed projects.
Market Risk. An investment in shares is subject to investment risk, including the possible loss of the entire principal amount invested. An investment in shares represents an indirect investment in the securities owned by the Fund. The value of these securities, like other market investments, may move up or down, sometimes rapidly and unpredictably. In addition, the Fund is subject to the risk that geopolitical and other similar events will disrupt the economy on a national or global level. For instance, war, terrorism, market manipulation, government defaults, government shutdowns, political changes or diplomatic developments, public health emergencies (such as the spread of infectious diseases, pandemics and epidemics) and natural/environmental disasters can all negatively impact the securities markets.
Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. The foregoing could impair the Fund’s ability to maintain operational standards, disrupt the operations of the Fund and its service providers, adversely affect the performance, value and liquidity of the Fund’s investments, and negatively impact the Fund’s performance and your investment in the Fund. The value of your shares at any point in time may be worth less than the value of your original investment, even after taking into account any reinvestment of dividends and distributions.
Liquidity Risk. There currently is no secondary market for the Fund’s shares and the Advisor does not expect that a secondary market will develop. Limited liquidity is provided to shareholders only through the Fund’s quarterly repurchase offers for no less than 5% of the Fund’s shares outstanding at net asset value. There is no guarantee that shareholders will be able to sell all of the shares they desire in a quarterly repurchase offer. The Fund’s investments also are subject to liquidity risk. Liquidity risk exists when particular investments of the Fund would be difficult to purchase or sell, possibly preventing the Fund from selling such illiquid securities at an advantageous time or price, or possibly requiring the Fund to dispose of other investments at unfavorable times or prices in order to satisfy its obligations.
Allocation Risk. The ability of the Fund to achieve its investment objective depends, in part, on the ability of the Advisor to allocate effectively the Fund’s assets among the various Institutional Investment Funds, Private REITs, Public REITs and Other Public Investment Vehicles in which the Fund invests and, with respect to each such asset class, among equity and fixed income securities. There can be no assurance that the actual allocations will be effective in achieving the Fund’s investment objective or delivering positive returns.
Correlation Risk. The Fund seeks to produce returns that are not correlated to the broader financial markets. Although the prices of equity securities and fixed-income securities, as well as other asset classes, often rise and fall at different times so that a fall in the price of one may be offset by a rise in the price of the other, in down markets the prices of these securities and asset classes can also fall in tandem. Because the Fund allocates its investments among different real estate asset classes, the Fund is subject to correlation risk.
Credit Risk. It is possible that issuers of debt securities may not make scheduled interest and principal payments, resulting in losses to the Fund. In addition, the credit quality of securities held may be lowered if an issuer’s financial condition changes and this also may negatively impact the Fund’s returns on investment in such securities.
Distribution Policy Risk. The Fund’s distribution policy is expected to result in distributions that equal a fixed percentage of the Fund’s current net asset value per share. All or a portion of a distribution may consist of a return of capital (i.e. from your original investment). Shareholders should not assume that the source of a distribution from the Fund is net profit. Shareholders should note that return of capital will reduce the tax basis of their shares and potentially increase the taxable gain, if any, upon disposition of their shares.
4 |
Fixed Income Risk. Typically, a rise in interest rates causes a decline in the value of fixed income securities. Recently, interest rates have risen sharply after maintaining historically low levels for a significant period of time. Current conditions may result in an increase in interest rate volatility, which in turn may result in a decline in the value of the fixed income investments held by the Fund. As a result, for the present, interest rate risk may be heightened. Fixed income securities are also subject to default risk.
Institutional Investment Fund Risk. The Fund’s investment in Institutional Investment Funds will require it to bear a pro rata share of the vehicles’ expenses, including management and performance fees. The fees the Fund pays to invest in an Institutional Investment Fund may be higher than if the manager of the Institutional Investment Fund managed the Fund’s assets directly. The performance fees charged by certain Institutional Investment Funds may create an incentive for its manager to make investments that are riskier and/or more speculative than those it might have made in the absence of a performance fee. Furthermore, Institutional Investment Funds, like the other “Underlying Funds” in which the Fund may invest, are subject to specific risks, depending on the nature of the vehicle, and also may employ leverage such that their returns are more than one times that of their benchmark which could amplify losses suffered by the Fund when compared to unleveraged investments. Shareholders of the Institutional Investment Funds are not entitled to the protections of the 1940 Act. For example, these funds need not have independent boards, shareholder approval of advisory contracts may not be required, may leverage to an unlimited extent, and may engage in joint transactions with affiliates. These characteristics present additional risks for shareholders.
Issuer and Non-Diversification Risk. The value of a specific security can perform differently from the market as a whole for reasons related to the investment manager or issuer, such as management performance, financial leverage and reduced demand for the respective properties and services. The Fund’s performance may be more sensitive to any single economic, business, political or regulatory occurrence than the value of shares of a diversified investment company because as a non-diversified fund, the Fund may invest more than 5% of its total assets in the securities of one or more issuers.
Lack of Control Over Institutional Investment Funds and Other Portfolio Investments. Once the Advisor or RREEF has selected an Institutional Investment Fund, Private REIT, Public REIT, or Other Public Investment Vehicle (each, an “Underlying Fund” and together, the “Underlying Funds”) for investment by the Fund, the Advisor and RREEF will have no control over the investment decisions made by any such Underlying Fund. Although the Fund and the Advisor or RREEF will evaluate regularly each Underlying Fund and its manager to determine whether their respective investment programs are consistent with the Fund’s investment objective, the Advisor and RREEF will not have any control over the investments made by any Underlying Fund. Even though the Underlying Funds are subject to certain constraints, the managers may change aspects of their investment strategies. The managers may do so at any time (for example, such change may occur immediately after providing the Advisor with the quarterly unaudited financial information for an Institutional Investment Fund). The Advisor or RREEF may reallocate the Fund’s investments among the Underlying Funds, but the Advisor’s ability to do so may be constrained by the withdrawal limitations imposed by certain of the Underlying Funds, which may prevent the Fund from reacting rapidly to market changes should an Underlying Fund fail to effect portfolio changes consistent with such market changes and the demands of the Advisor. Such withdrawal limitations may also restrict the Advisor’s ability to terminate investments in Underlying Funds that are poorly performing or have otherwise had adverse changes. The Advisor and RREEF will be dependent on information provided by the Underlying Fund, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s or RREEF’s ability to manage the Fund’s investment portfolio in accordance with its investment objectives.
Leveraging Risk. The use of leverage, such as borrowing money to purchase securities or otherwise invest the Fund’s assets, will cause the Fund to incur additional expenses and may significantly magnify the Fund’s losses in the event of adverse performance of the Fund’s underlying investments. In addition to any borrowing utilized by the Fund, the Underlying Funds in which the Fund invests may utilize leverage, subject to the limitations of their charters and operative documents. Leverage by Underlying Funds and/or the Fund has the effect of potentially increasing losses. In addition, interest rates (including benchmarks like Secured Overnight Financing Rate (“SOFR”) and the spreads to such benchmarks charged by lenders) are highly sensitive to external factors outside a borrower’s control, including general and local economic conditions (such as inflation, recession, money supply and unemployment) and the monetary and fiscal policies of various governmental agencies such as the Federal Reserve Board. During periods of increased interest rates, borrowing costs of the Fund will likely increase and may adversely affect the Fund’s performance.
Management Risk. The judgments of the Advisor or a Sub-Advisor about the attractiveness, value and potential appreciation of particular real estate segment and securities in which the Fund invests may prove to be incorrect and may not produce the desired results.
Possible Competition Between Underlying Funds and Between the Fund and the Underlying Funds. The Underlying Funds trade independently of each other and may pursue investment strategies that “compete” with each other for execution or that cause the Fund to participate in positions that offset each other (in which case the Fund would bear its pro rata share of commissions and fees without the potential for a profit). Also, the Fund’s investments in any particular Underlying Fund could increase the level of competition for the same trades that other Underlying Funds might otherwise make, including the priorities of order entry. This could make it difficult or impossible to take or liquidate a position in a particular security at a price consistent with the Advisor’s strategy.
Preferred Securities Risk. Preferred securities are subject to credit risk and interest rate risk. Interest rate risk is, in general, that the price of a debt security falls when interest rates rise. Securities with longer maturities tend to be more sensitive to interest rate changes. Credit risk is the risk that an issuer of a security may not be able to make principal and interest or dividend payments on the security as they become. Holders of preferred securities may not receive dividends, or the payment can be deferred for some period of time. In bankruptcy, creditors are generally paid before the holders of preferred securities.
REIT Risk. The value of investments in REIT shares may decline because of adverse developments affecting the real estate industry and real property values. In general, real estate values can be affected by a variety of factors, including supply and demand for properties, the economic health of the country or of different regions, and the strength of specific industries that rent properties. Also, qualification as a REIT under the Internal Revenue Code of 1986, as amended (the “Code”) in any particular year is a complex analysis that depends on a number of factors. There can be no assurance that an entity in which the Fund invests with the expectation
5 |
that it will be taxed as a REIT will, in fact, qualify as a REIT. An entity that fails to qualify as a REIT would be subject to a corporate level tax, would not be entitled to a deduction for dividends paid to its shareholders and would not pass through to its shareholders the character of income earned by the entity.
Repurchase Policy Risks. Quarterly repurchases by the Fund of its shares typically will be funded from available cash or sales of portfolio securities. The sale of securities to fund repurchases could reduce the market price of those securities, which in turn would reduce the Fund’s net asset value.
Underlying Funds Risk. Investments in real estate index funds (“Index Funds”), real estate exchange traded funds (“ETFs”), and Other Public Investment Vehicles are subject to investment advisory and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in such Other Public Investment Vehicles, and also may be higher than other funds that invest directly in securities. Further, Other Public Investment Vehicles are subject to specific risks, depending on the nature of the fund.
Valuation of Institutional Investment Funds. Institutional Investment Funds are not publicly traded and the Fund may consider information provided by the institutional asset manager to determine the value of the Fund’s investment therein. The valuation provided by an institutional asset manager as of a specific date may vary from the actual sale price that may be obtained if such investment were sold to a third party. To determine the value of the Fund’s investment in Institutional Investment Funds, the Advisor considers, among other things, information provided by the Institutional Investment Funds, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s ability to value accurately the Fund’s shares. Institutional Investment Funds that invest primarily in publicly traded securities are more easily valued.
U.S. Federal Income Tax Matters
The Fund intends to elect to be treated and to qualify each year for taxation as a regulated investment company under Subchapter M of the Code. In order for the Fund to so qualify, it must meet an income and asset diversification test each year. If the Fund so qualifies and satisfies the applicable distribution requirements, the Fund (but not its shareholders) will not be subject to federal income tax to the extent it distributes its investment company taxable income and net capital gains (the excess of net long-term capital gains over net short-term capital loss) in a timely manner to its shareholders in the form of dividends or capital gain distributions. The Code imposes a 4% nondeductible excise tax on regulated investment companies, such as the Fund, to the extent they do not meet certain distribution requirements by the end of each calendar year. The Fund anticipates meeting these distribution requirements. See “U.S. Federal Income Tax Matters.”
Distribution Policy
The Fund’s distribution policy is to make quarterly distributions to shareholders. The level of distributions (including any return of capital) is not fixed, but is expected to represent an annual rate of approximately 5.25% of the Fund’s current net asset value per share. However, this distribution policy is subject to change. Unless a shareholder elects otherwise, the shareholder’s distributions will be reinvested in additional shares of the same class under the Fund’s dividend reinvestment policy. Shareholders who elect not to participate in the Fund’s dividend reinvestment policy will receive all distributions in cash paid to the shareholder of record (or, if the shares are held in street or other nominee name, then to such nominee). See “Dividend Reinvestment Policy.”
Custodian
UMB Bank, N.A. (“UMB Bank”) serves as the custodian for the Fund. See “Management of the Fund.”
6 |
SUMMARY OF FUND EXPENSES
Shareholder Transaction Expenses |
Class C |
Maximum
Sales Load |
|
Maximum Early Withdrawal Charge (as a percent of original purchase price)1 |
Annual Expenses (as a percentage of net assets attributable to shares) |
|
Management Fees |
|
Other Expenses |
|
Shareholder Servicing Fee |
|
Distribution Fee2 |
|
Remaining Other Expenses |
|
Interest Payments on Borrowed Funds3 |
|
Acquired Fund Fees and Expenses |
|
Total Annual Expenses |
|
|
1. |
|
|
2. |
|
|
3. |
|
The above Summary of Fund Expenses table describes the fees and expenses that you may pay if you buy and hold shares of the Fund. More information about management fees, fee waivers and other expenses is available in Management of the Fund starting on page 18 of this prospectus.
The following example illustrates the hypothetical expenses that you would pay on a $1,000 investment assuming annual expenses attributable to shares remain unchanged and shares earn a 5% annual return:
Share Class |
1 Year |
3 Years |
5 Years |
10 Years |
Class C Shares |
$ |
$ |
$ |
$ |
|
1. |
|
Shareholders who choose to participate in repurchase offers by the Fund will not incur an early withdrawal charge, unless the repurchase is less than 365 days after purchase by a shareholder. However, if shareholders request repurchase proceeds be paid by wire transfer, such shareholders will be assessed an outgoing wire transfer fee at prevailing rates charged by the Transfer Agent, currently $10. The purpose of the above table is to help a holder of shares understand the fees and expenses that such holder would bear directly or indirectly. The example should not be considered a representation of actual future expenses. Actual expenses may be higher or lower than those shown.
7 |
FINANCIAL HIGHLIGHTS
Class C Shares
The financial highlights table below is intended to help you understand the Fund’s financial performance since its inception. Certain information reflects financial results for a single Share. The total returns in the table represent the rate that an investor would have earned (or lost) on an investment in the Fund (assuming reinvestment of all dividends and other distributions). This information has been derived from the Fund’s financial statements, which have been audited by Cohen & Company, Ltd., the Fund’s independent registered public accounting firm, whose report, along with the Fund’s financial statements, is included in the Fund’s Annual Report for the fiscal year ended September 30, 2024, which is available upon request.
|
For the |
For the |
For the |
For the |
For the |
For the |
For the |
For the |
For the |
For the |
||||||||||||||||||||||||||||||
Net asset value, beginning of year |
$ | 28.67 | $ | 34.85 | $ | 30.90 | $ | 27.89 | $ | 29.22 | $ | 29.02 | $ | 28.63 | $ | 28.61 | $ | 28.38 | $ | 27.89 | ||||||||||||||||||||
INCOME FROM INVESTMENT OPERATIONS: |
||||||||||||||||||||||||||||||||||||||||
Net investment income/(loss)(a) |
(0.50 | ) | (0.36 | ) | 0.12 | 0.26 | 0.23 | 0.10 | (0.01 | ) | 0.01 | (0.01 | ) | 0.16 | ||||||||||||||||||||||||||
Net realized and unrealized gain/(loss) |
(2.24 | ) | (4.16 | ) | 5.63 | 4.27 | (0.04 | ) | 1.63 | 1.93 | 1.52 | 1.75 | 1.82 | |||||||||||||||||||||||||||
Total from investment operations |
(2.74 | ) | (4.52 | ) | 5.75 | 4.53 | 0.19 | 1.73 | 1.92 | 1.53 | 1.74 | 1.98 | ||||||||||||||||||||||||||||
DISTRIBUTIONS: |
||||||||||||||||||||||||||||||||||||||||
From net investment income |
— | — | — | — | (0.06 | ) | — | — | — | — | (0.09 | ) | ||||||||||||||||||||||||||||
From net realized gain on investments |
(0.14 | ) | (0.19 | ) | (0.42 | ) | (0.63 | ) | (0.98 | ) | (0.32 | ) | (0.52 | ) | (0.37 | ) | (0.16 | ) | (0.29 | ) | ||||||||||||||||||||
Return of capital |
(1.25 | ) | (1.47 | ) | (1.38 | ) | (0.89 | ) | (0.48 | ) | (1.21 | ) | (1.01 | ) | (1.14 | ) | (1.35 | ) | (1.11 | ) | ||||||||||||||||||||
Total distributions |
(1.39 | ) | (1.66 | ) | (1.80 | ) | (1.52 | ) | (1.52 | ) | (1.53 | ) | (1.53 | ) | (1.51 | ) | (1.51 | ) | (1.49 | ) | ||||||||||||||||||||
Net asset value, end of year |
$ | 24.54 | $ | 28.67 | $ | 34.85 | $ | 30.90 | $ | 27.89 | $ | 29.22 | $ | 29.02 | $ | 28.63 | $ | 28.61 | $ | 28.38 | ||||||||||||||||||||
TOTAL RETURN(b)(c) |
(9.76 | )% | (13.26 | )% | 18.90 | % | 16.81 | % | 0.63 | % | 6.15 | % | 6.86 | % | 5.50 | % | 6.28 | % | 7.28 | % | ||||||||||||||||||||
RATIOS/SUPPLEMENTAL DATA: |
||||||||||||||||||||||||||||||||||||||||
Net assets, end of year (000s) |
$ | 397,749 | $ | 565,608 | $ | 706,009 | $ | 486,734 | $ | 437,183 | $ | 401,507 | $ | 290,549 | $ | 232,200 | $ | 153,859 | $ | 37,920 | ||||||||||||||||||||
Ratios to Average Net Assets (including interest expense) |
||||||||||||||||||||||||||||||||||||||||
Ratio of expenses to average net assets excluding fee waivers and reimbursements(d)(e) |
4.55 | % | 3.86 | % | 2.74 | % | 2.81 | % | 2.90 | % | 2.95 | % | 3.18 | % | 3.13 | % | 2.95 | % | 3.04 | % | ||||||||||||||||||||
Ratio of expenses to average net assets including fee waivers and reimbursements(e) |
4.55 | % | 3.86 | % | 2.74 | % | 2.81 | % | 2.92 | % | 2.96 | % | 3.12 | % | 2.97 | % | 2.56 | % | 2.55 | % | ||||||||||||||||||||
Ratio of net investment income/(loss) to average net assets(e) |
(1.88 | )% | (1.13 | )% | 0.36 | % | 0.91 | % | 0.79 | % | 0.35 | % | (0.04 | )% | 0.05 | % | (0.04 | )% | 0.55 | % | ||||||||||||||||||||
Ratios to Average Net Assets (excluding interest expense) |
||||||||||||||||||||||||||||||||||||||||
Ratio of expenses to average net assets excluding fee waivers and reimbursements(d)(e) |
2.68 | % | 2.67 | % | 2.65 | % | 2.70 | % | 2.66 | % | 2.69 | % | 2.74 | % | 2.79 | % | 2.95 | % | 3.02 | % | ||||||||||||||||||||
Ratio of expenses to average net assets including fee waivers and reimbursements(e) |
2.68 | % | 2.67 | % | 2.65 | % | 2.70 | % | 2.68 | % | 2.70 | % | 2.68 | % | 2.63 | % | 2.56 | % | 2.54 | % | ||||||||||||||||||||
Portfolio turnover rate |
14 | % | 13 | % | 4 | % | 26 | % | 27 | % | 8 | % | 13 | % | 16 | % | 18 | % | 35 | % | ||||||||||||||||||||
|
(a) |
Per share amounts are calculated using the average shares method. |
|
(b) |
Includes adjustments in accordance with accounting principles generally accepted in the United States and, consequently, the net asset value for financial reporting purposes and the returns based upon those net asset values may differ from the net asset values and returns for shareholder transactions. |
(c) |
Total returns are historical in nature and assume changes in net asset value per share, reinvestment of dividends and capital gains distributions, if any. Had the Advisor not absorbed a portion of the Fund expenses, total returns would have been lower. |
|
(d) |
Represents the ratio of expenses to average net assets absent fee waivers expense reimbursement and/or recoupment by the Advisor. |
|
(e) |
The ratios of expenses to average net assets and net investment income (loss) to average net assets do not directly reflect the expenses of the underlying institutional private real estate investments in which the Fund invests. The Fund invests in each underlying institutional private real estate investment based upon its net asset value, inclusive of management fees, which typically range from 0.50% to 1.30% on an annualized basis. The Fund’s Total Return is reported net of all fees and expenses. |
8 |
THE FUND
The Fund is a continuously offered, non-diversified, closed-end management investment company that is operated as an interval fund. The Fund was organized as a Delaware statutory trust on May 25, 2012. The Fund’s principal office is located at 919 Third Avenue, 40th Floor, New York, NY 10022, and its telephone number is 1-844-819-8287.
USE OF PROCEEDS
The net proceeds of the Fund’s continuous offering of shares, after payment of the sales load (if applicable) and other associated expenses, will be invested in accordance with the Fund’s investment objective and policies (as stated below) as soon as practicable after receipt. The Fund pays organizational costs and its offering expenses incurred with respect to its initial and continuous offering. Pending investment of the net proceeds in accordance with the Fund’s investment objective and policies, the Fund will invest in money market or short-term fixed-income mutual funds. Investors should expect, therefore, that before the Fund has fully invested the proceeds of the offering in accordance with its investment objective and policies, the Fund’s assets would earn interest income at a modest rate.
INVESTMENT OBJECTIVE, POLICIES AND STRATEGIES
Investment Objective and Policies
The Fund seeks primarily to generate current income while secondarily seeking long-term capital appreciation with low to moderate volatility and low correlation to the broader markets.
The Fund pursues its investment objectives by investing, under normal circumstances, at least 80% of its net assets, plus the amount of any borrowings for investment purposes, in real estate industry securities, primarily in income producing equity and debt securities. The Fund’s investments may be targeted in any one or more of the many sectors of the real estate market, including but not limited to the retail, office, multifamily, hospitality, industrial, residential, healthcare, life sciences, and self-storage sectors. The Fund concentrates investments in the real estate industry, meaning that under normal circumstances, it invests over 25% of its assets in real estate industry securities. The Fund may utilize leverage through borrowing for investment purposes or to satisfy repurchase requests. The Fund currently borrows money under two credit facilities.
The Fund defines real estate industry securities to include the common stock, partnership or similar interests, asset-backed securities, preferred stock, and secured or unsecured debt. Real estate industry securities may be issued by a wide variety of entities including: private real estate investment funds managed by institutional investment managers (“Institutional Investment Funds”); non-traded unregistered real estate investment trusts (“Private REITs”); publicly traded real estate investment trusts or other similar companies (“Public REITs”); Government Sponsored Entities (“GSEs”) such as Federal Home Loan Mortgage Corporation Structured Pass-Through Certificates (“K-Notes”), exchange traded funds, index mutual funds, and other investment vehicles such as closed-end funds and mutual funds that invest principally, directly or indirectly, in real estate (collectively, “Other Public Investment Vehicles”) and unregistered funds that invest principally in real estate.
The Fund may invest in issuers of real estate industry securities of any credit quality; including fixed-income and preferred securities rated less than investment grade that are sometimes referred to as high yield or “junk bonds.” The Fund may invest in debt securities of any duration or maturity. The Fund may also, to a limited extent, make real estate-related investments other than through real estate industry securities. The Advisor or RREEF will sell a security when other securities are available that offer higher expected current income, higher expected long-term capital appreciation, lower volatility or lower correlation to broader securities markets or a combination of the preceding.
The Fund’s SAI contains a list of the fundamental (those that may not be changed without a shareholder vote) and non-fundamental (if any) investment policies of the Fund under the heading “Investment Objective and Policies.”
Fund’s Target Investment Portfolio
The Advisor executes the Fund’s real estate investment strategy primarily through a strategic combination of global ‘best in class’ Institutional Investment Funds, publicly traded real estate securities, and real estate related debt investments. The Fund will not invest more than 10% of the Fund’s assets in private funds employing hedging strategies (commonly known as “hedge funds”, i.e., investment funds that would be investment companies but for the exemptions under Rule 3(c)(1) or 3(c)(7) under the 1940 Act).
The Advisor has retained Mercer to provide ongoing research and investment opinions of and/or recommendations of institutional investment managers using the Mercer’s proprietary screening process, which applies multiple factors based on quantitative and qualitative assessment of the management team and track record. The Advisor has engaged RREEF to invest a portion of the Fund’s portfolio, generally less than 20%, in publicly traded real estate securities (Public REITs and Other Public Investment Vehicles). RREEF selects securities to seek to maximize risk-adjusted returns by managing volatility and identifying securities that are priced inefficiently relative to its assessment of intrinsic value.
Institutional Investment Funds. Institutional Investment Funds are real estate investment funds managed by institutional investment managers with expertise in managing portfolios of real estate and real estate-related securities. Many Institutional Investment Funds have large minimum investment requirements and stringent investor qualification criteria intended to limit their direct investors to mainly institutions such as endowments and pension funds. It is the intent of the Fund to provide an element of the endowment model of investing to individual investors by permitting access to a portfolio of Institutional Investment Funds with diversification across multiple strategies, managers and sectors.
9 |
The Advisor also believes that the Fund may provide an additional benefit in terms of better fee pricing from the Institutional Investment Funds as a result of volume discounts, which pricing benefits may not otherwise be permitted or available to other investors. In addition, the Fund’s investments in Institutional Investment Funds are intended to deliver returns that have a low correlation to the broader markets.
The Fund’s typical investments in Institutional Investment Funds will be made through the purchase of common stock, limited liability company units, or limited partnership interests (or similar interests). Investment criteria will include evaluating a combination of strength of the sponsor and management; prior investment performance of the target fund as well as the performance of other funds managed by the sponsor; the attractiveness of the property sectors and geographical allocations of the fund; expected stability of income; expected capital appreciation, and target leverage levels.
REITs. The Fund may invest, directly or indirectly, in Real Estate Investment Trusts (“REITs”). REITs are investment vehicles that invest primarily in income-producing real estate or mortgages and other real estate-related loans or interests. Public REITs are listed on major stock exchanges such as the New York Stock Exchange (“NYSE”) or the National Association of Securities Dealers Automated Quotation System (“NASDAQ”), and invest directly in real estate, typically through either properties or mortgages.
Other Public Investment Vehicles. The Fund anticipates making limited investments in Other Public Investment Vehicles, including ETFs and Index Funds that invest primarily in real estate related assets, principally to temporarily invest the Fund’s capital pending its deployment into other higher-returning investment opportunities, or for temporary defensive purposes under adverse market conditions.
Exchange Traded Funds (“ETFs”). ETFs are typically managed by professionals and provide investors with diversification, cost and tax efficiency, liquidity, marginability, are useful for hedging, have the ability to go long and short, and some provide quarterly dividends. An ETF typically holds a portfolio of securities or contracts designed to track a particular market segment or index. ETFs are listed on major stock exchanges and are traded like stocks.
Index Funds. An Index Fund is a mutual fund with an investment objective of seeking to replicate the performance of a specific securities index, such as the National Association of Real Estate Investment Trusts (NAREIT) Index or the MSCI REIT Index. Most Index Funds are not actively managed and generally provide broad market exposure, low operating expenses and low portfolio turnover.
Other. In addition to ETFs and Index Funds, and subject to the Fund’s investment restrictions, the Fund may invest in investment companies that invest primarily in what the Advisor considers real estate industry securities, including closed-end funds and mutual funds. Shares of Closed-end Funds are typically listed for trading on major stock exchanges and, in some cases, may be traded in other over-the-counter markets.
Real Estate Related Debt Investments. The Fund may invest in real estate related direct debt including first and second mortgage loans, mezzanine loans and other structured debt investments.
Investment Strategy, and Criteria Used by the Advisor and Mercer in Selecting Investments
The Fund’s investment strategy focuses primarily on identifying Institutional Investment Funds that have:
|
● |
attractive risk-adjusted returns; |
|
● |
with low to moderate volatility; |
|
● |
low correlation to the broader markets; and |
|
● |
an emphasis on income generation. |
The Fund utilizes a comprehensive multi-manager, multi-sector, and multi-strategy approach. The Advisor primarily selects funds with the highest expected risk-adjusted returns from a real estate sector peer group of issuers with similar market capitalization and/or credit quality. Secondarily, the Advisor considers potential for capital appreciation. When constructing and balancing the Fund’s portfolio, the Advisor selects funds from real estate sectors that it believes have relatively low volatility and will not be highly correlated to each other or to the equity or fixed income markets, generally.
The Advisor, working closely with Mercer and in consideration of its recommendations, uses both a quantitative screening process and a qualitative selection process when selecting investments for the Fund to implement its real estate investment strategy. The Advisor and Mercer conduct research on various real estate investment managers and investment options in order to establish a selection of investments to fulfill the Fund’s investment objectives. Mercer’s assistance and recommendations for selection of investment funds are made according to asset allocation, return expectations and other guidelines set by the Advisor with oversight of the Board. No assurance can be given that any or all investment strategies, or the Fund’s investment program, will be successful.
Investment Strategy – Mercer Process
Mercer’s process begins with a proprietary database created and continuously maintained by its professionals - the Global Investment Manager Database (GIMD™) which gives Mercer access to up-to-date information and insights on a worldwide matrix of investment managers and strategies. GIMD™ contains information on numerous investment types across all asset classes, including real estate. This information ranges from access to and analysis of performance data to qualitative forward-looking research on investment managers supported by screening functionality. In the twelve months leading up to September 30, 2024, over 2,700 formal manager meetings were held and over 3,600 Research Reports were produced globally. As of September 30, 2024, GIMD™ contained information on over 6,800 investment managers and over 32,300 investment strategies.
10 |
Mercer, together with its global investment management affiliates, have over 3,300 delegated clients globally.
The Advisor has entered into a Sub-Advisory Agreement with Mercer Investments LLC (“Mercer” or a “Sub-Advisor”), 99 High Street, Boston, MA 02110.

The Advisor, in conjunction with Mercer, employs a regimen of quantitative and qualitative criteria to arrive at a universe of investments which are considered to be ‘best in class.’ By combining historical quantitative analysis with a sound knowledge of key qualitative attributes, the Advisor will evaluate a prospective investment’s potential for generating sustainable, positive, risk-adjusted returns under a wide variety of market conditions. Mercer’s investment selection and due diligence process are outlined in the chart below.

On-going monitoring of the Fund’s investments will be utilized to assist the Advisor in maintaining portfolio allocations and managing cash in-flows and outflows. The Advisor may strategically rebalance its investment strategies according to the current market conditions, but will remain true to its fundamental analysis with respect to real estate asset class and sector risk over time. The
11 |
Advisor manages investments over a long-term time horizon while being mindful of the historical context of the markets. Mercer will provide to the Advisor investment performance reporting and analysis, including discussions on investment strategy, portfolio construction, and market update reports. The illustration below further outlines this monitoring process.

Investment Strategy - Multi-Manager Diversification
The Fund intends to employ a Multi-Manager approach by identifying and investing with ‘best in class’ institutional asset managers with expertise in managing portfolios of real estate and real estate-related securities. The term ‘best in class’ refers to Institutional Investment Funds that the Advisor and Mercer have identified through Mercer’s proprietary screening process as having above average prospects.
Many of the Institutional Investment Funds have large minimum investment size and stringent investor qualification criteria intended to limit their direct investors to mainly institutions such as endowments and pension funds. As such, the Fund enables investors to invest with institutional investment managers that may not be otherwise permitted or available to them.
The Fund also enables investors to execute a comprehensive multi-strategy, multi-manager, multi-sector strategy by making a single investment in its shares, whereas due to the large minimums of many of the Institutional Investment Funds, such a strategy may not otherwise be permitted or available to the investor.
The sponsor believes that the Fund may provide an additional benefit in terms of lower fees from the Institutional Investment Funds as a result of volume discounts, which pricing benefits may not otherwise be permitted or available to them.
Investment Strategy - Multi-Strategy Diversification
The Fund intends to employ a Multi-Strategy approach to diversify the risk-reward profiles and the underlying types of real estate in which it invests, with the strategies noted below. Because each real estate strategy performs differently throughout the overall real estate and economic cycle, investment strategies that include multiple strategies generally have lower volatility than single strategy funds. Thus, a multi-strategy approach should assist the Fund in achieving its objective of lower portfolio volatility as well as lower correlation with the broader markets.
|
● |
Core. The Fund’s ‘core’ strategy targets high-quality portfolios with real estate assets that provide relatively lower and more stable returns. Such investments are typically located in primary markets and in the main property types (retail, office, industrial and multi-family). Properties are stable, well-maintained, well-leased and often of the Class A variety. For example, office properties, including life sciences, tend to be Class A buildings with investment grade tenants. Multifamily properties are usually in major metropolitan cities with higher rental rates. Retail would typically be more traditional neighborhood and community strip-mall centers, as well as regional and super regional malls. The Advisor believes that warehouse and research and development properties in strong distribution centers typically offer better chances for predictable cash flow within the industrial sector. As an example, a Class A office property may broadly be defined as 100,000 square feet or larger (five or more floors), concrete and steel construction, recently built and/or very well maintained (excellent condition), with business/support amenities and in a strong identifiable location with good access to a primary metropolitan market. Class A properties are the most prestigious buildings competing for premier tenants with rents above average for the area. |
|
● |
Core Plus. The Fund’s ‘core plus’ strategy seeks moderate risk portfolios with real estate that provides moderate returns. Such investments are predominantly core but with an emphasis on a modest value add management approach. A core plus portfolio requires slightly more complex financial structuring and management intensive focus than a core portfolio of investments. Focus is on the main property types, in both primary and secondary markets, in Class A or lower quality buildings that require some form of enhancement (i.e. repositioning, redevelopment and/or releasing). In comparison to the Class A example above, a Class B property may be renovated and/or in good condition, potentially smaller in size, in a good location in a primary or secondary metropolitan market. Class B properties compete for a wide range of users with rents in the average range for the area. |
12 |
|
● |
Value Add. The Fund’s ‘value add’ strategy typically focuses on more aggressive active asset management and often employs more leverage. Such investments typically are lower quality buildings, in both primary and secondary markets in the main property types or development projects. Properties are considered value add when they exhibit management or operational problems, require physical improvement, and/or suffer from capital constraints. Buildings often require enhancement to upgrade them to higher quality properties (i.e., redevelopment/repositioning/re-tenanting). |
Investment Strategy - Multi-Sector Diversification
The Fund intends to employ a Multi-Sector approach to diversify its investments by property type or sector - for example, across retail, office, multifamily, hospitality, industrial, residential, healthcare, life sciences and/or self-storage sectors. Because each real estate sector has its own investment cycle, correlations across property types are generally low. Thus, employing a multi-sector approach should assist the Fund in achieving its objective of low to moderate volatility as well as low correlation to the broader markets.
Additional Information Regarding Investment Strategy
The Fund may, from time to time, in attempting to respond to adverse market, economic, political or other similar conditions, take temporary defensive positions that are inconsistent with the Fund’s principal investment strategy. During such times, the Advisor may determine that the Fund should invest up to 100% of its assets in cash or cash equivalents, including money market instruments, prime commercial paper, repurchase agreements, Treasury bills and other short-term obligations of the U.S. Government, its agencies or instrumentalities. In addition to the foregoing, the Fund may utilize Other Public Investment Vehicles as temporary investments as the Fund raises capital or pending deployment of capital to other investment opportunities selected by the Advisor. In these and in other cases, the Fund may not achieve its investment objective. The Advisor may invest the Fund’s cash balances in any investments it deems appropriate. The Advisor expects that such investments will be made, without limitation and as permitted under the 1940 Act, in money market mutual funds, repurchase agreements, U.S. Treasury and U.S. agency securities, municipal bonds and bank accounts. Any income earned from such investments is ordinarily reinvested by the Fund in accordance with its investment program. Many of the considerations entering into recommendations and decisions of the Advisor and the Fund’s Portfolio Managers are subjective.
The frequency and amount of portfolio purchases and sales (known as the “portfolio turnover rate”) will vary from year to year. The portfolio turnover rate is not expected to exceed 100%, but may vary greatly from year to year and will not be a limiting factor if the Advisor determines that portfolio changes are appropriate. Although the Fund generally does not intend to trade for short-term profits, the Fund may engage in short-term trading strategies, and securities may be sold without regard to the length of time held when, in the opinion of the Advisor, investment considerations warrant such action. These policies may have the effect of increasing the annual rate of portfolio turnover of the Fund. Higher rates of portfolio turnover would likely result in higher brokerage commissions and may generate short-term capital gains taxable as ordinary income. If securities are not held for the applicable holding periods, dividends paid on them will not qualify for the advantageous federal tax rates. See “Tax Status” in the Fund’s SAI.
There is no assurance what portion, if any, of the Fund’s investments will qualify for the reduced federal income tax rates applicable to qualified dividends under the Code. As a result, there can be no assurance as to what portion of the Fund’s distributions will be designated as qualified dividend income. See “U.S. Federal Income Tax Matters.”
Investment Strategy and Criteria Used by RREEF in Selecting Public Real Estate Securities
The Advisor with RREEF has developed an investment strategy intended to maximize risk-adjusted returns by managing volatility and identifying securities that are priced inefficiently relative to RREEF’s assessment of intrinsic value. RREEF believes that real estate security performance is reflective of the underlying real estate portfolio and, therefore, over time will be driven by the pricing and fundamentals of their assets. The risk management process is highly focused on quantitative risk factors as well as fundamental portfolio risk factors. RREEF’s investment universe encompasses over 100 property companies in the United States with a total market capitalization of over $800 billion. RREEF is focused on companies that derive the majority of their operating income or asset base from commercial real estate (apartments, office, industrial, storage, hotels, retail, net lease). Operating and capital efficiency are critically important to a successful real estate company and hence RREEF typically focuses on companies with large, high quality asset bases. If there are securities outside of this group that meet these criteria, RREEF will include these as part of the investable universe. The investment universe is generally defined as all REITs and REOCs (real estate operating companies) with an equity market capitalization of at least $200 million that derive the majority of revenue or net asset value (NAV) from an equity interest in real estate activities. The U.S. real estate securities portion of the Fund’s portfolio managed by RREEF typically holds between 35-50 securities. Under normal circumstances, such securities will generally comprise between 5% and 20% of the Fund’s portfolio. With respect to any investments in non-publicly traded real estate related debt securities, the Advisor makes all investment decisions.
RISK FACTORS
An investment in the Fund’s shares is subject to risks. The value of the Fund’s investments will increase or decrease based on changes in the prices of the investments it holds. This will cause the value of the Fund’s shares to increase or decrease. You could lose money by investing in the Fund. By itself, the Fund does not constitute a balanced investment program. Before investing in the Fund you should consider carefully the following risks. There may be additional risks that the Fund does not currently foresee or consider material. You may wish to consult with your legal or tax advisors before deciding whether to invest in the Fund.
Real Estate Industry Concentration Risk. Because the Fund will concentrate its investments in real estate related securities, its portfolio will be significantly impacted by the performance of the real estate market and may experience more volatility and be exposed to greater risk than a more diversified portfolio. In addition, the Fund may invest in real estate equity or debt and therefore may be subject to risks similar to those associated with direct investment in real property. The value of the Fund’s shares will be affected by factors affecting the value of real estate and the earnings of companies engaged in the real estate industry. These factors
13 |
include, among others: (i) changes in general economic and market conditions; (ii) changes in the value of real estate properties; (iii) risks related to local economic conditions, overbuilding and increased competition; (iv) increases in property taxes and operating expenses; (v) changes in zoning laws; (vi) casualty and condemnation losses; (vii) variations in rental income, neighborhood values or the appeal of property to tenants; (viii) the availability of financing; (ix) climate change and (x) changes in interest rates. Many real estate companies utilize leverage, which increases investment risk and could adversely affect a company’s operations and market value in periods of rising interest rates. The value of securities of companies in the real estate industry may go through cycles of relative under-performance and over-performance in comparison to equity securities markets in general.
There are also special risks associated with particular sectors, or real estate operations, including, but not limited to, those risks described below:
Retail Properties. Retail properties are affected by the overall health of the economy and may be adversely affected by, among other things, the growth of alternative forms of retailing, bankruptcy, departure or cessation of operations of a tenant, a shift in consumer demand due to demographic changes, changes in spending patterns and lease terminations.
Office Properties. Office properties are affected by the overall health of the economy, and other factors such as a downturn in the businesses operated by their tenants, obsolescence and non-competitiveness.
Industrial Properties. Industrial properties are affected by the overall health of the economy and other factors such as downturns in the manufacturing, processing and shipping of goods.
Hospitality Properties. The risks of hotel, motel and similar hospitality properties include, among other things, the necessity of a high level of continuing capital expenditures, competition, increases in operating costs which may not be offset by increases in revenues, dependence on business and commercial travelers and tourism, increases in fuel costs and other expenses of travel, and adverse effects of general and local economic conditions. Hotel properties tend to be more sensitive to adverse economic conditions and competition than many other commercial properties.
Healthcare and Life Sciences Properties. Healthcare and life sciences properties and healthcare providers are affected by several significant factors, including federal, state and local laws governing licenses, certification, adequacy of care, pharmaceutical distribution, rates, equipment, personnel and other factors regarding operations, funding for biotech companies, continued availability of revenue from government reimbursement programs and competition on a local and regional basis. The failure of any healthcare operator to comply with governmental laws and regulations may affect its ability to operate its facility or receive government reimbursements.
Multifamily Properties. The value and successful operation of a multifamily property may be affected by a number of factors such as the location of the property, the ability of the management team, the level of mortgage interest rates, the presence of competing properties, adverse economic conditions in the locale, oversupply and rent control laws or other laws affecting such properties.
Residential Properties. Residential properties can be significantly affected by the national, regional and local real estate markets. This segment of the real estate industry also is sensitive to interest rate fluctuations which can cause changes in the availability of mortgage capital and directly affect the purchasing power of potential homebuyers. Thus, residential properties can be significantly affected by changes in government spending, consumer confidence, demographic patterns and the level of new and existing home sales.
Shopping Centers. Shopping center properties are dependent upon the successful operations and financial condition of their tenants, particularly certain of their major tenants, and could be adversely affected by bankruptcy of those tenants. In some cases, a tenant may lease a significant portion of the space in one center, and the filing of bankruptcy could cause significant revenue loss, including the loss of revenue from smaller tenants with co-tenancy rights. Like others in the commercial real estate industry, community centers are subject to environmental risks and interest rate risk. They also face the need to enter into new leases or renew leases on favorable terms to generate rental revenues. Community center properties could be adversely affected by changes in the local markets where their properties are located, as well as by adverse changes in national economic and market conditions.
Self-Storage Properties. The value and successful operation of a self-storage property may be affected by a number of factors, such as the ability of the management team, the location of the property, the presence of competing properties, changes in traffic patterns and effects of general and local economic conditions with respect to rental rates and occupancy levels.
Other factors may contribute to the risk of real estate investments:
Development Issues. Certain real estate companies in which the Fund directly or indirectly invests (“portfolio companies”) may engage in the development or construction of real estate properties. Portfolio companies are exposed to a variety of risks inherent in real estate development and construction, such as the risk that there will be insufficient tenant demand to occupy newly developed properties, and the risk that prices of construction materials or construction labor may rise materially during the development.
Lack of Insurance. Certain of the portfolio companies in the Fund’s portfolio may fail to carry comprehensive liability, fire, flood, earthquake extended coverage and rental loss insurance, or insurance in place may be subject to various policy specifications, limits and deductibles. Due to the prevalence of catastrophic events, the cost of insurance may increase materially. Should any type of uninsured loss occur, the portfolio company could lose its investment in, and anticipated profits and cash flows from, a number of properties and, as a result, adversely affect the Fund’s investment performance.
14 |
Dependence on Tenants. The value of the Fund’s portfolio companies’ properties and the ability of these companies to make distributions to their shareholders depends upon the ability of the tenants at the properties to generate enough income in excess of their tenant operating expenses to make their lease payments. Changes beyond the control of our portfolio companies may adversely affect their tenants’ ability to make their lease payments and, in such event, would substantially reduce both their income from operations and ability to make distributions to our portfolio companies and, consequently, the Fund.
Financial Leverage. Companies in the real estate industry may be highly leveraged and financial covenants may affect their ability to operate effectively. The use of floating rate loans may also negatively impact returns in a rising interest rate environment.
Environmental Issues. In connection with the ownership (direct or indirect), operation, management and development of real properties that may contain hazardous or toxic substances, a portfolio company may be considered an owner, operator or responsible party of such properties and, therefore, may be potentially liable for removal or remediation costs, as well as certain other costs, including governmental fines and liabilities for injuries to persons and property. The existence of any such material environmental liability could have a material adverse effect on the results of operations and cash flow of any such portfolio company and, as a result, the amount available to make distributions on shares of the Fund could be reduced. Environmental risk from high winds, hurricanes, fires, flood and extreme heat may also materially affect a property’s value.
Credit Market Conditions. Instability in credit markets can potentially make it more difficult for borrowers to obtain financing or refinancing on attractive terms or at all. Conditions in the credit markets may expose borrowers to increased interest expenses for borrowed money and tightening underwriting standards. There is also a risk that a general lack of liquidity or other events in the credit markets may adversely affect the ability of issuers in whose securities the Fund invests to finance real estate developments and projects or refinance completed projects.
This may also adversely affect the price at which portfolio companies can sell real estate, because purchasers may not be able to obtain financing on attractive terms or at all. These developments may potentially adversely affect the broader economy, which in turn may adversely affect the real estate markets. Additionally, such developments could reduce the Fund’s investment opportunities.
Market Risk. An investment in shares is subject to investment risk, including the possible loss of the entire principal amount invested. An investment in shares represents an indirect investment in the securities owned by the Fund. The value of these securities, like other market investments, may move up or down, sometimes rapidly and unpredictably. In addition, the Fund is subject to the risk that geopolitical and other similar events will disrupt the economy on a national or global level. For instance, war, terrorism, market manipulation, government defaults, government shutdowns, political changes or diplomatic developments, public health emergencies (such as the spread of infectious diseases, pandemics and epidemics) and natural/environmental disasters can all negatively impact the securities markets.
Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. The foregoing could impair the Fund’s ability to maintain operational standards, disrupt the operations of the Fund and its service providers, adversely affect the performance, value and liquidity of the Fund’s investments, and negatively impact the Fund’s performance and your investment in the Fund. The value of your shares at any point in time may be worth less than the value of your original investment, even after taking into account any reinvestment of dividends and distributions.
Liquidity Risk. The Fund is a closed-end investment company structured as an “interval fund” and is designed for medium to long-term investors. Unlike many closed-end investment companies, the Fund’s shares are not listed on any securities exchange and are not publicly traded. There currently is no secondary market for the shares and the Advisor does not expect that a secondary market will develop. Limited liquidity is provided to shareholders only through the Fund’s quarterly repurchase offers for no less than 5% of the Fund’s shares outstanding at per-class net asset value. There is no guarantee that shareholders will be able to sell all of the shares they desire in a quarterly repurchase offer. Since inception, the Fund has made 44 repurchase offers, 37 have resulted in the repurchase of all shares, seven have resulted in the repurchase of less than all shares tendered. The Fund’s investments are also subject to liquidity risk. Liquidity risk exists when particular investments of the Fund would be difficult to purchase or sell, possibly preventing the Fund from selling such illiquid securities at an advantageous time or price, or possibly requiring the Fund to dispose of other investments at unfavorable times or prices in order to satisfy its obligations. Funds with principal investment strategies that involve securities of companies with smaller market capitalizations, derivatives or securities with substantial market and/or credit risk tend to have the greatest exposure to liquidity risk.
Allocation Risk. The ability of the Fund to achieve its investment objective depends, in part, on the ability of the Advisor or RREEF to allocate effectively the Fund’s assets among the various Institutional Investment Funds, Private REITs, Public REITs and Other Public Investment Vehicles in which the Fund invests and, with respect to each such asset class, among equities and fixed income securities. There can be no assurance that the actual allocations will be effective in achieving the Fund’s investment objectives or delivering positive returns.
Correlation Risk. The Fund seeks to produce returns that are not correlated to the broader financial markets. Although the prices of equity securities and fixed-income securities, as well as other asset classes, often rise and fall at different times so that a fall in the price of one may be offset by a rise in the price of the other, in down markets the prices of these securities and asset classes can also fall in tandem. Because the Fund allocates its investments among different asset classes, the fund is subject to correlation risk.
Credit Risk. There is a risk that debt issuers will not make payments, resulting in losses to the Fund. In addition, the credit quality of securities may be lowered if an issuer’s financial condition changes. Lower credit quality may lead to greater volatility in the price of a security and in shares of the Fund. Lower credit quality also may affect liquidity and make it difficult to sell the security. Default,
15 |
or the market’s perception that an issuer is likely to default, could reduce the value and liquidity of securities, thereby reducing the value of your investment in Fund shares. In addition, default may cause the Fund to incur expenses in seeking recovery of principal or interest on its portfolio holdings.
Distribution Policy Risk. The Fund’s distribution policy is expected to result in distributions that equal a fixed percentage of the Fund’s current net asset value per share. Shareholders receiving periodic payments from the Fund may be under the impression that they are receiving net profits. However, all or a portion of a distribution may consist of a return of capital. Return of capital is the portion of a distribution that is a return of your original investment dollars in the Fund. Shareholders should not assume that the source of a distribution from the Fund is net profit. Shareholders should note that return of capital will reduce the tax basis of their shares and potentially increase the taxable gain, if any, upon disposition of their shares.
Fixed Income Risk. When the Fund invests in fixed income securities, the value of your investment in the Fund will fluctuate with changes in interest rates. Typically, a rise in interest rates causes a decline in the value of fixed income securities. In general, the market price of debt securities with longer maturities will increase or decrease more in response to changes in interest rates than shorter-term securities. Recently, interest rates have risen sharply after maintaining historically low levels for a significant period of time. Current conditions may result in an increase in interest rate volatility, which in turn may result in a decline in the value of the fixed income investments held by the Fund. As a result, for the present, interest rate risk may be heightened. Other risk factors include credit risk (the debtor may default) and prepayment risk (the debtor may pay its obligation early, reducing the amount of interest payments). These risks could affect the value of a particular investment, possibly causing the Fund’s share price and total return to be reduced and fluctuate more than other types of investments.
Institutional Investment Fund Risk. The Fund’s investment in Institutional Investment Funds will require it to bear a pro rata share of the vehicles’ expenses, including management and performance fees. The fees the Fund pays to invest in an Institutional Investment Fund may be higher than if the manager of the Institutional Investment Fund, managed the Fund’s assets directly. The incentive fees charged by certain Institutional Investment Funds may create an incentive for its manager to make investments that are riskier and/or more speculative than those it might have made in the absence of an incentive fee. The Funds are not publicly traded and therefore may not be as liquid as other types of investments. Furthermore, Institutional Investment Funds, like the other Underlying Funds in which the Fund may invest, are subject to specific risks, depending on the nature of the vehicle and also may employ leverage such that their returns are more than one times that of their benchmark which will amplify losses suffered by the Fund when compared to unleveraged investments. For example, these Funds need not have independent boards, shareholder approval of advisory contracts may not be required, may leverage to an unlimited extent, and may engage in joint transactions with affiliates.
Issuer and Non-Diversification Risk. The value of a specific security can be more volatile than the market as a whole and can perform differently from the value of the market as a whole. As a non-diversified fund, the Fund may invest more than 5% of its total assets in the securities of one or more issuers. The Fund’s performance may be more sensitive to any single economic, business, political or regulatory occurrence than the value of shares of a diversified investment company. The value of an issuer’s securities that are held in the Fund’s portfolio may decline for a number of reasons which directly relate to the issuer, such as management performance, financial leverage and reduced demand for the respective properties and services.
Lack of Control Over Institutional Investment Funds and Other Portfolio Investments. Once the Advisor or RREEF has selected an Underlying Fund for investment by the Fund, the Advisor and RREEF will have no control over the investment decisions made by any such Underlying Fund. Although the Advisor or RREEF will evaluate regularly each Underlying Fund and its manager to determine whether their respective investment programs are consistent with the Fund’s investment objective, the Advisor and RREEF will not have any control over the investments made by any Underlying Fund. Even though the Underlying Funds are subject to certain constraints, the managers may change aspects of their investment strategies. The managers may do so at any time (for example, such change may occur immediately after providing the Advisor with the quarterly unaudited financial information for an Institutional Investment Fund). The Advisor or RREEF may reallocate the Fund’s investments among the Underlying Funds, but the Advisor’s ability to do so may be constrained by the withdrawal limitations imposed by certain Underlying Funds, which may prevent the Fund from reacting rapidly to market changes should an Underlying Fund fail to effect portfolio changes consistent with such market changes and the demands of the Advisor. Such withdrawal limitations may also restrict the Advisor’s ability to terminate investments in Underlying Funds that are poorly performing or have otherwise had adverse changes. The Advisor and RREEF will be dependent on information provided by the Underlying Fund, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s or RREEF’s ability to manage the Fund’s investment portfolio in accordance with its investment objectives.
Leveraging Risk. The use of leverage, such as borrowing money to purchase securities or otherwise invest the Fund’s assets, will cause the Fund to incur additional expenses and may significantly magnify the Fund’s losses in the event of adverse performance of the Fund’s underlying investments. In addition to any borrowing utilized by the Fund, the Underlying Funds in which the Fund invests may utilize leverage, subject to the limitations of their charters and operative documents. Leverage by Underlying Funds and/or the Fund has the effect of potentially increasing losses. In addition, interest rates (including benchmarks like SOFR and the spreads to such benchmarks charged by lenders) are highly sensitive to external factors outside a borrower’s control, including general and local economic conditions (such as inflation, recession, money supply and unemployment) and the monetary and fiscal policies of various governmental agencies such as the Federal Reserve Board. During periods of increased interest rates, borrowing costs of the Fund will likely increase and may adversely affect the Fund’s performance.
Management Risk. The net asset value of the Fund changes daily based on the performance of the securities in which it invests. The Advisor’s or a Sub-Advisor’s judgments about the attractiveness, value and potential appreciation of particular real estate segment and securities in which the Fund invests may prove to be incorrect and may not produce the desired results.
16 |
Possible Competition Between Underlying Funds and Between the Fund and the Underlying Funds. The Underlying Funds trade independently of each other and may pursue investment strategies that “compete” with each other for execution or that cause the Fund to participate in positions that offset each other (in which case the Fund would bear its pro rata share of commissions and fees without the potential for a profit). Also, the Fund’s investments in any particular Underlying Fund could increase the level of competition for the same trades that other Underlying Funds might otherwise make, including the priorities of order entry. This could make it difficult or impossible to take or liquidate a position in a particular security at a price consistent with the Advisor’s or a Sub-Advisor’s strategy.
Preferred Securities Risk. There are various risks associated with investing in preferred securities, including credit risk, interest rate risk, deferral and omission of distributions, subordination to bonds and other debt securities in a company’s capital structure, limited liquidity, limited voting rights and special redemption rights. Interest rate risk is, in general, that the price of a debt security falls when interest rates rise. Securities with longer maturities tend to be more sensitive to interest rate changes. Credit risk is the risk that an issuer of a security may not be able to make principal and interest or dividend payments on the security as they become. Holders or preferred securities may not receive dividends, or the payment can be deferred for some period of time. In bankruptcy, creditors are generally paid before the holders of preferred securities.
REIT Risk. Investments (directly or indirectly) in REITs will subject the Fund to various risks. REIT share prices may decline because of adverse developments affecting the real estate industry and real property values. In general, real estate values can be affected by a variety of factors, including supply and demand for properties, the economic health of the country or of different regions, and the strength of specific industries that rent properties. REITs often invest in highly leveraged properties. Returns from REITs, which typically are small or medium capitalization stocks, may trail returns from the overall stock market. In addition, changes in interest rates may hurt real estate values or make REIT shares less attractive than other income-producing investments. REITs are also subject to heavy cash flow dependency, defaults by borrowers and self-liquidation.
Qualification as a REIT under the Internal Revenue Code of 1986, as amended, in any particular year is a complex analysis that depends on a number of factors. There can be no assurance that an entity in which the Fund invests with the expectation that it will be taxed as a REIT will, in fact, qualify as a REIT. An entity that fails to qualify as a REIT would be subject to a corporate level tax, would not be entitled to a deduction for dividends paid to its shareholders and would not pass through to its shareholders the character of income earned by the entity. If the Fund were to invest in an entity that failed to qualify as a REIT, such failure could significantly reduce the Fund’s yield on that investment. REITs can be classified as equity REITs, mortgage REITs and hybrid REITs. Equity REITs invest primarily in real property and earn rental income from leasing those properties. They may also realize gains or losses from the sale of properties. Equity REITs will be affected by conditions in the real estate rental market and by changes in the value of the properties they own. Mortgage REITs invest primarily in mortgages and similar real estate interests and receive interest payments from the owners of the mortgaged properties. Mortgage REITs will be affected by changes in creditworthiness of borrowers and changes in interest rates. Hybrid REITs invest both in real property and in mortgages. Equity and mortgage REITs are dependent upon management skills, may not be diversified and are subject to the risks of financing projects.
Dividends paid by REITs will not generally qualify for the reduced U.S. federal income tax rates applicable to qualified dividends under the Code. See “U.S. Federal Income Tax Matters.” The Fund’s investments in REITs may include an additional risk to shareholders. Some or all of a REIT’s annual distributions to its investors may constitute a non-taxable return of capital. Any such return of capital will generally reduce the Fund’s basis in the REIT investment, but not below zero. To the extent the distributions from a particular REIT exceed the Fund’s basis in such REIT, the Fund will generally recognize gain. In part because REIT distributions often include a nontaxable return of capital, Fund distributions to shareholders may also include a nontaxable return of capital. Shareholders that receive such a distribution will also reduce their tax basis in their shares of the Fund, but not below zero. To the extent the distribution exceeds a shareholder’s basis in the Fund’s shares, such shareholder will generally recognize a capital gain. The Fund does not have any investment restrictions with respect to investments in REITs.
Repurchase Policy Risks. Quarterly repurchases by the Fund of its shares typically will be funded from available cash or sales of portfolio securities. However, payment for repurchased shares may require the Fund to liquidate portfolio holdings earlier than the Advisor otherwise would liquidate such holdings, potentially resulting in losses, and may increase the Fund’s portfolio turnover. The Advisor may take measures to attempt to avoid or minimize such potential losses and turnover, and instead of liquidating portfolio holdings, may borrow money to finance repurchases of shares. If the Fund borrows to finance repurchases, interest on any such borrowing will negatively affect shareholders who do not tender their shares in a repurchase offer by increasing the Fund’s expenses and reducing any net investment income. To the extent the Fund finances repurchase proceeds by selling investments, the Fund may hold a larger proportion of its net assets in less liquid securities. Also, the sale of securities to fund repurchases could reduce the market price of those securities, which in turn would reduce the Fund’s net asset value.
Repurchase of shares will tend to reduce the number of outstanding shares and, depending upon the Fund’s investment performance, its net assets. A reduction in the Fund’s net assets may increase the Fund’s expense ratio, to the extent that additional shares are not sold. In addition, the repurchase of shares by the Fund may be a taxable event to shareholders.
Underlying Funds Risk. Other Public Investment Vehicles such as ETFs, Index Funds, closed-end funds, and mutual funds in which the Fund may invest are subject to investment advisory fees and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in such Underlying Funds and also may be higher than other funds that invest directly in securities. Underlying Funds are subject to specific risks, depending on the nature of the fund. The Fund’s performance depends in part upon the performance of the Underlying Fund managers and selected strategies, the adherence by such Underlying Fund managers to such selected strategies, the instruments used by such Underlying Fund managers and the Advisor’s or a Sub-Advisor’s ability to select Underlying Fund managers and strategies and effectively allocate Fund assets among them. Additionally, the market value of shares of Underlying Funds that are closed-end funds typically trade at a discount relative to their net asset value. This difference in price may be due to the fact that the supply and demand in the market for fund shares at any point in time is not always identical to the supply and demand in the market for the underlying basket of securities.
17 |
ETF shares may trade at a discount or a premium in market price if there is a limited market in such shares. Transactions in shares of closed-end funds and ETFs are also subject to brokerage and other trading costs, which could result in greater expenses to the Fund. Investments in pooled investment vehicles also may be illiquid, making it difficult for the Advisor to redeem the interest of the Fund in such vehicles in a reasonable amount of time.
Valuation of Institutional Investment Funds. While the valuations of the Fund’s investments in publicly-traded securities are more readily ascertainable, the Fund’s ownership interests in Institutional Investment Funds are not publicly traded and the Fund will depend on the institutional asset manager to a Private Investment Fund to provide a valuation of the Fund’s investment. Moreover, the valuation of the Fund’s investment in an Institutional Investment Fund, as provided by an institutional asset manager as of a specific date, may vary from the fair value of the investment that may be obtained if such investment were sold to a third party. For information about the value of the Fund’s investment in Institutional Investment Funds, the Advisor will be dependent on information provided by the Institutional Investment Funds, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s ability to accurately value the Fund’s shares.
MANAGEMENT OF THE FUND
Trustees and Officers
The Board is responsible for the overall management of the Fund, including supervision of the duties performed by the Advisor. The Board is comprised of five trustees. The Trustees are responsible for the Fund’s overall management, including adopting the investment and other policies of the Fund, electing and replacing officers and selecting and supervising the Fund’s investment advisor. The name and business address of the Trustees and officers of the Fund and their principal occupations and other affiliations during the past five years, as well as a description of committees of the Board, are set forth under “Management” in the Statement of Additional Information.
Investment Advisor
Bluerock Fund Advisors, LLC, located at 919 Third Avenue, 40th Floor, New York, NY 10022, serves as the Fund’s investment advisor. The Advisor is registered with the SEC as an investment advisor under the Advisers Act. The Advisor is a Delaware limited liability company formed on May 11, 2012.
Under the general supervision of the Fund’s Board, and pursuant to the terms of an Investment Management Agreement with the Fund, the Advisor will carry out the investment and reinvestment of the net assets of the Fund, will furnish continuously an investment program with respect to the Fund, and determine which securities should be purchased, sold or exchanged. In addition, the Advisor will supervise and provide oversight of the Fund’s service providers. The Advisor will furnish to the Fund office facilities, equipment and personnel for servicing the management of the Fund. The Advisor will compensate all Advisor personnel who provide services to the Fund. In return for these services, facilities and payments, the Fund has agreed to pay the Advisor, as compensation under the Investment Management Agreement, a monthly management fee computed at the annual rate of 1.50% of the daily net assets of the Fund. The Advisor may employ research services and service providers to assist in the Advisor’s market analysis and investment selection.
The Advisor and the Fund have entered into an expense limitation and reimbursement agreement (the “Expense Limitation Agreement”) under which the Advisor has agreed contractually to waive its fees and to pay or absorb the ordinary operating expenses (excluding any taxes, interest, brokerage commissions, acquired fund fees and expenses, and extraordinary expenses, such as litigation or reorganization costs, but including organizational costs and offering costs), to the extent that such expenses exceed 2.70% per annum of the Fund’s average daily net assets attributable to Class C shares (the “Expense Limitation”). In consideration of the Advisor’s agreement to limit the Fund’s expenses, the Fund has agreed to repay the Advisor in the amount of any fees the Advisor previously waived or Fund expenses reimbursed, subject to the limitations that: (1) the reimbursement will be made if payable not more than three years from the date incurred; (2) the reimbursement may not be made if it would cause the Expense Limitation then in effect or in effect at the time of the waiver to be exceeded; and (3) the reimbursement is approved by the Board. The Expense Limitation Agreement will remain in effect, at least until January 31, 2026, unless and until the Board approves its modification or termination. This agreement may be terminated only by the Board on 60 days written notice to the Advisor. After January 31, 2026, the Expense Limitation Agreement may be renewed at the Advisor’s and Board’s discretion.
A discussion regarding the basis for the Board’s approval of each of the Fund’s Investment Management Agreement with the Advisor and Sub-Advisory Agreements with Mercer and RREEF is available annually in the Fund’s March 31 semi-annual report to shareholders.
Affiliated Brokerage
Bluerock Capital Markets, LLC (“BCM”), a registered broker-dealer and an affiliate of the Advisor, may receive commissions on the sale of certain classes of Fund’s shares, but it does not receive compensation from the Fund in connection with the sale of Class C shares.
Advisor’s Investment Committee
The Advisor has established an Investment Committee comprised of five persons (the “Committee”) responsible for: setting overall investment policies and strategies of the Advisor; approval of Institutional Investment Funds being considered for investment by the Fund; establishing allocation targets for the investment portfolio of the Fund among the Institutional Investment Funds, Other Public Investment Vehicles and other entities in which the Fund intends to invest; and generally overseeing the activities of the Advisor’s Portfolio Managers (see below).
18 |
The members of the Committee, and their professional background and experience, are as follows:
R. Ramin Kamfar — Mr. Kamfar has served as a member of the Investment Committee and as Chairman of the Advisor since the inception of the Advisor in 2012. In addition, Mr. Kamfar is the founder of and serves as the Chairman and Chief Executive Officer of Bluerock Real Estate, LLC (“BRRE”), since its founding in October 2002. Mr. Kamfar served as Chairman and CEO of Bluerock Residential Growth REIT, a publicly traded REIT listed on the NYSE American (“BRG”), from its founding in 2009 until its sale in 2022. Mr. Kamfar currently serves as Chairman and CEO of Bluerock Homes Trust, a publicly traded REIT listed on the NYSE American (“BHM”) since its spin-off from BRG in 2022, as well as Chairman of Bluerock Asset Management, LLC since 2018. Mr. Kamfar started his career as an investment banker at Lehman Brothers Inc. in 1988, and has 30 years of experience in various aspects of real estate, mergers and acquisitions, private equity investing, investment banking, and public and private financings. Mr. Kamfar received an M.B.A. degree with distinction in Finance in 1988 from The Wharton School of the University of Pennsylvania and a B.S. degree with distinction in Finance in 1985 from the University of Maryland, College Park.
James G. Babb, III — Mr. Babb has served as a member of the Investment Committee since the inception of the Advisor in 2012. In addition, Mr. Babb has served in a variety of senior capacities, including his current role as Chief Strategy Officer, at BRRE, which he joined in 2007. Mr. Babb served as Chief Investment Officer of BRG from its founding in 2009 to 2020, as Chief Strategy Officer from 2020 until its sale in 2022 and as a Director of BRG from 2009 to 2014. Mr. Babb currently serves as Chief Strategy Officer of BHM. Mr. Babb was a founding principal of Starwood Capital Group (“Starwood”), a leading institutional real estate investment manager, where he helped lead the residential and office acquisitions initiatives from 1992 to 2003. During Mr. Babb’s tenure Starwood raised and invested funds on behalf of institutional investors through seven private real estate funds, and which in the aggregate ultimately invested approximately $8 billion in approximately 250 separate transactions. Mr. Babb also led Starwood’s efforts to expand its platform to invest in England and France. Mr. Babb received a B.A. degree in Economics in 1987 from the University of North Carolina, Chapel Hill.
Jordan B. Ruddy — Mr. Ruddy currently serves as Co-CIO of the Advisor and Portfolio Manager of the Fund. Mr. Ruddy has served as a member of the Investment Committee and as President of the Advisor since the inception of the Advisor in 2012. Mr. Ruddy also serves as president of Bluerock Asset Management, LLC. Mr. Ruddy served in several senior capacities of BRG from its founding in 2009 until its sale in 2022 and currently serves as President of BHM. Mr. Ruddy brings approximately 30 years of institutional real estate investment experience working with some of leading public and private firms in the industry. Prior to joining Bluerock, Mr. Ruddy served as a real estate investment banker at Banc of America Securities LLC, and at Smith Barney Inc. and at JP Morgan Chase (previously the Chase Manhattan Bank), and as Vice President of Amerimar Enterprises, a real estate company specializing in value-added investments nationwide. Mr. Ruddy received an M.B.A. degree in Finance and Real Estate in 1995 from The Wharton School of the University of Pennsylvania, and a B.S. degree with high honors in Economics in 1986 from the London School of Economics.
Ryan MacDonald — Mr. MacDonald has served as a member of the Investment Committee of the Advisor since January 2018. Mr. MacDonald currently serves as Chief Investment Officer for BHM and of BRRE and certain of its affiliates. Mr. MacDonald served in a variety of senior capacities for BRG, including Chief Investment Officer from 2020 until its sale. Since joining Bluerock in 2008, Mr. MacDonald is responsible for sourcing, underwriting, structuring, financing and closing of all of Bluerock’s real estate investments and dispositions. To date with Bluerock, Mr. MacDonald has been involved with real estate transactions with an aggregate value of approximately $11 billion. Prior to joining Bluerock, Mr. MacDonald was an Investment Analyst for PNC Realty Investors. Mr. MacDonald received a B.A. in Economics from the University of Maryland, College Park.
Adam Lotterman — Mr. Lotterman is co-founder of the Advisor and has been a key member of the Fund’s investment team since its inception in 2012. Mr. Lotterman currently serves as the Fund’s Senior Portfolio Manager, as well as the Advisor’s Co-Chief Investment Officer and Lead Economist. Prior to joining Bluerock, Mr. Lotterman was Vice President of Forman Capital, a private commercial real estate lender from 2011 to 2012. Mr. Lotterman was also an Adjunct Professor at Nova Southeastern University from 2010 to 2012, where he taught a master’s level course in Real Estate Market Analysis. Prior to that, Mr. Lotterman worked as a Senior Valuation Analyst at Bayview Asset Management (former hedge fund affiliate of The Blackstone Group) from 2010 to 2011, and from 2005 to 2010 Mr. Lotterman was the Senior Analyst for Goodkin Consulting, the former real estate consulting arm of PricewaterhouseCoopers. Mr. Lotterman received an M.S. in International Real Estate in 2006 from Florida International University, where he graduated first in class, and a B.S. Degree in microbiology with a minor in chemistry in 1997 from the University of Florida.
Advisor Portfolio Managers
Subject to the Committee’s oversight, Jordan B. Ruddy, a member of the Committee, and Adam Lotterman serve as the Fund’s Portfolio Managers and oversee the day-to-day investment operations of the Fund. Each has served as a Portfolio Manager to the Fund since October 2013.
Jordan B. Ruddy — Mr. Ruddy’s biographical information is presented above.
Adam Lotterman — Mr. Lotterman’s biographical information is presented above.
Tim Thran, CFA — Mr. Thran currently serves as Associate Portfolio Manager and Assistant Treasurer of the Fund. Mr. Thran joined Bluerock in 2017 and currently serves as a Managing Director of the Advisor. Mr. Thran works directly with the Fund’s Senior Portfolio Managers and is responsible for overseeing day-to-day investment operations and execution of the Fund’s strategy, including portfolio valuation, investment analysis, liquidity management and performance evaluation. Previously, Mr. Thran served at JPMorgan Asset Management from 2014 to 2016, directing daily oversight and controls on over $200 billion in retail mutual fund assets. From 2008 to 2014, Mr. Thran held multiple management roles at State Street Corporation, with a focus on accounting and compliance on the
19 |
company’s premier ETFs and mutual fund clients. Mr. Thran received an M.B.A. degree with a concentration in Investments from the D’Amore-McKim School of Business at Northeastern University and B.A. degrees in both Mathematics and Economics from the College of the Holy Cross. Mr. Thran is a CFA charterholder, CFA Institute.
Investment Sub-Advisor — Mercer
The Advisor has engaged Mercer Investments LLC, a registered adviser under the Advisers Act, to act as an investment sub-advisor. For more than 50 years, Mercer and its affiliates have provided global leadership in investment consulting and multi-manager fiduciary management, and is a leading advisor to sovereign wealth funds, pension plans, banks, family offices, insurance companies, endowments and foundations. Mercer, together with its affiliated investment businesses, have over 5,600 delegated and advisory clients globally with over $547 billion in assets under management as of September 30, 2024 and over $17.5 trillion in assets under advisement as of June 30, 2024. Asset under management reported here includes include aggregated assets for which Mercer Investments LLC (Mercer Investments) and their global affiliates providing discretionary investment management services as of the dates indicated. Assets under management is calculated differently from regulatory assets under management, which is reported in Form ADV and filed with the Securities and Exchange Commission.
Mercer is an affiliate of Mercer (US), LLC, a human resource and financial consulting company. Mercer (US), LLC has approximately 25,000+ employees as of September 30, 2024 based in more than 40 countries and serves over 36,000 clients worldwide and is a wholly owned subsidiary of Marsh & McLennan Companies (NYSE: MMC).
Investment Sub-Advisor — RREEF
The Advisor has engaged RREEF America L.L.C., a registered advisor under the Advisers Act, to provide investment management for a portion of the Fund’s portfolio, generally less than 20%. In addition, RREEF provides the Advisor with research and information that the Advisor uses to make investment decisions with respect to non-publicly traded real estate related debt securities. RREEF together with its affiliates in Europe and Asia, comprise the global real estate investment business of DWS, an indirect majority owned subsidiary of Deutsche Bank A.G. DWS’s real estate investment business, is one of the largest real estate investment managers globally with more than 330 professionals and staff located in 23 cities worldwide and approximately $78.9 billion in real estate and real estate-related assets under management as of September 30, 2024.
RREEF Portfolio Managers
Subject to the Advisor’s oversight, David W. Zonavetch, Bob Thomas, and John W. Vojticek serve as the Fund’s RREEF Portfolio Managers and oversee a portion of investment portfolio of the Fund. Mr. Zonavetch and Mr. Vojticek have served as a Portfolio Managers to the Fund since May 2016. Mr. Thomas has served as a Portfolio Manager to the Fund since January 2018.
David W. Zonavetch — Mr. Zonavetch has served as a Director and Co-Lead Portfolio Manager for RREEF since September 2013 and as Co-Lead Portfolio Manager - Real Estate Securities since February 2012. Previously, he served as Vice President and Portfolio Manager from February 2007 to February 2012. From February 2007 to February 2012, Mr. Zonavetch was a Vice President and Securities Analyst at RREEF Real Estate. He has nine years of experience in accounting and finance. From 1998 to 2001, Mr. Zonavetch served as a Senior Accountant in Corporate Finance of RREEF Real Estate, and from 2001 to 2003, he served as Securities Accounting Coordinator with RREEF Real Estate’s Securities Group, covering the office and self- storage sectors. From 1995 until joining RREEF Real Estate in 1998, Mr. Zonavetch worked as an analyst for Cendant Mobility Services Corp., a corporate employee relocation company. Mr. Zonavetch holds a B.S. in Finance from the University of Illinois at Urbana-Champaign and is a certified public accountant.
Bob Thomas — Mr. Thomas has served as a Managing Director and Co-Head of Americas Real Estate Securities, Alternatives for RREEF since 2017. He has 15 years of industry experience serving as lead portfolio manager of North America for global listed property funds at Henderson Global Investors from 2015 to 2016, he was co-lead portfolio manager of North America for global listed property funds at AMP Capital from 2012 to 2015, and as an analyst at Nuveen Asset Management from 2011 to 2012, at BNP Paribas Asset Management from 2005 to 2011 and at Security Capital Research & Management from 20014 to 2005. Mr. Thomas started his career as an investment banking analyst in the Real Estate group at KeyBanc Capital Markets in 2002. Mr. Thomas holds a B.A. in Economics from Duke University and an MBA in Finance, Management & Strategy from Kellogg School of Management, Northwestern University.
John W. Vojticek — Mr. Vojticek has served as a Managing Director and Chief Investment Officer of Real Estate & Infrastructure Securities and Global Portfolio Manager for RREEF since July 2011 and was Co-Head of Americas Real Estate Securities from 2006 to July 2011. Mr. Vojticek was responsible for launching the firm’s first listed infrastructure securities strategy in June 2008 and served as Head of the Listed Infrastructure Securities business from June 2008 until his appointment as Chief Information Officer in July 2011. Mr. Vojticek is an associate member of the National Association of Real Estate Investment Trusts. Mr. Vojticek holds a B.S. in Business Administration from the University of Southern California.
The Statement of Additional Information provides additional information about each Portfolio Manager’s compensation, other accounts managed and ownership of Fund shares.
20 |
Administrator, Accounting Agent and Transfer Agent
ALPS Fund Services, Inc. (“ALPS” or the “Administrator”), located at 1290 Broadway, Suite 1000, Denver, CO 80203, serves as Administrator and Accounting Agent for the Fund. For the services rendered to the Fund by ALPS, the Fund pays ALPS the greater of an annual minimum fee or an asset-based fee, which scales downward based upon net assets for fund administration and fund accounting services. SS&C GIDS, located at PO Box 219445, Kansas City, MO 64121-9445, serves as the Fund’s Transfer Agent and for such services the Fund pays the Transfer Agent separate fees.
Custodian
UMB Bank, N.A (“UMB Bank” or the “Custodian”), with principal offices at 1010 Grand Boulevard, Kansas City, Missouri 64106, serves as custodian for the securities and cash of the Fund’s portfolio. Under a Custody Agreement, UMB Bank holds the Fund’s assets in safekeeping and keeps all necessary records and documents relating to its duties.
Fund Expenses
The Advisor is obligated to pay expenses associated with providing the services stated in the Investment Management Agreement, including compensation of and office space for its officers and employees connected with investment and economic research, trading and investment management and administration of the Fund. The Advisor is obligated to pay the fees of any Trustee of the Fund who is affiliated with it.
The Administrator is obligated to pay expenses associated with providing the services contemplated by a Fund Services Administration Agreement (administration and accounting services), including compensation of and office space for its officers and employees employed in providing these services to the Fund.
The Fund pays all other expenses incurred in the operation of the Fund including, among other things, (i) expenses for legal and independent accountants’ services, (ii) costs of printing proxies, share certificates, if any, and reports to shareholders, (iii) charges of the custodian and transfer agent in connection with the Fund’s dividend reinvestment policy, (iv) fees and expenses of independent Trustees, (v) printing costs, (vi) membership fees in trade association, (vii) fidelity bond coverage for the Fund’s officers and Trustees, (viii) errors and omissions insurance for the Fund’s officers and Trustees, (ix) brokerage costs, (x) taxes, (xi) costs associated with the Fund’s quarterly repurchase offers, (xii) servicing fees and (xiii) other extraordinary or non-recurring expenses and other expenses properly payable by the Fund. The expenses incident to the offering and issuance of shares to be issued by the Fund will be recorded as a reduction of capital of the Fund attributable to the shares.
Class C shares are subject to a monthly shareholder servicing fee at an annual rate of up to 0.25% of the average daily net assets of the Fund attributable to the respective share class.
The Board has authorized the Advisor and RREEF to select brokers or dealers (including affiliates) to arrange for the purchase and sale of Fund securities, including principal transactions. Any commission, fee or other remuneration paid to an affiliated broker or dealer is paid in compliance with the Fund’s procedures adopted in accordance with Rule 17e-1 under the 1940 Act.
21 |
Control Persons and Principal Shareholders
A principal shareholder is any person who owns (either of record or beneficially) 5% or more of the outstanding shares of a fund. A control person is one who owns, either directly or indirectly, more than 25% of the voting securities of a company or acknowledges the existence of control. The Fund’s principal shareholders as of January 3, 2025, are listed in the chart below. Each shareholder listed below is a record shareholder, holding shares for the benefit of others.
Class A Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
6,523,152.52 |
26.75% |
EQUITABLE ADVISORS LLC LPL FINANCIAL SERVICES FBO LPL BIN 66920980 1055 LPL WAY FORT MILL SC, 29715-8101 |
4,721,545.33 |
19.36% |
CHARLES SCHWAB & CO INC SPECIAL CUSTODY A/C FBO CUSTOMERS 211 MAIN STREET SAN FRANCISCO, CA 94105-1905 |
3,107,371.03 |
12.74% |
NATIONAL FINANCIAL SERVICES LLC BIN #B9F699887 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
3,082,068.56 |
12.64% |
Class C Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
5,923,943.31 |
38.47% |
LPL FINANCIAL LLC FBO CUSTOMER ACCOUNTS 4707 EXECUTIVE DR. SAN DIEGO CA, 92121-3091 |
2,299,101.93 |
14.93% |
CHARLES SCHWAB AND CO INC SPECIAL CUSTODY A/C FBO CUSTOMERS 211 MAIN STREET SAN FRANCISCO, CA 94105-1905 |
2,076,778.96 |
13.49% |
NATIONAL FINANCIAL SERVICES LLC 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
895,604.35 |
5.82% |
Class I Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
CHARLES SCHWAB & CO INC SPECIAL CUSTODY A/C FBO CUSTOMERS 211 MAIN STREET SAN FRANCISCO, CA 92121 |
42,258,021.47 |
36.65% |
NATIONAL FINANCIAL SERVICES LLC 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
21,116,400.89 |
18.31% |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
21,101,606.20 |
18.30% |
LPL FINANCIAL SERVICES FBO LPL BIN 66920980 1055 LPL WAY FORT MILL SC 29715-8101 |
14,367,372.68 |
12.46% |
ROBERT W BAIRD & CO. INC. A/C 47100819 777 EAST WISCONSIN AVENUE MILWAUKEE, WI 53202 |
6,642,155.04 |
5.76% |
22 |
Class L Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
1,652,278.67 |
53.11% |
NATIONAL FINANCIAL SERVICES LLC 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
535,807.56 |
17.22% |
LPL FINANCIAL LLC FBO CUSTOMER ACCOUNTS 4707 EXECUTIVE DR. SAN DIEGO CA, 92121-3091 |
247,909.67 |
7.97% |
Class M Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
MORGAN STANLEY SMITH BARNEY LLC 1 NEW YORK PLAZA NEW YORK, NY 10004 |
4,313,743.14 |
98.46% |
As of January 3, 2025, the Trustees and officers, as a group, owned less than 1.00% of the shares of the Fund.
DETERMINATION OF NET ASSET VALUE
The net asset value of shares of the Fund is determined daily, as of the close of regular trading on the NYSE (normally, 4:00 p.m., Eastern Time). The NYSE is closed on weekends and New Year’s Day, Martin Luther King, Jr. Day, Presidents’ Day, Good Friday, Memorial Day, Juneteenth Day, Independence Day, Labor Day, Thanksgiving Day, and Christmas Day. Each Class C share will be offered at net asset value. During the continuous offering, the price of the shares will increase or decrease on a daily basis according to the net asset value of the shares.
In computing net asset value, portfolio securities of the Fund are valued at their current market values determined on the basis of market quotations as of the last quoted sales price on the security’s primary exchange. If market quotations are not readily available, as in the case of Institutional Investment Funds investing in private real estate, securities are valued at fair value as determined in good faith by the Advisor, in its capacity as the Board’s valuation designee, pursuant to Rule 2a-5 under the 1940 Act or with respect to securities traded or dealt in upon one or more securities exchanges (whether domestic or foreign), as described below. As a general matter, fair value represents the amount that the Fund could reasonably expect to receive if the Fund’s investment in the security were sold at the time of valuation, based on information reasonably available at the time the valuation is made and that the Advisor believes to be reliable. As the valuation designee, the Advisor acts under the Board’s oversight. The Board and the Advisor may enlist third party service providers, such as pricing services, broker-dealers or valuation firms, on an as-needed basis to assist in determining a security-specific fair value. The Board reviews the execution of this process and the resultant fair value prices at least quarterly to assure the process produces reliable results.
Fair valuation involves subjective judgments, and it is possible that the fair value determined for a security may differ materially from the value that could be realized upon the sale of the security. Like all investments that are valued at fair value, the Institutional Investment Funds will be difficult to value. There is no single standard for determining fair value of a security. Rather, in determining the fair value of a security for which there are no readily available market quotations, the Advisor, using information including that provided by a Sub-Advisor, may consider several factors, including fundamental analytical data relating to the investment in the security, the nature and duration of any restriction on the disposition of the security, the cost of the security at the date of purchase, the liquidity of the market for the security and the recommendation of the Fund’s Portfolio Managers. The Advisor may also consider periodic financial statements (audited and unaudited) or other information provided by the issuer. The Advisor will attempt to obtain current information to value all fair valued securities, but it is anticipated that portfolio holdings of the Institutional Investment Funds could be available on no more than a quarterly basis. Institutional Investment Funds that invest primarily in publicly traded securities are more easily valued.
The Advisor, with the assistance of other parties, will provide the Board with periodic reports, no less frequently than quarterly, that discuss the functioning of the valuation process, if applicable to that period, and that identify issues and valuations problems that have arisen, if any. To the extent deemed necessary by the Advisor, the fair value team or committee of the Board will review any securities valued by the Advisor in accordance with the Fund’s valuation policies.
Non-dollar-denominated securities, if any, are valued as of the close of the NYSE at the closing price of such securities in their principal trading market, but may be valued at fair value if subsequent events occurring before the computation of net asset value materially have affected the value of the securities. Trading may take place in foreign issues held by the Fund, if any, at times when the Fund is not open for business. As a result, the Fund’s net asset value may change at times when it is not possible to purchase or sell shares of the Fund. The Fund may use a third-party pricing service to assist it in determining the market value of securities in the Fund’s portfolio. The Fund’s net asset value per share is calculated, on a class-specific basis, by dividing the value of the Fund’s total assets (the value of the securities the Fund holds plus cash or other assets, including interest accrued but not yet received), less accrued expenses of the Fund, less the Fund’s other liabilities by the total number of shares outstanding.
23 |
For purposes of determining the net asset value of the Fund, readily marketable portfolio securities listed on the NYSE are valued, except as indicated below, at the last sale price reflected on the consolidated tape at the close of the NYSE on the business day as of which such value is being determined. If there has been no sale on such day, the securities are valued at the mean of the closing bid and asked prices on such day. If no bid or asked prices are quoted on such day or if market prices may be unreliable because of events occurring after the close of trading, then the security is valued by such method as the Advisor, as valuation designee, shall determine in good faith to reflect its fair market value. Readily marketable securities not listed on the NYSE but listed on other domestic or foreign securities exchanges are valued in a like manner. Portfolio securities traded on more than one securities exchange are valued at the last sale price on the business day as of which such value is being determined as reflected on the consolidated tape at the close of the exchange representing the principal market for such securities. Securities trading on the NASDAQ are valued at the NASDAQ official closing price.
Readily marketable securities traded in the over-the-counter market, including listed securities whose primary market is believed by the Advisor to be over-the-counter, are valued at the mean of the current bid and asked prices as reported by the NASDAQ or, in the case of securities not reported by the NASDAQ or a comparable source, as the Advisor deems appropriate to reflect their fair market value. Where securities are traded on more than one exchange and also over-the-counter, the securities will generally be valued using the quotations the Advisor believes reflect most closely the value of such securities.
CONFLICTS OF INTEREST
As a general matter, certain conflicts of interest may arise in connection with a portfolio manager’s management of a fund’s investments, on the one hand, and the investments of other accounts for which the portfolio manager is responsible, on the other. For example, it is possible that the various accounts managed could have different investment strategies that, at times, might conflict with one another to the possible detriment of the Fund. Alternatively, to the extent that the same investment opportunities might be desirable for more than one account, possible conflicts could arise in determining how to allocate them. Other potential conflicts might include conflicts created by specific portfolio manager compensation arrangements, and conflicts relating to selection of brokers or dealers to execute Fund portfolio trades and/or specific uses of commissions from Fund portfolio trades (for example, research, or “soft dollars”, if any). The Advisor, and Sub-Advisor, to the extent applicable, have adopted policies and procedures and have structured their Portfolio Managers’ compensation in a manner reasonably designed to safeguard the Fund from being negatively affected as a result of any such potential conflicts.
QUARTERLY REPURCHASES OF SHARES
Once each quarter, the Fund will offer to repurchase, at per-class net asset value no less than 5% of the outstanding shares of the Fund, unless such offer is suspended or postponed in accordance with regulatory requirements (as discussed below). The offer to purchase shares is a fundamental policy that may not be changed without the vote of the holders of a majority of the Fund’s outstanding voting securities (as defined in the 1940 Act). Shareholders will be notified in writing of each quarterly repurchase offer and the date the repurchase offer ends (the “Repurchase Request Deadline”). Shares will be repurchased at the per-class NAV per share determined as of the close of regular trading on the NYSE no later than the 14th day after the Repurchase Request Deadline, or the next business day if the 14th day is not a business day (each a “Repurchase Pricing Date”).
Shareholders will be notified in writing about each quarterly repurchase offer, how they may request that the Fund repurchase their shares and the “Repurchase Request Deadline,” which is the date the repurchase offer ends. Shares tendered for repurchase by shareholders prior to any Repurchase Request Deadline will be repurchased subject to the aggregate repurchase amounts established for that Repurchase Request Deadline. The time between the notification to shareholders and the Repurchase Request Deadline may vary from no more than 42 days to no less than 21 days. Payment pursuant to the repurchase will be made by checks to the shareholder’s address of record, or credited directly to a predetermined bank account on the Purchase Payment Date, which will be no more than seven days after the Repurchase Pricing Date. The Board may establish other policies for repurchases of shares that are consistent with the 1940 Act, regulations thereunder and other pertinent laws. Shareholders have no right to redeem Fund shares outside the regular quarterly repurchases, regardless of shareholder circumstances, and the Fund may not honor any such requests.
Determination of Repurchase Offer Amount
The Board, or a committee thereof, in its sole discretion, will determine the number of shares for each share class that the Fund will offer to repurchase (the “Repurchase Offer Amount”) for a given Repurchase Request Deadline. The Repurchase Offer Amount, however, will be no less than 5% and no more than 25% of the total number of shares outstanding on the Repurchase Request Deadline.
If shareholders tender for repurchase more than the Repurchase Offer Amount for a given repurchase offer, the Fund will repurchase the shares on a pro rata basis. However, the Fund may accept all shares tendered for repurchase by shareholders who own less than one hundred shares and who tender all of their shares, before prorating other amounts tendered.
Notice to Shareholders
No less than 21 days and more than 42 days before each Repurchase Request Deadline, the Fund shall send to each shareholder of record and to each beneficial owner of the shares that are the subject of the repurchase offer a notification (“Shareholder Notification”). The Shareholder Notification will contain information shareholders should consider in deciding whether to tender their shares for repurchase. The notice also will include detailed instructions on how to tender shares for repurchase, state the Repurchase Offer Amount and identify the dates of the Repurchase Request Deadline, the scheduled Repurchase Pricing Date, and the date the
24 |
repurchase proceeds are scheduled for payment (the “Repurchase Payment Deadline”). The notice also will set forth the NAV that has been computed no more than seven days before the date of notification, and how shareholders may ascertain the NAV after the notification date.
Repurchase Price
The repurchase price of the shares will be the NAV of the share class as of the close of regular trading on the NYSE on the Repurchase Pricing Date. The notice of the repurchase offer also will provide information concerning the NAV, such as the NAV as of a recent date or a sampling of recent NAVs, and a toll-free number for information regarding the repurchase offer. You may call 1-844-819-8287 to learn the NAV.
Early Withdrawal Charge
Selling brokers, or other financial intermediaries that have entered into distribution agreements with the Distributor may receive a commission of up to 1.00% of the purchase price of Class C shares.
Class C shareholders who tender for repurchase Class C shares that have been held, as of the time of repurchase, less than 365 days from the purchase date will be subject to an early withdrawal charge of 1.00% of the original purchase price. The Distributor may waive the imposition of the early withdrawal charge in the following situations: (1) shareholder death or (2) shareholder disability. Any such waiver does not imply that the early withdrawal charge will be waived at any time in the future or that such early withdrawal charge will be waived for any other shareholder.
Repurchase Amounts and Payment of Proceeds
Shares tendered for repurchase by shareholders prior to any Repurchase Request Deadline will be repurchased subject to the aggregate Repurchase Offer Amount established for that Repurchase Request Deadline. Payment pursuant to the repurchase offer will be made by check to the shareholder’s address of record, or credited directly to a predetermined bank account on the Purchase Payment Date, which will be no more than seven days after the Repurchase Pricing Date. The Board may establish other policies for repurchases of shares that are consistent with the 1940 Act, regulations thereunder and other pertinent laws.
If shareholders tender for repurchase more than the Repurchase Offer Amount for a given repurchase offer, the Fund will repurchase the shares on a pro rata basis. Notwithstanding the foregoing, the Fund may in its sole discretion and for administrative convenience accept all shares tendered for repurchase by shareholders who own less than one hundred shares and who tender all of their shares, before prorating other amounts tendered.
Suspension or Postponement of Repurchase Offer
The Fund may suspend or postpone a repurchase offer only: (a) if making or effecting the repurchase offer would cause the Fund to lose its status as a regulated investment company under the Code; (b) for any period during which the NYSE or any market on which the securities owned by the Fund are principally traded is closed, other than customary weekend and holiday closings, or during which trading in such market is restricted; (c) for any period during which an emergency exists as a result of which disposal by the Fund of securities owned by it is not reasonably practicable, or during which it is not reasonably practicable for the Fund fairly to determine the value of its net assets; or (d) for such other periods as the Commission may by order permit for the protection of shareholders of the Fund.
Liquidity Requirements
The Fund must maintain liquid assets equal to the Repurchase Offer Amount from the time that the notice is sent to shareholders until the Repurchase Pricing Date. The Fund will ensure that either a percentage of its net assets equal to at least 100% of the Repurchase Offer Amount consists of cash or assets that can be sold or disposed of in the ordinary course of business at approximately the price at which the Fund has valued the investment within the time period between the Repurchase Request Deadline and the Repurchase Payment Deadline, and/or a line of credit is available to satisfy the Repurchase Offer Amount. The Board has adopted procedures that are reasonably designed to ensure that the Fund’s assets are sufficiently liquid so that the Fund can comply with the repurchase offer and the liquidity requirements described in the previous paragraphs. If, at any time, the Fund falls out of compliance with these liquidity requirements, the Board will take whatever action it deems appropriate to ensure compliance.
Consequences of Repurchase Offers
Repurchase offers will typically be funded from available cash or sales of portfolio securities. Payment for repurchased shares, however, may require the Fund to liquidate portfolio holdings earlier than the Advisor otherwise would, thus increasing the Fund’s portfolio turnover and potentially causing the Fund to realize losses. The Advisor intends to take measures to attempt to avoid or minimize such potential losses and turnover, and instead of liquidating portfolio holdings, may borrow money to finance repurchases of shares. If the Fund borrows to finance repurchases, interest on that borrowing will negatively affect shareholders who do not tender their shares in a repurchase offer by increasing the Fund’s expenses and reducing any net investment income. To the extent the Fund finances repurchase amounts by selling Fund investments, the Fund may hold a larger proportion of its assets in less liquid securities. The sale of portfolio securities to fund repurchases also could reduce the market price of those underlying securities, which in turn would reduce the Fund’s net asset value.
Repurchase of the Fund’s shares will tend to reduce the number of outstanding shares and, depending upon the Fund’s investment performance, its net assets. A reduction in the Fund’s net assets would increase the Fund’s expense ratio, to the extent that additional shares are not sold and expenses otherwise remain the same (or increase). In addition, the repurchase of shares by the Fund will be a taxable event to shareholders.
25 |
The Fund is intended as a medium to long-term investment. The Fund’s quarterly repurchase offers are a shareholder’s only means of liquidity with respect to his or her shares. Shareholders have no right to redeem Fund shares outside the regular quarterly repurchases, regardless of shareholder circumstances, and the Fund may not honor any such requests. The shares are not traded on a national securities exchange and no secondary market exists for the shares, nor does the Fund expect a secondary market for its shares to exist in the future.
DISTRIBUTION POLICY
Quarterly Distribution Policy
The Fund’s distribution policy is to make quarterly distributions to shareholders. The level of quarterly distributions (including any return of capital) is not fixed, but is expected to represent an annual rate of approximately 5.25% of the Fund’s current net asset value per share. However, this distribution policy is subject to change. Shareholders receiving periodic payments from the Fund may be under the impression that they are receiving net profits. However, all or a portion of a distribution may consist of a return of capital. Shareholders should not assume that the source of a distribution from the Fund is net profit. A return of capital is not taxable to a shareholder unless it exceeds a shareholder’s tax basis in the shares. Returns of capital reduce a shareholder’s tax cost (or “tax basis”). Once a shareholder’s tax basis is reduced to zero, any further return of capital would be taxable. Shareholders should note that return of capital will reduce the tax basis of their shares and potentially increase the taxable gain, if any, upon disposition of their shares. As required under the Investment Company Act of 1940, the Fund will provide a notice to shareholders at the time of distribution when such distribution does not consist solely of net income. Additionally, each distribution payment will be accompanied by a written statement which discloses the source or sources of each distribution. The IRS requires you to report these amounts, excluding returns of capital, on your income tax return for the year declared. The Fund will provide disclosures, with each distribution, that estimate the percentages of the current and year-to-date distributions that represent (1) net investment income, (2) capital gains and (3) return of capital. At the end of the year, the Fund may be required under applicable law to re-characterize distributions made previously during that year among (1) ordinary income, (2) capital gains and (3) return of capital for tax purposes. An additional distribution may be made in December, and other additional distributions may be made with respect to a particular fiscal year in order to comply with applicable law. Distributions declared in December, if paid to shareholders by the end of January, are treated for federal income tax purposes as if received in December.
The distribution rate may be modified by the Board from time to time. If, for any quarterly distribution, investment company taxable income (which term includes net short-term capital gain), if any, and net tax-exempt income, if any, is less than the amount of the distribution, then the difference will generally be a tax-free return of capital distributed from the Fund’s assets. The Fund’s final distribution for each calendar year will include any remaining investment company taxable income and net tax-exempt income undistributed during the year, as well as all net capital gain realized during the year. If the total distributions made in any calendar year exceed investment company taxable income, net tax-exempt income and net capital gain, such excess distributed amount would be treated as ordinary dividend income to the extent of the Fund’s current and accumulated earnings and profits. Distributions in excess of the earnings and profits would first be a tax-free return of capital to the extent of the adjusted tax basis in the shares. After such adjusted tax basis is reduced to zero, the distribution would constitute capital gain (assuming the shares are held as capital assets). This distribution policy may, under certain circumstances, have certain adverse consequences to the Fund and its shareholders because it may result in a return of capital resulting in less of a shareholder’s assets being invested in the Fund and, over time, increase the Fund’s expense ratio. The distribution policy also may cause the Fund to sell a security at a time it would not otherwise do so in order to manage the distribution of income and gain.
Unless the registered owner of shares elects to receive cash, all dividends declared on shares will be automatically reinvested in additional shares of the Fund. See “Dividend Reinvestment Policy.”
The dividend distribution described above may result in the payment of approximately the same amount or percentage to the Fund’s shareholders each quarter. Section 19(a) of the 1940 Act and Rule 19a-1 thereunder require the Fund to provide a written statement accompanying any such payment that adequately discloses its source or sources. Thus, if the source of the dividend or other distribution were the original capital contribution of the shareholder, and the payment amounted to a return of capital, the Fund would be required to provide written disclosure to that effect. Nevertheless, persons who periodically receive the payment of a dividend or other distribution may be under the impression that they are receiving net profits when they are not. Shareholders should read any written disclosure provided pursuant to Section 19(a) and Rule 19a-1 carefully and should not assume that the source of any distribution from the Fund is net profit.
The Board reserves the right to change the quarterly distribution policy from time to time.
DIVIDEND REINVESTMENT POLICY
The Fund will operate under a dividend reinvestment policy administered by the Transfer Agent. Pursuant to the policy, the Fund’s income dividends or capital gains or other distributions (each, a “Distribution” and collectively, “Distributions”), net of any applicable U.S. withholding tax, are reinvested in the same class of shares of the Fund.
Shareholders automatically participate in the dividend reinvestment policy, unless and until an election is made to withdraw from the policy on behalf of such participating shareholder. Shareholders who do not wish to have Distributions automatically reinvested should so notify the Transfer Agent in writing at Bluerock Total Income+ Real Estate Fund, c/o SS&C GIDS, PO Box 219445, Kansas City, MO 64121-9445. Such written notice must be received by the Transfer Agent 30 days prior to the record date of the Distribution or the shareholder will receive such Distribution in shares through the dividend reinvestment policy. Under the dividend reinvestment policy, the Fund’s Distributions to shareholders are reinvested in full and fractional shares as described below.
When the Fund declares a Distribution, the Transfer Agent, on the shareholder’s behalf, will receive additional authorized shares from the Fund either newly issued or repurchased from shareholders by the Fund and held as treasury stock. The number of shares to be received when Distributions are reinvested will be determined by dividing the amount of the Distribution by the Fund’s net asset value per share.
26 |
The Transfer Agent will maintain all shareholder accounts and furnish written confirmations of all transactions in the accounts, including information needed by shareholders for personal and tax records. The Transfer Agent will hold shares in the account of the shareholders in non-certificated form in the name of the participant, and each shareholder’s proxy, if any, will include those shares purchased pursuant to the dividend reinvestment policy. Each participant, nevertheless, has the right to request certificates for whole and fractional shares owned. The Fund will issue certificates in its sole discretion. The Administrator will distribute all proxy solicitation materials, if any, to participating shareholders.
In the case of shareholders, such as banks, brokers or nominees, that hold shares for others who are beneficial owners participating under the dividend reinvestment policy, the Transfer Agent will administer the dividend reinvestment policy on the basis of the number of shares certified from time to time by the record shareholder as representing the total amount of shares registered in the shareholder’s name and held for the account of beneficial owners participating under the dividend reinvestment policy.
Neither the Transfer Agent nor the Fund shall have any responsibility or liability beyond the exercise of ordinary care for any action taken or omitted pursuant to the dividend reinvestment policy, nor shall they have any duties, responsibilities or liabilities except such as expressly set forth herein. Neither shall they be liable hereunder for any act done in good faith or for any good faith omissions to act, including, without limitation, failure to terminate a participant’s account prior to receipt of written notice of his or her death or with respect to prices at which shares are purchased or sold for the participants account and the terms on which such purchases and sales are made, subject to applicable provisions of the federal securities laws.
The automatic reinvestment of dividends will not relieve participants of any federal, state or local income tax that may be payable (or required to be withheld) on such dividends. See “U.S. Federal Income Tax Matters.”
The Fund reserves the right to amend or terminate the dividend reinvestment policy. There is no direct service charge to participants with regard to purchases under the dividend reinvestment policy; however, the Fund reserves the right to amend the dividend reinvestment policy to include a service charge payable by the participants.
All correspondence concerning the dividend reinvestment policy should be directed to the Transfer Agent at Bluerock Total Income+ Real Estate Fund, c/o SS&C GIDS, PO Box 219445, Kansas City, MO 64121-9445. Certain transactions can be performed by calling the toll-free number 1-844-819-8287.
U.S. FEDERAL INCOME TAX MATTERS
The following briefly summarizes some of the important federal income tax consequences to shareholders of investing in the Fund’s shares, reflects the federal tax law as of the date of this prospectus, and does not address special tax rules applicable to certain types of investors, such as corporate, tax-exempt and foreign investors. Investors should consult their tax advisors regarding other federal, state or local tax considerations that may be applicable in their particular circumstances, as well as any proposed tax law changes.
The following is a summary discussion of certain U.S. federal income tax consequences that may be relevant to a shareholder of the Fund that acquires, holds and/or disposes of shares of the Fund, and reflects provisions of the Internal Revenue Code of 1986, as amended, existing Treasury regulations, rulings published by the IRS, and other applicable authority, as of the date of this prospectus. These authorities are subject to change by legislative or administrative action, possibly with retroactive effect. The following discussion is only a summary of some of the important tax considerations generally applicable to investments in the Fund and the discussion set forth herein does not constitute tax advice. For more detailed information regarding tax considerations, see the Statement of Additional Information. There may be other tax considerations applicable to particular investors such as those holding shares in a tax deferred account such as an IRA or 401(k) plan. In addition, income earned through an investment in the Fund may be subject to state, local and foreign taxes.
The Fund intends to elect to be treated and to qualify each year for taxation as a regulated investment company under Subchapter M of the Code. In order for the Fund to qualify as a regulated investment company, it must meet an income and asset diversification test each year. If the Fund so qualifies and satisfies certain distribution requirements, the Fund (but not its shareholders) will not be subject to federal income tax to the extent it distributes its investment company taxable income and net capital gains (the excess of net long-term capital gains over net short-term capital loss) in a timely manner to its shareholders in the form of dividends or capital gain distributions. The Code imposes a 4% nondeductible excise tax on regulated investment companies, such as the Fund, to the extent they do not meet certain distribution requirements by the end of each calendar year. The Fund anticipates meeting these distribution requirements. Shareholders will not be subject to the alternative minimum tax.
The Fund intends to make distributions of investment company taxable income after payment of the Fund’s operating expenses no less frequently than annually. Unless a shareholder is ineligible to participate or elects otherwise, all distributions will be automatically reinvested in additional shares of the Fund pursuant to the dividend reinvestment policy. For U.S. federal income tax purposes, all dividends are generally taxable whether a shareholder takes them in cash or they are reinvested pursuant to the policy in additional shares of the Fund. Distributions of the Fund’s investment company taxable income (including short-term capital gains) will generally be treated as ordinary income to the extent of the Fund’s current and accumulated earnings and profits. Distributions of the Fund’s net capital gains (“capital gain dividends”), if any, are taxable to shareholders as capital gains, regardless of the length of time shares have been held by shareholders. Distributions, if any, in excess of the Fund’s earnings and profits will first reduce the adjusted tax basis of a holder’s shares and, after that basis has been reduced to zero, will constitute capital gains to the shareholder of the Fund (assuming the shares are held as a capital asset). A corporation that owns Fund shares generally will not be entitled to the dividends received deduction with respect to all of the dividends it receives from the Fund. Fund dividend payments that are attributable to qualifying dividends received by the Fund from certain domestic corporations may be designated by the Fund as being eligible for the dividends received deduction. There can be no assurance as to what portion of Fund dividend payments may be classified as qualifying dividends. The determination of the character for U.S. federal income tax purposes of any distribution from the Fund (i.e.
27 |
ordinary income dividends, capital gains dividends, qualified dividends or return of capital distributions) will be made as of the end of the Fund’s taxable year. Generally, no later than 60 days after the close of its taxable year, the Fund will provide shareholders with a written notice designating the amount of any capital gain distributions and any other distributions.
The Fund will inform its shareholders of the source and tax status of all distributions promptly after the close of each calendar year.
DESCRIPTION OF CAPITAL STRUCTURE AND SHARES
The Fund is an unincorporated statutory trust established under the laws of the State of Delaware upon the filing of a Certificate of Trust with the Secretary of State of Delaware on May 25, 2012. The Trustees are authorized to issue an unlimited number of shares. The Fund does not intend to hold annual meetings of its shareholders.
The Declaration of Trust, which has been filed with the SEC, permits the Fund to issue an unlimited number of full and fractional shares of beneficial interest, no par value. The Fund offers five different classes of shares: Class A, Class C, Class I, Class L, and Class M shares. The Class A, Class I, Class L and Class M shares are each offered by a different prospectus. The Fund began continuously offering its common shares on October 22, 2012. As of February 18, 2014, the Fund simultaneously redesignated its issued and outstanding common shares as Class A shares and created its Class C and Class I shares, which commenced offering April 1, 2014. As of May 30, 2017, the Fund created its Class L shares. As of February 1, 2020, the Fund created its Class M shares. An investment in any share class of the Fund represents an investment in the same assets of the Fund. However, the minimum investment amounts, sales loads, and ongoing fees and expenses for each share class may be different. The fees and expenses for the Fund are set forth in “Summary of Fund Expenses”. The details of each share class are set forth in “Plan of Distribution”.
The following table shows the amounts of the Fund’s shares that have been authorized and are outstanding as of January 3, 2025, of which none were owned by the Fund:
Title of Class |
Amount Authorized |
Amount Outstanding |
Class A |
Unlimited |
24,385,031.72 shares NAV $26.03 per share |
Unlimited |
shares NAV $24.05 per share |
|
Class I |
Unlimited |
115,282,227.36 shares NAV $26.80 per share |
Class L |
Unlimited |
3,111,066.77 shares NAV $25.54 per share |
Class M |
Unlimited |
4,381,277.79 shares NAV $24.24 per share |
Holders of shares will be entitled to the payment of dividends when, as and if declared by the Board. The Fund currently intends to make dividend distributions to its shareholders no less frequently than quarterly. Unless the registered owner of shares elects to receive cash, all dividends declared on shares will be automatically reinvested for shareholders in additional shares of the same class of the Fund. See “Dividend Reinvestment Policy.” The 1940 Act may limit the payment of dividends to the holders of shares. Each whole share shall be entitled to one vote as to matters on which it is entitled to vote pursuant to the terms of the Declaration of Trust on file with the SEC. Upon liquidation of the Fund, after paying or adequately providing for the payment of all liabilities of the Fund, and upon receipt of such releases, indemnities and refunding agreements as they deem necessary for their protection, the Trustees may distribute the remaining assets of the Fund among its shareholders. The shares are not liable to further calls or to assessment by the Fund. There are no pre-emptive rights associated with the shares. The Declaration of Trust provides that the Fund’s shareholders are not liable for any liabilities of the Fund. Although shareholders of an unincorporated statutory trust established under Delaware law, in certain limited circumstances, may be held personally liable for the obligations of the Fund as though they were general partners, the provisions of the Declaration of Trust described in the foregoing sentence make the likelihood of such personal liability remote.
The Fund generally will not issue share certificates. However, upon written request to the Fund’s Transfer Agent, a share certificate may be issued at the Fund’s discretion for any or all of the full shares credited to an investor’s account. Share certificates that have been issued to an investor may be returned at any time. The Fund’s Transfer Agent will maintain an account for each shareholder upon which the registration of shares are recorded, and transfers, permitted only in rare circumstances, such as death or bona fide gift, will be reflected by bookkeeping entry, without physical delivery. The Fund’s Transfer Agent will require that a shareholder provide requests in writing, accompanied by a valid signature guarantee form, when changing certain information in an account such as wiring instructions or telephone privileges.
Other Classes of Shares. The Fund offers Class A, Class I Class L, and Class M shares by a different prospectus. The other share classes are subject to different investment minimums, sales charges, and shareholder servicing fees and/or distribution servicing fees.
ANTI-TAKEOVER PROVISIONS IN THE DECLARATION OF TRUST
The Amended and Restated Declaration of Trust includes provisions that could have the effect of limiting the ability of other entities or persons to acquire control of the Fund or to change the composition of the Board, and could have the effect of depriving the Fund’s shareholders of an opportunity to sell their shares at a premium over prevailing market prices, if any, by discouraging a third party from seeking to obtain control of the Fund. These provisions may have the effect of discouraging attempts to acquire control of the Fund, which attempts could have the effect of increasing the expenses of the Fund and interfering with the normal operation of the
28 |
Fund. The Trustees are elected for indefinite terms and do not stand for reelection. A Trustee may be removed from office without cause only by a written instrument signed or adopted by a majority of the remaining Trustees or by a vote of the holders of at least two-thirds of the shares of the Fund that are entitled to elect a Trustee and that are entitled to vote on the matter. The Declaration of Trust does not contain any other specific inhibiting provisions that would operate only with respect to an extraordinary transaction such as a merger, reorganization, tender offer, sale or transfer of substantially all of the Fund’s asset, or liquidation. Reference should be made to the Declaration of Trust on file with the SEC for the full text of these provisions.
PLAN OF DISTRIBUTION
ALPS Distributors, Inc. (the “Distributor”), located at 1290 Broadway, Suite 1000, Denver, Colorado 80203, serves as the Fund’s principal underwriter and acts as the distributor of the Fund’s shares on a best efforts basis, subject to various conditions. The Fund’s shares are offered for sale through the Distributor at net asset value plus the applicable sales load. The Distributor also may enter into selected dealer agreements with other broker dealers for the sale and distribution of the Fund’s shares, including with affiliates of the Advisor. In reliance on Rule 415, the Fund intends to offer to sell its shares, on a continual basis, through the Distributor. No arrangement has been made to place funds received in an escrow, trust or similar account. The Distributor is not required to sell any specific number or dollar amount of the Fund’s shares. Shares of the Fund will not be listed on any national securities exchange and the Distributor will not act as a market marker in Fund shares. The Class C shares will pay to the Distributor a Distribution Fee that will accrue at an annual rate equal to 0.75% of the Fund’s average daily net assets attributable to Class C shares and is payable on a monthly basis.
The Distributor has entered into a “wholesaling” agreement with Bluerock Capital Markets, LLC (“BCM”), a registered broker-dealer and an affiliate of the Advisor. Pursuant to the terms of the wholesaling agreement, BCM will seek to market and otherwise promote the Fund through various “wholesale” distribution channels, including regional and independent retail broker-dealers. BCM may receive a portion of the sales load from the sale of certain classes of the Fund’s shares for the services it provides under the wholesaling agreement, but it does not receive compensation from the Fund in connection with the sale of Class C shares.
The Advisor or its affiliates, in the Advisor’s discretion and from their own resources, may pay additional compensation to brokers or dealers in connection with the sale and distribution of Fund shares (the “Additional Compensation”). In return for the Additional Compensation, the Fund may receive certain marketing advantages including access to a broker’s or dealer’s registered representatives, placement on a list of investment options offered by a broker or dealer, or the ability to assist in training and educating the broker’s or dealer’s registered representatives. The Additional Compensation may differ among brokers or dealers in amount or in the manner of calculation: payments of Additional Compensation may be fixed dollar amounts, or based on the aggregate value of outstanding shares held by shareholders introduced by the broker or dealer, or determined in some other manner. The receipt of Additional Compensation by a selling broker or dealer may create potential conflicts of interest between an investor and its broker or dealer who is recommending the Fund over other potential investments. Additionally, the Fund may pay a servicing fee to intermediaries and other financial industry professionals for providing ongoing services in respect of shareholders of the Fund. Such services may include electronic processing of client orders, electronic fund transfers between clients and the Fund, account reconciliations with the Fund’s Transfer Agent, facilitation of electronic delivery to clients of Fund documentation, monitoring client accounts for back-up withholding and any other special tax reporting obligations, maintenance of books and records with respect to the foregoing, and such other information and liaison services as the Fund or the Advisor may reasonably request.
The Fund and the Advisor have agreed to indemnify the Distributor against certain liabilities, including liabilities under the Securities Act of 1933, or to contribute to payments the Distributor may be required to make because of any of those liabilities. Such agreement does not include indemnification of the Distributor against liability resulting from willful misfeasance, bad faith or negligence on the part of the Distributor in the performance of its duties or from reckless disregard by the Distributor of its obligations and duties under the Distribution Agreement. The Distributor may, from time to time, engage in transactions with or perform services for the Advisor and its affiliates in the ordinary course of business.
Purchasing Shares
Investors may purchase shares directly from the Fund in accordance with the instructions below. Investors will be assessed fees for returned checks and stop payment orders at prevailing rates charged by SS&C GIDS, the Fund’s Transfer Agent. The returned check and stop payment fee is currently $25. Investors may buy and sell shares of the Fund through financial intermediaries and their agents that have made arrangements with the Fund and are authorized to buy and sell shares of the Fund (collectively, “Financial Intermediaries”). Such Financial Intermediaries are authorized to designate other intermediaries to receive purchase orders on the Fund’s behalf. The Fund will be deemed to have received a purchase order when a Financial Intermediary or, if applicable, its authorized designee, receives the order. Orders will be priced at the appropriate price next computed after it is received by a Financial Intermediary or their authorized designee and accepted by the Fund. A Financial Intermediary may hold shares in an omnibus account in the Financial Intermediary’s name or the Financial Intermediary or their authorized designee may maintain individual ownership records. The Fund may pay the Financial Intermediary for maintaining individual ownership records as well as providing other shareholder services. Financial intermediaries may charge fees for the services they provide in connection with processing your transaction order or maintaining an investor’s account with them. Investors should check with their Financial Intermediary to determine if it is subject to these arrangements. Financial Intermediaries are responsible for placing orders correctly and promptly with the Fund, forwarding payment promptly. Orders transmitted with a Financial Intermediary before the close of regular trading (generally 4:00 p.m., Eastern Time) on a day that the NYSE is open for business, will be priced based on the Fund’s NAV next computed after it is received by the Financial Intermediary.
The Fund reserves the right to reject or restrict purchase requests for any reason, particularly when the shareholder’s trading activity suggests that the shareholder may be engaged in disruptive trading activities. Neither the Fund nor the Advisor will be liable for any losses resulting from rejected purchase orders.
29 |
By Mail
To make an initial purchase by mail, complete an account application and mail the application, together with a check made payable to Bluerock Total Income+ Real Estate Fund to:
Bluerock Total Income+ Real Estate Fund
c/o SS&C GIDS
P.O. Box 219445
Kansas City, MO 64121-9445
All checks must be in U.S. Dollars drawn on a domestic bank. The Fund will not accept payment in cash or money orders. The Fund also does not accept cashier’s checks in amounts of less than $10,000. To prevent check fraud, the Fund will neither accept third party checks, Treasury checks, credit card checks, traveler’s checks or starter checks for the purchase of shares, nor post-dated checks, post-dated on-line bill pay checks, or any conditional purchase order or payment.
The Transfer Agent will charge a $25 fee against an investor’s account, in addition to any loss sustained by the Fund, for any payment that is returned. It is the policy of the Fund not to accept applications under certain circumstances or in amounts considered disadvantageous to shareholders. The Fund reserves the right to reject any application.
By Wire — Initial Investment
To make an initial investment in the Fund, the Transfer Agent must receive a completed account application before an investor wires funds. Investors may mail or overnight deliver an account application to the Transfer Agent. Upon receipt of the completed account application, the Transfer Agent will establish an account. The account number assigned will be required as part of the instruction that should be provided to an investor’s bank to send the wire. An investor’s bank must include both the name of the Fund, the account number, and the investor’s name so that monies can be correctly applied. If you wish to wire money to make an investment in the Fund, please call the Fund at 1-844-819-8287 for wiring instructions and to notify the Fund that a wire transfer is coming. Any commercial bank can transfer same-day funds via wire. The Fund will normally accept wired funds for investment on the day received if they are received by the Fund’s designated bank before the close of regular trading on the NYSE. Your bank may charge you a fee for wiring same-day funds. The bank should transmit funds by wire to:
ABA #: (number provided by calling toll-free number above)
Credit: SS&C GIDS
Account #: (number provided by calling toll-free number above)
Further Credit:
Bluerock Total Income+ Real Estate Fund
(shareholder registration)
(shareholder account number)
By Wire — Subsequent Investments
Before sending a wire, investors must contact the Transfer Agent to advise them of the intent to wire funds. This will ensure prompt and accurate credit upon receipt of the wire. Wired funds must be received prior to 4:00 p.m. Eastern Time to be eligible for same day pricing. The Fund, and its agents, including the transfer agent and custodian, are not responsible for the consequences of delays resulting from the banking or Federal Reserve wire system, or from incomplete wiring instructions.
Automatic Investment Plan — Subsequent Investments
You may participate in the Fund’s Automatic Investment Plan, an investment plan that automatically moves money from your bank account and invests it in the Fund through the use of electronic funds transfers or automatic bank drafts. You may elect to make subsequent investments by transfers of a minimum of $100 on specified days of each month into your established Fund account. Please contact the Fund at 1-844-819-8287 for more information about the Fund’s Automatic Investment Plan.
By Telephone
Investors may purchase additional shares of the Fund by calling 1-844-819-8287. If an investor elected this option on the account application, and the account has been open for at least 15 days, telephone orders will be accepted via electronic funds transfer from your bank account through the Automated Clearing House (ACH) network. Banking information must be established on the account prior to making a purchase. Orders for shares received prior to 4:00 p.m. Eastern Time will be purchased at the appropriate price calculated on that day.
Telephone trades must be received by or prior to market close. During periods of high market activity, shareholders may encounter higher than usual call waits. Please allow sufficient time to place your telephone transaction.
In compliance with the USA Patriot Act of 2001, the Transfer Agent will verify certain information on each account application as part of the Fund’s Anti-Money Laundering Program. As requested on the application, investors must supply full name, date of birth, social security number and permanent street address. Mailing addresses containing only a P.O. Box will not be accepted. Investors may call the Transfer Agent (SS&C GIDS) at 1-844-819-8287 for additional assistance when completing an application.
If the Transfer Agent does not have a reasonable belief of the identity of a customer, the account will be rejected or the customer will not be allowed to perform a transaction on the account until such information is received. The Fund also may reserve the right to close the account within 5 business days if clarifying information/documentation is not received.
30 |
Share Class Considerations
When selecting a share class, you should consider the following:
|
● |
which share classes are available to you; |
|
● |
the amount you intend to invest; |
|
● |
how long you expect to own the shares; and |
|
● |
total costs and expenses associated with a particular share class. |
Each investor’s financial considerations are different. You should speak with your financial advisor to help you decide which share class is best for you. Not all financial intermediaries offer all classes of shares. If your financial intermediary offers more than one class of shares, you should carefully consider which class of shares to purchase.
Class C Shares
Class C shares are sold at the prevailing NAV per Class C share and are not subject to any upfront sales charge; however, the following are additional features that should be taken into account when purchasing Class C shares:
|
● |
a minimum initial investment of $2,500 for regular accounts and $1,000 for retirement plan accounts, and a minimum subsequent investment of at least $100 for regular accounts and $50 for retirement plan accounts; |
|
● |
a monthly shareholder servicing fee at an annual rate of up to 0.25% of the average daily net assets of the Fund attributable to Class C shares; |
|
● |
a Distribution Fee which will accrue at an annual rate equal to 0.75% of the average daily net assets of the Fund attributable to Class C shares; and |
|
● |
an early withdrawal charge equal to 1.00% of the original purchase price of Class C shares repurchased by the Fund that have been held, as of the time of repurchase, less than 365 days from the purchase date. |
The Distributor advances the first year of the Distribution Fee and the shareholder servicing fee (equal to 1% of the amount invested) to dealers who sell Class C shares. The Advisor or an affiliate reimburses the Distributor for monies advanced to dealers. Because the Class C shares of the Fund are sold at the prevailing NAV per Class C share without an upfront sales load, the entire amount of your purchase is invested immediately.
Share Conversion
For investors currently owning Class A, Class C, and Class L and/or Class M shares, these shares may be convertible into Class I shares if (i) the broker/dealer or other financial intermediary responsible for the shareholder relationship requests such conversion, (ii) Class I shares are available to the broker dealer or financial intermediary, and (iii) the account would have been eligible to purchase Class I shares. More detailed information on Class I shares and the related investment minimums and other restrictions is available in the Fund’s Class I prospectus.
Class C shares will automatically convert into Class A shares after they have been held for eight years.
Shareholder Service Plan
The Fund has adopted a “Shareholder Services Plan” with respect to its Class C shares under which the Fund may compensate financial industry organizations for providing ongoing shareholder servicing of client accounts with whom they have distributed shares of the Fund. Such services may include electronic processing of client orders, electronic fund transfers between clients and the Fund, account reconciliations with the Fund’s transfer agent, facilitation of electronic delivery to clients of Fund documentation, monitoring client accounts for back-up withholding and any other special tax reporting obligations, maintenance of books and records with respect to the foregoing, and such other information and liaison services as the Fund or the Advisor may reasonably request. Under the Shareholder Services Plan, the Fund, with respect to its Class C shares, may incur expenses on an annual basis equal up to 0.25% of its average net assets attributable to Class C shares. Because these fees are paid from the Fund’s assets on an ongoing basis they will increase your costs over time and may cost you more than paying other types of sales charges.
Distribution Plan
The Fund, with respect to its Class C shares, is authorized under a “Distribution Plan” to pay to the Distributor a Distribution Fee for certain activities relating to the distribution of shares to investors and maintenance of shareholder accounts. These activities include marketing and other activities to support the distribution of the Class C shares. The Plan operates in a manner consistent with Rule 12b-1 under the 1940 Act, which regulates the manner in which an open-end investment company may directly or indirectly bear the expenses of distributing its shares. Although the Fund is not an open-end investment company, it has undertaken to comply with the terms of Rule 12b-1 as a condition of an exemptive order under the 1940 Act which permits it to have asset based distribution fees. Under the Distribution Plan, the Fund pays the Distributor a Distribution Fee at an annual rate of 0.75% of average daily net assets attributable to Class C shares. Because these fees are paid from the Fund’s assets on an ongoing basis they will increase your costs over time and may cost you more than paying other types of sales charges.
LEGAL MATTERS
Certain legal matters in connection with the shares will be passed upon for the Fund by Thompson Hine LLP, 41 South High Street, Suite 1700, Columbus, Ohio 43215.
31 |
REPORTS TO SHAREHOLDERS
The Fund makes available to its shareholders unaudited semi-annual and audited annual reports, including a list of investments held.
Householding
If you have elected to receive paper copies of the Fund’s annual and semi-annual reports, in an effort to decrease costs, the Fund intends to send only one copy of each to those addresses shared by two or more accounts and to shareholders reasonably believed to be from the same family or household. A shareholder must call 1-844-819-8287 to discontinue householding and request individual copies of these documents. Once the Fund receives notice to stop householding, individual copies will be sent beginning thirty days after receiving your request. This policy does not apply to account statements.
INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
Cohen & Company, Ltd. is the independent registered public accounting firm for the Fund and audits the Fund’s financial statements. Cohen & Company, Ltd. is located at 1835 Market St., Suite 310, Philadelphia, PA 19103.
ADDITIONAL INFORMATION
The Prospectus and the Statement of Additional Information do not contain all of the information set forth in the Registration Statement that the Fund has filed with the SEC (file No. 811-22710). The complete Registration Statement may be obtained from the SEC at www.sec.gov. See the cover page of this prospectus for information about how to obtain a paper copy of the Registration Statement or Statement of Additional Information without charge.
TABLE OF CONTENTS OF THE STATEMENT OF ADDITIONAL INFORMATION
General Information and History |
1 |
Investment Objectives and Policies |
1 |
Repurchases and Transfers of Shares |
9 |
Management of the Fund |
15 |
Codes of Ethics |
21 |
Proxy Voting Policies and Procedures |
21 |
Control Persons and Principal Holders |
22 |
Investment Advisory and Other Services |
23 |
Portfolio Managers |
26 |
Allocation of Brokerage |
30 |
Tax Status |
31 |
Other Information |
36 |
Independent Registered Public Accounting Firm |
37 |
Financial Statements |
37 |
Appendix A |
A-1 |
Appendix B |
B-1 |
32 |
PRIVACY POLICY & PRACTICES
Rev. January 2019
PRIVACY NOTICE
FACTS |
WHAT DOES THE BLUEROCK TOTAL INCOME+ REAL ESTATE FUND DO WITH YOUR PERSONAL INFORMATION? |
|
Why? |
Financial companies choose how they share your personal information. Federal law gives consumers the right to limit some but not all sharing. Federal law also requires us to tell you how we collect, share, and protect your personal information. Please read this notice carefully to understand what we do. |
|
What? |
The types of personal information we collect and share depend on the product or service you have with us. This information can include: |
|
●Social Security number
●Assets
●Retirement Assets
●Transaction History
●Checking Account Information |
●Purchase History
●Account Balances
●Account Transactions
●Wire Transfer Instructions |
|
When you are no longer our customer, we may continue to share your personal information as described in this notice. |
||
How? |
All financial companies need to share customers’ personal information to run their everyday business. In the section below, we list the reasons financial companies can share their customers’ personal information; the reasons the Bluerock Total Income+ Real Estate Fund chooses to share; and whether you can limit this sharing. |
|
Reasons we can share your personal information |
Does Bluerock Total Income+ Real Estate Fund share? |
Can you limit this sharing? |
For our everyday business purposes – such as to process your transactions, maintain your account(s), respond to court orders and legal investigations, or report to credit bureaus |
Yes |
No |
For our marketing purposes – to offer our products and services to you |
No |
We don’t share |
For joint marketing with other financial companies |
No |
We don’t share |
For our affiliates’ everyday business purposes – information about your transactions and experiences |
No |
We don’t share |
For our affiliates’ everyday business purposes – information about your creditworthiness |
No |
We don’t share |
For nonaffiliates to market to you |
No |
We don’t share |
Questions? |
Call 1-844-819-8287 |
33 |
Who we are |
|
Who is providing this notice? |
Bluerock Total Income+ Real Estate Fund |
What we do |
|
How does Bluerock Total Income+ Real Estate Fund protect my personal information? |
To protect your personal information from unauthorized access and use, we use security measures that comply with federal law. These measures include computer safeguards and secured files and buildings.
Our service providers are held accountable for adhering to strict policies and procedures to prevent any misuse of your nonpublic personal information. |
How does Bluerock Total Income+ Real Estate Fund collect my personal information? |
We collect your personal information, for example, when you
●Open an account
●Provide account information
●Give us your contact information
●Make deposits or withdrawals from your account
●Make a wire transfer
●Tell us where to send the money
●Tells us who receives the money
●Show your government-issued ID
●Show your driver’s license
We also collect your personal information from other companies. |
Why can’t I limit all sharing? |
Federal law gives you the right to limit only
●Sharing for affiliates’ everyday business purposes – information about your creditworthiness
●Affiliates from using your information to market to you
●Sharing for nonaffiliates to market to you
State laws and individual companies may give you additional rights to limit sharing. |
Definitions |
|
Affiliates |
Companies related by common ownership or control. They can be financial and nonfinancial companies.
●Bluerock Total Income+ Real Estate Fund does not share with our affiliates. |
Nonaffiliates |
Companies not related by common ownership or control. They can be financial and nonfinancial companies
●Bluerock Total Income+ Real Estate Fund does not share with nonaffiliates so they can market to you. |
Joint marketing |
A formal agreement between nonaffiliated financial companies that together market financial products or services to you.
●Bluerock Total Income+ Real Estate Fund doesn’t jointly market. |
34 |
Page Intentionally Left Blank
Page Intentionally Left Blank
Page Intentionally Left Blank

BLUEROCK TOTAL INCOME+ REAL ESTATE FUND
Class C Shares (TIPPX) of Beneficial Interest
PROSPECTUS
February 1, 2025
Investment Advisor
Bluerock Fund Advisor, LLC
All dealers that buy, sell or trade the Fund’s shares, whether or not participating in this offering, may be required to deliver a prospectus when acting on behalf of the Fund’s Distributor.
You should rely only on the information contained in or incorporated by reference into this prospectus. The Fund has not authorized any other person to provide you with different information. If anyone provides you with different or inconsistent information, you should not rely on it. The Fund is not making an offer to sell these securities in any jurisdiction where the offer or sale is not permitted.

Bluerock Total Income+ Real Estate Fund (the “Fund”) is a continuously offered, non-diversified, closed-end management investment company that is operated as an interval fund.
The Securities and Exchange Commission has not approved or disapproved these securities or determined if this Prospectus is truthful or complete. Any representation to the contrary is a criminal offense.
This prospectus is intended to concisely provide you, a prospective investor, with information about the Fund that you should know before investing in the shares of the Fund that are being offered through this prospectus. You are advised to thoroughly and carefully read this prospectus and retain it for future reference. Additional information about the Fund is also available on the Securities and Exchange Commission’s (“SEC”) website at http://www.sec.gov, including the Fund’s Statement of Additional Information dated February 1, 2025 (the “SAI”). The address of the SEC’s website is provided solely for the information of prospective shareholders and is not intended to be an active link. The table of contents of the SAI appears on page 32 of this prospectus. The SAI is incorporated by reference into this prospectus (legally made a part of this prospectus). The SAI, Fund annual and semi-annual reports and other information and shareholder inquiries regarding the Fund may be requested free of charge by writing the Fund at c/o SS&C Global Investor & Distribution Solutions, Inc., PO Box 219445, Kansas City, MO 64121-9445 (the “Transfer Agent” or “SS&C GIDS”), by calling the Transfer Agent toll-free at 1-844-819-8287, or by visiting the Fund’s website at http://www.bluerockfunds.com.
Investment Objectives. The Fund’s primary investment objective is to generate current income while secondarily seeking long-term capital appreciation with low to moderate volatility and low correlation to the broader markets.
Summary of Investment Strategy. The Fund pursues its investment objectives using a comprehensive multi-strategy, multi-manager, multi-sector approach, primarily investing in a strategic combination of what the Fund’s advisor believes are global ‘best in class’ institutional private real estate funds and public real estate securities.
The Advisor. The Fund’s investment advisor is Bluerock Fund Advisor, LLC (the “Advisor”), a registered advisor under the Investment Advisers Act of 1940, as amended (the “Advisers Act”). The Advisor has engaged Mercer Investments LLC (“Mercer” or a “Sub-Advisor”), a registered advisor under the Advisers Act, to provide ongoing research, opinions and recommendations of institutional asset managers and their investment funds for consideration by the Advisor on behalf of the Fund. Mercer, together with its affiliated investment businesses, have over 5,600 delegated and advisory clients globally with over $547 billion in assets under management as of September 30, 2024 and over $17.5 trillion in assets under advisement as of June 30, 2024. The Advisor has also engaged RREEF America L.L.C. (“RREEF” or a “Sub-Advisor”), a registered adviser under the Advisers Act, to provide investment management for a portion, generally less than 20%, of the Fund’s portfolio. RREEF, together with its affiliates in Europe and Asia, comprise the global real estate investment business of DWS Group GmbH & Co. KGaA (“DWS”), an indirect majority owned subsidiary of Deutsche Bank A.G. DWS’s real estate investment business, is one of the largest real estate investment managers globally with more than 330 professionals and staff located in 23 cities worldwide and approximately $78.9 billion in real estate and real estate-related assets under management as of September 30, 2024.
See “The Fund” and “Investment Objectives, Strategies and Investment Features.”
Securities Offered. The Fund engages in a continuous offering of classes of shares of beneficial interest of the Fund. Class I shares are offered by this prospectus. The Fund offers Class A, Class C, Class L and Class M shares by different prospectuses. The Fund is authorized as a Delaware statutory trust to issue an unlimited number of shares. The Fund is offering to sell, through its principal underwriter, ALPS Distributors, Inc., (the “Distributor”) on a continual basis under the terms of this prospectus, shares of beneficial interest at net asset value (“NAV”) per share of the relevant share class, plus any applicable sales load. As of January 3, 2025, the Fund’s NAV per share was $26.80 for Class I shares. The minimum initial investment for Class I shares is $1,000,000, while subsequent investments may be made in any amount. The Distributor is not required to sell any specific number or dollar amount of the Fund’s shares, but will use reasonable efforts to sell the shares. No termination date of the Fund’s continuous offering has been established. Monies received will be invested promptly and no arrangements have been made to place such monies in an escrow, trust or similar account. See “Plan of Distribution.”
The Fund’s shares have no history of public trading, nor is it intended that they will be listed on a public exchange at this time. No secondary market is expected to develop for the Fund’s shares, liquidity for the Fund’s shares will be provided only through quarterly repurchase offers for no less than 5% of the Fund’s shares and there is no guarantee that an investor will be able to sell all the shares that the investor desires to sell in the repurchase offer. Investing in the Fund’s shares involves substantial risks, including the risks set forth in the “Risk Factors” section of this prospectus.
|
Investment Advisor | Bluerock Fund Advisor, LLC |

TABLE OF CONTENTS
TABLE OF CONTENTS OF THE STATEMENT OF ADDITIONAL INFORMATION |
|
PROSPECTUS SUMMARY
This summary does not contain all of the information that you should consider before investing in the shares. You should review the more detailed information contained or incorporated by reference in this prospectus and in the Statement of Additional Information, particularly the information set forth below under the heading “Risk Factors.”
The Fund
Bluerock Total Income+ Real Estate Fund (the “Fund”) is a continuously offered, non-diversified, closed-end management investment company. See “The Fund.” The Fund is an interval fund that provides investor liquidity by offering to make quarterly repurchases of each class of shares at that class of shares’ net asset value, which will be calculated on a daily basis. See “Quarterly Repurchases of Shares,” and “Determination of Net Asset Value.”
Investment Objectives and Policies
The Fund’s primary investment objective is to generate current income while secondarily seeking long-term capital appreciation with low to moderate volatility and low correlation to the broader markets.
The Fund pursues its investment objectives by investing, under normal circumstances, at least 80% of net assets, plus the amount of any borrowings for investment purposes, in “real estate industry securities,” primarily in income producing equity and debt securities. The Fund invests in debt securities of any duration or maturity.
The Fund concentrates investments in the real estate industry, meaning that under normal circumstances, it invests over 25% of its assets in real estate industry securities. The Fund’s investments may be targeted in any one or more of the many sectors of the real estate market, including but not limited to the retail, office, multifamily, hospitality, industrial, residential, healthcare, life sciences, and self-storage sectors. The Fund defines real estate industry securities to include the common stock, partnership or similar interests, asset-backed securities, preferred stock, and secured or unsecured debt. Real estate industry securities may be issued by a wide variety of entities including: private real estate investment funds managed by institutional investment managers (“Institutional Investment Funds”); non-traded unregistered real estate investment trusts (“Private REITs”); publicly traded real estate investment trusts or other similar companies (“Public REITs”); Government Sponsored Entities (“GSEs”) such as Federal Home Loan Mortgage Corporation Structured Pass-Through Certificates (“K-Notes”); exchange traded funds, index mutual funds, and other investment vehicles such as closed-end funds and mutual funds that invest principally, directly or indirectly, in real estate (collectively, “Other Public Investment Vehicles”) and unregistered funds that invest principally in real estate. In certain circumstances or market environments, the Fund may reduce its investment in real estate industry securities and hold a larger position in cash or cash equivalents. The Fund will not invest in any issuer that is an affiliate of the Fund, or affiliate of a Fund affiliate (as defined by the Investment Company Act of 1940, as amended (the “1940 Act”)).
The Fund’s real estate industry investment policy is fundamental and may not be changed without shareholder approval. The Fund’s Statement of Additional Information (“SAI”) contains a list of all of the fundamental and non-fundamental investment policies of the Fund, under the heading “Investment Objectives and Policies.”
Investment Strategy
The Fund pursues its investment objectives using a comprehensive multi-strategy, multi-manager, multi-sector approach, primarily investing in a strategic combination of global ‘best in class’ institutional private real estate investment funds and public real estate securities.
The term ‘best in class’ refers to Institutional Investment Funds the Advisor has identified as offering above average prospects using information provided by Mercer and its proprietary screening process. Mercer’s screening process applies multiple factors including quantitative and qualitative assessment (as described more fully below) of the management team and track record, and is not generally available to the individual investor through financial filings or published reports. Mercer is one of the leading advisors to endowments, pension funds, sovereign wealth funds, and family offices globally.
The Fund executes a portion of its investment strategy, generally less than 20%, by seeking to invest in publicly traded real estate securities selected by RREEF, an indirect subsidiary of DWS. RREEF seeks to maximize risk-adjusted returns by managing volatility and identifying securities that are priced inefficiently relative to its assessment of intrinsic value and the public real estate securities may be of any credit quality; including fixed-income and preferred securities rated less than investment grade that are sometimes referred to as high yield or “junk bonds.” The Advisor or RREEF will sell a security when other securities are available that offer higher expected current income, long-term capital appreciation, lower volatility or lower correlation to broader securities markets or a combination of the preceding.
The Fund may utilize leverage through borrowing for investment purposes or to satisfy repurchase requests. The Fund currently borrows money under two credit facilities.
Many of the Institutional Investment Funds have a large minimum investment size and stringent investor qualification criteria that are intended to limit their direct investors to mainly institutions such as endowments and pension funds. As such, the Fund enables investors to invest with institutional investment managers that may not be otherwise permitted or available to them.
In addition, the Fund enables investors to execute a comprehensive multi-strategy, multi-manager, multi-sector strategy by making a single investment in the Fund, whereas due to the large minimums of many of the Institutional Investment Funds, such a strategy may not otherwise be permitted or available to the investor.
1 |
The Advisor also believes that the Fund may be able to provide an additional benefit in terms of lower fees from the Institutional Investment Funds as a result of volume discounts that may not otherwise be permitted or available to them.
Investment Advisor
Bluerock Fund Advisor, LLC was formed on May 11, 2012 and is registered with the SEC as an investment adviser. The Advisor is a subsidiary of Bluerock Asset Management, LLC (“BAM”); BAM, together with its affiliates (“Bluerock”), is a leading institutional alternative asset manager with more than $19.2 billion in acquired and managed assets based in New York with regional offices across the United States. Bluerock principals have a collective 100+ years of investing experience with more than $120 billion of real estate and capital markets experience and manage multiple well-recognized real estate private and public company platforms.
Sub-Advisors
The Advisor may, from time to time, engage one or more investment sub-advisors. Any sub-advisor chosen by the Advisor will be paid by the Advisor on only the portion of Fund assets allocated to any such sub-advisor. Shareholders do not pay any sub-advisor directly.
The Advisor has engaged Mercer, a registered investment adviser under the Advisers Act, to provide both ongoing research and opinions of institutional asset managers and their investment funds for consideration by the Advisor on behalf of the Fund as well as recommendations for the selection of investment funds for approval by the Advisor. The Advisor has engaged RREEF, a registered investment adviser under the Advisers Act, to invest a portion of the Fund’s portfolio in publicly traded real estate securities and to provide the Advisor with research and information with respect to non-publicly traded real estate related debt securities.
Advisor Fees and Expenses
The Advisor is entitled to receive a monthly fee at the annual rate of 1.50% of the Fund’s daily net assets. The Advisor and the Fund have entered into an expense limitation and reimbursement agreement (the “Expense Limitation Agreement”) under which the Advisor has contractually agreed to waive its fees and to pay or absorb the ordinary operating expenses of the Fund (excluding any taxes, interest, brokerage commissions, acquired fund fees and expenses, and extraordinary expenses, such as litigation or reorganization costs, but including organizational costs and offering costs), to the extent that such expenses exceed 1.70% per annum of the Fund’s average daily net assets (the “Expense Limitation”) attributable to Class I shares. In consideration of the Advisor’s agreement to limit the Fund’s expenses, the Fund has agreed to repay the Advisor in the amount of any fees the Advisor previously waived or Fund expenses reimbursed, subject to the limitations that: (1) the reimbursement will be made if payable not more than three years from the date incurred; (2) the reimbursement may not be made if it would cause the expense limitation then in effect or in effect at the time of the waiver to be exceeded; and (3) the reimbursement is approved by the Fund’s Board of Trustees (the “Board”). The Expense Limitation Agreement will remain in effect at least until January 31, 2026, unless and until the Board approves its modification or termination. After January 31, 2026, the Expense Limitation Agreement may be renewed at the Advisor’s and Board’s discretion. See “Management of the Fund.”
Administrator, Accounting Agent and Transfer Agent
ALPS Fund Services, Inc. (the “Administrator”) serves as the Fund’s administrator and accounting agent. SS&C Global Investor & Distribution Solutions, Inc. (the “Transfer Agent” or “SS&C GIDS”) serves as the transfer agent of the Fund. See “Management of the Fund.”
Distribution Fees
Class I Shares are not subject to a Distribution Fee. See “Plan of Distribution.”
Closed-End Fund Structure
Generally, closed-end funds differ from mutual funds in that closed-end funds do not typically redeem their shares at the option of the shareholder. Closed-end fund shares typically trade in the secondary market via a stock exchange. Unlike many closed-end funds, however, the Fund’s shares will not be listed on a stock exchange. Instead, the Fund will provide limited liquidity to shareholders by offering to repurchase a limited amount of the Fund’s shares (at least 5%) quarterly, which is discussed in more detail below. The Fund, similar to a mutual fund, is subject to continuous asset in-flows, although not subject to continuous out-flows.
Share Classes
The Fund offers Class I shares by this prospectus. The Fund began continuously offering its common shares on October 22, 2012. As of February 18, 2014, the Fund simultaneously redesignated its issued and outstanding common shares as Class A shares and created its Class C shares and Class I shares, each offered by a separate prospectus. As of May 30, 2017, the Fund created its Class L shares. As of February 1, 2020, the Fund created its Class M shares. An investment in any share class of the Fund represents an investment in the same assets of the Fund. However, the sales loads and ongoing fees and expenses for each share class are different. The loads, fees and expenses for the Fund are set forth in “Summary of Fund Expenses.” If an investor has hired an intermediary and is eligible to invest in more than one class of shares, the intermediary may help determine which share class is appropriate for that investor. When selecting a share class, you should consider which share classes are available to you, how much you intend to invest, the investment minimum, how long you expect to own shares, and the total costs and expenses associated with a particular share class.
2 |
Each investor’s financial considerations are different. You should speak with your financial advisor to help you decide which share class is best for you. Not all financial intermediaries offer all classes of shares and all share classes may not be available in every state. If your financial intermediary offers more than one class of shares, you should carefully consider which class of shares to purchase.
Investor Suitability
An investment in the Fund involves a considerable amount of risk. It is possible that you will lose some or all of your money. An investment in the Fund is suitable only for investors who can bear the risks associated with the limited liquidity of the shares and should be viewed as a medium to long-term investment. Before making your investment decision, you should (i) consider the suitability of this investment with respect to your investment objectives and personal financial situation and (ii) consider factors such as your personal net worth, income, age, risk tolerance and liquidity needs.
Repurchases of Shares
The Fund is an interval fund and, as such, has adopted a fundamental policy to make quarterly repurchase offers, at net asset value, of no less than 5% of the Fund’s outstanding shares. There is no guarantee that shareholders will be able to sell all of the shares they desire to sell in a quarterly repurchase offer. Liquidity will be provided to shareholders only through the Fund’s quarterly repurchases. See “Quarterly Repurchases of Shares.”
Summary of Risks
Investing in the Fund involves risks, including the risk that you may receive little or no return on your investment or that you may lose part or all of your investment. Before investing you should consider carefully the risks that you assume when you invest in the Fund’s shares. See “Risk Factors.”
Real Estate Industry Concentration Risk. The Fund will concentrate its investments in real estate related securities, and it may invest in real estate directly. As such, its portfolio will be significantly impacted by the performance of the real estate market and may experience more volatility and be exposed to greater risk than a more diversified portfolio. The value of companies engaged in the real estate industry is affected by: (i) changes in general economic and market conditions; (ii) changes in the value of real estate properties; (iii) risks related to local economic conditions, overbuilding and increased competition; (iv) increases in property taxes and operating expenses; (v) changes in zoning laws; (vi) casualty and condemnation losses; (vii) variations in rental income, neighborhood values or the appeal of property to tenants; (viii) the availability of financing; (ix) climate change and (x) changes in interest rates and leverage. There are also special risks associated with particular sectors, or real estate operations, including, but not limited to, those risks described below:
Retail Properties. Retail properties are affected by shifts in consumer demand due to demographic changes, changes in spending patterns and lease terminations.
Office Properties. Office properties are affected by a downturn in the businesses operated by their tenants.
Hospitality Properties. Hotel properties and other properties in the hospitality real estate sector, such as motels and extended-stay properties, are affected by declines in business and leisure travel.
Healthcare and Life Sciences Properties. Healthcare and life sciences properties are affected by potential federal, state and local laws governing licenses, certification, adequacy of care, pharmaceutical distribution, rates, equipment, personnel and other factors regarding operations, funding for biotech companies and the continued availability of revenue from government reimbursement programs.
Industrial Properties. Industrial properties are affected by downturns in the manufacturing, processing and shipping of goods.
Multifamily Properties. Multifamily properties are affected by adverse economic conditions in the locale, oversupply and rent control laws.
Residential Properties. Residential properties can be significantly affected by the national, regional and local real estate markets. This segment of the real estate industry also is sensitive to interest rate fluctuations which can cause changes in the availability of mortgage capital and directly affect the purchasing power of potential homebuyers. Thus, residential properties can be significantly affected by changes in government spending, consumer confidence, demographic patterns and the level of new and existing home sales.
Shopping Centers. Shopping center properties are affected by changes in the local markets where their properties are located and dependent upon the successful operations and financial condition of their major tenants.
Self-Storage Properties. Self-storage properties are affected by changes to competing local properties, consumer and small business demand for storage space, and the ability of the management team.
Other factors may contribute to the risk of real estate investments:
Development Issues. Real estate development companies in which the Underlying Funds (defined below) or the Fund may invest are affected by construction delays and insufficient tenant demand to occupy newly developed properties.
3 |
Lack of Insurance. Certain of the companies in the Fund’s portfolio may fail to carry comprehensive liability, fire, flood, wind or earthquake extended coverage and rental loss insurance, or insurance and may be subject to various policy specifications, limits and deductibles. Due to the prevalence of catastrophic events, the cost of insurance may increase materially.
Dependence on Tenants. The ability of companies in the real estate industry in which the Fund may invest to make distributions to shareholders depends upon the ability of the tenants at their properties to generate enough income in excess of tenant operating expenses to make their lease payments.
Financial Leverage. Companies in the real estate industry in which the Fund may invest may be highly leveraged and financial covenants may affect their ability to operate effectively. The use of floating rate loans may also negatively impact returns in a rising interest rate environment.
Environmental Issues. Owners of properties that may contain hazardous or toxic substances may be responsible for removal or remediation costs. Environmental risk from high winds, hurricanes, fires, flood and extreme heat may also materially affect a property’s value.
Credit Market Conditions. Instability in credit markets can potentially make it more difficult for borrowers to obtain financing or refinancing on attractive terms or at all. Conditions in the credit markets may expose borrowers to increased interest expenses for borrowed money and tightening underwriting standards. There is also a risk that a general lack of liquidity or other events in the credit markets may adversely affect the ability of issuers in whose securities the Fund invests to finance real estate developments and projects or refinance completed projects.
Market Risk. An investment in shares is subject to investment risk, including the possible loss of the entire principal amount invested. An investment in shares represents an indirect investment in the securities owned by the Fund. The value of these securities, like other market investments, may move up or down, sometimes rapidly and unpredictably. In addition, the Fund is subject to the risk that geopolitical and other similar events will disrupt the economy on a national or global level. For instance, war, terrorism, market manipulation, government defaults, government shutdowns, political changes or diplomatic developments, public health emergencies (such as the spread of infectious diseases, pandemics and epidemics) and natural/environmental disasters can all negatively impact the securities markets.
Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. The foregoing could impair the Fund’s ability to maintain operational standards, disrupt the operations of the Fund and its service providers, adversely affect the performance, value and liquidity of the Fund’s investments, and negatively impact the Fund’s performance and your investment in the Fund. The value of your shares at any point in time may be worth less than the value of your original investment, even after taking into account any reinvestment of dividends and distributions.
Liquidity Risk. There currently is no secondary market for the Fund’s shares and the Advisor does not expect that a secondary market will develop. Limited liquidity is provided to shareholders only through the Fund’s quarterly repurchase offers for no less than 5% of the Fund’s shares outstanding at net asset value. There is no guarantee that shareholders will be able to sell all of the shares they desire in a quarterly repurchase offer. The Fund’s investments also are subject to liquidity risk. Liquidity risk exists when particular investments of the Fund would be difficult to purchase or sell, possibly preventing the Fund from selling such illiquid securities at an advantageous time or price, or possibly requiring the Fund to dispose of other investments at unfavorable times or prices in order to satisfy its obligations.
Allocation Risk. The ability of the Fund to achieve its investment objective depends, in part, on the ability of the Advisor to allocate effectively the Fund’s assets among the various Institutional Investment Funds, Private REITs, Public REITs and Other Public Investment Vehicles in which the Fund invests and, with respect to each such asset class, among equity and fixed income securities. There can be no assurance that the actual allocations will be effective in achieving the Fund’s investment objective or delivering positive returns.
Correlation Risk. The Fund seeks to produce returns that are not correlated to the broader financial markets. Although the prices of equity securities and fixed-income securities, as well as other asset classes, often rise and fall at different times so that a fall in the price of one may be offset by a rise in the price of the other, in down markets the prices of these securities and asset classes can also fall in tandem. Because the Fund allocates its investments among different real estate asset classes, the Fund is subject to correlation risk.
Credit Risk. It is possible that issuers of debt securities may not make scheduled interest and principal payments, resulting in losses to the Fund. In addition, the credit quality of securities held may be lowered if an issuer’s financial condition changes and this also may negatively impact the Fund’s returns on investment in such securities.
Distribution Policy Risk. The Fund’s distribution policy is expected to result in distributions that equal a fixed percentage of the Fund’s current net asset value per share. All or a portion of a distribution may consist of a return of capital (i.e. from your original investment). Shareholders should not assume that the source of a distribution from the Fund is net profit. Shareholders should note that return of capital will reduce the tax basis of their shares and potentially increase the taxable gain, if any, upon disposition of their shares.
Fixed Income Risk. Typically, a rise in interest rates causes a decline in the value of fixed income securities. Recently, interest rates have risen sharply after maintaining historically low levels for a significant period of time. Current conditions may result in an increase in interest rate volatility, which in turn may result in a decline in the value of the fixed income investments held by the Fund. As a result, for the present, interest rate risk may be heightened. Fixed income securities are also subject to default risk.
4 |
Institutional Investment Fund Risk. The Fund’s investment in Institutional Investment Funds will require it to bear a pro rata share of the vehicles’ expenses, including management and performance fees. The fees the Fund pays to invest in an Institutional Investment Fund may be higher than if the manager of the Institutional Investment Fund managed the Fund’s assets directly. The performance fees charged by certain Institutional Investment Funds may create an incentive for its manager to make investments that are riskier and/or more speculative than those it might have made in the absence of a performance fee. Furthermore, Institutional Investment Funds, like the other “Underlying Funds” in which the Fund may invest, are subject to specific risks, depending on the nature of the vehicle, and also may employ leverage such that their returns are more than one times that of their benchmark which could amplify losses suffered by the Fund when compared to unleveraged investments. Shareholders of the Institutional Investment Funds are not entitled to the protections of the 1940 Act. For example, these funds need not have independent boards, shareholder approval of advisory contracts may not be required, may leverage to an unlimited extent, and may engage in joint transactions with affiliates. These characteristics present additional risks for shareholders.
Issuer and Non-Diversification Risk. The value of a specific security can perform differently from the market as a whole for reasons related to the investment manager or issuer, such as management performance, financial leverage and reduced demand for the respective properties and services. The Fund’s performance may be more sensitive to any single economic, business, political or regulatory occurrence than the value of shares of a diversified investment company because as a non-diversified fund, the Fund may invest more than 5% of its total assets in the securities of one or more issuers.
Lack of Control Over Institutional Investment Funds and Other Portfolio Investments. Once the Advisor or RREEF has selected an Institutional Investment Fund, Private REIT, Public REIT, or Other Public Investment Vehicle (each, an “Underlying Fund” and together, the “Underlying Funds”) for investment by the Fund, the Advisor and RREEF will have no control over the investment decisions made by any such Underlying Fund. Although the Fund and the Advisor or RREEF will evaluate regularly each Underlying Fund and its manager to determine whether their respective investment programs are consistent with the Fund’s investment objective, the Advisor and RREEF will not have any control over the investments made by any Underlying Fund. Even though the Underlying Funds are subject to certain constraints, the managers may change aspects of their investment strategies. The managers may do so at any time (for example, such change may occur immediately after providing the Advisor with the quarterly unaudited financial information for an Institutional Investment Fund). The Advisor or RREEF may reallocate the Fund’s investments among the Underlying Funds, but the Advisor’s ability to do so may be constrained by the withdrawal limitations imposed by certain of the Underlying Funds, which may prevent the Fund from reacting rapidly to market changes should an Underlying Fund fail to effect portfolio changes consistent with such market changes and the demands of the Advisor. Such withdrawal limitations may also restrict the Advisor’s ability to terminate investments in Underlying Funds that are poorly performing or have otherwise had adverse changes. The Advisor and RREEF will be dependent on information provided by the Underlying Fund, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s or RREEF’s ability to manage the Fund’s investment portfolio in accordance with its investment objectives.
Leveraging Risk. The use of leverage, such as borrowing money to purchase securities or otherwise invest the Fund’s assets, will cause the Fund to incur additional expenses and may significantly magnify the Fund’s losses in the event of adverse performance of the Fund’s underlying investments. In addition to any borrowing utilized by the Fund, the Underlying Funds in which the Fund invests may utilize leverage, subject to the limitations of their charters and operative documents. Leverage by Underlying Funds and/or the Fund has the effect of potentially increasing losses. In addition, interest rates (including benchmarks like Secured Overnight Financing Rate (“SOFR”) and the spreads to such benchmarks charged by lenders) are highly sensitive to external factors outside a borrower’s control, including general and local economic conditions (such as inflation, recession, money supply and unemployment) and the monetary and fiscal policies of various governmental agencies such as the Federal Reserve Board. During periods of increased interest rates, borrowing costs of the Fund will likely increase and may adversely affect the Fund’s performance.
Management Risk. The judgments of the Advisor or a Sub-Advisor about the attractiveness, value and potential appreciation of particular real estate segment and securities in which the Fund invests may prove to be incorrect and may not produce the desired results.
Possible Competition Between Underlying Funds and Between the Fund and the Underlying Funds. The Underlying Funds trade independently of each other and may pursue investment strategies that “compete” with each other for execution or that cause the Fund to participate in positions that offset each other (in which case the Fund would bear its pro rata share of commissions and fees without the potential for a profit). Also, the Fund’s investments in any particular Underlying Fund could increase the level of competition for the same trades that other Underlying Funds might otherwise make, including the priorities of order entry. This could make it difficult or impossible to take or liquidate a position in a particular security at a price consistent with the Advisor’s strategy.
Preferred Securities Risk. Preferred securities are subject to credit risk and interest rate risk. Interest rate risk is, in general, that the price of a debt security falls when interest rates rise. Securities with longer maturities tend to be more sensitive to interest rate changes. Credit risk is the risk that an issuer of a security may not be able to make principal and interest or dividend payments on the security as they become. Holders of preferred securities may not receive dividends, or the payment can be deferred for some period of time. In bankruptcy, creditors are generally paid before the holders of preferred securities.
REIT Risk. The value of investments in REIT shares may decline because of adverse developments affecting the real estate industry and real property values. In general, real estate values can be affected by a variety of factors, including supply and demand for properties, the economic health of the country or of different regions, and the strength of specific industries that rent properties. Also, qualification as a REIT under the Internal Revenue Code of 1986, as amended (the “Code”) in any particular year is a complex analysis that depends on a number of factors. There can be no assurance that an entity in which the Fund invests with the expectation that it will be taxed as a REIT will, in fact, qualify as a REIT. An entity that fails to qualify as a REIT would be subject to a corporate level tax, would not be entitled to a deduction for dividends paid to its shareholders and would not pass through to its shareholders the character of income earned by the entity.
5 |
Repurchase Policy Risks. Quarterly repurchases by the Fund of its shares typically will be funded from available cash or sales of portfolio securities. The sale of securities to fund repurchases could reduce the market price of those securities, which in turn would reduce the Fund’s net asset value.
Underlying Funds Risk. Investments in real estate index funds (“Index Funds”), real estate exchange traded funds (“ETFs”), and Other Public Investment Vehicles are subject to investment advisory and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in such Other Public Investment Vehicles, and also may be higher than other funds that invest directly in securities. Further, Other Public Investment Vehicles are subject to specific risks, depending on the nature of the fund.
Valuation of Institutional Investment Funds. Institutional Investment Funds are not publicly traded and the Fund may consider information provided by the institutional asset manager to determine the value of the Fund’s investment therein. The valuation provided by an institutional asset manager as of a specific date may vary from the actual sale price that may be obtained if such investment were sold to a third party. To determine the value of the Fund’s investment in Institutional Investment Funds, the Advisor considers, among other things, information provided by the Institutional Investment Funds, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s ability to value accurately the Fund’s shares. Institutional Investment Funds that invest primarily in publicly traded securities are more easily valued.
U.S. Federal Income Tax Matters
The Fund intends to elect to be treated and to qualify each year for taxation as a regulated investment company under Subchapter M of the Code. In order for the Fund to so qualify, it must meet an income and asset diversification test each year. If the Fund so qualifies and satisfies the applicable distribution requirements, the Fund (but not its shareholders) will not be subject to federal income tax to the extent it distributes its investment company taxable income and net capital gains (the excess of net long-term capital gains over net short-term capital loss) in a timely manner to its shareholders in the form of dividends or capital gain distributions. The Code imposes a 4% nondeductible excise tax on regulated investment companies, such as the Fund, to the extent they do not meet certain distribution requirements by the end of each calendar year. The Fund anticipates meeting these distribution requirements. See “U.S. Federal Income Tax Matters.”
Distribution Policy
The Fund’s distribution policy is to make quarterly distributions to shareholders. The level of distributions (including any return of capital) is not fixed, but is expected to represent an annual rate of approximately 5.25% of the Fund’s current net asset value per share. However, this distribution policy is subject to change. Unless a shareholder elects otherwise, the shareholder’s distributions will be reinvested in additional shares of the same class under the Fund’s dividend reinvestment policy. Shareholders who elect not to participate in the Fund’s dividend reinvestment policy will receive all distributions in cash paid to the shareholder of record (or, if the shares are held in street or other nominee name, then to such nominee). See “Dividend Reinvestment Policy.”
Custodian
UMB Bank, N.A. (“UMB Bank”) serves as the custodian for the Fund. See “Management of the Fund.”
6 |
SUMMARY OF FUND EXPENSES
Shareholder Transaction Expenses |
Class I |
Maximum
Sales Load |
|
Maximum Early Withdrawal Charge (as a percent of original purchase price) |
Annual Expenses (as a percentage of net assets attributable to shares) |
|
Management Fees |
|
Other Expenses |
|
Shareholder Servicing Fee |
|
Distribution Fee |
|
Remaining Other Expenses |
|
Interest Payments on Borrowed Funds1 |
|
Acquired Fund Fees and Expenses |
|
Total Annual Expenses |
|
Fee Waiver and Expense Reimbursement2 |
( |
Total Annual Expenses (after fee waiver and reimbursement) |
|
|
1. |
|
|
2. |
|
The following example illustrates the hypothetical expenses that you would pay on a $1,000 investment assuming annual expenses attributable to shares remain unchanged and shares earn a 5% annual return:
Share Class |
1 Year |
3 Years |
5 Years |
10 Years |
Class I Shares |
$ |
$ |
$ |
$ |
Shareholders who choose to participate in repurchase offers by the Fund will not incur an early withdrawal charge However, if shareholders request repurchase proceeds be paid by wire transfer, such shareholders will be assessed an outgoing wire transfer fee at prevailing rates charged by the Transfer Agent, currently $10. The purpose of the above table is to help a holder of shares understand the fees and expenses that such holder would bear directly or indirectly. The example should not be considered a representation of actual future expenses. Actual expenses may be higher or lower than those shown.
7 |
FINANCIAL HIGHLIGHTS
Class I Shares
The financial highlights table below is intended to help you understand the Fund’s financial performance since its inception. Certain information reflects financial results for a single Share. The total returns in the table represent the rate that an investor would have earned (or lost) on an investment in the Fund (assuming reinvestment of all dividends and other distributions). This information has been derived from the Fund’s financial statements, which have been audited by Cohen & Company, Ltd., the Fund’s independent registered public accounting firm, whose report, along with the Fund’s financial statements, is included in the Fund’s Annual Report for the fiscal year ended September 30, 2024, which is available upon request.
|
For the |
For the |
For the |
For the |
For the |
For the |
For the |
For the |
For the |
For the |
||||||||||||||||||||||||||||||
Net asset value, beginning of year |
$ | 31.55 | $ | 37.99 | $ | 33.35 | $ | 29.80 | $ | 30.92 | $ | 30.40 | $ | 29.70 | $ | 29.38 | $ | 28.85 | $ | 28.03 | ||||||||||||||||||||
INCOME FROM INVESTMENT OPERATIONS: |
||||||||||||||||||||||||||||||||||||||||
Net investment income/(loss)(a) |
(0.27 | ) | (0.05 | ) | 0.48 | 0.58 | 0.56 | 0.42 | 0.29 | 0.31 | 0.28 | 0.45 | ||||||||||||||||||||||||||||
Net realized and unrealized gain/(loss) |
(2.47 | ) | (4.57 | ) | 6.12 | 4.61 | (0.07 | ) | 1.72 | 2.01 | 1.57 | 1.79 | 1.88 | |||||||||||||||||||||||||||
Total from investment operations |
(2.74 | ) | (4.62 | ) | 6.60 | 5.19 | 0.49 | 2.14 | 2.30 | 1.88 | 2.07 | 2.33 | ||||||||||||||||||||||||||||
DISTRIBUTIONS: |
||||||||||||||||||||||||||||||||||||||||
From net investment income |
— | — | — | — | (0.06 | ) | — | — | — | — | (0.10 | ) | ||||||||||||||||||||||||||||
From net realized gain on investments |
(0.14 | ) | (0.19 | ) | (0.42 | ) | (0.63 | ) | (1.04 | ) | (0.32 | ) | (0.54 | ) | (0.37 | ) | (0.16 | ) | (0.29 | ) | ||||||||||||||||||||
Return of capital |
(1.39 | ) | (1.63 | ) | (1.54 | ) | (1.01 | ) | (0.51 | ) | (1.30 | ) | (1.06 | ) | (1.19 | ) | (1.38 | ) | (1.12 | ) | ||||||||||||||||||||
Total distributions |
(1.53 | ) | (1.82 | ) | (1.96 | ) | (1.64 | ) | (1.61 | ) | (1.62 | ) | (1.60 | ) | (1.56 | ) | (1.54 | ) | (1.51 | ) | ||||||||||||||||||||
Net asset value, end of year |
$ | 27.28 | $ | 31.55 | $ | 37.99 | $ | 33.35 | $ | 29.80 | $ | 30.92 | $ | 30.40 | $ | 29.70 | $ | 29.38 | $ | 28.85 | ||||||||||||||||||||
TOTAL RETURN(b)(c) |
(8.84 | )% | (12.44 | )% | 20.09 | % | 17.99 | % | 1.61 | % | 7.23 | % | 7.91 | % | 6.58 | % | 7.36 | % | 8.51 | % | ||||||||||||||||||||
RATIOS/SUPPLEMENTAL DATA: |
||||||||||||||||||||||||||||||||||||||||
Net assets, end of year (000s) |
$ | 3,245,874 | $ | 4,207,299 | $ | 5,288,747 | $ | 2,012,129 | $ | 1,341,848 | $ | 1,040,017 | $ | 471,116 | $ | 257,366 | $ | 110,845 | $ | 25,274 | ||||||||||||||||||||
Ratios to Average Net Assets (including interest expense) |
||||||||||||||||||||||||||||||||||||||||
Ratio of expenses to average net assets excluding fee waivers and reimbursements(d)(e) |
3.58 | % | 2.88 | % | 1.77 | % | 1.83 | % | 1.91 | % | 1.94 | % | 2.22 | % | 2.15 | % | 1.96 | % | 2.03 | % | ||||||||||||||||||||
Ratio of expenses to average net assets including fee waivers and reimbursements(e) |
3.57 | % | 2.88 | % | 1.78 | % | 1.81 | % | 1.91 | % | 1.95 | % | 2.15 | % | 1.99 | % | 1.56 | % | 1.54 | % | ||||||||||||||||||||
8 |
|
For the |
For the |
For the |
For the |
For the |
For the |
For the |
For the |
For the |
For the |
||||||||||||||||||||||||||||||
Ratio of net investment income/(loss) to average net assets(e) |
(0.90 | )% | (0.15 | )% | 1.30 | % | 1.89 | % | 1.82 | % | 1.38 | % | 0.95 | % | 1.06 | % | 0.96 | % | 1.59 | % | ||||||||||||||||||||
Ratios to Average Net Assets (excluding interest expense) |
||||||||||||||||||||||||||||||||||||||||
Ratio of expenses to average net assets excluding fee waivers and reimbursements(d)(e) |
1.71 | % | 1.70 | % | 1.68 | % | 1.72 | % | 1.67 | % | 1.69 | % | 1.75 | % | 1.80 | % | 1.96 | % | 2.02 | % | ||||||||||||||||||||
Ratio of expenses to average net assets including fee waivers and reimbursements(e) |
1.70 | % | 1.70 | % | 1.69 | % | 1.70 | % | 1.67 | % | 1.70 | % | 1.68 | % | 1.64 | % | 1.56 | % | 1.53 | % | ||||||||||||||||||||
Portfolio turnover rate |
14 | % | 13 | % | 4 | % | 26 | % | 27 | % | 8 | % | 13 | % | 16 | % | 18 | % | 35 | % | ||||||||||||||||||||
|
(a) |
Per share amounts are calculated using the average shares method. |
|
(b) |
Includes adjustments in accordance with accounting principles generally accepted in the United States and, consequently, the net asset value for financial reporting purposes and the returns based upon those net asset values may differ from the net asset values and returns for shareholder transactions. |
(c) |
Total returns are historical in nature and assume changes in net asset value per share, reinvestment of dividends and capital gains distributions, if any. Had the Advisor not absorbed a portion of the Fund expenses, total returns would have been lower. |
|
(d) |
Represents the ratio of expenses to average net assets absent fee waivers expense reimbursement and/or recoupment by the Advisor. |
|
(e) |
The ratios of expenses to average net assets and net investment income to average net assets do not directly reflect the expenses of the underlying institutional private real estate investments in which the Fund invests. The Fund invests in each underlying institutional private real estate investment based upon its net asset value, inclusive of management fees, which typically range from 0.50% to 1.30% on an annualized basis. The Fund’s Total Return is reported net of all fees and expenses. |
THE FUND
The Fund is a continuously offered, non-diversified, closed-end management investment company that is operated as an interval fund. The Fund was organized as a Delaware statutory trust on May 25, 2012. The Fund’s principal office is located at 919 Third Avenue, 40th Floor, New York, NY 10022, and its telephone number is 1-844-819-8287.
USE OF PROCEEDS
The net proceeds of the Fund’s continuous offering of shares, after payment of the sales load (if applicable) and other associated expenses, will be invested in accordance with the Fund’s investment objective and policies (as stated below) as soon as practicable after receipt. The Fund pays organizational costs and its offering expenses incurred with respect to its initial and continuous offering. Pending investment of the net proceeds in accordance with the Fund’s investment objective and policies, the Fund will invest in money market or short-term fixed-income mutual funds. Investors should expect, therefore, that before the Fund has fully invested the proceeds of the offering in accordance with its investment objective and policies, the Fund’s assets would earn interest income at a modest rate.
INVESTMENT OBJECTIVE, POLICIES AND STRATEGIES
Investment Objective and Policies
The Fund seeks primarily to generate current income while secondarily seeking long-term capital appreciation with low to moderate volatility and low correlation to the broader markets.
9 |
The Fund pursues its investment objectives by investing, under normal circumstances, at least 80% of its net assets, plus the amount of any borrowings for investment purposes, in real estate industry securities, primarily in income producing equity and debt securities. The Fund’s investments may be targeted in any one or more of the many sectors of the real estate market, including but not limited to the retail, office, multifamily, hospitality, industrial, residential, healthcare, life sciences, and self-storage sectors. The Fund concentrates investments in the real estate industry, meaning that under normal circumstances, it invests over 25% of its assets in real estate industry securities. The Fund may utilize leverage through borrowing for investment purposes or to satisfy repurchase requests. The Fund currently borrows money under two credit facilities.
The Fund defines real estate industry securities to include the common stock, partnership or similar interests, asset-backed securities, preferred stock, and secured or unsecured debt. Real estate industry securities may be issued by a wide variety of entities including: private real estate investment funds managed by institutional investment managers (“Institutional Investment Funds”); non-traded unregistered real estate investment trusts (“Private REITs”); publicly traded real estate investment trusts or other similar companies (“Public REITs”); Government Sponsored Entities (“GSEs”) such as Federal Home Loan Mortgage Corporation Structured Pass-Through Certificates (“K-Notes”), exchange traded funds, index mutual funds, and other investment vehicles such as closed-end funds and mutual funds that invest principally, directly or indirectly, in real estate (collectively, “Other Public Investment Vehicles”) and unregistered funds that invest principally in real estate.
The Fund may invest in issuers of real estate industry securities of any credit quality; including fixed-income and preferred securities rated less than investment grade that are sometimes referred to as high yield or “junk bonds.” The Fund may invest in debt securities of any duration or maturity. The Fund may also, to a limited extent, make real estate-related investments other than through real estate industry securities. The Advisor or RREEF will sell a security when other securities are available that offer higher expected current income, higher expected long-term capital appreciation, lower volatility or lower correlation to broader securities markets or a combination of the preceding.
The Fund’s SAI contains a list of the fundamental (those that may not be changed without a shareholder vote) and non-fundamental (if any) investment policies of the Fund under the heading “Investment Objective and Policies.”
Fund’s Target Investment Portfolio
The Advisor executes the Fund’s real estate investment strategy primarily through a strategic combination of global ‘best in class’ Institutional Investment Funds, publicly traded real estate securities, and real estate related debt investments. The Fund will not invest more than 10% of the Fund’s assets in private funds employing hedging strategies (commonly known as “hedge funds”, i.e., investment funds that would be investment companies but for the exemptions under Rule 3(c)(1) or 3(c)(7) under the 1940 Act).
The Advisor has retained Mercer to provide ongoing research and investment opinions of and/or recommendations of institutional investment managers using the Mercer’s proprietary screening process, which applies multiple factors based on quantitative and qualitative assessment of the management team and track record. The Advisor has engaged RREEF to invest a portion of the Fund’s portfolio, generally less than 20%, in publicly traded real estate securities (Public REITs and Other Public Investment Vehicles). RREEF selects securities to seek to maximize risk-adjusted returns by managing volatility and identifying securities that are priced inefficiently relative to its assessment of intrinsic value.
Institutional Investment Funds. Institutional Investment Funds are real estate investment funds managed by institutional investment managers with expertise in managing portfolios of real estate and real estate-related securities. Many Institutional Investment Funds have large minimum investment requirements and stringent investor qualification criteria intended to limit their direct investors to mainly institutions such as endowments and pension funds. It is the intent of the Fund to provide an element of the endowment model of investing to individual investors by permitting access to a portfolio of Institutional Investment Funds with diversification across multiple strategies, managers and sectors.
The Advisor also believes that the Fund may provide an additional benefit in terms of better fee pricing from the Institutional Investment Funds as a result of volume discounts, which pricing benefits may not otherwise be permitted or available to other investors. In addition, the Fund’s investments in Institutional Investment Funds are intended to deliver returns that have a low correlation to the broader markets.
The Fund’s typical investments in Institutional Investment Funds will be made through the purchase of common stock, limited liability company units, or limited partnership interests (or similar interests). Investment criteria will include evaluating a combination of strength of the sponsor and management; prior investment performance of the target fund as well as the performance of other funds managed by the sponsor; the attractiveness of the property sectors and geographical allocations of the fund; expected stability of income; expected capital appreciation, and target leverage levels.
REITs. The Fund may invest, directly or indirectly in Real Estate Investment Trusts (“REITs”). REITs are investment vehicles that invest primarily in income-producing real estate or mortgages and other real estate-related loans or interests. Public REITs are listed on major stock exchanges such as the New York Stock Exchange (“NYSE”) or the National Association of Securities Dealers Automated Quotation System (“NASDAQ”), and invest directly in real estate, typically through either properties or mortgages.
Other Public Investment Vehicles. The Fund anticipates making limited investments in Other Public Investment Vehicles, including ETFs and Index Funds that invest primarily in real estate related assets, principally to temporarily invest the Fund’s capital pending its deployment into other higher-returning investment opportunities, or for temporary defensive purposes under adverse market conditions.
10 |
Exchange Traded Funds (“ETFs”). ETFs are typically managed by professionals and provide investors with diversification, cost and tax efficiency, liquidity, marginability, are useful for hedging, have the ability to go long and short, and some provide quarterly dividends. An ETF typically holds a portfolio of securities or contracts designed to track a particular market segment or index. ETFs are listed on major stock exchanges and are traded like stocks.
Index Funds. An Index Fund is a mutual fund with an investment objective of seeking to replicate the performance of a specific securities index, such as the National Association of Real Estate Investment Trusts (NAREIT) Index or the MSCI REIT Index. Most Index Funds are not actively managed and generally provide broad market exposure, low operating expenses and low portfolio turnover.
Other. In addition to ETFs and Index Funds, and subject to the Fund’s investment restrictions, the Fund may invest in investment companies that invest primarily in what the Advisor considers real estate industry securities, including closed-end funds and mutual funds. Shares of Closed-end Funds are typically listed for trading on major stock exchanges and, in some cases, may be traded in other over-the-counter markets.
Real Estate Related Debt Investments. The Fund may invest in real estate related direct debt including first and second mortgage loans, mezzanine loans and other structured debt investments.
Investment Strategy, and Criteria Used by the Advisor and Mercer in Selecting Investments
The Fund’s investment strategy focuses primarily on identifying Institutional Investment Funds that have:
|
● |
attractive risk-adjusted returns; |
|
● |
with low to moderate volatility; |
|
● |
low correlation to the broader markets; and |
|
● |
an emphasis on income generation. |
The Fund utilizes a comprehensive multi-manager, multi-sector, and multi-strategy approach. The Advisor primarily selects funds with the highest expected risk-adjusted returns from a real estate sector peer group of issuers with similar market capitalization and/or credit quality. Secondarily, the Advisor considers potential for capital appreciation. When constructing and balancing the Fund’s portfolio, the Advisor selects funds from real estate sectors that it believes have relatively low volatility and will not be highly correlated to each other or to the equity or fixed income markets, generally.
The Advisor, working closely with Mercer and in consideration of its recommendations, uses both a quantitative screening process and a qualitative selection process when selecting investments for the Fund to implement its real estate investment strategy. The Advisor and Mercer conduct research on various real estate investment managers and investment options in order to establish a selection of investments to fulfill the Fund’s investment objectives. Mercer’s assistance and recommendations for selection of investment funds are made according to asset allocation, return expectations and other guidelines set by the Advisor with oversight of the Board. No assurance can be given that any or all investment strategies, or the Fund’s investment program, will be successful.
Investment Strategy – Mercer Process
Mercer’s process begins with a proprietary database created and continuously maintained by its professionals - the Global Investment Manager Database (GIMD™) which gives Mercer access to up-to-date information and insights on a worldwide matrix of investment managers and strategies. GIMD™ contains information on numerous investment types across all asset classes, including real estate. This information ranges from access to and analysis of performance data to qualitative forward-looking research on investment managers supported by screening functionality. In the twelve months leading up to September 30, 2024, over 2,700 formal manager meetings were held and over 3,600 Research Reports were produced globally. As of September 30, 2024, GIMD™ contained information on over 6,800 investment managers and over 32,300 investment strategies.
Mercer, together with its global investment management affiliates, have over 3,300 delegated clients globally.
The Advisor has entered into a Sub-Advisory Agreement with Mercer Investments LLC (“Mercer” or a “Sub-Advisor”), 99 High Street, Boston, MA 02110.
11 |

The Advisor, in conjunction with Mercer, employs a regimen of quantitative and qualitative criteria to arrive at a universe of investments which are considered to be ‘best in class.’ By combining historical quantitative analysis with a sound knowledge of key qualitative attributes, the Advisor will evaluate a prospective investment’s potential for generating sustainable, positive, risk-adjusted returns under a wide variety of market conditions. Mercer’s investment selection and due diligence process are outlined in the chart below.

On-going monitoring of the Fund’s investments will be utilized to assist the Advisor in maintaining portfolio allocations and managing cash in-flows and outflows. The Advisor may strategically rebalance its investment strategies according to the current market conditions, but will remain true to its fundamental analysis with respect to real estate asset class and sector risk over time. The
12 |
Advisor manages investments over a long-term time horizon while being mindful of the historical context of the markets. Mercer will provide to the Advisor investment performance reporting and analysis, including discussions on investment strategy, portfolio construction, and market update reports. The illustration below further outlines this monitoring process.

Investment Strategy - Multi-Manager Diversification
The Fund intends to employ a Multi-Manager approach by identifying and investing with ‘best in class’ institutional asset managers with expertise in managing portfolios of real estate and real estate-related securities. The term ‘best in class’ refers to Institutional Investment Funds that the Advisor and Mercer have identified through Mercer’s proprietary screening process as having above average prospects.
Many of the Institutional Investment Funds have large minimum investment size and stringent investor qualification criteria intended to limit their direct investors to mainly institutions such as endowments and pension funds. As such, the Fund enables investors to invest with institutional investment managers that may not be otherwise permitted or available to them.
The Fund also enables investors to execute a comprehensive multi-strategy, multi-manager, multi-sector strategy by making a single investment in its shares, whereas due to the large minimums of many of the Institutional Investment Funds, such a strategy may not otherwise be permitted or available to the investor.
The sponsor believes that the Fund may provide an additional benefit in terms of lower fees from the Institutional Investment Funds as a result of volume discounts, which pricing benefits may not otherwise be permitted or available to them.
Investment Strategy - Multi-Strategy Diversification
The Fund intends to employ a Multi-Strategy approach to diversify the risk-reward profiles and the underlying types of real estate in which it invests, with the strategies noted below. Because each real estate strategy performs differently throughout the overall real estate and economic cycle, investment strategies that include multiple strategies generally have lower volatility than single strategy funds. Thus, a multi-strategy approach should assist the Fund in achieving its objective of lower portfolio volatility as well as lower correlation with the broader markets.
|
● |
Core. The Fund’s ‘core’ strategy targets high-quality portfolios with real estate assets that provide relatively lower and more stable returns. Such investments are typically located in primary markets and in the main property types (retail, office, industrial and multi-family). Properties are stable, well-maintained, well-leased and often of the Class A variety. For example, office properties, including life sciences, tend to be Class A buildings with investment grade tenants. Multifamily properties are usually in major metropolitan cities with higher rental rates. Retail would typically be more traditional neighborhood and community strip-mall centers, as well as regional and super regional malls. The Advisor believes that warehouse and research and development properties in strong distribution centers typically offer better chances for predictable cash flow within the industrial sector. As an example, a Class A office property may broadly be defined as 100,000 square feet or larger (five or more floors), concrete and steel construction, recently built and/or very well maintained (excellent condition), with business/support amenities and in a strong identifiable location with good access to a primary metropolitan market. Class A properties are the most prestigious buildings competing for premier tenants with rents above average for the area. |
|
● |
Core Plus. The Fund’s ‘core plus’ strategy seeks moderate risk portfolios with real estate that provides moderate returns. Such investments are predominantly core but with an emphasis on a modest value add management approach. A core plus portfolio requires slightly more complex financial structuring and management intensive focus than a core portfolio of investments. Focus is on the main property types, in both primary and secondary markets, in Class A or lower quality buildings that require some form of enhancement (i.e. repositioning, redevelopment and/or releasing). In comparison to the Class A example above, a Class B property may be renovated and/or in good condition, potentially smaller in size, in a good location in a primary or secondary metropolitan market. Class B properties compete for a wide range of users with rents in the average range for the area. |
13 |
|
● |
Value Add. The Fund’s ‘value add’ strategy typically focuses on more aggressive active asset management and often employs more leverage. Such investments typically are lower quality buildings, in both primary and secondary markets in the main property types or development projects. Properties are considered value add when they exhibit management or operational problems, require physical improvement, and/or suffer from capital constraints. Buildings often require enhancement to upgrade them to higher quality properties (i.e., redevelopment/repositioning/re-tenanting). |
Investment Strategy - Multi-Sector Diversification
The Fund intends to employ a Multi-Sector approach to diversify its investments by property type or sector - for example, across retail, office, multifamily, hospitality, industrial, residential, healthcare, life sciences and/or self-storage sectors. Because each real estate sector has its own investment cycle, correlations across property types are generally low. Thus, employing a multi-sector approach should assist the Fund in achieving its objective of low to moderate volatility as well as low correlation to the broader markets.
Additional Information Regarding Investment Strategy
The Fund may, from time to time, in attempting to respond to adverse market, economic, political or other similar conditions, take temporary defensive positions that are inconsistent with the Fund’s principal investment strategy. During such times, the Advisor may determine that the Fund should invest up to 100% of its assets in cash or cash equivalents, including money market instruments, prime commercial paper, repurchase agreements, Treasury bills and other short-term obligations of the U.S. Government, its agencies or instrumentalities. In addition to the foregoing, the Fund may utilize Other Public Investment Vehicles as temporary investments as the Fund raises capital or pending deployment of capital to other investment opportunities selected by the Advisor. In these and in other cases, the Fund may not achieve its investment objective. The Advisor may invest the Fund’s cash balances in any investments it deems appropriate. The Advisor expects that such investments will be made, without limitation and as permitted under the 1940 Act, in money market mutual funds, repurchase agreements, U.S. Treasury and U.S. agency securities, municipal bonds and bank accounts. Any income earned from such investments is ordinarily reinvested by the Fund in accordance with its investment program. Many of the considerations entering into recommendations and decisions of the Advisor and the Fund’s Portfolio Managers are subjective.
The frequency and amount of portfolio purchases and sales (known as the “portfolio turnover rate”) will vary from year to year. The portfolio turnover rate is not expected to exceed 100%, but may vary greatly from year to year and will not be a limiting factor if the Advisor determines that portfolio changes are appropriate. Although the Fund generally does not intend to trade for short-term profits, the Fund may engage in short-term trading strategies, and securities may be sold without regard to the length of time held when, in the opinion of the Advisor, investment considerations warrant such action. These policies may have the effect of increasing the annual rate of portfolio turnover of the Fund. Higher rates of portfolio turnover would likely result in higher brokerage commissions and may generate short-term capital gains taxable as ordinary income. If securities are not held for the applicable holding periods, dividends paid on them will not qualify for the advantageous federal tax rates. See “Tax Status” in the Fund’s SAI.
There is no assurance what portion, if any, of the Fund’s investments will qualify for the reduced federal income tax rates applicable to qualified dividends under the Code. As a result, there can be no assurance as to what portion of the Fund’s distributions will be designated as qualified dividend income. See “U.S. Federal Income Tax Matters.”
Investment Strategy and Criteria Used by RREEF in Selecting Public Real Estate Securities
The Advisor with RREEF has developed an investment strategy intended to maximize risk-adjusted returns by managing volatility and identifying securities that are priced inefficiently relative to RREEF’s assessment of intrinsic value. RREEF believes that real estate security performance is reflective of the underlying real estate portfolio and, therefore, over time will be driven by the pricing and fundamentals of their assets. The risk management process is highly focused on quantitative risk factors as well as fundamental portfolio risk factors. RREEF’s investment universe encompasses over 100 property companies in the United States with a total market capitalization of over $800 billion. RREEF is focused on companies that derive the majority of their operating income or asset base from commercial real estate (apartments, office, industrial, storage, hotels, retail, net lease). Operating and capital efficiency are critically important to a successful real estate company and hence RREEF typically focuses on companies with large, high quality asset bases. If there are securities outside of this group that meet these criteria, RREEF will include these as part of the investable universe. The investment universe is generally defined as all REITs and REOCs (real estate operating companies) with an equity market capitalization of at least $200 million that derive the majority of revenue or net asset value (NAV) from an equity interest in real estate activities. The U.S. real estate securities portion of the Fund’s portfolio managed by RREEF typically holds between 35-50 securities. Under normal circumstances, such securities will generally comprise between 5% and 20% of the Fund’s portfolio. With respect to any investments in non-publicly traded real estate related debt securities, the Advisor makes all investment decisions.
RISK FACTORS
An investment in the Fund’s shares is subject to risks. The value of the Fund’s investments will increase or decrease based on changes in the prices of the investments it holds. This will cause the value of the Fund’s shares to increase or decrease. You could lose money by investing in the Fund. By itself, the Fund does not constitute a balanced investment program. Before investing in the Fund you should consider carefully the following risks. There may be additional risks that the Fund does not currently foresee or consider material. You may wish to consult with your legal or tax advisors before deciding whether to invest in the Fund.
Real Estate Industry Concentration Risk. Because the Fund will concentrate its investments in real estate related securities, its portfolio will be significantly impacted by the performance of the real estate market and may experience more volatility and be exposed to greater risk than a more diversified portfolio. In addition, the Fund may invest in real estate equity or debt and therefore may be subject to risks similar to those associated with direct investment in real property. The value of the Fund’s shares will be affected by factors affecting the value of real estate and the earnings of companies engaged in the real estate industry. These factors
14 |
include, among others: (i) changes in general economic and market conditions; (ii) changes in the value of real estate properties; (iii) risks related to local economic conditions, overbuilding and increased competition; (iv) increases in property taxes and operating expenses; (v) changes in zoning laws; (vi) casualty and condemnation losses; (vii) variations in rental income, neighborhood values or the appeal of property to tenants; (viii) the availability of financing; (ix) climate change and (x) changes in interest rates. Many real estate companies utilize leverage, which increases investment risk and could adversely affect a company’s operations and market value in periods of rising interest rates. The value of securities of companies in the real estate industry may go through cycles of relative under-performance and over-performance in comparison to equity securities markets in general.
There are also special risks associated with particular sectors, or real estate operations, including, but not limited to, those risks described below:
Retail Properties. Retail properties are affected by the overall health of the economy and may be adversely affected by, among other things, the growth of alternative forms of retailing, bankruptcy, departure or cessation of operations of a tenant, a shift in consumer demand due to demographic changes, changes in spending patterns and lease terminations.
Office Properties. Office properties are affected by the overall health of the economy, and other factors such as a downturn in the businesses operated by their tenants, obsolescence and non-competitiveness.
Industrial Properties. Industrial properties are affected by the overall health of the economy and other factors such as downturns in the manufacturing, processing and shipping of goods.
Hospitality Properties. The risks of hotel, motel and similar hospitality properties include, among other things, the necessity of a high level of continuing capital expenditures, competition, increases in operating costs which may not be offset by increases in revenues, dependence on business and commercial travelers and tourism, increases in fuel costs and other expenses of travel, and adverse effects of general and local economic conditions. Hotel properties tend to be more sensitive to adverse economic conditions and competition than many other commercial properties.
Healthcare and Life Sciences Properties. Healthcare and life sciences properties and healthcare providers are affected by several significant factors, including federal, state and local laws governing licenses, certification, adequacy of care, pharmaceutical distribution, rates, equipment, personnel and other factors regarding operations, funding for biotech companies, continued availability of revenue from government reimbursement programs and competition on a local and regional basis. The failure of any healthcare operator to comply with governmental laws and regulations may affect its ability to operate its facility or receive government reimbursements.
Multifamily Properties. The value and successful operation of a multifamily property may be affected by a number of factors such as the location of the property, the ability of the management team, the level of mortgage interest rates, the presence of competing properties, adverse economic conditions in the locale, oversupply and rent control laws or other laws affecting such properties.
Residential Properties. Residential properties can be significantly affected by the national, regional and local real estate markets. This segment of the real estate industry also is sensitive to interest rate fluctuations which can cause changes in the availability of mortgage capital and directly affect the purchasing power of potential homebuyers. Thus, residential properties can be significantly affected by changes in government spending, consumer confidence, demographic patterns and the level of new and existing home sales.
Shopping Centers. Shopping center properties are dependent upon the successful operations and financial condition of their tenants, particularly certain of their major tenants, and could be adversely affected by bankruptcy of those tenants. In some cases, a tenant may lease a significant portion of the space in one center, and the filing of bankruptcy could cause significant revenue loss, including the loss of revenue from smaller tenants with co-tenancy rights. Like others in the commercial real estate industry, community centers are subject to environmental risks and interest rate risk. They also face the need to enter into new leases or renew leases on favorable terms to generate rental revenues. Community center properties could be adversely affected by changes in the local markets where their properties are located, as well as by adverse changes in national economic and market conditions.
Self-Storage Properties. The value and successful operation of a self-storage property may be affected by a number of factors, such as the ability of the management team, the location of the property, the presence of competing properties, changes in traffic patterns and effects of general and local economic conditions with respect to rental rates and occupancy levels.
Other factors may contribute to the risk of real estate investments:
Development Issues. Certain real estate companies in which the Fund directly or indirectly invests (“portfolio companies”) may engage in the development or construction of real estate properties. Portfolio companies are exposed to a variety of risks inherent in real estate development and construction, such as the risk that there will be insufficient tenant demand to occupy newly developed properties, and the risk that prices of construction materials or construction labor may rise materially during the development.
Lack of Insurance. Certain of the portfolio companies in the Fund’s portfolio may fail to carry comprehensive liability, fire, flood, earthquake extended coverage and rental loss insurance, or insurance in place may be subject to various policy specifications, limits and deductibles. Due to the prevalence of catastrophic events, the cost of insurance may increase materially. Should any type of uninsured loss occur, the portfolio company could lose its investment in, and anticipated profits and cash flows from, a number of properties and, as a result, adversely affect the Fund’s investment performance.
15 |
Dependence on Tenants. The value of the Fund’s portfolio companies’ properties and the ability of these companies to make distributions to their shareholders depends upon the ability of the tenants at the properties to generate enough income in excess of their tenant operating expenses to make their lease payments. Changes beyond the control of our portfolio companies may adversely affect their tenants’ ability to make their lease payments and, in such event, would substantially reduce both their income from operations and ability to make distributions to our portfolio companies and, consequently, the Fund.
Financial Leverage. Companies in the real estate industry may be highly leveraged and financial covenants may affect their ability to operate effectively. The use of floating rate loans may also negatively impact returns in a rising interest rate environment.
Environmental Issues. In connection with the ownership (direct or indirect), operation, management and development of real properties that may contain hazardous or toxic substances, a portfolio company may be considered an owner, operator or responsible party of such properties and, therefore, may be potentially liable for removal or remediation costs, as well as certain other costs, including governmental fines and liabilities for injuries to persons and property. The existence of any such material environmental liability could have a material adverse effect on the results of operations and cash flow of any such portfolio company and, as a result, the amount available to make distributions on shares of the Fund could be reduced. Environmental risk from high winds, hurricanes, fires, flood and extreme heat may also materially affect a property’s value.
Credit Market Conditions. Instability in credit markets can potentially make it more difficult for borrowers to obtain financing or refinancing on attractive terms or at all. Conditions in the credit markets may expose borrowers to increased interest expenses for borrowed money and tightening underwriting standards. There is also a risk that a general lack of liquidity or other events in the credit markets may adversely affect the ability of issuers in whose securities the Fund invests to finance real estate developments and projects or refinance completed projects.
This may also adversely affect the price at which portfolio companies can sell real estate, because purchasers may not be able to obtain financing on attractive terms or at all. These developments may potentially adversely affect the broader economy, which in turn may adversely affect the real estate markets. Additionally, such developments could reduce the Fund’s investment opportunities.
Market Risk. An investment in shares is subject to investment risk, including the possible loss of the entire principal amount invested. An investment in shares represents an indirect investment in the securities owned by the Fund. The value of these securities, like other market investments, may move up or down, sometimes rapidly and unpredictably. In addition, the Fund is subject to the risk that geopolitical and other similar events will disrupt the economy on a national or global level. For instance, war, terrorism, market manipulation, government defaults, government shutdowns, political changes or diplomatic developments, public health emergencies (such as the spread of infectious diseases, pandemics and epidemics) and natural/environmental disasters can all negatively impact the securities markets.
Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. The foregoing could impair the Fund’s ability to maintain operational standards, disrupt the operations of the Fund and its service providers, adversely affect the performance, value and liquidity of the Fund’s investments, and negatively impact the Fund’s performance and your investment in the Fund. The value of your shares at any point in time may be worth less than the value of your original investment, even after taking into account any reinvestment of dividends and distributions.
Liquidity Risk. The Fund is a closed-end investment company structured as an “interval fund” and is designed for medium to long-term investors. Unlike many closed-end investment companies, the Fund’s shares are not listed on any securities exchange and are not publicly traded. There currently is no secondary market for the shares and the Advisor does not expect that a secondary market will develop. Limited liquidity is provided to shareholders only through the Fund’s quarterly repurchase offers for no less than 5% of the Fund’s shares outstanding at per-class net asset value. There is no guarantee that shareholders will be able to sell all of the shares they desire in a quarterly repurchase offer. Since inception, the Fund has made 44 repurchase offers, 37 have resulted in the repurchase of all shares, seven have resulted in the repurchase of less than all shares tendered. The Fund’s investments are also subject to liquidity risk. Liquidity risk exists when particular investments of the Fund would be difficult to purchase or sell, possibly preventing the Fund from selling such illiquid securities at an advantageous time or price, or possibly requiring the Fund to dispose of other investments at unfavorable times or prices in order to satisfy its obligations. Funds with principal investment strategies that involve securities of companies with smaller market capitalizations, derivatives or securities with substantial market and/or credit risk tend to have the greatest exposure to liquidity risk.
Allocation Risk. The ability of the Fund to achieve its investment objective depends, in part, on the ability of the Advisor or RREEF to allocate effectively the Fund’s assets among the various Institutional Investment Funds, Private REITs, Public REITs and Other Public Investment Vehicles in which the Fund invests and, with respect to each such asset class, among equities and fixed income securities. There can be no assurance that the actual allocations will be effective in achieving the Fund’s investment objectives or delivering positive returns.
Correlation Risk. The Fund seeks to produce returns that are not correlated to the broader financial markets. Although the prices of equity securities and fixed-income securities, as well as other asset classes, often rise and fall at different times so that a fall in the price of one may be offset by a rise in the price of the other, in down markets the prices of these securities and asset classes can also fall in tandem. Because the Fund allocates its investments among different asset classes, the fund is subject to correlation risk.
Credit Risk. There is a risk that debt issuers will not make payments, resulting in losses to the Fund. In addition, the credit quality of securities may be lowered if an issuer’s financial condition changes. Lower credit quality may lead to greater volatility in the price of a security and in shares of the Fund. Lower credit quality also may affect liquidity and make it difficult to sell the security. Default,
16 |
or the market’s perception that an issuer is likely to default, could reduce the value and liquidity of securities, thereby reducing the value of your investment in Fund shares. In addition, default may cause the Fund to incur expenses in seeking recovery of principal or interest on its portfolio holdings.
Distribution Policy Risk. The Fund’s distribution policy is expected to result in distributions that equal a fixed percentage of the Fund’s current net asset value per share. Shareholders receiving periodic payments from the Fund may be under the impression that they are receiving net profits. However, all or a portion of a distribution may consist of a return of capital. Return of capital is the portion of a distribution that is a return of your original investment dollars in the Fund. Shareholders should not assume that the source of a distribution from the Fund is net profit. Shareholders should note that return of capital will reduce the tax basis of their shares and potentially increase the taxable gain, if any, upon disposition of their shares.
Fixed Income Risk. When the Fund invests in fixed income securities, the value of your investment in the Fund will fluctuate with changes in interest rates. Typically, a rise in interest rates causes a decline in the value of fixed income securities. In general, the market price of debt securities with longer maturities will increase or decrease more in response to changes in interest rates than shorter-term securities. Recently, interest rates have risen sharply after maintaining historically low levels for a significant period of time. Current conditions may result in an increase in interest rate volatility, which in turn may result in a decline in the value of the fixed income investments held by the Fund. As a result, for the present, interest rate risk may be heightened. Other risk factors include credit risk (the debtor may default) and prepayment risk (the debtor may pay its obligation early, reducing the amount of interest payments). These risks could affect the value of a particular investment, possibly causing the Fund’s share price and total return to be reduced and fluctuate more than other types of investments.
Institutional Investment Fund Risk. The Fund’s investment in Institutional Investment Funds will require it to bear a pro rata share of the vehicles’ expenses, including management and performance fees. The fees the Fund pays to invest in an Institutional Investment Fund may be higher than if the manager of the Institutional Investment Fund, managed the Fund’s assets directly. The incentive fees charged by certain Institutional Investment Funds may create an incentive for its manager to make investments that are riskier and/or more speculative than those it might have made in the absence of an incentive fee. The Funds are not publicly traded and therefore may not be as liquid as other types of investments. Furthermore, Institutional Investment Funds, like the other Underlying Funds in which the Fund may invest, are subject to specific risks, depending on the nature of the vehicle and also may employ leverage such that their returns are more than one times that of their benchmark which will amplify losses suffered by the Fund when compared to unleveraged investments. For example, these Funds need not have independent boards, shareholder approval of advisory contracts may not be required, may leverage to an unlimited extent, and may engage in joint transactions with affiliates.
Issuer and Non-Diversification Risk. The value of a specific security can be more volatile than the market as a whole and can perform differently from the value of the market as a whole. As a non-diversified fund, the Fund may invest more than 5% of its total assets in the securities of one or more issuers. The Fund’s performance may be more sensitive to any single economic, business, political or regulatory occurrence than the value of shares of a diversified investment company. The value of an issuer’s securities that are held in the Fund’s portfolio may decline for a number of reasons which directly relate to the issuer, such as management performance, financial leverage and reduced demand for the respective properties and services.
Lack of Control Over Institutional Investment Funds and Other Portfolio Investments. Once the Advisor or RREEF has selected an Underlying Fund for investment by the Fund, the Advisor and RREEF will have no control over the investment decisions made by any such Underlying Fund. Although the Advisor or RREEF will evaluate regularly each Underlying Fund and its manager to determine whether their respective investment programs are consistent with the Fund’s investment objective, the Advisor and RREEF will not have any control over the investments made by any Underlying Fund. Even though the Underlying Funds are subject to certain constraints, the managers may change aspects of their investment strategies. The managers may do so at any time (for example, such change may occur immediately after providing the Advisor with the quarterly unaudited financial information for an Institutional Investment Fund). The Advisor or RREEF may reallocate the Fund’s investments among the Underlying Funds, but the Advisor’s ability to do so may be constrained by the withdrawal limitations imposed by certain Underlying Funds, which may prevent the Fund from reacting rapidly to market changes should an Underlying Fund fail to effect portfolio changes consistent with such market changes and the demands of the Advisor. Such withdrawal limitations may also restrict the Advisor’s ability to terminate investments in Underlying Funds that are poorly performing or have otherwise had adverse changes. The Advisor and RREEF will be dependent on information provided by the Underlying Fund, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s or RREEF’s ability to manage the Fund’s investment portfolio in accordance with its investment objectives.
Leveraging Risk. The use of leverage, such as borrowing money to purchase securities or otherwise invest the Fund’s assets, will cause the Fund to incur additional expenses and may significantly magnify the Fund’s losses in the event of adverse performance of the Fund’s underlying investments. In addition to any borrowing utilized by the Fund, the Underlying Funds in which the Fund invests may utilize leverage, subject to the limitations of their charters and operative documents. Leverage by Underlying Funds and/or the Fund has the effect of potentially increasing losses. In addition, interest rates (including benchmarks like SOFR and the spreads to such benchmarks charged by lenders) are highly sensitive to external factors outside a borrower’s control, including general and local economic conditions (such as inflation, recession, money supply and unemployment) and the monetary and fiscal policies of various governmental agencies such as the Federal Reserve Board. During periods of increased interest rates, borrowing costs of the Fund will likely increase and may adversely affect the Fund’s performance.
Management Risk. The net asset value of the Fund changes daily based on the performance of the securities in which it invests. The Advisor’s or a Sub-Advisor’s judgments about the attractiveness, value and potential appreciation of particular real estate segment and securities in which the Fund invests may prove to be incorrect and may not produce the desired results.
17 |
Possible Competition Between Underlying Funds and Between the Fund and the Underlying Funds. The Underlying Funds trade independently of each other and may pursue investment strategies that “compete” with each other for execution or that cause the Fund to participate in positions that offset each other (in which case the Fund would bear its pro rata share of commissions and fees without the potential for a profit). Also, the Fund’s investments in any particular Underlying Fund could increase the level of competition for the same trades that other Underlying Funds might otherwise make, including the priorities of order entry. This could make it difficult or impossible to take or liquidate a position in a particular security at a price consistent with the Advisor’s or a Sub-Advisor’s strategy.
Preferred Securities Risk. There are various risks associated with investing in preferred securities, including credit risk, interest rate risk, deferral and omission of distributions, subordination to bonds and other debt securities in a company’s capital structure, limited liquidity, limited voting rights and special redemption rights. Interest rate risk is, in general, that the price of a debt security falls when interest rates rise. Securities with longer maturities tend to be more sensitive to interest rate changes. Credit risk is the risk that an issuer of a security may not be able to make principal and interest or dividend payments on the security as they become. Holders or preferred securities may not receive dividends, or the payment can be deferred for some period of time. In bankruptcy, creditors are generally paid before the holders of preferred securities.
REIT Risk. Investments (directly or indirectly) in REITs will subject the Fund to various risks. REIT share prices may decline because of adverse developments affecting the real estate industry and real property values. In general, real estate values can be affected by a variety of factors, including supply and demand for properties, the economic health of the country or of different regions, and the strength of specific industries that rent properties. REITs often invest in highly leveraged properties. Returns from REITs, which typically are small or medium capitalization stocks, may trail returns from the overall stock market. In addition, changes in interest rates may hurt real estate values or make REIT shares less attractive than other income-producing investments. REITs are also subject to heavy cash flow dependency, defaults by borrowers and self-liquidation.
Qualification as a REIT under the Internal Revenue Code of 1986, as amended, in any particular year is a complex analysis that depends on a number of factors. There can be no assurance that an entity in which the Fund invests with the expectation that it will be taxed as a REIT will, in fact, qualify as a REIT. An entity that fails to qualify as a REIT would be subject to a corporate level tax, would not be entitled to a deduction for dividends paid to its shareholders and would not pass through to its shareholders the character of income earned by the entity. If the Fund were to invest in an entity that failed to qualify as a REIT, such failure could significantly reduce the Fund’s yield on that investment. REITs can be classified as equity REITs, mortgage REITs and hybrid REITs. Equity REITs invest primarily in real property and earn rental income from leasing those properties. They may also realize gains or losses from the sale of properties. Equity REITs will be affected by conditions in the real estate rental market and by changes in the value of the properties they own. Mortgage REITs invest primarily in mortgages and similar real estate interests and receive interest payments from the owners of the mortgaged properties. Mortgage REITs will be affected by changes in creditworthiness of borrowers and changes in interest rates. Hybrid REITs invest both in real property and in mortgages. Equity and mortgage REITs are dependent upon management skills, may not be diversified and are subject to the risks of financing projects.
Dividends paid by REITs will not generally qualify for the reduced U.S. federal income tax rates applicable to qualified dividends under the Code. See “U.S. Federal Income Tax Matters.” The Fund’s investments in REITs may include an additional risk to shareholders. Some or all of a REIT’s annual distributions to its investors may constitute a non-taxable return of capital. Any such return of capital will generally reduce the Fund’s basis in the REIT investment, but not below zero. To the extent the distributions from a particular REIT exceed the Fund’s basis in such REIT, the Fund will generally recognize gain. In part because REIT distributions often include a nontaxable return of capital, Fund distributions to shareholders may also include a nontaxable return of capital. Shareholders that receive such a distribution will also reduce their tax basis in their shares of the Fund, but not below zero. To the extent the distribution exceeds a shareholder’s basis in the Fund’s shares, such shareholder will generally recognize a capital gain. The Fund does not have any investment restrictions with respect to investments in REITs.
Repurchase Policy Risks. Quarterly repurchases by the Fund of its shares typically will be funded from available cash or sales of portfolio securities. However, payment for repurchased shares may require the Fund to liquidate portfolio holdings earlier than the Advisor otherwise would liquidate such holdings, potentially resulting in losses, and may increase the Fund’s portfolio turnover. The Advisor may take measures to attempt to avoid or minimize such potential losses and turnover, and instead of liquidating portfolio holdings, may borrow money to finance repurchases of shares. If the Fund borrows to finance repurchases, interest on any such borrowing will negatively affect shareholders who do not tender their shares in a repurchase offer by increasing the Fund’s expenses and reducing any net investment income. To the extent the Fund finances repurchase proceeds by selling investments, the Fund may hold a larger proportion of its net assets in less liquid securities. Also, the sale of securities to fund repurchases could reduce the market price of those securities, which in turn would reduce the Fund’s net asset value.
Repurchase of shares will tend to reduce the number of outstanding shares and, depending upon the Fund’s investment performance, its net assets. A reduction in the Fund’s net assets may increase the Fund’s expense ratio, to the extent that additional shares are not sold. In addition, the repurchase of shares by the Fund may be a taxable event to shareholders.
Underlying Funds Risk. Other Public Investment Vehicles such as ETFs, Index Funds, closed-end funds, and mutual funds in which the Fund may invest are subject to investment advisory fees and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in such Underlying Funds and also may be higher than other funds that invest directly in securities. Underlying Funds are subject to specific risks, depending on the nature of the fund. The Fund’s performance depends in part upon the performance of the Underlying Fund managers and selected strategies, the adherence by such Underlying Fund managers to such selected strategies, the instruments used by such Underlying Fund managers and the Advisor’s or a Sub-Advisor’s ability to select Underlying Fund managers and strategies and effectively allocate Fund assets among them. Additionally, the market value of shares of Underlying Funds that are closed-end funds typically trade at a discount relative to their net asset value. This difference in price may be due to the fact that the supply and demand in the market for fund shares at any point in time is not always identical to the supply and demand in the market for the underlying basket of securities.
18 |
ETF shares may trade at a discount or a premium in market price if there is a limited market in such shares. Transactions in shares of closed-end funds and ETFs are also subject to brokerage and other trading costs, which could result in greater expenses to the Fund. Investments in pooled investment vehicles also may be illiquid, making it difficult for the Advisor to redeem the interest of the Fund in such vehicles in a reasonable amount of time.
Valuation of Institutional Investment Funds. While the valuations of the Fund’s investments in publicly-traded securities are more readily ascertainable, the Fund’s ownership interests in Institutional Investment Funds are not publicly traded and the Fund will depend on the institutional asset manager to a Private Investment Fund to provide a valuation of the Fund’s investment. Moreover, the valuation of the Fund’s investment in an Institutional Investment Fund, as provided by an institutional asset manager as of a specific date, may vary from the fair value of the investment that may be obtained if such investment were sold to a third party. For information about the value of the Fund’s investment in Institutional Investment Funds, the Advisor will be dependent on information provided by the Institutional Investment Funds, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s ability to accurately value the Fund’s shares.
MANAGEMENT OF THE FUND
Trustees and Officers
The Board is responsible for the overall management of the Fund, including supervision of the duties performed by the Advisor. The Board is comprised of five trustees. The Trustees are responsible for the Fund’s overall management, including adopting the investment and other policies of the Fund, electing and replacing officers and selecting and supervising the Fund’s investment advisor. The name and business address of the Trustees and officers of the Fund and their principal occupations and other affiliations during the past five years, as well as a description of committees of the Board, are set forth under “Management” in the Statement of Additional Information.
Investment Advisor
Bluerock Fund Advisors, LLC, located at 919 Third Avenue, 40th Floor, New York, NY 10022, serves as the Fund’s investment advisor. The Advisor is registered with the SEC as an investment advisor under the Advisers Act. The Advisor is a Delaware limited liability company formed on May 11, 2012.
Under the general supervision of the Fund’s Board, and pursuant to the terms of an Investment Management Agreement with the Fund, the Advisor will carry out the investment and reinvestment of the net assets of the Fund, will furnish continuously an investment program with respect to the Fund, and determine which securities should be purchased, sold or exchanged. In addition, the Advisor will supervise and provide oversight of the Fund’s service providers. The Advisor will furnish to the Fund office facilities, equipment and personnel for servicing the management of the Fund. The Advisor will compensate all Advisor personnel who provide services to the Fund. In return for these services, facilities and payments, the Fund has agreed to pay the Advisor, as compensation under the Investment Management Agreement, a monthly management fee computed at the annual rate of 1.50% of the daily net assets of the Fund. The Advisor may employ research services and service providers to assist in the Advisor’s market analysis and investment selection.
The Advisor and the Fund have entered into an expense limitation and reimbursement agreement (the “Expense Limitation Agreement”) under which the Advisor has agreed contractually to waive its fees and to pay or absorb the ordinary operating expenses (excluding any taxes, interest, brokerage commissions, acquired fund fees and expenses, and extraordinary expenses, such as litigation or reorganization costs, but including organizational costs and offering costs), to the extent that such expenses exceed 1.70% per annum of the Fund’s average daily net assets attributable to Class I shares (the “Expense Limitation”). In consideration of the Advisor’s agreement to limit the Fund’s expenses, the Fund has agreed to repay the Advisor in the amount of any fees the Advisor previously waived or Fund expenses reimbursed, subject to the limitations that: (1) the reimbursement will be made if payable not more than three years from the date incurred; (2) the reimbursement may not be made if it would cause the Expense Limitation then in effect or in effect at the time of the waiver to be exceeded; and (3) the reimbursement is approved by the Board. The Expense Limitation Agreement will remain in effect, at least until January 31, 2026, unless and until the Board approves its modification or termination. This agreement may be terminated only by the Board on 60 days written notice to the Advisor. After January 31, 2026, the Expense Limitation Agreement may be renewed at the Advisor’s and Board’s discretion.
A discussion regarding the basis for the Board’s approval of each of the Fund’s Investment Management Agreement with the Advisor and Sub-Advisory Agreements with Mercer and RREEF is available annually in the Fund’s March 31 semi-annual report to shareholders.
Affiliated Brokerage
Bluerock Capital Markets, LLC (“BCM”), a registered broker-dealer and an affiliate of the Advisor, may receive commissions on the sale of certain classes of the Fund’s shares, but it does not receive compensation from the Fund in connection with the sale of Class I shares.
Advisor’s Investment Committee
The Advisor has established an Investment Committee comprised of five persons (the “Committee”) responsible for: setting overall investment policies and strategies of the Advisor; approval of Institutional Investment Funds being considered for investment by the Fund; establishing allocation targets for the investment portfolio of the Fund among the Institutional Investment Funds, Other Public Investment Vehicles and other entities in which the Fund intends to invest; and generally overseeing the activities of the Advisor’s Portfolio Managers (see below).
19 |
The members of the Committee, and their professional background and experience, are as follows:
R. Ramin Kamfar — Mr. Kamfar has served as a member of the Investment Committee and as Chairman of the Advisor since the inception of the Advisor in 2012. In addition, Mr. Kamfar is the founder of and serves as the Chairman and Chief Executive Officer of Bluerock Real Estate, LLC (“BRRE”), since its founding in October 2002. Mr. Kamfar served as Chairman and CEO of Bluerock Residential Growth REIT, a publicly traded REIT listed on the NYSE American (“BRG”), since its founding in 2009 until its sale in 2022. Mr. Kamfar currently serves as Chairman and CEO of Bluerock Homes Trust, a publicly traded REIT listed on the NYSE American (“BHM”) since its spin-off from BRG in 2022, as well as Chairman of Bluerock Asset Management, LLC since 2018. Mr. Kamfar started his career as an investment banker at Lehman Brothers Inc. in 1988, and has 30 years of experience in various aspects of real estate, mergers and acquisitions, private equity investing, investment banking, and public and private financings. Mr. Kamfar received an M.B.A. degree with distinction in Finance in 1988 from The Wharton School of the University of Pennsylvania, and a B.S. degree with distinction in Finance in 1985 from the University of Maryland, College Park.
James G. Babb, III — Mr. Babb has served as a member of the Investment Committee since the inception of the Advisor in 2012. In addition, Mr. Babb has served in a variety of senior capacities, including his current role as Chief Strategy Officer, at BRRE, which he joined in 2007. Mr. Babb served as Chief Investment Officer of BRG from its founding in 2009 to 2020, as Chief Strategy Officer from 2020 until its sale in 2022 and as a Director of BRG from 2009 to 2014. Mr. Babb currently serves as Chief Strategy Officer of BHM. Mr. Babb was a founding principal of Starwood Capital Group (“Starwood”), a leading institutional real estate investment manager, where he helped lead the residential and office acquisitions initiatives from 1992 to 2003. During Mr. Babb’s tenure Starwood raised and invested funds on behalf of institutional investors through seven private real estate funds, and which in the aggregate ultimately invested approximately $8 billion in approximately 250 separate transactions. Mr. Babb also led Starwood’s efforts to expand its platform to invest in England and France. Mr. Babb received a B.A. degree in Economics in 1987 from the University of North Carolina, Chapel Hill.
Jordan B. Ruddy — Mr. Ruddy currently serves as Co-CIO of the Advisor and Portfolio Manager of the Fund. Mr. Ruddy has served as a member of the Investment Committee and as President of the Advisor since the inception of the Advisor in 2012. Mr. Ruddy also serves as president of Bluerock Asset Management, LLC. Mr. Ruddy served in several senior capacities of BRG from its founding in 2009 until its sale in 2022 and currently serves as President of BHM. Mr. Ruddy brings approximately 30 years of institutional real estate investment experience working with some of leading public and private firms in the industry. Prior to joining Bluerock, Mr. Ruddy served as a real estate investment banker at Banc of America Securities LLC, and at Smith Barney Inc. and at JP Morgan Chase (previously the Chase Manhattan Bank), and as Vice President of Amerimar Enterprises, a real estate company specializing in value-added investments nationwide. Mr. Ruddy received an M.B.A. degree in Finance and Real Estate in 1995 from The Wharton School of the University of Pennsylvania, and a B.S. degree with high honors in Economics in 1986 from the London School of Economics.
Ryan MacDonald — Mr. MacDonald has served as a member of the Investment Committee of the Advisor since January 2018. Mr. MacDonald currently serves as Chief Investment Officer for BHM and of BRRE and certain of its affiliates. Mr. MacDonald served in a variety of senior capacities for BRG, including Chief Investment Officer from 2020 until its sale. Since joining Bluerock in 2008, Mr. MacDonald is responsible for sourcing, underwriting, structuring, financing and closing of all of Bluerock’s real estate investments and dispositions. To date with Bluerock, Mr. MacDonald has been involved with real estate transactions with an aggregate value of approximately $11 billion. Prior to joining Bluerock, Mr. MacDonald was an Investment Analyst for PNC Realty Investors. Mr. MacDonald received a B.A. in Economics from the University of Maryland, College Park.
Adam Lotterman — Mr. Lotterman is co-founder of the Advisor and has been a key member of the Fund’s investment team since its inception in 2012. Mr. Lotterman currently serves as the Fund’s Senior Portfolio Manager, as well as the Advisor’s Co-Chief Investment Officer and Lead Economist. Prior to joining Bluerock, Mr. Lotterman was Vice President of Forman Capital, a private commercial real estate lender from 2011 to 2012. Mr. Lotterman was also an Adjunct Professor at Nova Southeastern University from 2010 to 2012, where he taught a master’s level course in Real Estate Market Analysis. Prior to that, Mr. Lotterman worked as a Senior Valuation Analyst at Bayview Asset Management (former hedge fund affiliate of The Blackstone Group) from 2010 to 2011, and from 2005 to 2010 Mr. Lotterman was the Senior Analyst for Goodkin Consulting, the former real estate consulting arm of PricewaterhouseCoopers. Mr. Lotterman received an M.S. in International Real Estate in 2006 from Florida International University, where he graduated first in class, and a B.S. Degree in microbiology with a minor in chemistry in 1997 from the University of Florida.
Advisor Portfolio Managers
Subject to the Committee’s oversight, Jordan B. Ruddy, a member of the Committee, and Adam Lotterman serve as the Fund’s Portfolio Managers and oversee the day-to-day investment operations of the Fund. Each has served as a Portfolio Manager to the Fund since October 2013.
Jordan B. Ruddy — Mr. Ruddy’s biographical information is presented above.
Adam Lotterman — Mr. Lotterman’s biographical information is presented above.
Tim Thran, CFA — Mr. Thran currently serves as Associate Portfolio Manager and Assistant Treasurer of the Fund. Mr. Thran joined Bluerock in 2017 and currently serves as a Managing Director of the Advisor. Mr. Thran works directly with the Fund’s Senior Portfolio Managers and is responsible for overseeing day-to-day investment operations and execution of the Fund’s strategy, including portfolio valuation, investment analysis, liquidity management and performance evaluation. Previously, Mr. Thran served at JPMorgan Asset Management from 2014 to 2016, directing daily oversight and controls on over $200 billion in retail mutual fund assets. From 2008 to 2014, Mr. Thran held multiple management roles at State Street Corporation, with a focus on accounting and compliance on the
20 |
company’s premier ETFs and mutual fund clients. Mr. Thran received an M.B.A. degree with a concentration in Investments from the D’Amore-McKim School of Business at Northeastern University and B.A. degrees in both Mathematics and Economics from the College of the Holy Cross. Mr. Thran is a CFA charterholder, CFA Institute.
Investment Sub-Advisor — Mercer
The Advisor has engaged Mercer Investments LLC, a registered adviser under the Advisers Act, to act as an investment sub-advisor. For more than 50 years, Mercer and its affiliates have provided global leadership in investment consulting and multi-manager fiduciary management, and is a leading advisor to sovereign wealth funds, pension plans, banks, family offices, insurance companies, endowments and foundations. Mercer, together with its affiliated investment businesses, have over 5,600 delegated and advisory clients globally with over $547 billion in assets under management as of September 30, 2024 and over $17.5 trillion in assets under advisement as of June 30, 2024. Asset under management reported here includes include aggregated assets for which Mercer Investments LLC (Mercer Investments) and their global affiliates providing discretionary investment management services as of the dates indicated. Assets under management is calculated differently from regulatory assets under management, which is reported in Form ADV and filed with the Securities and Exchange Commission.
Mercer is an affiliate of Mercer (US), LLC, a human resource and financial consulting company. Mercer (US), LLC has approximately 25,000+ employees as of September 30, 2024 based in more than 40 countries and serves over 36,000 clients worldwide and is a wholly owned subsidiary of Marsh & McLennan Companies (NYSE: MMC).
Investment Sub-Advisor — RREEF
The Advisor has engaged RREEF America L.L.C., a registered advisor under the Advisers Act, to provide investment management for a portion of the Fund’s portfolio, generally less than 20%. In addition, RREEF provides the Advisor with research and information that the Advisor uses to make investment decisions with respect to non-publicly traded real estate related debt securities. RREEF together with its affiliates in Europe and Asia, comprise the global real estate investment business of DWS, an indirect majority owned subsidiary of Deutsche Bank A.G. DWS’s real estate investment business, is one of the largest real estate investment managers globally with more than 330 professionals and staff located in 23 cities worldwide and approximately $78.9 billion in real estate and real estate-related assets under management as of September 30, 2024.
RREEF Portfolio Managers
Subject to the Advisor’s oversight, David W. Zonavetch, Bob Thomas, and John W. Vojticek serve as the Fund’s RREEF Portfolio Managers and oversee a portion of investment portfolio of the Fund. Mr. Zonavetch and Mr. Vojticek have served as a Portfolio Managers to the Fund since May 2016. Mr. Thomas has served as a Portfolio Manager to the Fund since January 2018.
David W. Zonavetch — Mr. Zonavetch has served as a Director and Co-Lead Portfolio Manager for RREEF since September 2013 and as Co-Lead Portfolio Manager - Real Estate Securities since February 2012. Previously, he served as Vice President and Portfolio Manager from February 2007 to February 2012. From February 2007 to February 2012, Mr. Zonavetch was a Vice President and Securities Analyst at RREEF Real Estate. He has nine years of experience in accounting and finance. From 1998 to 2001, Mr. Zonavetch served as a Senior Accountant in Corporate Finance of RREEF Real Estate, and from 2001 to 2003, he served as Securities Accounting Coordinator with RREEF Real Estate’s Securities Group, covering the office and self- storage sectors. From 1995 until joining RREEF Real Estate in 1998, Mr. Zonavetch worked as an analyst for Cendant Mobility Services Corp., a corporate employee relocation company. Mr. Zonavetch holds a B.S. in Finance from the University of Illinois at Urbana-Champaign and is a certified public accountant.
Bob Thomas — Mr. Thomas has served as a Managing Director and Co-Head of Americas Real Estate Securities, Alternatives for RREEF since 2017. He has 15 years of industry experience serving as lead portfolio manager of North America for global listed property funds at Henderson Global Investors from 2015 to 2016, he was co-lead portfolio manager of North America for global listed property funds at AMP Capital from 2012 to 2015, and as an analyst at Nuveen Asset Management from 2011 to 2012, at BNP Paribas Asset Management from 2005 to 2011 and at Security Capital Research & Management from 20014 to 2005. Mr. Thomas started his career as an investment banking analyst in the Real Estate group at KeyBanc Capital Markets in 2002. Mr. Thomas holds a B.A. in Economics from Duke University and an MBA in Finance, Management & Strategy from Kellogg School of Management, Northwestern University.
John W. Vojticek — Mr. Vojticek has served as a Managing Director and Chief Investment Officer of Real Estate & Infrastructure Securities and Global Portfolio Manager for RREEF since July 2011 and was Co-Head of Americas Real Estate Securities from 2006 to July 2011. Mr. Vojticek was responsible for launching the firm’s first listed infrastructure securities strategy in June 2008 and served as Head of the Listed Infrastructure Securities business from June 2008 until his appointment as Chief Information Officer in July 2011. Mr. Vojticek is an associate member of the National Association of Real Estate Investment Trusts. Mr. Vojticek holds a B.S. in Business Administration from the University of Southern California.
The Statement of Additional Information provides additional information about each Portfolio Manager’s compensation, other accounts managed and ownership of Fund shares.
21 |
Administrator, Accounting Agent and Transfer Agent
ALPS Fund Services, Inc. (“ALPS” or the “Administrator”), located at 1290 Broadway, Suite 1000, Denver, CO 80203, serves as Administrator and Accounting Agent for the Fund. For the services rendered to the Fund by ALPS, the Fund pays ALPS the greater of an annual minimum fee or an asset-based fee, which scales downward based upon net assets for fund administration and fund accounting services. SS&C GIDS, located at PO Box 219445, Kansas City, MO 64121-9445, serves as the Fund’s Transfer Agent and for such services the Fund pays the Transfer Agent separate fees.
Custodian
UMB Bank, N.A (“UMB Bank” or the “Custodian”), with principal offices at 1010 Grand Boulevard, Kansas City, Missouri 64106, serves as custodian for the securities and cash of the Fund’s portfolio. Under a Custody Agreement, UMB Bank holds the Fund’s assets in safekeeping and keeps all necessary records and documents relating to its duties.
Fund Expenses
The Advisor is obligated to pay expenses associated with providing the services stated in the Investment Management Agreement, including compensation of and office space for its officers and employees connected with investment and economic research, trading and investment management and administration of the Fund. The Advisor is obligated to pay the fees of any Trustee of the Fund who is affiliated with it.
The Administrator is obligated to pay expenses associated with providing the services contemplated by a Fund Services Administration Agreement (administration and accounting services), including compensation of and office space for its officers and employees employed in providing these services to the Fund.
The Fund pays all other expenses incurred in the operation of the Fund including, among other things, (i) expenses for legal and independent accountants’ services, (ii) costs of printing proxies, share certificates, if any, and reports to shareholders, (iii) charges of the custodian and transfer agent in connection with the Fund’s dividend reinvestment policy, (iv) fees and expenses of independent Trustees, (v) printing costs, (vi) membership fees in trade association, (vii) fidelity bond coverage for the Fund’s officers and Trustees, (viii) errors and omissions insurance for the Fund’s officers and Trustees, (ix) brokerage costs, (x) taxes, (xi) costs associated with the Fund’s quarterly repurchase offers, (xii) servicing fees and (xiii) other extraordinary or non-recurring expenses and other expenses properly payable by the Fund. The expenses incident to the offering and issuance of shares to be issued by the Fund will be recorded as a reduction of capital of the Fund attributable to the shares.
The Board has authorized the Advisor and RREEF to select brokers or dealers (including affiliates) to arrange for the purchase and sale of Fund securities, including principal transactions. Any commission, fee or other remuneration paid to an affiliated broker or dealer is paid in compliance with the Fund’s procedures adopted in accordance with Rule 17e-1 under the 1940 Act.
Control Persons and Principal Shareholders
A principal shareholder is any person who owns (either of record or beneficially) 5% or more of the outstanding shares of a fund. A control person is one who owns, either directly or indirectly, more than 25% of the voting securities of a company or acknowledges the existence of control. The Fund’s principal shareholders as of January 3, 2025 are listed in the chart below. Each shareholder listed below is a record shareholder, holding shares for the benefit of others.
Class A Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
6,523,152.52 |
26.75% |
EQUITABLE ADVISORS LLC LPL FINANCIAL SERVICES FBO LPL BIN 66920980 1055 LPL WAY FORT MILL SC, 29715-8101 |
4,721,545.33 |
19.36% |
CHARLES SCHWAB & CO INC SPECIAL CUSTODY A/C FBO CUSTOMERS 211 MAIN STREET SAN FRANCISCO, CA 94105-1905 |
3,107,371.03 |
12.74% |
NATIONAL FINANCIAL SERVICES LLC BIN #B9F699887 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
3,082,068.56 |
12.64% |
22 |
Class C Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
5,923,943.31 |
38.47% |
LPL FINANCIAL LLC FBO CUSTOMER ACCOUNTS 4707 EXECUTIVE DR. SAN DIEGO CA, 92121-3091 |
2,299,101.93 |
14.93% |
CHARLES SCHWAB AND CO INC SPECIAL CUSTODY A/C FBO CUSTOMERS 211 MAIN STREET SAN FRANCISCO, CA 94105-1905 |
2,076,778.96 |
13.49% |
NATIONAL FINANCIAL SERVICES LLC 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
895,604.35 |
5.82% |
Class I Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
CHARLES SCHWAB & CO INC SPECIAL CUSTODY A/C FBO CUSTOMERS 211 MAIN STREET SAN FRANCISCO, CA 92121 |
42,258,021.47 |
36.65% |
NATIONAL FINANCIAL SERVICES LLC 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
21,116,400.89 |
18.31% |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
21,101,606.20 |
18.30% |
LPL FINANCIAL SERVICES FBO LPL BIN 66920980 1055 LPL WAY FORT MILL SC 29715-8101 |
14,367,372.68 |
12.46% |
ROBERT W BAIRD & CO. INC. A/C 47100819 777 EAST WISCONSIN AVENUE MILWAUKEE, WI 53202 |
6,642,155.04 |
5.76% |
Class L Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
1,652,278.67 |
53.11% |
NATIONAL FINANCIAL SERVICES LLC 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
535,807.56 |
17.22% |
LPL FINANCIAL LLC FBO CUSTOMER ACCOUNTS 4707 EXECUTIVE DR. SAN DIEGO CA, 92121-3091 |
247,909.67 |
7.97% |
Class M Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
MORGAN STANLEY SMITH BARNEY LLC 1 NEW YORK PLAZA NEW YORK, NY 10004 |
4,313,743.14 |
98.46% |
As of January 3, 2025, the Trustees and officers, as a group, owned less than 1.00% of the shares of the Fund.
23 |
DETERMINATION OF NET ASSET VALUE
The net asset value of shares of the Fund is determined daily, as of the close of regular trading on the NYSE (normally, 4:00 p.m., Eastern Time). The NYSE is closed on weekends and New Year’s Day, Martin Luther King, Jr. Day, Presidents’ Day, Good Friday, Memorial Day, Juneteenth Day, Independence Day, Labor Day, Thanksgiving Day, and Christmas Day. Each Class I share will be offered at net asset value. During the continuous offering, the price of the shares will increase or decrease on a daily basis according to the net asset value of the shares.
In computing net asset value, portfolio securities of the Fund are valued at their current market values determined on the basis of market quotations as of the last quoted sales price on the security’s primary exchange. If market quotations are not readily available, as in the case of Institutional Investment Funds investing in private real estate, securities are valued at fair value as determined in good faith by the Advisor, in its capacity as the Board’s valuation designee, pursuant to Rule 2a-5 under the 1940 Act or with respect to securities traded or dealt in upon one or more securities exchanges (whether domestic or foreign), as described below. As a general matter, fair value represents the amount that the Fund could reasonably expect to receive if the Fund’s investment in the security were sold at the time of valuation, based on information reasonably available at the time the valuation is made and that the Advisor believes to be reliable. As the valuation designee, the Advisor acts under the Board’s oversight. The Board and the Advisor may enlist third party service providers, such as pricing services, broker-dealers or valuation firms, on an as-needed basis to assist in determining a security-specific fair value. The Board reviews the execution of this process and the resultant fair value prices at least quarterly to assure the process produces reliable results.
Fair valuation involves subjective judgments, and it is possible that the fair value determined for a security may differ materially from the value that could be realized upon the sale of the security. Like all investments that are valued at fair value, the Institutional Investment Funds will be difficult to value. There is no single standard for determining fair value of a security. Rather, in determining the fair value of a security for which there are no readily available market quotations, the Advisor, using information including that provided by a Sub-Advisor, may consider several factors, including fundamental analytical data relating to the investment in the security, the nature and duration of any restriction on the disposition of the security, the cost of the security at the date of purchase, the liquidity of the market for the security and the recommendation of the Fund’s Portfolio Managers. The Advisor may also consider periodic financial statements (audited and unaudited) or other information provided by the issuer. The Advisor will attempt to obtain current information to value all fair valued securities, but it is anticipated that portfolio holdings of the Institutional Investment Funds could be available on no more than a quarterly basis. Institutional Investment Funds that invest primarily in publicly traded securities are more easily valued.
The Advisor, with the assistance of other parties, will provide the Board with periodic reports, no less frequently than quarterly, that discuss the functioning of the valuation process, if applicable to that period, and that identify issues and valuations problems that have arisen, if any. To the extent deemed necessary by the Advisor, the fair value team or committee of the Board will review any securities valued by the Advisor in accordance with the Fund’s valuation policies.
Non-dollar-denominated securities, if any, are valued as of the close of the NYSE at the closing price of such securities in their principal trading market, but may be valued at fair value if subsequent events occurring before the computation of net asset value materially have affected the value of the securities. Trading may take place in foreign issues held by the Fund, if any, at times when the Fund is not open for business. As a result, the Fund’s net asset value may change at times when it is not possible to purchase or sell shares of the Fund. The Fund may use a third-party pricing service to assist it in determining the market value of securities in the Fund’s portfolio. The Fund’s net asset value per share is calculated, on a class-specific basis, by dividing the value of the Fund’s total assets (the value of the securities the Fund holds plus cash or other assets, including interest accrued but not yet received), less accrued expenses of the Fund, less the Fund’s other liabilities by the total number of shares outstanding.
For purposes of determining the net asset value of the Fund, readily marketable portfolio securities listed on the NYSE are valued, except as indicated below, at the last sale price reflected on the consolidated tape at the close of the NYSE on the business day as of which such value is being determined. If there has been no sale on such day, the securities are valued at the mean of the closing bid and asked prices on such day. If no bid or asked prices are quoted on such day or if market prices may be unreliable because of events occurring after the close of trading, then the security is valued by such method as the Advisor, as valuation designee, shall determine in good faith to reflect its fair market value. Readily marketable securities not listed on the NYSE but listed on other domestic or foreign securities exchanges are valued in a like manner. Portfolio securities traded on more than one securities exchange are valued at the last sale price on the business day as of which such value is being determined as reflected on the consolidated tape at the close of the exchange representing the principal market for such securities. Securities trading on the NASDAQ are valued at the NASDAQ official closing price.
Readily marketable securities traded in the over-the-counter market, including listed securities whose primary market is believed by the Advisor to be over-the-counter, are valued at the mean of the current bid and asked prices as reported by the NASDAQ or, in the case of securities not reported by the NASDAQ or a comparable source, as the Advisor deems appropriate to reflect their fair market value. Where securities are traded on more than one exchange and also over-the-counter, the securities will generally be valued using the quotations the Advisor believes reflect most closely the value of such securities.
CONFLICTS OF INTEREST
As a general matter, certain conflicts of interest may arise in connection with a portfolio manager’s management of a fund’s investments, on the one hand, and the investments of other accounts for which the portfolio manager is responsible, on the other. For example, it is possible that the various accounts managed could have different investment strategies that, at times, might conflict with one another to the possible detriment of the Fund. Alternatively, to the extent that the same investment opportunities might be desirable for more than one account, possible conflicts could arise in determining how to allocate them. Other potential conflicts might include conflicts created by specific portfolio manager compensation arrangements, and conflicts relating to selection of brokers or
24 |
dealers to execute Fund portfolio trades and/or specific uses of commissions from Fund portfolio trades (for example, research, or “soft dollars”, if any). The Advisor, and Sub-Advisor, to the extent applicable, have adopted policies and procedures and have structured their Portfolio Managers’ compensation in a manner reasonably designed to safeguard the Fund from being negatively affected as a result of any such potential conflicts.
QUARTERLY REPURCHASES OF SHARES
Once each quarter, the Fund will offer to repurchase, at per-class net asset value no less than 5% of the outstanding shares of the Fund, unless such offer is suspended or postponed in accordance with regulatory requirements (as discussed below). The offer to purchase shares is a fundamental policy that may not be changed without the vote of the holders of a majority of the Fund’s outstanding voting securities (as defined in the 1940 Act). Shareholders will be notified in writing of each quarterly repurchase offer and the date the repurchase offer ends (the “Repurchase Request Deadline”). Shares will be repurchased at the per-class NAV per share determined as of the close of regular trading on the NYSE no later than the 14th day after the Repurchase Request Deadline, or the next business day if the 14th day is not a business day (each a “Repurchase Pricing Date”).
Shareholders will be notified in writing about each quarterly repurchase offer, how they may request that the Fund repurchase their shares and the “Repurchase Request Deadline,” which is the date the repurchase offer ends. Shares tendered for repurchase by shareholders prior to any Repurchase Request Deadline will be repurchased subject to the aggregate repurchase amounts established for that Repurchase Request Deadline. The time between the notification to shareholders and the Repurchase Request Deadline may vary from no more than 42 days to no less than 21 days. Payment pursuant to the repurchase will be made by checks to the shareholder’s address of record, or credited directly to a predetermined bank account on the Purchase Payment Date, which will be no more than seven days after the Repurchase Pricing Date. The Board may establish other policies for repurchases of shares that are consistent with the 1940 Act, regulations thereunder and other pertinent laws. Shareholders have no right to redeem Fund shares outside the regular quarterly repurchases, regardless of shareholder circumstances, and the Fund may not honor any such requests.
Determination of Repurchase Offer Amount
The Board, or a committee thereof, in its sole discretion, will determine the number of shares for each share class that the Fund will offer to repurchase (the “Repurchase Offer Amount”) for a given Repurchase Request Deadline. The Repurchase Offer Amount, however, will be no less than 5% and no more than 25% of the total number of shares outstanding on the Repurchase Request Deadline.
If shareholders tender for repurchase more than the Repurchase Offer Amount for a given repurchase offer, the Fund will repurchase the shares on a pro rata basis. However, the Fund may accept all shares tendered for repurchase by shareholders who own less than one hundred shares and who tender all of their shares, before prorating other amounts tendered.
Notice to Shareholders
No less than 21 days and more than 42 days before each Repurchase Request Deadline, the Fund shall send to each shareholder of record and to each beneficial owner of the shares that are the subject of the repurchase offer a notification (“Shareholder Notification”). The Shareholder Notification will contain information shareholders should consider in deciding whether to tender their shares for repurchase. The notice also will include detailed instructions on how to tender shares for repurchase, state the Repurchase Offer Amount and identify the dates of the Repurchase Request Deadline, the scheduled Repurchase Pricing Date, and the date the repurchase proceeds are scheduled for payment (the “Repurchase Payment Deadline”). The notice also will set forth the NAV that has been computed no more than seven days before the date of notification, and how shareholders may ascertain the NAV after the notification date.
Repurchase Price
The repurchase price of the shares will be the NAV of the share class as of the close of regular trading on the NYSE on the Repurchase Pricing Date. The notice of the repurchase offer also will provide information concerning the NAV, such as the NAV as of a recent date or a sampling of recent NAVs, and a toll-free number for information regarding the repurchase offer. You may call 1-844-819-8287 to learn the NAV.
Early Withdrawal Charge
Class I shares are not subject to an early withdrawal charge.
Repurchase Amounts and Payment of Proceeds
Shares tendered for repurchase by shareholders prior to any Repurchase Request Deadline will be repurchased subject to the aggregate Repurchase Offer Amount established for that Repurchase Request Deadline. Payment pursuant to the repurchase offer will be made by check to the shareholder’s address of record, or credited directly to a predetermined bank account on the Purchase Payment Date, which will be no more than seven days after the Repurchase Pricing Date. The Board may establish other policies for repurchases of shares that are consistent with the 1940 Act, regulations thereunder and other pertinent laws.
If shareholders tender for repurchase more than the Repurchase Offer Amount for a given repurchase offer, the Fund will repurchase the shares on a pro rata basis. Notwithstanding the foregoing, the Fund may in its sole discretion and for administrative convenience accept all shares tendered for repurchase by shareholders who own less than one hundred shares and who tender all of their shares, before prorating other amounts tendered.
25 |
Suspension or Postponement of Repurchase Offer
The Fund may suspend or postpone a repurchase offer only: (a) if making or effecting the repurchase offer would cause the Fund to lose its status as a regulated investment company under the Code; (b) for any period during which the NYSE or any market on which the securities owned by the Fund are principally traded is closed, other than customary weekend and holiday closings, or during which trading in such market is restricted; (c) for any period during which an emergency exists as a result of which disposal by the Fund of securities owned by it is not reasonably practicable, or during which it is not reasonably practicable for the Fund fairly to determine the value of its net assets; or (d) for such other periods as the Commission may by order permit for the protection of shareholders of the Fund.
Liquidity Requirements
The Fund must maintain liquid assets equal to the Repurchase Offer Amount from the time that the notice is sent to shareholders until the Repurchase Pricing Date. The Fund will ensure that either a percentage of its net assets equal to at least 100% of the Repurchase Offer Amount consists of cash or assets that can be sold or disposed of in the ordinary course of business at approximately the price at which the Fund has valued the investment within the time period between the Repurchase Request Deadline and the Repurchase Payment Deadline, and/or a line of credit is available to satisfy the Repurchase Offer Amount. The Board has adopted procedures that are reasonably designed to ensure that the Fund’s assets are sufficiently liquid so that the Fund can comply with the repurchase offer and the liquidity requirements described in the previous paragraphs. If, at any time, the Fund falls out of compliance with these liquidity requirements, the Board will take whatever action it deems appropriate to ensure compliance.
Consequences of Repurchase Offers
Repurchase offers will typically be funded from available cash or sales of portfolio securities. Payment for repurchased shares, however, may require the Fund to liquidate portfolio holdings earlier than the Advisor otherwise would, thus increasing the Fund’s portfolio turnover and potentially causing the Fund to realize losses. The Advisor intends to take measures to attempt to avoid or minimize such potential losses and turnover, and instead of liquidating portfolio holdings, may borrow money to finance repurchases of shares. If the Fund borrows to finance repurchases, interest on that borrowing will negatively affect shareholders who do not tender their shares in a repurchase offer by increasing the Fund’s expenses and reducing any net investment income. To the extent the Fund finances repurchase amounts by selling Fund investments, the Fund may hold a larger proportion of its assets in less liquid securities. The sale of portfolio securities to fund repurchases also could reduce the market price of those underlying securities, which in turn would reduce the Fund’s net asset value.
Repurchase of the Fund’s shares will tend to reduce the number of outstanding shares and, depending upon the Fund’s investment performance, its net assets. A reduction in the Fund’s net assets would increase the Fund’s expense ratio, to the extent that additional shares are not sold and expenses otherwise remain the same (or increase). In addition, the repurchase of shares by the Fund will be a taxable event to shareholders.
The Fund is intended as a medium to long-term investment. The Fund’s quarterly repurchase offers are a shareholder’s only means of liquidity with respect to his or her shares. Shareholders have no right to redeem Fund shares outside the regular quarterly repurchases, regardless of shareholder circumstances, and the Fund may not honor any such requests. The shares are not traded on a national securities exchange and no secondary market exists for the shares, nor does the Fund expect a secondary market for its shares to exist in the future.
DISTRIBUTION POLICY
Quarterly Distribution Policy
The Fund’s distribution policy is to make quarterly distributions to shareholders. The level of quarterly distributions (including any return of capital) is not fixed, but is expected to represent an annual rate of approximately 5.25% of the Fund’s current net asset value per share. However, this distribution policy is subject to change. Shareholders receiving periodic payments from the Fund may be under the impression that they are receiving net profits. However, all or a portion of a distribution may consist of a return of capital. Shareholders should not assume that the source of a distribution from the Fund is net profit. A return of capital is not taxable to a shareholder unless it exceeds a shareholder’s tax basis in the shares. Returns of capital reduce a shareholder’s tax cost (or “tax basis”). Once a shareholder’s tax basis is reduced to zero, any further return of capital would be taxable. Shareholders should note that return of capital will reduce the tax basis of their shares and potentially increase the taxable gain, if any, upon disposition of their shares. As required under the Investment Company Act of 1940, the Fund will provide a notice to shareholders at the time of distribution when such distribution does not consist solely of net income. Additionally, each distribution payment will be accompanied by a written statement which discloses the source or sources of each distribution. The IRS requires you to report these amounts, excluding returns of capital, on your income tax return for the year declared. The Fund will provide disclosures, with each distribution, that estimate the percentages of the current and year-to-date distributions that represent (1) net investment income, (2) capital gains and (3) return of capital. At the end of the year, the Fund may be required under applicable law to re-characterize distributions made previously during that year among (1) ordinary income, (2) capital gains and (3) return of capital for tax purposes. An additional distribution may be made in December, and other additional distributions may be made with respect to a particular fiscal year in order to comply with applicable law. Distributions declared in December, if paid to shareholders by the end of January, are treated for federal income tax purposes as if received in December.
The distribution rate may be modified by the Board from time to time. If, for any quarterly distribution, investment company taxable income (which term includes net short-term capital gain), if any, and net tax-exempt income, if any, is less than the amount of the distribution, then the difference will generally be a tax-free return of capital distributed from the Fund’s assets. The Fund’s final distribution for each calendar year will include any remaining investment company taxable income and net tax-exempt income
26 |
undistributed during the year, as well as all net capital gain realized during the year. If the total distributions made in any calendar year exceed investment company taxable income, net tax-exempt income and net capital gain, such excess distributed amount would be treated as ordinary dividend income to the extent of the Fund’s current and accumulated earnings and profits. Distributions in excess of the earnings and profits would first be a tax-free return of capital to the extent of the adjusted tax basis in the shares. After such adjusted tax basis is reduced to zero, the distribution would constitute capital gain (assuming the shares are held as capital assets). This distribution policy may, under certain circumstances, have certain adverse consequences to the Fund and its shareholders because it may result in a return of capital resulting in less of a shareholder’s assets being invested in the Fund and, over time, increase the Fund’s expense ratio. The distribution policy also may cause the Fund to sell a security at a time it would not otherwise do so in order to manage the distribution of income and gain.
Unless the registered owner of shares elects to receive cash, all dividends declared on shares will be automatically reinvested in additional shares of the Fund. See “Dividend Reinvestment Policy.”
The dividend distribution described above may result in the payment of approximately the same amount or percentage to the Fund’s shareholders each quarter. Section 19(a) of the 1940 Act and Rule 19a-1 thereunder require the Fund to provide a written statement accompanying any such payment that adequately discloses its source or sources. Thus, if the source of the dividend or other distribution were the original capital contribution of the shareholder, and the payment amounted to a return of capital, the Fund would be required to provide written disclosure to that effect. Nevertheless, persons who periodically receive the payment of a dividend or other distribution may be under the impression that they are receiving net profits when they are not. Shareholders should read any written disclosure provided pursuant to Section 19(a) and Rule 19a-1 carefully and should not assume that the source of any distribution from the Fund is net profit.
The Board reserves the right to change the quarterly distribution policy from time to time.
DIVIDEND REINVESTMENT POLICY
The Fund will operate under a dividend reinvestment policy administered by the Transfer Agent. Pursuant to the policy, the Fund’s income dividends or capital gains or other distributions (each, a “Distribution” and collectively, “Distributions”), net of any applicable U.S. withholding tax, are reinvested in the same class of shares of the Fund.
Shareholders automatically participate in the dividend reinvestment policy, unless and until an election is made to withdraw from the policy on behalf of such participating shareholder. Shareholders who do not wish to have Distributions automatically reinvested should so notify the Transfer Agent in writing at Bluerock Total Income+ Real Estate Fund, c/o SS&C GIDS, PO Box 219445, Kansas City, MO 64121-9445. Such written notice must be received by the Transfer Agent 30 days prior to the record date of the Distribution or the shareholder will receive such Distribution in shares through the dividend reinvestment policy. Under the dividend reinvestment policy, the Fund’s Distributions to shareholders are reinvested in full and fractional shares as described below.
When the Fund declares a Distribution, the Transfer Agent, on the shareholder’s behalf, will receive additional authorized shares from the Fund either newly issued or repurchased from shareholders by the Fund and held as treasury stock. The number of shares to be received when Distributions are reinvested will be determined by dividing the amount of the Distribution by the Fund’s net asset value per share.
The Transfer Agent will maintain all shareholder accounts and furnish written confirmations of all transactions in the accounts, including information needed by shareholders for personal and tax records. The Transfer Agent will hold shares in the account of the shareholders in non-certificated form in the name of the participant, and each shareholder’s proxy, if any, will include those shares purchased pursuant to the dividend reinvestment policy. Each participant, nevertheless, has the right to request certificates for whole and fractional shares owned. The Fund will issue certificates in its sole discretion. The Administrator will distribute all proxy solicitation materials, if any, to participating shareholders.
In the case of shareholders, such as banks, brokers or nominees, that hold shares for others who are beneficial owners participating under the dividend reinvestment policy, the Transfer Agent will administer the dividend reinvestment policy on the basis of the number of shares certified from time to time by the record shareholder as representing the total amount of shares registered in the shareholder’s name and held for the account of beneficial owners participating under the dividend reinvestment policy.
Neither the Transfer Agent nor the Fund shall have any responsibility or liability beyond the exercise of ordinary care for any action taken or omitted pursuant to the dividend reinvestment policy, nor shall they have any duties, responsibilities or liabilities except such as expressly set forth herein. Neither shall they be liable hereunder for any act done in good faith or for any good faith omissions to act, including, without limitation, failure to terminate a participant’s account prior to receipt of written notice of his or her death or with respect to prices at which shares are purchased or sold for the participants account and the terms on which such purchases and sales are made, subject to applicable provisions of the federal securities laws.
The automatic reinvestment of dividends will not relieve participants of any federal, state or local income tax that may be payable (or required to be withheld) on such dividends. See “U.S. Federal Income Tax Matters.”
The Fund reserves the right to amend or terminate the dividend reinvestment policy. There is no direct service charge to participants with regard to purchases under the dividend reinvestment policy; however, the Fund reserves the right to amend the dividend reinvestment policy to include a service charge payable by the participants.
All correspondence concerning the dividend reinvestment policy should be directed to the Transfer Agent at Bluerock Total Income+ Real Estate Fund, c/o SS&C GIDS, PO Box 219445, Kansas City, MO 64121-9445. Certain transactions can be performed by calling the toll-free number 1-844-819-8287.
27 |
U.S. FEDERAL INCOME TAX MATTERS
The following briefly summarizes some of the important federal income tax consequences to shareholders of investing in the Fund’s shares, reflects the federal tax law as of the date of this prospectus, and does not address special tax rules applicable to certain types of investors, such as corporate, tax-exempt and foreign investors. Investors should consult their tax advisors regarding other federal, state or local tax considerations that may be applicable in their particular circumstances, as well as any proposed tax law changes.
The following is a summary discussion of certain U.S. federal income tax consequences that may be relevant to a shareholder of the Fund that acquires, holds and/or disposes of shares of the Fund, and reflects provisions of the Internal Revenue Code of 1986, as amended, existing Treasury regulations, rulings published by the IRS, and other applicable authority, as of the date of this prospectus. These authorities are subject to change by legislative or administrative action, possibly with retroactive effect. The following discussion is only a summary of some of the important tax considerations generally applicable to investments in the Fund and the discussion set forth herein does not constitute tax advice. For more detailed information regarding tax considerations, see the Statement of Additional Information. There may be other tax considerations applicable to particular investors such as those holding shares in a tax deferred account such as an IRA or 401(k) plan. In addition, income earned through an investment in the Fund may be subject to state, local and foreign taxes.
The Fund intends to elect to be treated and to qualify each year for taxation as a regulated investment company under Subchapter M of the Code. In order for the Fund to qualify as a regulated investment company, it must meet an income and asset diversification test each year. If the Fund so qualifies and satisfies certain distribution requirements, the Fund (but not its shareholders) will not be subject to federal income tax to the extent it distributes its investment company taxable income and net capital gains (the excess of net long-term capital gains over net short-term capital loss) in a timely manner to its shareholders in the form of dividends or capital gain distributions. The Code imposes a 4% nondeductible excise tax on regulated investment companies, such as the Fund, to the extent they do not meet certain distribution requirements by the end of each calendar year. The Fund anticipates meeting these distribution requirements. Shareholders will not be subject to the alternative minimum tax.
The Fund intends to make distributions of investment company taxable income after payment of the Fund’s operating expenses no less frequently than annually. Unless a shareholder is ineligible to participate or elects otherwise, all distributions will be automatically reinvested in additional shares of the Fund pursuant to the dividend reinvestment policy. For U.S. federal income tax purposes, all dividends are generally taxable whether a shareholder takes them in cash or they are reinvested pursuant to the policy in additional shares of the Fund. Distributions of the Fund’s investment company taxable income (including short-term capital gains) will generally be treated as ordinary income to the extent of the Fund’s current and accumulated earnings and profits. Distributions of the Fund’s net capital gains (“capital gain dividends”), if any, are taxable to shareholders as capital gains, regardless of the length of time shares have been held by shareholders. Distributions, if any, in excess of the Fund’s earnings and profits will first reduce the adjusted tax basis of a holder’s shares and, after that basis has been reduced to zero, will constitute capital gains to the shareholder of the Fund (assuming the shares are held as a capital asset). A corporation that owns Fund shares generally will not be entitled to the dividends received deduction with respect to all of the dividends it receives from the Fund. Fund dividend payments that are attributable to qualifying dividends received by the Fund from certain domestic corporations may be designated by the Fund as being eligible for the dividends received deduction. There can be no assurance as to what portion of Fund dividend payments may be classified as qualifying dividends. The determination of the character for U.S. federal income tax purposes of any distribution from the Fund (i.e. ordinary income dividends, capital gains dividends, qualified dividends or return of capital distributions) will be made as of the end of the Fund’s taxable year. Generally, no later than 60 days after the close of its taxable year, the Fund will provide shareholders with a written notice designating the amount of any capital gain distributions and any other distributions.
The Fund will inform its shareholders of the source and tax status of all distributions promptly after the close of each calendar year.
DESCRIPTION OF CAPITAL STRUCTURE AND SHARES
The Fund is an unincorporated statutory trust established under the laws of the State of Delaware upon the filing of a Certificate of Trust with the Secretary of State of Delaware on May 25, 2012. The Trustees are authorized to issue an unlimited number of shares. The Fund does not intend to hold annual meetings of its shareholders.
The Declaration of Trust, which has been filed with the SEC, permits the Fund to issue an unlimited number of full and fractional shares of beneficial interest, no par value. The Fund offers five different classes of shares: Class A, Class C, Class I, Class L and Class M shares. The Class A, Class C, Class L and Class M shares are each offered by a different prospectus. The Fund began continuously offering its common shares on October 22, 2012. As of February 18, 2014, the Fund simultaneously redesignated its issued and outstanding common shares as Class A shares and created its Class C and Class I shares, which commenced offering April 1, 2014. As of May 30, 2017, the Fund created its Class L shares. As of February 1, 2020, the Fund created its Class M shares. An investment in any share class of the Fund represents an investment in the same assets of the Fund. However, the minimum investment amounts, sales loads, and ongoing fees and expenses for each share class may be different. The fees and expenses for the Fund are set forth in “Summary of Fund Expenses”. The details of each share class are set forth in “Plan of Distribution”.
28 |
The following table shows the amounts of the Fund’s shares that have been authorized and are outstanding as of January 3, 2025, of which none were owned by the Fund:
Title of Class |
Amount Authorized |
Amount Outstanding |
Class A |
Unlimited |
24,385,031.72 shares NAV $26.03 per share |
Class C |
Unlimited |
15,397,873.19 shares NAV $24.05 per share |
Unlimited |
shares NAV $26.80 per share |
|
Class L |
Unlimited |
3,111,066.77 shares NAV $25.54 per share |
Class M |
Unlimited |
4,381,277.79 shares NAV $24.24 per share |
Holders of shares will be entitled to the payment of dividends when, as and if declared by the Board. The Fund currently intends to make dividend distributions to its shareholders no less frequently than quarterly. Unless the registered owner of shares elects to receive cash, all dividends declared on shares will be automatically reinvested for shareholders in additional shares of the same class of the Fund. See “Dividend Reinvestment Policy.” The 1940 Act may limit the payment of dividends to the holders of shares. Each whole share shall be entitled to one vote as to matters on which it is entitled to vote pursuant to the terms of the Declaration of Trust on file with the SEC. Upon liquidation of the Fund, after paying or adequately providing for the payment of all liabilities of the Fund, and upon receipt of such releases, indemnities and refunding agreements as they deem necessary for their protection, the Trustees may distribute the remaining assets of the Fund among its shareholders. The shares are not liable to further calls or to assessment by the Fund. There are no pre-emptive rights associated with the shares. The Declaration of Trust provides that the Fund’s shareholders are not liable for any liabilities of the Fund. Although shareholders of an unincorporated statutory trust established under Delaware law, in certain limited circumstances, may be held personally liable for the obligations of the Fund as though they were general partners, the provisions of the Declaration of Trust described in the foregoing sentence make the likelihood of such personal liability remote.
The Fund generally will not issue share certificates. However, upon written request to the Fund’s Transfer Agent, a share certificate may be issued at the Fund’s discretion for any or all of the full shares credited to an investor’s account. Share certificates that have been issued to an investor may be returned at any time. The Fund’s Transfer Agent will maintain an account for each shareholder upon which the registration of shares are recorded, and transfers, permitted only in rare circumstances, such as death or bona fide gift, will be reflected by bookkeeping entry, without physical delivery. The Fund’s Transfer Agent will require that a shareholder provide requests in writing, accompanied by a valid signature guarantee form, when changing certain information in an account such as wiring instructions or telephone privileges.
Other Classes of Shares. The Fund offers Class A, Class C, Class L and Class M shares by a different prospectus. The other share classes are subject to different investment minimums, sales charges, and shareholder servicing fees and/or distribution servicing fees.
ANTI-TAKEOVER PROVISIONS IN THE DECLARATION OF TRUST
The Amended and Restated Declaration of Trust includes provisions that could have the effect of limiting the ability of other entities or persons to acquire control of the Fund or to change the composition of the Board, and could have the effect of depriving the Fund’s shareholders of an opportunity to sell their shares at a premium over prevailing market prices, if any, by discouraging a third party from seeking to obtain control of the Fund. These provisions may have the effect of discouraging attempts to acquire control of the Fund, which attempts could have the effect of increasing the expenses of the Fund and interfering with the normal operation of the Fund. The Trustees are elected for indefinite terms and do not stand for reelection. A Trustee may be removed from office without cause only by a written instrument signed or adopted by a majority of the remaining Trustees or by a vote of the holders of at least two-thirds of the shares of the Fund that are entitled to elect a Trustee and that are entitled to vote on the matter. The Declaration of Trust does not contain any other specific inhibiting provisions that would operate only with respect to an extraordinary transaction such as a merger, reorganization, tender offer, sale or transfer of substantially all of the Fund’s asset, or liquidation. Reference should be made to the Declaration of Trust on file with the SEC for the full text of these provisions.
PLAN OF DISTRIBUTION
ALPS Distributors, Inc. (the “Distributor”), located at 1290 Broadway, Suite 1000, Denver, Colorado 80203, serves as the Fund’s principal underwriter and acts as the distributor of the Fund’s shares on a best efforts basis, subject to various conditions. The Fund’s shares are offered for sale through the Distributor at net asset value. The Distributor also may enter into selected dealer agreements with other broker dealers for the sale and distribution of the Fund’s shares, including with affiliates of the Advisor. In reliance on Rule 415, the Fund intends to offer to sell its shares, on a continual basis, through the Distributor. No arrangement has been made to place funds received in an escrow, trust or similar account. The Distributor is not required to sell any specific number or dollar amount of the Fund’s shares. Shares of the Fund will not be listed on any national securities exchange and the Distributor will not act as a market marker in Fund shares. Class I Shares are not currently subject to a Distribution Fee.
29 |
The Distributor has entered into a “wholesaling” agreement with Bluerock Capital Markets, LLC (“BCM”), a registered broker-dealer and an affiliate of the Advisor. Pursuant to the terms of the wholesaling agreement, BCM will seek to market and otherwise promote the Fund through various “wholesale” distribution channels, including regional and independent retail broker-dealers. BCM may receive a portion of the sales load from the sale of certain classes of the Fund’s shares for the services it provides under the wholesaling agreement, but it does not receive compensation from the Fund in connection with the sale of Class I shares.
The Advisor or its affiliates, in the Advisor’s discretion and from their own resources, may pay additional compensation to brokers or dealers in connection with the sale and distribution of Fund shares (the “Additional Compensation”). In return for the Additional Compensation, the Fund may receive certain marketing advantages including access to a broker’s or dealer’s registered representatives, placement on a list of investment options offered by a broker or dealer, or the ability to assist in training and educating the broker’s or dealer’s registered representatives. The Additional Compensation may differ among brokers or dealers in amount or in the manner of calculation: payments of Additional Compensation may be fixed dollar amounts, or based on the aggregate value of outstanding shares held by shareholders introduced by the broker or dealer, or determined in some other manner. The receipt of Additional Compensation by a selling broker or dealer may create potential conflicts of interest between an investor and its broker or dealer who is recommending the Fund over other potential investments. Additionally, the Fund may pay a servicing fee to intermediaries and other financial industry professionals for providing ongoing services in respect of shareholders of the Fund. Such services may include electronic processing of client orders, electronic fund transfers between clients and the Fund, account reconciliations with the Fund’s Transfer Agent, facilitation of electronic delivery to clients of Fund documentation, monitoring client accounts for back-up withholding and any other special tax reporting obligations, maintenance of books and records with respect to the foregoing, and such other information and liaison services as the Fund or the Advisor may reasonably request.
The Fund and the Advisor have agreed to indemnify the Distributor against certain liabilities, including liabilities under the Securities Act of 1933, or to contribute to payments the Distributor may be required to make because of any of those liabilities. Such agreement does not include indemnification of the Distributor against liability resulting from willful misfeasance, bad faith or negligence on the part of the Distributor in the performance of its duties or from reckless disregard by the Distributor of its obligations and duties under the Distribution Agreement. The Distributor may, from time to time, engage in transactions with or perform services for the Advisor and its affiliates in the ordinary course of business.
Purchasing Shares
Investors may purchase shares directly from the Fund in accordance with the instructions below. Investors will be assessed fees for returned checks and stop payment orders at prevailing rates charged by SS&C GIDS, the Fund’s Transfer Agent. The returned check and stop payment fee is currently $25. Investors may buy and sell shares of the Fund through financial intermediaries and their agents that have made arrangements with the Fund and are authorized to buy and sell shares of the Fund (collectively, “Financial Intermediaries”). Such Financial Intermediaries are authorized to designate other intermediaries to receive purchase orders on the Fund’s behalf. The Fund will be deemed to have received a purchase order when a Financial Intermediary or, if applicable, its authorized designee, receives the order. Orders will be priced at the appropriate price next computed after it is received by a Financial Intermediary or their authorized designee and accepted by the Fund. A Financial Intermediary may hold shares in an omnibus account in the Financial Intermediary’s name or the Financial Intermediary or their authorized designee may maintain individual ownership records. The Fund may pay the Financial Intermediary for maintaining individual ownership records as well as providing other shareholder services. Financial intermediaries may charge fees for the services they provide in connection with processing your transaction order or maintaining an investor’s account with them. Investors should check with their Financial Intermediary to determine if it is subject to these arrangements. Financial Intermediaries are responsible for placing orders correctly and promptly with the Fund, forwarding payment promptly. Orders transmitted with a Financial Intermediary before the close of regular trading (generally 4:00 p.m., Eastern Time) on a day that the NYSE is open for business, will be priced based on the Fund’s NAV next computed after it is received by the Financial Intermediary.
The Fund reserves the right to reject or restrict purchase requests for any reason, particularly when the shareholder’s trading activity suggests that the shareholder may be engaged in disruptive trading activities. Neither the Fund nor the Advisor will be liable for any losses resulting from rejected purchase orders.
By Mail
To make an initial purchase by mail, complete an account application and mail the application, together with a check made payable to Bluerock Total Income+ Real Estate Fund to:
Bluerock Total Income+ Real Estate Fund
c/o SS&C GIDS
P.O. Box 219445
Kansas City, MO 64121-9445
All checks must be in U.S. Dollars drawn on a domestic bank. The Fund will not accept payment in cash or money orders. The Fund also does not accept cashier’s checks in amounts of less than $10,000. To prevent check fraud, the Fund will neither accept third party checks, Treasury checks, credit card checks, traveler’s checks or starter checks for the purchase of shares, nor post-dated checks, post-dated on-line bill pay checks, or any conditional purchase order or payment.
The Transfer Agent will charge a $25 fee against an investor’s account, in addition to any loss sustained by the Fund, for any payment that is returned. It is the policy of the Fund not to accept applications under certain circumstances or in amounts considered disadvantageous to shareholders. The Fund reserves the right to reject any application.
30 |
By Wire — Initial Investment
To make an initial investment in the Fund, the Transfer Agent must receive a completed account application before an investor wires funds. Investors may mail or overnight deliver an account application to the Transfer Agent. Upon receipt of the completed account application, the Transfer Agent will establish an account. The account number assigned will be required as part of the instruction that should be provided to an investor’s bank to send the wire. An investor’s bank must include both the name of the Fund, the account number, and the investor’s name so that monies can be correctly applied. If you wish to wire money to make an investment in the Fund, please call the Fund at 1-844-819-8287 for wiring instructions and to notify the Fund that a wire transfer is coming. Any commercial bank can transfer same-day funds via wire. The Fund will normally accept wired funds for investment on the day received if they are received by the Fund’s designated bank before the close of regular trading on the NYSE. Your bank may charge you a fee for wiring same-day funds. The bank should transmit funds by wire to:
ABA #: (number provided by calling toll-free number above)
Credit: SS&C GIDS
Account #: (number provided by calling toll-free number above)
Further Credit:
Bluerock Total Income+ Real Estate Fund
(shareholder registration)
(shareholder account number)
By Wire — Subsequent Investments
Before sending a wire, investors must contact the Transfer Agent to advise them of the intent to wire funds. This will ensure prompt and accurate credit upon receipt of the wire. Wired funds must be received prior to 4:00 p.m. Eastern Time to be eligible for same day pricing. The Fund, and its agents, including the transfer agent and custodian, are not responsible for the consequences of delays resulting from the banking or Federal Reserve wire system, or from incomplete wiring instructions.
Automatic Investment Plan — Subsequent Investments
You may participate in the Fund’s Automatic Investment Plan, an investment plan that automatically moves money from your bank account and invests it in the Fund through the use of electronic funds transfers or automatic bank drafts. You may elect to make subsequent investments by transfers of a minimum of $10,000 on specified days of each month into your established Fund account. Please contact the Fund at 1-844-819-8287 for more information about the Fund’s Automatic Investment Plan.
By Telephone
Investors may purchase additional shares of the Fund by calling 1-844-819-8287. If an investor elected this option on the account application, and the account has been open for at least 15 days, telephone orders will be accepted via electronic funds transfer from your bank account through the Automated Clearing House (ACH) network. Banking information must be established on the account prior to making a purchase. Orders for shares received prior to 4:00 p.m. Eastern Time will be purchased at the appropriate price calculated on that day.
Telephone trades must be received by or prior to market close. During periods of high market activity, shareholders may encounter higher than usual call waits. Please allow sufficient time to place your telephone transaction.
In compliance with the USA Patriot Act of 2001, the Transfer Agent will verify certain information on each account application as part of the Fund’s Anti-Money Laundering Program. As requested on the application, investors must supply full name, date of birth, social security number and permanent street address. Mailing addresses containing only a P.O. Box will not be accepted. Investors may call the Transfer Agent (SS&C GIDS) at 1-844-819-8287 for additional assistance when completing an application.
If the Transfer Agent does not have a reasonable belief of the identity of a customer, the account will be rejected or the customer will not be allowed to perform a transaction on the account until such information is received. The Fund also may reserve the right to close the account within 5 business days if clarifying information/documentation is not received.
Share Class Considerations
When selecting a share class, you should consider the following:
|
● |
which share classes are available to you; |
|
● |
the amount you intend to invest; |
|
● |
how long you expect to own the shares; and |
|
● |
total costs and expenses associated with a particular share class. |
Each investor’s financial considerations are different. You should speak with your financial advisor to help you decide which share class is best for you. Not all financial intermediaries offer all classes of shares. If your financial intermediary offers more than one class of shares, you should carefully consider which class of shares to purchase.
31 |
Class I Shares
Class I shares will be sold at the prevailing NAV per Class I share and are not subject to any upfront sales charge. The Class I shares are not subject to a Distribution Fee, shareholder servicing fees, or early withdrawal charges. Class I shares may only be available through certain financial intermediaries. Because the Class I shares of the Fund are sold at the prevailing NAV per Class I share without an upfront sales charge, the entire amount of your purchase is invested immediately. However, for all accounts, Class I shares require a minimum investment of $1,000,000, while subsequent investments may be made with any amount. Under certain limited circumstances, the Fund, in its sole discretion, may waive the minimum investment amount.
Shareholder Service Plan
Class I shares are not subject to shareholder servicing fee.
Distribution Plan
Class I shares are not subject to a distribution fee.
LEGAL MATTERS
Certain legal matters in connection with the shares will be passed upon for the Fund by Thompson Hine LLP, 41 South High Street, Suite 1700, Columbus, Ohio 43215.
REPORTS TO SHAREHOLDERS
The Fund makes available to its shareholders unaudited semi-annual and audited annual reports, including a list of investments held.
Householding
If you have elected to receive paper copies of the Fund’s annual and semi-annual reports, in an effort to decrease costs, the Fund intends to send only one copy of each to those addresses shared by two or more accounts and to shareholders reasonably believed to be from the same family or household. A shareholder must call 1-844-819-8287 to discontinue householding and request individual copies of these documents. Once the Fund receives notice to stop householding, individual copies will be sent beginning thirty days after receiving your request. This policy does not apply to account statements.
INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
Cohen & Company, Ltd. is the independent registered public accounting firm for the Fund and audits the Fund’s financial statements. Cohen & Company, Ltd. is located at 1835 Market St., Suite 310, Philadelphia, PA 19103.
ADDITIONAL INFORMATION
The Prospectus and the Statement of Additional Information do not contain all of the information set forth in the Registration Statement that the Fund has filed with the SEC (file No. 811-22710). The complete Registration Statement may be obtained from the SEC at www.sec.gov. See the cover page of this prospectus for information about how to obtain a paper copy of the Registration Statement or Statement of Additional Information without charge.
TABLE OF CONTENTS OF THE STATEMENT OF ADDITIONAL INFORMATION
General Information and History |
1 |
Investment Objectives and Policies |
2 |
Repurchases and Transfers of Shares |
9 |
Management of the Fund |
15 |
Codes of Ethics |
22 |
Proxy Voting Policies and Procedures |
22 |
Control Persons and Principal Holders |
22 |
Investment Advisory and Other Services |
23 |
Portfolio Managers |
27 |
Allocation of Brokerage |
31 |
Tax Status |
31 |
Other Information |
35 |
Independent Registered Public Accounting Firm |
36 |
Financial Statements |
36 |
Appendix A |
A-1 |
Appendix B |
B-1 |
32 |
PRIVACY POLICY & PRACTICES
Rev. January 2019
PRIVACY NOTICE
FACTS |
WHAT DOES THE BLUEROCK TOTAL INCOME+ REAL ESTATE FUND DO WITH YOUR PERSONAL INFORMATION? |
|
Why? |
Financial companies choose how they share your personal information. Federal law gives consumers the right to limit some but not all sharing. Federal law also requires us to tell you how we collect, share, and protect your personal information. Please read this notice carefully to understand what we do. |
|
What? |
The types of personal information we collect and share depend on the product or service you have with us. This information can include: |
|
● Social Security number
● Assets
● Retirement Assets
● Transaction History
● Checking Account Information |
● Purchase History
● Account Balances
● Account Transactions
● Wire Transfer Instructions |
|
When you are no longer our customer, we may continue to share your personal information as described in this notice. |
||
How? |
All financial companies need to share customers’ personal information to run their everyday business. In the section below, we list the reasons financial companies can share their customers’ personal information; the reasons the Bluerock Total Income+ Real Estate Fund chooses to share; and whether you can limit this sharing. |
|
Reasons we can share your personal information |
Does Bluerock Total Income+ Real Estate Fund share? |
Can you limit this sharing? |
For our everyday business purposes – such as to process your transactions, maintain your account(s), respond to court orders and legal investigations, or report to credit bureaus |
Yes |
No |
For our marketing purposes – to offer our products and services to you |
No |
We don’t share |
For joint marketing with other financial companies |
No |
We don’t share |
For our affiliates’ everyday business purposes – information about your transactions and experiences |
No |
We don’t share |
For our affiliates’ everyday business purposes – information about your creditworthiness |
No |
We don’t share |
For nonaffiliates to market to you |
No |
We don’t share |
Questions? |
Call 1-844-819-8287 |
33 |
Who we are |
|
Who is providing this notice? |
Bluerock Total Income+ Real Estate Fund |
What we do |
|
How does Bluerock Total Income+ Real Estate Fund protect my personal information? |
To protect your personal information from unauthorized access and use, we use security measures that comply with federal law. These measures include computer safeguards and secured files and buildings.
Our service providers are held accountable for adhering to strict policies and procedures to prevent any misuse of your nonpublic personal information. |
How does Bluerock Total Income+ Real Estate Fund collect my personal information? |
We collect your personal information, for example, when you
● Open an account
● Provide account information
● Give us your contact information
● Make deposits or withdrawals from your account
● Make a wire transfer
● Tell us where to send the money
● Tells us who receives the money
● Show your government-issued ID
● Show your driver’s license
We also collect your personal information from other companies. |
Why can’t I limit all sharing? |
Federal law gives you the right to limit only
● Sharing for affiliates’ everyday business purposes – information about your creditworthiness
● Affiliates from using your information to market to you
● Sharing for nonaffiliates to market to you
State laws and individual companies may give you additional rights to limit sharing. |
Definitions |
|
Affiliates |
Companies related by common ownership or control. They can be financial and nonfinancial companies.
● Bluerock Total Income+ Real Estate Fund does not share with our affiliates. |
Nonaffiliates |
Companies not related by common ownership or control. They can be financial and nonfinancial companies
● Bluerock Total Income+ Real Estate Fund does not share with nonaffiliates so they can market to you. |
Joint marketing |
A formal agreement between nonaffiliated financial companies that together market financial products or services to you.
● Bluerock Total Income+ Real Estate Fund doesn’t jointly market. |
34 |
Page Intentionally Left Blank
Page Intentionally Left Blank
Page Intentionally Left Blank

BLUEROCK TOTAL INCOME+ REAL ESTATE FUND
Class I Shares (TIPWX) of Beneficial Interest
PROSPECTUS
February 1, 2025
Investment Advisor
Bluerock Fund Advisor, LLC
All dealers that buy, sell or trade the Fund’s shares, whether or not participating in this offering, may be required to deliver a prospectus when acting on behalf of the Fund’s Distributor.
You should rely only on the information contained in or incorporated by reference into this prospectus. The Fund has not authorized any other person to provide you with different information. If anyone provides you with different or inconsistent information, you should not rely on it. The Fund is not making an offer to sell these securities in any jurisdiction where the offer or sale is not permitted.

Bluerock Total Income+ Real Estate Fund (the “Fund”) is a continuously offered, non-diversified, closed-end management investment company that is operated as an interval fund.
The Securities and Exchange Commission has not approved or disapproved these securities or determined if this Prospectus is truthful or complete. Any representation to the contrary is a criminal offense.
This prospectus is intended to concisely provide you, a prospective investor, with information about the Fund that you should know before investing in the shares of the Fund that are being offered through this prospectus. You are advised to thoroughly and carefully read this prospectus and retain it for future reference. Additional information about the Fund is also available on the Securities and Exchange Commission’s (“SEC”) website at http://www.sec.gov, including the Fund’s Statement of Additional Information dated February 1, 2025 (the “SAI”). The address of the SEC’s website is provided solely for the information of prospective shareholders and is not intended to be an active link. The table of contents of the SAI appears on page 33 of this prospectus. The SAI is incorporated by reference into this prospectus (legally made a part of this prospectus). The SAI, Fund annual and semi-annual reports and other information and shareholder inquiries regarding the Fund may be requested free of charge by writing the Fund at c/o SS&C Global Investor & Distribution Solutions, Inc., PO Box 219445, Kansas City, MO 64121-9445 (the “Transfer Agent” or “SS&C GIDS”), by calling the Transfer Agent toll-free at 1-844-819-8287, or by visiting the Fund’s website at http://www.bluerockfunds.com.
Investment Objectives. The Fund’s primary investment objective is to generate current income while secondarily seeking long-term capital appreciation with low to moderate volatility and low correlation to the broader markets.
Summary of Investment Strategy. The Fund pursues its investment objectives using a comprehensive multi-strategy, multi-manager, multi-sector approach, primarily investing in a strategic combination of what the Fund’s advisor believes are global ‘best in class’ institutional private real estate funds and public real estate securities.
The Advisor. The Fund’s investment advisor is Bluerock Fund Advisor, LLC (the “Advisor”), a registered advisor under the Investment Advisers Act of 1940, as amended (the “Advisers Act”). The Advisor has engaged Mercer Investments LLC (“Mercer” or a “Sub-Advisor”), a registered advisor under the Advisers Act, to provide ongoing research, opinions and recommendations of institutional asset managers and their investment funds for consideration by the Advisor on behalf of the Fund. Mercer, together with its affiliated investment businesses, have over 5,600 delegated and advisory clients globally with over $547 billion in assets under management as of September 30, 2024 and over $17.5 trillion in assets under advisement as of June 30, 2024. The Advisor has also engaged RREEF America L.L.C. (“RREEF” or a “Sub-Advisor”), a registered adviser under the Advisers Act, to provide investment management for a portion, generally less than 20%, of the Fund’s portfolio. RREEF, together with its affiliates in Europe and Asia, comprise the global real estate investment business of DWS Group GmbH & Co. KGaA (“DWS”), an indirect majority owned subsidiary of Deutsche Bank A.G. DWS’s real estate investment business, is one of the largest real estate investment managers globally with more than 330 professionals and staff located in 23 cities worldwide and approximately $78.9 billion in real estate and real estate-related assets under management as of September 30, 2024.
See “The Fund” and “Investment Objectives, Strategies and Investment Features.”
Securities Offered. The Fund engages in a continuous offering of classes of shares of beneficial interest of the Fund. Class L shares are offered by this prospectus. The Fund offers Class A, Class C, Class I and Class M shares by different prospectuses. The Fund is authorized as a Delaware statutory trust to issue an unlimited number of shares. The Fund is offering to sell, through its principal underwriter, ALPS Distributors, Inc., (the “Distributor”) on a continual basis under the terms of this prospectus, shares of beneficial interest at net asset value (“NAV”) per share of the relevant share class, plus any applicable sales load. As of January 3, 2025, the Fund’s NAV per share was $25.54 for Class L shares. The maximum sales load is 4.25% of the amount invested for Class L shares. The minimum initial investment by a shareholder for Class L shares is $2,500 for regular accounts and $1,000 for retirement plan accounts. Subsequent investments may be made with at least $100 for regular accounts and $50 for retirement plan accounts. The Fund anticipates offering its Class L shares through certain financial service intermediary platforms. The Distributor is not required to sell any specific number or dollar amount of the Fund’s shares, but will use reasonable efforts to sell the shares. No termination date of the Fund’s continuous offering has been established. Monies received will be invested promptly and no arrangements have been made to place such monies in an escrow, trust or similar account.
The Fund’s shares have no history of public trading, nor is it intended that they will be listed on a public exchange at this time. No secondary market is expected to develop for the Fund’s shares, liquidity for the Fund’s shares will be provided only through quarterly repurchase offers for no less than 5% of the Fund’s shares and there is no guarantee that an investor will be able to sell all the shares that the investor desires to sell in the repurchase offer. Investing in the Fund’s shares involves substantial risks, including the risks set forth in the “Risk Factors” section of this prospectus.
|
Investment Advisor | Bluerock Fund Advisor, LLC |

TABLE OF CONTENTS
PROSPECTUS SUMMARY |
1 |
SUMMARY OF FUND EXPENSES |
7 |
FINANCIAL HIGHLIGHTS |
8 |
THE FUND |
9 |
USE OF PROCEEDS |
9 |
INVESTMENT OBJECTIVE, POLICIES AND STRATEGIES |
9 |
RISK FACTORS |
13 |
MANAGEMENT OF THE FUND |
18 |
DETERMINATION OF NET ASSET VALUE |
23 |
CONFLICTS OF INTEREST |
24 |
QUARTERLY REPURCHASES OF SHARES |
24 |
DISTRIBUTION POLICY |
25 |
DIVIDEND REINVESTMENT POLICY |
26 |
U.S. FEDERAL INCOME TAX MATTERS |
27 |
DESCRIPTION OF CAPITAL STRUCTURE AND SHARES |
28 |
ANTI-TAKEOVER PROVISIONS IN THE DECLARATION OF TRUST |
28 |
PLAN OF DISTRIBUTION |
29 |
LEGAL MATTERS |
32 |
REPORTS TO SHAREHOLDERS |
32 |
INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM |
33 |
ADDITIONAL INFORMATION |
33 |
TABLE OF CONTENTS OF THE STATEMENT OF ADDITIONAL INFORMATION |
33 |
PRIVACY POLICY & PRACTICES |
34 |
PROSPECTUS SUMMARY
This summary does not contain all of the information that you should consider before investing in the shares. You should review the more detailed information contained or incorporated by reference in this prospectus and in the Statement of Additional Information, particularly the information set forth below under the heading “Risk Factors.”
The Fund
Bluerock Total Income+ Real Estate Fund (the “Fund”) is a continuously offered, non-diversified, closed-end management investment company. See “The Fund.” The Fund is an interval fund that provides investor liquidity by offering to make quarterly repurchases of each class of shares at that class of shares’ net asset value, which will be calculated on a daily basis. See “Quarterly Repurchases of Shares,” and “Determination of Net Asset Value.”
Investment Objectives and Policies
The Fund’s primary investment objective is to generate current income while secondarily seeking long-term capital appreciation with low to moderate volatility and low correlation to the broader markets.
The Fund pursues its investment objectives by investing, under normal circumstances, at least 80% of net assets, plus the amount of any borrowings for investment purposes, in “real estate industry securities,” primarily in income producing equity and debt securities. The Fund invests in debt securities of any duration or maturity.
The Fund concentrates investments in the real estate industry, meaning that under normal circumstances, it invests over 25% of its assets in real estate industry securities. The Fund’s investments may be targeted in any one or more of the many sectors of the real estate market, including but not limited to the retail, office, multifamily, hospitality, industrial, residential, healthcare, life sciences, and self-storage sectors. The Fund defines real estate industry securities to include the common stock, partnership or similar interests, asset-backed securities, preferred stock, and secured or unsecured debt. Real estate industry securities may be issued by a wide variety of entities including: private real estate investment funds managed by institutional investment managers (“Institutional Investment Funds”); non-traded unregistered real estate investment trusts (“Private REITs”); publicly traded real estate investment trusts or other similar companies (“Public REITs”); Government Sponsored Entities (“GSEs”) such as Federal Home Loan Mortgage Corporation Structured Pass-Through Certificates (“K-Notes”); exchange traded funds, index mutual funds, and other investment vehicles such as closed-end funds and mutual funds that invest principally, directly or indirectly, in real estate (collectively, “Other Public Investment Vehicles”) and unregistered funds that invest principally in real estate. In certain circumstances or market environments, the Fund may reduce its investment in real estate industry securities and hold a larger position in cash or cash equivalents. The Fund will not invest in any issuer that is an affiliate of the Fund, or affiliate of a Fund affiliate (as defined by the Investment Company Act of 1940, as amended (the “1940 Act”)).
The Fund’s real estate industry investment policy is fundamental and may not be changed without shareholder approval. The Fund’s Statement of Additional Information (“SAI”) contains a list of all of the fundamental and non-fundamental investment policies of the Fund, under the heading “Investment Objectives and Policies.”
Investment Strategy
The Fund pursues its investment objectives using a comprehensive multi-strategy, multi-manager, multi-sector approach, primarily investing in a strategic combination of global ‘best in class’ institutional private real estate investment funds and public real estate securities.
The term ‘best in class’ refers to Institutional Investment Funds the Advisor has identified as offering above average prospects using information provided by Mercer and its proprietary screening process. Mercer’s screening process applies multiple factors including quantitative and qualitative assessment (as described more fully below) of the management team and track record, and is not generally available to the individual investor through financial filings or published reports. Mercer is one of the leading advisors to endowments, pension funds, sovereign wealth funds, and family offices globally.
The Fund executes a portion of its investment strategy, generally less than 20%, by seeking to invest in publicly traded real estate securities selected by RREEF, an indirect subsidiary of DWS. RREEF seeks to maximize risk-adjusted returns by managing volatility and identifying securities that are priced inefficiently relative to its assessment of intrinsic value and the public real estate securities may be of any credit quality; including fixed-income and preferred securities rated less than investment grade that are sometimes referred to as high yield or “junk bonds.” The Advisor or RREEF will sell a security when other securities are available that offer higher expected current income, long-term capital appreciation, lower volatility or lower correlation to broader securities markets or a combination of the preceding.
The Fund may utilize leverage through borrowing for investment purposes or to satisfy repurchase requests. The Fund currently borrows money under two credit facilities.
Many of the Institutional Investment Funds have a large minimum investment size and stringent investor qualification criteria that are intended to limit their direct investors to mainly institutions such as endowments and pension funds. As such, the Fund enables investors to invest with institutional investment managers that may not be otherwise permitted or available to them.
In addition, the Fund enables investors to execute a comprehensive multi-strategy, multi-manager, multi-sector strategy by making a single investment in the Fund, whereas due to the large minimums of many of the Institutional Investment Funds, such a strategy may not otherwise be permitted or available to the investor.
1 |
The Advisor also believes that the Fund may be able to provide an additional benefit in terms of lower fees from the Institutional Investment Funds as a result of volume discounts that may not otherwise be permitted or available to them.
Investment Advisor
Bluerock Fund Advisor, LLC was formed on May 11, 2012 and is registered with the SEC as an investment adviser. The Advisor is a subsidiary of Bluerock Asset Management, LLC (“BAM”); BAM, together with its affiliates (“Bluerock”), is a leading institutional alternative asset manager with more than $19.2 billion in acquired and managed assets based in New York with regional offices across the United States. Bluerock principals have a collective 100+ years of investing experience with more than $120 billion of real estate and capital markets experience and manage multiple well-recognized real estate private and public company platforms.
Sub-Advisors
The Advisor may, from time to time, engage one or more investment sub-advisors. Any sub-advisor chosen by the Advisor will be paid by the Advisor on only the portion of Fund assets allocated to any such sub-advisor. Shareholders do not pay any sub-advisor directly.
The Advisor has engaged Mercer, a registered investment adviser under the Advisers Act, to provide both ongoing research and opinions of institutional asset managers and their investment funds for consideration by the Advisor on behalf of the Fund as well as recommendations for the selection of investment funds for approval by the Advisor. The Advisor has engaged RREEF, a registered investment adviser under the Advisers Act, to invest a portion of the Fund’s portfolio in publicly traded real estate securities and to provide the Advisor with research and information with respect to non-publicly traded real estate related debt securities.
Advisor Fees and Expenses
The Advisor is entitled to receive a monthly fee at the annual rate of 1.50% of the Fund’s daily net assets. The Advisor and the Fund have entered into an expense limitation and reimbursement agreement (the “Expense Limitation Agreement”) under which the Advisor has contractually agreed to waive its fees and to pay or absorb the ordinary operating expenses of the Fund (excluding any taxes, interest, brokerage commissions, acquired fund fees and expenses, and extraordinary expenses, such as litigation or reorganization costs, but including organizational costs and offering costs), to the extent that such expenses exceed 2.20% per annum of the Fund’s average daily net assets (the “Expense Limitation”) attributable to Class L shares. In consideration of the Advisor’s agreement to limit the Fund’s expenses, the Fund has agreed to repay the Advisor in the amount of any fees the Advisor previously waived or Fund expenses reimbursed, subject to the limitations that: (1) the reimbursement will be made if payable not more than three years from the date incurred; (2) the reimbursement may not be made if it would cause the expense limitation then in effect or in effect at the time of the waiver to be exceeded; and (3) the reimbursement is approved by the Fund’s Board of Trustees (the “Board”). The Expense Limitation Agreement will remain in effect at least until January 31, 2026, unless and until the Board approves its modification or termination. After January 31, 2026, the Expense Limitation Agreement may be renewed at the Advisor’s and Board’s discretion. See “Management of the Fund.”
Administrator, Accounting Agent and Transfer Agent
ALPS Fund Services, Inc. (the “Administrator”) serves as the Fund’s administrator and accounting agent. SS&C Global Investor & Distribution Solutions, Inc. (the “Transfer Agent” or “SS&C GIDS”) serves as the transfer agent of the Fund. See “Management of the Fund.”
Distribution Fees
Class L shares will pay to the Distributor a distribution fee (the “Distribution Fee”) that will accrue at an annual rate equal to 0.25% of the Fund’s average daily net assets attributable to Class L shares and is payable on a monthly basis. See “Plan of Distribution.”
Closed-End Fund Structure
Generally, closed-end funds differ from mutual funds in that closed-end funds do not typically redeem their shares at the option of the shareholder. Closed-end fund shares typically trade in the secondary market via a stock exchange. Unlike many closed-end funds, however, the Fund’s shares will not be listed on a stock exchange. Instead, the Fund will provide limited liquidity to shareholders by offering to repurchase a limited amount of the Fund’s shares (at least 5%) quarterly, which is discussed in more detail below. The Fund, similar to a mutual fund, is subject to continuous asset in-flows, although not subject to continuous out-flows.
Share Classes
The Fund offers Class L shares by this prospectus. The Fund began continuously offering its common shares on October 22, 2012. As of February 18, 2014, the Fund simultaneously redesignated its issued and outstanding common shares as Class A shares and created its Class C shares and Class I shares, each offered by a separate prospectus. As of May 30, 2017, the Fund created its Class L shares. As of February 1, 2020, the Fund created its Class M shares. An investment in any share class of the Fund represents an investment in the same assets of the Fund. However, the sales loads and ongoing fees and expenses for each share class are different. The loads, fees and expenses for the Fund are set forth in “Summary of Fund Expenses.” If an investor has hired an intermediary and is eligible to invest in more than one class of shares, the intermediary may help determine which share class is appropriate for that investor. When selecting a share class, you should consider which share classes are available to you, how much you intend to invest, the investment minimum, how long you expect to own shares, and the total costs and expenses associated with a particular share class.
2 |
Each investor’s financial considerations are different. You should speak with your financial advisor to help you decide which share class is best for you. Not all financial intermediaries offer all classes of shares and all share classes may not be available in every state. The Fund anticipates offering its Class L shares through a financial service intermediary platform. If your financial intermediary offers more than one class of shares, you should carefully consider which class of shares to purchase.
Investor Suitability
An investment in the Fund involves a considerable amount of risk. It is possible that you will lose some or all of your money. An investment in the Fund is suitable only for investors who can bear the risks associated with the limited liquidity of the shares and should be viewed as a medium to long-term investment. Before making your investment decision, you should (i) consider the suitability of this investment with respect to your investment objectives and personal financial situation and (ii) consider factors such as your personal net worth, income, age, risk tolerance and liquidity needs.
Repurchases of Shares
The Fund is an interval fund and, as such, has adopted a fundamental policy to make quarterly repurchase offers, at net asset value, of no less than 5% of the Fund’s outstanding shares. There is no guarantee that shareholders will be able to sell all of the shares they desire to sell in a quarterly repurchase offer. Liquidity will be provided to shareholders only through the Fund’s quarterly repurchases. See “Quarterly Repurchases of Shares.”
Summary of Risks
Investing in the Fund involves risks, including the risk that you may receive little or no return on your investment or that you may lose part or all of your investment. Before investing you should consider carefully the risks that you assume when you invest in the Fund’s shares. See “Risk Factors.”
Real Estate Industry Concentration Risk. The Fund will concentrate its investments in real estate related securities, and it may invest in real estate directly. As such, its portfolio will be significantly impacted by the performance of the real estate market and may experience more volatility and be exposed to greater risk than a more diversified portfolio. The value of companies engaged in the real estate industry is affected by: (i) changes in general economic and market conditions; (ii) changes in the value of real estate properties; (iii) risks related to local economic conditions, overbuilding and increased competition; (iv) increases in property taxes and operating expenses; (v) changes in zoning laws; (vi) casualty and condemnation losses; (vii) variations in rental income, neighborhood values or the appeal of property to tenants; (viii) the availability of financing; (ix) climate change and (x) changes in interest rates and leverage. There are also special risks associated with particular sectors, or real estate operations, including, but not limited to, those risks described below:
Retail Properties. Retail properties are affected by shifts in consumer demand due to demographic changes, changes in spending patterns and lease terminations.
Office Properties. Office properties are affected by a downturn in the businesses operated by their tenants.
Hospitality Properties. Hotel properties and other properties in the hospitality real estate sector, such as motels and extended-stay properties, are affected by declines in business and leisure travel.
Healthcare and Life Sciences Properties. Healthcare and life sciences properties are affected by potential federal, state and local laws governing licenses, certification, adequacy of care, pharmaceutical distribution, rates, equipment, personnel and other factors regarding operations, funding for biotech companies and the continued availability of revenue from government reimbursement programs.
Industrial Properties. Industrial properties are affected by downturns in the manufacturing, processing and shipping of goods.
Multifamily Properties. Multifamily properties are affected by adverse economic conditions in the locale, oversupply and rent control laws.
Residential Properties. Residential properties can be significantly affected by the national, regional and local real estate markets. This segment of the real estate industry also is sensitive to interest rate fluctuations which can cause changes in the availability of mortgage capital and directly affect the purchasing power of potential homebuyers. Thus, residential properties can be significantly affected by changes in government spending, consumer confidence, demographic patterns and the level of new and existing home sales.
Shopping Centers. Shopping center properties are affected by changes in the local markets where their properties are located and dependent upon the successful operations and financial condition of their major tenants.
Self-Storage Properties. Self-storage properties are affected by changes to competing local properties, consumer and small business demand for storage space, and the ability of the management team.
Other factors may contribute to the risk of real estate investments:
Development Issues. Real estate development companies in which the Underlying Funds (defined below) or the Fund may invest are affected by construction delays and insufficient tenant demand to occupy newly developed properties.
3 |
Lack of Insurance. Certain of the companies in the Fund’s portfolio may fail to carry comprehensive liability, fire, flood, wind or earthquake extended coverage and rental loss insurance, or insurance and may be subject to various policy specifications, limits and deductibles. Due to the prevalence of catastrophic events, the cost of insurance may increase materially.
Dependence on Tenants. The ability of companies in the real estate industry in which the Fund may invest to make distributions to shareholders depends upon the ability of the tenants at their properties to generate enough income in excess of tenant operating expenses to make their lease payments.
Financial Leverage. Companies in the real estate industry in which the Fund may invest may be highly leveraged and financial covenants may affect their ability to operate effectively. The use of floating rate loans may also negatively impact returns in a rising interest rate environment.
Environmental Issues. Owners of properties that may contain hazardous or toxic substances may be responsible for removal or remediation costs. Environmental risk from high winds, hurricanes, fires, flood and extreme heat may also materially affect a property’s value.
Credit Market Conditions. Instability in credit markets can potentially make it more difficult for borrowers to obtain financing or refinancing on attractive terms or at all. Conditions in the credit markets may expose borrowers to increased interest expenses for borrowed money and tightening underwriting standards. There is also a risk that a general lack of liquidity or other events in the credit markets may adversely affect the ability of issuers in whose securities the Fund invests to finance real estate developments and projects or refinance completed projects.
Market Risk. An investment in shares is subject to investment risk, including the possible loss of the entire principal amount invested. An investment in shares represents an indirect investment in the securities owned by the Fund. The value of these securities, like other market investments, may move up or down, sometimes rapidly and unpredictably. In addition, the Fund is subject to the risk that geopolitical and other similar events will disrupt the economy on a national or global level. For instance, war, terrorism, market manipulation, government defaults, government shutdowns, political changes or diplomatic developments, public health emergencies (such as the spread of infectious diseases, pandemics and epidemics) and natural/environmental disasters can all negatively impact the securities markets.
Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. The foregoing could impair the Fund’s ability to maintain operational standards, disrupt the operations of the Fund and its service providers, adversely affect the performance, value and liquidity of the Fund’s investments, and negatively impact the Fund’s performance and your investment in the Fund. The value of your shares at any point in time may be worth less than the value of your original investment, even after taking into account any reinvestment of dividends and distributions.
Liquidity Risk. There currently is no secondary market for the Fund’s shares and the Advisor does not expect that a secondary market will develop. Limited liquidity is provided to shareholders only through the Fund’s quarterly repurchase offers for no less than 5% of the Fund’s shares outstanding at net asset value. There is no guarantee that shareholders will be able to sell all of the shares they desire in a quarterly repurchase offer. The Fund’s investments also are subject to liquidity risk. Liquidity risk exists when particular investments of the Fund would be difficult to purchase or sell, possibly preventing the Fund from selling such illiquid securities at an advantageous time or price, or possibly requiring the Fund to dispose of other investments at unfavorable times or prices in order to satisfy its obligations.
Allocation Risk. The ability of the Fund to achieve its investment objective depends, in part, on the ability of the Advisor to allocate effectively the Fund’s assets among the various Institutional Investment Funds, Private REITs, Public REITs and Other Public Investment Vehicles in which the Fund invests and, with respect to each such asset class, among equity and fixed income securities. There can be no assurance that the actual allocations will be effective in achieving the Fund’s investment objective or delivering positive returns.
Correlation Risk. The Fund seeks to produce returns that are not correlated to the broader financial markets. Although the prices of equity securities and fixed-income securities, as well as other asset classes, often rise and fall at different times so that a fall in the price of one may be offset by a rise in the price of the other, in down markets the prices of these securities and asset classes can also fall in tandem. Because the Fund allocates its investments among different real estate asset classes, the Fund is subject to correlation risk.
Credit Risk. It is possible that issuers of debt securities may not make scheduled interest and principal payments, resulting in losses to the Fund. In addition, the credit quality of securities held may be lowered if an issuer’s financial condition changes and this also may negatively impact the Fund’s returns on investment in such securities.
Distribution Policy Risk. The Fund’s distribution policy is expected to result in distributions that equal a fixed percentage of the Fund’s current net asset value per share. All or a portion of a distribution may consist of a return of capital (i.e. from your original investment). Shareholders should not assume that the source of a distribution from the Fund is net profit. Shareholders should note that return of capital will reduce the tax basis of their shares and potentially increase the taxable gain, if any, upon disposition of their shares.
Fixed Income Risk. Typically, a rise in interest rates causes a decline in the value of fixed income securities. Recently, interest rates have risen sharply after maintaining historically low levels for a significant period of time. Current conditions may result in an increase in interest rate volatility, which in turn may result in a decline in the value of the fixed income investments held by the Fund. As a result, for the present, interest rate risk may be heightened. Fixed income securities are also subject to default risk.
4 |
Institutional Investment Fund Risk. The Fund’s investment in Institutional Investment Funds will require it to bear a pro rata share of the vehicles’ expenses, including management and performance fees. The fees the Fund pays to invest in an Institutional Investment Fund may be higher than if the manager of the Institutional Investment Fund managed the Fund’s assets directly. The performance fees charged by certain Institutional Investment Funds may create an incentive for its manager to make investments that are riskier and/or more speculative than those it might have made in the absence of a performance fee. Furthermore, Institutional Investment Funds, like the other “Underlying Funds” in which the Fund may invest, are subject to specific risks, depending on the nature of the vehicle, and also may employ leverage such that their returns are more than one times that of their benchmark which could amplify losses suffered by the Fund when compared to unleveraged investments. Shareholders of the Institutional Investment Funds are not entitled to the protections of the 1940 Act. For example, these funds need not have independent boards, shareholder approval of advisory contracts may not be required, may leverage to an unlimited extent, and may engage in joint transactions with affiliates. These characteristics present additional risks for shareholders.
Issuer and Non-Diversification Risk. The value of a specific security can perform differently from the market as a whole for reasons related to the investment manager or issuer, such as management performance, financial leverage and reduced demand for the respective properties and services. The Fund’s performance may be more sensitive to any single economic, business, political or regulatory occurrence than the value of shares of a diversified investment company because as a non-diversified fund, the Fund may invest more than 5% of its total assets in the securities of one or more issuers.
Lack of Control Over Institutional Investment Funds and Other Portfolio Investments. Once the Advisor or RREEF has selected an Institutional Investment Fund, Private REIT, Public REIT, or Other Public Investment Vehicle (each, an “Underlying Fund” and together, the “Underlying Funds”) for investment by the Fund, the Advisor and RREEF will have no control over the investment decisions made by any such Underlying Fund. Although the Fund and the Advisor or RREEF will evaluate regularly each Underlying Fund and its manager to determine whether their respective investment programs are consistent with the Fund’s investment objective, the Advisor and RREEF will not have any control over the investments made by any Underlying Fund. Even though the Underlying Funds are subject to certain constraints, the managers may change aspects of their investment strategies. The managers may do so at any time (for example, such change may occur immediately after providing the Advisor with the quarterly unaudited financial information for an Institutional Investment Fund). The Advisor or RREEF may reallocate the Fund’s investments among the Underlying Funds, but the Advisor’s ability to do so may be constrained by the withdrawal limitations imposed by certain of the Underlying Funds, which may prevent the Fund from reacting rapidly to market changes should an Underlying Fund fail to effect portfolio changes consistent with such market changes and the demands of the Advisor. Such withdrawal limitations may also restrict the Advisor’s ability to terminate investments in Underlying Funds that are poorly performing or have otherwise had adverse changes. The Advisor and RREEF will be dependent on information provided by the Underlying Fund, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s or RREEF’s ability to manage the Fund’s investment portfolio in accordance with its investment objectives.
Leveraging Risk. The use of leverage, such as borrowing money to purchase securities or otherwise invest the Fund’s assets, will cause the Fund to incur additional expenses and may significantly magnify the Fund’s losses in the event of adverse performance of the Fund’s underlying investments. In addition to any borrowing utilized by the Fund, the Underlying Funds in which the Fund invests may utilize leverage, subject to the limitations of their charters and operative documents. Leverage by Underlying Funds and/or the Fund has the effect of potentially increasing losses. In addition, interest rates (including benchmarks like Secured Overnight Financing Rate (“SOFR”) and the spreads to such benchmarks charged by lenders) are highly sensitive to external factors outside a borrower’s control, including general and local economic conditions (such as inflation, recession, money supply and unemployment) and the monetary and fiscal policies of various governmental agencies such as the Federal Reserve Board. During periods of increased interest rates, borrowing costs of the Fund will likely increase and may adversely affect the Fund’s performance.
Management Risk. The judgments of the Advisor or a Sub-Advisor about the attractiveness, value and potential appreciation of particular real estate segment and securities in which the Fund invests may prove to be incorrect and may not produce the desired results.
Possible Competition Between Underlying Funds and Between the Fund and the Underlying Funds. The Underlying Funds trade independently of each other and may pursue investment strategies that “compete” with each other for execution or that cause the Fund to participate in positions that offset each other (in which case the Fund would bear its pro rata share of commissions and fees without the potential for a profit). Also, the Fund’s investments in any particular Underlying Fund could increase the level of competition for the same trades that other Underlying Funds might otherwise make, including the priorities of order entry. This could make it difficult or impossible to take or liquidate a position in a particular security at a price consistent with the Advisor’s strategy.
Preferred Securities Risk. Preferred securities are subject to credit risk and interest rate risk. Interest rate risk is, in general, that the price of a debt security falls when interest rates rise. Securities with longer maturities tend to be more sensitive to interest rate changes. Credit risk is the risk that an issuer of a security may not be able to make principal and interest or dividend payments on the security as they become. Holders of preferred securities may not receive dividends, or the payment can be deferred for some period of time. In bankruptcy, creditors are generally paid before the holders of preferred securities.
REIT Risk. The value of investments in REIT shares may decline because of adverse developments affecting the real estate industry and real property values. In general, real estate values can be affected by a variety of factors, including supply and demand for properties, the economic health of the country or of different regions, and the strength of specific industries that rent properties. Also, qualification as a REIT under the Internal Revenue Code of 1986, as amended (the “Code”) in any particular year is a complex analysis that depends on a number of factors. There can be no assurance that an entity in which the Fund invests with the expectation that it will be taxed as a REIT will, in fact, qualify as a REIT. An entity that fails to qualify as a REIT would be subject to a corporate level tax, would not be entitled to a deduction for dividends paid to its shareholders and would not pass through to its shareholders the character of income earned by the entity.
5 |
Repurchase Policy Risks. Quarterly repurchases by the Fund of its shares typically will be funded from available cash or sales of portfolio securities. The sale of securities to fund repurchases could reduce the market price of those securities, which in turn would reduce the Fund’s net asset value.
Underlying Funds Risk. Investments in real estate index funds (“Index Funds”), real estate exchange traded funds (“ETFs”), and Other Public Investment Vehicles are subject to investment advisory and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in such Other Public Investment Vehicles, and also may be higher than other funds that invest directly in securities. Further, Other Public Investment Vehicles are subject to specific risks, depending on the nature of the fund.
Valuation of Institutional Investment Funds. Institutional Investment Funds are not publicly traded and the Fund may consider information provided by the institutional asset manager to determine the value of the Fund’s investment therein. The valuation provided by an institutional asset manager as of a specific date may vary from the actual sale price that may be obtained if such investment were sold to a third party. To determine the value of the Fund’s investment in Institutional Investment Funds, the Advisor considers, among other things, information provided by the Institutional Investment Funds, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s ability to value accurately the Fund’s shares. Institutional Investment Funds that invest primarily in publicly traded securities are more easily valued.
U.S. Federal Income Tax Matters
The Fund intends to elect to be treated and to qualify each year for taxation as a regulated investment company under Subchapter M of the Code. In order for the Fund to so qualify, it must meet an income and asset diversification test each year. If the Fund so qualifies and satisfies the applicable distribution requirements, the Fund (but not its shareholders) will not be subject to federal income tax to the extent it distributes its investment company taxable income and net capital gains (the excess of net long-term capital gains over net short-term capital loss) in a timely manner to its shareholders in the form of dividends or capital gain distributions. The Code imposes a 4% nondeductible excise tax on regulated investment companies, such as the Fund, to the extent they do not meet certain distribution requirements by the end of each calendar year. The Fund anticipates meeting these distribution requirements. See “U.S. Federal Income Tax Matters.”
Distribution Policy
The Fund’s distribution policy is to make quarterly distributions to shareholders. The level of distributions (including any return of capital) is not fixed, but is expected to represent an annual rate of approximately 5.25% of the Fund’s current net asset value per share. However, this distribution policy is subject to change. Unless a shareholder elects otherwise, the shareholder’s distributions will be reinvested in additional shares of the same class under the Fund’s dividend reinvestment policy. Shareholders who elect not to participate in the Fund’s dividend reinvestment policy will receive all distributions in cash paid to the shareholder of record (or, if the shares are held in street or other nominee name, then to such nominee). See “Dividend Reinvestment Policy.”
Custodian
UMB Bank, N.A. (“UMB Bank”) serves as the custodian for the Fund. See “Management of the Fund.”
6 |
SUMMARY OF FUND EXPENSES
Shareholder Transaction Expenses |
Class L |
Maximum Sales Load |
|
Maximum Early Withdrawal Charge (as a percent of original purchase price) |
Annual Expenses (as a percentage of net assets attributable to shares) |
|
Management Fees |
|
Other Expenses |
|
Shareholder Servicing Fee |
|
Distribution Fee1 |
|
Remaining Other Expenses |
|
Interest Payments on Borrowed Funds2 |
|
Acquired Fund Fees and Expenses |
|
Total Annual Expenses |
|
Fee Waiver and Expense Reimbursement3 |
( |
Total Annual Expenses (after fee waiver and reimbursement) |
|
1. |
|
|
2. |
|
|
3. |
|
The above Summary of Fund Expenses table describes the fees and expenses that you may pay if you buy and hold shares of the Fund. More information about management fees, fee waivers and other expenses is available in Management of the Fund starting on page 18 of this prospectus.
The following example illustrates the hypothetical expenses that you would pay on a $1,000 investment assuming annual expenses attributable to shares remain unchanged and shares earn a 5% annual return:
Share Class |
1 Year |
3 Years |
5 Years |
10 Years |
Class L Shares |
$ |
$ |
$ |
$ |
Shareholders who choose to participate in repurchase offers by the Fund will not incur an early withdrawal charge. However, if shareholders request repurchase proceeds be paid by wire transfer, such shareholders will be assessed an outgoing wire transfer fee at prevailing rates charged by the Transfer Agent, currently $10. The purpose of the above table is to help a holder of shares understand the fees and expenses that such holder would bear directly or indirectly. The example should not be considered a representation of actual future expenses. Actual expenses may be higher or lower than those shown.
7 |
FINANCIAL HIGHLIGHTS
Class L Shares
The financial highlights table below is intended to help you understand the Fund’s financial performance since its inception. Certain information reflects financial results for a single Share. The total returns in the table represent the rate that an investor would have earned (or lost) on an investment in the Fund (assuming reinvestment of all dividends and other distributions). This information has been derived from the Fund’s financial statements, which have been audited by Cohen & Company, Ltd., the Fund’s independent registered public accounting firm, whose report, along with the Fund’s financial statements, is included in the Fund’s Annual Report for the fiscal year ended September 30, 2024, which is available upon request.
|
For the |
For the |
For the |
For the |
For the |
For the |
For the |
For the |
||||||||||||||||||||||||
Net asset value, beginning of year |
$ | 30.26 | $ | 36.61 | $ | 32.31 | $ | 29.02 | $ | 30.25 | $ | 29.89 | $ | 29.34 | $ | 29.42 | ||||||||||||||||
INCOME FROM INVESTMENT OPERATIONS: |
||||||||||||||||||||||||||||||||
Net investment income/(loss)(a) |
(0.39 | ) | (0.23 | ) | 0.29 | 0.42 | 0.37 | 0.26 | 0.13 | (0.06 | ) | |||||||||||||||||||||
Net realized and unrealized gain/(loss) |
(2.37 | ) | (4.37 | ) | 5.90 | 4.46 | (0.03 | ) | 1.68 | 1.99 | 0.76 | |||||||||||||||||||||
Total from investment operations |
(2.76 | ) | (4.60 | ) | 6.19 | 4.88 | 0.34 | 1.94 | 2.12 | 0.70 | ||||||||||||||||||||||
|
||||||||||||||||||||||||||||||||
DISTRIBUTIONS: |
||||||||||||||||||||||||||||||||
From net investment income |
— | — | — | — | (0.06 | ) | — | — | — | |||||||||||||||||||||||
From net realized gain on investments |
(0.14 | ) | (0.19 | ) | (0.42 | ) | (0.63 | ) | (1.01 | ) | (0.32 | ) | (0.53 | ) | — | |||||||||||||||||
Return of capital |
(1.33 | ) | (1.56 | ) | (1.47 | ) | (0.96 | ) | (0.50 | ) | (1.26 | ) | (1.04 | ) | (0.78 | ) | ||||||||||||||||
Total distributions |
(1.47 | ) | (1.75 | ) | (1.89 | ) | (1.59 | ) | (1.57 | ) | (1.58 | ) | (1.57 | ) | (0.78 | ) | ||||||||||||||||
Net asset value, end of year |
$ | 26.03 | $ | 30.26 | $ | 36.61 | $ | 32.31 | $ | 29.02 | $ | 30.25 | $ | 29.89 | $ | 29.34 | ||||||||||||||||
TOTAL RETURN(b)(c) |
(9.31 | )% | (12.86 | )% | 19.46 | % | 17.38 | % | 1.14 | % | 6.70 | % | 7.40 | % | 2.40 | %(f) | ||||||||||||||||
RATIOS/SUPPLEMENTAL DATA: |
||||||||||||||||||||||||||||||||
Net assets, end of period/year (000s) |
$ | 82,480 | $ | 102,398 | $ | 124,675 | $ | 87,645 | $ | 73,014 | $ | 88,605 | $ | 42,975 | $ | 5,059 | ||||||||||||||||
Ratios to Average Net Assets (including interest expense) |
||||||||||||||||||||||||||||||||
Ratio of expenses to average net assets excluding fee waivers and reimbursements(d)(e) |
4.09 | % | 3.40 | % | 2.28 | % | 2.35 | % | 2.40 | % | 2.44 | % | 2.84 | % | 2.83 | %(g) | ||||||||||||||||
Ratio of expenses to average net assets including fee waivers and reimbursements(e) |
4.07 | % | 3.40 | % | 2.29 | % | 2.31 | % | 2.41 | % | 2.46 | % | 2.74 | % | 2.63 | %(g) | ||||||||||||||||
Ratio of net investment income/(loss) to average net assets(e) |
(1.40 | )% | (0.67 | )% | 0.81 | % | 1.40 | % | 1.25 | % | 0.87 | % | 0.44 | % | (0.64 | )%(g) | ||||||||||||||||
Ratios to Average Net Assets (excluding interest expense) |
||||||||||||||||||||||||||||||||
Ratio of expenses to average net assets excluding fee waivers and reimbursements(d)(e) |
2.22 | % | 2.20 | % | 2.20 | % | 2.24 | % | 2.17 | % | 2.18 | % | 2.27 | % | 2.35 | %(g) | ||||||||||||||||
Ratio of expenses to average net assets including fee waivers and reimbursements(e) |
2.20 | % | 2.20 | % | 2.21 | % | 2.20 | % | 2.18 | % | 2.20 | % | 2.17 | % | 2.14 | %(g) | ||||||||||||||||
Portfolio turnover rate |
14 | % | 13 | % | 4 | % | 26 | % | 27 | % | 8 | % | 13 | % | 16 | %(f) | ||||||||||||||||
|
* |
Class L commenced operations June 1, 2017. |
|
(a) |
Per share amounts are calculated using the average shares method. |
|
(b) |
Total returns are historical in nature and assumes changes in net asset value per share, reinvestment of dividends and capital gains distributions, if any, and do not reflect the impact of sales charges. Had the Advisor not absorbed a portion of the Fund expenses, total returns would have been lower. |
|
(c) |
Includes adjustments in accordance with accounting principles generally accepted in the United States and, consequently, the net asset value for financial reporting purposes and the returns based upon those net asset values may differ from the net asset values and returns for shareholder transactions. |
|
(d) |
Represents the ratio of expenses to average net assets absent fee waivers expense reimbursement and/or recoupment by the Advisor. |
|
(e) |
The ratios of expenses to average net assets and net investment income (loss) to average net assets do not directly reflect the expenses of the underlying institutional private real estate investments in which the Fund invests. The Fund invests in each underlying institutional private real estate investment based upon its net asset value, inclusive of management fees, which typically range from 0.50% to 1.30% on an annualized basis. The Fund’s Total Return is reported net of all fees and expenses. |
|
(f) |
Not annualized. |
|
(g) |
Annualized. |
8 |
THE FUND
The Fund is a continuously offered, non-diversified, closed-end management investment company that is operated as an interval fund. The Fund was organized as a Delaware statutory trust on May 25, 2012. The Fund’s principal office is located at 919 Third Avenue, 40th Floor, New York, NY 10022, and its telephone number is 1-844-819-8287.
USE OF PROCEEDS
The net proceeds of the Fund’s continuous offering of shares, after payment of the sales load (if applicable) and other associated expenses, will be invested in accordance with the Fund’s investment objective and policies (as stated below) as soon as practicable after receipt. The Fund pays organizational costs and its offering expenses incurred with respect to its initial and continuous offering. Pending investment of the net proceeds in accordance with the Fund’s investment objective and policies, the Fund will invest in money market or short-term fixed-income mutual funds. Investors should expect, therefore, that before the Fund has fully invested the proceeds of the offering in accordance with its investment objective and policies, the Fund’s assets would earn interest income at a modest rate.
INVESTMENT OBJECTIVE, POLICIES AND STRATEGIES
Investment Objective and Policies
The Fund seeks primarily to generate current income while secondarily seeking long-term capital appreciation with low to moderate volatility and low correlation to the broader markets.
The Fund pursues its investment objectives by investing, under normal circumstances, at least 80% of its net assets, plus the amount of any borrowings for investment purposes, in real estate industry securities, primarily in income producing equity and debt securities. The Fund’s investments may be targeted in any one or more of the many sectors of the real estate market, including but not limited to the retail, office, multifamily, hospitality, industrial, residential, healthcare, life sciences, and self-storage sectors. The Fund concentrates investments in the real estate industry, meaning that under normal circumstances, it invests over 25% of its assets in real estate industry securities. The Fund may utilize leverage through borrowing for investment purposes or to satisfy repurchase requests. The Fund currently borrows money under two credit facilities.
The Fund defines real estate industry securities to include the common stock, partnership or similar interests, asset-backed securities, preferred stock, and secured or unsecured debt. Real estate industry securities may be issued by a wide variety of entities including: private real estate investment funds managed by institutional investment managers (“Institutional Investment Funds”); non-traded unregistered real estate investment trusts (“Private REITs”); publicly traded real estate investment trusts or other similar companies (“Public REITs”); Government Sponsored Entities (“GSEs”) such as Federal Home Loan Mortgage Corporation Structured Pass-Through Certificates (“K-Notes”), exchange traded funds, index mutual funds, and other investment vehicles such as closed-end funds and mutual funds that invest principally, directly or indirectly, in real estate (collectively, “Other Public Investment Vehicles”) and unregistered funds that invest principally in real estate.
The Fund may invest in issuers of real estate industry securities of any credit quality; including fixed-income and preferred securities rated less than investment grade that are sometimes referred to as high yield or “junk bonds.” The Fund may invest in debt securities of any duration or maturity. The Fund may also, to a limited extent, make real estate-related investments other than through real estate industry securities. The Advisor or RREEF will sell a security when other securities are available that offer higher expected current income, higher expected long-term capital appreciation, lower volatility or lower correlation to broader securities markets or a combination of the preceding.
The Fund’s SAI contains a list of the fundamental (those that may not be changed without a shareholder vote) and non-fundamental (if any) investment policies of the Fund under the heading “Investment Objective and Policies.”
Fund’s Target Investment Portfolio
The Advisor executes the Fund’s real estate investment strategy primarily through a strategic combination of global ‘best in class’ Institutional Investment Funds, publicly traded real estate securities, and real estate related debt investments. The Fund will not invest more than 10% of the Fund’s assets in private funds employing hedging strategies (commonly known as “hedge funds”, i.e., investment funds that would be investment companies but for the exemptions under Rule 3(c)(1) or 3(c)(7) under the 1940 Act).
The Advisor has retained Mercer to provide ongoing research and investment opinions of and/or recommendations of institutional investment managers using the Mercer’s proprietary screening process, which applies multiple factors based on quantitative and qualitative assessment of the management team and track record. The Advisor has engaged RREEF to invest a portion of the Fund’s portfolio, generally less than 20%, in publicly traded real estate securities (Public REITs and Other Public Investment Vehicles). RREEF selects securities to seek to maximize risk-adjusted returns by managing volatility and identifying securities that are priced inefficiently relative to its assessment of intrinsic value.
Institutional Investment Funds. Institutional Investment Funds are real estate investment funds managed by institutional investment managers with expertise in managing portfolios of real estate and real estate-related securities. Many Institutional Investment Funds have large minimum investment requirements and stringent investor qualification criteria intended to limit their direct investors to mainly institutions such as endowments and pension funds. It is the intent of the Fund to provide an element of the endowment model of investing to individual investors by permitting access to a portfolio of Institutional Investment Funds with diversification across multiple strategies, managers and sectors.
9 |
The Advisor also believes that the Fund may provide an additional benefit in terms of better fee pricing from the Institutional Investment Funds as a result of volume discounts, which pricing benefits may not otherwise be permitted or available to other investors. In addition, the Fund’s investments in Institutional Investment Funds are intended to deliver returns that have a low correlation to the broader markets.
The Fund’s typical investments in Institutional Investment Funds will be made through the purchase of common stock, limited liability company units, or limited partnership interests (or similar interests). Investment criteria will include evaluating a combination of strength of the sponsor and management; prior investment performance of the target fund as well as the performance of other funds managed by the sponsor; the attractiveness of the property sectors and geographical allocations of the fund; expected stability of income; expected capital appreciation, and target leverage levels.
REITs. The Fund may invest, directly or indirectly, in Real Estate Investment Trusts (“REITs”). REITs are investment vehicles that invest primarily in income-producing real estate or mortgages and other real estate-related loans or interests. Public REITs are listed on major stock exchanges such as the New York Stock Exchange (“NYSE”) or the National Association of Securities Dealers Automated Quotation System (“NASDAQ”), and invest directly in real estate, typically through either properties or mortgages.
Other Public Investment Vehicles. The Fund anticipates making limited investments in Other Public Investment Vehicles, including ETFs and Index Funds that invest primarily in real estate related assets, principally to temporarily invest the Fund’s capital pending its deployment into other higher-returning investment opportunities, or for temporary defensive purposes under adverse market conditions.
Exchange Traded Funds (“ETFs”). ETFs are typically managed by professionals and provide investors with diversification, cost and tax efficiency, liquidity, marginability, are useful for hedging, have the ability to go long and short, and some provide quarterly dividends. An ETF typically holds a portfolio of securities or contracts designed to track a particular market segment or index. ETFs are listed on major stock exchanges and are traded like stocks.
Index Funds. An Index Fund is a mutual fund with an investment objective of seeking to replicate the performance of a specific securities index, such as the National Association of Real Estate Investment Trusts (NAREIT) Index or the MSCI REIT Index. Most Index Funds are not actively managed and generally provide broad market exposure, low operating expenses and low portfolio turnover.
Other. In addition to ETFs and Index Funds, and subject to the Fund’s investment restrictions, the Fund may invest in investment companies that invest primarily in what the Advisor considers real estate industry securities, including closed-end funds and mutual funds. Shares of Closed-end Funds are typically listed for trading on major stock exchanges and, in some cases, may be traded in other over-the-counter markets.
Real Estate Related Debt Investments. The Fund may invest in real estate related direct debt including first and second mortgage loans, mezzanine loans and other structured debt investments.
Investment Strategy, and Criteria Used by the Advisor and Mercer in Selecting Investments
The Fund’s investment strategy focuses primarily on identifying Institutional Investment Funds that have:
|
● |
attractive risk-adjusted returns; |
|
● |
with low to moderate volatility; |
|
● |
low correlation to the broader markets; and |
|
● |
an emphasis on income generation. |
The Fund utilizes a comprehensive multi-manager, multi-sector, and multi-strategy approach. The Advisor primarily selects funds with the highest expected risk-adjusted returns from a real estate sector peer group of issuers with similar market capitalization and/or credit quality. Secondarily, the Advisor considers potential for capital appreciation. When constructing and balancing the Fund’s portfolio, the Advisor selects funds from real estate sectors that it believes have relatively low volatility and will not be highly correlated to each other or to the equity or fixed income markets, generally.
The Advisor, working closely with Mercer and in consideration of its recommendations, uses both a quantitative screening process and a qualitative selection process when selecting investments for the Fund to implement its real estate investment strategy. The Advisor and Mercer conduct research on various real estate investment managers and investment options in order to establish a selection of investments to fulfill the Fund’s investment objectives. Mercer’s assistance and recommendations for selection of investment funds are made according to asset allocation, return expectations and other guidelines set by the Advisor with oversight of the Board. No assurance can be given that any or all investment strategies, or the Fund’s investment program, will be successful.
Investment Strategy – Mercer Process
Mercer’s process begins with a proprietary database created and continuously maintained by its professionals - the Global Investment Manager Database (GIMD™) which gives Mercer access to up-to-date information and insights on a worldwide matrix of investment managers and strategies. GIMD™ contains information on numerous investment types across all asset classes, including real estate. This information ranges from access to and analysis of performance data to qualitative forward-looking research on investment managers supported by screening functionality. In the twelve months leading up to September 30, 2024, over 2,700 formal manager meetings were held and over 3,600 Research Reports were produced globally. As of September 30, 2024, GIMD™ contained information on over 6,800 investment managers and over 32,300 investment strategies.
10 |
Mercer, together with its global investment management affiliates, have over 3,300 delegated clients globally.
The Advisor has entered into a Sub-Advisory Agreement with Mercer Investments LLC (“Mercer” or a “Sub-Advisor”), 99 High Street, Boston, MA 02110.

The Advisor, in conjunction with Mercer, employs a regimen of quantitative and qualitative criteria to arrive at a universe of investments which are considered to be ‘best in class.’ By combining historical quantitative analysis with a sound knowledge of key qualitative attributes, the Advisor will evaluate a prospective investment’s potential for generating sustainable, positive, risk-adjusted returns under a wide variety of market conditions. Mercer’s investment selection and due diligence process are outlined in the chart below.

On-going monitoring of the Fund’s investments will be utilized to assist the Advisor in maintaining portfolio allocations and managing cash in-flows and outflows. The Advisor may strategically rebalance its investment strategies according to the current market conditions, but will remain true to its fundamental analysis with respect to real estate asset class and sector risk over time. The
11 |
Advisor manages investments over a long-term time horizon while being mindful of the historical context of the markets. Mercer will provide to the Advisor investment performance reporting and analysis, including discussions on investment strategy, portfolio construction, and market update reports. The illustration below further outlines this monitoring process.

Investment Strategy - Multi-Manager Diversification
The Fund intends to employ a Multi-Manager approach by identifying and investing with ‘best in class’ institutional asset managers with expertise in managing portfolios of real estate and real estate-related securities. The term ‘best in class’ refers to Institutional Investment Funds that the Advisor and Mercer have identified through Mercer’s proprietary screening process as having above average prospects.
Many of the Institutional Investment Funds have large minimum investment size and stringent investor qualification criteria intended to limit their direct investors to mainly institutions such as endowments and pension funds. As such, the Fund enables investors to invest with institutional investment managers that may not be otherwise permitted or available to them.
The Fund also enables investors to execute a comprehensive multi-strategy, multi-manager, multi-sector strategy by making a single investment in its shares, whereas due to the large minimums of many of the Institutional Investment Funds, such a strategy may not otherwise be permitted or available to the investor.
The sponsor believes that the Fund may provide an additional benefit in terms of lower fees from the Institutional Investment Funds as a result of volume discounts, which pricing benefits may not otherwise be permitted or available to them.
Investment Strategy - Multi-Strategy Diversification
The Fund intends to employ a Multi-Strategy approach to diversify the risk-reward profiles and the underlying types of real estate in which it invests, with the strategies noted below. Because each real estate strategy performs differently throughout the overall real estate and economic cycle, investment strategies that include multiple strategies generally have lower volatility than single strategy funds. Thus, a multi-strategy approach should assist the Fund in achieving its objective of lower portfolio volatility as well as lower correlation with the broader markets.
|
● |
Core. The Fund’s ‘core’ strategy targets high-quality portfolios with real estate assets that provide relatively lower and more stable returns. Such investments are typically located in primary markets and in the main property types (retail, office, industrial and multi-family). Properties are stable, well-maintained, well-leased and often of the Class A variety. For example, office properties, including life sciences, tend to be Class A buildings with investment grade tenants. Multifamily properties are usually in major metropolitan cities with higher rental rates. Retail would typically be more traditional neighborhood and community strip-mall centers, as well as regional and super regional malls. The Advisor believes that warehouse and research and development properties in strong distribution centers typically offer better chances for predictable cash flow within the industrial sector. As an example, a Class A office property may broadly be defined as 100,000 square feet or larger (five or more floors), concrete and steel construction, recently built and/or very well maintained (excellent condition), with business/support amenities and in a strong identifiable location with good access to a primary metropolitan market. Class A properties are the most prestigious buildings competing for premier tenants with rents above average for the area. |
|
● |
Core Plus. The Fund’s ‘core plus’ strategy seeks moderate risk portfolios with real estate that provides moderate returns. Such investments are predominantly core but with an emphasis on a modest value add management approach. A core plus portfolio requires slightly more complex financial structuring and management intensive focus than a core portfolio of investments. Focus is on the main property types, in both primary and secondary markets, in Class A or lower quality buildings that require some form of enhancement (i.e. repositioning, redevelopment and/or releasing). In comparison to the Class A example above, a Class B property may be renovated and/or in good condition, potentially smaller in size, in a good location in a primary or secondary metropolitan market. Class B properties compete for a wide range of users with rents in the average range for the area. |
12 |
|
● |
Value Add. The Fund’s ‘value add’ strategy typically focuses on more aggressive active asset management and often employs more leverage. Such investments typically are lower quality buildings, in both primary and secondary markets in the main property types or development projects. Properties are considered value add when they exhibit management or operational problems, require physical improvement, and/or suffer from capital constraints. Buildings often require enhancement to upgrade them to higher quality properties (i.e., redevelopment/repositioning/re-tenanting). |
Investment Strategy - Multi-Sector Diversification
The Fund intends to employ a Multi-Sector approach to diversify its investments by property type or sector - for example, across retail, office, multifamily, hospitality, industrial, residential, healthcare, life sciences and/or self-storage sectors. Because each real estate sector has its own investment cycle, correlations across property types are generally low. Thus, employing a multi-sector approach should assist the Fund in achieving its objective of low to moderate volatility as well as low correlation to the broader markets.
Additional Information Regarding Investment Strategy
The Fund may, from time to time, in attempting to respond to adverse market, economic, political or other similar conditions, take temporary defensive positions that are inconsistent with the Fund’s principal investment strategy. During such times, the Advisor may determine that the Fund should invest up to 100% of its assets in cash or cash equivalents, including money market instruments, prime commercial paper, repurchase agreements, Treasury bills and other short-term obligations of the U.S. Government, its agencies or instrumentalities. In addition to the foregoing, the Fund may utilize Other Public Investment Vehicles as temporary investments as the Fund raises capital or pending deployment of capital to other investment opportunities selected by the Advisor. In these and in other cases, the Fund may not achieve its investment objective. The Advisor may invest the Fund’s cash balances in any investments it deems appropriate. The Advisor expects that such investments will be made, without limitation and as permitted under the 1940 Act, in money market mutual funds, repurchase agreements, U.S. Treasury and U.S. agency securities, municipal bonds and bank accounts. Any income earned from such investments is ordinarily reinvested by the Fund in accordance with its investment program. Many of the considerations entering into recommendations and decisions of the Advisor and the Fund’s Portfolio Managers are subjective.
The frequency and amount of portfolio purchases and sales (known as the “portfolio turnover rate”) will vary from year to year. The portfolio turnover rate is not expected to exceed 100%, but may vary greatly from year to year and will not be a limiting factor if the Advisor determines that portfolio changes are appropriate. Although the Fund generally does not intend to trade for short-term profits, the Fund may engage in short-term trading strategies, and securities may be sold without regard to the length of time held when, in the opinion of the Advisor, investment considerations warrant such action. These policies may have the effect of increasing the annual rate of portfolio turnover of the Fund. Higher rates of portfolio turnover would likely result in higher brokerage commissions and may generate short-term capital gains taxable as ordinary income. If securities are not held for the applicable holding periods, dividends paid on them will not qualify for the advantageous federal tax rates. See “Tax Status” in the Fund’s SAI.
There is no assurance what portion, if any, of the Fund’s investments will qualify for the reduced federal income tax rates applicable to qualified dividends under the Code. As a result, there can be no assurance as to what portion of the Fund’s distributions will be designated as qualified dividend income. See “U.S. Federal Income Tax Matters.”
Investment Strategy and Criteria Used by RREEF in Selecting Public Real Estate Securities
The Advisor with RREEF has developed an investment strategy intended to maximize risk-adjusted returns by managing volatility and identifying securities that are priced inefficiently relative to RREEF’s assessment of intrinsic value. RREEF believes that real estate security performance is reflective of the underlying real estate portfolio and, therefore, over time will be driven by the pricing and fundamentals of their assets. The risk management process is highly focused on quantitative risk factors as well as fundamental portfolio risk factors. RREEF’s investment universe encompasses over 100 property companies in the United States with a total market capitalization of over $800 billion. RREEF is focused on companies that derive the majority of their operating income or asset base from commercial real estate (apartments, office, industrial, storage, hotels, retail, net lease). Operating and capital efficiency are critically important to a successful real estate company and hence RREEF typically focuses on companies with large, high quality asset bases. If there are securities outside of this group that meet these criteria, RREEF will include these as part of the investable universe. The investment universe is generally defined as all REITs and REOCs (real estate operating companies) with an equity market capitalization of at least $200 million that derive the majority of revenue or net asset value (NAV) from an equity interest in real estate activities. The U.S. real estate securities portion of the Fund’s portfolio managed by RREEF typically holds between 35-50 securities. Under normal circumstances, such securities will generally comprise between 5% and 20% of the Fund’s portfolio. With respect to any investments in non-publicly traded real estate related debt securities, the Advisor makes all investment decisions.
RISK FACTORS
An investment in the Fund’s shares is subject to risks. The value of the Fund’s investments will increase or decrease based on changes in the prices of the investments it holds. This will cause the value of the Fund’s shares to increase or decrease. You could lose money by investing in the Fund. By itself, the Fund does not constitute a balanced investment program. Before investing in the Fund you should consider carefully the following risks. There may be additional risks that the Fund does not currently foresee or consider material. You may wish to consult with your legal or tax advisors before deciding whether to invest in the Fund.
Real Estate Industry Concentration Risk. Because the Fund will concentrate its investments in real estate related securities, its portfolio will be significantly impacted by the performance of the real estate market and may experience more volatility and be exposed to greater risk than a more diversified portfolio. In addition, the Fund may invest in real estate equity or debt and therefore may be subject to risks similar to those associated with direct investment in real property. The value of the Fund’s shares will be affected by factors affecting the value of real estate and the earnings of companies engaged in the real estate industry. These factors
13 |
include, among others: (i) changes in general economic and market conditions; (ii) changes in the value of real estate properties; (iii) risks related to local economic conditions, overbuilding and increased competition; (iv) increases in property taxes and operating expenses; (v) changes in zoning laws; (vi) casualty and condemnation losses; (vii) variations in rental income, neighborhood values or the appeal of property to tenants; (viii) the availability of financing; (ix) climate change and (x) changes in interest rates. Many real estate companies utilize leverage, which increases investment risk and could adversely affect a company’s operations and market value in periods of rising interest rates. The value of securities of companies in the real estate industry may go through cycles of relative under-performance and over-performance in comparison to equity securities markets in general.
There are also special risks associated with particular sectors, or real estate operations, including, but not limited to, those risks described below:
Retail Properties. Retail properties are affected by the overall health of the economy and may be adversely affected by, among other things, the growth of alternative forms of retailing, bankruptcy, departure or cessation of operations of a tenant, a shift in consumer demand due to demographic changes, changes in spending patterns and lease terminations.
Office Properties. Office properties are affected by the overall health of the economy, and other factors such as a downturn in the businesses operated by their tenants, obsolescence and non-competitiveness.
Industrial Properties. Industrial properties are affected by the overall health of the economy and other factors such as downturns in the manufacturing, processing and shipping of goods.
Hospitality Properties. The risks of hotel, motel and similar hospitality properties include, among other things, the necessity of a high level of continuing capital expenditures, competition, increases in operating costs which may not be offset by increases in revenues, dependence on business and commercial travelers and tourism, increases in fuel costs and other expenses of travel, and adverse effects of general and local economic conditions. Hotel properties tend to be more sensitive to adverse economic conditions and competition than many other commercial properties.
Healthcare and Life Sciences Properties. Healthcare and life sciences properties and healthcare providers are affected by several significant factors, including federal, state and local laws governing licenses, certification, adequacy of care, pharmaceutical distribution, rates, equipment, personnel and other factors regarding operations, funding for biotech companies, continued availability of revenue from government reimbursement programs and competition on a local and regional basis. The failure of any healthcare operator to comply with governmental laws and regulations may affect its ability to operate its facility or receive government reimbursements.
Multifamily Properties. The value and successful operation of a multifamily property may be affected by a number of factors such as the location of the property, the ability of the management team, the level of mortgage interest rates, the presence of competing properties, adverse economic conditions in the locale, oversupply and rent control laws or other laws affecting such properties.
Residential Properties. Residential properties can be significantly affected by the national, regional and local real estate markets. This segment of the real estate industry also is sensitive to interest rate fluctuations which can cause changes in the availability of mortgage capital and directly affect the purchasing power of potential homebuyers. Thus, residential properties can be significantly affected by changes in government spending, consumer confidence, demographic patterns and the level of new and existing home sales.
Shopping Centers. Shopping center properties are dependent upon the successful operations and financial condition of their tenants, particularly certain of their major tenants, and could be adversely affected by bankruptcy of those tenants. In some cases, a tenant may lease a significant portion of the space in one center, and the filing of bankruptcy could cause significant revenue loss, including the loss of revenue from smaller tenants with co-tenancy rights. Like others in the commercial real estate industry, community centers are subject to environmental risks and interest rate risk. They also face the need to enter into new leases or renew leases on favorable terms to generate rental revenues. Community center properties could be adversely affected by changes in the local markets where their properties are located, as well as by adverse changes in national economic and market conditions.
Self-Storage Properties. The value and successful operation of a self-storage property may be affected by a number of factors, such as the ability of the management team, the location of the property, the presence of competing properties, changes in traffic patterns and effects of general and local economic conditions with respect to rental rates and occupancy levels.
Other factors may contribute to the risk of real estate investments:
Development Issues. Certain real estate companies in which the Fund directly or indirectly invests (“portfolio companies”) may engage in the development or construction of real estate properties. Portfolio companies are exposed to a variety of risks inherent in real estate development and construction, such as the risk that there will be insufficient tenant demand to occupy newly developed properties, and the risk that prices of construction materials or construction labor may rise materially during the development.
Lack of Insurance. Certain of the portfolio companies in the Fund’s portfolio may fail to carry comprehensive liability, fire, flood, earthquake extended coverage and rental loss insurance, or insurance in place may be subject to various policy specifications, limits and deductibles. Due to the prevalence of catastrophic events, the cost of insurance may increase materially. Should any type of uninsured loss occur, the portfolio company could lose its investment in, and anticipated profits and cash flows from, a number of properties and, as a result, adversely affect the Fund’s investment performance.
14 |
Dependence on Tenants. The value of the Fund’s portfolio companies’ properties and the ability of these companies to make distributions to their shareholders depends upon the ability of the tenants at the properties to generate enough income in excess of their tenant operating expenses to make their lease payments. Changes beyond the control of our portfolio companies may adversely affect their tenants’ ability to make their lease payments and, in such event, would substantially reduce both their income from operations and ability to make distributions to our portfolio companies and, consequently, the Fund.
Financial Leverage. Companies in the real estate industry may be highly leveraged and financial covenants may affect their ability to operate effectively. The use of floating rate loans may also negatively impact returns in a rising interest rate environment.
Environmental Issues. In connection with the ownership (direct or indirect), operation, management and development of real properties that may contain hazardous or toxic substances, a portfolio company may be considered an owner, operator or responsible party of such properties and, therefore, may be potentially liable for removal or remediation costs, as well as certain other costs, including governmental fines and liabilities for injuries to persons and property. The existence of any such material environmental liability could have a material adverse effect on the results of operations and cash flow of any such portfolio company and, as a result, the amount available to make distributions on shares of the Fund could be reduced. Environmental risk from high winds, hurricanes, fires, flood and extreme heat may also materially affect a property’s value.
Credit Market Conditions. Instability in credit markets can potentially make it more difficult for borrowers to obtain financing or refinancing on attractive terms or at all. Conditions in the credit markets may expose borrowers to increased interest expenses for borrowed money and tightening underwriting standards. There is also a risk that a general lack of liquidity or other events in the credit markets may adversely affect the ability of issuers in whose securities the Fund invests to finance real estate developments and projects or refinance completed projects.
This may also adversely affect the price at which portfolio companies can sell real estate, because purchasers may not be able to obtain financing on attractive terms or at all. These developments may potentially adversely affect the broader economy, which in turn may adversely affect the real estate markets. Additionally, such developments could reduce the Fund’s investment opportunities.
Market Risk. An investment in shares is subject to investment risk, including the possible loss of the entire principal amount invested. An investment in shares represents an indirect investment in the securities owned by the Fund. The value of these securities, like other market investments, may move up or down, sometimes rapidly and unpredictably. In addition, the Fund is subject to the risk that geopolitical and other similar events will disrupt the economy on a national or global level. For instance, war, terrorism, market manipulation, government defaults, government shutdowns, political changes or diplomatic developments, public health emergencies (such as the spread of infectious diseases, pandemics and epidemics) and natural/environmental disasters can all negatively impact the securities markets.
Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. The foregoing could impair the Fund’s ability to maintain operational standards, disrupt the operations of the Fund and its service providers, adversely affect the performance, value and liquidity of the Fund’s investments, and negatively impact the Fund’s performance and your investment in the Fund. The value of your shares at any point in time may be worth less than the value of your original investment, even after taking into account any reinvestment of dividends and distributions.
Liquidity Risk. The Fund is a closed-end investment company structured as an “interval fund” and is designed for medium to long-term investors. Unlike many closed-end investment companies, the Fund’s shares are not listed on any securities exchange and are not publicly traded. There currently is no secondary market for the shares and the Advisor does not expect that a secondary market will develop. Limited liquidity is provided to shareholders only through the Fund’s quarterly repurchase offers for no less than 5% of the Fund’s shares outstanding at per-class net asset value. There is no guarantee that shareholders will be able to sell all of the shares they desire in a quarterly repurchase offer. Since inception, the Fund has made 44 repurchase offers, 37 have resulted in the repurchase of all shares, seven have resulted in the repurchase of less than all shares tendered. The Fund’s investments are also subject to liquidity risk. Liquidity risk exists when particular investments of the Fund would be difficult to purchase or sell, possibly preventing the Fund from selling such illiquid securities at an advantageous time or price, or possibly requiring the Fund to dispose of other investments at unfavorable times or prices in order to satisfy its obligations. Funds with principal investment strategies that involve securities of companies with smaller market capitalizations, derivatives or securities with substantial market and/or credit risk tend to have the greatest exposure to liquidity risk.
Allocation Risk. The ability of the Fund to achieve its investment objective depends, in part, on the ability of the Advisor or RREEF to allocate effectively the Fund’s assets among the various Institutional Investment Funds, Private REITs, Public REITs and Other Public Investment Vehicles in which the Fund invests and, with respect to each such asset class, among equities and fixed income securities. There can be no assurance that the actual allocations will be effective in achieving the Fund’s investment objectives or delivering positive returns.
Correlation Risk. The Fund seeks to produce returns that are not correlated to the broader financial markets. Although the prices of equity securities and fixed-income securities, as well as other asset classes, often rise and fall at different times so that a fall in the price of one may be offset by a rise in the price of the other, in down markets the prices of these securities and asset classes can also fall in tandem. Because the Fund allocates its investments among different asset classes, the fund is subject to correlation risk.
Credit Risk. There is a risk that debt issuers will not make payments, resulting in losses to the Fund. In addition, the credit quality of securities may be lowered if an issuer’s financial condition changes. Lower credit quality may lead to greater volatility in the price of a security and in shares of the Fund. Lower credit quality also may affect liquidity and make it difficult to sell the security. Default,
15 |
or the market’s perception that an issuer is likely to default, could reduce the value and liquidity of securities, thereby reducing the value of your investment in Fund shares. In addition, default may cause the Fund to incur expenses in seeking recovery of principal or interest on its portfolio holdings.
Distribution Policy Risk. The Fund’s distribution policy is expected to result in distributions that equal a fixed percentage of the Fund’s current net asset value per share. Shareholders receiving periodic payments from the Fund may be under the impression that they are receiving net profits. However, all or a portion of a distribution may consist of a return of capital. Return of capital is the portion of a distribution that is a return of your original investment dollars in the Fund. Shareholders should not assume that the source of a distribution from the Fund is net profit. Shareholders should note that return of capital will reduce the tax basis of their shares and potentially increase the taxable gain, if any, upon disposition of their shares.
Fixed Income Risk. When the Fund invests in fixed income securities, the value of your investment in the Fund will fluctuate with changes in interest rates. Typically, a rise in interest rates causes a decline in the value of fixed income securities. In general, the market price of debt securities with longer maturities will increase or decrease more in response to changes in interest rates than shorter-term securities. Recently, interest rates have risen sharply after maintaining historically low levels for a significant period of time. Current conditions may result in an increase in interest rate volatility, which in turn may result in a decline in the value of the fixed income investments held by the Fund. As a result, for the present, interest rate risk may be heightened. Other risk factors include credit risk (the debtor may default) and prepayment risk (the debtor may pay its obligation early, reducing the amount of interest payments). These risks could affect the value of a particular investment, possibly causing the Fund’s share price and total return to be reduced and fluctuate more than other types of investments.
Institutional Investment Fund Risk. The Fund’s investment in Institutional Investment Funds will require it to bear a pro rata share of the vehicles’ expenses, including management and performance fees. The fees the Fund pays to invest in an Institutional Investment Fund may be higher than if the manager of the Institutional Investment Fund, managed the Fund’s assets directly. The incentive fees charged by certain Institutional Investment Funds may create an incentive for its manager to make investments that are riskier and/or more speculative than those it might have made in the absence of an incentive fee. The Funds are not publicly traded and therefore may not be as liquid as other types of investments. Furthermore, Institutional Investment Funds, like the other Underlying Funds in which the Fund may invest, are subject to specific risks, depending on the nature of the vehicle and also may employ leverage such that their returns are more than one times that of their benchmark which will amplify losses suffered by the Fund when compared to unleveraged investments. For example, these Funds need not have independent boards, shareholder approval of advisory contracts may not be required, may leverage to an unlimited extent, and may engage in joint transactions with affiliates.
Issuer and Non-Diversification Risk. The value of a specific security can be more volatile than the market as a whole and can perform differently from the value of the market as a whole. As a non-diversified fund, the Fund may invest more than 5% of its total assets in the securities of one or more issuers. The Fund’s performance may be more sensitive to any single economic, business, political or regulatory occurrence than the value of shares of a diversified investment company. The value of an issuer’s securities that are held in the Fund’s portfolio may decline for a number of reasons which directly relate to the issuer, such as management performance, financial leverage and reduced demand for the respective properties and services.
Lack of Control Over Institutional Investment Funds and Other Portfolio Investments. Once the Advisor or RREEF has selected an Underlying Fund for investment by the Fund, the Advisor and RREEF will have no control over the investment decisions made by any such Underlying Fund. Although the Advisor or RREEF will evaluate regularly each Underlying Fund and its manager to determine whether their respective investment programs are consistent with the Fund’s investment objective, the Advisor and RREEF will not have any control over the investments made by any Underlying Fund. Even though the Underlying Funds are subject to certain constraints, the managers may change aspects of their investment strategies. The managers may do so at any time (for example, such change may occur immediately after providing the Advisor with the quarterly unaudited financial information for an Institutional Investment Fund). The Advisor or RREEF may reallocate the Fund’s investments among the Underlying Funds, but the Advisor’s ability to do so may be constrained by the withdrawal limitations imposed by certain Underlying Funds, which may prevent the Fund from reacting rapidly to market changes should an Underlying Fund fail to effect portfolio changes consistent with such market changes and the demands of the Advisor. Such withdrawal limitations may also restrict the Advisor’s ability to terminate investments in Underlying Funds that are poorly performing or have otherwise had adverse changes. The Advisor and RREEF will be dependent on information provided by the Underlying Fund, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s or RREEF’s ability to manage the Fund’s investment portfolio in accordance with its investment objectives.
Leveraging Risk. The use of leverage, such as borrowing money to purchase securities or otherwise invest the Fund’s assets, will cause the Fund to incur additional expenses and may significantly magnify the Fund’s losses in the event of adverse performance of the Fund’s underlying investments. In addition to any borrowing utilized by the Fund, the Underlying Funds in which the Fund invests may utilize leverage, subject to the limitations of their charters and operative documents. Leverage by Underlying Funds and/or the Fund has the effect of potentially increasing losses. In addition, interest rates (including benchmarks like SOFR and the spreads to such benchmarks charged by lenders) are highly sensitive to external factors outside a borrower’s control, including general and local economic conditions (such as inflation, recession, money supply and unemployment) and the monetary and fiscal policies of various governmental agencies such as the Federal Reserve Board. During periods of increased interest rates, borrowing costs of the Fund will likely increase and may adversely affect the Fund’s performance.
Management Risk. The net asset value of the Fund changes daily based on the performance of the securities in which it invests. The Advisor’s or a Sub-Advisor’s judgments about the attractiveness, value and potential appreciation of particular real estate segment and securities in which the Fund invests may prove to be incorrect and may not produce the desired results.
16 |
Possible Competition Between Underlying Funds and Between the Fund and the Underlying Funds. The Underlying Funds trade independently of each other and may pursue investment strategies that “compete” with each other for execution or that cause the Fund to participate in positions that offset each other (in which case the Fund would bear its pro rata share of commissions and fees without the potential for a profit). Also, the Fund’s investments in any particular Underlying Fund could increase the level of competition for the same trades that other Underlying Funds might otherwise make, including the priorities of order entry. This could make it difficult or impossible to take or liquidate a position in a particular security at a price consistent with the Advisor’s or a Sub-Advisor’s strategy.
Preferred Securities Risk. There are various risks associated with investing in preferred securities, including credit risk, interest rate risk, deferral and omission of distributions, subordination to bonds and other debt securities in a company’s capital structure, limited liquidity, limited voting rights and special redemption rights. Interest rate risk is, in general, that the price of a debt security falls when interest rates rise. Securities with longer maturities tend to be more sensitive to interest rate changes. Credit risk is the risk that an issuer of a security may not be able to make principal and interest or dividend payments on the security as they become. Holders or preferred securities may not receive dividends, or the payment can be deferred for some period of time. In bankruptcy, creditors are generally paid before the holders of preferred securities.
REIT Risk. Investments (directly or indirectly) in REITs will subject the Fund to various risks. REIT share prices may decline because of adverse developments affecting the real estate industry and real property values. In general, real estate values can be affected by a variety of factors, including supply and demand for properties, the economic health of the country or of different regions, and the strength of specific industries that rent properties. REITs often invest in highly leveraged properties. Returns from REITs, which typically are small or medium capitalization stocks, may trail returns from the overall stock market. In addition, changes in interest rates may hurt real estate values or make REIT shares less attractive than other income-producing investments. REITs are also subject to heavy cash flow dependency, defaults by borrowers and self-liquidation.
Qualification as a REIT under the Internal Revenue Code of 1986, as amended, in any particular year is a complex analysis that depends on a number of factors. There can be no assurance that an entity in which the Fund invests with the expectation that it will be taxed as a REIT will, in fact, qualify as a REIT. An entity that fails to qualify as a REIT would be subject to a corporate level tax, would not be entitled to a deduction for dividends paid to its shareholders and would not pass through to its shareholders the character of income earned by the entity. If the Fund were to invest in an entity that failed to qualify as a REIT, such failure could significantly reduce the Fund’s yield on that investment. REITs can be classified as equity REITs, mortgage REITs and hybrid REITs. Equity REITs invest primarily in real property and earn rental income from leasing those properties. They may also realize gains or losses from the sale of properties. Equity REITs will be affected by conditions in the real estate rental market and by changes in the value of the properties they own. Mortgage REITs invest primarily in mortgages and similar real estate interests and receive interest payments from the owners of the mortgaged properties. Mortgage REITs will be affected by changes in creditworthiness of borrowers and changes in interest rates. Hybrid REITs invest both in real property and in mortgages. Equity and mortgage REITs are dependent upon management skills, may not be diversified and are subject to the risks of financing projects.
Dividends paid by REITs will not generally qualify for the reduced U.S. federal income tax rates applicable to qualified dividends under the Code. See “U.S. Federal Income Tax Matters.” The Fund’s investments in REITs may include an additional risk to shareholders. Some or all of a REIT’s annual distributions to its investors may constitute a non-taxable return of capital. Any such return of capital will generally reduce the Fund’s basis in the REIT investment, but not below zero. To the extent the distributions from a particular REIT exceed the Fund’s basis in such REIT, the Fund will generally recognize gain. In part because REIT distributions often include a nontaxable return of capital, Fund distributions to shareholders may also include a nontaxable return of capital. Shareholders that receive such a distribution will also reduce their tax basis in their shares of the Fund, but not below zero. To the extent the distribution exceeds a shareholder’s basis in the Fund’s shares, such shareholder will generally recognize a capital gain. The Fund does not have any investment restrictions with respect to investments in REITs.
Repurchase Policy Risks. Quarterly repurchases by the Fund of its shares typically will be funded from available cash or sales of portfolio securities. However, payment for repurchased shares may require the Fund to liquidate portfolio holdings earlier than the Advisor otherwise would liquidate such holdings, potentially resulting in losses, and may increase the Fund’s portfolio turnover. The Advisor may take measures to attempt to avoid or minimize such potential losses and turnover, and instead of liquidating portfolio holdings, may borrow money to finance repurchases of shares. If the Fund borrows to finance repurchases, interest on any such borrowing will negatively affect shareholders who do not tender their shares in a repurchase offer by increasing the Fund’s expenses and reducing any net investment income. To the extent the Fund finances repurchase proceeds by selling investments, the Fund may hold a larger proportion of its net assets in less liquid securities. Also, the sale of securities to fund repurchases could reduce the market price of those securities, which in turn would reduce the Fund’s net asset value.
Repurchase of shares will tend to reduce the number of outstanding shares and, depending upon the Fund’s investment performance, its net assets. A reduction in the Fund’s net assets may increase the Fund’s expense ratio, to the extent that additional shares are not sold. In addition, the repurchase of shares by the Fund may be a taxable event to shareholders.
Underlying Funds Risk. Other Public Investment Vehicles such as ETFs, Index Funds, closed-end funds, and mutual funds in which the Fund may invest are subject to investment advisory fees and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in such Underlying Funds and also may be higher than other funds that invest directly in securities. Underlying Funds are subject to specific risks, depending on the nature of the fund. The Fund’s performance depends in part upon the performance of the Underlying Fund managers and selected strategies, the adherence by such Underlying Fund managers to such selected strategies, the instruments used by such Underlying Fund managers and the Advisor’s or a Sub-Advisor’s ability to select Underlying Fund managers and strategies and effectively allocate Fund assets among them. Additionally, the market value of shares of Underlying Funds that are closed-end funds typically trade at a discount relative to their net asset value. This difference in price may be due to the fact that the supply and demand in the market for fund shares at any point in time is not always identical to the supply and demand in the market for the underlying basket of securities.
17 |
ETF shares may trade at a discount or a premium in market price if there is a limited market in such shares. Transactions in shares of closed-end funds and ETFs are also subject to brokerage and other trading costs, which could result in greater expenses to the Fund. Investments in pooled investment vehicles also may be illiquid, making it difficult for the Advisor to redeem the interest of the Fund in such vehicles in a reasonable amount of time.
Valuation of Institutional Investment Funds. While the valuations of the Fund’s investments in publicly-traded securities are more readily ascertainable, the Fund’s ownership interests in Institutional Investment Funds are not publicly traded and the Fund will depend on the institutional asset manager to a Private Investment Fund to provide a valuation of the Fund’s investment. Moreover, the valuation of the Fund’s investment in an Institutional Investment Fund, as provided by an institutional asset manager as of a specific date, may vary from the fair value of the investment that may be obtained if such investment were sold to a third party. For information about the value of the Fund’s investment in Institutional Investment Funds, the Advisor will be dependent on information provided by the Institutional Investment Funds, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s ability to accurately value the Fund’s shares.
MANAGEMENT OF THE FUND
Trustees and Officers
The Board is responsible for the overall management of the Fund, including supervision of the duties performed by the Advisor. The Board is comprised of five trustees. The Trustees are responsible for the Fund’s overall management, including adopting the investment and other policies of the Fund, electing and replacing officers and selecting and supervising the Fund’s investment advisor. The name and business address of the Trustees and officers of the Fund and their principal occupations and other affiliations during the past five years, as well as a description of committees of the Board, are set forth under “Management” in the Statement of Additional Information.
Investment Advisor
Bluerock Fund Advisors, LLC, located at 919 Third Avenue, 40th Floor, New York, NY 10022, serves as the Fund’s investment advisor. The Advisor is registered with the SEC as an investment advisor under the Advisers Act. The Advisor is a Delaware limited liability company formed on May 11, 2012.
Under the general supervision of the Fund’s Board, and pursuant to the terms of an Investment Management Agreement with the Fund, the Advisor will carry out the investment and reinvestment of the net assets of the Fund, will furnish continuously an investment program with respect to the Fund, and determine which securities should be purchased, sold or exchanged. In addition, the Advisor will supervise and provide oversight of the Fund’s service providers. The Advisor will furnish to the Fund office facilities, equipment and personnel for servicing the management of the Fund. The Advisor will compensate all Advisor personnel who provide services to the Fund. In return for these services, facilities and payments, the Fund has agreed to pay the Advisor, as compensation under the Investment Management Agreement, a monthly management fee computed at the annual rate of 1.50% of the daily net assets of the Fund. The Advisor may employ research services and service providers to assist in the Advisor’s market analysis and investment selection.
The Advisor and the Fund have entered into an expense limitation and reimbursement agreement (the “Expense Limitation Agreement”) under which the Advisor has agreed contractually to waive its fees and to pay or absorb the ordinary operating expenses (excluding any taxes, interest, brokerage commissions, acquired fund fees and expenses, and extraordinary expenses, such as litigation or reorganization costs, but including organizational costs and offering costs), to the extent that such expenses exceed 2.20% per annum of the Fund’s average daily net assets attributable to Class L shares (the “Expense Limitation”). In consideration of the Advisor’s agreement to limit the Fund’s expenses, the Fund has agreed to repay the Advisor in the amount of any fees the Advisor previously waived or Fund expenses reimbursed, subject to the limitations that: (1) the reimbursement will be made if payable not more than three years from the date incurred; (2) the reimbursement may not be made if it would cause the Expense Limitation then in effect or in effect at the time of the waiver to be exceeded; and (3) the reimbursement is approved by the Board. The Expense Limitation Agreement will remain in effect, at least until January 31, 2026, unless and until the Board approves its modification or termination. This agreement may be terminated only by the Board on 60 days written notice to the Advisor. After January 31, 2026, the Expense Limitation Agreement may be renewed at the Advisor’s and Board’s discretion.
A discussion regarding the basis for the Board’s approval of each of the Fund’s Investment Management Agreement with the Advisor and Sub-Advisory Agreements with Mercer and RREEF is available annually in the Fund’s March 31 semi-annual report to shareholders.
Affiliated Brokerage
Bluerock Capital Markets, LLC (“BCM”), a registered broker-dealer and an affiliate of the Advisor, is paid a portion of the sales load, up to 0.75% of the offering price, charged on the sale of Class L shares.
Advisor’s Investment Committee
The Advisor has established an Investment Committee comprised of five persons (the “Committee”) responsible for: setting overall investment policies and strategies of the Advisor; approval of Institutional Investment Funds being considered for investment by the Fund; establishing allocation targets for the investment portfolio of the Fund among the Institutional Investment Funds, Other Public Investment Vehicles and other entities in which the Fund intends to invest; and generally overseeing the activities of the Advisor’s Portfolio Managers (see below).
18 |
The members of the Committee, and their professional background and experience, are as follows:
R. Ramin Kamfar — Mr. Kamfar has served as a member of the Investment Committee and as Chairman of the Advisor since the inception of the Advisor in 2012. In addition, Mr. Kamfar is the founder of and serves as the Chairman and Chief Executive Officer of Bluerock Real Estate, LLC (“BRRE”), since its founding in October 2002. Mr. Kamfar served as Chairman and CEO of Bluerock Residential Growth REIT, a publicly traded REIT listed on the NYSE American (“BRG”), from its founding in 2009 until its sale in 2022. Mr. Kamfar currently serves as Chairman and CEO of Bluerock Homes Trust, a publicly traded REIT listed on the NYSE American (“BHM”) since its spin-off from BRG in 2022, as well as Chairman of Bluerock Asset Management, LLC since 2018. Mr. Kamfar started his career as an investment banker at Lehman Brothers Inc. in 1988, and has 30 years of experience in various aspects of real estate, mergers and acquisitions, private equity investing, investment banking, and public and private financings. Mr. Kamfar received an M.B.A. degree with distinction in Finance in 1988 from The Wharton School of the University of Pennsylvania and a B.S. degree with distinction in Finance in 1985 from the University of Maryland, College Park.
James G. Babb, III — Mr. Babb has served as a member of the Investment Committee since the inception of the Advisor in 2012. In addition, Mr. Babb has served in a variety of senior capacities, including his current role as Chief Strategy Officer, at BRRE, which he joined in 2007. Mr. Babb served as Chief Investment Officer of BRG from its founding in 2009 to 2020, as Chief Strategy Officer from 2020 until its sale in 2022 and as a Director of BRG from 2009 to 2014. Mr. Babb currently serves as Chief Strategy Officer of BHM. Mr. Babb was a founding principal of Starwood Capital Group (“Starwood”), a leading institutional real estate investment manager, where he helped lead the residential and office acquisitions initiatives from 1992 to 2003. During Mr. Babb’s tenure Starwood raised and invested funds on behalf of institutional investors through seven private real estate funds, and which in the aggregate ultimately invested approximately $8 billion in approximately 250 separate transactions. Mr. Babb also led Starwood’s efforts to expand its platform to invest in England and France. Mr. Babb received a B.A. degree in Economics in 1987 from the University of North Carolina, Chapel Hill.
Jordan B. Ruddy — Mr. Ruddy currently serves as Co-CIO of the Advisor and Portfolio Manager of the Fund. Mr. Ruddy has served as a member of the Investment Committee and as President of the Advisor since the inception of the Advisor in 2012. Mr. Ruddy also serves as president of Bluerock Asset Management, LLC. Mr. Ruddy served in several senior capacities of BRG from its founding in 2009 until its sale in 2022 and currently serves as President of BHM. Mr. Ruddy brings approximately 30 years of institutional real estate investment experience working with some of leading public and private firms in the industry. Prior to joining Bluerock, Mr. Ruddy served as a real estate investment banker at Banc of America Securities LLC, and at Smith Barney Inc. and at JP Morgan Chase (previously the Chase Manhattan Bank), and as Vice President of Amerimar Enterprises, a real estate company specializing in value-added investments nationwide. Mr. Ruddy received an M.B.A. degree in Finance and Real Estate in 1995 from The Wharton School of the University of Pennsylvania, and a B.S. degree with high honors in Economics in 1986 from the London School of Economics.
Ryan MacDonald — Mr. MacDonald has served as a member of the Investment Committee of the Advisor since January 2018. Mr. MacDonald currently serves as Chief Investment Officer for BHM and of BRRE and certain of its affiliates. Mr. MacDonald served in a variety of senior capacities for BRG, including Chief Investment Officer from 2020 until its sale. Since joining Bluerock in 2008, Mr. MacDonald is responsible for sourcing, underwriting, structuring, financing and closing of all of Bluerock’s real estate investments and dispositions. To date with Bluerock, Mr. MacDonald has been involved with real estate transactions with an aggregate value of approximately $11 billion. Prior to joining Bluerock, Mr. MacDonald was an Investment Analyst for PNC Realty Investors. Mr. MacDonald received a B.A. in Economics from the University of Maryland, College Park.
Adam Lotterman — Mr. Lotterman is co-founder of the Advisor and has been a key member of the Fund’s investment team since its inception in 2012. Mr. Lotterman currently serves as the Fund’s Senior Portfolio Manager, as well as the Advisor’s Co-Chief Investment Officer and Lead Economist. Prior to joining Bluerock, Mr. Lotterman was Vice President of Forman Capital, a private commercial real estate lender from 2011 to 2012. Mr. Lotterman was also an Adjunct Professor at Nova Southeastern University from 2010 to 2012, where he taught a master’s level course in Real Estate Market Analysis. Prior to that, Mr. Lotterman worked as a Senior Valuation Analyst at Bayview Asset Management (former hedge fund affiliate of The Blackstone Group) from 2010 to 2011, and from 2005 to 2010 Mr. Lotterman was the Senior Analyst for Goodkin Consulting, the former real estate consulting arm of PricewaterhouseCoopers. Mr. Lotterman received an M.S. in International Real Estate in 2006 from Florida International University, where he graduated first in class, and a B.S. Degree in microbiology with a minor in chemistry in 1997 from the University of Florida.
Advisor Portfolio Managers
Subject to the Committee’s oversight, Jordan B. Ruddy, a member of the Committee, and Adam Lotterman serve as the Fund’s Portfolio Managers and oversee the day-to-day investment operations of the Fund. Each has served as a Portfolio Manager to the Fund since October 2013.
Jordan B. Ruddy — Mr. Ruddy’s biographical information is presented above.
Adam Lotterman — Mr. Lotterman’s biographical information is presented above.
Tim Thran, CFA — Mr. Thran currently serves as Associate Portfolio Manager and Assistant Treasurer of the Fund. Mr. Thran joined Bluerock in 2017 and currently serves as a Managing Director of the Advisor. Mr. Thran works directly with the Fund’s Senior Portfolio Managers and is responsible for overseeing day-to-day investment operations and execution of the Fund’s strategy, including portfolio valuation, investment analysis, liquidity management and performance evaluation. Previously, Mr. Thran served at JPMorgan Asset Management from 2014 to 2016, directing daily oversight and controls on over $200 billion in retail mutual fund assets. From 2008 to 2014, Mr. Thran held multiple management roles at State Street Corporation, with a focus on accounting and compliance on the
19 |
company’s premier ETFs and mutual fund clients. Mr. Thran received an M.B.A. degree with a concentration in Investments from the D’Amore-McKim School of Business at Northeastern University and B.A. degrees in both Mathematics and Economics from the College of the Holy Cross. Mr. Thran is a CFA charterholder, CFA Institute.
Investment Sub-Advisor – Mercer
The Advisor has engaged Mercer Investments LLC, a registered adviser under the Advisers Act, to act as an investment sub-advisor. For more than 50 years, Mercer and its affiliates have provided global leadership in investment consulting and multi-manager fiduciary management, and is a leading advisor to sovereign wealth funds, pension plans, banks, family offices, insurance companies, endowments and foundations. Mercer, together with its affiliated investment businesses, have over 5,600 delegated and advisory clients globally with over $547 billion in assets under management as of September 30, 2024 and over $17.5 trillion in assets under advisement as of June 30, 2024. Asset under management reported here includes include aggregated assets for which Mercer Investments LLC (Mercer Investments) and their global affiliates providing discretionary investment management services as of the dates indicated. Assets under management is calculated differently from regulatory assets under management, which is reported in Form ADV and filed with the Securities and Exchange Commission.
Mercer is an affiliate of Mercer (US), LLC, a human resource and financial consulting company. Mercer (US), LLC has approximately $25,000+ employees as of September 30, 2024 based in more than 40 countries and serves over 36,000 clients worldwide and is a wholly owned subsidiary of Marsh & McLennan Companies (NYSE: MMC).
Investment Sub-Advisor – RREEF
The Advisor has engaged RREEF America L.L.C., a registered advisor under the Advisers Act, to provide investment management for a portion of the Fund’s portfolio, generally less than 20%. In addition, RREEF provides the Advisor with research and information that the Advisor uses to make investment decisions with respect to non-publicly traded real estate related debt securities. RREEF together with its affiliates in Europe and Asia, comprise the global real estate investment business of DWS, an indirect majority owned subsidiary of Deutsche Bank A.G. DWS’s real estate investment business, is one of the largest real estate investment managers globally with more than 330 professionals and staff located in 23 cities worldwide and approximately $78.9 billion in real estate and real estate-related assets under management as of September 30, 2024.
RREEF Portfolio Managers
Subject to the Advisor’s oversight, David W. Zonavetch, Bob Thomas, and John W. Vojticek serve as the Fund’s RREEF Portfolio Managers and oversee a portion of investment portfolio of the Fund. Mr. Zonavetch and Mr. Vojticek have served as a Portfolio Managers to the Fund since May 2016. Mr. Thomas has served as a Portfolio Manager to the Fund since January 2018.
David W. Zonavetch — Mr. Zonavetch has served as a Director and Co-Lead Portfolio Manager for RREEF since September 2013 and as Co-Lead Portfolio Manager - Real Estate Securities since February 2012. Previously, he served as Vice President and Portfolio Manager from February 2007 to February 2012. From February 2007 to February 2012, Mr. Zonavetch was a Vice President and Securities Analyst at RREEF Real Estate. He has nine years of experience in accounting and finance. From 1998 to 2001, Mr. Zonavetch served as a Senior Accountant in Corporate Finance of RREEF Real Estate, and from 2001 to 2003, he served as Securities Accounting Coordinator with RREEF Real Estate’s Securities Group, covering the office and self- storage sectors. From 1995 until joining RREEF Real Estate in 1998, Mr. Zonavetch worked as an analyst for Cendant Mobility Services Corp., a corporate employee relocation company. Mr. Zonavetch holds a B.S. in Finance from the University of Illinois at Urbana-Champaign and is a certified public accountant.
Bob Thomas — Mr. Thomas has served as a Managing Director and Co-Head of Americas Real Estate Securities, Alternatives for RREEF since 2017. He has 15 years of industry experience serving as lead portfolio manager of North America for global listed property funds at Henderson Global Investors from 2015 to 2016, he was co-lead portfolio manager of North America for global listed property funds at AMP Capital from 2012 to 2015, and as an analyst at Nuveen Asset Management from 2011 to 2012, at BNP Paribas Asset Management from 2005 to 2011 and at Security Capital Research & Management from 20014 to 2005. Mr. Thomas started his career as an investment banking analyst in the Real Estate group at KeyBanc Capital Markets in 2002. Mr. Thomas holds a B.A. in Economics from Duke University and an MBA in Finance, Management & Strategy from Kellogg School of Management, Northwestern University.
John W. Vojticek — Mr. Vojticek has served as a Managing Director and Chief Investment Officer of Real Estate & Infrastructure Securities and Global Portfolio Manager for RREEF since July 2011 and was Co-Head of Americas Real Estate Securities from 2006 to July 2011. Mr. Vojticek was responsible for launching the firm’s first listed infrastructure securities strategy in June 2008 and served as Head of the Listed Infrastructure Securities business from June 2008 until his appointment as Chief Information Officer in July 2011. Mr. Vojticek is an associate member of the National Association of Real Estate Investment Trusts. Mr. Vojticek holds a B.S. in Business Administration from the University of Southern California.
The Statement of Additional Information provides additional information about each Portfolio Manager’s compensation, other accounts managed and ownership of Fund shares.
20 |
Administrator, Accounting Agent and Transfer Agent
ALPS Fund Services, Inc. (“ALPS” or the “Administrator”), located at 1290 Broadway, Suite 1000, Denver, CO 80203, serves as Administrator and Accounting Agent for the Fund. For the services rendered to the Fund by ALPS, the Fund pays ALPS the greater of an annual minimum fee or an asset-based fee, which scales downward based upon net assets for fund administration and fund accounting services. SS&C GIDS, located at PO Box 219445, Kansas City, MO 64121-9445, serves as the Fund’s Transfer Agent and for such services the Fund pays the Transfer Agent separate fees.
Custodian
UMB Bank, N.A (“UMB Bank” or the “Custodian”), with principal offices at 1010 Grand Boulevard, Kansas City, Missouri 64106, serves as custodian for the securities and cash of the Fund’s portfolio. Under a Custody Agreement, UMB Bank holds the Fund’s assets in safekeeping and keeps all necessary records and documents relating to its duties.
Fund Expenses
The Advisor is obligated to pay expenses associated with providing the services stated in the Investment Management Agreement, including compensation of and office space for its officers and employees connected with investment and economic research, trading and investment management and administration of the Fund. The Advisor is obligated to pay the fees of any Trustee of the Fund who is affiliated with it.
The Administrator is obligated to pay expenses associated with providing the services contemplated by a Fund Services Administration Agreement (administration and accounting services), including compensation of and office space for its officers and employees employed in providing these services to the Fund.
The Fund pays all other expenses incurred in the operation of the Fund including, among other things, (i) expenses for legal and independent accountants’ services, (ii) costs of printing proxies, share certificates, if any, and reports to shareholders, (iii) charges of the custodian and transfer agent in connection with the Fund’s dividend reinvestment policy, (iv) fees and expenses of independent Trustees, (v) printing costs, (vi) membership fees in trade association, (vii) fidelity bond coverage for the Fund’s officers and Trustees, (viii) errors and omissions insurance for the Fund’s officers and Trustees, (ix) brokerage costs, (x) taxes, (xi) costs associated with the Fund’s quarterly repurchase offers, (xii) servicing fees and (xiii) other extraordinary or non-recurring expenses and other expenses properly payable by the Fund. The expenses incident to the offering and issuance of shares to be issued by the Fund will be recorded as a reduction of capital of the Fund attributable to the shares.
Class L shares are subject to a monthly shareholder servicing fee at an annual rate of up to 0.25% of the average daily net assets of the Fund attributable to the respective share class.
The Board has authorized the Advisor and RREEF to select brokers or dealers (including affiliates) to arrange for the purchase and sale of Fund securities, including principal transactions. Any commission, fee or other remuneration paid to an affiliated broker or dealer is paid in compliance with the Fund’s procedures adopted in accordance with Rule 17e-1 under the 1940 Act.
21 |
Control Persons and Principal Shareholders
A principal shareholder is any person who owns (either of record or beneficially) 5% or more of the outstanding shares of a fund. A control person is one who owns, either directly or indirectly, more than 25% of the voting securities of a company or acknowledges the existence of control. The Fund’s principal shareholders as of January 3, 2025 are listed in the chart below. Each shareholder listed below is a record shareholder, holding shares for the benefit of others.
Class A Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
6,523,152.52 |
26.75% |
EQUITABLE ADVISORS LLC LPL FINANCIAL SERVICES FBO LPL BIN 66920980 1055 LPL WAY FORT MILL SC, 29715-8101 |
4,721,545.33 |
19.36% |
CHARLES SCHWAB & CO INC SPECIAL CUSTODY A/C FBO CUSTOMERS 211 MAIN STREET SAN FRANCISCO, CA 94105-1905 |
3,107,371.03 |
12.74% |
NATIONAL FINANCIAL SERVICES LLC BIN #B9F699887 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
3,082,068.56 |
12.64% |
Class C Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
5,923,943.31 |
38.47% |
LPL FINANCIAL LLC FBO CUSTOMER ACCOUNTS 4707 EXECUTIVE DR. SAN DIEGO CA, 92121-3091 |
2,299,101.93 |
14.93% |
CHARLES SCHWAB AND CO INC SPECIAL CUSTODY A/C FBO CUSTOMERS 211 MAIN STREET SAN FRANCISCO, CA 94105-1905 |
2,076,778.96 |
13.49% |
NATIONAL FINANCIAL SERVICES LLC 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
895,604.35 |
5.82% |
Class I Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
CHARLES SCHWAB & CO INC SPECIAL CUSTODY A/C FBO CUSTOMERS 211 MAIN STREET SAN FRANCISCO, CA 92121 |
42,258,021.47 |
36.65% |
NATIONAL FINANCIAL SERVICES LLC 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
21,116,400.89 |
18.31% |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
21,101,606.20 |
18.30% |
LPL FINANCIAL SERVICES FBO LPL BIN 66920980 1055 LPL WAY FORT MILL SC 29715-8101 |
14,367,372.68 |
12.46% |
ROBERT W BAIRD & CO. INC. A/C 47100819 777 EAST WISCONSIN AVENUE MILWAUKEE, WI 53202 |
6,642,155.04 |
5.76% |
22 |
Class L Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
1,652,278.67 |
53.11% |
NATIONAL FINANCIAL SERVICES LLC 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
535,807.56 |
17.22% |
LPL FINANCIAL LLC FBO CUSTOMER ACCOUNTS 4707 EXECUTIVE DR. SAN DIEGO CA, 92121-3091 |
247,909.67 |
7.97% |
Class M Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
MORGAN STANLEY SMITH BARNEY LLC 1 NEW YORK PLAZA NEW YORK, NY 10004 |
4,313,743.14 |
98.46% |
As of January 3, 2025, the Trustees and officers, as a group, owned less than 1.00% of the shares of the Fund.
DETERMINATION OF NET ASSET VALUE
The net asset value of shares of the Fund is determined daily, as of the close of regular trading on the NYSE (normally, 4:00 p.m., Eastern Time). The NYSE is closed on weekends and New Year’s Day, Martin Luther King, Jr. Day, Presidents’ Day, Good Friday, Memorial Day, Juneteenth Day, Independence Day, Labor Day, Thanksgiving Day, and Christmas Day. Each Class L share will be offered at net asset value. During the continuous offering, the price of the shares will increase or decrease on a daily basis according to the net asset value of the shares.
In computing net asset value, portfolio securities of the Fund are valued at their current market values determined on the basis of market quotations as of the last quoted sales price on the security’s primary exchange. If market quotations are not readily available, as in the case of Institutional Investment Funds investing in private real estate, securities are valued at fair value as determined in good faith by the Advisor, in its capacity as the Board’s valuation designee, pursuant to Rule 2a-5 under the 1940 Act or with respect to securities traded or dealt in upon one or more securities exchanges (whether domestic or foreign), as described below. As a general matter, fair value represents the amount that the Fund could reasonably expect to receive if the Fund’s investment in the security were sold at the time of valuation, based on information reasonably available at the time the valuation is made and that the Advisor believes to be reliable. As the valuation designee, the Advisor acts under the Board’s oversight. The Board and the Advisor may enlist third party service providers, such as pricing services, broker-dealers or valuation firms, on an as-needed basis to assist in determining a security-specific fair value. The Board reviews the execution of this process and the resultant fair value prices at least quarterly to assure the process produces reliable results.
Fair valuation involves subjective judgments, and it is possible that the fair value determined for a security may differ materially from the value that could be realized upon the sale of the security. Like all investments that are valued at fair value, the Institutional Investment Funds will be difficult to value. There is no single standard for determining fair value of a security. Rather, in determining the fair value of a security for which there are no readily available market quotations, the Advisor, using information including that provided by a Sub-Advisor, may consider several factors, including fundamental analytical data relating to the investment in the security, the nature and duration of any restriction on the disposition of the security, the cost of the security at the date of purchase, the liquidity of the market for the security and the recommendation of the Fund’s Portfolio Managers. The Advisor may also consider periodic financial statements (audited and unaudited) or other information provided by the issuer. The Advisor will attempt to obtain current information to value all fair valued securities, but it is anticipated that portfolio holdings of the Institutional Investment Funds could be available on no more than a quarterly basis. Institutional Investment Funds that invest primarily in publicly traded securities are more easily valued.
The Advisor, with the assistance of other parties, will provide the Board with periodic reports, no less frequently than quarterly, that discuss the functioning of the valuation process, if applicable to that period, and that identify issues and valuations problems that have arisen, if any. To the extent deemed necessary by the Advisor, the fair value team or committee of the Board will review any securities valued by the Advisor in accordance with the Fund’s valuation policies.
Non-dollar-denominated securities, if any, are valued as of the close of the NYSE at the closing price of such securities in their principal trading market, but may be valued at fair value if subsequent events occurring before the computation of net asset value materially have affected the value of the securities. Trading may take place in foreign issues held by the Fund, if any, at times when the Fund is not open for business. As a result, the Fund’s net asset value may change at times when it is not possible to purchase or sell shares of the Fund. The Fund may use a third-party pricing service to assist it in determining the market value of securities in the Fund’s portfolio. The Fund’s net asset value per share is calculated, on a class-specific basis, by dividing the value of the Fund’s total assets (the value of the securities the Fund holds plus cash or other assets, including interest accrued but not yet received), less accrued expenses of the Fund, less the Fund’s other liabilities by the total number of shares outstanding.
23 |
For purposes of determining the net asset value of the Fund, readily marketable portfolio securities listed on the NYSE are valued, except as indicated below, at the last sale price reflected on the consolidated tape at the close of the NYSE on the business day as of which such value is being determined. If there has been no sale on such day, the securities are valued at the mean of the closing bid and asked prices on such day. If no bid or asked prices are quoted on such day or if market prices may be unreliable because of events occurring after the close of trading, then the security is valued by such method as the Advisor, as valuation designee, shall determine in good faith to reflect its fair market value. Readily marketable securities not listed on the NYSE but listed on other domestic or foreign securities exchanges are valued in a like manner. Portfolio securities traded on more than one securities exchange are valued at the last sale price on the business day as of which such value is being determined as reflected on the consolidated tape at the close of the exchange representing the principal market for such securities. Securities trading on the NASDAQ are valued at the NASDAQ official closing price.
Readily marketable securities traded in the over-the-counter market, including listed securities whose primary market is believed by the Advisor to be over-the-counter, are valued at the mean of the current bid and asked prices as reported by the NASDAQ or, in the case of securities not reported by the NASDAQ or a comparable source, as the Advisor deems appropriate to reflect their fair market value. Where securities are traded on more than one exchange and also over-the-counter, the securities will generally be valued using the quotations the Advisor believes reflect most closely the value of such securities.
CONFLICTS OF INTEREST
As a general matter, certain conflicts of interest may arise in connection with a portfolio manager’s management of a fund’s investments, on the one hand, and the investments of other accounts for which the portfolio manager is responsible, on the other. For example, it is possible that the various accounts managed could have different investment strategies that, at times, might conflict with one another to the possible detriment of the Fund. Alternatively, to the extent that the same investment opportunities might be desirable for more than one account, possible conflicts could arise in determining how to allocate them. Other potential conflicts might include conflicts created by specific portfolio manager compensation arrangements, and conflicts relating to selection of brokers or dealers to execute Fund portfolio trades and/or specific uses of commissions from Fund portfolio trades (for example, research, or “soft dollars”, if any). The Advisor, and Sub-Advisor, to the extent applicable, have adopted policies and procedures and have structured their Portfolio Managers’ compensation in a manner reasonably designed to safeguard the Fund from being negatively affected as a result of any such potential conflicts.
QUARTERLY REPURCHASES OF SHARES
Once each quarter, the Fund will offer to repurchase, at per-class net asset value no less than 5% of the outstanding shares of the Fund, unless such offer is suspended or postponed in accordance with regulatory requirements (as discussed below). The offer to purchase shares is a fundamental policy that may not be changed without the vote of the holders of a majority of the Fund’s outstanding voting securities (as defined in the 1940 Act). Shareholders will be notified in writing of each quarterly repurchase offer and the date the repurchase offer ends (the “Repurchase Request Deadline”). Shares will be repurchased at the per-class NAV per share determined as of the close of regular trading on the NYSE no later than the 14th day after the Repurchase Request Deadline, or the next business day if the 14th day is not a business day (each a “Repurchase Pricing Date”).
Shareholders will be notified in writing about each quarterly repurchase offer, how they may request that the Fund repurchase their shares and the “Repurchase Request Deadline,” which is the date the repurchase offer ends. Shares tendered for repurchase by shareholders prior to any Repurchase Request Deadline will be repurchased subject to the aggregate repurchase amounts established for that Repurchase Request Deadline. The time between the notification to shareholders and the Repurchase Request Deadline may vary from no more than 42 days to no less than 21 days. Payment pursuant to the repurchase will be made by checks to the shareholder’s address of record, or credited directly to a predetermined bank account on the Purchase Payment Date, which will be no more than seven days after the Repurchase Pricing Date. The Board may establish other policies for repurchases of shares that are consistent with the 1940 Act, regulations thereunder and other pertinent laws. Shareholders have no right to redeem Fund shares outside the regular quarterly repurchases, regardless of shareholder circumstances, and the Fund may not honor any such requests.
Determination of Repurchase Offer Amount
The Board, or a committee thereof, in its sole discretion, will determine the number of shares for each share class that the Fund will offer to repurchase (the “Repurchase Offer Amount”) for a given Repurchase Request Deadline. The Repurchase Offer Amount, however, will be no less than 5% and no more than 25% of the total number of shares outstanding on the Repurchase Request Deadline.
If shareholders tender for repurchase more than the Repurchase Offer Amount for a given repurchase offer, the Fund will repurchase the shares on a pro rata basis. However, the Fund may accept all shares tendered for repurchase by shareholders who own less than one hundred shares and who tender all of their shares, before prorating other amounts tendered.
Notice to Shareholders
No less than 21 days and more than 42 days before each Repurchase Request Deadline, the Fund shall send to each shareholder of record and to each beneficial owner of the shares that are the subject of the repurchase offer a notification (“Shareholder Notification”). The Shareholder Notification will contain information shareholders should consider in deciding whether to tender their shares for repurchase. The notice also will include detailed instructions on how to tender shares for repurchase, state the Repurchase Offer Amount and identify the dates of the Repurchase Request Deadline, the scheduled Repurchase Pricing Date, and the date the repurchase proceeds are scheduled for payment (the “Repurchase Payment Deadline”). The notice also will set forth the NAV that has been computed no more than seven days before the date of notification, and how shareholders may ascertain the NAV after the notification date.
24 |
Repurchase Price
The repurchase price of the shares will be the NAV of the share class as of the close of regular trading on the NYSE on the Repurchase Pricing Date. The notice of the repurchase offer also will provide information concerning the NAV, such as the NAV as of a recent date or a sampling of recent NAVs, and a toll-free number for information regarding the repurchase offer. You may call 1-844-819-8287 to learn the NAV.
Repurchase Amounts and Payment of Proceeds
Shares tendered for repurchase by shareholders prior to any Repurchase Request Deadline will be repurchased subject to the aggregate Repurchase Offer Amount established for that Repurchase Request Deadline. Payment pursuant to the repurchase offer will be made by check to the shareholder’s address of record, or credited directly to a predetermined bank account on the Purchase Payment Date, which will be no more than seven days after the Repurchase Pricing Date. The Board may establish other policies for repurchases of shares that are consistent with the 1940 Act, regulations thereunder and other pertinent laws.
If shareholders tender for repurchase more than the Repurchase Offer Amount for a given repurchase offer, the Fund will repurchase the shares on a pro rata basis. Notwithstanding the foregoing, the Fund may in its sole discretion and for administrative convenience accept all shares tendered for repurchase by shareholders who own less than one hundred shares and who tender all of their shares, before prorating other amounts tendered.
Suspension or Postponement of Repurchase Offer
The Fund may suspend or postpone a repurchase offer only: (a) if making or effecting the repurchase offer would cause the Fund to lose its status as a regulated investment company under the Code; (b) for any period during which the NYSE or any market on which the securities owned by the Fund are principally traded is closed, other than customary weekend and holiday closings, or during which trading in such market is restricted; (c) for any period during which an emergency exists as a result of which disposal by the Fund of securities owned by it is not reasonably practicable, or during which it is not reasonably practicable for the Fund fairly to determine the value of its net assets; or (d) for such other periods as the Commission may by order permit for the protection of shareholders of the Fund.
Liquidity Requirements
The Fund must maintain liquid assets equal to the Repurchase Offer Amount from the time that the notice is sent to shareholders until the Repurchase Pricing Date. The Fund will ensure that either a percentage of its net assets equal to at least 100% of the Repurchase Offer Amount consists of cash or assets that can be sold or disposed of in the ordinary course of business at approximately the price at which the Fund has valued the investment within the time period between the Repurchase Request Deadline and the Repurchase Payment Deadline, and/or a line of credit is available to satisfy the Repurchase Offer Amount. The Board has adopted procedures that are reasonably designed to ensure that the Fund’s assets are sufficiently liquid so that the Fund can comply with the repurchase offer and the liquidity requirements described in the previous paragraphs. If, at any time, the Fund falls out of compliance with these liquidity requirements, the Board will take whatever action it deems appropriate to ensure compliance.
Consequences of Repurchase Offers
Repurchase offers will typically be funded from available cash or sales of portfolio securities. Payment for repurchased shares, however, may require the Fund to liquidate portfolio holdings earlier than the Advisor otherwise would, thus increasing the Fund’s portfolio turnover and potentially causing the Fund to realize losses. The Advisor intends to take measures to attempt to avoid or minimize such potential losses and turnover, and instead of liquidating portfolio holdings, may borrow money to finance repurchases of shares. If the Fund borrows to finance repurchases, interest on that borrowing will negatively affect shareholders who do not tender their shares in a repurchase offer by increasing the Fund’s expenses and reducing any net investment income. To the extent the Fund finances repurchase amounts by selling Fund investments, the Fund may hold a larger proportion of its assets in less liquid securities. The sale of portfolio securities to fund repurchases also could reduce the market price of those underlying securities, which in turn would reduce the Fund’s net asset value.
Repurchase of the Fund’s shares will tend to reduce the number of outstanding shares and, depending upon the Fund’s investment performance, its net assets. A reduction in the Fund’s net assets would increase the Fund’s expense ratio, to the extent that additional shares are not sold and expenses otherwise remain the same (or increase). In addition, the repurchase of shares by the Fund will be a taxable event to shareholders.
The Fund is intended as a medium to long-term investment. The Fund’s quarterly repurchase offers are a shareholder’s only means of liquidity with respect to his or her shares. Shareholders have no right to redeem Fund shares outside the regular quarterly repurchases, regardless of shareholder circumstances, and the Fund may not honor any such requests. The shares are not traded on a national securities exchange and no secondary market exists for the shares, nor does the Fund expect a secondary market for its shares to exist in the future.
DISTRIBUTION POLICY
Quarterly Distribution Policy
The Fund’s distribution policy is to make quarterly distributions to shareholders. The level of quarterly distributions (including any return of capital) is not fixed, but is expected to represent an annual rate of approximately 5.25% of the Fund’s current net asset value per share. However, this distribution policy is subject to change. Shareholders receiving periodic payments from the Fund
25 |
may be under the impression that they are receiving net profits. However, all or a portion of a distribution may consist of a return of capital. Shareholders should not assume that the source of a distribution from the Fund is net profit. A return of capital is not taxable to a shareholder unless it exceeds a shareholder’s tax basis in the shares. Returns of capital reduce a shareholder’s tax cost (or “tax basis”). Once a shareholder’s tax basis is reduced to zero, any further return of capital would be taxable. Shareholders should note that return of capital will reduce the tax basis of their shares and potentially increase the taxable gain, if any, upon disposition of their shares. As required under the Investment Company Act of 1940, the Fund will provide a notice to shareholders at the time of distribution when such distribution does not consist solely of net income. Additionally, each distribution payment will be accompanied by a written statement which discloses the source or sources of each distribution. The IRS requires you to report these amounts, excluding returns of capital, on your income tax return for the year declared. The Fund will provide disclosures, with each distribution, that estimate the percentages of the current and year-to-date distributions that represent (1) net investment income, (2) capital gains and (3) return of capital. At the end of the year, the Fund may be required under applicable law to re-characterize distributions made previously during that year among (1) ordinary income, (2) capital gains and (3) return of capital for tax purposes. An additional distribution may be made in December, and other additional distributions may be made with respect to a particular fiscal year in order to comply with applicable law. Distributions declared in December, if paid to shareholders by the end of January, are treated for federal income tax purposes as if received in December.
The distribution rate may be modified by the Board from time to time. If, for any quarterly distribution, investment company taxable income (which term includes net short-term capital gain), if any, and net tax-exempt income, if any, is less than the amount of the distribution, then the difference will generally be a tax-free return of capital distributed from the Fund’s assets. The Fund’s final distribution for each calendar year will include any remaining investment company taxable income and net tax-exempt income undistributed during the year, as well as all net capital gain realized during the year. If the total distributions made in any calendar year exceed investment company taxable income, net tax-exempt income and net capital gain, such excess distributed amount would be treated as ordinary dividend income to the extent of the Fund’s current and accumulated earnings and profits. Distributions in excess of the earnings and profits would first be a tax-free return of capital to the extent of the adjusted tax basis in the shares. After such adjusted tax basis is reduced to zero, the distribution would constitute capital gain (assuming the shares are held as capital assets). This distribution policy may, under certain circumstances, have certain adverse consequences to the Fund and its shareholders because it may result in a return of capital resulting in less of a shareholder’s assets being invested in the Fund and, over time, increase the Fund’s expense ratio. The distribution policy also may cause the Fund to sell a security at a time it would not otherwise do so in order to manage the distribution of income and gain.
Unless the registered owner of shares elects to receive cash, all dividends declared on shares will be automatically reinvested in additional shares of the Fund. See “Dividend Reinvestment Policy.”
The dividend distribution described above may result in the payment of approximately the same amount or percentage to the Fund’s shareholders each quarter. Section 19(a) of the 1940 Act and Rule 19a-1 thereunder require the Fund to provide a written statement accompanying any such payment that adequately discloses its source or sources. Thus, if the source of the dividend or other distribution were the original capital contribution of the shareholder, and the payment amounted to a return of capital, the Fund would be required to provide written disclosure to that effect. Nevertheless, persons who periodically receive the payment of a dividend or other distribution may be under the impression that they are receiving net profits when they are not. Shareholders should read any written disclosure provided pursuant to Section 19(a) and Rule 19a-1 carefully and should not assume that the source of any distribution from the Fund is net profit.
The Board reserves the right to change the quarterly distribution policy from time to time.
DIVIDEND REINVESTMENT POLICY
The Fund will operate under a dividend reinvestment policy administered by the Transfer Agent. Pursuant to the policy, the Fund’s income dividends or capital gains or other distributions (each, a “Distribution” and collectively, “Distributions”), net of any applicable U.S. withholding tax, are reinvested in the same class of shares of the Fund.
Shareholders automatically participate in the dividend reinvestment policy, unless and until an election is made to withdraw from the policy on behalf of such participating shareholder. Shareholders who do not wish to have Distributions automatically reinvested should so notify the Transfer Agent in writing at Bluerock Total Income+ Real Estate Fund, c/o SS&C GIDS, PO Box 219445, Kansas City, MO 64121-9445. Such written notice must be received by the Transfer Agent 30 days prior to the record date of the Distribution or the shareholder will receive such Distribution in shares through the dividend reinvestment policy. Under the dividend reinvestment policy, the Fund’s Distributions to shareholders are reinvested in full and fractional shares as described below.
When the Fund declares a Distribution, the Transfer Agent, on the shareholder’s behalf, will receive additional authorized shares from the Fund either newly issued or repurchased from shareholders by the Fund and held as treasury stock. The number of shares to be received when Distributions are reinvested will be determined by dividing the amount of the Distribution by the Fund’s net asset value per share.
The Transfer Agent will maintain all shareholder accounts and furnish written confirmations of all transactions in the accounts, including information needed by shareholders for personal and tax records. The Transfer Agent will hold shares in the account of the shareholders in non-certificated form in the name of the participant, and each shareholder’s proxy, if any, will include those shares purchased pursuant to the dividend reinvestment policy. Each participant, nevertheless, has the right to request certificates for whole and fractional shares owned. The Fund will issue certificates in its sole discretion. The Administrator will distribute all proxy solicitation materials, if any, to participating shareholders.
26 |
In the case of shareholders, such as banks, brokers or nominees, that hold shares for others who are beneficial owners participating under the dividend reinvestment policy, the Transfer Agent will administer the dividend reinvestment policy on the basis of the number of shares certified from time to time by the record shareholder as representing the total amount of shares registered in the shareholder’s name and held for the account of beneficial owners participating under the dividend reinvestment policy.
Neither the Transfer Agent nor the Fund shall have any responsibility or liability beyond the exercise of ordinary care for any action taken or omitted pursuant to the dividend reinvestment policy, nor shall they have any duties, responsibilities or liabilities except such as expressly set forth herein. Neither shall they be liable hereunder for any act done in good faith or for any good faith omissions to act, including, without limitation, failure to terminate a participant’s account prior to receipt of written notice of his or her death or with respect to prices at which shares are purchased or sold for the participants account and the terms on which such purchases and sales are made, subject to applicable provisions of the federal securities laws.
The automatic reinvestment of dividends will not relieve participants of any federal, state or local income tax that may be payable (or required to be withheld) on such dividends. See “U.S. Federal Income Tax Matters.”
The Fund reserves the right to amend or terminate the dividend reinvestment policy. There is no direct service charge to participants with regard to purchases under the dividend reinvestment policy; however, the Fund reserves the right to amend the dividend reinvestment policy to include a service charge payable by the participants.
All correspondence concerning the dividend reinvestment policy should be directed to the Transfer Agent at Bluerock Total Income+ Real Estate Fund, c/o SS&C GIDS, PO Box 219445, Kansas City, MO 64121-9445. Certain transactions can be performed by calling the toll-free number 1-844-819-8287.
U.S. FEDERAL INCOME TAX MATTERS
The following briefly summarizes some of the important federal income tax consequences to shareholders of investing in the Fund’s shares, reflects the federal tax law as of the date of this prospectus, and does not address special tax rules applicable to certain types of investors, such as corporate, tax-exempt and foreign investors. Investors should consult their tax advisors regarding other federal, state or local tax considerations that may be applicable in their particular circumstances, as well as any proposed tax law changes.
The following is a summary discussion of certain U.S. federal income tax consequences that may be relevant to a shareholder of the Fund that acquires, holds and/or disposes of shares of the Fund, and reflects provisions of the Internal Revenue Code of 1986, as amended, existing Treasury regulations, rulings published by the IRS, and other applicable authority, as of the date of this prospectus. These authorities are subject to change by legislative or administrative action, possibly with retroactive effect. The following discussion is only a summary of some of the important tax considerations generally applicable to investments in the Fund and the discussion set forth herein does not constitute tax advice. For more detailed information regarding tax considerations, see the Statement of Additional Information. There may be other tax considerations applicable to particular investors such as those holding shares in a tax deferred account such as an IRA or 401(k) plan. In addition, income earned through an investment in the Fund may be subject to state, local and foreign taxes.
The Fund intends to elect to be treated and to qualify each year for taxation as a regulated investment company under Subchapter M of the Code. In order for the Fund to qualify as a regulated investment company, it must meet an income and asset diversification test each year. If the Fund so qualifies and satisfies certain distribution requirements, the Fund (but not its shareholders) will not be subject to federal income tax to the extent it distributes its investment company taxable income and net capital gains (the excess of net long-term capital gains over net short-term capital loss) in a timely manner to its shareholders in the form of dividends or capital gain distributions. The Code imposes a 4% nondeductible excise tax on regulated investment companies, such as the Fund, to the extent they do not meet certain distribution requirements by the end of each calendar year. The Fund anticipates meeting these distribution requirements. Shareholders will not be subject to the alternative minimum tax.
The Fund intends to make distributions of investment company taxable income after payment of the Fund’s operating expenses no less frequently than annually. Unless a shareholder is ineligible to participate or elects otherwise, all distributions will be automatically reinvested in additional shares of the Fund pursuant to the dividend reinvestment policy. For U.S. federal income tax purposes, all dividends are generally taxable whether a shareholder takes them in cash or they are reinvested pursuant to the policy in additional shares of the Fund. Distributions of the Fund’s investment company taxable income (including short-term capital gains) will generally be treated as ordinary income to the extent of the Fund’s current and accumulated earnings and profits. Distributions of the Fund’s net capital gains (“capital gain dividends”), if any, are taxable to shareholders as capital gains, regardless of the length of time shares have been held by shareholders. Distributions, if any, in excess of the Fund’s earnings and profits will first reduce the adjusted tax basis of a holder’s shares and, after that basis has been reduced to zero, will constitute capital gains to the shareholder of the Fund (assuming the shares are held as a capital asset). A corporation that owns Fund shares generally will not be entitled to the dividends received deduction with respect to all of the dividends it receives from the Fund. Fund dividend payments that are attributable to qualifying dividends received by the Fund from certain domestic corporations may be designated by the Fund as being eligible for the dividends received deduction. There can be no assurance as to what portion of Fund dividend payments may be classified as qualifying dividends. The determination of the character for U.S. federal income tax purposes of any distribution from the Fund (i.e. ordinary income dividends, capital gains dividends, qualified dividends or return of capital distributions) will be made as of the end of the Fund’s taxable year. Generally, no later than 60 days after the close of its taxable year, the Fund will provide shareholders with a written notice designating the amount of any capital gain distributions and any other distributions.
The Fund will inform its shareholders of the source and tax status of all distributions promptly after the close of each calendar year.
27 |
DESCRIPTION OF CAPITAL STRUCTURE AND SHARES
The Fund is an unincorporated statutory trust established under the laws of the State of Delaware upon the filing of a Certificate of Trust with the Secretary of State of Delaware on May 25, 2012. The Trustees are authorized to issue an unlimited number of shares. The Fund does not intend to hold annual meetings of its shareholders.
The Declaration of Trust, which has been filed with the SEC, permits the Fund to issue an unlimited number of full and fractional shares of beneficial interest, no par value. The Fund offers five different classes of shares: Class A, Class C, Class I, Class L and Class M shares. The Class A, Class C, Class I and Class M shares are each offered by a different prospectus. The Fund began continuously offering its common shares on October 22, 2012. As of February 18, 2014, the Fund simultaneously redesignated its issued and outstanding common shares as Class A shares and created its Class C and Class I shares, which commenced offering April 1, 2014. As of May 30, 2017, the Fund created its Class L shares. As of February 1, 2020, the Fund created its Class M shares. An investment in any share class of the Fund represents an investment in the same assets of the Fund. However, the minimum investment amounts, sales loads, and ongoing fees and expenses for each share class may be different. The fees and expenses for the Fund are set forth in “Summary of Fund Expenses”. The details of each share class are set forth in “Plan of Distribution”.
The following table shows the amounts of the Fund’s shares that have been authorized and are outstanding as of January 3, 2025, of which none were owned by the Fund:
Title of Class |
Amount Authorized |
Amount Outstanding |
Class A |
Unlimited |
24,385,031.72 shares NAV $26.03 per share |
Class C |
Unlimited |
15,397,873.19 shares NAV $24.05 per share |
Class I |
Unlimited |
115,282,227.36 shares NAV $26.80 per share |
Unlimited |
shares NAV $25.54 per share |
|
Class M |
Unlimited |
4,381,277.79 shares NAV $24.24 per share |
Holders of shares will be entitled to the payment of dividends when, as and if declared by the Board. The Fund currently intends to make dividend distributions to its shareholders no less frequently than quarterly. Unless the registered owner of shares elects to receive cash, all dividends declared on shares will be automatically reinvested for shareholders in additional shares of the same class of the Fund. See “Dividend Reinvestment Policy.” The 1940 Act may limit the payment of dividends to the holders of shares. Each whole share shall be entitled to one vote as to matters on which it is entitled to vote pursuant to the terms of the Declaration of Trust on file with the SEC. Upon liquidation of the Fund, after paying or adequately providing for the payment of all liabilities of the Fund, and upon receipt of such releases, indemnities and refunding agreements as they deem necessary for their protection, the Trustees may distribute the remaining assets of the Fund among its shareholders. The shares are not liable to further calls or to assessment by the Fund. There are no pre-emptive rights associated with the shares. The Declaration of Trust provides that the Fund’s shareholders are not liable for any liabilities of the Fund. Although shareholders of an unincorporated statutory trust established under Delaware law, in certain limited circumstances, may be held personally liable for the obligations of the Fund as though they were general partners, the provisions of the Declaration of Trust described in the foregoing sentence make the likelihood of such personal liability remote.
The Fund generally will not issue share certificates. However, upon written request to the Fund’s Transfer Agent, a share certificate may be issued at the Fund’s discretion for any or all of the full shares credited to an investor’s account. Share certificates that have been issued to an investor may be returned at any time. The Fund’s Transfer Agent will maintain an account for each shareholder upon which the registration of shares are recorded, and transfers, permitted only in rare circumstances, such as death or bona fide gift, will be reflected by bookkeeping entry, without physical delivery. The Fund’s Transfer Agent will require that a shareholder provide requests in writing, accompanied by a valid signature guarantee form, when changing certain information in an account such as wiring instructions or telephone privileges.
Other Classes of Shares. The Fund offers Class A, Class C, Class I and Class M shares by a different prospectus. The other share classes are subject to different investment minimums, sales charges, and shareholder servicing fees and/or distribution servicing fees.
ANTI-TAKEOVER PROVISIONS IN THE DECLARATION OF TRUST
The Amended and Restated Declaration of Trust includes provisions that could have the effect of limiting the ability of other entities or persons to acquire control of the Fund or to change the composition of the Board, and could have the effect of depriving the Fund’s shareholders of an opportunity to sell their shares at a premium over prevailing market prices, if any, by discouraging a third party from seeking to obtain control of the Fund. These provisions may have the effect of discouraging attempts to acquire control of the Fund, which attempts could have the effect of increasing the expenses of the Fund and interfering with the normal operation of the Fund. The Trustees are elected for indefinite terms and do not stand for reelection. A Trustee may be removed from office without cause only by a written instrument signed or adopted by a majority of the remaining Trustees or by a vote of the holders of at least two-thirds of the shares of the Fund that are entitled to elect a Trustee and that are entitled to vote on the matter. The Declaration of Trust does not contain any other specific inhibiting provisions that would operate only with respect to an extraordinary transaction such as a merger, reorganization, tender offer, sale or transfer of substantially all of the Fund’s asset, or liquidation. Reference should be made to the Declaration of Trust on file with the SEC for the full text of these provisions.
28 |
PLAN OF DISTRIBUTION
ALPS Distributors, Inc. (the “Distributor”), located at 1290 Broadway, Suite 1000, Denver, Colorado 80203, serves as the Fund’s principal underwriter and acts as the distributor of the Fund’s shares on a best efforts basis, subject to various conditions. The Fund’s shares are offered for sale through the Distributor at net asset value plus the applicable sales load. The Distributor also may enter into selected dealer agreements with other broker dealers for the sale and distribution of the Fund’s shares, including with affiliates of the Advisor. In reliance on Rule 415, the Fund intends to offer to sell its shares, on a continual basis, through the Distributor. No arrangement has been made to place funds received in an escrow, trust or similar account. The Distributor is not required to sell any specific number or dollar amount of the Fund’s shares. Shares of the Fund will not be listed on any national securities exchange and the Distributor will not act as a market marker in Fund shares. The Class L shares will pay to the Distributor a Distribution Fee that will accrue at an annual rate equal to 0.25% of the Fund’s average daily net assets attributable to Class L shares and is payable on a monthly basis.
The Distributor has entered into a “wholesaling” agreement with Bluerock Capital Markets, LLC (“BCM”), a registered broker-dealer and an affiliate of the Advisor. Pursuant to the terms of the wholesaling agreement, BCM will seek to market and otherwise promote the Fund through various “wholesale” distribution channels, including regional and independent retail broker-dealers. BCM is paid a portion of the sales load, up to 0.75% of the offering price, charged on the sale of Class L shares (the “Dealer Manager Fee”) for the services it provides under the wholesaling agreement.
The Advisor or its affiliates, in the Advisor’s discretion and from their own resources, may pay additional compensation to brokers or dealers in connection with the sale and distribution of Fund shares (the “Additional Compensation”). In return for the Additional Compensation, the Fund may receive certain marketing advantages including access to a broker’s or dealer’s registered representatives, placement on a list of investment options offered by a broker or dealer, or the ability to assist in training and educating the broker’s or dealer’s registered representatives. The Additional Compensation may differ among brokers or dealers in amount or in the manner of calculation: payments of Additional Compensation may be fixed dollar amounts, or based on the aggregate value of outstanding shares held by shareholders introduced by the broker or dealer, or determined in some other manner. The receipt of Additional Compensation by a selling broker or dealer may create potential conflicts of interest between an investor and its broker or dealer who is recommending the Fund over other potential investments. Additionally, the Fund may pay a servicing fee to intermediaries and other financial industry professionals for providing ongoing services in respect of shareholders of the Fund. Such services may include electronic processing of client orders, electronic fund transfers between clients and the Fund, account reconciliations with the Fund’s Transfer Agent, facilitation of electronic delivery to clients of Fund documentation, monitoring client accounts for back-up withholding and any other special tax reporting obligations, maintenance of books and records with respect to the foregoing, and such other information and liaison services as the Fund or the Advisor may reasonably request.
The Fund and the Advisor have agreed to indemnify the Distributor against certain liabilities, including liabilities under the Securities Act of 1933, or to contribute to payments the Distributor may be required to make because of any of those liabilities. Such agreement does not include indemnification of the Distributor against liability resulting from willful misfeasance, bad faith or negligence on the part of the Distributor in the performance of its duties or from reckless disregard by the Distributor of its obligations and duties under the Distribution Agreement. The Distributor may, from time to time, engage in transactions with or perform services for the Advisor and its affiliates in the ordinary course of business.
Purchasing Shares
Investors may purchase shares directly from the Fund in accordance with the instructions below. Investors will be assessed fees for returned checks and stop payment orders at prevailing rates charged by SS&C GIDS, the Fund’s Transfer Agent. The returned check and stop payment fee is currently $25. Investors may buy and sell shares of the Fund through financial intermediaries and their agents that have made arrangements with the Fund and are authorized to buy and sell shares of the Fund (collectively, “Financial Intermediaries”). Such Financial Intermediaries are authorized to designate other intermediaries to receive purchase orders on the Fund’s behalf. The Fund will be deemed to have received a purchase order when a Financial Intermediary or, if applicable, its authorized designee, receives the order. Orders will be priced at the appropriate price next computed after it is received by a Financial Intermediary or their authorized designee and accepted by the Fund. A Financial Intermediary may hold shares in an omnibus account in the Financial Intermediary’s name or the Financial Intermediary or their authorized designee may maintain individual ownership records. The Fund may pay the Financial Intermediary for maintaining individual ownership records as well as providing other shareholder services. Financial intermediaries may charge fees for the services they provide in connection with processing your transaction order or maintaining an investor’s account with them. Investors should check with their Financial Intermediary to determine if it is subject to these arrangements. Financial Intermediaries are responsible for placing orders correctly and promptly with the Fund, forwarding payment promptly. Orders transmitted with a Financial Intermediary before the close of regular trading (generally 4:00 p.m., Eastern Time) on a day that the NYSE is open for business, will be priced based on the Fund’s NAV next computed after it is received by the Financial Intermediary.
The Fund reserves the right to reject or restrict purchase requests for any reason, particularly when the shareholder’s trading activity suggests that the shareholder may be engaged in disruptive trading activities. Neither the Fund nor the Advisor will be liable for any losses resulting from rejected purchase orders.
29 |
By Mail
To make an initial purchase by mail, complete an account application and mail the application, together with a check made payable to Bluerock Total Income+ Real Estate Fund to:
Bluerock Total Income+ Real Estate Fund
c/o SS&C GIDS
P.O. Box 219445
Kansas City, MO 64121-9445
All checks must be in U.S. Dollars drawn on a domestic bank. The Fund will not accept payment in cash or money orders. The Fund also does not accept cashier’s checks in amounts of less than $10,000. To prevent check fraud, the Fund will neither accept third party checks, Treasury checks, credit card checks, traveler’s checks or starter checks for the purchase of shares, nor post-dated checks, post-dated on-line bill pay checks, or any conditional purchase order or payment.
The Transfer Agent will charge a $25 fee against an investor’s account, in addition to any loss sustained by the Fund, for any payment that is returned. It is the policy of the Fund not to accept applications under certain circumstances or in amounts considered disadvantageous to shareholders. The Fund reserves the right to reject any application.
By Wire — Initial Investment
To make an initial investment in the Fund, the Transfer Agent must receive a completed account application before an investor wires funds. Investors may mail or overnight deliver an account application to the Transfer Agent. Upon receipt of the completed account application, the Transfer Agent will establish an account. The account number assigned will be required as part of the instruction that should be provided to an investor’s bank to send the wire. An investor’s bank must include both the name of the Fund, the account number, and the investor’s name so that monies can be correctly applied. If you wish to wire money to make an investment in the Fund, please call the Fund at 1-844-819-8287 for wiring instructions and to notify the Fund that a wire transfer is coming. Any commercial bank can transfer same-day funds via wire. The Fund will normally accept wired funds for investment on the day received if they are received by the Fund’s designated bank before the close of regular trading on the NYSE. Your bank may charge you a fee for wiring same-day funds. The bank should transmit funds by wire to:
ABA #: (number provided by calling toll-free number above)
Credit: SS&C GIDS
Account #: (number provided by calling toll-free number above)
Further Credit:
Bluerock Total Income+ Real Estate Fund
(shareholder registration)
(shareholder account number)
By Wire — Subsequent Investments
Before sending a wire, investors must contact the Transfer Agent to advise them of the intent to wire funds. This will ensure prompt and accurate credit upon receipt of the wire. Wired funds must be received prior to 4:00 p.m. Eastern Time to be eligible for same day pricing. The Fund, and its agents, including the transfer agent and custodian, are not responsible for the consequences of delays resulting from the banking or Federal Reserve wire system, or from incomplete wiring instructions.
Automatic Investment Plan — Subsequent Investments
You may participate in the Fund’s Automatic Investment Plan, an investment plan that automatically moves money from your bank account and invests it in the Fund through the use of electronic funds transfers or automatic bank drafts. You may elect to make subsequent investments by transfers of a minimum of $100 on specified days of each month into your established Fund account. Please contact the Fund at 1-844-819-8287 for more information about the Fund’s Automatic Investment Plan.
By Telephone
Investors may purchase additional shares of the Fund by calling 1-844-819-8287. If an investor elected this option on the account application, and the account has been open for at least 15 days, telephone orders will be accepted via electronic funds transfer from your bank account through the Automated Clearing House (ACH) network. Banking information must be established on the account prior to making a purchase. Orders for shares received prior to 4:00 p.m. Eastern Time will be purchased at the appropriate price calculated on that day.
Telephone trades must be received by or prior to market close. During periods of high market activity, shareholders may encounter higher than usual call waits. Please allow sufficient time to place your telephone transaction.
In compliance with the USA Patriot Act of 2001, the Transfer Agent will verify certain information on each account application as part of the Fund’s Anti-Money Laundering Program. As requested on the application, investors must supply full name, date of birth, social security number and permanent street address. Mailing addresses containing only a P.O. Box will not be accepted. Investors may call the Transfer Agent (SS&C GIDS) at 1-844-819-8287 for additional assistance when completing an application.
30 |
If the Transfer Agent does not have a reasonable belief of the identity of a customer, the account will be rejected or the customer will not be allowed to perform a transaction on the account until such information is received. The Fund also may reserve the right to close the account within 5 business days if clarifying information/documentation is not received.
Share Class Considerations
When selecting a share class, you should consider the following:
|
● |
which share classes are available to you; |
|
● |
the amount you intend to invest; |
|
● |
how long you expect to own the shares; and |
|
● |
total costs and expenses associated with a particular share class. |
Each investor’s financial considerations are different. You should speak with your financial advisor to help you decide which share class is best for you. Not all financial intermediaries offer all classes of shares. If your financial intermediary offers more than one class of shares, you should carefully consider which class of shares to purchase.
Class L Shares
Class L shares are sold at the prevailing NAV per Class L share and are subject to an upfront sales charge. The following additional features should also be taken into account when purchasing Class L shares:
|
● |
a minimum initial investment of $2,500 for regular accounts and $1,000 for retirement plan accounts, and a minimum subsequent investment of at least $100 for regular accounts and $50 for retirement plan accounts; |
|
● |
a monthly shareholder servicing fee at an annual rate of up to 0.25% of the average daily net assets of the Fund attributable to Class L shares; |
|
● |
a Distribution Fee which will accrue at an annual rate equal to 0.25% of the average daily net assets of the Fund attributable to Class L shares. |
Investors purchasing Class L shares will pay a sales load based on the amount of their investment in the Fund. The sales load payable by each investor depends upon the amount invested by such investor in the Fund, but may range from 1.25% to 4.25%, as set forth in the table below. A reallowance to participating broker-dealers will be made by the Distributor from the sales load paid by each investor. The following sales loads apply to your purchases of shares of the Fund:
Amount |
Broker Commission/ |
Dealer |
Sales Load as % of |
Sales Load as % of |
Under $250,000 |
3.50% |
0.75% |
4.25% |
4.44% |
$250,000-$499,999 |
2.50% |
0.75% |
3.25% |
3.36% |
$500,000-$999,999 |
1.50% |
0.50% |
2.00% |
2.04% |
$1,000,000 and Above |
1.00% |
0.25% |
1.25% |
1.27% |
Share Conversion
For investors currently owning Class A, Class C, and Class L and/or Class M shares, these shares may be convertible into Class I shares if (i) the broker/dealer or other financial intermediary responsible for the shareholder relationship requests such conversion, (ii) Class I shares are available to the broker dealer or financial intermediary, and (iii) the account would have been eligible to purchase Class I shares. More detailed information on Class I shares and the related investment minimums and other restrictions is available in the Fund’s Class I prospectus.
Class L shares will automatically convert into Class A shares after they have been held for eight years.
Right of Accumulation
For the purposes of determining the applicable reduced sales charge, the right of accumulation allows you to include prior purchases of Class L shares of the Fund as part of your current investment as well as reinvested dividends. To qualify for this option, you must be either:
|
● |
an individual; |
|
● |
an individual and spouse purchasing shares for your own account or trust or custodial accounts for your minor children; or |
|
● |
a fiduciary purchasing for any one trust, estate or fiduciary account, including employee benefit plans created under Sections 401, 403 or 457 of the Internal Revenue Code, including related plans of the same employer. |
For example, the following illustrates the operation of the right of accumulation:
If a shareholder owned Class L shares of the Fund through an investment of $249,999 (including sales charge) and wished to purchase additional Class L shares of the Fund through an investment of $50,000 (including sales charge), the sales charge applicable on the $50,000 purchase would be at the 3.25% rate, rather than the 4.25% rate that would otherwise apply to a $50,000 purchase. The discount will be applied to the current purchase (i.e., the $50,000 purchase), not to any previous transaction.
31 |
You may add the current value of all of your existing investments in the Fund and certain other funds advised by the Advisor or its affiliates (collectively, “Bluerock Family Funds”) to determine the front-end sales charge to be applied to your current Class L purchase. Only balances currently held entirely at the Bluerock Family Funds or, if held in an account through a financial services firm, at the same firm through whom you are making your current purchase, will be eligible to be added to your current purchase for purposes of determining your Class L sales charge. You may include the value of Bluerock Family Funds’ investments held by the members of your immediately family, including the value of Bluerock Family Funds’ investments held by you or them in individual retirement plans, such as individual retirement accounts, or IRAs, provided such balances are also currently held entirely at the Bluerock Family Funds or, if held in an account through a financial services firm, at the same financial services firm through whom you are making your current purchase. The value of shares eligible for a cumulative quantity discount equals the cumulative cost of the shares purchased (not including reinvested dividends) or the current account market value; whichever is greater. The current market value of the shares is determined by multiplying the number of shares by the previous day’s NAV. If you believe there are cumulative quantity discount eligible shares that can be combined with your current purchase to achieve a sales charge breakpoint, you must, at the time of your purchase (including at the time of any future purchase) specifically identify those shares to your current purchase broker-dealer.
If you plan to rely on this right of accumulation, you must notify the Fund’s distributor at the time of your purchase. You will need to give the Distributor your account numbers. Existing holdings of family members or other related accounts of a shareholder may be combined for purposes of determining eligibility. If applicable, you will need to provide the account numbers of your spouse and your minor children as well as the ages of your minor children.
Letter of Intent
The letter of intent allows you to count all investments within a 13-month period in Class L shares of the Fund as if you were making them all at once for the purposes of calculating the applicable reduced sales charges. The minimum initial investment under a letter of intent is 5% of the total letter of intent amount. The letter of intent does not preclude the Fund from discontinuing sales of its shares. You may include a purchase not originally made pursuant to a letter of intent under a letter of intent entered into within 90 days of the original purchase. To determine the applicable sales charge reduction, you also may include (1) the cost of Class L shares of the Fund which were previously purchased at a price including a front end sales charge during the 90-day period prior to the Distributor receiving the letter of intent, and (2) the historical cost of shares of other Funds you currently own acquired in exchange for Class L shares, respectively, the Fund purchased during that period at a price including a front-end sales charge. You may combine purchases and exchanges by family members (limited to spouse and children, under the age of 21, living in the same household). You should retain any records necessary to substantiate historical costs because the Fund, the transfer agent and any financial intermediaries may not maintain this information. Shares acquired through reinvestment of dividends are not aggregated to achieve the stated investment goal.
Shareholder Service Plan
The Fund has adopted a “Shareholder Services Plan” with respect to its Class L shares under which the Fund may compensate financial industry organizations for providing ongoing shareholder servicing of client accounts with whom they have distributed shares of the Fund. Such services may include electronic processing of client orders, electronic fund transfers between clients and the Fund, account reconciliations with the Fund’s transfer agent, facilitation of electronic delivery to clients of Fund documentation, monitoring client accounts for back-up withholding and any other special tax reporting obligations, maintenance of books and records with respect to the foregoing, and such other information and liaison services as the Fund or the Advisor may reasonably request. Under the Shareholder Services Plan, the Fund, with respect to its Class L shares, may incur expenses on an annual basis equal up to 0.25% of its average net assets attributable to Class L shares. Because these fees are paid from the Fund’s assets on an ongoing basis they will increase your costs over time and may cost you more than paying other types of sales charges.
Distribution Plan
The Fund, with respect to its Class L shares, is authorized under a “Distribution Plan” to pay to the Distributor a Distribution Fee for certain activities relating to the distribution of shares to investors and maintenance of shareholder accounts. These activities include marketing and other activities to support the distribution of the Class L shares. The Plan operates in a manner consistent with Rule 12b-1 under the 1940 Act, which regulates the manner in which an open-end investment company may directly or indirectly bear the expenses of distributing its shares. Although the Fund is not an open-end investment company, it has undertaken to comply with the terms of Rule 12b-1 as a condition of an exemptive order under the 1940 Act which permits it to have asset based distribution fees. Under the Distribution Plan, the Fund pays the Distributor a Distribution Fee at an annual rate of 0.25% of average daily net assets attributable to Class L shares. Because these fees are paid from the Fund’s assets on an ongoing basis, they will increase your cost over time and may cost you more than paying other types of sales charges.
LEGAL MATTERS
Certain legal matters in connection with the shares will be passed upon for the Fund by Thompson Hine LLP, 41 South High Street, Suite 1700, Columbus, Ohio 43215.
REPORTS TO SHAREHOLDERS
The Fund makes available to its shareholders unaudited semi-annual and audited annual reports, including a list of investments held.
32 |
Householding
If you have elected to receive paper copies of the Fund’s annual and semi-annual reports, in an effort to decrease costs, the Fund intends to send only one copy of each to those addresses shared by two or more accounts and to shareholders reasonably believed to be from the same family or household. A shareholder must call 1-844-819-8287 to discontinue householding and request individual copies of these documents. Once the Fund receives notice to stop householding, individual copies will be sent beginning thirty days after receiving your request. This policy does not apply to account statements.
INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
Cohen & Company, Ltd. is the independent registered public accounting firm for the Fund and audits the Fund’s financial statements. Cohen & Company, Ltd. is located at 1835 Market St., Suite 310, Philadelphia, PA 19103.
ADDITIONAL INFORMATION
The Prospectus and the Statement of Additional Information do not contain all of the information set forth in the Registration Statement that the Fund has filed with the SEC (file No. 811-22710). The complete Registration Statement may be obtained from the SEC at www.sec.gov. See the cover page of this prospectus for information about how to obtain a paper copy of the Registration Statement or Statement of Additional Information without charge.
TABLE OF CONTENTS OF THE STATEMENT OF ADDITIONAL INFORMATION
[To Be Updated]
General Information and History |
1 |
Investment Objectives and Policies |
2 |
Repurchases and Transfers of Shares |
9 |
Management of the Fund |
15 |
Codes of Ethics |
22 |
Proxy Voting Policies and Procedures |
22 |
Control Persons and Principal Holders |
22 |
Investment Advisory and Other Services |
23 |
Portfolio Managers |
27 |
Allocation of Brokerage |
31 |
Tax Status |
31 |
Other Information |
35 |
Independent Registered Public Accounting Firm |
36 |
Financial Statements |
36 |
Appendix A |
A-1 |
Appendix B |
B-1 |
33 |
PRIVACY POLICY & PRACTICES
Rev. January 2019
PRIVACY NOTICE
FACTS |
WHAT DOES THE BLUEROCK TOTAL INCOME+ REAL ESTATE FUND DO WITH YOUR PERSONAL INFORMATION? |
|
Why? |
Financial companies choose how they share your personal information. Federal law gives consumers the right to limit some but not all sharing. Federal law also requires us to tell you how we collect, share, and protect your personal information. Please read this notice carefully to understand what we do. |
|
What? |
The types of personal information we collect and share depend on the product or service you have with us. This information can include: |
|
● Social Security number
● Assets
● Retirement Assets
● Transaction History
● Checking Account Information |
● Purchase History
● Account Balances
● Account Transactions
● Wire Transfer Instructions |
|
When you are no longer our customer, we may continue to share your personal information as described in this notice. |
||
How? |
All financial companies need to share customers’ personal information to run their everyday business. In the section below, we list the reasons financial companies can share their customers’ personal information; the reasons the Bluerock Total Income+ Real Estate Fund chooses to share; and whether you can limit this sharing. |
|
Reasons we can share your personal information |
Does Bluerock Total Income+ Real Estate Fund share? |
Can you limit this sharing? |
For our everyday business purposes – such as to process your transactions, maintain your account(s), respond to court orders and legal investigations, or report to credit bureaus |
Yes |
No |
For our marketing purposes – to offer our products and services to you |
No |
We don’t share |
For joint marketing with other financial companies |
No |
We don’t share |
For our affiliates’ everyday business purposes – information about your transactions and experiences |
No |
We don’t share |
For our affiliates’ everyday business purposes – information about your creditworthiness |
No |
We don’t share |
For nonaffiliates to market to you |
No |
We don’t share |
Questions? |
Call 1-844-819-8287 |
34 |
Who we are |
|
Who is providing this notice? |
Bluerock Total Income+ Real Estate Fund |
What we do |
|
How does Bluerock Total Income+ Real Estate Fund protect my personal information? |
To protect your personal information from unauthorized access and use, we use security measures that comply with federal law. These measures include computer safeguards and secured files and buildings.
Our service providers are held accountable for adhering to strict policies and procedures to prevent any misuse of your nonpublic personal information. |
How does Bluerock Total Income+ Real Estate Fund collect my personal information? |
We collect your personal information, for example, when you
● Open an account
● Provide account information
● Give us your contact information
● Make deposits or withdrawals from your account
● Make a wire transfer
● Tell us where to send the money
● Tells us who receives the money
● Show your government-issued ID
● Show your driver’s license
We also collect your personal information from other companies. |
Why can’t I limit all sharing? |
Federal law gives you the right to limit only
● Sharing for affiliates’ everyday business purposes – information about your creditworthiness
● Affiliates from using your information to market to you
● Sharing for nonaffiliates to market to you
State laws and individual companies may give you additional rights to limit sharing. |
Definitions |
|
Affiliates |
Companies related by common ownership or control. They can be financial and nonfinancial companies.
● Bluerock Total Income+ Real Estate Fund does not share with our affiliates. |
Nonaffiliates |
Companies not related by common ownership or control. They can be financial and nonfinancial companies
● Bluerock Total Income+ Real Estate Fund does not share with nonaffiliates so they can market to you. |
Joint marketing |
A formal agreement between nonaffiliated financial companies that together market financial products or services to you.
● Bluerock Total Income+ Real Estate Fund doesn’t jointly market. |
35 |
Page Intentionally Left Blank
Page Intentionally Left Blank

BLUEROCK TOTAL INCOME+ REAL ESTATE FUND
Class L Shares (TIPLX) of Beneficial Interest
PROSPECTUS
February 1, 2025
Investment Advisor
Bluerock Fund Advisor, LLC
All dealers that buy, sell or trade the Fund’s shares, whether or not participating in this offering, may be required to deliver a prospectus when acting on behalf of the Fund’s Distributor.
You should rely only on the information contained in or incorporated by reference into this prospectus. The Fund has not authorized any other person to provide you with different information. If anyone provides you with different or inconsistent information, you should not rely on it. The Fund is not making an offer to sell these securities in any jurisdiction where the offer or sale is not permitted.

Bluerock Total Income+ Real Estate Fund (the “Fund”) is a continuously offered, non-diversified, closed-end management investment company that is operated as an interval fund.
The Securities and Exchange Commission has not approved or disapproved these securities or determined if this Prospectus is truthful or complete. Any representation to the contrary is a criminal offense.
This prospectus is intended to concisely provide you, a prospective investor, with information about the Fund that you should know before investing in the shares of the Fund that are being offered through this prospectus. You are advised to thoroughly and carefully read this prospectus and retain it for future reference. Additional information about the Fund is also available on the Securities and Exchange Commission’s (“SEC”) website at http://www.sec.gov, including the Fund’s Statement of Additional Information dated February 1, 2025 (the “SAI”). The address of the SEC’s website is provided solely for the information of prospective shareholders and is not intended to be an active link. The table of contents of the SAI appears on page 32 of this prospectus. The SAI is incorporated by reference into this prospectus (legally made a part of this prospectus). The SAI, Fund annual and semi-annual reports and other information and shareholder inquiries regarding the Fund may be requested free of charge by writing the Fund at c/o SS&C Global Investor & Distribution Solutions, Inc., PO Box 219445, Kansas City, MO 64121-9445 (the “Transfer Agent” or “SS&C GIDS”), by calling the Transfer Agent toll-free at 1-844-819-8287, or by visiting the Fund’s website at http://www.bluerockfunds.com.
Investment Objectives. The Fund’s primary investment objective is to generate current income while secondarily seeking long-term capital appreciation with low to moderate volatility and low correlation to the broader markets.
Summary of Investment Strategy. The Fund pursues its investment objectives using a comprehensive multi-strategy, multi-manager, multi-sector approach, primarily investing in a strategic combination of what the Fund’s advisor believes are global ‘best in class’ institutional private real estate funds and public real estate securities.
The Advisor. The Fund’s investment advisor is Bluerock Fund Advisor, LLC (the “Advisor”), a registered advisor under the Investment Advisers Act of 1940, as amended (the “Advisers Act”). The Advisor has engaged Mercer Investments LLC (“Mercer” or a “Sub-Advisor”), a registered advisor under the Advisers Act, to provide ongoing research, opinions and recommendations of institutional asset managers and their investment funds for consideration by the Advisor on behalf of the Fund. Mercer, together with its affiliated investment businesses, have over 5,600 delegated and advisory clients globally with over $547 billion in assets under management as of September 30, 2024 and over $17.5 trillion in assets under advisement as of June 30, 2024. The Advisor has also engaged RREEF America L.L.C. (“RREEF” or a “Sub-Advisor”), a registered adviser under the Advisers Act, to provide investment management for a portion, generally less than 20%, of the Fund’s portfolio. RREEF, together with its affiliates in Europe and Asia, comprise the global real estate investment business of DWS Group GmbH & Co. KGaA (“DWS”), an indirect majority owned subsidiary of Deutsche Bank A.G. DWS’s real estate investment business, is one of the largest real estate investment managers globally with more than 330 professionals and staff located in 23 cities worldwide and approximately $78.9 billion in real estate and real estate-related assets under management as of September 30, 2024.
See “The Fund” and “Investment Objectives, Strategies and Investment Features.”
Securities Offered. The Fund engages in a continuous offering of classes of shares of beneficial interest of the Fund. Class M shares are offered by this prospectus. The Fund offers Class A, Class C, Class I and Class L shares by different prospectuses. The Fund is authorized as a Delaware statutory trust to issue an unlimited number of shares. The Fund is offering to sell, through its principal underwriter, ALPS Distributors, Inc., (the “Distributor”) on a continual basis under the terms of this prospectus, shares of beneficial interest at net asset value (“NAV”) per share of the relevant share class, plus any applicable sales load. As of January 3, 2025 the Fund’s NAV per share was $24.24 for Class M shares. The Class M shares are not subject to sales charges. The minimum initial investment by a shareholder for Class M shares is $25,000. The subsequent minimum investment in Class M shares is $10,000. The Distributor is not required to sell any specific number or dollar amount of the Fund’s shares, but will use reasonable efforts to sell the shares. No termination date of the Fund’s continuous offering has been established. Monies received will be invested promptly and no arrangements have been made to place such monies in an escrow, trust or similar account.
The Fund’s shares have no history of public trading, nor is it intended that they will be listed on a public exchange at this time. No secondary market is expected to develop for the Fund’s shares, liquidity for the Fund’s shares will be provided only through quarterly repurchase offers for no less than 5% of the Fund’s shares and there is no guarantee that an investor will be able to sell all the shares that the investor desires to sell in the repurchase offer. Investing in the Fund’s shares involves substantial risks, including the risks set forth in the “Risk Factors” section of this prospectus.
|
Investment Advisor | Bluerock Fund Advisor, LLC |

TABLE OF CONTENTS
PROSPECTUS SUMMARY |
1 |
SUMMARY OF FUND EXPENSES |
7 |
FINANCIAL HIGHLIGHTS |
8 |
THE FUND |
9 |
USE OF PROCEEDS |
9 |
INVESTMENT OBJECTIVE, POLICIES AND STRATEGIES |
9 |
RISK FACTORS |
14 |
MANAGEMENT OF THE FUND |
18 |
DETERMINATION OF NET ASSET VALUE |
23 |
CONFLICTS OF INTEREST |
24 |
QUARTERLY REPURCHASES OF SHARES |
24 |
DISTRIBUTION POLICY |
26 |
DIVIDEND REINVESTMENT POLICY |
26 |
U.S. FEDERAL INCOME TAX MATTERS |
27 |
DESCRIPTION OF CAPITAL STRUCTURE AND SHARES |
28 |
ANTI-TAKEOVER PROVISIONS IN THE DECLARATION OF TRUST |
28 |
PLAN OF DISTRIBUTION |
29 |
LEGAL MATTERS |
31 |
REPORTS TO SHAREHOLDERS |
31 |
INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM |
32 |
ADDITIONAL INFORMATION |
32 |
TABLE OF CONTENTS OF THE STATEMENT OF ADDITIONAL INFORMATION |
32 |
PRIVACY POLICY & PRACTICES |
33 |
PROSPECTUS SUMMARY
This summary does not contain all of the information that you should consider before investing in the shares. You should review the more detailed information contained or incorporated by reference in this prospectus and in the Statement of Additional Information, particularly the information set forth below under the heading “Risk Factors.”
The Fund
Bluerock Total Income+ Real Estate Fund (the “Fund”) is a continuously offered, non-diversified, closed-end management investment company. See “The Fund.” The Fund is an interval fund that provides investor liquidity by offering to make quarterly repurchases of each class of shares at that class of shares’ net asset value, which will be calculated on a daily basis. See “Quarterly Repurchases of Shares,” and “Determination of Net Asset Value.”
Investment Objectives and Policies
The Fund’s primary investment objective is to generate current income while secondarily seeking long-term capital appreciation with low to moderate volatility and low correlation to the broader markets.
The Fund pursues its investment objectives by investing, under normal circumstances, at least 80% of net assets, plus the amount of any borrowings for investment purposes, in “real estate industry securities,” primarily in income producing equity and debt securities. The Fund invests in debt securities of any duration or maturity.
The Fund concentrates investments in the real estate industry, meaning that under normal circumstances, it invests over 25% of its assets in real estate industry securities. The Fund’s investments may be targeted in any one or more of the many sectors of the real estate market, including but not limited to the retail, office, multifamily, hospitality, industrial, residential, healthcare, life sciences, and self-storage sectors. The Fund defines real estate industry securities to include the common stock, partnership or similar interests, asset-backed securities, preferred stock, and secured or unsecured debt. Real estate industry securities may be issued by a wide variety of entities including: private real estate investment funds managed by institutional investment managers (“Institutional Investment Funds”); non-traded unregistered real estate investment trusts (“Private REITs”); publicly traded real estate investment trusts or other similar companies (“Public REITs”); Government Sponsored Entities (“GSEs”) such as Federal Home Loan Mortgage Corporation Structured Pass-Through Certificates (“K-Notes”); exchange traded funds, index mutual funds, and other investment vehicles such as closed-end funds and mutual funds that invest principally, directly or indirectly, in real estate (collectively, “Other Public Investment Vehicles”) and unregistered funds that invest principally in real estate. In certain circumstances or market environments, the Fund may reduce its investment in real estate industry securities and hold a larger position in cash or cash equivalents. The Fund will not invest in any issuer that is an affiliate of the Fund, or affiliate of a Fund affiliate (as defined by the Investment Company Act of 1940, as amended (the “1940 Act”)).
The Fund’s real estate industry investment policy is fundamental and may not be changed without shareholder approval. The Fund’s Statement of Additional Information (“SAI”) contains a list of all of the fundamental and non-fundamental investment policies of the Fund, under the heading “Investment Objectives and Policies.”
Investment Strategy
The Fund pursues its investment objectives using a comprehensive multi-strategy, multi-manager, multi-sector approach, primarily investing in a strategic combination of global ‘best in class’ institutional private real estate investment funds and public real estate securities.
The term ‘best in class’ refers to Institutional Investment Funds the Advisor has identified as offering above average prospects using information provided by Mercer and its proprietary screening process. Mercer’s screening process applies multiple factors including quantitative and qualitative assessment (as described more fully below) of the management team and track record, and is not generally available to the individual investor through financial filings or published reports. Mercer is one of the leading advisors to endowments, pension funds, sovereign wealth funds, and family offices globally.
The Fund executes a portion of its investment strategy, generally less than 20%, by seeking to invest in publicly traded real estate securities selected by RREEF, an indirect subsidiary of DWS. RREEF seeks to maximize risk-adjusted returns by managing volatility and identifying securities that are priced inefficiently relative to its assessment of intrinsic value and the public real estate securities may be of any credit quality; including fixed-income and preferred securities rated less than investment grade that are sometimes referred to as high yield or “junk bonds.” The Advisor or RREEF will sell a security when other securities are available that offer higher expected current income, long-term capital appreciation, lower volatility or lower correlation to broader securities markets or a combination of the preceding.
The Fund may utilize leverage through borrowing for investment purposes or to satisfy repurchase requests. The Fund currently borrows money under two credit facilities.
Many of the Institutional Investment Funds have a large minimum investment size and stringent investor qualification criteria that are intended to limit their direct investors to mainly institutions such as endowments and pension funds. As such, the Fund enables investors to invest with institutional investment managers that may not be otherwise permitted or available to them.
In addition, the Fund enables investors to execute a comprehensive multi-strategy, multi-manager, multi-sector strategy by making a single investment in the Fund, whereas due to the large minimums of many of the Institutional Investment Funds, such a strategy may not otherwise be permitted or available to the investor.
1 |
The Advisor also believes that the Fund may be able to provide an additional benefit in terms of lower fees from the Institutional Investment Funds as a result of volume discounts that may not otherwise be permitted or available to them.
Investment Advisor
Bluerock Fund Advisor, LLC was formed on May 11, 2012 and is registered with the SEC as an investment adviser. The Advisor is a subsidiary of Bluerock Asset Management, LLC (“BAM”); BAM, together with its affiliates (“Bluerock”), is a leading institutional alternative asset manager with more than $19.2 billion in acquired and managed assets based in New York with regional offices across the United States. Bluerock principals have a collective 100+ years of investing experience with more than $120 billion of real estate and capital markets experience and manage multiple well-recognized real estate private and public company platforms.
Sub-Advisors
The Advisor may, from time to time, engage one or more investment sub-advisors. Any sub-advisor chosen by the Advisor will be paid by the Advisor on only the portion of Fund assets allocated to any such sub-advisor. Shareholders do not pay any sub-advisor directly.
The Advisor has engaged Mercer, a registered investment adviser under the Advisers Act, to provide both ongoing research and opinions of institutional asset managers and their investment funds for consideration by the Advisor on behalf of the Fund as well as recommendations for the selection of investment funds for approval by the Advisor. The Advisor has engaged RREEF, a registered investment adviser under the Advisers Act, to invest a portion of the Fund’s portfolio in publicly traded real estate securities and to provide the Advisor with research and information with respect to non-publicly traded real estate related debt securities.
Advisor Fees and Expenses
The Advisor is entitled to receive a monthly fee at the annual rate of 1.50% of the Fund’s daily net assets. The Advisor and the Fund have entered into an expense limitation and reimbursement agreement (the “Expense Limitation Agreement”) under which the Advisor has contractually agreed to waive its fees and to pay or absorb the ordinary operating expenses of the Fund (excluding any taxes, interest, brokerage commissions, acquired fund fees and expenses, and extraordinary expenses, such as litigation or reorganization costs, but including organizational costs and offering costs), to the extent that such expenses exceed 2.45% per annum of the Fund’s average daily net assets (the “Expense Limitation”) attributable to Class M shares. In consideration of the Advisor’s agreement to limit the Fund’s expenses, the Fund has agreed to repay the Advisor in the amount of any fees the Advisor previously waived or Fund expenses reimbursed, subject to the limitations that: (1) the reimbursement will be made if payable not more than three years from the date incurred; (2) the reimbursement may not be made if it would cause the expense limitation then in effect or in effect at the time of the waiver to be exceeded; and (3) the reimbursement is approved by the Fund’s Board of Trustees (the “Board”). The Expense Limitation Agreement will remain in effect at least until January 31, 2026, unless and until the Board approves its modification or termination. After January 31, 2026, the Expense Limitation Agreement may be renewed at the Advisor’s and Board’s discretion. See “Management of the Fund.”
Administrator, Accounting Agent and Transfer Agent
ALPS Fund Services, Inc. (the “Administrator”) serves as the Fund’s administrator and accounting agent. SS&C Global Investor & Distribution Solutions, Inc. (the “Transfer Agent” or “SS&C GIDS”) serves as the transfer agent of the Fund. See “Management of the Fund.”
Distribution Fees
Class M shares will pay to the Distributor a distribution fee (the “Distribution Fee”) that will accrue at an annual rate equal to 0.75% of the Fund’s average daily net assets attributable to Class M shares and is payable on a monthly basis. See “Plan of Distribution.”
Closed-End Fund Structure
Generally, closed-end funds differ from mutual funds in that closed-end funds do not typically redeem their shares at the option of the shareholder. Closed-end fund shares typically trade in the secondary market via a stock exchange. Unlike many closed-end funds, however, the Fund’s shares will not be listed on a stock exchange. Instead, the Fund will provide limited liquidity to shareholders by offering to repurchase a limited amount of the Fund’s shares (at least 5%) quarterly, which is discussed in more detail below. The Fund, similar to a mutual fund, is subject to continuous asset in-flows, although not subject to continuous out-flows.
Share Classes
The Fund offers Class M shares by this prospectus. The Fund began continuously offering its common shares on October 22, 2012. As of February 18, 2014, the Fund simultaneously redesignated its issued and outstanding common shares as Class A shares and created its Class C shares and Class I shares, each offered by a separate prospectus. As of May 30, 2017, the Fund created its Class L shares. As of February 1, 2020, the Fund created its Class M shares. An investment in any share class of the Fund represents an investment in the same assets of the Fund. However, the sales loads and ongoing fees and expenses for each share class are different. The loads, fees and expenses for the Fund are set forth in “Summary of Fund Expenses.” If an investor has hired an intermediary and is eligible to invest in more than one class of shares, the intermediary may help determine which share class is appropriate for that investor. When selecting a share class, you should consider which share classes are available to you, how much you intend to invest, the investment minimum, how long you expect to own shares, and the total costs and expenses associated with a particular share class.
2 |
Each investor’s financial considerations are different. You should speak with your financial advisor to help you decide which share class is best for you. Not all financial intermediaries offer all classes of shares and all share classes may not be available in every state. If your financial intermediary offers more than one class of shares, you should carefully consider which class of shares to purchase.
Investor Suitability
An investment in the Fund involves a considerable amount of risk. It is possible that you will lose some or all of your money. An investment in the Fund is suitable only for investors who can bear the risks associated with the limited liquidity of the shares and should be viewed as a medium to long-term investment. Before making your investment decision, you should (i) consider the suitability of this investment with respect to your investment objectives and personal financial situation and (ii) consider factors such as your personal net worth, income, age, risk tolerance and liquidity needs.
Repurchases of Shares
The Fund is an interval fund and, as such, has adopted a fundamental policy to make quarterly repurchase offers, at net asset value, of no less than 5% of the Fund’s outstanding shares. There is no guarantee that shareholders will be able to sell all of the shares they desire to sell in a quarterly repurchase offer. Liquidity will be provided to shareholders only through the Fund’s quarterly repurchases. See “Quarterly Repurchases of Shares.”
Summary of Risks
Investing in the Fund involves risks, including the risk that you may receive little or no return on your investment or that you may lose part or all of your investment. Before investing you should consider carefully the risks that you assume when you invest in the Fund’s shares. See “Risk Factors.”
Real Estate Industry Concentration Risk. The Fund will concentrate its investments in real estate related securities, and it may invest in real estate directly. As such, its portfolio will be significantly impacted by the performance of the real estate market and may experience more volatility and be exposed to greater risk than a more diversified portfolio. The value of companies engaged in the real estate industry is affected by: (i) changes in general economic and market conditions; (ii) changes in the value of real estate properties; (iii) risks related to local economic conditions, overbuilding and increased competition; (iv) increases in property taxes and operating expenses; (v) changes in zoning laws; (vi) casualty and condemnation losses; (vii) variations in rental income, neighborhood values or the appeal of property to tenants; (viii) the availability of financing; (ix) climate change and (x) changes in interest rates and leverage. There are also special risks associated with particular sectors, or real estate operations, including, but not limited to, those risks described below:
Retail Properties. Retail properties are affected by shifts in consumer demand due to demographic changes, changes in spending patterns and lease terminations.
Office Properties. Office properties are affected by a downturn in the businesses operated by their tenants.
Hospitality Properties. Hotel properties and other properties in the hospitality real estate sector, such as motels and extended-stay properties, are affected by declines in business and leisure travel.
Healthcare and Life Sciences Properties. Healthcare and life sciences properties are affected by potential federal, state and local laws governing licenses, certification, adequacy of care, pharmaceutical distribution, rates, equipment, personnel and other factors regarding operations, funding for biotech companies and the continued availability of revenue from government reimbursement programs.
Industrial Properties. Industrial properties are affected by downturns in the manufacturing, processing and shipping of goods.
Multifamily Properties. Multifamily properties are affected by adverse economic conditions in the locale, oversupply and rent control laws.
Residential Properties. Residential properties can be significantly affected by the national, regional and local real estate markets. This segment of the real estate industry also is sensitive to interest rate fluctuations which can cause changes in the availability of mortgage capital and directly affect the purchasing power of potential homebuyers. Thus, residential properties can be significantly affected by changes in government spending, consumer confidence, demographic patterns and the level of new and existing home sales.
Shopping Centers. Shopping center properties are affected by changes in the local markets where their properties are located and dependent upon the successful operations and financial condition of their major tenants.
Self-Storage Properties. Self-storage properties are affected by changes to competing local properties, consumer and small business demand for storage space, and the ability of the management team.
Other factors may contribute to the risk of real estate investments:
Development Issues. Real estate development companies in which the Underlying Funds (defined below) or the Fund may invest are affected by construction delays and insufficient tenant demand to occupy newly developed properties.
3 |
Lack of Insurance. Certain of the companies in the Fund’s portfolio may fail to carry comprehensive liability, fire, flood, wind or earthquake extended coverage and rental loss insurance, or insurance and may be subject to various policy specifications, limits and deductibles. Due to the prevalence of catastrophic events, the cost of insurance may increase materially.
Dependence on Tenants. The ability of companies in the real estate industry in which the Fund may invest to make distributions to shareholders depends upon the ability of the tenants at their properties to generate enough income in excess of tenant operating expenses to make their lease payments.
Financial Leverage. Companies in the real estate industry in which the Fund may invest may be highly leveraged and financial covenants may affect their ability to operate effectively. The use of floating rate loans may also negatively impact returns in a rising interest rate environment.
Environmental Issues. Owners of properties that may contain hazardous or toxic substances may be responsible for removal or remediation costs. Environmental risk from high winds, hurricanes, fires, flood and extreme heat may also materially affect a property’s value.
Credit Market Conditions. Instability in credit markets can potentially make it more difficult for borrowers to obtain financing or refinancing on attractive terms or at all. Conditions in the credit markets may expose borrowers to increased interest expenses for borrowed money and tightening underwriting standards. There is also a risk that a general lack of liquidity or other events in the credit markets may adversely affect the ability of issuers in whose securities the Fund invests to finance real estate developments and projects or refinance completed projects.
Market Risk. An investment in shares is subject to investment risk, including the possible loss of the entire principal amount invested. An investment in shares represents an indirect investment in the securities owned by the Fund. The value of these securities, like other market investments, may move up or down, sometimes rapidly and unpredictably. In addition, the Fund is subject to the risk that geopolitical and other similar events will disrupt the economy on a national or global level. For instance, war, terrorism, market manipulation, government defaults, government shutdowns, political changes or diplomatic developments, public health emergencies (such as the spread of infectious diseases, pandemics and epidemics) and natural/environmental disasters can all negatively impact the securities markets.
Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. The foregoing could impair the Fund’s ability to maintain operational standards, disrupt the operations of the Fund and its service providers, adversely affect the performance, value and liquidity of the Fund’s investments, and negatively impact the Fund’s performance and your investment in the Fund. The value of your shares at any point in time may be worth less than the value of your original investment, even after taking into account any reinvestment of dividends and distributions.
Liquidity Risk. There currently is no secondary market for the Fund’s shares and the Advisor does not expect that a secondary market will develop. Limited liquidity is provided to shareholders only through the Fund’s quarterly repurchase offers for no less than 5% of the Fund’s shares outstanding at net asset value. There is no guarantee that shareholders will be able to sell all of the shares they desire in a quarterly repurchase offer. The Fund’s investments also are subject to liquidity risk. Liquidity risk exists when particular investments of the Fund would be difficult to purchase or sell, possibly preventing the Fund from selling such illiquid securities at an advantageous time or price, or possibly requiring the Fund to dispose of other investments at unfavorable times or prices in order to satisfy its obligations.
Allocation Risk. The ability of the Fund to achieve its investment objective depends, in part, on the ability of the Advisor to allocate effectively the Fund’s assets among the various Institutional Investment Funds, Private REITs, Public REITs and Other Public Investment Vehicles in which the Fund invests and, with respect to each such asset class, among equity and fixed income securities. There can be no assurance that the actual allocations will be effective in achieving the Fund’s investment objective or delivering positive returns.
Correlation Risk. The Fund seeks to produce returns that are not correlated to the broader financial markets. Although the prices of equity securities and fixed-income securities, as well as other asset classes, often rise and fall at different times so that a fall in the price of one may be offset by a rise in the price of the other, in down markets the prices of these securities and asset classes can also fall in tandem. Because the Fund allocates its investments among different real estate asset classes, the Fund is subject to correlation risk.
Credit Risk. It is possible that issuers of debt securities may not make scheduled interest and principal payments, resulting in losses to the Fund. In addition, the credit quality of securities held may be lowered if an issuer’s financial condition changes and this also may negatively impact the Fund’s returns on investment in such securities.
Distribution Policy Risk. The Fund’s distribution policy is expected to result in distributions that equal a fixed percentage of the Fund’s current net asset value per share. All or a portion of a distribution may consist of a return of capital (i.e. from your original investment). Shareholders should not assume that the source of a distribution from the Fund is net profit. Shareholders should note that return of capital will reduce the tax basis of their shares and potentially increase the taxable gain, if any, upon disposition of their shares.
Fixed Income Risk. Typically, a rise in interest rates causes a decline in the value of fixed income securities. Recently, interest rates have risen sharply after maintaining historically low levels for a significant period of time. Current conditions may result in an increase in interest rate volatility, which in turn may result in a decline in the value of the fixed income investments held by the Fund. As a result, for the present, interest rate risk may be heightened. Fixed income securities are also subject to default risk.
4 |
Institutional Investment Fund Risk. The Fund’s investment in Institutional Investment Funds will require it to bear a pro rata share of the vehicles’ expenses, including management and performance fees. The fees the Fund pays to invest in an Institutional Investment Fund may be higher than if the manager of the Institutional Investment Fund managed the Fund’s assets directly. The performance fees charged by certain Institutional Investment Funds may create an incentive for its manager to make investments that are riskier and/or more speculative than those it might have made in the absence of a performance fee. Furthermore, Institutional Investment Funds, like the other Underlying Funds in which the Fund may invest, are subject to specific risks, depending on the nature of the vehicle, and also may employ leverage such that their returns are more than one times that of their benchmark which could amplify losses suffered by the Fund when compared to unleveraged investments. Shareholders of the Institutional Investment Funds are not entitled to the protections of the 1940 Act. For example, these funds need not have independent boards, shareholder approval of advisory contracts may not be required, may leverage to an unlimited extent, and may engage in joint transactions with affiliates. These characteristics present additional risks for shareholders.
Issuer and Non-Diversification Risk. The value of a specific security can perform differently from the market as a whole for reasons related to the investment manager or issuer, such as management performance, financial leverage and reduced demand for the respective properties and services. The Fund’s performance may be more sensitive to any single economic, business, political or regulatory occurrence than the value of shares of a diversified investment company because as a non-diversified fund, the Fund may invest more than 5% of its total assets in the securities of one or more issuers.
Lack of Control Over Institutional Investment Funds and Other Portfolio Investments. Once the Advisor or RREEF has selected an Institutional Investment Fund, Private REIT, Public REIT, or Other Public Investment Vehicle (each, an “Underlying Fund” and together, the “Underlying Funds”) for investment by the Fund, the Advisor and RREEF will have no control over the investment decisions made by any such Underlying Fund. Although the Fund and the Advisor or RREEF will evaluate regularly each Underlying Fund and its manager to determine whether their respective investment programs are consistent with the Fund’s investment objective, the Advisor and RREEF will not have any control over the investments made by any Underlying Fund. Even though the Underlying Funds are subject to certain constraints, the managers may change aspects of their investment strategies. The managers may do so at any time (for example, such change may occur immediately after providing the Advisor with the quarterly unaudited financial information for an Institutional Investment Fund). The Advisor or RREEF may reallocate the Fund’s investments among the Underlying Funds, but the Advisor’s ability to do so may be constrained by the withdrawal limitations imposed by certain of the Underlying Funds, which may prevent the Fund from reacting rapidly to market changes should an Underlying Fund fail to effect portfolio changes consistent with such market changes and the demands of the Advisor. Such withdrawal limitations may also restrict the Advisor’s ability to terminate investments in Underlying Funds that are poorly performing or have otherwise had adverse changes. The Advisor and RREEF will be dependent on information provided by the Underlying Fund, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s or RREEF’s ability to manage the Fund’s investment portfolio in accordance with its investment objectives.
Leveraging Risk. The use of leverage, such as borrowing money to purchase securities or otherwise invest the Fund’s assets, will cause the Fund to incur additional expenses and may significantly magnify the Fund’s losses in the event of adverse performance of the Fund’s underlying investments. In addition to any borrowing utilized by the Fund, the Underlying Funds in which the Fund invests may utilize leverage, subject to the limitations of their charters and operative documents. Leverage by Underlying Funds and/or the Fund has the effect of potentially increasing losses. In addition, interest rates (including benchmarks like Secured Overnight Financing Rate (“SOFR”) and the spreads to such benchmarks charged by lenders) are highly sensitive to external factors outside a borrower’s control, including general and local economic conditions (such as inflation, recession, money supply and unemployment) and the monetary and fiscal policies of various governmental agencies such as the Federal Reserve Board. During periods of increased interest rates, borrowing costs of the Fund will likely increase and may adversely affect the Fund’s performance.
Management Risk. The judgments of the Advisor or a Sub-Advisor about the attractiveness, value and potential appreciation of particular real estate segment and securities in which the Fund invests may prove to be incorrect and may not produce the desired results.
Possible Competition Between Underlying Funds and Between the Fund and the Underlying Funds. The Underlying Funds trade independently of each other and may pursue investment strategies that “compete” with each other for execution or that cause the Fund to participate in positions that offset each other (in which case the Fund would bear its pro rata share of commissions and fees without the potential for a profit). Also, the Fund’s investments in any particular Underlying Fund could increase the level of competition for the same trades that other Underlying Funds might otherwise make, including the priorities of order entry. This could make it difficult or impossible to take or liquidate a position in a particular security at a price consistent with the Advisor’s strategy.
Preferred Securities Risk. Preferred securities are subject to credit risk and interest rate risk. Interest rate risk is, in general, that the price of a debt security falls when interest rates rise. Securities with longer maturities tend to be more sensitive to interest rate changes. Credit risk is the risk that an issuer of a security may not be able to make principal and interest or dividend payments on the security as they become. Holders of preferred securities may not receive dividends, or the payment can be deferred for some period of time. In bankruptcy, creditors are generally paid before the holders of preferred securities.
REIT Risk. The value of investments in REIT shares may decline because of adverse developments affecting the real estate industry and real property values. In general, real estate values can be affected by a variety of factors, including supply and demand for properties, the economic health of the country or of different regions, and the strength of specific industries that rent properties. Also, qualification as a REIT under the Internal Revenue Code of 1986, as amended (the “Code”) in any particular year is a complex analysis that depends on a number of factors. There can be no assurance that an entity in which the Fund invests with the expectation that it will be taxed as a REIT will, in fact, qualify as a REIT. An entity that fails to qualify as a REIT would be subject to a corporate level tax, would not be entitled to a deduction for dividends paid to its shareholders and would not pass through to its shareholders the character of income earned by the entity.
5 |
Repurchase Policy Risks. Quarterly repurchases by the Fund of its shares typically will be funded from available cash or sales of portfolio securities. The sale of securities to fund repurchases could reduce the market price of those securities, which in turn would reduce the Fund’s net asset value.
Underlying Funds Risk. Investments in real estate index funds (“Index Funds”), real estate exchange traded funds (“ETFs”), and Other Public Investment Vehicles are subject to investment advisory and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in such Other Public Investment Vehicles, and also may be higher than other funds that invest directly in securities. Further, Other Public Investment Vehicles are subject to specific risks, depending on the nature of the fund.
Valuation of Institutional Investment Funds. Institutional Investment Funds are not publicly traded and the Fund may consider information provided by the institutional asset manager to determine the value of the Fund’s investment therein. The valuation provided by an institutional asset manager as of a specific date may vary from the actual sale price that may be obtained if such investment were sold to a third party. To determine the value of the Fund’s investment in Institutional Investment Funds, the Advisor considers, among other things, information provided by the Institutional Investment Funds, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s ability to value accurately the Fund’s shares. Institutional Investment Funds that invest primarily in publicly traded securities are more easily valued.
U.S. Federal Income Tax Matters
The Fund intends to elect to be treated and to qualify each year for taxation as a regulated investment company under Subchapter M of the Code. In order for the Fund to so qualify, it must meet an income and asset diversification test each year. If the Fund so qualifies and satisfies the applicable distribution requirements, the Fund (but not its shareholders) will not be subject to federal income tax to the extent it distributes its investment company taxable income and net capital gains (the excess of net long-term capital gains over net short-term capital loss) in a timely manner to its shareholders in the form of dividends or capital gain distributions. The Code imposes a 4% nondeductible excise tax on regulated investment companies, such as the Fund, to the extent they do not meet certain distribution requirements by the end of each calendar year. The Fund anticipates meeting these distribution requirements. See “U.S. Federal Income Tax Matters.”
Distribution Policy
The Fund’s distribution policy is to make quarterly distributions to shareholders. The level of distributions (including any return of capital) is not fixed, but is expected to represent an annual rate of approximately 5.25% of the Fund’s current net asset value per share. However, this distribution policy is subject to change. Unless a shareholder elects otherwise, the shareholder’s distributions will be reinvested in additional shares of the same class under the Fund’s dividend reinvestment policy. Shareholders who elect not to participate in the Fund’s dividend reinvestment policy will receive all distributions in cash paid to the shareholder of record (or, if the shares are held in street or other nominee name, then to such nominee). See “Dividend Reinvestment Policy.”
Custodian
UMB Bank, N.A. (“UMB Bank”) serves as the custodian for the Fund. See “Management of the Fund.”
6 |
SUMMARY OF FUND EXPENSES
Shareholder Transaction Expenses |
Class M |
Maximum Sales Load |
|
Maximum Early Withdrawal Charge (as a percent of original purchase price) |
Annual Expenses (as a percentage of net assets attributable to shares) |
|
Management Fees |
|
Other Expenses |
|
Shareholder Servicing Fee |
|
Distribution Fee1 |
|
Remaining Other Expenses |
|
Interest Payments on Borrowed Funds2 |
|
Acquired Fund Fees and Expenses |
|
Total Annual Expenses |
|
|
1. |
|
|
2. |
|
The above Summary of Fund Expenses table describes the fees and expenses that you may pay if you buy and hold shares of the Fund. More information about management fees, fee waivers and other expenses is available in Management of the Fund starting on page 18 of this prospectus.
The following example illustrates the hypothetical expenses that you would pay on a $1,000 investment assuming annual expenses attributable to shares remain unchanged and shares earn a 5% annual return:
Share Class |
1 Year |
3 Years |
5 Years |
10 Years |
Class M Shares |
$ |
$ |
$ |
$ |
Shareholders who choose to participate in repurchase offers by the Fund will not incur an early withdrawal charge, unless the repurchase is less than 365 days after purchase by a shareholder. However, if shareholders request repurchase proceeds be paid by wire transfer, such shareholders will be assessed an outgoing wire transfer fee at prevailing rates charged by the Transfer Agent, currently $10. The purpose of the above table is to help a holder of shares understand the fees and expenses that such holder would bear directly or indirectly. The example should not be considered a representation of actual future expenses. Actual expenses may be higher or lower than those shown.
7 |
FINANCIAL HIGHLIGHTS
Class M Shares
The financial highlights table below is intended to help you understand the Fund’s financial performance since its inception. Certain information reflects financial results for a single Share. The total returns in the table represent the rate that an investor would have earned (or lost) on an investment in the Fund (assuming reinvestment of all dividends and other distributions). This information has been derived from the Fund’s financial statements, which have been audited by Cohen & Company, Ltd., the Fund’s independent registered public accounting firm, whose report, along with the Fund’s financial statements, is included in the Fund’s Annual Report for the fiscal year ended September 30, 2024, which is available upon request.
|
For the |
For the |
For the |
|||||||||
Net asset value, beginning of period/year |
$ | 28.80 | $ | 34.93 | $ | 31.78 | ||||||
INCOME FROM INVESTMENT OPERATIONS: |
||||||||||||
Net investment income/(loss)(b) |
(0.43 | ) | (0.30 | ) | 0.14 | |||||||
Net realized and unrealized gain/(loss) |
(2.26 | ) | (4.17 | ) | 4.39 | |||||||
Total from investment operations |
(2.69 | ) | (4.47 | ) | 4.53 | |||||||
DISTRIBUTIONS: |
||||||||||||
From net realized gain on investments |
(0.14 | ) | (0.19 | ) | — | |||||||
Return of capital |
(1.25 | ) | (1.47 | ) | (1.38 | ) | ||||||
Total distributions |
(1.39 | ) | (1.66 | ) | (1.38 | ) | ||||||
Net asset value, end of period/year |
$ | 24.72 | $ | 28.80 | $ | 34.93 | ||||||
TOTAL RETURN(c)(d) |
(9.51 | )% | (13.07 | )% | 14.35 | %(e) | ||||||
RATIOS/SUPPLEMENTAL DATA: |
||||||||||||
Net assets, end of period/year (000s) |
$ | 110,851 | $ | 135,176 | $ | 135,362 | ||||||
Ratios to Average Net Assets (including interest expense) |
||||||||||||
Ratio of expenses to average net assets excluding fee waivers and reimbursements(f)(g) |
4.30 | % | 3.66 | % | 2.46 | %(h) | ||||||
Ratio of expenses to average net assets including fee waivers and reimbursements(f) |
4.30 | % | 3.66 | % | 2.46 | %(h) | ||||||
Ratio of net investment income/(loss) to average net assets(f) |
(1.63 | )% | (0.94 | )% | 0.54 | %(h) | ||||||
Ratios to Average Net Assets (excluding interest expense) |
||||||||||||
Ratio of expenses to average net assets excluding fee waivers and reimbursements(f)(g) |
2.43 | % | 2.44 | % | 2.35 | %(h) | ||||||
Ratio of expenses to average net assets including fee waivers and reimbursements(f) |
2.43 | % | 2.44 | % | 2.35 | %(h) | ||||||
Portfolio turnover rate |
14 | % | 13 | % | 4 | % | ||||||
|
(a) |
Class M commenced operations on December 27, 2021. |
|
(b) |
Per share amounts are calculated using the average shares method. |
|
(c) |
Total returns are historical in nature and assumes changes in net asset value per share, reinvestment of dividends and capital gains distributions, if any. Had the Advisor not absorbed a portion of the Fund expenses, total returns would have been lower. |
|
(d) |
Includes adjustments in accordance with accounting principles generally accepted in the United States and, consequently, the net asset value for financial reporting purposes and the returns based upon those net asset values may differ from the net asset values and returns for shareholder transactions. |
|
(e) |
Not annualized. |
|
(f) |
The ratios of expenses to average net assets and net investment income (loss) to average net assets do not directly reflect the expenses of the underlying institutional private real estate investments in which the Fund invests. The Fund invests in each underlying institutional private real estate investment based upon its net asset value, inclusive of management fees, which typically range from 0.50% to 1.30% on an annualized basis. The Fund’s Total Return is reported net of all fees and expenses. |
|
(g) |
Represents the ratio of expenses to average net assets absent fee waivers expense reimbursement and/or recoupment by the Advisor. |
|
(h) |
Annualized. |
8 |
THE FUND
The Fund is a continuously offered, non-diversified, closed-end management investment company that is operated as an interval fund. The Fund was organized as a Delaware statutory trust on May 25, 2012. The Fund’s principal office is located at 919 Third Avenue, 40th Floor, New York, NY 10022, and its telephone number is 1-844-819-8287.
USE OF PROCEEDS
The net proceeds of the Fund’s continuous offering of shares, after payment of the sales load (if applicable) and other associated expenses, will be invested in accordance with the Fund’s investment objective and policies (as stated below) as soon as practicable after receipt. The Fund pays organizational costs and its offering expenses incurred with respect to its initial and continuous offering. Pending investment of the net proceeds in accordance with the Fund’s investment objective and policies, the Fund will invest in money market or short-term fixed-income mutual funds. Investors should expect, therefore, that before the Fund has fully invested the proceeds of the offering in accordance with its investment objective and policies, the Fund’s assets would earn interest income at a modest rate.
INVESTMENT OBJECTIVE, POLICIES AND STRATEGIES
Investment Objective and Policies
The Fund seeks primarily to generate current income while secondarily seeking long-term capital appreciation with low to moderate volatility and low correlation to the broader markets.
The Fund pursues its investment objectives by investing, under normal circumstances, at least 80% of its net assets, plus the amount of any borrowings for investment purposes, in real estate industry securities, primarily in income producing equity and debt securities. The Fund’s investments may be targeted in any one or more of the many sectors of the real estate market, including but not limited to the retail, office, multifamily, hospitality, industrial, residential, healthcare, life sciences, and self-storage sectors. The Fund concentrates investments in the real estate industry, meaning that under normal circumstances, it invests over 25% of its assets in real estate industry securities. The Fund may utilize leverage through borrowing for investment purposes or to satisfy repurchase requests. The Fund currently borrows money under two credit facilities.
The Fund defines real estate industry securities to include the common stock, partnership or similar interests, asset-backed securities, preferred stock, and secured or unsecured debt. Real estate industry securities may be issued by a wide variety of entities including: private real estate investment funds managed by institutional investment managers (“Institutional Investment Funds”); non-traded unregistered real estate investment trusts (“Private REITs”); publicly traded real estate investment trusts or other similar companies (“Public REITs”); Government Sponsored Entities (“GSEs”) such as Federal Home Loan Mortgage Corporation Structured Pass-Through Certificates (“K-Notes”), exchange traded funds, index mutual funds, and other investment vehicles such as closed-end funds and mutual funds that invest principally, directly or indirectly, in real estate (collectively, “Other Public Investment Vehicles”) and unregistered funds that invest principally in real estate.
The Fund may invest in issuers of real estate industry securities of any credit quality; including fixed-income and preferred securities rated less than investment grade that are sometimes referred to as high yield or “junk bonds.” The Fund may invest in debt securities of any duration or maturity. The Fund may also, to a limited extent, make real estate-related investments other than through real estate industry securities. The Advisor or RREEF will sell a security when other securities are available that offer higher expected current income, higher expected long-term capital appreciation, lower volatility or lower correlation to broader securities markets or a combination of the preceding.
The Fund’s SAI contains a list of the fundamental (those that may not be changed without a shareholder vote) and non-fundamental (if any) investment policies of the Fund under the heading “Investment Objective and Policies.”
Fund’s Target Investment Portfolio
The Advisor executes the Fund’s real estate investment strategy primarily through a strategic combination of global ‘best in class’ Institutional Investment Funds, publicly traded real estate securities, and real estate related debt investments. The Fund will not invest more than 10% of the Fund’s assets in private funds employing hedging strategies (commonly known as “hedge funds”, i.e., investment funds that would be investment companies but for the exemptions under Rule 3(c)(1) or 3(c)(7) under the 1940 Act).
The Advisor has retained Mercer to provide ongoing research and investment opinions of and/or recommendations of institutional investment managers using the Mercer’s proprietary screening process, which applies multiple factors based on quantitative and qualitative assessment of the management team and track record. The Advisor has engaged RREEF to invest a portion of the Fund’s portfolio, generally less than 20%, in publicly traded real estate securities (Public REITs and Other Public Investment Vehicles). RREEF selects securities to seek to maximize risk-adjusted returns by managing volatility and identifying securities that are priced inefficiently relative to its assessment of intrinsic value.
Institutional Investment Funds. Institutional Investment Funds are real estate investment funds managed by institutional investment managers with expertise in managing portfolios of real estate and real estate-related securities. Many Institutional Investment Funds have large minimum investment requirements and stringent investor qualification criteria intended to limit their direct investors to mainly institutions such as endowments and pension funds. It is the intent of the Fund to provide an element of the endowment model of investing to individual investors by permitting access to a portfolio of Institutional Investment Funds with diversification across multiple strategies, managers and sectors.
9 |
The Advisor also believes that the Fund may provide an additional benefit in terms of better fee pricing from the Institutional Investment Funds as a result of volume discounts, which pricing benefits may not otherwise be permitted or available to other investors. In addition, the Fund’s investments in Institutional Investment Funds are intended to deliver returns that have a low correlation to the broader markets.
The Fund’s typical investments in Institutional Investment Funds will be made through the purchase of common stock, limited liability company units, or limited partnership interests (or similar interests). Investment criteria will include evaluating a combination of strength of the sponsor and management; prior investment performance of the target fund as well as the performance of other funds managed by the sponsor; the attractiveness of the property sectors and geographical allocations of the fund; expected stability of income; expected capital appreciation, and target leverage levels.
REITs. The Fund may invest, directly or indirectly, in Real Estate Investment Trusts (“REITs”). REITs are investment vehicles that invest primarily in income-producing real estate or mortgages and other real estate-related loans or interests. Public REITs are listed on major stock exchanges such as the New York Stock Exchange (“NYSE”) or the National Association of Securities Dealers Automated Quotation System (“NASDAQ”), and invest directly in real estate, typically through either properties or mortgages.
Other Public Investment Vehicles. The Fund anticipates making limited investments in Other Public Investment Vehicles, including ETFs and Index Funds that invest primarily in real estate related assets, principally to temporarily invest the Fund’s capital pending its deployment into other higher-returning investment opportunities, or for temporary defensive purposes under adverse market conditions.
Exchange Traded Funds (“ETFs”). ETFs are typically managed by professionals and provide investors with diversification, cost and tax efficiency, liquidity, marginability, are useful for hedging, have the ability to go long and short, and some provide quarterly dividends. An ETF typically holds a portfolio of securities or contracts designed to track a particular market segment or index. ETFs are listed on major stock exchanges and are traded like stocks.
Index Funds. An Index Fund is a mutual fund with an investment objective of seeking to replicate the performance of a specific securities index, such as the National Association of Real Estate Investment Trusts (NAREIT) Index or the MSCI REIT Index. Most Index Funds are not actively managed and generally provide broad market exposure, low operating expenses and low portfolio turnover.
Other. In addition to ETFs and Index Funds, and subject to the Fund’s investment restrictions, the Fund may invest in investment companies that invest primarily in what the Advisor considers real estate industry securities, including closed-end funds and mutual funds. Shares of Closed-end Funds are typically listed for trading on major stock exchanges and, in some cases, may be traded in other over-the-counter markets.
Real Estate Related Debt Investments. The Fund may invest in real estate related direct debt including first and second mortgage loans, mezzanine loans and other structured debt investments.
Investment Strategy, and Criteria Used by the Advisor and Mercer in Selecting Investments
The Fund’s investment strategy focuses primarily on identifying Institutional Investment Funds that have:
|
● |
attractive risk-adjusted returns; |
|
● |
with low to moderate volatility; |
|
● |
low correlation to the broader markets; and |
|
● |
an emphasis on income generation. |
The Fund utilizes a comprehensive multi-manager, multi-sector, and multi-strategy approach. The Advisor primarily selects funds with the highest expected risk-adjusted returns from a real estate sector peer group of issuers with similar market capitalization and/or credit quality. Secondarily, the Advisor considers potential for capital appreciation. When constructing and balancing the Fund’s portfolio, the Advisor selects funds from real estate sectors that it believes have relatively low volatility and will not be highly correlated to each other or to the equity or fixed income markets, generally.
The Advisor, working closely with Mercer and in consideration of its recommendations, uses both a quantitative screening process and a qualitative selection process when selecting investments for the Fund to implement its real estate investment strategy. The Advisor and Mercer conduct research on various real estate investment managers and investment options in order to establish a selection of investments to fulfill the Fund’s investment objectives. Mercer’s assistance and recommendations for selection of investment funds are made according to asset allocation, return expectations and other guidelines set by the Advisor with oversight of the Board. No assurance can be given that any or all investment strategies, or the Fund’s investment program, will be successful.
Investment Strategy – Mercer Process
Mercer’s process begins with a proprietary database created and continuously maintained by its professionals - the Global Investment Manager Database (GIMD™) which gives Mercer access to up-to-date information and insights on a worldwide matrix of investment managers and strategies. GIMD™ contains information on numerous investment types across all asset classes, including real estate. This information ranges from access to and analysis of performance data to qualitative forward-looking research on investment
10 |
managers supported by screening functionality. In the twelve months leading up to September 30, 2024, over 2,700 formal manager meetings were held and over 3,600 Research Reports were produced globally. As of September 30, 2024, GIMD™ contained information on over 6,800 investment managers and over 32,300 investment strategies.
Mercer, together with its global investment management affiliates, have over 3,300 delegated clients globally.
The Advisor has entered into a Sub-Advisory Agreement with Mercer Investments LLC (“Mercer” or a “Sub-Advisor”), 99 High Street, Boston, MA 02110.

The Advisor, in conjunction with Mercer, employs a regimen of quantitative and qualitative criteria to arrive at a universe of investments which are considered to be ‘best in class.’ By combining historical quantitative analysis with a sound knowledge of key qualitative attributes, the Advisor will evaluate a prospective investment’s potential for generating sustainable, positive, risk-adjusted returns under a wide variety of market conditions. Mercer’s investment selection and due diligence process are outlined in the chart below.

On-going monitoring of the Fund’s investments will be utilized to assist the Advisor in maintaining portfolio allocations and managing cash in-flows and outflows. The Advisor may strategically rebalance its investment strategies according to the current market conditions, but will remain true to its fundamental analysis with respect to real estate asset class and sector risk over time. The
11 |
Advisor manages investments over a long-term time horizon while being mindful of the historical context of the markets. Mercer will provide to the Advisor investment performance reporting and analysis, including discussions on investment strategy, portfolio construction, and market update reports. The illustration below further outlines this monitoring process.

Investment Strategy - Multi-Manager Diversification
The Fund intends to employ a Multi-Manager approach by identifying and investing with ‘best in class’ institutional asset managers with expertise in managing portfolios of real estate and real estate-related securities. The term ‘best in class’ refers to Institutional Investment Funds that the Advisor and Mercer have identified through Mercer’s proprietary screening process as having above average prospects.
Many of the Institutional Investment Funds have large minimum investment size and stringent investor qualification criteria intended to limit their direct investors to mainly institutions such as endowments and pension funds. As such, the Fund enables investors to invest with institutional investment managers that may not be otherwise permitted or available to them.
The Fund also enables investors to execute a comprehensive multi-strategy, multi-manager, multi-sector strategy by making a single investment in its shares, whereas due to the large minimums of many of the Institutional Investment Funds, such a strategy may not otherwise be permitted or available to the investor.
The sponsor believes that the Fund may provide an additional benefit in terms of lower fees from the Institutional Investment Funds as a result of volume discounts, which pricing benefits may not otherwise be permitted or available to them.
Investment Strategy - Multi-Strategy Diversification
The Fund intends to employ a Multi-Strategy approach to diversify the risk-reward profiles and the underlying types of real estate in which it invests, with the strategies noted below. Because each real estate strategy performs differently throughout the overall real estate and economic cycle, investment strategies that include multiple strategies generally have lower volatility than single strategy funds. Thus, a multi-strategy approach should assist the Fund in achieving its objective of lower portfolio volatility as well as lower correlation with the broader markets.
|
● |
Core. The Fund’s ‘core’ strategy targets high-quality portfolios with real estate assets that provide relatively lower and more stable returns. Such investments are typically located in primary markets and in the main property types (retail, office, industrial and multi-family). Properties are stable, well-maintained, well-leased and often of the Class A variety. For example, office properties, including life sciences, tend to be Class A buildings with investment grade tenants. Multifamily properties are usually in major metropolitan cities with higher rental rates. Retail would typically be more traditional neighborhood and community strip-mall centers, as well as regional and super regional malls. The Advisor believes that warehouse and research and development properties in strong distribution centers typically offer better chances for predictable cash flow within the industrial sector. As an example, a Class A office property may broadly be defined as 100,000 square feet or larger (five or more floors), concrete and steel construction, recently built and/or very well maintained (excellent condition), with business/support amenities and in a strong identifiable location with good access to a primary metropolitan market. Class A properties are the most prestigious buildings competing for premier tenants with rents above average for the area. |
|
● |
Core Plus. The Fund’s ‘core plus’ strategy seeks moderate risk portfolios with real estate that provides moderate returns. Such investments are predominantly core but with an emphasis on a modest value add management approach. A core plus portfolio requires slightly more complex financial structuring and management intensive focus than a core portfolio of investments. Focus is on the main property types, in both primary and secondary markets, in Class A or lower quality buildings that require some form of enhancement (i.e. repositioning, redevelopment and/or releasing). In comparison to the Class A example above, a Class B property may be renovated and/or in good condition, potentially smaller in size, in a good location in a primary or secondary metropolitan market. Class B properties compete for a wide range of users with rents in the average range for the area. |
12 |
|
● |
Value Add. The Fund’s ‘value add’ strategy typically focuses on more aggressive active asset management and often employs more leverage. Such investments typically are lower quality buildings, in both primary and secondary markets in the main property types or development projects. Properties are considered value add when they exhibit management or operational problems, require physical improvement, and/or suffer from capital constraints. Buildings often require enhancement to upgrade them to higher quality properties (i.e., redevelopment/repositioning/re-tenanting). |
Investment Strategy - Multi-Sector Diversification
The Fund intends to employ a Multi-Sector approach to diversify its investments by property type or sector - for example, across retail, office, multifamily, hospitality, industrial, residential, healthcare, life sciences and/or self-storage sectors. Because each real estate sector has its own investment cycle, correlations across property types are generally low. Thus, employing a multi-sector approach should assist the Fund in achieving its objective of low to moderate volatility as well as low correlation to the broader markets.
Additional Information Regarding Investment Strategy
The Fund may, from time to time, in attempting to respond to adverse market, economic, political or other similar conditions, take temporary defensive positions that are inconsistent with the Fund’s principal investment strategy. During such times, the Advisor may determine that the Fund should invest up to 100% of its assets in cash or cash equivalents, including money market instruments, prime commercial paper, repurchase agreements, Treasury bills and other short-term obligations of the U.S. Government, its agencies or instrumentalities. In addition to the foregoing, the Fund may utilize Other Public Investment Vehicles as temporary investments as the Fund raises capital or pending deployment of capital to other investment opportunities selected by the Advisor. In these and in other cases, the Fund may not achieve its investment objective. The Advisor may invest the Fund’s cash balances in any investments it deems appropriate. The Advisor expects that such investments will be made, without limitation and as permitted under the 1940 Act, in money market mutual funds, repurchase agreements, U.S. Treasury and U.S. agency securities, municipal bonds and bank accounts. Any income earned from such investments is ordinarily reinvested by the Fund in accordance with its investment program. Many of the considerations entering into recommendations and decisions of the Advisor and the Fund’s Portfolio Managers are subjective.
The frequency and amount of portfolio purchases and sales (known as the “portfolio turnover rate”) will vary from year to year. The portfolio turnover rate is not expected to exceed 100%, but may vary greatly from year to year and will not be a limiting factor if the Advisor determines that portfolio changes are appropriate. Although the Fund generally does not intend to trade for short-term profits, the Fund may engage in short-term trading strategies, and securities may be sold without regard to the length of time held when, in the opinion of the Advisor, investment considerations warrant such action. These policies may have the effect of increasing the annual rate of portfolio turnover of the Fund. Higher rates of portfolio turnover would likely result in higher brokerage commissions and may generate short-term capital gains taxable as ordinary income. If securities are not held for the applicable holding periods, dividends paid on them will not qualify for the advantageous federal tax rates. See “Tax Status” in the Fund’s SAI.
There is no assurance what portion, if any, of the Fund’s investments will qualify for the reduced federal income tax rates applicable to qualified dividends under the Code. As a result, there can be no assurance as to what portion of the Fund’s distributions will be designated as qualified dividend income. See “U.S. Federal Income Tax Matters.”
Investment Strategy and Criteria Used by RREEF in Selecting Public Real Estate Securities
The Advisor with RREEF has developed an investment strategy intended to maximize risk-adjusted returns by managing volatility and identifying securities that are priced inefficiently relative to RREEF’s assessment of intrinsic value. RREEF believes that real estate security performance is reflective of the underlying real estate portfolio and, therefore, over time will be driven by the pricing and fundamentals of their assets. The risk management process is highly focused on quantitative risk factors as well as fundamental portfolio risk factors. RREEF’s investment universe encompasses over 100 property companies in the United States with a total market capitalization of over $800 billion. RREEF is focused on companies that derive the majority of their operating income or asset base from commercial real estate (apartments, office, industrial, storage, hotels, retail, net lease). Operating and capital efficiency are critically important to a successful real estate company and hence RREEF typically focuses on companies with large, high quality asset bases. If there are securities outside of this group that meet these criteria, RREEF will include these as part of the investable universe. The investment universe is generally defined as all REITs and REOCs (real estate operating companies) with an equity market capitalization of at least $200 million that derive the majority of revenue or net asset value (NAV) from an equity interest in real estate activities. The U.S. real estate securities portion of the Fund’s portfolio managed by RREEF typically holds between 35-50 securities. Under normal circumstances, such securities will generally comprise between 5% and 20% of the Fund’s portfolio. With respect to any investments in non-publicly traded real estate related debt securities, the Advisor makes all investment decisions.
13 |
RISK FACTORS
An investment in the Fund’s shares is subject to risks. The value of the Fund’s investments will increase or decrease based on changes in the prices of the investments it holds. This will cause the value of the Fund’s shares to increase or decrease. You could lose money by investing in the Fund. By itself, the Fund does not constitute a balanced investment program. Before investing in the Fund you should consider carefully the following risks. There may be additional risks that the Fund does not currently foresee or consider material. You may wish to consult with your legal or tax advisors before deciding whether to invest in the Fund.
Real Estate Industry Concentration Risk. Because the Fund will concentrate its investments in real estate related securities, its portfolio will be significantly impacted by the performance of the real estate market and may experience more volatility and be exposed to greater risk than a more diversified portfolio. In addition, the Fund may invest in real estate equity or debt and therefore may be subject to risks similar to those associated with direct investment in real property. The value of the Fund’s shares will be affected by factors affecting the value of real estate and the earnings of companies engaged in the real estate industry. These factors include, among others: (i) changes in general economic and market conditions; (ii) changes in the value of real estate properties; (iii) risks related to local economic conditions, overbuilding and increased competition; (iv) increases in property taxes and operating expenses; (v) changes in zoning laws; (vi) casualty and condemnation losses; (vii) variations in rental income, neighborhood values or the appeal of property to tenants; (viii) the availability of financing; (ix) climate change and (x) changes in interest rates. Many real estate companies utilize leverage, which increases investment risk and could adversely affect a company’s operations and market value in periods of rising interest rates. The value of securities of companies in the real estate industry may go through cycles of relative under-performance and over-performance in comparison to equity securities markets in general.
There are also special risks associated with particular sectors, or real estate operations, including, but not limited to, those risks described below:
Retail Properties. Retail properties are affected by the overall health of the economy and may be adversely affected by, among other things, the growth of alternative forms of retailing, bankruptcy, departure or cessation of operations of a tenant, a shift in consumer demand due to demographic changes, changes in spending patterns and lease terminations.
Office Properties. Office properties are affected by the overall health of the economy, and other factors such as a downturn in the businesses operated by their tenants, obsolescence and non-competitiveness.
Industrial Properties. Industrial properties are affected by the overall health of the economy and other factors such as downturns in the manufacturing, processing and shipping of goods.
Hospitality Properties. The risks of hotel, motel and similar hospitality properties include, among other things, the necessity of a high level of continuing capital expenditures, competition, increases in operating costs which may not be offset by increases in revenues, dependence on business and commercial travelers and tourism, increases in fuel costs and other expenses of travel, and adverse effects of general and local economic conditions. Hotel properties tend to be more sensitive to adverse economic conditions and competition than many other commercial properties.
Healthcare and Life Sciences Properties. Healthcare and life sciences properties and healthcare providers are affected by several significant factors, including federal, state and local laws governing licenses, certification, adequacy of care, pharmaceutical distribution, rates, equipment, personnel and other factors regarding operations, funding for biotech companies, continued availability of revenue from government reimbursement programs and competition on a local and regional basis. The failure of any healthcare operator to comply with governmental laws and regulations may affect its ability to operate its facility or receive government reimbursements.
Multifamily Properties. The value and successful operation of a multifamily property may be affected by a number of factors such as the location of the property, the ability of the management team, the level of mortgage interest rates, the presence of competing properties, adverse economic conditions in the locale, oversupply and rent control laws or other laws affecting such properties.
Residential Properties. Residential properties can be significantly affected by the national, regional and local real estate markets. This segment of the real estate industry also is sensitive to interest rate fluctuations which can cause changes in the availability of mortgage capital and directly affect the purchasing power of potential homebuyers. Thus, residential properties can be significantly affected by changes in government spending, consumer confidence, demographic patterns and the level of new and existing home sales.
Shopping Centers. Shopping center properties are dependent upon the successful operations and financial condition of their tenants, particularly certain of their major tenants, and could be adversely affected by bankruptcy of those tenants. In some cases, a tenant may lease a significant portion of the space in one center, and the filing of bankruptcy could cause significant revenue loss, including the loss of revenue from smaller tenants with co-tenancy rights. Like others in the commercial real estate industry, community centers are subject to environmental risks and interest rate risk. They also face the need to enter into new leases or renew leases on favorable terms to generate rental revenues. Community center properties could be adversely affected by changes in the local markets where their properties are located, as well as by adverse changes in national economic and market conditions.
Self-Storage Properties. The value and successful operation of a self-storage property may be affected by a number of factors, such as the ability of the management team, the location of the property, the presence of competing properties, changes in traffic patterns and effects of general and local economic conditions with respect to rental rates and occupancy levels.
14 |
Other factors may contribute to the risk of real estate investments:
Development Issues. Certain real estate companies in which the Fund directly or indirectly invests (“portfolio companies”) may engage in the development or construction of real estate properties. Portfolio companies are exposed to a variety of risks inherent in real estate development and construction, such as the risk that there will be insufficient tenant demand to occupy newly developed properties, and the risk that prices of construction materials or construction labor may rise materially during the development.
Lack of Insurance. Certain of the portfolio companies in the Fund’s portfolio may fail to carry comprehensive liability, fire, flood, earthquake extended coverage and rental loss insurance, or insurance in place may be subject to various policy specifications, limits and deductibles. Due to the prevalence of catastrophic events, the cost of insurance may increase materially. Should any type of uninsured loss occur, the portfolio company could lose its investment in, and anticipated profits and cash flows from, a number of properties and, as a result, adversely affect the Fund’s investment performance.
Dependence on Tenants. The value of the Fund’s portfolio companies’ properties and the ability of these companies to make distributions to their shareholders depends upon the ability of the tenants at the properties to generate enough income in excess of their tenant operating expenses to make their lease payments. Changes beyond the control of our portfolio companies may adversely affect their tenants’ ability to make their lease payments and, in such event, would substantially reduce both their income from operations and ability to make distributions to our portfolio companies and, consequently, the Fund.
Financial Leverage. Companies in the real estate industry may be highly leveraged and financial covenants may affect their ability to operate effectively. The use of floating rate loans may also negatively impact returns in a rising interest rate environment.
Environmental Issues. In connection with the ownership (direct or indirect), operation, management and development of real properties that may contain hazardous or toxic substances, a portfolio company may be considered an owner, operator or responsible party of such properties and, therefore, may be potentially liable for removal or remediation costs, as well as certain other costs, including governmental fines and liabilities for injuries to persons and property. The existence of any such material environmental liability could have a material adverse effect on the results of operations and cash flow of any such portfolio company and, as a result, the amount available to make distributions on shares of the Fund could be reduced. Environmental risk from high winds, hurricanes, fires, flood and extreme heat may also materially affect a property’s value.
Credit Market Conditions. Instability in credit markets can potentially make it more difficult for borrowers to obtain financing or refinancing on attractive terms or at all. Conditions in the credit markets may expose borrowers to increased interest expenses for borrowed money and tightening underwriting standards. There is also a risk that a general lack of liquidity or other events in the credit markets may adversely affect the ability of issuers in whose securities the Fund invests to finance real estate developments and projects or refinance completed projects.
This may also adversely affect the price at which portfolio companies can sell real estate, because purchasers may not be able to obtain financing on attractive terms or at all. These developments may potentially adversely affect the broader economy, which in turn may adversely affect the real estate markets. Additionally, such developments could reduce the Fund’s investment opportunities.
Market Risk. An investment in shares is subject to investment risk, including the possible loss of the entire principal amount invested. An investment in shares represents an indirect investment in the securities owned by the Fund. The value of these securities, like other market investments, may move up or down, sometimes rapidly and unpredictably. In addition, the Fund is subject to the risk that geopolitical and other similar events will disrupt the economy on a national or global level. For instance, war, terrorism, market manipulation, government defaults, government shutdowns, political changes or diplomatic developments, public health emergencies (such as the spread of infectious diseases, pandemics and epidemics) and natural/environmental disasters can all negatively impact the securities markets.
Therefore, the Fund could lose money over short periods due to short-term market movements and over longer periods during more prolonged market downturns. The foregoing could impair the Fund’s ability to maintain operational standards, disrupt the operations of the Fund and its service providers, adversely affect the performance, value and liquidity of the Fund’s investments, and negatively impact the Fund’s performance and your investment in the Fund. The value of your shares at any point in time may be worth less than the value of your original investment, even after taking into account any reinvestment of dividends and distributions.
Liquidity Risk. The Fund is a closed-end investment company structured as an “interval fund” and is designed for medium to long-term investors. Unlike many closed-end investment companies, the Fund’s shares are not listed on any securities exchange and are not publicly traded. There currently is no secondary market for the shares and the Advisor does not expect that a secondary market will develop. Limited liquidity is provided to shareholders only through the Fund’s quarterly repurchase offers for no less than 5% of the Fund’s shares outstanding at per-class net asset value. There is no guarantee that shareholders will be able to sell all of the shares they desire in a quarterly repurchase offer. Since inception, the Fund has made 44 repurchase offers, 37 have resulted in the repurchase of all shares, seven have resulted in the repurchase of less than all shares tendered. The Fund’s investments are also subject to liquidity risk. Liquidity risk exists when particular investments of the Fund would be difficult to purchase or sell, possibly preventing the Fund from selling such illiquid securities at an advantageous time or price, or possibly requiring the Fund to dispose of other investments at unfavorable times or prices in order to satisfy its obligations. Funds with principal investment strategies that involve securities of companies with smaller market capitalizations, derivatives or securities with substantial market and/or credit risk tend to have the greatest exposure to liquidity risk.
15 |
Allocation Risk. The ability of the Fund to achieve its investment objective depends, in part, on the ability of the Advisor or RREEF to allocate effectively the Fund’s assets among the various Institutional Investment Funds, Private REITs, Public REITs and Other Public Investment Vehicles in which the Fund invests and, with respect to each such asset class, among equities and fixed income securities. There can be no assurance that the actual allocations will be effective in achieving the Fund’s investment objectives or delivering positive returns.
Correlation Risk. The Fund seeks to produce returns that are not correlated to the broader financial markets. Although the prices of equity securities and fixed-income securities, as well as other asset classes, often rise and fall at different times so that a fall in the price of one may be offset by a rise in the price of the other, in down markets the prices of these securities and asset classes can also fall in tandem. Because the Fund allocates its investments among different asset classes, the fund is subject to correlation risk.
Credit Risk. There is a risk that debt issuers will not make payments, resulting in losses to the Fund. In addition, the credit quality of securities may be lowered if an issuer’s financial condition changes. Lower credit quality may lead to greater volatility in the price of a security and in shares of the Fund. Lower credit quality also may affect liquidity and make it difficult to sell the security. Default, or the market’s perception that an issuer is likely to default, could reduce the value and liquidity of securities, thereby reducing the value of your investment in Fund shares. In addition, default may cause the Fund to incur expenses in seeking recovery of principal or interest on its portfolio holdings.
Distribution Policy Risk. The Fund’s distribution policy is expected to result in distributions that equal a fixed percentage of the Fund’s current net asset value per share. Shareholders receiving periodic payments from the Fund may be under the impression that they are receiving net profits. However, all or a portion of a distribution may consist of a return of capital. Return of capital is the portion of a distribution that is a return of your original investment dollars in the Fund. Shareholders should not assume that the source of a distribution from the Fund is net profit. Shareholders should note that return of capital will reduce the tax basis of their shares and potentially increase the taxable gain, if any, upon disposition of their shares.
Fixed Income Risk. When the Fund invests in fixed income securities, the value of your investment in the Fund will fluctuate with changes in interest rates. Typically, a rise in interest rates causes a decline in the value of fixed income securities. In general, the market price of debt securities with longer maturities will increase or decrease more in response to changes in interest rates than shorter-term securities. Recently, interest rates have risen sharply after maintaining historically low levels for a significant period of time. Current conditions may result in an increase in interest rate volatility, which in turn may result in a decline in the value of the fixed income investments held by the Fund. As a result, for the present, interest rate risk may be heightened. Other risk factors include credit risk (the debtor may default) and prepayment risk (the debtor may pay its obligation early, reducing the amount of interest payments). These risks could affect the value of a particular investment, possibly causing the Fund’s share price and total return to be reduced and fluctuate more than other types of investments.
Institutional Investment Fund Risk. The Fund’s investment in Institutional Investment Funds will require it to bear a pro rata share of the vehicles’ expenses, including management and performance fees. The fees the Fund pays to invest in an Institutional Investment Fund may be higher than if the manager of the Institutional Investment Fund, managed the Fund’s assets directly. The incentive fees charged by certain Institutional Investment Funds may create an incentive for its manager to make investments that are riskier and/or more speculative than those it might have made in the absence of an incentive fee. The Funds are not publicly traded and therefore may not be as liquid as other types of investments. Furthermore, Institutional Investment Funds, like the other Underlying Funds in which the Fund may invest, are subject to specific risks, depending on the nature of the vehicle and also may employ leverage such that their returns are more than one times that of their benchmark which will amplify losses suffered by the Fund when compared to unleveraged investments. For example, these Funds need not have independent boards, shareholder approval of advisory contracts may not be required, may leverage to an unlimited extent, and may engage in joint transactions with affiliates.
Issuer and Non-Diversification Risk. The value of a specific security can be more volatile than the market as a whole and can perform differently from the value of the market as a whole. As a non-diversified fund, the Fund may invest more than 5% of its total assets in the securities of one or more issuers. The Fund’s performance may be more sensitive to any single economic, business, political or regulatory occurrence than the value of shares of a diversified investment company. The value of an issuer’s securities that are held in the Fund’s portfolio may decline for a number of reasons which directly relate to the issuer, such as management performance, financial leverage and reduced demand for the respective properties and services.
Lack of Control Over Institutional Investment Funds and Other Portfolio Investments. Once the Advisor or RREEF has selected an Underlying Fund for investment by the Fund, the Advisor and RREEF will have no control over the investment decisions made by any such Underlying Fund. Although the Advisor or RREEF will evaluate regularly each Underlying Fund and its manager to determine whether their respective investment programs are consistent with the Fund’s investment objective, the Advisor and RREEF will not have any control over the investments made by any Underlying Fund. Even though the Underlying Funds are subject to certain constraints, the managers may change aspects of their investment strategies. The managers may do so at any time (for example, such change may occur immediately after providing the Advisor with the quarterly unaudited financial information for an Institutional Investment Fund). The Advisor or RREEF may reallocate the Fund’s investments among the Underlying Funds, but the Advisor’s ability to do so may be constrained by the withdrawal limitations imposed by certain Underlying Funds, which may prevent the Fund from reacting rapidly to market changes should an Underlying Fund fail to effect portfolio changes consistent with such market changes and the demands of the Advisor. Such withdrawal limitations may also restrict the Advisor’s ability to terminate investments in Underlying Funds that are poorly performing or have otherwise had adverse changes. The Advisor and RREEF will be dependent on information provided by the Underlying Fund, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s or RREEF’s ability to manage the Fund’s investment portfolio in accordance with its investment objectives.
Leveraging Risk. The use of leverage, such as borrowing money to purchase securities or otherwise invest the Fund’s assets, will cause the Fund to incur additional expenses and may significantly magnify the Fund’s losses in the event of adverse performance of the Fund’s underlying investments. In addition to any borrowing utilized by the Fund, the Underlying Funds in which the Fund invests
16 |
may utilize leverage, subject to the limitations of their charters and operative documents. Leverage by Underlying Funds and/or the Fund has the effect of potentially increasing losses. In addition, interest rates (including benchmarks like SOFR and the spreads to such benchmarks charged by lenders) are highly sensitive to external factors outside a borrower’s control, including general and local economic conditions (such as inflation, recession, money supply and unemployment) and the monetary and fiscal policies of various governmental agencies such as the Federal Reserve Board. During periods of increased interest rates, borrowing costs of the Fund will likely increase and may adversely affect the Fund’s performance.
Management Risk. The net asset value of the Fund changes daily based on the performance of the securities in which it invests. The Advisor’s or a Sub-Advisor’s judgments about the attractiveness, value and potential appreciation of particular real estate segment and securities in which the Fund invests may prove to be incorrect and may not produce the desired results.
Possible Competition Between Underlying Funds and Between the Fund and the Underlying Funds. The Underlying Funds trade independently of each other and may pursue investment strategies that “compete” with each other for execution or that cause the Fund to participate in positions that offset each other (in which case the Fund would bear its pro rata share of commissions and fees without the potential for a profit). Also, the Fund’s investments in any particular Underlying Fund could increase the level of competition for the same trades that other Underlying Funds might otherwise make, including the priorities of order entry. This could make it difficult or impossible to take or liquidate a position in a particular security at a price consistent with the Advisor’s or a Sub-Advisor’s strategy.
Preferred Securities Risk. There are various risks associated with investing in preferred securities, including credit risk, interest rate risk, deferral and omission of distributions, subordination to bonds and other debt securities in a company’s capital structure, limited liquidity, limited voting rights and special redemption rights. Interest rate risk is, in general, that the price of a debt security falls when interest rates rise. Securities with longer maturities tend to be more sensitive to interest rate changes. Credit risk is the risk that an issuer of a security may not be able to make principal and interest or dividend payments on the security as they become. Holders or preferred securities may not receive dividends, or the payment can be deferred for some period of time. In bankruptcy, creditors are generally paid before the holders of preferred securities.
REIT Risk. Investments (directly or indirectly) in REITs will subject the Fund to various risks. REIT share prices may decline because of adverse developments affecting the real estate industry and real property values. In general, real estate values can be affected by a variety of factors, including supply and demand for properties, the economic health of the country or of different regions, and the strength of specific industries that rent properties. REITs often invest in highly leveraged properties. Returns from REITs, which typically are small or medium capitalization stocks, may trail returns from the overall stock market. In addition, changes in interest rates may hurt real estate values or make REIT shares less attractive than other income-producing investments. REITs are also subject to heavy cash flow dependency, defaults by borrowers and self-liquidation.
Qualification as a REIT under the Internal Revenue Code of 1986, as amended, in any particular year is a complex analysis that depends on a number of factors. There can be no assurance that an entity in which the Fund invests with the expectation that it will be taxed as a REIT will, in fact, qualify as a REIT. An entity that fails to qualify as a REIT would be subject to a corporate level tax, would not be entitled to a deduction for dividends paid to its shareholders and would not pass through to its shareholders the character of income earned by the entity. If the Fund were to invest in an entity that failed to qualify as a REIT, such failure could significantly reduce the Fund’s yield on that investment. REITs can be classified as equity REITs, mortgage REITs and hybrid REITs. Equity REITs invest primarily in real property and earn rental income from leasing those properties. They may also realize gains or losses from the sale of properties. Equity REITs will be affected by conditions in the real estate rental market and by changes in the value of the properties they own. Mortgage REITs invest primarily in mortgages and similar real estate interests and receive interest payments from the owners of the mortgaged properties. Mortgage REITs will be affected by changes in creditworthiness of borrowers and changes in interest rates. Hybrid REITs invest both in real property and in mortgages. Equity and mortgage REITs are dependent upon management skills, may not be diversified and are subject to the risks of financing projects.
Dividends paid by REITs will not generally qualify for the reduced U.S. federal income tax rates applicable to qualified dividends under the Code. See “U.S. Federal Income Tax Matters.” The Fund’s investments in REITs may include an additional risk to shareholders. Some or all of a REIT’s annual distributions to its investors may constitute a non-taxable return of capital. Any such return of capital will generally reduce the Fund’s basis in the REIT investment, but not below zero. To the extent the distributions from a particular REIT exceed the Fund’s basis in such REIT, the Fund will generally recognize gain. In part because REIT distributions often include a nontaxable return of capital, Fund distributions to shareholders may also include a nontaxable return of capital. Shareholders that receive such a distribution will also reduce their tax basis in their shares of the Fund, but not below zero. To the extent the distribution exceeds a shareholder’s basis in the Fund’s shares, such shareholder will generally recognize a capital gain. The Fund does not have any investment restrictions with respect to investments in REITs.
Repurchase Policy Risks. Quarterly repurchases by the Fund of its shares typically will be funded from available cash or sales of portfolio securities. However, payment for repurchased shares may require the Fund to liquidate portfolio holdings earlier than the Advisor otherwise would liquidate such holdings, potentially resulting in losses, and may increase the Fund’s portfolio turnover. The Advisor may take measures to attempt to avoid or minimize such potential losses and turnover, and instead of liquidating portfolio holdings, may borrow money to finance repurchases of shares. If the Fund borrows to finance repurchases, interest on any such borrowing will negatively affect shareholders who do not tender their shares in a repurchase offer by increasing the Fund’s expenses and reducing any net investment income. To the extent the Fund finances repurchase proceeds by selling investments, the Fund may hold a larger proportion of its net assets in less liquid securities. Also, the sale of securities to fund repurchases could reduce the market price of those securities, which in turn would reduce the Fund’s net asset value.
Repurchase of shares will tend to reduce the number of outstanding shares and, depending upon the Fund’s investment performance, its net assets. A reduction in the Fund’s net assets may increase the Fund’s expense ratio, to the extent that additional shares are not sold. In addition, the repurchase of shares by the Fund may be a taxable event to shareholders.
17 |
Underlying Funds Risk. Other Public Investment Vehicles such as ETFs, Index Funds, closed-end funds, and mutual funds in which the Fund may invest are subject to investment advisory fees and other expenses, which will be indirectly paid by the Fund. As a result, the cost of investing in the Fund will be higher than the cost of investing directly in such Underlying Funds and also may be higher than other funds that invest directly in securities. Underlying Funds are subject to specific risks, depending on the nature of the fund. The Fund’s performance depends in part upon the performance of the Underlying Fund managers and selected strategies, the adherence by such Underlying Fund managers to such selected strategies, the instruments used by such Underlying Fund managers and the Advisor’s or a Sub-Advisor’s ability to select Underlying Fund managers and strategies and effectively allocate Fund assets among them. Additionally, the market value of shares of Underlying Funds that are closed-end funds typically trade at a discount relative to their net asset value. This difference in price may be due to the fact that the supply and demand in the market for fund shares at any point in time is not always identical to the supply and demand in the market for the underlying basket of securities. ETF shares may trade at a discount or a premium in market price if there is a limited market in such shares. Transactions in shares of closed-end funds and ETFs are also subject to brokerage and other trading costs, which could result in greater expenses to the Fund. Investments in pooled investment vehicles also may be illiquid, making it difficult for the Advisor to redeem the interest of the Fund in such vehicles in a reasonable amount of time.
Valuation of Institutional Investment Funds. While the valuations of the Fund’s investments in publicly-traded securities are more readily ascertainable, the Fund’s ownership interests in Institutional Investment Funds are not publicly traded and the Fund will depend on the institutional asset manager to a Private Investment Fund to provide a valuation of the Fund’s investment. Moreover, the valuation of the Fund’s investment in an Institutional Investment Fund, as provided by an institutional asset manager as of a specific date, may vary from the fair value of the investment that may be obtained if such investment were sold to a third party. For information about the value of the Fund’s investment in Institutional Investment Funds, the Advisor will be dependent on information provided by the Institutional Investment Funds, including quarterly unaudited financial statements, which if inaccurate could adversely affect the Advisor’s ability to accurately value the Fund’s shares.
MANAGEMENT OF THE FUND
Trustees and Officers
The Board is responsible for the overall management of the Fund, including supervision of the duties performed by the Advisor. The Board is comprised of five trustees. The Trustees are responsible for the Fund’s overall management, including adopting the investment and other policies of the Fund, electing and replacing officers and selecting and supervising the Fund’s investment advisor. The name and business address of the Trustees and officers of the Fund and their principal occupations and other affiliations during the past five years, as well as a description of committees of the Board, are set forth under “Management” in the Statement of Additional Information.
Investment Advisor
Bluerock Fund Advisors, LLC, located at 919 Third Avenue, 40th Floor, New York, NY 10022, serves as the Fund’s investment advisor. The Advisor is registered with the SEC as an investment advisor under the Advisers Act. The Advisor is a Delaware limited liability company formed on May 11, 2012.
Under the general supervision of the Fund’s Board, and pursuant to the terms of an Investment Management Agreement with the Fund, the Advisor will carry out the investment and reinvestment of the net assets of the Fund, will furnish continuously an investment program with respect to the Fund, and determine which securities should be purchased, sold or exchanged. In addition, the Advisor will supervise and provide oversight of the Fund’s service providers. The Advisor will furnish to the Fund office facilities, equipment and personnel for servicing the management of the Fund. The Advisor will compensate all Advisor personnel who provide services to the Fund. In return for these services, facilities and payments, the Fund has agreed to pay the Advisor, as compensation under the Investment Management Agreement, a monthly management fee computed at the annual rate of 1.50% of the daily net assets of the Fund. The Advisor may employ research services and service providers to assist in the Advisor’s market analysis and investment selection.
The Advisor and the Fund have entered into an expense limitation and reimbursement agreement (the “Expense Limitation Agreement”) under which the Advisor has agreed contractually to waive its fees and to pay or absorb the ordinary operating expenses (excluding any taxes, interest, brokerage commissions, acquired fund fees and expenses, and extraordinary expenses, such as litigation or reorganization costs, but including organizational costs and offering costs), to the extent that such expenses exceed 2.45% per annum of the Fund’s average daily net assets attributable to Class M shares (the “Expense Limitation”). In consideration of the Advisor’s agreement to limit the Fund’s expenses, the Fund has agreed to repay the Advisor in the amount of any fees the Advisor previously waived or Fund expenses reimbursed, subject to the limitations that: (1) the reimbursement will be made if payable not more than three years from the date incurred; (2) the reimbursement may not be made if it would cause the Expense Limitation then in effect or in effect at the time of the waiver to be exceeded; and (3) the reimbursement is approved by the Board. The Expense Limitation Agreement will remain in effect, at least until January 31, 2026, unless and until the Board approves its modification or termination. This agreement may be terminated only by the Board on 60 days written notice to the Advisor. After January 31, 2026, the Expense Limitation Agreement may be renewed at the Advisor’s and Board’s discretion.
A discussion regarding the basis for the Board’s approval of each of the Fund’s Investment Management Agreement with the Advisor and Sub-Advisory Agreements with Mercer and RREEF is available annually in the Fund’s March 31 semi-annual report to shareholders.
18 |
Affiliated Brokerage
Bluerock Capital Markets, LLC (“BCM”), a registered broker-dealer and an affiliate of the Advisor, may receive commissions on the sale of certain classes of the Fund’s shares, but it does not receive compensation from the Fund in connection with the sale of Class M shares.
Advisor’s Investment Committee
The Advisor has established an Investment Committee comprised of five persons (the “Committee”) responsible for: setting overall investment policies and strategies of the Advisor; approval of Institutional Investment Funds being considered for investment by the Fund; establishing allocation targets for the investment portfolio of the Fund among the Institutional Investment Funds, Other Public Investment Vehicles and other entities in which the Fund intends to invest; and generally overseeing the activities of the Advisor’s Portfolio Managers (see below).
The members of the Committee, and their professional background and experience, are as follows:
R. Ramin Kamfar — Mr. Kamfar has served as a member of the Investment Committee and as Chairman of the Advisor since the inception of the Advisor in 2012. In addition, Mr. Kamfar is the founder of and serves as the Chairman and Chief Executive Officer of Bluerock Real Estate, LLC (“BRRE”), since its founding in October 2002. Mr. Kamfar served as Chairman and CEO of Bluerock Residential Growth REIT, a publicly traded REIT listed on the NYSE American (“BRG”), from its founding in 2009 until its sale in 2022. Mr. Kamfar currently serves as Chairman and CEO of Bluerock Homes Trust, a publicly traded REIT listed on the NYSE American (“BHM”) since its spin-off from BRG in 2022, as well as Chairman of Bluerock Asset Management, LLC since 2018. Mr. Kamfar started his career as an investment banker at Lehman Brothers Inc. in 1988, and has 30 years of experience in various aspects of real estate, mergers and acquisitions, private equity investing, investment banking, and public and private financings. Mr. Kamfar received an M.B.A. degree with distinction in Finance in 1988 from The Wharton School of the University of Pennsylvania and a B.S. degree with distinction in Finance in 1985 from the University of Maryland, College Park.
James G. Babb, III — Mr. Babb has served as a member of the Investment Committee since the inception of the Advisor in 2012. In addition, Mr. Babb has served in a variety of senior capacities, including his current role as Chief Strategy Officer, at BRRE, which he joined in 2007. Mr. Babb served as Chief Investment Officer of BRG from its founding in 2009 to 2020, as Chief Strategy Officer from 2020 until its sale in 2022 and as a Director of BRG from 2009 to 2014. Mr. Babb currently serves as Chief Strategy Officer of BHM. Mr. Babb was a founding principal of Starwood Capital Group (“Starwood”), a leading institutional real estate investment manager, where he helped lead the residential and office acquisitions initiatives from 1992 to 2003. During Mr. Babb’s tenure Starwood raised and invested funds on behalf of institutional investors through seven private real estate funds, and which in the aggregate ultimately invested approximately $8 billion in approximately 250 separate transactions. Mr. Babb also led Starwood’s efforts to expand its platform to invest in England and France. Mr. Babb received a B.A. degree in Economics in 1987 from the University of North Carolina, Chapel Hill.
Jordan B. Ruddy — Mr. Ruddy currently serves as Co-CIO of the Advisor and Portfolio Manager of the Fund. Mr. Ruddy has served as a member of the Investment Committee and as President of the Advisor since the inception of the Advisor in 2012. Mr. Ruddy also serves as president of Bluerock Asset Management, LLC. Mr. Ruddy served in several senior capacities of BRG from its founding in 2009 until its sale in 2022 and currently serves as President of BHM. Mr. Ruddy brings approximately 30 years of institutional real estate investment experience working with some of leading public and private firms in the industry. Prior to joining Bluerock, Mr. Ruddy served as a real estate investment banker at Banc of America Securities LLC, and at Smith Barney Inc. and at JP Morgan Chase (previously the Chase Manhattan Bank), and as Vice President of Amerimar Enterprises, a real estate company specializing in value-added investments nationwide. Mr. Ruddy received an M.B.A. degree in Finance and Real Estate in 1995 from The Wharton School of the University of Pennsylvania, and a B.S. degree with high honors in Economics in 1986 from the London School of Economics.
Ryan MacDonald — Mr. MacDonald has served as a member of the Investment Committee of the Advisor since January 2018. Mr. MacDonald currently serves as Chief Investment Officer for BHM and of BRRE and certain of its affiliates. Mr. MacDonald served in a variety of senior capacities for BRG, including Chief Investment Officer from 2020 until its sale. Since joining Bluerock in 2008, Mr. MacDonald is responsible for sourcing, underwriting, structuring, financing and closing of all of Bluerock’s real estate investments and dispositions. To date with Bluerock, Mr. MacDonald has been involved with real estate transactions with an aggregate value of approximately $11 billion. Prior to joining Bluerock, Mr. MacDonald was an Investment Analyst for PNC Realty Investors. Mr. MacDonald received a B.A. in Economics from the University of Maryland, College Park.
Adam Lotterman — Mr. Lotterman is co-founder of the Advisor and has been a key member of the Fund’s investment team since its inception in 2012. Mr. Lotterman currently serves as the Fund’s Senior Portfolio Manager, as well as the Advisor’s Co-Chief Investment Officer and Lead Economist. Prior to joining Bluerock, Mr. Lotterman was Vice President of Forman Capital, a private commercial real estate lender from 2011 to 2012. Mr. Lotterman was also an Adjunct Professor at Nova Southeastern University from 2010 to 2012, where he taught a master’s level course in Real Estate Market Analysis. Prior to that, Mr. Lotterman worked as a Senior Valuation Analyst at Bayview Asset Management (former hedge fund affiliate of The Blackstone Group) from 2010 to 2011, and from 2005 to 2010 Mr. Lotterman was the Senior Analyst for Goodkin Consulting, the former real estate consulting arm of PricewaterhouseCoopers. Mr. Lotterman received an M.S. in International Real Estate in 2006 from Florida International University, where he graduated first in class, and a B.S. Degree in microbiology with a minor in chemistry in 1997 from the University of Florida.
19 |
Advisor Portfolio Managers
Subject to the Committee’s oversight, Jordan B. Ruddy, a member of the Committee, and Adam Lotterman serve as the Fund’s Portfolio Managers and oversee the day-to-day investment operations of the Fund. Each has served as a Portfolio Manager to the Fund since October 2013.
Jordan B. Ruddy — Mr. Ruddy’s biographical information is presented above.
Adam Lotterman — Mr. Lotterman’s biographical information is presented above.
Tim Thran, CFA — Mr. Thran currently serves as Associate Portfolio Manager and Assistant Treasurer of the Fund. Mr. Thran joined Bluerock in 2017 and currently serves as a Managing Director of the Advisor. Mr. Thran works directly with the Fund’s Senior Portfolio Managers and is responsible for overseeing day-to-day investment operations and execution of the Fund’s strategy, including portfolio valuation, investment analysis, liquidity management and performance evaluation. Previously, Mr. Thran served at JPMorgan Asset Management from 2014 to 2016, directing daily oversight and controls on over $200 billion in retail mutual fund assets. From 2008 to 2014, Mr. Thran held multiple management roles at State Street Corporation, with a focus on accounting and compliance on the company’s premier ETFs and mutual fund clients. Mr. Thran received an M.B.A. degree with a concentration in Investments from the D’Amore-McKim School of Business at Northeastern University and B.A. degrees in both Mathematics and Economics from the College of the Holy Cross. Mr. Thran is a CFA charterholder, CFA Institute.
Investment Sub-Advisor – Mercer
The Advisor has engaged Mercer Investments LLC, a registered adviser under the Advisers Act, to act as an investment sub-advisor. For more than 50 years, Mercer and its affiliates have provided global leadership in investment consulting and multi-manager fiduciary management, and is a leading advisor to sovereign wealth funds, pension plans, banks, family offices, insurance companies, endowments and foundations. Mercer, together with its affiliated investment businesses, have over 5,600 delegated and advisory clients globally with over $547 billion in assets under management as of September 30, 2024 and over $17.5 trillion in assets under advisement as of June 30, 2024. Asset under management reported here includes include aggregated assets for which Mercer Investments LLC (Mercer Investments) and their global affiliates providing discretionary investment management services as of the dates indicated. Assets under management is calculated differently from regulatory assets under management, which is reported in Form ADV and filed with the Securities and Exchange Commission.
Mercer is an affiliate of Mercer (US), LLC, a human resource and financial consulting company. Mercer (US), LLC has approximately 25,000+ employees as of September 30, 2024 based in more than 40 countries and serves over 36,000 clients worldwide and is a wholly owned subsidiary of Marsh & McLennan Companies (NYSE: MMC).
Investment Sub-Advisor – RREEF
The Advisor has engaged RREEF America L.L.C., a registered advisor under the Advisers Act, to provide investment management for a portion of the Fund’s portfolio, generally less than 20%. In addition, RREEF provides the Advisor with research and information that the Advisor uses to make investment decisions with respect to non-publicly traded real estate related debt securities. RREEF together with its affiliates in Europe and Asia, comprise the global real estate investment business of DWS, an indirect majority owned subsidiary of Deutsche Bank A.G. DWS’s real estate investment business, is one of the largest real estate investment managers globally with more than 330 professionals and staff located in 23 cities worldwide and approximately $78.9 billion in real estate and real estate-related assets under management as of September 30, 2024.
RREEF Portfolio Managers
Subject to the Advisor’s oversight, David W. Zonavetch, Bob Thomas, and John W. Vojticek serve as the Fund’s RREEF Portfolio Managers and oversee a portion of investment portfolio of the Fund. Mr. Zonavetch and Mr. Vojticek have served as a Portfolio Managers to the Fund since May 2016. Mr. Thomas has served as a Portfolio Manager to the Fund since January 2018.
David W. Zonavetch — Mr. Zonavetch has served as a Director and Co-Lead Portfolio Manager for RREEF since September 2013 and as Co-Lead Portfolio Manager - Real Estate Securities since February 2012. Previously, he served as Vice President and Portfolio Manager from February 2007 to February 2012. From February 2007 to February 2012, Mr. Zonavetch was a Vice President and Securities Analyst at RREEF Real Estate. He has nine years of experience in accounting and finance. From 1998 to 2001, Mr. Zonavetch served as a Senior Accountant in Corporate Finance of RREEF Real Estate, and from 2001 to 2003, he served as Securities Accounting Coordinator with RREEF Real Estate’s Securities Group, covering the office and self- storage sectors. From 1995 until joining RREEF Real Estate in 1998, Mr. Zonavetch worked as an analyst for Cendant Mobility Services Corp., a corporate employee relocation company. Mr. Zonavetch holds a B.S. in Finance from the University of Illinois at Urbana-Champaign and is a certified public accountant.
Bob Thomas — Mr. Thomas has served as a Managing Director and Co-Head of Americas Real Estate Securities, Alternatives for RREEF since 2017. He has 15 years of industry experience serving as lead portfolio manager of North America for global listed property funds at Henderson Global Investors from 2015 to 2016, he was co-lead portfolio manager of North America for global listed property funds at AMP Capital from 2012 to 2015, and as an analyst at Nuveen Asset Management from 2011 to 2012, at BNP Paribas Asset Management from 2005 to 2011 and at Security Capital Research & Management from 20014 to 2005. Mr. Thomas started his career as an investment banking analyst in the Real Estate group at KeyBanc Capital Markets in 2002. Mr. Thomas holds a B.A. in Economics from Duke University and an MBA in Finance, Management & Strategy from Kellogg School of Management, Northwestern University.
20 |
John W. Vojticek — Mr. Vojticek has served as a Managing Director and Chief Investment Officer of Real Estate & Infrastructure Securities and Global Portfolio Manager for RREEF since July 2011 and was Co-Head of Americas Real Estate Securities from 2006 to July 2011. Mr. Vojticek was responsible for launching the firm’s first listed infrastructure securities strategy in June 2008 and served as Head of the Listed Infrastructure Securities business from June 2008 until his appointment as Chief Information Officer in July 2011. Mr. Vojticek is an associate member of the National Association of Real Estate Investment Trusts. Mr. Vojticek holds a B.S. in Business Administration from the University of Southern California.
The Statement of Additional Information provides additional information about each Portfolio Manager’s compensation, other accounts managed and ownership of Fund shares.
Administrator, Accounting Agent and Transfer Agent
ALPS Fund Services, Inc. (“ALPS” or the “Administrator”), located at 1290 Broadway, Suite 1000, Denver, CO 80203, serves as Administrator and Accounting Agent for the Fund. For the services rendered to the Fund by ALPS, the Fund pays ALPS the greater of an annual minimum fee or an asset-based fee, which scales downward based upon net assets for fund administration and fund accounting services. SS&C GIDS, located at PO Box 219445, Kansas City, MO 64121-9445, serves as the Fund’s Transfer Agent and for such services the Fund pays the Transfer Agent separate fees.
Custodian
UMB Bank, N.A (“UMB Bank” or the “Custodian”), with principal offices at 1010 Grand Boulevard, Kansas City, Missouri 64106, serves as custodian for the securities and cash of the Fund’s portfolio. Under a Custody Agreement, UMB Bank holds the Fund’s assets in safekeeping and keeps all necessary records and documents relating to its duties.
Fund Expenses
The Advisor is obligated to pay expenses associated with providing the services stated in the Investment Management Agreement, including compensation of and office space for its officers and employees connected with investment and economic research, trading and investment management and administration of the Fund. The Advisor is obligated to pay the fees of any Trustee of the Fund who is affiliated with it.
The Administrator is obligated to pay expenses associated with providing the services contemplated by a Fund Services Administration Agreement (administration and accounting services), including compensation of and office space for its officers and employees employed in providing these services to the Fund.
The Fund pays all other expenses incurred in the operation of the Fund including, among other things, (i) expenses for legal and independent accountants’ services, (ii) costs of printing proxies, share certificates, if any, and reports to shareholders, (iii) charges of the custodian and transfer agent in connection with the Fund’s dividend reinvestment policy, (iv) fees and expenses of independent Trustees, (v) printing costs, (vi) membership fees in trade association, (vii) fidelity bond coverage for the Fund’s officers and Trustees, (viii) errors and omissions insurance for the Fund’s officers and Trustees, (ix) brokerage costs, (x) taxes, (xi) costs associated with the Fund’s quarterly repurchase offers, (xii) servicing fees and (xiii) other extraordinary or non-recurring expenses and other expenses properly payable by the Fund. The expenses incident to the offering and issuance of shares to be issued by the Fund will be recorded as a reduction of capital of the Fund attributable to the shares.
Class M shares are not subject to a shareholder servicing fee.
The Board has authorized the Advisor and RREEF to select brokers or dealers (including affiliates) to arrange for the purchase and sale of Fund securities, including principal transactions. Any commission, fee or other remuneration paid to an affiliated broker or dealer is paid in compliance with the Fund’s procedures adopted in accordance with Rule 17e-1 under the 1940 Act.
21 |
Control Persons and Principal Shareholders
A principal shareholder is any person who owns (either of record or beneficially) 5% or more of the outstanding shares of a fund. A control person is one who owns, either directly or indirectly, more than 25% of the voting securities of a company or acknowledges the existence of control. The Fund’s principal shareholders as of January 3, 2025 are listed in the chart below. Each shareholder listed below is a record shareholder, holding shares for the benefit of others.
Class A Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
PERSHING LLC |
6,523,152.52 |
26.75% |
EQUITABLE ADVISORS LLC |
4,721,545.33 |
19.36% |
CHARLES SCHWAB & CO INC |
3,107,371.03 |
12.74% |
NATIONAL FINANCIAL SERVICES LLC |
3,082,068.56 |
12.64% |
Class C Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
PERSHING LLC |
5,923,943.31 |
38.47% |
LPL FINANCIAL LLC |
2,299,101.93 |
14.93% |
CHARLES SCHWAB AND CO INC |
2,076,778.96 |
13.49% |
NATIONAL FINANCIAL SERVICES LLC |
895,604.35 |
5.82% |
Class I Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
CHARLES SCHWAB & CO INC |
42,258,021.47 |
36.65% |
NATIONAL FINANCIAL SERVICES LLC |
21,116,400.89 |
18.31% |
PERSHING LLC |
21,101,606.20 |
18.30% |
LPL FINANCIAL SERVICES |
14,367,372.68 |
12.46% |
ROBERT W BAIRD & CO. INC. |
6,642,155.04 |
5.76% |
22 |
Class L Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
PERSHING LLC |
1,652,278.67 |
53.11% |
NATIONAL FINANCIAL SERVICES LLC |
535,807.56 |
17.22% |
LPL FINANCIAL LLC |
247,909.67 |
7.97% |
Class M Shares |
||
Name and Address |
Shares Owned |
Percentage of Class |
MORGAN STANLEY SMITH BARNEY LLC |
4,313,743.14 |
98.46% |
As of January 3, 2025, the Trustees and officers, as a group, owned less than 1.00% of the shares of the Fund.
DETERMINATION OF NET ASSET VALUE
The net asset value of shares of the Fund is determined daily, as of the close of regular trading on the NYSE (normally, 4:00 p.m., Eastern Time). The NYSE is closed on weekends and New Year’s Day, Martin Luther King, Jr. Day, Presidents’ Day, Good Friday, Memorial Day, Juneteenth Day, Independence Day, Labor Day, Thanksgiving Day, and Christmas Day. Each Class M share will be offered at net asset value. During the continuous offering, the price of the shares will increase or decrease on a daily basis according to the net asset value of the shares.
In computing net asset value, portfolio securities of the Fund are valued at their current market values determined on the basis of market quotations as of the last quoted sales price on the security’s primary exchange. If market quotations are not readily available, as in the case of Institutional Investment Funds investing in private real estate, securities are valued at fair value as determined in good faith by the Advisor, in its capacity as the Board’s valuation designee, pursuant to Rule 2a-5 under the 1940 Act or with respect to securities traded or dealt in upon one or more securities exchanges (whether domestic or foreign), as described below. As a general matter, fair value represents the amount that the Fund could reasonably expect to receive if the Fund’s investment in the security were sold at the time of valuation, based on information reasonably available at the time the valuation is made and that the Advisor believes to be reliable. As the valuation designee, the Advisor acts under the Board’s oversight. The Board and the Advisor may enlist third party service providers, such as pricing services, broker-dealers or valuation firms, on an as-needed basis to assist in determining a security-specific fair value. The Board reviews the execution of this process and the resultant fair value prices at least quarterly to assure the process produces reliable results.
Fair valuation involves subjective judgments, and it is possible that the fair value determined for a security may differ materially from the value that could be realized upon the sale of the security. Like all investments that are valued at fair value, the Institutional Investment Funds will be difficult to value. There is no single standard for determining fair value of a security. Rather, in determining the fair value of a security for which there are no readily available market quotations, the Advisor, using information including that provided by a Sub-Advisor, may consider several factors, including fundamental analytical data relating to the investment in the security, the nature and duration of any restriction on the disposition of the security, the cost of the security at the date of purchase, the liquidity of the market for the security and the recommendation of the Fund’s Portfolio Managers. The Advisor may also consider periodic financial statements (audited and unaudited) or other information provided by the issuer. The Advisor will attempt to obtain current information to value all fair valued securities, but it is anticipated that portfolio holdings of the Institutional Investment Funds could be available on no more than a quarterly basis. Institutional Investment Funds that invest primarily in publicly traded securities are more easily valued.
The Advisor, with the assistance of other parties, will provide the Board with periodic reports, no less frequently than quarterly, that discuss the functioning of the valuation process, if applicable to that period, and that identify issues and valuations problems that have arisen, if any. To the extent deemed necessary by the Advisor, the fair value team or committee of the Board will review any securities valued by the Advisor in accordance with the Fund’s valuation policies.
Non-dollar-denominated securities, if any, are valued as of the close of the NYSE at the closing price of such securities in their principal trading market, but may be valued at fair value if subsequent events occurring before the computation of net asset value materially have affected the value of the securities. Trading may take place in foreign issues held by the Fund, if any, at times when the Fund is not open for business. As a result, the Fund’s net asset value may change at times when it is not possible to purchase or sell shares of the Fund. The Fund may use a third-party pricing service to assist it in determining the market value of securities in the Fund’s portfolio. The Fund’s net asset value per share is calculated, on a class-specific basis, by dividing the value of the Fund’s total assets (the value of the securities the Fund holds plus cash or other assets, including interest accrued but not yet received), less accrued expenses of the Fund, less the Fund’s other liabilities by the total number of shares outstanding.
23 |
For purposes of determining the net asset value of the Fund, readily marketable portfolio securities listed on the NYSE are valued, except as indicated below, at the last sale price reflected on the consolidated tape at the close of the NYSE on the business day as of which such value is being determined. If there has been no sale on such day, the securities are valued at the mean of the closing bid and asked prices on such day. If no bid or asked prices are quoted on such day or if market prices may be unreliable because of events occurring after the close of trading, then the security is valued by such method as the Advisor, as valuation designee, shall determine in good faith to reflect its fair market value. Readily marketable securities not listed on the NYSE but listed on other domestic or foreign securities exchanges are valued in a like manner. Portfolio securities traded on more than one securities exchange are valued at the last sale price on the business day as of which such value is being determined as reflected on the consolidated tape at the close of the exchange representing the principal market for such securities. Securities trading on the NASDAQ are valued at the NASDAQ official closing price.
Readily marketable securities traded in the over-the-counter market, including listed securities whose primary market is believed by the Advisor to be over-the-counter, are valued at the mean of the current bid and asked prices as reported by the NASDAQ or, in the case of securities not reported by the NASDAQ or a comparable source, as the Advisor deems appropriate to reflect their fair market value. Where securities are traded on more than one exchange and also over-the-counter, the securities will generally be valued using the quotations the Advisor believes reflect most closely the value of such securities.
CONFLICTS OF INTEREST
As a general matter, certain conflicts of interest may arise in connection with a portfolio manager’s management of a fund’s investments, on the one hand, and the investments of other accounts for which the portfolio manager is responsible, on the other. For example, it is possible that the various accounts managed could have different investment strategies that, at times, might conflict with one another to the possible detriment of the Fund. Alternatively, to the extent that the same investment opportunities might be desirable for more than one account, possible conflicts could arise in determining how to allocate them. Other potential conflicts might include conflicts created by specific portfolio manager compensation arrangements, and conflicts relating to selection of brokers or dealers to execute Fund portfolio trades and/or specific uses of commissions from Fund portfolio trades (for example, research, or “soft dollars”, if any). The Advisor, and Sub-Advisor, to the extent applicable, have adopted policies and procedures and have structured their Portfolio Managers’ compensation in a manner reasonably designed to safeguard the Fund from being negatively affected as a result of any such potential conflicts.
QUARTERLY REPURCHASES OF SHARES
Once each quarter, the Fund will offer to repurchase, at per-class net asset value no less than 5% of the outstanding shares of the Fund, unless such offer is suspended or postponed in accordance with regulatory requirements (as discussed below). The offer to purchase shares is a fundamental policy that may not be changed without the vote of the holders of a majority of the Fund’s outstanding voting securities (as defined in the 1940 Act). Shareholders will be notified in writing of each quarterly repurchase offer and the date the repurchase offer ends (the “Repurchase Request Deadline”). Shares will be repurchased at the per-class NAV per share determined as of the close of regular trading on the NYSE no later than the 14th day after the Repurchase Request Deadline, or the next business day if the 14th day is not a business day (each a “Repurchase Pricing Date”).
Shareholders will be notified in writing about each quarterly repurchase offer, how they may request that the Fund repurchase their shares and the “Repurchase Request Deadline,” which is the date the repurchase offer ends. Shares tendered for repurchase by shareholders prior to any Repurchase Request Deadline will be repurchased subject to the aggregate repurchase amounts established for that Repurchase Request Deadline. The time between the notification to shareholders and the Repurchase Request Deadline may vary from no more than 42 days to no less than 21 days. Payment pursuant to the repurchase will be made by checks to the shareholder’s address of record, or credited directly to a predetermined bank account on the Purchase Payment Date, which will be no more than seven days after the Repurchase Pricing Date. The Board may establish other policies for repurchases of shares that are consistent with the 1940 Act, regulations thereunder and other pertinent laws. Shareholders have no right to redeem Fund shares outside the regular quarterly repurchases, regardless of shareholder circumstances, and the Fund may not honor any such requests.
Determination of Repurchase Offer Amount
The Board, or a committee thereof, in its sole discretion, will determine the number of shares for each share class that the Fund will offer to repurchase (the “Repurchase Offer Amount”) for a given Repurchase Request Deadline. The Repurchase Offer Amount, however, will be no less than 5% and no more than 25% of the total number of shares outstanding on the Repurchase Request Deadline.
If shareholders tender for repurchase more than the Repurchase Offer Amount for a given repurchase offer, the Fund will repurchase the shares on a pro rata basis. However, the Fund may accept all shares tendered for repurchase by shareholders who own less than one hundred shares and who tender all of their shares, before prorating other amounts tendered.
Notice to Shareholders
No less than 21 days and more than 42 days before each Repurchase Request Deadline, the Fund shall send to each shareholder of record and to each beneficial owner of the shares that are the subject of the repurchase offer a notification (“Shareholder Notification”). The Shareholder Notification will contain information shareholders should consider in deciding whether to tender their shares for repurchase. The notice also will include detailed instructions on how to tender shares for repurchase, state the Repurchase Offer Amount and identify the dates of the Repurchase Request Deadline, the scheduled Repurchase Pricing Date, and the date the
24 |
repurchase proceeds are scheduled for payment (the “Repurchase Payment Deadline”). The notice also will set forth the NAV that has been computed no more than seven days before the date of notification, and how shareholders may ascertain the NAV after the notification date.
Repurchase Price
The repurchase price of the shares will be the NAV of the share class as of the close of regular trading on the NYSE on the Repurchase Pricing Date. The notice of the repurchase offer also will provide information concerning the NAV, such as the NAV as of a recent date or a sampling of recent NAVs, and a toll-free number for information regarding the repurchase offer. You may call 1-844-819-8287 to learn the NAV.
Early Withdrawal Charge
Class M shares are not subject to an early withdrawal charge.
Repurchase Amounts and Payment of Proceeds
Shares tendered for repurchase by shareholders prior to any Repurchase Request Deadline will be repurchased subject to the aggregate Repurchase Offer Amount established for that Repurchase Request Deadline. Payment pursuant to the repurchase offer will be made by check to the shareholder’s address of record, or credited directly to a predetermined bank account on the Purchase Payment Date, which will be no more than seven days after the Repurchase Pricing Date. The Board may establish other policies for repurchases of shares that are consistent with the 1940 Act, regulations thereunder and other pertinent laws.
If shareholders tender for repurchase more than the Repurchase Offer Amount for a given repurchase offer the Fund will repurchase the shares on a pro rata basis. Notwithstanding the foregoing, the Fund may in its sole discretion and for administrative convenience accept all shares tendered for repurchase by shareholders who own less than one hundred shares and who tender all of their shares, before prorating other amounts tendered.
Suspension or Postponement of Repurchase Offer
The Fund may suspend or postpone a repurchase offer only: (a) if making or effecting the repurchase offer would cause the Fund to lose its status as a regulated investment company under the Code; (b) for any period during which the NYSE or any market on which the securities owned by the Fund are principally traded is closed, other than customary weekend and holiday closings, or during which trading in such market is restricted; (c) for any period during which an emergency exists as a result of which disposal by the Fund of securities owned by it is not reasonably practicable, or during which it is not reasonably practicable for the Fund fairly to determine the value of its net assets; or (d) for such other periods as the Commission may by order permit for the protection of shareholders of the Fund.
Liquidity Requirements
The Fund must maintain liquid assets equal to the Repurchase Offer Amount from the time that the notice is sent to shareholders until the Repurchase Pricing Date. The Fund will ensure that either a percentage of its net assets equal to at least 100% of the Repurchase Offer Amount consists of cash or assets that can be sold or disposed of in the ordinary course of business at approximately the price at which the Fund has valued the investment within the time period between the Repurchase Request Deadline and the Repurchase Payment Deadline, and/or a line of credit is available to satisfy the Repurchase Offer Amount. The Board has adopted procedures that are reasonably designed to ensure that the Fund’s assets are sufficiently liquid so that the Fund can comply with the repurchase offer and the liquidity requirements described in the previous paragraphs. If, at any time, the Fund falls out of compliance with these liquidity requirements, the Board will take whatever action it deems appropriate to ensure compliance.
Consequences of Repurchase Offers
Repurchase offers will typically be funded from available cash or sales of portfolio securities. Payment for repurchased shares, however, may require the Fund to liquidate portfolio holdings earlier than the Advisor otherwise would, thus increasing the Fund’s portfolio turnover and potentially causing the Fund to realize losses. The Advisor intends to take measures to attempt to avoid or minimize such potential losses and turnover, and instead of liquidating portfolio holdings, may borrow money to finance repurchases of shares. If the Fund borrows to finance repurchases, interest on that borrowing will negatively affect shareholders who do not tender their shares in a repurchase offer by increasing the Fund’s expenses and reducing any net investment income. To the extent the Fund finances repurchase amounts by selling Fund investments, the Fund may hold a larger proportion of its assets in less liquid securities. The sale of portfolio securities to fund repurchases also could reduce the market price of those underlying securities, which in turn would reduce the Fund’s net asset value.
Repurchase of the Fund’s shares will tend to reduce the number of outstanding shares and, depending upon the Fund’s investment performance, its net assets. A reduction in the Fund’s net assets would increase the Fund’s expense ratio, to the extent that additional shares are not sold and expenses otherwise remain the same (or increase). In addition, the repurchase of shares by the Fund will be a taxable event to shareholders.
The Fund is intended as a medium to long-term investment. The Fund’s quarterly repurchase offers are a shareholder’s only means of liquidity with respect to his or her shares. Shareholders have no right to redeem Fund shares outside the regular quarterly repurchases, regardless of shareholder circumstances, and the Fund may not honor any such requests. The shares are not traded on a national securities exchange and no secondary market exists for the shares, nor does the Fund expect a secondary market for its shares to exist in the future.
25 |
DISTRIBUTION POLICY
Quarterly Distribution Policy
The Fund’s distribution policy is to make quarterly distributions to shareholders. The level of quarterly distributions (including any return of capital) is not fixed, but is expected to represent an annual rate of approximately 5.25% of the Fund’s current net asset value per share. However, this distribution policy is subject to change. Shareholders receiving periodic payments from the Fund may be under the impression that they are receiving net profits. However, all or a portion of a distribution may consist of a return of capital. Shareholders should not assume that the source of a distribution from the Fund is net profit. A return of capital is not taxable to a shareholder unless it exceeds a shareholder’s tax basis in the shares. Returns of capital reduce a shareholder’s tax cost (or “tax basis”). Once a shareholder’s tax basis is reduced to zero, any further return of capital would be taxable. Shareholders should note that return of capital will reduce the tax basis of their shares and potentially increase the taxable gain, if any, upon disposition of their shares. As required under the Investment Company Act of 1940, the Fund will provide a notice to shareholders at the time of distribution when such distribution does not consist solely of net income. Additionally, each distribution payment will be accompanied by a written statement which discloses the source or sources of each distribution. The IRS requires you to report these amounts, excluding returns of capital, on your income tax return for the year declared. The Fund will provide disclosures, with each distribution, that estimate the percentages of the current and year-to-date distributions that represent (1) net investment income, (2) capital gains and (3) return of capital. At the end of the year, the Fund may be required under applicable law to re-characterize distributions made previously during that year among (1) ordinary income, (2) capital gains and (3) return of capital for tax purposes. An additional distribution may be made in December, and other additional distributions may be made with respect to a particular fiscal year in order to comply with applicable law. Distributions declared in December, if paid to shareholders by the end of January, are treated for federal income tax purposes as if received in December.
The distribution rate may be modified by the Board from time to time. If, for any quarterly distribution, investment company taxable income (which term includes net short-term capital gain), if any, and net tax-exempt income, if any, is less than the amount of the distribution, then the difference will generally be a tax-free return of capital distributed from the Fund’s assets. The Fund’s final distribution for each calendar year will include any remaining investment company taxable income and net tax-exempt income undistributed during the year, as well as all net capital gain realized during the year. If the total distributions made in any calendar year exceed investment company taxable income, net tax-exempt income and net capital gain, such excess distributed amount would be treated as ordinary dividend income to the extent of the Fund’s current and accumulated earnings and profits. Distributions in excess of the earnings and profits would first be a tax-free return of capital to the extent of the adjusted tax basis in the shares. After such adjusted tax basis is reduced to zero, the distribution would constitute capital gain (assuming the shares are held as capital assets). This distribution policy may, under certain circumstances, have certain adverse consequences to the Fund and its shareholders because it may result in a return of capital resulting in less of a shareholder’s assets being invested in the Fund and, over time, increase the Fund’s expense ratio. The distribution policy also may cause the Fund to sell a security at a time it would not otherwise do so in order to manage the distribution of income and gain.
Unless the registered owner of shares elects to receive cash, all dividends declared on shares will be automatically reinvested in additional shares of the Fund. See “Dividend Reinvestment Policy.”
The dividend distribution described above may result in the payment of approximately the same amount or percentage to the Fund’s shareholders each quarter. Section 19(a) of the 1940 Act and Rule 19a-1 thereunder require the Fund to provide a written statement accompanying any such payment that adequately discloses its source or sources. Thus, if the source of the dividend or other distribution were the original capital contribution of the shareholder, and the payment amounted to a return of capital, the Fund would be required to provide written disclosure to that effect. Nevertheless, persons who periodically receive the payment of a dividend or other distribution may be under the impression that they are receiving net profits when they are not. Shareholders should read any written disclosure provided pursuant to Section 19(a) and Rule 19a-1 carefully and should not assume that the source of any distribution from the Fund is net profit.
The Board reserves the right to change the quarterly distribution policy from time to time.
DIVIDEND REINVESTMENT POLICY
The Fund will operate under a dividend reinvestment policy administered by the Transfer Agent. Pursuant to the policy, the Fund’s income dividends or capital gains or other distributions (each, a “Distribution” and collectively, “Distributions”), net of any applicable U.S. withholding tax, are reinvested in the same class of shares of the Fund.
Shareholders automatically participate in the dividend reinvestment policy, unless and until an election is made to withdraw from the policy on behalf of such participating shareholder. Shareholders who do not wish to have Distributions automatically reinvested should so notify the Transfer Agent in writing at Bluerock Total Income+ Real Estate Fund, c/o SS&C GIDS, PO Box 219445, Kansas City, MO 64121-9445. Such written notice must be received by the Transfer Agent 30 days prior to the record date of the Distribution or the shareholder will receive such Distribution in shares through the dividend reinvestment policy. Under the dividend reinvestment policy, the Fund’s Distributions to shareholders are reinvested in full and fractional shares as described below.
When the Fund declares a Distribution, the Transfer Agent, on the shareholder’s behalf, will receive additional authorized shares from the Fund either newly issued or repurchased from shareholders by the Fund and held as treasury stock. The number of shares to be received when Distributions are reinvested will be determined by dividing the amount of the Distribution by the Fund’s net asset value per share.
26 |
The Transfer Agent will maintain all shareholder accounts and furnish written confirmations of all transactions in the accounts, including information needed by shareholders for personal and tax records. The Transfer Agent will hold shares in the account of the shareholders in non-certificated form in the name of the participant, and each shareholder’s proxy, if any, will include those shares purchased pursuant to the dividend reinvestment policy. Each participant, nevertheless, has the right to request certificates for whole and fractional shares owned. The Fund will issue certificates in its sole discretion. The Administrator will distribute all proxy solicitation materials, if any, to participating shareholders.
In the case of shareholders, such as banks, brokers or nominees, that hold shares for others who are beneficial owners participating under the dividend reinvestment policy, the Transfer Agent will administer the dividend reinvestment policy on the basis of the number of shares certified from time to time by the record shareholder as representing the total amount of shares registered in the shareholder’s name and held for the account of beneficial owners participating under the dividend reinvestment policy.
Neither the Transfer Agent nor the Fund shall have any responsibility or liability beyond the exercise of ordinary care for any action taken or omitted pursuant to the dividend reinvestment policy, nor shall they have any duties, responsibilities or liabilities except such as expressly set forth herein. Neither shall they be liable hereunder for any act done in good faith or for any good faith omissions to act, including, without limitation, failure to terminate a participant’s account prior to receipt of written notice of his or her death or with respect to prices at which shares are purchased or sold for the participants account and the terms on which such purchases and sales are made, subject to applicable provisions of the federal securities laws.
The automatic reinvestment of dividends will not relieve participants of any federal, state or local income tax that may be payable (or required to be withheld) on such dividends. See “U.S. Federal Income Tax Matters.”
The Fund reserves the right to amend or terminate the dividend reinvestment policy. There is no direct service charge to participants with regard to purchases under the dividend reinvestment policy; however, the Fund reserves the right to amend the dividend reinvestment policy to include a service charge payable by the participants.
All correspondence concerning the dividend reinvestment policy should be directed to the Transfer Agent at Bluerock Total Income+ Real Estate Fund, c/o SS&C GIDS, PO Box 219445, Kansas City, MO 64121-9445. Certain transactions can be performed by calling the toll-free number 1-844-819-8287.
U.S. FEDERAL INCOME TAX MATTERS
The following briefly summarizes some of the important federal income tax consequences to shareholders of investing in the Fund’s shares, reflects the federal tax law as of the date of this prospectus, and does not address special tax rules applicable to certain types of investors, such as corporate, tax-exempt and foreign investors. Investors should consult their tax advisors regarding other federal, state or local tax considerations that may be applicable in their particular circumstances, as well as any proposed tax law changes.
The following is a summary discussion of certain U.S. federal income tax consequences that may be relevant to a shareholder of the Fund that acquires, holds and/or disposes of shares of the Fund, and reflects provisions of the Internal Revenue Code of 1986, as amended, existing Treasury regulations, rulings published by the IRS, and other applicable authority, as of the date of this prospectus. These authorities are subject to change by legislative or administrative action, possibly with retroactive effect. The following discussion is only a summary of some of the important tax considerations generally applicable to investments in the Fund and the discussion set forth herein does not constitute tax advice. For more detailed information regarding tax considerations, see the Statement of Additional Information. There may be other tax considerations applicable to particular investors such as those holding shares in a tax deferred account such as an IRA or 401(k) plan. In addition, income earned through an investment in the Fund may be subject to state, local and foreign taxes.
The Fund intends to elect to be treated and to qualify each year for taxation as a regulated investment company under Subchapter M of the Code. In order for the Fund to qualify as a regulated investment company, it must meet an income and asset diversification test each year. If the Fund so qualifies and satisfies certain distribution requirements, the Fund (but not its shareholders) will not be subject to federal income tax to the extent it distributes its investment company taxable income and net capital gains (the excess of net long-term capital gains over net short-term capital loss) in a timely manner to its shareholders in the form of dividends or capital gain distributions. The Code imposes a 4% nondeductible excise tax on regulated investment companies, such as the Fund, to the extent they do not meet certain distribution requirements by the end of each calendar year. The Fund anticipates meeting these distribution requirements. Shareholders will not be subject to the alternative minimum tax.
The Fund intends to make distributions of investment company taxable income after payment of the Fund’s operating expenses no less frequently than annually. Unless a shareholder is ineligible to participate or elects otherwise, all distributions will be automatically reinvested in additional shares of the Fund pursuant to the dividend reinvestment policy. For U.S. federal income tax purposes, all dividends are generally taxable whether a shareholder takes them in cash or they are reinvested pursuant to the policy in additional shares of the Fund. Distributions of the Fund’s investment company taxable income (including short-term capital gains) will generally be treated as ordinary income to the extent of the Fund’s current and accumulated earnings and profits. Distributions of the Fund’s net capital gains (“capital gain dividends”), if any, are taxable to shareholders as capital gains, regardless of the length of time shares have been held by shareholders. Distributions, if any, in excess of the Fund’s earnings and profits will first reduce the adjusted tax basis of a holder’s shares and, after that basis has been reduced to zero, will constitute capital gains to the shareholder of the Fund (assuming the shares are held as a capital asset). A corporation that owns Fund shares generally will not be entitled to the dividends received deduction with respect to all of the dividends it receives from the Fund. Fund dividend payments that are attributable to qualifying dividends received by the Fund from certain domestic corporations may be designated by the Fund as being eligible for the dividends received deduction. There can be no assurance as to what portion of Fund dividend payments may be classified as qualifying dividends. The determination of the character for U.S. federal income tax purposes of any distribution from the Fund (i.e.
27 |
ordinary income dividends, capital gains dividends, qualified dividends or return of capital distributions) will be made as of the end of the Fund’s taxable year. Generally, no later than 60 days after the close of its taxable year, the Fund will provide shareholders with a written notice designating the amount of any capital gain distributions and any other distributions.
The Fund will inform its shareholders of the source and tax status of all distributions promptly after the close of each calendar year.
DESCRIPTION OF CAPITAL STRUCTURE AND SHARES
The Fund is an unincorporated statutory trust established under the laws of the State of Delaware upon the filing of a Certificate of Trust with the Secretary of State of Delaware on May 25, 2012. The Trustees are authorized to issue an unlimited number of shares. The Fund does not intend to hold annual meetings of its shareholders.
The Declaration of Trust, which has been filed with the SEC, permits the Fund to issue an unlimited number of full and fractional shares of beneficial interest, no par value. The Fund offers five different classes of shares: Class A, Class C, Class I, Class L and Class M shares. The Class A, Class C, Class I and Class L shares are each offered by a different prospectus. The Fund began continuously offering its common shares on October 22, 2012. As of February 18, 2014, the Fund simultaneously redesignated its issued and outstanding common shares as Class A shares and created its Class C and Class I shares, which commenced offering April 1, 2014. As of May 30, 2017, the Fund created its Class L shares. As of February 1, 2020, the Fund created its Class M shares. An investment in any share class of the Fund represents an investment in the same assets of the Fund. However, the minimum investment amounts, sales loads, and ongoing fees and expenses for each share class may be different. The fees and expenses for the Fund are set forth in “Summary of Fund Expenses”. The details of each share class are set forth in “Plan of Distribution”.
The following table shows the amounts of the Fund’s shares that have been authorized and are outstanding as of January 3, 2025, of which none were owned by the Fund:
Title of Class |
Amount Authorized |
Amount Outstanding |
Class A |
Unlimited |
24,385,031.72 shares NAV $26.03 per share |
Class C |
Unlimited |
15,397,873.19 shares NAV $24.05 per share |
Class I |
Unlimited |
115,282,227.36 shares NAV $26.80 per share |
Class L |
Unlimited |
3,111,066.77 shares NAV $25.54 per share |
Unlimited |
shares NAV $24.24 per share |
Holders of shares will be entitled to the payment of dividends when, as and if declared by the Board. The Fund currently intends to make dividend distributions to its shareholders no less frequently than quarterly. Unless the registered owner of shares elects to receive cash, all dividends declared on shares will be automatically reinvested for shareholders in additional shares of the same class of the Fund. See “Dividend Reinvestment Policy.” The 1940 Act may limit the payment of dividends to the holders of shares. Each whole share shall be entitled to one vote as to matters on which it is entitled to vote pursuant to the terms of the Declaration of Trust on file with the SEC. Upon liquidation of the Fund, after paying or adequately providing for the payment of all liabilities of the Fund, and upon receipt of such releases, indemnities and refunding agreements as they deem necessary for their protection, the Trustees may distribute the remaining assets of the Fund among its shareholders. The shares are not liable to further calls or to assessment by the Fund. There are no pre-emptive rights associated with the shares. The Declaration of Trust provides that the Fund’s shareholders are not liable for any liabilities of the Fund. Although shareholders of an unincorporated statutory trust established under Delaware law, in certain limited circumstances, may be held personally liable for the obligations of the Fund as though they were general partners, the provisions of the Declaration of Trust described in the foregoing sentence make the likelihood of such personal liability remote.
The Fund generally will not issue share certificates. However, upon written request to the Fund’s Transfer Agent, a share certificate may be issued at the Fund’s discretion for any or all of the full shares credited to an investor’s account. Share certificates that have been issued to an investor may be returned at any time. The Fund’s Transfer Agent will maintain an account for each shareholder upon which the registration of shares are recorded, and transfers, permitted only in rare circumstances, such as death or bona fide gift, will be reflected by bookkeeping entry, without physical delivery. The Fund’s Transfer Agent will require that a shareholder provide requests in writing, accompanied by a valid signature guarantee form, when changing certain information in an account such as wiring instructions or telephone privileges.
Other Classes of Shares. The Fund offers Class A, Class C, Class I and Class L shares by a different prospectus. The other share classes are subject to different investment minimums, sales charges, and shareholder servicing fees and/or distribution servicing fees.
ANTI-TAKEOVER PROVISIONS IN THE DECLARATION OF TRUST
The Amended and Restated Declaration of Trust includes provisions that could have the effect of limiting the ability of other entities or persons to acquire control of the Fund or to change the composition of the Board, and could have the effect of depriving the Fund’s shareholders of an opportunity to sell their shares at a premium over prevailing market prices, if any, by discouraging a third party from seeking to obtain control of the Fund. These provisions may have the effect of discouraging attempts to acquire control of the Fund, which attempts could have the effect of increasing the expenses of the Fund and interfering with the normal operation of the
28 |
Fund. The Trustees are elected for indefinite terms and do not stand for reelection. A Trustee may be removed from office without cause only by a written instrument signed or adopted by a majority of the remaining Trustees or by a vote of the holders of at least two-thirds of the shares of the Fund that are entitled to elect a Trustee and that are entitled to vote on the matter. The Declaration of Trust does not contain any other specific inhibiting provisions that would operate only with respect to an extraordinary transaction such as a merger, reorganization, tender offer, sale or transfer of substantially all of the Fund’s asset, or liquidation. Reference should be made to the Declaration of Trust on file with the SEC for the full text of these provisions.
PLAN OF DISTRIBUTION
ALPS Distributors, Inc. (the “Distributor”), located at 1290 Broadway, Suite 1000, Denver, Colorado 80203, serves as the Fund’s principal underwriter and acts as the distributor of the Fund’s shares on a best efforts basis, subject to various conditions. The Fund’s shares are offered for sale through the Distributor at net asset value plus the applicable sales load. The Distributor also may enter into selected dealer agreements with other broker dealers for the sale and distribution of the Fund’s shares, including with affiliates of the Advisor. In reliance on Rule 415, the Fund intends to offer to sell its shares, on a continual basis, through the Distributor. No arrangement has been made to place funds received in an escrow, trust or similar account. The Distributor is not required to sell any specific number or dollar amount of the Fund’s shares. Shares of the Fund will not be listed on any national securities exchange and the Distributor will not act as a market marker in Fund shares. The Class M shares will pay to the Distributor a Distribution Fee that will accrue at an annual rate equal to 0.75% of the Fund’s average daily net assets attributable to Class M shares and is payable on a monthly basis.
The Distributor has entered into a “wholesaling” agreement with Bluerock Capital Markets, LLC (“BCM”), a registered broker-dealer and an affiliate of the Advisor. Pursuant to the terms of the wholesaling agreement, BCM will seek to market and otherwise promote the Fund through various “wholesale” distribution channels, including regional and independent retail broker-dealers. BCM may receive a portion of the sales load from the sale certain classes of the Fund’s shares for the services it provides under the wholesaling agreement, but it does not receive compensation from the Fund in connection with the sale of Class M shares.
The Advisor or its affiliates, in the Advisor’s discretion and from their own resources, may pay additional compensation to brokers or dealers in connection with the sale and distribution of Fund shares (the “Additional Compensation”). In return for the Additional Compensation, the Fund may receive certain marketing advantages including access to a broker’s or dealer’s registered representatives, placement on a list of investment options offered by a broker or dealer, or the ability to assist in training and educating the broker’s or dealer’s registered representatives. The Additional Compensation may differ among brokers or dealers in amount or in the manner of calculation: payments of Additional Compensation may be fixed dollar amounts, or based on the aggregate value of outstanding shares held by shareholders introduced by the broker or dealer, or determined in some other manner. The receipt of Additional Compensation by a selling broker or dealer may create potential conflicts of interest between an investor and its broker or dealer who is recommending the Fund over other potential investments. Additionally, the Fund may pay a servicing fee to intermediaries and other financial industry professionals for providing ongoing services in respect of shareholders of the Fund. Such services may include electronic processing of client orders, electronic fund transfers between clients and the Fund, account reconciliations with the Fund’s Transfer Agent, facilitation of electronic delivery to clients of Fund documentation, monitoring client accounts for back-up withholding and any other special tax reporting obligations, maintenance of books and records with respect to the foregoing, and such other information and liaison services as the Fund or the Advisor may reasonably request.
The Fund and the Advisor have agreed to indemnify the Distributor against certain liabilities, including liabilities under the Securities Act of 1933, or to contribute to payments the Distributor may be required to make because of any of those liabilities. Such agreement does not include indemnification of the Distributor against liability resulting from willful misfeasance, bad faith or negligence on the part of the Distributor in the performance of its duties or from reckless disregard by the Distributor of its obligations and duties under the Distribution Agreement. The Distributor may, from time to time, engage in transactions with or perform services for the Advisor and its affiliates in the ordinary course of business.
Purchasing Shares
Investors may purchase shares directly from the Fund in accordance with the instructions below. Investors will be assessed fees for returned checks and stop payment orders at prevailing rates charged by SS&C GIDS, the Fund’s Transfer Agent. The returned check and stop payment fee is currently $25. Investors may buy and sell shares of the Fund through financial intermediaries and their agents that have made arrangements with the Fund and are authorized to buy and sell shares of the Fund (collectively, “Financial Intermediaries”). Such Financial Intermediaries are authorized to designate other intermediaries to receive purchase orders on the Fund’s behalf. The Fund will be deemed to have received a purchase order when a Financial Intermediary or, if applicable, its authorized designee, receives the order. Orders will be priced at the appropriate price next computed after it is received by a Financial Intermediary or their authorized designee and accepted by the Fund. A Financial Intermediary may hold shares in an omnibus account in the Financial Intermediary’s name or the Financial Intermediary or their authorized designee may maintain individual ownership records. The Fund may pay the Financial Intermediary for maintaining individual ownership records as well as providing other shareholder services. Financial intermediaries may charge fees for the services they provide in connection with processing your transaction order or maintaining an investor’s account with them. Investors should check with their Financial Intermediary to determine if it is subject to these arrangements. Financial Intermediaries are responsible for placing orders correctly and promptly with the Fund, forwarding payment promptly. Orders transmitted with a Financial Intermediary before the close of regular trading (generally 4:00 p.m., Eastern Time) on a day that the NYSE is open for business, will be priced based on the Fund’s NAV next computed after it is received by the Financial Intermediary.
The Fund reserves the right to reject or restrict purchase requests for any reason, particularly when the shareholder’s trading activity suggests that the shareholder may be engaged in disruptive trading activities. Neither the Fund nor the Advisor will be liable for any losses resulting from rejected purchase orders.
29 |
By Mail
To make an initial purchase by mail, complete an account application and mail the application, together with a check made payable to Bluerock Total Income+ Real Estate Fund to:
Bluerock Total Income+ Real Estate Fund
c/o SS&C GIDS
P.O. Box 219445
Kansas City, MO 64121-9445
All checks must be in U.S. Dollars drawn on a domestic bank. The Fund will not accept payment in cash or money orders. The Fund also does not accept cashier’s checks in amounts of less than $10,000. To prevent check fraud, the Fund will neither accept third party checks, Treasury checks, credit card checks, traveler’s checks or starter checks for the purchase of shares, nor post-dated checks, post-dated on-line bill pay checks, or any conditional purchase order or payment.
The Transfer Agent will charge a $25 fee against an investor’s account, in addition to any loss sustained by the Fund, for any payment that is returned. It is the policy of the Fund not to accept applications under certain circumstances or in amounts considered disadvantageous to shareholders. The Fund reserves the right to reject any application.
By Wire — Initial Investment
To make an initial investment in the Fund, the Transfer Agent must receive a completed account application before an investor wires funds. Investors may mail or overnight deliver an account application to the Transfer Agent. Upon receipt of the completed account application, the Transfer Agent will establish an account. The account number assigned will be required as part of the instruction that should be provided to an investor’s bank to send the wire. An investor’s bank must include both the name of the Fund, the account number, and the investor’s name so that monies can be correctly applied. If you wish to wire money to make an investment in the Fund, please call the Fund at 1-844-819-8287 for wiring instructions and to notify the Fund that a wire transfer is coming. Any commercial bank can transfer same-day funds via wire. The Fund will normally accept wired funds for investment on the day received if they are received by the Fund’s designated bank before the close of regular trading on the NYSE. Your bank may charge you a fee for wiring same-day funds. The bank should transmit funds by wire to:
ABA #: (number provided by calling toll-free number above)
Credit: SS&C GIDS
Account #: (number provided by calling toll-free number above)
Further Credit:
Bluerock Total Income+ Real Estate Fund
(shareholder registration)
(shareholder account number)
By Wire — Subsequent Investments
Before sending a wire, investors must contact the Transfer Agent to advise them of the intent to wire funds. This will ensure prompt and accurate credit upon receipt of the wire. Wired funds must be received prior to 4:00 p.m. Eastern Time to be eligible for same day pricing. The Fund, and its agents, including the transfer agent and custodian, are not responsible for the consequences of delays resulting from the banking or Federal Reserve wire system, or from incomplete wiring instructions.
Automatic Investment Plan — Subsequent Investments
You may participate in the Fund’s Automatic Investment Plan, an investment plan that automatically moves money from your bank account and invests it in the Fund through the use of electronic funds transfers or automatic bank drafts. You may elect to make subsequent investments by transfers of a minimum of $100 on specified days of each month into your established Fund account. Please contact the Fund at 1-844-819-8287 for more information about the Fund’s Automatic Investment Plan.
By Telephone
Investors may purchase additional shares of the Fund by calling 1-844-819-8287. If an investor elected this option on the account application, and the account has been open for at least 15 days, telephone orders will be accepted via electronic funds transfer from your bank account through the Automated Clearing House (ACH) network. Banking information must be established on the account prior to making a purchase. Orders for shares received prior to 4:00 p.m. Eastern Time will be purchased at the appropriate price calculated on that day.
Telephone trades must be received by or prior to market close. During periods of high market activity, shareholders may encounter higher than usual call waits. Please allow sufficient time to place your telephone transaction.
In compliance with the USA Patriot Act of 2001, the Transfer Agent will verify certain information on each account application as part of the Fund’s Anti-Money Laundering Program. As requested on the application, investors must supply full name, date of birth, social security number and permanent street address. Mailing addresses containing only a P.O. Box will not be accepted. Investors may call the Transfer Agent (SS&C GIDS) at 1-844-819-8287 for additional assistance when completing an application.
30 |
If the Transfer Agent does not have a reasonable belief of the identity of a customer, the account will be rejected or the customer will not be allowed to perform a transaction on the account until such information is received. The Fund also may reserve the right to close the account within 5 business days if clarifying information/documentation is not received.
Share Class Considerations
When selecting a share class, you should consider the following:
|
● |
which share classes are available to you; |
|
● |
the amount you intend to invest; |
|
● |
how long you expect to own the shares; and |
|
● |
total costs and expenses associated with a particular share class. |
Each investor’s financial considerations are different. You should speak with your financial advisor to help you decide which share class is best for you. Not all financial intermediaries offer all classes of shares. If your financial intermediary offers more than one class of shares, you should carefully consider which class of shares to purchase.
Class M Shares
Class M shares will be sold at the prevailing NAV per Class M share and are not subject to any upfront sales charge; however, the following are additional features that should be taken into account when purchasing Class M shares:
|
● |
a minimum initial investment of $25,000 and a minimum subsequent investment of at least $10,000; |
|
● |
Class M shares are not subject to shareholder servicing fee; |
|
● |
a Distribution Fee which will accrue at an annual rate equal to 0.75% of the average daily net assets of the Fund attributable to Class M shares; and |
|
● |
Class M shares are not subject to an early withdrawal charge. |
Because the Class M shares of the Fund will be sold at the prevailing NAV per Class M share without an upfront sales load, the entire amount of your purchase is invested immediately.
Share Conversion
For investors currently owning Class A, Class C, Class L or Class M shares, these shares may be convertible into Class I shares if (i) the broker/dealer or other financial intermediary responsible for the shareholder relationship requests such conversion, (ii) Class I shares are available to the broker dealer or financial intermediary, and (iii) the account would have been eligible to purchase Class I shares. More detailed information on Class I shares and the related investment minimums and other restrictions is available in the Fund’s Class I prospectus.
Shareholder Service Plan
Class M shares are not subject to a shareholder servicing fee.
Distribution Plan
The Fund, with respect to its Class M shares, is authorized under a “Distribution Plan” to pay to the Distributor a Distribution Fee for certain activities relating to the distribution of shares to investors and maintenance of shareholder accounts. These activities include marketing and other activities to support the distribution of the Class M shares. The Plan operates in a manner consistent with Rule 12b-1 under the 1940 Act, which regulates the manner in which an open-end investment company may directly or indirectly bear the expenses of distributing its shares. Although the Fund is not an open-end investment company, it has undertaken to comply with the terms of Rule 12b-1 as a condition of an exemptive order under the 1940 Act which permits it to have asset based distribution fees. Under the Distribution Plan, the Fund pays the Distributor a Distribution Fee at an annual rate of 0.75% of average daily net assets attributable to Class M shares. Because these fees are paid from the Fund’s assets on an ongoing basis they will increase your costs over time and may cost you more than paying other types of sales charges.
LEGAL MATTERS
Certain legal matters in connection with the shares will be passed upon for the Fund by Thompson Hine LLP, 41 South High Street, Suite 1700, Columbus, Ohio 43215.
REPORTS TO SHAREHOLDERS
The Fund makes available to its shareholders unaudited semi-annual and audited annual reports, including a list of investments held.
31 |
Householding
If you have elected to receive paper copies of the Fund’s annual and semi-annual reports, in an effort to decrease costs, the Fund intends to send only one copy of each to those addresses shared by two or more accounts and to shareholders reasonably believed to be from the same family or household. A shareholder must call 1-844-819-8287 to discontinue householding and request individual copies of these documents. Once the Fund receives notice to stop householding, individual copies will be sent beginning thirty days after receiving your request. This policy does not apply to account statements.
INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
Cohen & Company, Ltd. is the independent registered public accounting firm for the Fund and audits the Fund’s financial statements. Cohen & Company, Ltd. is located at 1835 Market St., Suite 310, Philadelphia, PA 19103.
ADDITIONAL INFORMATION
The Prospectus and the Statement of Additional Information do not contain all of the information set forth in the Registration Statement that the Fund has filed with the SEC (file No. 811-22710). The complete Registration Statement may be obtained from the SEC at www.sec.gov. See the cover page of this prospectus for information about how to obtain a paper copy of the Registration Statement or Statement of Additional Information without charge.
TABLE OF CONTENTS OF THE STATEMENT OF ADDITIONAL INFORMATION
General Information and History |
1 |
Investment Objectives and Policies |
2 |
Repurchases and Transfers of Shares |
9 |
Management of the Fund |
15 |
Codes of Ethics |
22 |
Proxy Voting Policies and Procedures |
22 |
Control Persons and Principal Holders |
22 |
Investment Advisory and Other Services |
23 |
Portfolio Managers |
27 |
Allocation of Brokerage |
31 |
Tax Status |
31 |
Other Information |
35 |
Independent Registered Public Accounting Firm |
36 |
Financial Statements |
36 |
Appendix A |
A-1 |
Appendix B |
B-1 |
32 |
PRIVACY POLICY & PRACTICES
Rev. January 2019
PRIVACY NOTICE
FACTS |
WHAT DOES THE BLUEROCK TOTAL INCOME+ REAL ESTATE FUND DO WITH YOUR PERSONAL INFORMATION? |
|
Why? |
Financial companies choose how they share your personal information. Federal law gives consumers the right to limit some but not all sharing. Federal law also requires us to tell you how we collect, share, and protect your personal information. Please read this notice carefully to understand what we do. |
|
What? |
The types of personal information we collect and share depend on the product or service you have with us. This information can include: |
|
● Social Security number
● Assets
● Retirement Assets
● Transaction History
● Checking Account Information |
● Purchase History
● Account Balances
● Account Transactions
● Wire Transfer Instructions |
|
When you are no longer our customer, we may continue to share your personal information as described in this notice. |
||
How? |
All financial companies need to share customers’ personal information to run their everyday business. In the section below, we list the reasons financial companies can share their customers’ personal information; the reasons the Bluerock Total Income+ Real Estate Fund chooses to share; and whether you can limit this sharing. |
|
Reasons we can share your personal information |
Does Bluerock Total Income+ Real Estate Fund share? |
Can you limit this sharing? |
For our everyday business purposes – such as to process your transactions, maintain your account(s), respond to court orders and legal investigations, or report to credit bureaus |
Yes |
No |
For our marketing purposes – to offer our products and services to you |
No |
We don’t share |
For joint marketing with other financial companies |
No |
We don’t share |
For our affiliates’ everyday business purposes – information about your transactions and experiences |
No |
We don’t share |
For our affiliates’ everyday business purposes – information about your creditworthiness |
No |
We don’t share |
For nonaffiliates to market to you |
No |
We don’t share |
Questions? |
Call 1-844-819-8287 |
33 |
Who we are |
|
Who is providing this notice? |
Bluerock Total Income+ Real Estate Fund |
What we do |
|
How does Bluerock Total Income+ Real Estate Fund protect my personal information? |
To protect your personal information from unauthorized access and use, we use security measures that comply with federal law. These measures include computer safeguards and secured files and buildings.
Our service providers are held accountable for adhering to strict policies and procedures to prevent any misuse of your nonpublic personal information. |
How does Bluerock Total Income+ Real Estate Fund collect my personal information? |
We collect your personal information, for example, when you
● Open an account
● Provide account information
● Give us your contact information
● Make deposits or withdrawals from your account
● Make a wire transfer
● Tell us where to send the money
● Tells us who receives the money
● Show your government-issued ID
● Show your driver’s license
We also collect your personal information from other companies. |
Why can’t I limit all sharing? |
Federal law gives you the right to limit only
● Sharing for affiliates’ everyday business purposes – information about your creditworthiness
● Affiliates from using your information to market to you
● Sharing for nonaffiliates to market to you
State laws and individual companies may give you additional rights to limit sharing. |
Definitions |
|
Affiliates |
Companies related by common ownership or control. They can be financial and nonfinancial companies.
● Bluerock Total Income+ Real Estate Fund does not share with our affiliates. |
Nonaffiliates |
Companies not related by common ownership or control. They can be financial and nonfinancial companies
● Bluerock Total Income+ Real Estate Fund does not share with nonaffiliates so they can market to you. |
Joint marketing |
A formal agreement between nonaffiliated financial companies that together market financial products or services to you.
● Bluerock Total Income+ Real Estate Fund doesn’t jointly market. |
34 |
Page Intentionally Left Blank
Page Intentionally Left Blank
Page Intentionally Left Blank

BLUEROCK TOTAL INCOME+ REAL ESTATE FUND
Class M Shares (TIPMX) of Beneficial Interest
PROSPECTUS
February 1, 2025
Investment Advisor
Bluerock Fund Advisor, LLC
All dealers that buy, sell or trade the Fund’s shares, whether or not participating in this offering, may be required to deliver a prospectus when acting on behalf of the Fund’s Distributor.
You should rely only on the information contained in or incorporated by reference into this prospectus. The Fund has not authorized any other person to provide you with different information. If anyone provides you with different or inconsistent information, you should not rely on it. The Fund is not making an offer to sell these securities in any jurisdiction where the offer or sale is not permitted.

BLUEROCK TOTAL INCOME+ REAL ESTATE FUND
Principal Executive Offices
919 Third Avenue, 40th Floor, New York, NY 10022
1-844-819-8287
This Statement of Additional Information (“SAI”) is not a prospectus. This SAI should be read in conjunction with the Class A, Class C, Class I, Class L and Class M shares’ prospectuses of Bluerock Total Income+ Real Estate Fund, each dated February 1, 2025, (each a “Prospectus” and collectively, the “Prospectuses”), each which may be supplemented from time to time. The Prospectuses are hereby incorporated by reference into this SAI (legally made a part of this SAI). Capitalized terms used but not defined in this SAI have the meanings given to them in the Prospectus. This SAI does not include all information that a prospective investor should consider before purchasing the Fund’s securities.
You should obtain and read the relevant share class Prospectus and any related Prospectus supplement prior to purchasing any of the Fund’s securities. A copy of the Prospectuses may be obtained without charge by calling the Fund toll-free at 1-844-819-8287 or by visiting http://www.bluerockfunds.com. Information on the website is not incorporated herein by reference. The registration statement of which the Prospectuses are a part can be reviewed and copied at the Public Reference Room of the U.S. Securities and Exchange Commission (“SEC”) at 100 F Street NE, Washington, D.C. You may obtain information on the operation of the Public Reference Room by calling the SEC at 1-202-551-8090. The Fund’s filings with the SEC also are available to the public on the SEC’s Internet web site at www.sec.gov. Copies of these filings may be obtained, after paying a duplicating fee, by electronic request at the following E-mail address: [email protected], or by writing the SEC’s Public Reference Section, 100 F Street NE, Washington, D.C. 20549.
 |
Investment Advisor | Bluerock Fund Advisor, LLC The date of this SAI is February 1, 2025 |
TABLE OF CONTENTS
| General Information and History | 1 |
| Investment Objectives and Policies | 1 |
| Repurchases and Transfers of Shares | 9 |
| Management of the Fund | 15 |
| Codes of Ethics | 21 |
| Proxy Voting Policies and Procedures | 21 |
| Control Persons and Principal Holders | 22 |
| Investment Advisory and Other Services | 23 |
| Portfolio Managers | 26 |
| Allocation of Brokerage | 30 |
| Tax Status | 31 |
| Other Information | 36 |
| Independent Registered Public Accounting Firm | 37 |
| Financial Statements | 37 |
| Appendix A | A-1 |
| Appendix B | B-1 |
GENERAL INFORMATION AND HISTORY
Bluerock Total Income+ Real Estate Fund is a continuously offered, non-diversified, closed-end management investment company that is operated as an interval fund (the “Fund” or the “Trust”). The Fund was organized as a Delaware statutory trust on May 25, 2012. The Fund’s principal office is located at 919 Third Avenue, 40th Floor, New York, NY 10022, and its telephone number is 1-844-819-8287. The investment objective and principal investment strategies of the Fund, as well as the principal risks associated with the Fund’s investment strategies, are set forth in the Prospectuses. Certain additional investment information is set forth below. The Fund may issue an unlimited number of shares of beneficial interest. All shares of the Fund have equal rights and privileges. Each share of the Fund is entitled to one vote on all matters as to which shares are entitled to vote. In addition, each share of the Fund is entitled to participate, on a class-specific basis, equally with other shares (i) in dividends and distributions declared by the Fund and (ii) on liquidation to its proportionate share of the assets remaining after satisfaction of outstanding liabilities. Shares of the Fund are fully paid, non-assessable and fully transferable when issued and have no pre-emptive, conversion or exchange rights. Fractional shares have proportionately the same rights, including voting rights, as are provided for a full share.
The Fund engages in continuous offerings of: Class A, Class C, Class I, Class L and Class M shares. Each class of shares is offered by a separate prospectus. Each share class represents an interest in the same assets of the Fund, has the same rights and is identical in all material respects except that (i) each class of shares may be subject to different (or no) sales loads, (ii) each class of shares may bear different (or no) distribution and shareholder servicing fees; (iii) each class of shares may have different shareholder features, such as minimum investment amounts; (iv) certain other class-specific expenses will be borne solely by the class to which such expenses are attributable, including transfer agent fees attributable to a specific class of shares, printing and postage expenses related to preparing and distributing materials to current shareholders of a specific class, registration fees paid by a specific class of shares, the expenses of administrative personnel and services required to support the shareholders of a specific class, litigation or other legal expenses relating to a class of shares, Trustees’ fees or expenses paid as a result of issues relating to a specific class of shares and accounting fees and expenses relating to a specific class of shares and (v) each class has exclusive voting rights with respect to matters relating to its own distribution arrangements. The Fund’s Board of Trustees (the “Board” or “Trustees”) may classify and reclassify the shares of the Fund into additional classes of shares at a future date.
INVESTMENT OBJECTIVES AND POLICIES
Investment Objectives
The Fund’s primary investment objective is to generate current income while secondarily seeking long-term capital appreciation with low to moderate volatility and low correlation to the broader markets.
1
Fundamental Policies
The Fund’s stated fundamental policies, which may only be changed by the affirmative vote of a majority of the outstanding voting securities of the Fund (the shares), are listed below. For the purposes of this SAI, “majority of the outstanding voting securities of the Fund” means the vote, at an annual or special meeting of shareholders, duly called, (a) of 67% or more of the shares present at such meeting, if the holders of more than 50% of the outstanding shares are present or represented by proxy; or (b) of more than 50% of the outstanding shares, whichever is less. The Fund may not:
(1) Borrow money, except to the extent permitted by the Investment Company Act of 1940, as amended (the “1940 Act”) (which currently limits borrowing to no more than 33-1/3% of the value of the Fund’s total assets, including the value of the assets purchased with the proceeds of its indebtedness, if any). The Fund may borrow for investment purposes, for temporary liquidity, or to finance repurchases of its shares.
(2) Issue senior securities, except to the extent permitted by Section 18 of the 1940 Act (which currently limits the issuance of a class of senior securities that is indebtedness to no more than 33-1/3% of the value of the Fund’s total assets or, if the class of senior security is stock, to no more than 50% of the value of the Fund’s total assets).
(3) Purchase securities on margin, but may sell securities short and write put and call options.
(4) Underwrite securities of other issuers, except insofar as the Fund may be deemed an underwriter under the Securities Act of 1933, as amended (the “Securities Act”) in connection with the disposition of its portfolio securities. The Fund may invest in restricted securities (those that must be registered under the Securities Act before they may be offered or sold to the public) to the extent permitted by the 1940 Act.
(5) Invest more than 25% of the market value of its assets in the securities of companies or entities engaged in any one industry, except the real estate industry. This limitation does not apply to investment in the securities of the U.S. Government, its agencies or instrumentalities. Under normal circumstances, the Fund invests over 25% of its assets in the securities of companies in the real estate industry.
(6) Purchase or sell commodities, commodity contracts, including commodity futures contracts, unless acquired as a result of ownership of securities or other investments, except that the Fund may invest in securities or other instruments backed by or linked to commodities, and invest in companies that are engaged in a commodities business or have a significant portion of their assets in commodities, and may invest in commodity pools and other entities that purchase and sell commodities and commodity contracts.
(7) Make loans to others, except (a) where each loan is represented by a note executed by the borrower, (b) through the purchase of debt securities in accordance with its investment objectives and policies, (c) to the extent the entry into a repurchase agreement is deemed to be a loan, and (d) by loaning portfolio securities.
2
Other Fundamental Policies
(1) In addition, the Fund has adopted a fundamental policy that it will make quarterly repurchase offers for no less than for 5% of the Fund’s shares outstanding at net asset value (“NAV”) less any early withdrawal charge, unless suspended or postponed in accordance with regulatory requirements, and each repurchase pricing shall occur no later than the 14th day after the Repurchase Request Deadline, or the next business day if the 14th is not a business day.
(2) The Fund may invest in real estate or interests in real estate, securities that are secured by or represent interests in real estate (e.g. mortgage loans evidenced by notes or other writings defined to be a type of security), mortgage-related securities or investing in companies engaged in the real estate business or that have a significant portion of their assets in real estate (including real estate investment trusts).
If a restriction on the Fund’s investments is adhered to at the time an investment is made, a subsequent change in the percentage of Fund assets invested in certain securities or other instruments, or change in average duration of the Fund’s investment portfolio, resulting from changes in the value of the Fund’s total assets, will not be considered a violation of the restriction; provided, however, that the asset coverage requirement applicable to borrowings shall be maintained in the manner contemplated by applicable law.
Non-Fundamental Policies
The following are additional investment limitations of the Fund and may be changed by the Board without shareholder approval.
(1) 80% Investment Policy. The Fund has adopted a policy to invest at least 80% of its assets (defined as net assets plus the amount of any borrowing for investment purposes) in real estate industry securities, as defined in the Prospectus. Shareholders of the Fund will be provided with at least 60 days prior notice of any change in the Fund’s 80% policy. The notice will be provided in a separate written document containing the following, or similar, statement, in boldface type: “Important Notice Regarding Change in Investment Policy.” The statement will also appear on the envelope in which the notice is delivered, unless the notice is delivered separately from other communications to the shareholder.
If a restriction on a Fund’s investments is adhered to at the time an investment is made, a subsequent change in the percentage of Fund assets invested in certain securities or other instruments, or change in average duration of a Fund’s investment portfolio, resulting from changes in the value of a Fund’s total assets, will not be considered a violation of the restriction; provided, however, that the asset coverage requirement applicable to borrowings shall be maintained in the manner contemplated by applicable law.
Certain Portfolio Securities and Other Operating Policies
As discussed in the Prospectus, the Fund invests in securities of Institutional Investment Funds, Other Public Investment Vehicles, Real Estate Related Debt Securities and other real estate industry securities. No assurance can be given that any or all investment strategies, or the Fund’s investment program, will be successful. The Fund’s investment advisor is Bluerock Fund Advisor, LLC (the “Advisor”). The Advisor is responsible for allocating the Fund’s assets among various securities using its investment strategies, subject to policies adopted by the Board. Additional information regarding the types of securities and financial instruments is set forth below.
3
Convertible Securities
The Fund may invest in convertible securities. Convertible securities are hybrid securities that have characteristics of both bonds and common stocks and are subject to risks associated with both debt securities and equity securities. Convertible securities are similar to fixed-income securities because they usually pay a fixed interest rate (or dividend) and are obligated to repay principal on a given date in the future. The market value of fixed-income and preferred securities tends to decline as interest rates increase and tends to increase as interest rates decline. Convertible securities have characteristics of a fixed-income security and are particularly sensitive to changes in interest rates when their conversion value is lower than the value of the bond or preferred share. Fixed-income and preferred securities also are subject to credit risk, which is the risk that an issuer of a security may not be able to make principal and interest or dividend payments on the security as they become due. Fixed-income and preferred securities also may be subject to prepayment or redemption risk. If a convertible security held by the Fund is called for redemption, the Fund will be required to surrender the security for redemption, convert it into the issuing company’s common stock or cash or sell it to a third party at a time that may be unfavorable to the Fund. In addition, the Fund may invest in fixed-income and preferred securities rated less than investment grade that are sometimes referred to as high yield or “junk bonds.” These securities are speculative investments that carry greater risks and are more susceptible to real or perceived adverse economic and competitive industry conditions than higher quality securities. Such securities also may be subject to resale restrictions. The lack of a liquid market for these securities could decrease the Fund’s share price. Convertible securities have characteristics similar to common stocks especially when their conversion value is the same as the value of the bond or preferred share. The price of equity securities may rise or fall because of economic or political changes. Stock prices in general may decline over short or even extended periods of time. Market prices of equity securities in broad market segments may be adversely affected by a prominent issuer having experienced losses or by the lack of earnings or such an issuer’s failure to meet the market’s expectations with respect to new products or services, or even by factors wholly unrelated to the value or condition of the issuer, such as changes in interest rates.
Institutional Investment Funds
The Fund attempts to achieve its investment objectives by allocating its capital among a select group of institutional asset managers with expertise in managing portfolios of real estate and real estate related securities. Institutional Investment Funds typically accept investments on a continuous basis, have quarterly repurchases, and do not have a defined termination date.
In addition to diversification across property type and geographic markets, Institutional Investment Funds may diversify by differing underlying economic drivers, including anticipated job growth, population growth or inflation. No specific limits have been established within the Fund’s investment guidelines for property type and geographic investments; however, many of the Institutional Investment Funds have NAV limitations for any one individual property held by such Funds relative to the NAV of the Institutional Investment Fund’s overall portfolio. While some institutional asset managers will seek diversification across property types, certain Institutional Investment Funds may have a more specific focus and not seek such diversification, but instead utilize an investment strategy utilizing expertise within specific or multiple property categories.
4
The Institutional Investment Funds may utilize leverage, pursuant to their operative documents, as a way to seek or enhance returns. Dependent upon the investment strategy, geographic focus and/or other economic or property specific factors, each Institutional Investment Fund will have differing limitations on the utilization of leverage. Such limitations are Institutional Investment Fund specific and may apply to an overall portfolio limitation as well as a property specific limitation. The Fund intends to limit its direct borrowing and the overall leverage of its portfolio to an amount that does not exceed 33 1/3% of the Fund’s gross asset value.
Real Estate Related Debt Securities
The Fund may invest in real estate related direct debt including first and second mortgage loans, mezzanine loans and other structured debt investments.
Government Sponsored Entities
The Fund may invest in Government Sponsored Entities (“GSEs”) such as Federal Home Loan Mortgage Corporation Structured Pass-Through Certificates, known as “K-Notes.” K-Notes are securitized interests in pools of multifamily mortgages that are assembled by the Federal Home Loan Mortgage Corporation (“Freddie Mac”) and issued by special purpose trusts. K-Notes are issued with varying levels of maturity and seniority. Some K-Notes are repurchased and reissued by Freddie Mac with a Freddie Mac guarantee, while other K-Notes do not have a Freddie Mac guarantee. The Fund expects to invest in the privately offered subordinate classes of K-Notes. Because more-senior classes have payment priority over subordinate classes of K-Notes, the value of subordinate K-Notes is highly sensitive to the default rate and foreclosure recovery rate on the underlying apartment loans. Subordinate K-Notes are also subject to liquidity risk because they are not available to the investing public and have a limited secondary market composed of institutional investors.
Money Market Instruments
The Fund may invest, for defensive purposes or otherwise, some or all of its assets in high quality fixed-income securities, money market instruments, and money market mutual funds, or hold cash or cash equivalents in such amounts as the Fund or RREEF deems appropriate under the circumstances. Pending allocation of this offering proceeds and thereafter, from time to time, the Fund also may invest in these instruments and Other Public Investment Vehicles. Money market instruments are high quality, short-term fixed-income obligations, which generally have remaining maturities of one year or less, and may include U.S. Government securities, commercial paper, certificates of deposit and bankers’ acceptances issued by domestic branches of U.S. banks that are members of the Federal Deposit Insurance Corporation (the “FDIC”), and repurchase agreements.
5
Other Investment Companies
The Fund may invest in securities of other investment companies, including exchange-traded funds (“ETFs”). The Fund will indirectly bear its proportionate share of any management fees and other expenses paid by investment companies in which it invests, in addition to the management fees (and other expenses) paid by the Fund. The Fund’s investments in other investment companies are subject to statutory limitations prescribed by the 1940 Act, including in certain circumstances a prohibition on the Fund acquiring more than 3% of the voting shares of any other investment company, and a prohibition on investing more than 5% of the Fund’s total assets in securities of any one investment company or more than 10% of its total assets in the securities of all investment companies. In addition, Section 12(d)(1)(F) of the 1940 Act provides that the provisions of paragraph 12(d)(1) shall not apply to securities purchased or otherwise acquired by the Fund if (i) immediately after such purchase or acquisition not more than 3% of the total outstanding stock of such registered investment company is owned by the Fund and all affiliated persons of the Fund; and (ii) the Fund has not, and is not proposing to offer or sell any security issued by it through a principal underwriter or otherwise at a public or offering price which includes a sales load of more than 1.5%. An investment company that issues shares to the Fund pursuant to paragraph 12(d)(1)(F) shall not be required to redeem its shares in an amount exceeding 1% of such investment company’s total outstanding shares in any period of less than thirty days. The Fund (or the Advisor acting on behalf of the Fund) must comply with the following voting restrictions: when the Fund exercises voting rights, by proxy or otherwise, with respect to investment companies owned by the Fund, the Fund will either seek instruction from the Fund’s shareholders with regard to the voting of all proxies and vote in accordance with such instructions, or vote the shares held by the Fund in the same proportion as the vote of all other holders of such security. Further, the Fund may rely on Rule 12d1-3, which allows unaffiliated investment companies to exceed the 5% Limitation and the 10% Limitation, provided the aggregate sales loads any investor pays does not exceed the limits on sales loads established by the Financial Industry Regulatory Authority (“FINRA”) for funds of funds. Many ETFs, however, have obtained exemptive relief from the SEC to permit unaffiliated funds (such as the Fund) to invest in their shares beyond these statutory limits, subject to certain conditions and pursuant to contractual arrangements between the ETFs and the investing funds. The Fund may rely on these exemptive orders in investing in ETFs.
ETFs are shares of unaffiliated investment companies issuing shares which are traded like traditional equity securities on a national stock exchange. Much like an index mutual fund, an ETF represents a portfolio of securities, which is often designed to track a particular market segment or index. An investment in an ETF, like one in any investment company, carries the same risks as those of its underlying securities. An ETF may fail to accurately track the returns of the market segment or index that it is designed to track, and the price of an ETF’s shares may fluctuate or lose money. In addition, because they, unlike other investment companies, are traded on an exchange, ETFs are subject to the following risks: (i) the market price of the ETF’s shares may trade at a premium or discount to the ETF’s net asset value; (ii) an active trading market for an ETF may not develop or be maintained; and (iii) there is no assurance that the requirements of the exchange necessary to maintain the listing of the ETF will continue to be met or remain unchanged. In the event substantial market or other disruptions affecting ETFs should occur in the future, the liquidity and value of the Fund’s shares could also be substantially and adversely affected.
6
Although not a principal investment strategy, the Fund may not invest more than 10% of its assets in private funds employing hedging strategies (commonly known as “hedge funds”, i.e., investment funds that would be investment companies but for the exemptions under Rule 3(c)(1) or 3(c)(7) under the 1940 Act). Among other things, the hedge funds may invest in U.S. and non-U.S. equity and debt securities and may engage in leverage, short selling and derivative transactions. Hedge funds typically offer their securities privately without registration under the Securities Act, in large minimum denominations (often at least $1 million) to a limited number of high net worth individual and institutional investors hedge funds are not registered as investment companies under the 1940 Act pursuant to an exemption from registration under the 1940 Act.
Typically, investment managers of hedge funds are compensated through asset-based fees and incentive-based allocations. The hedge funds employ a variety of “alternative” investment strategies to achieve attractive risk-adjusted returns (i.e., returns adjusted to take into account the volatility of those returns) with low correlation to the broad equity and fixed-income markets. “Alternative” investment strategies, unlike “relative return strategies,” are generally managed without reference to the performance of equity, debt and other markets. Alternative investment strategies permit the managers of hedge funds to use leveraged or short sale positions to take advantage of perceived inefficiencies in the global capital markets. Alternative investment strategies differ from the investment programs of traditional registered investment companies, such as mutual funds. “Traditional” investment companies are generally characterized by long-only investments and restricted use of leverage.
Special Investment Techniques
The Fund may use a variety of special investment instruments and techniques to hedge against various risks or other factors and variables that may affect the values of the Fund’s portfolio securities. The Fund may employ different techniques over time, as new instruments and techniques are introduced or as a result of regulatory developments. Some special investment techniques that the Fund may use may be considered speculative and involve a high degree of risk, even when used for hedging purposes. A hedging transaction may not perform as anticipated, and the Fund may suffer losses as a result of its hedging activities.
Derivatives
Generally. The Fund may engage in transactions involving options and futures and other derivative financial instruments. Derivatives can be volatile and involve various types and degrees of risk. By using derivatives, the Fund may be permitted to increase or decrease the level of risk, or change the character of the risk, to which the portfolio is exposed.
A small investment in derivatives could have a substantial impact on the Fund’s performance. The market for many derivatives is, or suddenly can become, illiquid. Changes in liquidity may result in significant and rapid changes in the prices for derivatives. If the Fund were to invest in derivatives at an inopportune time, or the Advisor evaluates market conditions incorrectly, the Fund’s derivative investment could negatively impact the Fund’s return, or result in a loss. In addition, the Fund could experience a loss if its derivatives were poorly correlated with its other investments, or if the Fund were unable to liquidate its position because of an illiquid secondary market.
7
Options and Futures. The Fund may engage in the use of options and futures contracts, including options on baskets of specific securities, or other derivative instruments written by broker-dealers or other financial intermediaries. These transactions may be effected on securities exchanges or in the over-the-counter market, or they may be negotiated directly with counterparties. In cases where instruments are purchased over-the-counter or negotiated directly with counterparties, the Fund is subject to the risk that the counterparty will be unable or unwilling to perform its obligations under the contract. These transactions may also be illiquid and, if so, it might be difficult to close out a position.
The Fund may purchase call and put options on specific securities. The Fund may also write and sell covered or uncovered call options for both hedging purposes and to pursue the Fund’s investment objectives. A put option gives the purchaser of the option the right to sell, and obligates the writer to buy, the underlying security at a stated price at any time before the option expires. Similarly, a call option gives the purchaser of the option the right to buy, and obligates the writer to sell, the underlying security at a stated price at any time before the option expires.
In a covered call option, the Fund owns the underlying security. The sale of such an option exposes the Fund to a potential loss of opportunity to realize appreciation in the market price of the underlying security during the term of the option. Using covered call options might expose the Fund to other risks, as well. For example, the Fund might be required to continue holding a security that the Fund might otherwise have sold to protect against depreciation in the market price of the security. The Fund is also exposed to price declines in the underlying security.
In an uncovered call option, the Fund does not own the underlying security. The sale of such an option exposes the Fund to potentially unlimited loss if the market for the instrument for which the call is written appreciates instead of depreciating. The Fund does not anticipate writing uncovered call options frequently.
Transactions using options, either covered or uncovered (other than options that the Fund has purchased), expose the Fund to an obligation to another party. The Fund will not enter into any such transactions unless it owns either (i) an offsetting (“covered”) position in securities or other options or (ii) cash or liquid securities with a value sufficient at all times to cover its potential obligations not covered as provided in (i) above (“uncovered”). The Fund will comply with SEC guidelines regarding cover for these instruments and, if the guidelines so require, set aside cash or liquid securities in a segregated account with the custodian in the prescribed amount. Under current SEC guidelines, the Fund will segregate assets to cover transactions in which the Fund writes or sells options.
Assets used as cover or held in a segregated account cannot be sold while the position in the corresponding option is open, unless they are replaced with similar assets. As a result, the commitment of a large portion of the Fund’s assets to cover or segregated accounts could impede portfolio management or the Fund’s ability to meet redemption requests or other current obligations.
8
When writing options, the Fund may close its position by purchasing an option on the same security with the same exercise price and expiration date as the option that it has previously written on the security. If the amount paid to purchase an option is less or more than the amount received from the sale, the Fund will, accordingly, realize a profit or loss. To close out a position as a purchaser of an option, the Fund would liquidate the position by selling the option previously purchased.
The use of derivatives that are subject to regulation by the Commodity Futures Trading Commission (the “CFTC”) by the Fund could cause the Fund to be a commodity pool, which would require the Fund to comply with certain rules of the CFTC. However, the Fund intends to conduct its operations to avoid regulation as a commodity pool. In connection with its management of the Fund, the Advisor has claimed such an exclusion from the definition of a commodity pool operator under the Commodity Exchange Act (“CEA”). Therefore, it is not subject to the registration and regulatory requirements of the CEA.
Successful use of futures also is subject to the Advisor’s ability to correctly predict movements in the relevant market. To the extent that a transaction is entered into for hedging purposes, successful use is also subject to the Advisor’s ability to evaluate the appropriate correlation between the transaction being hedged and the price movements of the futures contract.
The Fund may also purchase and sell stock index futures contracts. A stock index futures contract obligates the Fund to pay or receive an amount of cash equal to a fixed dollar amount specified in the futures contract, multiplied by the difference between the settlement price of the contract on the contract’s last trading day, and the value of the index based on the stock prices of the securities that comprise it at the opening of trading in those securities on the next business day. The Fund may purchase and sell interest rate futures contracts, which represent obligations to purchase or sell an amount of a specific debt security at a future date at a specific price.
Options on Securities Indexes. The Fund may purchase and sell call and put options on stock indexes listed on national securities exchanges or traded in the over-the-counter market for hedging or speculative purposes. A stock index fluctuates with changes in the market values of the stocks included in the index. Accordingly, successful use of options on stock indexes will be subject to the Advisor’s ability to correctly evaluate movements in the stock market generally, or of a particular industry or market segment. Uncovered call options expose the Fund to potentially unlimited liability. Uncovered put options expose the Fund to potential losses equal to the strike price of the put option less the premium received.
Swap Agreements. The Fund may enter into a variety of swap agreements, including equity, interest rate, and index swap agreements. The Fund is not limited to any particular form of swap agreement if the Advisor determines that other forms are consistent with the Fund’s investment objectives and policies. Swap agreements are contracts entered into by two parties (primarily institutional investors) for periods ranging from a few weeks to more than a year. In a standard swap transaction, the parties agree to exchange the returns (or differentials in rates of return) earned or realized on particular predetermined investments or instruments, which may be adjusted for an interest factor. The gross returns to be exchanged or “swapped” between the parties are generally calculated with respect to a “notional amount,” i.e., the return on or increase in value of a particular dollar amount invested at a particular interest rate, in a particular foreign currency, or in a “basket” of securities representing a particular index. Additional forms of swap agreements include (i) interest rate caps, under which, in return for a premium, one party agrees to make payments to the other to the extent interest rates exceed a specified rate or “cap;” (ii) interest rate floors, under which, in return for a premium, one party agrees to make payments to the other to the extent interest rates fall below a specified level or “floor;” and (iii) interest rate collars, under which a party sells a cap and purchases a floor (or vice versa) in an attempt to protect itself against interest rate movements exceeding certain minimum or maximum levels.
9
Generally, the Fund’s obligations (or rights) under a swap agreement will be equal only to the net amount to be paid or received under the agreement, based on the relative values of the positions held by the parties. The risk of loss is limited to the net amount of interest payments that a party is contractually required to make. As such, if the counterparty to a swap defaults, the Fund’s risk of loss consists of the net amount of payments that it is entitled to receive.
Non-Diversified Status
Because the Fund is “non-diversified” under the 1940 Act, it is subject only to certain federal tax diversification requirements. Under federal tax laws, the Fund may, with respect to 50% of its total assets, invest up to 25% of its total assets in the securities of any issuer. With respect to the remaining 50% of the Fund’s total assets, (i) the Fund may not invest more than 5% of its total assets in the securities of any one issuer, and (ii) the Fund may not acquire more than 10% of the outstanding voting securities of any one issuer. These tests apply at the end of each quarter of the taxable year and are subject to certain conditions and limitations under the Code. These tests do not apply to investments in United States Government Securities and regulated investment companies.
When-Issued, Delayed Delivery and Forward Commitment Securities
To reduce the risk of changes in securities prices and interest rates, the Fund may purchase securities on a forward commitment, when- issued or delayed delivery basis. This means that delivery and payment occur a number of days after the date of the commitment to purchase. The payment obligation and the interest rate receivable with respect to such purchases are determined when the Fund enters into the commitment, but the Fund does not make payment until it receives delivery from the counterparty. The Fund may, if it is deemed advisable, sell the securities after it commits to a purchase but before delivery and settlement takes place.
Securities purchased on a forward commitment, when-issued or delayed delivery basis are subject to changes in value based upon the public’s perception of the creditworthiness of the issuer and changes (either real or anticipated) in the level of interest rates. Purchasing securities on a when-issued or delayed delivery basis can present the risk that the yield available in the market when the delivery takes place may be higher than that obtained in the transaction itself. Purchasing securities on a forward commitment, when-issued or delayed delivery basis when the Fund is fully, or almost fully invested, results in a form of leverage and may cause greater fluctuation in the value of the net assets of the Fund. In addition, there is a risk that securities purchased on a when-issued or delayed delivery basis may not be delivered, and that the purchaser of securities sold by the Fund on a forward basis will not honor its purchase obligation. In such cases, the Fund may incur a loss.
10
REPURCHASES AND TRANSFERS OF SHARES
Repurchase Offers
The Board has adopted a resolution setting forth the Fund’s fundamental policy that it will conduct quarterly repurchase offers (the “Repurchase Offer Policy”). The Repurchase Offer Policy sets the interval between each repurchase offer at one quarter and provides that the Fund shall conduct a repurchase offer each quarter (unless suspended or postponed in accordance with regulatory requirements). The Repurchase Offer Policy also provides that the repurchase pricing shall occur not later than the 14th day after the Repurchase Request Deadline or the next business day if the 14th day is not a business day. The Fund’s Repurchase Offer Policy is fundamental and cannot be changed without shareholder approval. The Fund may, for the purpose of paying for repurchased shares, be required to liquidate portfolio holdings earlier than the Advisor would otherwise have liquidated these holdings. Such liquidations may result in losses, and may increase the Fund’s portfolio turnover.
Repurchase Offer Policy Summary of Terms
| 1. | The Fund will make repurchase offers at periodic intervals pursuant to Rule 23c-3 under the 1940 Act, as that rule may be amended from time to time. |
| 2. | The repurchase offers will generally be made quarterly. |
| 3. | The Fund must receive repurchase requests submitted by shareholders in response to the Fund’s repurchase offer on or before the date specified in the repurchase offer, which will be within 21 to 42 days of the date the repurchase offer is made (or the preceding business day if the New York Stock Exchange is closed on that day) (the “Repurchase Request Deadline”). |
| 4. | The maximum time between the Repurchase Request Deadline and the next date on which the Fund determines the net asset value applicable to the purchase of shares (the “Repurchase Pricing Date”) is 14 calendar days (or the next business day if the fourteenth day is not a business day). |
The Fund may not condition a repurchase offer upon the tender of any minimum amount of shares. The Fund may deduct from the repurchase proceeds an early withdrawal charge that is paid to the Fund and that is reasonably intended to compensate the Fund for expenses directly related to the repurchase. The early withdrawal charge may not exceed 2% of the proceeds. Generally, the Fund does not charge an early withdrawal charge. However, Class A shareholders who tender for repurchase Class A shares that were purchased in amounts of $1,000,000 or more and that have been held, less than one year (365 days) following such shareholder’s initial purchase will be subject to an early withdrawal charge of 1.00% of the original purchase price of the shares repurchased by the Fund. Additionally, Class C shareholders who tender for repurchase of Class C shares that have been held, less than one year (365 days) following such shareholder’s initial purchase, will be subject to an early withdrawal charge of 1.00% of the value of the original purchase price. The Fund’s distributor, ALPS Distributors, Inc. (the “Distributor”), may waive the imposition of the early withdrawal charge in the following shareholder situations: (1) shareholder death or (2) shareholder disability. Any such waiver does not imply that the early withdrawal charge will be waived at any time in the future or that such early withdrawal charge will be waived for any other shareholder. Class I, Class L and Class M shares are not subject to an early withdrawal charge.
11
Procedures: All periodic repurchase offers must comply with the following procedures:
Repurchase Offer Amount: Each quarter, the Fund may offer to repurchase at least 5% and no more than 25% of the Fund’s outstanding shares on the Repurchase Request Deadline (the “Repurchase Offer Amount”). The Board shall determine the quarterly Repurchase Offer Amount.
Shareholder Notification: At least 21 days before each Repurchase Request Deadline, the Fund shall send to each shareholder of record and to each beneficial owner of the shares that are the subject of the repurchase offer a notification (“Shareholder Notification”) providing the following information:
| 1. | A statement that the Fund is offering to repurchase its shares from shareholders at net asset value; | |
| 2. | Any fees applicable to such repurchase, if any; | |
| 3. | The Repurchase Offer Amount; | |
| 4. | The dates of the Repurchase Request Deadline, Repurchase Pricing Date, and the date by which the Fund must pay shareholders for any shares repurchased (which shall not be more than seven days after the Repurchase Pricing Date) (the “Repurchase Payment Deadline”); | |
| 5. | The risk of fluctuation in net asset value between the Repurchase Request Deadline and the Repurchase Pricing Date, and the possibility that the Fund may use an earlier Repurchase Pricing Date; | |
| 6. | The procedures for shareholders to request repurchase of their shares and the right of shareholders to withdraw or modify their repurchase requests until the Repurchase Request Deadline; | |
| 7. | The procedures under which the Fund may repurchase such shares on a pro rata basis if shareholders tender more than the Repurchase Offer Amount; | |
| 8. | The circumstances in which the Fund may suspend or postpone a repurchase offer; | |
| 9. | The net asset value of the shares computed no more than seven days before the date of the notification and the means by which shareholders may ascertain the net asset value thereafter; and | |
| 10. | The market price, if any, of the shares on the date on which such net asset value was computed, and the means by which shareholders may ascertain the market price thereafter. |
12
The Fund must file Form N-23c-3 (“Notification of Repurchase Offer”) and three copies of the Shareholder Notification with the SEC within three business days after sending the notification to shareholders.
Notification of Beneficial Owners: Where the Fund knows that shares subject of a repurchase offer are held of record by a broker, dealer, voting trustee, bank, association or other entity that exercises fiduciary powers in nominee name or otherwise, the Fund must follow the procedures for transmitting materials to beneficial owners of securities that are set forth in Rule 14a-13 under the Securities Exchange Act of 1934.
Repurchase Requests: Repurchase requests must be submitted by shareholders by the Repurchase Request Deadline. The Fund shall permit repurchase requests to be withdrawn or modified at any time until the Repurchase Request Deadline, but shall not permit repurchase requests to be withdrawn or modified after the Repurchase Request Deadline.
Repurchase Requests in Excess of the Repurchase Offer Amount: If shareholders tender more than the Repurchase Offer Amount, the Fund may, but is not required to, repurchase an additional amount of shares not to exceed 2% of the outstanding shares of the Fund on the Repurchase Request Deadline. If the Fund determines not to repurchase more than the Repurchase Offer Amount, or if shareholders tender shares in an amount exceeding the Repurchase Offer Amount plus 2% of the outstanding shares on the Repurchase Request Deadline, the Fund shall repurchase the shares tendered on a pro rata basis. This policy, however, does not prohibit the Fund from:
| 1. | Accepting all repurchase requests by persons who own, beneficially or of record, an aggregate of not more than 100 shares and who tender all of their stock for repurchase, before prorating shares tendered by others, or |
| 2. | Accepting by lot shares tendered by shareholders who request repurchase of all shares held by them and who, when tendering their shares, elect to have either (i) all or none or (ii) at least a minimum amount or none accepted, if the Fund first accepts all shares tendered by shareholders who do not make this election. |
Suspension or Postponement of Repurchase Offers: The Fund shall not suspend or postpone a repurchase offer except pursuant to a vote of a majority of the Board, including a majority of the Trustees who are not interested persons of the Fund, and only:
| 1. | If the repurchase would cause the Fund to lose its status as a regulated investment company under Subchapter M of the Internal Revenue Code; |
| 2. | If the repurchase would cause the shares that are the subject of the offer that are either listed on a national securities exchange or quoted in an inter-dealer quotation system of a national securities association to be neither listed on any national securities exchange nor quoted on any inter-dealer quotation system of a national securities association; |
13
| 3. | For any period during which the New York Stock Exchange or any other market in which the securities owned by the Fund are principally traded is closed, other than customary week-end and holiday closings, or during which trading in such market is restricted; |
| 4. | For any period during which an emergency exists as a result of which disposal by the Fund of securities owned by it is not reasonably practicable, or during which it is not reasonably practicable for the Fund fairly to determine the value of its net assets; or |
| 5. | For such other periods as the SEC may by order permit for the protection of shareholders of the Fund. |
If a repurchase offer is suspended or postponed, the Fund shall provide notice to shareholders of such suspension or postponement. If the Fund renews the repurchase offer, the Fund shall send a new Shareholder Notification to shareholders.
Computing Net Asset Value: The Fund’s current net asset value per share (“NAV”) shall be computed no less frequently than weekly, and daily on the five business days preceding a Repurchase Request Deadline, on such days and at such specific time or times during the day as set by the Board. Currently, the Board has determined that the Fund’s NAV shall be determined daily following the close of the New York Stock Exchange. The Fund’s NAV need not be calculated on:
| 1. | Days on which changes in the value of the Fund’s portfolio securities will not materially affect the current NAV of the shares; |
| 2. | Days during which no order to purchase shares is received, other than days when the NAV would otherwise be computed; or |
| 3. | Customary national, local, and regional business holidays described or listed in the Prospectuses. |
Liquidity Requirements: From the time the Fund sends a Shareholder Notification to shareholders until the Repurchase Pricing Date, a percentage of the Fund’s assets equal to at least 100% of the Repurchase Offer Amount (the “Liquidity Amount”) shall consist of assets that individually can be sold or disposed of in the ordinary course of business, at approximately the price at which the Fund has valued the investment, within a period equal to the period between a Repurchase Request Deadline and the Repurchase Payment Deadline, or of assets that mature by the next Repurchase Payment Deadline, and/or through access to a line of credit. This requirement means that individual assets must be salable under these circumstances. It does not require that the entire Liquidity Amount must be salable. In the event that the Fund’s assets fail to comply with this requirement, the Board shall cause the Fund to take such action as it deems appropriate to ensure compliance.
Liquidity Policy: The Board may delegate day-to-day responsibility for evaluating liquidity of specific assets to the Fund’s investment advisor, but shall continue to be responsible for monitoring the investment advisor’s performance of its duties and the composition of the portfolio. Accordingly, the Board has approved this policy that is reasonably designed to ensure that the Fund’s portfolio assets are sufficiently liquid so that the Fund can comply with its fundamental policy on repurchases and comply with the liquidity requirements in the preceding paragraph.
14
| 1. | In evaluating liquidity, the following factors are relevant, but not necessarily determinative: |
| a. | The frequency of trades and quotes for the security. |
| b. | The number of dealers willing to purchase or sell the security and the number of potential purchasers. |
| c. | Dealer undertakings to make a market in the security. |
| d. | The nature of the marketplace trades (e.g., the time needed to dispose of the security, the method of soliciting offer and the mechanics of transfer). |
| e. | The size of the Fund’s holdings of a given security in relation to the total amount of outstanding of such security or to the average trading volume for the security. |
| f. | The availability of the line of credit. |
| 2. | If market developments impair the liquidity of a security, the investment advisor should review the advisability of retaining the security in the portfolio. The investment advisor should report the basis for its determination to retain a security at the next Board meeting. |
| 3. | The Board shall review the overall composition and liquidity of the Fund’s portfolio on a quarterly basis. |
| 4. | These procedures may be modified as the Board deems necessary. |
Registration Statement Disclosure: The Fund’s registration statement must disclose its intention to make or consider making such repurchase offers.
Annual Report Disclosure: The Fund shall include in its annual report to shareholders the following:
| 1. | Disclosure of its fundamental policy regarding periodic repurchase offers. |
| 2. | Disclosure regarding repurchase offers by the Fund during the period covered by the annual report, which disclosure shall include: |
| a. | the number of repurchase offers, |
| b. | the repurchase offer amount and the amount tendered in each repurchase offer, |
| c. | and the extent to which in any repurchase offer the Fund repurchased stock pursuant to the procedures in this section. |
15
Advertising: The Fund, or any underwriter for the Fund, must comply, as if the Fund were an open-end investment company, with the provisions of Section 24(b) of the 1940 Act and the rules thereunder and file, if necessary, with FINRA or the SEC any advertisement, pamphlet, circular, form letter, or other sales literature addressed to or intended for distribution to prospective investors.
Involuntary Repurchases
The Fund may, in accordance with Section 23 of the 1940 Act, and any applicable rules thereunder, at any time, repurchase, at net asset value, shares held by a shareholder, or any person acquiring shares from or through a shareholder, without shareholder consent if: the shares have been transferred to or have vested in any other person other than by operation of law as the result of the death, dissolution, bankruptcy or incompetency of a shareholder; ownership of the shares by the shareholder or other person will cause the Fund to be in violation of, or require registration of the shares, or subject the Fund to additional registration or regulation under, the securities, commodities or other laws of the United States or any other relevant jurisdiction; continued ownership of the shares may be harmful or injurious to the business or reputation of the Fund or may subject the Fund or any shareholders to an undue risk of adverse tax or other fiscal consequences; the shareholder owns shares having an aggregate net asset value less than an amount determined from time to time by the Trustees; or it would be in the interests of the Fund, as determined by the Board, for the Fund to repurchase the Shares.
Transfers of Shares
No person may become a substituted shareholder without the written consent of the Board, which consent may be withheld for any reason in the Board’s sole and absolute discretion. Shares may be transferred only (i) by operation of law pursuant to the death, bankruptcy, insolvency or dissolution of a shareholder or (ii) with the written consent of the Board, which may be withheld in its sole and absolute discretion. The Board may, in its discretion, delegate to the Advisor its authority to consent to transfers of shares. Each shareholder and transferee is required to pay all expenses, including attorneys and accountants fees, incurred by the Fund in connection with such transfer.
Other Information About Determination of NAV
The Fund may hold investments, such as private placements or other non-traded securities or temporarily illiquid securities, for which market quotations are not readily available or are determined to be unreliable. These investments will be valued at their fair market value as determined in good faith by the Advisor, in its capacity as the Board’s valuation designee, pursuant to Rule 2a-5 under the 1940 Act. As the valuation designee, the Advisor executes the Fund’s valuation policies and acts under the Board’s oversight. The Board and the Advisor may enlist third party service providers, such as a fair value team composed of one of more representatives from the Advisor and the Fund. Representatives from the Administrator participate in each meeting of the fair value committee in an advisory capacity. The Advisor may also enlist the Sub-Advisors (defined below) or third-party consultants (such as an audit firm or financial officer of a security issuer) on an as-needed basis to assist in determining a security-specific fair value. The Board reviews the execution of this process and the resultant fair value prices quarterly to assure the process produces reliable results.
16
Valuation Designee and Valuation Process.
The Fund’s investments are valued collectively via inputs from each group supporting the Advisor. For example, fair value determinations are required for the following investments: (i) investments for which market quotations are insufficient or not readily available on a particular business day (including securities for which there is a short and temporary lapse in the provision of a price by the regular pricing source), (ii) investments for which, in the judgment of the Advisor, the prices or values available do not represent the fair value of the instrument. Factors which may cause the Advisor or to make such a judgment include, but are not limited to, the following: only a bid price or an asked price is available; the spread between bid and asked prices is substantial; the frequency of sales; the thinness of the market; the size of reported trades; and actions of the securities markets, such as the suspension or limitation of trading; (iii) investments determined to be illiquid; and (iv) investments with respect to which an event that will affect the value thereof has occurred (a “significant event”) since the closing prices were established on the principal exchange on which they are traded, but prior to the Fund’s calculation of its net asset value.
Standards for Fair Value Determinations.
As a general principle, the fair value of an investment is the amount that the Fund might reasonably expect to realize upon its current sale. The Fund has adopted Financial Accounting Standards Board Statement of Financial Accounting Standards Codification Topic 820, Fair Value Measurements and Disclosures (“ASC 820”). In accordance with ASC 820, fair value is defined as the price that the Fund would receive upon selling an investment in a timely transaction to an independent buyer in the principal or most advantageous market of the investment. ASC 820 establishes a three-tier hierarchy to maximize the use of observable market data and minimize the use of unobservable inputs and to establish classification of fair value measurements for disclosure purposes. Inputs refer broadly to the assumptions that market participants would use in pricing the asset or liability, including assumptions about risk, for example, the risk inherent in a particular valuation technique used to measure fair value including such a pricing model and/or the risk inherent in the inputs to the valuation technique. Inputs may be observable or unobservable. Observable inputs are inputs that reflect the assumptions market participants would use in pricing the asset or liability developed based on market data obtained from sources independent of the reporting entity. Unobservable inputs are inputs that reflect the reporting entity’s own assumptions about the assumptions market participants would use in pricing the asset or liability, developed based on the best information available under the circumstances.
Various inputs are used in determining the value of the Fund’s investments relating to ASC 820. These inputs are summarized in the three broad levels listed below.
Level 1 - quoted prices in active markets for identical securities.
17
Level 2 - other significant observable inputs (including quoted prices for similar securities, interest rates, prepayment speeds, credit risk, etc.)
Level 3 - significant unobservable inputs (including the Fund’s own assumptions in determining the fair value of investments)
The Advisor as valuation designee takes into account relevant factors and surrounding circumstances, which may include: (i) the nature and pricing history (if any) of the investment; (ii) whether any dealer quotations for the investment are available; (iii) possible valuation methodologies that could be used to determine the fair value of the investment; (iv) the recommendation of Portfolio Manager of the Fund with respect to the valuation of the investment; (v) whether the same or similar investments are held by other funds managed by the Advisor (or a Sub-Advisor) or other funds and the method used to price the investment in those funds; (vi) the extent to which the fair value to be determined for the investment will result from the use of data or formulae produced by independent third parties and (vii) the liquidity or illiquidity of the market for the investment.
Board Oversight. The Board meets at least quarterly to consider the valuations provided by the Advisor.
MANAGEMENT OF THE FUND
The Board has overall responsibility to manage and control the business affairs of the Fund, including the complete and exclusive authority to oversee and to establish policies regarding the management, conduct and operation of the Fund’s business. The Board exercises the same powers, authority and responsibilities on behalf of the Fund as are customarily exercised by the board of directors of a registered investment company organized as a corporation. The business of the Trust is managed under the direction of the Board in accordance with the Agreement and Declaration of Trust and the Trust’s By-laws (the “Governing Documents”), each as amended from time to time, which have been filed with the Securities and Exchange Commission and are available upon request. The Board consists of five individuals, three of whom are not “interested persons” (as defined under the 1940 Act) of the Trust, the Advisor, any Sub-Advisor or the Distributor (“Independent Trustees”). Pursuant to the Governing Documents of the Trust, the Trustees shall elect officers including a President, a Secretary, a Treasurer, a Principal Executive Officer and a Principal Financial Officer. The Board retains the power to conduct, operate and carry on the business of the Trust and has the power to incur and pay any expenses, which, in the opinion of the Board, are necessary or incidental to carry out any of the Trust’s purposes. The Trustees, officers, employees and agents of the Trust, when acting in such capacities, shall not be subject to any personal liability except for his or her own bad faith, willful misfeasance, gross negligence or reckless disregard of his or her duties.
Board Leadership Structure
The Trust is led by Mr. Ramin Kamfar, who has served as the Chairman of the Board since the Trust was organized in 2012. Additionally, under certain 1940 Act governance guidelines that apply to the Trust, the Independent Trustees will meet in executive session, at least quarterly. Under the Trust’s Agreement and Declaration of Trust and By-Laws, the Chairman of the Board is responsible for (a) presiding at board meetings, (b) calling special meetings on an as-needed basis, (c) execution and administration of Trust policies including (i) setting the agendas for board meetings and (ii) providing information to board members in advance of each board meeting and between board meetings. The Trust believes that its Chairman, the chair of the Audit Committee, and, as an entity, the full Board, provide effective leadership that is in the best interests of the Trust and each shareholder.
18
Board Risk Oversight
The Board is comprised of five trustees, three of whom are Independent Trustees, with a standing independent Audit Committee with a separate chair, and a standing independent Nominating and Governance Committee. The Board is responsible for overseeing risk management, and the full Board regularly engages in discussions of risk management and receives compliance reports that inform its oversight of risk management from the Fund’s Chief Compliance Officer at quarterly meetings and on an ad hoc basis, when and if necessary. The Audit Committee considers financial and reporting risk within its area of responsibilities. The Nominating and Governance Committee considers and evaluates the structure, composition and operation of the Board, including any committees, evaluates and recommend individuals to serve on the Board, and considers and makes recommendations relating to the compensation of the Independent Trustees. Generally, the Board believes that its oversight of material risks is adequately maintained through the compliance-reporting chain where the Chief Compliance Officer is the primary recipient and communicator of such risk-related information.
Trustee Qualifications
Generally, the Trust believes that each Trustee is competent to serve because of their individual overall merits including: (i) experience, (ii) qualifications, (iii) attributes and (iv) skills.
Mr. Kamfar has over 30 years of experience in various aspects of real estate, mergers and acquisitions, private equity investing, investment banking, public and private financings, and retail operations, and possesses deep institutional knowledge and industry expertise. He also possesses deep corporate finance and operational experience from both the perspective of an investment banker and of an executive. Mr. Kamfar received an M.B.A. degree with distinction in Finance in 1988 from The Wharton School of the University of Pennsylvania and a B.S. degree with distinction in Finance in 1985 from the University of Maryland, College Park.
Mr. Majumder is a partner at the law firm of Frost Brown Todd, LLP where he focuses his practice on corporate and securities transactions primarily in the energy (oil & gas, coal, and renewables), mining, health care, and information technology industry verticals. He represents underwriters, placement agents, and issuers in both public and private offerings of securities; public and privately-held companies in both cross-border and domestic mergers and acquisitions (M&A); private equity funds, hedge funds, and venture capital funds in connection with their formation as well as their investments; and companies receiving private equity and venture capital financing. Prior to Frost Brown Todd, Mr. Majumder was a partner at the law firm of Reed Smith, where he serves as the co-office managing partner of the firm’s Dallas office and firm wide co-head of the firm’s India practice. Prior to Reed Smith, Mr. Majumder was a partner at the law firm of Perkins Coie until May 2019, where he served as the Managing Partner of the firm’s Dallas office and firmwide Co-Chair of its India practice. Mr. Majumder specializes in corporate and securities transactions with an emphasis on the representation of underwriters, placement agents and issuers in both public and private offerings, private investment in public equity (PIPE) transactions and venture capital and private equity funds. Prior to Perkins Coie, Mr. Majumder was a partner in the law firm of K&L Gates LLP from May 2005 to March 2013. From January 2000 to April 2005, Mr. Majumder was a partner at the firm of Gardere Wynne Sewell LLP. Through his law practice, Mr. Majumder has gained significant experience relating to the acquisition of a number of types of real property assets including raw land, improved real estate and oil and gas interests. Mr. Majumder is NACD Directorship Certified®. He is an active member of the Park Cities Rotary Club, a charter member of the Dallas Chapter of The Indus Entrepreneurs and an Associates Board member of the Cox School of Business at Southern Methodist University. Mr. Majumder received a J.D. degree in 1993 from Washington and Lee University School of Law, and a B.A. degree in 1990 from Trinity University.
19
Mr. Tio is a Senior Managing Director for the commercial finance team at Greystone, where he specializes in real estate lending and investment advisory services. Prior to Greystone, Mr. Tio was a Senior Managing Director for Ackman-Ziff Real Estate Capital Advisors, where he was an advisor and principal in many commercial, residential, and hospitality deals on the East Coast. Mr. Tio’s experience as a managing director for commercial real estate-related departments of several investment firms has given him strong understanding of the commercial real estate and distressed real estate markets. Prior to serving in these executive positions, Mr. Tio was involved in real estate investment, financing, sales and brokerage for 25 years. Mr. Tio received a B.S. degree in Biochemistry in 1982 from Hofstra University.
Mr. Adamiyatt has served as Treasurer and Principal Financial Officer of the Fund since 2018 and as Trustee since 2019. Mr. Adamiyatt serves as an Executive Director, Chief Financial Officer and Chief Strategy Officer of Bluerock, where he oversees the finance and control functions as well as directing strategy and business development for the firm’s asset management platform. Mr. Adamiyatt joined Bluerock in 2018 after a career spanning 30 years as a financial services executive, serving as both a Senior Investment Banker and a Chief Financial Officer of a publicly traded company. Prior to joining Bluerock, Mr. Adamiyatt was an Executive Director and Chief Financial Officer of Earthport Plc, a financial technology company listed on the London Stock Exchange. During his investment banking career, Mr. Adamiyatt held senior leadership and management positions at several global investment banks, serving as Head of Financial Institutions Group at UBS Americas and Bear Stearns as well as Co-Head of Financial Institutions M&A at Lehman Brothers. He was a member of the investment banking operating, business review and fairness opinion committees during his tenure as an Investment Banker. Mr. Adamiyatt was educated at the Wharton School of the University of Pennsylvania, Columbia University, and Oxford University.
Mr. Jafarnia currently serves as Chief Legal Officer and General Counsel for Vise. Prior to Vise, Mr. Jafarnia served as General Counsel and Co-Founder for Opto Investments, Inc. from January 2021 until December 2024. Prior to Opto, Mr. Jafarnia served as General Counsel and Chief Compliance Officer at Artivest Holdings, Inc. from 2018 until 2021, and as Chief Compliance Officer for the Altegris KKR Commitments Fund. Prior to Artivest, Mr. Jafarnia served as Managing Director for Legal and Business Development at Provasi Capital Partners LP. Prior to that, from October 2014 to December 2017, he served as Senior Vice President of W.P. Carey Inc. (NYSE: WPC), as well as Senior Vice President and Chief Compliance Officer of Carey Credit Advisors, Inc. and as Chief Compliance Officer and General Counsel of Carey Financial, LLC. Prior to joining W. P. Carey Inc., Mr. Jafarnia served as Counsel to two American Lawyer Global100 law firms in New York. From March 2014 to October 2014, Mr. Jafarnia served as Counsel in the REIT practice group at the law firm of Greenberg Traurig, LLP. From August 2012 to March 2014, Mr. Jafarnia served as Counsel in the Financial Services & Products Group and was a member of the REIT practice group of Alston & Bird, LLP. Between 2004 and 2012, Mr. Jafarnia served as a senior executive, in-house counsel, and Chief Compliance Officer for several alternative investment program sponsors, including, among others, American Realty Capital, a real estate investment program sponsor, and its affiliated broker-dealer, Realty Capital Securities, LLC. In addition, Mr. Jafarnia has served as a non-executive independent member of the board of directors for two publicly traded companies: 1) Ashford Hospitality Trust, Inc. (NYSE: AHT) since January 2013; and 2) Bluerock Residential Growth REIT, Inc. (NYSE American: BRG) since June 2019. Mr. Jafarnia received an LL.M. in Securities and Financial Regulation in 2011 from Georgetown University Law Center, a J.D. degree in 1992 from Temple University, and a B.A. degree in Economics and Government in 1988 from the University of Texas at Austin.
20
Following is a list of the Trustees and executive officers of the Trust and their principal occupations over the last five years. Unless otherwise noted, the address of each Trustee and Officer is c/o ALPS Fund Services, Inc., 1290 Broadway, Suite 1000, Denver, CO 80203.
Independent Trustees
Name, Year of Birth |
Position/Term of Office* |
Principal Occupation During the Past Five Years |
Number of Portfolios in Fund Complex** Overseen by Trustee |
Other Directorships held by Trustee During Last Five Years |
I. Bobby Majumder, 1968 |
Trustee Since 2012 |
Partner, Frost Brown Todd, LLP (September 2021 – Present); Partner, Reed Smith (May 2019 – August 2021); Partner, Perkins Coie LLP (2013 – May 2019). | 2 | Bluerock Residential Growth REIT, Inc. (2009 – 2022); Bluerock High Income Institutional Credit Fund (2022 – Present); Bluerock Homes Trust, Inc. (2021 – Present). |
Romano Tio, 1960 |
Trustee Since 2012 |
Senior Managing Director, Greystone (real estate lending, investment and advisory company) (2021 – Present); Senior Managing Director, Ackman-Ziff Real Estate Capital Advisors (2017 – 2021). | 2 | Bluerock Residential Growth REIT, Inc. (2009 – 2022); Bluerock High Income Institutional Credit Fund (2022 – Present); Bluerock Homes Trust, Inc. (2021 – Present). |
Kamal Jafarnia, 1966 |
Trustee Since 2021 |
Chief Legal Officer and General Counsel for Vise (2025 – Present); General Counsel for Opto Investments, Inc. (fintech and investment management firm) (2021 – 2024); General Counsel and CCO for Artivest Holdings and Altegris Investment Management (fintech enablement platform) (2018 – 2021). | 2 | Ashford Hospitality Trust, Inc. (2013– Present); Bluerock Residential Growth REIT, Inc. (2019 – 2022); Bluerock High Income Institutional Credit Fund (2022 – Present); Bluerock Homes Trust, Inc. (2021 – Present). |
21
Interested Trustees and Officers
Name, Year of Birth |
Position/Term of Office* |
Principal Occupation During the Past Five Years |
Number of Portfolios in Fund Complex** Overseen by Trustee |
Other Directorships held by Trustee During Last 5 Years |
Ramin Kamfar, 1963 |
Trustee Since 2012 |
Chairman, Bluerock Real Estate, LLC (2002 – Present); Chairman, Bluerock Fund Advisor, LLC (2012 – Present); and Bluerock Asset Management, LLC (2018 – Present). | 2 | Bluerock Residential Growth REIT (2008 – 2022); Bluerock High Income Institutional Credit Fund (2021 – Present); Bluerock Homes Trust, Inc. (2021 – Present). |
| Simon Adamiyatt, 1962 |
Trustee Since 2019
Treasurer/ Chief Financial Officer Since 2018 |
Executive Director, Bluerock Real Estate, LLC (2018 – Present). | 1 | n/a |
| Jordan Ruddy, 1963 |
President Since 2013 |
Chief Operating Officer, Bluerock Real Estate, LLC (2002 – Present); President, Bluerock Fund Advisor, LLC (2013 – Present); President, Bluerock Asset Management, LLC (2020 – Present); Director, Bluerock Asset Management, LLC (2018 – 2020). | n/a | n/a |
| Jason Emala, 1978 |
Secretary Since 2018 |
General Counsel/Chief Legal Officer/Chief Compliance Officer of the Advisor and various Bluerock entities (2018 – Present). | n/a | n/a |
Lucas Foss, 1977 |
Chief Compliance Officer Since 2022 |
Vice President and Deputy Chief Compliance Officer,ALPS (November 2017- present); CCO of X- SquareBalanced Fund, Goehring & Rozencwajg InvestmentFunds, Broadstone Real Estate Access Fund, Inc.,Clough Global Funds; Clough Funds Trust; SPDR® S&P500® ETF Trust, SPDR® Dow Jones® Industrial AverageETF Trust, SPDR® S&P MIDCAP 400® ETF Trust, ALPSSeries Trust, 1WS Credit Income Fund and BluerockTotal Income + Real Estate Fund. | n/a | n/a |
| * | The term of office for each Trustee and officer listed above will continue indefinitely. |
| ** | The Fund Complex currently includes the Trust and Bluerock High Income Institutional Credit Fund. |
22
Board Committees
Audit Committee
The Board has an Audit Committee that consists of each Trustee that is not an “interested person” of the Trust within the meaning of the 1940 Act. The Audit Committee’s responsibilities include: (i) recommending to the Board the selection, retention or termination of the Trust’s independent auditors; (ii) reviewing with the independent auditors the scope, performance and anticipated cost of their audit; (iii) discussing with the independent auditors certain matters relating to the Trust’s financial statements, including any adjustment to such financial statements recommended by such independent auditors, or any other results of any audit; (iv) reviewing on a periodic basis a formal written statement from the independent auditors with respect to their independence, discussing with the independent auditors any relationships or services disclosed in the statement that may impact the objectivity and independence of the Trust’s independent auditors and recommending that the Board take appropriate action in response thereto to satisfy itself of the auditor’s independence; and (v) considering the comments of the independent auditors and management’s responses thereto with respect to the quality and adequacy of the Trust’s accounting and financial reporting policies and practices and internal controls. The Audit Committee operates pursuant to an Audit Committee Charter. During the fiscal year ended September 30, 2024, the Audit Committee held four meetings.
Nominating and Governance Committee
The Board has a Nominating and Governance Committee that consists of each Trustee that is not an “interested person” of the Trust within the meaning of the 1940 Act. The Nominating and Governance Committee’s responsibilities include: (i) nominating individuals to serve as both Independent Trustees and interested Trustees; (ii) establishing and maintaining guidelines for selecting candidates for election to the Board; (iii) reviewing periodically the size and composition of the Board as a whole; (iv) evaluating annually the operations of the Board and its committees and assisting the Board in conducting its annual self-evaluation; (v) reviewing, as necessary, the responsibilities of any committees of the Board; (vi) reviewing Trustee compensation annually; and (vii) reviewing periodically the Board’s, and all Board committee’s corporate Governance policies and practices and recommends, as it deems appropriate, any changes to the Board. The Nominating and Governance Committee operates pursuant to a Nominating and Governance Committee Charter. During the fiscal year ended September 30, 2024, the Nominating and Governance Committee did not meet.
23
Trustee Ownership
The following table indicates the dollar range of equity securities that each Trustee beneficially owned in the Fund as of December 31, 2024.
| Name of Trustee | Dollar Range of Equity Securities in the Fund |
Aggregate
Dollar Range of Equity Securities in All Registered Investment Companies Overseen by Trustee in Family of Investment Companies* |
| I. Bobby Majumder | $50,001–$100,000 | $50,001–$100,000 |
| Ramin Kamfar^ | Over $100,000 | Over $100,000 |
| Romano Tio | $50,001–$100,000 | $50,001–$100,000 |
| Kamal Jafarnia | $50,001–$100,000 | $50,001–$100,000 |
| Simon Adamiyatt | $10,001 -$50,000 | $10,001 -$50,000 |
| * | The “family of investment companies” includes the Fund and Bluerock High Income Institutional Credit Fund. |
| ^ | Includes Mr. Kamfar’s interests through ownership of Bluerock Asset Management. |
Compensation
Each Trustee who is not affiliated with the Trust or the Advisor receives an annual fee of $60,000, paid quarterly, of which $40,000 is paid in cash and the remaining $20,000 is paid in the equivalent amount of the Fund shares, as well as reimbursement for any reasonable expenses incurred attending the meetings. None of the executive officers receive compensation from the Trust.
The table below details the amount of compensation the Trustees earned during the Fund’s fiscal year ended September 30, 2024. The Trust does not have a bonus, profit sharing, pension or retirement plan.
| Name and Position | Aggregate Compensation From Fund |
Pension or Retirement Benefits Accrued as Part of Fund Expenses |
Estimated Annual Benefits Upon Retirement |
Total Compensation to Directors |
| Interested Trustees | ||||
| Simon Adamiyatt* | $0 | None | None | $0 |
| Ramin Kamfar* | $0 | None | None | $0 |
| Independent Trustees | ||||
| I. Bobby Majumder | $60,000 | None | None | $60,000 |
| Romano Tio | $60,000 | None | None | $60,000 |
| Kamal Jafarnia | $60,000 | None | None | $60,000 |
| * | Mr. Kamfar and Mr. Adamiyatt are interested and do not receive compensation from the trust as a trustee. |
24
CODES OF ETHICS
Each of the Fund, the Advisor, the Sub-Advisors, and the Distributor has adopted a code of ethics under Rule 17j-1 of the 1940 Act (collectively the “Ethics Codes”). Rule 17j-1 and the Ethics Codes are designed to prevent unlawful practices in connection with the purchase or sale of securities by covered personnel (“Access Persons”). The Ethics Codes permit Access Persons, subject to certain restrictions, to invest in securities, including securities that may be purchased or held by the Fund. Under the Ethics Codes, Access Persons may engage in personal securities transactions, but are required to report their personal securities transactions for monitoring purposes. In addition, certain Access Persons are required to obtain approval before investing in initial public offerings or private placements. The Codes of Ethics can be reviewed and copies at the SEC’s Public Reference Room in Washington, D.C. Information on the operation of the Public Reference Room may be obtained by calling the SEC at 1-202-551-8090. The codes are available on the EDGAR database on the SEC’s website at www.sec.gov, and also may be obtained, after paying a duplicating fee, by electronic request at the following e-mail address: [email protected], or by writing the SEC’s Public Reference Section, Washington, D.C. 20549.
PROXY VOTING POLICIES AND PROCEDURES
The Board has adopted Proxy Voting Policies and Procedures (“Policies”) on behalf of the Trust, which delegate the responsibility for voting proxies to the Advisor, subject to the Board’s continuing oversight. The Policies require that the Advisor vote proxies received in a manner consistent with the best interests of the Fund and shareholders. The Policies also require the Advisor to present to the Board, at least annually, the Advisor’s Proxy Policies and a record of each proxy voted by the Advisor on behalf of the Fund, including a report on the resolution of all proxies identified by the Advisor involving a conflict of interest. The Advisor has delegated certain proxy voting responsibilities to RREEF for the portfolio securities that it manages; provided that to the extent RREEF’s proxy voting policy is inconsistent with the proxy voting guidelines set forth in the Advisor’s proxy voting policies and procedures, the Advisor’s proxy voting guidelines will control.
Where a proxy proposal raises a material conflict between the interests of the Advisor or RREEF any affiliated person(s) of the Advisor/RREEF, the Distributor or any affiliated person of the Distributor, or any affiliated person of the Trust and the Fund’s or its shareholder’s interests, the Advisor/RREEF (as applicable) will resolve the conflict by voting in accordance with the policy guidelines or at the Trust’s directive using the recommendation of an independent third party. If the third party’s recommendations are not received in a timely fashion, the Advisor will abstain from voting. A copy of the Advisor’s proxy voting policies is attached hereto as Appendix A and a copy of the proxy voting policy utilized by RREEF is attached hereto as Appendix B.
Information regarding how the Fund voted proxies relating to portfolio securities held by the Fund during the most recent 12-month period ending June 30 is available (1) without charge, upon request, by calling the Fund toll-free at 1-844-819-8287; and (2) on the U.S. Securities and Exchange Commission’s website at http://www.sec.gov. In addition, a copy of the Fund’s proxy voting policies and procedures are also available by calling toll-free at 1-844-819-8287 and will be sent within three business days of receipt of a request.
25
CONTROL PERSONS AND PRINCIPAL HOLDERS
A principal shareholder is any person who owns (either of record or beneficially) 5% or more of the outstanding shares of a fund. A control person is one who owns, either directly or indirectly, more than 25% of the voting securities of a company or acknowledges the existence of control. The Fund’s principal shareholders as of January 3, 2025 are listed in the chart below. Each shareholder listed below is a record shareholder, holding shares for the benefit of others.
| Class A Shares | ||
| Name and Address | Shares Owned | Percentage of Class |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
6,523,152.52 | 26.75% |
EQUITABLE ADVISORS LLC LPL FINANCIAL SERVICES FBO LPL BIN 66920980 1055 LPL WAY FORT MILL SC, 29715-8101 |
4,721,545.33 | 19.36% |
CHARLES SCHWAB & CO INC SPECIAL CUSTODY A/C FBO CUSTOMERS 211 MAIN STREET SAN FRANCISCO, CA 94105-1905 |
3,107,371.03 | 12.74% |
NATIONAL FINANCIAL SERVICES LLC BIN #B9F699887 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
3,082,068.56 | 12.64% |
| Class C Shares | ||
| Name and Address | Shares Owned | Percentage of Class |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
5,923,943.31 | 38.47% |
LPL FINANCIAL LLC FBO CUSTOMER ACCOUNTS 4707 EXECUTIVE DR. SAN DIEGO CA, 92121-3091 |
2,299,101.93 | 14.93% |
CHARLES SCHWAB AND CO INC SPECIAL CUSTODY A/C FBO CUSTOMERS 211 MAIN STREET SAN FRANCISCO, CA 94105-1905 |
2,076,778.96 | 13.49% |
NATIONAL FINANCIAL SERVICES LLC 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
895,604.35 | 5.82% |
26
| Class I Shares | ||
| Name and Address | Shares Owned | Percentage of Class |
CHARLES SCHWAB & CO INC SPECIAL CUSTODY A/C FBO CUSTOMERS 211 MAIN STREET SAN FRANCISCO, CA 92121 |
42,258,021.47 | 36.65% |
NATIONAL FINANCIAL SERVICES LLC 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
21,116,400.89 | 18.31% |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
21,101,606.20 | 18.30% |
LPL FINANCIAL SERVICES FBO LPL BIN 66920980 1055 LPL WAY FORT MILL SC 29715-8101 |
14,367,372.68 | 12.46% |
ROBERT W BAIRD & CO. INC. A/C 47100819 777 EAST WISCONSIN AVENUE MILWAUKEE, WI 53202 |
6,642,155.04 | 5.76% |
| Class L Shares | ||
| Name and Address | Shares Owned | Percentage of Class |
PERSHING LLC PO BOX 2052 JERSEY CITY, NJ 07303-2052 |
1,652,278.67 | 53.11% |
NATIONAL FINANCIAL SERVICES LLC 499 WASHINGTON BLVD JERSEY CITY, NJ 07310-1995 |
535,807.56 | 17.22% |
LPL FINANCIAL LLC FBO CUSTOMER ACCOUNTS 4707 EXECUTIVE DR. SAN DIEGO CA, 92121-3091 |
247,909.67 | 7.97% |
27
| Class M Shares | ||
| Name and Address | Shares Owned | Percentage of Class |
MORGAN STANLEY SMITH BARNEY LLC 1 NEW YORK PLAZA NEW YORK, NY 10004 |
4,313,743.14 | 98.46% |
As of January 3, 2025, the Trustees and officers, as a group, owned less than 1.00% of the shares of the Fund
INVESTMENT ADVISORY AND OTHER SERVICES
The Advisor
Bluerock Fund Advisor, LLC, located at 919 Third Avenue, 40th Floor, New York, NY 10022, serves as the Fund’s investment advisor. The Advisor is registered with the SEC as an investment advisor under the Investment Advisers Act of 1940, as amended (“Advisers Act”). The Advisor is a Delaware limited liability company formed in May 2012. The Advisor is controlled by Ramin Kamfar through his ownership of the Manager of Advisor. Mr. Kamfar also serves as a Trustee of the Trust.
Under the general supervision of the Board, the Advisor will carry out the investment and reinvestment of the net assets of the Fund, will furnish continuously an investment program with respect to the Fund, and will determine which securities should be purchased, sold or exchanged. In addition, the Advisor will supervise and provide oversight of the Fund’s service providers. The Advisor will furnish to the Fund office facilities, equipment and personnel for servicing the management of the Fund. The Advisor will compensate all Advisor personnel who provide services to the Fund. In return for these services, facilities and payments, the Fund has agreed to pay the Advisor as compensation under the Investment Management Agreement a monthly management fee computed at the annual rate of 1.50% of the Fund’s daily net assets. The Advisor may employ research services and service providers to assist in the Advisor’s market analysis and investment selection. For the fiscal year ended September 30, 2022, the Advisor earned $77,004,479 in advisory fees, of which $0 were waived and $501,484 of previously waived fees were recouped. For the fiscal year ended September 30, 2023, the Advisor earned $99,210,524 in advisory fees, of which $4,183 were waived and $0 of previously waived fees were recouped. For the fiscal year ended September 30, 2024, the Advisor earned $76,437,679 in advisory fees, of which $471,392 were waived and $0 of previously waived fees were recouped.
The Advisor and the Fund have entered into an expense limitation and reimbursement agreement (the “Expense Limitation Agreement”) under which the Advisor has agreed contractually to waive its fees and to pay or absorb the ordinary operating expenses of the Fund to the extent that such expenses exceed 1.95%, 2.70%, 1.70%, 2.20%, and 2.45% per annum (excluding any taxes, interest, brokerage commissions, acquired fund fees and expenses, and extraordinary expenses, such as litigation or reorganization costs, but including organizational costs and offering costs) of the Fund’s average daily net assets attributable to Class A, Class C, Class I, Class L and Class M shares, respectively (the “Expense Limitation”). In consideration of the Advisor’s agreement to limit the Fund’s expenses, the Fund has agreed to repay the Advisor in the amount of any fees the Advisor previously waived and or Fund expenses reimbursed, subject to the limitations that: (1) the reimbursement will be made if payable not more than three years from the date incurred; (2) the reimbursement may not be made if it would cause the Expense Limitation then in effect or in effect at the time of the waiver to be exceeded; and (3) the reimbursement is approved by the Board. The Expense Limitation Agreement will remain in effect, at least until January 31, 2026, unless and until the Board approves its modification or termination. This agreement may be terminated only by the Board on 60 days’ written notice to the Advisor. After January 31, 2026, the Expense Limitation Agreement may be renewed at the Advisor’s and Board’s discretion.
28
Sub-Advisor – Mercer
The Advisor has entered into a Sub-Advisory Agreement with Mercer Investments, LLC (“Mercer” and together with RREEF, the “Sub-Advisors”), 99 High Street, Boston, MA 02110, a registered advisor under the Advisers Act, to provide both ongoing research and opinions of institutional asset managers and their investment funds to the Advisor on behalf of the Fund as well as recommendations for the selection of investment funds to the Advisor. Under the terms of the Sub-Advisory Agreement, Mercer receives fees from the Advisor (not the Fund) as follows: 0.025% of the Fund’s assets invested in publicly traded real estate securities, and 0.15% for up to $250 million in total Fund assets, 0.13% for $250 million to $500 million in total Fund assets, 0.12% for $500 million to $750 million in total Fund assets, 0.10% for $750 million to $1 billion in total Fund assets, 0.08% for $1 billion to $1.3 billion in total Fund assets, 0.07% for $1.3 billion to $1.5 billion in total Fund assets, 0.06% for $1.5 billion to $2 billion in total Fund assets, 0.05% for $2 billion to $2.5 billion in total Fund assets, 0.045% for $2.5 billion to $3 billion in total Fund assets, 0.04% for $3 billion to $3.5 billion in total Fund assets, 0.035% for $3.5 billion to $4 billion in total Fund assets, 0.03% for $4 billion to $4.5 billion in total Fund assets, 0.025% for $4.5 billion to $5 billion in total Fund assets, 0.02% for $5 billion to $5.5 billion in total Fund assets, 0.015% for $5.5 billion to $6 billion in total Fund assets, 0.010% for $6 billion or more in total Fund assets invested in private real estate assets.
Sub-Advisor – RREEF
The Advisor has entered into a First Amended and Restated Sub-Advisory Agreement with RREEF, 222 S. Riverside Plaza, Floor 26, Chicago, IL 60606, a registered adviser under the Advisers Act, to provide investment management for a portion, generally less than 20%, of the Fund’s portfolio. In addition, RREEF provides the Adviser with research and information that the Advisor uses to make investment decisions with respect to non-publicly traded real estate related debt securities. Under the terms of the First Amended and Restated Sub-Advisory Agreement, RREEF receives fees from the Advisor (not the Fund). For the portion of the Fund invested in liquid real assets, sub-advisory fees are calculated at an annual rate of 0.60% for up to $50 million in assets allocated to RREEF, 0.55% for $50 million to $100 million in assets allocated to RREEF, and 0.50% for greater than $100 million in assets allocated to RREEF. For the portion of the Fund which is invested in non-publicly traded real estate related debt securities, sub-advisory fees are calculated at an annual rate of 0.75% for up to $350 million in assets allocated to RREEF, 0.60% in excess of $350 million through $700 million in assets allocated to RREEF, and 0.55% for assets in excess of $700 million allocated to RREEF.
29
RREEF is a wholly-owned subsidiary of DWS Group GmbH & Co. KGaA (“DWS”). DWS, is, in turn, an affiliate of Deutsche Bank AG (“DB”) due to, among other things, DB’s 79.49% ownership interest in DWS. Consistent with its fiduciary relationships with the Fund, RREEF continues to serve as a sub-advisor to the Fund, subject to oversight by the Advisor.
Conflicts of Interest
The Advisor and the Sub-Advisors may provide investment advisory and other services, directly and through affiliates, to various entities and accounts other than the Fund (“Advisor Accounts”). The Fund has no interest in these activities. The Advisor and the Sub-Advisors and the investment professionals, who on behalf of the Advisor or a Sub-Advisor, provide investment advisory services to the Fund, are engaged in substantial activities other than on behalf of the Fund, may have differing economic interests in respect of such activities, and may have conflicts of interest in allocating their time and activity between the Fund and the Advisor Accounts. Such persons devote only so much time to the affairs of the Fund as in their judgment is necessary and appropriate. Set out below are practices that the Advisor follows.
Participation in Investment Opportunities
Directors, principals, officers, employees and affiliates of the Advisor may buy and sell securities or other investments for their own accounts and may have actual or potential conflicts of interest with respect to investments made on behalf of the Fund. As a result of differing trading and investment strategies or constraints, positions may be taken by directors, principals, officers, employees and affiliates of the Advisor, or by the Advisor for the Advisor Accounts, if any, that are the same as, different from or made at a different time than, positions taken for the Fund.
Conflicts of Interest Regarding RREEF
| ● | Real, potential or apparent conflicts of interest may arise when a portfolio manager has day-to-day portfolio management responsibilities with respect to more than one fund or account, including the following: |
| ● | Certain investments may be appropriate for the Fund and also for other clients advised by RREEF, including other client accounts managed by the fund’s portfolio management team. Investment decisions for the Fund and other clients are made with a view to achieving their respective investment objectives and after consideration of such factors as their current holdings, availability of cash for investment and the size of their investments generally. A particular security may be bought or sold for only one client or in different amounts and at different times for more than one but less than all clients. Likewise, because clients of RREEF may have differing investment strategies, a particular security may be bought for one or more clients when one or more other clients are selling the security. The investment results achieved for the Fund may differ from the results achieved for other clients of RREEF. In addition, purchases or sales of the same security may be made for two or more clients on the same day. In such event, such transactions will be allocated among the clients in a manner believed by RREEF to be most equitable to each client, generally utilizing a pro rata allocation methodology. In some cases, the allocation procedure could potentially have an adverse effect or positive effect on the price or amount of the securities purchased or sold by the Fund. Purchase and sale orders for the fund may be combined with those of other clients of RREEF in the interest of achieving the most favorable net results to the fund and the other clients. |
30
| ● | To the extent that a portfolio manager has responsibilities for managing multiple client accounts, a portfolio manager will need to divide time and attention among relevant accounts. RREEF attempts to minimize these conflicts by aligning its portfolio management teams by investment strategy and by employing similar investment models across multiple client accounts. |
| ● | In some cases, an apparent conflict may arise where RREEF has an incentive, such as a performance-based fee, in managing one account and not with respect to other accounts it manages. RREEF will not determine allocations based on whether it receives a performance-based fee from the client. Additionally, RREEF has in place supervisory oversight processes to periodically monitor performance deviations for accounts with like strategies. |
| ● | RREEF and its affiliates and the investment team of the Fund may manage other mutual funds and separate accounts on a long only or a long-short basis. The simultaneous management of long and short portfolios creates potential conflicts of interest including the risk that short sale activity could adversely affect the market value of the long positions (and vice versa), the risk arising from sequential orders in long and short positions, and the risks associated with receiving opposing orders at the same time. RREEF has adopted procedures that it believes are reasonably designed to mitigate these and other potential conflicts of interest. Included in these procedures are specific guidelines developed to provide fair and equitable treatment for all clients whose accounts are managed by each fund’s portfolio management team. RREEF and the portfolio management team have established monitoring procedures, a protocol for supervisory reviews, as well as compliance oversight to ensure that potential conflicts of interest relating to this type of activity are properly addressed. |
RREEF is owned by the DWS Group, a multinational global financial services firm that is a majority owned subsidiary of Deutsche Bank AG. Therefore, RREEF is affiliated with a variety of entities that provide, and/or engage in commercial banking, insurance, brokerage, investment banking, financial advisory, broker-dealer activities (including sales and trading), hedge funds, real estate and private equity investing, in addition to the provision of investment management services to institutional and individual investors. Since Deutsche Bank, its affiliates, directors, officers and employees (“Deutsche Bank”) are engaged in businesses and have interests in addition to managing asset management accounts, such wide ranging activities involve real, potential or apparent conflicts of interest. These interests and activities include potential advisory, transactional and financial activities and other interests in securities and companies that may be directly or indirectly purchased or sold by Deutsche Bank for its clients’ advisory accounts. RREEF may take investment positions in securities in which other clients or related persons within Deutsche Bank have different investment positions. There may be instances in which RREEF is purchasing or selling for its client accounts, or pursuing an outcome in the context of a workout or restructuring with respect to, securities in which Deutsche Bank is undertaking the same or differing strategy in other businesses or other client accounts. These are considerations of which advisory clients should be aware and which may cause conflicts that could be to the disadvantage of RREEF’s advisory clients, including the Fund. RREEF has instituted business and compliance policies, procedures and disclosures that are designed to identify, monitor and mitigate conflicts of interest and, as appropriate, to report them to the Fund’s Board.
31
PORTFOLIO MANAGERS
Advisor Portfolio Managers
Jordan Ruddy and Adam Lotterman are the Advisor’s Portfolio Managers. They have primary responsibility for management of the Fund’s investment portfolio and have served the Fund in this capacity since October 2013, subject to oversight by the Fund’s Investment Committee. Mr. Ruddy does not receive compensation from the Advisor, but is compensated for his duties with an affiliate of the Advisor. Mr. Lotterman receives a salary and discretionary bonus from an affiliate of the Advisor and a share of the profits, if any, through his ownership share in the Advisor. Because the Fund’s Portfolio Managers may manage assets for other pooled investment vehicles and/or other accounts (including institutional clients, pension plans and certain high net worth individuals) (collectively “Client Accounts”), or may be affiliated with such Client Accounts, there may be an incentive to favor one Client Account over another, resulting in conflicts of interest. For example, the Advisor may, directly or indirectly, receive fees from Client Accounts that are higher than the fee it receives from the Fund, or it may, directly or indirectly, receive a performance-based fee on a Client Account. In those instances, a portfolio manager may have an incentive to not favor the Fund over the Client Accounts. The Advisor has adopted trade allocation and other policies and procedures that it believes are reasonably designed to address these and other conflicts of interest.
As of September 30, 2024, the Advisor’s Portfolio Managers owned Fund shares in the following amounts:
| Portfolio Managers | Dollar Range of Shares Owned |
| Jordan Ruddy | $100,001 to $500,000 |
| Adam Lotterman | $500,001 to $1,000,000 |
As of September 30, 2024, the Advisor’s Portfolio Managers were responsible for the management of the following types of accounts in addition to the Fund:
Jordan Ruddy
| Other Accounts By Type | Total Number of Accounts by Account Type |
Total Assets By Account Type |
Number of Accounts by Type Subject to a Performance Fee |
Total Assets By Account Type Subject to a Performance Fee |
| Registered Investment Companies | 0 | 0 | 0 | $0 |
| Other Pooled Investment Vehicles | 0 | 0 | 0 | $0 |
| Other Accounts | 0 | 0 | 0 | $0 |
32
Adam Lotterman
| Other Accounts By Type | Total Number of Accounts by Account Type |
Total Assets By Account Type |
Number of Accounts by Type Subject to a Performance Fee |
Total Assets By Account Type Subject to a Performance Fee |
| Registered Investment Companies | 0 | 0 | 0 | $0 |
| Other Pooled Investment Vehicles | 0 | 0 | 0 | $0 |
| Other Accounts | 0 | 0 | 0 | $0 |
RREEF Portfolio Managers
David W. Zonavetch, Bob Thomas, and John W. Vojticek serve as the Fund’s RREEF Portfolio Managers and, subject to the Advisor’s oversight, oversee a portion of investment portfolio of the Fund. Mr. Zonavetch and Mr. Vojticek have served as Portfolio Managers to the Fund since May 2016. Mr. Thomas has served as a Portfolio Manager to the Fund since January 2018. RREEF, including its employees and affiliates are part of DWS. The brand DWS represents DWS Group GmbH & Co. KGaA (“DWS Group”) and any of its subsidiaries such as DWS Investment Management Americas, Inc. and RREEF America L.L.C., which offers advisory services. DWS seeks to offer its investment professionals competitive short-term and long-term compensation based on continuous, above average, fund performance relative to the market. This includes measurement of short and long-term performance against industry and portfolio benchmarks.
As employees of DWS, RREEF Portfolio Managers are paid are paid by RREEF on a total compensation basis, which includes: (i) fixed pay (base salary) and (ii) variable compensation. Fixed pay is the key and primary element of compensation for the majority of the RREEF Portfolio Managers and reflects the value of the individual’s role and function within the organization. It rewards factors that an employee brings to the organization such as skills and experience, while reflecting regional and divisional specifics. Fixed pay levels play a significant role in ensuring competitiveness of RREEF in the labor market, thus benchmarking provides a valuable input when determining fixed pay levels. Variable compensation is a discretionary compensation element that enables RREEF to provide an additional reward to employees, including the RREEF Portfolio Managers, for their performance and behaviors, while reflecting DWS affordability and the financial situation of DWS. Variable compensation aims to: (i) recognize that every employee contributes to the DWS’s success through the franchise component of Variable Compensation (Franchise Component), (ii) reflect individual performance, investment performance, behaviors and culture through discretionary individual VC (Individual Component), and (iii) reward outstanding contributions at the junior levels through the discretionary Recognition Award. Employee seniority as well as divisional and regional specifics determine which VC elements are applicable for a given employee and the conditions under which they apply. Both Franchise and Individual Components may be awarded in shares or other share-based instruments and other deferral arrangements.
33
Variable compensation for DWS employees, including the RREEF Portfolio Managers, can be delivered via cash, restricted equity awards, and/or restricted incentive awards or restricted compensation. Restricted compensation may include: (i) notional fund investments; (ii) restricted equity or notional equity; (iii) restricted cash; or (iv) such other form as DWS may decide in its sole discretion. Variable compensation comprises a greater proportion of total compensation as an employee’s, including the RREEF Portfolio Manager’s, seniority and total compensation level increase. Proportion of variable compensation delivered via a long-term incentive award, which is subject to performance and forfeiture provisions, will increase significantly as the amount of the variable compensation increases. In addition, additional forfeiture and claw back provisions, including complete forfeiture and claw back of variable compensation, may apply in certain circumstances. For key investment professionals, in particular, a portion of any long-term incentives will be in the form of notional investments aligned, where possible, to the funds they manage.
In general, RREEF seeks to offer their investment professionals, including the RREEF Portfolio Managers, competitive short-term and long-term compensation based on continuous, above average, fund performance relative to the market. This includes measurement of short and long-term performance against industry and portfolio benchmarks. To evaluate RREEF’s investment professionals, including the RREEF Portfolio Managers, in light of and consistent with the compensation principles set forth above, RREEF reviews investment performance for all accounts managed in relation to the appropriate Morningstar peer group universe with respect to a fund, iMoneyNet peer group with respect to a money market fund or relevant benchmark index(es) set forth in the governing documents with respect to each other account type. The ultimate goal of this process is to evaluate the degree to which investment professionals deliver investment performance that meets or exceeds their clients’ risk and return objectives. When determining total compensation, RREEF considers a number of quantitative, qualitative and other factors: (i) Quantitative measures (e.g. one-, three- and five-year pre-tax returns versus the appropriate Morningstar peer group universe for a fund, or versus the appropriate iMoneyNet peer group for a money market fund, taking risk targets into account) are utilized to measure performance; (ii) Qualitative measures (e.g. adherence to, as well as contributions to, the enhancement of the investment process) are included in the performance review; and (iii) Other factors (e.g. non-investment related performance, teamwork, adherence to compliance rules, risk management and “living the values” of RREEF) are included as part of a discretionary component of the review process, giving management the ability to consider additional markers of performance on a subjective basis. Furthermore, it is important to note that RREEF functions within a controlled environment based upon the risk limits established by DWS Group’s risk division, in conjunction with DWS Group management. Because risk consideration is inherent in all business activities, performance assessment factors in an employee’s ability to assess and manage risk.
34
As of September 30, 2024, the RREEF Portfolio Managers owned no Fund shares. The following table shows the other accounts managed by the RREEF Portfolio Managers as of September 30, 2024. For purposes of this table, “similarly managed accounts” include all accounts that are managed: (i) by the same RREEF Portfolio Managers that are jointly and primarily responsible for the day-to-day management of the Fund; and (ii) with an investment style, objective, policies and strategies substantially similar to those that are used to manage the Fund.
David Zonavetch
| Other Accounts By Type | Total Number of Accounts by Account Type |
Total Assets By Account Type |
Number of Accounts by Type Subject to a Performance Fee |
Total Assets By Account Type Subject to a Performance Fee |
| Registered Investment Companies | 4 | $1,709,400,090 | 0 | $0 |
| Other Pooled Investment Vehicles | 15 | $1,989,039,076 | 2 | $114,569,860 |
| Other Accounts | 13 | $2,955,715,517 | 4 | $453,491,748 |
Bob Thomas
| Other Accounts By Type | Total Number of Accounts by Account Type |
Total Assets By Account Type |
Number of Accounts by Type Subject to a Performance Fee |
Total Assets By Account Type Subject to a Performance Fee |
| Registered Investment Companies | 4 | $1,709,400,090 | 0 | $0 |
| Other Pooled Investment Vehicles | 15 | $1,989,039,076 | 2 | $114,569,860 |
| Other Accounts | 13 | $2,955,715,517 | 4 | $453,491,748 |
John Vojticek
| Other Accounts By Type | Total Number of Accounts by Account Type |
Total Assets By Account Type |
Number of Accounts by Type Subject to a Performance Fee |
Total Assets By Account Type Subject to a Performance Fee |
| Registered Investment Companies | 7 | $7,261,204,731 | 0 | $0 |
| Other Pooled Investment Vehicles | 37 | $9,921,605,327 | 4 | $344,993,396 |
| Other Accounts | 42 | $12,785,405,652 | 11 | $954,217,003 |
35
In addition to the accounts above, RREEF Portfolio Managers may manage accounts in a personal capacity that may include holdings that are similar to, or the same as, those of the Fund. RREEF has in place a Code of Ethics that is designed to address conflicts of interest and that, among other things, imposes restrictions on the ability of portfolio managers and other “access persons” to invest in securities that may be recommended or traded in each fund and other client accounts.
Distributor
ALPS Distributors, Inc., located at 1290 Broadway, Suite 1000, Denver, Colorado 80203, serves as the principal underwriter and distributor for the shares of the Trust pursuant to a distribution agreement with the Trust (the “Distribution Agreement”). The Distributor is registered as a broker-dealer under the Securities Exchange Act of 1934 and each U.S. state’s securities laws and is a member of FINRA. The Distribution Agreement provides that the Distributor, as agent in connection with the distribution of Fund shares, will use best efforts to facilitate the sale of the Fund’s shares. The Distributor did not retain as compensation any amounts paid to it by the Fund in the past three fiscal years.
ALLOCATION OF BROKERAGE
Specific decisions to purchase or sell securities for the Fund are made by the Portfolio Managers who are employees of the Advisor or RREEF. The Advisor and RREEF are authorized by the Trustees to allocate the orders placed on behalf of the Fund to brokers or dealers who may, but need not, provide research or statistical material or other services to the Fund or the Advisor for the Fund’s use. Such allocation is to be in such amounts and proportions as the Advisor may determine. During the fiscal year ended September 30, 2022, the Fund paid $189,867 in brokerage commissions. During the fiscal year ended September 30, 2023, the Fund paid $64,057 in brokerage commissions. During the fiscal year ended September 30, 2024, the Fund paid $69,862 in brokerage commissions.
In selecting a broker or dealer to execute each particular transaction, the Advisor and/or RREEF will take the following into consideration: execution capability, trading expertise, accuracy of execution, commission rates, reputation and integrity, fairness in resolving disputes, financial responsibility and responsiveness.
Brokers or dealers executing a portfolio transaction on behalf of the Fund may receive a commission in excess of the amount of commission another broker or dealer would have charged for executing the transaction if the Advisor and/or RREEF, as appropriate, determines in good faith that such commission is reasonable in relation to the value of brokerage and research services provided to the Fund. In allocating portfolio brokerage, the Advisor and/or RREEF may select brokers or dealers who also provide brokerage, research and other services to other accounts over which the Advisor and/or RREEF exercises investment discretion. Some of the services received as the result of Fund transactions may primarily benefit accounts other than the Fund, while services received as the result of portfolio transactions effected on behalf of those other accounts may primarily benefit the Fund.
36
Affiliated Party Brokerage
The Advisor and its affiliates (and the Sub-Advisors) will not purchase securities or other property from, or sell securities or other property to, the Fund, except that the Fund may in accordance with rules under the 1940 Act engage in transactions with accounts that are affiliated with the Fund as a result of common officers, directors, advisors, members, managing general partners or common control. These transactions would be effected in circumstances in which the Advisor determined that it would be appropriate for the Fund to purchase and another client to sell, or the Fund to sell and another client to purchase, the same security or instrument each on the same day.
The Advisor places its trades under a policy adopted by the Trustees pursuant to Section 17(e) and Rule 17(e)(1) under the 1940 Act which places limitations on the securities transactions effected through Bluerock Capital Markets, LLC, a broker-dealer that is affiliated with the Advisor. The Fund may execute portfolio trades through Bluerock Capital Markets, LLC. The policy of the Fund with respect to brokerage is reviewed by the Trustees from time to time, and transactions affected through Bluerock Capital Markets, LLC are reviewed by the Trustees quarterly. Because of the possibility of further regulatory developments affecting the securities exchanges and brokerage practices generally, the foregoing practices may be modified. During the fiscal years ended September 30, 2022, September 30, 2023 and September 30, 2024 the Fund did not pay any affiliated brokerage commissions.
TAX STATUS
The following discussion is general in nature and should not be regarded as an exhaustive presentation of all possible tax ramifications. All shareholders should consult a qualified tax advisor regarding their investment in the Fund.
The Fund intends to qualify as regulated investment company under Subchapter M of the Internal Revenue Code of 1986, as amended (the “Code”), which requires compliance with certain requirements concerning the sources of its income, diversification of its assets, and the amount and timing of its distributions to shareholders. Such qualification does not involve supervision of management or investment practices or policies by any government agency or bureau. By so qualifying, the Fund should not be subject to federal income or excise tax on its net investment income or net capital gain, which are distributed to shareholders in accordance with the applicable timing requirements. Net investment income and net capital gain of the Fund will be computed in accordance with Section 852 of the Code. Net investment income is made up of dividends and interest less expenses. Net capital gain for a fiscal year is computed by taking into account any capital loss carryforward of the Fund.
As of September 30, 2024, the components of distributable earnings on a tax basis were as follows:
Undistributed Ordinary Income |
Undistributed Long-Term Gains |
Post October Loss and Late Year Loss |
Capital Loss Carry Forward |
Other Book/Tax Differences |
Unrealized Appreciation/ (Depreciation) |
Total Accumulated Earnings/ (Accumulated Losses) |
| $0 | $0 | $0 | $0 | $(121,566,570) | $229,473,791 | $107,907,221 |
37
The difference between book basis and tax basis distributable earnings and unrealized appreciation/(depreciation) is primarily attributable to the tax deferral of losses on wash sales and tax adjustments for partnerships.
The Fund intends to distribute all of its net investment income, any excess of net short-term capital gains over net long-term capital losses, and any excess of net long-term capital gains over net short-term capital losses in accordance with the timing requirements imposed by the Code and therefore should not be required to pay any federal income or excise taxes. Distributions of net investment income will be made quarterly and net capital gain will be made after the end of each fiscal year, and no later than December 31 of each year. Both types of distributions will be in shares of the Fund unless a shareholder elects to receive cash.
To be treated as a regulated investment company under Subchapter M of the Code, the Fund must also (a) derive at least 90% of its gross income from dividends, interest, payments with respect to securities loans, net income from certain publicly traded partnerships and gains from the sale or other disposition of securities or foreign currencies, or other income (including, but not limited to, gains from options, futures or forward contracts) derived with respect to the business of investing in such securities or currencies, and (b) diversify its holdings so that, at the end of each fiscal quarter, (i) at least 50% of the market value of the Fund’s assets is represented by cash, U.S. government securities and securities of other regulated investment companies, and other securities (for purposes of this calculation, generally limited in respect of any one issuer, to an amount not greater than 5% of the market value of the Fund’s assets and 10% of the outstanding voting securities of such issuer) and (ii) not more than 25% of the value of its assets is invested in the securities of (other than U.S. government securities or the securities of other regulated investment companies) any one issuer, two or more issuers which the Fund controls and which are determined to be engaged in the same or similar trades or businesses, or the securities of certain publicly traded partnerships.
If the Fund fails to qualify as a regulated investment company under Subchapter M in any fiscal year, it will be treated as a corporation for federal income tax purposes. As such, the Fund would be required to pay income taxes on its net investment income and net realized capital gains, if any, at the rates generally applicable to corporations. Shareholders of the Fund generally would not be liable for income tax on the Fund’s net investment income or net realized capital gains in their individual capacities. Distributions to shareholders, whether from the Fund’s net investment income or net realized capital gains, would be treated as taxable dividends to the extent of current or accumulated earnings and profits of the Fund.
The Fund is subject to a 4% nondeductible excise tax on certain undistributed amounts of ordinary income and capital gain under a prescribed formula contained in Section 4982 of the Code. The formula requires payment to shareholders during a calendar year of distributions representing at least 98% of the Fund’s ordinary income for the calendar year and at least 98.2% of its capital gain net income (i.e., the excess of its capital gains over capital losses) realized during the one-year period ending October 31 during such year plus 100% of any income that was neither distributed nor taxed to the Fund during the preceding calendar year. Under ordinary circumstances, the Fund expects to time its distributions so as to avoid liability for this tax.
38
The following discussion of tax consequences is for the general information of shareholders that are subject to tax. Shareholders that are IRAs or other qualified retirement plans are exempt from income taxation under the Code.
Distributions of taxable net investment income and the excess of net short-term capital gain over net long-term capital loss are taxable to shareholders as ordinary income.
Distributions of net capital gain (“capital gain dividends”) generally are taxable to shareholders as long-term capital gain, regardless of the length of time the shares of the Fund have been held by such shareholders.
A redemption of Fund shares by a shareholder will result in the recognition of taxable gain or loss in an amount equal to the difference between the amount realized and the shareholder’s tax basis in his or her Fund shares. Such gain or loss is treated as a capital gain or loss if the shares are held as capital assets. However, any loss realized upon the redemption of shares within six months from the date of their purchase will be treated as a long-term capital loss to the extent of any amounts treated as capital gain dividends during such six-month period. All or a portion of any loss realized upon the redemption of shares may be disallowed to the extent shares are purchased (including shares acquired by means of reinvested dividends) within 30 days before or after such redemption.
Distributions of taxable net investment income and net capital gain will be taxable as described above, whether received in additional cash or shares. Shareholders electing to receive distributions in the form of additional shares will have a cost basis for federal income tax purposes in each share so received equal to the net asset value of a share on the reinvestment date.
All distributions of taxable net investment income and net capital gain, whether received in shares or in cash, must be reported by each taxable shareholder on his or her federal income tax return. Dividends or distributions declared in October, November or December as of a record date in such a month, if any, will be deemed to have been received by shareholders on December 31, if paid during January of the following year. Redemptions of shares may result in tax consequences (gain or loss) to the shareholder and are also subject to these reporting requirements.
Under the Code, the Fund will be required to report to the Internal Revenue Service all distributions of taxable income and capital gains as well as gross proceeds from the redemption or exchange of Fund shares, except in the case of certain exempt shareholders. Under the backup withholding provisions of Section 3406 of the Code, distributions of taxable net investment income and net capital gain and proceeds from the redemption or exchange of the shares of a regulated investment company may be subject to withholding of federal income tax in the case of non- exempt shareholders who fail to furnish the investment company with their taxpayer identification numbers and with required certifications regarding their status under the federal income tax law, or if the Fund is notified by the IRS or a broker that withholding is required due to an incorrect TIN or a previous failure to report taxable interest or dividends. If the withholding provisions are applicable, any such distributions and proceeds, whether taken in cash or reinvested in additional shares, will be reduced by the amounts required to be withheld.
39
Payments to a shareholder that is either a foreign financial institution (“FFI”) or a non-financial foreign entity (“NFFE”) within the meaning of the Foreign Account Tax Compliance Act (“FACTA”) may be subject to a generally nonrefundable 30% withholding tax on: (a) income dividends paid by the Fund and (b) certain capital gain distributions and the proceeds arising from the sale of Fund shares paid by the Fund after December 30, 2018. FACTA withholding tax generally can be avoided: (a) by an FFI, subject to any applicable intergovernmental agreement or exemption, if it enters into a valid agreement with the IRS to, among other requirements, report required information relating to certain direct and indirect ownership of foreign financial accounts held by U.S. persons with the FFI and (b) by an NFFE, if it: (i) certifies that it has no substantial U.S. persons or owners or (ii) if it does have such owners, reports the information relating to them. The Fund may disclose the information that it receives from its shareholders to the IRS, non-U.S. taxing authorities or other parties as necessary to comply with FACTA. Withholding also may be required if a foreign entity that is a shareholder of the Fund fails to provide the Fund with appropriate certifications or other documentation concerning its status under FACTA.
Certain U.S. Income Tax Information for Non-U.S. Investors. Non-U.S. investors in the Fund (shareholders who, as to the United States, are nonresident alien individuals, foreign trusts or estates, foreign corporations, or foreign partnerships) may be subject to U.S. income and withholding tax and are subject to special U.S. tax certification requirements. Non-U.S. investors should consult their tax advisors about the applicability of U.S. tax and withholding and the use of the appropriate forms to certify their status.
In general. The United States imposes a flat 30% withholding tax (or a withholding tax at a lower treaty rate) on U.S. source dividends, including on income dividends paid to shareholders by the Fund, subject to certain exemptions described below. However, notwithstanding such exemptions from U.S. withholding at the source, any dividends and distributions of income and capital gains, including the proceeds from the sale of Fund shares, will be subject to backup withholding at a rate of 24% if the shareholder fails to properly certify that the shareholder is not a U.S. person.
Capital gain dividends. In general, capital gain dividends reported by the Fund to shareholders, as paid from its net long-term capital gains, other than long-term capital gains realized on disposition of U.S. real property interests (see the discussion below), are not subject to U.S. withholding tax unless the shareholder is a nonresident alien individual present in the United States for a period or periods aggregating 183 days or more during the calendar year.
Interest-related dividends and short-term capital gain dividends. Certain dividends reported by the Fund to shareholders as “interest-related dividends” and paid from its “qualified net interest income” from U.S. sources are not subject to U.S. withholding tax. “Qualified interest income” includes, in general, U.S. source (i) bank deposit interest, (ii) short-term original issue discount, (iii) interest (including original issue discount, market discount, or acquisition discount) on an obligation that is in registered form, unless it is earned on an obligation issued by a corporation or partnership in which the Fund is a 10-percent shareholder or is contingent interest, and (iv) any interest-related dividend from another regulated investment company. Similarly, short-term capital gain dividends reported by the Fund to shareholders as paid from its net short-term capital gains, other than short-term capital gains realized on disposition of U.S. real property interests (see the discussion below), are not subject to U.S. withholding tax unless the shareholder was a nonresident alien individual present in the United States for a period or periods aggregating 183 days or more during the calendar year.
40
The Fund reserves the right to not report interest-related dividends or short-term capital gain dividends. Additionally, the Fund’s reporting of interest-related dividends or short-term capital gain dividends may not be passed through to shareholders by intermediaries who have assumed tax reporting responsibilities for this income in managed or omnibus accounts due to systems limitations or operational constraints.
Other net investment income. Ordinary dividends paid by the Fund to non-U.S. investors on the income earned on portfolio investments in (i) the stock of domestic and foreign corporations and (ii) the debt of foreign issuers generally will be subject to U.S. withholding tax. Foreign shareholders may be subject to U.S. withholding tax at a rate of 30% on the income resulting from an election to pass-through foreign tax credits to shareholders but may not be able to claim a credit or deduction with respect to the withholding tax for the foreign tax treated as having been paid by them.
Income effectively connected with a U.S. trade or business. If the income from the Fund is effectively connected with a U.S. trade or business carried on by a foreign shareholder, then ordinary income dividends, capital gain dividends and any gains realized upon the sale or tender of shares of the Fund will be subject to U.S. federal income tax at the rates applicable to U.S. citizens or domestic corporations and require the filing of a nonresident U.S. income tax return.
Investment in U.S. real property. The Foreign Investment in Real Property Tax Act of 1980 (“FIRPTA”) makes a non-U.S. person subject to U.S. tax on disposition of a U.S. real property interest (“USRPI”) as if the person were a U.S. person. Such gain is sometimes referred to as FIRPTA gain. If the Fund is a U.S. real property holding corporation (“USRPHC”) and is not domestically controlled, any gain realized on the sale or exchange of Fund shares by a non-U.S. shareholder that owns at any time during the five-year period ending on the date of disposition more than 5% of a class of Fund shares or (any foreign shareholder if shares in the Fund are not considered regularly traded on an established securities market) would be FIRPTA gain. The Fund will be a USRPHC if, in general, 50% or more of the fair market value of the Fund’s assets consists of U.S. real property interests, including stock of certain U.S. REITs.
The Code provides a look-through rule for distributions of FIRPTA gain when a RIC is classified as a qualified investment entity. A RIC will be classified as a qualified investment entity if, in general, 50% or more of the RIC’s assets consist of interests in U.S. REITs and other USRPHCs. If a RIC is a qualified investment entity and the non-U.S. shareholder owns more than 5% of a class of Fund shares at any time during the one-year period ending on the date of the FIRPTA distribution, the FIRPTA distribution to the non-U.S. shareholder is treated as gain from the disposition of a USRPI, causing the distribution to be subject to U.S. withholding tax at the corporate income tax rate, and requiring the non-US shareholder to file a nonresident U.S. income tax return. In addition, even if the non-U.S. shareholder does not own more than 5% of a class of Fund shares, but the Fund is a qualified investment entity, the FIRPTA distribution will be taxable as ordinary dividends (rather than as a capital gain or short-term capital gain dividend) subject to withholding at 30% or lower treaty rate.
41
FIRPTA “wash sale” rule. If the Fund is a qualified investment entity that is domestically controlled (i.e., less than 50% in value of the Fund has been owned directly or indirectly by non-U.S. shareholders during the 5-year period ending on the date of disposition) and a non-U.S. shareholder of the Fund (i) disposes of its interest in the Fund during the 30-day period preceding a FIRPTA distribution, (ii) acquires an identical stock interest during the 61-day period beginning the first day of such 30-day period preceding the FIRPTA distribution, and (iii) does not in fact receive the FIRPTA distribution in a manner that subjects the non-U.S. shareholder to tax under FIRPTA, then the non-U.S. shareholder is required to pay U.S. tax on an amount equal to the amount of the distribution that was not taxed under FIRPTA as a result of the disposition. These rules also apply to substitute dividend payments and other similar arrangements; the portion of the substitute dividend or similar payment treated as FIRPTA gain equals the portion of the RIC distribution such payment is in lieu of that otherwise would have been treated as FIRPTA gain.
U.S. tax certification rules. Special U.S. tax certification requirements may apply to non-U.S. shareholders both to avoid U.S. backup withholding imposed at a rate of 24% and to obtain the benefits of any treaty between the United States and the shareholder’s country of residence. In general, if you are a non-U.S. shareholder, you must provide a Form W-8 BEN (or other applicable Form W-8) to establish that you are not a U.S. person, to claim that you are the beneficial owner of the income and, if applicable, to claim a reduced rate of, or exemption from, withholding as a resident of a country with which the United States has an income tax treaty. A Form W-8 BEN provided without a U.S. taxpayer identification number will remain in effect for a period beginning on the date signed and ending on the last day of the third succeeding calendar year unless an earlier change of circumstances makes the information on the form incorrect. Certain payees and payments are exempt from backup withholding.
The tax consequences to a non-U.S. shareholder entitled to claim the benefits of an applicable tax treaty may be different from those described herein. Non-U.S. shareholders are urged to consult their own tax advisors with respect to the particular tax consequences to them of an investment in the Fund, including the applicability of foreign tax.
OTHER INFORMATION
Each share represents a proportional interest in the assets of the Fund. Each share has one vote at shareholder meetings, with fractional shares voting proportionally, on matters submitted to the vote of shareholders. There are no cumulative voting rights. Shares do not have pre-emptive or conversion or redemption provisions. In the event of a liquidation of the Fund, shareholders are entitled to share pro rata in the net assets of the Fund available for distribution to shareholders after all expenses and debts have been paid.
42
Compliance Service Provider
SS&C / ALPS Fund Services, Inc., located at 1290 Broadway, Suite 1000, Denver, CO 80203, provides a Chief Compliance Officer to the Fund as well as related compliance services pursuant to a consulting agreement between SS&C / ALPS Fund Services, Inc. and the Fund.
Administrator
SS&C / ALPS Fund Services, Inc. (“ALPS”), located at 1290 Broadway, Suite 1000, Denver, CO 80203, serves as the Fund’s administrator and fund accountant pursuant to a fund services agreement between ALPS and the Fund. For its services as administrator and fund accountant, the Fund pays ALPS the greater of a minimum fee or fees based on the annual net assets of the Fund (with such minimum fees subject to an annual cost of living adjustment) plus out of pocket expenses. For the fiscal year ended September 30, 2024, the Fund paid ALPS $1,325,729 for administrative and accounting services. For the fiscal year ended September 30, 2023, the Fund paid ALPS $1,604,881 for administrative and accounting services. For the fiscal year ended September 30, 2022, the Fund paid ALPS $1,371,376 for administrative and accounting services.
Transfer Agent
SS&C Global Investor & Distribution Solutions, Inc. (“SS&C GIDS”), at PO Box 219445, Kansas City, MO 64121-9445, serves as the Fund’s Transfer Agent. For its services as transfer agent, the Fund pays SS&C GIDS the greater of a minimum fee or fees based on the annual net assets of the Fund (with such minimum fees subject to an annual cost of living adjustment) plus out of pocket expenses.
Legal Counsel
Thompson Hine LLP, 41 South High Street, Suite 1700, Columbus, Ohio 43215, acts as legal counsel to the Fund.
Custodian
UMB Bank, N.A (“UMB Bank”), with principal offices at 1010 Grand Boulevard, Kansas City, Missouri 64106, serves as the custodian of the Fund’s assets, and may maintain custody of the Fund’s assets with domestic and foreign sub-custodians (which may be banks, trust companies, securities depositories and clearing agencies) approved by the Trustees. Assets of the Fund are not held by the Advisor or commingled with the assets of other accounts other than to the extent that securities are held in the name of a custodian in a securities depository, clearing agency or omnibus customer account of such custodian.
INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
Cohen & Company, Ltd. is the independent registered public accounting firm for the Fund and audits the Fund’s financial statements. Cohen & Company, Ltd. is located at 1835 Market St., Suite 310, Philadelphia, PA 19103.
43
FINANCIAL STATEMENTS
The Financial Statements and independent registered public accounting firm’s report thereon contained in the Fund’s annual report dated September 30, 2024, are incorporated by reference in this Statement of Additional Information. The Fund’s annual report is available upon request, without charge, by calling the Fund toll-free at 1-844-819-8287.
44
APPENDIX A
BLUEROCK FUND ADVISOR, LLC
PROXY VOTING POLICIES AND PROCEDURES
Proxy Voting Policy
Background: Pursuant to Rule 206(4)-6 and Rule 204-2 under the Advisers Act, it is a fraudulent, deceptive, or manipulative act, practice or course of business, within the meaning of Section 206(4) of the Advisers Act, for an investment adviser to exercise voting authority with respect to client securities, unless (i) the adviser has adopted and implemented written policies and procedures that are reasonably designed to ensure that the adviser votes proxies in the best interests of its clients, (ii) the adviser describes its proxy voting procedures to its clients and provides copies on request, and (iii) the adviser discloses to clients how they may obtain information on how the adviser voted their proxies.
Policy: The Advisor will vote proxies on behalf of its individual clients. In order to fulfill its responsibilities under the Advisors Act, the Advisor has adopted the following policies and procedures for proxy voting with regard to companies in the investment portfolio of the Fund(s).
Voting Proxies
| 1. | All proxies sent to clients that are actually received by the Advisor (to vote on behalf of the client) will be provided to the Operations Unit. |
| 2. | The Operations Unit will generally adhere to the following procedures (subject to limited exception): |
| (a) | A written record of each proxy received by the Advisor (on behalf of its clients) will be kept in the Advisor’s files; |
| (b) | The Operations Unit will determine which of the Advisor holds the security to which the proxy relates; |
| (c) | Prior to voting any proxies, the Operations Unit will determine if there are any conflicts of interest related to the proxy in question in accordance with the general guidelines set forth below. If a conflict is identified, the Operations Unit will then make a determination (which may be in consultation with outside legal counsel) as to whether the conflict is material. |
| (d) | If no material conflict is identified pursuant to these procedures, the Operations Unit will vote the proxy in accordance with the guidelines set forth below. The Operations Unit will deliver the proxy in accordance with instructions related to such proxy in a timely and appropriate manner |
A-1
Conflicts of Interest
| 1. | As stated above, in evaluating how to vote a proxy, the Operations Unit will first determine whether there is a conflict of interest related to the proxy in question between Advisor and its Advisory Clients. This examination will include (but will not be limited to) an evaluation of whether the Advisor (or any affiliate of the Advisor) has any relationship with the company (or an affiliate of the company) to which the proxy relates outside of an investment in such company by a client of the Advisor. |
| 2 | If a conflict is identified and deemed “material” by the Operations Unit, the Advisor will determine whether voting in accordance with the proxy voting guidelines outlined below is in the best interests of the client (which may include utilizing an independent third party to vote such proxies). |
| 3 | With respect to material conflicts, the Advisor will determine whether it is appropriate to disclose the conflict to affected clients give such clients the opportunity to vote the proxies in question themselves. However, with respect to ERISA clients whose advisory contract reserves the right to vote proxies when the Advisor has determined that a material conflict exists that affects its best judgment as a fiduciary to the ERISA client, the Advisor will: |
| (a) | Give the ERISA client the opportunity to vote the proxies in question themselves; or |
| (b) | Follow designated special proxy voting procedures related to voting proxies pursuant to the terms of the investment management agreement with such ERISA clients (if any). |
Proxy Voting Guidelines
| 1. | The Advisor, when acting on behalf of the Fund, must comply with the following voting restrictions unless it is determined that the Fund is not relying on Section 12(d)(1)(F) and or Rule 12d1-3: |
| a. | when the Fund exercises voting rights, by proxy or otherwise, with respect to any investment company owned by the Fund, the Fund will either |
| i. | seek instruction from the Fund’s shareholders with regard to the voting of all proxies and vote in accordance with such instructions, or |
| ii. | vote the shares held by the Fund in the same proportion as the vote of all other holders of such security. |
Disclosure of Procedures
A summary of above these proxy voting procedures will be included in Part 2 of the Advisor’s Form ADV and a Fund client’s SAI, as applicable, and will be updated whenever these policies and procedures are updated. Clients will be provided with contact information as to how they can obtain information about:
A-2
(a) the Advisor’s proxy voting procedures (i.e., a copy of these procedures); and (b) how the Advisor voted proxies that are relevant to the affected client.
Record-keeping Requirements
The Operations Unit will be responsible for maintaining files relating to the Advisor’s proxy voting procedures. Records will be maintained and preserved for five years from the end of the fiscal year during which the last entry was made on a record, with records for the first two years kept in the offices of the Advisor. Records of the following will be included in the files:
| 1. | Copies of these proxy voting policies and procedures, and any amendments thereto; |
| 2. | A copy of each proxy statement that the Advisor actually received; provided, however, that the Advisor may rely on obtaining a copy of proxy statements from the SEC’s EDGAR system for those proxy statements that are so available; |
| 3. | A record of each vote that the Advisor casts; |
| 4. | A copy of any document that the Advisor created that was material to making a decision how to vote the proxies, or memorializes that decision (if any); and |
| 5. | A copy of each written request for information on how the Advisor voted such client’s proxies and a copy of any written response to any request for information on how the Advisor voted proxies on behalf of clients. |
A-3
APPENDIX B
RREEF
PROXY VOTING POLICIES AND PROCEDURES
Proxy Voting Policy and Guidelines – DWS

| 1. | SCOPE |
DWS has adopted and implemented the following Policies and Guidelines, which it believes are reasonably designed to ensure that proxies are voted in the best economic interest of clients and in accordance with its fiduciary duties and local regulation. This Proxy Voting Policy and Guidelines – DWS (“Policy and Guidelines”) shall apply to all accounts managed by US domiciled advisers and to all US client accounts managed by non- US regional offices. Non-US regional offices are required to maintain procedures and to vote proxies as may be required by law on behalf of their non-US clients. In addition, DWS’s proxy policies reflect the fiduciary standards and responsibilities for ERISA accounts.
The attached guidelines represent a set of global recommendations that were determined by the Global Proxy Voting Sub-Committee (“the PVSC”). These guidelines were developed to provide DWS with a comprehensive list of recommendations that represent how DWS will generally vote proxies for its clients. The recommendations derived from the application of these guidelines are not intended to influence the various DWS legal entities either directly or indirectly by parent or affiliated companies. In addition, the organizational structures and documents of the various DWS legal entities allows, where necessary or appropriate, the execution by individual DWS subsidiaries of the proxy voting rights independently of any parent or affiliated company. This applies in particular to non US fund management companies. The individuals that make proxy voting decisions are also free to act independently, subject to the normal and customary supervision by the Management/Boards of these DWS legal entities.
| 2. | DWS’S PROXY VOTING RESPONSIBILITIES |
Proxy votes are the property of DWS’s advisory clients.1 As such, DWS’s authority and responsibility to vote such proxies depend upon its contractual relationships with its clients or other delegated authority. DWS has delegated responsibility for effecting its advisory clients’ proxy votes to Institutional Shareholder Services (“ISS”), an independent third-party proxy voting specialist. ISS votes DWS’s advisory clients’ proxies in accordance with DWS’s proxy guidelines or DWS’s specific instructions. Where a client has given specific instructions as to how a proxy should be voted, DWS will notify ISS to carry out those instructions. Where no specific instruction exists, DWS will follow the procedures in voting the proxies set forth in this document. Certain Taft-Hartley clients may direct DWS to have ISS vote their proxies in accordance with Taft-Hartley Voting Guidelines.
B-1
Clients may in certain instances contract with their custodial agent and notify DWS that they wish to engage in securities lending transactions. In such cases, it is the responsibility of the custodian to deduct the number of shares that are on loan so that they do not get voted twice. To the extent a security is out on loan and DWS determines that a proxy vote (or other shareholder action) is materially important to the client’s account, DWS may request, on a best efforts basis, that the agent recall the security prior to the record date to allow DWS to vote the securities.
| 1 | For purposes of this document, “clients” refers to persons or entities: (i) for which DWS serves as investment adviser or sub- adviser; (ii) for which DWS votes proxies; and (iii) that have an economic or beneficial ownership interest in the portfolio securities of issuers soliciting such proxies. |
| 3. | POLICIES |
| 3.1. | Proxy Voting Activities are Conducted in the Best Economic Interest of Clients |
DWS has adopted the following Policies and Guidelines to ensure that proxies are voted in accordance with the best economic interest of its clients, as determined by DWS in good faith after appropriate review.
| 3.2. | The Global Proxy Voting Sub-Committee |
The Global Proxy Voting Sub-Committee is an internal working group established by the applicable DWS’s Investment Risk Oversight Committee pursuant to a written charter. The PVSC is responsible for overseeing DWS’s proxy voting activities, including:
| ● | Adopting, monitoring and updating guidelines, attached as Attachment A (the “Guidelines”), that provide how DWS will generally vote proxies pertaining to a comprehensive list of common proxy voting matters; |
| ● | Voting proxies where: (i) the issues are not covered by specific client instruction or the Guidelines; (ii) the Guidelines specify that the issues are to be determined on a case-by-case basis; or (iii) where an exception to the Guidelines may be in the best economic interest of DWS’s clients; and |
| ● | Monitoring Proxy Vendor Oversight’s proxy voting activities (see below). |
DWS’s Proxy Vendor Oversight, a function of DWS’s Operations Group, is responsible for coordinating with ISS to administer DWS’s proxy voting process and for voting proxies in accordance with any specific client instructions or, if there are none, the Guidelines, and overseeing ISS’ proxy responsibilities in this regard.
B-2
| 3.3. | Availability of Proxy Voting Policies and Proxy Voting Record |
Copies of this Policy, as it may be updated from time to time, is made available to clients as required by law and otherwise at DWS’s discretion. Clients may also obtain information on how their proxies were voted by DWS as required by law and otherwise at DWS’s discretion. Note, however, that DWS must not selectively disclose its investment company clients’ proxy voting records. Proxy Vendor Oversight will make proxy voting reports available to advisory clients upon request. The investment companies’ proxy voting records will be disclosed to shareholders by means of publicly-available annual filings of each company’s proxy voting record for the 12-month periods ending June 30 (see Section 6 below), if so required by relevant law.
| 4. | PROCEDURES |
The key aspects of DWS’s proxy voting process are delineated below.
| 4.1. | The PVSC’s Proxy Voting Guidelines |
The Guidelines set forth the PVSC’s standard voting positions on a comprehensive list of common proxy voting matters. The PVSC has developed and continues to update the Guidelines based on consideration of current corporate governance principles, industry standards, client feedback, and the impact of the matter on issuers and the value of the investments.
The PVSC will review the Guidelines as necessary to support the best economic interests of DWS’s clients and, in any event, at least annually. The PVSC will make changes to the Guidelines, whether as a result of the annual review or otherwise, taking solely into account the best economic interests of clients. Before changing the Guidelines, the PVSC will thoroughly review and evaluate the proposed change and the reasons therefore, and the PVSC Chair will ask PVSC members whether anyone outside of the DWS organization (but within Deutsche Bank and its affiliates) or any entity that identifies itself as an DWS advisory client has requested or attempted to influence the proposed change and whether any member has a conflict of interest with respect to the proposed change. If any such matter is reported to the PVSC Chair, the Chair will promptly notify the Conflicts of Interest Management Sub-Committee and will defer the approval, if possible. Lastly, the PVSC will fully document its rationale for approving any change to the Guidelines.
The Guidelines may reflect a voting position that differs from the actual practices of the public company(ies) within the Deutsche Bank organization or of the investment companies for which DWS or an affiliate serves as investment adviser or sponsor. Investment companies, particularly closed-end investment companies, are different from traditional operating companies. These differences may call for differences in voting positions on the same matter. Further, the manner in which DWS votes investment company proxies may differ from proposals for which a DWS-advised or sponsored investment company solicits proxies from its shareholders. As reflected in the Guidelines, proxies solicited by closed-end (and open-end) investment companies are voted in accordance with the Guidelines.
B-3
| 4.2. | Specific Proxy Voting Decisions Made by the PVSC |
Proxy Vendor Oversight will refer to the PVSC all proxy proposals: (i) that are not covered by specific client instructions or the Guidelines; or (ii) that, according to the Guidelines, should be evaluated and voted on a case-by-case basis.
Additionally, if Proxy Vendor Oversight,2 the PVSC Chair or any member of the PVSC, a Portfolio Manager, a Research Analyst or a sub-adviser believes that voting a particular proxy in accordance with the Guidelines may not be in the best economic interests of clients, that individual may bring the matter to the attention of the PVSC Chair and/or Proxy Vendor Oversight.
| 2 | Proxy Vendor Oversight generally monitors upcoming proxy solicitations for heightened attention from the press or the industry and for novel or unusual proposals or circumstances, which may prompt Proxy Vendor Oversight to bring the solicitation to the attention of the PVSC Chair. DWS Portfolio Managers, DWS Research Analysts and sub-advisers also may bring a particular proxy vote to the attention of the PVSC Chair, as a result of their ongoing monitoring of portfolio securities held by advisory clients and/or their review of the periodic proxy voting record reports that the PVSC Chair distributes to DWS portfolio managers and DWS research analyst |
If Proxy Vendor Oversight refers a proxy proposal to the PVSC or the PVSC determines that voting a particular proxy in accordance with the Guidelines is not in the best economic interests of clients, the PVSC will evaluate and vote the proxy, subject to the procedures below regarding conflicts.
The PVSC endeavors to hold meetings to decide how to vote particular proxies sufficiently before the voting deadline so that the procedures below regarding conflicts can be completed before the PVSC’s voting determination.
| 4.3. | Proxies that Cannot Be Voted or Instances When DWS Abstains from Voting |
In some cases, the PVSC may determine that it is in the best economic interests of its clients not to vote certain proxies, or that it may not be feasible to vote certain proxies. If the conditions below are met with regard to a proxy proposal, DWS will abstain from voting:
| ⮚ | Neither the Guidelines nor specific client instructions cover an issue; |
| ⮚ | ISS does not make a recommendation on the issue; and |
| ⮚ | The PVSC cannot convene on the proxy proposal at issue to make a determination as to what would be in the client’s best interest. (This could happen, for example, if the Conflicts of Interest Management Sub-Committee found that there was a material conflict or if despite all best efforts being made, the PVSC quorum requirement could not be met). |
In addition, it is DWS’s policy not to vote proxies of issuers subject to laws of those jurisdictions that impose restrictions upon selling shares after proxies are voted, in order to preserve liquidity. In other cases, it may not be possible to vote certain proxies, despite good faith efforts to do so. For example, some jurisdictions do not provide adequate notice to shareholders so that proxies may be voted on a timely basis. Voting rights on securities that have been loaned to third-parties transfer to those third-parties, with loan termination often being the only way to attempt to vote proxies on the loaned securities. Lastly, the PVSC may determine that the costs to the client(s) associated with voting a particular proxy or group of proxies outweighs the economic benefits expected from voting the proxy or group of proxies.
B-4
Proxy Vendor Oversight will coordinate with the PVSC Chair regarding any specific proxies and any categories of proxies that will not or cannot be voted. The reasons for not voting any proxy shall be documented.
| 4.4. | Conflict of Interest Procedures |
| 4.4.1. | Procedures to Address Conflicts of Interest and Improper Influence |
Overriding Principle. In the limited circumstances where the PVSC votes proxies,3 the PVSC will vote those proxies in accordance with what it, in good faith, determines to be the best economic interests of DWS’s clients.4
| 3 | As mentioned above, the PVSC votes proxies where: (i) neither a specific client instruction nor a Guideline directs how the proxy should be voted; (ii) where the Guidelines specify that an issue is to be determined on a case-by-case basis; or (iii) where voting in accordance with the Guidelines may not be in the best economic interests of clients. |
| 4 | Proxy Vendor Oversight, who serves as the non-voting secretary of the PVSC, may receive routine calls from proxy solicitors and other parties interested in a particular proxy vote. Any contact that attempts to exert improper pressure or influence shall be reported to the Conflicts of Interest Management Sub-Committee. |
Independence of the PVSC. As a matter of Compliance policy, the PVSC and Proxy Vendor Oversight are structured to be independent from other parts of Deutsche Bank. Members of the PVSC and the employee responsible for Proxy Vendor Oversight are employees of DWS. As such, they may not be subject to the supervision or control of any employees of Deutsche Bank Corporate and Investment Banking division (“CIB”). Their compensation cannot be based upon their contribution to any business activity outside of DWS without prior approval of Legal and Compliance. They can have no contact with employees of Deutsche Bank outside of DWS regarding specific clients, business matters, or initiatives without the prior approval of Legal and Compliance. They furthermore may not discuss proxy votes with any person outside of DWS (and within DWS only on a need to know basis).
Conflict Review Procedures. The “Conflicts of Interest Management Sub-Committee” within DWS monitors for potential material conflicts of interest in connection with proxy proposals that are to be evaluated by the PVSC. The Conflicts of Interest Management Sub-Committee members include DWS Compliance, the chief compliance officers of the advisors and the DWS Funds. Promptly upon a determination that a proxy vote shall be presented to the PVSC, the PVSC Chair shall notify the Conflicts of Interest Management Sub- Committee. The Conflicts of Interest Management Sub-Committee shall promptly collect and review any information deemed reasonably appropriate to evaluate, in its reasonable judgment, if DWS or any person participating in the proxy voting process has, or has the appearance of, a material conflict of interest. For the purposes of this policy, a conflict of interest shall be considered “material” to the extent that a reasonable person could expect the conflict to influence, or appear to influence, the PVSC’s decision on the particular vote at issue. PVSC should provide the Conflicts of Interest Management Sub-Committee a reasonable amount of time (no less than 24 hours) to perform all necessary and appropriate reviews. To the extent that a conflicts review cannot be sufficiently completed by the Conflicts of Interest Management Sub-Committee the proxies will be voted in accordance with the standard Guidelines.
B-5
The information considered by the Conflicts of Interest Management Sub-Committee may include without limitation information regarding: (i) DWS client relationships; (ii) any relevant personal conflict known by the Conflicts of Interest Management Sub-Committee or brought to the attention of that sub-committee; and (iii) any communications with members of the PVSC (or anyone participating or providing information to the PVSC) and any person outside of the DWS organization (but within Deutsche Bank and its affiliates) or any entity that identifies itself as an DWS advisory client regarding the vote at issue. In the context of any determination, the Conflicts of Interest Management Sub-Committee may consult with and shall be entitled to rely upon all applicable outside experts, including legal counsel.
Upon completion of the investigation, the Conflicts of Interest Management Sub-Committee will document its findings and conclusions. If the Conflicts of Interest Management Sub-Committee determines that: (i) DWS has a material conflict of interest that would prevent it from deciding how to vote the proxies concerned without further client consent; or (ii) certain individuals should be recused from participating in the proxy vote at issue, the Conflicts of Interest Management Sub-Committee will so inform the PVSC Chair.
If notified that DWS has a material conflict of interest as described above, the PVSC chair will obtain instructions as to how the proxies should be voted either from: (i) if time permits, the affected clients; or (ii) in accordance with the standard Guidelines. If notified that certain individuals should be recused from the proxy vote at issue, the PVSC Chair shall do so in accordance with the procedures set forth below.
Note: Any DWS employee who becomes aware of a potential, material conflict of interest in respect of any proxy vote to be made on behalf of clients shall notify Compliance or the Conflicts of Interest Management Sub-Committee. Compliance shall call a meeting of the Conflict of Interest Management Sub- Committee to evaluate such conflict and determine a recommended course of action.
Procedures to be followed by the PVSC. At the beginning of any discussion regarding how to vote any proxy, the PVSC Chair (or his or her delegate) will inquire as to whether any PVSC member (whether voting or ex officio) or any person participating in the proxy voting process has a personal conflict of interest or has actual knowledge of an actual or apparent conflict that has not been reported to the Conflicts of Interest Management Sub-Committee.
B-6
The PVSC Chair also will inquire of these same parties whether they have actual knowledge regarding whether any Director, officer, or employee outside of the DWS organization (but within Deutsche Bank and its affiliates) or any entity that identifies itself as an DWS advisory client, has: (i) requested that DWS, Proxy Vendor Oversight (or any member thereof), or a PVSC member vote a particular proxy in a certain manner; (ii) attempted to influence DWS, Proxy Vendor Oversight (or any member thereof), a PVSC member or any other person in connection with proxy voting activities; or (iii) otherwise communicated with a PVSC member, or any other person participating or providing information to the PVSC regarding the particular proxy vote at issue and which incident has not yet been reported to the Conflicts of Interest Management Sub-Committee.
If any such incidents are reported to the PVSC Chair, the Chair will promptly notify the Conflicts of Interest Management Sub-Committee and, if possible, will delay the vote until the Conflicts of Interest Management Sub-Committee can complete the conflicts report. If a delay is not possible, the Conflicts of Interest Management Sub-Committee will instruct the PVSC” (i) whether anyone should be recused from the proxy voting process or (ii) whether DWS should vote the proxy in accordance with the standard guidelines, seek instructions as to how to vote the proxy at issue from ISS or, if time permits, the affected clients. These inquiries and discussions will be properly reflected in the PVSC’s minutes.
Duty to Report. Any DWS employee, including any PVSC member (whether voting or ex officio), that is aware of any actual or apparent conflict of interest relevant to, or any attempt by any person outside of the DWS organization (but within Deutsche Bank and its affiliates) or any entity that identifies itself as an DWS advisory client to influence how DWS votes its proxies has a duty to disclose the existence of the situation to the PVSC Chair (or his or her designee) and the details of the matter to the Conflicts of Interest Management Sub-Committee. In the case of any person participating in the deliberations on a specific vote, such disclosure should be made before engaging in any activities or participating in any discussion pertaining to that vote.
Recusal of Members. The PVSC will recuse from participating in a specific proxy vote any PVSC members (whether voting or ex officio) and/or any other person who: (i) are personally involved in a material conflict of interest; or (ii) who, as determined by the Conflicts of Interest Management Sub-Committee, have actual knowledge of a circumstance or fact that could affect their independent judgment, in respect of such vote. The PVSC will also exclude from consideration the views of any person (whether requested or volunteered) if the PVSC or any member thereof knows, or if the Conflicts of Interest Management Sub-Committee has determined, that such other person has a material conflict of interest with respect to the particular proxy or has attempted to influence the vote in any manner prohibited by these policies.
If, after excluding all relevant PVSC voting members pursuant to the paragraph above, there are three or more PVSC voting members remaining, those remaining PVSC members will determine how to vote the proxy in accordance with these Policies and Guidelines. If there are fewer than three PVSC voting members remaining, the PVSC Chair will vote the proxy in accordance with the standard Guidelines or will obtain instructions as to how to have the proxy voted from, if time permits, the affected clients and otherwise from ISS.
B-7
| 4.4.2. | Investment Companies and Affiliated Public Companies |
Investment Companies. As reflected in the Guidelines, all proxies solicited by open-end and closed-end investment companies are voted in accordance with the pre-determined guidelines of ISS, unless the investment company client directs DWS to vote differently on a specific proxy or specific categories of proxies. However, regarding investment companies for which DWS or an affiliate serves as investment adviser or principal underwriter, such proxies are voted in the same proportion as the vote of all other shareholders (i.e., “mirror” or “echo” voting). Master Fund proxies solicited from feeder Funds are voted in accordance with applicable provisions of Section 12 of the Investment Company Act of 1940 (“Investment Company Act”).
Subject to participation agreements with certain Exchange Traded Funds (“ETF”) issuers that have received exemptive orders from the US Securities and Exchange Commission (“SEC”) allowing investing DWS Funds to exceed the limits set forth in Section 12(d)(1)(A) and (B) of the Investment Company Act, DWS will echo vote proxies for ETFs in which Deutsche Bank holds more than 25% of outstanding voting shares globally when required to do so by participation agreements and SEC orders.
Affiliated Public Companies. For proxies solicited by non-investment company issuers of or within the DWS or Deutsche Bank organization (e.g., shares of DWS or Deutsche Bank), these proxies will be voted in the same proportion as the vote of other shareholders (i.e., “mirror” or “echo” voting). In markets where mirror voting is not permitted, DWS will “Abstain” from voting such shares.
Note: With respect to the DWS Central Cash Management Government Fund (registered under the Investment Company Act), the Fund is not required to engage in echo voting and the investment adviser will use these Guidelines and may determine, with respect to the DWS Central Cash Management Government Fund, to vote contrary to the positions in the Guidelines, consistent with the Fund’s best interest.
| 4.4.3. | Other Procedures that Limit Conflicts of Interest |
DWS and other entities in the Deutsche Bank organization have adopted a number of policies, procedures, and internal controls that are designed to avoid various conflicts of interest, including those that may arise in connection with proxy voting, including but not limited to:
| ⮚ | Code of Conduct– DB Group; |
| ⮚ | Conflicts of Interest Policy – DWS Group; |
| ⮚ | Code of Ethics – DWS US; |
| ⮚ | Code of Ethics – DWS ex US |
| ⮚ | Code of Professional Conduct – US. |
B-8
The PVSC expects that these policies, procedures, and internal controls will greatly reduce the chance that the PVSC (or its members) would be involved in, aware of, or influenced by an actual or apparent conflict of interest.
All impacted business units are required to adopt, implement, and maintain procedures to ensure compliance with this Section. At a minimum, such procedures must: (i) assign roles and responsibilities for carrying out the procedures, including responsibility for periodically updating the procedures; (ii) identify clear escalation paths for identified breaches of the procedures; and (iii) contain a legend or table mapping the procedures to this Section (e.g., cross-referencing Section or page numbers).
| 5. | RECORDKEEPING |
At a minimum, the following records must be properly maintained and readily accessible in order to evidence compliance with this Policy.
| ⮚ | DWS will maintain a record of each proxy vote cast by DWS that includes among other things, company name, meeting date, proposals presented, vote cast, and shares voted. |
| ⮚ | Proxy Vendor Oversight maintains records for each of the proxy ballots it votes. Specifically, the records include, but are not limited to: |
| ● | The proxy statement (and any additional solicitation materials) and relevant portions of annual statements; |
| ● | Any additional information considered in the voting process that may be obtained from an issuing company, its agents, or proxy research firms; |
| ● | Analyst worksheets created for stock option plan and share increase analyses; and |
| ● | Proxy Edge print-screen of actual vote election. |
| ⮚ | DWS will: (i) retain this Policy and the Guidelines; (ii) will maintain records of client requests for proxy voting information; and (iii) will retain any documents Proxy Vendor Oversight or the PVSC prepared that were material to making a voting decision or that memorialized the basis for a proxy voting decision. |
| ⮚ | The PVSC also will create and maintain appropriate records documenting its compliance with this Policy, including records of its deliberations and decisions regarding conflicts of interest and their resolution. |
| ⮚ | With respect to DWS’s investment company clients, ISS will create and maintain records of each company’s proxy voting record for the 12-month periods ending June 30. DWS will compile the following information for each matter relating to a portfolio security considered at any shareholder meeting held during the period covered by the report (and with respect to which the company was entitled to vote): |
B-9
| ● | The name of the issuer of the portfolio security; |
| ● | The exchange ticker symbol of the portfolio security (if symbol is available through reasonably practicable means); |
| ● | The Council on Uniform Securities Identification Procedures (“CUSIP”) number for the portfolio security (if the number is available through reasonably practicable means); |
| ● | The shareholder meeting date; |
| ● | A brief identification of the matter voted on; |
| ● | Whether the matter was proposed by the issuer or by a security holder; |
| ● | Whether the company cast its vote on the matter; |
| ● | How the company cast its vote (e.g., for or against proposal, or abstain; for or withhold regarding election of Directors); and |
| ● | Whether the company cast its vote for or against Management. |
Note: This list is intended to provide guidance only in terms of the records that must be maintained in accordance with this policy. In addition, please note that records must be maintained in accordance with the Records Management Policy - Deutsche Bank Group and applicable policies and procedures thereunder.
With respect to electronically stored records, “properly maintained” is defined as complete, authentic (unalterable), usable and backed-up. At a minimum, records should be retained for a period of not less than six years (or longer, if necessary to comply with applicable regulatory requirements), the first three years in an appropriate DWS office.
| 6. | OVERSIGHT RESPONSIBILITES |
Proxy Vendor Oversight will review a reasonable sampling of votes on a regular basis to ensure that ISS has cast the votes in a manner consistent with the Guidelines. Proxy Vendor Oversight will provide the PVSC with a quarterly report of its review and identify any issues encountered during the period. Proxy Vendor Oversight will also perform a post season review once a year on certain proposals to assess whether ISS voted consistent with the Guidelines.
In addition, the PVSC will, in cooperation with Proxy Vendor Oversight and DWS Compliance, consider, on at least an annual basis, whether ISS has the capacity and competence to adequately analyze the matters for which it is responsible. This includes whether ISS has effective polices, and methodologies and a review of ISS’s policies and procedures with respect to conflicts.
B-10
The PVSC also monitors the proxy voting process by reviewing summary proxy information presented by ISS to determine, among other things, whether any changes should be made to the Guidelines. This review will take place at least quarterly and is documented in the PVSC’s minutes.
B-11

STATEMENT OF ADDITIONAL INFORMATION
Class A Shares (TIPRX), Class C Shares (TIPPX),
Class I Shares (TIPWX),
Class L Shares (TIPLX) and Class M Shares (TIPMX) of Beneficial Interest
February 1, 2025
B-12
PART C - OTHER INFORMATION
Item 25. Financial Statements and Exhibits
| 1. | Financial Statements |
Part A: The financial highlights of the Bluerock Total Income+ Real Estate Fund (the “Registrant”) for the fiscal year ended September 30, 2024 are included in Part A of this registration statement in the section entitled “Financial Highlights.”
Part B: The Registrant’s audited Financial Statements and the notes thereto in the Registrant’s Annual Report to Shareholders for the fiscal year ended September 30, 2024, filed electronically with the Securities and Exchange Commission (the “SEC”) pursuant to Section 30(b)(2) of the Investment Company Act of 1940, as amended (the “1940 Act”), are incorporated by reference into Part B of this registration statement.
| 2. | Exhibits |
| a. | (1) | Agreement and Declaration of Trust (Incorporated by reference to Form N-2 (1933 Act File No. 333-181848) filed on June 1, 2012) |
| (2) | Certificate of Trust (Incorporated by reference to Form N-2 (1933 Act File No. 333-181848) filed on June 1, 2012) |
| (3) | Certificate of Amendment to Agreement and Declaration of Trust (Incorporated by reference to Form N-2 (1933 Act File No. 333-181848) filed on August 23, 2012) |
| b. | By-Laws (Incorporated by reference to Pre-Effective Amendment No. 1 (1933 Act File No. 333-181848) to the Registrant’s Registration Statement on Form N-2, filed on August 23, 2012) |
| c. | Voting Trust Agreements: None. |
| d. | Instruments Defining Rights of Security Holders. |
| (1) | See Article III, “Shares” and Article V “Shareholders’ Voting Powers and Meetings” of the Registrant’s Agreement and Declaration of Trust. See also, Article 12, “Meetings” of shareholders of the Registrant’s By-Laws. |
| (2) | Amended Multiple Class Plan (Incorporated by reference to the Registration Statement on Form N-2 (1933 Act File No. 333-2236114) filed on January 28, 2020) |
| e. | Dividend reinvestment plan: See Part A of this Registration Statement in the section entitled “Dividend Reinvestment Policy.” |
| f. | Rights of subsidiaries long-term debt holders: Not applicable. |
| (3) | Investment Management Agreement with RREEF America L.L.C. (Incorporated by reference to the Registrant’s Registration Statement on Form N-2 (1933 Act File No. 333-211369), filed on May 13, 2016) |
| (a) | Amendment to the Distribution Agreement (Incorporated by reference to the Registration Statement on Form N-2 (1933 Act File No. 333-2236114), filed on January 28, 2020) |
| (2) | Distribution Letter Agreement (Incorporated by reference to the Registrant’s Registration Statement on Form N-2 (1933 Act File No. 333-222772), filed on January 29, 2018) |
| (3) | Wholesale Marketing Agreement (Incorporated by reference to the Registrant’s Registration Statement on Form N-2 (1933 Act File No. 333-222772), filed on January 28, 2018) |
| (7) | Distribution Plan for Class M Shares (Incorporated by reference to Post-Effective (1933 Act File No. 333-236114) to the Registrant’s Registration Statement on Form N-2, filed on January 28, 2020) |
| i. | Bonus, profit sharing, pension and similar arrangements for Fund Trustees and Officers: None. |
| m. | Non-resident Trustee Consent to Service of Process: Not applicable. |
| n. | Consent of Independent Registered Public Accounting Firm – (Filed herewith) |
| o. | Omitted Financial Statements: None. |
| q. | Model Retirement Plan: None. |
Item 26. Marketing Arrangements: Not Applicable.
Item 27. Other Expenses of Issuance and Distribution: Not Applicable.
Item 28. Persons Controlled by or Under Common Control with Registrant: None.
Item 29. Number of Holders of Securities as of January 3, 2025:
| Title of Class | Number of Record Holders |
| Shares of Beneficial Ownership - Class A | [12,633] |
| Shares of Beneficial Ownership - Class C | [10,688] |
| Shares of Beneficial Ownership - Class I | [45,805] |
| Shares of Beneficial Ownership - Class L | [1,816] |
| Shares of Beneficial Ownership - Class M | [1,374] |
Item 30. Indemnification
Reference is made to Article VIII Section 2 of the Registrant’s Agreement and Declaration of Trust (the “Declaration of Trust”), filed as Exhibit (a)(2) hereto, and to Section 8 of the Registrant’s Underwriting Agreement, to be filed as Exhibit (h)(1) hereto. The Registrant hereby undertakes that it will apply the indemnification provisions of the Declaration of Trust and Underwriting Agreement in a manner consistent with Release 40-11330 of the Securities and Exchange Commission (the “SEC”) under the 1940 Act, so long as the interpretation therein of Sections 17(h) and 17(i) of the 1940 Act remains in effect. The Registrant maintains insurance on behalf of any person who is or was an independent trustee, officer, employee, or agent of the Registrant against certain liability asserted against and incurred by, or arising out of, his or her position. However, in no event will the Registrant pay that portion of the premium, if any, for insurance to indemnify any such person for any act for which the Registrant itself is not permitted to indemnify.
Insofar as indemnification for liability arising under the Securities Act of 1933, as amended (the “1933 Act”) may be permitted to directors, officers and controlling persons of the registrant pursuant to the foregoing provisions, or otherwise, the registrant has been advised that in the opinion of the SEC such indemnification is against public policy as expressed in the 1933 Act and is, therefore, unenforceable. In the event that a claim for indemnification against such liabilities (other than the payment by the registrant of expenses incurred or paid by a director, trustee, officer or controlling person of the registrant in the successful defense of any action, suit or proceeding) is asserted by such director, trustee, officer or controlling person in connection with the securities being registered, the registrant will, unless in the opinion of its counsel the matter has been settled by controlling precedent, submit to a court of appropriate jurisdiction the question whether such indemnification by it is against public policy as expressed in the 1933 Act and will be governed by the final adjudication of such issue.
Item 31. Business and Other Connections of Investment Advisor
A description of any other business, profession, vocation, or employment of a substantial nature in which the investment advisor of the Registrant, and each member, director, executive officer, or partner of any such investment advisor, is or has been, at any time during the past two fiscal years, engaged in for his or her own account or in the capacity of member, trustee, officer, employee, partner or director, is set forth in the Registrant’s prospectus in the section entitled “Management of the Fund.” Information as to the members and officers of the Advisor is included in its Form ADV as filed with the SEC (File No. 801- 22710), and is incorporated herein by reference.
Item 32. Location of Accounts and Records
ALPS Fund Services, Inc., the Fund’s administrator, maintains certain required accounting related and financial books and records of the Registrant at located at 1290 Broadway, Suite 1000, Denver, CO 80203. The other required books and records are maintained by the Bluerock Fund Advisor, LLC at 919 Third Avenue, 40th Floor, New York, NY 10022.
Item 33. Management Services: Not Applicable.
Item 34. Undertakings
1. Not Applicable.
2. The Registrant undertakes to file, during any period in which offers or sales are being made, a post-effective amendment to the registration statement: (a) (i) to include any prospectus required by Section 10(a)(3) of the 1933 Act; (ii) to reflect in the prospectus any facts or events after the effective date of the registration statement (or the most recent post-effective amendment thereof) which, individually or in the aggregate, represent a fundamental change in the information set forth in the registration statement; and (iii) to include any material information with respect to the plan of distribution not previously disclosed in the registration statement or any material change to such information in the registration statement. (b) For the purpose of determining any liability under the 1933 Act, each post-effective amendment that contains a form of prospectus shall be deemed to be a new registration statement relating to the securities offered therein, and the offering of such securities at that time shall be deemed to be the initial bona fide offering thereof. (c) The Registrant undertakes to remove from registration by means of a post-effective amendment any of the securities being registered which remain unsold at the termination of the offering. (d) The Registrant undertakes that, for the purpose of determining liability under the 1933 Act, if the Registrant is subject to Rule 430C, each prospectus filed pursuant to Rule 497(b), (c), (d) or I under the 1933 Act as part of a registration statement relating to an offering, other than prospectuses filed in reliance on Rule 430A under the 1933 Act, shall be deemed to be part of and included in the registration statement as of the date it is first used after effectiveness; provided however, that no statement made in a registration statement or prospectus that is part of the registration statement or made in a document incorporated or deemed incorporated by reference into the registration statement or prospectus that is part of the registration statement will, as to a purchaser with a time of contract of sale prior to such first use, supersede or modify any statement that was made in the registration statement or prospectus that was part of the registration statement or made in any such document immediately prior to such date of first use (e) The Registrant undertakes that, for the purpose of determining liability under the 1933 Act, in a primary offering of securities of the undersigned Registrant pursuant to this registration statement, regardless of the underwriting method used to sell the securities to the purchaser, if the securities are offered or sold to such purchaser by means of any of the following communications, the undersigned Registrant will be a seller to the purchaser and will be considered to offer or sell such securities to the purchaser: (i) any preliminary prospectus or prospectus of the undersigned Registrant relating to the offering required to be filed pursuant to Rule 497 under the 1933 Act; (ii) the portion of any advertisement pursuant to Rule 482 under the 1933 Act relating to the offering containing material information about the undersigned Registrant or its securities provided by or on behalf of the undersigned Registrant; and (iii) any other communication that is an offer in the offering made by the undersigned Registrant to the purchaser.
3. The Registrant undertakes:
(a) to file, during any period in which offers or sales are being made, a post-effective amendment to this Registration Statement:
(1) to include any prospectus required by Section 10(a)(3) of the Securities Act of 1933, as amended (“Securities Act”);
(2) to reflect in the prospectus any facts or events arising after the effective date of the registration statement (or the most recent post-effective amendment thereof) which, individually or in the aggregate, represent a fundamental change in the information set forth in the registration statement; and
(3) to include any material information with respect to the plan of distribution not previously disclosed in the registration statement or any material change to such information in the registration statement;
(b) that, for the purpose of determining any liability under the Securities Act, each such post-effective amendment shall be deemed to be a new registration statement relating to the securities offered therein, and the offering of those securities at that time shall be deemed to be the initial bona fide offering thereof;
(c) to remove from registration by means of a post-effective amendment any of the securities being registered which remain unsold at the termination of the offering;
(d) that, for the purpose of determining liability under the Securities Act to any purchaser:
(1) if the Registrant is relying on Rule 430B [17 CFR 230.430B]:
(A) Each prospectus filed by the Registrant pursuant to Rule 424(b)(3) shall be deemed to be part of the registration statement as of the date the filed prospectus was deemed part of and included in the registration statement; and
(B) Each prospectus required to be filed pursuant to Rule 424(b)(2), (b)(5), or (b)(7) as part of a registration statement in reliance on Rule 430B relating to an offering made pursuant to Rule 415(a)(1)(i), (x), or (xi) for the purpose of providing the information required by Section 10(a) of the Securities Act shall be deemed to be part of and included in the registration statement as of the earlier of the date such form of prospectus is first used after effectiveness or the date of the first contract of sale of securities in the offering described in the prospectus. As provided in Rule 430B, for liability purposes of the issuer and any person that is at that date an underwriter, such date shall be deemed to be a new effective date of the registration statement relating to the securities in the registration statement to which that prospectus relates, and the offering of such securities at that time shall be deemed to be the initial bona fide offering thereof. Provided, however, that no statement made in a registration statement or prospectus that is part of the registration statement or made in a document incorporated or deemed incorporated by reference into the registration statement or prospectus that is part of the registration statement will, as to a purchaser with a time of contract of sale prior to such effective date, supersede or modify any statement that was made in the registration statement or prospectus that was part of the registration statement or made in any such document immediately prior to such effective date; or
(2) if the Registrant is subject to Rule 430C [17 CFR 230.430C]: each prospectus filed pursuant to Rule 424(b) under the Securities Act as part of a registration statement relating to an offering, other than registration statements relying on Rule 430B or other than prospectuses filed in reliance on Rule 430A, shall be deemed to be part of and included in the registration statement as of the date it is first used after effectiveness. Provided, however, that no statement made in a registration statement or prospectus that is part of the registration statement or made in a document incorporated or deemed incorporated by reference into the registration statement or prospectus that is part of the registration statement will, as to a purchaser with a time of contract of sale prior to such first use, supersede or modify any statement that was made in the registration statement or prospectus that was part of the registration statement or made in any such document immediately prior to such date of first use.
(e) that for the purpose of determining liability of the Registrant under the Securities Act to any purchaser in the initial distribution of securities:
The undersigned Registrant undertakes that in a primary offering of securities of the undersigned Registrant pursuant to this registration statement, regardless of the underwriting method used to sell the securities to the purchaser, if the securities are offered or sold to such purchaser by means of any of the following communications, the undersigned Registrant will be a seller to the purchaser and will be considered to offer or sell such securities to the purchaser:
(1) any preliminary prospectus or prospectus of the undersigned Registrant relating to the offering required to be filed pursuant to Rule 424 under the Securities Act;
(2) free writing prospectus relating to the offering prepared by or on behalf of the undersigned Registrant or used or referred to by the undersigned Registrants;
(3) the portion of any advertisement pursuant to Rule 482 [17 CFR 230.482] under the Securities Act relating to the offering containing material information about the undersigned Registrant or its securities provided by or on behalf of the undersigned Registrant; and
(4) any other communication that is an offer in the offering made by the undersigned Registrant to the purchaser.
4. Not Applicable.
5. Not Applicable.
6. Not Applicable.
7. The Registrant undertakes to send by first class mail or other means designed to ensure equally prompt delivery within two business days of receipt of a written or oral request, the Registrant’s statement of additional information.
SIGNATURES
Pursuant to the requirements of the Securities Act of 1933, as amended, and the Investment Company Act of 1940, as amended, the Fund certifies that it meets the requirements for effectiveness of this Registration Statement under Rule 486(b) under the Securities Act and has duly caused this amendment to its registration statement to be signed on its behalf by the undersigned, thereunto duly authorized, in the City of New York, State of New York, on the 27th day of January, 2025.
BLUEROCK TOTAL INCOME+ REAL ESTATE FUND
| By: | /s/ Jordan Ruddy | |
| Name: | Jordan Ruddy | |
| Title: | President and Principal Executive Officer |
Pursuant to the requirements of the 1933 Act, this amendment to the Registration Statement has been signed below by the following persons in their respective capacities and on the date noted.
| Name | Title | Date |
| Ramin Kamfar** | Trustee | January 27, 2025 |
| Bobby Majumder** | Trustee | January 27, 2025 |
| Kamal Jafarnia** | Trustee | January 27, 2025 |
| Romano Tio** | Trustee | January 27, 2025 |
| Simon Adamiyatt** | Trustee, Treasurer and Principal Financial Officer | January 27, 2025 |
| Jordan Ruddy** | President and Principal Executive Officer | January 27, 2025 |
| ** By: | /s/ JoAnn Strasser | |
| Date: | January 27, 2025 | |
| JoAnn Strasser | ||
| Attorney-in-Fact – Pursuant to Powers of Attorney |
EXHIBIT INDEX
| Description | Exhibit Number |
| Consent of Counsel | 99.2(l)(b) |
| Consent of Independent Registered Public Accounting Firm | 99.2(n) |
ATTACHMENTS / EXHIBITS

FREE Breaking News Alerts from StreetInsider.com!
StreetInsider.com Top Tickers, 10/7/2026
- S&P 500, Nasdaq retreat from record highs as yields and oil climb
- Want to be a stock market bear? BCA says watch potential U.S. tax increases
- SpaceX seeks $40bn in financing for Nvidia chip purchase
- Chip stock could soar nearly 200%, analyst says: "If you don’t buy it, they will"
- Musk rules out TSMC role in Terafab operations; Intel gains
Serious News for Serious Traders! Try StreetInsider.com Premium Free!
You May Also Be Interested In
- Capital Pain, Not Technology, Is Driving Real Estate’s Shift to Everyday Investors
- Danone: Information on the total number of voting rights and shares
- From Childhood Roots to a Carrollwood Homecoming: Sparkle Grooming Co. Opens October 12
Create E-mail Alert Related Categories
SEC FilingsSign up for StreetInsider Free!
Receive full access to all new and archived articles, unlimited portfolio tracking, e-mail alerts, custom newswires and RSS feeds - and more!
