



Form 485BPOS Viking Mutual Funds
 Tweet
 Share
 E-mail
As filed with the Securities and Exchange Commission
on
1933 Act Registration Number: 333-77993
1940 Act Registration Number: 811-09277
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM
| REGISTRATION STATEMENT UNDER THE SECURITIES ACT OF 1933 | ☒ |
| Pre-Effective Amendment No. | ☐ |
| Post-Effective Amendment No. 54 | ☒ |
and/or
| REGISTRATION STATEMENT UNDER THE INVESTMENT COMPANY ACT OF 1940 | ☒ |
| Amendment No. 54 |
(Check appropriate box or boxes.)
(Exact name of Registrant as Specified in Charter)
| 1 North Main Street, Minot, North Dakota | 58703 | |
| (Address of principal offices) | (Zip code) |
Registrant’s Telephone Number, Including Area Code 701-852-5292
Shannon D. Radke, 1 North Main Street, Minot, North Dakota 58703
(Name and Address of Agent for Service)
With Copies to:
JoAnn Strasser, Thompson Hine, LLP, 41 South High Street, Suite 1700, Columbus, Ohio 43215-6101
Approximate Date of Proposed Public Offering As soon as practicable after effectiveness
It is proposed that this filing will become effective (check appropriate box)
| ☐ | immediately upon filing pursuant to paragraph (b) | |
| ☒ | on | |
| ☐ | 60 days after filing pursuant to paragraph (a)(1) | |
| ☐ | on (date), pursuant to paragraph (a)(1) | |
| ☐ | 75 days after filing pursuant to paragraph (a)(2) | |
| ☐ | on (date), pursuant to paragraph (a)(2) of Rule 485 |
If appropriate, check the following box:
| ☐ | This post-effective amendment designates a new effective date for a previously filed post-effective amendment. |
Title of Securities Being Registered: Shares of Beneficial Interest
 | |
| VIKING MUTUAL FUNDS | |
| Class A and Class I Shares | |
| KANSAS MUNICIPAL FUND | |
| Class A: | |
| MAINE MUNICIPAL FUND | |
| Class A: | |
| NEBRASKA MUNICIPAL FUND | |
| Class A: | |
| OKLAHOMA MUNICIPAL FUND | |
| Class A: | |
| VIKING TAX-FREE FUND FOR MONTANA | |
| Class A: | |
| VIKING TAX-FREE FUND FOR NORTH DAKOTA | |
| Class A: | |
|
PROSPECTUS
The Securities and Exchange Commission has not approved or disapproved these securities or determined if this prospectus is accurate or complete. Any representation to the contrary is a criminal offense.
| |
TABLE OF CONTENTS
The Kansas Municipal Fund (the “Fund”) seeks the highest level of current income that is exempt from federal and Kansas personal income taxes and is consistent with preservation of capital.
This table describes the fees and expenses
that you may pay if you buy, hold, and sell shares of the Fund. You may pay other fees, such as brokerage commissions and other fees
to financial intermediaries, which are not reflected in the tables and examples below.
| Class A Shares | Class I Shares | |
| Maximum Sales Charge (Load) Imposed on Purchases (as a percentage of offering price) | ||
| Maximum Deferred Sales Charge (Load) (as a percentage of the lesser of purchase price or redemption proceeds) | ||
| Maximum Sales Charge (Load) Imposed on Reinvested Dividends | ||
| Redemption Fee Imposed (as a percentage of amount redeemed, if applicable) | ||
| Exchange Fee |
| Management Fees | ||
| Distribution and Service (12b-1) Fees | ||
| Other Expenses | ||
| Total Annual Fund Operating Expenses | ||
| Fee Waivers and Expense Reimbursements(1) | ( | ( |
| Total Annual Fund Operating Expenses After Fee Waivers and Expense Reimbursements(1) | ||
| (1) |
| 1 Year | 3 Years | 5 Years | 10 Years | |
| Redemption | ||||
| Class A | $ |
$ |
$ |
$ |
| Class I | $ |
$ |
$ |
$ |
To pursue its objective, the Fund normally invests at least 80% of its net assets (including any borrowings for investment purposes) in municipal securities that pay interest free from (a) federal income taxes, including the federal alternative minimum tax, and (b) Kansas personal income taxes.
Municipal bonds are debt securities issued by or on behalf of states, territories, and possessions of the United States and their political subdivisions, agencies, authorities, and instrumentalities. The two general classifications of municipal bonds are “general obligation” and “revenue” bonds. General obligation bonds are secured by the issuer’s pledge of its faith, credit, and taxing power for the payment of principal and interest. Revenue bonds are payable only from the revenues derived from a particular facility or class of facilities or, in some cases, from the proceeds of a special excise tax or other specific revenue source.
| Fund Summary – Kansas Municipal Fund Page 1 |
The investment manager actively manages the Fund’s portfolio by selecting securities that it believes will provide the best balance between risk and return within the Fund’s range of allowable investments. The investment manager will consider selling a security with deteriorating credit or limited upside potential compared to other available bonds.
The Fund may invest up to 30% of its net assets in U.S. territorial obligations (including qualifying obligations of Puerto Rico, the U.S. Virgin Islands, and Guam), the interest on which is exempt from federal and Kansas personal income taxes. The Fund may invest up to 20% of its net assets in private activity bonds (which are revenue bonds that finance privately operated facilities), the interest on which is a tax preference item for purposes of the federal alternative minimum tax.
The Fund may invest more than 25% of its net assets in municipal securities that finance similar types of projects, such as education, healthcare, housing, industrial development, transportation, utilities, or pollution control. Economic, business, political, or other changes can affect all securities of a similar type.
All of the municipal securities in which the Fund invests are rated investment grade (BBB- or higher) at the time of purchase by a nationally recognized statistical rating service such as S&P Global Ratings or Moody’s Investors Service, Inc. or are of comparable quality as determined by the Fund’s investment manager. If, subsequent to the purchase of a municipal security, the rating of a municipal security falls below investment grade, the Fund will not be required to dispose of the security.
| Fund Summary – Kansas Municipal Fund Page 2 |
| Fund Summary – Kansas Municipal Fund Page 3 |
| Fund Summary – Kansas Municipal Fund Page 4 |
The following bar chart and table provide some
indication of the risks of investing in the Fund. The Fund’s past performance (before and after taxes) is not necessarily an indication
of how the Fund will perform in the future. Updated performance information is available at

During the ten-year period shown in the bar
chart, the
The table below shows the Fund’s average
annual total returns for 1, 5, and 10 years for Class A shares, and 1 year and since inception for Class I shares, and how they compare
with those of a broad measure of market performance.
(for the periods ended December 31, 2023) | ||||||
| 1 Year | 5 Years | 10 Years | Since Inception | |||
| Class A (Inception date: | ||||||
| Class I (Inception date: | ||||||
| (1) |
Management
Investment Adviser—Viking Fund Management, LLC is the Fund’s investment adviser.
Portfolio Managers—Shannon D. Radke, Senior Portfolio Manager and President of Viking Fund Management, LLC, has served as the Fund’s portfolio manager since November 2010. Josh Larson, Portfolio Manager, has served as the Fund’s portfolio manager since November 2014.
Purchase and Sale of Fund Shares
You may purchase, redeem, or exchange shares of the Fund on any business day, which is any day the New York Stock Exchange is open for business. You may purchase, redeem, or exchange shares of the Fund either through a financial advisor or directly from the Fund.
The minimum initial purchase or exchange into the Fund is $1,000 ($50 for accounts opened through an automatic investment plan account and $250 for an IRA account). The minimum subsequent investment is $50. The Fund may, however, accept investments of smaller initial or subsequent amounts at its discretion. Class I shares are not available for IRAs or employer sponsored IRAs, unless purchased through a fee-based advisory account with a financial intermediary. You may contact the Fund’s transfer agent, Integrity Fund Services, LLC, by mail at PO Box 759, Minot, ND 58702, or by calling 800-601-5593.
| Fund Summary – Kansas Municipal Fund Page 5 |
Tax Information
Distributions of the Fund’s net interest income from tax-exempt securities are generally expected to be exempt from regular federal income tax and Kansas state income tax; however, distributions derived from interest paid on certain “private activity bonds” may be subject to the federal alternative minimum tax. In addition, a portion of the Fund’s distributions may be taxable as ordinary income or capital gains and subject to state and local taxes including Kansas state income tax. The tax treatment of distributions is the same whether you reinvest them in additional Fund shares or receive them in cash.
Payments to Broker-Dealers and Other Financial Intermediaries
If you purchase the Fund through a broker-dealer or other financial intermediary (such as a bank), the Fund and its related companies may pay the intermediary for the sale of Fund shares and related services. These payments may create a conflict of interest by influencing the broker-dealer or other intermediary and your salesperson to recommend the Fund over another investment. Ask your salesperson or visit your financial intermediary’s website for more information.
| Fund Summary – Kansas Municipal Fund Page 6 |
The Maine Municipal Fund (the “Fund”) seeks the highest level of current income that is exempt from federal and Maine personal income taxes and is consistent with preservation of capital.
This table describes the fees and expenses
that you may pay if you buy, hold, and sell shares of the Fund. You may pay other fees, such as brokerage commissions and other fees
to financial intermediaries, which are not reflected in the tables and examples below.
| Class A Shares | Class I Shares | |
| Maximum Sales Charge (Load) Imposed on Purchases (as a percentage of offering price) | ||
| Maximum Deferred Sales Charge (Load) (as a percentage of the lesser of purchase price or redemption proceeds) | ||
| Maximum Sales Charge (Load) Imposed on Reinvested Dividends | ||
| Redemption Fee Imposed (as a percentage of amount redeemed, if applicable) | ||
| Exchange Fee |
| Management Fees | ||
| Distribution and Service (12b-1) Fees | ||
| Other Expenses | ||
| Total Annual Fund Operating Expenses | ||
| Fee Waivers and Expense Reimbursements(1) | ( | ( |
| Total Annual Fund Operating Expenses After Fee Waivers and Expense Reimbursements(1) | ||
| (1) |
| 1 Year | 3 Years | 5 Years | 10 Years | |
| Redemption | ||||
| Class A | $ |
$ |
$ |
$ |
| Class I | $ |
$ |
$ |
$ |
To pursue its objective, the Fund normally invests at least 80% of its net assets (including any borrowings for investment purposes) in municipal securities that pay interest free from (a) federal income taxes, including the federal alternative minimum tax, and (b) Maine personal income taxes.
Municipal bonds are debt securities issued by or on behalf of states, territories, and possessions of the United States and their political subdivisions, agencies, authorities, and instrumentalities. The two general classifications of municipal bonds are “general obligation” and “revenue” bonds. General obligation bonds are secured by the issuer’s pledge of its faith, credit, and taxing power for the payment of principal and interest. Revenue bonds are payable only from the revenues derived from a particular facility or class of facilities or, in some cases, from the proceeds of a special excise tax or other specific revenue source.
| Fund Summary – Maine Municipal Fund Page 7 |
The investment manager actively manages the Fund’s portfolio by selecting securities that it believes will provide the best balance between risk and return within the Fund’s range of allowable investments. The investment manager will consider selling a security with deteriorating credit or limited upside potential compared to other available bonds.
The Fund may invest up to 30% of its net assets in U.S. territorial obligations (including qualifying obligations of Puerto Rico, the U.S. Virgin Islands, and Guam), the interest on which is exempt from federal and Maine personal income taxes. The Fund may invest up to 20% of its net assets in private activity bonds (which are revenue bonds that finance privately operated facilities), the interest on which is a tax preference item for purposes of the federal alternative minimum tax.
The Fund may invest more than 25% of its net assets in municipal securities that finance similar types of projects, such as education, healthcare, housing, industrial development, transportation, utilities, or pollution control. Economic, business, political, or other changes can affect all securities of a similar type.
All of the municipal securities in which the Fund invests are rated investment grade (BBB- or higher) at the time of purchase by a nationally recognized statistical rating service such as S&P Global Ratings or Moody’s Investors Service, Inc. or are of comparable quality as determined by the Fund’s investment manager. If, subsequent to the purchase of a municipal security, the rating of a municipal security falls below investment grade, the Fund will not be required to dispose of the security.
The Fund is non-diversified and therefore may invest a greater percentage of its assets in securities of a more limited number of issuers compared to a diversified mutual fund.
| Fund Summary – Maine Municipal Fund Page 8 |
| Fund Summary – Maine Municipal Fund Page 9 |
| Fund Summary – Maine Municipal Fund Page 10 |
The following bar chart and table provide some
indication of the risks of investing in the Fund.

During the ten-year period shown in the bar
chart, the
The table below shows the Fund’s average
annual total returns for 1, 5, and 10 years for Class A shares, and 1 year and since inception for Class I shares, and how they compare
with those of a broad measure of market performance.
(for the periods ended December 31, 2023) | ||||||
| 1 Year | 5 Years | 10 Years | Since Inception | |||
| Class A (Inception date: | ||||||
| - | ||||||
| - | ||||||
| Class
I (Inception date: | ||||||
| (1) |
Management
Investment Adviser—Viking Fund Management, LLC is the Fund’s investment adviser.
Portfolio Managers—Shannon D. Radke, Senior Portfolio Manager and President of Viking Fund Management, LLC, has served as the Fund’s portfolio manager since November 2010. Josh Larson, Portfolio Manager, has served as the Fund’s portfolio manager since November 2014.
| Fund Summary – Maine Municipal Fund Page 11 |
Purchase and Sale of Fund Shares
You may purchase, redeem, or exchange shares of the Fund on any business day, which is any day the New York Stock Exchange is open for business. You may purchase, redeem, or exchange shares of the Fund either through a financial advisor or directly from the Fund.
The minimum initial purchase or exchange into the Fund is $1,000 ($50 for accounts opened through an automatic investment plan account and $250 for an IRA account). The minimum subsequent investment is $50. The Fund may, however, accept investments of smaller initial or subsequent amounts at its discretion. Class I shares are not available for IRAs or employer sponsored IRAs, unless purchased through a fee-based advisory account with a financial intermediary. You may contact the Fund’s transfer agent, Integrity Fund Services, LLC, by mail at PO Box 759, Minot, ND 58702, or by calling 800-601-5593.
Tax Information
Distributions of the Fund’s net interest income from tax-exempt securities are generally expected to be exempt from regular federal income tax and Maine state income tax; however, distributions derived from interest paid on certain “private activity bonds” may be subject to the federal alternative minimum tax. In addition, a portion of the Fund’s distributions may be taxable as ordinary income or capital gains and subject to state and local taxes including Maine state income tax. The tax treatment of distributions is the same whether you reinvest them in additional Fund shares or receive them in cash.
Payments to Broker-Dealers and Other Financial Intermediaries
If you purchase the Fund through a broker-dealer or other financial intermediary (such as a bank), the Fund and its related companies may pay the intermediary for the sale of Fund shares and related services. These payments may create a conflict of interest by influencing the broker-dealer or other intermediary and your salesperson to recommend the Fund over another investment. Ask your salesperson or visit your financial intermediary’s website for more information.
| Fund Summary – Maine Municipal Fund Page 12 |
The Nebraska Municipal Fund (the “Fund”) seeks the highest level of current income that is exempt from federal and Nebraska personal income taxes and is consistent with preservation of capital.
This table describes the fees and expenses
that you may pay if you buy, hold, and sell shares of the Fund. You may pay other fees, such as brokerage commissions and other fees
to financial intermediaries, which are not reflected in the tables and examples below.
| Class A Shares | Class I Shares | |
| Maximum Sales Charge (Load) Imposed on Purchases (as a percentage of offering price) | ||
| Maximum Deferred Sales Charge (Load) (as a percentage of the lesser of purchase price or redemption proceeds) | ||
| Maximum Sales Charge (Load) Imposed on Reinvested Dividends | ||
| Redemption Fee Imposed (as a percentage of amount redeemed, if applicable) | ||
| Exchange Fee |
| Management Fees | ||
| Distribution and Service (12b-1) Fees | ||
| Other Expenses | ||
| Total Annual Fund Operating Expenses | ||
| Fee Waivers and Expense Reimbursements(1) | ( | ( |
| Total Annual Fund Operating Expenses After Fee Waivers and Expense Reimbursements(1) | ||
| (1) |
| 1 Year | 3 Years | 5 Years | 10 Years | |
| Redemption | ||||
| Class A | $ |
$ |
$ |
$ |
| Class I | $ |
$ |
$ |
$ |
To pursue its objective, the Fund normally invests at least 80% of its net assets (including any borrowings for investment purposes) in municipal securities that pay interest free from (a) federal income taxes, including the federal alternative minimum tax, and (b) Nebraska personal income taxes.
Municipal bonds are debt securities issued by or on behalf of states, territories, and possessions of the United States and their political subdivisions, agencies, authorities, and instrumentalities. The two general classifications of municipal bonds are “general obligation” and “revenue” bonds. General obligation bonds are secured by the issuer’s pledge of its faith, credit, and taxing power for the payment of principal and interest. Revenue bonds are payable only from the revenues derived from a particular facility or class of facilities or, in some cases, from the proceeds of a special excise tax or other specific revenue source.
| Fund Summary – Nebraska Municipal Fund Page 13 |
The investment manager actively manages the Fund’s portfolio by selecting securities that it believes will provide the best balance between risk and return within the Fund’s range of allowable investments. The investment manager will consider selling a security with deteriorating credit or limited upside potential compared to other available bonds.
The Fund may invest up to 30% of its net assets in U.S. territorial obligations (including qualifying obligations of Puerto Rico, the U.S. Virgin Islands, and Guam), the interest on which is exempt from federal and Nebraska personal income taxes. The Fund may invest up to 20% of its net assets in private activity bonds (which are revenue bonds that finance privately operated facilities), the interest on which is a tax preference item for purposes of the federal alternative minimum tax.
The Fund may invest more than 25% of its net assets in municipal securities that finance similar types of projects, such as education, healthcare, housing, industrial development, transportation, utilities, or pollution control. Economic, business, political, or other changes can affect all securities of a similar type.
All of the municipal securities in which the Fund invests are rated investment grade (BBB- or higher) at the time of purchase by a nationally recognized statistical rating service such as S&P Global Ratings or Moody’s Investors Service, Inc. or are of comparable quality as determined by the Fund’s investment manager. If, subsequent to the purchase of a municipal security, the rating of a municipal security falls below investment grade, the Fund will not be required to dispose of the security.
The Fund is non-diversified and therefore may invest a greater percentage of its assets in securities of a more limited number of issuers compared to a diversified mutual fund.
| Fund Summary – Nebraska Municipal Fund Page 14 |
| Fund Summary – Nebraska Municipal Fund Page 15 |
| Fund Summary – Nebraska Municipal Fund Page 16 |
The following bar chart and table provide
some indication of the risks of investing in the Fund.

During the ten-year period shown in the bar
chart, the
The table below shows the Fund’s average
annual total returns for 1, 5, and 10 years for Class A shares, and 1 year and since inception for Class I shares, and how they compare
with those of a broad measure of market performance. The return information below reflects applicable sales charges.
(for the periods ended December 31, 2023) | ||||||
| 1 Year | 5 Years | 10 Years | Since Inception | |||
| Class A (Inception date: | ||||||
| Class I (Inception date: | ||||||
| (1) |
Management
Investment Adviser—Viking Fund Management, LLC is the Fund’s investment adviser.
Portfolio Managers—Shannon D. Radke, Senior Portfolio Manager and President of Viking Fund Management, LLC, has served as the Fund’s portfolio manager since November 2010. Josh Larson, Portfolio Manager, has served as the Fund’s portfolio manager since November 2014.
| Fund Summary – Nebraska Municipal Fund Page 17 |
Purchase and Sale of Fund Shares
You may purchase, redeem, or exchange shares of the Fund on any business day, which is any day the New York Stock Exchange is open for business. You may purchase, redeem, or exchange shares of the Fund either through a financial advisor or directly from the Fund.
The minimum initial purchase or exchange into the Fund is $1,000 ($50 for accounts opened through an automatic investment plan account and $250 for an IRA account). The minimum subsequent investment is $50. The Fund may, however, accept investments of smaller initial or subsequent amounts at its discretion. Class I shares are not available for IRAs or employer sponsored IRAs, unless purchased through a fee-based advisory account with a financial intermediary. You may contact the Fund’s transfer agent, Integrity Fund Services, LLC, by mail at PO Box 759, Minot, ND 58702, or by calling 800-601-5593.
Tax Information
Distributions of the Fund’s net interest income from tax-exempt securities are generally expected to be exempt from regular federal income tax and Nebraska state income tax; however, distributions derived from interest paid on certain “private activity bonds” may be subject to the federal alternative minimum tax. In addition, a portion of the Fund’s distributions may be taxable as ordinary income or capital gains and subject to state and local taxes including Nebraska state income tax. The tax treatment of distributions is the same whether you reinvest them in additional Fund shares or receive them in cash.
Payments to Broker-Dealers and Other Financial Intermediaries
If you purchase the Fund through a broker-dealer or other financial intermediary (such as a bank), the Fund and its related companies may pay the intermediary for the sale of Fund shares and related services. These payments may create a conflict of interest by influencing the broker-dealer or other intermediary and your salesperson to recommend the Fund over another investment. Ask your salesperson or visit your financial intermediary’s website for more information.
| Fund Summary – Nebraska Municipal Fund Page 18 |
The Oklahoma Municipal Fund (the “Fund”) seeks the highest level of current income that is exempt from federal and Oklahoma personal income taxes and is consistent with the preservation of capital.
This table describes the fees and expenses
that you may pay if you buy, hold, and sell shares of the Fund. You may pay other fees, such as brokerage commissions and other fees
to financial intermediaries, which are not reflected in the tables and examples below.
| Class A Shares | Class I Shares | |
| Maximum Sales Charge (Load) Imposed on Purchases (as a percentage of offering price) | ||
| Maximum Deferred Sales Charge (Load) (as a percentage of the lesser of purchase price or redemption proceeds) | ||
| Maximum Sales Charge (Load) Imposed on Reinvested Dividends | ||
| Redemption Fee Imposed (as a percentage of amount redeemed, if applicable) | ||
| Exchange Fee |
| Management Fees | ||
| Distribution and Service (12b-1) Fees | ||
| Other Expenses | ||
| Total Annual Fund Operating Expenses | ||
| Fee Waivers and Expense Reimbursements(1) | ( | ( |
| Total Annual Fund Operating Expenses After Fee Waivers and Expense Reimbursements(1) | ||
| (1) |
| 1 Year | 3 Years | 5 Years | 10 Years | |
| Redemption | ||||
| Class A | $ |
$ |
$ |
$ |
| Class I | $ |
$ |
$ |
$ |
To pursue its objective, the Fund normally invests at least 80% of its net assets (including any borrowings for investment purposes) in municipal securities that pay interest free from (a) federal income taxes, including the federal alternative minimum tax, and (b) Oklahoma personal income taxes.
Municipal bonds are debt securities issued by or on behalf of states, territories, and possessions of the United States and their political subdivisions, agencies, authorities, and instrumentalities. The two general classifications of municipal bonds are “general obligation” and “revenue” bonds. General obligation bonds are secured by the issuer’s pledge of its faith, credit, and taxing power for the payment of principal and interest. Revenue bonds are payable only from the revenues derived from a particular facility or class of facilities or, in some cases, from the proceeds of a special excise tax or other specific revenue source.
| Fund Summary – Oklahoma Municipal Fund Page 19 |
The investment manager actively manages the Fund’s portfolio by selecting securities that it believes will provide the best balance between risk and return within the Fund’s range of allowable investments. The investment manager will consider selling a security with deteriorating credit or limited upside potential compared to other available bonds.
The Fund may invest up to 30% of its net assets in U.S. territorial obligations (including qualifying obligations of Puerto Rico, the U.S. Virgin Islands, and Guam), the interest on which is exempt from federal and Oklahoma personal income taxes. The Fund may invest up to 20% of its net assets in private activity bonds (which are revenue bonds that finance privately operated facilities), the interest on which is a tax preference item for purposes of the federal alternative minimum tax.
The Fund may invest more than 25% of its net assets in municipal securities that finance similar types of projects, such as education, healthcare, housing, industrial development, transportation, utilities, or pollution control. Economic, business, political, or other changes can affect all securities of a similar type.
All of the municipal securities in which the Fund invests are rated investment grade (BBB- or higher) at the time of purchase by a nationally recognized statistical rating service such as S&P Global Ratings or Moody’s Investors Service, Inc. or are of comparable quality as determined by the Fund’s investment manager. If, subsequent to the purchase of a municipal security, the rating of a municipal security falls below investment grade, the Fund will not be required to dispose of the security.
| Fund Summary – Oklahoma Municipal Fund Page 20 |
| Fund Summary – Oklahoma Municipal Fund Page 21 |
| Fund Summary – Oklahoma Municipal Fund Page 22 |
The following bar chart and table provide some
indication of the risks of investing in the Fund.
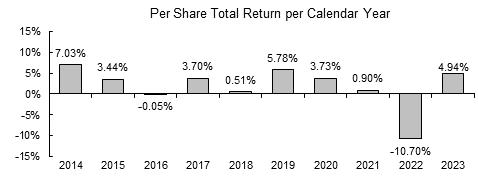
During the ten-year period shown in the bar
chart, the
The table below shows the Fund’s average
annual total returns for 1, 5, and 10 years for Class A shares, and 1 year and since inception for Class I shares, and how they compare
with those of a broad measure of market performance.
(for the periods ended December 31, 2023) | ||||||
| 1 Year | 5 Years | 10 Years | Since Inception | |||
| Class A (Inception date: | ||||||
| Class I (Inception date: | ||||||
| (1) |
Management
Investment Adviser—Viking Fund Management, LLC is the Fund’s investment adviser.
Portfolio Managers—Shannon D. Radke, Senior Portfolio Manager and President of Viking Fund Management, LLC, has served as the Fund’s portfolio manager since November 2010. Josh Larson, Portfolio Manager, has served as the Fund’s portfolio manager since November 2014.
| Fund Summary – Oklahoma Municipal Fund Page 23 |
Purchase and Sale of Fund Shares
You may purchase, redeem, or exchange shares of the Fund on any business day, which is any day the New York Stock Exchange is open for business. You may purchase, redeem, or exchange shares of the Fund either through a financial advisor or directly from the Fund.
The minimum initial purchase or exchange into the Fund is $1,000 ($50 for accounts opened through an automatic investment plan account and $250 for an IRA account). The minimum subsequent investment is $50. The Fund may, however, accept investments of smaller initial or subsequent amounts at its discretion. Class I shares are not available for IRAs or employer sponsored IRAs, unless purchased through a fee-based advisory account with a financial intermediary. You may contact the Fund’s transfer agent, Integrity Fund Services, LLC, by mail at PO Box 759, Minot, ND 58702, or by calling 800-601-5593.
Tax Information
Distributions of the Fund’s net interest income from tax-exempt securities are generally expected to be exempt from regular federal income tax and Oklahoma state income tax; however, distributions derived from interest paid on certain “private activity bonds” may be subject to the federal alternative minimum tax. In addition, a portion of the Fund’s distributions may be taxable as ordinary income or capital gains and subject to state and local taxes including Oklahoma state income tax. The tax treatment of distributions is the same whether you reinvest them in additional Fund shares or receive them in cash.
Payments to Broker-Dealers and Other Financial Intermediaries
If you purchase the Fund through a broker-dealer or other financial intermediary (such as a bank), the Fund and its related companies may pay the intermediary for the sale of Fund shares and related services. These payments may create a conflict of interest by influencing the broker-dealer or other intermediary and your salesperson to recommend the Fund over another investment. Ask your salesperson or visit your financial intermediary’s website for more information.
| Fund Summary – Oklahoma Municipal Fund Page 24 |
The Viking Tax-Free Fund for Montana (the “Fund”) seeks the highest level of current income that is exempt from federal and Montana personal income taxes and is consistent with preservation of capital.
This table describes the fees and expenses
that you may pay if you buy, hold, and sell shares of the Fund.
| Class A Shares | Class I Shares | |
| Maximum Sales Charge (Load) Imposed on Purchases (as a percentage of offering price) | ||
| Maximum Deferred Sales Charge (Load) (as a percentage of the lesser of purchase price or redemption proceeds) | ||
| Maximum Sales Charge (Load) Imposed on Reinvested Dividends | ||
| Redemption Fee Imposed (as a percentage of amount redeemed, if applicable) | ||
| Exchange Fee |
| Management Fees | ||
| Distribution and Service (12b-1) Fees | ||
| Other Expenses | ||
| Total Annual Fund Operating Expenses | ||
| Fee Waivers and Expense Reimbursements(1) | ( | ( |
| Total Annual Fund Operating Expenses After Fee Waivers and Expense Reimbursements(1) | ||
| (1) |
| 1 Year | 3 Years | 5 Years | 10 Years | |
| Redemption | ||||
| Class A | $ |
$ |
$ |
$ |
| Class I | $ |
$ |
$ |
$ |
To pursue its objective, the Fund normally invests at least 80% of its net assets (including any borrowings for investment purposes) in municipal securities that pay interest free from (a) federal income taxes, including the federal alternative minimum tax, and (b) Montana personal income taxes.
Municipal bonds are debt securities issued by or on behalf of states, territories, and possessions of the United States and their political subdivisions, agencies, authorities, and instrumentalities. The two general classifications of municipal bonds are “general obligation” and “revenue” bonds. General obligation bonds are secured by the issuer’s pledge of its faith, credit, and taxing power for the payment of principal and interest. Revenue bonds are payable only from the revenues derived from a particular facility or class of facilities or, in some cases, from the proceeds of a special excise tax or other specific revenue source.
| Fund Summary – Viking Tax-Free Fund for Montana Page 25 |
The investment manager actively manages the Fund’s portfolio by selecting securities that it believes will provide the best balance between risk and return within the Fund’s range of allowable investments. The investment manager will consider selling a security with deteriorating credit or limited upside potential compared to other available bonds.
The Fund may invest up to 30% of its net assets in U.S. territorial obligations (including qualifying obligations of Puerto Rico, the U.S. Virgin Islands, and Guam), the interest on which is exempt from federal and Montana personal income taxes. The Fund may invest up to 20% of its net assets in private activity bonds (which are revenue bonds that finance privately operated facilities), the interest on which is a tax preference item for purposes of the federal alternative minimum tax.
The Fund may invest more than 25% of its net assets in municipal securities that finance similar types of projects, such as education, healthcare, housing, industrial development, transportation, utilities, or pollution control. Economic, business, political, or other changes that affect a type of project can similarly affect all securities of a similar type related to these projects. The Fund is non-diversified. This means that the Fund may invest a larger percentage of its assets in more limited number of issuers than a diversified fund.
All of the municipal securities in which the Fund invests are rated investment grade (BBB- or higher) at the time of purchase by a nationally recognized statistical rating organization such as S&P Global Ratings or Moody’s Investors Service, Inc. or are of comparable quality as determined by the Fund’s investment manager. If, subsequent to the purchase of a municipal security, the rating of a municipal security falls below investment grade, the Fund will not be required to dispose of the security.
| Fund Summary – Viking Tax-Free Fund for Montana Page 26 |
| Fund Summary – Viking Tax-Free Fund for Montana Page 27 |
| Fund Summary – Viking Tax-Free Fund for Montana Page 28 |
The following bar chart and table provide
some indication of the risks of investing in the Fund.
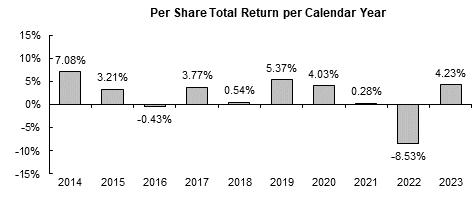
During the ten-year period shown in the bar
chart, the
The table below shows the Fund’s average
annual total returns for 1, 5, and 10 years for Class A shares, and for 1, and 5 year and since inception for Class I shares, and how
they compare with those of a broad measure of market performance.
| Average Annual Total Returns (for the periods ended December 31, 2023) | ||||||
| 1 Year | 5 Years | 10 Years | Since Inception | |||
| Class A (Inception date: | ||||||
| Class I (Inception date: | ||||||
| (1) |
Management
Investment Adviser—Viking Fund Management, LLC is the Fund’s investment adviser.
Portfolio Managers—Shannon D. Radke, Senior Portfolio Manager and President of Viking Fund Management, LLC, has served as the Fund’s portfolio manager since its inception in August 1999. Josh Larson, Portfolio Manager, has served as the Fund’s portfolio manager since April 2015.
Purchase and Sale of Fund Shares
You may purchase, redeem, or exchange shares of the Fund on any business day, which is any day the New York Stock Exchange is open for business. You may purchase, redeem, or exchange shares of the Fund either through a financial advisor or directly from the Fund.
| Fund Summary – Viking Tax-Free Fund for Montana Page 29 |
The minimum initial purchase or exchange into the Fund is $1,000 ($50 for accounts opened through an automatic investment plan account and $250 for an IRA account). The minimum subsequent investment is $50. The Fund may, however, accept investments of smaller initial or subsequent amounts at its discretion. Class I shares are not available for IRAs or employer sponsored IRAs, unless purchased through a fee-based advisory account with a financial intermediary. You may contact the Fund’s transfer agent, Integrity Fund Services, LLC, by mail at PO Box 759, Minot, ND 58702, or by calling 800-601-5593.
Tax Information
Distributions of the Fund’s net interest income from tax-exempt securities are generally expected to be exempt from regular federal income tax and Montana state income tax; however, distributions derived from interest paid on certain “private activity bonds” may be subject to the federal alternative minimum tax. In addition, a portion of the Fund’s distributions may be taxable as ordinary income or capital gains and subject to state and local taxes including Montana state income tax. The tax treatment of distributions is the same whether you reinvest them in additional Fund shares or receive them in cash.
Payments to Broker-Dealers and Other Financial Intermediaries
If you purchase the Fund through a broker-dealer or other financial intermediary (such as a bank), the Fund and its related companies may pay the intermediary for the sale of Fund shares and related services. These payments may create a conflict of interest by influencing the broker-dealer or other intermediary and your salesperson to recommend the Fund over another investment. Ask your salesperson or visit your financial intermediary’s website for more information.
| Fund Summary – Viking Tax-Free Fund for Montana Page 30 |
The Viking Tax-Free Fund for North Dakota (the “Fund”) seeks the highest level of current income that is exempt from federal and North Dakota personal income taxes and is consistent with preservation of capital.
This table describes the fees and expenses
that you may pay if you buy, hold, and sell shares of the Fund. You may pay other fees, such as brokerage commissions and other fees
to financial intermediaries, which are not reflected in the tables and examples below.
| Class A Shares | Class I Shares | |
| Maximum Sales Charge (Load) Imposed on Purchases (as a percentage of offering price) | ||
| Maximum Deferred Sales Charge (Load) (as a percentage of the lesser of purchase price or redemption proceeds) | ||
| Maximum Sales Charge (Load) Imposed on Reinvested Dividends | ||
| Redemption Fee Imposed (as a percentage of amount redeemed, if applicable) | ||
| Exchange Fee |
| Management Fees | ||
| Distribution and Service (12b-1) Fees | ||
| Other Expenses | ||
| Total Annual Fund Operating Expenses | ||
| Fee Waivers and Expense Reimbursements(1) | ( | ( |
| Total Annual Fund Operating Expenses After Fee Waivers and Expense Reimbursements(1) | ||
| (1) |
| 1 Year | 3 Years | 5 Years | 10 Years | |
| Redemption | ||||
| Class A | $ |
$ |
$ |
$ |
| Class I | $ |
$ |
$ |
$ |
To pursue its objective, the Fund normally invests at least 80% of its net assets (including any borrowings for investment purposes) in municipal securities that pay interest free from (a) federal income taxes, including the federal alternative minimum tax, and (b) North Dakota personal income taxes.
Municipal bonds are debt securities issued by or on behalf of states, territories, and possessions of the United States and their political subdivisions, agencies, authorities, and instrumentalities. The two general classifications of municipal bonds are “general obligation” and “revenue” bonds. General obligation bonds are secured by the issuer’s pledge of its faith, credit, and taxing power for the payment of principal and interest. Revenue bonds are payable only from the revenues derived from a particular facility or class of facilities or, in some cases, from the proceeds of a special excise tax or other specific revenue source.
| Fund Summary – Viking Tax-Free Fund for North Dakota Page 31 |
The investment manager actively manages the Fund’s portfolio by selecting securities that it believes will provide the best balance between risk and return within the Fund’s range of allowable investments. The investment manager will consider selling a security with deteriorating credit or limited upside potential compared to other available bonds.
The Fund may invest up to 30% of its net assets in U.S. territorial obligations (including qualifying obligations of Puerto Rico, the U.S. Virgin Islands, and Guam), the interest on which is exempt from federal and North Dakota personal income taxes. The Fund may invest up to 20% of its net assets in private activity bonds (which are revenue bonds that finance privately operated facilities), the interest on which is a tax preference item for purposes of the federal alternative minimum tax.
The Fund may invest more than 25% of its net assets in municipal securities that finance similar types of projects, such as education, healthcare, housing, industrial development, transportation, utilities, or pollution control. Economic, business, political, or other changes that affect a type of project can similarly affect all securities of a similar type related to these projects. The Fund is non-diversified. This means that the Fund may invest a larger percentage of its assets in more limited number of issuers than a diversified fund.
All of the municipal securities in which the Fund invests are rated investment grade (BBB- or higher) at the time of purchase by a nationally recognized statistical rating organization such as S&P Global Ratings or Moody’s Investors Service, Inc. or are of comparable quality as determined by the Fund’s investment manager. If, subsequent to the purchase of a municipal security, the rating of a municipal security falls below investment grade, the Fund will not be required to dispose of the security.
| Fund Summary – Viking Tax-Free Fund for North Dakota Page 32 |
| Fund Summary – Viking Tax-Free Fund for North Dakota Page 33 |
| Fund Summary – Viking Tax-Free Fund for North Dakota Page 34 |
The following bar chart and table provide
some indication of the risks of investing in the Fund.
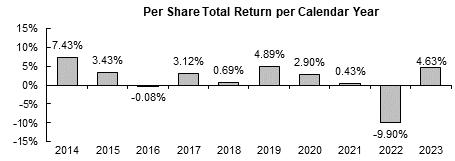
During the ten-year period shown in the bar
chart, the
The table below shows the Fund’s average
annual total returns for 1, 5, and 10 years for Class A shares, and for 1, and 5 year and since inception for Class I shares, and how
they compare with those of a broad measure of market performance.
(for the periods ended December 31, 2023) | ||||||
| 1 Year | 5 Years | 10 Years | Since Inception | |||
| Class A (Inception date: | ||||||
| - | ||||||
| - | ||||||
| Class I (Inception date: | ||||||
| (1) |
Management
Investment Adviser —Viking Fund Management, LLC is the Fund’s investment adviser.
Portfolio Managers —Shannon D. Radke, Senior Portfolio Manager and President of Viking Fund Management, LLC, has served as the Fund’s portfolio manager since its inception in August 1999. Josh Larson, Portfolio Manager, has served as the Fund’s portfolio manager since April 2015.
Purchase and Sale of Fund Shares
You may purchase, redeem, or exchange shares of the Fund on any business day, which is any day the New York Stock Exchange is open for business. You may purchase, redeem, or exchange shares of the Fund either through a financial advisor or directly from the Fund.
The minimum initial purchase or exchange into the Fund is $1,000 ($50 for accounts opened through an automatic investment plan account and $250 for an IRA account). The minimum subsequent investment is $50. The Fund may, however, accept investments of smaller initial or subsequent amounts at its discretion. Class I shares are not available for IRAs or employer sponsored IRAs, unless purchased through a fee-based advisory account with a financial intermediary. You may contact the Fund’s transfer agent, Integrity Fund Services, LLC, by mail at PO Box 759, Minot, ND 58702, or by calling 800-601-5593.
| Fund Summary – Viking Tax-Free Fund for North Dakota Page 35 |
Tax Information
Distributions of the Fund’s net interest income from tax-exempt securities are generally expected to be exempt from regular federal income tax and North Dakota state income tax; however, distributions derived from interest paid on certain “private activity bonds” may be subject to the federal alternative minimum tax. In addition, a portion of the Fund’s distributions may be taxable as ordinary income or capital gains and subject to state and local taxes including North Dakota state income tax. The tax treatment of distributions is the same whether you reinvest them in additional Fund shares or receive them in cash.
Payments to Broker-Dealers and Other Financial Intermediaries
If you purchase the Fund through a broker-dealer or other financial intermediary (such as a bank), the Fund and its related companies may pay the intermediary for the sale of Fund shares and related services. These payments may create a conflict of interest by influencing the broker-dealer or other intermediary and your salesperson to recommend the Fund over another investment. Ask your salesperson or visit your financial intermediary’s website for more information.
| Fund Summary – Viking Tax-Free Fund for North Dakota Page 36 |
ADDITIONAL INFORMATION ABOUT THE FUNDS
Investment Objectives and Policies
The Kansas Municipal Fund (the “Kansas Fund”) seeks the highest level of current income that is exempt from federal and Kansas personal income taxes and is consistent with preservation of capital.
The Maine Municipal Fund (the “Maine Fund”) seeks the highest level of current income that is exempt from federal and Maine personal income taxes and is consistent with preservation of capital.
The Nebraska Municipal Fund (the “Nebraska Fund”) seeks the highest level of current income that is exempt from federal and Nebraska personal income taxes and is consistent with preservation of capital.
The Oklahoma Municipal Fund (the “Oklahoma Fund”) seeks the highest level of current income that is exempt from federal and Oklahoma personal income taxes and is consistent with preservation of capital.
The Viking Tax-Free Fund for Montana (the “Montana Fund”) seeks the highest level of current income that is exempt from federal and Montana personal income taxes and is consistent with preservation of capital.
The Viking Tax-Free Fund for North Dakota (the “North Dakota Fund”) seeks the highest level of current income that is exempt from federal and North Dakota personal income taxes and is consistent with preservation of capital.
The Kansas Fund, Maine Fund, Nebraska Fund, Oklahoma Fund, Montana Fund, and North Dakota Fund are each referred to herein as a “Fund” and collectively as the “Funds.” Each Fund’s investment objective is a fundamental investment policy. A Fund’s fundamental investment policy cannot be changed without the consent of the holders of a majority of that Fund’s outstanding shares. Please see the Statement of Additional Information (“SAI”) for additional fundamental policies and related information applicable to the Funds.
Temporary Defensive Positions
During unusual market or other conditions, a Fund may temporarily depart from its investment objective and invest up to 100% of its assets in short-term U.S. Government obligations, cash, and cash equivalents. During such times, the Fund may be unable to pursue its investment objective. In addition, interest on these short-term investments may be taxable.
Principal Risks
Risk is inherent in all investing. Investing in the Funds involves risk, including the risk that you may receive little or no return on your investment or that you may even lose part or all of your investment. An investment in the Funds is not a deposit of a bank and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other government agency. Before you invest in a Fund, you should consider its principal risks. Below is additional information about certain of the principal risks that are described in the Fund Summaries:
General Market Risk: Each Fund’s net asset value, yield and total return will fluctuate based upon changes in the value of its portfolio securities. The market value of securities in which a Fund invests is based upon the market’s perception of the underlying value and is not necessarily an objective measure of the securities’ values. The value of a security or other asset may decline due to changes in general market conditions, economic trends or events that are not specifically related to the issuer of the security or other asset, including factors that affect certain countries, regions, markets, or sectors to which the issuer is not directly exposed. Local, regional or global events such as war, acts of terrorism, the spread of infectious illness or other public health issue, natural disasters, climate change and climate related events, international conflicts, recessions, or other events could have a significant impact on the portfolio and its investments. The occurrence of global events similar to those in recent years may result in market volatility and may have long term effects on both the U.S. and global financial markets. There is no assurance that a Fund will achieve its investment objective. An investment in a Fund is not by itself a complete or balanced investment program.
Non-Diversified Fund Risk: Each Fund, except the Kansas Fund and Oklahoma Fund, is non-diversified and as such, may invest a relatively high percentage of its assets in the securities of a single issuer. As a result, the Funds are exposed to greater market risk, as their portfolio securities may be more susceptible to any single economic, business, political, or regulatory occurrence than the portfolio securities of a diversified fund.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 37 |
In addition, because of the relatively small number of issuers of municipal securities in the respective state, the Funds are more likely to invest a higher percentage of their assets in the securities of a single issuer than an investment company that invests in a broad range of tax-exempt securities. As a result, the Funds are subject to greater risks of loss if an issuer is unable to make interest or principal payments or if the market value of such securities declines.
Each Fund also may invest in the securities of issuers of municipal securities in U.S. territories and possessions. As a result, to the extent they invest in such securities, the Funds will be more susceptible to economic, political, or regulatory developments that could adversely affect issuers in a U.S. territory or possession and therefore the value of the Funds’ portfolios.
Municipal Securities Risk: The market values of municipal securities may decline, at times sharply and unpredictably. Market values of municipal securities are affected by a number of different factors, including tax, legislative and political changes, changes in interest rates, the credit quality of municipal securities issuers, and general economic and market conditions. Adverse conditions in an industry significant to a local economy could have a correspondingly adverse effect on the financial condition of local issuers. Other factors that could affect municipal securities include a change in the local, state or national economy, demographic factors, ecological or environmental concerns, statutory limitations on an issuer’s ability to increase taxes, and other developments generally affecting the revenue of issuers (for example, legislation or court decisions reducing state aid to local governments or mandating additional services). Lower-quality municipal securities may suffer larger price declines and more volatility than higher-quality municipal securities in response to negative issuer-specific developments or general economic news. During times of low demand or decreased liquidity in the municipal securities market, prices of municipal securities, particularly lower-quality municipal securities, may decline sharply, without regard to changes in interest rates or issuer-specific credit-related events. Such periods of decreased liquidity may occur when dealers that make a market in municipal securities are unable or unwilling to do so, particularly during periods of economic or financial distress.
Single State Risks: Because each Fund invests a significant portion of its assets in the securities of issuers located in a given state or U.S. territory or possession, it will be disproportionately affected by political and economic conditions and developments in that state, territory or possession. In addition, economic, political or regulatory changes in that state, territory or possession could adversely affect municipal bond issuers in that state, territory or possession and therefore the value of a Fund’s investment portfolio.
The Funds may invest in bonds of municipal issuers located in Puerto Rico. In recent years, municipal securities issued by Puerto Rico and its agencies and instrumentalities have been subject to multiple credit downgrades as a result of Puerto Rico’s ongoing fiscal challenges and uncertainty about the ability to make full repayment on these obligations. More recently, certain issuers of Puerto Rican municipal securities have failed to make payments on obligations that have come due, and additional missed payments or defaults may occur in the future.
For additional information, see Appendix A to the SAI.
Interest Rate Risk: Interest rate risk is the risk that debt securities will decline in value because of changes in interest rates. As nominal interest rates rise, the value of certain debt securities held by the Fund are likely to decrease. Debt securities with longer maturities tend to be more sensitive to changes in interest rates, usually making them more volatile than securities with shorter maturities. Rising interest rates also may lengthen the duration of debt securities with call features, since exercise of the call becomes less likely as interest rates rise, which in turn will make the securities more sensitive to changes in interest rates and result in even steeper price declines in the event of further interest rate increases.
Credit Risk: Credit risk is the possibility that an issuer will be unable to make interest payments or repay principal. Economic downturns often result in reduced levels of taxes collected and revenues earned for municipalities. This, in turn, lessens the financial strength of a municipality and increases the credit risk of the securities it issues.
Generally, lower rated bonds provide higher current income but are considered to carry greater credit risk than higher rated bonds. The ratings of a rating agency represent its opinion as to the credit quality of the debt securities it undertakes to rate and do not evaluate market risk. Ratings are not absolute standards of credit quality; consequently, debt securities with the same maturity, duration, coupon, and rating may have different yields. Rating agencies may fail to make timely changes in credit ratings and an issuer’s current financial condition may be better or worse than a rating indicates.
Cybersecurity Risk: As the use of technology has become more prevalent in the course of business, the Funds have become potentially more susceptible to operational and financial risks through breaches in cybersecurity. These risks include theft, loss, misuse, improper release, corruption and destruction of, or unauthorized access to, confidential or highly restricted data relating to a Fund and its shareholders; and compromises or failures to systems, networks, devices and applications relating to the operations of a Fund and its service providers. Cybersecurity issues may result in, among other things, financial losses to a Fund and its shareholders; the inability of a Fund to transact business with its shareholders or to engage in portfolio transactions; delays or mistakes in the calculation of a Fund’s net asset value or other materials provided to shareholders; the inability to process transactions with shareholders or other parties; violations of privacy and other laws; regulatory fines, penalties and reputational damage; and compliance and remediation costs, legal fees and other expenses. A Fund’s service providers, financial intermediaries, entities in which a Fund invests and parties with which a Fund engages in portfolio or other transactions also may be adversely impacted by cybersecurity risks, resulting in losses to a Fund or its shareholders. There can be no guarantee that any risk management systems established to address and reduce cybersecurity risks will succeed, and the Funds cannot control such systems put in place by service providers, issuers or other third parties whose operations may affect the Funds and/or their shareholders.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 38 |
Valuation Risk: The sales price a Fund could receive for any particular portfolio investment may differ from the Fund’s valuation of the investment, particularly for securities that trade in thin or volatile markets or that are valued using a fair value methodology. Investors who purchase or redeem Fund shares on days when a Fund is holding fair-valued securities may receive fewer or more shares or lower or higher redemption proceeds than they would have received if the Fund had not fair-valued the security or had used a different valuation methodology.
Tax Risk: Tax risk is the risk that income from municipal securities held by a Fund could be declared taxable because of, for example, unfavorable changes in tax laws, adverse interpretations by the Internal Revenue Service or state tax authorities, or noncompliant conduct of a bond issuer. Moreover, a portion of the Funds’ otherwise exempt-interest dividends may be taxable to those shareholders subject to the alternative minimum tax. In addition, proposals have been made to restrict or eliminate the federal income tax exemption for interest on municipal securities, and similar proposals may be introduced in the future. Proposed “flat tax” and “value added tax” proposals could also have the effect of eliminating the tax preference for municipal securities. Some of these proposals would apply to interest on municipal securities issued before the date of enactment, which would adversely affect their value to a material degree. If such a proposal were enacted, the availability of municipal securities for investment by the Funds and the value of the Funds’ portfolios would be adversely affected.
Portfolio Holdings
The Funds have established policies and procedures with respect to the disclosure of portfolio holdings and other information concerning Fund characteristics. Such policies and procedures regarding disclosure of portfolio holdings are designed to prevent the misuse of material, non-public information about the Funds. A description of these policies and procedures is provided in the SAI.
DISTRIBUTION AND TAXES
Dividends and Capital Gain Distributions
Each Fund declares daily dividends from its net investment income. Net investment income consists of all interest income earned on portfolio assets less all Fund expenses. Income dividends are distributed monthly and net realized capital gains, if any, are distributed annually.
To receive a dividend or other distribution, you must be a shareholder on the record date. The record dates for the Funds’ distributions will vary. The amount of the Funds’ distributions will vary, and there is no guarantee each Fund will pay distributions.
The Funds automatically reinvest your dividends and capital gains distributions in additional Fund shares at net asset value unless you request distributions to be received in cash. You may change your selected method of distribution, provided such change will be effective only for distributions paid seven or more days after Integrity Fund Services, LLC (“Integrity Fund Services” or the “Transfer Agent”) receives the request.
Dividends that are not reinvested are paid by check or transmitted electronically to your bank account, with the same names as the account registration, using the ACH network. You may have your distribution check paid to a third party or sent to an address other than your address of record, although a signature guarantee will be required. For further information, please contact Integrity Fund Services at 800-601-5593.
Taxes
This section summarizes some of the main U.S. federal income tax consequences of owning shares of a Fund. This section is current as of the date of this prospectus. Tax laws and interpretations change frequently and these summaries do not describe all of the tax consequences to all taxpayers. For example, these summaries generally do not describe your situation if you are a corporation, a non-U.S. person, a broker/dealer, or other investor with special circumstances. Because the Funds invest primarily in municipal securities from a particular state, the regular monthly dividends payable from the net tax-exempt interest earned from such municipal securities that you, as a taxpayer in that state, receive, are generally expected to be exempt from regular federal income tax and, subject to the provisions of that state’s tax law, the regular personal income tax of that state. This section, however, does not describe your state, local or foreign tax consequences. For more detailed information regarding certain state tax consequences of a Fund investment, see the SAI.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 39 |
This federal income tax summary is based in part on the advice of counsel to the Funds. The Internal Revenue Service (“IRS”) could disagree with any conclusions set forth in this section. In addition, counsel to the Funds was not asked to review, and has not reached a conclusion with respect to, the federal income tax treatment of the assets to be acquired by the Funds. This may not be sufficient for you to use for the purpose of avoiding penalties under federal tax law.
As with any investment, you should seek advice based on your individual circumstances from your own tax advisor.
Fund Status
Each Fund intends to qualify as a regulated investment company (“RIC”) under the U.S. federal income tax laws. During periods when a Fund qualifies as a RIC and distributes all its income, the Fund generally will not pay federal income taxes.
Distributions
Except for exempt-interest dividends as described below, Fund distributions are generally taxable. After the end of each year, you will receive a tax statement that separates your Fund’s distributions into categories. The statement will separate the distributions into three categories: ordinary income distributions, capital gain dividends, and exempt-interest dividends. Ordinary income distributions are generally taxed at your ordinary tax rate. The Funds intend to distribute dividends that qualify as “exempt-interest dividends,” which generally are excluded from your gross income for federal income tax purposes. Distributions of the Funds’ interest income on certain private activity bonds may be an item of tax preference for purposes of the alternative minimum tax applicable to individuals. Some or all of the exempt-interest dividends may have other tax consequences (e.g., they may affect the amount of your social security benefits that are taxed), and income exempt from federal income tax may be subject to state and local tax. Although the Funds do not seek to realize taxable income or capital gains, the Funds may realize and distribute taxable ordinary income or capital gains as a result of their normal investment activities. Generally, you will treat all capital gain dividends as long-term capital gains regardless of how long you have owned your shares. To determine your actual tax liability for your capital gain dividends, you must calculate your total net capital gain or loss for the tax year after considering all of your other taxable transactions, as described below. In addition, the Funds may make distributions that represent a return of capital for federal income tax purposes. If a Fund makes a return of capital distribution, the distribution will not be taxable to you to the extent of your basis in your shares and thereafter will be treated as a capital gain. Because a return of capital distribution reduces the basis of your shares, a return of capital distribution may result in a higher capital gain or lower capital loss when you sell your shares. The tax status of your distributions from your Fund is not affected by whether you reinvest your distributions in additional shares or receive them in cash. The tax laws may require you to treat distributions made to you in January as if you had received them on December 31 of the previous year. Income from the Fund may also be subject to a 3.8% “Medicare tax.” This tax generally applies to your net investment income if your adjusted gross income exceeds certain threshold amounts, which are $250,000 in the case of married couples filing joint returns and $200,000 in the case of single individuals. Interest that is excluded from gross income and exempt-interest dividends from a Fund are generally not included in your net investment income for purposes of this tax. The Funds do not expect to make distributions that constitute qualified dividend income.
Dividends Received Deduction
A corporation that owns shares generally will not be entitled to the dividends received deduction with respect to the dividends received from a Fund.
Sale or Redemption of Shares
If you sell or redeem your shares, you will generally recognize a capital gain or loss that is taxable. To determine the amount of this gain or loss, you must subtract your tax basis in your shares from the amount you receive in the transaction. Your tax basis in your shares is generally equal to the cost of your shares, generally including sales charges. In some cases, however, you may have to adjust your tax basis after you purchase your shares. Further, if you hold your shares in a Fund for six months or less, any loss incurred by you related to the disposition of such a share will be disallowed to the extent of the exempt-interest dividends you received, except as otherwise described in the next section.
Capital Gains and Losses
If you are an individual, the maximum federal income tax rate for net capital gain is generally 20%. Capital gains may also be subject to the “Medicare tax” described above.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 40 |
Net capital gain equals net long-term capital gain minus net short-term capital loss for the taxable year. Capital gain or loss is long-term if the holding period for the asset is more than one year and is short-term if the holding period for the asset is one year or less. You must exclude the date you purchase your shares to determine your holding period. If you hold a share in a Fund for six months or less, any loss incurred by you related to the disposition of such share will be disallowed to the extent of the exempt-interest dividends you received, except in the case of a regular dividend paid by the Fund if the Fund declares exempt-interest dividends on a daily basis in an amount equal to at least 90 percent of its net tax-exempt interest and distributes such dividends on a monthly or more frequent basis. To the extent, if any, it is not disallowed, it will be re-characterized as long-term capital loss to the extent of any capital gain dividend received. The tax rates for capital gains realized from assets held for one year or less are generally the same as for ordinary income. The Internal Revenue Code of 1986, as amended (the “Code”), treats certain capital gains as ordinary income in special situations and may limit your ability to use capital losses.
Exchanges
If you exchange shares of your Fund for shares of another fund, the exchange would generally be considered a sale of the exchanged shares for federal income tax purposes, and any gain on the transaction may be subject to federal income tax.
Buying Shares Close to a Record Date
Buying Fund shares shortly before the record date for a taxable dividend is commonly known as “buying the dividend.” The entire dividend may be taxable to you even though a portion of the dividend effectively represents a return of your purchase price.
Medicare Tax
An additional 3.8% Medicare tax is imposed on certain net investment income (including dividends and capital gain distributions received from a Fund and net gains from redemptions or other taxable dispositions of shares of the Fund) of U.S. individuals, estates and trusts to the extent that such person’s “modified adjusted gross income” (in the case of an individual) or “adjusted gross income”(in the case of an estate or trust) exceeds a threshold amount.
Backup Withholding
A Fund may be required to withhold U.S. federal income tax at a rate of 24% from all distributions (including exempt-interest dividends) and redemption proceeds payable to shareholders who fail to provide the Fund with their correct taxpayer identification number or to make required certifications, or who have been notified (or a Fund is notified) by the IRS that they are subject to backup withholding. This withholding is not an additional tax. Any amounts withheld may be credited against the shareholder’s federal income tax liability, provided the required information is furnished to the IRS.
Foreign Investors
If you are a foreign investor (i.e., generally an investor other than a U.S. citizen or resident, or a U.S. corporation, partnership, estate, or trust), you should be aware that, generally, subject to applicable tax treaties, distributions from the Funds will be characterized as dividends for federal income tax purposes (other than dividends which the Funds properly report as capital gain dividends) and, other than exempt-interest dividends, will be subject to U.S. income taxes (including withholding taxes) subject to certain exceptions described below. However, distributions received by a foreign investor from the Funds that are properly reported by the Funds as capital gain dividends may not be subject to U.S. federal income taxes (including withholding taxes) provided that the Funds make certain elections and certain other conditions are met. Distributions from the Funds that are properly reported by the Funds as an interest-related dividend attributable to certain interest income received by the Funds or as a short-term capital gain dividend attributable to certain net short-term capital gain income received by the Funds may not be subject to U.S. federal income taxes, including withholding taxes when received by certain foreign investors, provided that the Funds make certain elections and certain other conditions are met. In addition, distributions may be subject to a U.S. withholding tax of 30% in the case of distributions to (i) certain non-U.S. financial institutions that have not entered into an agreement with the U.S. Treasury to collect and disclose certain information and are not resident in a jurisdiction that has entered into such an agreement with the U.S. Treasury and (ii) certain other non-U.S. entities that do not provide certain certifications and information about the entity’s U.S. owners. Dispositions of shares and capital gain dividends received by such persons may be subject to such withholding after December 31, 2018. A Fund may elect not to report any amounts as interest-related dividends or as short-term capital gain dividends. You should also consult your tax advisor with respect to other U.S. tax withholding and reporting requirements.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 41 |
Foreign Account Tax Compliance Act
In addition, distributions in respect of shares may be subject to a U.S. withholding tax of 30% in the case of distributions to (i) certain non-U.S. financial institutions that have not entered into an agreement with the U.S. Treasury to collect and disclose certain information and are not resident in a jurisdiction that has entered into such an agreement with the U.S. Treasury and (ii) certain other non-U.S. entities that do not provide certain certifications and information about the entity’s U.S. owners. Dispositions of shares and capital gain dividends received by such persons may be subject to such withholding after December 31, 2018. You should also consult your tax advisor with respect to other U.S. tax withholding and reporting requirements.
Cost Basis Method
For shares acquired on or after January 1, 2012, you may elect a cost basis method to apply to existing and future accounts you may establish. The cost basis method you select will determine the order in which shares are redeemed and how your cost basis information is calculated and subsequently reported to you and to the IRS. Please contact your tax advisor to determine which cost basis method best suits your specific situation. If you hold your account directly with Viking Mutual Funds, please contact Integrity Fund Services at 800-601-5593 for instructions on how to make your election. If you hold your account with a financial intermediary, please contact that financial intermediary for instructions on how to make your election. If you hold your account directly with Viking Mutual Funds and do not elect a cost basis method, your account will default to the First In, First Out (FIFO) method. Under this method, the first shares purchased are treated as sold first. Financial intermediaries choose their own default method.
MANAGEMENT
The Board of Trustees (the “Board”) has overall responsibility for the management of the Funds. Viking Fund Management, LLC (“Viking Management,” “investment manager” or the “Adviser”), PO Box 500, Minot, North Dakota 58702, is the Funds’ investment manager. Since July 31, 2009, Viking Management has been a wholly-owned subsidiary of Corridor Investors, LLC (“Corridor”), a North Dakota limited liability company that was organized in January 2009. As of November 3, 2024, Viking Management had net assets under management of approximately $940 million.
The Funds have retained Viking Management to provide the Funds with investment advice and portfolio management. Viking Management has acted as investment manager for the North Dakota Fund and Montana Fund since their inception in August 1999. Since August 1, 2009, Viking Management has also acted as investment manager to the Kansas Fund, Maine Fund, Nebraska Fund, and Oklahoma Fund and the six funds in The Integrity Funds. The six Integrity Funds, together with the Funds, comprise the Integrity/Viking family of funds (the “Integrity/Viking Funds”). The portfolio management team for each Fund consists of Shannon D. Radke (Senior Portfolio Manager) and Josh Larson (Portfolio Manager).
Mr. Radke is a Governor and President of Viking Management and a Governor of Corridor. In addition to the Funds, Mr. Radke serves as co-portfolio manager to various other funds currently advised by Viking Management. Mr. Radke holds a Bachelor of Business Administration degree in Banking and Finance from the University of North Dakota. He has been engaged in the securities business since 1988 as a securities representative and as operations manager and later as chief operating officer of an investment advisory firm. Mr. Radke founded Viking Management in September 1998.
Mr. Larson holds Bachelor of Science degrees in Finance and Management from Minot State University. He joined Integrity/Viking Funds in 2010 in the fund accounting division and as a research analyst for certain funds advised by Viking Management. In addition, Mr. Larson has served as a co-portfolio manager to the Integrity Dividend Harvest Fund since May 2012, to the Integrity Growth & Income Fund since May 2013, and to the Dividend Summit Fund since May 2023.
The SAI provides additional information about the portfolio managers’ compensation, other accounts managed by the portfolio managers and the portfolio managers’ ownership of securities in the Funds.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 42 |
Viking Management is responsible for: (a) providing a program of continuous investment management for each Fund in accordance with the Fund’s investment objectives, policies and restrictions; (b) making investment decisions for each Fund; and (c) placing orders to purchase and sell securities for each Fund. The investment advisory agreement between the Funds and Viking Management (the “Investment Advisory Agreement”) provides for an annual fund management fee computed daily and paid monthly at the following annual rates as a percentage of each Fund’s average daily net assets:
| Fund | Annual Rate (as a percentage of average daily net assets) |
| Kansas Fund | 0.50% |
| Maine Fund | 0.50% |
| Nebraska Fund | 0.50% |
| Oklahoma Fund | 0.50% |
| Montana Fund | 0.50% |
| North Dakota Fund | 0.50% |
For the fiscal year ended July 31, 2024, the Funds paid, after contractual waivers and expense reimbursements, if any, the following management fees to Viking Management, as a percentage of average net assets:
| Fund | Fee Paid
to Viking Management (as a percentage of average daily net assets) |
| Kansas Fund | 0.30% |
| Maine Fund | 0.00% |
| Nebraska Fund | 0.24% |
| Oklahoma Fund | 0.30% |
| Montana Fund | 0.31% |
| North Dakota Fund | 0.18% |
Each Fund generally pays its own operating expenses, including but not limited to the costs associated with custodian, administrative, transfer agent, accounting, legal and audit services. (Please refer to the SAI for an additional discussion of Fund expenses.) A portion of these costs may be reimbursed by the Investment Adviser, either at its discretion or pursuant to a contractual fee waiver and expense reimbursement agreement.
Viking Management has contractually agreed to waive its fees or reimburse each Fund for its expenses (excluding taxes, brokerage fees, commissions, extraordinary and non-recurring expenses, and the fees and expenses of acquired funds), through November 29, 2025 so that the Fund’s total annual operating expenses do not exceed 0.98% of average daily net assets with respect to Class A shares and 0.73% of average daily net assets with respect to Class I shares. The terms of the expense limitation agreement provide that effective November 28, 2018 Viking Management is entitled to recoup from a Fund such amounts waived or reimbursed for a period of up to three years from the date on which Viking Management waived fees or reimbursed expenses for the Fund. Each Fund will make repayments to the Adviser only if such repayment does not cause the annual Fund operating expenses (after the repayment is taken into account) to exceed both (1) the expense limitation in place when such amounts were waived and (2) the Fund’s current expense limitation.
In addition, certain affiliated service providers, including Integrity Fund Services, LLC and Integrity Funds Distributor, LLC, may voluntarily waive from time to time all or a portion of their respective fees, which waiver may occur before Viking Management waives any of its fee or reimburses any expenses to satisfy its contractual expense limitation agreement. Amounts voluntarily waived are not eligible for repayment.
A discussion regarding the basis for the Board of Trustees’ approval of the Investment Advisory Agreement is available in the semi-annual report to shareholders for the period ended January 31, 2024.
Manager-of-Managers
Under the Investment Advisory Agreement between Viking Management and the Funds, Viking Management is authorized, at its own cost and expense, to enter into a sub-advisory agreement with a sub-adviser with respect to the respective Fund. If an investment adviser delegates portfolio management duties to a sub-adviser, the Investment Company Act of 1940 (the “1940 Act”) generally requires that the sub-advisory agreement between the adviser and the sub-adviser be approved by the Board and by Fund shareholders. Specifically, Section 15 of the 1940 Act, in relevant part, makes it unlawful for any person to act as an investment adviser (including as a sub-adviser) to a mutual fund, except pursuant to a written contract that has been approved by shareholders.
In 2009, shareholders of each Fund approved a “manager-of-managers” structure for their Fund. The Funds have received an order from the Securities and Exchange Commission (“SEC”) permitting the Funds to be managed under a “manager-of-managers” structure (the “SEC Order”). The SEC Order generally permits Viking Management to enter into and materially amend sub-advisory agreements with unaffiliated sub-advisers subject to approval by the Board of Trustees, but without obtaining shareholder approval. If a sub-adviser is hired to provide sub-advisory services to a Fund, such Fund will provide information concerning the sub-adviser to shareholders of the Fund concerned.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 43 |
Under the “manager-of-managers” structure for a Fund, Viking Management would remain the primary provider of investment advisory services to the Fund, would be permitted to hire or change sub-advisers, as appropriate, and would have ultimate responsibility (subject to oversight by the Funds’ Board of Trustees) to oversee sub-advisers and recommend to the Board their hiring, termination, and replacement. Viking Management would remain responsible for providing general management services to a Fund utilizing the manager-of-managers structure, including overall supervisory responsibility for the general management and investment of the Fund’s assets, and, subject to review and approval of the Board of Trustees, would, among other things: (i) set the Fund’s overall investment strategies; (ii) evaluate, select, and recommend sub-advisers to manage all or a part of the Fund’s assets; (iii) when appropriate, allocate and reallocate the Fund’s assets among multiple sub-advisers; (iv) monitor and evaluate the performance of sub-advisers; and (v) implement procedures reasonably designed to ensure that the sub-advisers comply with the Fund’s investment objectives, policies and restrictions.
FUND SERVICE PROVIDERS
The custodian of the assets of the Funds other than cash is UMB Bank, N.A., Institutional Custody, 928 Grand Blvd, Kansas City, MO 64105.
Integrity Fund Services, a wholly-owned subsidiary of Corridor, is the Funds’ transfer agent and accounting and administrative services provider. As such, Integrity Fund Services performs pricing, data processing, accounting, and other administrative services for the operation of the Funds and the maintenance of shareholder accounts.
THE SHARES OFFERED
Each Fund offers Class A shares and Class I shares. As described below, Class A shares and Class I shares differ in certain ways, including with respect to sales charges and fees. Information about the manner in which the Funds offer shares is set forth below in this section and subsequent sections of the prospectus. Information relating to eligibility to invest in a particular share class, minimum investment amounts, investor services, and sales charge reductions and waivers applies if you are transacting directly with the Funds. Shares of the Funds are also available through certain financial intermediaries, such as a bank or broker-dealer. If you invest through an intermediary, you are not transacting directly with a Fund and you must follow that intermediary’s transaction procedures which may include different requirements to invest in a particular share class, minimum investment amounts, investor services, and sales charge reductions and waivers. Appendix A to the prospectus sets forth a description of the sales charge reductions and waivers applicable to Fund shares purchased through Edward Jones, Raymond James, Oppenheimer & Co. Inc., Robert W. Baird & Co., and Morgan Stanley Wealth Management, as such information was provided to the Funds by the intermediary.
Your intermediary may impose charges for its services in addition to the fees charged by the Funds. You should consult with your intermediary for information regarding its conditions, procedures, and fees for transacting in Fund shares. The Funds are not responsible for the implementation of any intermediary’s transaction procedures or sales charge reductions and waivers.
Class A Shares
You can buy Class A shares at the offering price, which is the net asset value (“NAV”) per share plus an up-front sales charge. Each Fund has adopted a plan under Rule 12b-1 under the 1940 Act with respect to its Class A shares that authorizes each Fund to compensate its distributor, Integrity Funds Distributor, LLC (“Integrity Funds Distributor” or the “Distributor”) for services performed and expenses incurred by the Distributor in connection with the distribution of Class A shares of the Fund and for providing personal services and the maintenance of shareholder accounts. Under its respective plan, with respect to its Class A shares, each Fund may pay an annual Rule 12b-1 fee of up to 0.25% of its average daily net assets for distribution and shareholder services. The Distributor may pay a portion of the distribution and services fees to your financial adviser for providing distribution and ongoing services to you, respectively. The Distributor retains the up-front sales charge and the service fee on accounts with no authorized dealer of record. Because these fees are paid out of a Fund’s assets on an on-going basis, over time these fees will increase the cost of your investment and may cost you more than paying other types of sales charges.
The up-front sales charge and the commissions paid to dealers for the Funds are as follows:
| When You Invest This Amount | Sales Charge as % of Public Offering Price | Sales Charge as % of Net Amount Invested | Authorized Dealer Commission as % of Public Offering Price |
| Less than $50,000 | 2.50% | 2.56% | 2.00% |
| $50,000 but less than $100,000 | 2.00% | 2.04% | 1.75% |
| $100,000 but less than $200,000 | 1.50% | 1.52% | 1.25% |
| $200,000 or more | 0.00% | 0.00% | 1.00%* |
| *The Distributor will pay a commission of 1.00% out of its own resources to broker-dealers who initiate and are responsible for the purchase of shares of $200,000 or more, unless the dealer waives its commission in connection with the purchase. | |||
Please see Appendix A - Intermediary-Specific Sales Charge Waivers and Discounts in the prospectus for a description of variations in sales charges and waivers for Fund shares purchased through Edward Jones, Raymond James, Oppenheimer & Co. Inc., Robert W. Baird & Co., and Morgan Stanley Wealth Management.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 44 |
Limited Contingent Deferred Sales Charge
Certain investors that purchase Fund shares without an up-front sales charge will have to pay a limited contingent deferred sales charge (“CDSC”) of 1.00% if they redeem those shares within twenty-four months of purchase. Your investment may be subject to this CDSC if:
| ● | you purchased $200,000 or more of Fund shares and the Fund’s distributor paid your investment representative a commission; | |
| ● | you purchased Fund shares subject to a sales charge waiver, and the Fund’s distributor paid your investment representative a commission. |
In the case of a partial redemption, the CDSC is calculated as if any shares not subject to the charge are redeemed first and shares subject to the CDSC are then redeemed in the order purchased. The limited CDSC only applies if you redeem these shares within twenty-four months of purchase. The sales charge will be applied as a percentage of the initial purchase amount or the amount of redemption proceeds, whichever is less. You do not pay a CDSC on shares acquired by reinvesting dividends and capital gains.
Please see Appendix A - Intermediary-Specific Sales Charge Waivers and Discounts in the prospectus for a description of variations in sales charges and waivers for Fund shares purchased through Edward Jones, Raymond James, Oppenheimer & Co. Inc., Robert W. Baird & Co., and Morgan Stanley Wealth Management.
Sales Charge Reductions and Waivers
If you qualify for any of the sales charge reductions or waivers below, please let us know at the time you make your investment to help ensure you receive the lower sales charge.
Please see Appendix A - Intermediary-Specific Sales Charge Waivers and Discounts in the prospectus for a description of variations in sales charges and waivers for Fund shares purchased through Edward Jones, Raymond James, Oppenheimer & Co. Inc., Robert W. Baird & Co., and Morgan Stanley Wealth Management.
Quantity Discounts
Integrity Fund Services offers several ways for you to combine your purchases in the Integrity/Viking Funds to take advantage of the lower sales charges for large purchases of shares.
| ● | Cumulative Quantity Discount-lets you combine the amount of your current purchase with the cost or current value, whichever is higher, of your existing shares in the Integrity/Viking Funds for purposes of calculating the sales charge. You may also combine the shares of your spouse, and your children or grandchildren, if they are under the age of 21. Your retirement plan accounts, family trust accounts, and solely-controlled business accounts may also be included. | |
| ● | Letter of Intent (“LOI”)-expresses your intent to buy a stated dollar amount of shares over a 13-month period and lets you receive the same sales charge as if all shares had been purchased at one time. A portion of your shares will be reserved to cover any additional sales charge that may apply if you do not buy the amount stated in your LOI. |
In order to be sure you obtain a sales charge discount, you should inform your investment representative or Integrity Fund Services at the time of purchase that you are eligible for a reduction, or else you may not receive a sales charge discount to which you are otherwise entitled. In order to determine your eligibility to receive a sales charge discount, it may be necessary for you to provide information and records (including account statements) of all relevant accounts invested in a Fund and other Integrity/Viking Funds, such as:
| ● | information or records regarding shares of the Fund or other Integrity/Viking Funds held in all accounts (e.g., retirement accounts) of the shareholder at a financial intermediary; | |
| ● | information or records regarding shares of the Fund or other Integrity/Viking Funds held in any account of the shareholder at another financial intermediary; and | |
| ● | information or records regarding shares of the Fund or other Integrity/Viking Funds held at any financial intermediary by related parties of the shareholder, such as members of the same family or household. |
Please retain any records necessary to substantiate your historical costs because the Funds, the Transfer Agent, and financial intermediaries may not maintain this information.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 45 |
Reinstatement Privilege
If you redeem Fund shares, you may reinstate all or part of your redemption proceeds within 365 days at NAV without incurring any additional charges. You may only reinstate into the same share class from which you redeemed. If you paid a CDSC, the Funds will refund your CDSC as additional shares in proportion to the reinstatement amount of your redemption proceeds, and your holding period will also be reinstated. The Funds may modify or terminate this privilege at any time. You should consult your tax advisor about the tax consequences of exercising your reinstatement privilege. The Funds must be notified that an investment is a reinstatement.
Group Purchases
If you are a member of a qualified group (as described in the SAI), you may buy shares of the Funds at a reduced sales charge that applies to the group as a whole. The sales charge is based on the combined dollar value of the group members’ existing investments, plus the amount of the current purchase.
Sales Charge Waivers
Shares of a Fund may be purchased without an initial sales charge by particular classes of investors, including:
| ● | current and former registered representatives and employees, including their immediate families, of broker-dealers having selling group agreements with Integrity Funds Distributor or any trust, pension, profit-sharing, or other benefit plan for such persons (immediate family is defined to include the individual, his/her spouse, and their children, their parents, and their siblings); | |
| ● | current and former employees (including their spouses and dependent children) of banks and other financial services firms that provide advisory, custody, or administrative services related to the Fund pursuant to an agreement with the Fund, Corridor or one of its affiliates, or any trust, pension, profit-sharing, or other benefit plan for such persons; | |
| ● | individuals and institutions purchasing shares in connection with the acquisition of the assets of or merger or consolidation with another investment company; | |
| ● | investors purchasing through certain asset- or transaction-fee based investment advisers, broker-dealers, bank trust departments, and other financial services firms; | |
| ● | 401(k), 403(b), 457, profit-sharing, and defined benefit plans; excluded from this waiver are SEPs, SARSEPs, and SIMPLE IRAs; and | |
| ● | foundations and endowments, provided the foundation or endowment has assets of $200,000 or more. |
The elimination of the up-front sales charge for certain individuals and institutions is provided because of anticipated economies of scale and reduced sales-related efforts. A Fund must be notified in advance that you believe your investment qualifies for a sales charge reduction or waiver. The Funds make available, free of charge, more information about sales charge reductions and waivers through the Funds’ website at www.integrityvikingfunds.com, and in the SAI. Additional information is also available from your financial adviser.
CDSC Waivers
For each Fund, a CDSC may not be assessed on redemptions of such Fund:
| • | following the death of the last surviving shareholder on the account or the post-purchase disability of all registered shareholders, as defined in Section 729(m)(7) of the Code (the beneficiary on an account with a Transfer on Death registration is deemed the last surviving shareholder on the account); | |
| • | due to the termination of a trust following the death of the trustor/grantor or beneficiary, provided that the trust document specifically states that the trust is terminated upon death; | |
| • | representing minimum required distributions from an IRA or other retirement plan as required under the Internal Revenue Code. |
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 46 |
Class I Shares
You can buy Class I shares of each Fund at the offering price, which is the net asset value (“NAV”) per share without any up-front sales charge. As Class I shares are not subject to sales charges or ongoing service or distribution fees, they have lower ongoing expenses than the other classes.
Class I shares may also be available on certain brokerage platforms. An investor transacting in Class I shares through a broker acting as an agent for the investor may be required to pay a commission and/or other forms of compensation to the broker. Fund shares are available in other share classes that have different fees and expenses.
In addition to certain categories of investors listed below, Class I shares are available for purchase by clients of financial intermediaries who charge such clients an ongoing fee for advisory, investment, consulting or related services. Such clients may include individuals, corporations, endowments and foundations. The minimum initial investment is $1,000 ($50 for accounts opened through an automatic investment plan account and $250 for an IRA account).
Class I shares are available for purchase by the following categories of investors:
| ● | investors who purchase through a fee-based advisory account with a financial intermediary (as described above); | |
| ● | employer sponsored retirement and benefit plans, endowments, or foundations; | |
| ● | banks or bank trust departments investing for their own account or for funds over which they exercise exclusive discretionary investment authority and that are held in a fiduciary, agency, advisory, custodial, or similar capacity; | |
| ● | subject to applicable law and/or exemptive relief, any registered investment company that is not affiliated with the Integrity/Viking Funds and which invest in securities of other investment companies; | |
| ● | any plan organized under Section 529 under the Code (i.e., a 529 plan); | |
| ● | any person who, for at least the last 90 days, has been an officer, director, or employee of any financial intermediary for themselves, their immediate family members (“immediate family members” are defined as spouses or domestic partners, parents, children, grandparents, grandchildren, parents-in-law, sons-in-law and daughters-in-law, siblings, a sibling’s spouse, and a spouse’s siblings), their IRAs or employer sponsored IRAs; | |
| ● | current, former, and retired trustees/directors, employees and officers of any Integrity/Viking Fund for themselves, their immediate family members, their IRAs or employer sponsored IRAs; | |
| ● | current, former, and retired officers, directors, and governors of Corridor and its affiliates, for themselves, their immediate family members, their IRAs or employer sponsored IRAs; | |
| ● | current, former, and retired employees of Corridor and its affiliates for themselves, their immediate family members, their IRAs or employer sponsored IRAs, any corporation, partnership, sole proprietorship, or other business organization in which such persons own a 25% or greater stake; and | |
| ● | persons who retain an ownership interest in or who are the beneficial owners of an interest in Corridor for themselves, their immediate family members, their IRAs or employer sponsored IRAs, any corporation, sole proprietorship, or other business organization in which such persons own a 25% or greater stake. |
Unless otherwise noted above, Class I shares are not available for IRAs or employer sponsored IRAs, unless purchased through a fee-based advisory account with a financial intermediary.
Holders of Class I shares may purchase additional Class I shares using dividends and capital gains distributions on their shares.
Please refer to the SAI for more information about Class I shares, including more detailed eligibility requirements. Additional information is also available from your financial advisor, who can also help you prepare any necessary application forms.
HOW TO BUY SHARES
Fund shares may be purchased on any business day, which is any day the New York Stock Exchange (“NYSE”) is open for business. Generally, the NYSE is closed on weekends, federal holidays, and Good Friday. The close of regular trading on the NYSE is normally 3:00 p.m., Central Time. Each Fund will process purchase orders that it receives in proper form prior to the close of regular trading on a day on which the NYSE is open at the NAV determined on that day. An order is in “proper form” if the Fund’s transfer agent, Integrity Fund Services, LLC (“Integrity Fund Services” or the “Transfer Agent”), has all of the information and documentation it deems necessary to effect your order, which would typically mean that it has received federal funds, a wire, a check or Automated Clearing House (“ACH”) transaction, together with a completed account application. Should you wish to purchase shares via wire transfer, please call the Transfer Agent at 800-601-5593 for wire instructions. The wire must be received by 3:00 p.m., Central time, for you to receive that day’s share price. Each Fund will process purchase orders that it receives in proper form after the close of regular trading on the next day that the NYSE is open for regular trading.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 47 |
You may buy shares through investment dealers who have sales agreements with the Distributor or directly from the Distributor. If you do not have a dealer, call 800-276-1262 and the Distributor can refer you to one. Shares may also be purchased through banks and certain other financial institutions that have agency agreements with the Distributor. If you buy, hold, or sell Fund shares through an investment dealer, bank, or other financial institution or intermediary, the transaction policies of the intermediary will apply, which may vary from those described below. In addition, your intermediary may charge you fees for executing transactions and for other services that are not described in the prospectus. These shareholders should contact their financial intermediary for additional information regarding its transaction policies, procedures, and fees.
Purchase requests should be addressed to the authorized dealer or agent from whom you received this prospectus. Such dealers or agents may place a telephone order with the Distributor for the purchase of shares. Checks should be made payable to the name of the applicable Fund. The Transfer Agent will charge a $15.00 fee against a shareholder’s account for any payment returned for insufficient funds. The shareholder will also be responsible for any losses suffered by the Fund as a result.
A Fund may reject any purchase orders, including exchanges, for any reason. A Fund will reject any purchase orders, including exchanges, from investors that, in the Investment Adviser’s opinion, may constitute excessive trading. For these purposes, the Investment Adviser may consider an investor’s trading history in the Fund or other Integrity/Viking Funds, and accounts under common ownership or control.
You may be asked to provide additional information in order for the Transfer Agent or a dealer to verify your identity in accordance with requirements under anti-money laundering regulations. Accounts may be restricted and/or closed, and the monies withheld, pending verification of this information or as otherwise required under these and other federal regulations.
Shares of the Funds have not been registered for sale outside of the United States. The Funds generally do not sell shares to investors residing outside of the United States, even if they are United States citizens or lawful permanent residents, except to investors with United States military APO (Army Post Office) or FPO (Fleet Post Office) addresses.
The Funds may not be available for purchase in every state. Please consult your investment representative or Integrity Fund Services concerning the availability of a particular Fund in your state.
To make any ownership changes to any accounts over $100,000, a signature guarantee will be required.
How to Buy Shares, Open an Account, or Add to an Account
| Buying Shares | Opening an Account | Adding to an Account |
| Through your investment representative | Contact your investment representative. | Contact your investment representative. |
| By Mail |
Make your check payable to the Fund in which you are investing.
Mail the check and your signed application to Integrity Fund Services. |
Make your check payable to the Fund in which you
are investing. Include your account number on the check. Fill out the deposit slip from your confirmation statement. If you do not have a slip, include a note with your name, the Fund name, and your account number.
Mail the check and deposit slip or note to Integrity Fund Services. |
| By Wire |
Call to receive wire instructions.
Mail your signed application to Integrity Fund Services.
To make a same day wire investment, please call Integrity Fund Services by 1:00 p.m. Central Time and make sure your wire arrives by 3:00 p.m. |
Call to receive wire instructions.
To make a same day wire investment, please call Integrity Fund Services by 1:00 p.m. Central Time and make sure your wire arrives by 3:00 p.m. |
| By Exchange |
Call Integrity Fund Services at the number below, or send signed written instructions.
Integrity Fund Services, LLC |
Call Integrity Fund Services at the number below, or send signed written instructions.
For overnight deliveries: |
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 48 |
Account Application
If you are opening a new account, please complete and sign the enclosed account application. To save time, you can sign up now for services you may want on your account by completing the appropriate sections of the application.
Customer Identification Procedures
The Funds are required under the Uniting and Strengthening America by Providing Appropriate Tools Required to Intercept and Obstruct Terrorism Act of 2001 (“USA PATRIOT Act”) to adopt certain policies and programs to prevent money-laundering activities, including procedures to verify the identity of customers opening new accounts, including legal entity customers. When completing a new account application, you will be required to supply your full name, date of birth, social security number or other taxpayer identification number, and permanent street address (not a post office Box) to assist in verifying your identity. Effective May 11, 2018, these anti-money laundering and customer identification procedures apply with respect to new accounts opened by legal entity customers, and the Funds require similar identifying information for each individual that directly or indirectly owns 25% or more of the equity interests in the legal entity or that has managerial control of the legal entity. However, the requirements to look through to and obtain identifying information of the beneficial owners and controlling managers of legal entity customers generally do not apply to financial institutions regulated by a federal or state regulator, entities registered with the SEC, and omnibus accounts of financial intermediaries, among other excluded entities. As required by law, the Funds may employ various procedures, such as comparing the information to fraud databases or requesting additional information or documentation from you, to ensure that the information supplied by you is correct. Under certain circumstances, it may be appropriate for the Funds to close or suspend further activity in an account.
Shares of the Funds have not been registered for sale outside of the United States. The Funds generally do not sell shares to investors residing outside of the United States, even if they are United States citizens or lawful permanent residents, except to investors with United States military APO (Army Post Office) or FPO (Fleet Post Office) addresses.
Each Fund reserves the right to redeem Fund accounts that are reduced to a value of less than $1,000 for any reason, including market fluctuation. Should a Fund elect to exercise this right, the investor will be notified before such redemption is processed that the value of the investor’s account is less than $1,000 and that the investor will have sixty days to increase the account to at least the $1,000 minimum amount before the account is redeemed.
Minimum Investments and Share Price
You may open an account with a minimum initial investment of $1,000 ($50 for the Automatic Investment Plan (described below) and $250 for an IRA) and make additional investments at any time with as little as $50. The Funds may change these minimum investments at any time and may accept investments of smaller amounts at their discretion.
Each Fund reserves the right to redeem Fund accounts that are reduced to a value of less than $1,000 for any reason, including market fluctuation. Should a Fund elect to exercise this right, the investor will be notified before such redemption is processed that the value of the investor’s account is less than $1,000 and that the investor will have sixty days to increase the account to at least the $1,000 minimum amount before the account is redeemed. The investor will not be assessed a CDSC if the account is redeemed.
The price you pay for shares will depend on how and when the Fund receives your order. You will receive the share price next determined after the Fund has received your order. If you place your order by contacting the Fund directly, your order must be received by the Fund prior to the close of regular trading of the NYSE (normally 3:00 p.m., Central Time) for you to receive that day’s price. However, if you place your order through a dealer prior to the close of regular trading of the NYSE, you will receive that day’s price. Dealers are obligated to transmit orders promptly. See “Calculating Share Price” for a discussion of how shares are priced.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 49 |
Please see Appendix A - Intermediary-Specific Sales Charge Waivers and Discounts in the prospectus for a description of variations in sales charges and waivers for Fund shares purchased through Edward Jones, Raymond James, Oppenheimer & Co. Inc., Robert W. Baird & Co., and Morgan Stanley Wealth Management.
Investor Services
Automatic Investment Plan—the Monthomatic Investment Plan
Once you have established a Fund account, systematic investing allows you to make monthly investments through automatic deductions from your bank account (the “Monthomatic Plan”). Simply complete the appropriate section of the account application form or call Integrity Fund Services at 800-601-5593 for the appropriate forms.
With the Monthomatic Plan, you can make monthly investments of $50 or more per month by authorizing Integrity Fund Services to take money out of your bank, savings and loan association, or credit union (“financial institution”) account. If an investor has expedited wire transfer redemption privileges with his or her fund account, such investor must designate the same financial institution account for both the Monthomatic Plan and the wire redemption programs. If you redeem shares within fifteen days after purchasing them under the Monthomatic Plan and your account does not have sufficient funds, your redemption proceeds may not be sent until your account has sufficient funds, which may take up to fifteen days. You can stop the withdrawals at any time by sending a written notice to Integrity Fund Services at P.O. Box 759, Minot, ND 58702. The termination will become effective within seven days after Integrity Fund Services has received the request. The Funds may terminate or modify the Monthomatic Plan at any time and may immediately terminate a shareholder’s Monthomatic Plan if any item is unpaid by the shareholder’s financial institution. There is no charge for the Monthomatic Plan.
Distribution Options
You may reinvest distributions you receive from a Fund in an existing account of the Fund. You can also have your distributions deposited in a bank account, or mailed by check. Deposits to a bank account may be made by electronic funds transfer.
Please indicate on your application the distribution option you have chosen; otherwise Integrity Fund Services will reinvest your distributions in the Fund.
Telephone Privileges
You will automatically receive telephone privileges when you open your account, allowing you and your investment representative to buy, sell, or exchange your shares and make certain other changes to your account by phone.
For accounts with more than one registered owner, telephone privileges also allow the Funds to accept written instructions signed by only one owner for transactions and account changes that could otherwise be made by phone. For all other transactions and changes, all registered owners must sign the instructions.
As long as Integrity Fund Services takes certain measures to verify telephone requests, Integrity Fund Services will not be responsible for any losses that may occur from unauthorized requests. Of course, you can decline telephone exchange or redemption privileges on your account application.
Exchanging Shares
You can exchange Class A shares between any Integrity/Viking Fund with an up-front sales charge structure without paying any additional sales charges. Additionally, you can exchange Class I shares of a Fund for Class I shares of another Integrity/Viking Fund that offers Class I shares. Before requesting an exchange, review the prospectus of the Integrity/Viking Fund you wish to acquire. Exchange purchases are subject to eligibility requirements as well as the minimum investment requirements of the fund shares purchased. Exchange redemptions and purchases are processed simultaneously at the share prices next determined after the exchange order is received. If you purchased Class A shares subject to a CDSC, the CDSC will not be assessed at the time of the exchange. However, you will be required to pay any remaining deferred sales charge owed on the exchanged shares at the time the acquired shares are redeemed, if any. For purposes of calculating the CDSC, your holding period will begin on the day you purchased the shares being exchanged.
For federal income tax purposes, an exchange is a sale of shares and may result in a taxable gain or loss followed by a purchase of shares of the fund into which you exchange. The Internal Revenue Service could however assert that a loss could not be currently deducted. Special rules may apply to determine the amount of gain or loss on an exchange occurring within 90 days after the purchase of the exchanged shares.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 50 |
The terms of an employee-sponsored retirement plan may affect a shareholder’s right to exchange shares as described above. Contact your plan sponsor or administrator to determine if all of the exchange options discussed above are available under your plan.
Exchanges are made upon receipt of a properly completed exchange request form or letter of instruction. Alternatively, you may make exchanges by telephone by calling Integrity Fund Services at 800-601-5593. The exchange privilege may be changed or discontinued at any time upon 60 days’ notice to shareholders.
Please see Appendix A - Intermediary-Specific Sales Charge Waivers and Discounts in the prospectus for a description of variations in sales charges and waivers for Fund shares purchased through Edward Jones, Raymond James, Oppenheimer & Co. Inc., Robert W. Baird & Co., and Morgan Stanley Wealth Management.
Share Class Conversions
Shares of one class of a Fund may be converted to shares of another class of the same Fund, provided that you are eligible to buy the new share class. Investors who hold Fund shares through a financial intermediary that does not have an agreement to make certain share classes of the Funds available or that cannot systematically support the conversion may not be eligible to convert their shares. Furthermore, your financial intermediary may have discretion to effect a conversion on your behalf. Consult with your financial intermediary for details.
In general, the conversion of shares of one class of a Fund for shares of another class of the same Fund is not considered a taxable event for federal income tax purposes. Any CDSC associated with the shares being converted will be assessed immediately prior to the conversion into shares of the new share class. Shares redeemed to pay the CDSC would be considered a taxable redemption. Please consult your own tax advisor for further information.
Please see Appendix A - Intermediary-Specific Sales Charge Waivers and Discounts in the prospectus for a description of variations in sales charges and waivers for Fund shares purchased through Edward Jones, Raymond James, Oppenheimer & Co. Inc., and Robert W. Baird & Co.
HOW TO SELL SHARES
You can sell your shares on any day the New York Stock Exchange is open. Generally, the New York Stock Exchange is closed on weekends, federal holidays, and Good Friday.
| Through Your Investment Representative | Contact your investment representative. Please note that your investment representative may charge a processing or service fee. |
| By Mail |
Send written instructions and endorsed share certificates (if you hold share certificates) to Integrity Fund Services. Corporate, partnership, or trust accounts may need to send additional documents.
Specify the Fund, account number, and dollar value or number of shares you wish to sell. Be sure to include all necessary signatures and any additional documents, as well as signature guarantees if required.
A check will be mailed to the name(s) and address on the account, or otherwise according to your written instructions. |
| By Phone |
As long as your transaction is for $100,000 or less, you do not hold share certificates and you have not changed your address by phone within the last 30 days, you can sell your shares by phone.
A check will be mailed to the name(s) and address on the account. Written instructions, with a signature guarantee, are required to send the check to another address or to make it payable to another person. |
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 51 |
| By Wire |
You can call or write to have redemption proceeds of $1,000 or more wired to a bank or escrow account, subject to a wire transfer fee discussed below. See the policies above for selling shares by mail or phone.
Before requesting a wire, please make sure Integrity Fund Services has your bank account information on file. If Integrity Fund Services does not have this information, you will need to send written instructions with your bank’s name and address, your bank account number, the ABA routing number, and a signature guarantee.
Requests received in proper form by 3:00 p.m. Central Time will be wired the next business day. |
| By Exchange or Share Class Conversion |
Obtain a current prospectus for the Fund you are considering.
Call the Transfer Agent at the number below or send signed written instructions. See the policies above for selling shares by mail or phone. However, a signature guarantee will not be required to exchange shares of any amount.
If you hold share certificates, you will need to return them to the Fund before your exchange can be processed. |
| Integrity Fund Services, LLC | ||
| Mailing address: P.O. Box 759 Minot, ND 58702 |
For overnight deliveries: 1 Main Street North Minot, ND 58703 | |
| Call toll free: 800-601-5593 | ||
Selling Shares in Writing
Requests to sell $100,000 worth of shares or less can generally be made over the phone or by written request. Sometimes, however, to protect you and the Funds, written instructions signed by all registered owners, with a signature guarantee for each owner, will be required if:
| ● | you are selling more than $100,000 worth of shares; | |
| ● | you want your proceeds paid to someone who is not a registered owner; | |
| ● | you want to send your proceeds somewhere other than the address of record, or pre-authorized bank or brokerage firm account; or | |
| ● | you have changed the address on your account by phone within the last 30 days. |
Selling Recently Purchased Shares
If you sell shares recently purchased with a check or draft, Integrity Fund Services may delay sending you the proceeds until your check or draft has cleared, which may take up to fifteen days. A certified or cashier’s check may clear in less time.
Systematic Withdrawal Plan
This plan allows you to automatically sell your shares and receive regular payments from your account. If the value of your account is at least $5,000, you may request to have a specific amount regularly withdrawn automatically from your account. To sign up, complete the appropriate section of your application.
Redemption Proceeds
Redemption payments will be made in the form of a check or can be sent to your bank through the ACH network. In addition, redemption checks may be sent by overnight mail for a fee which will reduce the amount of your redemption proceeds. Redemption proceeds may be transmitted through a wire transfer for a fee which will reduce the amount of your redemption proceeds. Normally, your redemption proceeds will be sent the next business day after Integrity Fund Services receives your request in proper form, but it may take up to seven days if making immediate payment would adversely affect the Fund. Integrity Fund Services is not able to pay out redemption proceeds in the form of currency.
In addition, a Fund may suspend the right of redemption under the following unusual circumstances:
| ● | when the New York Stock Exchange is closed (other than for weekends and holidays) or trading is restricted, as determined by the SEC; |
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 52 |
| ● | when an emergency exists as determined by the SEC, making disposal of portfolio securities or the valuation of net assets not reasonably practicable; or | |
| ● | during any period when the SEC has by order permitted a suspension of redemption for the protection of shareholders. |
In case of any such suspension, you may either withdraw your request for redemption or receive payment based on the net asset value per share next determined after the termination of the suspension.
Under normal conditions, each Fund typically expects to meet redemption requests through the use of the Fund’s holdings of cash or cash equivalents or by selling other portfolio assets. The Funds reserve the right to satisfy an order to sell Fund shares with liquid securities rather than cash, for certain very large orders. If the Fund pays redemption proceeds by distributing securities in kind, you could incur brokerage costs and/or other transaction costs and charges, as well as tax liability, when converting the distributed securities to cash. You may also be subject to market risk, which means that the value of the distributed securities may decline as a result of unfavorable market-induced changes affecting particular industries, sectors, or issuers. Notwithstanding the above, the Montana Fund and the North Dakota Fund are obligated to redeem shares solely in cash up to the lesser of $250,000 or 1.00% of the net asset value of the Fund during any 90-day period for any one shareholder of record.
Account Policies
Calculating Share Price
The price of a Fund’s shares is based on the Fund’s NAV. Each Fund calculates the NAV per share each business day at the close of regular trading on the New York Stock Exchange (normally 3:00 p.m. Central Time). Shares will not be priced on the days on which the New York Stock Exchange is closed for trading. NAV is calculated by dividing a Fund’s net assets by the number of its shares outstanding.
Requests to buy and sell shares are processed based on the NAV next calculated after we receive your request in proper form.
The Funds’ portfolio holdings will be valued using market quotations to the extent market quotations are readily available and reliable. Fixed income securities for which market quotations are readily available are valued at the mean between the quoted bid and ask prices. Short-term securities with remaining maturities of less than 60 days may be fair valued at amortized cost or at original cost plus accrued interest, subject to Board supervision, as discussed below. To the extent a Fund invests in open-end management investment companies, such Fund’s NAV will be calculated based upon the NAVs of the registered open-end investment companies (other than exchange-traded funds, which are valued at their current market value) in which the Fund invests; the prospectuses for these companies would explain the circumstances under which those companies will use fair value pricing and the effects of fair value pricing. Other securities, including restricted securities and other assets are valued at fair value as described below. If an event were to occur after the value of an instrument was established but before NAV per share was determined, which would likely materially change the NAV, then the instrument would be valued using fair value considerations as described below.
The Board approved amended valuation procedures for the Funds that took effect on September 8, 2022 pursuant to new Rule 2a-5 under the 1940 Act (“Amended Valuation Procedures”). Pursuant to new Rule 2a-5 and the Amended Valuation Procedures, the Board has designated the Adviser as the Funds’ “valuation designee” to perform all fair valuations of the Funds’ portfolio holdings, subject to the Board’s oversight. The Adviser, as the Funds’ valuation designee, has established procedures for its fair valuation of the Funds’ portfolio holdings, which address, among other things, determining when market quotations are not readily available or reliable (which is usually the case for municipal securities) and the fair valuation of such portfolio holdings, as well as the selection and oversight of third-party pricing services for fair valuation. In establishing the fair value of debt securities, the Adviser generally uses valuations provided by pricing services that consider factors such as: the yields and prices of comparable municipal bonds; the type of issue, coupon, maturity, and rating; indications of value from dealers; and general market conditions. Pricing services may also use a computer based “matrix” system to compare securities to determine valuations.
Significant events, including new developments in the securities markets or major occurrences outside of the securities markets, such as natural disasters and armed conflicts, may result in market quotations for portfolio holdings not being reliable. These portfolio holdings will be fair valued. By fair valuing a security whose price may have been affected by events occurring after the close of trading in its respective market or by news after the last market pricing of the security, the Adviser attempts to establish a price that the Fund might reasonably expect to receive upon the current sale of that security. Examples of circumstances which may require further consideration to be given to whether market quotations are available, valid, or reliable, include the lack of reported trades for or infrequent sales of a portfolio security, the suspension of trading on an exchange on which a portfolio security was traded and markets closing early. In addition, while the Funds do not generally invest in thinly traded securities, in the event that they do, such securities may be valued at fair value.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 53 |
Fair valuation of the Funds’ portfolio holdings is intended to ensure that the prices at which Fund shares are purchased and redeemed are fair, and do not result in dilution of shareholder interests or other harm to shareholders. Valuing securities at fair value involves greater reliance on judgment than valuation of securities based on readily available market quotations. The Adviser, when using fair value methods to price securities, may value those securities higher or lower than another mutual fund using market quotations or fair value to price the same securities. There can be no assurance that a Fund could obtain the fair value assigned to a security if it were to sell the security at approximately the time at which the Fund determines its NAV.
To the extent that a Fund’s assets are traded in other markets on days when the Fund is not open for business and does not price its shares, the NAV of the Fund’s shares may be affected on those days when shareholders may not be able to purchase or sell the Fund’s shares. In addition, trading in some of the Fund’s assets may not occur on days when the Fund is open for business.
Statements and Reports
You will receive a confirmation statement for each transaction as well as quarterly account statements. The Funds’ financial reports will be available every six months on Form N-CSR.
The dealer or other investment representative of record on your account will also receive statements and other information about your account directly from the Funds.
Joint Accounts and Ownership Changes to Accounts
Unless you specify a different registration, accounts with two or more owners are registered as “joint tenants with rights of survivorship.” To make any ownership changes to a joint account, all owners must agree in writing, regardless of the law in your state. To make any ownership changes to any accounts over $100,000, a signature guarantee will be required.
Market Timing Policy
The Funds are designed for long-term investors and are not intended for investors that engage in excessive short-term trading activity (including purchases and sales of Fund shares in response to short-term market fluctuations) that may be harmful to the Funds, including but not limited to market timing. Short-term or excessive trading into and out of a Fund can disrupt portfolio management strategies, harm performance, and increase Fund expenses for all shareholders, including long-term shareholders who do not generate these costs. A Fund may be more or less affected by short-term trading in Fund shares, depending on various factors such as: the size of the Fund, the amount of assets the Fund typically maintains in cash or cash equivalents; the dollar amount, number, and frequency of trades in Fund shares; and other factors. Arbitrage market timing may also be attempted in funds that hold significant investments in securities and other types of investments that may not be frequently traded. There is the possibility that arbitrage market timing, under certain circumstances, may dilute the value of Fund shares if redeeming shareholders receive proceeds (and buying shareholders receive shares) based on NAVs that do not reflect appropriate fair value prices. Each Fund may refuse to sell shares to market timers and will take such other actions necessary to stop excessive or disruptive trading activities, including closing an account to new purchases believed to be held by or for a market timer and as further set out below. The Funds do not accommodate frequent purchases and redemptions of Fund shares by Fund shareholders. The Funds’ Board of Trustees has adopted and implemented the following policies and procedures to discourage and prevent market timing or excessive short-term trading in the Funds: (i) trade activity monitoring; (ii) restricting certain transactions; and (iii) using fair value pricing in certain instances. Each of these procedures is described in more detail below.
Although these procedures are designed to discourage excessive short-term trading, none of these procedures alone nor all of them taken together eliminate the possibility that excessive short-term trading activity in a Fund may occur. Moreover, each of these procedures involves judgments that are inherently subjective. Viking Management and its agents seek to make these judgments to the best of their abilities in a manner that they believe is consistent with shareholder interests. The Funds may modify these procedures in response to changing regulatory requirements imposed by the SEC or to enhance the effectiveness of these procedures and to further restrict trading activities by market timers. Although the Funds and their service providers seek to use these methods to detect and prevent abusive trading activities, there can be no assurances that such activities can be mitigated or eliminated.
Trade Activity Monitoring
The Funds, Viking Management, and their agents monitor selected trades and flows of money in and out of the Funds in an effort to detect excessive short-term trading activities and for consistent enforcement of the procedures. If, as a result of this monitoring, a Fund, Viking Management, or one of their agents believes that a shareholder has engaged in excessive short-term trading, the Transfer Agent will, at its discretion, ask the shareholder to stop such activities or refuse to process purchases or exchanges in the shareholder’s account. The Funds may reject any purchase or exchange orders for any reason, without prior notice, particularly purchase or exchange orders that the Funds believe are made on behalf of market timers.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 54 |
Restrictions on Certain Transactions
In order to prevent market timing, the Funds will impose the following restrictions:
| ● | the Funds will restrict or refuse purchase or exchange orders, for any reason, by those persons that the Funds or Integrity Funds Distributor, LLC (the “Distributor”) believes constitute excessive trading; | |
| ● | the Funds will reject transactions that violate the Funds’ excessive trading policies or their exchange limits; | |
| ● | in order to limit excessive exchange activity and otherwise to promote the best interests of the Funds, the Funds will monitor all redemptions that take place within 30 days of purchase; and | |
| ● | the Funds will process trades received after the close of regular trading on the NYSE (generally 3:00 p.m., Central Time) at the NAV next calculated. |
However, trades transmitted through National Securities Clearing Corporation (“NSCC”) that are received by Integrity Fund Services after 3:00 p.m., Central Time but received by the broker-dealer, bank, or other financial institution transmitting the trade through NSCC before 3:00 p.m., Central Time are processed with the date the trade is received by such financial institution.
Investors are subject to this market timing policy whether a direct shareholder of the Funds or investing indirectly in the Funds through a financial intermediary such as a broker-dealer, a bank, an insurance company separate account, an investment adviser, an administrator, or trustee of an IRS recognized tax-deferred savings plan such as a 401(k) retirement plan and a 529 college savings plan that maintains an omnibus account with the Funds for trading on behalf of its customers.
While the Funds will encourage financial intermediaries to apply the market timing trading policy to their customers who invest indirectly in the Funds, the Funds are limited in their ability to monitor the trading activity or enforce the market timing trading policy with respect to customers of financial intermediaries. For example, should it occur, the Funds may not be able to detect market timing that may be facilitated by financial intermediaries or is difficult to identify because of the omnibus accounts used by those intermediaries for aggregated purchases, exchanges, and redemptions on behalf of all their customers. More specifically, unless the financial intermediaries have the ability to apply the market timing trading policy to their customers (for example, participants in a 401(k) retirement plan) through such methods as implementing short-term trading limitations or restrictions and monitoring trading activity for what might constitute market timing, the Funds may not be able to determine whether trading by customers of financial intermediaries is contrary to the Funds’ market timing trading policy. However, under federal securities law, funds are generally required to enter into shareholder information agreements with certain financial intermediaries that hold fund shares in “omnibus accounts” on behalf of others. Pursuant to these arrangements, the financial intermediary agrees to, among other things provide certain information upon fund request about shareholders and transactions in these accounts to help enable funds to enforce restrictions on market timing and similar abusive transactions. The financial intermediary will also execute any instructions from the fund to restrict or prohibit purchases or exchanges by a shareholder the fund has identified as violating its market timing policies.
Additional Policies
Please note that the Funds maintain additional policies and reserve certain rights, including:
| ● | The Funds may refuse any order to buy shares, including any purchase under the exchange privilege or conversion right. | |
| ● | At any time, the Funds may change their investment minimums or waive or lower their minimums for certain purchases. | |
| ● | The Funds may modify or discontinue the exchange privilege or conversion right on 60 days’ notice. | |
| ● | The Funds are not available for purchase in every jurisdiction. Please consult your investment representative or Integrity Fund Services concerning the availability of a particular Fund. | |
| ● | To permit investors to obtain the current price, dealers are responsible for transmitting all orders to the Funds promptly. | |
| ● | The Funds may modify or discontinue the available sales charge reductions and waivers at any time. | |
| ● | Integrity Fund Services will charge a $15.00 fee against a shareholder’s account for any payment returned for insufficient funds. The shareholder will also be responsible for any losses suffered by the Funds as a result. |
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 55 |
DEALER COMPENSATION
As discussed above, if you purchase your Fund shares through a financial adviser, which includes any broker, dealer, bank, bank trust department, registered investment adviser, financial planner, retirement plan administrator, or any other institutions having a selling, administration, or similar agreement with the Adviser, the Distributor, or one of its affiliates, the financial adviser may receive commissions or other concessions which are paid from various sources, such as from sale charges, Rule 12b-1 distribution and service fees, or otherwise from the Adviser or the Distributor.
The Distributor or one or more of its affiliates may also from time to time make additional payments, out of their own resources, to certain authorized dealers that sell shares of the Integrity/Viking Funds distributed by the Distributor in order to promote the sales and retention of fund shares by those firms and their customers. The amounts of these payments vary by authorized dealer firm and, with respect to a given firm, are typically calculated by reference to the amount of the firm’s recent gross sales of Integrity/Viking Fund shares and/or total assets of Integrity/Viking Funds held by the firm’s customers. The level of payments that the Distributor is willing to provide to a particular authorized dealer firm may be affected by, among other factors, the firm’s total assets held in and recent investments in Integrity/Viking Funds, the firm’s level of participation in Integrity/Viking Funds sales and marketing programs, the firm’s compensation program for its registered representatives who sell Integrity/Viking Fund shares and provide services to Integrity/Viking Funds’ shareholders, and the asset class of the Integrity/Viking Funds for which these payments are provided. For the period from August 1, 2023 through the Funds’ fiscal period ended July 31, 2024, these payments in the aggregate were approximately 0.002% to 0.012% of the assets in the Integrity/Viking Funds, although payments to particular authorized dealers can be significantly higher. The SAI contains additional information about these payments, including the names of the dealer firms to which the payments are expected to be made. This compensation is not reflected in the fees and expenses listed for each Fund under the heading “Fees and Expenses of the Fund” in its Fund Summary because such compensation is not directly paid by the Fund. The Distributor or one or more of its affiliates may also make payments to dealers and other financial intermediaries in connection with sales meetings, due diligence meetings, prospecting seminars and other meetings at which the Distributor promotes its products and services.
The amount of payments by the Distributor and/or its affiliates to a dealer or other financial intermediary could be significant and could create an incentive for the dealer or other intermediary or its representatives to recommend or offer shares of the Funds to you. The dealer or other financial intermediary may elevate the prominence or profile of the Funds within its organization by, for example, placing the Funds on a list of preferred or recommended Funds and/or granting the Distributor and/or its affiliates preferential or enhanced opportunities to promote the Funds in various ways within the dealer’s or other financial intermediary’s organization.
CERTAIN FEES PAID TO FINANCIAL INTERMEDIARIES
Financial intermediaries and retirement plans may have certain accounts and arrangements with the Funds. With respect to such accounts and arrangements, Integrity Fund Services may pay a financial intermediary certain amounts for sub-transfer agency or other administrative services, for which it may receive reimbursement from the Funds. Such sub-transfer agency or other administrative services may include, but are not limited to, the following: processing and mailing trade confirmations, monthly statements, prospectuses, annual reports, semiannual reports and shareholder notices and other required communications for current shareholders; capturing and processing tax data; issuing and mailing dividend checks to current shareholders who have selected cash distributions; preparing record date shareholder lists for proxy solicitations; collecting and posting distributions to shareholder accounts; and establishing and maintaining systematic withdrawals, automated investment plans and shareholder account registrations.
The payments the Funds make to Integrity Fund Services to reimburse it for all or a portion of the sub-transfer agency or other administrative services are in addition to the distribution and service fees that the Funds pay under their Rule 12b-1 plans and the fees that the Funds pay to Integrity Fund Services for the services it provides as the Funds’ transfer agent and accounting and administrative services provider. The aggregate amount of these payments may be substantial and the amounts attributable to particular intermediaries may vary significantly.
SHAREHOLDER INQUIRIES AND MAILINGS
All inquiries regarding the Funds should be directed to:
Integrity Funds Distributor, LLC
PO Box 500
Minot, ND 58702
Phone: 800-276-1262
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 56 |
All inquiries regarding account information should be directed to:
Integrity Fund Services, LLC
PO Box 759
Minot, ND 58702
Phone: 800-601-5593
To reduce expenses, the Funds may mail only one copy of the prospectus and each annual and semi-annual report to those addresses shared by two or more accounts. If you wish to receive individual copies of these documents, please call Integrity Funds Distributor, LLC at 800-276-1262 (or contact your financial institution). We will begin sending you individual copies thirty days after receiving your request.
FINANCIAL HIGHLIGHTS
These financial highlights tables are intended to help you understand each Fund’s financial performance for the past five fiscal years. Certain information reflects financial results for a single Fund share. The total returns in the tables represent the rate that an investor would have earned (or lost) on an investment in each such Fund (assuming reinvestment of all dividends and distributions).
The information shown in these tables for the Funds’ respective fiscal periods has been audited by Cohen & Company, Ltd., the Funds’ independent registered public accounting firm, whose report for the most recent fiscal period, along with the Funds’ financial statements, are included in the Funds’ annual Form N-CSR, which is available upon request.
Further information about a Fund’s performance is contained in the Fund’s latest annual or semi-annual shareholder report and Form N-CSR. You may obtain a free copy of the Fund’s latest annual or semi-annual shareholder report and Form N-CSR upon request from the Fund.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 57 |
Kansas Municipal Fund Class A
Selected per share data and ratios for the periods indicated
| Year | Year | Year | Year | Year | ||||||||||||||||
| Ended | Ended | Ended | Ended | Ended | ||||||||||||||||
| 7/31/24 | 7/31/23 | 7/31/22 | 7/31/21 | 7/31/20 | ||||||||||||||||
| NET ASSET VALUE, BEGINNING OF PERIOD | $ | 9.75 | $ | 10.17 | $ | 11.08 | $ | 11.15 | $ | 10.83 | ||||||||||
| Income (loss) from investment operations: | ||||||||||||||||||||
| Net investment income (loss)(1) | $ | 0.25 | $ | 0.22 | $ | 0.18 | $ | 0.19 | $ | 0.23 | ||||||||||
| Net realized and unrealized gain (loss) on investments(2) | (0.05 | ) | (0.42 | ) | (0.91 | ) | (0.07 | ) | 0.32 | |||||||||||
| Total from investment operations | $ | 0.20 | $ | (0.20 | ) | $ | (0.73 | ) | $ | 0.12 | $ | 0.55 | ||||||||
| Dividends from net investment income | $ | (0.25 | ) | $ | (0.22 | ) | $ | (0.18 | ) | $ | (0.19 | ) | $ | (0.23 | ) | |||||
| NET ASSET VALUE, END OF PERIOD | $ | 9.70 | $ | 9.75 | $ | 10.17 | $ | 11.08 | $ | 11.15 | ||||||||||
| Total Return (excludes any applicable sales charge) | 2.09 | % | (1.98 | %) | (6.62 | %) | 1.05 | % | 5.11 | % | ||||||||||
| RATIOS/SUPPLEMENTAL DATA | ||||||||||||||||||||
| Net assets, end of period (in thousands) | $ | 52,202 | $ | 55,633 | $ | 60,816 | $ | 70,686 | $ | 63,309 | ||||||||||
| Ratio of expenses to average net assets after waivers(3) | 0.98 | % | 0.98 | % | 0.98 | % | 0.98 | % | 0.98 | % | ||||||||||
| Ratio of expenses to average net assets before waivers | 1.18 | % | 1.17 | % | 1.15 | % | 1.15 | % | 1.17 | % | ||||||||||
| Ratio of net investment income to average net assets(3) | 2.59 | % | 2.21 | % | 1.75 | % | 1.67 | % | 2.06 | % | ||||||||||
| Portfolio turnover rate | 29.19 | % | 33.60 | % | 15.28 | % | 4.30 | % | 15.21 | % | ||||||||||
| (1) | Per share net investment income (loss) has been calculated using the average daily shares method. |
| (2) | Net realized and unrealized gain/(loss) per share are balancing amounts necessary to reconcile the change in net asset value per share for the period, and may not reconcile with the aggregate gains and losses in the statement of operations due to share transactions for the period. |
| (3) | This row reflects the impact, if any, of fee waivers or reimbursements by the Adviser and/or affiliated service providers. |
Total return represents the rate that an investor would have earned or lost on an investment in the Fund assuming reinvestment of all dividends and distributions.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 58 |
Kansas Municipal Fund Class I
Selected per share data and ratios for the periods indicated
| Year | Year | Year | Year | Year | ||||||||||||||||
| Ended | Ended | Ended | Ended | Ended | ||||||||||||||||
| 7/31/24 | 7/31/23 | 7/31/22 | 7/31/21 | 7/31/20 | ||||||||||||||||
| NET ASSET VALUE, BEGINNING OF PERIOD | $ | 9.75 | $ | 10.17 | $ | 11.08 | $ | 11.15 | $ | 10.83 | ||||||||||
| Income (loss) from investment operations: | ||||||||||||||||||||
| Net investment income (loss)(1) | $ | 0.27 | $ | 0.24 | $ | 0.20 | $ | 0.21 | $ | 0.25 | ||||||||||
| Net realized and unrealized gain (loss) on investments(2) | (0.04 | ) | (0.42 | ) | (0.91 | ) | (0.07 | ) | 0.32 | |||||||||||
| Total from investment operations | $ | 0.23 | $ | (0.18 | ) | $ | (0.71 | ) | $ | 0.14 | $ | 0.57 | ||||||||
| Dividends from net investment income | $ | (0.27 | ) | $ | (0.24 | ) | $ | (0.20 | ) | $ | (0.21 | ) | $ | (0.25 | ) | |||||
| NET ASSET VALUE, END OF PERIOD | $ | 9.71 | $ | 9.75 | $ | 10.17 | $ | 11.08 | $ | 11.15 | ||||||||||
| Total Return (excludes any applicable sales charge) | 2.45 | % | (1.74 | %) | (6.38 | %) | 1.30 | % | 5.36 | % | ||||||||||
| RATIOS/SUPPLEMENTAL DATA | ||||||||||||||||||||
| Net assets, end of period (in thousands) | $ | 6,630 | $ | 7,798 | $ | 10,443 | $ | 10,503 | $ | 6,756 | ||||||||||
| Ratio of expenses to average net assets after waivers(3) | 0.73 | % | 0.73 | % | 0.73 | % | 0.73 | % | 0.73 | % | ||||||||||
| Ratio of expenses to average net assets before waivers | 0.93 | % | 0.92 | % | 0.90 | % | 0.90 | % | 0.92 | % | ||||||||||
| Ratio of net investment income to average net assets(3) | 2.84 | % | 2.46 | % | 1.97 | % | 1.92 | % | 2.31 | % | ||||||||||
| Portfolio turnover rate | 29.19 | % | 33.60 | % | 15.28 | % | 4.30 | % | 15.21 | % | ||||||||||
| (1) | Per share net investment income (loss) has been calculated using the average daily shares method. |
| (2) | Net realized and unrealized gain/(loss) per share are balancing amounts necessary to reconcile the change in net asset value per share for the period, and may not reconcile with the aggregate gains and losses in the statement of operations due to share transactions for the period. |
| (3) | This row reflects the impact, if any, of fee waivers or reimbursements by the Adviser and/or affiliated service providers. |
Total return represents the rate that an investor would have earned or lost on an investment in the Fund assuming reinvestment of all dividends and distributions.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 59 |
Maine Municipal Fund Class A
Selected per share data and ratios for the periods indicated
| Year | Year | Year | Year | Year | ||||||||||||||||
| Ended | Ended | Ended | Ended | Ended | ||||||||||||||||
| 7/31/24 | 7/31/23 | 7/31/22 | 7/31/21 | 7/31/20 | ||||||||||||||||
| NET ASSET VALUE, BEGINNING OF PERIOD | $ | 9.49 | $ | 9.87 | $ | 10.89 | $ | 10.97 | $ | 10.85 | ||||||||||
| Income (loss) from investment operations: | ||||||||||||||||||||
| Net investment income (loss)(1) | $ | 0.25 | $ | 0.21 | $ | 0.18 | $ | 0.19 | $ | 0.21 | ||||||||||
| Net realized and unrealized gain (loss) on investments(2) | 0.03 | (0.38 | ) | (1.02 | ) | (0.08 | ) | 0.12 | ||||||||||||
| Total from investment operations | $ | 0.28 | $ | (0.17 | ) | $ | (0.84 | ) | $ | 0.11 | $ | 0.33 | ||||||||
| Dividends from net investment income | $ | (0.25 | ) | $ | (0.21 | ) | $ | (0.18 | ) | $ | (0.19 | ) | $ | (0.21 | ) | |||||
| NET ASSET VALUE, END OF PERIOD | $ | 9.52 | $ | 9.49 | $ | 9.87 | $ | 10.89 | $ | 10.97 | ||||||||||
| Total Return (excludes any applicable sales charge) | 3.05 | % | (1.74 | %) | (7.74 | %) | 1.00 | % | 3.08 | % | ||||||||||
| RATIOS/SUPPLEMENTAL DATA | ||||||||||||||||||||
| Net assets, end of period (in thousands) | $ | 8,421 | $ | 9,818 | $ | 10,908 | $ | 13,477 | $ | 14,573 | ||||||||||
| Ratio of expenses to average net assets after waivers(3) | 0.98 | % | 0.98 | % | 0.98 | % | 0.98 | % | 0.98 | % | ||||||||||
| Ratio of expenses to average net assets before waivers | 1.54 | % | 1.53 | % | 1.46 | % | 1.40 | % | 1.40 | % | ||||||||||
| Ratio of net investment income to average net assets(3) | 2.69 | % | 2.16 | % | 1.76 | % | 1.73 | % | 1.94 | % | ||||||||||
| Portfolio turnover rate | 69.10 | % | 0.00 | % | 9.66 | % | 15.80 | % | 22.13 | % | ||||||||||
| (1) | Per share net investment income (loss) has been calculated using the average daily shares method. |
| (2) | Net realized and unrealized gain/(loss) per share are balancing amounts necessary to reconcile the change in net asset value per share for the period, and may not reconcile with the aggregate gains and losses in the statement of operations due to share transactions for the period. |
| (3) | This row reflects the impact, if any, of fee waivers or reimbursements by the Adviser and/or affiliated service providers. |
Total return represents the rate that an investor would have earned or lost on an investment in the Fund assuming reinvestment of all dividends and distributions.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 60 |
Maine Municipal Fund Class I
Selected per share data and ratios for the periods indicated
| Year | Year | Year | Year | Year | ||||||||||||||||
| Ended | Ended | Ended | Ended | Ended | ||||||||||||||||
| 7/31/24 | 7/31/23 | 7/31/22 | 7/31/21 | 7/31/20 | ||||||||||||||||
| NET ASSET VALUE, BEGINNING OF PERIOD | $ | 9.49 | $ | 9.87 | $ | 10.89 | $ | 10.98 | $ | 10.85 | ||||||||||
| Income (loss) from investment operations: | ||||||||||||||||||||
| Net investment income (loss)(1) | $ | 0.28 | $ | 0.23 | $ | 0.21 | $ | 0.22 | $ | 0.24 | ||||||||||
| Net realized and unrealized gain (loss) on investments(2) | 0.03 | (0.38 | ) | (1.02 | ) | (0.09 | ) | 0.13 | ||||||||||||
| Total from investment operations | $ | 0.31 | $ | (0.15 | ) | $ | (0.81 | ) | $ | 0.13 | $ | 0.37 | ||||||||
| Dividends from net investment income | $ | (0.28 | ) | $ | (0.23 | ) | $ | (0.21 | ) | $ | (0.22 | ) | $ | (0.24 | ) | |||||
| NET ASSET VALUE, END OF PERIOD | $ | 9.52 | $ | 9.49 | $ | 9.87 | $ | 10.89 | $ | 10.98 | ||||||||||
| Total Return (excludes any applicable sales charge) | 3.30 | % | (1.50 | %) | (7.52 | %) | 1.16 | % | 3.43 | % | ||||||||||
| RATIOS/SUPPLEMENTAL DATA | ||||||||||||||||||||
| Net assets, end of period (in thousands) | $ | 123 | $ | 517 | $ | 602 | $ | 973 | $ | 1,063 | ||||||||||
| Ratio of expenses to average net assets after waivers(3) | 0.73 | % | 0.73 | % | 0.73 | % | 0.73 | % | 0.73 | % | ||||||||||
| Ratio of expenses to average net assets before waivers | 1.29 | % | 1.28 | % | 1.21 | % | 1.15 | % | 1.15 | % | ||||||||||
| Ratio of net investment income to average net assets(3) | 2.94 | % | 2.41 | % | 2.01 | % | 1.98 | % | 2.19 | % | ||||||||||
| Portfolio turnover rate | 69.10 | % | 0.00 | % | 9.66 | % | 15.80 | % | 22.13 | % | ||||||||||
| (1) | Per share net investment income (loss) has been calculated using the average daily shares method. |
| (2) | Net realized and unrealized gain/(loss) per share are balancing amounts necessary to reconcile the change in net asset value per share for the period, and may not reconcile with the aggregate gains and losses in the statement of operations due to share transactions for the period. |
| (3) | This row reflects the impact, if any, of fee waivers or reimbursements by the Adviser and/or affiliated service providers. |
Total return represents the rate that an investor would have earned or lost on an investment in the Fund assuming reinvestment of all dividends and distributions.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 61 |
Nebraska Municipal Fund Class A
Selected per share data and ratios for the periods indicated
| Year | Year | Year | Year | Year | ||||||||||||||||
| Ended | Ended | Ended | Ended | Ended | ||||||||||||||||
| 7/31/24 | 7/31/23 | 7/31/22 | 7/31/21 | 7/31/20 | ||||||||||||||||
| NET ASSET VALUE, BEGINNING OF PERIOD | $ | 9.47 | $ | 9.81 | $ | 10.64 | $ | 10.77 | $ | 10.58 | ||||||||||
| Income (loss) from investment operations: | ||||||||||||||||||||
| Net investment income (loss)(1) | $ | 0.26 | $ | 0.19 | $ | 0.15 | $ | 0.17 | $ | 0.21 | ||||||||||
| Net realized and unrealized gain (loss) on investments(2) | (0.09 | ) | (0.34 | ) | (0.83 | ) | (0.13 | ) | 0.19 | |||||||||||
| Total from investment operations | $ | 0.17 | $ | (0.15 | ) | $ | (0.68 | ) | $ | 0.04 | $ | 0.40 | ||||||||
| Dividends from net investment income | $ | (0.26 | ) | $ | (0.19 | ) | $ | (0.15 | ) | $ | (0.17 | ) | $ | (0.21 | ) | |||||
| NET ASSET VALUE, END OF PERIOD | $ | 9.38 | $ | 9.47 | $ | 9.81 | $ | 10.64 | $ | 10.77 | ||||||||||
| Total Return (excludes any applicable sales charge) | 1.87 | % | (1.56 | %) | (6.39 | %) | 0.38 | % | 3.81 | % | ||||||||||
| RATIOS/SUPPLEMENTAL DATA | ||||||||||||||||||||
| Net assets, end of period (in thousands) | $ | 29,749 | $ | 33,188 | $ | 49,780 | $ | 55,363 | $ | 51,557 | ||||||||||
| Ratio of expenses to average net assets after waivers(3) | 0.98 | % | 0.98 | % | 0.98 | % | 0.98 | % | 0.98 | % | ||||||||||
| Ratio of expenses to average net assets before waivers | 1.24 | % | 1.20 | % | 1.17 | % | 1.18 | % | 1.19 | % | ||||||||||
| Ratio of net investment income to average net assets(3) | 2.81 | % | 1.93 | % | 1.51 | % | 1.59 | % | 1.96 | % | ||||||||||
| Portfolio turnover rate | 79.45 | % | 19.33 | % | 26.33 | % | 8.21 | % | 13.06 | % | ||||||||||
| (1) | Per share net investment income (loss) has been calculated using the average daily shares method. |
| (2) | Net realized and unrealized gain/(loss) per share are balancing amounts necessary to reconcile the change in net asset value per share for the period, and may not reconcile with the aggregate gains and losses in the statement of operations due to share transactions for the period. |
| (3) | This row reflects the impact, if any, of fee waivers or reimbursements by the Adviser and/or affiliated service providers. |
Total return represents the rate that an investor would have earned or lost on an investment in the Fund assuming reinvestment of all dividends and distributions.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 62 |
Nebraska Municipal Fund Class I
Selected per share data and ratios for the periods indicated
| Year | Year | Year | Year | Year | ||||||||||||||||
| Ended | Ended | Ended | Ended | Ended | ||||||||||||||||
| 7/31/24 | 7/31/23 | 7/31/22 | 7/31/21 | 7/31/20 | ||||||||||||||||
| NET ASSET VALUE, BEGINNING OF PERIOD | $ | 9.47 | $ | 9.81 | $ | 10.63 | $ | 10.76 | $ | 10.57 | ||||||||||
| Income (loss) from investment operations: | ||||||||||||||||||||
| Net investment income (loss)(1) | $ | 0.29 | $ | 0.21 | $ | 0.18 | $ | 0.20 | $ | 0.23 | ||||||||||
| Net realized and unrealized gain (loss) on investments(2) | (0.10 | ) | (0.34 | ) | (0.82 | ) | (0.13 | ) | 0.19 | |||||||||||
| Total from investment operations | $ | 0.19 | $ | (0.13 | ) | $ | (0.64 | ) | $ | 0.07 | $ | 0.42 | ||||||||
| Dividends from net investment income | $ | (0.29 | ) | $ | (0.21 | ) | $ | (0.18 | ) | $ | (0.20 | ) | $ | (0.23 | ) | |||||
| NET ASSET VALUE, END OF PERIOD | $ | 9.37 | $ | 9.47 | $ | 9.81 | $ | 10.63 | $ | 10.76 | ||||||||||
| Total Return (excludes any applicable sales charge) | 2.02 | % | (1.32 | %) | (6.07 | %) | 0.63 | % | 4.07 | % | ||||||||||
| RATIOS/SUPPLEMENTAL DATA | ||||||||||||||||||||
| Net assets, end of period (in thousands) | $ | 2,966 | $ | 3,695 | $ | 2,520 | $ | 2,495 | $ | 1,660 | ||||||||||
| Ratio of expenses to average net assets after waivers(3) | 0.73 | % | 0.73 | % | 0.73 | % | 0.73 | % | 0.73 | % | ||||||||||
| Ratio of expenses to average net assets before waivers | 0.99 | % | 0.95 | % | 0.92 | % | 0.93 | % | 0.94 | % | ||||||||||
| Ratio of net investment income to average net assets(3) | 3.06 | % | 2.18 | % | 1.76 | % | 1.84 | % | 2.21 | % | ||||||||||
| Portfolio turnover rate | 79.45 | % | 19.33 | % | 26.33 | % | 8.21 | % | 13.06 | % | ||||||||||
| (1) | Per share net investment income (loss) has been calculated using the average daily shares method. |
| (2) | Net realized and unrealized gain/(loss) per share are balancing amounts necessary to reconcile the change in net asset value per share for the period, and may not reconcile with the aggregate gains and losses in the statement of operations due to share transactions for the period. |
| (3) | This row reflects the impact, if any, of fee waivers or reimbursements by the Adviser and/or affiliated service providers. |
Total return represents the rate that an investor would have earned or lost on an investment in the Fund assuming reinvestment of all dividends and distributions.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 63 |
Oklahoma Municipal Fund Class A
Selected per share data and ratios for the periods indicated
| Year | Year | Year | Year | Year | ||||||||||||||||
| Ended | Ended | Ended | Ended | Ended | ||||||||||||||||
| 7/31/24 | 7/31/23 | 7/31/22 | 7/31/21 | 7/31/20 | ||||||||||||||||
| NET ASSET VALUE, BEGINNING OF PERIOD | $ | 10.64 | $ | 11.02 | $ | 12.14 | $ | 12.08 | $ | 11.86 | ||||||||||
| Income (loss) from investment operations: | ||||||||||||||||||||
| Net investment income (loss)(1) | $ | 0.29 | $ | 0.23 | $ | 0.17 | $ | 0.18 | $ | 0.24 | ||||||||||
| Net realized and unrealized gain (loss) on investments(2) | (0.05 | ) | (0.38 | ) | (1.12 | ) | 0.06 | 0.22 | ||||||||||||
| Total from investment operations | $ | 0.24 | $ | (0.15 | ) | $ | (0.95 | ) | $ | 0.24 | $ | 0.46 | ||||||||
| Dividends from net investment income | $ | (0.29 | ) | $ | (0.23 | ) | $ | (0.17 | ) | $ | (0.18 | ) | $ | (0.24 | ) | |||||
| NET ASSET VALUE, END OF PERIOD | $ | 10.59 | $ | 10.64 | $ | 11.02 | $ | 12.14 | $ | 12.08 | ||||||||||
| Total Return (excludes any applicable sales charge) | 2.33 | % | (1.34 | %) | (7.88 | %) | 2.03 | % | 3.92 | % | ||||||||||
| RATIOS/SUPPLEMENTAL DATA | ||||||||||||||||||||
| Net assets, end of period (in thousands) | $ | 42,700 | $ | 51,337 | $ | 61,402 | $ | 77,021 | $ | 62,321 | ||||||||||
| Ratio of expenses to average net assets after waivers(3) | 0.98 | % | 0.98 | % | 0.98 | % | 0.98 | % | 0.98 | % | ||||||||||
| Ratio of expenses to average net assets before waivers | 1.18 | % | 1.18 | % | 1.15 | % | 1.14 | % | 1.17 | % | ||||||||||
| Ratio of net investment income to average net assets(3) | 2.77 | % | 2.16 | % | 1.45 | % | 1.51 | % | 1.99 | % | ||||||||||
| Portfolio turnover rate | 69.12 | % | 22.50 | % | 38.98 | % | 11.13 | % | 13.69 | % | ||||||||||
| (1) | Per share net investment income (loss) has been calculated using the average daily shares method. |
| (2) | Net realized and unrealized gain/(loss) per share are balancing amounts necessary to reconcile the change in net asset value per share for the period, and may not reconcile with the aggregate gains and losses in the statement of operations due to share transactions for the period. |
| (3) | This row reflects the impact, if any, of fee waivers or reimbursements by the Adviser and/or affiliated service providers. |
Total return represents the rate that an investor would have earned or lost on an investment in the Fund assuming reinvestment of all dividends and distributions.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 64 |
Oklahoma Municipal Fund Class I
Selected per share data and ratios for the periods indicated
| Year | Year | Year | Year | Year | ||||||||||||||||
| Ended | Ended | Ended | Ended | Ended | ||||||||||||||||
| 7/31/24 | 7/31/23 | 7/31/22 | 7/31/21 | 7/31/20 | ||||||||||||||||
| NET ASSET VALUE, BEGINNING OF PERIOD | $ | 10.65 | $ | 11.03 | $ | 12.15 | $ | 12.09 | $ | 11.87 | ||||||||||
| Income (loss) from investment operations: | ||||||||||||||||||||
| Net investment income (loss)(1) | $ | 0.32 | $ | 0.26 | $ | 0.20 | $ | 0.21 | $ | 0.27 | ||||||||||
| Net realized and unrealized gain (loss) on investments(2) | (0.05 | ) | (0.38 | ) | (1.12 | ) | 0.06 | 0.22 | ||||||||||||
| Total from investment operations | $ | 0.27 | $ | (0.12 | ) | $ | (0.92 | ) | $ | 0.27 | $ | 0.49 | ||||||||
| Dividends from net investment income | $ | (0.32 | ) | $ | (0.26 | ) | $ | (0.20 | ) | $ | (0.21 | ) | $ | (0.27 | ) | |||||
| NET ASSET VALUE, END OF PERIOD | $ | 10.60 | $ | 10.65 | $ | 11.03 | $ | 12.15 | $ | 12.09 | ||||||||||
| Total Return (excludes any applicable sales charge) | 2.59 | % | (1.09 | %) | (7.64 | %) | 2.29 | % | 4.18 | % | ||||||||||
| RATIOS/SUPPLEMENTAL DATA | ||||||||||||||||||||
| Net assets, end of period (in thousands) | $ | 2,275 | $ | 3,321 | $ | 3,216 | $ | 4,970 | $ | 4,799 | ||||||||||
| Ratio of expenses to average net assets after waivers(3) | 0.73 | % | 0.73 | % | 0.73 | % | 0.73 | % | 0.73 | % | ||||||||||
| Ratio of expenses to average net assets before waivers | 0.93 | % | 0.93 | % | 0.90 | % | 0.89 | % | 0.92 | % | ||||||||||
| Ratio of net investment income to average net assets(3) | 3.02 | % | 2.41 | % | 1.70 | % | 1.76 | % | 2.25 | % | ||||||||||
| Portfolio turnover rate | 69.12 | % | 22.50 | % | 38.98 | % | 11.13 | % | 13.69 | % | ||||||||||
| (1) | Per share net investment income (loss) has been calculated using the average daily shares method. |
| (2) | Net realized and unrealized gain/(loss) per share are balancing amounts necessary to reconcile the change in net asset value per share for the period, and may not reconcile with the aggregate gains and losses in the statement of operations due to share transactions for the period. |
| (3) | This row reflects the impact, if any, of fee waivers or reimbursements by the Adviser and/or affiliated service providers. |
Total return represents the rate that an investor would have earned or lost on an investment in the Fund assuming reinvestment of all dividends and distributions.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 65 |
Viking Tax-Free Fund for Montana Class A
Selected per share data and ratios for the periods indicated
| Year | Year | Year | Year | Year | ||||||||||||||||
| Ended | Ended | Ended | Ended | Ended | ||||||||||||||||
| 7/31/24 | 7/31/23 | 7/31/22 | 7/31/21 | 7/31/20 | ||||||||||||||||
| NET ASSET VALUE, BEGINNING OF PERIOD | $ | 9.22 | $ | 9.51 | $ | 10.34 | $ | 10.35 | $ | 10.18 | ||||||||||
| Income (loss) from investment operations: | ||||||||||||||||||||
| Net investment income (loss)(1) | $ | 0.25 | $ | 0.22 | $ | 0.17 | $ | 0.17 | $ | 0.22 | ||||||||||
| Net realized and unrealized gain (loss) on investments(2) | (0.07 | ) | (0.29 | ) | (0.83 | ) | (0.01 | ) | 0.17 | |||||||||||
| Total from investment operations | $ | 0.18 | $ | (0.07 | ) | $ | (0.66 | ) | $ | 0.16 | $ | 0.39 | ||||||||
| Dividends from net investment income | $ | (0.25 | ) | $ | (0.22 | ) | $ | (0.17 | ) | $ | (0.17 | ) | $ | (0.22 | ) | |||||
| NET ASSET VALUE, END OF PERIOD | $ | 9.15 | $ | 9.22 | $ | 9.51 | $ | 10.34 | $ | 10.35 | ||||||||||
| Total Return (excludes any applicable sales charge) | 1.98 | % | (0.76 | %) | (6.46 | %) | 1.57 | % | 3.89 | % | ||||||||||
| RATIOS/SUPPLEMENTAL DATA | ||||||||||||||||||||
| Net assets, end of period (in thousands) | $ | 50,466 | $ | 54,906 | $ | 65,357 | $ | 79,710 | $ | 72,738 | ||||||||||
| Ratio of expenses to average net assets after waivers(3) | 0.98 | % | 0.98 | % | 0.98 | % | 0.98 | % | 0.98 | % | ||||||||||
| Ratio of expenses to average net assets before waivers | 1.17 | % | 1.17 | % | 1.14 | % | 1.13 | % | 1.15 | % | ||||||||||
| Ratio of net investment income to average net assets(3) | 2.72 | % | 2.33 | % | 1.68 | % | 1.65 | % | 2.15 | % | ||||||||||
| Portfolio turnover rate | 31.96 | % | 16.20 | % | 26.78 | % | 12.00 | % | 10.52 | % | ||||||||||
| (1) | Per share net investment income (loss) has been calculated using the average daily shares method. |
| (2) | Net realized and unrealized gain/(loss) per share are balancing amounts necessary to reconcile the change in net asset value per share for the period, and may not reconcile with the aggregate gains and losses in the statement of operations due to share transactions for the period. |
| (3) | This row reflects the impact, if any, of fee waivers or reimbursements by the Adviser and/or affiliated service providers. |
Total return represents the rate that an investor would have earned or lost on an investment in the Fund assuming reinvestment of all dividends and distributions.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 66 |
Viking Tax-Free Fund for Montana Class I
Selected per share data and ratios for the periods indicated
| Year | Year | Year | Year | Year | ||||||||||||||||
| Ended | Ended | Ended | Ended | Ended | ||||||||||||||||
| 7/31/24 | 7/31/23 | 7/31/22 | 7/31/21 | 7/31/20 | ||||||||||||||||
| NET ASSET VALUE, BEGINNING OF PERIOD | $ | 9.22 | $ | 9.51 | $ | 10.34 | $ | 10.35 | $ | 10.18 | ||||||||||
| Income (loss) from investment operations: | ||||||||||||||||||||
| Net investment income (loss)(1) | $ | 0.27 | $ | 0.24 | $ | 0.19 | $ | 0.20 | $ | 0.25 | ||||||||||
| Net realized and unrealized gain (loss) on investments(2) | (0.07 | ) | (0.29 | ) | (0.83 | ) | (0.01 | ) | 0.17 | |||||||||||
| Total from investment operations | $ | 0.20 | $ | (0.05 | ) | $ | (0.64 | ) | $ | 0.19 | $ | 0.42 | ||||||||
| Dividends from net investment income | $ | (0.27 | ) | $ | (0.24 | ) | $ | (0.19 | ) | $ | (0.20 | ) | $ | (0.25 | ) | |||||
| NET ASSET VALUE, END OF PERIOD | $ | 9.15 | $ | 9.22 | $ | 9.51 | $ | 10.34 | $ | 10.35 | ||||||||||
| Total Return (excludes any applicable sales charge) | 2.23 | % | (0.51 | %) | (6.21 | %) | 1.82 | % | 4.15 | % | ||||||||||
| RATIOS/SUPPLEMENTAL DATA | ||||||||||||||||||||
| Net assets, end of period (in thousands) | $ | 10,247 | $ | 11,607 | $ | 15,776 | $ | 18,055 | $ | 13,456 | ||||||||||
| Ratio of expenses to average net assets after waivers(3) | 0.73 | % | 0.73 | % | 0.73 | % | 0.73 | % | 0.73 | % | ||||||||||
| Ratio of expenses to average net assets before waivers | 0.92 | % | 0.92 | % | 0.89 | % | 0.88 | % | 0.90 | % | ||||||||||
| Ratio of net investment income to average net assets(3) | 2.97 | % | 2.58 | % | 1.93 | % | 1.90 | % | 2.40 | % | ||||||||||
| Portfolio turnover rate | 31.96 | % | 16.20 | % | 26.78 | % | 12.00 | % | 10.52 | % | ||||||||||
| (1) | Per share net investment income (loss) has been calculated using the average daily shares method. |
| (2) | Net realized and unrealized gain/(loss) per share are balancing amounts necessary to reconcile the change in net asset value per share for the period, and may not reconcile with the aggregate gains and losses in the statement of operations due to share transactions for the period. |
| (3) | This row reflects the impact, if any, of fee waivers or reimbursements by the Adviser and/or affiliated service providers. |
Total return represents the rate that an investor would have earned or lost on an investment in the Fund assuming reinvestment of all dividends and distributions.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 67 |
Viking Tax-Free Fund for North Dakota Class A
Selected per share data and ratios for the periods indicated
| Year | Year | Year | Year | Year | ||||||||||||||||
| Ended | Ended | Ended | Ended | Ended | ||||||||||||||||
| 7/31/24 | 7/31/23 | 7/31/22 | 7/31/21 | 7/31/20 | ||||||||||||||||
| NET ASSET VALUE, BEGINNING OF PERIOD | $ | 9.11 | $ | 9.51 | $ | 10.36 | $ | 10.39 | $ | 10.31 | ||||||||||
| Income (loss) from investment operations: | ||||||||||||||||||||
| Net investment income (loss)(1) | $ | 0.24 | $ | 0.19 | $ | 0.16 | $ | 0.19 | $ | 0.23 | ||||||||||
| Net realized and unrealized gain (loss) on investments(2) | (0.12 | ) | (0.40 | ) | (0.85 | ) | (0.03 | ) | 0.08 | |||||||||||
| Total from investment operations | $ | 0.12 | $ | (0.21 | ) | $ | (0.69 | ) | $ | 0.16 | $ | 0.31 | ||||||||
| Dividends from net investment income | $ | (0.24 | ) | $ | (0.19 | ) | $ | (0.16 | ) | $ | (0.19 | ) | $ | (0.23 | ) | |||||
| NET ASSET VALUE, END OF PERIOD | $ | 8.99 | $ | 9.11 | $ | 9.51 | $ | 10.36 | $ | 10.39 | ||||||||||
| Total Return (excludes any applicable sales charge) | 1.35 | % | (2.18 | %) | (6.70 | %) | 1.57 | % | 3.06 | % | ||||||||||
| RATIOS/SUPPLEMENTAL DATA | ||||||||||||||||||||
| Net assets, end of period (in thousands) | $ | 19,274 | $ | 22,552 | $ | 27,459 | $ | 30,747 | $ | 28,719 | ||||||||||
| Ratio of expenses to average net assets after waivers(3) | 0.98 | % | 0.98 | % | 0.98 | % | 0.98 | % | 0.98 | % | ||||||||||
| Ratio of expenses to average net assets before waivers | 1.30 | % | 1.28 | % | 1.23 | % | 1.24 | % | 1.26 | % | ||||||||||
| Ratio of net investment income to average net assets(3) | 2.67 | % | 2.08 | % | 1.63 | % | 1.85 | % | 2.25 | % | ||||||||||
| Portfolio turnover rate | 55.91 | % | 12.19 | % | 22.82 | % | 22.02 | % | 21.95 | % | ||||||||||
| (1) | Per share net investment income (loss) has been calculated using the average daily shares method. |
| (2) | Net realized and unrealized gain/(loss) per share are balancing amounts necessary to reconcile the change in net asset value per share for the period, and may not reconcile with the aggregate gains and losses in the statement of operations due to share transactions for the period. |
| (3) | This row reflects the impact, if any, of fee waivers or reimbursements by the Adviser and/or affiliated service providers. |
Total return represents the rate that an investor would have earned or lost on an investment in the Fund assuming reinvestment of all dividends and distributions.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 68 |
Viking Tax-Free Fund for North Dakota Class I
Selected per share data and ratios for the periods indicated
| Year | Year | Year | Year | Year | ||||||||||||||||
| Ended | Ended | Ended | Ended | Ended | ||||||||||||||||
| 7/31/24 | 7/31/23 | 7/31/22 | 7/31/21 | 7/31/20 | ||||||||||||||||
| NET ASSET VALUE, BEGINNING OF PERIOD | $ | 9.11 | $ | 9.51 | $ | 10.36 | $ | 10.39 | $ | 10.32 | ||||||||||
| Income (loss) from investment operations: | ||||||||||||||||||||
| Net investment income (loss)(1) | $ | 0.26 | $ | 0.21 | $ | 0.19 | $ | 0.22 | $ | 0.26 | ||||||||||
| Net realized and unrealized gain (loss) on investments(2) | (0.12 | ) | (0.40 | ) | (0.85 | ) | (0.03 | ) | 0.07 | |||||||||||
| Total from investment operations | $ | 0.14 | $ | (0.19 | ) | $ | (0.66 | ) | $ | 0.19 | $ | 0.33 | ||||||||
| Dividends from net investment income | $ | (0.26 | ) | $ | (0.21 | ) | $ | (0.19 | ) | $ | (0.22 | ) | $ | (0.26 | ) | |||||
| NET ASSET VALUE, END OF PERIOD | $ | 8.99 | $ | 9.11 | $ | 9.51 | $ | 10.36 | $ | 10.39 | ||||||||||
| Total Return (excludes any applicable sales charge) | 1.61 | % | (1.94 | %) | (6.46 | %) | 1.83 | % | 3.22 | % | ||||||||||
| RATIOS/SUPPLEMENTAL DATA | ||||||||||||||||||||
| Net assets, end of period (in thousands) | $ | 1,357 | $ | 1,491 | $ | 1,631 | $ | 2,069 | $ | 2,150 | ||||||||||
| Ratio of expenses to average net assets after waivers(3) | 0.73 | % | 0.73 | % | 0.73 | % | 0.73 | % | 0.73 | % | ||||||||||
| Ratio of expenses to average net assets before waivers | 1.05 | % | 1.03 | % | 0.98 | % | 0.99 | % | 1.01 | % | ||||||||||
| Ratio of net investment income to average net assets(3) | 2.92 | % | 2.33 | % | 1.88 | % | 2.10 | % | 2.50 | % | ||||||||||
| Portfolio turnover rate | 55.91 | % | 12.19 | % | 22.82 | % | 22.02 | % | 21.95 | % | ||||||||||
| (1) | Per share net investment income (loss) has been calculated using the average daily shares method. |
| (2) | Net realized and unrealized gain/(loss) per share are balancing amounts necessary to reconcile the change in net asset value per share for the period, and may not reconcile with the aggregate gains and losses in the statement of operations due to share transactions for the period. |
| (3) | This row reflects the impact, if any, of fee waivers or reimbursements by the Adviser and/or affiliated service providers. |
Total return represents the rate that an investor would have earned or lost on an investment in the Fund assuming reinvestment of all dividends and distributions.
| Viking Mutual Funds | Prospectus | November 30, 2024 Page 69 |
APPENDIX A—INTERMEDIARY-SPECIFIC SALES CHARGE WAIVERS AND DISCOUNTS
The sales charge reductions and waivers applicable to Fund shares purchased through Edward Jones, Raymond James, Oppenheimer & Co. Inc., Robert W. Baird & Co., and Morgan Stanley Wealth Management are set forth below. The financial intermediary-specific information below is provided by, or based on information provided by, the financial intermediaries noted. Each financial intermediary’s transaction procedures, including the sales charge reductions and waivers set forth below, are implemented by and are the responsibility of the applicable financial intermediary set forth below, not the Fund. You should consult with your intermediary for additional information or if you have questions regarding its sales charge reductions and waivers.
Policies Regarding Transactions through Edward D. Jones & Co., L.P. (“Edward Jones”)
The following information has been provided by Edward Jones:
Effective on or after September 3, 2024, the following information supersedes prior information with respect to transactions and positions held in fund shares through an Edward Jones system. Clients of Edward Jones (also referred to as “shareholders”) purchasing fund shares on the Edward Jones commission and fee-based platforms are eligible only for the following sales charge discounts (also referred to as “breakpoints”) and waivers, which can differ from discounts and waivers described elsewhere in the mutual fund prospectus or statement of additional information (“SAI”) or through another broker-dealer. In all instances, it is the shareholder’s responsibility to inform Edward Jones at the time of purchase of any relationship, holdings of Integrity/Viking Funds, or other facts qualifying the purchaser for discounts or waivers. Edward Jones can ask for documentation of such circumstance. Shareholders should contact Edward Jones if they have questions regarding their eligibility for these discounts and waivers.
Breakpoints
| ● | Breakpoint pricing, otherwise known as volume pricing, at dollar thresholds as described in the prospectus. |
Rights of Accumulation (“ROA”)
| ● | The applicable sales charge on a purchase of Class A shares is determined by taking into account all share classes (except certain money market funds and any assets held in group retirement plans) of the mutual fund family held by the shareholder or in an account grouped by Edward Jones with other accounts for the purpose of providing certain pricing considerations (“pricing groups”). If grouping assets as a shareholder, this includes all share classes held on the Edward Jones platform and/or held on another platform. The inclusion of eligible fund family assets in the ROA calculation is dependent on the shareholder notifying Edward Jones of such assets at the time of calculation. Money market funds are included only if such shares were sold with a sales charge at the time of purchase or acquired in exchange for shares purchased with a sales charge. |
| ● | The employer maintaining a SEP IRA plan and/or SIMPLE IRA plan may elect to establish or change ROA for the IRA accounts associated with the plan to a plan-level grouping as opposed to including all share classes at a shareholder or pricing group level. |
| ● | ROA is determined by calculating the higher of cost minus redemptions or market value (current shares x NAV). |
Letter of Intent (“LOI”)
| ● | Through a LOI, shareholders can receive the sales charge and breakpoint discounts for purchases shareholders intend to make over a 13-month period from the date Edward Jones receives the LOI. The LOI is determined by calculating the higher of cost or market value of qualifying holdings at LOI initiation in combination with the value that the shareholder intends to buy over a 13-month period to calculate the front-end sales charge and any breakpoint discounts. Each purchase the shareholder makes during that 13-month period will receive the sales charge and breakpoint discount that applies to the total amount. The inclusion of eligible fund family assets in the LOI calculation is dependent on the shareholder notifying Edward Jones of such assets at the time of calculation. Purchases made before the LOI is received by Edward Jones are not adjusted under the LOI and will not reduce the sales charge previously paid. Sales charges will be adjusted if LOI is not met. |
| ● | If the employer maintaining a SEP IRA plan and/or SIMPLE IRA plan has elected to establish or change ROA for the IRA accounts associated with the plan to a plan-level grouping, LOIs will also be at the plan-level and may only be established by the employer. |
Sales Charge Waivers
Sales charges are waived for the following shareholders and in the following situations:
| ● | Associates of Edward Jones and its affiliates and their family members who are in the same pricing group (as determined by Edward Jones under its policies and procedures) as the associate. This waiver will continue for the remainder of the associate’s life if the associate retires from Edward Jones in good-standing and remains in good standing pursuant to Edward Jones’ policies and procedures. |
| Viking Mutual Funds | Appendix A – Intermediary Specific Sales Charge Waivers and Discounts | November 30, 2024 Page A-1 |
| ● | Shares purchased in an Edward Jones fee-based program. |
| ● | Shares purchased through reinvestment of capital gains distributions and dividend reinvestment. Shares purchased from the proceeds of redeemed shares of the same fund family so long as the following conditions are met: the proceeds are from the sale of shares within 60 days of the purchase, the sale and purchase are made from a share class that charges a front load and one of the following (“Rights of Reinstatement”): |
| * | The redemption and repurchase occur in the same account. |
| * | The redemption proceeds are used to process an: IRA contribution, excess contributions, conversion, recharacterizing of contributions, or distribution, and the repurchase is done in an account within the same Edward Jones grouping for ROA. |
| ● | The Right of Reinstatement excludes systematic or automatic transactions including, but not limited to, purchases made through payroll deductions, liquidations to cover account fees, and reinvestments from non-mutual fund products. |
| ● | Shares purchased through reinvestment of capital gains distributions and dividend reinvestment. |
| ● | Shares purchased from the proceeds of redeemed shares of the same fund family so long as the following conditions are met: 1) the proceeds are from the sale of shares within 60 days of the purchase, and 2) the sale and purchase are made in the same share class and the same account or the purchase is made in an individual retirement account with proceeds from liquidations in a non-retirement account. |
| ● | Shares exchanged into Class A shares from another share class so long as the exchange is into the same fund and was initiated at the discretion of Edward Jones. Edward Jones is responsible for any remaining CDSC due to the fund company, if applicable. Any future purchases are subject to the applicable sales charge as disclosed in the prospectus. |
| ● | Exchanges from Class C shares to Class A shares of the same fund, generally, in the 84th month following the anniversary of the purchase date or earlier at the discretion of Edward Jones. |
Contingent Deferred Sales Charge (“CDSC”) Waiver
If the shareholder purchases shares that are subject to a CDSC and those shares are redeemed before the CDSC is expired, the shareholder is responsible to pay the CDSC except in the following conditions:
| ● | The death or disability of the shareholder. |
| ● | Systematic withdrawals with up to 10% per year of the account value. |
| ● | Return of excess contributions from an Individual Retirement Account (IRA). |
| ● | Shares sold as part of a required minimum distribution for IRA and retirement accounts if the redemption is taken in or after the year the shareholder reaches qualified age based on applicable IRS regulations. |
| ● | Shares sold to pay Edward Jones fees or costs in such cases where the transaction is initiated by Edward Jones. |
| ● | Shares exchanged in an Edward Jones fee-based program. |
| ● | Shares acquired through NAV reinstatement. |
| ● | Shares redeemed at the discretion of Edward Jones for Minimum Balances, as described below. |
Other Important Information Regarding Transactions through Edward Jones
Minimum Purchase Amounts
| ● | Initial purchase minimum: $250 |
| ● | Subsequent purchase minimum: none |
Minimum Balances
| ● | Edward Jones has the right to redeem at its discretion fund holdings with a balance of $250 or less. The following are examples of accounts that are not included in this policy: |
| ú | A fee-based account held on an Edward Jones platform |
| ú | A 529 account held on an Edward Jones platform |
| ú | An account with an active systematic investment plan or LOI |
Exchanging Share Classes
| ● | At any time it deems necessary, Edward Jones has the authority to exchange at NAV a shareholder’s holdings in a fund to Class A shares of the same fund. |
| Viking Mutual Funds | Appendix A – Intermediary Specific Sales Charge Waivers and Discounts | November 30, 2024 Page A-2 |
Shareholders Purchasing Fund Shares through Raymond James and its Affiliates
The following information is provided by Raymond James and its affiliates:
Intermediary-Defined Sales Charge Waiver Policies
The availability of certain initial or deferred sales charge waivers and discounts may depend on the particular financial intermediary or type of account through which you purchase or hold Fund shares.
Intermediaries may have different policies and procedures regarding the availability of front-end sales load waivers or contingent deferred (back-end) sales load (“CDSC”) waivers, which are discussed below. In all instances, it is the purchaser’s responsibility to notify the fund or the purchaser’s financial intermediary at the time of purchase of any relationship or other facts qualifying the purchaser for sales charge waivers or discounts. For waivers and discounts not available through a particular intermediary, shareholders will have to purchase fund shares directly from the fund or through another intermediary to receive these waivers or discounts.
Raymond James & Associates, Inc., Raymond James Financial Services, Inc. and each entity’s affiliates (“Raymond James”)
Effective March 1, 2019, shareholders purchasing fund shares through a Raymond James platform or account, or through an introducing broker-dealer or independent registered investment adviser for which Raymond James provides trade execution, clearance, and/or custody services, will be eligible only for the following load waivers (front-end sales charge waivers and contingent deferred, or back-end, sales charge waivers) and discounts, which may differ from those disclosed elsewhere in this fund’s prospectus or SAI.
Front-end Sales Load Waivers on Class A Shares Available at Raymond James
| ● | Shares purchased in an investment advisory program. |
| ● | Shares purchased within the same fund family through a systematic reinvestment of capital gains and dividend distributions. |
| ● | Employees and registered representatives of Raymond James or its affiliates and their family members as designated by Raymond James. |
| ● | Shares purchased from the proceeds of redemptions within the same fund family, provided (1) the repurchase occurs within 90 days following the redemption, (2) the redemption and purchase occur in the same account, and (3) redeemed shares were subject to a front-end or deferred sales load (known as Rights of Reinstatement). |
CDSC Waivers on Classes A, B, and C Shares Available at Raymond James
| ● | Death or disability of the shareholder. |
| ● | Shares sold as part of a systematic withdrawal plan as described in the fund’s prospectus. |
| ● | Return of excess contributions from an IRA Account. |
| ● | Shares sold as part of a required minimum distribution for IRA and retirement accounts due to the shareholder reaching age 70½ as described in the fund’s prospectus. |
| ● | Shares sold to pay Raymond James fees but only if the transaction is initiated by Raymond James. |
| ● | Shares acquired through a right of reinstatement. |
Front-end Load Discounts Available at Raymond James: Breakpoints, Rights of Accumulation, and/or Letters of Intent
| ● | Breakpoints as described in this prospectus. |
| ● | Rights of accumulation which entitle shareholders to breakpoint discounts will be automatically calculated based on the aggregated holding of fund family assets held by accounts within the purchaser’s household at Raymond James. Eligible fund family assets not held at Raymond James may be included in the calculation of rights of accumulation calculation only if the shareholder notifies his or her financial advisor about such assets. |
| ● | Letters of intent which allow for breakpoint discounts based on anticipated purchases within a fund family, over a 13-month time period. Eligible fund family assets not held at Raymond James may be included in the calculation of letters of intent only if the shareholder notifies his or her financial advisor about such assets. |
| Viking Mutual Funds | Appendix A – Intermediary Specific Sales Charge Waivers and Discounts | November 30, 2024 Page A-3 |
Shareholders Purchasing Fund Shares through Oppenheimer & Co and its Affiliates
The following information is provided by Oppenheimer & Co. Inc. (“OPCO”) and its affiliates:
Effective on or after March 17, 2020, shareholders purchasing Fund shares through an OPCO platform or account are eligible only for the following load waivers (front-end sales charge waivers and contingent deferred, or back-end, sales charge waivers) and discounts, which may differ from those disclosed elsewhere in this Fund’s prospectus or SAI.
Front-end Sales Load Waivers on Class A Shares Available at OPCO
| ● | Employer-sponsored retirement, deferred compensation and employee benefit plans (including health savings accounts) and trusts used to fund those plans, provided that the shares are not held in a commission-based brokerage account and shares are held for the benefit of the plan |
| ● | Shares purchased by or through a 529 Plan |
| ● | Shares purchased through a OPCO affiliated investment advisory program |
| ● | Shares purchased through reinvestment of capital gains distributions and dividend reinvestment when purchasing shares of the same fund (but not any other fund within the fund family) |
| ● | Shares purchased from the proceeds of redemptions within the same fund family, provided (1) the repurchase occurs within 90 days following the redemption, (2) the redemption and purchase occur in the same account, and (3) redeemed shares were subject to a front-end or deferred sales load (known as Rights of Restatement). |
| ● | Employees and registered representatives of OPCO or its affiliates and their family members |
| ● | Directors or Trustees of the Fund, and employees of the Fund’s investment adviser or any of its affiliates, as described in this prospectus |
CDSC Waivers on A and C Shares Available at OPCO
| ● | Death or disability of the shareholder |
| ● | Shares sold as part of a systematic withdrawal plan as described in the Fund’s prospectus |
| ● | Return of excess contributions from an IRA Account |
| ● | Shares sold as part of a required minimum distribution for IRA and retirement accounts due to the shareholder reaching the qualified age based on applicable IRS regulations as described in the prospectus |
| ● | Shares sold to pay OPCO fees but only if the transaction is initiated by OPCO |
| ● | Shares acquired through a right of reinstatement |
Front-end load Discounts Available at OPCO: Breakpoints, Rights of Accumulation & Letters of Intent
| ● | Breakpoints as described in this prospectus. |
| ● | Rights of Accumulation (ROA) which entitle shareholders to breakpoint discounts will be automatically calculated based on the aggregated holding of fund family assets held by accounts within the purchaser’s household at OPCO. Eligible fund family assets not held at OPCO may be included in the ROA calculation only if the shareholder notifies his or her financial advisor about such assets. |
| Viking Mutual Funds | Appendix A – Intermediary Specific Sales Charge Waivers and Discounts | November 30, 2024 Page A-4 |
Shareholders Purchasing Fund Shares through Robert W. Baird & Co. (“Baird”)
Effective on or after September 2, 2020, shareholders purchasing Fund shares through an Baird platform or account are eligible only for the following load waivers (front-end sales charge waivers and contingent deferred, or back-end, sales charge waivers) and discounts, which may differ from those disclosed elsewhere in this Fund’s prospectus or SAI.
Front-End Sales Waivers on Class A shares Available at Baird
| ● | Shares purchased through reinvestment of capital gains distributions and dividend reinvestment when purchasing shares of the same fund |
| ● | Shares purchased by employees and registered representatives of Baird or its affiliate and their family members as designated by Baird |
| ● | Shares purchased using the proceeds of redemptions from an Integrity/Viking Fund, provided (1) the repurchase occurs within 90 days following the redemption, (2) the redemption and purchase occur in the same accounts, and (3) redeemed shares were subject to a front-end or deferred sales charge (known as rights of reinstatement) |
| ● | Employer-sponsored retirement plans or charitable accounts in a transactional brokerage account at Baird, including 401(k) plans, 457 plans, employer-sponsored 403(b) plans, profit sharing and money purchase pension plans and defined benefit plans. For purposes of this provision, employer-sponsored retirement plans do not include SEP IRAs, Simple IRAs or SAR-SEPs |
CDSC Waivers on Class A shares Available at Baird
| ● | Shares sold due to death or disability of the shareholder |
| ● | Shares sold as part of a systematic withdrawal plan as described in the Fund’s Prospectus |
| ● | Shares bought due to returns of excess contributions from an IRA Account |
| ● | Shares sold as part of a required minimum distribution for IRA and retirement accounts due to the shareholder reaching the qualified age based on applicable Internal Revenue Service regulations as may be described in the Fund’s prospectus |
| ● | Shares sold to pay Baird fees but only if the transaction is initiated by Baird |
| ● | Shares acquired through a right of reinstatement |
Front-End Sales Charge Discounts Available at Baird: Breakpoints and/or Rights of Accumulations
| ● | Breakpoints as described in this prospectus. |
| ● | Rights of accumulations which entitles shareholders to breakpoint discounts will be automatically calculated based on the aggregated holding of Integrity/Viking Fund assets held by accounts within the purchaser’s household at Baird. Eligible Integrity/Viking Fund assets not held at Baird may be included in the rights of accumulations calculation only if the shareholder notifies his or her financial advisor about such assets |
| ● | Letters of Intent (LOI) allow for breakpoint discounts based on anticipated purchases of Integrity/Viking Funds through Baird, over a 13-month period of time |
| Viking Mutual Funds | Appendix A – Intermediary Specific Sales Charge Waivers and Discounts | November 30, 2024 Page A-5 |
Shareholders
Purchasing Fund Shares through Morgan Stanley Wealth Management
(“Morgan Stanley”)
Shareholders purchasing Fund shares through a Morgan Stanley brokerage account will be eligible only for the following front-end sales charge waivers with respect to Class A shares, which may differ from and may be more limited than those disclosed elsewhere in this Fund’s Prospectus or SAI.
Front-end Sales Charge Waivers on Class A Shares Available at Morgan Stanley
| ● | Employer-sponsored retirement plans (e.g., 401(k) plans, 457 plans, employer-sponsored 403(b) plans, profit sharing and money purchase pension plans and defined benefit plans). For purposes of this provision, employer-sponsored retirement plans do not include SEP IRAs, Simple IRAs, SAR-SEPs or Keogh plans |
| ● | Morgan Stanley employee and employee-related accounts according to MSSB’s account linking rules |
| ● | Shares purchased through reinvestment of dividends and capital gains distributions when purchasing shares of the same fund |
| ● | Shares purchased through a Morgan Stanley self-directed brokerage account |
| ● | Class C (i.e., level-load) shares that are no longer subject to a contingent deferred sales charge and are converted to Class A shares of the same fund pursuant to Morgan Stanley Wealth Management’s share class conversion program |
| ● | Shares purchased from the proceeds of redemptions within the same fund family, provided the repurchase occurs within 90 days’ following the redemption, (ii) the redemption and purchase occur in the same account, and (iii) redeemed shares were subject to a front-end or deferred sales charge. |
| Viking Mutual Funds | Appendix A – Intermediary Specific Sales Charge Waivers and Discounts | November 30, 2024 Page A-6 |
VIKING MUTUAL FUNDS
Kansas Municipal Fund
Maine Municipal Fund
Nebraska Municipal Fund
Oklahoma Municipal Fund
Viking Tax-Free Fund for Montana
Viking Tax-Free Fund for North Dakota
1 Main Street North • Minot, ND 58703
• 701-852-5292
PO Box 500 • Minot, ND 58702
PO Box 759 • Minot, ND 58702
800-276-1262 • Marketing • Fax 701-838-4902
800-601-5593 • Transfer Agent • Fax 701-852-2548
Investment
Manager
Viking Fund Management, LLC
PO Box 500
Minot, ND 58702
Principal
Underwriter
Integrity Funds Distributor, LLC
PO Box 500
Minot, ND 58702
Custodian
UMB Bank, N.A.
Institutional Custody
928 Grand Blvd
Kansas City, MO 64105
Transfer
Agent
Integrity Fund Services, LLC
PO Box 759
Minot, ND 58702
Independent
Registered Public Accounting Firm
Cohen & Company, Ltd.
1350 Euclid Ave Suite 800
Cleveland, OH 44115
Legal
Counsel
Thompson Hine LLP
41 S High St Ste 1700
Columbus, OH 43215-6101
To learn more about the Funds, you may want to read the Funds’ SAI, which contains additional information about the Funds. The Funds have incorporated the SAI into the prospectus by reference, which means that you should consider the contents of the SAI to be part of this prospectus. Additional information about the Funds’ investments is available in the Funds’ annual and semi-annual reports to shareholders and Form N-CSR. In the Funds’ annual report, you will find a discussion of the market conditions and investment strategies that significantly affected the Funds’ performance during their last fiscal year. You will find the Funds’ annual and semi-annual financial statements in Form N-CSR. The SAI, the Funds’ annual and semi-annual reports to shareholders, Form N-CSR, and other information, such as Fund financial statements, are available without charge upon request. Call Integrity Funds Distributor at 800-276-1262 to request a free copy of the Funds’ SAI; to request the Funds’ annual or semi-annual report; to request the Funds’ financial statements on Form N-CSR; to request other information about the Funds, and to make shareholder inquiries, or visit the Funds’ website at www.integrityvikingfunds.com.
Prospective investors and shareholders who have questions about the Funds may write to:
Integrity Funds Distributor, LLC
PO Box 500
Minot, ND 58702
or call 800-276-1262
Reports and other information about the Funds are available on the EDGAR Database on the SEC’s website at http://www.sec.gov. and copies of this information may be obtained, after paying a duplicating fee, by electronic request at the following e-mail address: publicinfo@sec.gov.
Investment Company Act File No: 811-09277
 | November 30, 2024 |
Statement of Additional Information
VIKING MUTUAL FUNDS
Class A and Class I Shares
KANSAS MUNICIPAL FUND
Class A:KSMUX and Class I: KSITX
MAINE MUNICIPAL FUND
Class A:MEMUX and Class I: MEIMX
NEBRASKA MUNICIPAL FUND
Class A:NEMUX and Class I: NEITX
OKLAHOMA MUNICIPAL FUND
Class A:OKMUX and Class I: OKMIX
VIKING TAX-FREE FUND FOR MONTANA
Class A: VMTTX and Class I: VMTIX
VIKING TAX-FREE FUND FOR NORTH DAKOTA
Class A: VNDFX and Class I: VNDIX
PO Box 500
Minot, North
Dakota 58702
701-852-5292
800-601-5593 • Transfer Agent
800-276-1262 • Marketing
The Kansas Municipal Fund, Maine Municipal Fund, Nebraska Municipal Fund, Oklahoma Municipal Fund, Viking Tax-Free Fund for Montana, and Viking Tax-Free Fund for North Dakota (each a “Fund” and collectively, the “Funds”) are mutual funds that offer shares pursuant to a prospectus dated November 30, 2024 (“Prospectus”). This Statement of Additional Information (“SAI”) is not a prospectus. It contains information in addition to the information in the Funds’ Prospectus. The Funds’ Prospectus, which may be amended from time to time, contains the basic information you should know before investing in a Fund. You should read this SAI together with the Funds’ Prospectus.
The Funds’ audited financial statements for the most recently completed fiscal year, including the notes thereto and the independent registered public accounting firm’s report, thereon, included in the annual Form N-CSR, are hereby incorporated into this SAI by reference.
For a free copy of the current Prospectus or Form N-CSR, contact your investment representative, call 800-276-1262, or you may access the Prospectus, the Funds’ semi-annual and annual reports, and Form N-CSRs from the Funds’ website at www.integrityvikingfunds.com.
Mutual funds:
| ● | are not insured by the FDIC or any other government agency; |
| ● | have no bank guarantees; |
| ● | may lose value, so an investor may lose money |
TABLE OF CONTENTS
HISTORY OF THE FUNDS
Viking Mutual Funds is an open-end investment company established under Delaware law by a Trust Instrument dated March 30, 1999. It is a series company as contemplated under Rule 18f-2 under the Investment Company Act of 1940, as amended (the “1940 Act”). Each of the Funds is a series of Viking Mutual Funds.
Effective after the close of business on October 31, 2017, the Kansas Municipal Fund (the “Kansas Fund”), Maine Municipal Fund (the “Maine Fund”), Nebraska Municipal Fund (the “Nebraska Fund”), and Oklahoma Municipal Fund (the “Oklahoma Fund”) each acquired the assets of the corresponding series of the same name, which was organized as a series of Integrity Managed Portfolios, in exchange for shares of the Fund and the assumption by the Fund of the liabilities of the predecessor series of Integrity Managed Portfolios (the “Reorganizations”). The purpose of the Reorganizations was to consolidate all of the municipal portfolios advised by Viking Fund Management, LLC under the Trust. References to the Kansas Fund, Maine Fund, Nebraska Fund, and Oklahoma Fund include each Fund and its corresponding predecessor fund under Integrity Managed Portfolios. The term “Integrity Viking Funds” and “Fund Complex” refers to all of the mutual funds advised by Viking Fund Management, LLC, which includes the Funds and six series of The Integrity Funds known as the Integrity Dividend Harvest Fund, Integrity Dividend Summit Fund, Integrity Growth & Income Fund, Integrity High Income Fund, Integrity Mid-North American Resources Fund, and Integrity Short Term Government Fund.
Viking Tax-Free Fund for Montana (the “Montana Fund”) commenced operations on August 3, 1999. Effective after the close of business on July 31, 2009, the Montana Fund acquired the stated assets of the Montana Tax-Free Fund, Inc., which was previously managed by Integrity Money Management, Inc. (the “Prior Integrity Montana Fund”), in exchange for shares of the Montana Fund and the assumption of the stated liabilities of the Prior Integrity Montana Fund.
Viking Tax-Free Fund for North Dakota (the “North Dakota Fund”) commenced operations on August 3, 1999. Effective after the close of business on July 31, 2009, the North Dakota Fund acquired the stated assets of the ND Tax-Free Fund, Inc., which was previously managed by Integrity Money Management, Inc. (the “Prior Integrity ND Fund”), in exchange for shares of the North Dakota Fund and the assumption of the stated liabilities of the Prior Integrity ND Fund.
Each Fund, except the Kansas Fund and Oklahoma Fund, are non-diversified.
INVESTMENT RESTRICTIONS
For purposes of all investment policies of a Fund: (i) the references to the 1940 Act include the rules thereunder, interpretations of the SEC, and any exemptive order upon which a Fund may rely; and (ii) the references to the Internal Revenue Code of 1986, as amended (the “Code”) include the rules thereunder, Internal revenue Service (“IRS”) interpretations, and any private letter ruling or similar authority upon which a Fund may rely. Except with respect to the fundamental policy relating to borrowing money as set forth in (1) below, or as required by the 1940 Act or the Code, or as otherwise noted below, if any percentage restriction on investment or utilization of assets is adhered to at the time an investment is made, a later change in percentage resulting from change in the market values of a Fund’s assets or purchases and redemptions of shares will not be considered a violation of the limitation.
Fundamental Investment Restrictions
The Funds have adopted the following restrictions as fundamental policies. This means that any restriction may be changed only if the change is approved, as set forth in the Investment Company Act of 1940, as amended (the “1940 Act”) by (i) more than 50% of a Fund’s outstanding shares or (ii) 67% or more of a Fund’s shares present at a shareholder meeting if more than 50% of the Fund’s outstanding shares are represented at the meeting in person or by proxy, whichever is less.
The Kansas Fund seeks the highest level of current income that is exempt from federal and Kansas personal income taxes and is consistent with the preservation of capital. The Fund’s investment objective is fundamental. To pursue its objective, the Fund normally invests at least 80% of its net assets (including any borrowings for investment purposes) in municipal securities that pay interest free from (a) federal income taxes, including the federal alternative minimum tax, and (b) Kansas personal income taxes.
The Maine Fund seeks the highest level of current income that is exempt from federal and Maine personal income taxes and is consistent with the preservation of capital. The Fund’s investment objective is fundamental. To pursue its objective, the Fund normally invests at least 80% of its net assets (including any borrowings for investment purposes) in municipal securities that pay interest free from (a) federal income taxes, including the federal alternative minimum tax, and (b) Maine personal income taxes.
The Nebraska Fund seeks the highest level of current income that is exempt from federal and Nebraska personal income taxes and is consistent with the preservation of capital. The Fund’s investment objective is fundamental. To pursue its objective, the Fund normally invests at least 80% of its net assets (including any borrowings for investment purposes) in municipal securities that pay interest free from (a) federal income taxes, including the federal alternative minimum tax, and (b) Nebraska personal income taxes.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-1 |
The Oklahoma Fund seeks the highest level of current income that is exempt from federal and Oklahoma personal income taxes and is consistent with the preservation of capital. The Fund’s investment objective is fundamental. To pursue its objective, the Fund normally invests at least 80% of its net assets (including any borrowings for investment purposes) in municipal securities that pay interest free from (a) federal income taxes, including the federal alternative minimum tax, and (b) Oklahoma personal income taxes.
The Montana Fund seeks the highest level of current income that is exempt from federal and Montana personal income taxes and is consistent with the preservation of capital. The Fund’s investment objective is fundamental. In addition, the Fund has a fundamental policy pursuant to which it invests at least 80% of its net assets (including any borrowings for investment purposes) in municipal securities that pay interest free from federal income taxes, including the federal alternative minimum tax.
The North Dakota Fund seeks the highest level of current income that is exempt from federal and North Dakota personal income taxes and is consistent with the preservation of capital. The Fund’s investment objective is fundamental. In addition, the Fund has a fundamental policy pursuant to which it invests at least 80% of its net assets (including any borrowings for investment purposes) in municipal securities that pay interest free from federal income taxes, including the federal alternative minimum tax.
The following fundamental restrictions apply to each Fund.
A Fund may not:
| (1) | issue any senior securities, borrow money or mortgage or pledge any of the assets of the Fund, except that borrowings for temporary or emergency purposes may be made in an amount up to 5% of total assets. |
| (2) | buy any securities on margin or sell any securities short. |
| (3) | make loans, except by purchase of debt obligations in which the Fund may invest consistent with its investment policies. |
| (4) | underwrite securities issued by other persons except insofar as the Fund may be technically deemed an underwriter under the federal securities laws in connection with the disposition of portfolio securities. |
| (5) | purchase the securities of any issuer which would result in the Fund owning more than 10% of the outstanding voting securities of an issuer. |
| (6) | purchase or sell real estate, although it may purchase securities which are secured by or represent interests in real estate. |
| (7) | purchase or sell commodities or commodity contracts, financial future contracts, puts, calls, straddles, spreads or any combination thereof or derivative securities of any kind, or interests in oil, gas or other mineral exploration or development programs. |
| (8) | invest in companies for the purpose of exercising control or management. |
| (9) | purchase any security if thereafter 25% or more of the total assets of the Fund would be invested in securities of issuers having their principal business activities in the same industry; this restriction does not apply to securities issued or guaranteed by the U.S. Government, its agencies, authorities, or instrumentalities, or to tax-exempt obligations issued or guaranteed by a U.S. territory or possession or a state or local government, or a political subdivision of any of the foregoing. |
| (10) | invest more than 5% of its total assets in securities of any single investment company, nor more than 10% of its total assets in securities of two or more investment companies, except as part of a merger, consolidation or acquisition of assets or invest in securities of any single investment company if as a result of such investment, the Fund owns more than 3% of the total voting stock of such investment company; except that the Fund may invest in money market mutual funds to the extent permitted by federal law, including the 1940 Act and rules promulgated thereunder. |
| (11) | invest in foreign securities. |
Non-Fundamental Investment Restrictions
Each Fund has a non-fundamental policy restricting its investment in illiquid securities to 15% of net assets. Illiquid securities are any investment that the Fund reasonably expects cannot be sold or disposed of in current market conditions in seven calendar days or less without the sale or disposition significantly changing the market value of the investment.
If a bankruptcy or other extraordinary event occurs concerning a particular security a Fund owns, the Fund may receive stock, real estate, or other investments that the Fund would not, or could not, buy. If this happens, the Fund intends to sell such investments as soon as practicable while maximizing the return to shareholders.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-2 |
Excluding the Funds’ restrictions regarding borrowing and illiquid securities, any investment restriction or limitation which involves a maximum percentage of securities or assets shall not be considered to be violated unless an excess over the percentage occurs immediately after an acquisition of securities and such excess results therefrom. If events subsequent to a transaction result in a Fund exceeding the percentage limitation on borrowing or illiquid securities, the investment manager will take appropriate steps to reduce the percentage of borrowings or the percentage held in illiquid securities, as may be required by law, within a reasonable amount of time. More specifically with respect to illiquid securities, the investment manager will take reasonable and appropriate steps to bring the Fund back into compliance with the 15% percentage limitation described above.
DESCRIPTION OF INVESTMENT TECHNIQUES AND RISKS
The following is a description of the various types of securities the Funds may buy and certain of the accompanying risks. A more complete discussion of the principal investment strategies and principal risks of the Funds is set forth in the Prospectus. The Funds may not necessarily buy all of these securities or use all of these techniques.
Unless restricted by the fundamental policies of any Fund, the following policies supplement the objectives and policies of the Funds as set forth in the Prospectus.
Principal Investment Techniques and Risks
Municipal bonds meet longer-term capital needs and generally have maturities from one to 30 years when issued. They have two principal classifications: general obligation bonds and revenue bonds.
General Obligation Bonds
Issuers of general obligation bonds include states, counties, cities, towns and regional districts. The proceeds of these obligations are used to fund a wide range of public projects, including construction or improvement, of schools, highways, and roads. The basic security behind general obligation bonds is the issuer’s pledge of its full faith, credit, and taxing power for the payment of principal and interest. The taxes that can be levied for the payment of debt service may be limited or unlimited as to the rate or amount of special assessments.
Revenue Bonds
The full faith, credit, and taxing power of the issuer do not secure revenue bonds. Instead, the principal security for a revenue bond is generally the net revenue derived from a particular facility, group of facilities, or, in some cases, the proceeds of a special excise tax or other specific revenue source. Revenue bonds are issued to finance a wide variety of capital projects, including: electric, gas, water and sewer systems; highways, bridges, and tunnels; port and airport facilities; colleges and universities; and hospitals. The principal security behind these bonds may vary. For example, housing finance authorities have a wide range of security, including partially or fully insured mortgages, rent subsidized and/or collateralized mortgages, and/or the net revenues from housing or other public projects. Many bonds provide additional security in the form of a debt service reserve fund that may be used to make principal and interest payments. Some authorities have further security in the form of state assurances (although without obligation) to make up deficiencies in the debt service reserve fund.
All of the municipal securities in which the Funds invest are rated investment grade (BBB- or higher), at the time of purchase by a nationally recognized statistical rating organization such as S&P Global Ratings (“S&P”), Moody’s Investors Service (“Moody’s”) or Fitch Ratings (“Fitch”) or are of comparable quality as determined by the investment manager.
Ratings of municipal bonds represent the opinions of the rating services with respect to the securities and are not absolute standards of quality. Please see “Description of Bond Ratings” for a description of the ratings.
With respect to unrated securities, it is also the Funds’ intent to buy securities that, in the view of the investment manager, would be comparable in quality to the Funds’ rated securities and have been determined to be consistent with the Funds’ objectives without exposing the Funds to excessive risk. The Funds will not buy issues that are in default or that the investment manager believes involve excessive risk.
Tax-Exempt Industrial Development Revenue Bonds
The Funds may invest in industrial development revenue bonds the interest on which is exempt from federal income tax in the opinion of the bond issuer’s counsel. Tax-exempt industrial development revenue bonds are issued by or on behalf of public authorities to finance various privately operated facilities for business, manufacturing, housing, sports and pollution control, as well as public facilities such as airports, mass transit systems, ports, and parking. The payment of principal and interest is solely dependent on the ability of the facility’s user to meet its financial obligations and the pledge, if any, of the facility or other property as security for payment.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-3 |
Callable Bonds
Each Fund may invest in callable bonds, which allow the issuer to repay some or all of the bonds ahead of schedule. If a bond is called, the Fund will receive the principal amount and accrued interest, and may receive a small additional payment as a call premium. The Fund may sell a callable bond before its call date, if it believes the bond is at its maximum premium potential. An issuer is more likely to call its bonds when interest rates are falling, because the issuer can issue new bonds with lower interest payments. If a bond is called, the Fund may have to replace it with a lower-yielding security. If the Fund originally paid a premium for the bond because it had appreciated in value from its original issue price, the Fund also may not be able to recover the full amount it paid for the bond. One way for the Fund to protect itself from call risk is to buy bonds with call protection. Call protection is an assurance that the bond will not be called for a specific time period, typically five to 10 years from when the bond is issued. In light of the Funds’ pricing policies and certain amortization procedures required by the Internal Revenue Service (“IRS”), the Funds do not expect to suffer any material adverse impact related to the value at which they carry bonds in connection with calls of bonds purchased at a premium. As with any investment strategy, however, there is no guarantee that a call may not have a more substantial impact than anticipated.
Escrow-secured or defeased bonds are created when an issuer refunds, before maturity, an outstanding bond issue that is not immediately callable (or pre-refunds), and sets aside funds for redemption of the bonds at a future date. The issuer uses the proceeds from a new bond issue to buy high grade, interest bearing debt securities, generally direct obligations of the U.S. government. These securities are then deposited in an irrevocable escrow account held by a trustee bank to secure all future payments of principal and interest on the pre-refunded bond. Escrow-secured bonds often receive a triple A or equivalent rating from Moodys, S&P, or Fitch.
Municipal Securities and Single-State Considerations
Each Fund focuses its investments in the municipal securities of a single state and may also invest in the securities of issuers located in U.S. territories and possessions. The values of municipal securities held by the Fund may be adversely affected by local political and economic conditions and developments. Adverse conditions in an industry significant to a local economy could have a correspondingly adverse effect on the financial condition of local issuers. Other factors that could affect municipal securities include a change in the local, state or national economy, demographic factors, ecological or environmental concerns, statutory limitations on the issuer’s ability to increase taxes, and other developments generally affecting the revenue of issuers (for example, legislation or court decisions reducing state aid to local governments or mandating additional services).
To the extent that a Fund invests a significant portion of its assets in the securities of issuers located in a given state or U.S. territory or possession, it will be disproportionately affected by political and economic conditions and developments in that state, territory or possession. In addition, economic, political or regulatory changes in that state, territory or possession could adversely affect municipal bond issuers in that state or territory or possession and therefore the value of a Fund’s investment portfolio.
The Funds may invest in municipal securities of municipal issuers located in Puerto Rico. In recent years, municipal securities issued by Puerto Rico and its agencies and instrumentalities have been subject to multiple credit downgrades as a result of Puerto Rico’s ongoing fiscal challenges and uncertainty about the ability to make full repayment on these obligations. More recently, certain issuers of Puerto Rican municipal securities have failed to make payments on obligations that have come due, and additional missed payments or defaults may occur in the future.
Set forth in Appendix A are summaries of certain factors that bear upon the risk of investing in municipal securities issued by public authorities in the states of the Funds as well as Guam, Puerto Rico and the U.S. Virgin Islands.
Municipal Market Disruption Risk
The value of municipal securities may be affected by uncertainties in the municipal market related to legislation or litigation involving the taxation of municipal securities or the rights of municipal securities holders in the event of a bankruptcy. As described below under “Tax risk,” proposals have been introduced to restrict or eliminate the federal income tax exemption for interest on municipal securities, and similar proposals may be introduced in the future. Proposed “flat tax” and “value added tax” proposals could also have the effect of eliminating the tax preference for municipal securities. Proposals also may be introduced before the state legislatures that would affect the state tax treatment of a municipal fund’s distributions. If such proposals were enacted, the availability of municipal securities and the value of a municipal fund’s holdings would be affected and the Trustees would reevaluate the Funds’ investment objectives and policies. Historically, municipal bankruptcies have been relatively rare, and certain provisions of the U.S. Bankruptcy Code governing such bankruptcies are unclear. Further, the application of state law to municipal issuers could produce varying results among the states or among municipal securities issuers within a state. These legal uncertainties could affect the municipal securities market generally, certain specific segments of the market, or the relative credit quality of particular securities. Any of these effects could have a significant impact on the prices of some or all of the municipal securities held by a Fund.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-4 |
Tax Risk
Income from municipal securities held by the Funds could be declared taxable because of unfavorable changes in tax laws, adverse interpretations by the Internal Revenue Service or state tax authorities, or noncompliant conduct of a bond issuer. Moreover, a portion of the Funds’ otherwise exempt-interest dividends may be taxable to those shareholders subject to the alternative minimum tax. In addition, proposals have been made to restrict or eliminate the federal income tax exemption for interest on municipal securities, and similar proposals may be introduced in the future. Proposed “flat tax” and “value added tax” proposals could also have the effect of eliminating the tax preference for municipal securities. Some of these proposals would apply to interest on municipal securities issued before the date of enactment, which would adversely affect their value to a material degree. If such a proposal were enacted, the availability of municipal securities for investment by the Funds and the value of the Funds’ portfolios would be adversely affected.
Cybersecurity Risk
As the use of technology has become more prevalent in the course of business, the Funds have become potentially more susceptible to operational and financial risks through breaches in cybersecurity. These risks include theft, loss, misuse, improper release, corruption and destruction of, or unauthorized access to, confidential or highly restricted data relating to a Fund and its shareholders; and compromises or failures to systems, networks, devices and applications relating to the operations of a Fund and its service providers. Cybersecurity issues may result in, among other things, financial losses to a Fund and its shareholders; the inability of a Fund to transact business with its shareholders or to engage in portfolio transactions; delays or mistakes in the calculation of a Fund’s net asset value (“NAV”) or other materials provided to shareholders; the inability to process transactions with shareholders or other parties; violations of privacy and other laws; regulatory fines, penalties and reputational damage; and compliance and remediation costs, legal fees and other expenses. A Fund’s service providers, financial intermediaries, entities in which a Fund invests and parties with which a Fund engages in portfolio or other transactions also may be adversely impacted by cybersecurity risks, resulting in losses to a Fund or its shareholders. There can be no guarantee that any risk management systems established to address and reduce cybersecurity risks will succeed, and the Funds cannot control such systems put in place by service providers, issuers or other third parties whose operations may affect the Funds and/or their shareholders. A Fund’s share price may decline as a result of unauthorized actions taken during a security breach or subsequent market activity in response to the security breach.
Liquidity Risk
Liquidity risk is the risk that a Fund may not be able to sell a holding in a timely manner at a desired price. Liquidity risk may result from the lack of an active market, the reduced number of traditional market participants, or the reduced capacity of traditional market participants to make a market in securities. The secondary market for certain municipal securities tends to be less developed and liquid than many other securities markets, which may adversely affect a Fund’s ability to sell such municipal securities at attractive prices. Moreover, inventories of municipal securities held by brokers and dealers have decreased in recent years, lessening their ability to market in these securities. This reduction in market making capacity has the potential to decrease a Fund’s ability to buy or sell bonds, and increase bond price volatility and trading costs, particularly during periods of economic or market stress. As a result, a Fund may be forced to accept a lower price to sell a security, to sell other securities to raise cash, or to give up an investment opportunity, any of which could have a negative effect on performance. If a Fund needed to sell large blocks of securities to raise cash (such as to meet heavy shareholder redemptions), those sales could further reduce the securities’ prices and hurt performance.
Valuation Risk
The sales price a Fund could receive for any particular portfolio investment may differ from the Fund’s valuation of the investment, particularly for securities that trade in thin or volatile markets or that are valued using a fair value methodology. Investors who purchase or redeem Fund shares on days when a Fund is holding fair-valued securities may receive fewer or more shares or lower or higher redemption proceeds than they would have received if the Fund had not fair-valued the security or had used a different valuation methodology.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-5 |
Non-Principal Investment Techniques and Risks
Municipal Lease Obligations
The Funds may invest in municipal lease obligations, including certificates of participation. Since annual appropriations are required to make lease payments, municipal lease obligations generally are not subject to constitutional limitations on the issuance of debt and may allow an issuer to increase government liabilities beyond constitutional debt limits. When faced with increasingly tight budgets, local governments have more discretion to curtail lease payments under a municipal lease obligation than they do to curtail payments on other municipal securities. If not enough money is appropriated to make the lease payments, the leased property may be repossessed as security for holders of the municipal lease obligations. If this happens, there is no assurance that the property’s private sector or re-leasing value will be enough to make all outstanding payments on the municipal lease obligations or that the payments will continue to be tax-free. While cancellation risk is inherent to municipal lease obligations, the investment manager believes that this risk may be reduced, although not eliminated, by the Funds’ policies on the quality of securities in which they may invest.
Zero Coupon Securities
The Funds may invest in zero-coupon and delayed interest securities. Zero-coupon securities make no periodic interest payments, but are sold at a deep discount from their face value. The buyer recognizes a rate of return determined by the gradual appreciation of the security, which is redeemed at face value on a specified maturity date. The discount varies depending on the time remaining until maturity, as well as market interest rates, liquidity of the security, and the issuer’s perceived credit quality. The discount, in the absence of financial difficulties of the issuer, typically decreases as the final maturity date approaches. If the issuer defaults, a Fund may not receive any return on its investment.
Because zero-coupon securities bear no interest, their value is generally more volatile than the value of other fixed-income securities. Since zero-coupon bondholders do not receive interest payments, zero-coupon securities fall more drastically than bonds paying interest on a current basis when interest rates rise. When interest rates fall, zero-coupon securities rise more rapidly in value, because the bonds reflect a fixed rate of return.
An investment in zero-coupon and delayed interest securities may cause a Fund to recognize income and make distributions to shareholders before it receives any cash payments on its investments. To generate cash to satisfy distribution requirements, a Fund may have to sell portfolio securities that it otherwise would have continued to hold or to use cash flows from other sources such as the sale of Fund shares.
When-Issued Securities
Municipal securities are frequently offered on a when-issued basis. When so offered, the price, which is generally expressed in yield terms, is fixed at the time the commitment to buy is made, but delivery and payment take place at a later date. During the time between purchase and settlement, no payment is made by the Funds to the issuer and no interest accrues to the Funds. If the other party to the transaction fails to deliver the security, the Funds could miss a favorable price or yield opportunity, or could experience a loss.
When a Fund makes the commitment to buy a municipal security on a when-issued basis, it records the transaction and reflects the value of the security in the determination of its NAV. The Funds believe that their NAVs or income will not be negatively affected by the purchase of municipal securities on a when-issued basis. The Funds will not engage in when-issued transactions for investment leverage purposes.
Although the Funds will generally buy municipal securities on a when-issued basis with the intention of acquiring the securities, they may sell the securities before the settlement date if it is considered advisable. If assets of the Funds are held in cash pending the settlement of a purchase of securities, the Funds will not earn income on those assets.
U.S. Government Obligations
Each Fund may invest in U.S. Government obligations. U.S. Government obligations are issued by the U.S. Treasury or by agencies and instrumentalities of the U.S. Government and are backed by the full faith and credit of the U.S. government. They include Treasury bills, notes, and bonds.
Other Investment Companies
The Funds may invest in the shares of other investment companies. Such investments may be the most practical manner in which the Funds can invest in certain securities because those securities themselves may not be available at the time a Fund is ready to make an investment.
As a shareholder in an investment company, a Fund would bear its pro rata share of that investment company’s expenses. Investment in other investment companies, such as closed-end funds, may involve the payment of substantial premiums above the value of such issuers’ portfolio securities. A Fund does not intend to invest in such investment companies unless, in the judgment of the Fund’s investment manager, the potential benefits of such investment justify the payment of any applicable premium or sales charge. See “Investment Restrictions” above.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-6 |
Temporary Defensive Positions
During unusual market or other conditions, each Fund may temporarily depart from its investment objective and invest up to 100% of its assets in short-term U.S. Government obligations, cash, and cash equivalents. These short-term investments may be taxable.
TRUSTEES AND OFFICERS
Viking Mutual Funds (the “Trust”) has a Board of Trustees (the “Board of Trustees” or the “Board”). The Board is responsible for the overall management of the Funds, including general supervision and review of each Fund’s investment activities. The Board, in turn, elects the officers of the Funds who are responsible for administering each Fund’s day-to-day operations. Among other things, the Board of Trustees, generally oversees the portfolio management of each Fund and reviews and approves each Fund’s advisory contracts and other principal contracts.
The Trustees who are not “interested persons” (for regulatory purposes) of the Trust or an investment adviser or principal underwriter of the Funds (the “Independent Trustees”) are charged with, among other functions, recommending to the full Board approval of the distribution, transfer agency and accounting services agreements and the investment advisory agreements. A Trustee who is an “interested person” (for regulatory purposes) of the Trust is referred to as an “Interested Trustee.”
The Role of the Board
The Board provides oversight of the management and operations of the Trust. Like all mutual funds, the day-to-day responsibility for the management and operation of the Trust is the responsibility of various service providers to the Trust, such as the Trust’s investment adviser, distributor, administrator, custodian, and transfer agent, each of which is discussed in greater detail in this SAI. The Board approves all significant agreements between the Trust and its service providers, including the agreements with Viking Fund Management, LLC (“Viking Management” or the “Investment Adviser”), the distributor, the administrator, the custodian and the transfer agent. The Board has appointed various officers of the Trust, with responsibility to monitor and report to the Board on the Trust’s day-to-day operations. In conducting this oversight, the Board receives regular reports from these officers and service providers regarding the Trust’s operations. The Board has appointed a Chief Compliance Officer (“CCO”) who administers the Trust’s compliance program and regularly reports to the Board as to compliance matters. Some of these reports are provided as part of formal “Board Meetings” which are typically held quarterly, in person, and involve the Board’s review of recent Trust operations. From time to time one or more members of the Board may also meet with Trust officers in less formal settings, between formal “Board Meetings,” to discuss various topics. In all cases, however, the role of the Board and of any individual Trustee is one of oversight and not of management of the day-to-day affairs of the Trust and its oversight role does not make the Board a guarantor of the Trust’s investments, operations, or activities.
Board Leadership Structure
The Board has structured itself in a manner that it believes allows it to effectively perform its oversight function. It has established two standing committees-an Audit Committee and a Governance and Nominating Committee, which are discussed in greater detail under “Board Committees”, below. Seventy-five percent of the members of the Board are Independent Trustees, and each of the Audit Committee and Governance and Nominating Committee are comprised entirely of Independent Trustees. The Independent Trustees have engaged their own independent counsel to advise them on matters relating to their responsibilities in connection with the Trust.
Robert E. Walstad, the Chairman of the Board, is an Interested Trustee by virtue of his ownership of a membership interest in Corridor Investors, LLC (“Corridor”), the parent company of Viking Management, Integrity Fund Services, LLC and Integrity Funds Distributor, LLC. He is also a governor of Corridor. The Trust has appointed R. James Maxson as Lead Independent Trustee. As such, Mr. Maxson is responsible for: (i) coordinating activities of the Independent Trustees; (ii) working with the Investment Adviser, the Chairman of the Board, the committee chairmen, the CCO, and the independent legal counsel to the Independent Trustees, as applicable, to determine the agenda for Board and committee meetings; (iii) serving as the principal contact for and facilitating communication between the Independent Trustees and the Funds’ service providers, particularly the Investment Adviser; and (iv) any other duties that the Independent Trustees may delegate to the Lead Independent Trustee.
The same four persons on the Board of the Trust comprise the board of trustees of The Integrity Funds, which constitutes the other funds in the Fund Complex. Given that the funds in the Fund Complex are served by the same service providers and generally face the same issues, the Board believes that this “unitary” structure promotes efficiency and consistency in the governance and oversight of the funds in the Fund Complex, and may reduce the costs, administrative burdens and possible conflicts that may result from having multiple boards comprised of different individuals.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-7 |
The Trust has determined that the Board’s leadership structure, taking into account, among other things, its committee structure, which permits certain areas of responsibility to be allocated to the Independent Trustees, the role of its Lead Independent Trustee described above and its “unitary” structure described above, is appropriate given the characteristics and circumstances of the Trust and the Fund Complex.
Board Oversight of Risk Management
The Board’s oversight extends to the Trust’s risk management processes. As part of its oversight function, the Board receives and reviews various risk management reports and assessments and discusses related matters with appropriate management and other personnel. Because risk management is a broad concept comprised of many elements (including, for example, but not limited to, investment risks, issuer risks, compliance risks, valuation risks, counterparty risks, operational risks, business continuity risks, and legal, compliance, and regulatory risks) the oversight of different types of risks is handled in different ways. For example, the full Board as well as the committees meet regularly with the CCO to discuss compliance and operational risks. The CCO also provides updates to the Board of Trustees on the operation of the Trust’s compliance policies and procedures and on how these procedures are designed to mitigate risk. The Audit Committee also meets with the Treasurer and the Trust’s independent public accounting firm to discuss, among other things, the internal control structure of the Trust’s financial reporting function. The full Board receives reports from the Investment Adviser and portfolio managers on actual and possible risks affecting the Funds. They also report to the Board on various elements of risk, including investment, credit, liquidity, valuation, operational, and compliance risks, as well as other overall business risks that could impact the Funds. Finally, the CCO and/or other officers of the Trust report to the Board in the event that any material risk issues arise in between Board meetings.
The Board recognizes that not all risks that may affect the Funds can be identified, that it may not be practical or cost-effective to eliminate or mitigate certain risks, that it may be necessary to bear certain risks (such as investment-related risks) to achieve each Fund’s goals, and that the processes, procedures and controls employed to address certain risks may be limited in their effectiveness. Moreover, reports received by the Trustees as to risk management matters are typically summaries of the relevant information. As a result of the foregoing and other factors, the Board’s risk management oversight is subject to certain limitations.
Information about Each Trustee’s Qualifications, Experience, Attributes, or Skills
The Board believes that each Trustee’s experience, qualifications, attributes or skills on an individual basis and in combination with those of the other Trustees lead to the conclusion that the Board possesses the requisite attributes and skills. In addition to the information provided in the table below, listed below for each Trustee is additional information concerning the experiences, qualifications and attributes that led to the conclusion, as of the date of this SAI, that each current Trustee should serve as a trustee.
Interested Trustee
Robert E. Walstad. Mr. Walstad has been engaged in the securities business since 1972. Currently, he is chairman of the board of the funds in the Fund Complex and, until May 1, 2013, was a co-portfolio manager of the Integrity Mid-North American Resources Fund and the Integrity Growth & Income Fund. He was the president of Integrity Money Management, Inc. from 1988 to 2007, and provided general direction and supervision in connection with the management of several funds in the Fund Complex. He has also previously served as president of several funds in the Fund Complex.
Independent Trustees
Wade A. Dokken. Mr. Dokken has extensive experience in the financial services business. He is currently a member of WealthVest Financial Partners, a broker-dealer focused, national annuity wholesaling firm, and is also the co-founder and co-president of WealthVest Marketing, a financial services marketing and distribution firm specializing in high quality fixed and fixed index annuities from insurance companies. From 1989 to 2000, he was an executive of American Skandia (and, from 2000 to 2003, its chief executive officer) where, among other things, he was chairman of the board of American Skandia Trust, overseeing the American Skandia mutual funds, and a member of the international board of Skandia Life, overseeing mutual fund and pension businesses throughout Europe, Asia and South America.
R. James Maxson. Mr. Maxson was a practicing attorney with Maxson Law Office, P.C. until 2019. He is currently an Associate Supreme Court Justice for the Three Affiliated Tribes (Mandan, Hidatsa, and Arikara). Mr. Maxson currently serves on the board of directors of the Peoples State Bank of Velva, North Dakota. He was previously chair of the Minot Area Development Corporation and the Vincent United Methodist Foundation and on the board of directors of the Kennedy Memorial Foundation. In addition, he is a former North Dakota State Senator, a former President of the North Dakota Trial Lawyers Association, and a former Democratic National Committeeman for North Dakota, as well as a former member of the boards of directors of St. Joseph’s Community Health Foundation, St. Joseph’s Foundation, and the Minot Community Land Trust.
Jerry M. Stai. Mr. Stai is on the faculty of Minot State University where he teaches accounting and finance courses, including corporate finance, investments, and financial institutions and markets.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-8 |
Board Committees
The Audit Committee consists of the three Independent Trustees of the Funds: Jerry M. Stai, R. James Maxson, and Wade A. Dokken. The primary function of the Audit Committee is to assist the full Board of Trustees in fulfilling its oversight responsibilities to the shareholders and the investment community relating to fund accounting, reporting practices and the quality and integrity of the financial reports. To satisfy these responsibilities, the Audit Committee reviews with the independent auditors the audit plan and results and recommendations following independent audits, reviews the performance of the independent auditors, and recommends engagement or discharge of the auditors to the full Board of Trustees, reviews the independence of the independent auditors, reviews the adequacy of the Funds’ internal controls, and prepares and submits Committee meeting minutes and supporting documentation to the full Board. During the Funds’ fiscal year ended July 31, 2024, the Audit Committee held two meetings.
The Governance and Nominating Committee consists of the three Independent Trustees of the Funds: Jerry M. Stai, R. James Maxson, and Wade A. Dokken. The primary function of the Governance and Nominating Committee is to identify individuals qualified to become Board members and recommend nominations for election to the Board of Trustees. The Governance and Nominating Committee also takes a leadership role in shaping the governance of the Funds. The Governance and Nominating Committee has adopted a charter and meets at least quarterly. The Governance and Nominating Committee prepares and submits meeting minutes and supporting documentation to the full Board. During the Funds’ fiscal year ending of July 31, 2024, the Governance and Nominating Committee held five meetings.
When considering whether to add additional or substitute Trustees to the Board of Trustees, the Independent Trustees shall take into account any proposals for candidates that are properly submitted to the Trust’s Secretary. Shareholders wishing to present one or more candidates for Trustee consideration may do so by submitting a signed written request to the Trust’s Secretary at Viking Mutual Funds, Attention: Secretary, PO Box 500, Minot, North Dakota 58702. The request must include the following information:
| • | name and address of shareholder and, if applicable, name of broker or record holder; |
| • | number of shares owned; |
| • | name of fund(s) in the Integrity/Viking family of funds (“Integrity/Viking Funds”) in which shares are owned; |
| • | whether the proposed candidate(s) consent to being identified in any proxy statement utilized in connecting with the election of Trustees; |
| • | the name and background information of the proposed candidates; and |
| • | a representation that the candidate or candidates are willing to provide additional information about themselves, including assurances as to their independence. |
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-9 |
Additional Information about Trustees and Officers
Pursuant to the Trust’s Trust Instrument, each Trustee shall hold office for life until his or her successor is elected or the Trust terminates; except that (a) any Trustee may resign by delivering a written resignation; (b) any Trustee may be removed with or without cause at any time by a written instrument signed by at least two-thirds of the other Trustees; (c) any Trustee who requests to be retired, or who has become unable to serve, may be retired by a written instrument signed by a majority of the other Trustees; and (d) any Trustee may be removed at any shareholder meeting by a vote of at least two-thirds of the outstanding shares. Pursuant to the by-laws of the Trust, each officer elected by the Trustees shall hold office until his or her successor shall have been elected and qualified or until his or her earlier death, inability to serve, or resignation. Officers serve at the pleasure of the Trustees and may be removed at any time with or without cause.
Independent Trustees
| Name,
Address, and Date of Birth |
Position with Trust | Date Service Began | Number of Funds Overseen by Trustee in Fund Complex | Principal
Occupations for Past Five Years |
Other Directorships Held During Past Five Years | |||||
| Wade
A. Dokken 1 N. Main St. Minot, ND 58703 March 3, 1960 |
Trustee | February 2016 |
12 | Member, WealthVest Financial Partners (2009 to present); Co-President, WealthVest Marketing (2009 to present); Trustee: The Integrity Funds (2016 to present) | None | |||||
| R.
James Maxson 1 N. Main St. Minot, ND 58703 December 12, 1947 |
Trustee | August 2009 | 12 | Associate Supreme Court Justice: Three Affiliated Tribes (2014 to present); Attorney: Maxson Law Office P.C. (2002 to 2019); Trustee: The Integrity Funds (2003 to present) | Peoples State Bank of Velva | |||||
| Jerry
M. Stai 2405 11th Ave NW Minot, ND 58703 March 31, 1952 |
Trustee | August 2009 | 12 | Faculty: Minot State University (1999 to present); Trustee: The Integrity Funds (2006 to present) | None | |||||
Interested Trustee
| Name, Address, and Date of Birth |
Position with Trust | Date Service Began | Number of Funds Overseen by Trustee in Fund Complex | Principal Occupations for Past Five Years |
Other Directorships Held During Past Five Years | |||||
| Robert E. Walstad(1) 1 N. Main St. Minot, ND 58703 August 16, 1944 |
Trustee, Chairman | August 2009 |
12 | Governor (2009 to present): Corridor Investors, LLC; Trustee and Chairman: The Integrity Funds (2003 to present) | None | |||||
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-10 |
Officers
| Name,
Address, and Date of Birth |
Position with Trust | Date Service Began | Principal
Occupations for Past Five Years |
Other Directorships Held During Past Five Years | ||||
| Shannon
D. Radke(2) 1 N. Main St. Minot, ND 58703 September 7, 1966 |
President | 1999 | Governor, CEO, and President (2009 to present): Corridor Investors, LLC; Governor and President (1998 to present) and Senior Portfolio Manager (1999 to present): Viking Fund Management, LLC; Governor and President (2009 to present): Integrity Fund Services, LLC and Integrity Funds Distributor, LLC; President: The Integrity Funds (2009 to present) | Minot Area Community Foundation | ||||
| Peter
A. Quist(2) 1 N. Main St. Minot, ND 58703 February 23, 1934 |
Vice President | August 2009 | Governor (2009 to present): Corridor Investors, LLC; Attorney (inactive); Vice President: The Integrity Funds (2003 to present) | N/A | ||||
| Shelly
Nahrstedt 1 N. Main St. Minot, ND 58703 August 31, 1961 |
Treasurer | August 2020 | Chief Operating Officer, Integrity Fund Services, LLC and Corridor Investors, LLC, and Treasurer, The Integrity Funds (2020 to present); Director of Financial Fund Administration, PNC Capital Advisors, LLC, and Treasurer, PNC Funds (2018-2019). | Monteagle Funds | ||||
| Addie
Larson 1 N. Main St. Minot, ND 58703 September 3, 1992 |
Assistant Treasurer | November 2023 | Sales Tax Auditor III, State of North Dakota (2018-2019); Senior Accountant, City of Minot (2019-2022); Fund Accounting Manager, Integrity Fund Services, LLC (2022 to present); and Assistant Treasurer, The Integrity Funds (2023 to present) and Viking Mutual Funds (2023 to present) | N/A | ||||
| Brent
M. Wheeler(2) 1 N. Main St. Minot, ND 58703 October 9, 1970 |
Mutual Fund Chief Compliance Officer and Secretary | August 2009 and October 2009 | Mutual Fund Chief Compliance Officer: The Integrity Funds (2005 to present); Secretary: The Integrity Funds (2009 to present) | N/A | ||||
| (1) | Trustee who is an “interested person” of the Fund as defined in the 1940 Act. Mr. Walstad is an interested person by virtue of his ownership of a membership interest in Corridor, the parent company of Viking Management, Integrity Fund Services, LLC, and Integrity Funds Distributor, LLC. He is also a governor of Corridor. |
| (2) | Shannon D. Radke, Peter A. Quist, Shelly Nahrstedt, Addie Larson, and Brent M. Wheeler each own membership interests in Corridor (the parent company of Viking Management, Integrity Fund Services, LLC and Integrity Funds Distributor, LLC). Mr. Radke and Mr. Quist are also governors of Corridor. In addition, Mr. Radke is an officer of Corridor, an officer and a governor of Viking Fund Management, LLC, and an officer and a governor of Integrity Fund Services, LLC and Integrity Funds Distributor, LLC. |
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-11 |
In summarizing the above information, Messrs. Walstad, Dokken, Maxson, and Stai are Trustees of the two open-end investment companies that make up the Fund Complex. Mr. Radke serves as President, Mr. Quist serves as Vice President, Ms. Nahrstedt serves as Treasurer, Ms. Larson serves as Assistant Treasurer, and Mr. Wheeler serves as Secretary and Mutual Fund Chief Compliance Officer to the same two open-end investment companies that make up the Fund Complex.
The Trust’s Trust Instrument provides that the Trust will indemnify its trustees and officers against liabilities and expenses reasonably incurred in connection with litigation in which they may be involved because of their offices with the Trust, unless it is adjudicated that they (a) engaged in bad faith, willful misfeasance, gross negligence, or reckless disregard of the duties involved in the conduct of their offices, or (b) did not act in good faith in the reasonable belief that their action was in the best interest of the Trust. In the case of settlement, such indemnification will not be provided unless it has been determined (by court or other body approving the settlement or other disposition, by a majority of disinterested trustees based upon a review of readily available facts, or in a written opinion of independent counsel) that such officers or trustees have not engaged in willful misfeasance, bad faith, gross negligence, or reckless disregard of their duties. In addition, the Trust has entered into a separate Indemnification Agreement with each of the Trustees and officers of the Trust whereby the Trust has generally agreed to indemnify such persons to the fullest extent permitted by the laws of the State of Delaware. These Indemnification Agreements acknowledge, however, that, in certain instances, applicable law or public policy may prohibit the Trust from indemnifying its Trustees and officers.
Share Ownership in the Funds
For each Trustee, the dollar range of equity securities in the Funds beneficially owned by the Trustee and the aggregate dollar range of equity securities in all registered investment companies overseen by the Trustee in the same family of investment companies as the Trust are shown below as of December 31, 2023:
|
Interested Trustee |
Independent Trustees | |||
|
Robert E. Walstad |
Wade A. Dokken |
R. James Maxson |
Jerry M. Stai | |
| Kansas Fund | None | None | None | None |
| Maine Fund | None | None | None | None |
| Nebraska Fund | None | None | None | None |
| Oklahoma Fund | None | None | None | None |
| Montana Fund | None | None | None | None |
| North Dakota Fund | None | None | $10,001 – $50,000 | None |
| All Registered Investment Companies Overseen by Trustee in Family of Investment Companies (Aggregate) | $50,001 - $100,000 | $10,001 - $50,000 | over $100,000 | $1 – $10,000 |
As of November 1, 2024, the Trustees and Officers of the Trust, as a group, owned of record and beneficially less than 1% of the shares of each Fund.
As of December 31, 2023, no Independent Trustee or his immediate family members owned beneficially or of record securities in an investment adviser or principal underwriter of the Funds, or a person (other than a registered investment company) directly or indirectly controlling, controlled by or under common control with an investment adviser or principal underwriter of the Funds.
Compensation
Trustees who are not considered to be “interested persons,” as that term is defined in the 1940 Act, of Viking Mutual Funds (previously defined as “Independent Trustees”), are paid an annual fee of $30,500 for service as trustee on the boards of the trusts in the Fund Complex. In addition, each Independent Trustee is entitled to receive a fee of $3,500 for attendance at each meeting of the Board of Trustees (whether attendance is telephonic or in person) that is not on the regular Board of Trustees meeting schedule. Mr. Walstad, as an “interested person” of the Funds, receives no compensation from the Funds for serving as Trustee; however, he does receive compensation from Corridor for serving in such capacity. The Funds have no retirement or pension plans for Trustees. The table below sets forth compensation earned by the Independent Trustees from the Funds and the Fund Complex for the fiscal year ended July 31, 2024.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-12 |
| Interested Trustee | Independent Trustees | |||||||||||||||
| Aggregate Compensation from each Fund | Robert E. Walstad | Wade A. Dokken | R. James Maxson | Jerry M. Stai | ||||||||||||
| Kansas Fund | $ | 0 | $ | 2,194 | $ | 2,194 | $ | 2,194 | ||||||||
| Maine Fund | $ | 0 | $ | 353 | $ | 353 | $ | 353 | ||||||||
| Nebraska Fund | $ | 0 | $ | 1,361 | $ | 1,361 | $ | 1,361 | ||||||||
| Oklahoma Fund | $ | 0 | $ | 1,850 | $ | 1,850 | $ | 1,850 | ||||||||
| Montana Fund | $ | 0 | $ | 2,319 | $ | 2,319 | $ | 2,319 | ||||||||
| North Dakota Fund | $ | 0 | $ | 841 | $ | 841 | $ | 841 | ||||||||
| Total Compensation from Funds and Fund Complex(1) | $ | 0 | $ | 30,500 | $ | 30,500 | $ | 30,500 | ||||||||
| (1) | Based on the compensation paid by the Funds and the other funds in the complex to the Trustees during the period from August 1, 2023 through the Funds’ fiscal period end of July 31, 2024, for services as a trustee to the Funds and the six open-end series of The Integrity Funds that comprise the Fund Complex. |
PORTFOLIO HOLDINGS DISCLOSURE
The Trust’s Board has adopted Portfolio Holdings Disclosure Policies and Procedures (the “Policy”) to protect the interests of Fund shareholders and to address potential conflicts of interests that could arise between the interests of Fund shareholders and the interests of the Funds’ investment advisers, principal underwriters, or affiliated persons of the Funds’ investment advisers or principal underwriters. This Policy is applicable to Viking Management, which is the investment manager to the Funds (the “Adviser” for purposes of this section).
The Policy is intended to prevent the misuse of material non-public information regarding the portfolio holdings of the Fund (“Holdings Information”). Holdings Information will be disclosed to select third parties only when the Funds have a legitimate business purpose for doing so, and the Recipients (as defined below) are subject to a duty of confidentiality that includes a duty not to trade based on the non-public information. Under the Policy, the receipt of compensation by a Fund, the Adviser, or an affiliate as consideration for disclosing Holdings Information will not be deemed a legitimate business purpose. Recipients will receive Holdings Information only after furnishing written assurances to the Adviser and/or the Funds that the Holdings Information will remain confidential, and Recipients and persons with access to the Holdings Information will be prohibited from trading based on the Holdings Information. In all instances, Holdings Information will be disclosed only when consistent with the antifraud provisions of the federal securities laws and the Adviser’s fiduciary duties, and with the Adviser’s and the Fund’s obligations to prevent the misuse of material, non-public information.
The Fund’s service providers, such as the investment adviser, custodian, transfer agent, accounting service provider, administrator, independent public accountant, and legal counsel need access to such information in the performance of their duties and responsibilities and will receive portfolio holdings information as needed. Depending upon the service provider’s particular duty that requires portfolio holdings information, such information may be provided at varying frequencies and lags from the date of the information.
Pursuant to the Policy, the Funds, the Adviser, and their agents are obligated to:
| • | act in the best interests of Fund shareholders by protecting non-public and potentially material portfolio holdings information; |
| • | ensure that Holdings Information is not provided to a favored group of clients or potential clients; and |
| • | adopt such safeguards and controls around the release of Holdings Information so that no client or group of clients is unfairly disadvantaged as a result of such release. |
The following policies and procedures will apply to the disclosure of listings of portfolio holdings for one or more of the Funds by the Adviser and the Funds:
Internet Site and Quarterly Advertisements
Pursuant to the Policy, the Funds may post up to the top 25 holdings for each Fund on the Internet at www.integrityvikingfunds.com. This Holdings Information may be updated daily. The Funds also may include up to the top 25 holdings quarterly through printed marketing material, which is also posted on the website. This printed material is updated as of the end of the calendar quarter and is available within fifteen days of each quarter end. The Holdings Information posted on the Internet and listed in the printed marketing material may list the securities in numeric order, beginning with the security constituting the largest percentage held by the Fund, and
| • | may include the name of the security, the CUSIP, SEDOL and/or ticker symbol, the number of shares held by the Fund, the percentage weight of such security within the Fund; and |
| • | will contain appropriate disclaimers. |
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-13 |
SEC Filings
The Funds must disclose their complete portfolio holdings quarterly to the SEC using Form N-PORT within 60 days of the end of the first and third quarter end of the Funds’ fiscal year and using Form N-CSR for the second and fourth quarter of the Funds’ fiscal year. The N-PORT report is not required to be mailed to shareholders, but is made public through the SEC electronic filings.
Other Disclosure
To the extent that this Policy would require the release of Holdings Information regarding a particular portfolio holding for a Fund, subject to applicable law, the portfolio manager for the Fund may request that the holding be withheld from the Holdings Information if the release of such Holdings Information would otherwise be sensitive or inappropriate due to liquidity and other market considerations, in each case as determined by the portfolio manager in consultation with the Investment Adviser Chief Compliance Officer (or his/her designee).
Each of the Investment Adviser’s officers (“Designated Persons”) may authorize providing non-public Holdings Information of the Funds that is current as of one business day after the month-end to only those financial advisers, registered accountholders, authorized consultants, authorized custodians or third-party data service providers (each a “Recipient”) who (i) specifically request the more current non-public Holdings Information for a legitimate business purpose which is not inconsistent with the Funds’ legitimate business purpose and (ii) execute a Use and Nondisclosure Agreement (each, a “Nondisclosure Agreement”), and abide by its trading restrictions. The disclosure may include additional information; however, any such additional information provided to a Recipient shall not include any material information about the Funds’ trading strategies or pending transactions. The following parties currently receive non-public Holdings Information regarding one or both of the Funds on an ongoing basis pursuant to a Nondisclosure Agreement: Bloomberg; FactSet; and Lipper.
Designated Persons may approve the distribution in an electronic format of Holdings Information posted on the public website of the Funds to Recipients and rating agencies upon request, and such Recipients and rating agencies will not be required to execute a Nondisclosure Agreement.
Occasions may arise where a Designated Person, the Investment Adviser, the Funds, or an affiliate may have a conflict of interest in connection with a Recipient’s request for disclosure of non-public Holdings Information. In order to protect the interests of shareholders and the Funds and to ensure no adverse effect on the shareholders or the Funds, in the limited instances where a Designated Person is considering releasing non-public Holdings Information, the Policy requires the Designated Person to disclose the conflict to the CCO of the Trust. If the CCO determines, to the best of his knowledge following appropriate due diligence, that the disclosure of non-public Holdings Information would be in the best interests to the Funds, and will not adversely affect the Funds, the CCO may approve the disclosure.
The Adviser and the Funds currently do not disclose Holdings Information except as noted above. The Funds and the Adviser will not enter into any arrangement providing for the disclosure of Holdings Information for the receipt of compensation or benefit of any kind in return for the disclosure of the Holdings Information.
MANAGEMENT AND OTHER SERVICES
The Board has overall responsibility for the management of the Funds. Viking Management, P.O. Box 500, Minot, North Dakota 58702, is the Funds’ investment manager. Since July 31, 2009, Viking Management has been a wholly-owned subsidiary of Corridor, a North Dakota limited liability company that was organized in January 2009 by Robert E. Walstad and Shannon D. Radke. Corridor provides investment advisory, distribution and other services to the Funds, as well as to the other funds in the Fund Complex described above under “Trustees and Officers,” primarily through its subsidiaries.
As indicated above under “Trustees and Officers,” (i) Shannon D. Radke, an officer of the Trust, is also a governor, member and officer of Corridor and a governor and officer of Viking Management; (ii) Robert E. Walstad, a Trustee and Chairman of the Board of the Trust, is also a governor and member of Corridor; (iii) Peter A. Quist, an officer of the Trust, is also a governor and member of Corridor; and (iv) Shelly Nahrstedt, an officer of the Trust, is also a member of Corridor; (v) Addie Larson, an officer of the Trust, is also a member of Corridor; and (vi) Brent M. Wheeler, an officer of the Trust, is also a member of Corridor.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-14 |
The Funds have retained Viking Management to provide the Funds with investment advice and portfolio management. The portfolio management team for each Fund consists of Shannon D. Radke (Senior Portfolio Manager) and Josh Larson (Portfolio Manager). Since August 1, 2009, Viking Management has also acted as investment manager to the remaining Funds in Viking Mutual Funds and the six funds in The Integrity Funds.
The following table lists the number and types of other accounts managed by Mr. Radke and Mr. Larson, and assets under management in those accounts as of July 31, 2024:
| Name of Portfolio Manager | Number of Registered Investment Company Accounts (Other than the Funds) & Total Assets for Such Accounts | Number of Other Pooled Investment Vehicles Managed and Total Assets for Such Accounts | Number of Other Accounts Managed and Total Assets for Such Accounts | Beneficial Ownership of Equity Securities in the Funds Managed |
| Shannon D. Radke | 3 accounts with assets of $504 million | None | None | None |
| Josh Larson | 3 accounts with assets of $483 million | None | None | None |
The advisory fee is not based on the performance of the respective account for any of the registered investment companies, pooled investment vehicles or other accounts referred to above.
As compensation for the advisory services furnished to the Funds, each Fund is obligated under the investment advisory agreement to pay Viking Management monthly compensation calculated daily by applying the annual rates of 0.50% to the Funds’ daily net assets. The investment management fee for each Fund is allocated proportionally between the Fund’s Class A and Class I shares.
For the three most recent fiscal years, the table below sets forth (i) the management fees (net of fee waivers and expense reimbursements, discussed below) paid by the Funds and (ii) the fees waived and expenses reimbursed by Viking Management for the specified periods.
| Fund | Date
of Fiscal Year End |
$
Earned (Gross) |
Advisory
Fee Waivers and Expense Reimbursements |
$
Paid Net of Fees Waived and Expense Reimbursements |
| Kansas Fund | 7/31/2022 | $388,683 | $129,582 | $259,101 |
| 7/31/2023 | $324,005 | $125,158 | $198,847 | |
| 7/31/2024 | $304,512 | $122,198 | $182,314 | |
| Maine Fund | 7/31/2022 | $ 64,413 | $ 62,715 | $ 1,698 |
| 7/31/2023 | $ 53,046 | $ 58,758 | $ 0 | |
| 7/31/2024 | $ 51,833 | $ 57,713 | $ 0 | |
| Nebraska Fund | 7/31/2022 | $280,558 | $107,280 | $173,278 |
| 7/31/2023 | $224,682 | $100,193 | $124,489 | |
| 7/31/2024 | $171,996 | $ 88,798 | $ 83,198 | |
| Oklahoma Fund | 7/31/2022 | $372,316 | $128,239 | $244,077 |
| 7/31/2023 | $287,655 | $115,141 | $172,514 | |
| 7/31/2024 | $245,390 | $ 99,757 | $145,633 | |
| Montana Fund | 7/31/2022 | $451,208 | $143,955 | $307,253 |
| 7/31/2023 | $354,258 | $133,646 | $220,612 | |
| 7/31/2024 | $321,790 | $119,811 | $201,979 | |
| North Dakota Fund | 7/31/2022 | $160,082 | $ 79,832 | $ 80,250 |
| 7/31/2023 | $129,333 | $ 76,459 | $ 52,874 | |
| 7/31/2024 | $109,779 | $ 69,819 | $ 39,960 |
During each Fund’s most recent fiscal period reflected in the table above, Viking Management contractually agreed to waive its fees or reimburse each Fund for its expenses (excluding taxes, brokerage fees, commissions, extraordinary and non-recurring expenses, and the fees and expenses of acquired funds), so that the Fund’s total annual operating expenses did not exceed 0.98% for Class A Shares and 0.73% for Class I Shares of average daily net assets. Current contractual fee waiver and expense reimbursement agreements are described below under “Current contractual fee waiver and expense reimbursement agreements.” In addition, certain affiliated service providers, including Integrity Fund Services, LLC and Integrity Funds Distributor, LLC, may voluntarily waive from time to time all or a portion of their respective fees, which waiver may occur before Viking Management waives any of its fee or reimburses any expenses to satisfy its contractual expense limitation agreement.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-15 |
Conflicts of Interest
Actual or apparent conflicts of interest may arise when a portfolio manager has day-to-day management responsibilities with respect to more than one fund or other account. More specifically, portfolio managers who manage multiple funds are presented with the following potential conflicts.
The management of multiple funds and accounts may result in a portfolio manager devoting unequal time and attention to the management of each fund or account. The management of multiple funds and accounts, however, also may give rise to potential conflicts of interest if the funds and accounts have different objectives, benchmarks, time horizons, and fees as the portfolio manager must allocate his time, investment ideas, and investment opportunities across multiple funds and accounts.
| • | With respect to securities transactions for the Funds, Viking Management determines which broker to use to execute each order, consistent with the duty to seek best execution of the transaction. The portfolio manager may execute transactions for another fund or account that may adversely impact the value of securities held by the Funds. Securities selected for funds or accounts other than the Funds may outperform the securities selected for the Funds. |
| • | The appearance of a conflict of interest may arise where Viking Management has an incentive, such as a performance-based management fee, which relates to the management of one fund or account but not all funds with respect to which a portfolio manager has day-to-day management responsibilities. The management of personal accounts may give rise to potential conflicts of interest; there is no assurance that the Funds’ code of ethics will adequately address such conflicts. |
| • | The Funds have adopted a code of ethics that, among other things, permits personal trading by employees, including the portfolio manager, under conditions where it has been determined that such trades would not adversely impact client accounts. Nevertheless, the management of personal accounts may give rise to potential conflicts of interest and there is no assurance that these codes of ethics will adequately address such conflicts. |
Viking Management and the Funds have adopted certain compliance procedures which are designed to address these types of conflicts. However, there is no guarantee that such procedures will detect each and every situation in which a conflict arises.
Compensation
The portfolio managers for the Funds are paid a salary. Although the salary is subject to periodic adjustment, it is not based on Fund performance or the value of assets held in the Funds’ portfolio. In addition, Corridor sponsors a 401(k) plan for all its employees. This plan is funded by employee elective deferrals and a 4% match by Corridor of the employee’s gross pay as long as the employee has elected to contribute at least 4% of his or her gross pay. Mr. Radke also owns a membership interest in Corridor equal to approximately 10.55% of Corridor’s total membership interests. He initially received a membership interest in 2009 in exchange for, among other things, his contributions to Corridor of experience and his role in the operations of Corridor. Mr. Radke also purchased a portion of his membership interests in Corridor. In connection with his role, Mr. Larson also owns a membership interest in Corridor that is equal to less than 1% of Corridor’s total membership interests.
Ownership of Securities
As of July 31, 2024, the Funds’ portfolio managers beneficially owned no shares in the Funds.
Current Contractual Fee Waiver and Expense Reimbursement Agreements
As described in the Funds’ Prospectus, Viking Management has contractually agreed to waive its fees or reimburse each Fund for its expenses through November 29, 2025, so that each Fund’s total annual operating expenses (excluding taxes, brokerage fees, commissions, extraordinary and non-recurring expenses, and acquired fund fees and expenses) during this period do not exceed 0.98% for Class A Shares and 0.73% for Class I Shares of the average daily net assets. These contractual waivers may not be altered by the investment manager during the stated period. The terms of the expense limitation agreement provide that Viking Management is entitled to recoup from a Fund such amounts waived or reimbursed for a period of up to three years from the date on which Viking Management waived fees or reimbursed expenses for the Fund. The Fund will make repayments to the Adviser only if such repayment does not cause the annual Fund operating expenses (after the repayment is taken into account) to exceed both (1) the expense limitation in place when such amounts were waived and (2) the Fund’s current expense limitation. Amounts waived or reimbursed by the Adviser prior to November 28, 2018 are not eligible for repayment.
In addition, certain affiliated service providers, including Integrity Fund Services, LLC and Integrity Funds Distributor, LLC, may voluntarily waive from time to time all or a portion of their respective fees, which waiver may occur before Viking Management waives any of its fee or reimburses any expenses to satisfy its contractual expense limitation agreement. Amounts voluntarily waived are not eligible for repayment.
Term of Investment Advisory Agreement
For each Fund, the investment advisory agreement that is currently in effect between the Trust and Viking Management (the “Advisory Agreement”) must be approved each year by (1) a vote, cast in person at a meeting called for that purpose, of a majority of the Independent Trustees, and (2) the majority vote of either the full Board or the vote of a majority of the outstanding shares of a Fund.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-16 |
Code of Ethics
Viking Management, Integrity Funds Distributor, LLC and the Funds have adopted codes of ethics under Rule 17j-1(c) of the 1940 Act. The purpose of a code of ethics is to avoid potential conflicts of interest and to prevent fraud, deception, or misconduct with respect to the Funds. Each code of ethics permits personnel covered by the code to invest in securities, including securities that may be purchased or held by the Funds, subject to the restrictions of the code.
Manager-of-Managers
Under the Advisory Agreement, Viking Management is authorized, at its own cost and expense, to enter into a sub-advisory agreement with a sub-adviser with respect to the respective Fund. If an investment adviser delegates portfolio management duties to a sub-adviser, the 1940 Act generally requires that the sub-advisory agreement between the adviser and the sub-adviser be approved by the Board and by Fund shareholders. Specifically, Section 15 of the 1940 Act, in relevant part, makes it unlawful for any person to act as an investment adviser (including as a sub-adviser) to a mutual fund, except pursuant to a written contract that has been approved by shareholders.
In 2009, shareholders of each Fund approved a “manager-of-managers” structure for their Fund. The Funds have received an order from the SEC permitting the Funds to be managed under a “manager-of-managers” structure (the “SEC Order”). The SEC Order generally permits Viking Management to enter into and materially amend sub-advisory agreements with unaffiliated sub-advisers subject to approval by the Board of Trustees, but without obtaining shareholder approval. If a sub-adviser is hired to provide sub-advisory services to a Fund, the Fund will provide information concerning the sub-adviser to shareholders of the Fund concerned.
Under the “manager-of-managers” structure for a Fund, Viking Management would remain the primary provider of investment advisory services to the Fund, would be permitted to hire or change sub-advisers, as appropriate, and would have ultimate responsibility (subject to oversight by the Funds’ Board of Trustees) to oversee sub-advisers and recommend to the Board their hiring, termination and replacement. Viking Management would remain responsible for providing general management services to a Fund utilizing the manager-of-managers structure, including overall supervisory responsibility for the general management and investment of the Fund’s assets, and, subject to review and approval of the Board of Trustees, would, among other things: (i) set the Fund’s overall investment strategies; (ii) evaluate, select, and recommend sub-advisers to manage all or a part of the Fund’s assets; (iii) when appropriate, allocate and reallocate the Fund’s assets among multiple sub-advisers; (iv) monitor and evaluate the performance of sub-advisers; and (v) implement procedures reasonably designed to ensure that the sub-advisers comply with the Fund’s investment objectives, policies, and restrictions.
TRANSFER AGENT, FUND ACCOUNTING SERVICE PROVIDER, AND ADMINISTRATOR
Prior to August 1, 2009, Viking Management provided administrative, accounting and transfer agent services to the Funds. Since August 1, 2009, Integrity Fund Services, LLC (“Integrity Fund Services” or the “Transfer Agent”), a wholly-owned subsidiary of Corridor, a North Dakota limited liability company affiliated with Viking Management and Integrity Funds Distributor, LLC, provides each Fund with transfer agent, accounting, and administrative services. Integrity Fund Services is located at 1 Main Street North, Minot, North Dakota 58703.
Transfer Agent
As transfer agent, Integrity Fund Services performs many of the Funds’ clerical and administrative functions. For its transfer agency services, every month each Fund pays Integrity Fund Services an asset-based fee plus reimbursement of out-of-pocket expenses. The Transfer Agent is responsible for (among other things) administering and/or performing transfer agent functions; for acting as service agent in connection with dividend and distribution functions; and for performing shareholder account information and administrative agent functions in connection with the issuance, transfer, and redemption or repurchase (including coordination with the custodian) of shares.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-17 |
Accounting Service Provider and Administrator
Accounting services provided by Integrity Fund Services as accounting service provider to the Funds may include, but are not limited to, daily fee accruals, security valuation, calculation of daily net asset value, calculation of a daily dividend rate, and preparation of semi-annual and annual reports, and Form N-CSRs. As administrator for the Funds, Integrity Fund Services manages all aspects of a Fund’s operations except those provided by other service providers. For accounting and administrative services, each Fund pays to Integrity Fund Services at the end of each calendar month a flat fee plus an asset-based fee and reimburses Integrity Fund Services for certain out-of-pocket expenses.
For the fiscal year ends noted, the Funds paid to Integrity Fund Services the following amounts for services provided:
| Fund | Date
of Fiscal Year End |
Combined
Accounting Services and Administrative Services Fees(1) |
Transfer Agency Fee(1) |
| Kansas Fund | 7/31/2022 | $144,831 | $107,003 |
| 7/31/2023 | $126,721 | $ 89,858 | |
| 7/31/2024 | $121,362 | $ 84,010 | |
| Maine Fund | 7/31/2022 | $ 54,036 | $ 23,528 |
| 7/31/2023 | $ 50,853 | $ 20,340 | |
| 7/31/2024 | $ 50,612 | $ 19,473 | |
| Nebraska Fund | 7/31/2022 | $114,556 | $ 78,088 |
| 7/31/2023 | $ 98,911 | $ 63,606 | |
| 7/31/2024 | $ 84,258 | $ 49,714 | |
| Oklahoma Fund | 7/31/2022 | $140,248 | $ 99,974 |
| 7/31/2023 | $116,543 | $ 78,662 | |
| 7/31/2024 | $104,808 | $ 67,287 | |
| Montana Fund | 7/31/2022 | $162,338 | $121,428 |
| 7/31/2023 | $135,192 | $ 96,523 | |
| 7/31/2024 | $126,200 | $ 87,091 | |
| North Dakota Fund | 7/31/2022 | $ 80,823 | $ 47,628 |
| 7/31/2023 | $ 72,213 | $ 40,709 | |
| 7/31/2024 | $ 66,837 | $ 33,390 |
| (1) | After waivers and reimbursements, if any. |
CUSTODIAN
UMB Bank, N.A., Institutional Custody, 928 Grand Blvd, Kansas City, Missouri 64105 serves as the custodian of the Funds and has custody of all securities and assets of the Funds other than cash. UMB Bank, N.A., among other things, attends to the collection of principal and income and payment for and collection of proceeds of securities bought and sold by the Funds.
INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
Each Fund’s independent registered public accounting firm is Cohen & Company, Ltd., 1350 Euclid Ave., Ste 800, Cleveland, OH 44115. Shareholders will receive annual financial statements, together with a report of the independent registered public accounting firm and semi-annual unaudited financial statements of the Funds. The independent registered public accounting firm will report on the Funds’ annual financial statements, review certain regulatory reports, and perform other professional accounting, auditing, and advisory services when engaged to do so by the Funds.
COUNSEL
Thompson Hine LLP, 41 South High Street, Suite 1700, Columbus, Ohio, 43215-6101 serves as counsel for the Trust.
PORTFOLIO TRANSACTIONS
Viking Management places orders for the purchase and sale of portfolio securities on behalf of the Funds, and will do so in accordance with the policies described below.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-18 |
For transactions in fixed-income securities, purchases, and sales of portfolio securities generally are transacted with issuers, underwriters, or dealers that serve as primary market-makers, who act as principals for the securities on a net basis. The Funds typically do not pay brokerage commissions for such purchases and sales. Instead, the price paid for newly issued securities usually includes a concession or discount paid by the issuer to the underwriter, and the prices quoted by market-makers reflect a spread between the bid and the asked prices from which the dealer derives a profit. In effecting securities transactions, each Fund seeks to obtain the best price and execution of orders. For transactions in fixed-income securities, selection of broker-dealers is generally based on the availability of a security and its price and on the overall quality of execution provided by the broker-dealer. In purchasing and selling portfolio securities other than as described above (for example, in the secondary market), each Fund seeks to obtain best execution at the most favorable prices through responsible broker-dealers and, in the case of agency transactions, at competitive commission rates. In selecting broker-dealers to execute transactions, Viking Management considers such factors as the price of the security, the rate of commission, the size and difficulty of the order, and the reliability, integrity, financial condition, and general execution and operational capabilities of competing broker-dealers. In agency transactions, Viking Management also may consider the brokerage and research services that broker-dealers provide to the Funds or Viking Management.
Each Fund may execute agency portfolio transactions with broker-dealers who provide research and execution services to the Fund or other investment accounts over which Viking Management exercises investment discretion. Such services may include advice concerning the value of securities; the advisability of investing in, purchasing, or selling securities; and the availability of securities or the purchasers or sellers of securities. In addition, such broker-dealers may furnish analyses and reports concerning issuers, industries, securities, economic factors and trends, portfolio strategy, and performance of investment accounts; and effect securities transactions and perform functions incidental thereto (such as clearance and settlement). Research may not solely or necessarily be for the benefit of a Fund.
Subject to applicable limitations of the federal securities laws, the Funds may pay a broker-dealer commissions for agency transactions that are in excess of the amount of commissions charged by other broker-dealers in recognition of their research and execution services. In order to cause the Funds to pay such higher commissions, Viking Management must determine in good faith that such commissions are reasonable in relation to the value of the brokerage and research services provided by such executing broker-dealers. In reaching this determination, it will not attempt to place a specific dollar value on the brokerage and research services provided, or to determine what portion of the compensation should be related to those services. No Fund effects transactions with or through broker-dealers in accordance with any formula or for selling shares of a Fund. However, broker-dealers who effect or execute portfolio transactions may from time to time effect purchases of Fund shares for their customers.
Investment decisions for each Fund are made independently from those of other funds managed by Viking Management. It sometimes happens that the same security is held in the portfolio of more than one of these funds or investment accounts. Simultaneous transactions are inevitable when several funds and investment accounts are managed by the same investment adviser, particularly when the same security is suitable for the investment objective of more than one fund or investment account.
When two or more Funds or accounts are simultaneously engaged in the purchase or sale of the same security, the prices and amounts are allocated in accordance with procedures believed to be appropriate and equitable for each Fund or account. In some cases this system could have a detrimental effect on the price or value of the security as far as each Fund is concerned. In other cases, however, the ability of the Funds to participate in volume transactions will produce better executions and prices for the Funds.
For the fiscal years ended July 31, 2022, 2023, and 2024 no agency transactions were executed by Viking Management on behalf of the Funds as transactions for these Funds were done on a principal basis. Therefore, no brokerage commissions were paid by the Funds during those periods.
Portfolio Turnover
Portfolio transactions will be undertaken principally to accomplish a Fund’s objective in relation to anticipated movements in the general level of interest rates, but a Fund may also engage in short-term trading consistent with its objective. Securities may be sold in anticipation of a market decline (a rise in interest rates) or purchased in anticipation of a market rise (a decline in interest rates) and later sold. In addition, a security may be sold and another purchased at approximately the same time to take advantage of what the Investment Adviser believes to be a temporary disparity in the normal yield relationship between the two securities. Yield disparities may occur for reasons not directly related to the investment quality of particular issues or the general movement of interest rates, due to such factors as changes in the overall demand for or supply of various types of municipal securities or changes in the investment objectives of investors.
Each Fund’s investment policies may lead to frequent changes in investments, particularly in periods of rapidly fluctuating interest rates. A change in securities held by a Fund is known as “portfolio turnover” and may involve the payment by the Fund of dealer mark-ups or underwriting commissions and other transaction costs, on the sale of securities, including municipal securities, as well as on the reinvestment of the proceeds in other securities. Each Fund anticipates that its annual portfolio turnover rate will not exceed 75%. Portfolio turnover rate for a fiscal year is the ratio of the lesser of the dollar amount of the purchases or sales of portfolio securities to the monthly average of the value of portfolio securities excluding securities whose maturities at acquisition were one year or less. Each Fund’s portfolio turnover rate will not be a limiting factor when the Fund deems it desirable to sell or purchase securities. Frequent changes in a Fund’s portfolio securities may result in higher transaction costs for the Fund.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-19 |
TAXATION OF THE FUNDS
This section summarizes some of the main U.S. federal income tax consequences of owning shares of a Fund. This section is current as of the date of this SAI. Tax laws and interpretations change frequently, and these summaries do not describe all of the tax consequences to all taxpayers. For example, these summaries generally do not describe your situation if you are a corporation, a non-U.S. person, a broker-dealer, or other investor with special circumstances. In addition, this section does not describe your state, local, or foreign tax consequences.
This federal income tax summary is based in part on the advice of counsel to the Funds. The Internal Revenue Service (“IRS”) could disagree with any conclusions set forth in this section.
As with any investment, prospective investors should seek advice based on their individual circumstances from their own tax advisor.
Each Fund intends to qualify annually and to elect to be treated as a regulated investment company (“RIC”) under the Internal Revenue Code of 1986, as amended (the “Code”).
To qualify for the favorable U.S. federal income tax treatment generally accorded to RICs, each Fund must, among other things, (a) derive in each taxable year at least 90% of its gross income from dividends, interest, payments with respect to securities loans and gains from the sale or other disposition of stock, securities, or foreign currencies or other income (including but not limited to gains from options, futures, or forward contracts) derived with respect to its business of investing in such stock, securities or currencies and net income derived from interests in qualified publicly traded partnerships; (b) diversify its holdings so that, at the end of each quarter of the taxable year, (i) at least 50% of the market value of the Fund’s total assets is represented by cash and cash items (including receivables), U.S. Government securities, the securities of other RICs and other securities, with such other securities of any one issuer generally limited for the purposes of this calculation to an amount not greater than 5% of the value of the Fund’s total assets and not greater than 10% of the outstanding voting securities of such issuer, and (ii) not more than 25% of the value of its total assets is invested in the securities (other than U.S. Government securities or the securities of other RICs) of any one issuer, or two or more issuers which the Fund controls which are engaged in the same, similar or related trades or businesses or the securities of one or more qualified publicly traded partnerships; and (c) distribute at least 90% of its investment company taxable income (which includes, among other items, dividends, taxable interest and net short-term capital gains in excess of net long-term capital losses) and at least 90% of its net tax-exempt interest income each taxable year. There are certain exceptions for failure to qualify if the failure is for reasonable cause or is de minimis, and certain corrective action is taken and certain tax payments are made by the Fund.
Under the Regulated Investment Company Modernization Act of 2010 (“Act”), funds are permitted to carry forward net capital losses incurred in taxable years beginning after December 22, 2010 for an unlimited period of time. The short-term and long-term character of such losses are retained rather than being treated as short-term as under previous law. Pre-enactment losses are eligible to be carried forward for a maximum period of eight years. Pursuant to the Act, post-enactment net capital losses must be utilized before pre-enactment capital losses. As a result, pre-enactment capital loss carryforwards may be more likely to expire unused. The Funds’ capital loss carryforward amounts as of July 31, 2024 were as follows:
| Kansas Fund | Maine Fund | Nebraska Fund | Oklahoma Fund | Montana Fund | North Dakota Fund | |||||||||||||||||||
| Non-expiring short-term losses | $ | 1,279,253 | $ | 476,250 | $ | 1,263,891 | $ | 1,510,535 | $ | 3,144,364 | $ | 877,291 | ||||||||||||
| Non-expiring long-term losses | $ | 4,258,335 | $ | 765,814 | $ | 4,026,191 | $ | 5,396,238 | $ | 5,833,681 | $ | 3,154,456 | ||||||||||||
| Total Capital Loss Carryforwards | $ | 5,537,588 | $ | 1,242,064 | $ | 5,290,082 | $ | 6,906,773 | $ | 8,978,045 | $ | 4,031,747 | ||||||||||||
| Capital loss carryforward utilized | $ | 0 | $ | 0 | $ | 0 | $ | 0 | $ | 0 | $ | 0 | ||||||||||||
As a RIC, each Fund generally will not be subject to U.S. federal income tax on its investment company taxable income (as that term is defined in the Code, but without regard to the deduction for dividends paid) and net capital gain (the excess of net long-term capital gain over net short-term capital loss), if any, that it distributes to shareholders. Each Fund intends to distribute to its shareholders, at least annually, substantially all of its investment company taxable income and net capital gain. If a Fund retains any net capital gain or investment company taxable income, it will generally be subject to federal income tax at regular corporate rates on the amount retained. In addition, amounts not distributed on a timely basis in accordance with a calendar year distribution requirement are subject to a nondeductible 4% excise tax unless, generally, the Fund distributes during each calendar year an amount equal to the sum of (1) at least 98% of its ordinary income (not taking into account any capital gains or losses) for the calendar year, (2) at least 98.2% of its capital gains in excess of its capital losses (adjusted for certain ordinary losses) for the one-year period ending October 31 of the calendar year, and (3) any ordinary income and capital gains for previous years that were not distributed during those years. In order to prevent application of the excise tax, each Fund intends to make its distributions in accordance with the calendar year distribution requirement. A distribution will be treated as paid on December 31 of the current calendar year if it is declared by the Fund in October, November, or December with a record date in such a month and paid by the Fund during January of the following calendar year. Such distributions will be taxable to shareholders in the calendar year in which the distributions are declared, rather than the calendar year in which the distributions are received.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-20 |
Subject to certain reasonable cause and de minimis exceptions, if a Fund failed to qualify as a RIC or failed to satisfy the 90% distribution requirement in any taxable year, the Fund would be taxed as an ordinary corporation on its taxable income (even if such income were distributed to its shareholders) and all distributions out of earnings and profits would be taxed to shareholders as ordinary income, including any dividends attributable to tax-exempt interest income earned by the Fund.
Distributions
Exempt-Interest Dividends
If, at the close of each quarter of the taxable year of a Fund, at least 50% of the value of the respective Fund’s total assets consists of tax-exempt municipal securities, then such Fund is authorized to pay exempt-interest dividends to its shareholders. An exempt-interest dividend is any dividend or part thereof (other than a capital gain dividend) paid by the Fund and properly reported by the Fund as an exempt-interest dividend in written statements furnished to its shareholders. The maximum amount of dividends for a year that a Fund may designate as exempt-interest dividends is equal to its net tax-exempt interest earned from municipal securities for such year. Each Fund intends to invest in sufficient municipal securities so that it will qualify to pay exempt-interest dividends to its shareholders and to provide timely notice to its shareholders of the portion of its dividends that so qualify.
Exempt-interest dividends distributed to shareholders generally are excluded from gross income for federal income tax purposes except in the case of certain substantial users of facilities financed with the proceeds of certain of the bonds owned by the Funds and related persons. Such exempt-interest dividends may be taken into account in determining the alternative minimum tax, as discussed hereinafter. The percentage of income that is tax-exempt is generally applied uniformly to all distributions made during each calendar year and thus is an annual average for a Fund rather than a day-by-day determination for each shareholder whether received in shares or in cash.
Insurance proceeds received by a Fund under any insurance policies which represent maturing interest on defaulted obligations held by the Fund will be excludable from federal gross income if and to the same extent as such interest would have been so excludable if paid by the issuer of the defaulted obligation, provided that at the time such policies are purchased, the amounts paid for such policies are reasonable, customary, and consistent with the reasonable expectation that the issuer of the obligation, rather than the insurer, will pay debt service on the bonds.
If a Fund invests in certain pay-in-kind securities, zero coupon securities, deferred interest securities or, in general, any other securities with original issue discount (or with market discount if the Fund elects to include market discount in income currently), the Fund must accrue income on such investments for each taxable year, which generally will be prior to the receipt of the corresponding cash payments. However, a Fund must distribute to shareholders, at least annually, all or substantially all of its investment company taxable income (determined without regard to the deduction for dividends paid) and its net tax-exempt income, including such income it is required to accrue, to qualify as a RIC and (with respect to its ordinary income and capital gain) to avoid federal income and excise taxes. Therefore, a Fund may have to dispose of its portfolio securities under disadvantageous circumstances to generate cash, or may have to leverage itself by borrowing the cash, to satisfy these distribution requirements.
The market discount rules of the Code apply to tax-exempt municipal securities purchased after April 30, 1993. In general, market discount is the amount (if any) by which the stated redemption price at maturity exceeds an investor’s purchase price (except to the extent that such difference, if any, is attributable to original issue discount not yet accrued), subject to a statutory de minimis rule. Market discount can arise based on the price a Fund pays for municipal securities. Market discount is taxable as ordinary income. Market discount that accretes while a Fund holds a municipal security is recognized as ordinary income by the Fund when principal payments are received on the municipal security or upon sale or at redemption (including early redemption), unless the Fund elects to include market discount in taxable income as it accrues. Distributions to shareholders of a Fund, to the extent of any market discount that is included in the Fund’s taxable income, is taxable to shareholders as ordinary income.
For individuals, interest paid on certain “private activity bonds” issued on or after August 8, 1986, will be treated as an item of tax preference and may, therefore, be subject to the alternative minimum tax. If such private activity bonds are held by a Fund, a proportionate share of the exempt-interest dividends paid by the Fund will be treated as interest on private activity bonds. Such exempt-interest dividends constitute a tax preference item subject to the alternative minimum tax. Each Fund will annually supply shareholders with a report indicating the percentage of Fund income attributable to bonds subject to the alternative minimum tax.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-21 |
Under Section 86 of the Code, up to 85% of a social security recipient’s benefits may be included in gross income for a benefit recipient if the sum of his modified adjusted gross income, which includes income from tax-exempt sources such as tax-exempt bonds and distributions made by a Fund, plus 50% of his social security benefits exceed certain base amounts. Exempt-interest dividends from the Funds are still excluded from gross income to the extent described above; they are however included in the calculation of whether a recipient’s income exceeds certain established amounts.
Interest on indebtedness which is incurred to purchase or carry shares of a mutual fund which distributes exempt-interest dividends during the year is not deductible for federal income tax purposes. Further, a Fund may not be an appropriate investment for persons who are “substantial users” of facilities financed by industrial development bonds held by the respective Fund or are “related persons” to such users; such persons should consult their tax advisers before investing in the respective Fund.
Ordinary Income Dividends and Capital Gain Dividends
Dividends paid out of a Fund’s investment company taxable income are generally taxable to a shareholder as ordinary income to the extent of the Fund’s current and accumulated earnings and profits, whether paid in cash or reinvested in additional shares. Because the Funds invest in debt securities rather than stock of corporations, it is anticipated that none or only a small portion of the Fund’s distributions paid to individual and other non-corporate shareholders will be qualified dividend income eligible for taxation at long-term capital gain tax rates.
A corporation that owns shares generally will not be entitled to the dividends received deduction with respect to dividends received from the Funds.
Distributions of net capital gain (the excess of net long-term capital gain over net short-term capital loss), if any, properly reported as capital gain dividends are taxable to a shareholder as long-term capital gains, regardless of how long the shareholder has held Fund shares. Shareholders receiving distributions in the form of additional shares, rather than cash, generally will have a tax basis in each such share equal to the value of a share of the Fund on the reinvestment date. A distribution of an amount in excess of a Fund’s current and accumulated earnings and profits will be treated by a shareholder as a return of capital for federal income tax purposes. If a Fund makes a return of capital distribution, the distribution will not be taxable to you to the extent of your basis in your shares and thereafter will be treated as a capital gain. Because a return of capital distribution reduces the basis of your shares, a return of capital distribution may result in a higher capital gain or lower capital loss when you sell your shares.
Shareholders will be notified annually as to the U.S. federal income tax status of distributions, and shareholders receiving distributions in the form of additional shares will receive a report as to the value of those shares.
Income and gains from a Fund may also be subject to a 3.8 percent “Medicare tax.” This tax generally applies to your net investment income if your adjusted gross income exceeds certain threshold amounts, which are $250,000 in the case of married couples filing joint returns and $200,000 in the case of single individuals. Interest that is excluded from gross income and exempt-interest dividends from a Fund are generally not included in your net investment income for purposes of this tax.
Sale or Exchange of Fund Shares
Upon the sale or other disposition of shares of a Fund, which a shareholder holds as a capital asset, such a shareholder may realize a capital gain or loss which will be long-term or short-term, depending upon the shareholder’s holding period for the shares. Generally, a shareholder’s gain or loss will be a long-term gain or loss if the shares have been held for more than one year.
Any loss realized on a sale or exchange will be disallowed to the extent that shares disposed of are replaced (including through reinvestment of dividends) within a period of 61 days beginning 30 days before and ending 30 days after the disposition of shares or to the extent that the shareholder, during such period, acquires or enters into an option or contract to acquire, substantially identical stock or securities. In such a case, the basis of the shares acquired will be adjusted to reflect the disallowed loss.
If you hold a share in a Fund for six months or less, any loss incurred by you related to the disposition of such share will be disallowed to the extent of the exempt-interest dividends you received, except in the case of a regular dividend paid by the Fund if the Fund declares exempt-interest dividends on a daily basis in an amount equal to at least 90 percent of its net tax-exempt interest and distributes such dividends on a monthly or more frequent basis. To the extent, if any, it is not disallowed, it will be recharacterized as long-term capital loss to the extent of the capital gain dividends received. In addition, a shareholder cannot take into account any sales or similar charge incurred in acquiring shares of a Fund (a “load charge”) in computing gain or loss on the sale of shares of a Fund if the shareholder sells such shares within 90 days of the date the shares are acquired and the shareholder obtains and subsequently exercises, by January 31 of the calendar year following the calendar year of the sale, the right to reinvest in shares of any mutual fund without the payment of a load charge or with the payment of a reduced charge. (However, such charges shall be treated as incurred in connection with the reinvestment in the shares and will be included in the adjusted basis of such shares.)
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-22 |
Nature of Fund’s Investments
Certain of the Funds’ investment practices are subject to special and complex federal income tax provisions that may, among other things:
| • | disallow, suspend, or otherwise limit the allowance of certain losses or deductions; | |
| • | convert lower taxed long-term capital gain into higher taxed short-term capital gain or ordinary income; | |
| • | convert an ordinary loss or a deduction into a capital loss (the deductibility of which is more limited); | |
| • | cause a Fund to recognize income or gain without a corresponding receipt of cash; | |
| • | adversely affect the time as to when a purchase or sale of stock or securities is deemed to occur; and | |
| • | adversely alter the characterization of certain complex financial transactions. |
Buying Shares Close to a Record Date
Distributions by a Fund reduce the NAV of such Fund’s shares. Should a taxable distribution reduce the NAV below a shareholder’s cost basis, the distribution would be taxable to the shareholder as ordinary income or capital gain as described above, even though, from an investment standpoint, it may constitute a partial return of capital. Specifically, investors should be careful to consider the tax implications of buying shares just prior to a distribution by the Fund. The price of shares purchased at that time includes the amount of the forthcoming distribution, but the distribution will generally be taxable to them.
Backup Withholding
A Fund may be required to withhold U.S. federal income tax from all distributions and sale proceeds payable to shareholders who fail to provide the Fund with their correct taxpayer identification number, fail to make required certifications, or who have been notified by the IRS that they are subject to backup withholding. Corporate shareholders and certain other shareholders specified in the Code generally are exempt from such backup withholding. Special U.S. tax certification requirements apply to non-U.S. investors. This withholding is not an additional tax. Any amounts withheld may be credited against the shareholder’s U.S. federal income tax liability.
Non-U.S. Shareholders
U.S. taxation of a shareholder who, as to the United States, is a nonresident alien individual, a foreign trust or estate, a foreign corporation or foreign partnership (“non-U.S. shareholder”) depends on whether the income of a Fund is “effectively connected” with a U.S. trade or business carried on by the shareholder.
In addition to the rules described in this section concerning the potential imposition of withholding on distributions to non-U.S. persons, distributions to non-U.S. persons that are “financial institutions” may be subject to a withholding tax of 30% unless an agreement is in place between the financial institution and the U.S. Treasury to collect and disclose information about accounts, equity investments, or debt interests in the financial institution held by one or more U.S. persons or the institution is resident in a jurisdiction that has entered into such an agreement with the U.S. Treasury. For these purposes, a “financial institution” means any entity that (i) accepts deposits in the ordinary course of a banking or similar business, (ii) holds financial assets for the account of others as a substantial portion of its business, or (iii) is engaged (or holds itself out as being engaged) primarily in the business of investing, reinvesting or trading in securities, partnership interests, commodities or any interest (including a futures contract or option) in such securities, partnership interests, or commodities. Dispositions of shares and capital gain dividends received by such persons may be subject to such withholding after December 31, 2019.
Distributions to non-financial non-U.S. entities (other than publicly traded foreign entities, entities owned by residents of U.S. possessions, foreign governments, international organizations, or foreign central banks) will also be subject to a withholding tax of 30% if the entity does not certify that the entity does not have any substantial U.S. owners or provide the name, address, and taxpayer identification number of each substantial U.S. owner. Dispositions of shares and capital gain dividends received by such persons may be subject to such withholding after December 31, 2019.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-23 |
Ordinary Income Dividends and Capital Gain Dividends
If the income from a Fund is not “effectively connected” with a U.S. trade or business carried on by the non-U.S. shareholder, distributions of investment company taxable income, generally not including exempt-interest dividends, will generally be subject to a U.S. tax of 30% (or lower treaty rate), which tax is generally withheld from such distributions.
Capital gain dividends and any amounts retained by a Fund which are properly reported by the Fund as undistributed capital gains will not be subject to U.S. tax at the rate of 30% (or lower treaty rate) unless the non-U.S. shareholder is a nonresident alien individual and is physically present in the United States for more than 182 days during the taxable year and meets certain other requirements. However, this 30% tax on capital gains of nonresident alien individuals who are physically present in the United States for more than the 182 day period only applies in exceptional cases because any individual present in the United States for more than 182 days during the taxable year is generally treated as a resident for U.S. income tax purposes; in that case, he or she would be subject to U.S. income tax on his or her worldwide income at the graduated rates applicable to U.S. citizens, rather than the 30% U.S. tax. In the case of a non-U.S. shareholder who is a nonresident alien individual, a Fund may be required to withhold U.S. income tax from distributions of net capital gain unless the non-U.S. shareholder certifies his or her non-U.S. status under penalties of perjury or otherwise establishes an exemption. If a non-U.S. shareholder is a nonresident alien individual, any gain such shareholder realizes upon the sale or exchange of such shareholder’s shares of a Fund in the United States will ordinarily be exempt from U.S. tax unless the gain is U.S. source income and such shareholder is physically present in the United States for more than 182 days during the taxable year and meets certain other requirements.
Distributions from a Fund that are properly reported by the Fund as an interest-related dividend attributable to certain interest income received by the Fund or as a short-term capital gain dividend attributable to certain net short-term capital gain income received by the Fund may not be subject to U.S. federal income taxes, including withholding taxes when received by certain foreign investors, provided that the Fund makes certain elections and certain other conditions are met.
Income Effectively Connected
If the income from a Fund is “effectively connected” with a U.S. trade or business carried on by a non-U.S. shareholder, then distributions of investment company taxable income, generally not including exempt-interest dividends, and capital gain dividends, any amounts retained by such Fund which are properly reported by the Fund as undistributed capital gains and any gains realized upon the sale or exchange of shares of the Fund will be subject to U.S. income tax at the graduated rates applicable to U.S. citizens, residents and domestic corporations. Non-U.S. corporate shareholders may also be subject to the branch profits tax imposed by the Code. The tax consequences to a non-U.S. shareholder entitled to claim the benefits of an applicable tax treaty may differ from those described herein. Non-U.S. shareholders are advised to consult their own tax advisors with respect to the particular tax consequences to them of an investment in a Fund.
Other Taxation
Fund shareholders may be subject to state, local, and foreign taxes on their Fund distributions. Shareholders are advised to consult their own tax advisors with respect to the particular tax consequences to them of an investment in the Fund.
State Taxes
The treatment of certain dividends from each Fund under the tax laws of particular states is discussed below. It should be noted that this treatment may change if a Fund ever fails to qualify as a RIC for federal income tax purposes or if the exempt-interest dividends paid by a Fund are not excluded from gross income for federal income tax purposes. The discussion also assumes that each Fund will meet certain reporting and filing requirements under the applicable state laws and regulations. This discussion is based on state laws as enacted and construed on the date of this SAI and in certain cases is based on administrative guidance from state revenue departments. These laws and interpretations can, of course, change at any time. Only certain specific taxes are discussed below and Fund shares and Fund distributions may be subject to other state and local taxes. In addition, the discussions below are generally limited to Fund distributions attributable to certain tax-exempt interest. Generally, other distributions from a Fund are subject to all state income taxes, except that under certain circumstances, many states do provide exemptions for distributions attributable to interest on certain United States government obligations. Additionally, you may be subject to state income tax to the extent you sell or exchange Fund shares and realize a capital gain on the transaction.
Generally, unlike the federal individual income tax, state income taxes do not provide beneficial treatment of long-term capital gains, including capital gain dividends from a Fund. Further, most states restrict deductions for capital losses.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-24 |
Ownership of shares in a Fund could result in other state and local income tax consequences to certain taxpayers. For example, interest expense incurred or continued to purchase or carry shares of a Fund, if the Fund distributes dividends exempt from a particular state income tax, generally is not deductible for purposes of that income tax.
Prospective investors should consult their tax advisers with respect to all state and local tax issues related to the ownership of shares in a Fund and the receipt of distributions from a Fund.
Kansas Fund
Exempt interest dividends from the Kansas Fund that are excluded from gross income for federal income tax purposes and that are attributable to interest received directly by the Kansas Fund on (i) obligations of the State of Kansas or its political subdivisions issued after December 31, 1987; (ii) obligations of the State of Kansas or its political subdivisions issued prior to January 1, 1988, the interest on which is expressly exempt from income tax under Kansas law; and (iii) obligations of possessions of the United States that are exempt from state taxation under federal law, are excluded from taxable income for purposes of the income tax imposed by the State of Kansas on individuals, fiduciaries, and corporations (other than insurance companies, national banking associations, banks, trust companies, federally chartered savings banks, and savings and loan associations). Distributions from the Kansas Fund, including exempt-interest dividends, may be subject to the taxes imposed by the State of Kansas on insurance companies, national banking associations, banks, trust companies, federally chartered savings banks, and savings and loan associations, when received by shareholders subject to such taxes.
Maine Fund
Exempt-interest dividends from the Maine Fund that are excluded from gross income for federal income tax purposes and that are derived from interest received directly by the Maine Fund on: (i) certain obligations of the State of Maine and its political subdivisions that are exempt from Maine income taxation under Maine law; and (ii) obligations of United States possessions that are exempt from state taxation under federal law, are excluded from taxable income for purposes of the income tax imposed by the State of Maine on individuals, trusts, estates, and corporations. However, dividends taken into account in determining a taxpayer’s federal alternative minimum tax liability may also be taken into account in determining the taxpayer’s state minimum tax that is imposed by the State of Maine on certain corporations. Shares of the Maine Fund and dividends from the Maine Fund may also be taken into account in determining the amount of the franchise tax imposed by the State of Maine on certain financial institutions.
Nebraska Fund
Exempt-interest dividends from the Nebraska Fund that are excluded from gross income for federal income tax purposes and that are attributable to and are reported to an investor as being derived from, interest received directly by the Nebraska Fund on: (i) obligations of the State of Nebraska or its political subdivisions; and (ii) obligations of United States possessions that are exempt from state taxation under federal law are excluded from taxable income for purposes of the income tax imposed by the State of Nebraska on individuals and the income tax imposed by the State of Nebraska on certain corporations. Dividends from the Nebraska Fund could affect the maximum franchise tax rate imposed by the State of Nebraska on certain financial institutions.
Oklahoma Fund
Exempt-interest dividends from the Oklahoma Fund that are excluded from gross income for federal income tax purposes and that are attributable to interest received directly by the Oklahoma Fund on: (i) obligations of the State of Oklahoma or its political subdivisions, to the extent that such interest is specifically exempt from income taxation under the laws of the State of Oklahoma; and (ii) obligations of possessions of the United States that are exempt from state taxation under federal law, are excluded from taxable income for purposes of the income tax imposed by the State of Oklahoma on individuals and corporations.
Montana Fund
You may exclude any exempt-interest dividends paid to you by the Montana Fund from your taxable income for purposes of the personal income tax imposed by the State of Montana on individuals, estates, and trusts, if the dividends can be excluded from gross income for federal income tax purposes and if they are attributable to interest received directly by the Montana Fund on: (i) obligations of the State of Montana or its counties, municipalities, districts or other political subdivisions; or (ii) obligations of possessions of the United States that are exempt from state taxation under federal law.
Distributions from the Montana Fund, including exempt-interest dividends, may be subject to the Montana corporate income tax and the Montana alternative corporate income tax when paid to shareholders subject to those taxes.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-25 |
North Dakota Fund
Individuals, estates and trusts may exclude exempt-interest dividends from the North Dakota Fund from taxable income for purposes of the North Dakota personal income tax if they can be excluded from gross income for federal income tax purposes and are attributable to interest received directly by the North Dakota Fund.
Distributions from the North Dakota Fund, including exempt-interest dividends, may be subject to the North Dakota income tax imposed on corporations when paid to shareholders subject to such tax.
The tax discussion set forth above is for general information only. Annually, shareholders of a Fund receive information as to the tax status of distributions made by the Fund in each calendar year. The foregoing relates to federal and state income taxation as in effect as of the date of this SAI. Investors should consult their own tax advisors regarding the federal, state, local, foreign, and other tax consequences of an investment in a Fund, including the effects of any change or any proposed change, in the tax laws.
ORGANIZATION, VOTING RIGHTS, AND PRINCIPAL HOLDERS
Each Fund is a separate operating series of the Trust, a Delaware statutory trust organized pursuant to a Trust Instrument dated March 30, 1999. The Trust is registered under the 1940 Act as an open-end management investment company, commonly known as a mutual fund. The Trust has six separate operating series, the Funds. Each Fund, except the Kansas Fund and Oklahoma Fund, is non-diversified. Each Fund invests all of its net investable assets in a separate portfolio of securities. Currently, each Fund offers Class A shares and Class I shares. Class A shares and Class I shares differ in certain respects, including with regard to sales charges and fees. The Trustees of the Trust may establish additional series or classes of shares without the approval of shareholders. The assets of each series belong only to that series, and the liabilities of each series are borne solely by that series and no other.
Description of Shares
Each Fund is authorized to issue an unlimited number of shares of beneficial interest (par value $0.001 per share). Shares of each Fund represent equal proportionate interests in the assets of that Fund only and have identical voting, dividend, redemption, liquidation, and other rights. All shares issued are fully paid and non-assessable, and shareholders have no preemptive or other rights to subscribe to any additional shares.
Shareholder Meetings
The Trustees of the Trust do not intend to hold annual meetings of shareholders of any Fund. The Trustees will call special meetings of shareholders of a Fund only if required under the 1940 Act or in their discretion or upon the written request of holders of 10% or more of the outstanding shares of the Fund entitled to vote.
Central Provisions of Trust Instrument
Under Delaware law, the shareholders of each Fund will not be personally liable for the obligations of that Fund; a shareholder is entitled to the same limitation of personal liability extended to shareholders of a corporation. To guard against the risk that Delaware law might not be applied in other states, the Trust Instrument requires that every written obligation of the Trust or a Fund contain a statement that such obligation may be enforced only against the assets of the Trust or Fund and provides for indemnification out of Trust or Fund property of any shareholder nevertheless held personally liable for Trust or Fund obligations, respectively.
Principal Shareholders
As of November 3, 2024, the Officers and Trustees of the Trust owned, as a group, less than 1% of the shares of each Fund. To the best knowledge of the respective Funds, as of November 8, 2024, except as set forth below, no persons owned, of record or beneficially, 5% or more, or a controlling interest (ownership of greater than 25%) of the outstanding shares of any of the Funds. In certain cases, the Funds do not have any knowledge of who the ultimate beneficiaries are of the respective shares. A control person is one who owns, either directly or indirectly, more than 25% of the voting securities of a Fund or acknowledges the existence of control. A shareholder with a controlling interest could affect the outcome of proxy voting or the direction of management of the respective Fund.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-26 |
| Kansas Fund, Class A | ||
| Name | Address | Percent Ownership |
| Edward D Jones & Co | 12555 Manchester Road Saint Louis, MO 63131-3729 |
47.00% |
| Pershing LLC | 1 Pershing Plaza Jersey City, NJ 07399-0002 |
10.73% |
| Kansas Fund, Class I | ||
| Name | Address | Percent Ownership |
| Pershing LLC | 1 Pershing Plaza Jersey City, NJ 07399-0002 |
43.09% |
| RogCo | 126
S Summit PO Box 1047 Arkansas City, KS 67005-2625 |
30.82% |
| NFS LLC FEBO | 499 Washington Blvd Jersey City, NJ 07310-1995 |
7.15% |
| Maine Fund, Class A | ||
| Name | Address | Percent Ownership |
| Edward D Jones & Co | 12555 Manchester Road Saint Louis, MO 63131-3729 |
16.44% |
| Pershing LLC | 1 Pershing Plaza Jersey City, NJ 07399-0002 |
14.07% |
| Timothy S Clifford Jr | 187 Exeter Rd Hampton Falls, NH 03844-2010 |
8.31% |
| NFS LLC FEBO | 499 Washington Blvd Jersey City, NJ 07310-1995 |
7.70% |
| Maine Fund, Class I | ||
| Name | Address | Percent Ownership |
| Charles Schwab Co Inc | 211 Main Street San Francisco, CA 94105-4122 |
59.25% |
| Pershing LLC | 1 Pershing Plaza Jersey City, NJ 07399-0002 |
38.56% |
| Nebraska Fund, Class A | ||
| Name | Address | Percent Ownership |
| Edward D Jones & Co | 12555 Manchester Road Saint Louis, MO 63131-3729 |
45.32% |
| LPL Financial | 4707 Executive Drive San Diego, CA 92121-3091 |
8.68% |
| Pershing LLC | 1 Pershing Plaza Jersey City, NJ 07399-0002 |
7.44% |
| Nebraska Fund, Class I | ||
| Name | Address | Percent Ownership |
| Pershing LLC | 1 Pershing Plaza Jersey City, NJ 07399-0002 |
42.33% |
| NFS | 499 Washington Blvd Jersey City, NJ 07310-0002 |
21.48% |
| LPL Financial | 4707 Executive Drive San Diego, CA 92121-3091 |
17.00% |
| D.A. Davidson & Co. | 8 Third Street North Great Falls, MT 59401-3104 |
7.62% |
| Oklahoma Fund, Class A | ||
| Name | Address | Percent Ownership |
| Edward D Jones & Co | 12555 Manchester Road Saint Louis, MO 63131-3729 |
69.06% |
| LPL Financial | 4707 Executive Drive San Diego, CA 92121-3091 |
8.80% |
| Pershing LLC | 1 Pershing Plaza Jersey City, NJ 07399-0002 |
7.93% |
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-27 |
| Oklahoma Fund, Class I | ||
| Name | Address | Percent Ownership |
| RogCo | 126 S Summit PO Box 1047 Arkansas City, KS 67005-2625 |
47.04% |
| Bruecks | 800 Kouba Drive Yukon, OK 73099-3931 |
8.14% |
| Bruecks | 612 Victoria Drive Yukon, OK 73099-5399 |
6.10% |
| Raymond James & Assoc Inc | 880 Carillon Parkway Saint Petersburg, FL 33716-1102 |
5.33% |
| Montana Fund, Class A | ||
| Name | Address | Percent Ownership |
| Edward D Jones & Co | 12555 Manchester Road Saint Louis, MO 63131-3729 |
49.28% |
| First Clearing, LLC | 2801 Market Street Saint Louis, MO 63103-2523 |
12.86% |
| LPL Financial | 4707 Executive Drive San Diego, CA 92121-3091 |
6.60% |
| Pershing LLC | 1 Pershing Plaza Jersey City, NJ 07399-0002 |
5.72% |
| Montana Fund, Class I | ||
| Name | Address | Percent Ownership |
| LPL Financial | 4707 Executive Drive San Diego, CA 92121-3091 |
26.23% |
| Band & Co c/o US Bank NA | 1555 N Rivercenter
Drive Suite 302 Milwaukee, WI 53212-3958 |
21.30% |
| Charles Schwab Co Inc | 211 Main Street San Francisco, CA 94105-4122 |
15.69% |
| Pershing LLC | 1 Pershing Plaza Jersey City, NJ 07399-0002 |
11.06% |
| First Clearing, LLC | 2801 Market Street Saint Louis, MO 63103-2523 |
9.98% |
| Patsy Kreitzberg | 880 Carillon Parkway Saint Petersburg, FL 33716-1102 |
6.21% |
| North Dakota Fund, Class A | ||
| Name | Address | Percent Ownership |
| NFS LLC FEBO | 499 Washington Blvd Jersey City, NJ 07310-0002 |
38.99% |
| Edward D Jones & Co | 12555 Manchester Road Saint Louis, MO 63131-3729 |
23.78% |
North Dakota Fund, Class I | ||
| Name | Address | Percent Ownership |
| Charles Schwab Co Inc | 211 Main Street San Francisco, CA 94105-4122 |
35.03% |
| Pershing LLC | 1 Pershing Plaza Jersey City, NJ 07399-0002 |
19.49% |
| Peter A. Quist | 389 E Brandon Drive Bismarck, ND 58503-0440 |
9.55% |
BUYING AND SELLING SHARES
Each Fund offers Class A shares and Class I shares. Class A shares and Class I shares are described below and in the Prospectus.
The Funds continuously offer their shares through securities dealers who have an agreement with Integrity Funds Distributor, LLC (“Integrity Funds Distributor” or the “Distributor”). A securities dealer includes any financial institution that, either directly or through affiliates, has an agreement with the Distributor to handle customer orders and accounts with the Funds. This reference is for convenience only and does not indicate a legal conclusion of capacity. Banks and financial institutions that sell shares of the Funds may be required by state law to register as securities dealers.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-28 |
Class I shares may also be available on certain brokerage platforms. An investor transacting in Class I shares through a broker acting as an agent for the investor may be required to pay a commission and/or other forms of compensation to the broker. Fund shares are available in other share classes that have different fees and expenses.
All checks, drafts, wires and other payment mediums used to buy or sell shares of the Funds must be denominated in U.S. dollars. The Funds may either (a) reject any order to buy or sell shares denominated in any other currency or (b) honor the transaction and make adjustments to your account for the transaction as of a date and with a foreign currency exchange factor determined by the drawee bank.
If you buy shares through the reinvestment of dividends, the shares will be purchased at the net asset value determined on the business day following the dividend record date (sometimes known as the ex-dividend date).
As described in the Prospectus, you can buy Class I shares of each Fund at the offering price, which is the net asset value per share. There is no sales charge or Rule 12b-1 fee that is charged on the Class I shares of any Fund. The minimum initial investment for each Fund per share class is $1,000 ($50 for the Monthomatic Investment Plan and $250 for an individual retirement account (IRA)), and the minimum subsequent investment is $50, but the Funds may accept investments of smaller amounts at their discretion and such minimum amounts may be changed at any time.
Class I shares are available for purchase by the following categories of investors:
| ● | investors who purchase through a fee-based advisory account with a financial intermediary; | |
| ● | employer sponsored retirement and benefit plans, endowments, or foundations; | |
| ● | banks or bank trust departments investing for their own account or for funds over which they exercise exclusive discretionary investment authority and that are held in a fiduciary, agency, advisory, custodial, or similar capacity; | |
| ● | subject to applicable law and/or exemptive relief, any registered investment company that is not affiliated with the Integrity/Viking Funds and which invests in securities of other investment companies; | |
| ● | any plan organized under section 529 under the Code (i.e., a 529 plan); | |
| ● | any person who, for at least the last 90 days, has been an officer, director, or employee of any financial intermediary for themselves, their immediate family members (“immediate family members” are defined as spouses or domestic partners, parents, children, grandparents, grandchildren, parents-in-law, sons-in-law and daughters-in-law, siblings, a sibling’s spouse, and a spouse’s siblings), their IRAs or employer sponsored IRAs; | |
| ● | current, former, and retired trustees/directors, employees and officers of any Integrity/Viking Fund for themselves, their immediate family members, their IRAs or employer sponsored IRAs; | |
| ● | current, former, and retired officers, directors and governors of Corridor and its affiliates, for themselves, their immediate family members, their IRAs or employer sponsored IRAs; | |
| ● | current, former, and retired employees of Corridor and its affiliates for themselves, their immediate family members, their IRAs or employer sponsored IRAs, any corporation, partnership, sole proprietorship, or other business organization in which such persons own a 25% or greater stake; and | |
| ● | persons who retain an ownership interest in or who are the beneficial owners of an interest in Corridor for themselves, their immediate family members, their IRAs or employer sponsored IRAs, any corporation, sole proprietorship or other business organization in which such persons own a 25% or greater stake. |
Unless otherwise noted, Class I shares are not available for IRAs or employer sponsored IRAs, unless purchased through a fee-based advisory account with a financial intermediary. Any shares purchased by investors falling within any of the last five categories listed above must be acquired for investment purposes and on the condition that they will not be transferred or resold except through redemption by a Fund.
Holders of Class I shares may purchase additional Class I shares using dividends and capital gains distributions on their shares.
If you are eligible to purchase either Class I shares at net asset value or Class A shares with or without the initial sales charge discussed below, you should be aware of the differences between these two classes of shares. Class A shares are subject to an annual service fee to compensate financial intermediaries for providing you with ongoing account services. Class I shares are not subject to a distribution or service fee and, consequently, holders of Class I shares may not receive the same types or levels of services from financial intermediaries. In choosing between Class A shares and Class I shares, you should weigh the benefits of the services to be provided by financial intermediaries against the annual service fee imposed upon the Class A shares.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-29 |
Each Fund reserves the right to redeem Fund accounts that are reduced to a value of less than $1,000 for any reason, including market fluctuation. Should a Fund elect to exercise this right, the investor will be notified before such redemption is processed that the value of the investor’s account is less than $1,000 and that the investor will have sixty days to increase the account to at least the $1,000 minimum amount before the account is redeemed. The investor will not be assessed a contingent deferred sales charge if the account is redeemed.
Initial Sales Charges—Class A Shares
The maximum initial sales charge for the Funds is 2.50%. The initial sales charge may be reduced or waived, as described below. The Funds offer several ways for you to combine your purchases of shares of the Funds to take advantage of the lower sales charges for large purchases. Reduced sales charge amounts are shown in the Funds’ Prospectus under “The Shares Offered-Class A Shares.” However, you may be subject to a 1% contingent deferred sales charge (“CDSC”) on Class A shares purchased without an initial sales charge when such shares are redeemed within 24 months of purchase.
Please see Appendix A - Intermediary-Specific Sales Charge Waivers and Discounts in the prospectus for a description of variations in sales charges and waivers for Fund shares purchased through Edward Jones, Raymond James, Oppenheimer & Co. Inc., Robert W. Baird & Co., and Morgan Stanley Wealth Management.
Cumulative Quantity Discount—Class A Shares
For purposes of calculating the sales charge, you may combine the amount of your current purchase with the cost or current value, whichever is higher, of your existing shares in the Funds or the other funds in the Integrity/Viking Funds. You may also combine the shares of your spouse, children if they are under the age of 21 or grandchildren if they are under the age of 21. You may also add any partnership or corporation if you own a 25% or greater stake, and you may add any retirement plan accounts for which you or your spouse is the beneficial owner. Companies with one or more retirement plans may add together the total plan assets invested in the Integrity/Viking Funds to determine the sales charge that applies.
In order to be sure you obtain a sales charge discount, you should inform your investment representative or Integrity Fund Services, at the time of purchase, of the existence of other accounts in which there are holdings eligible to be aggregated to meet sales load breakpoints.
Please see Appendix A - Intermediary-Specific Sales Charge Waivers and Discounts in the prospectus for a description of variations in sales charges and waivers for Fund shares purchased through Edward Jones, Raymond James, Oppenheimer & Co. Inc., Robert W. Baird & Co., and Morgan Stanley Wealth Management.
Letter of Intent (LOI)—Class A Shares
You may buy Class A shares at a reduced sales charge by completing the letter of intent section of your account application. A letter of intent is a commitment by you to invest a specified dollar amount in Class A shares of Integrity/Viking Funds during a 13-month period. The amount you agree to invest determines the sales charge you pay. By completing the letter of intent section of the application, you acknowledge and agree to the following:
| • | you authorize the Distributor to reserve 5% of your total intended purchase registered in your name until you fulfill your LOI. Your periodic statements will include the reserved shares in the total shares you own, and the Funds will pay or reinvest dividend and capital gain distributions on the reserved shares according to the distribution option you have chosen. | |
| • | you give the Distributor a security interest in the reserved shares and appoint the Distributor as attorney-in-fact. | |
| • | the Distributor may sell any or all of the reserved shares to cover any additional sales charge if you do not fulfill the terms of the LOI. | |
| • | although you may exchange your shares, you may not sell reserved shares until you complete the LOI or pay the higher sales charge |
After you file your LOI with a Fund, you may buy Class A shares at the sales charge applicable to the amount specified in your LOI. Sales charge reductions based on purchases in more than one Integrity/Viking Fund will be effective only after notification to the Distributor that the investment qualifies for a discount. It is the responsibility of the dealer of record and/or the investor to advise the Distributor about the LOI when placing purchase orders during the LOI period. Any purchases you made within 90 days before you filed your LOI may also qualify for a retroactive reduction in the sales charge. Accumulated holdings (as described in the discussion above entitled “Cumulative quantity discount”) eligible to be aggregated as of the day immediately before the LOI period may be credited towards satisfying the LOI. If you file your LOI with a Fund before a change in the Fund’s sales charge, you may complete your LOI at the lower of the new sales charge or the sales charge in effect when the LOI was filed.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-30 |
Your holdings in the Integrity/Viking Funds acquired more than 90 days before you filed your LOI will be counted towards the completion of the LOI, but they will not be entitled to a retroactive reduction in the sales charge. Any redemptions you make during the 13-month period will be subtracted from the amount of the purchases for purposes of determining whether the terms of the LOI have been completed.
If the terms of your LOI are met, the reserved shares will be deposited to an account in your name or delivered to you as you direct. If the amount of your total purchases (including reinvested dividends), less redemptions, is more than the amount specified in your LOI and is an amount that would qualify for a further sales charge reduction, a retroactive price adjustment will be made by the Distributor and the securities dealer through whom purchases were made. The price adjustment will be made on purchases made within 90 days before and on those made after you filed your LOI and will be applied towards the purchase of additional shares at the offering price applicable to a single purchase on the dollar amount of the total purchases.
If the amount of your total purchases (including reinvested dividends), less redemptions, is less than the amount specified in your LOI, the sales charge will be adjusted upward, depending on the actual amount purchased (including reinvested dividends and less redemptions) during the period. You will need to send the Distributor an amount equal to the difference in the actual dollar amount of sales charge paid and the amount of sales charge that would have applied to the total purchases if the total of the purchases had been made at one time. Upon payment of this amount, the reserved shares held for your account will be deposited to an account in your name or delivered to you or as you direct. If within 20 days after written request the difference in sales charge is not paid, an appropriate number of reserved shares will be redeemed to realize the difference. If you redeem the total amount in your account before you fulfill your LOI, the additional sales charge due will be deducted from the sale proceeds and the balance will be forwarded to you.
For LOIs filed on behalf of retirement plans, the level and any reduction in sales charge for these plans will be based on actual plan participation and the projected investments in the Integrity/Viking Funds under the LOI. These plans are not subject to the requirement to reserve 5% of the total intended purchase or to the policy on upward adjustments in sales charges described above, or to any penalty as a result of the early termination of a plan, nor are these plans entitled to receive retroactive adjustments in price for investments made before executing the LOI.
Please see Appendix A - Intermediary-Specific Sales Charge Waivers and Discounts in the prospectus for a description of variations in sales charges and waivers for Fund shares purchased through Edward Jones, Raymond James, Oppenheimer & Co. Inc., Robert W. Baird & Co., and Morgan Stanley Wealth Management.
Group Purchases—Class A Shares
If you are a member of a qualified group, you may buy Class A shares at a reduced sales charge that applies to the group as a whole. The sales charge is based on the combined dollar value of the group members’ existing investments, plus the amount of the current purchase.
A qualified group is one that:
| • | was formed at least six months ago | |
| • | has a purpose other than buying fund shares at a discount | |
| • | has more than five members | |
| • | can arrange for meetings between the Distributor’s representatives and group members | |
| • | agrees to include the Fund’s sales and other materials in publications and mailings to its members at reduced or no cost to the Distributor |
Please see Appendix A - Intermediary-Specific Sales Charge Waivers and Discounts in the prospectus for a description of variations in sales charges and waivers for Fund shares purchased through Edward Jones, Raymond James, Oppenheimer & Co. Inc., Robert W. Baird & Co., and Morgan Stanley Wealth Management.
Sales Charge Waivers for Certain Investors—Class A Shares
Class A shares may be purchased without an initial sales charge by various individuals and institutions, including:
| • | current and former registered representatives and employees, including their immediate families, of broker-dealers having selling group agreements with Integrity Funds Distributor or any trust, pension, profit-sharing, or other benefit plan for such persons (immediate family is defined to include the individual, his/her spouse, and their children, their parents, and their siblings); |
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-31 |
| • | current and former employees (including their spouses and dependent children) of banks and other financial services firms that provide advisory, custody, or administrative services related to the Fund pursuant to an agreement with the Fund, Corridor or one of its affiliates, or any trust, pension, profit-sharing, or other benefit plan for such persons; | |
| • | individuals and institutions purchasing shares in connection with the acquisition of the assets of or merger or consolidation with another investment company; | |
| • | investors purchasing through certain asset- or transaction-fee based investment advisers, broker-dealers, bank trust departments, and other financial services firms; | |
| • | 401(k), 403(b), 457, profit-sharing, and defined benefit plans; excluded from this waiver are SEPs, SARSEPs, and SIMPLE IRAs; and | |
| • | foundations and endowments, provided the foundation or endowment has assets of $200,000 or more. |
The elimination of the up-front sales charge for certain individuals and institutions is provided because of anticipated economies of scale and reduced sales-related efforts. A Fund must be notified in advance that you believe your investment qualifies for a sales charge reduction or waiver. The Funds make available, free of charge, more information about sales charge reductions and waivers through the Fund’s website at www.integrityvikingfunds.com, from the Prospectus, or from your financial adviser.
Please see Appendix A - Intermediary-Specific Sales Charge Waivers and Discounts in the prospectus for a description of variations in sales charges and waivers for Fund shares purchased through Edward Jones, Raymond James, Oppenheimer & Co. Inc., Robert W. Baird & Co., and Morgan Stanley Wealth Management.
CDSC Waivers
For each Fund, a CDSC may not be assessed on redemptions of such Fund:
| • | following the death of the last surviving shareholder on the account or the post-purchase disability of all registered shareholders, as defined in Section 729(m)(7) of the Internal Revenue Code of 1986 (the beneficiary on an account with a Transfer on Death registration is deemed the last surviving shareholder on the account); | |
| • | due to the termination of a trust following the death of the trustor/grantor or beneficiary, provided that the trust document specifically states that the trust is terminated upon death; | |
| • | representing minimum required distributions from an IRA or other retirement plan as required under the Internal Revenue Code. |
Dealer Compensation
The Distributor or one or more of its affiliates, at their own expense, currently provide additional compensation to certain investment dealers that sell shares of the Integrity/Viking Funds. The level of payments made to a particular dealer in any given year will vary. A number of factors, as enumerated in the Prospectus, will be considered in determining the level of payments. The Distributor makes these payments to help defray marketing and distribution costs incurred by particular dealers in connection with the sale of Integrity/Viking Funds, including costs associated with educating a firm’s financial advisors about the features and benefits of the Integrity/Viking Funds. The Distributor will, on a regular basis, determine the advisability of continuing these payments. Additionally, the Distributor or one or more of its affiliates may also directly sponsor various meetings that facilitate educating financial advisors and shareholders about the Integrity/Viking Funds.
As of the date of this SAI, the Distributor expects that it will pay additional compensation to the following dealers:
J.P. Morgan Clearing Corp.
Morgan Stanley Smith Barney LLC
UBS Financial Services, Inc.
Investors may wish to take intermediary payment arrangements into account when considering and evaluating any recommendations relating to Fund shares.
Monthomatic Investment Plan
A shareholder may purchase additional Fund shares through a monthomatic investment plan (minimum initial investment is $50). With the monthomatic investment plan, monthly investments (minimum $50) are made automatically from the shareholder’s account, at a bank, savings and loan association, or credit union into the shareholder’s Fund account. By enrolling in the monthomatic investment plan, the shareholder authorizes the Fund and its agents to either draw checks or initiate Automated Clearing House debits against the designated account at a bank or other financial institution. Such account must have check or draft writing privileges. A shareholder may terminate the monthomatic investment plan by sending written notice to the Transfer Agent. See “Automatic Investment Plan-the Monthomatic Investment Plan” in the Prospectus for additional information.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-32 |
Exchange Privilege and Share Class Conversions
As described in the Prospectus under “Investor Services-Exchanging Shares,” each Fund offers an exchange privilege. The exchange privilege permits a Class A shareholder in a Fund to exchange Class A shares between any Integrity/Viking Fund with an up front sales charge structure without paying any additional sales charges. Class I shareholders in a Fund may exchange Class I shares for Class I shares of another Integrity/Viking Fund that offers Class I shares. Exchange purchases are subject to eligibility requirements as well as the minimum investment requirements of the fund purchased. Exchange redemptions and purchases are processed simultaneously at the share prices next determined after the exchange order is received.
As described in the Prospectus under “Investor Services-Share Class Conversions,” shares of certain classes of a Fund may be converted into shares of certain other classes of the same Fund, provided that you are eligible to buy the new share class. Investors who hold Fund shares through a financial intermediary that does not have an agreement to make certain share classes of the Funds available or that cannot systematically support the conversion may not be eligible to convert their shares. Furthermore, your financial intermediary may have discretion to effect a conversion on your behalf. Consult with your financial intermediary for details.
In general, the conversion of shares of one class of a Fund for shares of another class of the same Fund is not considered a taxable event for federal income tax purposes. Any CDSC associated with the shares being converted will be assessed immediately prior to the conversion into shares of the new share class. Shares redeemed to pay the CDSC would be considered a taxable redemption. Please consult your own tax advisor for further information.
The exchange privilege and conversion right may be changed or discontinued upon sixty days’ written notice to shareholders and are available only to shareholders where such exchanges or conversions may be legally made. A shareholder considering an exchange or conversion should obtain and read the prospectus of the applicable Integrity/Viking Fund and consider the differences between it and the fund whose shares he owns or class of shares he owns, as applicable, before making an exchange or conversion. For further information on how to exercise the exchange privilege or to effect conversions, contact the Transfer Agent.
Please see Appendix A - Intermediary-Specific Sales Charge Waivers and Discounts in the prospectus for a description of variations in sales charges and waivers for Fund shares purchased through Edward Jones, Raymond James, Oppenheimer & Co. Inc., Robert W. Baird & Co., and Morgan Stanley Wealth Management.
Systematic Withdrawal Plan
The systematic withdrawal plan allows you to sell your shares and receive regular payments from your account on a monthly, quarterly, semiannual, or annual basis. The value of your account must be at least $5,000. There are no service charges for establishing or maintaining a systematic withdrawal plan.
Payments under the plan will be made from the redemption of an equivalent amount of shares in your account, on the 5th or 20th day of the month in which a payment is scheduled. If the 5th or 20th falls on a weekend or holiday, the redemption will be processed on the next business day. When you sell your shares under a systematic withdrawal plan, it is a taxable transaction.
To avoid paying sales charges on money you plan to withdraw within a short period of time, you may not want to set up a systematic withdrawal plan if you plan to buy shares on a regular basis.
Redeeming shares through a systematic withdrawal plan may reduce or exhaust the shares in your account. This is especially likely to occur if there is a market decline. If a withdrawal amount exceeds the value of your account, your account will be closed and the remaining balance in your account will be sent to you.
You may discontinue a systematic withdrawal plan or change the amount and schedule of withdrawal payments by notifying the Funds by mail or by phone at least seven business days before the end of the month preceding a scheduled payment. The Funds may discontinue a systematic withdrawal plan by notifying you in writing and will automatically discontinue a systematic withdrawal plan if all shares in your account are withdrawn or if the Fund receives notification of the shareholder’s death or incapacity.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-33 |
Share Certificates
Shares will be credited to your Fund account. Share certificates will no longer be issued. This eliminates the costly problem of replacing lost, stolen, or destroyed certificates. If a certificate is lost, stolen or destroyed, the holder may have to pay an insurance premium to replace it.
Any outstanding share certificates must be returned to the Fund if you want to sell or exchange those shares or if you would like to start a systematic withdrawal plan. The certificates should be properly endorsed. You can do this either by signing the back of the certificate or by completing a share assignment form. For your protection, you may prefer to complete a share assignment form and to send the certificate and assignment form in separate envelopes.
General Information
Distribution or redemption checks sent to you do not earn interest or any other income during the time the checks remain uncashed. Neither the Funds nor their affiliates will be liable for any loss caused by your failure to cash such checks. The Funds are not responsible for tracking down uncashed checks, unless a check is returned as undeliverable.
In most cases, if mail is returned as undeliverable, the Funds are required to take certain steps to try to find you free of charge. If these attempts are unsuccessful, however, the costs of any additional efforts to find you may be deducted from your account. These costs may include a percentage of the account when a search company charges a percentage fee in exchange for its location services.
The wiring of redemption proceeds is a special service that is made available whenever possible. By offering this service to you, the Funds are not bound to meet any redemption request in less than the seven day period prescribed by law. Neither the Funds nor their agents shall be liable to you or any other person if, for any reason, a redemption request by wire is not processed as described in the Prospectus.
Integrity Fund Services may pay certain financial institutions that maintain omnibus accounts with the Funds on behalf of numerous beneficial owners for recordkeeping operations performed with respect to such owners. For each beneficial owner in the omnibus account, a Fund may reimburse Integrity Fund Services an amount not to exceed the per account fee that the Fund normally pays Integrity Fund Services for shareholder services. These financial institutions may also charge a fee for their services directly to their clients.
If you buy or sell shares through your securities dealer, your order will be processed based on the net asset value next calculated after we receive your request. Your securities dealer is responsible for promptly transmitting your order to the Fund. Any loss to you resulting from your dealer’s failure to transmit your order to the Fund in a timely fashion must be settled between you and your securities dealer.
In the event of disputes involving multiple claims of ownership or authority to control your account, each Fund has the right (but has no obligation) to: (a) freeze the account and require the written agreement of all persons deemed by the Fund to have a potential property interest in the account, before executing instructions regarding the account; (b) interplead disputed funds or accounts with a court of competent jurisdiction; or (c) surrender ownership of all or a portion of the account to the IRS in response to a notice of levy.
PRICING SHARES
When you buy shares, you pay the offering price. The offering price for Class A shares is the NAV per share plus any applicable sales charge. The offering price for Class I shares is the NAV per share. NAV per share is calculated to two decimal places using standard rounding criteria. When you sell shares, you receive the NAV of the shares redeemed.
The value of a mutual fund is determined by deducting the fund’s liabilities from the total assets of the portfolio. The NAV per share is determined by dividing the NAV of the fund by the number of shares outstanding.
Set forth below is an example of the method of computing the offering price of Class A shares of each of the Funds, including applicable sales charges. The example assumes a purchase of shares from a Fund aggregating less than $100,000 for each Fund, subject to the schedule of Class A sales charges set forth in the Prospectus at a price based upon the net asset value of the shares on July 31, 2024.
| Net Asset Value per Share |
Per Share Sales Charge |
Per Share Offering Price to the Public |
Shares Outstanding | |
| Kansas Fund | $ 9.70 | $0.25 | $ 9.95 | 5,381,029 |
| Maine Fund | $ 9.52 | $0.24 | $ 9.76 | 884,879 |
| Nebraska Fund | $ 9.38 | $0.24 | $ 9.62 | 3,172,251 |
| Oklahoma Fund | $10.59 | $0.27 | $10.86 | 4,031,026 |
| Montana Fund | $ 9.15 | $0.23 | $ 9.38 | 5,516,751 |
| North Dakota Fund | $ 8.99 | $0.23 | $ 9.22 | 2,143,691 |
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-34 |
The Funds calculate the NAV per share each business day at the close of regular trading on the New York Stock Exchange (“NYSE”) (normally 3:00 p.m. Central Time). The Funds do not calculate the NAV on days the NYSE is closed for trading.
The Underwriter
Prior to August 1, 2009, Viking Fund Distributors, LLC (“Viking Distributors”) acted as the principal underwriter in the continuous public offering of the Funds’ shares. Currently, shares of each Fund are offered on a continuous basis through Integrity Funds Distributor, located at 1 Main Street North, Minot, North Dakota 58703, which has acted as the Funds’ distributor since August 2009.
Since July 31, 2009, Integrity Funds Distributor has been a wholly-owned subsidiary of Corridor. Prior to July 31, 2009, Integrity Funds Distributor was a wholly-owned subsidiary of Integrity Mutual Funds, Inc. Shannon D. Radke is an officer and governor of Corridor, an officer of the Funds, and an officer and governor of Integrity Funds Distributor. Peter A. Quist is a governor of Corridor and an officer of the Funds. Robert E. Walstad is a governor of Corridor and a Trustee and Chairman of the Board. Brent M. Wheeler, an officer of the Trust, is also a member of Corridor. See “Trustees and Officers” above. Mr. Radke, Mr. Walstad, Mr. Quist, and Mr. Wheeler are each members of Corridor and, accordingly, may indirectly benefit from the payment of 12b-1 fees described below under “Distribution and service (12b-1 fees)” (with respect to Class A shares) or brokerage commissions by the Funds to the Distributor.
Pursuant to a Distribution Agreement with each Fund, Integrity Funds Distributor serves as principal underwriter and distributor of the Funds. Pursuant to this agreement, Integrity Funds Distributor purchases shares of the Funds for resale to the public, either directly or through securities brokers, dealers, banks, or other agents, and is obligated to purchase only those shares for which it has received purchase orders. Integrity Funds Distributor has agreed to use its best efforts to solicit orders for the sale of the Funds’ shares. Integrity Funds Distributor receives for its services the applicable sales charge of a Fund’s Class A shares, and reallows a majority or all of such amount to the dealers who sold the shares; Integrity Funds Distributor may act as such a dealer. Integrity Funds Distributor does not receive any sales charge with respect to the Class I shares of a Fund.
The table below shows the aggregate dollar amount of underwriting commissions Integrity Funds Distributor received in connection with the offering of the Funds’ Class A shares and the net underwriting discounts and commissions Integrity Funds Distributor retained after allowances to dealers for the three most recent fiscal years.
| Fiscal Year Ended: | Aggregate Underwriting Commissions ($) |
Amount Retained by Integrity Funds Distributor ($) | |
| Kansas Fund | |||
| 7/31/2022 | 36,354 | 9,043 | |
| 7/31/2023 | 21,659 | 3,663 | |
| 7/31/2024 | 26,008 | 4,563 | |
| Maine Fund | |||
| 7/31/2022 | 3,940 | 724 | |
| 7/31/2023 | 507 | 70 | |
| 7/31/2024 | 2,001 | 426 | |
| Nebraska Fund | |||
| 7/31/2022 | 18,996 | 3,234 | |
| 7/31/2023 | 13,409 | 1,914 | |
| 7/31/2024 | 6,578 | 1,047 | |
| Oklahoma Fund | |||
| 7/31/2022 | 23,434 | 3,596 | |
| 7/31/2023 | 7,009 | 1,329 | |
| 7/31/2024 | 6,168 | 991 | |
| Montana Fund | |||
| 7/31/2022 | 24,609 | 4,188 | |
| 7/31/2023 | 11,118 | 2,683 | |
| 7/31/2024 | 12,189 | 1,955 | |
| North Dakota Fund | |||
| 7/31/2022 | 3,315 | 797 | |
| 7/31/2023 | 895 | 485 | |
| 7/31/2024 | 192 | 36 | |
Integrity Funds Distributor may be entitled to compensation under the Rule 12b-1 plan, as discussed below. Except as noted, Integrity Funds Distributor receives no other compensation from the Funds for acting as underwriter.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-35 |
Compensation
The following table sets forth the amount of underwriting commissions, brokerage commissions, compensation on redemptions, and any other compensation received by Integrity Funds Distributor from the respective Fund indicated below (with respect to Class A shares) during the most recent fiscal year.
| Net Underwriting Discounts and Commissions |
Compensation on Redemptions and Repurchases |
Brokerage Commissions |
Other Compensation(1) | |
| Kansas Fund | $4,563 | $ 2,000 | $0 | $134,472 |
| Maine Fund | $ 386 | $23,561 | $0 | $ 25,364 |
| Nebraska Fund | $1,043 | $ 0 | $0 | $ 77,725 |
| Oklahoma Fund | $ 991 | $ 0 | $0 | $114,691 |
| Montana Fund | $1,953 | $ 0 | $0 | $133,764 |
| North Dakota Fund | $ 36 | $ 1,873 | $0 | $ 51,260 |
| (1) | Integrity Funds Distributor received this amount under the Rule 12b-1 plan of the respective Fund, net of waivers. |
Distribution and Service (12b-1) Fees
The Funds have adopted a distribution and service plan dated July 31, 2009 with respect to each Fund’s Class A shares (the “Plan”), in accordance with the requirements of Rule 12b-1 under the 1940 Act and the requirements of the applicable rules of the Financial Industry Regulatory Authority (FINRA) regarding asset-based sales charges.
Pursuant to the Plan, each Fund may compensate Integrity Funds Distributor for its expenditures in financing any activity primarily intended to result in the sale of Fund shares and for maintenance and personal service provided to existing shareholders. The Plan authorizes payments to Integrity Funds Distributor of up to 0.25% annually of the average daily net assets of Class A shares of the Funds. All distribution expenses over this amount will be borne by those who have incurred them.
The Plan
The Plan provides for periodic payments by Integrity Funds Distributor to brokers, dealers and other financial intermediaries for providing shareholder services and for promotional and other sales related costs. Expenditures under the Plan may also include, among others, a prorated portion of Integrity Funds Distributor’s overhead expenses; the expenses of printing prospectuses and reports used for sales purposes; and preparing and distributing sales literature and advertisements. The portion of payments by a Fund’ for shareholder servicing may not exceed an annual rate of 0.25% of the average daily net asset value of the Fund’s Class A shares owned by clients of such broker, dealer or financial intermediary.
The fee is an expense. This means that all Class A shareholders, regardless of when they purchased their shares, will bear Rule 12b-1 expenses at the same rate. The fees shall be payable regardless of whether those fees exceed or are less than the actual expenses incurred by Integrity Funds Distributor with respect to each Fund in a particular year.
The Plan has been approved in accordance with the provisions of Rule 12b-1. The Plan is renewable annually by a vote of the Board, including a majority vote of the Board members who are not interested persons of the Fund and who have no direct or indirect financial interest in the operation of the Plan, cast in person at a meeting called for that purpose. The Plan may be terminated at any time by vote of a majority of the non-interested Board members or by vote of a majority of the outstanding shares of the Fund.
The Plan may not be amended to increase materially the amount to be spent for distribution expenses without approval by a majority of the outstanding shares of the Fund, and all material amendments to the Plan shall be approved by a vote of the non-interested Board members, cast in person at a meeting called for the purpose of voting on any such amendment.
Integrity Funds Distributor is required to report in writing to the Board at least quarterly on the amounts and purpose of any payment made under the Plan.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-36 |
The table below provides, for each Fund’s most recent fiscal year, the fees payable by the Funds’ Class A shares under the Plans, the fees paid by the Funds’ Class A shares under the Plans net of waivers, and the amount of fees waived by the Distributor.
| 12b-1 Fees Payable for the Fiscal Year Ended July 31, 2024 |
12b-1 Fees After Waivers |
Fees Waived by Distributor | |
| Kansas Fund | $134,472 | $134,472 | $0 |
| Maine Fund | $ 25,364 | $ 25,364 | $0 |
| Nebraska Fund | $ 77,725 | $ 77,725 | $0 |
| Oklahoma Fund | $114,691 | $114,691 | $0 |
| Montana Fund | $133,764 | $133,764 | $0 |
| North Dakota Fund | $ 51,260 | $ 51,260 | $0 |
Expenditures
The 12b-1 fees paid by the Funds’ Class A shares during their most recent fiscal year were spent toward the following distribution-related expenses:
| Advertising & Promotion |
Compensation to Dealers (including commission and service fees) |
Compensation to Sales Personnel and Payroll Taxes |
Distribution Related Overhead |
Absorbed by the Distributor(1) | |
| Kansas Fund | $650 | $119,776 | $72,822 | $8,066 | $(66,842) |
| Maine Fund | $107 | $ 30,451 | $13,072 | $1,431 | $(19,697) |
| Nebraska Fund | $367 | $ 61,664 | $41,757 | $4,631 | $(30,694) |
| Oklahoma Fund | $535 | $100,316 | $61,106 | $6,770 | $(54,036) |
| Montana Fund | $638 | $140,241 | $71,983 | $8,004 | $(87,102) |
| North Dakota Fund | $242 | $ 36,175 | $27,495 | $3,048 | $(15,700) |
| (1) | The difference between 12b-1 Fees paid by the Funds and Plan expenses incurred by the Distributor. Negative amounts represent unreimbursed expenses, that is, expenses that qualified for the Plan but that were paid by the Distributor. |
As of July 31, 2024 the following unreimbursed Plan expenses had been incurred by the Distributor with respect to the Funds’ Class A shares in a previous year and carried over to future years:
| Dollar Amount | Percentage of Fund Net Assets | ||
| Kansas Fund | $ | (1,138,632) | 2.18% |
| Maine Fund | $ | (128,273) | 1.52% |
| Nebraska Fund | $ | (1,492,944) | 5.02% |
| Oklahoma Fund | $ | (1,981,436) | 4.64% |
| Montana Fund | $ | (981,508) | 1.94% |
| North Dakota Fund | $ | (345,551) | 1.79% |
You can ask your dealer for information about any payments it receives from the Distributor and any services provided.
FINANCIAL STATEMENTS
The audited financial statements of the Funds for their most recent fiscal period ended July 31, 2024 appear in the Funds’ annual Form N-CSR, and are incorporated herein by reference. The Funds’ annual Form N-CSR is available without charge by calling 800-276-1262.
DESCRIPTION OF BOND RATINGS
The following descriptions of ratings are based on information publicly available from Moody’s, S&P, and Fitch.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-37 |
Moody’s Long-Term Obligation Ratings
Ratings assigned on Moody’s global long-term rating scale are forward-looking opinions of the relative credit risks of financial obligations issued by non-financial corporates, financial institutions, structured finance vehicles, project finance vehicles, and public sector entities. Long-term ratings are assigned to issuers or obligations with an original maturity of one year or more and reflect both on the likelihood of a default or impairment on contractual financial obligations and the expected financial loss suffered in the event of default or impairment. For certain structured finance, preferred stock and hybrid securities in which payment default events are either not defined or do not match investors’ expectations for timely payment, the ratings reflect the likelihood of impairment (as defined by Moody’s) and financial loss in the event of impairment.
| Investment Grade | ||
| Aaa | Obligations rated “Aaa” are judged to be of the highest quality, subject to the lowest level of credit risk. | |
| Aa | Obligations rated “Aa” are judged to be of high quality and are subject to very low credit risk. | |
| A | Obligations rated “A” are judged to be upper-medium grade and are subject to low credit risk. | |
| Baa | Obligations rated “Baa” are judged to be medium-grade and subject to moderate credit risk and as such may possess certain speculative characteristics. | |
| Below Investment Grade | ||
| Ba | Obligations rated “Ba” are judged to be speculative and are subject to substantial credit risk. | |
| B | Obligations rated “B” are considered speculative and are subject to high credit risk. | |
| Caa | Obligations rated “Caa” are judged to be speculative of poor standing and are subject to very high credit risk. | |
| Ca | Obligations rated “Ca” are highly speculative and are likely in, or very near, default, with some prospect of recovery of principal and interest. | |
| C | Obligations rated “C” are the lowest rated and are typically in default, with little prospect for recovery of principal or interest. | |
| Note: | Moody’s appends numerical modifiers 1, 2, and 3 to each generic rating category from “Aa” through “Caa”. The modifier 1 indicates that the obligation ranks in the higher end of its generic rating category; the modifier 2 indicates a mid-range ranking; and the modifier 3 indicates a ranking in the lower end of that generic rating category. Additionally, a “(hyb)” indicator is appended to all ratings of hybrid securities issued by banks, insurers, finance companies, and securities firms.* | |
| * | By their terms, hybrid securities allow for the omission of scheduled dividends, interest, or principal payments, which can potentially result in impairment if such a omission occurs. Hybrid securities may also be subject to contractually allowable write-downs of principal that could result in impairment. Together with the hybrid indicator, the long-term obligation rating assigned to a hybrid security is an expression of the relative credit risk associated with that security. | |
S&P Long-Term Issue Ratings
An S&P Global Ratings issue credit rating is a forward-looking opinion about the creditworthiness of an obligor with respect to a specific financial obligation, a specific class of financial obligations, or a specific financial program (including ratings on medium-term note programs and commercial paper programs). Medium-term notes are assigned long-term ratings.
Issue credit ratings are based, in varying degrees, on S&P Global Ratings’ analysis of the following considerations:
| ● | The likelihood of payment—the capacity and willingness of the obligor to meet its financial commitments on an obligation in accordance with the terms of the obligation; | |
| ● | The nature and provisions of the financial obligation, and the promise we impute; and | |
| ● | The protection afforded by, and relative position of, the financial obligation in the event of a bankruptcy, reorganization, or other arrangement under the laws of bankruptcy and other laws affecting creditors’ rights. |
An issue rating is an assessment of default risk but may incorporate an assessment of relative seniority or ultimate recovery in the event of default. Junior obligations are typically rated lower than senior obligations, to reflect the lower priority in bankruptcy, as noted above. (Such differentiation may apply when an entity has both senior and subordinated obligations, secured and unsecured obligations, or operating company and holding company obligations.)
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-38 |
| Investment Grade | |
| AAA | An obligation rated “AAA” has the highest rating assigned by S&P. The obligor’s capacity to meet its financial commitments on the obligation is extremely strong. |
| AA | An obligation rated “AA” differs from the highest-rated obligations only to a small degree. The obligor’s capacity to meet its financial commitment on the obligation is very strong. |
| A | An obligation rated “A” is somewhat more susceptible to the adverse effects of changes in circumstances and economic conditions than obligations in higher-rated categories. However, the obligor’s capacity to meet its financial commitment on the obligation is still strong. |
| BBB | An obligation rated “BBB” exhibits adequate protection parameters. However, adverse economic conditions or changing circumstances are more likely to lead to a weakened capacity of the obligor to meet its financial commitment on the obligation. |
| Below Investment Grade | |
| BB, B, CCC, CC, and C | Obligations rated “BB”, “B”, “CCC”, “CC”, and “C” are regarded as having significant speculative characteristics. BB indicates the least degree of speculation and C the highest. While such obligations will likely have some quality and protective characteristics, these may be outweighed by large uncertainties or major exposures to adverse conditions. |
| BB | An obligation rated “BB” is less vulnerable to nonpayment than other speculative issues. However, it faces major ongoing uncertainties or exposure to adverse business, financial, or economic conditions that could lead to the obligor’s inadequate capacity to meet its financial commitments on the obligation. |
| B | An obligation rated “B” is more vulnerable to nonpayment than obligations rated BB”, but the obligor currently has the capacity to meet its financial commitments on the obligation. Adverse business, financial, or economic conditions will likely impair the obligor’s capacity or willingness to meet its financial commitments on the obligation. |
| CCC | An obligation rated “CCC” is currently vulnerable to nonpayment, and is dependent upon favorable business, financial, and economic conditions for the obligor to meet its financial commitments on the obligation. In the event of adverse business, financial, or economic conditions, the obligor is not likely to have the capacity to meet its financial commitments on the obligation. |
| CC | An obligation rated “CC” is currently highly vulnerable to nonpayment. The “CC” rating is used when a default has not yet occurred, but S&P expects default to be a virtual certainty, regardless of the anticipated time to default. |
| C | An obligation rated “C” is currently highly vulnerable to nonpayment, and the obligation is expected to have lower relative seniority or lower ultimate recovery compared with obligations that are rated higher. |
| D | An obligation rated “D” is in default or breach of an imputed promise. For non-hybrid capital instruments, the “D” rating category is used when payments on an obligation are not made on the date due, unless S&P believes that such payments will be made within five business days in the absence of a stated grace period or within the earlier of the stated grace period or 30 calendar days. The “D” rating also will be used upon the filing of a bankruptcy petition or the taking of similar action and where default on an obligation is a virtual certainty, for example due to automatic stay provisions. An obligation’s rating is lowered to “D” if it is subject to a distressed debt restructuring. |
| NR | This indicates that no rating has been requested, or that there is insufficient information on which to base a rating, or that S&P does not rate a particular obligation as a matter of policy. |
| Plus (+) or Minus (-) |
The ratings from “AA” to “CCC” may be modified by the addition of a plus (+) or minus (-) sign to show relative standing within the major rating categories. |
Fitch’s Long-Term Ratings for Structured, Project and Public Finance Obligations
| AAA: Highest credit quality |
‘AAA’ ratings denote the lowest expectation of default risk. They are assigned only in cases of exceptionally strong capacity for payment of financial commitments. This capacity is highly unlikely to be adversely affected by foreseeable events. |
| AA: Very high credit quality |
‘AA’ ratings denote expectations of very low default risk. They indicate very strong capacity for payment of financial commitments. This capacity is not significantly vulnerable to foreseeable events. |
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-39 |
| A: High credit quality |
‘A’ ratings denote expectations of low default risk. The capacity for payment of financial commitments is considered strong. This capacity may, nevertheless, be more vulnerable to adverse business or economic conditions than is the case for higher ratings. |
| BBB: Good credit quality |
‘BBB’ ratings indicate that expectations of default risk are currently low. The capacity for payment of financial commitments is considered adequate but adverse business or economic conditions are more likely to impair this capacity. |
| BB: Speculative |
‘BB’ ratings indicate an elevated vulnerability to default risk, particularly in the event of adverse changes in business or economic conditions over time. |
| B: Highly speculative |
‘B’ ratings indicate that material default risk is present, but a limited margin of safety remains. Financial commitments are currently being met; however, capacity for continued payment is vulnerable to deterioration in the business and economic environment. |
| CCC: Substantial credit risk |
Default is a real possibility. |
| CC: Very high levels of credit risk |
Default of some kind appears probable. |
| C: Exceptionally high levels of credit risk |
Default appears imminent or inevitable. |
| D: Default: |
Indicates a default. Default generally is defined as one of the following: |
| ● | failure to make payment of principal and/or interest under the contractual terms of the rated obligation; | |
| ● | bankruptcy filings, administration, receivership, liquidation or other winding-up or cessation of the business of an issuer/obligor; or | |
| ● | distressed exchange of an obligation, where creditors were offered securities with diminished structural or economic terms compared with the existing obligation to avoid a probable payment default. |
Description of Municipal Short-Term Ratings
Moody’s Municipal Short-Term Obligation Ratings
| MIG 1 | This designation denotes superior credit quality. Excellent protection is afforded by established cash flows, highly reliable liquidity support, or demonstrated broad-based access to the market for refinancing. |
| MIG 2 | This designation denotes strong credit quality. Margins of protection are ample, although not as large as in the preceding group. |
| MIG 3 | This designation denotes acceptable credit quality. Liquidity and cash flow protection may be narrow, and market access for refinancing is likely to be less well-established. |
| SG | This designation denotes speculative-grade credit quality. Debt instruments in this category may lack sufficient margins of protection. |
S&P’s Municipal Note Ratings
| SP-1 | Strong capacity to pay principal and interest. An issue determined to possess a very strong capacity to pay debt service is given a plus (+) designation. |
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-40 |
| SP-2 | Satisfactory capacity to pay principal and interest, with some vulnerability to adverse financial and economic changes over the term of the notes. |
| SP-3 | Speculative capacity to pay principal and interest. |
| D | “D” is assigned upon failure to pay the note when due, completion of a distressed exchange offer, or the filing of a bankruptcy petition or the taking of similar action and where default on an obligation is a virtual certainty, for example due to automatic stay provisions. |
Fitch’s Short-Term Ratings Assigned to Issuers or Obligations in Corporate, Public and Structured Finance
| F1: Highest short-term credit quality |
Indicates the strongest intrinsic capacity for timely payment of financial commitments; may have an added “+” to denote any exceptionally strong credit feature. |
| F2: Good short-term credit quality |
Good intrinsic capacity for timely payment of financial commitments. |
| F3: Fair short-term credit quality |
The intrinsic capacity for timely payment of financial commitments is adequate. |
| B: Speculative short-term credit quality |
Minimal capacity for timely payment of financial commitments, plus heightened vulnerability to near-term adverse changes in financial and economic conditions. |
| C: High short-term default risk |
Default is a real possibility. |
| RD: Restricted default |
Indicates an entity that has defaulted on one or more of its financial commitments, although it continues to meet other financial obligations. Typically applicable to entity ratings only. |
| D: Default |
Indicates a broad-based default event for an entity, or the default of a short-term obligation. |
PROXY VOTING
Information on how the Funds voted proxies relating to portfolio securities during the most recent 12-month period ended June 30 is available by the following August 31 without charge, upon request, by calling 800-276-1262, on the Trust’s Internet site at www.integrityvikingfunds.com, and on the SEC’s Internet site at www.sec.gov.
To the extent a Fund invests in any voting securities, the Board of Trustees has delegated to the Investment Adviser the final authority and responsibility for voting proxies with respect to each Fund’s underlying securities holdings. In the event a Fund were to receive a proxy, the Investment Adviser may follow proxy voting guidelines developed by an independent third party such as Glass, Lewis & Co. The Trustees will review each Fund’s proxy voting records from time to time and will annually consider revising its proxy voting policy.
The Investment Adviser may abstain from voting from time to time where it determines that the costs associated with voting a proxy outweigh the benefits derived from exercising the right to vote. The Investment Adviser will monitor situations that may result in a potential conflict of interest, in particular between a Fund’s shareholders and Investment Adviser or any of its affiliates or an affiliate of the Funds. If any such conflict is discovered, the issue will be examined in detail by the Investment Adviser and in such circumstances, the Investment Adviser generally will refrain from voting the proxies giving rise to conflict, until the Trustees, after consultation, instruct on an appropriate course of action to vote the proxies in the best interest of the relevant Fund.
| Viking Mutual Funds | Statement of Additional Information | November 30, 2024 Page B-41 |
APPENDIX A—FACTORS PERTAINING TO STATES AND U.S. TERRITORIES
The information regarding states and U.S. territories was obtained from official statements of issuers located in the respective states and U.S. territories as well as from other publicly available official documents and statements. The Funds have not independently verified any of the information contained in such statements and documents. The information below is intended only as a general summary and is not intended as a discussion of any specific factor that may affect any particular obligation or issuer. While the following summarizes certain information currently available from the above sources, it does not reflect economic conditions or developments that may have occurred or trends that may have materialized since the dates indicated. Additionally, many factors including national economic, social and environmental policies and conditions, which are not within the control of issuers of municipal securities, could affect or could have an adverse impact on the financial condition of a state and its various agencies and political subdivisions or U.S. territories and possessions. Viking Management is unable to predict whether or to what extent such factors or other factors may affect issuers of municipal securities in which a Fund invests, the market value or marketability of these municipal securities or the ability of the respective issuers of the municipal securities acquired by a Fund to pay interest on or principal of the municipal securities.
Factors pertaining to Kansas
Since the Kansas Fund invests a significant portion of its assets in Kansas municipal securities, the Kansas Fund is susceptible to political, economic or regulatory factors affecting issuers of Kansas municipal obligations.
The Kansas economy is expected to experience modest real growth throughout the forecast period. Persistent elevated levels of inflation are forecast to largely offset the relatively strong nominal growth of the Kansas economy. Major economic variables have been adjusted since the Consensus Group last convened in April 2023, including Gross State Product (GSP) and Kansas Personal Income (KPI). The forecasted rates of nominal growth in the national and Kansas economies have been increased for calendar year (CY) 2023, CY 2024, and CY 2025. Nominal U.S. Gross Domestic Product (GDP) is now expected to increase by 6.3 percent in CY 2023, up from the previous forecast of 5.8 percent, and nominal U.S. GDP growth in CY 2024 and CY 2025 is now forecasted to be 4.7 percent and 4.6 percent, respectively, up from the previous estimates of 4.55 percent in each year. Nominal Kansas GSP is now expected to increase by 6.4 percent in CY 2023, up from a previous projected increase of 5.8 percent. Additionally, nominal Kansas GSP is expected to grow by 4.7 percent and 4.6 percent in CY 2024 and CY 2025, respectively, up from the previous estimates of 4.55 percent in each year.
The overall Kansas unemployment rate is expected to increase from 2.7 percent experienced in CY 2022 to 2.9 percent in CY 2023, which is down from 3.3 percent at the time of the previous estimate. Kansas unemployment rates are now forecasted to rise to 3.4 percent in CY 2024, which is down from a forecast of 3.8 percent at the time of the previous estimate and remain steady at 3.4 percent in CY 2025. The national unemployment rate is projected to remain above the Kansas rate, with the U.S. rate now expected to be 3.8 percent in CY 2023 and 4.1 percent in both CY 2024 and CY 2025. Previous expectations were for a 4.5 percent national unemployment rate in CY 2023 and 4.6 percent in both CY 2024 and CY 2025.
The number of unemployed Kansans and the number of unemployment insurance claims increased from September 2022 to September 2023. There were 4,402 individuals receiving unemployment insurance benefits in September 2022 and 6,105 individuals receiving unemployment insurance benefits in September 2023.
Between September 2022 and September 2023, Kansas seasonally adjusted total nonfarm jobs have increased by 22,200. This change is due to an increase of 16,000 private sector jobs and 6,200 government jobs. The labor force participation rate increased from 66.3% in September 2022 to 66.7% in September 2023.
The combined net position of the State (government and business-type activities) totaled $18.69 billion at the end of 2023, compared to $16.21 billion at the end of the previous year, an increase of 15.31 percent.
The largest portion of net position reflects investment in capital assets such as land, buildings, equipment, and infrastructure (roads, bridges, and other immovable assets), less any related debt used to acquire those assets that are still outstanding. The State uses these capital assets to provide services to citizens; consequently, these assets are not available for future spending. Although investment in its capital assets is reported net of related debt, it should be noted that the resources needed to repay this debt must be provided from other sources, since the capital assets themselves cannot be used to liquidate these liabilities.
For fiscal year 2023, the governmental funds reported a combined ending fund balance of $5.99 billion, an increase of $1.27 billion in comparison with the prior year. Of the total amount, $0.83 billion represents the fund balance of the Non-Major Governmental funds. The General Fund reported an unassigned fund balance for fiscal year 2023 of a positive $4.05 billion, as compared to the prior year unassigned balance of a positive $2.49 billion.
| Viking Mutual Funds | Appendix A –Factors Pertaining to States and U.S. Territories | November 30, 2024 Page B-B-1 |
Original estimates for expenditures for fiscal year 2023 were increased by $100.9 million in the final revised budget for the fiscal year. Fiscal year 2023 ended with expenditures $599.3 million below the final revised estimate.
The original budget estimate provided for revenues less than expenditures of $394.1 million. The final revised budget provided for $171.9 million of revenues less than expenditures. Subsequently, fiscal year 2023 was closed with revenues greater than expenditures of $1.04 billion.
The General Fund is the chief operating fund of the State. At the end of the current fiscal year, unassigned fund balance of the General Fund was a positive $4.051 billion, while the total fund balance was a positive $4.056 billion. During fiscal year 2023, the State experienced increased revenue in property tax, income and inheritance tax, sales and excise taxes, gross receipts tax, charges for services, investment earnings, capital grants, and other revenues. The cash and investment balance is approximately $0.86 billion higher in fiscal year 2023 than it was in fiscal year 2022.
The State does not have the statutory authority to issue general obligation bonds. The Legislature has authorized the issuance of specific purpose revenue bonds and other forms of long-term obligations.
The total long-term debt obligations decreased by $1.87 billion during the current fiscal year. This net decrease was primarily due to net decreases of $2.29 billion in bonds outstanding, offset by an increase of $389.6 million due to net pension liability.
The above information provided is only a brief summary of the complex factors affecting the financial situation in Kansas and is derived from sources that are generally available to investors and are believed to be accurate. No independent verification has been made of the accuracy or completeness of any of the preceding information. It is based in part on information obtained from various state and local agencies in Kansas or contained in Official Statements for various Kansas municipal obligations.
Factors pertaining to Maine
Since the Maine Fund invests a significant portion of its assets in Maine municipal securities, the Maine Fund is susceptible to political, economic or regulatory factors affecting issuers of Maine municipal obligations.
The net position of Governmental Activities increased by $601.0 million, while net position of Business-Type Activities increased by $73.2 million. The State’s assets and deferred outflows exceeded its liabilities and deferred inflows by $3.261 billion at the close of fiscal year 2023. Of this amount $1.603 billion was reported as negative “Unrestricted” net position. A negative balance means that it would be necessary to convert restricted assets (e.g., capital assets) to unrestricted assets if all ongoing obligations were immediately due and payable. Component units reported net position of $3.894 billion, an increase of $126.4 million (3.4 percent) from the previous year.
At the end of the fiscal year, the State’s governmental funds reported a combined ending fund balance of $3.023 billion, an increase of $314.0 million from the previous year. The General Fund’s total fund balance was $1.358 billion, an increase of $383.0 million from the previous year. The General Fund fund balance increase was primarily due to the decrease in transfers to other funds of $345.6 million, as compared to the prior year. The Other Special Revenue Fund total fund balance was $1.349 billion, a decrease of $154.8 million from the prior year.
The proprietary funds reported net position at year-end of $1.057 billion, a decrease of $97.8 million from the previous year. The decrease is the net result of an increase in two Enterprise Funds, the Employment Security Fund of $48.4 million and Ferry Service Fund of $16.7 million and a decrease of $159.2 million in the Retiree Health Insurance Fund, an Internal Service Fund.
The State’s liability for general obligation bonds increased by $55.8 million during the fiscal year, which represents the difference between new issuances and payments of outstanding debt. During the year, the State issued $167.1 in new general obligation bonds and made principal payments of $111.3 million.
The Maine Consensus Economic Forecasting Commission (CEFC) convened on October 23, 2023, to review and revise its forecast through 2027. This meeting builds on the Commission’s forecast update of April 1, 2023, incorporating the most recent data available for all relevant baseline data.
The CEFC noted ongoing heightened uncertainty in economic conditions in the near-term, especially regarding geo-political upheaval, but does not anticipate a recession in its forecast. The Commission expects that higher demand for labor will continue to draw enough workers into Maine in the coming years to offset retirements from the Baby Boom generation. However, the Commission recognizes that access to housing may hamper growth in the coming years. High inflation and interest rates have continued into 2023, and the CEFC noted that the Federal Reserve is expected to continue pursuing policies that will constrain inflation, but inflation risks are likely to take several years to fully ease. Inflation and interest rates, demographic changes, access to housing, and a tight labor market were among the key risks to continued economic growth that the CEFC considered as it revised its forecasts.
| Viking Mutual Funds | Appendix A –Factors Pertaining to States and U.S. Territories | November 30, 2024 Page B-B-2 |
The Commission left its nonfarm employment forecast unchanged for all years, with the expectation that higher demand for labor will continue to draw enough workers into Maine in the coming years to offset retirements from the Baby Boom generation.
Total personal income growth in 2022 was 3.9%, revised up from the BEA’s preliminary estimate of 2.6%. The Commission revised its forecast for total personal income growth in 2023 up from 5.2% to 5.9% but downward for calendar years 2024 through 2027. The Commission revised those years down to 4.5%, 4.3%, 4.4%, and 4.4% from 4.9%, 4.5%, 4.6%, and 4.7%, respectively.
Wage and salary income, the largest component of personal income, increased by 8.5% in 2022, just under the preliminary estimate of 8.6%. The Commission revised its forecast for 2023 up to 7.5% from 6.0% based on data from the Maine Department of Labor and Maine Revenue Services for the first half of 2023. The rest of the forecast remained unchanged.
The Commission revised its forecast for inflation using the Consumer Price Index (CPI) down in all years, going from 5.8% to 4.1% in 2023, 4.0% to 3.2% in 2024, 3.5% to 2.7% in 2025, 3.5 to 2.7% in 2026, and 2.7% from 3.0% in 2027. These revisions were made based on the year-to-date CPI data and to better align with the Moody’s Analytics and S&P forecasts for these years.
At June 30, 2023, the State of Maine reported an ending fund balance of $1.358 billion in the General Fund on a GAAP basis, an increase of more than $383.0 million since the end of fiscal year 2022. The General Fund “unassigned” fund balance on a GAAP basis at June 30, 2023 was $1.0 billion.
The above information provided is only a brief summary of the complex factors affecting the financial situation in Maine and is derived from sources that are generally available to investors and are believed to be accurate. No independent verification has been made of the accuracy or completeness of any of the preceding information. It is based in part on information obtained from various state and local agencies in Maine or contained in Official Statements for various Maine municipal obligations.
Factors pertaining to Nebraska
Since the Nebraska Fund invests a significant portion of its assets in Nebraska municipal securities, the Nebraska Fund is susceptible to political, economic or regulatory factors affecting issuers of Nebraska municipal obligations.
The General Fund operations of the State are almost entirely dependent upon the income and sales taxes the State receives each year. Such taxes represent 96 percent of all General Fund revenues. Net revenue from income taxes and sales taxes for the fiscal year ended June 30, 2023 decreased $15 million from the prior year.
The current forecast for fiscal year 2024 anticipates net receipts in the General Fund to increase about $77 million, a 1.2% increase over fiscal year 2023.
Significant changes in other governmental funds include an increase in federal revenue to support Coronavirus relief efforts. On March 11, 2021 the American Rescue Plan Act, P.L.117-2 (ARPA Act) was enacted. In that law, Nebraska was allocated $1.04 billion through the Coronavirus State Fiscal Recovery Fund, $129 million through the Coronavirus Capital Projects Fund, $50 million through the Homeowners Assistance Fund, and $48 million through the 2nd Emergency Rental Assistance Program. In fiscal year 2023, $231 million was recognized as revenue in the federal fund for these ARPA funds.
For the fiscal year ending June 30, 2023 the State’s General Fund ended the fiscal year with a cash and investments balance of $3,701 million. The balance had exceeded $1 billion dollars for the prior three years.
Long-term liabilities shown on the government-wide financial statements totaled $1,154 million at June 30, 2023, which is a $424 million increase from the prior year, primarily due to an increase in the State’s pension liability. The remaining liabilities consist of Medicaid liability, claims payable for workers’ compensation, medical excess liability, lease liability, certificates of participation, unemployment insurance and employee health insurance, in addition to the calculated amount for accrued vacation and vested sick leave due to employees when they retire. After a retired employee reaches the age of 65, the State has no further obligation for other post-employment benefits, except for a very small number of employees.
The focus of the State’s Governmental Funds is to provide information on near-term inflows and outflows and the availability of spendable resources. At June 30, 2023, the State’s Governmental Funds reported combined ending fund balances of $9,372 million. Of this amount, $713 million is non-spendable, either due to its form or legal constraints, and $4,632 million is restricted for specific programs by external constraints, constitutional provisions or contractual obligations. Revenue restricted by enabling legislation and public school land lease revenues are included in restricted fund balance. An additional $1,986 million of total fund balance has been committed to specific purposes. Committed amounts cannot be used for any other purpose unless approved by the Legislature. An additional $74 million of total fund balance has been assigned to specific purposes, as expressed by legislative intent. The remaining $1,967 million is unassigned and available for appropriations.
| Viking Mutual Funds | Appendix A –Factors Pertaining to States and U.S. Territories | November 30, 2024 Page B-B-3 |
The General Fund is the chief operating fund of the State. The major General Fund liability is the estimated tax refunds payable of $679 million. However, such refunds payable are $17 million more than the expected taxes owed the State. Other assets of the General Fund available to pay non tax-refund liabilities exceed such liabilities by $3,588 million.
On June 30, 2022, the General Fund had a positive fund balance of $3,297 million. For 2023, expenditures increased $556 million from 2022 and revenues increase by $159 million. The revenues were $632 million more than expenditures for 2023 while revenues were $1,029 million more than expenditures in 2022. The General Fund balance in 2023 increased by $208 million, after adjusting for transfers in and out of the General Fund, ending with a fund balance of $3,505 million on June 30, 2023.
Revenues increase during 2023 finishing $159 million up from 2022. This increase was primarily due to a decrease in income tax revenue of $208 million (a 5.34% decrease) from 2022, an increase in sales and use tax revenue of $142 million (a 6.63% increase) over 2022, a decrease in business and franchise taxes of $7 million (a 6.22% decrease) and an increase in investment income of $207 million (a 108% increase) from 2022. Expenditures increased during 2023 by $556 million over 2022 due to increases in General Government spending of $44 million, an increase for Education and Higher Education – Colleges and University of $55 and $22 million, respectively, an increase in Health and Social Services of $308 million, and an increase from 2022 for Public Safety of $87 million. Overall expenditures were less than budgeted due to continued efforts by agency heads to be conservative in spending.
To compensate for downturns in revenues, the State has maintained a budgetary basis Cash Reserve Fund. While this Cash Reserve Fund is commingled with General Fund cash in the General Fund financial statements, it is separate and distinct in that, by State Statute, it can only be used (1) when the cash balance of the General Fund is insufficient to meet General Fund current obligations and (2) for legislatively mandated transfers to other funds. Any money transferred in accordance with item one above must be repaid as soon as there is sufficient cash in the General Fund cash account to do so. No such need existed in 2023.
The Cash Reserve Fund balance was $467 million at the beginning of 2022. In 2022, there were net transfers in of $461 million leaving a Cash Reserve Fund balance at June 30, 2022 of $928 million. In 2023, there were statutory transfers to the Fund of $1,338 million and other statutory transfers out equaling $628 million leaving a Fund balance of $1,638 million at June 30, 2023. The Cash Reserve Fund is reflected as committed to economic stabilization on the governmental funds balance sheet.
Article XIII of the State’s Constitution prohibits the State from incurring debt in excess of one hundred thousand dollars. However, there is a provision in the State’s Constitution that permits the issuance of revenue bonds for: (1) construction of highways; and (2) construction of water conservation and management structures. At June 30, 2023, there was no outstanding debt for either of these purposes.
The above information provided is only a brief summary of the complex factors affecting the financial situation in Nebraska and is derived from sources that are generally available to investors and are believed to be accurate. No independent verification has been made of the accuracy or completeness of any of the preceding information. It is based in part on information obtained from various state and local agencies in Nebraska or contained in Official Statements for various Nebraska municipal obligations.
Factors pertaining to Oklahoma
Since the Oklahoma Fund invests a significant portion of its assets in Oklahoma municipal securities, the Oklahoma Fund is susceptible to political, economic or regulatory factors affecting issuers of Oklahoma municipal obligations.
Oklahoma achieved a historically low rate of 2.9% unemployment for the first few months of 2022. However, following national economic trends, unemployment levels rose to a level more in line with pre-pandemic levels of between 3.6% and 3.4% by summer 2024.
The tight labor market has given rise to consistent growth in wages, with average hourly earnings reaching a historic high of $30.10 in January 2024.
Together, high wages and low unemployment drove record growth in general revenue fund collections during 2022 and 2023, primarily due to increases in state sales and income taxes collections. A reversion to more typical pre-pandemic levels of unemployment, historically high wages, and moderated inflation indicates that economic growth is expected to continue throughout 2024, albeit at a slower rate.
Energy markets trended toward relative stability going into calendar year 2024, compared to the volatility of previous years.
By 2022, oil and gas markets had recovered from the supply and demand shocks of the COVID-19 pandemic, as well as the winter ice storms of 2021. Another supply shock, Russia’s invasion of Ukraine in February 2022, resulted in a sudden short-term increase in oil and gas prices.
| Viking Mutual Funds | Appendix A –Factors Pertaining to States and U.S. Territories | November 30, 2024 Page B-B-4 |
Oil prices peaked in the summer of 2022, but moderated through the first half of 2024, coinciding with tightening monetary policy. While gas prices trended upwards in early 2022, a combination of increased supply capacity and constrained demand (due to a warmer than average winter) moderated prices throughout 2023 and into 2024. Production capacity followed a similar trajectory, as indicated by monthly average rig counts increasing to meet demand throughout 2022 before gradually decreasing in 2023 with a moderate rebound going into 2024.
Gross production taxes make up a meaningful portion of state revenues and are impacted by energy prices and production. Supply and demand escalations throughout 2022 greatly increased state revenues as well as month-to-month volatility, conditions which both moderated throughout 2023. Current trends driven by monetary tightening and increased inventories indicate that oil and gas revenues in 2024 may decrease from the historic highs of the past two years while maintaining greater month-to-month stability. However, the risk of supply and demand shocks due to geopolitical events and extreme weather make longer-term trends difficult to accurately predict.
The State of Oklahoma’s total debt for the general fund decreased by $57.1 million, or 3.1%, during the current fiscal year. Business-type activities’ debt increased by $314.0 million or 21.1%.
By statute, Oklahoma Industrial Finance Authority has authority to issue general obligation bonds not to exceed $90,000,000 plus the balance in its bond redemption account. This results in $60,000,000 of authorized but unissued general obligation bonds.
The above information provided is only a brief summary of the complex factors affecting the financial situation in Oklahoma and is derived from sources that are generally available to investors and are believed to be accurate. No independent verification has been made of the accuracy or completeness of any of the preceding information. It is based in part on information obtained from various state and local agencies in Oklahoma or contained in Official Statements for various Oklahoma municipal obligations.
Factors pertaining to Montana
Since the Viking Tax-Free Fund for Montana invests a significant portion of its assets in Montana municipal securities, the Viking Tax-Free Fund for Montana is susceptible to political, economic or regulatory factors affecting issuers of Montana municipal obligations.
Montana’s primary economic base is concentrated in service-providing industries. Production is sourced primarily from service-providing industries (e.g., healthcare, trade/transportation/utilities, financial services, professional and business services). In 2022, service-providing industries accounted for over 85% of the state’s real Gross State Product (GSP), with goods industries accounting for the remaining. Montana’s four largest industries by share of real GSP are trade/transportation/utilities services, financial services, education and health services, and professional and business services. Other important industries for Montana include manufacturing, construction, and leisure/hospitality (driven by nonresident travel). These three industries each account for between 4% to 7% of real GSP. Montana’s industry mix remains roughly the same through 2023.
Nonfarm payroll employment (NPE) is the number of paid workers in all businesses, excluding those who work for farms, serve in the military, or volunteer for nonprofit organizations. Montana’s NPE is on a steady incline, increasing to 529,700 in June 2023 adding 11,800 jobs (an increase of 2.3%) since June 2022. Employment gains continued into the 2024 fiscal year. The statewide unemployment rate averaged 2.3% in 2023, down from 2.6% in 2022. The unemployment rate fell to a record-low 2.3% in the first quarter of 2023 and remained consistently 2.3% through 2023, with the number of unemployed Montanans also hitting a record low of nearly 13,000. Employment is at an all-time high, unemployment rates have reached record lows, and economic production continues to grow at a steady pace despite tight labor markets and inflationary headwinds. Extraordinary job growth and accelerated wage growth have strengthened Montana households and supported continued economic expansion throughout the State. Like GSP, Montana’s employment is concentrated in the service-providing sector. Industries in this sector account for about 83% of total NPE in the state.
Montana’s tight labor market has pushed nominal wage growth higher over the past few years as firms compete for qualified workers. Per the 2023 Labor Day Report issued by the Montana Department of Labor and Industry, the average wage for Montana workers rose by over 6% in 2022. Montana’s average annual wage was $54,525 in 2022, ranking 44th among states. Inflation outpaced wage growth in 2022, resulting in real average wage declines of 1.6%. The demand for construction workers drove significant wage gains in 2022. Construction worker wages grew by 1.5% on an inflation-adjusted basis in 2022 over the last year. Construction was one of only two industries to experience positive real wage gains in 2022, alongside the business services industry. Personal income, which measures the value Montanans receive from their economic activity, grew steadily in 2022. After rapid personal income growth in 2020 and 2021, growth moderated to 3.1% in 2022 – ranking Montana 19th in the nation for fastest personal income growth.
| Viking Mutual Funds | Appendix A –Factors Pertaining to States and U.S. Territories | November 30, 2024 Page B-B-5 |
The General Fund is the chief operating fund of the State. For fiscal year 2023, the total fund balance of the General Fund was reported at approximately $1.9 billion. Of this balance, $57.4 million is nonspendable. The remaining balance is spendable with $1.0 billion committed, $22.2 million assigned, and $812.6 million unassigned. This spendable fund balance of the General Fund represents 34.7% of the $5.4 billion spendable governmental fund balances for all governmental funds. The assigned fund balance, $22.2 million, represents outstanding encumbrances at the end of the fiscal year. The committed fund balance of $1.0 billion relates to funding set aside by the Legislature for specific initiatives such as the budget stabilization reserve, property tax rebates, fire suppression funds, and more. For a full list of committed balances, see Note 1, section R. Further detail on the breakdown of fund balance for the General Fund is provided in Note 14 – Major Purpose Presentation.
Total fund balance decreased by $72.9 million when compared to the previously reported fund balance of $2.0 billion.
Montana continues to receive excellent general obligation bond ratings from Moody’s Investor Service (Aa1), Standard and Poor’s Corporation (AA), and Fitch Ratings (AA+), which remain unchanged from 2022.
State debt may be authorized either by a two-thirds vote of the members of each house of the Legislature or by a favorable vote of a majority of the State’s electors voting thereon. There is no constitutional limit on the amount of debt that may be incurred by the State. The Montana Constitution does, however, prohibit incurring debt to cover deficits caused by appropriations exceeding anticipated revenue.
The State’s general obligation debt decreased from $130.8 million on June 30, 2022, to none at June 30, 2023.
The above information provided is only a brief summary of the complex factors affecting the financial situation in Montana and is derived from sources that are generally available to investors and are believed to be accurate. No independent verification has been made of the accuracy or completeness of any of the preceding information. It is based in part on information obtained from various agencies in Montana or contained in Official Statements for various Montana municipal obligations.
Factors pertaining to North Dakota
Since the Viking Tax-Free Fund for North Dakota invests a significant portion of its assets in North Dakota municipal securities, the Viking Tax-Free Fund for North Dakota is susceptible to political, economic or regulatory factors affecting issuers of North Dakota municipal obligations.
Although North Dakota’s economy is increasingly diversified, the agricultural industry continues to play a key role in the state’s economy. The North Dakota Agricultural Statistics report states: North Dakota led the nation in the production of all dry edible beans, pinto beans, canola, flaxseed, honey, oats, rye, all sunflowers, durum wheat and spring wheat for 2022. North Dakota also ranked second in the production of barley, pink beans, small red beans, lentils, dry edible peas, and sugar beets.
The energy industry plays an important role in the state’s economy. The development of wind and coal resources, the production of ethanol and bio-diesel, and oil and natural gas extraction all contribute to the state’s economy. North Dakota reached an all-time high for oil production which 8 averaged over 1.52 million barrels of oil produced per day in November 2019. North Dakota’s current crude oil production ranks third in the nation, behind first-ranked Texas and second ranked New Mexico. Oil prices have rebounded since the crash of oil prices at the end of fiscal year 2020 when North Dakota producers were receiving prices below $15 per barrel. North Dakota price is averaging around $77 per barrel to start off the 2023-25 biennium which is above the estimated price of $70.00 used for budgeting purposes for the first year of the biennium.
According to the United States Census Bureau, the state’s resident population for 2022 was approximately 779,000 people. Health care and social assistance jobs account for the highest percent of employment in the state. Other leading areas of employment are retail trade, accommodation and food services, educational services, construction, and manufacturing. The unemployment rate for the state in August 2023 was 1.9%, compared to 3.8% for the United States.
A listing of the state’s 20 largest employers demonstrates the diversity of the economy. Top employers include: health care providers, educational services, social assistance, the U.S military, manufacturers, financial, banking and insurance companies.
North Dakota exporting continues to stay flat when comparing 2022 to 2021. The International Trade Administration showed that North Dakota’s exports were about $5.2 billion for both 2021 and 2022.
The State’s total debt (bonds, certificates of participation, lease, SBITA, and notes payable) increased approximately 35.4% during the fiscal year to $3.9 billion, an increase of $1.01 billion, which represents the net difference between new issuances and payments. During the year the State issued $570.3 million in bonds and $4.08 billion in notes.
Long-term Debt: Article X, Section 13 of the Constitution of North Dakota provides that the state may issue or guarantee the payment of bonds provided that all bonds in excess of $2 million are: secured by first mortgage upon property and no further indebtedness may be incurred by the state unless evidenced by a bond issue; authorized by law, for a certain purpose; provisioned to pay the interest semiannually, and pay the principal within 30 years. The law authorized the bond issue must specifically appropriate the provisions to the payment of the principal and interest of the bond. The State has no general obligation bonds outstanding at June 30, 2023.
The above information provided is only a brief summary of the complex factors affecting the financial situation in North Dakota and is derived from sources that are generally available to investors and are believed to be accurate. No independent verification has been made of the accuracy or completeness of any of the preceding information. It is based in part on information obtained from various agencies in North Dakota or contained in Official Statements for various North Dakota municipal obligations.
| Viking Mutual Funds | Appendix A –Factors Pertaining to States and U.S. Territories | November 30, 2024 Page B-B-6 |
Factors pertaining to Guam
Each Fund may invest in Guam municipal bonds and, therefore, may be impacted by political, economic, or regulatory developments that affect issuers in Guam and their ability to pay principal and interest on their obligations.
Real gross domestic product (GDP) for Guam increased 5.1 percent in 2022 after increasing 2.1 percent in 2021, according to statistics released by the U.S. Bureau of Economic Analysis (BEA). These statistics were developed under the Statistical Improvement Program, funded by the Office of Insular Affairs (OIA) of the U.S. Department of the Interior.
The increase in real GDP reflected increases in exports, private fixed investment, government spending, and personal consumption expenditures. Imports, a subtraction item in the calculation of GDP, increased.
Exports of goods and services increased 150.4 percent. The increase in exports was accounted for by exports of services, which consists primarily of spending by visitors. Exports of services increased 262.0 percent; data from the Guam Visitors Bureau arrival summary reports show that visitor arrivals increased over 300 percent.
Private fixed investment increased 14.7 percent, reflecting growth in equipment and structures. Private-sector construction projects included a 60-megawatt solar farm, resort renovations, and retail outlets.
Government spending increased 1.4 percent, reflecting growth in federal government spending that was partly offset by a decrease in territorial government spending. U.S. Department of Defense construction was a notable source of growth, as progress continued on multiple U.S. military projects, including housing and dining facilities for a new Marine Corps base.
Personal consumption expenditures increased 1.2 percent, reflecting widespread growth among consumer spending categories. Consumer spending was supported by growth in compensation and direct cash assistance administered by the territorial government.
In 2021, real GDP increased 2.1 percent. The newly available GDP by industry data, which are released on a 1-year lag, reveal that the private sector was the source of growth in real GDP in 2021.
The private sector increased 4.4 percent, primarily reflecting growth in other private industries, such as health care and social assistance and financial services. Construction also increased, reflecting retail outlet and multiunit residential development projects.
The government sector decreased 1.1 percent, partly offsetting the growth in the private sector. Both federal and territorial government real value added decreased.
Total compensation increased from $3,527 million in 2020 to $3,615 million in 2021. The $88 million increase reflected increases in both private-sector and government compensation. The largest contributor to the increase was construction.
The above information provided is only a brief summary of the complex factors affecting the financial situation in Guam and is derived from sources that are generally available to investors and are believed to be accurate. No independent verification has been made of the accuracy or completeness of any of the preceding information. It is based in part on information obtained from various agencies in Guam or contained in Official Statements for various Guam municipal obligations.
Factors pertaining to Puerto Rico
Each Fund may invest in Puerto Rico municipal bonds and, therefore, may be impacted by political, economic, or regulatory developments that affect issuers in Puerto Rico and their ability to pay principal and interest on their obligations.
The Commonwealth of Puerto Rico has a population of about 3.2 million. The San Juan-Caguas area is the largest of the island’s seven metropolitan areas, representing roughly 75 percent of the island’s economy. Puerto Rico had suffered from a severe and prolonged economic slump from 2006-17 with GDP, population, and employment all on a downward trend. That downturn was punctuated by Hurricane Maria in 2017, followed by the most extensive power outage in U.S. history, which caused a further, but short-lived, drop-off in the economy. Since then, the economy has been growing interrupted only briefly by a steep drop early in the pandemic. However, the economy bounced back strongly, and as of mid-2022, private-sector employment was at a fifteen-year high. The medical manufacturing cluster remains a key part of the island’s economy, though employment in this industry is well below its peak levels of 2005. Puerto Rico’s tourism sector is still relatively small, but it has been one of the Commonwealth’s strongest job creators in recent years. In addition, a fledgling aerospace industry has emerged around Aguadilla and Arecibo. Wages in Puerto Rico tend to be about half the level of the mainland, and income inequality is considerably higher. However, educational attainment is only modestly lower than on the mainland. The island has made great progress in resolving and rebounding from its extensive fiscal crisis.
| Viking Mutual Funds | Appendix A –Factors Pertaining to States and U.S. Territories | November 30, 2024 Page B-B-7 |
The above information provided is only a brief summary of the complex factors affecting the financial situation in Puerto Rico and is derived from sources that are generally available to investors and are believed to be accurate. No independent verification has been made of the accuracy or completeness of any of the preceding information. It is based in part on information obtained from various agencies in Puerto Rico or contained in Official Statements for various municipal obligations of Puerto Rico.
Factors pertaining to U.S. Virgin Islands
Each Fund may invest in U.S. Virgin Islands (“USVI”) municipal bonds and, therefore, may be impacted by political, economic, or regulatory developments that affect issuers in the U.S. Virgin Islands and their ability to pay principal and interest on their obligations.
Situated just east of Puerto Rico, the U.S. Virgin Islands are a U.S. territory that includes the islands of St. Thomas, St. Croix, and St. John. Its population fell by a striking 18 percent over the last decade to 87,000 in 2020-the lowest level since the 1970s. Its economy has been weakened by a series of blows-the closure in 2012 of the Hovensa oil refinery, a major employer; Hurricanes Irma and Maria in 2017, which caused extensive damage and disruptions; and the pandemic in 2020, which devastated its key tourism industry, which is highly dependent on cruise ship visits. Like Puerto Rico, the U.S. Virgin Islands have been under fiscal stress, but unlike its neighbor to the west, this territory has not resolved the issue. While the U.S. Virgin Islands have not defaulted on debt payments, public debt is high and market access for borrowing is limited.
The above information provided is only a brief summary of the complex factors affecting the financial situation in the U.S. Virgin Islands and is derived from sources that are generally available to investors and are believed to be accurate. No independent verification has been made of the accuracy or completeness of any of the preceding information. It is based in part on information obtained from various agencies in the U.S. Virgin Islands or contained in Official Statements for various municipal obligations of the U.S. Virgin Islands.
| Viking Mutual Funds | Appendix A –Factors Pertaining to States and U.S. Territories | November 30, 2024 Page B-B-8 |
PART C
OTHER INFORMATION
ITEM 28: EXHIBITS
| (a) | (1) | Certificate of Trust. Incorporated by reference to Registrant’s registration statement, filed May 7, 1999, SEC Accession No. 0001082744-99-000013. |
| (2) | Trust Instrument of Viking Mutual Funds. Incorporated by reference to Registrant’s registration statement, filed May 7, 1999, SEC Accession No. 0001082744-99-000013. | |
| (3) | Schedule A—Current Series of Viking Mutual Funds dated May 18, 2017. Incorporated by reference to Exhibit (a)(3) of Post-Effective Amendment No. 37 to Registrant’s registration statement, filed June 29, 2017, SEC Accession No. 0001082744-17-00034. | |
| (b) | By-laws of Viking Mutual Funds. Incorporated by reference to Registrant’s registration statement, filed May 3, 2010, SEC Accession No. 0001082744-10-000016. |
| (c) | Declaration of Trust filed under (a) and By-laws filed under (b). |
| (d) | Amended Investment Advisory Agreement Between Viking Mutual Funds and Viking Fund Management, LLC, on behalf of all Series as of October 27, 2017. Incorporated by reference to Post-Effective Amendment No. 40 to the Registrant’s registration statement, filed November 1, 2017, SEC Accession No. 0001082744-17-000081. |
| (e) | (1) | Distribution Agreement with Integrity Funds Distributor, LLC for Viking Tax-Free Fund for Montana. Incorporated by reference to Registrant’s registration statement, filed May 3, 2010, SEC Accession No. 0001082744-10-000016. |
| (2) | Distribution Agreement with Integrity Funds Distributor, LLC for Viking Tax-Free Fund for North Dakota. Incorporated by reference to Registrant’s registration statement, filed May 3, 2010, SEC Accession No. 0001082744-10-000016. | |
| (3) | Distribution Agreement with Integrity Funds Distributor, LLC for Kansas Municipal Fund. Incorporated by reference to Post-Effective Amendment No. 40 to the Registrant’s Registration Statement, filed November 1, 2017, SEC Accession No. 0001082744-17-000081. | |
| (4) | Distribution Agreement with Integrity Funds Distributor, LLC for Maine Municipal Fund. Incorporated by reference to Post-Effective Amendment No. 40 to the Registrant’s Registration Statement, filed November 1, 2017, SEC Accession No. 0001082744-17-000081. | |
| (5) | Distribution Agreement with Integrity Funds Distributor, LLC for Nebraska Municipal Fund. Incorporated by reference to Post-Effective Amendment No. 40 to the Registrant’s Registration Statement, filed November 1, 2017, SEC Accession No. 0001082744-17-000081. | |
| (6) | Distribution Agreement with Integrity Funds Distributor, LLC for Oklahoma Municipal Fund. Incorporated by reference to Post-Effective Amendment No. 40 to the Registrant’s Registration Statement, filed November 1, 2017, SEC Accession No. 0001082744-17-000081. | |
| (f) | Not Applicable. |
| (g) | Custody Agreement dated October 2, 2019 with UMB Bank, N.A. on behalf of all Series. Incorporated by reference to Post-Effective Amendment No. 46 to Registrant’s registration statement, filed November 27, 2019, SEC Accession No. 0001082744-19-000087. |
| (h) | (1) | (a) | Amended and Restated Transfer Agency Agreement Between Viking Mutual Funds and Integrity Fund Services, LLC. Incorporated by reference to Post-Effective Amendment No. 40 to Registrant’s registration statement, filed November 1, 2017, SEC Accession No. 0001082744-17-000081. |
| (b) | Addendum to Transfer Agency Agreement. Incorporated by reference to Registrant’s registration statement, filed April 30, 2012, SEC Accession No. 0001082744-12-000010. | ||
| (2) | (a) | Amended and Restated Administrative and Accounting Services Agreement Between Viking Mutual Funds and Integrity Fund Services, LLC. Incorporated by reference to Post-Effective Amendment No. 40 to Registrant’s registration statement, filed November 1, 2017, SEC Accession No. 0001082744-17-000081. | |
| (b) | Addendum to Administrative and Accounting Services Agreement is filed herewith. | ||
| Viking Mutual Funds | Part C | November 30, 2024 Page C-1 |
| (3) | Management Fee Waiver and Expense Reimbursement Agreement Between Viking Mutual Funds and Viking Fund Management, LLC is filed herewith. |
| (4) | Form of Indemnification Agreement. Incorporated by reference to Post-Effective Amendment No. 27 to Registrant’s registration statement, filed April 30, 2015, SEC Accession No. 0001082744-15-000011. |
| (i) | Legal Opinion and Consent of Thompson Hine LLP, dated November 27, 2024, is filed herewith. |
| (j) | Consent of Independent Registered Public Accounting Firm is filed herewith. |
| (k) | Not Applicable. |
| (l) | Not Applicable. |
| (m) | Amended Plan of Distribution and Service Pursuant to Rule 12b-1 (Class A Shares). Incorporated by reference to Post-Effective Amendment No. 40 to Registrant’s registration statement, filed November 1, 2017, SEC Accession No. 0001082744-17-000081. |
| (n) | Amended and Restated Multiple Class Plan Adopted Pursuant to Rule 18f-3, on behalf of all Series. Incorporated by reference to Post-Effective Amendment No. 40 to Registrant’s registration statement, filed November 1, 2017, SEC Accession No. 0001082744-17-000081. |
| (o) | Power of Attorney Authorization. Incorporated by reference to Post-Effective Amendment No. 48 to Registrant’s registration statement filed November 27, 2020, SEC Accession No. 0001082744-20-000096. |
| (p) | Code of Ethics applicable to Registrant and Registrant’s investment adviser and principal underwriter. Incorporated by reference to Post-Effective Amendment No. 35 to Registrant’s registration statement, filed April 28, 2017, SEC Accession No. 0001082744-17-000021. |
ITEM 29: PERSONS CONTROLLED BY OR UNDER COMMON CONTROL WITH REGISTRANT
No person is controlled by or under common control with the Registrant.
ITEM 30: INDEMNIFICATION
A Delaware statutory trust may provide in its governing instrument for indemnification of its officers and trustees from and against any and all claims and demands whatsoever. Article IX, Section 2 of the Trust Instrument provides that the Registrant shall indemnify any present or former trustee, officer, employee or agent of the Registrant (Covered Person) to the fullest extent permitted by law against liability and all expenses reasonably incurred or paid by him or her in connection with any claim, action, suit or proceeding (Action) in which he or she becomes involved as a party or otherwise by virtue of his or her being or having been a Covered Person and against amounts paid or incurred by him or her in settlement thereof. Indemnification will not be provided to a person adjudged by a court or other body to be liable to the Registrant or its shareholders by reason of willful misfeasance, bad faith, gross negligence or reckless disregard of the duties involved in the conduct of his office (Disabling Conduct), or not to have acted in good faith in the reasonable belief that his or her action was in the best interest of the Registrant. In the event of a settlement, no indemnification may be provided unless there has been a determination that the officer or trustee did not engage in Disabling Conduct (i) by the court or other body approving the settlement; (ii) by at least a majority of those trustees who are neither interested persons, as that term is defined in the Investment Company Act of 1940 (1940 Act), of the Registrant (Independent Trustees), nor are parties to the matter based upon a review of readily available facts; or (iii) by written opinion of independent legal counsel based upon a review of readily available facts.
Pursuant to Article IX, Section 3 of the Trust Instrument, if any present or former shareholder of any series (Series) of the Registrant shall be held personally liable solely by reason of his or her being or having been a shareholder and not because of his or her acts or omissions or for some other reason, the present or former shareholder (or his or her heirs, executors, administrators or other legal representatives or in the case of any entity, its general successor) shall be entitled out of the assets belonging to the applicable Series to be held harmless from and indemnified against all loss and expense arising from such liability. The Registrant, on behalf of the affected Series, shall, upon request by such shareholder, assume the defense of any claim made against such shareholder for any act or obligation of the Series and satisfy any judgment thereon from the assets of the Series.
| Viking Mutual Funds | Part C | November 30, 2024 Page C-2 |
Insofar as indemnification for liabilities arising under the Securities Act of 1933 (1933 Act) may be permitted to trustees, officers and controlling persons of the Registrant pursuant to the foregoing provisions, or otherwise, the Registrant has been advised that in the opinion of the Securities and Exchange Commission, such indemnification is against public policy as expressed in the Act and is, therefore, unenforceable. In the event that a claim for indemnification against such liabilities (other than the payment by the Registrant of expenses incurred or paid by a trustee, officer or controlling person of the Registrant in the successful defense of any action, suit or proceeding) is asserted by such trustee, officer or controlling person, the Registrant will, unless in the opinion of its counsel the matter has been settled by controlling precedent, submit to a court of appropriate jurisdiction the question whether such indemnification by it is against public policy as expressed in the 1933 Act and will be governed by the final adjudication of such issue.
In addition, the Trust has entered into a separate Indemnification Agreement with each of its trustees (as well as its officers) whereby the Trust has generally agreed to indemnify such persons to the fullest extent permitted by the laws of the State of Delaware. These Indemnification Agreements acknowledge, however, that, in certain instances, applicable law or public policy may prohibit the Trust from indemnifying its trustees and officers. (See Exhibit (h)(4).)
The Distribution and Services Agreement between the Trust, on behalf of each Series, (the “Fund”) and Integrity Funds Distributor (“Integrity”) provides with regard to indemnification that:
| (a) | The Fund agrees to indemnify, defend, and hold Integrity, its several officers and governors, and any person who controls Integrity within the meaning of Section 15 of the Securities Act of 1933, as amended (the “1933 Act”), free and harmless from and against any and all claims, demands, liabilities, and expenses (including the cost of investigating or defending such claims, demands, or liabilities and any counsel fees incurred in connection therewith) which Integrity, its officers and governors, or any such controlling person may incur under the 1933 Act, the Investment Company Act of 1940, as amended (the “1940 Act”), or common law or otherwise, arising out of or based upon any untrue statement or alleged untrue statement of a material fact contained in any registration statement, any prospectus, or any statement of additional information, or arising out of or based upon any omission or alleged omission to state a material fact required to be stated in any registration statement, any prospectus, or any statement of additional information, or necessary to make the statements in any of them not misleading; provided, however, that the Fund’s agreement to indemnify Integrity, its officers or governors, and any such controlling person shall not be deemed to cover any claims, demands, liabilities, or expenses arising out of or based upon any statements or representations made by Integrity or its representatives or agents other than such statements and representations as are contained in any registration statement, prospectus, or statement of additional information and in such financial and other statements as are furnished to Integrity pursuant to paragraph 2.2 of the Distribution and Services Agreement; and further provided that the Fund’s agreement to indemnify Integrity and the Fund’s representations and warranties hereinbefore set forth in paragraph 3 of the Distribution and Services Agreement shall not be deemed to cover any liability to the Fund or its shareholders to which Integrity would otherwise be subject by reason of willful misfeasance, bad faith, or gross negligence in the performance of its duties, or by reason of Integrity’s reckless disregard of its obligations and duties under the Distribution and Services Agreement. The Fund’s agreement to indemnify Integrity, its officers and governors, and any such controlling person, as aforesaid, is expressly conditioned upon the Fund’s being notified of any action brought against Integrity, its officers or governors, or any such controlling person, such notification to be given by letter or by telegram addressed to the Fund at its principal office in Minot, North Dakota, and sent to the Fund by the person against whom such action is brought, within ten days after the summons or other first legal process shall have been served. The failure so to notify the Fund of any such action shall not relieve the Fund from any liability that the Fund may have to the person against whom such action is brought by reason of any such untrue statement or omission or alleged omission otherwise than on account of the Fund’s indemnity agreement contained in paragraph 4.1 of the Distribution and Services Agreement. The Fund’s indemnification agreement contained in paragraph 4.1 of the Distribution and Services Agreement and the Fund’s representations and warranties in the Distribution and Services Agreement shall remain operative and in full force and effect regardless of any investigation made by or on behalf of Integrity, its officers and governors, or any controlling person, and shall survive the delivery of any Shares. The agreement of indemnity will inure exclusively to Integrity’s benefit, to the benefit of its several officers and governors, and their respective estates, and to the benefit of the controlling persons and their successors. The Fund agrees to notify Integrity promptly of the commencement of any litigation or proceedings against the Fund or any of its officers or trustees in connection with the issuance and sale of any Shares. | |
| (b) | Integrity agrees to indemnify, defend, and hold the Fund, its several officers and trustees, and any person who controls the Fund within the meaning of Section 15 of the 1933 Act, free and harmless from and against any and all claims, demands, liabilities, and expenses (including the costs of investigating or defending such claims, demands, or liabilities and any counsel fees incurred in connection therewith) that the Fund, its officers or trustees, or any such controlling person may incur under the 1933 Act, the 1940 Act, or common law or otherwise, but only to the extent that such liability or expense incurred by the Fund, its officers or trustees, or such controlling person resulting from such claims or demands shall arise out of or be based upon (a) any unauthorized sales literature, advertisements, information, statements, or representations or (b) any untrue or alleged untrue statement of a material fact contained in information furnished in writing by Integrity to the Fund and used in the answers to any of the items of the registration statement or in the corresponding statements made in the prospectus or statement of additional information, or shall arise out of or be based upon any omission or alleged omission to state a material fact in connection with such information furnished in writing by Integrity to the Fund and required to be stated in such answers or necessary to make such information not misleading. Integrity’s agreement to indemnify the Fund, its officers and trustees, and any such controlling person, as aforesaid, is expressly conditioned upon Integrity’s being notified of any action brought against the Fund, its officers or trustees, or any such controlling person, such notification to be given by letter or telegram addressed to Integrity at its principal office in Minot, North Dakota, and sent to Integrity by the person against whom such action is brought, within ten days after the summons or other first legal process shall have been served. The failure so to notify Integrity of any such action shall not relieve Integrity from any liability that Integrity may have to the Fund, its officers or trustees, or to such controlling person by reason of any such untrue or alleged untrue statement or omission or alleged omission otherwise than on account of Integrity’s indemnity agreement contained in paragraph 4.2 of the Distribution and Services Agreement. Integrity agrees to notify the Fund promptly of the commencement of any litigation or proceedings against Integrity or any of its officers or governors in connection with the issuance and sale of any Shares. |
| Viking Mutual Funds | Part C | November 30, 2024 Page C-3 |
ITEM 31: BUSINESS AND OTHER CONNECTIONS OF INVESTMENT ADVISER
The business of Viking Fund Management, Inc. (“Viking Management”) is summarized under “Management and Other Services” in the Statement of Additional Information constituting Part B of this Registration Statement, which summary is incorporated herein by reference.
The information required by this Item 31 with respect to each director, officer, or partner of the Registrant’s adviser, Viking Management, is incorporated by reference to Form ADV filed by Viking Management with the Securities and Exchange Commission pursuant to the Investment Advisers Act of 1940, as amended (File No. 801-56605).
ITEM 32: PRINCIPAL UNDERWRITERS
| (a) | Integrity Funds Distributor, LLC, the principal underwriter distributing securities of the Registrant, also serves as the principal underwriter for The Integrity Funds. Integrity Funds Distributor, LLC is registered with the Securities and Exchange Commission as a broker-dealer and is a member of the Financial Industry Regulatory Authority (“FINRA”). | ||||
| (b) | Set forth below is information concerning the directors and officers of the Registrant’s principal underwriter. | ||||
| NAME AND PRINCIPAL BUSINESS ADDRESS |
POSITIONS AND OFFICES WITH UNDERWRITER |
POSITIONS AND OFFICES WITH REGISTRANT |
|||
| Shannon D. Radke 1 North Main Street Minot, North Dakota 58703 |
Governor, President | President | |||
| Brock J. Teets 1 North Main Street Minot, North Dakota 58703 |
Governor, Vice President | None | |||
| Jonathan R. Hanson 1 North Main Street Minot, North Dakota 58703 |
Governor, Secretary | None | |||
| Kraig Klebe 1 North Main Street Minot, North Dakota 58703 |
Governor, Treasurer | None | |||
| Trey A. Welstad 1 North Main Street Minot, North Dakota 58703 |
Chief Compliance Officer | None | |||
| (c) | No commissions or other compensation were received directly or indirectly from the Registrant by any principal underwriter who was not an affiliated person of the Registrant. | ||||
ITEM 33: LOCATION OF ACCOUNTS AND RECORDS
The custodian of the assets of the Funds other than cash is UMB Bank, N.A., Institutional Custody, 928 Grand Blvd, Kansas City, Missouri 64105. Integrity Fund Services, LLC serves as transfer agent, dividend disbursing, administrative, and accounting services agent of the Registrant and maintains all records related to those functions. Integrity Funds Distributor, LLC serves as the principal underwriter of the Registrant and maintains all records related to that function. Viking Fund Management, LLC serves as the Registrant’s investment adviser and maintains all records related to that function. The Registrant maintains all of its corporate records. The address of Integrity Funds Distributor, LLC, Integrity Fund Services, LLC, Viking Fund Management, LLC and the Registrant is 1 Main Street North, Minot, North Dakota 58703.
| Viking Mutual Funds | Part C | November 30, 2024 Page C-4 |
ITEM 34: MANAGEMENT SERVICES
Other than as set forth in Parts A and B of this Registration Statement, the Registrant is not a party to any management-related service contract.
ITEM 35: UNDERTAKINGS
None
SIGNATURES
Pursuant to the requirements of the Securities Act of 1933 and the Investment Company Act of 1940, the Registrant, VIKING MUTUAL FUNDS, certifies that it meets all of the requirements for effectiveness of this Registration Statement under Rule 485(b) under the Securities Act of 1933 and has duly caused this Post-Effective Amendment Number 54 to its Registration Statement to be signed on its behalf by the undersigned, thereto duly authorized, in the City of Minot and State of North Dakota on the 27th day of November, 2024.
| VIKING MUTUAL FUNDS | ||
| By: | /s/ Shannon D. Radke | |
| Shannon D. Radke | ||
| President | ||
Pursuant to the requirements of the Securities Act of 1933, this Post-Effective Amendment Number 54 to its Registration Statement has been signed below by the following persons in the capacities indicated on November 27, 2024.
| Signature | Title | |||
| /s/ Shannon D. Radke | President | |||
| Shannon D. Radke | (Principal Executive Officer) | |||
| /s/ Shelly Nahrstedt | Treasurer | |||
| Shelly Nahrstedt | (Principal Financial and Accounting Officer) | |||
| Robert E. Walstad* | Trustee and Chairman of the Board | ) | ||
| Jerry M. Stai* | Trustee | ) | By: | /s/ Shannon D. Radke |
| R. James Maxson* | Trustee | ) | Shannon D. Radke | |
| Wade A. Dokken* | Trustee | Attorney-in-Fact |
| * | An original power of attorney authorizing Shannon D. Radke to execute any amendment to Registration Statement No. 333-77993 for each of the trustees of the Registrant on whose behalf this Post-Effective Amendment No. 54 to the Registration Statement has been executed and filed with the Securities and Exchange Commission on November 27, 2020. |
EXHIBITS
| Viking Mutual Funds | Part C | November 30, 2024 Page C-5 |
ATTACHMENTS / EXHIBITS
Serious News for Serious Traders! Try StreetInsider.com Premium Free!
You May Also Be Interested In
- Carbon Trade eXchange Launches CTX Corporate One for Institutional-Scale, High-Quality Carbon Credits
- Li Bang International Corporation Inc. Announces Results of September 2026 Extraordinary General Meeting
- Tencent Cloud Launches Tencent Cloud DataBuddy, an Agent-Native Data + AI Workbench
Create E-mail Alert Related Categories
SEC FilingsSign up for StreetInsider Free!
Receive full access to all new and archived articles, unlimited portfolio tracking, e-mail alerts, custom newswires and RSS feeds - and more!
