




Form 485APOS Cavanal Hill Funds
 Tweet
 Share
 E-mail
As filed with the Securities and Exchange Commission on October 6, 2026
Registration Nos. 033-35190 and 811-06114
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM N-1A
| REGISTRATION STATEMENT UNDER THE SECURITIES ACT OF 1933 | ☑ | |
| Post-Effective Amendment No. 91 | ☑ | |
| REGISTRATION STATEMENT UNDER THE INVESTMENT COMPANY ACT OF 1940 | ☑ | |
| Amendment No. 88 | ☑ |
CAVANAL HILL® FUNDS
(Exact Name of Registrant as Specified in Charter)
4400 Easton Commons, Suite 200
Columbus, Ohio 43219
(Address of Principal Executive Office) (Zip Code)
(800) 762-7085
(Registrant’s Telephone Number, including Area Code)
Catherine Dunn,
President
Cavanal Hill Funds
4400 Easton Commons, Suite 200
Columbus, Ohio 43219
(Name and Address of Agent for Service)
with a copy to:
Amy Newsome
Frederic Dorwart, Lawyers PLLC
124 East Fourth Street
Tulsa, OK 74103
Approximate Date of Proposed Public Offering: Continuous.
It is proposed that this filing will become effective (check appropriate box):
| ☐ | Immediately upon filing pursuant to paragraph (b) |
| ☐ | On December 28, 2026 pursuant to paragraph (b) |
| ☐ | 60 days after filing pursuant to paragraph (a)(1) |
| ☐ | On December 28, 2026 pursuant to paragraph (a)(1) |
| ☒ | 75 days after filing pursuant to paragraph (a)(2) |
| ☐ | On December 28, 2026 pursuant to paragraph (a)(2) of Rule 485 |
If appropriate, check the following box:
| ☐ | This post-effective amendment designates a new effective date for a previously-filed post-effective amendment. |
Title of securities being registered: Shares of Beneficial Interest
Subject to Completion, dated October 6, 2026
The information in this prospectus is not complete and may be changed. We may not sell these securities until the registration statement filed with the Securities and Exchange Commission is effective. This prospectus is not an offer to sell these securities and is not soliciting an offer to buy these securities in any state where the offer or sale is not permitted.

December 28, 2026

The Securities and Exchange Commission has not approved or disapproved these securities or passed upon the adequacy of this prospectus. Any representation to the contrary is a criminal offense.
Table of Contents
| Fund Summary Section | |
| 2 - 41 | |
| Money Market Funds | |
| 2 | U.S. Treasury Fund |
| 6 | Government Securities Money Market Fund |
| Bond Funds | |
| 10 | Limited Duration Fund |
| 15 | Bond Fund |
| 20 | Strategic Enhanced Yield Fund |
| Equity Funds | |
| 26 | World Energy & Power Fund |
| 32 | Hedged Equity Income Fund |
| 37 | Industrial Frontier Fund |
| Your Account | |
| 43 | Customer Identification Information |
| 43 | Opening an Account and Buying Shares |
| 45 | Selling Shares |
| 47 | Shareholder Fees |
| 48 | Distribution/Service (12b-1) Fees |
| 48 | Shareholder Servicing Plan |
| 50 | Distribution and Shareholder Servicing Arrangements — Revenue Sharing |
| 50 | Exchanging Shares |
| 50 | Transaction Policies |
| 52 | Additional Investor Services |
| 52 | Dividends and Capital Gains |
| 52 | Taxes |
| 54 | Additional Information about the Funds |
| Investment Practices and Risks | |
| 55 | Investment Practices |
| 59 | Investment Instruments |
| 62 | Investment Risks |
| Investment Management | |
| 68 | Investment Adviser |
| Financial Highlights | |
| 72 | Financial Highlights |
| Glossary of Investment Terms | |
| 74 | Glossary |
| More Information | |
| Back Cover | |
| www.cavanalhillfunds.com | 1-800-762-7085 |
| U.S. TREASURY FUND |
| SUMMARY |
Investment Objective
To seek current income with liquidity and stability of principal.
Fees and Expenses of the Fund
This table describes the fees and expenses that you may pay if you buy, hold and sell shares of the U.S. Treasury Fund. An investor transacting in Institutional Shares, which do not have any front-end sales charge, contingent deferred sales charge, or other asset-based fee for sales or distribution, may be required to pay a commission to a broker or other financial intermediary for effecting such transactions on an agency basis. Such commissions are not reflected in the tables or the example below. Shares of the Fund are available in other share classes that have different fees and expenses.
Shareholder Fees (fees paid directly from your investment): None.
Annual Fund Operating Expenses (expenses that you pay each year as a percentage of the value of your investment). |
Administrative Shares |
Institutional Shares |
Select Shares |
| Management Fees | 0.05% | 0.05% | 0.05% |
| Distribution and/or Service (12b-1) Fees | 0.25% | — | — |
| Other Expenses | [•]% | [•]% | [•]% |
| Shareholder Servicing Fees | 0.25% | 0.25% | 0.25% |
| Acquired Fund Fees and Expenses | [•]% | [•]% | [•]% |
| Total Annual Fund Operating Expenses | [•]% | [•]% | [•]% |
| Less Fee Waivers† | — | (0.17)% | (0.25)% |
| Total Annual Fund Operating Expenses After Fee Waivers | [•]% | [•]% | [•]% |
| † | Affiliates of the Adviser have contractually agreed to waive all Shareholder Servicing Fees to which they are entitled paid by Select Shares and 0.17% paid by Institutional Shares. The affiliate waivers result in a reduction of the Shareholder Servicing Fee paid by all purchasers of a Class to the extent shown in the table. Contractual waivers are in place for the period through December 31, 2027, and may only be terminated or modified with the approval of the Fund’s Board of Trustees. |
Example
This example is intended to help you compare the cost of investing in the Fund with the cost of investing in other mutual funds. The example assumes that you invest $10,000 in the Fund for the time periods indicated and then redeem all of your shares at the end of those periods. The example also assumes that your investment has a 5% return each year and that the Fund’s operating expenses remain the same. Although your actual costs may be higher or lower, based on these assumptions your costs would be:
| 1 Year | 3 Years | 5 Years | 10 Years | |
| Administrative Shares | $[•] | $[•] | $[•] | $[•] |
| Institutional Shares | $[•] | $[•] | $[•] | $[•] |
| Select Shares | $[•] | $[•] | $[•] | $[•] |
Principal Investment Strategy
To pursue its objective, under normal circumstances, the Fund invests at least 99.5% of its total assets in cash, U.S. Government Securities, or repurchase agreements collateralized by U.S. Government Securities and other U.S. Treasury investment companies. The Fund also invests at least 80% of its net assets in U.S. Treasury Obligations or repurchase agreements collateralized by U.S. Treasury Obligations. These policies will not be changed without at least 60 days prior notice to shareholders. As a money market fund, the dollar-weighted average portfolio maturity of the Fund will not exceed 60 days and the dollar-weighted average portfolio life cannot exceed 120 days.
| www.cavanalhillfunds.com | 2 | 1-800-762-7085 |
Principal Investment Risks
You could lose money by investing in the Fund. Although the Fund seeks to preserve the value of your investment at $1.00 per share, it cannot guarantee it will do so. An investment in the Fund is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other government agency. The Fund’s sponsor has no legal obligation to provide financial support to the Funds, beyond what is disclosed in the footnote under the “Annual Fund Operating Expenses” table, and you should not expect that the sponsor will provide additional financial support to the Fund at any time. In addition, the principal risks of investing in the Fund, which could adversely affect the Fund’s net asset value, yield or total return are:
| • | Interest Rate Risk — The value of the Fund’s interest-bearing investments may decline due to an increase in interest rates. In general, the longer a security’s maturity, the greater the interest rate risk. For a portfolio with a duration of 3 years, each 1% rise in interest rates would reduce the value of the portfolio by an estimated 3%. The Fund’s yield may decrease due to a decline in interest rates. Very low or negative interest rates may magnify interest rate risk. Future declines in interest rate levels could cause the Fund’s earnings to fall below the Fund’s expense ratio, resulting in a negative yield and a decline in the Fund’s share price. Changing interest rates, including negative interest rates, may have unpredictable effects on markets, may result in heightened market volatility and may detract from Fund performance to the extent the Fund is exposed to such interest rates. |
| • | Market Risk — The value of the Fund’s assets will fluctuate as the markets in which the Fund invests fluctuate. The value of the Fund’s investments may decline, sometimes rapidly and unpredictably, simply because of economic changes or other events, such as inflation (or expectations for inflation), deflation (or expectations for deflation), interest rates, global demand for particular products or resources, market instability, debt crises and downgrades, embargoes, tariffs, sanctions and other trade barriers, regulatory events, other governmental trade or market control programs and related geopolitical events. In addition, the value of the Fund’s investments may be negatively affected by the occurrence of global events such as war, military conflict, acts of terrorism, social unrest, environmental disasters, natural disasters or events, recessions, supply chain disruptions, political instability, and infectious disease epidemics or pandemics. |
| • | Liquidity Risk — Certain securities may be difficult or impossible to sell at the time and the price that would normally prevail in the market. The portfolio manager may have to lower the price, sell other securities instead or forego an investment opportunity, any of which could have a negative effect on Fund management or performance. This includes the risk of missing out on an investment opportunity because the assets necessary to take advantage of it are tied up in less advantageous investments. If a Fund is required to sell securities quickly or at a particular time (including sales to meet redemption requests) the Fund could realize a loss. |
| • | Investment in Other Investment Companies Risk — Investments in other investment companies are subject to market and selection risk. In addition, if the Fund acquires shares of investments companies, shareholders bear both their proportionate share of expenses in the Fund (including management fees and other expenses) and, indirectly, the expenses of the investment companies. |
| • | Redemption Risk — The risk that heavy redemptions could cause the Fund to liquidate its assets at inopportune times or at a loss or depressed value, particularly during periods of declining or illiquid markets, and that could affect the fund’s ability to maintain a $1.00 share price. Redemption risk is greater to the extent that the fund has investors with large shareholdings, short investment horizons or unpredictable cash flow needs. The redemption by one or more large shareholders of their holdings in the fund could cause the remaining shareholders in the fund to lose money. |
| • | Floating Rate Notes Risk — Securities with floating or variable interest rates can be less sensitive to interest rate changes than securities with fixed interest rates, but may decline in value if their coupon rates do not reset as high, or as quickly, as comparable market interest rates, and generally carry lower yields than fixed notes of the same maturity. |
| • | Management Risk — There is no guarantee that the investment techniques and risk analyses used by the Fund’s portfolio managers will produce the desired results. |
| • | Regulatory Risk — The risk that a change in laws or regulations will materially affect a security, business, sector or market. A change in laws or regulations made by the government or a regulatory body can increase the costs of operating a business, reduce the attractiveness of investment and/or change the competitive landscape. Regulatory risk also includes the risk associated with federal and state laws which may restrict the remedies that a lender has when a borrower defaults on loans. These laws include restrictions on foreclosures, redemption rights after foreclosure, federal and state bankruptcy and debtor relief laws, restrictions on “due on sale” clauses, and state usury laws. |
To the extent that the Fund makes investments with additional risks, those risks could increase volatility or reduce performance. The Fund may trade securities actively, which could increase its transaction costs (thus lowering performance) and may increase the amount of taxes that you pay.
For more information about these risks, please refer to the section titled “Investment Practices and Risks” in the Fund’s prospectus.
| www.cavanalhillfunds.com | 3 | 1-800-762-7085 |
Performance Information
The bar chart and the performance table below illustrate some of the risks and return volatility of an investment in the Fund by showing changes in the Fund’s performance from year to year and by showing the Fund’s average annual returns for 1, 5 and 10 years. The Fund’s past performance does not necessarily indicate how the Fund will perform in the future. Updated performance information may be obtained on the Fund’s website www.cavanalhillfunds.com or by calling 1-800-762-7085.
This bar chart shows changes in the Fund’s performance from year to year1. The returns for Institutional and Select Shares will differ from the returns for Administrative Shares (which are shown in the bar chart) because of differences in the expenses of each Class.
Annual Total Returns for Administrative Shares and predecessor (Periods Ended 12/31)

| 1 | The performance information shown above is based on a calendar year. The Fund’s total return from 1/1/26 to 9/30/26 was [•]%. |
This table shows the Fund’s average annual total returns for periods ended December 31, 2025. The Select Shares commenced operations on December 26, 2017. The performance shown for periods prior to commencement of operations of the Select Shares is that of the Institutional Shares. The shares would have substantially similar performance because shares are invested in the same portfolio of securities. The performance shown is lower than actual returns would have been because the predecessor class had a higher expense ratio.
Average Annual Total Returns for Administrative, Institutional and Select Shares and predecessors.
(Periods Ended 12/31/2025)
| U.S. Treasury Fund | 1 Year | 5 Years | 10 Years | |
| Administrative Shares | [•]% | [•]% | [•]% | |
| Institutional Shares | [•]% | [•]% | [•]% | |
| Select Shares | [•]% | [•]% | [•]% |
Yield
The 7-day yield for the period ended 12/31/25 was [•]% for Administrative Shares; [•]% for Institutional Shares; and [•]% for Select Shares.
You may obtain the most current yield information for the Fund by calling (800) 762-7085.
Investment Adviser
Cavanal Hill® Investment Management, Inc. serves as the investment adviser for the Fund.
Purchase and Sale of Fund Shares
The following initial and additional purchase requirements apply:
| Initial Purchase | Additional Purchases | |
| Administrative Shares | $1,000 | None |
| Institutional Shares | $1,000 | None |
| Select Shares | $1,000,000 | None |
| www.cavanalhillfunds.com | 4 | 1-800-762-7085 |
Shares may be sold (redeemed) on any business day. You may sell by:
| • | Sending a written request by mail to the Funds Custodian: BOKF, NA, Attention: Cavanal Hill Funds, P.O. Box 182730, Columbus, Ohio 43218-2730. |
| • | Sending a written request by overnight mail to: Cavanal Hill Funds, c/o FIS Investor Services, LLC, 4249 Easton Way, Suite 400, Columbus, OH, 43219-6171. |
| • | Calling us at 1-800-762-7085 with instructions as to how you wish to complete the transaction (mail, wire, electronic transfer). |
Tax Information
The Fund’s distributions are generally taxable to you as ordinary income, capital gains, or a combination of the two, unless you are investing through a tax-deferred arrangement, such as a 401(k) plan or an individual retirement account. Retirement accounts may be taxed at a later date.
Payments to Broker-Dealers and Other Financial Intermediaries
If you purchase shares of the Fund through a broker-dealer or other financial intermediary (such as a bank), the Fund or its service providers may pay the intermediary for the sale of Fund shares and related services. These payments may create a conflict of interest by influencing the broker-dealer or other intermediary and your salesperson to recommend the Fund over another investment. Ask your salesperson or visit your financial intermediary’s website for more information. In addition, if you purchase shares that do not have any front-end sales charge, contingent deferred sales charge, or other asset-based fee for sales or distribution from a broker or other financial intermediary on an acting agency basis, you may be required to pay a commission in an amount charged and separately disclosed to you by such party.
| www.cavanalhillfunds.com | 5 | 1-800-762-7085 |
| GOVERNMENT SECURITIES MONEY MARKET FUND |
| SUMMARY |
Investment Objective
To seek current income with liquidity and stability of principal.
Fees and Expenses of the Fund
This table describes the fees and expenses that you may pay if you buy, hold and sell shares of the Government Securities Money Market Fund. An investor transacting in Institutional Shares, which do not have any front-end sales charge, contingent deferred sales charge, or other asset-based fee for sales or distribution, may be required to pay a commission to a broker or other financial intermediary for effecting such transactions on an agency basis. Such commissions are not reflected in the tables or the example below. Shares of the Fund are available in other share classes that have different fees and expenses.
Shareholder Fees (fees paid directly from your investment): None.
Annual Fund Operating Expenses (expenses that you pay each year as a percentage of the value of your investment). |
Administrative Shares |
Institutional Shares |
Select Shares |
Premier Shares |
| Management Fees | 0.05% | 0.05% | 0.05% | 0.05% |
| Distribution and/or Service (12b-1) Fees | 0.25% | — | — | 0.50% |
| Other Expenses | [•]% | [•]% | [•]% | [•]% |
| Shareholder Servicing Fees | 0.25% | 0.25% | 0.25% | 0.25% |
| Acquired Fund Fees and Expenses | [•]% | [•]% | [•]% | [•]% |
| Total Annual Fund Operating Expenses | [•]% | [•]% | [•]% | [•]% |
| Less Fee Waivers† | — | (0.17)% | (0.25)% | (0.25)% |
| Total Annual Fund Operating Expenses After Fee Waivers | [•]% | [•]% | [•]% | [•]% |
| † | Affiliates of the Adviser have contractually agreed to waive all Shareholder Servicing Fees to which they are entitled paid by Select and Premier Shares and 0.17% paid by Institutional Shares. The affiliate waivers result in a reduction of the Shareholder Servicing Fee paid by all purchasers of a Class to the extent shown in the table. Contractual waivers are in place for the period through December 31, 2027, and may only be terminated or modified with the approval of the Fund’s Board of Trustees. |
Example
This example is intended to help you compare the cost of investing in the Fund with the cost of investing in other mutual funds. The example assumes that you invest $10,000 in the Fund for the time periods indicated and then redeem all of your shares at the end of those periods. The example also assumes that your investment has a 5% return each year and that the Fund’s operating expenses remain the same. Although your actual costs may be higher or lower, based on these assumptions your costs would be:
| 1 Year | 3 Years | 5 Years | 10 Years | |
| Administrative Shares | $[•] | $[•] | $[•] | $[•] |
| Institutional Shares | $[•] | $[•] | $[•] | $[•] |
| Select Shares | $[•] | $[•] | $[•] | $[•] |
| Premier Shares | $[•] | $[•] | $[•] | $[•] |
Principal Investment Strategy
To pursue its objective, under normal circumstances, the Fund invests at least 99.5% of its total assets in cash, U.S. Government Securities, or repurchase agreements collateralized by U.S. Government Securities and other U.S. Government Security investment companies. The Fund also invests at least 80% of its net assets in U.S. Government Securities or repurchase agreements collateralized by U.S. Government Securities. These policies will not be changed without at least 60 days prior notice to shareholders.
The dollar-weighted average portfolio maturity of the Fund will not exceed 60 days and the dollar-weighted average portfolio life cannot exceed 120 days.
| www.cavanalhillfunds.com | 6 | 1-800-762-7085 |
Principal Investment Risks
You could lose money by investing in the Fund. Although the Fund seeks to preserve the value of your investment at $1.00 per share, it cannot guarantee it will do so. An investment in the Fund is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other government agency. The Fund’s sponsor has no legal obligation to provide financial support to the Funds, beyond what is disclosed in the footnote under the “Annual Fund Operating Expenses” table, and you should not expect that the sponsor will provide additional financial support to the Fund at any time. In addition, the principal risks of investing in the Fund, which could adversely affect the Fund’s net asset value, yield or total return are:
| • | Interest Rate Risk — The value of the Fund’s interest-bearing investments may decline due to an increase in interest rates. In general, the longer a security’s maturity, the greater the interest rate risk. For a portfolio with a duration of 3 years, each 1% rise in interest rates would reduce the value of the portfolio by an estimated 3%. The Fund’s yield may decrease due to a decline in interest rates. Very low or negative interest rates may magnify interest rate risk. Future declines in interest rate levels could cause the Fund’s earnings to fall below the Fund’s expense ratio, resulting in a negative yield and a decline in the Fund’s share price. Changing interest rates, including negative interest rates, may have unpredictable effects on markets, may result in heightened market volatility and may detract from Fund performance to the extent the Fund is exposed to such interest rates. |
| • | Market Risk — The value of the Fund’s assets will fluctuate as the markets in which the Fund invests fluctuate. The value of the Fund’s investments may decline, sometimes rapidly and unpredictably, simply because of economic changes or other events, such as inflation (or expectations for inflation), deflation (or expectations for deflation), interest rates, global demand for particular products or resources, market instability, debt crises and downgrades, embargoes, tariffs, sanctions and other trade barriers, regulatory events, other governmental trade or market control programs and related geopolitical events. In addition, the value of the Fund’s investments may be negatively affected by the occurrence of global events such as war, military conflict, acts of terrorism, social unrest, environmental disasters, natural disasters or events, recessions, supply chain disruptions, political instability, and infectious disease epidemics or pandemics. |
| • | Liquidity Risk — Certain securities may be difficult or impossible to sell at the time and the price that would normally prevail in the market. The portfolio manager may have to lower the price, sell other securities instead or forego an investment opportunity, any of which could have a negative effect on Fund management or performance. This includes the risk of missing out on an investment opportunity because the assets necessary to take advantage of it are tied up in less advantageous investments. If a Fund is required to sell securities quickly or at a particular time (including sales to meet redemption requests) the Fund could realize a loss. |
| • | Redemption Risk — The risk that heavy redemptions could cause the Fund to liquidate its assets at inopportune times or at a loss or depressed value, particularly during periods of declining or illiquid markets, and that could affect the fund’s ability to maintain a $1.00 share price. Redemption risk is greater to the extent that the fund has investors with large shareholdings, short investment horizons or unpredictable cash flow needs. The redemption by one or more large shareholders of their holdings in the fund could cause the remaining shareholders in the fund to lose money. |
| • | Floating Rate Notes Risk — Securities with floating or variable interest rates can be less sensitive to interest rate changes than securities with fixed interest rates, but may decline in value if their coupon rates do not reset as high, or as quickly, as comparable market interest rates, and generally carry lower yields than fixed notes of the same maturity. |
| • | Management Risk — There is no guarantee that the investment techniques and risk analyses used by the Fund’s portfolio managers will produce the desired results. |
| • | Regulatory Risk — The risk that a change in laws or regulations will materially affect a security, business, sector or market. A change in laws or regulations made by the government or a regulatory body can increase the costs of operating a business, reduce the attractiveness of investment and/or change the competitive landscape. Regulatory risk also includes the risk associated with federal and state laws which may restrict the remedies that a lender has when a borrower defaults on loans. These laws include restrictions on foreclosures, redemption rights after foreclosure, federal and state bankruptcy and debtor relief laws, restrictions on “due on sale” clauses, and state usury laws. |
| • | Investment in Other Investment Companies Risk — Investments in other investment companies are subject to market and selection risk. In addition, if the Fund acquires shares of investments companies, shareholders bear both their proportionate share of expenses in the Fund (including management fees and other expenses) and, indirectly, the expenses of the investment companies. |
To the extent that the Fund makes investments with additional risks, those risks could increase volatility or reduce performance. The Fund may trade securities actively, which could increase its transaction costs (thus lowering performance) and may increase the amount of taxes that you pay.
For more information about these risks, please refer to the section titled “Investment Practices and Risks” in the Fund’s prospectus.
| www.cavanalhillfunds.com | 7 | 1-800-762-7085 |
Performance Information
The bar chart and the performance table below illustrate some of the risks and return volatility of an investment in the Fund by showing changes in the Fund’s performance from year to year and by showing the Fund’s average annual returns for 1, 5 and 10 years. The Fund’s past performance does not necessarily indicate how the Fund will perform in the future. Updated performance information may be obtained on the Fund’s website www.cavanalhillfunds.com or by calling 1-800-762-7085.
This bar chart shows changes in the Fund’s performance from year to year1. The returns for Institutional, Select and Premier Shares will differ from the returns for Administrative Shares (which are shown in the bar chart) because of differences in the expenses of each Class.
Annual Total Returns for Administrative Shares and predecessor (Periods Ended 12/31)

| 1 | The performance information shown above is based on a calendar year. The Fund’s total return from 1/1/26 to 9/30/26 was [•]%. |
This table shows the Fund’s average annual total returns for periods ended December 31, 2025. The Select Shares commenced operations on September 15, 2016. The performance shown for periods prior to commencement of operations of the Select Shares is that of the Institutional Shares. The shares would have substantially similar performance because shares are invested in the same portfolio of securities. The performance shown is lower than actual returns would have been because the predecessor class had a higher expense ratio.
Average Annual Total Returns for Administrative, Institutional, Premier and Select Shares and predecessors.
(Periods Ended 12/31/2025)
| Government Securities Money Market Fund | 1 Year | 5 Years | 10 Years | |
| Administrative Shares | [•]% | [•]% | [•]% | |
| Institutional Shares | [•]% | [•]% | [•]% | |
| Premier Shares | [•]% | [•]% | [•]% | |
| Select Shares | [•]% | [•]% | [•]% |
Yield
The 7-day yield for the period ended 12/31/25 was [•]% for Administrative Shares; [•]% for Institutional Shares; [•]% for Premier Shares; and [•]% for Select Shares.
You may obtain the most current yield information for the Fund by calling (800) 762-7085.
Investment Adviser
Cavanal Hill® Investment Management, Inc. serves as the investment adviser for the Fund.
Purchase and Sale of Fund Shares
The following initial and additional purchase requirements apply:
| Initial Purchase | Additional Purchases | |
| Administrative Shares | $1,000 | None |
| Institutional Shares | $1,000 | None |
| Select Shares | $1,000,000 | None |
| Premier Shares | $1,000 | None |
| www.cavanalhillfunds.com | 8 | 1-800-762-7085 |
Shares may be purchased, sold (redeemed) or exchanged on any business day. You may sell by:
| • | Sending a written request by mail to the Funds Custodian: BOKF, NA, Attention: Cavanal Hill Funds, P.O. Box 182730, Columbus, Ohio 43218-2730. |
| • | Sending a written request by overnight mail to: Cavanal Hill Funds, c/o FIS Investor Services, LLC, 4249 Easton Way, Suite 400, Columbus, OH, 43219-6171. |
| • | Calling us at 1-800-762-7085 with instructions as to how you wish to complete the transaction (mail, wire, electronic transfer). |
Tax Information
The Fund’s distributions are generally taxable to you as ordinary income, capital gains, or a combination of the two, unless you are investing through a tax-deferred arrangement, such as a 401(k) plan or an individual retirement account. Retirement accounts may be taxed at a later date.
Payments to Broker-Dealers and Other Financial Intermediaries
If you purchase shares of the Fund through a broker-dealer or other financial intermediary (such as a bank), the Fund or its service providers may pay the intermediary for the sale of Fund shares and related services. These payments may create a conflict of interest by influencing the broker-dealer or other intermediary and your salesperson to recommend the Fund over another investment. Ask your salesperson or visit your financial intermediary’s website for more information. In addition, if you purchase shares that do not have any front-end sales charge, contingent deferred sales charge, or other asset-based fee for sales or distribution from a broker or other financial intermediary on an acting agency basis, you may be required to pay a commission in an amount charged and separately disclosed to you by such party.
| www.cavanalhillfunds.com | 9 | 1-800-762-7085 |
| LIMITED DURATION FUND |
| SUMMARY |
Investment Objective
Primarily to seek income and secondarily to seek capital appreciation.
Fees and Expenses of the Fund
This table describes the fees and expenses that you may pay if you buy, hold and sell shares of the Limited Duration Fund. You may qualify for sales charge discounts if you and your family invest or agree to invest in the future, at least $200,000 in Cavanal Hill Funds. More information about these and other discounts is available from your financial professional and in the section “Initial Sales Charge (Bond and Equity Funds, Class A Shares Only)” on page [•]of the prospectus and “Contingent Deferred Sales Charges (CDSC-Class A and C Only)” on page [•]in the prospectus and in the section “Additional Purchase and Redemption Information” on page [•]of the Statement of Additional Information. An investor transacting in Institutional Shares, which do not have any front-end sales charge, contingent deferred sales charge, or other asset-based fee for sales or distribution, may be required to pay a commission to a broker or other financial intermediary for effecting such transactions on an agency basis. Such commissions are not reflected in the tables or the example below. Shares of the Fund are available in other share classes that have different fees and expenses.
Shareholder Fees (fees paid directly from your investment) |
A Shares |
Investor Shares |
Institutional Shares |
| Maximum Sales Charge (Load) imposed on Purchases (as a percentage of offering price) | 2.00% | None | None |
Maximum Deferred Sales Charge (Load) (as a percentage of the lesser of original purchase price or redemption proceeds) |
1.00%* | None | None |
Annual Fund Operating Expenses (expenses that you pay each year as a percentage of the value of your investment). |
A |
Investor Shares |
Institutional Shares |
| Management Fees | 0.15% | 0.15% | 0.15% |
| Distribution and/or Service (12b-1) Fees | 0.25% | 0.25% | — |
| Other Expenses | [•]% | [•]% | [•]% |
| Shareholder Servicing Fees | 0.10% | 0.25% | 0.25% |
| Acquired Fund Fees and Expenses | [•]% | [•]% | [•]% |
| Total Annual Fund Operating Expenses | [•]% | [•]% | [•]% |
| Less Fee Waivers† | [•]% | [•]% | [•]% |
| Total Annual Fund Operating Expenses After Fee Waivers | [•]% | [•]% | [•]% |
| * | Class A Shares are available with no front-end sales charge on investments of $200,000 or more. There is, however, a contingent deferred sales charge (CDSC) of 1.00% on any Class A Shares upon which a dealer concession was paid that are sold within one year of purchase. |
| † | The Adviser has contractually agreed to waive fees payable to it or reimburse certain expenses so that expenses (other than extraordinary expenses and any Acquired Fund Fees and Expenses) for each Class do not exceed 0.50%, plus class-specific fees until December 31, 2027. Affiliates of the Adviser have contractually agreed to waive all Shareholder Servicing Fees to which they are entitled. The affiliate waivers result in a reduction of the Shareholder Servicing Fee paid by all purchasers of a Class to the extent shown in the table. Contractual waivers are in place for the period through December 31, 2027, and may only be terminated or modified with the approval of the Fund’s Board of Trustees. |
Example
This example is intended to help you compare the cost of investing in the Fund with the cost of investing in other mutual funds. The example assumes that you invest $10,000 in the Fund for the time periods indicated and then redeem all of your shares at the end of those periods. The example also assumes that your investment has a 5% return each year and that the Fund’s operating expenses remain the same. Although your actual costs may be higher or lower, based on these assumptions your costs would be:
| 1 Year | 3 Year | 5 Year | 10 Year | |
| A Shares | $[•] | $[•] | $[•] | $[•] |
| Investor Shares | $[•] | $[•] | $[•] | $[•] |
| Institutional Shares | $[•] | $[•] | $[•] | $[•] |
| www.cavanalhillfunds.com | 10 | 1-800-762-7085 |
Portfolio Turnover
The Limited Duration Fund pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover rate may indicate higher transaction costs and may result in higher taxes when Fund shares are held in a taxable account. These costs, which are not reflected in annual fund operating expenses or in the example, affect the Fund’s performance. During the most recent fiscal year, the Fund’s portfolio turnover rate was [•]% of the average value of its portfolio.
Principal Investment Strategy
To pursue its objective, under normal circumstances, the Fund invests primarily in debt obligations such as bonds, notes and debentures, and bills issued by U.S. corporations or by the U.S. government, its agencies or instrumentalities, municipal securities, mortgage-backed securities, asset-backed securities, and collateralized mortgage obligations and fixed income ETFs. Such debt obligations are “investment grade,” rated within the four highest ratings categories assigned by a nationally recognized statistical ratings organization or, if not rated, found by the Adviser under guidelines approved by the Trust’s Board of Trustees to be of comparable quality. The Fund also invests in money market instruments.
If the rating of a security is downgraded after purchase, the portfolio management team will determine whether it is in the best interest of the Fund’s shareholders to continue to hold the security. In making that determination, the factors considered at the time of purchase are reviewed. The Fund does not apply an automatic sale trigger.
In managing the portfolio, the portfolio management team searches for inefficiencies not only at the macro, or top down level, but also at the individual security level. Purchase and sale decisions are based on the Adviser’s judgment about issuers, risk, prices of securities, market conditions, potential returns, and other economic factors.
Under normal circumstances, the Fund invests at least 80% of its net assets in bonds and maintains an average portfolio duration of less than three and one-half years. These policies will not be changed without at least 60 days prior notice to shareholders. In addition, the Fund normally invests at least 65% of its net assets in interest-bearing bonds.
Duration provides a measure of a fund’s sensitivity to changes in interest-rates. In general, the longer a fund’s duration, the more its price will fluctuate when interest rates change. A fund with a duration of 10 years is twice as sensitive to interest rate changes as a fund with a five-year duration. A fund with a five-year duration would generally be expected to lose 5% from its net asset value if interest rates rose by one percentage point or gain 5% if interest rates fell by one percentage point.
Principal Investment Risks
Loss of money is a risk of investing in the Fund. In addition, the principal risks of investing in the Fund, which could adversely affect the Fund’s net asset value, yield or total return are:
| • | Interest Rate Risk — The value of the Fund’s interest-bearing investments may decline due to an increase in interest rates. In general, the longer a security’s maturity, the greater the interest rate risk. For a portfolio with a duration of 3 years, each 1% rise in interest rates would reduce the value of the portfolio by an estimated 3%. The Fund’s yield may decrease due to a decline in interest rates. Very low or negative interest rates may magnify interest rate risk. Future declines in interest rate levels could cause the Fund’s earnings to fall below the Fund’s expense ratio, resulting in a negative yield and a decline in the Fund’s share price. Changing interest rates, including negative interest rates, may have unpredictable effects on markets, may result in heightened market volatility and may detract from Fund performance to the extent the Fund is exposed to such interest rates. |
| • | Credit Risk — Credit risk is the possibility that the issuer of a debt instrument or a counterparty to an agreement fails to fulfill its obligations, reducing the Fund’s return. This includes failure by a bond issuer to repay interest and principal. |
| • | Liquidity Risk — Certain securities may be difficult or impossible to sell at the time and the price that would normally prevail in the market. The portfolio manager may have to lower the price, sell other securities instead or forego an investment opportunity, any of which could have a negative effect on Fund management or performance. This includes the risk of missing out on an investment opportunity because the assets necessary to take advantage of it are tied up in less advantageous investments. If a Fund is required to sell securities quickly or at a particular time (including sales to meet redemption requests) the Fund could realize a loss. |
| • | Prepayment/Call Risk — There is a chance that the repayment of an asset-backed or mortgage-backed obligation will occur sooner than expected. Call risk is the possibility that, during periods of falling interest rates, a bond issuer will “call” — or repay — its bond before the bond’s maturity date. |
| • | Market Risk — The value of the Fund’s assets will fluctuate as the markets in which the Fund invests fluctuate. The value of the Fund’s investments may decline, sometimes rapidly and unpredictably, simply because of economic changes or other events, such as inflation (or expectations for inflation), deflation (or expectations for deflation), interest rates, global demand for particular products or resources, market instability, debt crises and downgrades, embargoes, tariffs, sanctions and other trade barriers, regulatory events, other governmental trade or market control programs and related geopolitical events. In addition, the value of the Fund’s investments may be negatively affected by the occurrence of global events such as war, military conflict, acts of terrorism, social unrest, environmental disasters, natural disasters or events, recessions, supply chain disruptions, political instability, and infectious disease epidemics or pandemics. |
| www.cavanalhillfunds.com | 11 | 1-800-762-7085 |
| • | Mortgage-Backed Securities Risk — The value of the Fund’s mortgage-backed securities can fall if the owners of the underlying mortgages pay off their mortgages sooner than expected, which could happen when interest rates fall, or later than expected, which could happen when interest rates rise. If the underlying mortgages are paid off sooner than expected, the Fund may have to reinvest this money in mortgage-backed or other securities that have lower yields. |
| • | Collateralized Mortgage Obligations Risk — There are risks associated with collateralized mortgage obligations that relate to the risks of the underlying mortgage pass-through securities (i.e., an increase or decrease in prepayment rates, resulting from a decrease or increase in mortgage interest rates, will affect the yield, average life, and price of collateralized mortgage obligations). |
| • | Asset-Backed Securities Risk — Payment of interest and repayment of principal may be impacted by the cash flows generated by the assets backing asset-backed securities. The value of the Fund’s asset-backed securities may also be affected by changes in interest rates, the availability of information concerning the interests in and structure of the pools of purchase contracts, financing leases or sales agreements that are represented by these securities, the creditworthiness of the servicing agent for the pool, the originator of the loans or receivables, or the entities that provide any supporting letters of credit, surety bonds, or other credit enhancements. |
| • | Exchange Traded Fund (ETF) Risk — The ETFs in which the Fund invests are subject to the risks applicable to the types of securities and investments used by the ETFs. Because an ETF charges its own fees and expenses, fund shareholders will indirectly bear these costs. The use of leverage in an ETF can magnify any price movements, resulting in high volatility. Due to daily rebalancing, leverage, and liquidity, inverse ETFs may perform worse than the inverse movement of the underlying referenced financial asset, index or commodity’s return. |
| • | Valuation Risk — The risk associated with the assessment of appropriate pricing in a changing market where trading information may not be readily available. |
| • | Portfolio Turnover Risk — A Fund may engage in active and frequent trading to achieve its principal investment objectives. This may result in the realization and distribution to shareholders of higher capital gains as compared to a fund with less active trading policies, which would increase an investor’s tax liability unless shares are held through a tax deferred or exempt vehicle. Frequent trading also increases transaction costs, which could detract from a Fund’s performance. |
| • | Management Risk — There is no guarantee that the investment techniques and risk analyses used by the Fund’s portfolio managers will produce the desired results. |
| • | Regulatory Risk — The risk that a change in laws or regulations will materially affect a security, business, sector or market. A change in laws or regulations made by the government or a regulatory body can increase the costs of operating a business, reduce the attractiveness of investment and/or change the competitive landscape. Regulatory risk also includes the risk associated with federal and state laws which may restrict the remedies that a lender has when a borrower defaults on loans. These laws include restrictions on foreclosures, redemption rights after foreclosure, federal and state bankruptcy and debtor relief laws, restrictions on “due on sale” clauses, and state usury laws. |
To the extent that the Fund makes investments with additional risks, those risks could increase volatility or reduce performance. The Fund may trade securities actively, which could increase its transaction costs (thus lowering performance) and may increase the amount of taxes that you pay.
For more information about these risks, please refer to the section titled “Investment Practices and Risks” in the Fund’s prospectus. An investment in the Fund is not a deposit of any bank and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other government agency.
Performance Information
The bar chart and the performance table below illustrate some of the risks and return volatility of an investment in the Fund by showing changes in the Fund’s performance from year to year and by showing how the Fund’s average annual returns for 1, 5, and 10 years compare with those of a broad measure of market performance. The Fund’s past performance (before or after taxes) does not necessarily indicate how the Fund will perform in the future. Updated performance information may be obtained on the Fund’s website www.cavanalhillfunds.com or by calling 1-800-762-7085.
| www.cavanalhillfunds.com | 12 | 1-800-762-7085 |
This bar chart shows changes in the Fund’s performance from year to year1. The returns for A Shares and Institutional Shares will differ from the returns for Investor Shares (which are shown in the bar chart) because of differences in the expenses of each class.
Annual Total Returns for Investor Shares (Periods Ended 12/31)
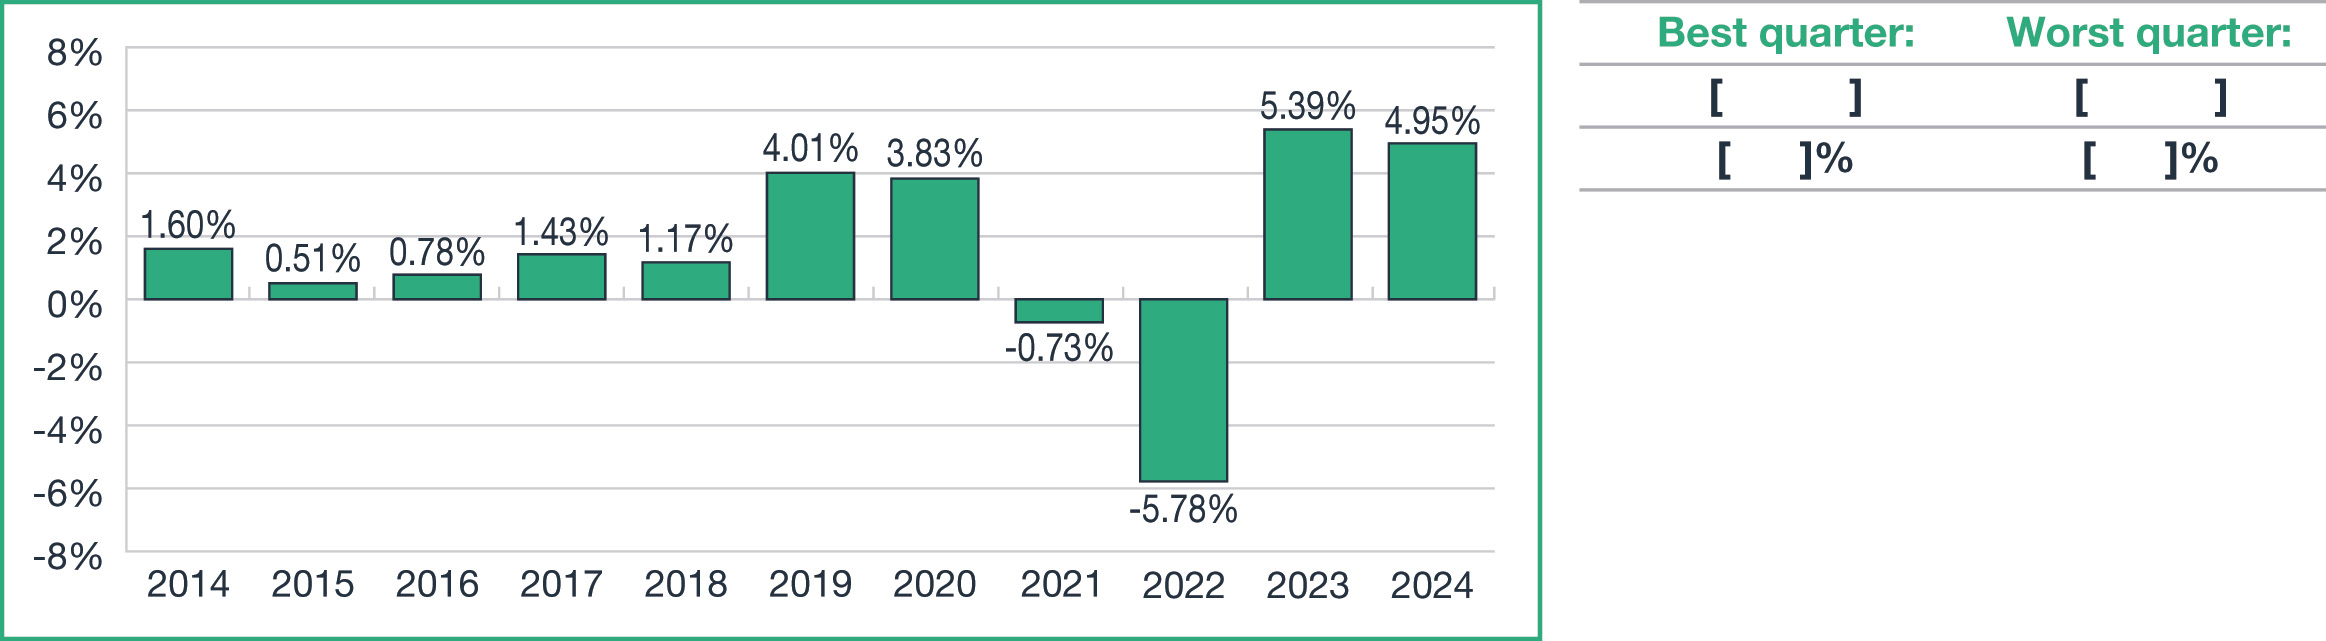
| 1 | The performance information shown above is based on a calendar year. The Fund’s total return from 1/1/26 to 9/30/26 was [•]%. |
This table compares the Fund’s average annual total returns for periods ended December 31, 2025, to those of the ICE BofA Merrill Lynch 1-5 Year U.S. Corporate/Government Index and the Bloomberg U.S. Aggregate Bond Index. The ICE BofA Merrill Lynch 1-5 Year U.S. Corporate/Government Bond Index demonstrates how the Fund’s performance compares with the returns of indices with similar investment objectives, whereas the Bloomberg U.S. Aggregate Bond Index is a broad-based index, which provides a benchmark reflecting the overall U.S. fixed income market. The stated returns assume the highest historical federal marginal income and capital gains tax rates. These after-tax returns do not reflect the effect of any applicable state and local taxes. Actual after-tax returns depend on an investor’s tax situation and may differ from those shown. After-tax returns are not relevant to investors holding shares through tax-deferred programs, such as IRA or 401(k) plans. After-tax returns are shown only for the Investor Shares and after-tax returns for other shares will vary.
| Average Annual Total Returns (Periods Ended 12/31/25) | 1 Year | 5 Years | 10 Years |
| Investor Shares | |||
| Return Before Taxes | [•]% | [•]% | [•]% |
| Return After Taxes on Distributions | [•]% | [•]% | [•]% |
| Return After Taxes on Distributions and Sale of Fund Shares | [•]% | [•]% | [•]% |
| Institutional Shares | |||
| Return Before Taxes | [•]% | [•]% | [•]% |
| A Shares | |||
| Return Before Taxes (With Load) | [•]% | [•]% | [•]% |
ICE BofA Merrill Lynch 1-5 Year U.S. Corporate/Government Index (reflects no deduction for expenses, fees or taxes) |
[•]% | [•]% | [•]% |
Bloomberg U.S. Aggregate Bond Index (reflects no deduction for expenses, fees or taxes) |
[•]% | [•]% | [•]% |
Investment Adviser
Cavanal Hill® Investment Management, Inc. serves as the investment adviser for the Fund.
Portfolio Managers
The following individuals are jointly and primarily responsible for the day-to-day management of the Fund’s portfolio:
Michael P. Maurer, CFA, is a Senior Vice President of Cavanal Hill Investment Management, Inc. and has been a portfolio manager of the Fund since 2003.
Chase McLean is an Assistant Vice President of Cavanal Hill Investment Management, Inc. and has been a portfolio manager of the Fund since December 28, 2025.
| www.cavanalhillfunds.com | 13 | 1-800-762-7085 |
Purchase and Sale of Fund Shares
The following initial and additional purchase requirements apply:
| Initial Purchase | Additional Purchases | |
| Bond and Equity Funds | ||
| A Shares | None | None |
| Investor Shares | $100 | None |
| Institutional Shares | $1,000 | None |
Shares may be purchased, sold (redeemed) or exchanged on any business day by:
| • | Sending a written request by mail to the Funds Custodian: BOKF, NA, Attention: Cavanal Hill Funds, P.O. Box 182730, Columbus, Ohio 43218-2730. |
| • | Sending a written request by overnight mail to: Cavanal Hill Funds, c/o FIS Investor Services, LLC, 4249 Easton Way, Suite 400, Columbus, OH, 43219-6171. |
| • | Calling us at 1-800-762-7085 with instructions as to how you wish to complete the transaction (mail, wire, electronic transfer). |
Tax Information
The Fund’s distributions are generally taxable to you as ordinary income, capital gains, or a combination of the two, unless you are investing through a tax-deferred arrangement, such as a 401(k) plan or an individual retirement account. Retirement accounts may be taxed at a later date.
Payments to Broker-Dealers and Other Financial Intermediaries
If you purchase shares of the Fund through a broker-dealer or other financial intermediary (such as a bank), the Fund or its service providers may pay the intermediary for the sale of Fund shares and related services. These payments may create a conflict of interest by influencing the broker-dealer or other intermediary and your salesperson to recommend the Fund over another investment. Ask your salesperson or visit your financial intermediary’s website for more information. In addition, if you purchase shares that do not have any front-end sales charge, contingent deferred sales charge, or other asset-based fee for sales or distribution from a broker or other financial intermediary on an acting agency basis, you may be required to pay a commission in an amount charged and separately disclosed to you by such party.
| www.cavanalhillfunds.com | 14 | 1-800-762-7085 |
| BOND FUND |
| SUMMARY |
Investment Objective
To seek total return.
Fees and Expenses of the Fund
This table describes the fees and expenses that you may pay if you buy, hold and sell shares of the Bond Fund. You may qualify for sales charge discounts if you and your family invest or agree to invest in the future, at least $200,000 in Cavanal Hill Funds. More information about these and other discounts is available from your financial professional and in the section “Initial Sales Charge (Bond and Equity Funds, Class A Shares Only)” on page [•]of the prospectus and “Contingent Deferred Sales Charges (CDSC-Class A and C Only)” on page [•]in the prospectus and in the section “Additional Purchase and Redemption Information” on page [•]of the Statement of Additional Information. An investor transacting in Institutional Shares, which do not have any front-end sales charge, contingent deferred sales charge, or other asset-based fee for sales or distribution, may be required to pay a commission to a broker or other financial intermediary for effecting such transactions on an agency basis. Such commissions are not reflected in the tables or the example below. Shares of the Fund are available in other share classes that have different fees and expenses.
Shareholder Fees (fees paid directly from your investment) |
A |
Investor Shares |
Institutional Shares |
| Maximum Sales Charge (Load) imposed on Purchases (as a percentage of offering price) | 2.00% | None | None |
Maximum Deferred Sales Charge (Load) (as a percentage of the lesser of original purchase price or redemption proceeds) |
1.00%* | None | None |
Annual Fund Operating Expenses (expenses that you pay each year as a percentage of the value of your investment). |
A |
Investor Shares |
Institutional Shares |
| Management Fees | 0.20% | 0.20% | 0.20% |
| Distribution and/or Service (12b-1) Fees | 0.25% | 0.25% | — |
| Other Expenses | [•]% | [•]% | [•]% |
| Shareholder Servicing Fees | 0.10% | 0.25% | 0.25% |
| Total Annual Fund Operating Expenses | [•]% | [•]% | [•]% |
| Less Fee Waivers† | [•]% | [•]% | [•]% |
| Total Annual Fund Operating Expenses After Fee Waivers | [•]% | [•]% | [•]% |
| * | Class A Shares are available with no front-end sales charge on investments of $200,000 or more. There is, however, a contingent deferred sales charge (CDSC) of 1.00% on any Class A Shares upon which a dealer concession was paid that are sold within one year of purchase. |
| † | Affiliates of the Adviser have contractually agreed to waive all Shareholder Servicing Fees to which they are entitled. The affiliate waivers result in a reduction of the Shareholder Servicing Fee paid by all purchasers of a Class to the extent shown in the table. Contractual waivers are in place for the period through December 31, 2027, and may only be terminated or modified with the approval of the Fund’s Board of Trustees. |
Example
This example is intended to help you compare the cost of investing in the Fund with the cost of investing in other mutual funds. The example assumes that you invest $10,000 in the Fund for the time periods indicated and then redeem all of your shares at the end of those periods. The example also assumes that your investment has a 5% return and each year that the Fund’s operating expenses remain the same. Although your actual costs may be higher or lower, based on these assumptions your costs would be:
| 1 Year | 3 Year | 5 Year | 10 Year | |
| A Shares | $[•] | $[•] | $[•] | $[•] |
| Investor Shares | $[•] | $[•] | $[•] | $[•] |
| Institutional Shares | $[•] | $[•] | $[•] | $[•] |
| www.cavanalhillfunds.com | 15 | 1-800-762-7085 |
Portfolio Turnover
The Bond Fund pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover rate may indicate higher transaction costs and may result in higher taxes when Fund shares are held in a taxable account. These costs, which are not reflected in annual fund operating expenses or in the example, affect the Fund’s performance. During the most recent fiscal year, the Fund’s portfolio turnover rate was [•]% of the average value of its portfolio.
Principal Investment Strategy
To pursue its objective, the Fund invests, under normal market conditions, primarily in debt obligations such as bonds, notes and debentures, and bills issued by U.S. corporations or by the U.S. government, its agencies, or instrumentalities, municipal securities, mortgage-backed securities, asset-backed securities, collateralized mortgage obligations and fixed income ETFs. Such debt obligations are “investment grade,” rated within the four highest ratings categories assigned by a nationally recognized statistical ratings organization, or, if not rated, found by the Adviser under guidelines approved by the Trust’s Board of Trustees to be of comparable quality. The Fund also invests in money market instruments.
Total return is defined as a percentage change, over a specified time period, in a mutual fund’s net asset value, with the ending net asset value adjusted to account for the reinvestment of all distributions of dividends and capital gains.
If the rating of a security is downgraded after purchase, the portfolio management team will determine whether it is in the best interest of the Fund’s shareholders to continue to hold the security. In making that determination, the factors considered at the time of purchase are reviewed. The Fund does not apply an automatic sale trigger.
The Fund will generally maintain a dollar-weighted average portfolio maturity of three to ten years.
In managing the portfolio, the portfolio management team searches for inefficiencies not only at the macro, or top down level, but also at the individual security level. Purchase and sale decisions are based on the Adviser’s judgment about issuers, risk, prices of securities, market conditions, potential returns, and other economic factors.
Under normal circumstances the Fund invests at least 80% of its net assets in bonds. This policy will not be changed without at least 60 days prior notice to shareholders.
Principal Investment Risks
Loss of money is a risk of investing in the Fund. In addition, the principal risks of investing in the Fund, which could adversely affect the Fund’s net asset value, yield or total return are:
| • | Interest Rate Risk — The value of the Fund’s interest-bearing investments may decline due to an increase in interest rates. In general, the longer a security’s maturity, the greater the interest rate risk. For a portfolio with a duration of 3 years, each 1% rise in interest rates would reduce the value of the portfolio by an estimated 3%. The Fund’s yield may decrease due to a decline in interest rates. Very low or negative interest rates may magnify interest rate risk. Future declines in interest rate levels could cause the Fund’s earnings to fall below the Fund’s expense ratio, resulting in a negative yield and a decline in the Fund’s share price. Changing interest rates, including negative interest rates, may have unpredictable effects on markets, may result in heightened market volatility and may detract from Fund performance to the extent the Fund is exposed to such interest rates. |
| • | Credit Risk — Credit risk is the possibility that the issuer of a debt instrument or a counterparty to an agreement fails to fulfill its obligations, reducing the Fund’s return. This includes failure by a bond issuer to repay interest and principal. |
| • | Liquidity Risk — Certain securities may be difficult or impossible to sell at the time and the price that would normally prevail in the market. The portfolio manager may have to lower the price, sell other securities instead or forego an investment opportunity, any of which could have a negative effect on Fund management or performance. This includes the risk of missing out on an investment opportunity because the assets necessary to take advantage of it are tied up in less advantageous investments. If a Fund is required to sell securities quickly or at a particular time (including sales to meet redemption requests) the Fund could realize a loss. |
| • | Prepayment/Call Risk — There is a chance that the repayment of an asset-backed or mortgage-backed obligation will occur sooner than expected. Call risk is the possibility that, during periods of falling interest rates, a bond issuer will “call” — or repay — its bond before the bond’s maturity date. |
| • | Market Risk — The value of the Fund’s assets will fluctuate as the markets in which the Fund invests fluctuate. The value of the Fund’s investments may decline, sometimes rapidly and unpredictably, simply because of economic changes or other events, such as inflation (or expectations for inflation), deflation (or expectations for deflation), interest rates, global demand for particular products or resources, market instability, debt crises and downgrades, embargoes, tariffs, sanctions and other trade barriers, regulatory events, other governmental trade or market control programs and related geopolitical events. In addition, the value of the Fund’s investments may be negatively affected by the occurrence of global events such as war, military conflict, acts of terrorism, social unrest, environmental disasters, natural disasters or events, recessions, supply chain disruptions, political instability, and infectious disease epidemics or pandemics. |
| www.cavanalhillfunds.com | 16 | 1-800-762-7085 |
| • | Mortgage-Backed Securities Risk — The value of the Fund’s mortgage-backed securities can fall if the owners of the underlying mortgages pay off their mortgages sooner than expected, which could happen when interest rates fall, or later than expected, which could happen when interest rates rise. If the underlying mortgages are paid off sooner than expected, the Fund may have to reinvest this money in mortgage-backed or other securities that have lower yields. |
| • | Collateralized Mortgage Obligations Risk — There are risks associated with collateralized mortgage obligations that relate to the risks of the underlying mortgage pass-through securities (i.e., an increase or decrease in prepayment rates, resulting from a decrease or increase in mortgage interest rates, will affect the yield, average life, and price of collateralized mortgage obligations). |
| • | Asset-Backed Securities Risk — Payment of interest and repayment of principal may be impacted by the cash flows generated by the assets backing asset-backed securities. The value of the Fund’s asset-backed securities may also be affected by changes in interest rates, the availability of information concerning the interests in and structure of the pools of purchase contracts, financing leases or sales agreements that are represented by these securities, the creditworthiness of the servicing agent for the pool, the originator of the loans or receivables, or the entities that provide any supporting letters of credit, surety bonds, or other credit enhancements. |
| • | Exchange Traded Fund (ETF) Risk — The ETFs in which the Fund invests are subject to the risks applicable to the types of securities and investments used by the ETFs. Because an ETF charges its own fees and expenses, fund shareholders will indirectly bear these costs. The use of leverage in an ETF can magnify any price movements, resulting in high volatility. Due to daily rebalancing, leverage, and liquidity, inverse ETFs may perform worse than the inverse movement of the underlying referenced financial asset, index or commodity’s return. |
| • | Valuation Risk — The risk associated with the assessment of appropriate pricing in a changing market where trading information may not be readily available. |
| • | Management Risk — There is no guarantee that the investment techniques and risk analyses used by the Fund’s portfolio managers will produce the desired results. |
| • | Regulatory Risk — The risk that a change in laws or regulations will materially affect a security, business, sector or market. A change in laws or regulations made by the government or a regulatory body can increase the costs of operating a business, reduce the attractiveness of investment and/or change the competitive landscape. Regulatory risk also includes the risk associated with federal and state laws which may restrict the remedies that a lender has when a borrower defaults on loans. These laws include restrictions on foreclosures, redemption rights after foreclosure, federal and state bankruptcy and debtor relief laws, restrictions on “due on sale” clauses, and state usury laws. |
To the extent that the Fund makes investments with additional risks, those risks could increase volatility or reduce performance. The Fund may trade securities actively, which could increase its transaction costs (thus lowering performance) and may increase the amount of taxes that you pay.
For more information about these risks, please refer to the section titled “Investment Practices and Risks” in the Fund’s prospectus. An investment in the Fund is not a deposit of any bank and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other government agency.
Performance Information
The bar chart and the performance table below illustrate some of the risks and return volatility of an investment in the Fund by showing changes in the Fund’s performance from year to year and by showing how the Fund’s average annual returns for 1, 5 and 10 years compare with those of a broad measure of market performance. The Fund’s past performance (before or after taxes) does not necessarily indicate how the Fund will perform in the future. Updated performance information may be obtained on the Fund’s website www.cavanalhillfunds.com or by calling 1-800-762-7085.
| www.cavanalhillfunds.com | 17 | 1-800-762-7085 |
This bar chart shows changes in the Fund’s performance from year to year1. The returns for A Shares and Institutional Shares will differ from the returns for Investor Shares (which are shown in the bar chart) because of differences in the expenses of each Class.
Annual Total Returns for Investor Shares (Periods Ended 12/31)

| 1 | The performance information shown above is based on a calendar year. The Fund’s total return from 1/1/26 to 9/30/26 was [•]%. |
This table compares the Fund’s average annual total returns for periods ended December 31, 2025, to those of the Bloomberg U.S. Aggregate Bond Index. The stated returns assume the highest historical federal marginal income and capital gains tax rates. These after-tax returns do not reflect the effect of any applicable state and local taxes. Actual after-tax returns depend on an investor’s tax situation and may differ from those shown. After-tax returns are not relevant to investors holding shares through tax-deferred programs, such as IRA or 401(k) plans. After-tax returns are shown only for the Investor Class Shares and after-tax returns for other shares will vary.
| Average Annual Total Returns (Periods Ended 12/31/24) | 1 Year | 5 Years | 10 Years | |
| Investor Shares | ||||
| Return Before Taxes | [•]% | [•]% | [•]% | |
| Return After Taxes on Distributions | [•]% | [•]% | [•]% | |
| Return After Taxes on Distributions and Sale of Fund Shares | [•]% | [•]% | [•]% | |
| Institutional Shares | ||||
| Return Before Taxes | [•]% | [•]% | [•]% | |
| A Shares | ||||
| Return Before Taxes (With Load) | [•]% | [•]% | [•]% | |
Bloomberg
U.S. Aggregate Bond Index |
[•]% | [•]% | [•]% | |
Investment Adviser
Cavanal Hill® Investment Management, Inc. serves as the investment adviser for the Fund.
Portfolio Managers
The following individuals are jointly and primarily responsible for the day-to-day management of the Fund’s portfolio:
Michael P. Maurer, CFA, is a Senior Vice President of Cavanal Hill Investment Management, Inc. and has been a portfolio manager of the Fund since 2003.
Chase McLean is an Assistant Vice President of Cavanal Hill Investment Management, Inc. and has been a portfolio manager of the Fund since December 28, 2025.
| www.cavanalhillfunds.com | 18 | 1-800-762-7085 |
Purchase and Sale of Fund Shares
The following initial and additional purchase requirements apply:
| Initial Purchase | Additional Purchases | |
| Bond and Equity Funds | ||
| A Shares | None | None |
| Investor Shares | $100 | None |
| Institutional Shares | $1,000 | None |
Shares may be purchased, sold (redeemed) or exchanged on any business day by:
| • | Sending a written request by mail to the Funds Custodian: BOKF, NA, Attention: Cavanal Hill Funds, P.O. Box 182730, Columbus, Ohio 43218-2730. |
| • | Sending a written request by overnight mail to: Cavanal Hill Funds, c/o FIS Investor Services, LLC, 4249 Easton Way, Suite 400, Columbus, OH, 43219-6171. |
| • | Calling us at 1-800-762-7085 with instructions as to how you wish to complete the transaction (mail, wire, electronic transfer). |
Tax Information
The Fund’s distributions are generally taxable to you as ordinary income, capital gains, or a combination of the two, unless you are investing through a tax-deferred arrangement, such as a 401(k) plan or an individual retirement account. Retirement accounts may be taxed at a later date.
Payments to Broker-Dealers and Other Financial Intermediaries
If you purchase shares of the Fund through a broker-dealer or other financial intermediary (such as a bank), the Fund or its service providers may pay the intermediary for the sale of Fund shares and related services. These payments may create a conflict of interest by influencing the broker-dealer or other intermediary and your salesperson to recommend the Fund over another investment. Ask your salesperson or visit your financial intermediary’s website for more information. In addition, if you purchase shares that do not have any front-end sales charge, contingent deferred sales charge, or other asset-based fee for sales or distribution from a broker or other financial intermediary on an acting agency basis, you may be required to pay a commission in an amount charged and separately disclosed to you by such party.
| www.cavanalhillfunds.com | 19 | 1-800-762-7085 |
| STRATEGIC ENHANCED YIELD FUND |
| SUMMARY |
Investment Objective
To primarily seek current income and, secondarily, the opportunity for capital appreciation to produce total return.
Fees and Expenses of the Fund
This table describes the fees and expenses that you may pay if you buy, hold and sell shares of the Strategic Enhanced Yield Fund. You may qualify for sales charge discounts if you and your family invest or agree to invest in the future, at least $200,000 in Cavanal Hill Funds. More information about these and other discounts is available from your financial professional and in the section “Initial Sales Charge (Bond and Equity Funds, Class A Shares Only)” on page [•]of the prospectus and “Contingent Deferred Sales Charges (CDSC-Class A and C Only)” on page [•]in the prospectus and in the section “Additional Purchase and Redemption Information” on page [•]of the Statement of Additional Information. An investor transacting in Institutional Shares, which do not have any front-end sales charge, contingent deferred sales charge, or other asset-based fee for sales or distribution, may be required to pay a commission to a broker or other financial intermediary for effecting such transactions on an agency basis. Such commissions are not reflected in the tables or the example below. Shares of the Fund are available in other share classes that have different fees and expenses.
| Shareholder
Fees (fees paid directly from your investment) |
A Shares |
Investor Shares | Institutional Shares |
| Maximum Sales Charge (Load) imposed on Purchases (as a percentage of offering price) | 2.00% | None | None |
Maximum Deferred Sales Charge (Load) (as a percentage of the lesser of original purchase price or redemption proceeds) |
1.00%* | None | None |
Annual Fund Operating Expenses (expenses that you pay each year as a percentage of the value of your investment). |
A Shares |
Investor Shares | Institutional Shares |
| Management Fees | 0.50% | 0.50% | 0.50% |
| Distribution and/or Service (12b-1) Fees | 0.25% | 0.25% | — |
| Other expenses | [•]% | [•]% | [•]% |
| Shareholder Servicing Fees | 0.10% | 0.25% | 0.25% |
| Acquired Fund Fees and Expenses | [•] | [•] | [•] |
| Total Annual Fund Operating Expenses | [•]% | [•]% | [•]% |
| Less Fee Waivers† | [•]% | [•]% | [•]% |
| Total Annual Fund Operating Expenses After Fee Waivers | [•]% | [•]% | [•]% |
| * | Class A Shares are available with no front-end sales charge on investments of $200,000 or more. There is, however, a contingent deferred sales charge (CDSC) of 1.00% on any Class A Shares upon which a dealer concession was paid that are sold within one year of purchase. |
| † | The Adviser has contractually agreed to waive fees payable to it or reimburse certain expenses so that expenses (other than extraordinary expenses and any Acquired Fund Fees and Expenses) for each Class do not exceed 0.76%, plus class-specific fees, until December 31, 2027. Affiliates of the Adviser have contractually agreed to waive all Shareholder Servicing Fees to which they are entitled. The affiliate waivers result in a reduction of the Shareholder Servicing Fee paid by all purchasers of a Class to the extent shown in the table. Contractual waivers are in place for the period through December 31, 2027, and may only be terminated or modified with the approval of the Fund’s Board of Trustees. |
Example
This example is intended to help you compare the cost of investing in the Fund with the cost of investing in other mutual funds. The example assumes that you invest $10,000 in the Fund for the time periods indicated and then redeem all of your shares at the end of those periods. The example also assumes that your investment has a 5% return each year and that the Fund’s operating expenses remain the same. Although your actual costs may be higher or lower, based on these assumptions your costs would be:
| 1 Year | 3 Year | 5 Year | 10 Year | |
| A Shares | $[•] | $[•] | $1, [•] | $[•] |
| Investor Shares | $[•] | $[•] | $[•] | $[•] |
| Institutional Shares | $[•] | $[•] | $[•] | $[•] |
| www.cavanalhillfunds.com | 20 | 1-800-762-7085 |
Portfolio Turnover
The Strategic Enhanced Yield Fund pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover rate may indicate higher transaction costs and may result in higher taxes when Fund shares are held in a taxable account. These costs, which are not reflected in annual fund operating expenses or in the example, affect the Fund’s performance. During the most recent fiscal year, the Fund’s portfolio turnover rate was [•]% of the average value of its portfolio.
Principal Investment Strategy
The Fund seeks to achieve its investment objective by investing in a diversified portfolio of fixed income instruments of varying maturities. In an effort to actively enhance total return and minimize risk, the Fund will engage in opportunistic trading among various sectors based on the perceived market anomalies and inefficiencies detected by the Fund’s portfolio managers, which may be found in illiquid or thinly traded securities and those that may not accurately reflect relevant market information. Total return is defined as a percentage change, over a specified time period, in a mutual fund’s net asset value, with the ending net asset value adjusted to account for the reinvestment of all distributions of dividends and capital gains.
Under normal circumstances, the Fund invests at least 80% of its net assets in fixed income instruments, both domestic and foreign. This investment policy will not be changed by the Fund without at least 60 days’ prior notice to shareholders. The principal “Fixed income instruments” that the Fund invests in are securities issued or guaranteed by the U.S. Government and its agencies and instrumentalities, U.S. corporate bonds, global corporate bonds and sovereign bonds denominated in U.S. and non-U.S. dollars, mortgage-backed securities, asset-backed securities, municipal securities, and privately-issued securities that may be resold only in accordance with Rule 144A or Regulation S under the Securities Act of 1933 (the “1933 Act”). Privately issued securities are those securities that are exempt from registration under the 1933 Act and that may be resold only in accordance with Rule 144A, which allows for the private resale of securities to qualified institutional buyers, and Regulation S, which allows for the private sale of securities outside the U.S. The mortgage-backed securities in which the Fund invests are fixed rate mortgage-backed securities backed by Fannie Mae, Freddie Mac, and Ginnie Mae.
The Fund may also invest in securities listed, traded or dealt in foreign countries, including emerging markets countries. Such securities may be denominated in foreign currencies and include sovereign, supra-national and quasi-sovereign bonds and debt instruments. There is no limit on the foreign issuers in which the Fund can invest, provided that the Fund will not invest in any foreign issuer or country in which investment is prohibited by law. The Fund will consider an issuer to be doing a substantial amount of business outside the U.S. if it derives more than 50% of its assets, revenue or income outside of the U.S. The Fund may also invest in preferred stock. The Fund may invest in U.S. Treasury futures for hedging purposes. U.S. Treasury futures with economic characteristics similar to fixed income instruments will be included as investments that satisfy the Fund’s 80% policy discussed above.
“Investment-grade” securities are securities that are rated by at least one major rating agency in one of its top four rating categories, meaning those securities that have a rating of Baa3 by Moody’s, BBB- by S&P or BBB- by Fitch Ratings Ltd., or, if unrated, that are determined by the Adviser to be of similar quality, at the time of purchase. The Fund will seek to enhance yield by investing up to a combined 60% of its assets in fixed income securities rated below investment grade (also known as “high yield securities” or “junk bonds”), emerging market debt securities, including both sovereign and corporate issuers, and securities denominated in foreign currencies.
The Adviser expects that the Fund’s average duration will range between 20% shorter and 20% longer than that of the Bloomberg US Aggregate Index. For example, on October 31, 2026, the duration was [•] years, meaning the Fund’s average duration would range between [•] years (20% shorter than the Bloomberg US Aggregate Index) and [•] years (20% longer than the Bloomberg US Aggregate Index). Duration provides a measure of a fund’s sensitivity to changes in interest-rates. In general, the longer a fund’s duration, the more its price will fluctuate when interest rates change. A fund with a duration of 10 years is twice as sensitive to interest rate changes as a fund with a five-year duration. A fund with a five-year duration would generally be expected to lose 5% from its net asset value if interest rates rose by one percentage point or gain 5% if interest rates fell by one percentage point.
In selecting fixed income instruments for the Fund, the Adviser actively monitors potential investment opportunities throughout the world and bases its purchase and sale decisions on a fundamental analysis of global economic trends and underlying global economic fundamentals.
| www.cavanalhillfunds.com | 21 | 1-800-762-7085 |
Principal Investment Risks
Loss of money is a risk of investing in the Fund. In addition, the principal risks of investing in the Fund, which could adversely affect the Fund’s net asset value, yield or total return are:
| • | Credit Risk — Credit risk is the possibility that the issuer of a debt instrument or a counterparty to an agreement fails to fulfil its obligations, reducing the Fund’s return. This includes failure by a bond issuer to repay interest and principal. |
| • | Market Risk — The value of the Fund’s assets will fluctuate as the markets in which the Fund invests fluctuate. The value of the Fund’s investments may decline, sometimes rapidly and unpredictably, simply because of economic changes or other events, such as inflation (or expectations for inflation), deflation (or expectations for deflation), interest rates, global demand for particular products or resources, market instability, debt crises and downgrades, embargoes, tariffs, sanctions and other trade barriers, regulatory events, other governmental trade or market control programs and related geopolitical events. In addition, the value of the Fund’s investments may be negatively affected by the occurrence of global events such as war, military conflict, acts of terrorism, social unrest, environmental disasters, natural disasters or events, recessions, supply chain disruptions, political instability, and infectious disease epidemics or pandemics. |
| • | Liquidity Risk — Certain securities may be difficult or impossible to sell at the time and the price that would normally prevail in the market. The portfolio manager may have to lower the price, sell other securities instead or forego an investment opportunity, any of which could have a negative effect on Fund management or performance. This includes the risk of missing out on an investment opportunity because the assets necessary to take advantage of it are tied up in less advantageous investments. If a Fund is required to sell securities quickly or at a particular time (including sales to meet redemption requests) the Fund could realize a loss. |
| • | Interest Rate Risk — The value of the Fund’s interest-bearing investments may decline due to an increase in interest rates. In general, the longer a security’s maturity, the greater the interest rate risk. For a portfolio with a duration of 3 years, each 1% rise in interest rates would reduce the value of the portfolio by an estimated 3%. The Fund’s yield may decrease due to a decline in interest rates. Very low or negative interest rates may magnify interest rate risk. Future declines in interest rate levels could cause the Fund’s earnings to fall below the Fund’s expense ratio, resulting in a negative yield and a decline in the Fund’s share price. Changing interest rates, including negative interest rates, may have unpredictable effects on markets, may result in heightened market volatility and may detract from Fund performance to the extent the Fund is exposed to such interest rates. |
| • | Foreign Investment Risk — The risk associated with higher transaction costs, delayed settlements, currency controls or adverse economic and political developments. This also includes the risk that fluctuations in the exchange rates between the U.S. dollar and foreign currencies may negatively affect an investment. Exchange rate volatility may affect the ability of an issuer to repay U.S. dollar denominated debt, thereby increasing credit risk. Foreign securities may also be affected by incomplete or inaccurate financial information on companies. There is a risk of loss attributable to social upheavals, unfavorable governmental or political actions, seizure of foreign deposits, changes in tax or trade statutes, and governmental collapse and war. These risks are more significant in emerging markets. |
| • | Valuation Risk — The risk associated with the assessment of appropriate pricing in a changing market where trading information may not be readily available. |
| • | Non-U.S. Denominated Currency Risk — Sovereign debt instruments are subject to the risk that a governmental entity may delay or refuse to pay interest or repay principal on its sovereign debt, due, for example, to cash flow problems, insufficient foreign currency reserves, political considerations, the relative size of the governmental entity’s debt position in relation to the economy or the failure to put in place economic reforms required by the International Monetary Fund or other multilateral agencies. |
| • | Emerging Market Risk — Risks associated with investing in emerging market securities include potentially restrictive political and economic structures and abrupt changes to those structures, changes in price visibility and liquidity in markets and securities, fluctuations in currency exchange rates, volatility in interest rates, and sudden changes in tax policy. |
| • | Prepayment/Call Risk — There is a chance that the repayment of an asset-backed or mortgage-backed obligation will occur sooner than expected. Call risk is the possibility that, during periods of falling interest rates, a bond issuer will “call” — or repay — its bond before the bond’s maturity date. |
| • | High Yield Securities Risk — Fixed income securities rated below investment grade and unrated securities of similar credit quality (commonly referred to as “junk bonds” or high yield securities) are regarded as being predominantly speculative as to the issuer’s ability to make payments of principal and interest. Investments in such securities involves substantial risk. Issuers of high yield securities may be highly leveraged and may not have available to them more traditional methods of financing. Therefore, the risks associated with acquiring the securities of such issuers generally are greater than is the case with investment grade securities. The value of high yield securities tends to be very volatile due to such factors as specific corporate developments, interest rate sensitivity, less secondary market activity, and negative perceptions of high yield securities and the junk bond markets generally, particularly in times of market stress. |
| www.cavanalhillfunds.com | 22 | 1-800-762-7085 |
| • | Mortgage-Backed Securities Risk — The value of the Fund’s mortgage-backed securities can fall if the owners of the underlying mortgages pay off their mortgages sooner than expected, which could happen when interest rates fall, or later than expected, which could happen when interest rates rise. If the underlying mortgages are paid off sooner than expected, the Fund may have to reinvest this money in mortgage-backed or other securities that have lower yields. |
| • | Asset-Backed Securities Risk — Payment of interest and repayment of principal may be impacted by the cash flows generated by the assets backing asset-backed securities. The value of the Fund’s asset-backed securities may also be affected by changes in interest rates, the availability of information concerning the interests in and structure of the pools of purchase contracts, financing leases or sales agreements that are represented by these securities, the creditworthiness of the servicing agent for the pool, the originator of the loans or receivables, or the entities that provide any supporting letters of credit, surety bonds, or other credit enhancements. |
| • | Derivative Risk — The risk of investing in derivative instruments, including liquidity, interest rate, market, credit and management risks, mispricing or improper valuation. Changes in the value of a derivative may not correlate perfectly with the underlying asset, rate or index, and the Fund could lose more than the principal amount invested. |
| • | Leverage Risk — The risk associated with securities or practices that multiply small index or market movements into large changes in value. Leverage is often associated with investments in derivatives, but also may be embedded directly in the characteristics of other securities. Leverage risk is hedged when a derivative (a security whose value is based on another security or index) is used as a hedge against an opposite position that a Fund also holds, any loss generated by the derivative should be substantially offset by gains on the hedged investment, and vice versa. Hedges are sometimes subject to imperfect matching between the derivative and underlying security, and there can be no assurance that a Fund’s hedging transactions will be effective. |
| • | Private/Restricted Securities Risk — The Fund can invest in private placements and restricted securities. Such investments involve a high degree of business and financial risk and can result in substantial or complete losses. Competition among private funds can be intense and there is no assurance that the marketing efforts of any particular portfolio company will be successful or that its business will succeed. Additionally, privately held companies are not subject to Securities and Exchange Commission reporting requirements, are not required to maintain their accounting records in accordance with generally accepted accounting principles, and are not required to maintain effective internal controls over financial reporting. As a result, timely or accurate information may at times not be readily available about the business, financial condition and results of operations of the privately held companies in which the Fund invests. |
| • | Redemption Risk — The risk that heavy redemptions could cause the Fund to liquidate its assets at inopportune times or at a loss or depressed value, particularly during periods of declining or illiquid markets, and that could affect the fund’s ability to maintain a $1.00 share price. Redemption risk is greater to the extent that the fund has investors with large shareholdings, short investment horizons or unpredictable cash flow needs. The redemption by one or more large shareholders of their holdings in the fund could cause the remaining shareholders in the fund to lose money. |
| • | Floating Rate Notes Risk — Securities with floating or variable interest rates can be less sensitive to interest rate changes than securities with fixed interest rates, but may decline in value if their coupon rates do not reset as high, or as quickly, as comparable market interest rates, and generally carry lower yields than fixed notes of the same maturity. |
| • | Hedging Risk — Hedging may not be effective based on timing, the underlying instrument hedged, or duration of the hedge. |
| • | Management Risk — There is no guarantee that the investment techniques and risk analyses used by the Fund’s portfolio managers will produce the desired results. |
| • | Regulatory Risk — The risk that a change in laws or regulations will materially affect a security, business, sector or market. A change in laws or regulations made by the government or a regulatory body can increase the costs of operating a business, reduce the attractiveness of investment and/or change the competitive landscape. Regulatory risk also includes the risk associated with federal and state laws which may restrict the remedies that a lender has when a borrower defaults on loans. These laws include restrictions on foreclosures, redemption rights after foreclosure, federal and state bankruptcy and debtor relief laws, restrictions on “due on sale” clauses, and state usury laws. |
To the extent that the Fund makes investments with additional risks, those risks could increase volatility or reduce performance. The Fund may trade securities actively, which could increase its transaction costs (thus lowering performance) and may increase the amount of taxes that you pay. For more information about these risks, please refer to the section titled “Investment Practices and Risks” in the Fund’s prospectus. An investment in the Fund is not a deposit of any bank and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other government agency.
| www.cavanalhillfunds.com | 23 | 1-800-762-7085 |
Performance Information
The bar chart and the performance table below illustrate some of the risks and return volatility of an investment in the Fund by showing changes in the Fund’s performance from year to year and by showing how the Fund’s average annual returns for 1 and 5 years and since inception compare with those of a broad measure of market performance. The Fund’s past performance (before or after taxes) does not necessarily indicate how the Fund will perform in the future. Updated performance information may be obtained on the Fund’s website www.cavanalhillfunds.com or by calling 1-800-762-7085.
This bar chart shows changes in the Fund’s performance from year to year1. The returns for A Shares and Institutional Shares will differ from the returns for Investor Shares (which are shown in the bar chart) because of differences in the expenses of each Class.
Annual Total Returns for Investor Shares (Periods Ended 12/31)

| 1 | The performance information shown above is based on a calendar year. The Fund’s total return from 1/1/26 to 9/30/26 was [•]%. |
This table compares the Fund’s average annual total returns for periods ended December 31, 2025, to those of the Bloomberg U.S. Aggregate Bond Index. The stated returns assume the highest historical federal marginal income and capital gains tax rates. These after-tax returns do not reflect the effect of any applicable state and local taxes. Actual after-tax returns depend on an investor’s tax situation and may differ from those shown. After-tax returns are not relevant to investors holding shares through tax-deferred programs, such as IRA or 401(k) plans. After-tax returns are shown only for the Investor Class Shares and after-tax returns for other shares will vary.
| Average Annual Total Returns (Periods Ended 12/31/25) | 1 Year | 5 Years | Since Inception (12/26/2017) | |
| Investor Shares | ||||
| Return Before Taxes | [•]% | [•]% | [•]% | |
| Return After Taxes on Distributions | [•]% | [•]% | [•]% | |
| Return After Taxes on Distributions and Sale of Fund Shares | [•]% | [•]% | [•]% | |
| Institutional Shares | ||||
| Return Before Taxes | [•]% | [•]% | [•]% | |
| A Shares | ||||
| Return Before Taxes (With Load) | [•]% | [•]% | [•]% | |
| Bloomberg U.S. Aggregate Bond Index (reflects no deduction for expenses, fees or taxes) |
[•]% | [•]% | [•]% | |
Investment Adviser
Cavanal Hill® Investment Management, Inc. serves as the investment adviser for the Fund. LM Capital Group, LLC serves as the investment sub-adviser for the Fund.
Portfolio Managers
The following individuals are jointly and primarily responsible for the day-to-day management of the Fund’s portfolio:
Luis Maizel is a Sr. Managing Director for LM Capital Group, LLC and has been a Portfolio Manager of the Fund since 2022. Michael Chalker is a Portfolio Manager for LM Capital Group, LLC and has been a Portfolio Manager of the Fund since 2022.
Mario Modiano is a Portfolio Manager for LM Capital Group, LLC and has been a Portfolio Manager of the Fund since 2026.
| www.cavanalhillfunds.com | 24 | 1-800-762-7085 |
Purchase and Sale of Fund Shares
The following initial and additional purchase requirements apply:
| Initial Purchase | Additional Purchases | |
| Bond and Equity Funds | ||
| A Shares | None | None |
| Investor Shares | $100 | None |
| Institutional Shares | $1,000 | None |
Shares may be purchased, sold (redeemed) or exchanged on any business day by:
| • | Sending a written request by mail to the Funds Custodian: BOKF, NA, Attention: Cavanal Hill Funds, P.O. Box 182730, Columbus, Ohio 43218-2730. |
| • | Sending a written request by overnight mail to: Cavanal Hill Funds, c/o FIS Investor Services, LLC, 4249 Easton Way, Suite 400, Columbus, OH, 43219-6171. |
| • | Calling us at 1-800-762-7085 with instructions as to how you wish to complete the transaction (mail, wire, electronic transfer). |
Tax Information
The Fund’s distributions are generally taxable to you as ordinary income, capital gains, or a combination of the two, unless you are investing through a tax-deferred arrangement, such as a 401(k) plan or an individual retirement account. Retirement accounts may be taxed at a later date.
Payments to Broker-Dealers and Other Financial Intermediaries
If you purchase shares of the Fund through a broker-dealer or other financial intermediary (such as a bank), the Fund or its service providers may pay the intermediary for the sale of Fund shares and related services. These payments may create a conflict of interest by influencing the broker-dealer or other intermediary and your salesperson to recommend the Fund over another investment. Ask your salesperson or visit your financial intermediary’s website for more information. In addition, if you purchase shares that do not have any front-end sales charge, contingent deferred sales charge, or other asset-based fee for sales or distribution from a broker or other financial intermediary on an acting agency basis, you may be required to pay a commission in an amount charged and separately disclosed to you by such party.
| www.cavanalhillfunds.com | 25 | 1-800-762-7085 |
| WORLD ENERGY & POWER FUND |
| SUMMARY |
Investment Objective
To seek growth and income.
Fees and Expenses of the Fund
This table describes the fees and expenses that you may pay if you buy, hold and sell shares of the World Energy & Power Fund. You may qualify for sales charge discounts if you and your family invest or agree to invest in the future, at least $200,000 in Cavanal Hill Funds. More information on these and other discounts is available from your financial professional and in the section “Initial Sales Charge (Bond and Equity Funds, Class A Shares Only)” on page [•] of the prospectus and “Contingent Deferred Sales Charges (CDSC-Class A and C Only)” on page [•] in the prospectus and in the section “Additional Purchase and Redemption Information” on page [•] of the Statement of Additional Information. An investor transacting in Institutional Shares, which do not have any front-end sales charge, contingent deferred sales charge, or other asset-based fee for sales or distribution, may be required to pay a commission to a broker or other financial intermediary for effecting such transactions on an agency basis. Such commissions are not reflected in the tables or the example below. Shares of the Fund are available in other share classes that have different fees and expenses.
Shareholder Fees (fees paid directly from your investment) |
A
Shares |
C
Shares |
Investor Shares |
Institutional Shares |
| Maximum Sales Charge (Load) imposed on Purchases (as a percentage of offering price) | 2.00% | None | None | None |
Maximum Deferred Sales Charge (Load) (as a percentage of the lesser of original purchase price or redemption proceeds) |
1.00%* | 1.00%* | None | None |
Annual Fund Operating Expenses (expenses that you pay each year as a percentage of the value of your investment). |
A Shares |
C Shares |
Investor Shares |
Institutional Shares |
| Management Fees | 0.60% | 0.60% | 0.60% | 0.60% |
| Distribution and/or Service (12b-1) Fees | 0.25% | 1.00% | 0.25% | — |
| Other Expenses | [•]% | [•]% | [•]% | [•]% |
| Shareholder Servicing Fees | 0.10% | 0.25% | 0.25% | 0.25% |
| Acquired Fund Fees and Expenses | [•]% | [•]% | [•]% | [•]% |
| Total Annual Fund Operating Expenses | [•]% | [•]% | [•]% | [•]% |
| Less Fee Waivers† | ([•])% | ([•])% | ([•])% | ([•])% |
| Total Annual Fund Operating Expenses After Fee Waivers | [•]% | [•]% | [•]% | [•]% |
* Class A Shares are available with no front-end sales charge on investments of $200,000 or more. There is, however, a contingent deferred sales charge (CDSC) of 1.00% on any Class A Shares upon which a dealer concession was paid that are sold within one year of purchase. In addition, while C Shares are offered at NAV, without any initial sales charge, a 1.00% CDSC may be charged on any C Shares upon which a dealer concession has been paid that are sold within one year of purchase.
† The Adviser has contractually agreed to waive fees payable to it or reimburse certain expenses so that expenses (other than extraordinary expenses and any Acquired Fund Fees and Expenses) for each Class do not exceed 0.90%, plus class-specific fees until December 31, 2027. Affiliates of the Adviser have contractually agreed to waive all Shareholder Servicing Fees to which they are entitled. The affiliate waivers result in a reduction of the Shareholder Servicing Fee paid by all purchasers of a Class to the extent shown in the table. Contractual waivers are in place for the period through December 31, 2027, and may only be terminated or modified with the approval of the Fund’s Board of Trustees.
Example
This example is intended to help you compare the cost of investing in the Fund with the cost of investing in other mutual funds. The example assumes that you invest $10,000 in the Fund for the time periods indicated and then redeem all of your shares at the end of those periods. The example also assumes that your investment has a 5% return each year and that the Fund’s operating expenses remain the same. Although your actual costs may be higher or lower, based on these assumptions your costs would be:
| 1 Year | 3 Years | 5 Years | 10 Years | |||||
| A Shares | $[•] | $[•] | $[•] | $[•] | ||||
| C Shares | $[•] | $[•] | $[•] | $[•] | ||||
| Investor Shares | $[•] | $[•] | $[•] | $[•] | ||||
| Institutional Shares | $[•] | $[•] | $[•] | $[•] |
| www.cavanalhillfunds.com | 26 | 1-800-762-7085 |
Portfolio Turnover
The World Energy & Power Fund pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover rate may indicate higher transaction costs and may result in higher taxes when Fund shares are held in a taxable account. These costs, which are not reflected in annual fund operating expenses or in the example, affect the Fund’s performance. During the most recent fiscal year, the Fund’s portfolio turnover rate was [•]% of the average value of its portfolio.
Principal Investment Strategy
To pursue its objective, under normal circumstances, the Fund invests at least 80% of its net assets in a wide range of energy and power-related financial instruments issued in the U.S. and markets around the world. This policy will not be changed without at least 60 days prior notice to shareholders. Energy and power-related financial instruments may include foreign and domestic securities of issuers that derive more than fifty percent of their assets, revenue or income from activities related to the exploration, extraction, mining, research, development, conservation, refinement, production, transfer, transmission, and transportation of conventional, alternative, renewable and sustainable energy and power sources, as well as utilities, petrochemicals, plastics, and suppliers and servicers to such industries. Investments typically include a combination of common stock, bonds, exchange traded funds (“ETFs”) and exchange traded notes (“ETNs”) but may also include other asset types that are related to energy industry activities. The Fund’s energy-related financial instruments may include sponsored and unsponsored ADRs and GDRs. The Fund may also seek to provide exposure to the investment returns of commodities through investment in commodity-linked derivative instruments, commodity futures, options on commodity future contracts, and investment vehicles that focus on commodities such as ETFs that invest in commodities, commodity options and futures.
The Fund may engage in active and frequent trading.
Under normal market conditions, the Fund will invest at least 40%, but may invest up to 100%, of its net assets in the securities of issuers organized or having their principal place of business outside the U.S. or doing a substantial amount of business outside the
U.S. The Fund will consider an issuer to be doing a substantial amount of business outside the U.S. if it derives more than 50% of its assets, revenue or income outside of the U.S. or is an international focused ETF or ETN. Under normal market conditions, the Fund invests in issuers from at least three different countries. The Adviser invests the Fund’s assets based on its judgment about issuers, risk, prices of securities, market conditions, potential returns, and other economic factors in the U.S. and around the world.
The Fund may invest in long and short positions in securities of issuers of any market capitalization, emerging market securities, American depositary receipts, European depositary receipts, global depositary receipts, and master limited partnerships (“MLPs”). The Fund may also invest in pooled investment vehicles, including other registered investment companies (“RICs”), ETNs and ETFs, including leveraged and inverse ETFs.
The Fund may invest in fixed income securities of any credit quality and maturity, including those of defaulted/distressed issuers. These securities can be rated below investment grade (“junk bonds” or high yield securities) and thus rated below Baa3 by Moody’s, BBB- by S&P or BBB- by Fitch Ratings Ltd. or unrated and securities in default. Fixed income investments may include foreign and domestic sovereign issued securities.
Principal Investment Risks
Loss of money is a risk of investing in the Fund. In addition, the principal risks of investing in the Fund, which could adversely affect the Fund’s net asset value, yield or total return are:
| • | Market Risk — The value of the Fund’s assets will fluctuate as the markets in which the Fund invests fluctuate. The value of the Fund’s investments may decline, sometimes rapidly and unpredictably, simply because of economic changes or other events, such as inflation (or expectations for inflation), deflation (or expectations for deflation), interest rates, global demand for particular products or resources, market instability, debt crises and downgrades, embargoes, tariffs, sanctions and other trade barriers, regulatory events, other governmental trade or market control programs and related geopolitical events. In addition, the value of the Fund’s investments may be negatively affected by the occurrence of global events such as war, military conflict, acts of terrorism, social unrest, environmental disasters, natural disasters or events, recessions, supply chain disruptions, political instability, and infectious disease epidemics or pandemics. |
| • | Energy Industry Risk — Investment risks associated with investing in energy securities include price fluctuation caused by real and perceived inflationary trends and political developments, the cost assumed in complying with environmental regulation, changes in environmental regulation, energy conservation, demand for energy resources, fluctuations in energy prices, exploration and production spending, technological developments, depletion of resources, import controls, weather, world events and economic conditions. |
| www.cavanalhillfunds.com | 27 | 1-800-762-7085 |
| • | Issuer Specific Risk — The value of a security may decline for a number of reasons which directly relate to the issuer, such as management performance, earnings and sales trends, investor perceptions, financial leverage and reduced demand for the issuer’s goods or services. |
| • | Concentration Risk — The Fund’s concentration in energy-related industry securities may present more risks than would be the case with funds that diversify investments in numerous industries and sectors of the economy. A downturn in the energy sectors would have a larger impact on the World Energy & Power Fund than on a fund that does not concentrate in these industries. Energy sector securities can be significantly affected by events related to political developments, energy conservation, commodity prices, and tax and government regulations. The performance of securities in the Fund may, at times, lag the performance of companies in other sectors or the broader market as a whole. |
| • | Commodity Risk — The Fund’s exposure to commodities may subject the Fund to greater volatility than investments in traditional securities. The commodities markets may fluctuate widely based on a variety of factors, including changes in overall market movements, domestic and foreign political and economic events and policies, war, acts of terrorism, changes in domestic or foreign interest rates and/or investor expectations concerning interest rates, domestic and foreign inflation rates and investment and trading activities of mutual funds, hedge funds and commodities funds. Prices of various commodities may also be affected by factors such as weather, embargoes, tariffs and other regulatory developments. The prices of commodities can also fluctuate widely due to supply and demand disruptions in major producing or consuming regions. Investments in commodity futures may be more volatile than the price of the underlying commodity. |
| • | Depositary Receipts Risk — Depositary receipts are generally subject to the same risks as the foreign securities that they evidence or into which they may be converted. In addition to investment risks associated with the underlying issuer, depositary receipts expose the Fund to additional risks associated with the non-uniform terms that apply to depositary receipt programs, credit exposure to the depository bank and to the sponsors and other parties with whom the depository bank establishes the programs, currency risk and the risk of an illiquid market for depositary receipts. The issuers of unsponsored depositary receipts are not obligated to disclose information that is, in the United States, considered material. Therefore, there may be less information available regarding these issuers and there may not be a correlation between such information and the market value of the depositary receipts. |
| • | Currency Risk — The potential risk of loss from unfavorable changes in the exchange rates between the U.S. dollar and foreign currencies. Funds that invest directly in foreign currencies, or in securities that trade in, or receive revenues in, foreign currencies, or in derivatives that provide exposure to foreign currencies are subject to the risk that those currencies will decline in value relative to the U.S. dollar, or, in the case of hedging positions, that the U.S. dollar will decline in value relative to the currency being hedged. Exchange rate volatility may affect the ability of an issuer to repay U.S. dollar denominated debt, thereby increasing credit risk. |
| • | Mid Cap Risk — The risk that the stocks of mid-capitalization companies often have greater price volatility, lower trading volume, and less liquidity than the stocks of larger, more established companies. |
| • | Small Cap Risk — Small cap companies may be more vulnerable to adverse business or economic developments. They may also be less liquid and/or more volatile than securities of larger companies or the market averages in general. Small cap companies may be adversely affected during periods when investors prefer to hold securities of large capitalization companies. |
| • | Credit Risk — Credit risk is the possibility that the issuer of a debt instrument or a counterparty to an agreement fails to fulfill its obligations, reducing the Fund’s return. This includes failure by a bond issuer to repay interest and principal. |
| • | Portfolio Turnover Risk — A Fund may engage in active and frequent trading to achieve its principal investment objectives. This may result in the realization and distribution to shareholders of higher capital gains as compared to a fund with less active trading policies, which would increase an investor’s tax liability unless shares are held through a tax deferred or exempt vehicle. Frequent trading also increases transaction costs, which could detract from a Fund’s performance. |
| • | Emerging Markets Risk — Risks associated with investing in emerging market securities include potentially restrictive political and economic structures and abrupt changes to those structures, changes in price visibility and liquidity in markets and securities, fluctuations in currency exchange rates, volatility in interest rates, and sudden changes in tax policy. |
| • | Foreign Investment Risk — The risk associated with higher transaction costs, delayed settlements, currency controls or adverse economic and political developments. This also includes the risk that fluctuations in the exchange rates between the U.S. dollar and foreign currencies may negatively affect an investment. Exchange rate volatility may affect the ability of an issuer to repay U.S. dollar denominated debt, thereby increasing credit risk. Foreign securities may also be affected by incomplete or inaccurate financial information on companies. There is a risk of loss attributable to social upheavals, unfavorable governmental or political actions, seizure of foreign deposits, changes in tax or trade statutes, and governmental collapse and war. These risks are more significant in emerging markets. |
| www.cavanalhillfunds.com | 28 | 1-800-762-7085 |
| • | High Yield Securities Risk — Fixed income securities rated below investment grade and unrated securities of similar credit quality (commonly referred to as “junk bonds” or high yield securities) are regarded as being predominantly speculative as to the issuer’s ability to make payments of principal and interest. Investments in such securities involve substantial risk. Issuers of high yield securities may be highly leveraged and may not have available to them more traditional methods of financing. Therefore, the risks associated with acquiring the securities of such issuers generally are greater than is the case with investment grade securities. The value of high yield securities tends to be very volatile due to such factors as specific corporate developments, interest rate sensitivity, less secondary market activity, and negative perceptions of high yield securities and the junk bond markets generally, particularly in times of market stress. |
| • | Exchange Traded Fund (ETF) Risk — The ETFs in which the Fund invests are subject to the risks applicable to the types of securities and investments used by the ETFs. Because an ETF charges its own fees and expenses, fund shareholders will indirectly bear these costs. The use of leverage in an ETF can magnify any price movements, resulting in high volatility. Due to daily rebalancing, leverage, and liquidity, inverse ETFs may perform worse than the inverse movement of the underlying referenced financial asset, index or commodity’s return. |
| • | Exchange Traded Note (ETN) Risk — Because ETNs are unsecured, unsubordinated debt securities, an investment in an ETN exposes the Fund to the risk that an ETN issuer’s credit rating may be downgraded. The value of an ETN may be influenced by time to maturity, level of supply and demand for the ETN, volatility and lack of liquidity in underlying securities’ markets, changes in the applicable interest rates and economic, legal, political, or geographic events that affect the referenced index. In addition, the Fund will bear its proportionate share of the fees and expenses of the ETN, which may cause the Fund’s operating expenses to be higher and its performance to be lower. |
| • | Interest Rate Risk — The value of the Fund’s interest-bearing investments may decline due to an increase in interest rates. In general, the longer a security’s maturity, the greater the interest rate risk. For a portfolio with a duration of 3 years, each 1% rise in interest rates would reduce the value of the portfolio by an estimated 3%. The Fund’s yield may decrease due to a decline in interest rates. Very low or negative interest rates may magnify interest rate risk. Future declines in interest rate levels could cause the Fund’s earnings to fall below the Fund’s expense ratio, resulting in a negative yield and a decline in the Fund’s share price. Changing interest rates, including negative interest rates, may have unpredictable effects on markets, may result in heightened market volatility and may detract from Fund performance to the extent the Fund is exposed to such interest rates. |
| • | Liquidity Risk — Certain securities may be difficult or impossible to sell at the time and the price that would normally prevail in the market. The portfolio manager may have to lower the price, sell other securities instead or forego an investment opportunity, any of which could have a negative effect on Fund management or performance. This includes the risk of missing out on an investment opportunity because the assets necessary to take advantage of it are tied up in less advantageous investments. If a Fund is required to sell securities quickly or at a particular time (including sales to meet redemption requests) the Fund could realize a loss. |
| • | Management Risk — There is no guarantee that the investment techniques and risk analyses used by the Fund’s portfolio managers will produce the desired results. |
| • | Valuation Risk — The risk associated with the assessment of appropriate pricing in a changing market where trading information may not be readily available. |
| • | Master Limited Partnership Risk — The interests or “units” of an MLP are listed and traded on securities exchanges or in the over-the-counter market and their value fluctuates predominantly based on prevailing market conditions and the success of the MLP. MLPs carry many of the risks inherent in investing in a partnership. Unit holders of an MLP may not be afforded corporate protections to the same extent as shareholders of a corporation. In addition, unlike owners of common stock of a corporation, holders of common units of an MLP may have more limited control and limited rights to vote on matters affecting the MLP and have no ability to elect directors annually. In the event of liquidation, common units have preference over subordinated units, but not over debt or preferred units, to the remaining assets of the MLP. |
| • | Regulatory Risk — The risk that a change in laws or regulations will materially affect a security, business, sector or market. A change in laws or regulations made by the government or a regulatory body can increase the costs of operating a business, reduce the attractiveness of investment and/or change the competitive landscape. Regulatory risk also includes the risk associated with federal and state laws which may restrict the remedies that a lender has when a borrower defaults on loans. These laws include restrictions on foreclosures, redemption rights after foreclosure, federal and state bankruptcy and debtor relief laws, restrictions on “due on sale” clauses, and state usury laws. |
| www.cavanalhillfunds.com | 29 | 1-800-762-7085 |
For more information about these risks, please refer to the section titled “Investment Practices and Risks” in the Fund’s prospectus. An investment in the Fund is not a deposit of any bank and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other government agency.
Performance Information
The bar chart and the performance table below illustrate some of the risks and return volatility of an investment in the Fund by showing changes in the Fund’s performance from year to year and by showing how the Fund’s average annual returns for 1, 5 and 10 years compare with those of a broad measure of market performance. The Fund’s past performance (before or after taxes) does not necessarily indicate how the Fund will perform in the future. Updated performance information may be obtained on the Fund’s website www.cavanalhillfunds.com or by calling 1-800-762-7085.
This bar chart shows changes in the Fund’s performance from year to year1. The returns for A Shares, C Shares and Institutional Shares will differ from the returns for Investor Shares (which are shown in the bar chart) because of differences in the expenses of each class.
Annual Total Returns for Investor Shares (Periods Ended 12/31)

| 1 | The performance information shown above is based on a calendar year. The Fund’s total return from 1/1/26 to 9/30/26 was [•]%. |
This table compares the Fund’s average annual total returns for periods ended December 31, 2025, to those of the MSCI World Energy Index and the S&P 500 Index. The MSCI World Energy Index demonstrates how the Fund’s performance compares with the returns of indices with similar investment objectives, whereas the S&P 500 Index is a broad-based index, which provides a benchmark reflecting the stock performance of the 500 largest companies listed on stock exchanges in the United States. The A Shares initially imposed a sales charge of 5.50% which was reduced to 3.50% on December 31, 2014 and then to 2.00% on December 26, 2017. The stated returns assume the highest historical federal marginal income and capital gains tax rates. These after-tax returns do not reflect the effect of any applicable state and local taxes. Actual after-tax returns depend on an investor’s tax situation and may differ from those shown. After-tax returns are not relevant to investors holding shares through tax-deferred programs, such as IRA or 401(k) plans. After-tax returns are shown only for the Investor Class Shares and after-tax returns for other shares will vary.
| Average Annual Total Returns (Periods Ended 12/31/25) | 1 Year | 5 Years | 10 Years |
| Investor Shares | |||
| Return Before Taxes | [•]% | [•]% | [•]% |
| Return After Taxes on Distributions | [•]% | [•]% | [•]% |
| Return After Taxes on Distributions and Sale of Fund Shares | [•]% | [•]% | [•]% |
| Institutional Shares | |||
| Return Before Taxes | [•]% | [•]% | [•]% |
| A Shares | |||
| Return Before Taxes (With Load) | [•]% | [•]% | [•]% |
| C Shares | |||
| Return Before Taxes | [•]% | [•]% | [•]% |
| MSCI World Energy Index (reflects no deduction for expenses, fees or taxes) |
[•]% | [•]% | [•]% |
| S&P 500 Index (reflects no deduction for expenses, fees or taxes) |
[•]% | [•]% | [•]% |
| www.cavanalhillfunds.com | 30 | 1-800-762-7085 |
Investment Adviser
Cavanal Hill® Investment Management, Inc. serves as the investment adviser for the Fund.
Portfolio Managers
The following individuals are jointly and primarily responsible for the day-to-day management of the Fund’s portfolio:
Matthew C. Stephani, CFA, is President of Cavanal Hill Investment Management, Inc., and has been a Portfolio Manager of the Fund since 2014.
Michael P. Maurer, CFA, is a Senior Vice President of Cavanal Hill Investment Management, Inc. and has been a Portfolio Manager of the Fund since 2014.
Thomas W. Verdel, CFA, is a Senior Vice President of Cavanal Hill Investment Management, Inc. and has been a Portfolio Manager of the Fund since 2014.
Benjamin C. Wolthuizen, CFA, is a Vice President of Cavanal Hill Investment Management, Inc. and has been a Portfolio Manager of the Fund since 2025.
Purchase and Sale of Fund Shares
The following initial and additional purchase requirements apply:
| Initial Purchase | Additional Purchases | |
| A Shares | None | None |
| C Shares | None | None |
| Investor Shares | $100 | None |
| Institutional Shares | $1,000 | None |
Shares may be purchased, sold (redeemed) or exchanged on any business day by:
| • | Sending a written request by mail to the Funds Custodian: BOKF, NA, Attention: Cavanal Hill Funds, P.O. Box 182730, Columbus, Ohio 43218-2730. |
| • | Sending a written request by overnight mail to: Cavanal Hill Funds, c/o FIS Investor Services, LLC, 4249 Easton Way, Suite 400, Columbus, OH, 43219-6171. |
| • | Calling us at 1-800-762-7085 with instructions as to how you wish to complete the transaction (mail, wire, electronic transfer). |
Tax Information
The Fund’s distributions are generally taxable to you as ordinary income, capital gains, or a combination of the two, unless you are investing through a tax-deferred arrangement, such as a 401(k) plan or an individual retirement account. Retirement accounts may be taxed at a later date.
Payments to Broker-Dealers and Other Financial Intermediaries
If you purchase shares of the Fund through a broker-dealer or other financial intermediary (such as a bank), the Fund or its service providers may pay the intermediary for the sale of Fund shares and related services. These payments may create a conflict of interest by influencing the broker-dealer or other intermediary and your salesperson to recommend the Fund over another investment. Ask your salesperson or visit your financial intermediary’s website for more information. In addition, if you purchase shares that do not have any front-end sales charge, contingent deferred sales charge, or other asset-based fee for sales or distribution from a broker or other financial intermediary on an acting agency basis, you may be required to pay a commission in an amount charged and separately disclosed to you by such party.
| www.cavanalhillfunds.com | 31 | 1-800-762-7085 |
| HEDGED EQUITY INCOME FUND |
| SUMMARY |
Investment Objective
To seek current income with the potential for long-term capital appreciation with less volatility than the broad equity market.
Fees and Expenses of the Fund
This table describes the fees and expenses that you may pay if you buy and hold shares of the Hedged Equity Income Fund. You may qualify for sales charge discounts if you and your family invest or agree to invest in the future, at least $200,000 in Cavanal Hill Funds. More information about these and other discounts is available from your financial professional and in the section “Initial Sales Charge (Bond and Equity Funds, Class A Shares Only)” on page [•] of the prospectus and “Contingent Deferred Sales Charges (CDSC-Class A Only)” on page [•] in the prospectus and in the section “Additional Purchase and Redemption Information” on page [•] of the Statement of Additional Information. An investor transacting in Institutional Shares, which do not have any front-end sales charge, contingent deferred sales charge, or other asset-based fee for sales or distribution, may be required to pay a commission to a broker or other financial intermediary for effecting such transactions on an agency basis. Such commissions are not reflected in the tables or the example below. Shares of the Fund are available in other share classes that have different fees and expenses.
Shareholder Fees (fees paid directly from your investment) |
A
Shares |
C Shares |
Investor Shares | Institutional Shares |
| Maximum Sales Charge (Load) imposed on Purchases (as a percentage of offering price) | 2.00% | None | None | None |
Maximum Deferred Sales Charge (Load) (as a percentage of the lesser of original purchase price or redemption proceeds) |
1.00%* | None | None | None |
Annual Fund Operating Expenses (expenses that you pay each year as a percentage of the value of your investment). |
A Shares |
C Shares |
Investor Shares | Institutional Shares |
| Management Fees | 0.80% | [•]% | 0.80% | 0.80% |
| Distribution and/or Service (12b-1) Fees | 0.25% | [•]% | 0.25% | — |
| Other Expenses | [•]% | [•]% | [•]% | •[]% |
| Shareholder Servicing Fees | 0.10% | [•]% | 0.25% | 0.25% |
| Total Annual Fund Operating Expenses | [•]% | [•]% | [•]% | [•]% |
| Less Fee Waivers† | ([•])% | [•]% | ([•])% | ([•])% |
| Total Annual Fund Operating Expenses After Fee Waivers | [•]% | [•]% | [•]% | [•]% |
| * | Class A Shares are available with no front-end sales charge on investments of $200,000 or more. There is, however, a contingent deferred sales charge (CDSC) of 1.00% on any Class A Shares upon which a dealer concession was paid that are sold within one year of purchase. In addition, while C Shares are offered at NAV, without any initial sales charge, a 1.00% CDSC may be charged on any C Shares upon which a dealer concession has been paid that are sold within one year of purchase. |
| † | The Adviser has contractually agreed to waive fees payable to it or reimburse certain expenses so that expenses (other than extraordinary expenses and any Acquired Fund Fees and Expenses) for each Class do not exceed 1.10%, plus class-specific fees until December 31, 2027. Affiliates of the Adviser have contractually agreed to waive all Shareholder Servicing Fees to which they are entitled. The affiliate waivers result in a reduction of the Shareholder Servicing Fee paid by all purchasers of a Class to the extent shown in the table. Contractual waivers are in place for the period through December 31, 2027, and may only be terminated or modified with the approval of the Fund’s Board of Trustees. |
Example
This example is intended to help you compare the cost of investing in the Fund with the cost of investing in other mutual funds. The example assumes that you invest $10,000 in the Fund for the time periods indicated and then redeem all of your shares at the end of those periods. The example also assumes that your investment has a 5% return each year and that the Fund’s operating expenses remain the same. Although your actual costs may be higher or lower, based on these assumptions your costs would be:
| 1 Year | 3 Year | 5 Year | 10 Year | |
| A Shares | $[•] | $[•] | $[•] | $[•] |
| C Shares | $[•] | $[•] | $[•] | $[•] |
| Investor Shares | $[•] | $[•] | $[•] | $[•] |
| Institutional Shares | $[•] | $[•] | $[•] | $[•] |
Portfolio Turnover
The Hedged Equity Income Fund pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover rate may indicate higher transaction costs and may result in higher taxes when Fund shares are held in a taxable account. These costs, which are not reflected in annual fund operating expenses or in the example, affect the Fund’s performance. During the most recent fiscal year, the Fund’s portfolio turnover rate was [•]% of the average value of its portfolio.
| www.cavanalhillfunds.com | 32 | 1-800-762-7085 |
Principal Investment Strategy
To pursue its objective, under normal circumstances, the Fund invests primarily in dividend paying equity securities, with at least 80% of its net assets in income generating equity securities and equity-related instruments traded on U.S. exchanges. For purposes of this policy, the Fund includes common stocks and securities convertible into common stocks of companies with any market capitalization and sponsored or unsponsored American Depositary Receipts (ADRs). Under normal circumstances, the fund will seek to generate current income. Some of the income will be distributed to shareholders in the form of dividends from portfolio securities; income will also be generated from option premiums by writing (selling) call options on its portfolio securities, all of which will be covered calls. A covered call refers to a financial transaction in which the investor selling a call option owns an equivalent amount of the underlying security. The investor’s ownership of the long position in the asset is the “cover” because the seller can deliver the shares if the buyer of the call option chooses to exercise. The fund seeks to produce current income from dividends and, to a lesser extent, from option writing premiums. Because of the tax treatment options activity receives, call premium income may not be distributed to shareholders. The Fund will buy index and ETF put options as well as put options on individual securities in order to seek to both reduce volatility and provide downside market protection for the portfolio.
The portfolio management team of the Fund selects equity securities that it believes have strong earnings, cash flow and revenue growth prospects, industry leadership with a competitive advantage, strong management teams, understandable and observable fundamental dynamics, and can pay consistent and sustainable dividends. At the time of initial investment selection, common stocks will have a minimum market cap of $1 billion. The portfolio will typically invest in 25 to 40 holdings across multiple economic sectors and will not invest more than 40% of the fund’s net assets in any one such sector to diversify risk.
The extent of option writing activity will depend on the portfolio management team’s judgment regarding perceived value associated with security prices, market conditions, the attractiveness of writing call options on the fund’s stock holdings, and timing issues related to monthly option expiration dates. Writing covered calls produces income from premiums, a portion of which will be used to purchase puts which helps to reduce the volatility (and risk profile) of the fund by providing downside protection.
The fund is required to pledge collateral for the covered call option trades and will hold the security as collateral for all such covered call option trades. Put options collateral is limited to the total cash paid for the option. The fund’s Custodian will segregate such collateral for the benefit of the counterparty. High levels of new investment inflow can lead to periods of higher cash levels, as investment opportunities are identified. Similarly, during periods in which stock markets advance, the exercise of options may result in higher cash levels.
The Fund is non-diversified, meaning it may invest in fewer individual holdings than a diversified fund. Therefore, the Fund is more exposed to individual security volatility than a diversified fund.
Purchase and sale decisions are based on the Adviser’s judgment about issuers, risk, prices of securities, market conditions, potential returns, and other economic factors.
Principal Investment Risks
Loss of money is a risk of investing in the Fund. In addition, the principal risks of investing in the Fund, which could adversely affect the Fund’s net asset value, yield or total return are:
| • | Market Risk — The value of the Fund’s assets will fluctuate as the markets in which the Fund invests fluctuate. The value of the Fund’s investments may decline, sometimes rapidly and unpredictably, simply because of economic changes or other events, such as inflation (or expectations for inflation), deflation (or expectations for deflation), interest rates, global demand for particular products or resources, market instability, debt crises and downgrades, embargoes, tariffs, sanctions and other trade barriers, regulatory events, other governmental trade or market control programs and related geopolitical events. In addition, the value of the Fund’s investments may be negatively affected by the occurrence of global events such as war, military conflict, acts of terrorism, social unrest, environmental disasters, natural disasters or events, recessions, supply chain disruptions, political instability, and infectious disease epidemics or pandemics. |
| • | Issuer Specific — The value of a security may decline for a number of reasons which directly relate to the issuer, such as management performance, earnings and sales trends, investor perceptions, financial leverage or reduced demand for the issuer’s goods or services. |
| • | Derivative Risk — The risk of investing in derivative instruments, including liquidity, interest rate, market, credit and management risks, mispricing or improper valuation. Changes in the value of a derivative may not correlate perfectly with the underlying asset, rate or index, and the Fund could lose more than the principal amount invested. |
| www.cavanalhillfunds.com | 33 | 1-800-762-7085 |
| • | Call Options Risk — Investments in call options involve risks different from, or possibly greater than, the risks associated with investing directly in securities, including leverage risk, tracking risk and counterparty default risk. The risk of potential losses if equity markets or an individual equity security do not move as expected and the potential for greater losses than if these techniques had not been used. By writing covered call options, a fund will not benefit from any potential increases in the value of the underlying asset above the exercise price, but will bear the risk of declines in the value of the asset. As the seller (writer) of a call option, the Fund will tend to lose money if the value of the reference index or security rises above the strike price. As the buyer of a call option, the Fund risks losing the entire premium invested if the value of the reference index or security is below (above) the call strike at maturity. Writing of covered call options are also subject to the risk that the counterparty to the transaction will not fulfil its obligations. |
| • | Put Option Risk — When the Fund purchases a put option on a security or index it may lose the entire premium paid if the underlying security or index does not decrease in value. The Fund is also exposed to default by the put writer who may be unwilling or unable to perform its contractual obligations to the Fund. |
| • | Hedging Risk — The risk that the stocks in the portfolio may decrease in value more than the increase in value of the put options. Puts that are purchased on ETFs or indexes do not hedge the company-specific risk of stocks owned in the portfolio. Hedging may not be effective based on timing, the underlying instrument hedged, or duration of the hedge. |
| • | Limited Number of Holdings Risk — As a large percentage of a Fund’s assets may be invested in a limited number of securities, each investment has a greater effect on a Fund’s overall performance and any change in the value of those securities could significantly affect the value of your investment in the fund. |
| • | Non-Diversification Risk — Investments of a “non-diversified” mutual fund are not required to meet certain diversification requirements under Federal law. Compared with “diversified” portfolios, a non-diversified fund may invest a greater percentage of its assets in the securities of an issuer. A decline in the value of those investments would cause the Fund’s overall value to decline to a greater degree than if the Fund held more diversified holdings. |
| • | Management Risk — There is no guarantee that the investment techniques and risk analyses used by the Fund’s portfolio managers will produce the desired results. |
| • | Dividend Paying Security Risk — The fund’s investment in dividend-paying stocks could cause the fund to underperform similar funds that invest without consideration of a company’s track record of paying dividends. Stock of companies with a history of paying dividends may not participate in a broad market advance to the same degree as most other stocks, and a sharp rise in interest rates or economic downturn could cause a company to unexpectedly reduce or eliminate its dividend. |
| • | Depositary Receipts Risk — Depositary receipts are generally subject to the same risks as the foreign securities that they evidence or into which they may be converted. In addition to investment risks associated with the underlying issuer, depositary receipts expose the Fund to additional risks associated with the non-uniform terms that apply to depositary receipt programs, credit exposure to the depository bank and to the sponsors and other parties with whom the depository bank establishes the programs, currency risk and the risk of an illiquid market for depositary receipts. The issuers of unsponsored depositary receipts are not obligated to disclose information that is, in the United States, considered material. Therefore, there may be less information available regarding these issuers and there may not be a correlation between such information and the market value of the depositary receipts. |
| • | Mid Cap Risk — The risk that the stocks of mid-capitalization companies often have greater price volatility, lower trading volume, and less liquidity than the stocks of larger, more established companies. |
| • | Small Cap Risk — Small cap companies may be more vulnerable to adverse business or economic developments. They may also be less liquid and/or more volatile than securities of larger companies or the market averages in general. Small cap companies may be adversely affected during periods when investors prefer to hold securities of large capitalization companies. |
| • | Tax Risk — If positions held by the Fund were treated as “straddles” for federal income tax purposes, or a Fund’s risk of loss with respect to a position was otherwise diminished as set forth in Treasury Regulations, dividends on stocks that are a part of such positions would not constitute qualified dividend income subject to such favorable income tax treatment or qualify for the dividends received deduction for corporate shareholders. In addition, generally, straddles are subject to certain rules that may affect the amount, character and timing of the Fund’s gains and losses with respect to straddle positions by requiring, among other things, that: (1) any loss realized on disposition of one position of a straddle may not be recognized to the extent that the Fund has unrealized gains with respect to the other position in such straddle; (2) the Fund’s holding period in straddle positions be suspended while the straddle exists (possibly resulting in a gain being treated as short-term capital gain rather than long-term capital gain); (3) the losses recognized with respect to certain straddle positions that are part of a mixed straddle and that are non-Section 1256 contracts be treated as 60% long-term and 40% short-term capital loss; (4) losses recognized with respect to certain straddle positions that would otherwise constitute short-term capital losses be treated as long-term capital losses; and (5) the deduction of interest and carrying charges attributable to certain straddle positions may be deferred. To the extent that the Fund makes investments with additional risks, those risks could increase volatility or reduce performance. The Fund may trade securities actively, which could increase its transaction costs (thus lowering performance) and may increase the amount of taxes that you pay. |
| www.cavanalhillfunds.com | 34 | 1-800-762-7085 |
For more information about these risks, please refer to the section titled “Investment Practices and Risks” in the Fund’s prospectus. An investment in the Fund is not a deposit of any bank and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other government agency.
Performance Information
The bar chart and the performance table below illustrate some of the risks and return volatility of an investment in the Fund by showing changes in the Fund’s performance from year to year and by showing how the Fund’s average annual returns for 1 year and since inception compare with those of a broad measure of market performance. The Fund’s past performance (before or after taxes) does not necessarily indicate how the Fund will perform in the future. Updated performance information may be obtained on the Fund’s website www.cavanalhillfunds.com or by calling 1-800-762-7085.
This bar chart shows changes in the Fund’s performance from year to year1. The returns for A Shares and Institutional Shares will differ from the returns for Investor Shares (which are shown in the bar chart) because of differences in the expenses of each Class.
Annual Total Returns for Investor Shares (Periods Ended 12/31)

| 1 | The performance information shown above is based on a calendar year. The Fund’s total return from 1/1/26 to 9/30/26 was [•]%. |
This table compares the Fund’s average annual total returns for periods ended December 31, 2025, to those of the CBOE S&P 500 BuyWrite Monthly Index and the S&P 500 Index. The CBOE S&P 500 BuyWrite Monthly Index demonstrates how the Fund’s performance compares with the returns of indices with similar investment objectives, whereas the S&P 500 Index is a broad-based index, which provides a benchmark reflecting the stock performance of the 500 largest companies listed on stock exchanges in the United States. The stated returns assume the highest historical federal marginal income and capital gains tax rates. These after-tax returns do not reflect the effect of any applicable state and local taxes. Actual after-tax returns depend on an investor’s tax situation and may differ from those shown. After-tax returns are not relevant to investors holding shares through tax-deferred programs, such as IRA or 401(k) plans. After-tax returns are shown only for the Investor Class Shares and after-tax returns for other shares will vary. Class C Shares of the Fund had not commenced operations as of December 31, 2025, and therefore performance information for Class C Shares is not shown.
| Average Annual Total Returns (Periods Ended 12/31/25) | 1 Year | 5 Year | Since
Inception (12/28/20) |
| Investor Shares | |||
| Return Before Taxes | [•]% | [•]% | [•]% |
| Return After Taxes on Distributions | [•]% | [•]% | [•]% |
| Return After Taxes on Distributions and Sale of Fund Shares | [•]% | [•]% | [•]% |
| Institutional Shares | |||
| Return Before Taxes | [•]% | [•]% | [•]% |
| A Shares | |||
| Return Before Taxes (With Load) | [•]% | [•]% | [•]% |
CBOE S&P 500 BuyWrite Monthly Index (reflects no deduction for expenses, fees or taxes) |
[•]% | [•]% | [•]% |
| S&P 500 Index | [•]% | [•]% | [•]% |
| www.cavanalhillfunds.com | 35 | 1-800-762-7085 |
Investment Adviser
Cavanal Hill® Investment Management, Inc. serves as the investment adviser for the Fund. Lavaca Capital, LLC serves as the investment sub-adviser for the Fund.
Portfolio Managers
The following individuals are primarily responsible for the day-to-day management of the Fund’s portfolio:
Brandon R. Barnes, CFA, is a Senior Vice President of Cavanal Hill Investment Management, Inc. and has been a Portfolio Manager of the Fund since 2020.
Michael C. Schloss is a Vice President of Cavanal Hill Investment Management, Inc. and has been a Portfolio Manager of the Fund since 2020.
Scott Phillips is the Founder, and CEO & CIO of Lavaca Capital, LLC and has been a Portfolio Manager of the Fund since 2020. Jacob Johnson is a Portfolio Manager at Lavaca Capital, LLC and has been a Portfolio Manager of the Fund since 2020.
Purchase and Sale of Fund Shares
The following initial and additional purchase requirements apply:
| Initial Purchase | Additional Purchases | |
| Bond and Equity Funds | ||
| A Shares | None | None |
| C Shares | None | None |
| Investor Shares | $100 | None |
| Institutional Shares | $1,000 | None |
Shares may be purchased, sold (redeemed) or exchanged on any business day by:
| • | Sending a written request by mail to the Funds Custodian: BOKF, NA, Attention: Cavanal Hill Funds, P.O. Box 182730, Columbus, Ohio 43218-2730. |
| • | Sending a written request by overnight mail to: Cavanal Hill Funds, c/o FIS Investor Services, LLC, 4249 Easton Way, Suite 400, Columbus, OH, 43219-6171. |
| • | Calling us at 1-800-762-7085 with instructions as to how you wish to complete the transaction (mail, wire, electronic transfer). |
Tax Information
The Fund’s distributions are generally taxable to you as ordinary income, capital gains, or a combination of the two, unless you are investing through a tax-deferred arrangement, such as a 401(k) plan or an individual retirement account. Retirement accounts may be taxed at a later date.
Payments to Broker-Dealers and Other Financial Intermediaries
If you purchase shares of the Fund through a broker-dealer or other financial intermediary (such as a bank), the Fund or its service providers may pay the intermediary for the sale of Fund shares and related services. These payments may create a conflict of interest by influencing the broker-dealer or other intermediary and your salesperson to recommend the Fund over another investment. Ask your salesperson or visit your financial intermediary’s website for more information. In addition, if you purchase shares that do not have any front-end sales charge, contingent deferred sales charge, or other asset-based fee for sales or distribution from a broker or other financial intermediary on an acting agency basis, you may be required to pay a commission in an amount charged and separately disclosed to you by such party.
| www.cavanalhillfunds.com | 36 | 1-800-762-7085 |
| INDUSTRIAL FRONTIER FUND |
| SUMMARY |
Investment Objective
To seek long term capital appreciation.
Fees and Expenses of the Fund
This table describes the fees and expenses that you may pay if you buy, hold and sell shares of the Industrial Frontier Fund. You may qualify for sales charge discounts if you and your family invest or agree to invest in the future, at least $200,000 in Cavanal Hill Funds. More information on these and other discounts is available from your financial professional and in the section “Initial Sales Charge (Bond and Equity Funds, Class A Shares Only)” on page [•] of the prospectus and “Contingent Deferred Sales Charges (CDSC-Class A and C Only)” on page [•] in the prospectus and in the section “Additional Purchase and Redemption Information” on page [•] of the Statement of Additional Information. An investor transacting in Institutional Shares, which do not have any front-end sales charge, contingent deferred sales charge, or other asset-based fee for sales or distribution, may be required to pay a commission to a broker or other financial intermediary for effecting such transactions on an agency basis. Such commissions are not reflected in the tables or the example below. Shares of the Fund are available in other share classes that have different fees and expenses.
Shareholder Fees (fees paid directly from your investment) |
A Shares |
C Shares |
Investor Shares |
Institutional Shares |
Maximum Sales Charge (Load) imposed on Purchases (as a percentage of offering price) |
2.00% | None | None | None |
Maximum Deferred Sales Charge (Load) (as a percentage of the lesser of original purchase price or redemption proceeds) |
1.00%* | 1.00%* | None | None |
Annual Fund Operating Expenses (expenses that you pay each year as a percentage of the value of your investment). |
A |
C |
Investor Shares |
Institutional Shares |
| Management Fees | 0.60% | 0.60% | 0.60% | 0.60% |
| Distribution and/or Service (12b-1) Fees | 0.25% | 1.00% | 0.25% | 0.00% |
| Other Expenses | 0.31% | 0.31% | 0.31% | 0.31% |
| Shareholder Servicing Fees | [•]% | [•]% | [•]% | [•]% |
| Acquired Fund Fees and Expenses | [•]% | [•]% | [•]% | [•]% |
| Total Annual Fund Operating Expenses | [•]% | [•]% | [•]% | [•]% |
| Less Fee Waivers† | ([•])% | ([•])% | ([•])% | ([•])% |
| Total Annual Fund Operating Expenses After Fee Waivers | [•]% | [•]% | [•]% | [•]% |
| * | Class A Shares are available with no front-end sales charge on investments of $200,000 or more. There is, however, a contingent deferred sales charge (CDSC) of 1.00% on any Class A Shares upon which a dealer concession was paid that are sold within one year of purchase. In addition, while C Shares are offered at NAV, without any initial sales charge, a 1.00% CDSC may be charged on any C Shares upon which a dealer concession has been paid that are sold within one year of purchase. |
| † | The Adviser has contractually agreed to waive fees payable to it or reimburse certain expenses so that expenses (other than extraordinary expenses and any Acquired Fund Fees and Expenses) for each Class do not exceed 0.90%, plus class-specific fees until December 31, 2027. Affiliates of the Adviser have contractually agreed to waive all Shareholder Servicing Fees to which they are entitled. The affiliate waivers result in a reduction of the Shareholder Servicing Fee paid by all purchasers of a Class to the extent shown in the table. Contractual waivers are in place for the period through December 31, 2027, and may only be terminated or modified with the approval of the Fund’s Board of Trustees. |
Example
This example is intended to help you compare the cost of investing in the Fund with the cost of investing in other mutual funds. The example assumes that you invest $10,000 in the Fund for the time periods indicated and then redeem all of your shares at the end of those periods. The example also assumes that your investment has a 5% return each year and that the Fund’s operating expenses remain the same. Although your actual costs may be higher or lower, based on these assumptions your costs would be:
| 1 Year | 3 Years | |
| A Shares | $[•] | $[•] |
| C Shares | $[•] | $[•] |
| Investor Shares | $[•] | $[•] |
| Institutional Shares | $[•] | $[•] |
| www.cavanalhillfunds.com | 37 | 1-800-762-7085 |
Portfolio Turnover
The Industrial Frontier Fund pays transaction costs, such as commissions, when it buys and sells securities (or “turns over” its portfolio). A higher portfolio turnover rate may indicate higher transaction costs and may result in higher taxes when Fund shares are held in a taxable account. These costs, which are not reflected in annual fund operating expenses or in the example, affect the Fund’s performance. Because the Fund is newly organized, no turnover information is presented at this time.
Principal Investment Strategy
To pursue its objective, under normal circumstances, the Fund invests at least 80% of its net assets in a wide range of companies in the “industrial frontier,” which will include traditional industry sector companies, companies that sell into industrial end markets, and those that benefit from mega-trends identified by the Fund’s portfolio managers. This policy will not be changed without at least 60 days prior notice to shareholders.
More specifically, a company is an industrial frontier company if, at the time of investment, it satisfies at least one of the following: (a) classified as Industrial by the Global Industry Classification Standard (GICS®) or a comparable third-party classification system; (b) derives at least 50% of its revenues from industrial end markets, including sales to customers in manufacturing, transportation and logistics, aerospace and defense, construction and engineering, commercial and professional services, trading companies and distributors, and industrial real estate, or (c) classified as Technology or Materials by the GICS, or a comparable third-party classification system, and the portfolio managers of the fund determine that at least 50% of the company’s revenues are derived from participation in industrial mega-trends. While such trends may shift over time as themes mature and new themes emerge, examples of mega-trends could include: buildout of artificial intelligence infrastructure; onshoring of manufacturing back to the U.S. from abroad; geopolitical events driving increases in defense spending and modernization; development of physical artificial intelligence applications, including robotics; emergence of space-related commerce; structural requirements for electrical power and cybersecurity.
Investments typically include a combination of common stock, bonds, exchange traded funds (“ETFs”) and exchange traded notes (“ETNs”) but may also include other asset types that are related to industrial frontier activities. The Fund’s financial instruments may include sponsored and unsponsored ADRs and GDRs. The Fund may invest in long positions in securities of issuers of any market capitalization, as well as emerging market securities, American depositary receipts, European depositary receipts, and global depositary receipts. The Fund may also invest in pooled investment vehicles, including other registered investment companies (“RICs”), ETNs and ETFs, including leveraged and inverse ETFs.
The Fund may invest in fixed income securities of any credit quality and maturity, including those of defaulted/distressed issuers. These securities can be rated below investment grade (“junk bonds” or high yield securities) and thus rated below Baa3 by Moody’s, BBB- by S&P or BBB- by Fitch Ratings Ltd. or unrated and securities in default. Fixed income investments may include foreign and domestic sovereign issued securities.
The Fund may invest up to 15% of its net assets in alternative investments including private equity, venture capital, hedge funds, direct private investment, interval funds, business development companies, tender offer funds, and real assets among other investments.
The Fund is non-diversified, meaning it may invest in fewer individual holdings than a diversified fund. Therefore, the Fund is more exposed to individual security volatility than a diversified fund. The Fund may engage in active and frequent trading.
The Adviser invests the Fund’s assets based on its judgment about issuers, risk, prices of securities, market conditions, potential returns, and other economic factors in the U.S. and around the world. Portfolio managers will seek to identify companies with the following characteristics: sustainable competitive advantage, industry barriers to entry, forecastable, sustainable earnings growth, and attractive valuation. Changes in fundamental strategy of a company represent a potential sale trigger.
| www.cavanalhillfunds.com | 38 | 1-800-762-7085 |
Principal Investment Risks
Loss of money is a risk of investing in the Fund. In addition, the principal risks of investing in the Fund, which could adversely affect the Fund’s net asset value, yield or total return are:
| • | Market Risk — The value of the Fund’s assets will fluctuate as the markets in which the Fund invests fluctuate. The value of the Fund’s investments may decline, sometimes rapidly and unpredictably, simply because of economic changes or other events, such as inflation (or expectations for inflation), deflation (or expectations for deflation), interest rates, global demand for particular products or resources, market instability, debt crises and downgrades, embargoes, tariffs, sanctions and other trade barriers, regulatory events, other governmental trade or market control programs and related geopolitical events. In addition, the value of the Fund’s investments may be negatively affected by the occurrence of global events such as war, military conflict, acts of terrorism, social unrest, environmental disasters, natural disasters or events, recessions, supply chain disruptions, political instability, and infectious disease epidemics or pandemics. |
| • | Issuer Specific Risk — The value of a security may decline for a number of reasons which directly relate to the issuer, such as management performance, earnings and sales trends, investor perceptions, financial leverage and reduced demand for the issuer’s goods or services. |
| • | Concentration Risk — The Fund’s concentration in industrials-related industry securities may present more risks than would be the case with funds that diversify investments in numerous industries and sectors of the economy. A downturn in the industrials sectors would have a larger impact on the Fund than on a fund that does not concentrate in these industries. Industrials sector securities can be significantly affected by economic and manufacturing cycles, government spending and regulation, trade and tariff policy, commodity and input prices, and technological change. The performance of securities in the Fund may, at times, lag the performance of companies in other sectors or the broader market as a whole. |
| • | Non-Diversification Risk — Investments of a “non-diversified” mutual fund are not required to meet certain diversification requirements under Federal law. Compared with “diversified” portfolios, a non-diversified fund may invest a greater percentage of its assets in the securities of an issuer. A decline in the value of those investments would cause the Fund’s overall value to decline to a greater degree than if the Fund held more diversified holdings. |
| • | Depositary Receipts Risk — Depositary receipts are generally subject to the same risks as the foreign securities that they evidence or into which they may be converted. In addition to investment risks associated with the underlying issuer, depositary receipts expose the Fund to additional risks associated with the non-uniform terms that apply to depositary receipt programs, credit exposure to the depository bank and to the sponsors and other parties with whom the depository bank establishes the programs, currency risk and the risk of an illiquid market for depositary receipts. The issuers of unsponsored depositary receipts are not obligated to disclose information that is, in the United States, considered material. Therefore, there may be less information available regarding these issuers and there may not be a correlation between such information and the market value of the depositary receipts. |
| • | Currency Risk — The potential risk of loss from unfavorable changes in the exchange rates between the U.S. dollar and foreign currencies. Funds that invest directly in foreign currencies, or in securities that trade in, or receive revenues in, foreign currencies, or in derivatives that provide exposure to foreign currencies are subject to the risk that those currencies will decline in value relative to the U.S. dollar, or, in the case of hedging positions, that the U.S. dollar will decline in value relative to the currency being hedged. Exchange rate volatility may affect the ability of an issuer to repay U.S. dollar denominated debt, thereby increasing credit risk. |
| • | Mid Cap Risk — The risk that the stocks of mid-capitalization companies often have greater price volatility, lower trading volume, and less liquidity than the stocks of larger, more established companies. |
| • | Small Cap Risk — Small cap companies may be more vulnerable to adverse business or economic developments. They may also be less liquid and/or more volatile than securities of larger companies or the market averages in general. Small cap companies may be adversely affected during periods when investors prefer to hold securities of large capitalization companies. |
| www.cavanalhillfunds.com | 39 | 1-800-762-7085 |
| • | Credit Risk — Credit risk is the possibility that the issuer of a debt instrument or a counterparty to an agreement fails to fulfill its obligations, reducing the Fund’s return. This includes failure by a bond issuer to repay interest and principal. |
| • | Portfolio Turnover Risk — A Fund may engage in active and frequent trading to achieve its principal investment objectives. This may result in the realization and distribution to shareholders of higher capital gains as compared to a fund with less active trading policies, which would increase an investor’s tax liability unless shares are held through a tax deferred or exempt vehicle. Frequent trading also increases transaction costs, which could detract from a Fund’s performance. |
| • | Emerging Markets Risk — Risks associated with investing in emerging market securities include potentially restrictive political and economic structures and abrupt changes to those structures, changes in price visibility and liquidity in markets and securities, fluctuations in currency exchange rates, volatility in interest rates, and sudden changes in tax policy. |
| • | Foreign Investment Risk — The risk associated with higher transaction costs, delayed settlements, currency controls or adverse economic and political developments. This also includes the risk that fluctuations in the exchange rates between the U.S. dollar and foreign currencies may negatively affect an investment. Exchange rate volatility may affect the ability of an issuer to repay U.S. dollar denominated debt, thereby increasing credit risk. Foreign securities may also be affected by incomplete or inaccurate financial information on companies. There is a risk of loss attributable to social upheavals, unfavorable governmental or political actions, seizure of foreign deposits, changes in tax or trade statutes, and governmental collapse and war. These risks are more significant in emerging markets. |
| • | High Yield Securities Risk — Fixed income securities rated below investment grade and unrated securities of similar credit quality (commonly referred to as “junk bonds” or high yield securities) are regarded as being predominantly speculative as to the issuer’s ability to make payments of principal and interest. Investments in such securities involve substantial risk. Issuers of high yield securities may be highly leveraged and may not have available to them more traditional methods of financing. Therefore, the risks associated with acquiring the securities of such issuers generally are greater than is the case with investment grade securities. The value of high yield securities tends to be very volatile due to such factors as specific corporate developments, interest rate sensitivity, less secondary market activity, and negative perceptions of high yield securities and the junk bond markets generally, particularly in times of market stress. |
| • | Exchange Traded Fund (ETF) Risk — The ETFs in which the Fund invests are subject to the risks applicable to the types of securities and investments used by the ETFs. Because an ETF charges its own fees and expenses, fund shareholders will indirectly bear these costs. The use of leverage in an ETF can magnify any price movements, resulting in high volatility. Due to daily rebalancing, leverage, and liquidity, inverse ETFs may perform worse than the inverse movement of the underlying referenced financial asset, index or commodity’s return. |
| • | Exchange Traded Note (ETN) Risk — Because ETNs are unsecured, unsubordinated debt securities, an investment in an ETN exposes the Fund to the risk that an ETN issuer’s credit rating may be downgraded. The value of an ETN may be influenced by time to maturity, level of supply and demand for the ETN, volatility and lack of liquidity in underlying securities’ markets, changes in the applicable interest rates and economic, legal, political, or geographic events that affect the referenced index. In addition, the Fund will bear its proportionate share of the fees and expenses of the ETN, which may cause the Fund’s operating expenses to be higher and its performance to be lower. |
| • | Interest Rate Risk — The value of the Fund’s interest-bearing investments may decline due to an increase in interest rates. In general, the longer a security’s maturity, the greater the interest rate risk. For a portfolio with a duration of 3 years, each 1% rise in interest rates would reduce the value of the portfolio by an estimated 3%. The Fund’s yield may decrease due to a decline in interest rates. Very low or negative interest rates may magnify interest rate risk. Future declines in interest rate levels could cause the Fund’s earnings to fall below the Fund’s expense ratio, resulting in a negative yield and a decline in the Fund’s share price. Changing interest rates, including negative interest rates, may have unpredictable effects on markets, may result in heightened market volatility and may detract from Fund performance to the extent the Fund is exposed to such interest rates. |
| www.cavanalhillfunds.com | 40 | 1-800-762-7085 |
| • | Liquidity Risk — Certain securities may be difficult or impossible to sell at the time and the price that would normally prevail in the market. The portfolio manager may have to lower the price, sell other securities instead or forego an investment opportunity, any of which could have a negative effect on Fund management or performance. This includes the risk of missing out on an investment opportunity because the assets necessary to take advantage of it are tied up in less advantageous investments. If a Fund is required to sell securities quickly or at a particular time (including sales to meet redemption requests) the Fund could realize a loss. |
| • | Management Risk — There is no guarantee that the investment techniques and risk analyses used by the Fund’s portfolio managers will produce the desired results. |
| • | Regulatory Risk — The risk that a change in laws or regulations will materially affect a security, business, sector or market. A change in laws or regulations made by the government or a regulatory body can increase the costs of operating a business, reduce the attractiveness of investment and/or change the competitive landscape. Regulatory risk also includes the risk associated with federal and state laws which may restrict the remedies that a lender has when a borrower defaults on loans. These laws include restrictions on foreclosures, redemption rights after foreclosure, federal and state bankruptcy and debtor relief laws, restrictions on “due on sale” clauses, and state usury laws. |
| • | Industrial Sector Risk — Investment risks associated with investing in industrial securities include fluctuations in economic growth, business investment, capital spending, manufacturing activity, infrastructure spending, and government procurement. Industrial companies may be adversely affected by changes in commodity and raw material costs, labor availability, supply chain disruptions, transportation costs, trade policies, tariffs, geopolitical developments, environmental regulations, and interest rates. Industrial companies may also be affected by project delays, cost overruns, changing customer demand, and cyclicality in end markets, which may adversely impact profitability and stock prices. |
| • | Technology Sector Risk — Investment risks associated with investing in technology securities include rapid technological change, product obsolescence, evolving industry standards, intense competition, and changing consumer and business preferences. Technology companies may be adversely affected by cybersecurity incidents, intellectual property disputes, regulatory developments, data privacy concerns, dependence on key personnel, and disruptions in semiconductor and other component supply chains. Technology companies often rely on innovation and future growth expectations, which can result in greater volatility and sensitivity to changes in market sentiment, earnings expectations, and economic conditions than the broader market. |
| • | Materials Sector Risk — Investment risks associated with investing in materials securities include fluctuations in commodity prices, global supply and demand conditions, industrial production, manufacturing activity, and infrastructure spending. Companies engaged in the production, processing, or distribution of metals, chemicals, construction materials, and critical minerals may be adversely affected by changes in energy costs, transportation expenses, labor availability, environmental regulations, permitting delays, trade policies, tariffs, geopolitical developments, and supply chain disruptions. Materials companies may also be affected by resource quality and availability, operational accidents, project delays, changing customer demand, and cyclicality in end markets such as construction, manufacturing, energy, and technology, which may adversely impact profitability and stock prices. |
| • | Alternative Investments Risk — Investment risks associated with investing in alternative investments include limited liquidity, reduced transparency, and the absence of a public trading market. Private companies may operate in emerging industries, rely on developing technologies, or pursue business models that have not been proven at scale, which may increase operational and financial risk. Private investments may be difficult to value and may be subject to greater valuation uncertainty than publicly traded securities. Such investments may be adversely affected by capital availability, financing conditions, regulatory developments, execution challenges, and changing market demand. Alternative investments may also be subject to restrictions on transfer, longer investment horizons, and delays in realizing value, which may result in greater volatility and could adversely impact the Fund's performance. |
| • | Valuation Risk — The risk associated with the assessment of appropriate pricing in a changing market where trading information may not be readily available. |
For more information about these risks, please refer to the section titled “Investment Practices and Risks” in the Fund’s prospectus. An investment in the Fund is not a deposit of any bank and is not insured or guaranteed by the Federal Deposit Insurance Corporation or any other government agency.
| www.cavanalhillfunds.com | 41 | 1-800-762-7085 |
Performance Information
Because it has not yet completed a full calendar year of operations, no performance information is presented for the Fund at this time. In the future, performance information will be presented in this section of the prospectus. Also, shareholder reports containing financial and performance information will be mailed to shareholders semi-annually. Updated performance information may be obtained on the Fund’s website www.cavanalhillfunds.com or by calling 1-800-762-7085.
Investment Adviser
Cavanal Hill® Investment Management, Inc. serves as the investment adviser for the Fund.
Portfolio Managers
The following individuals are primarily responsible for the day-to-day management of the Fund’s portfolio:
Matthew C. Stephani, CFA, is President of Cavanal Hill Investment Management, Inc., and has been a Portfolio Manager of the Fund since 2026.
Brandon R. Barnes, CFA, is a Senior Vice President of Cavanal Hill Investment Management, Inc. and has been a Portfolio Manager of the Fund since 2026.
Vincent H. Nguyen, CFA, is a Vice President of Cavanal Hill Investment Management, Inc. and has been a Portfolio Manager of the Fund since 2026.
Purchase and Sale of Fund Shares
The following initial and additional purchase requirements apply:
| Initial Purchase | Additional Purchases | |
| Bond and Equity Funds | ||
| A Shares | None | None |
| C Shares | None | None |
| Investor Shares | $100 | None |
| Institutional Shares | $1,000 | None |
Shares may be purchased, sold (redeemed) or exchanged on any business day by:
| • | Sending a written request by mail to the Funds Custodian: BOKF, NA, Attention: Cavanal Hill Funds, P.O. Box 182730, Columbus, Ohio 43218-2730. |
| • | Sending a written request by overnight mail to: Cavanal Hill Funds, c/o FIS Investor Services, LLC, 4249 Easton Way, Suite 400, Columbus, OH, 43219-6171. |
| • | Calling us at 1-800-762-7085 with instructions as to how you wish to complete the transaction (mail, wire, electronic transfer). |
Tax Information
The Fund’s distributions are generally taxable to you as ordinary income, capital gains, or a combination of the two, unless you are investing through a tax-deferred arrangement, such as a 401(k) plan or an individual retirement account. Retirement accounts may be taxed at a later date.
Payments to Broker-Dealers and Other Financial Intermediaries
If you purchase shares of the Fund through a broker-dealer or other financial intermediary (such as a bank), the Fund or its service providers may pay the intermediary for the sale of Fund shares and related services. These payments may create a conflict of interest by influencing the broker-dealer or other intermediary and your salesperson to recommend the Fund over another investment. Ask your salesperson or visit your financial intermediary’s website for more information. In addition, if you purchase shares that do not have any front-end sales charge, contingent deferred sales charge, or other asset-based fee for sales or distribution from a broker or other financial intermediary on an acting agency basis, you may be required to pay a commission in an amount charged and separately disclosed to you by such party.
| www.cavanalhillfunds.com | 42 | 1-800-762-7085 |
| Your Account |
Customer Identification Information
To help the government fight the funding of terrorism and money laundering activities, federal law requires all financial institutions to obtain, verify and record information that identifies each person that opens a new account, and to determine whether such person’s name appears on government lists of known or suspected terrorists and terrorist organizations.
As a result, the Funds must obtain the following information for each person that opens a new account:
| • | Name; |
| • | Date of birth (for individuals); |
| • | Residential or business street address (although post office boxes are permitted for mailing); and |
| • | Social security number, taxpayer identification number, or other identifying number. |
You may also be asked for a copy of your driver’s license, passport or other identifying document in order to verify your identity. In addition, it may be necessary to verify your identity by cross-referencing your identification information with a consumer report or other electronic database. Additional information may be required to open accounts for corporations and other entities. Federal law prohibits the Funds and other financial institutions from opening a new account unless they receive the minimum identifying information listed above. After an account is opened, the Funds may restrict your ability to purchase additional shares until your identity is verified. The Funds may close your account or take other appropriate action if they are unable to verify your identity within a reasonable time. If your account is closed for this reason, your shares will be redeemed at the net asset value (“NAV”) next calculated after the account is closed.
Each Fund will only accept new account applications and additional purchases of Fund shares from an established shareholder account that (1) reflects a residential address for an individual (or the principal place of business for an entity) located within the U.S. or its territories; or (2) reflects a U.S. military address; and (3) in every case, is associated with a valid U.S. taxpayer identification number.
Opening an Account and Buying Shares
| 1. | Read this prospectus carefully. |
| 2. | Determine how much you want to invest. |
| 3. | Complete the appropriate parts of the Account Registration Form, carefully following the instructions. You must submit additional documentation when opening trust, corporate or power of attorney accounts. For more information, please contact your financial representative or call the Funds at (800) 762-7085. |
| 4. | You may purchase Administrative Shares and Premier Shares by following the procedures established by the Distributor in connection with requirements of qualified accounts maintained by BOKF, NA, BOK Financial Securities, Inc., or other financial institutions approved by the Distributor. These procedures may include sweep arrangements where an account is “swept” automatically no less frequently than weekly into a Cavanal Hill Money Market Fund. |
The following initial and additional purchase requirements apply to the Funds*:
| Initial Purchase | Additional Purchases | |
| Bond and Equity Funds | ||
| A Shares** | None | None |
| C Shares | None | None |
| Investor Shares | $100 | None |
| Institutional Shares** | $1,000 | None |
| Money Market Funds | ||
| Administrative | $1,000 | None |
| Institutional** | $1,000 | None |
| Select | $1,000,000 | None |
| Premier | $1,000 | None |
| * | In certain circumstances approved by the Fund’s Board of Trustees, these minimums may be waived or lowered at the Fund’s discretion. Initial and additional purchase requirements are automatically waived for purchases in an account belonging to an employee of BOKF, NA, or its affiliates. With the exception of the Institutional Share Class, each Share Class offers an Auto Invest Plan, for which the minimum initial investment is $100 and the minimum for subsequent investments is $50. Please refer to the section titled “Additional Investor Services.” |
| ** | Institutional Class shares are offered to individual and institutional investors through brokers and other financial intermediaries having contractual arrangements with the Distributor. A request to purchase Class A Shares directly through the Distributor will automatically be treated as a request to purchase Institutional Shares. |
| • | Investors may purchase shares of the each of the Funds, other than the A Shares of the Bond and Equity Funds, at the net asset value without a sales charge. |
| www.cavanalhillfunds.com | 43 | 1-800-762-7085 |
| • | Shares may be offered through certain financial intermediaries that charge their customers transaction or other fees with respect to their customers’ investments in the Funds. |
| • | Each Fund reserves the right to refuse a purchase order for any reason, including if it believes that doing so would be in the best interest of the Fund or its shareholders. |
Opening an Account and Buying Shares
| OPENING AN ACCOUNT | ADDING TO AN ACCOUNT | |
| By Mail | • Make out a personal check or bank draft for the investment amount, payable to the Cavanal Hill Funds. | • Make out a personal check or bank draft for the investment amount, payable to the Cavanal Hill Funds. |
| • Deliver the check or bank draft and your completed Account Registration Form to the Funds’ Custodian at BOKF, NA, Attention: Cavanal Hill Funds, P.O. Box 182730, Columbus, Ohio 43218-2730. | • Deliver the check or bank draft and investment slip attached to your account statement (or, if unavailable, provide the Fund name, amount invested, account name, and account number) to the Funds’ Custodian at BOKF, NA, Attention: Cavanal Hill Funds, P.O. Box 182730, Columbus, Ohio 43218-2730. | |
| By Overnight Mail | • Make out a personal check or bank draft for the investment amount, payable to the Cavanal Hill Funds. | • Make out a personal check or bank draft for the investment amount, payable to the Cavanal Hill Funds. |
| • Deliver the check or bank draft and your completed Account Registration Form to c/o FIS Investor Services, LLC, 4249 Easton Way, Suite 400, Columbus, OH, 43219-6171. | • Deliver the check or bank draft and investment slip attached to your account statement (or, if unavailable, provide the Fund name, amount invested, account name, and account number) to c/o FIS Investor Services, LLC, 4249 Easton Way, Suite 400, Columbus, OH, 43219-6171. | |
| By Telephone or Wire Transfer | • Call (800) 762-7085 for instructions on opening an account by wire transfer. | • Deliver your completed Account Registration Form to the Funds at: c/o FIS Investor Services, LLC, 4249 Easton Way, Suite 400, Columbus, OH, 43219-6171. |
| • To place an order by telephone, call the Funds at (800) 762-7085 for instructions on purchasing additional shares by wire transfer. | ||
| • Your bank may charge a fee to wire funds. | ||
| By Electronic Funds Transfer | • Your bank must participate in the Automated Clearing House and must be a U.S. bank. | • Establish the electronic purchase option on your Account Registration Form or call (800) 762-7085. |
| • Call (800) 762-7085 to arrange an electronic purchase. | ||
| • Your bank may charge a fee to electronically transfer funds. | ||
All purchases made by check should be in U.S. dollars.
Third party checks, credit card checks, starter checks on initial purchases,
traveler’s checks, money orders or cash will not be accepted.
| www.cavanalhillfunds.com | 44 | 1-800-762-7085 |
| TO SELL SOME OR ALL OF YOUR SHARES | |
| By Mail | • Write a letter of instruction indicating the Fund name, your account number, the name(s) in which the account is registered and the dollar value or number of shares you wish to sell. |
| • Include the account owner signature(s). | |
| • Mail the materials to the Funds’ Custodian at BOKF, NA, Attention: Cavanal Hill Funds, P.O. Box 182730, Columbus, Ohio 43218-2730. | |
| • A check will be mailed to the name(s) and address in which the account is registered, or otherwise according to your letter of instruction. | |
| By Overnight Mail | • Write a letter of instruction indicating the Fund name, your account number, the name(s) in which the account is registered and the dollar value or number of shares you wish to sell. |
| • Include the account owner signature(s). | |
| • Mail the materials to Cavanal Hill Funds, c/o FIS Investor Services, LLC, 4249 Easton Way, Suite 400, Columbus, OH, 43219-6171. | |
| • A check will be mailed to the name(s) and address in which the account is registered, or otherwise according to your letter of instruction. | |
| By Telephone | • Call (800) 762-7085 with instructions as to how you wish to receive your funds (mail, wire, electronic transfer). |
| By Wire | • Accounts of any type which have elected the wire option on the Account Registration Form may call (800) 762-7085 to request a wire transfer. |
| • If you call on any Business Day (as described in “Transaction Policies”), your payment will normally be wired to your bank on the next Business Day. | |
| • The Fund reserves the right to charge a wire fee. | |
| • Your bank may charge a fee to wire funds. | |
| By Electronic Funds Transfer | • Shareholders with accounts at a U.S. bank which participates in the Automated Clearing House may call (800) 762-7085 to request an electronic funds transfer. |
| • If you call on any Business Day (as described in “Transaction Policies”), the NAV of your shares will be determined on the same day and you will receive your proceeds within a week after your request is received. | |
| • Your bank may charge a fee to electronically transfer funds. | |
| www.cavanalhillfunds.com | 45 | 1-800-762-7085 |
Signature Authorization. For some transactions, the Cavanal Hill Funds require proof that your signature authorizing a transaction is authentic. This verification can be provided in all cases by either a Signature Validation Program (SVP) stamp or a Medallion signature guarantee (MSG). MSG and SVP stamps can be obtained from financial institutions, including banks, broker/dealers, credit unions and savings associations. Please verify with the institution that it is an eligible guarantor institution prior to signing. In some instances, a Notary Public stamp is an acceptable alternative.
| • | Add/change banking instructions (SVP or MSG); |
| • | Add/change authorized account traders (SVP or MSG); |
| • | Change of name (Notary Public, SVP or MSG); |
| • | Add/change beneficiaries (Notary Public, SVP or MSG); |
| • | Adding a Power of Attorney (Notary Public, SVP or MSG); |
| • | Add/change Trustee (Notary Public, SVP or MSG): and |
| • | UTMA/UGMA custodian change (Notary Public, SVP or MSG). |
Selling Shares in Writing. You will need a Medallion Signature Guarantee unless:
| • | the redemption check is payable to the shareholder(s) of record, and the check is mailed to the shareholder(s) of record and mailed to the address of record, or |
| • | the redemption proceeds are being wired according to bank instructions currently on your account. |
Receiving Your Money. Properly documented redemption requests received by a Fund or an authorized agent of the Fund will be effective the day received. The Funds typically expect that it will take one to three days following the receipt of a redemption request to pay out redemption proceeds. At various times, however, a Fund may be requested to redeem shares for which it has not yet received good payment; collection of payment may take ten or more days. If you have made your initial investment by check, you cannot receive the proceeds of that check until it has cleared (which may require up to 10 business days). You can avoid this delay by purchasing shares with a certified check. You may receive proceeds of your sale in a check, wire or ACH. The Funds typically expect to hold cash or cash equivalents to meet redemption requests. The Funds may also use the proceeds from the sale of portfolio securities to meet redemption requests. As described under “Redemption In Kind” below, the Funds reserve the right to redeem in kind. Redemptions in kind are typically used to meet redemption requests that represent a large percentage of a Fund’s net assets in order to minimize the effect of large redemptions on the Fund and its remaining shareholders. These redemption methods will be used regularly in the circumstances described and may also be used in stressed market conditions.
Involuntary Sales of Your Shares. Due to the relatively high costs of handling small investments, each Fund reserves the right to redeem your shares at NAV if your account balance in any Fund, other than the A Shares of the Bond and Equity Funds, drops below $500. Each Fund also reserves the right to redeem your shares at NAV in order to comply with its responsibilities under the Investment Company Act of 1940 (the “1940 Act”). Before a Fund exercises its right to redeem your shares you will be given at least sixty days’ written notice.
Postponement of Redemption Request. The Funds may postpone payment for shares at times when the New York Stock Exchange (“NYSE”) is closed or under any emergency circumstances as determined by the Securities and Exchange Commission. If you experience difficulty making a telephone redemption during periods of drastic economic or market change, you can send the Funds your request by regular or overnight mail. Follow the instructions above under “Selling Your Shares.”
Redemption In Kind. The Funds reserve the right to make payment in securities rather than cash, known as “redemption in kind.” This could occur under extraordinary circumstances, such as a very large redemption that could affect Fund operations (for example, more than 1% of a Fund’s net assets). If a Fund deems it advisable for the benefit of all shareholders, redemption in kind will consist (in whole or in part) of securities equal in market value to your shares. In kind payment may come in the form of a pro-rata-slice of the Fund’s portfolio (potentially with certain exclusions and modifications), individual securities on a representative basket of securities, in each case, subject to regulatory guidance. When you convert these securities to cash, you will pay transaction charges.
Undeliverable Redemption and Distribution Checks. If distribution or redemption checks (1) are returned and marked as “undeliverable” or (2) remain uncashed for six months, your account will be changed automatically so that all future distributions are reinvested in your account. Checks that remain uncashed for six months will be cancelled and the money reinvested in the appropriate Fund as of the cancellation date. No interest is paid during the time the check is outstanding.
Repurchases. If you redeem Class A Shares, and within 60 days buy new Class A Shares of the same or another Cavanal Hill Fund (equal to all or at least $200 of the redemption amount), you will not pay a sales charge on the new purchase amount. This right may be exercised once a year and within 60 days of the redemption, provided that the A Shares Class of the selected Fund is currently open to new investors or the shareholder has a current account in that fund. Shares will be purchased at the NAV calculated at the close of trading on the day the request is received. To exercise this privilege, the Fund must receive written notification from the shareholder of record or the financial intermediary of record, at the time of purchase. Investors should consult a tax adviser concerning the tax consequences of exercising this reinstatement privilege.
| www.cavanalhillfunds.com | 46 | 1-800-762-7085 |
Payments to Financial Intermediaries
The Funds and their affiliated service providers may pay fees as described below to broker-dealers and other financial institutions whose customers are shareholders of the Funds, including affiliates of Cavanal Hill® Investment Management, Inc. (“Cavanal Hill Investment Management” or the “Adviser”), for sale of Fund shares and related services.
Important Notice Regarding Delivery of Shareholder Documents
To reduce expenses, we may mail only one copy of each of the Fund’s prospectus, annual report or semi-annual report to those addresses shared by two or more accounts, unless we receive contrary instruction from you. If you are a direct shareholder and wish to receive individual copies of these documents, please call us at 1-800-762-7085. If you are not a direct shareholder, please contact your financial institution to opt out of householding. We will begin sending you individual copies thirty days after receiving your request.
Initial Sales Charge (Bond and Equity Funds, Class A Shares Only)
The Class A Shares of the Bond and Equity Funds are subject to an initial sales charge. The sales charge is used to compensate participating dealers for their expenses incurred in connection with the distribution of the Class A Shares. The amount of the initial sales charge is based upon the amount purchased:
You may qualify for reduced sales charges or sales charge exceptions. To qualify for these reductions or exceptions, you or your financial adviser must notify the transfer agent and provide the necessary documentation at the time of purchase that your purchase qualifies for such treatment.
| • | Rights of Accumulation. You may combine your new purchases of Class A Shares of a Fund with other Bond or Equity Fund shares currently owned for the purpose of qualifying for the lower initial sales charge rates that apply to purchasers of more than $200,000. The applicable initial sales charge for the new purchase is based on the total of your current purchase and the value of other Bond or Equity Fund shares owned based on their current public offering price. |
| • | Letters of Intent. Under a Letter of Intent (LOI), you commit to purchase a specified dollar amount of Class A Shares of one or more Bond or Equity Funds during a 13-month period. If you agree to purchase over $200,000, you will not pay an initial sales charge. If the full amount committed in the LOI is not invested by the end of the 13-month period, your account will be assessed the higher initial sales charge that would normally be applicable to the amount actually invested. |
| • | Class A Series of the Funds may be purchased without an initial sales charge by the following persons (and their spouses and children under 21 years of age): (i) registered representatives and other employees of intermediaries that have selling agreements with the Distributor to sell Class A Shares; (ii) directors, officers, and employees of the Adviser and its affiliates; (iii) Trustees and officers of the Trust; (iv) Investors that purchase directly from the Fund. In addition, the initial sales charge may be waived on purchases of Class A Shares through financial intermediaries that have entered into an agreement with the Distributor that allows the waiver of the sales charge. The Funds do not currently have any such sales waiver agreements in place with financial intermediaries. |
| www.cavanalhillfunds.com | 47 | 1-800-762-7085 |
| • | Shareholders purchasing Fund shares through a Morgan Stanley Wealth Management brokerage account will be eligible only for the following front-end sales charge exceptions and the initial sales charge exceptions available to other investors listed immediately above are not available to investors investing through a Morgan Stanley Wealth Management brokerage account. |
| • | Employer-sponsored retirement plans (e.g., 401(k) plans, 457 plans, employer-sponsored 403(b) plans, profit sharing and money purchase pension plans and defined benefit plans). For purposes of this provision, employer-sponsored retirement plans do not include SEP IRAs, Simple IRAs, SAR-SEPs or Keogh plans |
| • | Morgan Stanley employee and employee-related accounts according to MSSB’s account linking rules |
| • | Shares purchased through reinvestment of dividends and capital gains distributions when purchasing shares of the same fund |
| • | Shares purchased through a Morgan Stanley self-directed brokerage account |
| • | Class C (i.e., level-load) shares that are no longer subject to a contingent deferred sales charge and are converted to Class A shares of the same fund pursuant to Morgan Stanley Wealth Management’s share class conversion program |
| • | Shares purchased from the proceeds of redemptions within the same fund family, provided (i) the repurchase occurs within 90 days’ following the redemption, (ii) the redemption and purchase occur in the same account, and (iii) redeemed shares were subject to a front-end or deferred sales charge. |
For further information about the initial sales charge applicable to the Class A Shares of the Bond and Equity Funds, see the Statement of Additional Information section “Additional Purchase and Redemption Information.”
Contingent Deferred Sales Charges (CDSC-Class A and C Only)
Class A Shares. Investors who purchase or own $200,000 or more of Class A Shares do not pay an initial sales charge. However, if you redeem Class A Shares purchased without paying sales charge prior to 12 months after the date of purchase, you will be subject to a CDSC of 1%. The CDSC on redemptions of shares is computed based on the lower of their original purchase price or current net asset value, net of reinvested dividends and capital gains distributions. In determining whether to charge a CDSC, shares are accounted for on a first-in, first-out basis, which means that you will redeem shares on which there is no CDSC first and, then, shares in the order of their purchase.
The Distributor will pay dealer commissions on Class A Shares trades of $200,000 or more. The amount available for such payments is:
Up to 1% of the first $4 million
plus 0.50% on the next $6 million
plus 0.25% on purchases more than $10 million
Class C Shares. Class C Shares are not subject to an initial sales charge so you will invest the full amount of your purchase price. However, Class C Shares pay an annual 12b-1 Distribution/Service Fee of 1.00% (0.75% in asset-based sales charge and 0.25% in 12b-1 service fee) and an annual Shareholder Servicing Fee of 0.25% of average net assets. Because these fees are paid out of the Fund’s assets over time, they will increase the cost of your investment and may cost you more than if you had purchased Class A Shares. Class C Shares of each Fund will automatically convert into Class A Shares of the same Fund after they have been held for ten years. This automatic conversion will be executed without any sales charge, fee or other charge. The Internal Revenue Service currently takes the position that such automatic conversions are not taxable. Should its position change, the automatic conversion feature may be replaced with a conversion option. If you sell your Class C Shares within 12 months after purchase, you may pay a 1.00% CDSC, which will be applied to the lesser of amount invested or redemption value of the shares redeemed.
Shareholders who are investing $200,000 through a sales charge reduction feature, including a shareholder eligible to purchase Class A Shares at no sales charge on a purchase of $200,000 or more of Class A Shares, or through Rights of Accumulation, an LOI or grouping purchases by certain related persons may not purchase Class C Shares. In such case, requests to purchase Class C Shares will automatically be treated as a request to purchase Class A Shares. The Fund will not apply the limitation to Class C Share purchases made by shareholders whose shares are held in an omnibus account on any of the Cavanal Hill Fund records, and it will be the selling broker-dealer’s responsibility to apply the limitation for such purchases.
Distribution/Service (12b-1) Fees
The Funds have adopted a plan under Rule 12b-1 that allows for the payment of distribution and service fees to the Distributor for the sale and distribution of shares and for additional services provided to shareholders. The Distributor pays the fees it receives to financial intermediaries whose customers purchase shares of the Funds, including financial intermediaries that are affiliates of the Adviser and Distributor. Because these fees are paid out of a Fund’s assets continuously, over time these fees will increase the cost of your investment and may cost you more than paying other types of sales charges. The distribution fee is 0.25% of the average daily net assets of the Class A, Administrative Class and Investor Shares of each Fund. The Premier Shares have a 0.50% distribution fee. The Class C Shares are subject to a 1.00% distribution fee, 0.75% of which is an asset-based sales charge and 0.25% of which is a 12b-1 service fee. The Institutional and Select Shares do not have a distribution fee. However, an investor purchasing Institutional Shares through a broker or other financial intermediary, may be required to pay a commission in an amount charged and separately disclosed to you by such party. Shares of the Funds are available in other share classes that have different fees and expenses.
| www.cavanalhillfunds.com | 48 | 1-800-762-7085 |
| Distribution Fee | Distribution Fee Waivers | |
| Bond and Equity Funds | ||
| A Shares | 0.25% | No Waiver |
| C Shares | 1.00% | No Waiver |
| Investor Shares | 0.25% | No Waiver |
| Institutional Shares | 0.00% | N/A – No 12b-1 Fee |
| Money Market Funds | ||
| Administrative | 0.25% | No Waiver |
| Institutional | 0.00% | N/A – No 12b-1 Fee |
| Select | 0.00% | N/A – No 12b-1 Fee |
| Premier | 0.50% | No Waiver |
The Funds have adopted a Shareholder Servicing Plan, under which the Funds may enter into agreements with certain financial intermediaries who will provide certain support services to the Funds’ shareholders. For performing these services, Shareholder Servicing Agents may receive an annual fee of up to 0.25% of the average daily net assets of the shares of each Fund, other than the Class A Shares of the Bond and Equity Funds, for which a fee of 0.10% of the daily net assets is available. “Shareholder Servicing Agents” may include investment advisers, brokers, financial planners, banks, insurance companies, retirement or 401(k) plan administrators and others, including affiliates of the Adviser. The Funds have entered into agreements under the Shareholder Servicing Plan with BOKF, NA, the owner of the Adviser, and BOK Financial Securities, Inc., to provide financial intermediary services to the Funds’ shareholders in exchange for payments by the Funds for such services under the Shareholder Servicing Plan. BOKF, NA and BOK Financial Securities, Inc. have agreed to the contractual fee waivers shown in the table below for the Shareholder Servicing Fees to which they are entitled. The affiliate waivers result in a reduction of the Shareholder Servicing Fee paid by all purchasers of a Class to the extent shown in the table. Contractual waivers are in place for the period through December 31, 2026, and may only be modified with the approval of the Funds’ Board of Trustees.
| Shareholder Servicing Fee | Affiliate Shareholder Servicing Fee Waivers | |
| Bond and Equity Funds | ||
| A Shares | 0.10% | Waived in Full |
| C Shares | 0.25% | Waived in Full |
| Investor Shares | 0.25% | Waived in Full |
| Institutional Shares | 0.25% | Waived in Full |
| Money Market Funds | ||
| Administrative | 0.25% | No Waiver |
| Institutional | 0.25% | 0.17% Waived |
| Select | 0.25% | Waived in Full |
| Premier | 0.25% | Waived in Full |
| www.cavanalhillfunds.com | 49 | 1-800-762-7085 |
Distribution and Shareholder Servicing Arrangements — Revenue Sharing
The Adviser, and from time to time affiliates of the Adviser, at their own expense and out of their own legitimate profits, provide additional cash incentives to Shareholder Servicing Agents in connection with the sale, distribution, retention and servicing of the shares of the Funds. These additional cash incentives, sometimes referred to as “revenue sharing arrangements,” are payments over and above the sales charges (including 12b-1 fees) and service fees paid by the Funds. These additional cash payments are generally made to Shareholder Servicing Agents that provide shareholder servicing, marketing or access to sales meetings, sales representatives and Shareholder Servicing Agent management representatives. These payments are negotiated and may be based on such factors as: the number or value of shares that the Shareholder Servicing Agent sells or may sell; the value of client assets invested; or the type and nature of services or support furnished by the Shareholder Servicing Agent. Cash compensation may also be paid to Shareholder Servicing Agents for inclusion of the Funds on a sales list including a preferred or select sales list, in other sales programs or as an expense reimbursement in cases where the Shareholder Servicing Agent provides shareholder services to Fund shareholders. The Adviser may also pay cash compensation in the form of finder’s fees that vary depending on the Fund and the dollar amount of shares sold. These payments may be significant and may create an incentive for Shareholder Servicing Agents or their agents to recommend or sell shares of the Funds to you. If you have purchased shares of a Fund through a Shareholder Servicing Agent, please speak with that agent to learn more about any payments it receives from the Adviser or its affiliates, as well as fees or commissions the agent charges. You should also consult disclosures made by your Shareholder Servicing Agent at the time of purchase. These payments are not reflected in the fees and expenses listed in the fee table section of the Funds’ prospectus, and will not change the NAV or the price of a Fund’s shares, because they are not paid by the Funds.
Commissions. If you purchase shares that do not have any front-end sales charge, contingent deferred sales charge, or other asset-based fee for sales or distribution from a broker or other financial intermediary acting on an agency basis, you may be required to pay a commission in an amount charged and separately disclosed to you by such party.
Because the Funds do not charge the fees and are not parties to any such commission arrangement between you and your broker or other financial intermediary, any purchases and redemptions will be made at the applicable NAV (before imposition of the commission) and are not reflected in the “Fees and Expenses of the Fund” section of the Funds’ Prospectus.
Brokers, Dealers and Agents. Please note that (i) investors may be charged fees—in addition to those assessed by the Funds—if they effect transactions through a Shareholder Servicing Agent, (ii) the Funds have, and may from time to time authorize one or more Shareholder Servicing Agents to receive on their behalf, purchase and redemption orders, and Shareholder Servicing Agents so authorized may also be authorized to designate other agents to receive purchase and redemption orders on the Funds’ behalf, (iii) with respect to orders received by a Shareholder Servicing Agent authorized to receive purchase and redemption orders on the Funds’ behalf, the Fund will be deemed to have received an order when an authorized agent, or, if applicable, such agent’s authorized designee, receives the order, and (iv) unless restricted by the 1940 Act and the rules of the SEC under the 1940 Act, customer orders will be priced at a Fund’s NAV next computed after such orders are received by an authorized agent or such authorized agent’s authorized designee.
How to Exchange Your Shares. Shares of any Cavanal Hill Bond or Equity Fund, other than Class C Shares, may be exchanged without payment of a sales charge for the same class of shares of any Cavanal Hill Fund. Shares of any Cavanal Hill Money Market Fund may be exchanged without payment of a sales charge for shares of the same class of any other Money Market Fund. Exchanges of shares from any Money Market Fund to any Equity or Bond Fund generally will be subject to the sales charge applicable to the shares sought to be acquired through the exchange. Shares of one share class may be exchanged for shares of another share class with a higher initial purchase requirement without payment of a sales charge if you become eligible to purchase such share class. Any exchange will be made on the basis of the relative net asset values of the shares exchanged. The Funds reserve the right to redeem in the event that a shareholder no longer meets the minimum investment requirements. The Funds reserve the right to eliminate or to alter the terms of this exchange offer upon sixty days’ notice to shareholders.
A shareholder wishing to exchange his or her shares may do so by contacting the Funds at (800) 762-7085 or by providing written instructions to the Funds at FIS Investor Services, LLC, 4249 Easton Way - Suite 400, Columbus, OH 43219-3035. Any shareholder who wishes to make an exchange must have received a current Prospectus of the Fund in which he or she wishes to invest before the exchange will be effected.
Calculation of Net Asset Value. The NAV per share of a Fund is determined by dividing the total market value of the Fund’s investments and other assets, less any liabilities, by the total number of outstanding shares of the Fund.
Valuation of Shares – Bond and Equity Funds.
| • | The NAV of each of the Bond and Equity Funds is determined as of the close of regular trading of the NYSE (generally 4 p.m. Eastern time) on each day in which the NYSE is open for regular trading (a “Business Day”). On any Business Day that the NYSE closes early, the Funds will close for trading at the time the NYSE closes. Purchase, redemption and exchange orders must be received by the NYSE close on those days to receive that day’s NAV. To the extent a Fund invests through a foreign exchange, value may change at times when a Fund shareholder is not able to trade. |
| • | The assets in each of the Bond and Equity Funds are valued at market value. If market quotations are not readily available, the securities will be valued at fair value by the Funds’ Pricing Committee. For further information about valuation of investments, see the Statement of Additional Information. |
| • | The Funds may invest in one or more open-end management investment companies that are registered under the 1940 Act. The Funds’ net asset value calculation includes the net asset values of the registered open-ended management investment companies in which the Funds invest. The prospectuses for these companies explain the circumstances under which those companies will use fair value pricing and the effects of using fair value pricing. |
| www.cavanalhillfunds.com | 50 | 1-800-762-7085 |
Valuation of Shares – Money Market Funds.
| • | The NAV of each of the Money Market Funds is determined at 4 p.m. Eastern time on each day in which the NYSE and bond market are open for regular trading (a “Business Day”). On any Business Day that the NYSE closes early, the Money Market Funds will close for trading at the time the NYSE or bond market closes. On any day when SIFMA recommends that the securities markets close trading early, each Fund may close trading early. Purchase, redemption and exchange orders must be received by the close on those days to receive that day’s NAV. |
| • | The assets in each Money Market Fund are valued based upon the amortized cost method. For further information about valuation of investments, see the Statement of Additional Information. |
| • | The NAV of each of the Money Market Funds is expected to remain at a constant $1.00 per share, although there is no assurance that this will be maintained. |
Liquidity Fees and Redemption Gates. Under Rule 2a-7, a government money market fund has the right to institute a discretionary liquidity fee (not to exceed two percent of the value of the shares redeemed) or to suspend the right of redemption (“redemption gate”) temporarily (for up to 10 business days in any 90-day period), if the Fund’s Weekly Liquid Assets fall below thirty percent of its total assets and the Fund’s Board of Trustees, including a majority of the trustees who are not interested persons of the Fund, determines that the liquidity fee or redemption gate is in the best interest of the Fund.
To the extent that the Board determines to institute a discretionary liquidity fee or a redemption gate policy on a government money market fund, it will provide not less than 60 days’ advance written notice of such policy to government money market fund shareholders and will supplement its registration statement with the appropriate disclosures.
Buy and Sell Prices. When you buy shares, you pay the NAV next determined after your order is received by the Fund or its designated agent, which could be the following Business Day. When you sell shares, you receive the NAV next determined after your order is received by the Fund or its designated agent, which could be the following Business Day.
Fair Value Pricing Policies. Each of the Bond and Equity Funds will fair value price its securities when market quotations are not readily available. Generally, this would include securities for which trading has been halted, securities whose value has been materially affected by the occurrence of a significant event (as defined below), securities whose price has become stale (i.e., the market price has remained unchanged for five business days), and other securities where a market price is not available from either a national pricing service or a broker. In addition, the Funds’ Pricing Committee will review exception priced securities (i.e., securities for which the market value is provided by a quote from a single broker rather than a national pricing service) on a quarterly basis. In these situations, the Funds’ Pricing Committee, under the general supervision of the Board of Trustees, will employ certain methodologies to determine a fair value for the securities. Fair value pricing should result in a more accurate determination of a Fund’s NAV price, which should eliminate the potential for arbitrage in a Fund.
A “significant event” is one that occurred before the valuation time, is not reflected in the most recent market price of a security, and materially affects the value of a security. Generally, such “significant events” relate to developments in foreign securities that occur after the close of trading in their respective markets. With the exception of the World Energy & Power Fund, the Funds’ foreign investments are generally limited to debt securities issued by foreign banks and foreign branches or subsidiaries of U.S. banks. Thus, the situations in which the Funds will be required to fair value price because of a significant event are limited.
Market Timing Trading Policy. The Bond and Equity Funds do not authorize, and use reasonable methods to discourage, short term or excessive trading, often referred to as “market timing.” Market timing is an investment strategy using frequent purchases, redemptions and/or exchanges in an attempt to profit from short-term market movements. Market timing or excessive trading may result in dilution of the value of fund shares held by long-term shareholders, disrupt portfolio management, and increase fund expenses for all shareholders. The Funds will take reasonable steps to discourage excessive short-term trading and the Funds’ Board of Trustees has adopted the following policies and procedures with respect to market timing. The Funds will monitor selected trades in an effort to detect excessive short-term trading. If a Fund has reason to believe that a shareholder has engaged in excessive short-term trading, the Fund may ask the shareholder to stop such activities or refuse to process purchases or exchanges in the shareholder’s accounts. In addition to rejecting purchase orders in connection with suspected market timing activities, the Funds can reject a purchase order for any reason. While the Funds cannot assure the prevention of all excessive trading and market timing, by making these judgments the Funds believe they are acting in a manner that is in the best interests of shareholders.
Market Timers may disrupt portfolio management and harm fund performance. To the extent that the Funds are unable to identify market timers effectively, long-term investors may be adversely affected. Although the Funds use a variety of methods to detect and deter market timing, due to the complexity involved in identifying excessive trading there is no assurance that the Funds efforts will identify and eliminate all trades or trading practices that may be considered abusive. In accordance with Rule 22c-2 under the 1940 Act, the Trust has entered into information sharing agreements with certain financial intermediaries. Under these agreements, a financial intermediary is obligated to: (1) adopt and enforce during the term of the agreement, a market timing policy, the terms of which are acceptable to the Trust; (2) furnish the Trust, upon its request, with information regarding customer trading activities in shares of the Trust; and (3) enforce its market-timing policy with respect to customers identified by the Trust as having engaged in market timing. When information regarding transactions in the Trust’s shares is requested by the Trust and such information is in the possession of a person that is itself a financial intermediary to a financial intermediary (an “indirect intermediary”), any financial intermediary with whom the Trust has an information sharing agreement is obligated to obtain transaction information from the indirect intermediary or, if directed by the Trust, to restrict or prohibit the indirect intermediary from purchasing shares of the Trust on behalf of other persons. The Funds apply these policies and procedures to all shareholders believed to be engaged in market timing or excessive trading. The Funds have no arrangements to permit any investor to trade frequently in shares of the funds, nor will it enter into any such arrangements in the future. Because the Money Market Funds are designed to offer investors a liquid cash option that they may sell as often as they wish, they are not subject to the same policies and procedures. We reserve the right to modify our policies and procedures related to market timing at any time without prior notice as we deem in our sole discretion to be in the best interests of Fund shareholders, or to comply with state or Federal legal requirements.
| www.cavanalhillfunds.com | 51 | 1-800-762-7085 |
Auto Invest Plan (AIP). AIP lets you set up periodic additional investments in the Funds through automatic deductions from your bank account. The plan is not available for Institutional Shares. To participate in the AIP, complete the appropriate section in the Account Registration Form. The minimum initial investment in the AIP is $100 and the minimum for subsequent investments is $50 per month or quarter per Fund. To participate in the AIP from your bank account, please attach a voided check to your Account Registration Form.
Directed Dividend Option. By selecting the appropriate box in the Account Registration Form, you can elect to receive your distributions via check or have distributions (capital gains and dividends) reinvested in another Cavanal Hill Fund without a sales charge. You must maintain the minimum balance in each Fund into which you plan to reinvest distributions or the reinvestment will be suspended and your distributions paid to you. The Fund may modify or terminate this directed dividend option without notice. You can change or terminate your participation in the directed dividend option at any time.
Systematic Withdrawal Plan (SWP). If you have at least $10,000 in your account, you may use SWP, which allows you to receive regular distributions from your account. The plan is not available for Institutional Shares of the Bond or Equity Funds. Under the plan you may elect to receive automatic payments via check of at least $100 per Fund or more on a monthly or quarterly basis. You may arrange to receive regular distributions from your account via check by completing the appropriate section in the Account Registration Form and attaching a voided check or by calling (800) 762-7085. The maximum withdrawal per year is 12% of the account value at the time of election.
As a mutual fund shareholder, you may receive capital gain, income from your investment, or both. The Bond Funds and the Money Market Funds declare dividends daily and pay dividends monthly. The Equity Funds declare and pay dividends quarterly. The Funds will distribute net investment income and net capital gain (that is, the excess of net long-term capital gain over net short-term capital loss), if any, at least once a year. It is unlikely that the Money Market Funds will realize any capital gain, however it is possible depending on market conditions.
We will automatically reinvest any income and capital-gain distributions to which you are entitled in additional shares of the applicable Fund(s) unless you notify our Distributor that you want to receive your distributions in cash. To do so, send a written request, including your name and account number, to:
Cavanal Hill Funds
c/o Cavanal Hill Distributors, Inc.
One Williams Center, 15th Floor
Bank of Oklahoma Tower
Tulsa, OK 74172
Such a request will become effective for distributions having record dates after the date on which our Distributor receives your request. The taxation of dividends will not be affected by the form in which you receive them.
Your mutual fund investments may have a material impact on your tax situation. We have summarized some of the main tax implications that you should know below. Note, however, that the following provides only a general description. The information contained herein will not apply to you if you are investing through a tax-deferred or tax-free account such as an IRA or a qualified employee benefit plan. In addition, if you are not a resident of the United States, you may have to pay taxes besides those described here, such as U.S. withholding and estate taxes. Please consult your tax adviser to see how investing in the Fund(s) will affect your own tax situation.
| • | Important Note. If you have not done so already, be sure to provide us with your correct taxpayer identification number and certify that it is correct. Unless we have that information, the Funds may be required by law to withhold a portion of the taxable distribution that you would otherwise be entitled to receive from your Fund investments as well as a portion of any proceeds that you would normally receive from selling Fund shares. |
Each Fund intends to distribute, at least annually, substantially all of its net investment income and net capital gain. We will send you a statement each year showing the tax status of all distributions that you receive from us. The laws governing taxes change frequently, however, so please consult your tax adviser for the most up-to-date information and specific guidance regarding your particular tax situation. You can find more information about the potential tax consequences of mutual fund investing in our Statement of Additional Information.
| • | Taxes on Fund Distributions. You may owe taxes on Fund distributions even if they represent income or capital gain that the Fund earned before you invested in it (and thus were included in the price you paid for your shares). |
Distributions, whether received in cash or reinvested in additional shares of a Fund, may be subject to federal income tax. For federal income tax purposes, distributions of net investment income (other than those distributions that are properly designated as exempt-interest dividends, which are discussed below) that you receive from a Fund generally are taxable as ordinary income. In general, distributions of net investment income designated by a Fund as derived from “qualified dividend income” (as further defined in the Statement of Additional Information) will be taxed at long-term capital gain tax rates provided the shareholder meets the holding-period and other requirements with respect to the Fund’s Shares. Dividends of net investment income that are not designated as derived from qualified dividend income will be taxable as ordinary income. The Funds do not expect a significant portion of Fund distributions to be derived from qualified dividend income.
| www.cavanalhillfunds.com | 52 | 1-800-762-7085 |
These dividends generally are excludable from a shareholder’s gross income for federal income tax purposes, although they might result in liability for the federal alternative minimum tax for individual shareholders and for state and local tax purposes for individual and corporate shareholders. You should consult your tax adviser concerning your own tax situation. Additionally, the receipt of exempt-interest dividends might cause recipients of social security or railroad retirement benefits to be taxed on a portion of such benefits. If you receive social security or railroad retirement benefits, you should consult your tax adviser to determine what effect, if any, an investment might have on the federal taxation of your benefits.
Taxes on distributions from a Fund of capital gain are determined by how long the Fund owned the investments that generated them, rather than how long a shareholder has owned his or her shares in the Fund. Distributions of gain from the sale of investments that a Fund owned for one year or less will be taxable as ordinary income (regardless of how long you have owned shares in the Fund). Distributions of net capital gain from the sale of investments that a Fund owned for more than one year and that are properly reported by the Fund as capital-gain dividends will be taxable as long-term capital gain (regardless of how long you have owned shares in the Fund). Capital gain of a corporate shareholder is taxed at the same rate as ordinary income.
| • | Tax Consequences of Selling or Exchanging Shares. Any gain resulting from the sale or exchange of Fund shares generally will be taxable as long-term or short-term capital gain, depending upon how long you have held your shares and assuming the shares were held as capital assets. |
| • | State and Local Taxes. In addition to federal taxes, you may have to pay state and local taxes on the dividends or capital gain, if any, you receive from a Fund, as well as on any capital gain, if any, you realize from selling or exchanging Fund shares. |
| • | Tax Consequences of Certain Fund Investments. A Fund’s investments in certain debt obligations, mortgage-backed securities, asset-backed securities, and derivative securities might require the Fund to accrue and distribute income not yet received. In order to generate sufficient cash to make the requisite distributions, the Fund might be required to liquidate other investments in its portfolio that it otherwise would have continued to hold, including at times when it is not advantageous to liquidate such investments. |
| • | Funds Investing in Foreign Securities. If a Fund invests in foreign securities, the income those securities generate may be subject to foreign withholding taxes, which might decrease their yield. Foreign governments may also impose taxes on other payments or gains that the Fund earns on these securities. In general, shareholders in such a Fund will not be entitled to claim a credit or deduction for these foreign taxes on their U.S. tax return. In addition, foreign investments may prompt a fund to distribute income more frequently or in greater amounts than do purely domestic funds, which might increase your tax liability. |
The portfolio management teams of the Funds do not actively consider tax consequences when making investment decisions. From time to time, the Funds may realize capital gain as a by-product of ordinary investment activities. As a result, the amount and timing of Fund distributions, and the amount and type of taxable income allocated to Fund investors, may vary considerably from year to year.
| www.cavanalhillfunds.com | 53 | 1-800-762-7085 |
The above is a general summary of the tax implications of investing in the Funds. Please consult your tax adviser to determine whether these considerations are relevant to your particular investments and tax situation as well as to obtain more information on your own tax situation, including possible foreign, state and local taxes. More information about taxes is contained in our Statement of Additional Information.
Additional Information about the Funds
Temporary Defensive Positions. The Funds may, from time to time, take temporary defensive positions that are inconsistent with the Funds’ principal investment strategies and investment restrictions in attempting to respond to adverse market, economic, political, or other conditions. In these and in other cases, a Fund may not achieve its investment objective. Without limiting the foregoing, during temporary defensive periods, as determined by the Adviser, each of the Limited Duration Fund, the Strategic Enhanced Yield Fund, the Bond Fund, the U.S. Treasury Fund, the Government Securities Money Market Fund and the Equity Funds may hold up to 100% of its respective total assets in cash or cash equivalents. Additional information regarding temporary defensive positions is available in our Statement of Additional Information.
Disclosure of Portfolio Holdings. Information regarding the Funds’ policies and procedures regarding the disclosure of portfolio holdings is contained in our Statement of Additional Information.
Investment in Exchange Traded Funds. The Bond and Equity Funds may each invest in index-based exchange traded funds, which are RICs unaffiliated with the Funds, that seek to replicate the performance of a stock market index or a group of stock markets in a particular geographic area. Thus, investments in exchange traded funds offer, among other things, an efficient means to achieve diversification to a particular industry that would otherwise only be possible through a series of transactions and numerous holdings. Although similar diversification benefits may be achieved through an investment in another investment company, exchange traded funds generally offer greater liquidity and lower expenses. Because an exchange traded fund charges its own fees and expenses, fund shareholders will indirectly bear these costs. The Funds will also incur brokerage commissions and related charges when purchasing shares in an exchange traded fund in secondary market transactions. Unlike typical investment company shares, which are valued once daily, shares in an exchange traded fund may be purchased or sold on a listed securities exchange throughout the trading day at market prices that are generally close to net asset value. See “Investment Practices and Risks” for information regarding the risks associated with investment in an exchange traded fund.
Exchange traded funds are investment companies. Each of the Funds may invest in securities of any RIC to the extent permitted by the Fund’s investment strategy and the applicable provisions of Section 12(d) of the 1940 Act and regulations issued by the SEC thereunder. In addition, such Funds’ investment may exceed the statutory limits in reliance on an exemptive order issued by the SEC subject to such investments being consistent with the overall objective and policies of the Fund making such investment.
Investments in Investment Companies. For purposes of the Funds’ policies that specify 80% or 99.5%, the Funds will “look through” investments in investment companies and will include such investments, as appropriate, in their respective percentage totals.
| www.cavanalhillfunds.com | 54 | 1-800-762-7085 |
| Investment Practices and Risks |
The Funds invest in a variety of securities and employ a number of investment techniques. Each security and technique involves certain risks. The information presented below includes a description of each Fund’s principal investment strategy, followed by a list of the securities and techniques used by each Fund, designated as a principal or non-principal investment, as well as the risks inherent in their use. For a more complete discussion, see the Statement of Additional Information. Descriptions of the investment instruments and the associated risks follows.
| U.S. TREASURY FUND | |
Under normal circumstances, the Fund invests at least 99.5% of its total assets in cash, U.S. Government Securities, or repurchase agreements collateralized by U.S. Government Securities and other U.S. Treasury investment companies. This policy will not be changed without at least 60 days prior notice to shareholders. The dollar-weighted average portfolio maturity of the Fund will not exceed 60 days and the dollar-weighted average portfolio life cannot exceed 120 days.
The particular types of securities in which the Fund invests, and associated risks, are provided below: | |
| INVESTMENTS | RISKS |
PRINCIPAL: Repurchase Agreements, U.S. Treasury Obligations, U.S. Treasury Investment Companies, Variable and Floating Rate Instruments |
Interest Rate, Market, Liquidity, Redemption, Floating Rate Notes, Management, Regulatory, Investment in Other Investment Companies |
NON-PRINCIPAL: Foreign Securities, Illiquid Securities, Money Market Instruments, Mortgage-Backed Securities, Reverse Repurchase Agreements, Securities Lending, Treasury Receipts, When-Issued Securities, Zero-Coupon Debt Obligations |
Banking, Credit, Credit Enhancement, Foreign Investment, Interest Rate, Issuer Specific, Leverage, Liquidity, Market, Prepayment/Call, Redemption, Regulatory, Valuation, Zero-Coupon |
| GOVERNMENT SECURITIES MONEY MARKET FUND | |
Under normal circumstances, the Fund invests at least 99.5% of its total assets in cash, U.S. Government Securities or repurchase agreements collateralized by U.S. Government Securities and other U.S. Government Security investment companies. This policy will not be changed without at least 60 days prior written notice to shareholders. The dollar-weighted average portfolio maturity of the Fund will not exceed 60 days and the dollar-weighted average portfolio life cannot exceed 120 days.
The particular types of securities in which the Fund invests, and associated risks, are provided below: | |
| INVESTMENTS | RISKS |
PRINCIPAL: Repurchase Agreements, U.S. Government Agency Securities, U.S. Treasury Obligations, U.S. Government Security Investment Companies, Variable and Floating Rate Instruments |
Interest Rate, Market, Liquidity, Redemption, Floating Rate Notes, Management, Regulatory, Investment in Other Investment Companies |
NON-PRINCIPAL:
Bonds, Foreign Securities, Illiquid Securities, Money Market Instruments, Mortgage-Backed Securities, Municipal Securities, Reverse Repurchase Agreements, Treasury Receipts, When-Issued Securities, Zero-Coupon Debt Obligations |
Banking, Credit, Credit Enhancement, Interest Rate, Issuer Specific, Leverage, Liquidity, Market, Prepayment/Call, Regulatory, Tax, Valuation, Zero-Coupon |
| www.cavanalhillfunds.com | 55 | 1-800-762-7085 |
| LIMITED DURATION FUND | |
The Fund invests primarily in debt obligations such as bonds, notes and debentures, and bills issued by U.S. corporations or by the U.S. government, its agencies or instrumentalities, municipal securities, and derivatives including mortgage-backed securities, asset-backed securities and collateralized mortgage obligations. Such debt obligations are rated at the time of purchase within the four highest ratings categories assigned by an NRSRO, or, if not rated, found by the Adviser under guidelines approved by the Trust’s Board of Trustees to be of comparable quality. The Fund also invests in money market instruments. Under normal circumstances, the Fund invests at least 80% of its net assets in bonds and maintains an average portfolio duration of less than three and one-half years. This policy will not be changed without at least 60 days prior notice to shareholders. In addition, the Fund normally invests at least 65% of its net assets in interest-bearing bonds.
The particular types of securities in which the Fund invests, and associated risks, are provided below: | |
| INVESTMENTS | RISKS |
PRINCIPAL: Asset-Backed Securities, Bonds, Collateralized Mortgage Obligations, Money Market Instruments, Mortgage-Backed Securities, Municipal Securities, U.S. Government Agency Securities, U.S. Treasury Obligations, Variable and Floating Rate Instruments |
Interest Rate, Credit, Liquidity, Prepayment/Call, Market, Mortgage-Backed, Collateralized Mortgage Obligations, Exchange Traded Fund, Asset-Backed Securities, Valuation, Turnover, Management, Regulatory |
NON-PRINCIPAL: Certificates of Deposit, Commercial Paper, Derivatives, Exchange Traded Funds, Foreign Securities, Futures and Related Options, Illiquid Securities, Investment Company Securities, Master Limited Partnerships, Repurchase Agreements, Reverse Repurchase Agreements, Restricted Securities, Securities Lending, Time Deposits, When-Issued Securities, Zero-Coupon Debt Obligations |
Banking, Credit, Credit Enhancement, Foreign Investment, High Yield Securities, Interest Rate, Issuer Specific, Leverage, Liquidity, Market, Tax, Valuation, Zero-Coupon |
| BOND FUND | |
The Fund invests, under normal market conditions, primarily in debt obligations such as bonds, notes and debentures, and bills issued by U.S. corporations or by the U.S. government, its agencies, or instrumentalities, municipal securities, and derivatives including mortgage-backed securities, asset-backed securities and collateralized mortgage obligations. Such debt obligations are rated at the time of purchase within the four highest ratings categories assigned by an NRSRO, or, if not rated, found by the Adviser under guidelines approved by the Trust’s Board of Trustees to be of comparable quality. The Fund also invests in money market instruments. The Fund will generally maintain a dollar-weighted average portfolio maturity of three to ten years. Under normal circumstances the Fund invests at least 80% of its net assets in bonds. This policy will not be changed without at least 60 days prior notice to shareholders.
The particular types of securities in which the Fund invests, and associated risks, are provided below: | |
| INVESTMENTS | RISKS |
PRINCIPAL: Asset-Backed Securities, Bonds, Collateralized Mortgage Obligations, Money Market Instruments, Mortgage-Backed Securities, Municipal Securities, U.S. Government Agency Securities, U.S. Treasury Obligations, Variable and Floating Rate Instruments |
Interest Rate, Credit, Liquidity, Prepayment/Call, Market, Mortgage-Backed Securities, Collateralized Mortgage Obligations, Exchange Traded Fund, Asset-Backed Securities, Valuation, Management, Regulatory |
NON-PRINCIPAL: Certificates of Deposit, Commercial Paper, Derivatives, Exchange Traded Funds, Foreign Securities Futures and Related Options, Illiquid Securities, Investment Company Securities, Master Limited Partnerships, Repurchase Agreements, Reverse Repurchase Agreements, Restricted Securities, Securities Lending, Time Deposits, Variable and Floating Rate Instruments, When-Issued Securities, Zero-Coupon Debt Obligations |
Banking, Credit, Credit Enhancement, Foreign Investment, High Yield Securities, Interest Rate, Issuer Specific, Leverage, Liquidity, Market, Regulatory, Tax, Valuation, Zero-Coupon |
| www.cavanalhillfunds.com | 56 | 1-800-762-7085 |
| STRATEGIC ENHANCED YIELD FUND | |
The Fund seeks to achieve its investment objective by investing in a diversified portfolio of fixed income instruments of varying maturities. In an effort to actively enhance total return and minimize risk, the Fund will engage in opportunistic trading among various sectors based on the perceived market anomalies and inefficiencies detected by the Fund’s portfolio managers, which may be found in illiquid or thinly traded securities and those that may not accurately reflect relevant market information. Total return is defined as a percentage change, over a specified time period, in a mutual fund’s net asset value, with the ending net asset value adjusted to account for the reinvestment of all distributions of dividends and capital gains. Under normal circumstances, the Fund invests at least 80% of its net assets in fixed income instruments. This investment policy will not be changed by the Fund without at least 60 days’ prior notice to shareholders.
The particular types of securities in which the Fund invests, and associated risks, are provided below: | |
| INVESTMENTS | RISKS |
PRINCIPAL: Asset-Backed Securities, Bonds, Collateralized Mortgage Obligations, Derivatives, Exchange Traded Funds, Foreign Securities, Money Market Instruments, Mortgage-Backed Securities, Municipal Securities, U.S. Government Agency Securities, U.S. Treasury Obligations |
Credit, Market, Liquidity, Interest Rate, Foreign Investment, Valuation, Non-U.S. Denominated Currency, Emerging Market, Prepayment/Call, High Yield Securities, Mortgage-Backed Securities, Asset Backed Securities, Derivative, Leverage, Private/Restricted Securities, Redemption, Floating Rate Notes, Hedging, Management, Regulatory |
NON-PRINCIPAL: ADR/EDR/GDRs, Bankers’ Acceptances, Call and Put Options, Certificates of Deposit, Commercial Paper, Foreign Securities Futures and Related Options, Illiquid Securities, Investment Company Securities, Master Limited Partnerships, Repurchase Agreements, Reverse Repurchase Agreements, Securities Lending, Time Deposits, Variable and Floating Rate Instruments, When-Issued Securities, Zero-Coupon Debt Obligations |
Banking, Credit, Credit Enhancement, Foreign Investment, Interest Rate, Issuer Specific, Leverage, Liquidity, Market, Regulatory, Tax, Valuation, Zero-Coupon |
| WORLD ENERGY & POWER FUND | |
Under normal circumstances, the Fund invests at least 80% of its net assets in a wide range of energy-related financial instruments issued in the U.S. and markets around the world. This policy will not be changed without at least 60 days prior notice to shareholders. Investments generally include a combination of equities, derivatives, bonds, ETFs and ETNs.
The particular types of securities in which the Fund invests, and associated risks, are provided below: | |
| INVESTMENTS | RISKS |
PRINCIPAL: ADR/EDR/GDRs, Bonds, Common Stock, Emerging Market Securities, Exchange Traded Funds, Exchange Traded Notes, Foreign Securities, Investment Company Securities, Master Limited Partnerships, Money Market Instruments, Variable and Floating Rate Instruments |
Market, Energy Industry, Issuer Specific, Concentration, Commodity, Depositary Receipts, Currency, Mid Cap, Small Cap, Credit, Portfolio Turnover, Emerging Market, Foreign Investment, High Yield Securities, Exchange Traded Fund, Exchange Traded Note, Interest Rate, Liquidity, Management, Valuation, Master Limited Partnership, Regulatory |
NON-PRINCIPAL: Asset-Backed Securities, Commodity Exposure Instruments, Call and Put Options, Convertible Securities, Currencies, Derivatives, Futures and Related Options, Illiquid Securities, Inverse Exchange Traded Funds, Municipal Securities, Preferred Stock, Private Funds, Repurchase Agreements, Restricted Securities, Time Deposits, U.S. Treasury Obligations, When-Issued Securities, Zero-Coupon Debt Obligations |
Banking, Credit, Derivative, Income, Interest Rate, Inverse ETF, Issuer Specific, Leverage, Liquidity, Market, Pre-payment/Call, Regulatory, Short Sale, Valuation, Tax, Zero-Coupon |
| www.cavanalhillfunds.com | 57 | 1-800-762-7085 |
| HEDGED EQUITY INCOME FUND | |
| Under normal circumstances, the Fund invests primarily in dividend paying equity securities, with at least 80% of its net assets in income generating equity securities and equity-related instruments traded on U.S. exchanges. For purposes of this policy, the Fund includes common stocks and securities convertible into common stocks of companies with any market capitalization and sponsored or unsponsored American Depositary Receipts (ADRs). Under normal circumstances, the fund will seek to generate current earnings income. Some of the income will be distributed to shareholders in the form of dividends from portfolio securities; income will also be generated from option premiums by writing (selling) call options on its portfolio securities, all of which will be covered calls. A covered call refers to a financial transaction in which the investor selling a call option owns an equivalent amount of the underlying security. The investor’s ownership of the long position in the asset is the “cover” because the seller can deliver the shares if the buyer of the call option chooses to exercise. The fund seeks to produce current income from dividends and, to a lesser extent, from option writing premiums. Because of the tax treatment options activity receives, call premium income may not be distributed to shareholders. The Fund will buy index and ETF puts as well as puts on individual securities to provide downside market protection for the portfolio. | |
| INVESTMENTS | RISKS |
PRINCIPAL: Common Stock, Call and Put Options, Derivatives, ADR/EDR/GDRs, Money Market Instruments |
Market, Issuer Specific, Derivative, Call and Put Options, Hedging, Depository Risks, Tax Risks, Limited Number of Holdings, Non-Diversification, Management, Dividend Paying Security, Mid Cap, Small Cap |
NON-PRINCIPAL: Exchange Traded Funds, Exchange Traded Notes, Futures and Related Options, Investment Company Securities, Preferred Stock, When-Issued Securities |
Banking, Credit, Exchange Traded Fund, Exchange Traded Note, Interest Rate, Issuer Specific, Leverage, Liquidity, Market, Preferred Stock, Regulatory, Valuation |
| INDUSTRIAL FRONTIER FUND | |
| Under normal circumstances, the Fund invests at least 80% of its net assets in a wide range of companies in the “industrial frontier,” which will include traditional industry sector companies and those that benefit from mega-trends identified by the Fund’s portfolio managers. More specifically, a company is an industrial frontier company if, at the time of investment, it satisfies at least one of the following: (a) classified as Industrial by the Global Industry Classification Standard (GICS®) or a comparable third-party classification system; (b) derives at least 50% of its revenues from industrial end markets, including sales to customers in manufacturing, transportation and logistics, aerospace and defense, construction and engineering, commercial and professional services, trading companies and distributors, and industrial real estate, or (c) classified as Technology or Materials by the GICS, or a comparable third-party classification system, and the portfolio managers of the fund determine that at least 50% of the company’s revenues are derived from participation in industrial mega-trends. While such trends may shift over time as themes mature and new themes emerge, examples of mega-trends could include: buildout of artificial intelligence infrastructure; onshoring of manufacturing back to the U.S. from abroad; geopolitical events driving increases in defense spending and modernization; development of physical alternative intelligence applications, including robotics; emergence of space-related commerce; structural requirements for electrical power and cybersecurity. | |
| INVESTMENTS | RISKS |
PRINCIPAL: ADR/EDR/GDRs, Alternative Investments, Bonds, Common Stock, Exchange Traded Funds, Exchange Traded Notes, Money Market Instruments, Variable and Floating Rate Instruments |
Market, Issuer Specific, Concentration, Depositary Receipts, Currency, Exchange Traded Fund, Exchange Traded Note, Mid Cap, Small Cap, Credit, Portfolio Turnover, Emerging Market, Foreign Investment, High Yield Securities, Interest Rate, Liquidity, Management, Valuation, Regulatory, Industrial Sector, Technology Sector, Materials Sector |
NON-PRINCIPAL: Asset-Backed Securities, Illiquid Securities, Inverse Exchange Traded Funds, Master Limited Partnerships, Municipal Securities, Investment Company Securities, Preferred Stock, Repurchase Agreements, Restricted Securities, Time Deposits, U.S. Treasury Obligations, When-Issued Securities, Zero-Coupon Debt Obligations |
Banking, Credit, Income, Interest Rate, Inverse ETF, Issuer Specific, Leverage, Liquidity, Market, Pre-payment/Call, Regulatory, Valuation, Tax, Zero-Coupon |
| www.cavanalhillfunds.com | 58 | 1-800-762-7085 |
| Investment Instruments |
Below is a more complete description of the types of securities and investment techniques listed above and the risks inherent in their use.
| INSTRUMENT | RISK TYPE | |
American Depositary Receipts (ADRs), European Depositary Receipts (EDRs) and Global Depositary Receipts (GDRs): ADRs are foreign shares of a company held by a U.S. bank that issues a receipt evidencing ownership. EDRs are receipts issued in Europe, typically by foreign banks and trust companies, that evidence ownership of either foreign or domestic underlying securities. GDRs are depositary receipts structured as global debt issues to facilitate trading on an international basis. |
• Depository Receipts • Foreign Investment • Issuer Specific |
• Market • Regulatory |
Alternative Investments: Investments that fall outside traditional asset classes such as public equities, bonds, and cash equivalents. Examples include private equity, venture capital, hedge funds, direct private investment, interval funds, business development companies, tender offer funds, and real assets among other investments. |
• Credit • Interest Rate • Issuer Specific • Leverage • Liquidity |
• Management • Market • Regulatory • Tax • Valuation |
Asset-Backed Securities: Securities secured by company receivables, home equity loans, truck and auto loans, leases, credit card receivables and other securities backed by other types of receivables or other assets. |
• Credit • Interest Rate • Issuer Specific • Liquidity • Market |
• Pre-payment • Regulatory • Valuation |
Bankers’ Acceptances: Bills of exchange or time drafts drawn on and accepted by a commercial bank. Maturities are generally six months or less. |
• Banking • Credit • Interest Rate • Issuer Specific |
• Liquidity • Market • Regulatory |
Bonds: Interest-bearing or discounted government, municipal, or corporate securities that obligate the issuer to pay the bondholder a specified sum of money, usually at specific intervals, and to repay the principal amount of the loan at maturity. |
• Banking • Credit • High Yield Securities • Interest Rate • Issuer Specific |
• Liquidity • Market • Prepayment/Call • Regulatory |
Call and Put Options: A call option gives the buyer the right to buy, and obligates the seller of the option to sell, a security at a specified price. A put option gives the buyer the right to sell, and obligates the seller of the option to buy a security at a specified price. The Funds may buy options and, if they sell options, will sell only covered call and secured put options. |
• Credit • Derivative • Issuer Specific • Leverage |
• Liquidity • Market • Regulatory |
Certificates of Deposit: Negotiable instruments with a stated maturity. |
• Banking • Credit • Interest Rate • Issuer Specific |
• Liquidity • Market • Regulatory |
Collateralized Mortgage Obligations: A fixed income security that uses mortgage-backed securities as collateral. |
• Credit • Interest Rate • Issuer Specific • Liquidity |
• Market • Pre-payment • Regulatory • Valuation |
Commercial Paper: Secured and unsecured short-term promissory notes issued by corporations and other entities including foreign entities. Maturities generally vary from a few days to nine months. |
• Banking • Credit • Issuer Specific • Liquidity |
• Interest Rate • Foreign Investment • Market • Regulatory |
Commodity Exposure Instruments: Commodity-linked derivative instruments, commodity futures, options on commodity futures contracts and commodity-focused ETFs. |
• Commodity • Credit • Derivative • Interest Rate • Issuer Specific |
• Leverage • Liquidity • Market • Regulatory • Valuation |
Common Stock: Shares of ownership of a company. |
• Banking • Issuer Specific • Liquidity • Market |
• Mid Cap • Regulatory • Small Cap |
| www.cavanalhillfunds.com | 59 | 1-800-762-7085 |
| INSTRUMENT | RISK TYPE | |
Convertible Securities: Bonds or preferred stock that convert to common stock. |
• Credit • Interest Rate • Issuer Specific |
• Liquidity • Market • Regulatory |
Currencies: Obligations of foreign governments. |
• Banking • Credit • Foreign Investment |
• Interest Rate • Market • Regulatory |
Derivatives: Instruments whose value is derived from the value of an underlying asset, contract, reference rate, index or security, or any combination thereof. |
• Credit • Interest Rate • Issuer Specific • Liquidity |
• Leverage • Market • Regulatory • Valuation |
Exchange Traded Funds: Securities that are issued by investment companies and traded on securities exchanges. Each of the Funds, except the U.S. Treasury and the Government Securities Money Market Fund, may invest in securities of any RIC to the extent permitted by the Fund’s investment strategy and the applicable statutory limits under the 1940 Act, SEC regulations and exemptive orders. |
• Interest Rate • Issuer Specific • Liquidity |
• Market • Regulatory |
Exchange Traded Notes: A senior, unsecured, unsubordinated debt security issued by an underwriting bank and traded on securities exchanges. Similar to other debt securities, ETNs have a maturity date and are backed only by the credit of the issuer. The returns of ETNs are usually linked to the performance of a market benchmark; as debt securities, ETNs don’t own securities in the index tracked. |
• Credit • Interest Rate • Issuer Specific • Leverage |
• Liquidity • Market • Regulatory |
Foreign Securities: Stocks, bonds, and money market securities issued by foreign companies including obligations of foreign banks, overseas branches of U.S. banks and supranational entities. |
• Banking • Emerging Market • Foreign Investment • Interest Rate |
• Issuer Specific • Liquidity • Market • Regulatory |
Futures and Related Options: A contract providing for the future sale and purchase of a specified amount of a specified security, class of securities, or an index at a specified time in the future and at a specified price. |
• Credit • Derivative • Interest Rate • Issuer Specific |
• Leverage • Liquidity • Market • Regulatory |
Illiquid Securities: Illiquid securities are those securities which cannot be disposed of in the ordinary course of business, seven days or less, at approximately the value at which the Fund has valued the securities. |
• Interest Rate • Issuer Specific • Liquidity |
• Market • Regulatory • Valuation |
Inverse Exchange Traded Funds: An exchange traded fund that is constructed by using various derivatives for the purpose of profiting from a decline in the value of an underlying benchmark. |
• Interest Rate • Inverse ETF • Issuer Specific |
• Liquidity • Market |
Investment Company Securities: Each of the Funds may invest in securities of any RIC to the extent permitted by the Fund’s investment strategy and the applicable statutory limits under the 1940 Act and rules, regulations and exemptive orders issued by the SEC thereunder. |
• Issuer Specific • Market |
• Regulatory |
Loan Participation Interests: Loan participation interests are interests in bank loans made to corporations. In these arrangements the bank transfers the cash stream of the underlying bank loan to the participating investor. |
• Credit • Interest Rate • Issuer Specific |
• Liquidity • Market • Regulatory |
Master Limited Partnerships (MLPs): MLPs are partnerships that are publicly traded on a securities exchange. Typical limited partnerships are in real estate, oil and gas and equipment leasing, and they also finance movies, research and development, and other projects. |
• Issuer Specific • Market • Master Limited Partnership |
• Regulatory |
| www.cavanalhillfunds.com | 60 | 1-800-762-7085 |
| INSTRUMENT | RISK TYPE | |
Money Market Instruments: U.S. dollar-denominated debt securities that have remaining maturities of 397 days or less. These securities may include U.S. government obligations, commercial paper and other short-term corporate obligations, repurchase agreements collateralized with U.S. government securities, certificates of deposit, bankers’ acceptances, and other financial institution obligations. These securities may carry fixed or variable interest rates. |
• Banking • Credit • Interest Rate • Issuer Specific |
• Liquidity • Market • Regulatory |
Mortgage-Backed Securities: Debt obligations secured by real estate loans and pools of loans. These include collateralized mortgage obligations and real estate mortgage investment conduits. |
• Banking • Credit • Interest Rate • Issuer Specific • Liquidity |
• Market • Regulatory • Pre-payment • Valuation |
Municipal Securities: Securities issued by a state or political subdivision to obtain funds for various public purposes. |
• Banking • Credit • Interest Rate • Issuer Specific • Liquidity |
• Market • Municipal Bond • Prepayment/Call • Regulatory • Tax |
Preferred Stock: Preferred stocks are equity securities that generally pay dividends at a specified rate and have preference over common stock in the payment of dividends and liquidation. Preferred stock generally does not carry voting rights. |
• Issuer Specific • Market |
• Regulatory |
Repurchase Agreements: The purchase of a security and the simultaneous commitment to return the security to the seller at an agreed upon price on an agreed upon date. This is treated as a loan by a Fund. |
• Banking • Credit • Interest Rate • Issuer Specific |
• Liquidity • Market • Regulatory |
Reverse Repurchase Agreements: The sale of a security and the simultaneous commitment to buy the security back at an agreed upon price on an agreed upon date. This is treated as a borrowing by a Fund. |
• Banking • Credit • Interest Rate • Issuer Specific |
• Leverage • Liquidity • Market • Regulatory |
Restricted Securities: Securities not registered under the Securities Act of 1933, such as privately placed commercial paper and Rule 144A securities. |
• Interest Rate • Issuer Specific • Liquidity |
• Market • Regulatory |
Securities Lending: The lending of up to 33 1/3% of a Fund’s total assets. In return the Fund will receive cash, other securities, or letters of credit. |
• Credit • Issuer Specific • Leverage |
• Liquidity • Market • Regulatory |
Time Deposits: Non-negotiable receipts issued by a bank in exchange for the deposit of funds. |
• Banking • Credit • Interest Rate • Issuer Specific |
• Liquidity • Market • Regulatory |
Treasury Receipts: Treasury receipts, Treasury investment growth receipts, and certificates of accrual of Treasury securities. |
• Interest Rate • Issuer Specific |
• Market • Regulatory |
U.S. Government Agency Securities: Securities issued by agencies and instrumentalities of the U.S. government, but not guaranteed or insured by the U.S. government. These include Fannie Mae and Freddie Mac. |
• Credit • Interest Rate • Issuer Specific • Liquidity |
• Market • Prepayment/Call • Regulatory |
U.S. Government Securities: Include U.S. Treasury Obligations and U.S. Government Agency Securities. |
• Credit • Interest Rate • Issuer Specific • Liquidity |
• Market • Prepayment/Call • Regulatory |
U.S. Treasury Obligations: Bills, notes and bonds that are direct obligations of the U.S. government. |
• Interest Rate • Issuer Specific |
• Market • Regulatory |
Variable and Floating Rate Instruments: Obligations with interest rates which are reset daily, weekly, quarterly or some other period and which may be payable to the Fund on demand. |
• Banking • Credit • Interest Rate • Issuer Specific |
• Liquidity • Market • Regulatory • Credit Enhancement |
When-Issued Securities: Contract to purchase securities at a fixed price for delivery at a future date. |
• Credit • Interest Rate • Issuer Specific |
• Liquidity • Market • Regulatory |
Zero-Coupon Debt Obligations: Bonds and other debt that pay no interest, but are issued at a discount from their value at maturity. When held to maturity, their entire return equals the difference between their issue price and their maturity value. |
• Credit • Interest Rate • Issuer Specific |
• Market • Regulatory • Zero-Coupon |
| www.cavanalhillfunds.com | 61 | 1-800-762-7085 |
| Investment Risks |
Below is a more complete discussion of the types of risks inherent in the securities and investment techniques listed above as well as those risks discussed in “Principal Investment Risks.” Because of these risks, the value of the securities held by each Fund may fluctuate, as will the value of your investment in the Fund. Certain investments and Funds are more susceptible to these risks than others.
| • | Alternative Investments Risk — Investment risks associated with investing in alternative investments include limited liquidity, reduced transparency, and the absence of a public trading market. Private companies may operate in emerging industries, rely on developing technologies, or pursue business models that have not been proven at scale, which may increase operational and financial risk. Private investments may be difficult to value and may be subject to greater valuation uncertainty than publicly traded securities. Such investments may be adversely affected by capital availability, financing conditions, regulatory developments, execution challenges, and changing market demand. Alternative investments may also be subject to restrictions on transfer, longer investment horizons, and delays in realizing value, which may result in greater volatility and could adversely impact the Fund's performance. |
| • | Asset-Backed Securities Risk — Payment of interest and repayment of principal may be impacted by the cash flows generated by the assets backing asset-backed securities. The value of the Fund’s asset-backed securities may also be affected by changes in interest rates, the availability of information concerning the interests in and structure of the pools of purchase contracts, financing leases or sales agreements that are represented by these securities, the creditworthiness of the servicing agent for the pool, the originator of the loans or receivables, or the entities that provide any supporting letters of credit, surety bonds, or other credit enhancements. |
| • | Banking Risk — To the extent that a Fund invests in securities issued by U.S. Banks, foreign banks or U.S. branches of foreign banks, the Fund’s performance will be susceptible to the risks associated with the financial services sector. The financial services sector is highly dependent on the supply of short-term financing. The value of securities of issuers in the banking and financial services sector can be sensitive to changes in government regulation and interest rates and to economic downturns in the United States and abroad. |
| • | Call Options Risk — Investments in call options involve risks different from, or possibly greater than, the risks associated with investing directly in securities, including leverage risk, tracking risk and counterparty default risk. The risk of potential losses if equity markets or an individual equity security do not move as expected and the potential for greater losses than if these techniques had not been used. By writing covered call options, a fund will not benefit from any potential increases in the value of the underlying asset above the exercise price, but will bear the risk of declines in the value of the asset. As the seller (writer) of a call option, the Fund will tend to lose money if the value of the reference index or security rises above the strike price. As the buyer of a call option, the Fund risks losing the entire premium invested if the value of the reference index or security is below (above) the call strike at maturity. Writing of covered call options are also subject to the risk that the counterparty to the transaction will not fulfil its obligations. |
| • | Collateralized Mortgage Obligations Risk — There are risks associated with collateralized mortgage obligations that relate to the risks of the underlying mortgage pass-through securities (i.e., an increase or decrease in prepayment rates, resulting from a decrease or increase in mortgage interest rates, will affect the yield, average life, and price of collateralized mortgage obligations). |
| • | Commodity Risk — Investments in commodity futures may be more volatile than the price of the underlying commodity. The Fund’s exposure to commodities may subject the Fund to greater volatility than investments in traditional securities. The commodities markets may fluctuate widely based on a variety of factors, including changes in overall market movements, domestic and foreign political and economic events and policies, war, acts of terrorism, changes in domestic or foreign interest rates and/or investor expectations concerning interest rates, domestic and foreign inflation rates and investment and trading activities of mutual funds, hedge funds and commodities funds. Prices of various commodities may also be affected by factors such as weather, embargoes, tariffs and other regulatory developments. The prices of commodities can also fluctuate widely due to supply and demand disruptions in major producing or consuming regions. Investments in commodity futures may be more volatile than the price of the underlying commodity. |
| • | Concentration Risk — A concentrated portfolio may add a measure of volatility to performance, as major or in a particular sector of the economy will likely affect the fund more than a fund with greater diversification. |
| • | Credit Risk — The risk that the issuer of a security, or the counterparty to a contract, will default or otherwise become unable to honor a financial obligation. Credit risk is generally higher for non-investment grade securities. The price of a security can be adversely affected prior to actual default as its credit status deteriorates and the probability of default rises. Credit risk includes the risk that performance may be affected by political and economic factors at the state, regional or national level, including budgetary problems and declining tax bases. With respect to government sponsored entities such as FHLB, TVA, Fannie Mae, FFCB and Freddie Mac, though the issuer may be chartered or sponsored by Acts of Congress, their securities are neither insured nor guaranteed by the U.S. Treasury and therefore have more issuer default risk than any direct obligations of the U.S. Treasury or obligations guaranteed by the U.S. government. In the event that those government sponsored entities cannot meet their obligations, there can be no assurance that the U.S. government would provide support, and the Fund’s performance could be adversely affected. Direct obligations of the U.S. Treasury and obligations guaranteed by the U.S. government generally present minimal credit risks. However, repurchase agreements with respect to such obligations involve the risks of a default or insolvency of the other party to the agreement, including possible delays or restrictions on a Fund’s ability to dispose of the underlying securities. |
| • | Credit Enhancement Risk — Credit enhancement risk involves the possibility that a “credit enhancer,” such as a letter of credit, declines in quality and therefore leads to a decrease in the value of the Fund’s investments. |
| www.cavanalhillfunds.com | 62 | 1-800-762-7085 |
| • | Currency Risk — The potential risk of loss from unfavorable changes in the exchange rates between the U.S. dollar and foreign currencies. Funds that invest directly in foreign currencies, or in securities that trade in, or receive revenues in, foreign currencies, or in derivatives that provide exposure to foreign currencies are subject to the risk that those currencies will decline in value relative to the U.S. dollar, or, in the case of hedging positions, that the U.S. dollar will decline in value relative to the currency being hedged. Exchange rate volatility may affect the ability of an issuer to repay U.S. dollar denominated debt, thereby increasing credit risk. |
| • | Cyber Security Risk — As the use of the internet and other technologies has become more prevalent in the course of business, the Funds have become more susceptible to operational and financial risks associated with cyber security. Cyber security incidents can result from deliberate attacks such as gaining unauthorized access to digital systems (e.g., through “hacking” or malicious software coding) for purposes of misappropriating assets or sensitive information, corrupting data, or causing operational disruption, or from unintentional events, such as the inadvertent release of confidential information. Cyber security failures or breaches of the Funds or their service providers or the issuers of securities in which the Funds invest have the ability to cause disruptions and impact business operations, potentially resulting in financial losses, the inability of Fund shareholders to transact business, violations of applicable privacy and other laws, regulatory fines, penalties, reputational damage, reimbursement or other compensation costs, and/or additional compliance costs. While measures have been developed which are designed to reduce the risks associated with cyber security, there is no guarantee that those measures will be effective, particularly since the Funds do not directly control the cyber security defenses or plans of their service providers, financial intermediaries and companies in which they invest or with which they do business. |
| • | Depositary Receipts Risk — Depositary receipts are generally subject to the same risks as the foreign securities that they evidence or into which they may be converted. In addition to investment risks associated with the underlying issuer, depositary receipts expose the Fund to additional risks associated with the non-uniform terms that apply to depositary receipt programs, credit exposure to the depository bank and to the sponsors and other parties with whom the depository bank establishes the programs, currency risk and the risk of an illiquid market for depositary receipts. The issuers of unsponsored depositary receipts are not obligated to disclose information that is, in the United States, considered material. Therefore, there may be less information available regarding these issuers and there may not be a correlation between such information and the market value of the depositary receipts. |
| • | Derivative Risk — The risk of investing in derivative instruments, including liquidity, interest rate, market, credit and management risks, mispricing or improper valuation. Changes in the value of a derivative may not correlate perfectly with the underlying asset, rate or index, and the Fund could lose more than the principal amount invested. |
| • | Dividend Paying Security Risk — The fund’s investment in dividend-paying stocks could cause the fund to underperform similar funds that invest without consideration of a company’s track record of paying dividends. Stock of companies with a history of paying dividends may not participate in a broad market advance to the same degree as most other stocks, and a sharp rise in interest rates or economic downturn could cause a company to unexpectedly reduce or eliminate its dividend. |
| • | Emerging Market Risk — Risks associated with investing in emerging market securities include potentially restrictive political and economic structures and abrupt changes to those structures, changes in price visibility and liquidity in markets and securities, fluctuations in currency exchange rates, volatility in interest rates, and sudden changes in tax policy. |
| • | Energy Industry Risk — Investment risks associated with investing in energy securities include price fluctuation caused by real and perceived inflationary trends and political developments, the cost assumed in complying with environmental regulation, changes in environmental regulation, energy conservation, demand for energy resources, fluctuations in energy prices, exploration and production spending, technological developments, depletion of resources, import controls, weather, world events and economic conditions. |
| • | Exchange Traded Fund (ETF) Risk — The ETFs in which the Fund invests are subject to the risks applicable to the types of securities and investments used by the ETFs. Because an ETF charges its own fees and expenses, fund shareholders will indirectly bear these costs. The use of leverage in an ETF can magnify any price movements, resulting in high volatility. Due to daily rebalancing, leverage, and liquidity, inverse ETFs may perform worse than the inverse movement of the underlying referenced financial asset, index or commodity’s return. |
| • | Exchange Traded Note (ETN) Risk — Because ETNs are unsecured, unsubordinated debt securities, an investment in an ETN exposes the Fund to the risk that an ETN issuer’s credit rating may be downgraded. The value of an ETN may be influenced by time to maturity, level of supply and demand for the ETN, volatility and lack of liquidity in underlying securities’ markets, changes in the applicable interest rates and economic, legal, political, or geographic events that affect the referenced index. In addition, the Fund will bear its proportionate share of the fees and expenses of the ETN, which may cause the Fund’s operating expenses to be higher and its performance to be lower. |
| • | Floating Rate Notes Risk — Securities with floating or variable interest rates can be less sensitive to interest rate changes than securities with fixed interest rates, but may decline in value if their coupon rates do not reset as high, or as quickly, as comparable market interest rates, and generally carry lower yields than fixed notes of the same maturity. |
| www.cavanalhillfunds.com | 63 | 1-800-762-7085 |
| • | Foreign Investment Risk — The risk associated with higher transaction costs, delayed settlements, currency controls or adverse economic and political developments. This also includes the risk that fluctuations in the exchange rates between the U.S. dollar and foreign currencies may negatively affect an investment. Exchange rate volatility may affect the ability of an issuer to repay U.S. dollar denominated debt, thereby increasing credit risk. Foreign securities may also be affected by incomplete or inaccurate financial information on companies. There is a risk of loss attributable to social upheavals, unfavorable governmental or political actions, seizure of foreign deposits, changes in tax or trade statutes, and governmental collapse and war. These risks are more significant in emerging markets. |
| • | Hedging Risk — The risk that the stocks in the portfolio may decrease in value more than the increase in value of the put options. Puts that are purchased on ETFs or indexes do not hedge the company-specific risk of stocks owned in the portfolio. Hedging may not be effective based on timing, the underlying instrument hedged, or duration of the hedge. |
| • | High Yield Securities Risk — Fixed income securities rated below investment grade and unrated securities of similar credit quality (commonly referred to as “junk bonds” or high yield securities) are regarded as being predominantly speculative as to the issuer’s ability to make payments of principal and interest. Investments in such securities involves substantial risk. Issuers of high yield securities may be highly leveraged and may not have available to them more traditional methods of financing. Therefore, the risks associated with acquiring the securities of such issuers generally are greater than is the case with investment grade securities. The value of high yield securities tends to be very volatile due to such factors as specific corporate developments, interest rate sensitivity, less secondary market activity, and negative perceptions of high yield securities and the junk bond markets generally, particularly in times of market stress. |
| • | Industrial Sector Risk — Investment risks associated with investing in industrial securities include fluctuations in economic growth, business investment, capital spending, manufacturing activity, infrastructure spending, and government procurement. Industrial companies may be adversely affected by changes in commodity and raw material costs, labor availability, supply chain disruptions, transportation costs, trade policies, tariffs, geopolitical developments, environmental regulations, and interest rates. Industrial companies may also be affected by project delays, cost overruns, changing customer demand, and cyclicality in end markets, which may adversely impact profitability and stock prices. |
| • | Interest Rate Risk — The risk that debt prices overall will decline over short or even long periods due to rising interest rates. A rise in rates typically causes a fall in values of interest-bearing securities, while a fall in rates typically causes a rise in values of such securities. Interest rate risk should be modest for shorter term securities, moderate for intermediate-term securities, and high for longer-term securities. If a portfolio has a three-year average maturity, then a 1% increase in interest rates would cause an estimated 3% decline in asset value of the portfolio. In addition, certain securities such as mortgage-backed obligations are subject to optional and mandatory redemption and therefore subject to risk regarding the interest rates at which redemption proceeds may be reinvested. The Fund’s yield may decrease due to a decline in interest rates. Very low or negative interest rates may magnify interest rate risk. Recent and any future declines in interest rate levels could cause the Fund’s earnings to fall below the Fund’s expense ratio, resulting in a negative yield and a decline in the Fund’s share price. Changing interest rates, including rates that fall below zero, may have unpredictable effects on markets, may result in heightened market volatility and may detract from Fund performance to the extent the Fund is exposed to such interest rates. |
| • | Inverse ETF Risk — An inverse ETF seeks to provide returns that are the opposite of the underlying referenced financial asset, index, or commodity’s returns. Due to daily rebalancing, leverage, and liquidity, inverse ETFs may perform worse that the inverse movement of the underlying reference financial asset, index, or commodity’s returns. |
| • | Issuer Specific Risk — The value of a security may decline for a number of reasons which directly relate to the issuer, such as management performance, earnings and sales trends, investor perceptions, financial leverage or reduced demand for the issuer’s goods or services. |
| • | Leverage Risk — The risk associated with securities or practices that multiply small index or market movements into large changes in value. Leverage is often associated with investments in derivatives, but also may be embedded directly in the characteristics of other securities. Leverage risk is hedged when a derivative (a security whose value is based on another security or index) is used as a hedge against an opposite position that a Fund also holds, any loss generated by the derivative should be substantially offset by gains on the hedged investment, and vice versa. Hedges are sometimes subject to imperfect matching between the derivative and underlying security, and there can be no assurance that a Fund’s hedging transactions will be effective. |
| • | Limited Number of Holdings Risk — As a large percentage of a Fund’s assets may be invested in a limited number of securities, each investment has a greater effect on a Fund’s overall performance and any change in the value of those securities could significantly affect the value of your investment in the fund. |
| • | Liquidity Risk — The risk that certain securities may be difficult or impossible to sell at the time and the price that would normally prevail in the market. The portfolio manager may have to lower the price, sell other securities instead or forego an investment opportunity, any of which could have a negative effect on Fund management or performance. This includes the risk of missing out on an investment opportunity because the assets necessary to take advantage of it are tied up in less advantageous investments. If a Fund is required to sell securities quickly or at a particular time (including sales to meet redemption requests) the Fund could realize a loss. |
| • | Management Risk — There is no guarantee that the investment techniques and risk analyses used by a Fund’s portfolio managers will produce the desired results. |
| www.cavanalhillfunds.com | 64 | 1-800-762-7085 |
| • | Market Risk — The value of the Fund’s assets will fluctuate as the markets in which the Fund invests fluctuate. The value of the Fund’s investments may decline, sometimes rapidly and unpredictably, simply because of economic changes or other events, such as inflation (or expectations for inflation), deflation (or expectations for deflation), interest rates, global demand for particular products or resources, market instability, debt crises and downgrades, embargoes, tariffs, sanctions and other trade barriers, regulatory events, other governmental trade or market control programs and related geopolitical events. In addition, the value of the Fund’s investments may be negatively affected by the occurrence of global events such as war, military conflict, acts of terrorism, social unrest, environmental disasters, natural disasters or events, recessions, supply chain disruptions, political instability, and infectious disease epidemics or pandemics. |
| • | Master Limited Partnership Risk — The interests or “units” of an MLP are listed and traded on securities exchanges or in the over-the-counter market and their value fluctuates predominantly based on prevailing market conditions and the success of the MLP. MLPs carry many of the risks inherent in investing in a partnership. Unit holders of an MLP may not be afforded corporate protections to the same extent as shareholders of a corporation. In addition, unlike owners of common stock of a corporation, holders of common units of an MLP may have more limited control and limited rights to vote on matters affecting the MLP and have no ability to elect directors annually. In the event of liquidation, common units have preference over subordinated units, but not over debt or preferred units, to the remaining assets of the MLP. |
| • | Materials Sector Risk — Investment risks associated with investing in materials securities include fluctuations in commodity prices, global supply and demand conditions, industrial production, manufacturing activity, and infrastructure spending. Companies engaged in the production, processing, or distribution of metals, chemicals, construction materials, and critical minerals may be adversely affected by changes in energy costs, transportation expenses, labor availability, environmental regulations, permitting delays, trade policies, tariffs, geopolitical developments, and supply chain disruptions. Materials companies may also be affected by resource quality and availability, operational accidents, project delays, changing customer demand, and cyclicality in end markets such as construction, manufacturing, energy, and technology, which may adversely impact profitability and stock prices. |
| • | Mid Cap Risk — The risk that the stocks of mid-capitalization companies often have greater price volatility, lower trading volume, and less liquidity than the stocks of larger, more established companies. |
| • | Mortgage-Backed Securities Risk — The value of the Fund’s mortgage-backed securities can fall if the owners of the underlying mortgages pay off their mortgages sooner than expected, which could happen when interest rates fall, or later than expected, which could happen when interest rates rise. If the underlying mortgages are paid off sooner than expected, the Fund may have to reinvest this money in mortgage-backed or other securities that have lower yields. |
| • | Municipal Bond Risk — Like other bonds, municipal bonds have credit risk. It is possible that the government that issued the bond will not have the funds to make timely payments of interest or principal. Municipal bonds often count on the projects they finance to bring in expected revenues and there is a risk that the projects will fail to produce the revenue needed to pay off the bonds. |
| • | Non-Diversification Risk — Investments of a “non-diversified” mutual fund are not required to meet certain diversification requirements under Federal law. Compared with “diversified” portfolios, a non-diversified fund may invest a greater percentage of its assets in the securities of an issuer. A decline in the value of those investments would cause the Fund’s overall value to decline to a greater degree than if the Fund held more diversified holdings. |
| • | Portfolio Turnover Risk — A Fund may engage in active and frequent trading to achieve its principal investment objectives. This may result in the realization and distribution to shareholders of higher capital gains as compared to a fund with less active trading policies, which would increase an investor’s tax liability unless shares are held through a tax deferred or exempt vehicle. Frequent trading also increases transaction costs, which could detract from a Fund’s performance. |
| • | Preferred Stock Risk — Preferred stock is subordinated to bonds and other debt instruments in a company’s capital structure and therefore will be subject to greater credit risk than those debt instruments. In addition, preferred stock is subject to other risks, such as having no or limited voting rights, being subject to special redemption rights, having distributions deferred or skipped, having limited liquidity, changing tax treatments and possibly being in heavily regulated industries. |
| • | Prepayment/Call Risk — The risk that the principal repayment of a security will occur at an unexpected time. Prepayment risk is the chance that the repayment of certain types of securities (e.g., asset-backed securities, mortgage-backed securities and collateralized mortgage obligations) will occur sooner than expected. Call risk is the possibility that during periods of falling interest rates, a bond issuer will “call” — or repay — its high-yielding bond before the bond’s maturity date. Changes in prepayment/call rates can result in greater price and yield volatility. |
Prepayments/calls generally accelerate when interest rates decline. When mortgage and other obligations are pre-paid, a Fund may have to reinvest in securities with a lower yield. In this event, the Fund would experience a decline in income — and the potential for taxable capital gains. Further, with early prepayment, a Fund may fail to recover any premium paid, resulting in an unexpected capital loss. Prepayment/call risk is generally low for securities with a short-term maturity, moderate for securities with an intermediate-term maturity, and high for securities with a long-term maturity.
| • | Private/Restricted Securities Risk — The Fund can invest in private placements and restricted securities. Such investments involve a high degree of business and financial risk and can result in substantial or complete losses. Competition among private funds can be intense and there is no assurance that the marketing efforts of any particular portfolio company will be successful or that its business will succeed. Additionally, privately held companies are not subject to Securities and Exchange Commission reporting requirements, are not required to maintain their accounting records in accordance with generally accepted accounting principles, and are not required to maintain effective internal controls over financial reporting. As a result, timely or accurate information may at times not be readily available about the business, financial condition and results of operations of the privately held companies in which the Fund invests. |
| www.cavanalhillfunds.com | 65 | 1-800-762-7085 |
| • | Put Option Risk — When the Fund purchases a put option on a security or index it may lose the entire premium paid if the underlying security or index does not decrease in value. The Fund is also exposed to default by the put writer who may be unwilling or unable to perform its contractual obligations to the Fund. |
| • | Redemption Risk — The risk that heavy redemptions could cause the Fund to liquidate its assets at inopportune times or at a loss or depressed value, particularly during periods of declining or illiquid markets, and that could affect the fund’s ability to maintain a $1.00 share price. Redemption risk is greater to the extent that the fund has investors with large shareholdings, short investment horizons or unpredictable cash flow needs. The redemption by one or more large shareholders of their holdings in the fund could cause the remaining shareholders in the fund to lose money. The Fund may impose a liquidity fee or suspend redemptions as permitted by applicable regulations. |
| • | Regulatory Risk — The risk that a change in laws or regulations will materially affect a security, business, sector or market. A change in laws or regulations made by the government or a regulatory body can increase the costs of operating a business, reduce the attractiveness of investment and/or change the competitive landscape. Regulatory risk also includes the risk associated with federal and state laws which may restrict the remedies that a lender has when a borrower defaults on loans. These laws include restrictions on foreclosures, redemption rights after foreclosure, federal and state bankruptcy and debtor relief laws, restrictions on “due on sale” clauses, and state usury laws. |
Changes in the laws and regulations applicable to and governing money market funds, such as Rule 2a-7 under the 1940 Act, can impact the Funds. The Rule 2a-7 amendments will affect the manner in which the Funds and other money market funds are structured and operated, and may impact Fund expenses, returns and liquidity. The degree to which a money market fund will be impacted by the rule amendments will depend upon the type of fund and type of investors (e.g., retail or institutional).
| • | Small Cap Risk — Small cap companies may be more vulnerable to adverse business or economic developments. They may also be less liquid and/or more volatile than securities of larger companies or the market averages in general. Small cap companies may be adversely affected during periods when investors prefer to hold securities of large capitalization companies. |
| • | Tax Risk — The risk that the issuer of securities will fail to comply with certain requirements of the Code, which could cause adverse tax consequences. To qualify to pay exempt-interest dividends, which are treated as items of interest excludable from gross income for federal income tax purposes, at least 50% of the value of the total assets of the Bond Fund must consist of obligations exempt from regular income tax as of the close of each quarter of the Fund’s taxable year. If the proportion of taxable investments held by the Bond Fund exceeded 50% of the Fund’s total assets as of the close of any quarter of the Bond Fund’s taxable year, the Bond Fund would not, for that taxable year, satisfy the general eligibility test that would otherwise permit it to pay exempt-interest dividends for that taxable year. The Bond Fund will invest in municipal securities in reliance at the time of purchase on an opinion of bond counsel to the issuer that the interest paid on those securities will be excludable from gross income for federal income tax purposes, and the Adviser will not independently verify that opinion. Subsequent to the Bond Fund’s acquisition of such a municipal security, however, the security may be determined to pay, or to have paid, taxable income. As a result, the treatment of dividends previously paid or to be paid by the Bond Fund as “exempt-interest dividends” could be adversely affected, subjecting the Bond Fund’s shareholders to increased federal income tax liabilities. Distributions of ordinary taxable income (including any net short-term capital gain) will be taxable to shareholders as ordinary income (and not eligible for favorable taxation as “qualified dividend income”), and capital gain dividends will be taxable as long-term capital gains. |
If positions held by the Hedged Equity Income Fund were treated as “straddles” for federal income tax purposes, or the Hedged Equity Income Fund’s risk of loss with respect to a position was otherwise diminished as set forth in Treasury Regulations, dividends on stocks that are a part of such positions would not constitute qualified dividend income subject to such favorable income tax treatment or qualify for the dividends received deduction for corporate shareholders. In addition, generally, straddles are subject to certain rules that may affect the amount, character and timing of the Hedged Equity Income Fund’s gains and losses with respect to straddle positions by requiring, among other things, that: (1) any loss realized on disposition of one position of a straddle may not be recognized to the extent that the Hedged Equity Income Fund has unrealized gains with respect to the other position in such straddle; (2) the Hedged Equity Income Fund’s holding period in straddle positions be suspended while the straddle exists (possibly resulting in a gain being treated as short-term capital gain rather than long-term capital gain); (3) the losses recognized with respect to certain straddle positions that are part of a mixed straddle and that are non-Section 1256 contracts be treated as 60% long-term and 40% short-term capital loss; (4) losses recognized with respect to certain straddle positions that would otherwise constitute short-term capital losses be treated as long-term capital losses; and (5) the deduction of interest and carrying charges attributable to certain straddle positions may be deferred.
| www.cavanalhillfunds.com | 66 | 1-800-762-7085 |
To the extent a Fund invests in commodities and certain commodity-linked derivative instruments directly, it will seek to restrict its income from such investments that do not generate qualifying income, such as certain commodity-linked derivative instruments, to a maximum of 10% of its gross income (when combined with its other investments that produce non-qualifying income) to comply with the qualifying income test necessary for a Fund to qualify as a RIC under Subchapter M of the Code. However, a Fund may generate more non-qualifying income than anticipated, may not be able to generate qualifying income in a particular taxable year at levels sufficient to meet the qualifying income test, or may not be able to accurately predict the non-qualifying income from these investments. Accordingly, the extent to which a Fund invests in commodities or commodity-linked derivative instruments directly may be limited by the qualifying income test, which a Fund must continue to satisfy to maintain its status as a RIC. Failure to comply with the qualifying income test would have significant negative tax consequences to Fund shareholders. Under certain circumstances, a Fund may be able to cure a failure to meet the qualifying income test, but in order to do so a Fund may incur significant Fund-level taxes, which would effectively reduce (and could eliminate) a Fund’s returns.
| • | Technology Sector Risk — Investment risks associated with investing in technology securities include rapid technological change, product obsolescence, evolving industry standards, intense competition, and changing consumer and business preferences. Technology companies may be adversely affected by cybersecurity incidents, intellectual property disputes, regulatory developments, data privacy concerns, dependence on key personnel, and disruptions in semiconductor and other component supply chains. Technology companies often rely on innovation and future growth expectations, which can result in greater volatility and sensitivity to changes in market sentiment, earnings expectations, and economic conditions than the broader market. |
| • | Valuation Risk — The risk associated with the assessment of appropriate pricing in a changing market where trading information may not be readily available. |
| • | Zero-Coupon Risk — The market prices of securities structured as zero coupon or pay-in-kind securities are generally affected to a greater extent by interest rate changes. These securities tend to be more volatile than securities that pay interest periodically. |
See the Funds’ Statement of Additional Information for more information concerning Investment Practices and Risks.
| www.cavanalhillfunds.com | 67 | 1-800-762-7085 |
Investment Management
Investment management services are provided to each of the Funds by Cavanal Hill® Investment Management, Inc. (“Cavanal Hill Investment Management” or the “Adviser”), pursuant to an Investment Advisory Agreement. The Adviser is a wholly-owned subsidiary of BOKF, NA (“BOK”). It began serving as investment adviser to the Funds on May 12, 2001. The Adviser, subject to the general supervision of the Board of Trustees of the Funds, is responsible for providing research, investment decision making, strategizing and risk management, and day-to-day portfolio management. Cavanal Hill Investment Management is located at One Williams Center, 15th Floor, Tulsa, OK 74172-0172. As of September 30, 2026, Cavanal Hill Investment Management had approximately $[ ] billion in assets under management.
BOK is a subsidiary of BOK Financial Corporation (“BOK Financial”). BOK Financial is controlled by its principal shareholder, George B. Kaiser. Subsidiaries of BOK Financial provide a full array of wealth management, trust, custody and administration, and commercial and retail banking services, as well as non-banking financial services. Non-banking subsidiaries provide various financial services, including mortgage banking, broker-dealer and investment advisory services, private equity and alternative investing, and credit life, accident, and health insurance on certain loans originated by its subsidiaries. As of September 30, 2026, BOK Financial and its subsidiaries had approximately $[ ] billion in assets under management or in custody.
Each Fund pays Cavanal Hill Investment Management fees in return for providing investment management services. The aggregate Management Fees paid to the Adviser, after contractual fee reductions, by the Funds for the fiscal year ended August 31, 2026, were as follows:
| % OF AVERAGE | ||
| FUND | NET ASSETS | |
| Bond Funds | ||
| • Limited Duration Income Fund | [0.00] | %* |
| • Bond Fund | [0.20] | % |
| • Strategic Enhanced Yield Fund | [0.00] | %* |
| Equity Funds | ||
| • World Energy & Power Fund | [0.50] | % |
| • Hedged Equity Income Fund | [0.35] | % |
| • Industrial Frontier Fund | [0.60] | %* |
| Money Market Funds | ||
| • U.S. Treasury Fund | [0.05] | % |
| • Government Securities Money Market Fund | [0.05] | % |
* Advisor reimbursed the fund for fees and did not receive any Management Fees.
A discussion regarding the basis for the Board of Trustees approving the Investment Advisory Agreement with Cavanal Hill Investment Management is available in the Funds’ reports on Form N-CSR for the period ended August 31, 2026.
* Contractual rate. The Industrial Frontier Fund had not commenced operations as of August 31, 2026. A discussion regarding the basis for the Board of Trustees approving the Investment Advisory Agreement with respect to the Industrial Frontier Fund will be available in the Fund's first report on Form N-CSR.
Investment Sub-Advisers
Investment Sub-Advisory Services are provided to the Hedged Equity Income Fund by Lavaca Capital, LLC (“Lavaca”) pursuant to an Investment Sub-Advisory Agreement. It began serving as investment sub-adviser on December 28, 2021. Lavaca, subject to the general supervision of the Board of Trustees of the Funds, is responsible for providing hedging services to the Hedged Equity Income Fund. Lavaca is located at 2700 Post Oak Blvd., Suite 1250, Houston, TX 77056. As of September 30, 2026, Lavaca had approximately $[ ] million in assets under management. Lavaca is paid half of the fees payable to Cavanal Hill Investment Management for the services provided to the Hedged Equity Income Fund.
Investment Sub-Advisory Services are provided to the Strategic Enhanced Yield Fund by LM Capital Group, LLC (“LM Capital”) pursuant to an Investment Sub-Advisory Agreement. LM Capital began serving as investment sub-adviser on December 28, 2022. LM Capital, subject to the general supervision of the Board of Trustees of the Funds, is responsible for the day-to-day management of the Strategic Enhanced Yield Fund. LM Capital is located at 750 B Street, Suite 3010, San Diego, CA 92101. As of September 30, 2026, LM Capital had approximately $[ ] billion in assets under management. LM Capital is paid (i) 40 basis points of all assets under management held in the Strategic Enhanced Yield Fund up to $30 million and (ii) 25 basis points of all assets under management held in the Strategic Enhanced Yield Fund exceeding $30 million, in each case, of the 50 basis points of the fee payable to Cavanal Hill Investment Management for the services provided to the Strategic Enhanced Yield Fund. www.cavanalhillfunds.com 66 1-800-762-7085
| www.cavanalhillfunds.com | 68 | 1-800-762-7085 |
The persons jointly and primarily responsible for the day-to-day management of each Bond and Equity Fund, as well as their previous business experience, are as follows:
| Fund | Portfolio Manager(s) | Portfolio
Manager of this Fund Since |
Recent Professional Experience | |||
| Limited Duration Fund | Michael P. Maurer | 2003 | Mr. Maurer is a Senior Vice President and has been a fixed income fund manager at Cavanal Hill Investment Management since 2003. Before joining the Adviser, Mr. Maurer was a corporate bond/high yield trader at A.G. Edwards & Sons, Inc., in St. Louis, MO from August 1993 to October 2002. He also performed as a market analyst/debt strategist for A.G. Edwards. Mr. Maurer holds the Chartered Financial Analyst® designation. | |||
| Chase McLean | 2025 | Mr. McLean is an Assistant Vice President and has been a fixed income fund manager at Cavanal Hill Investment Management since 2025. He previously served as an analyst at Cavanal Hill Investment Management beginning in 2023, supporting both investment grade and high yield strategies. Prior to joining Cavanal Hill Investment Management, Mr. McLean was an employee in the Accelerated Career Track program at BOK Financial from 2021-2022. He obtained a Bachelor of Science in Economics from the Colorado School of Mines. | ||||
| Bond Fund | Michael P. Maurer | 2003 | See above. | |||
| Chase McLean | 2025 | See above. | ||||
| Strategic Enhanced Yield Fund | Luis Maizel | 2022 | Mr. Maizel is a co-founder and Senior Managing Director of LM Capital. His experience includes serving as Vice President of Finance for Grupoventas, S.A.; faculty member at the Harvard Business School; and President of Industrial Kuick, S.A. He currently serves as a Portfolio Manager for several LM Capital Emerging Market Debt and Enhanced Core Plus fixed income portfolios. | |||
| Michael Chalker | 2022 | Mr. Chalker joined LM Capital in 2014 and is a Vice President and Research/Portfolio Manager. Prior to joining the firm, Mr. Chalker was an Analyst at Altegris Investments. At LM Capital, Mr. Chalker manages or co-manages several Intermediate, Strategic Core and Active Core Plus portfolios. | ||||
| Mario Modiano | 2026 | Mr. Modiano is a Senior Portfolio Manager at LM Capital and joined LM Capital in 2004. Mr. Modiano’s prior experience includes an intern position at the World Bank Group; Head of Department of Operations Research at the Banco de Comercio in Mexico; and President/Chief Executive Officer of EPI S.A. Mr. Modiano manages or co-manages several of LM Capital’s Active Core Plus and Emerging Market Debt portfolios. |
| www.cavanalhillfunds.com | 69 | 1-800-762-7085 |
| Fund | Portfolio Manager(s) | Portfolio
Manager of this Fund Since |
Recent Professional Experience | |||
| World Energy & Power Fund | Matthew C. Stephani | 2014 | Mr. Stephani serves as the President of Cavanal Hill Investment Management. Previously, he was the director of the Fundamental Equity team at Cavanal Hill from 2012 to 2020 after joining the firm in 2006. Before joining the Adviser, Mr. Stephani was a Senior Vice President and a Portfolio Manager at Great Companies, LLC from 2001 to 2006. Mr. Stephani holds the Chartered Financial Analyst® designation. | |||
| Michael P. Maurer | 2014 | See above. | ||||
Thomas W. Verdel |
2014 | Mr. Verdel is a Senior Vice President and a Portfolio Manager at Cavanal Hill Investment Management which he joined in 2005. Mr. Verdel holds the Chartered Financial Analyst® designation. | ||||
| Benjamin C. Wolthuizen | 2025 | Mr. Wolthuizen is an Vice President and Portfolio Manager at Cavanal Hill Investment Management since 2025, having joined the firm first in 2019. In addition to managing the World Energy & Power Fund, Mr. Wolthuizen is responsible for the management of Cavanal Hill Investment Management’s fundamental equity strategies. Mr. Wolthuizen earned a Bachelor of Science degree from Iowa State University and holds the Chartered Financial Analyst® designation. | ||||
| Hedged Equity Income Fund | Brandon R. Barnes | 2020 | Mr. Barnes is a Senior Vice President and a Senior Portfolio Manager at Cavanal Hill Investment Management. In addition to managing the Hedged Equity Income Fund and Industrial Frontier Fund, Mr. Barnes has been the director of the firm’s Fundamental Equity team since 2020. Mr. Barnes was previously a research analyst for the Fundamental Equity team since joining the Adviser in 2011. Mr. Barnes holds the Chartered Financial Analyst® designation. | |||
| Michael C. Schloss | 2020 | Mr. Schloss is a Vice President and Portfolio Manager at Cavanal Hill Investment Management since 2000. In addition to managing the Hedged Equity Income Fund, Mr. Schloss is responsible for managing Cavanal Hill’s fundamental equity strategies. Before joining the Adviser, Mr. Schloss was an investor relations analyst for the Williams Companies and an equity analyst for PRP Performa AG in Vaduz, Liechtenstein. Mr. Schloss began his career as a financial consultant for Merrill Lynch in 1992. | ||||
| Scott Phillips | 2020 | Mr. Phillips founded Lavaca Capital in 2014 and oversees all the firm’s operations, with a special focus on Portfolio Management. Prior to founding Lavaca Capital, he oversaw the investments of a family office with a focus on derivative investments and has over 15 years of investment management experience. Scott began his career in the Houston Audit Practice of KPMG and is a licensed CPA. Scott is a graduate of the University of Texas at Austin with undergraduate & graduate degrees in Accounting and Finance. | ||||
| Jacob Johnson | 2020 | Mr. Johnson joined Lavaca in 2018 and is a Portfolio Manager with the firm. Prior to joining Lavaca, he served in financial commodity sales and trading roles with banks Societe Generale and Mitsubishi UFJ Financial Group. Previously, he held similar positions with BP, Reliant Energy and Shell Trading. Jacob has over 20 years derivative investment experience in both exchange traded and complex OTC option structures. Jacob holds a degree in Mechanical Engineering from The University of Texas at Austin and an MBA from Rice University. |
| www.cavanalhillfunds.com | 70 | 1-800-762-7085 |
| Fund | Portfolio Manager(s) | Portfolio
Manager of this Fund Since |
Recent Professional Experience |
| Industrial Frontier Fund | Matthew C. Stephani | 2026 | See above | |||
| Brandon R. Barnes | 2026 | See above | ||||
| Vincent H. Nguyen | 2026 | Mr. Nguyen is a Vice President and Portfolio Manager at Cavanal Hill Investment Management. In addition to managing the Industrial Frontier Fund, he is responsible for the management of Cavanal Hill’s fundamental equity strategies. Previously, Mr. Nguyen was a research analyst for the firm’s Fundamental Equity team after joining Cavanal Hill in 2019. Prior to joining the Adviser, Mr. Nguyen was a senior research analyst at CoBiz Wealth Management from 2010 to 2019. Mr. Nguyen holds the Chartered Financial Analyst® designation. |
Each Bond and Equity Fund is managed by a portfolio management team. Each member of a particular portfolio management team has authority over all aspects of the relevant Fund’s investment portfolio, including but not limited to, purchases and sales of individual securities, developing the Fund’s investment strategy, portfolio construction techniques, portfolio risk assessment, and the management of daily cash flows in accordance with portfolio holdings. Additional information regarding each Portfolio Manager’s compensation, other accounts managed by the Portfolio Manager, and the Portfolio Manager’s ownership of shares in Funds for which they are Portfolio Managers is available in the Statement of Additional Information.
| www.cavanalhillfunds.com | 71 | 1-800-762-7085 |
The financial highlights table is intended to help you understand the Funds’ financial performance for the past five years or, if shorter, the period of each Fund’s operations. Certain information reflects financial results for a single Fund share. The total returns in the table represent the rate that an investor would have earned or lost on an investment in the Fund (assuming reinvestment of all dividends and distributions). The information for each of the periods in the five-year period ended August 31, 2026, has been derived from information audited by KPMG LLP, whose report, along with the Funds’ financial statements, are included in the annual report, which is available upon request. Financial Highlights are not shown for the Industrial Frontier Fund or for Class C Shares of the Hedged Equity Income Fund, which had not commenced operations as of August 31, 2026.
How to Read the Financial Highlights Table
This explanation uses the Investor Share Class of the Limited Duration Fund as an example. The Investor Share Class began fiscal 2026 with a net asset value (price) of $[•] per share. During the year, the Investor Share Class earned $[•] per share from investment activities (net investment income and realized/unrealized gains/losses on investment transactions).
Shareholders received $[•] per share in the form of dividend distributions. A portion of each year’s distributions may come from the prior year’s income or capital gains.
The earnings $[•] per share minus the distributions $[•] per share resulted in a share price of $[•] at the end of the year. For a shareholder who reinvested the distributions in the purchase of more shares, the total return from the Investor Share Class was [•]% for the year.
As of August 31, 2026, the Investor Share Class had $[•] million in net assets. For the fiscal year, its expense ratio after fee waivers was [•]% ($[•] per $1,000 net assets); and its net investment income amounted to [•]% of its average net assets.
| www.cavanalhillfunds.com | 72 | 1-800-762-7085 |
Financial Highlights
To be filed.
| www.cavanalhillfunds.com | 73 | 1-800-762-7085 |
Alternative Minimum Tax (AMT)
A measure designed to assure that individuals pay at least a minimum amount of federal income taxes. Certain securities used to fund private, for-profit activities are subject to AMT.
Bond
A debt security issued by a corporation, government, or government agency in exchange for the money you lend it. In most instances, the issuer agrees to pay back the loan by a specific date and make regular interest payments until that date.
Capital Gains Distribution
Payment to mutual fund shareholders of gains realized on securities that the fund has sold at a profit, minus any realized losses.
Common Stock
A security representing ownership rights in a corporation. A stockholder is entitled to share in the company’s profits, some of which may be paid out as dividends.
Credit Quality
A measure of a bond issuer’s or contracting party’s ability to repay interest and principal in a timely manner.
Diversified
Holding a variety of securities so that a fund’s return is not badly hurt by the poor performance of a single security or industry.
Dividends
Payment to shareholders of income from interest or dividends generated by a fund’s investments.
Fixed Income Securities
Investments, such as bonds, that have a fixed payment schedule. While the level of income offered by these securities is predetermined, their prices may fluctuate.
Growth Stocks
Stocks of companies believed to have above-average prospects for growth. Reflecting market expectations for superior growth, the prices of growth stocks often are relatively high in comparison to revenue, earnings, book value, and dividends.
Index
An unmanaged group of securities whose overall performance is used as a standard to measure investment performance.
Investment Adviser
An organization that makes the day-to-day decisions regarding a fund’s investments.
Investment Grade
A debt obligation whose credit quality is considered by independent rating agencies to be sufficient to ensure timely payment of principal and interest under current economic circumstances and is rated in one of the four highest ratings categories assigned by a nationally recognized statistical ratings organization.
Liquidity
The degree of a security’s marketability (that is, how quickly the security can be sold at a fair price and converted to cash).
Maturity
The date when a bond issuer agrees to repay the bond’s principal, or face value, to the bond’s buyer.
Money Market Fund
A mutual fund that seeks to provide income, liquidity, and a stable share price by investing in very short-term, liquid investments.
Money Market Instruments
Short-term, liquid investments (usually with a maturity of 13 months or less) which include U.S. Treasury bills, bank certificates of deposit (CDs), repurchase agreements, commercial paper, and bankers’ acceptances.
| www.cavanalhillfunds.com | 74 | 1-800-762-7085 |
Municipal Security
Debt obligations issued by a state or local government. Interest income from municipal securities, and therefore dividend income from municipal bond funds, is generally free from federal income taxes, as well as taxes in the state in which the securities were issued.
Mutual Fund
An investment company that pools the money of many people and invests it in a variety of securities in an effort to achieve a specific objective over time.
Net Asset Value (NAV)
The market value of a mutual fund’s total assets, minus liabilities, divided by the number of shares outstanding. The value of a single share is called its share value or share price.
Operating Expenses
The percentage of a fund’s average net assets used to pay its expenses. Operating expenses include investment advisory fees, distribution/service (12b-1) fees, shareholder servicing fees, and administration fees.
Securities
Stocks, bonds, money market instruments, and other investment vehicles.
Total Return
A percentage change, over a specified time period, in a mutual fund’s net asset value, with the ending net asset value adjusted to account for the reinvestment of all distributions of dividends and capital gains.
Value Stocks
Stocks whose growth prospects are generally regarded as subpar by the market. Reflecting these market expectations, the prices of value stocks typically are below-average in comparison to such factors as revenue, earnings, book value, and dividends.
Volatility
The fluctuations in value of a mutual fund or other security. The greater a fund’s volatility, the wider the fluctuations between its high and low prices.
Yield
Income (interest or dividends) earned by an investment, expressed as a percentage of the investment’s price.
| www.cavanalhillfunds.com | 75 | 1-800-762-7085 |
More Information
More information may be obtained free of charge upon request.
The Statement of Additional Information (“SAI”), a current version of which is on file with the SEC, contains more details about the Funds and is incorporated by reference into the prospectus (is legally a part of this prospectus).
The Funds’ annual and semi-annual reports to shareholders, as well as the Funds’ forms N-CSR and N-CSRS, contain additional information about the Funds’ investments. The Funds’ annual report also discusses the market conditions and investment strategies that significantly affected the Funds’ performance during its last fiscal year.
The Funds also file their complete schedule of portfolio holdings with the SEC for the 1st and 3rd quarters of each fiscal year. The Funds’ most recent portfolio holdings are also available at http://www.cavanalhillfunds.com.
If you have questions about the Funds or your account, or wish to obtain free copies of the Funds’ current prospectuses, SAI, annual or semi-annual reports, Form N-CSR or N-CSRS, please contact us as follows:
By Telephone:
Call 1-800-762-7085
By Mail:
Cavanal Hill Funds
4249 Easton Way - Suite 400
Columbus, Ohio 43219-6171
By Internet:
http://www.cavanalhillfunds.com
From the SEC:
You can also obtain the SAI, Form N-CSR and Form N-CSRS, Proxy Voting Policies and Procedures and other information about the Cavanal Hill Funds, from the SEC’s web site (http://www.sec.gov). You may request documents by mail from the SEC, upon payment of a duplicating fee, by writing to: Securities and Exchange Commission, Public Reference Section, Washington DC 20549-0102 or by sending an e-mail to: [email protected].
Investment Adviser & Administrator
Cavanal Hill Investment
Management, Inc.
One Williams Center, 15th Floor
Tulsa, Oklahoma 74172-0172
Distributor
Cavanal Hill Distributors, Inc.
One Williams Center, 15th Floor
Bank of Oklahoma Tower
Tulsa, Oklahoma 74172-0172
Cavanal Hill Funds’ Investment Company Act registration number is 811-06114.
| www.cavanalhillfunds.com | 76 | 1-800-762-7085 |
STATEMENT OF ADDITIONAL INFORMATION
CAVANAL HILL® FUNDS
DATED December [ ], 2026
| MONEY MARKET FUNDS | |||||||
| U.S. Treasury Fund | Government Securities Money Market Fund | ||||||
| Administrative: | APGXX | Administrative: | APCXX | ||||
| Institutional: | APKXX | Institutional: | APHXX | ||||
| Select: | APNXX | Select: | APSXX | ||||
| Premier: | APPXX | ||||||
| BOND FUNDS | |||||||
| Limited Duration Fund | Bond Fund | ||||||
| A: | AASTX | A: | AABOX | ||||
| Investor: | APSTX | Investor: | APBDX | ||||
| Institutional: | AISTX | Institutional: | AIBNX | ||||
| Strategic Enhanced Yield Fund | |||||||
| A: | AAENX | ||||||
| Investor: | APENX | ||||||
| Institutional: | AIENX | ||||||
| EQUITY FUNDS | |||||||
| World Energy & Power Fund | Hedged Equity Income Fund | Industrial Frontier Fund | |||||
| A: | AAWEX | A: | AALIX | A | [•] | ||
| C: | ACWEX | C: | [•] | C | [•] | ||
| Investor: | APWEX | Investor: | APLIX | Investor | [•] | ||
| Institutional: | AIWEX | Institutional: | AILIX | Institutional | [•] | ||
This Statement of Additional Information (“SAI”) is not a prospectus, but should be read in conjunction with the Prospectus for the Cavanal Hill Funds dated December 28, 2026. This SAI is incorporated in its entirety into the Prospectus. A copy of the Prospectus for the Cavanal Hill Funds may be obtained by writing to the Cavanal Hill Funds at One Williams Center, 15th Floor, Bank of Oklahoma Tower, Tulsa, Oklahoma, 74172, or by telephoning 1-800-762-7085.
The Report of the Independent Registered Public Accounting Firm, Financial Highlights, and Financial Statements included in the Cavanal Hill Funds’ Annual Report filed as part of the Form N-CSR for the fiscal year ended August 31, 2026, are incorporated by reference into this SAI. A copy of the Form N-CSR, including the Annual Report may be obtained without charge upon request by contacting the Distributor, Cavanal Hill Distributors, at One Williams Center, 15th Floor, Bank of Oklahoma Tower, Tulsa, Oklahoma, 74172 or by telephoning toll-free at 1-800-762-7085.
TABLE OF CONTENTS
The Cavanal Hill Funds (the “Trust”) is an open-end management investment company established in 1987 as a Massachusetts business trust. The Trust currently consists of eight series of units of beneficial interest (“Shares”), representing interests in the following portfolios:
Cavanal Hill U.S. Treasury Fund (the “U.S. Treasury Fund”) and Cavanal Hill Government Securities Money Market Fund (the “Government Securities Money Market Fund”), Cavanal Hill Limited Duration Fund (the “Limited Duration Fund”), Cavanal Hill Bond Fund (the “Bond Fund”), Cavanal Hill Strategic Enhanced Yield Fund (the “Strategic Enhanced Yield Fund”), Cavanal Hill World Energy & Power Fund (the “World Energy & Power Fund”), Cavanal Hill Hedged Equity Income Fund (the “Hedged Equity Income Fund”), and Cavanal Hill Industrial Frontier Fund (the “Industrial Frontier Fund”) (each a “Fund,” and together, the “Funds”).
Each Fund is diversified, with the exception of the Hedged Equity Income Fund and Industrial Frontier Fund, which are non-diversified. The U.S. Treasury Fund and the Government Securities Money Market Fund are sometimes referred to as the “Money Market Funds.” The Limited Duration Fund, the Bond Fund, and the Strategic Enhanced Yield Fund are sometimes referred to as the “Bond Funds,” and the World Energy & Power Fund, the Hedged Equity Income Fund, and the Industrial Frontier Fund are sometimes referred to as the “Equity Funds.” The Trust offers Class A, No-Load Investor Class (“Investor Class”) and Institutional Class Shares of the Bond and Equity Funds. The Equity Funds also offer Class C Shares. The Trust offers Administrative Class, Institutional Class and Select Class Shares of the Money Market Funds. The Government Securities Money Market Fund also offers Premier Class Shares. The information contained in this document expands upon subjects discussed in the Prospectus for the Funds. An investment in a Fund should not be made without first reading that Fund’s Prospectus.
IMPORTANT DISCLOSURE ABOUT THE WORLD ENERGY & POWER FUND
Non-Affiliation
The Cavanal Hill World Energy & Power Fund invests in energy related companies around the globe based on the advice of Cavanal Hill Investment Management®, Inc. (“Cavanal Hill Investment Management” or “Adviser”). The Adviser is an indirect wholly-owned subsidiary of BOK Financial Corporation (“BOK Financial”), a financial services company that is majority-owned by George B. Kaiser. Mr. Kaiser is an active trader of energy derivatives, and owns a wide range of oil and gas upstream, midstream and downstream assets located in a wide range of locations. Neither George B. Kaiser nor any affiliated entity or person is involved in the recommendation, selection or evaluation of World Energy & Power Fund holdings, other than those Adviser personnel that are specifically charged with managing the Fund. BOK Financial has adopted strict policies to ensure that no energy related investment information is shared between Advisory personnel and Mr. Kaiser or affiliated entities and individuals.
1
ADDITIONAL INFORMATION ON THE FUNDS
All securities or instruments in which the Money Market Funds invest are valued based on the amortized cost valuation technique pursuant to Rule 2a-7 under the Investment Company Act of 1940, as amended (the “1940 Act”). All instruments in which the Money Market Funds invest will have remaining maturities of 397 days or less, though instruments subject to repurchase agreements and certain variable or floating rate obligations may bear longer maturities. The average dollar-weighted maturity of the securities in each of the Money Market Funds will not exceed 60 days and the dollar-weighted average portfolio life cannot exceed 120 days. Obligations purchased by the Money Market Funds are limited to U.S. dollar-denominated obligations which have been determined to present minimal credit risks.
The U.S. Treasury Fund invests at least 99.5% of its total assets in cash, U.S. Government Securities, other U.S. Government Securities investment companies or repurchase agreements collateralized by U.S. Government Securities and other U.S. Treasury investment companies. The Fund also invests at least 80% of its net assets in U.S. Treasury Obligations or repurchase agreements collateralized by U.S. Treasury Obligations. The Government Securities Money Market Fund invests at least 99.5% of its total assets in cash, U.S. Government Securities, other U.S. Government Securities investment companies, or repurchase agreements collateralized by U.S. Government Securities and other U.S. Government Security investment companies. The Fund also invests at least 80% of its net assets in U.S. Government Securities or repurchase agreements collateralized by U.S. Government Securities. These policies will not be changed without at least 60 days prior notice to shareholders.
The Government Securities Money Market Fund will invest only in issuers or instruments that at the time of purchase (1) have received one of the two highest short-term ratings by at least two nationally recognized statistical ratings organizations (“NRSROs”); (2) are single rated and have received one of the two highest short-term ratings by a NRSRO; (3) are unrated, but are determined to be of comparable quality by the Adviser pursuant to guidelines approved by the Board of Trustees and subject to the ratification of the Board of Trustees; or (4) are a government security or a U.S. Government Securities investment company.
For purposes of the Funds’ policies that specify 80% or 99.5%, the Funds will “look through” investments in investment companies and will include such investments, as appropriate, in their respective percentage totals.
As discussed below, there are a number of important differences among the government-sponsored entities and agencies and instrumentalities of the U.S. government that issue Mortgage-backed securities and among the securities that they issue. The differences in levels of credit support result in different degrees of credit risk. The Government Securities Money Market Fund will invest in the obligations of such government-sponsored entities and agencies and instrumentalities only when the Adviser deems the credit risk with respect thereto to be minimal.
The Limited Duration Fund, and the Bond Fund will invest in debt securities only if they are “investment grade,” carrying a rating within the four highest ratings categories assigned by a NRSRO at the time of purchase or, if unrated, are deemed by Cavanal Hill Investment Management under guidelines approved by the Trust’s Board of Trustees to present attractive opportunities and to be of comparable quality to the securities so rated. If the rating of a security is downgraded after purchase, the portfolio management team will determine whether it is in the best interest of the Fund’s shareholders to continue to hold the security. In making that determination, the factors considered at the time of purchase are reviewed. The Fund does not apply an automatic sale trigger. See “Appendix” for an explanation of these and other ratings used in this SAI. The Strategic Enhanced Yield Fund may invest a significant portion of its net assets in non-rated securities or securities that are rated below investment grade (“junk bonds” or high yield securities) and thus rated below Baa3 by Moody’s, BBB- by S&P or BBB- by Fitch Ratings Ltd. or unrated.
The Limited Duration Fund, the Strategic Enhanced Yield Fund and the Bond Fund, under normal market conditions, will each invest at least 80% of the value of its net assets in bonds.
2
Bonds, notes, and debentures in which the Bond Funds may invest may differ in interest rates, maturities and times of issuance. The market value of the Bond Funds’ debt securities will change in response to interest rate changes and other factors. When market prices are unavailable or deemed to be inaccurate because of recent market developments, matrix pricing or fair value pricing will be utilized. During periods of falling interest rates, the value of outstanding debt securities generally rise. Conversely, during periods of rising interest rates, the value of such securities generally declines. Moreover, while securities with longer maturities tend to produce higher yields, the price of longer maturity securities is also subject to greater fluctuations as a result of changes in interest rates. Conversely, securities with shorter maturities generally have less price movement than securities of comparable quality with longer maturities. Changes by NRSROs in the rating of any debt security and in the ability of an issuer to make payments of interest and principal also affect the value of these investments. Except under conditions of default, changes in the value of a bond fund’s portfolio securities generally will not affect cash income derived from these securities but will affect a bond fund’s net asset value (“NAV”).
Certain debt securities such as, but not limited to, Mortgage-backed securities and collateralized mortgage obligations (a “CMO”), as well as securities subject to prepayment of principal prior to the stated maturity date, are expected to be repaid prior to their stated maturity dates. The Adviser determines the “expected average life” of the securities based on the expected payment date (which is earlier than the stated maturity dates of the securities). For purposes of calculating the weighted average portfolio maturity, the expected average life of such securities, as determined by the Adviser, will be used.
Under normal circumstances, the World Energy & Power Fund invests at least 80% of its net assets in a wide range of energy-related financial instruments issued in the U.S. and markets around the world. Energy-related financial instruments may include foreign and domestic securities of issuers that derive more than 50% percent of their assets, revenue or income from activities related to the exploration, extraction, mining, research, development, conservation, refinement, production, transfer, transmission or transportation of conventional, alternative, renewable or sustainable energy sources, utilities, petrochemicals, plastics or suppliers or servicers to such industries. Investments typically include a combination of common stock, bonds and exchange traded funds (“ETFs”) but may also include other asset types that are related to energy industry activities. The World Energy & Power Fund may also seek to increase the return of the Fund and to hedge (or protect) the value of its assets by investing in derivative instruments, including options, futures and indexed securities. The World Energy & Power Fund may also seek to provide exposure to the investment returns of commodities through investment in investment vehicles that exclusively invest in commodities such as ETFs that may hold commodities, commodity derivatives or both.
The World Energy & Power Fund may engage in active and frequent trading.
Under normal market conditions, the World Energy & Power Fund will invest at least 40%, but may invest up to 100%, of its net assets in the securities of issuers organized or having their principal place of business outside the U.S. or doing a substantial amount of business outside the U.S. The Fund will consider an issuer to be doing a substantial amount of business outside the U.S. if it derives more than 50% percent of its assets, revenue or income outside of the U.S. or is an international focused ETF. Under normal market conditions, the World Energy & Power Fund invests in issuers from at least three different countries. The Adviser invests the Fund’s assets based on its judgment about issuers, risk, prices of securities, market conditions and other economic factors in the U.S. and around the world.
3
The World Energy & Power Fund may invest in long and short positions in securities of issuers of any market capitalization, emerging market securities, American depositary receipts (“ADRs”), European depositary receipts, (“EDRs”), global depositary receipts (“GDRs”), and master limited partnerships (“MLPs”). Sponsored and unsponsored ADRs and GDRs constitute a portion of the Fund’s energy-related instruments. The Fund may also invest in pooled investment vehicles, including other RICs and ETFs, including leveraged and inverse ETFs.
The World Energy & Power Fund may from time to time invest in fixed income securities of any credit quality and maturity, including those of defaulted/distressed issuers and bank loans. Fixed income investments may include foreign and domestic sovereign securities. These securities can be rated below investment grade (“junk bonds” or high yield securities) and thus rated below Baa3 by Moody’s, BBB- by S&P or BBB- by Fitch Ratings Ltd. or unrated and securities in default. The World Energy & Power Fund may also engage in short sales when the Adviser believes that a security is overvalued or to hedge existing positions. At any time that a Fund has an open short sale position, the Fund is required to own or have the right to obtain securities equivalent in kind and amount to the securities sold short or to segregate with BOKF, NA (the “Custodian”) an amount of cash or liquid assets to cover the short position. The Funds do not intend to use leverage so proceeds from a short sale will be used as collateral.
Under normal market conditions, the Hedged Equity Income Fund invests primarily in dividend paying equity securities, with at least 80% of its net assets in equity securities and equity-related instruments traded on U.S. exchanges. For purposes of this policy, the Fund includes common stocks and securities convertible into common stocks of companies with any market capitalization and sponsored or unsponsored ADRs. Under normal circumstances, the fund will seek to generate current income. Some of the income will be distributed to shareholders in the form of dividends from portfolio securities; income will also be generated from option premiums by writing (selling) call options on its portfolio securities, all of which will be covered calls. A covered call refers to a financial transaction in which the investor selling a call option owns an equivalent amount of the underlying security. The investor’s ownership of the long position in the asset is the “cover” because the seller can deliver the shares if the buyer of the call option chooses to exercise. The Fund seeks to produce current income from dividends and, to a lesser extent, from option writing premiums. Because of the tax treatment options activity receives, call premium income may not be distributed to shareholders. The Fund will buy put options on indexes, ETFs, or individual securities in order to seek to both reduce volatility and provide downside protection for the portfolio.
The portfolio management team of the Hedged Equity Income Fund selects equity securities that it believes have strong earnings, cash flow and revenue growth prospects, industry leadership with a competitive advantage, strong management teams, understandable and observable fundamental dynamics, and can pay consistent and sustainable dividends. At the time of initial investment selection, common stocks will have a minimum market cap of $1 billion. The portfolio will typically invest in 25 to 40 holdings across multiple economic sectors and will not invest more than 40% of the fund’s net assets in any one such sector to diversify risk.
The extent of the Hedged Equity Income Fund option writing activity will depend on the portfolio management team’s judgment regarding perceived value associated with security prices, market conditions and attractiveness of writing call options on the fund’s stock holdings but under normal circumstances, the fund expects to write (sell) call options on 50% to 100% of the fund’s equity securities. Writing covered calls produces income from premiums, a portion of which will be used to purchase puts which helps to reduce the volatility (and risk profile) of the fund by providing downside protection.
The Hedged Equity Income Fund is required to pledge collateral for the covered call option trades and will hold the security as collateral for all such covered call option trades. The Custodian will segregate such collateral for the benefit of the counterparty. High levels of new investment inflow can lead to periods of higher cash levels, as investment opportunities are identified. Similarly, during periods in which stock markets advance, the exercise of options may result in higher cash levels.
The Hedged Equity Income Fund and Industrial Frontier Fund are non-diversified, meaning each may invest in fewer individual holdings than a diversified fund. Therefore, each Fund is more exposed to individual security volatility than a diversified fund. Purchase and sale decisions are based on the Adviser’s judgment about issuers, risk, prices of securities, market conditions, potential returns, and other economic factors.
Under normal circumstances, the Industrial Frontier Fund invests at least 80% of its net assets in a wide range of companies in the “industrial frontier,” which will include traditional industry sector companies, companies that sell into industrial end markets, and those that benefit from mega-trends identified by the Fund’s portfolio managers. This policy will not be changed without at least 60 days prior notice to shareholders.
4
More specifically, a company is an industrial frontier company if, at the time of investment, it satisfies at least one of the following: (a) classified as Industrial by the Global Industry Classification Standard (GICS®) or a comparable third-party classification system; (b) derives at least 50% of its revenues from industrial end markets, including sales to customers in manufacturing, transportation and logistics, aerospace and defense, construction and engineering, commercial and professional services, trading companies and distributors, and industrial real estate, or (c) classified as Technology or Materials by the GICS, or a comparable third-party classification system, and the portfolio managers of the fund determine that at least 50% of the company’s revenues are derived from participation in industrial mega-trends. While such trends may shift over time as themes mature and new themes emerge, examples of mega-trends could include: buildout of artificial intelligence infrastructure; onshoring of manufacturing back to the U.S. from abroad; geopolitical events driving increases in defense spending and modernization; development of physical alternative artificial intelligence applications, including robotics; emergence of space-related commerce; structural requirements for electrical power and cybersecurity.
Investments of the Industrial Frontier Fund typically include a combination of common stock, bonds, ETFs and ETNs but may also include other asset types that are related to industrial frontier activities. The Fund’s financial instruments may include sponsored and unsponsored ADRs and GDRs. The Fund may invest in long positions in securities of issuers of any market capitalization, as well as emerging market securities, American depositary receipts, European depositary receipts, and global depositary receipts, . The Fund may also invest in pooled investment vehicles, including other RICs, ETNs and ETFs, including leveraged and inverse ETFs.
The Industrial Frontier Fund may invest in fixed income securities of any credit quality and maturity, including those of defaulted/distressed issuers. These securities can be rated below investment grade (“junk bonds” or high yield securities) and thus rated below Baa3 by Moody’s, BBB- by S&P or BBB- by Fitch Ratings Ltd. or unrated and securities in default. Fixed income investments may include foreign and domestic sovereign issued securities.
The Industrial Frontier Fund may invest up to 15% of its net assets in alternative investments including private equity, venture capital, hedge funds, direct private investment, interval funds, business development companies, tender offer funds, and real assets among other investments.
The Industrial Frontier Fund is non-diversified, meaning it may invest in fewer individual holdings than a diversified fund. Therefore, the Fund is more exposed to individual security volatility than a diversified fund. The Fund may engage in active and frequent trading.
The Adviser invests the Industrial Frontier Fund’s assets based on its judgment about issuers, risk, prices of securities, market conditions, potential returns, and other economic factors in the U.S. and around the world. Portfolio managers will seek to identify companies with the following characteristics: sustainable competitive advantage, industry barriers to entry, forecastable, sustainable earnings growth, and attractive valuation. Changes in fundamental strategy of a company represent a potential sale trigger.
5
With the exception of the World Energy & Power Fund and the Industrial Frontier Fund, in general, the Funds do not concentrate in any particular industry or group of industries, as concentration is defined or interpreted under the 1940 Act, or the rules or regulations thereunder, as such statute, rules or regulations may be amended from time to time, or by regulatory guidance or interpretations of such statute, rules or regulations. Under normal market conditions, the World Energy & Power Fund will concentrate its investments in energy-related industries. Investments may include, but are not limited to: foreign and domestic securities related to the exploration, mining, development, refinement, production, transfer, transmission, and transportation of conventional, alternative, renewable and sustainable energy, utilities and suppliers to such industries. The World Energy & Power Fund will not concentrate in any other industry or group of industries. Under normal market conditions, the Industrial Frontier Fund will concentrate its investments in industrials-related industries. The Industrial Frontier Fund will not concentrate in any other industry or group of industries.
“Concentration” is generally interpreted under the 1940 Act to be investing more than 25% of total assets in an industry or group of industries. For purposes of determining concentration, the various Funds do not consider certain investments to constitute an “industry” or include them in the general limitation: (a) obligations issued or guaranteed by the U.S. government or its agencies and instrumentalities; (b) wholly owned finance companies will be considered to be in the industries of their parents if their activities are primarily related to financing the activities of their parents; (c) utilities will be divided according to their services (for example, gas, gas transmission, electric and gas, electric, and telephone will each be considered a separate industry); and (d) tax-exempt Municipal Securities (as defined herein) or governmental guarantees of Municipal Securities. Also, the Funds do not consider investment companies to constitute an “industry” and will “look through” investments in investment companies to the underlying securities held by such investment companies when determining the Fund’s exposure to a particular industry.
6
ADDITIONAL INFORMATION ON FUND INSTRUMENTS
The Limited Duration Fund, the Strategic Enhanced Yield Fund, the Bond Fund, the World Energy & Power Fund, the Hedged Equity Income Fund, and the Industrial Frontier Fund may invest in securities backed by automobile receivables and credit card receivables and other securities backed by other types of receivables or other assets. Credit support for asset-backed securities may be based on the underlying assets and/or provided through credit enhancements by a third party. Credit enhancement techniques include letters of credit, insurance bonds, limited guarantees (which are generally provided by the issuer), senior-subordinated structures and over-collateralization. These Funds will only purchase an asset-backed security if it is rated at the time of purchase within the four highest ratings categories assigned by an NRSRO, with the exception of the Strategic Enhanced Yield Fund, the World Energy & Power Fund and the Industrial Frontier Fund, which may invest in fixed income securities of any credit quality. Some asset-backed securities, such as asset-backed commercial paper, often carry only short-term ratings. The World Energy & Power Fund, the Strategic Enhanced Yield Fund, and the Government Securities Money Market Fund may purchase asset-based securities that carry only a short-term rating. Some types of asset-backed securities are considered to be illiquid.
Each of the Funds, except the U.S. Treasury Fund and the Government Securities Money Market Fund, may invest in obligations of the banking industry such as bankers’ acceptances, commercial paper, loan participations, bearer deposit notes, promissory notes, floating or variable rate obligations, certificates of deposit, and demand and time deposits.
Bankers’ Acceptances: Bankers’ acceptances are negotiable drafts or bills of exchange typically drawn by an importer or exporter to pay for specific merchandise, which are “accepted” by a bank, meaning, in effect, that the bank unconditionally agrees to pay the face value of the instrument on maturity. The Funds will invest in only those bankers’ acceptances guaranteed by U.S. and foreign banks having, at the time of investment, total assets in excess of $1 billion (as of the date of their most recently published financial statements).
Certificates of Deposit: Certificates of deposit are negotiable certificates issued against funds deposited in a commercial bank for a definite period of time and earning a specified return or a floating rate of return based on an index, such as the Secured Overnight Financing Rate or “SOFR”. Certificates of deposit will be those of U.S and foreign commercial banks and their domestic and foreign branches. The Funds may also invest in Eurodollar certificates of deposit, which are U.S. dollar-denominated certificates of deposit issued by branches of foreign and domestic banks located outside the United States and Yankee certificates of deposit, which are certificates of deposit issued by a U.S. branch of a foreign bank denominated in U.S. dollars and held in the United States.
In addition, the Funds may invest in bearer deposit notes, which are negotiable time deposits with a specific maturity date issued by a bank, and time deposits, which are interest bearing non-negotiable deposits at a bank that have a specific maturity date.
Commercial Paper: Commercial paper consists of secured and unsecured promissory notes issued by corporations. Except as noted below with respect to variable rate master demand notes, issues of commercial paper normally have maturities of nine months or less and fixed rates of return or a floating rate of return based on an index, such as SOFR. The specified Funds may also invest in Canadian commercial paper which is commercial paper issued by a Canadian corporation or a Canadian counterpart of a U.S. corporation and in Europaper which is U.S. dollar-denominated commercial paper of a foreign issuer.
With the exception of the Strategic Enhanced Yield Fund, the World Energy & Power Fund and the Industrial Frontier Fund, the Funds will only purchase commercial paper rated at the time of purchase within the four highest ratings categories assigned by an NRSRO or, if not rated, found by the Adviser under guidelines approved by the Trust’s Board of Trustees to be of comparable quality. The Strategic Enhanced Yield Fund and the World Energy & Power Fund may invest in fixed income securities of any credit quality.
7
Each of the Funds, except the U.S. Treasury Fund and the Government Securities Money Market Fund, may invest in bonds and other debt securities of U.S. and non-U.S. issuers, including obligations of industrial, utility, banking and other corporate issuers. All debt securities are subject to the risk of an issuer’s inability to meet principal and interest payments on the obligation and may also be subject to price volatility due to such factors as fluctuation of market interest rates, market perception of the creditworthiness of the issuer and general market liquidity.
Each of the Funds, except the U.S. Treasury Fund and the Government Securities Money Market Fund, may write (sell) “covered” call options and purchase options to close out options previously written by the Fund. Such options must be listed on a national securities exchange. The purpose of these Funds in writing covered call options is to generate additional premium income. This premium income will serve to enhance the Fund’s total return and will reduce the effect of any price decline of the security involved in the option.
A call option gives the holder (buyer) the “right to purchase” a security at a specified price (the exercise price) at any time until a certain date (the expiration date). So long as the obligation of the writer of a call option continues, the writer may be assigned an exercise notice by the broker-dealer, through whom such option was sold, requiring the writer to deliver the underlying security against payment of the exercise price. This obligation terminates upon the expiration of the call option, or such earlier time at which the writer effects a closing purchase transaction by purchasing an option identical to that previously sold. To secure the writer’s obligation to deliver the underlying security in the case of a call option, subject to the rules of the Options Clearing Corporation, a writer is required to deposit in escrow the underlying security or other assets in accordance with such rules. The Funds will write only covered call options. This means that a Fund will only write a call option on a security which a Fund already owns. With the exception of the Hedged Equity Income Fund, a Fund will not write a covered call option if, as a result, the aggregate market value of all portfolio securities covering call options or currencies subject to put options exceeds 25% of the market value of the Fund’s net assets. The Hedged Equity Income Fund may write covered call options on up to 100% of the equity securities it holds. When market prices are unavailable or deemed to be inaccurate due to recent market developments, matrix pricing or fair value pricing will be utilized.
Portfolio securities on which call options may be written will be purchased solely on the basis of investment considerations consistent with each Fund’s investment objectives. The writing of covered call options is a conservative investment technique believed to involve relatively little risk (in contrast to the writing of naked or uncovered options), but capable of enhancing a Fund’s total return. When writing a covered call option, a Fund, in return for the premium, gives up the opportunity for profit from a price increase in the underlying security above the exercise price, but conversely retains the risk of loss should the price of the security decline. Unlike one who owns securities not subject to an option, a Fund has no control over when it may be required to sell the underlying securities, as it may receive an exercise notice at any time prior to the expiration of its obligation as a writer. If a call option that a Fund has written expires, a Fund will realize a gain in the amount of the premium; however, such gain may be offset by a decline in the market value of the underlying security during the option period. If the call option is exercised, a Fund will realize a gain or loss from the sale of the underlying security. The security covering the call will be maintained in a segregated account of the Custodian. The Funds do not consider a security covered by a call to be “pledged” as that term is used in each Fund’s policy that limits the pledging or mortgaging of its net assets.
The premium each Fund will receive from writing a call option will reflect, among other things, the current market price of the underlying security, the relationship of the exercise price to such market price, the historical price volatility of the underlying security, and the length of the option period. The premium received is the fair market value of the option at the date written or purchased. Once the decision to write a covered call option has been made, the Adviser, in determining whether a particular call option should be written on a particular security, will consider the reasonableness of the anticipated premium and the likelihood that a liquid secondary market will exist for those options. The premium received by a Fund for writing covered call options will be recorded as a liability in the Fund’s statement of assets and liabilities. This liability will be adjusted daily to the option’s current market value, which will be the latest sale price at the time at which the NAV per Share of the Fund is computed, or, in the absence of such sale, the latest asked price. The liability will be extinguished upon expiration of the option, the purchase of an identical option in a closing transaction, or delivery of the underlying security upon the exercise of the option.
8
Closing transactions will be effected in order to realize a profit on an outstanding call option, to prevent an underlying security from being called, or to permit the sale of the underlying security. Furthermore, effecting a closing transaction will permit a Fund to write another call option on the underlying security with either a different exercise price or expiration date or both. If a Fund desires to sell a particular security from its portfolio on which it has written a call option, it will seek to effect a closing transaction prior to, or concurrently with, the sale of the security. There is no assurance that a Fund will be able to effect such closing transactions at a favorable price. If a Fund cannot enter into such a transaction, it may be required to hold a security that it might otherwise have sold, in which case it would continue to be at market risk on the security. This could result in higher transaction costs. A Fund will pay transaction costs in connection with the writing of options to close out previously written options. Such transaction costs are normally higher than those applicable to purchases and sales of portfolio securities.
Call options written by a Fund will normally have expiration dates of less than nine months from the date written. The exercise price of the options may be below, equal to, or above the current market values of the underlying securities at the time the options are written. From time to time, a Fund may purchase an underlying security for delivery in accordance with an exercise notice of a call option assigned to it, rather than delivering such security from its portfolio. In such cases, additional costs will be incurred.
A Fund will realize a profit or loss from a closing transaction if the cost of the transaction is less or more than the premium received from the writing of the option. Because increases in the market price of a call option will generally reflect increases in the market price of the underlying security, any loss resulting from the repurchase of a call option is likely to be offset in whole or in part by appreciation of the underlying security owned by the Fund.
Each of the Funds, except the U.S. Treasury Fund and the Government Securities Money Market Fund, may invest in commercial paper, which consists of secured and unsecured promissory notes issued by corporations. Except as noted below with respect to variable rate master demand notes, issues of commercial paper normally have maturities of nine months or less and fixed rates of return. The Funds may also invest in Canadian commercial paper which is commercial paper issued by a Canadian corporation or a Canadian counterpart of a U.S. corporation and in Europaper which is U.S. dollar-denominated commercial paper of a foreign issuer. With the exception of the Strategic Enhanced Yield Fund and the World Energy & Power Fund, the Funds will only purchase commercial paper rated at the time of purchase within the four highest ratings categories assigned by an NRSRO or, if not rated, found by the Adviser under guidelines approved by the Trust’s Board of Trustees to be of comparable quality and present minimal credit risk. The Strategic Enhanced Yield Fund and the World Energy & Power Fund may invest in commercial paper of any credit quality.
COMMODITY EXPOSURE INSTRUMENTS
The World Energy & Power Fund may invest in commodity-focused ETFs. Commodity-focused ETFs may invest in futures contracts that track the price of a commodity, commodity options, or directly in physical commodities, such ETFs may include inverse ETFs.
Common stock represents a share of ownership in a company and usually carries voting rights and may earn dividends. Unlike preferred stock, common stock dividends are not fixed but are declared at the discretion of the issuer’s board of directors. Common stock occupies the most junior position in a company’s capital structure. As with all equity securities, the price of common stock fluctuates based on changes in a company’s financial condition and overall market and economic conditions.
Each of the Funds, except the U.S. Treasury Fund and the Government Securities Money Market Fund, may invest in convertible securities. Convertible securities include any debt securities or preferred stock which may be converted into common stock or which carry the right to purchase common stock. Generally, convertible securities entitle the holder to exchange the securities for a specified number of shares of common stock, usually of the same company, at specified prices within a certain period of time.
9
The terms of any convertible security determine its ranking in a company’s capital structure. In the case of subordinated convertible debentures, the holders’ claims on assets and earnings are subordinated to the claims of other creditors, and are senior to the claims of preferred and common shareholders. In the case of convertible preferred stock, the holders’ claims on assets and earnings are subordinated to the claims of all creditors and are senior to the claims of common shareholders.
Convertible securities have characteristics similar to both debt and equity securities. Due to the conversion feature, the market value of convertible securities tends to move together with the market value of the underlying common stock. As a result, selection of convertible securities, to a great extent, is based on the potential for capital appreciation that may exist in the underlying stock. The value of convertible securities is also affected by prevailing interest rates, the credit quality of the issuer, and any call provisions. In some cases, the issuer may cause a convertible security to convert to common stock. In other situations, it may be advantageous for a Fund to cause the conversion of convertible securities to common stock. If a convertible security converts to common stock, a Fund may hold such common stock in its portfolio even if it does not ordinarily invest in common stock.
EXCHANGE TRADED FUNDS (“ETFs”)
ETFs are pooled investment vehicles whose ownership interests are purchased and sold in a securities exchange. ETFs may be structured investment companies, depositary receipts or other pooled investment vehicles. As shareholders of an ETF, the Funds will bear their pro rata portion of any fees and expenses of the ETFs.
The Bond and Equity Funds may each use ETFs to gain exposure to various asset classes and markets or types of strategies and investments. By way of example, ETFs may be structured as broad-based ETFs that invest in a broad group of stocks from different industries and market sectors or market ETFs that invest in debt securities from a select sector of the economy, a single industry or related industries; or ETFs that invest in foreign and emerging markets securities. Other types of ETFs continue to be developed and the Funds may invest in them to the extent consistent with its investment objective, policies and restrictions. The ETFs in which the Funds invest are subject to the risks applicable to the types of securities and investments used by the ETFs (e.g., debt securities are subject to risks like credit and interest rate risks; emerging markets securities are subject to risks like currency risks and foreign and emerging markets risks; derivatives are subject to leverage and counterparty risk).
ETFs may be actively managed or index-based. Actively managed ETFs are subject to management risk and may not achieve their objective if the ETF’s manager’s expectations regarding particular securities or markets are not met. An index-based ETF’s objective is to track the performance of a specified index. Index-based ETFs invest in a securities portfolio that includes substantially all of the securities (in substantially the same) amount as the securities included in the designated index. Because passively managed ETFs are designed to track an index, securities may be purchased, retained and sold at times when an actively managed ETF would not do so. As a result, shareholders of a Fund that invest in such an ETF can expect greater risk of loss (and a correspondingly greater prospect of gain) from changes in the value of securities that are heavily weighted in the index than would be the case if the ETF were not fully invested in such securities. This risk is increased if a few component securities represent a highly concentrated weighting in the designated index.
EXCHANGE TRADED NOTES (“ETNs”)
ETNs are senior, unsecured, unsubordinated debt security issued by an underwriting bank and traded on securities exchanges. Similar to other debt securities, ETNs have a maturity date and are backed only by the credit of the issuer. ETNs typically do not pay any interest payments to investors. Instead, the issuer promises to pay the holder of the ETN an amount determined by the performance of the underlying index or benchmark on the ETN’s maturity date (typically 10, 30 or in some cases even 40 years from issuance), minus any specified fees. In addition, unlike traditional bonds, ETNs trade on exchanges throughout the day at prices determined by the market, similar to stocks or ETFs. But unlike ETFs, ETNs do not buy or hold assets to replicate or approximate the performance of the underlying index. Market prices of ETNs may fluctuate due to movements in the indexes they track, as well as other factors, including ETN issuances and redemption activity.
The Strategic Enhanced Yield Fund, the World Energy & Power Fund, the Hedged Equity Income Fund and the Industrial Frontier Fund may each use ETNs to gain exposure to various investment sectors from commodities to emerging markets.
10
Because ETNs are unsecured, unsubordinated debt securities, an investment in an ETN exposes the Fund to the risk that an ETN issuer’s credit rating may be downgraded or that the issuer may default. The value of an ETN may be influenced by time to maturity, level of supply and demand for the ETN, volatility and lack of liquidity in underlying securities’ markets, changes in the applicable interest rates and economic, legal, political, or geographic events that affect the referenced index. In addition, the Fund will bear its proportionate share of the fees and expenses of the ETN, which may cause the Fund’s operating expenses to be higher and its performance to be lower.
The Bond and Equity Funds and the Money Market Funds may, subject to their investment objectives, restrictions and policies, invest in certain obligations or securities of foreign issuers. Permissible investments may include obligations of foreign branches, agencies or subsidiaries of U.S. banks and of foreign banks and investments in foreign securities. For the Bond and Equity Funds, investments may include European certificates of deposit, European time deposits, Canadian time deposits and Yankee certificates of deposit, Canadian commercial paper, and Europaper (U.S. dollar-denominated commercial paper of a foreign issuer). Securities of foreign issuers may include, but are not limited to, EDRs and GDRs. EDRs and GDRs are not listed on the New York Stock Exchange. As a result, it may be difficult to obtain information about EDRs and GDRs. The Strategic Enhanced Yield Fund, the Bond, Limited Duration and World Energy & Power Funds may also invest in Canadian, Supra-national, and World Bank Bonds, Eurodollars, and similar instruments. In addition, the World Energy & Power Fund may invest, directly or indirectly, in foreign currencies.
The Equity Funds may also invest in foreign securities through the purchase of sponsored and unsponsored ADRs. Sponsored ADRs are listed on the New York Stock Exchange; unsponsored ADRs are not. Therefore, there may be less information available about the issuers of unsponsored ADRs than the issuers of sponsored ADRs.
Under normal market conditions, the World Energy & Power Fund will invest at least 40%, but could invest up to 100%, of its portfolio in securities issued by companies organized or having their principal place of business outside the U.S. or doing a substantial amount of business outside the U.S. The World Energy & Power Fund will consider an issuer to be doing a substantial amount of business outside the U.S. if it derives more than 50% percent of its assets, revenue or income outside of the U.S. or is an internationally focused ETF. In the event that market conditions are not deemed favorable, the World Energy & Power Fund would invest at least 30% in foreign securities or securities issued by companies doing a substantial amount of business outside the U.S. Under normal market conditions, the World Energy & Power Fund will invest in securities from at least three different countries.
These instruments may subject a Fund to investment risks that differ in some respects from those related to investments in obligations of U.S. domestic issuers. Such risks include future adverse political and economic developments, the possible imposition of withholding taxes on interest or other income, possible seizure, nationalization, or expropriation of foreign deposits, the possible establishment of exchange controls or taxation at the source, greater fluctuations in value due to changes in exchange rates, or the adoption of other foreign governmental restrictions, which might adversely affect the payment of principal and interest on such obligations. Such investments may also entail higher custodial fees and sales commissions than domestic investments. Foreign issuers of securities or obligations are often subject to accounting treatment and engage in business practices different from those respecting domestic issuers of similar securities or obligations. Foreign branches of U.S. banks and foreign banks may be subject to less stringent reserve requirements than those applicable to domestic branches of U.S. banks. Special U.S. tax considerations may apply to a Fund’s foreign investments.
The Bond and Equity Funds may (1) enter into contracts for the future delivery of securities and futures contracts based on a specific security, class of securities or an index, (2) purchase or sell options on any such futures contracts, and (3) engage in related closing transactions. When a Fund purchases a futures contract, it agrees to buy a specified quantity of the underlying instrument at a specified future date or, in the case of an index futures contract, to make a cash payment based on the value of a securities index. When a Fund sells a futures contract, it agrees to sell a specified quantity of the underlying instrument at a specified future date or, in the case of an index futures contract, to receive a cash payment based on the value of the securities index.
11
When interest rates are expected to rise or market values of portfolio securities are expected to fall, a Fund can seek, through the sale of futures contracts, to offset a decline in the value of its portfolio securities. When interest rates are expected to fall or market values are expected to rise, a Fund, through the purchase of such contracts, can attempt to secure better rates or prices for the Fund than might later be available in the market when it effects anticipated purchases.
The acquisition of put and call options on futures contracts will, respectively, give a Fund the right (but not the obligation), for a specified price, to sell or to purchase the underlying futures contract, upon exercise of the option, at any time during the option period.
Futures transactions involve brokerage costs and require a Fund to segregate assets to cover contracts that would require it to purchase securities. A Fund may lose the expected benefit of futures transactions if interest rates or securities prices move in an unanticipated manner. Such unanticipated changes may also result in poorer overall performance than if the Fund had not entered into any futures transactions. In addition, the value of a Fund’s futures positions may not prove to be perfectly or even highly correlated with the value of its portfolio securities, limiting the Fund’s ability to hedge effectively against interest rate and/or market risk and giving rise to additional risks. There is no assurance of liquidity in the secondary market for purposes of closing out futures positions.
Aggregate initial margin deposits for futures contracts, and premiums paid for related options, may not exceed 5% of a Fund’s total assets, and the value of securities that are the subject of such futures and options (both for receipt and delivery) may not exceed one-third of the market value of a Fund’s total assets. Futures transactions will be limited to the extent necessary to maintain each Fund’s qualification as a regulated investment company (“RIC”).
ILLIQUID SECURITIES — PRIVATE PLACEMENTS AND RESTRICTED SECURITIES
Each of the Funds, except the U.S. Treasury Fund, may invest in securities issued in reliance on the so-called “private placement” exemption from registration afforded by Section 4(a)(2) of the Securities Act of 1933 (the “Securities Act”), and resold to qualified institutional buyers under Securities Act Rule 144A (“Section 4(a)(2) paper”). Section 4(a)(2) paper is restricted as to disposition under the federal securities laws, and generally is sold to institutional investors, who agree that they are purchasing the paper for investment and not with a view to public distribution. Any resale by the purchaser must be in an exempt transaction. Section 4(a)(2) paper normally is resold to other institutional investors through or with the assistance of the issuer or investment dealers who make a market in the Section 4(a)(2) paper, thus providing liquidity. Section 4(a) (2) paper may also be resold to the issuer or certain broker-dealers. The Funds may purchase both liquid and illiquid Section 4(a)(2) paper; however, the Bond and Equity Funds will not invest more than 15% and the Money Market Funds will not invest more than 5% of their net assets in Section 4(a)(2) paper that is illiquid.
Because it is not possible to predict with assurance exactly how the market for Section 4(a)(2) paper will develop, the Adviser, with the general supervision of the Board of Trustees and pursuant to the guidelines approved by the Board of Trustees, will carefully monitor the Funds’ investments in these securities, focusing on such important factors, among others, as valuation, liquidity, and availability of information. Investments in Section 4(a)(2) paper could have the effect of reducing a Fund’s liquidity to the extent that qualified institutional buyers become for a time not interested in purchasing these restricted securities.
An ETF that is constructed by using various derivatives for the purpose of profiting from a decline in the value of an underlying benchmark. An inverse ETF seeks to provide returns that are the opposite of the underlying referenced financial asset, index, or commodity’s returns. Due to daily rebalancing, leverage, and liquidity, inverse ETFs may perform worse that the inverse movement of the underlying reference financial asset, index, or commodity’s returns. Some inverse ETFs are leveraged, meaning that they attempt to mimic 200% or 300% positive or negative returns of an index.
12
Subject to their respective investment restrictions, each of the Funds may invest in shares of other investment companies, including open-end funds, closed-end funds, ETFs and other Cavanal Hill Funds. The Funds may invest in securities of any RIC to the extent permitted by the applicable statutory limits under the 1940 Act and rules, regulations and exemptive orders issued by the SEC thereunder. These investment companies typically pay an investment advisory fee out of their assets. Therefore, these investments may be subject to duplicate management, advisory and distribution fees. When a Fund invests in another Cavanal Hill Fund, Management Fees and Administrative Fees of the investing Fund are rebated but other fees are not.
The World Energy & Power Fund may purchase certain loan participation interests. Loan participation interests represent interests in bank loans made to corporations. The contractual arrangement with the bank transfers the cash stream of the underlying bank loan to the participating investor. Because the issuing bank does not guarantee the participations, they are subject to the credit risks generally associated with the underlying corporate borrower. The secondary market, if any, for these loan participations is extremely limited and any such participations purchased by the investor are regarded as illiquid. In addition, because it may be necessary under the terms of the loan participation for the investor to assert through the issuing bank such rights as may exist against the underlying corporate borrower, in the event the underlying corporate borrower fails to pay principal, and interest when due, the investor may be subject to delays, expenses and risks that are greater than those that would have been involved if the investor had purchased a direct obligation (such as commercial paper) of such borrower. Moreover, under the terms of the loan participation, the investor may be regarded as a creditor of the issuing bank (rather than of the underlying corporate borrower), so that the issuer may also be subject to the risk that the issuing bank may become insolvent. Further, in the event of the bankruptcy or insolvency of the corporate borrower, the loan participation may be subject to certain defenses that can be asserted by such borrower as a result of improper conduct by the issuing bank.
The Strategic Enhanced Yield Fund, the Bond Fund and each of the Equity Funds may invest in MLPs in accordance with each Fund’s investment objectives, restrictions and policies. Certain companies are organized as MLPs in which ownership interests are publicly traded. MLPs often own several properties or businesses (or directly own interests) that are related to real estate development and oil and gas industries, but they also may finance motion pictures, research and development and other projects or provide financial services. Generally, an MLP is operated under the supervision of one or more managing general partners. Limited partners (like a Fund that invests in an MLP) are not involved in the day-to-day management of the partnership. They are allocated income and capital gains associated with the partnership project in accordance with the terms established in the partnership agreement.
MLP investments are equity securities and are subject to the same risks as other equity securities. In addition, risks of investing in an MLP include those inherent in investing in a partnership as opposed to a corporation. For example, state law governing partnerships is often less restrictive than state law governing corporations. Accordingly, there may be less protections afforded investors in an MLP than investors in a corporation. Additional risks involved with investing in an MLP are risks associated with the specific industry or industries in which the partnership invests, such as the risks of investing in the oil and gas industry.
Each of the Funds, except the World Energy & Power Fund and the Industrial Frontier Fund, may, consistent with each Fund’s investment objectives, restrictions and policies, invest in Mortgage-backed securities issued or guaranteed by the U.S. government, its agencies or instrumentalities.
Mortgage-backed securities, for purposes of the Funds’ Prospectus and this SAI, represent pools of mortgage loans assembled for sale to investors by various governmental agencies such as the Government National Mortgage Association (“GNMA”) and government-related organizations such as the Federal National Mortgage Association (“FNMA”) and the Federal Home Loan Mortgage Corporation (“FHLMC”), as well as by nongovernmental issuers such as investment banks, commercial banks, savings and loan institutions, mortgage bankers, and private mortgage insurance companies. Although certain Mortgage-backed securities are guaranteed by a third party or otherwise similarly secured, the market value of such securities, which may fluctuate, is not so secured. If a Fund purchases a Mortgage-backed security at a premium, that premium may be lost if there is a decline in the market value of the security whether resulting from changes in interest rates or prepayments in the underlying mortgage collateral. As with other interest-bearing securities, the prices of such securities are inversely affected by changes in interest rates. However, though the value of a Mortgage-backed security may decline when interest rates rise, the converse is not necessarily true as in periods of declining interest rates the mortgages underlying the securities are prone to prepayment. For this and other reasons, a Mortgage-backed security’s stated maturity may be shortened by unscheduled prepayments on the underlying mortgages and, therefore, it is not possible to predict accurately the security’s return to a Fund. In addition, regular payments received in respect of Mortgage-backed securities include both interest and principal. No assurance can be given as to the return a Fund will receive when these amounts are reinvested.
13
The mortgage market in the United States experienced difficulties after the 2008 financial downturn that may continue to adversely affect the performance and market value of certain of the Fund’s Mortgage-backed investments.
There are a number of important differences among the government-sponsored entities and agencies and instrumentalities of the U.S. government that issue Mortgage-backed securities and among the securities that they issue. The differences in levels of credit support result in different degrees of credit risk.
Ginnie Maes — Mortgage-backed securities issued by the GNMA, including GNMA Mortgage Pass-Through Certificates. Ginnie Maes are either direct obligations of GNMA or are guaranteed by it as to the timely payment of principal, interest, or both. GNMA is a wholly-owned U.S. government corporation within the Department of Housing and Urban Development and, as a result, Ginnie Maes are backed by the full faith and credit of the United States.
Fannie Maes — Mortgage-backed securities issued by the FNMA, including FNMA Guaranteed Mortgage Pass-Through Certificates. Fannie Maes are either direct obligations of FNMA or are guaranteed by it as to the timely payment of principal, interest, or both. FNMA is a government-sponsored enterprise, but it is not a part of the U.S. government. As a result, Fannie Maes are not backed by or entitled to the full faith and credit of the United States, nor is the U.S. government obligated to provide FNMA funds necessary to cover its obligations in respect of Fannie Maes.
Freddie Macs — Mortgage-backed securities issued by the FHLMC, including FHLMC Mortgage Participation Certificates. Freddie Macs are either direct obligations of FHLMC or are guaranteed by it as to the timely payment of principal, interest, or both. FHLMC is a corporate instrumentality of the United States, created pursuant to an Act of Congress. Freddie Macs are, however, not backed by or entitled to the full faith and credit of the United States, nor is the U.S. government obligated to provide FHLMC funds necessary to cover its obligations in respect of Freddie Macs.
The Federal Housing Finance Agency (FHFA) mandated that Fannie Mae and Freddie Mac cease issuing their own Mortgage-backed securities and begin issuing “Uniform Mortgage-Backed Securities” or “UMBS” in 2019. Each UMBS will have a 55-day remittance cycle and can be used as collateral in either a Fannie Mae or Freddie Mac security or held for investment. Investors may be approached to convert existing Mortgage-backed securities into UMBS, possibly with an inducement fee being offered to holders of Freddie Mac mortgage-backed securities.
The Government Securities Money Market Fund, the Limited Duration Fund, the Bond Fund, and the Strategic Enhanced Yield Fund also may invest in CMOs structured on pools of mortgage pass-through certificates or mortgage loans. The Government Securities Money Market Fund will only invest in CMOs which meet the quality requirements of Rule 2a-7 under the 1940 Act. CMOs will be purchased by the Government Securities Money Market Fund only if rated at the time of purchase in one of the three highest rating categories by an NRSRO or, if not rated, found by the Adviser under guidelines approved by the Trust’s Board of Trustees to be of comparable quality. The Strategic Enhanced Yield Fund may invest in CMOs of any credit quality.
The Funds may, consistent with each Fund’s investment objectives, restrictions and policies, invest in Municipal Securities. Municipal Securities include debt obligations issued to obtain funds for various public purposes, such as the construction of a wide range of public facilities, the refunding of outstanding obligations, the payment of general operating expenses, and the extension of loans to other public institutions and facilities.
The Strategic Enhanced Yield Fund, the Bond Fund, the Limited Duration Fund, the World Energy & Power Fund and the Hedged Equity Income Fund, under normal market conditions, may invest in Municipal Securities the income from which is not exempt from federal income taxes.
14
The Funds may purchase short-term tax-exempt General Obligations Notes, Tax Anticipation Notes, Bond Anticipation Notes, Revenue Anticipation Notes, Project Notes, and other forms of short-term tax exempt loans. Such notes are issued with a short-term maturity in anticipation of the receipt of tax funds, the proceeds of bond placements, or other revenues. Project Notes are issued by a state or local housing agency and are sold by the Department of Housing and Urban Development. While the issuing state or local housing agency has the primary obligation with respect to its Project Notes, they are also secured by the full faith and credit of the United States through agreements with the issuing authority which provide that, if required, the federal government will lend the issuer an amount equal to the principal of and interest on the Project Notes.
The two principal classifications of Municipal Securities which may be held by the Funds are “general obligation” securities and “revenue” securities. General obligation securities are secured by the issuer’s pledge of its full faith, credit and taxing power for the payment of principal and interest. Revenue securities are payable only from the revenues derived from a particular facility or class of facilities or, in some cases, from proceeds of a special excise tax or other specific revenue source such as the user of the facility being financed. Private activity bonds held by the Funds are in most cases revenue securities and are not payable from the unrestricted revenues of the issuer. Consequently, the credit quality of private activity bonds is usually directly related to the credit standing of the corporate user of the facility involved.
The Funds may also invest in “moral obligation” securities, which are normally issued by special purpose public authorities. If the issuer of moral obligation securities is unable to meet its debt service obligations from current revenues, it may draw on a reserve fund, the restoration of which is a moral commitment, but not a legal obligation of the state or municipality which created the issuer.
The Strategic Enhanced Yield Fund, the World Energy & Power Fund and the Industrial Frontier Fund may invest in fixed income securities of any credit quality. The Limited Duration Fund and the Bond Fund invest in Municipal Securities which are rated at the time of purchase within the four highest rating groups assigned by an NRSRO, in the case of bonds; rated within the four highest ratings category assigned by an NRSRO, in the case of notes; rated in the highest ratings category assigned by an NRSRO, in the case of tax-exempt commercial paper; or rated in the highest ratings category assigned by an NRSRO, in the case of variable rate demand obligations. The Funds may also purchase Municipal Securities which are unrated at the time of purchase but are determined to be of comparable quality by the Adviser pursuant to guidelines approved by the Trust’s Board of Trustees. The applicable Municipal Securities ratings are described in the Appendix.
There are variations in the quality of Municipal Securities, both within a particular classification and between classifications, and the yields on Municipal Securities depend upon a variety of factors, including general money market conditions, the financial condition of the issuer, general conditions of the municipal bond market, the size of a particular offering, the maturity of the obligations, and the rating of the issue. The ratings of NRSROs represent their opinions as to the quality of Municipal Securities. It should be emphasized, however, that ratings are general and are not absolute standards of quality, and Municipal Securities with the same maturity, interest rate and rating may have different yields while Municipal Securities of the same maturity and interest rate with different ratings may have the same yield. Subsequent to its purchase by a Fund, an issue of Municipal Securities may cease to be rated or its rating may be reduced below the minimum rating required for purchase by the Fund. The Adviser will consider such an event in determining whether the Fund should continue to hold such securities.
Although a Fund may invest more than 25% of its net assets in (i) Municipal Securities whose issuers are in the same state, (ii) Municipal Securities the interest on which is paid solely from revenues of similar projects, and (iii) private activity bonds, they do not currently intend to do so on a regular basis. To the extent these Funds’ assets are concentrated in Municipal Securities that are payable from the revenues of similar projects or are issued by issuers located in the same state, or are concentrated in private activity bonds, the Funds will be subject to the specific risks presented by the laws and economic conditions relating to such states, projects and bonds to a greater extent than it would be if its assets were not so concentrated.
15
An issuer’s obligations under its Municipal Securities are subject to the provisions of bankruptcy, insolvency, and other laws affecting the rights and remedies of creditors, such as the federal bankruptcy code, and laws, if any, which may be enacted by Congress or state legislatures extending the time for payment of principal or interest, or both, or imposing other constraints upon the enforcement of such obligations. The power or ability of an issuer to meet its obligations for the payment of interest on and principal of its Municipal Securities may be materially adversely affected by litigation or other conditions.
Each of the Funds, except the U.S. Treasury Fund and the Government Securities Money Market Fund, may purchase call options. A call option gives the purchaser of the option the right to buy, and a writer has the obligation to sell, the underlying security at the stated exercise price at any time prior to the expiration of the option, regardless of the market price of the security. The premium paid to the writer is consideration for undertaking the obligations under the option contract. Call options purchased by the Funds will be valued at the last sale price, or in the absence of such a price, at the mean between bid and asked price.
The Funds may also purchase index options. Index options (or options on securities indices) are similar in many respects to options on securities, except that an index option gives the holder the right to receive, upon exercise, cash instead of securities, if the closing value of the securities index upon which the option is based is greater than the exercise price of the option.
Purchasing options is a specialized investment technique that entails a substantial risk of a complete loss of the amounts paid as premiums to writers of options. With the exception of the Hedged Equity Income Fund, each of the Funds will purchase call options and index options only when its total investment in such options immediately after such purchase will not exceed 5% of its total assets.
Subject to investment restrictions set forth below, each of the Funds may acquire “puts.” The U.S. Treasury Fund and the Government Securities Money Market Fund may only acquire a put in association with the purchase of an extendable or evergreen types of repurchase agreements that have a put feature. A put is a right to sell a specified security (or securities) within a specified period of time at a specified exercise price. The amount payable to a Fund upon its exercise of a “put” on debt securities is normally (i) the Fund’s acquisition cost of the securities (excluding any accrued interest which the portfolio paid on their acquisition), less any amortized market premium or plus any amortized market or original issue discount during the period the Fund owned the securities, plus (ii) all interest accrued on the securities since the last interest payment date during that period.
Puts may be acquired by a Fund to facilitate the liquidity of its portfolio assets. Puts may also be used to facilitate the reinvestment of a Fund’s assets at a rate of return more favorable than that of the underlying security or to limit the potential losses involved in a decline in an equity security’s market value. The Hedged Equity Income Fund buys puts to hedge the equity holdings. Put options purchased may include puts on individual securities, ETFs, and indices.
Each Fund intends to enter into puts only with dealers, banks, and broker-dealers which, in the Adviser’s opinion, present minimal credit risks.
Preferred stock is a class of stock that generally pays dividends at a specified rate and has preference over common stock in the payment of dividends and liquidation. Preferred stock generally does not carry voting rights. As with all equity securities, the price of preferred stock fluctuates based on changes in a company’s financial condition and on overall market and economic conditions.
16
Securities held by each of the Funds may be subject to repurchase agreements. Under the terms of a repurchase agreement, a Fund would acquire securities from a financial institution such as a member bank of the Federal Deposit Insurance Corporation, the Federal Reserve system or a registered broker-dealer, which the Adviser deems creditworthy under guidelines approved by the Board of Trustees, subject to the seller’s agreement to repurchase such securities at a mutually agreed-upon date and price. The repurchase price would generally equal the price paid by the Fund plus interest negotiated on the basis of current short-term rates, which may be more or less than the rate on the underlying portfolio securities. The seller under a repurchase agreement will be required to maintain the value of collateral held pursuant to the agreement at not less than the repurchase price (including accrued interest). If the seller were to default on its repurchase obligation or become insolvent, a Fund would suffer a loss to the extent that the proceeds from a sale of the underlying portfolio securities were less than the repurchase price under the agreement, or to the extent that the disposition of such securities by the Fund were delayed pending court action. There is also the risk that the collateral underlying a repurchase agreement will decline in value, and that counter-parties will not meet their obligation to provide additional or substituted collateral in those circumstances. Additionally, there is no controlling legal precedent confirming that a Fund would be entitled, as against a claim by such seller or its receiver or trustee in bankruptcy, to retain the underlying securities, although the Board of Trustees of the Trust believes that, under the regular procedures normally in effect for custody of each Fund’s securities subject to repurchase agreements and under applicable federal laws, a court of competent jurisdiction would rule in favor of a Fund if presented with the question. Securities subject to repurchase agreements will be held by each Fund’s Custodian, sub-custodian, or in the Federal Reserve/Treasury book-entry system. Repurchase agreements are considered to be loans by an investment company under the 1940 Act.
Each Fund may borrow funds for temporary purposes by entering into reverse repurchase agreements in accordance with the investment restrictions described below. Pursuant to such agreements, a Fund would sell portfolio securities to financial institutions such as banks and broker-dealers and agree to repurchase them at a mutually agreed upon date and price. At the time a Fund enters into a reverse repurchase agreement, it will place in a segregated custodial account assets, such as liquid high quality debt securities, consistent with the Fund’s investment objective having a value not less than 100% of the repurchase price (including accrued interest), and will subsequently monitor the account to ensure that such required value is maintained. Reverse repurchase agreements involve the risk that the market value of the securities sold by a Fund may decline below the price at which such Fund is obligated to repurchase the securities. Reverse repurchase agreements are considered to be borrowings by an investment company under the 1940 Act.
Each of the Funds may lend its portfolio securities to broker-dealers, banks or institutional borrowers of securities. A Fund must receive 100% collateral in the form of cash, U.S. government securities or other high quality debt securities. This collateral must be valued daily by the Adviser and should the market value of the loaned securities increase, the borrower must furnish additional collateral to the Fund. During the time portfolio securities are on loan, the borrower will pay the Fund any dividends or interest paid on such securities. Loans will be subject to termination by a Fund or the borrower at any time. While a Fund will not have the right to vote securities in loan, the Trust generally intends to terminate the loan and regain the right to vote if that is considered material with respect to the investment. A Fund will only enter into loan arrangements with broker-dealers, banks or other institutions which the Adviser has determined are creditworthy under guidelines approved by the Trust’s Board of Trustees. Each Fund will limit securities loans to 33-1/3% of the value of its total assets.
The U.S. Treasury Fund invests exclusively in direct obligations of the U.S. government, some or all of which may be subject to repurchase agreements. The other Funds may invest in obligations issued or guaranteed by the U.S. government, its agencies or instrumentalities, some of which may be subject to repurchase agreements. Obligations of certain agencies and instrumentalities of the U.S. government are supported by the full faith and credit of the U.S. government; others are supported by the right of the issuer to borrow from the government; others are supported by the discretionary authority of the U.S. government to purchase the agency’s obligations; and still others are supported only by the credit of the instrumentality. No assurance can be given that the U.S. government would provide financial support to U.S. government-sponsored agencies or instrumentalities if it is not obligated to do so by law. A Fund will invest in the obligations of such agencies or instrumentalities only when the Adviser believes that the credit risk with respect thereto is minimal.
17
VARIABLE RATE AND FLOATING RATE NOTES
Debt instruments eligible for investment by the Funds may include variable rate and floating rate notes. The U.S. Treasury Fund may only invest in variable rate and floating rate notes that are direct obligations of the U.S. government. The Government Securities Money Market Fund may only invest in variable rate and floating rate notes that are obligations of the U.S. government or its agencies or instrumentalities. A variable rate note is one whose terms provide for the readjustment of its interest rate on set dates and which, upon such readjustment, can reasonably be expected to have a fair market value that approximates its par value. A floating rate note is one whose terms provide for the readjustment of its interest rate whenever a specified interest rate changes and which, at any time, can reasonably be expected to have a market value that approximates its par value. Variable and floating rate notes purchased by a Fund, other than the Strategic Enhanced Yield Fund or the World Energy & Power Fund, will be rated at the time of purchase in the four highest ratings categories assigned by an NRSRO or, if not rated, as determined by the Adviser under guidelines approved by the Funds’ Board of Trustees to be of comparable quality. The Strategic Enhanced Yield Fund and the World Energy & Power Fund may invest in variable and floating rate notes of any credit quality. An inactive secondary market with respect to a particular variable or floating rate note could make it difficult for the Fund to dispose of the variable or floating rate note involved in the event the issuer of the note defaulted on its payment obligations, and the Fund could, for this or other reasons, suffer a loss to the extent of the default. Variable or floating rate notes may be secured by bank letters of credit or drafts.
Coupon rates on floating rate notes are tied to a benchmark lending rate, such as the Secured Overnight Financing Rate or “SOFR”. The Federal Reserve Bank of New York began publishing the SOFR in April 2018. SOFR, which is a broad measure of the cost of overnight borrowing of cash collateralized by Treasury securities, is intended to serve as a reference rate for U.S. dollar-based debt and derivatives.
Variable rate master demand notes in which the Strategic Enhanced Yield Fund may invest are unsecured demand notes that permit the indebtedness thereunder to vary, and provide for periodic adjustments in the interest rate according to the terms of the instrument. Although the secondary market for the notes may be limited, the Fund may demand payment of principal and accrued interest at any time. The period of time remaining until the principal amount can be recovered under a variable rate master demand note generally shall not exceed seven days. To the extent such maximum period were exceeded, the note in question would be considered illiquid. The Strategic Enhanced Yield Fund may invest in variable rate master demand notes of any credit quality.
In determining average dollar-weighted portfolio maturity, a variable rate master demand note will be deemed to have a maturity equal to the longer of the period of time remaining until the next readjustment of the interest rate or the period of time remaining until the principal amount can be recovered from the issuer through demand. Variable or floating rate notes with stated maturities of more than one year may, based on the amortized cost valuation technique pursuant to Rule 2a-7 under the 1940 Act, be deemed to have shorter maturities in accordance with such Rule.
Each Fund may purchase securities on a when-issued basis. When-issued securities are securities purchased for delivery at an unknown or unspecified settlement date at a stated price and yield and thereby involve a risk that the yield obtained in the transaction will be less than those available in the market when delivery takes place. A Fund relies on the seller to consummate the trade and will generally not pay for such securities or start earning interest on them until they are received. When a Fund agrees to purchase such securities, its Custodian will set aside cash or liquid high grade securities equal to the amount of the commitment in a separate account with the Custodian or a sub-custodian of the Fund. Failure of the seller to consummate the trade may result in the Fund incurring a loss or missing an opportunity to obtain a price considered to be advantageous. Securities purchased on a when-issued basis are recorded as an asset and are subject to changes in value based upon changes in the general level of interest rates.
Each Fund expects that commitments to purchase when-issued securities will not exceed 25% of the value of its total assets absent unusual market conditions. In the event that its commitments to purchase when-issued securities ever exceed 25% of the value of its total assets, a Fund’s liquidity and the ability of the Adviser to manage it might be severely affected. No Fund intends to purchase when-issued securities for speculative purposes but only in furtherance of its investment objective.
Each of the Funds may hold zero-coupon obligations, to the extent consistent with each Fund’s investment objectives, restrictions and policies. The U.S. Treasury Fund and the Government Securities Money Market Fund may only hold zero-coupon obligations issued by the U.S. Treasury or U.S. government agencies. Zero-coupon obligations pay no current interest and are typically sold at prices greatly discounted from par value, with par value to be paid to the holder at maturity. The return on a zero-coupon obligation, when held to maturity, equals the difference between the par value and the original purchase price. Zero-coupon obligations have greater price volatility than coupon obligations and such obligations will be purchased only if, at the time of purchase, the yield spread, considered in light of the obligation’s duration, is considered advantageous.
18
Even though such bonds do not pay current interest in cash, a Fund nonetheless is required to accrue interest income on these investments and to distribute the interest income on a current basis. In order to generate sufficient cash to make the requisite distributions, the Funds could be required at times to liquidate other investments in its portfolio that it otherwise would have continued to hold, including when it is not advantageous to liquidate such investments.
Each Fund may, from time to time, take temporary defensive positions that are inconsistent with such Fund’s principal investment strategy in attempting to respond to adverse market, economic, political, or other conditions. In these and in other cases, a Fund may not achieve its investment objective. Without limiting the foregoing, during temporary defensive periods, as determined by the Adviser, each of the Funds may hold up to 100% of its respective total assets in cash or cash equivalents.
Unless otherwise specifically noted, the following investment restrictions are fundamental and, as such, may be changed with respect to a particular Fund only by a vote of a majority of the outstanding Shares of that Fund. These restrictions supplement the investment objective and policies of the Funds as set forth in the Prospectus. The fundamental investment restrictions have been adopted to avoid wherever possible the necessity of shareholder meetings unless otherwise required by the 1940 Act. Except with respect to the Fund’s restrictions governing the borrowing of money, if a percentage restriction is satisfied at the time of investment, a later increase or decrease in such percentage resulting from a change in asset value will not constitute a violation of such restriction.
| 1. | None of the Funds shall purchase securities on margin, except that the Funds may obtain such short-term credits as are necessary for the clearance of portfolio transactions, and the Funds may make margin payments in connection with futures contracts, options, forward contracts, swaps, caps, floors, collars and other financial instruments. |
| 2. | None of the Funds shall sell securities short (unless it owns or has the right to obtain securities equivalent in kind and amount to the securities sold short or has segregated with the Custodian an amount of cash or liquid assets to cover the short position), however, this policy does not prevent the Funds from entering into short positions in foreign currency, futures contracts, options, forward contracts, swaps, caps, floors, collars and other financial instruments. |
| 3. | None of the Funds shall write call options if the Fund does not own the underlying security. |
| 4. | None of the Funds shall participate on a joint, or joint and several, basis in any securities trading account, except for use of short-term credit necessary for clearance of purchases of portfolio securities. |
| 5. | None of the Funds shall underwrite the securities of other issuers, except to the extent that a Fund may be deemed to be an underwriter under certain securities laws in the disposition of “restricted securities.” |
| 6. | None of the Funds shall purchase or sell commodities or commodity contracts, except that (i) the Bond Fund may invest in futures contracts and options on futures contracts for commodities if, immediately thereafter, the aggregate initial margin deposits for futures contracts, and premium paid for related options, does not exceed 5% of such Fund’s total assets and the value of securities that are the subject of such futures and options (both for receipt and delivery) does not exceed one-third of the value of the Fund’s total assets and (ii) the World Energy & Power Fund shall be limited to investments in commodity derivative instruments; provided, however, it may purchase ETFs that invest in commodities, commodity futures and options. |
| 7. | None of the Funds shall purchase participations or other direct interests in oil, gas or mineral exploration or development programs or leases (however, investments by the Bond and Equity Funds in marketable securities of companies engaged in such activities are not precluded). |
19
| 8. | None of the Funds shall invest in any issuer for purposes of exercising control or management. |
| 9. | None of the Funds shall purchase or retain securities of any issuer if the officers or Trustees of the Funds or the officers or directors of the Adviser owning beneficially more than one-half of 1% of the securities of such issuer together own beneficially more than 5% of such securities. |
| 10. | None of the Funds shall invest more than 5% of a Fund’s total assets in the securities of issuers which together with any predecessors have a record of less than three years of continuous operation. |
| 11. | None of the Funds shall purchase or sell real estate, including real estate limited partnership interests (however, each Bond Fund and Equity Fund may, to the extent appropriate to its investment objective, purchase securities secured by real estate or interests therein or securities issued by companies investing in real estate or interests therein). |
| 12. | Under the 1940 Act, and the rules, regulations and interpretations thereunder, a “diversified company,” as to 75% of its total assets, may not purchase securities of any one issuer (other than obligations of, or guaranteed by, the U.S. government, its agencies or its instrumentalities) if, as a result, more than 5% of the value of its total assets would be invested in the securities of such issuer or more than 10% of the issuer’s voting securities would be held by the fund. Each of the Funds, other than the Hedged Equity Income Fund and the Industrial Fronter Fund, is a “diversified company” and shall be subject to the foregoing limitations. In addition, though not a fundamental investment restriction (and therefore subject to change without a shareholder vote), to the extent required by rules of the SEC, the U.S. Treasury Fund and the Government Securities Money Market Fund each generally apply the diversified company restriction with respect to 100% of their portfolios (rather than 75%). As non-diversified funds, the Hedged Equity Income Fund and Industrial Frontier Fund not subject to the foregoing limitations. |
| 13. | “Concentration” is generally interpreted under the 1940 Act to mean investing more than 25% of total assets in an industry or group of industries. With the exception of the World Energy & Power Fund and the Industrial Frontier Fund, none of the Funds may purchase a security if, as a result, more than 25% of the value of its total assets would be invested in securities of one or more issuers conducting their principal business activities in the same industry, provided that (a) this limitation shall not apply to the purchase of obligations issued or guaranteed by the U.S. government or its agencies and instrumentalities, or, for money market funds, in accordance with its investment objectives and policies, bank certificates of deposits, bankers’ acceptances, and repurchase agreements secured by bank instruments (such bank certificates of deposits, bankers’ acceptances, and repurchase agreements secured by bank instruments may be issued or guaranteed by U.S. banks and U.S. branches of foreign banks); (b) wholly owned finance companies will be considered to be in the industries of their parents if their activities are primarily related to financing the activities of their parents; and (c) utilities will be divided according to their services (for example, gas, gas transmission, electric and gas, electric, and telephone will each be considered a separate industry) and (d) this limitation shall not apply to tax-exempt Municipal Securities or governmental guarantees of Municipal Securities; and further, that for the purpose of this limitation only, private activity bonds that are backed only by the assets and revenues of a non-governmental user shall not be deemed to be Municipal Securities. The World Energy & Power Fund shall not concentrate its investments in any industry or group of industries other than the energy industry or group of industries. The Industrial Frontier Fund shall not concentrate its investments in any industry or group of industries other than the industrials-related industry or group of industries. |
| 14. | The 1940 Act limits a Fund’s ability to borrow money. A Fund may borrow from any bank, provided that immediately after any such borrowing there is an asset coverage of at least 300% for all borrowings by such Fund. None of the Funds shall borrow money, except that (i) each Fund may obtain such short-term credits as are necessary for the clearance of portfolio transactions and (ii) each Fund may borrow from banks and enter into reverse repurchase agreements for temporary purposes in amounts up to 10% of the value of its total assets at the time of such borrowing. Any mortgage, pledge, or hypothecation in connection with any such borrowing shall be in amounts not in excess of the lesser of the dollar amounts borrowed or 10% of the value of such Fund’s total assets at the time of its borrowing. No Fund will purchase securities while its borrowings (including reverse repurchase agreements) exceed 5% of the total assets of such Fund. |
| 15. | None of the Funds shall make loans, except that each Fund may purchase or hold debt instruments in accordance with its investment objectives and policies, may lend portfolio securities in accordance with its investment objectives and policies and may enter into repurchase agreements. |
20
| 16. | None of the Funds may invest more than the applicable percentage of such Fund’s net assets in securities with legal or contractual restrictions on resale or for which no readily available market exists but exclude such securities if resaleable pursuant to Rule 144A under the Securities Act. For the Money Market Funds that percentage is 5%; for the other Funds, the percentage is 15%. |
| 17. | None of the Funds shall enter into repurchase agreements with maturities in excess of seven days if such investment, together with other instruments in such Fund that are not readily marketable, exceeds the percentage of such Fund’s net assets that are permitted to be invested in illiquid securities. For the Money Market Funds that percentage is 5%; for the other Funds, the percentage is 15%. |
| 18. | The 1940 Act limits the amount that a Fund may invest in other investment companies, prohibiting a Fund from: (i) owning more than 3% of the total outstanding voting stock of a single other investment company; (ii) investing more than 5% of its total assets in the securities of a single other investment company; and (iii) investing more than 10% of its total assets in securities of all other investment companies. However, subject to the provisions of Section 12(d)(1) of the 1940 Act and rules and regulations issued by the SEC thereunder, each of the Funds may invest in shares of affiliated or unaffiliated RICs in excess of statutory limits, to the extent permitted by its investment strategy. |
| 19. | The 1940 Act prohibits an open-end fund from issuing senior securities, as defined in the 1940 Act, except under very limited circumstances. None of the Funds shall issue senior securities except as specifically permitted. |
In addition, the U.S. Treasury Fund may not:
| 1. | Purchase securities other than U.S. Treasury bills, notes and other obligations backed by the full faith and credit of the U.S. government, some of which may be subject to repurchase agreements; provided, however, the U.S. Treasury Fund may purchase investment company securities that meet the qualifications necessary to be classified as a U.S. Treasury Fund. |
The Funds have also adopted non-fundamental investment restrictions, set forth below. This recognizes the need to react quickly to changes in the law or new investment opportunities in the securities markets and the cost and time involved in obtaining shareholder approvals for diversely held investment companies. Any changes in the non-fundamental investment policies approved by the Trustees will be communicated to its Shareholders at least 60 days prior to effectiveness. The 80% investment requirements below will be based on net assets plus any borrowings for investment purposes.
| 1. | The Limited Duration Fund, the Bond Fund, and the Strategic Enhanced Yield Fund under normal market conditions, will each invest at least 80% of the value of its net assets in bonds. |
| 2. | The Bond Fund, under normal circumstances, maintains an average portfolio maturity between 3 and 10 years. |
| 3. | The Limited Duration Fund, under normal circumstances, maintains an average portfolio duration of less than three and one-half years. |
21
| 4. | The U.S. Treasury Fund, under normal circumstances, invests at least 99.5% of its total assets in cash, U.S. Government Securities or repurchase agreements collateralized by U.S. Government Securities. The Fund also invests at least 80% of its net assets in U.S. Treasury Obligations or repurchase agreements collateralized by U.S. Treasury Obligations. |
| 5. | The Government Securities Money Market Fund, under normal circumstances, invests at least 99.5% of its total assets in cash, U.S. Government Securities or repurchase agreements collateralized by U.S. Government Securities. The Fund also invests at least 80% of its net assets in U.S. Government Securities or repurchase agreements collateralized by U.S. Government Securities. |
| 6. | The World Energy & Power Fund, under normal circumstances, invests at least 80% of its net assets in a wide range of energy-related financial instruments issued in the U.S. and markets around the world. |
| 7. | The World Energy & Power Fund, under normal circumstances, invests in securities of issuers from at least three different countries. |
| 8. | The Hedged Equity Income Fund, under normal circumstances, invests at least 80% of its net assets in equity securities and equity-related instruments. |
| 9. | The Industrial Fronter Fund, under normal circumstances, invests at least 80% of its net assets in a wide range of companies in the “industrial frontier.” |
| 10. | The Limited Duration Fund, the Bond Fund, the Strategic Enhanced Yield Fund, the World Energy & Power Fund, the Hedged Equity Income Fund and the Industrial Frontier Fund will not rely on the exception set forth in Fundamental Policy 13(a), which shall apply only to the Money Market Funds. |
Any notice required to be delivered to shareholders of a Fund for the purpose of announcing an intended change in a non-fundamental policy of the Fund (as described in this SAI or in the Prospectus) will be provided in plain English in a separate written document. Each such notice will contain, in bold-face type and placed prominently in the document, the following statement: “Important Notice Regarding Change in Investment Policy”. This statement will also appear on the envelope in which such notice is delivered.
The portfolio turnover rate for each Bond and Equity Fund is calculated by dividing the lesser of purchases or sales of portfolio securities for the year by the monthly average value of the portfolio securities. The calculation excludes all securities whose maturities, at the time of acquisition, were one year or less. Fund turnover may vary greatly from year to year as well as within a particular year, and may also be affected by cash requirements for redemptions of Shares and by requirements that enable the Funds to receive certain favorable tax treatments. Fund turnover will not be a limiting factor in making portfolio decisions. High turnover rates will generally result in higher transaction costs to a Fund and may result in additional tax consequences to a Fund’s Shareholders, including an increase in short-term capital gains which are generally taxed to individual Shareholders at ordinary income tax rates.
The portfolio turnover rates for each of the Bond and Equity Funds in the subject fiscal years ended August 31 were as follows:*
| FUND | 2026 (%) | 2025 (%) | ||||||
| Limited Duration Fund | [ ] | 6 | ||||||
| Bond Fund | [ ] | 24 | ||||||
| Strategic Enhanced Yield Fund | [ ] | 112 | ||||||
| World Energy & Power Fund | [ ] | 175 | ||||||
| Hedged Equity Income Fund | [ ] | 18 | ||||||
* The Industrial Frontier Fund had not commenced operations as of August 31, 2026.
22
ADDITIONAL TAX INFORMATION CONCERNING THE FUNDS
The following discussion is a brief summary of some of the important federal (and, where noted, state and local) income tax consequences affecting each Fund and its shareholders. The discussion is very general, and prospective investors are urged to consult their tax advisors about the impact an investment in a Fund may have on their own tax situations and the possible application of foreign, federal, state, and local law.
The following discussion is based on the Internal Revenue Code of 1986, as amended (the “Code”) and Treasury Regulations as in effect on January 1, 2025. Prospective investors are urged to consult their tax advisors regarding the effect of recent and proposed future changes to the tax laws.
Each Fund generally will be treated as a separate entity for federal income tax purposes, and thus the provisions of the Code, generally will be applied to each Fund separately. Net long-term and short-term capital gains, net income and operating expenses therefore will be determined separately for each Fund.
QUALIFICATION AS A REGULATED INVESTMENT COMPANY
It is the policy of each Fund to elect to be treated as and to qualify each year as a RIC under Subchapter M of the Code. By following such policy, each Fund expects to eliminate or reduce to a nominal amount the federal income taxes to which such Fund may be subject.
In order to qualify for the special tax treatment accorded regulated investment companies and their shareholders, a Fund must, among other things, (a) derive at least 90% of its gross income for each taxable year from (i) dividends, interest, payments with respect to certain securities loans, and gains from the sale or other disposition of stock, securities, or foreign currencies, or other income (including, but not limited to, gains from options, futures, or forward contracts) derived with respect to its business of investing in such stock, securities, or currencies and (ii) net income derived from interests in “qualified publicly traded partnerships” (“QPTPs”, as defined below); (b) diversify its holdings so that, at the end of each quarter of the Fund’s taxable year (i) at least 50% of the market value of its total assets is represented by cash, cash items (including receivables), U.S. government securities, securities of other regulated investment companies, and other securities, limited in respect of any one issuer to a value not greater than 5% of the value of the Fund’s total assets and 10% of the outstanding voting securities of such issuer, and (ii) not more than 25% of the value of its total assets is invested, including through corporations in which a Fund owns a 20% or more voting stock interest, (x) in the securities (other than those of the U.S. government or other regulated investment companies) of any one issuer or of two or more issuers which the Fund controls and which are engaged in the same, similar, or related trades or businesses, or (y) in the securities of one or more QPTPs; and (c) each taxable year distribute at least 90% of the sum of its investment company taxable income (as that term is defined in the Code without regard to the deduction for dividends paid — generally taxable ordinary income, and the excess, if any, of its net short-term capital gain over its net long-term capital loss) and net tax-exempt interest income, for such year.
In general, for purposes of the 90% gross income requirement described in (a) above, income derived from a partnership will be treated as qualifying income only to the extent such income is attributable to items of income of the partnership which would be qualifying income if realized by the RIC. 100% of the net income derived from an interest in a QPTP (defined as a partnership interest traded on an established securities market or readily tradable on a secondary market or the substantial equivalent thereof and that derives less than 90% of its income from the qualifying income described in (a)(i) above) will, however, be treated, in aggregate, as qualifying income. Although income from QPTPs is qualifying income, as discussed above, such investments cannot exceed 25% of the Fund’s total assets. In addition, although the passive-loss rules of the Code generally do not apply to regulated investment companies, such rules do apply to a RIC with respect to items attributable to an interest in a QPTP.
For purposes of the diversification requirements set forth in (b) above, the term “outstanding voting securities of such issuer” will include the equity securities of a QPTP. Also, for purposes of the diversification requirements set forth in (b) above, in the case of a Fund’s investments in loan participations, the Fund shall treat both the financial intermediary and the issuer of the underlying loan participation as an issuer.
23
Gains from foreign currencies (including foreign-currency options, foreign-currency futures and foreign-currency forward contracts) currently constitute qualifying income for purposes of the 90% gross income test. The Treasury Department does, however, have the authority to issue regulations (possibly with retroactive effect) that exclude a fund’s foreign-currency gains from the definition of “qualifying income” to the extent that such income is not directly related to the fund’s principal business of investing in stock or securities.
If a Fund qualifies as a RIC that is accorded special tax treatment, the Fund will not be subject to federal income taxation on income that is distributed in a timely manner to its shareholders in the form of dividends, including dividends that are properly reported as Capital Gain Dividends or exempt-interest dividends (as each is defined below). If a Fund should fail to qualify as a RIC accorded special tax treatment in any taxable year, the Fund would be subject to taxation on its taxable income at the corporate income tax rates (without any deduction for distributions to its shareholders), and all distributions from earnings and profits, including any distributions of net tax-exempt income and net long-term capital gains, would be taxable to shareholders as dividends. Some portions of such distributions may be eligible for the dividends-received deduction in the case of corporate shareholders and qualified dividend income for non-corporate shareholders. In addition, the Fund could be required to recognize unrealized gains, pay substantial taxes and interest and make substantial distributions before requalifying as a RIC that is accorded special tax treatment.
A Fund will, however, not fail to qualify as a RIC if a failure to satisfy the annual 90% gross income test described in (a) above is due to reasonable cause and not due to willful neglect, provided the failure is reported to the United States Internal Revenue Service (“IRS”). In such cases, the Fund would be required to pay a tax equal to the excess of the non-qualifying gross income over 1/9 of the qualifying income.
A Fund will also not fail to qualify as a RIC if a failure to satisfy the asset test described in (b) above is due to reasonable cause and not due to willful neglect, provided the failure is reported to the IRS and the failure is timely cured by a disposition of assets or the asset test is otherwise timely satisfied. In such cases the Fund would be required to pay a tax equal to the greater of $50,000 or the corporate income tax rate multiplied by the income generated by the assets that caused the failure. Failure of the asset test by a de minimis amount also will not cause a Fund to fail to qualify as a RIC, and in such cases no penalty tax would be due.
Capital loss carryovers may be used to offset current capital gains (whether short-term or long-term) indefinitely, and will retain their character as short-term or long-term capital losses.
As of August 31, 2026, the following Funds had capital loss carryforwards not subject to expiration:
| Fund | Short-Term Amount | Long-Term Amount | Total | |||||||||
| U.S. Treasury Fund | $ | [ ] | $ | [ ] | $ | [ ] | ||||||
| Government Securities Money Market Fund | $ | [ ] | $ | [ ] | $ | [ ] | ||||||
| Limited Duration Fund | $ | [ ] | $ | [ ] | $ | [ ] | ||||||
| Bond Fund | $ | [ ] | $ | [ ] | $ | [ ] | ||||||
| Strategic Enhanced Yield Fund | $ | [ ] | $ | [ ] | $ | [ ] | ||||||
| World Energy & Power Fund | $ | [ ] | $ | [ ] | $ | [ ] | ||||||
| Hedged Equity Income Fund | $ | [ ] | $ | [ ] | $ | [ ] | ||||||
All or a portion are limited as a result of changes in ownership in connection with business combinations. Unused limitations during a year accumulate for future use in offsetting net capital gains.
To the extent that these carryforwards are used to offset future capital gains, it is probable that the gains that are offset will not be distributed to shareholders.
24
EXCISE TAX ON REGULATED INVESTMENT COMPANIES
If a Fund fails to distribute in a calendar year at least an amount equal to the sum of 98% of its ordinary income for the year and 98.2% of its capital gain net income for the one-year period ending October 30 and any retained amount from the prior calendar year, the Fund will be subject to a nondeductible 4% excise tax on the undistributed amounts. For these purposes, a Fund will be treated as having distributed any amount on which it is subject to income tax. Each Fund intends generally to make distributions sufficient to avoid imposition of this 4% excise tax, but each Fund reserves the right to pay an excise tax rather than make an additional distribution when circumstances warrant (e.g., the estimated excise tax amount is deemed by a Fund to be de minimis). Certain derivative instruments give rise to ordinary income and loss. As the Funds have a taxable year that begins in one calendar year and ends in the next calendar year, each Fund will be required to make this excise-tax distribution during its taxable year. There is a risk that a Fund could recognize income prior to making this excise-tax distribution and could recognize loss after making this distribution. As a result, an excise tax distribution could constitute, in whole or in part, a return of capital (see discussion below).
Each Fund expects to qualify to be taxed as a RIC and to be relieved of all or substantially all federal income taxes. The Funds may be subject to certain state or local tax laws depending upon the extent of their activities in the states and localities in which their offices are maintained, in which their agents or independent contractors are located, or in which they are otherwise deemed to be conducting business.
Each Fund will distribute, at least annually, its net investment income and net realized capital gain. Distributions of any net investment income (other than distributions properly designated as qualified dividend income and exempt-interest dividends, as discussed below) generally are taxable to shareholders as ordinary income. Taxes on distributions of capital gain are determined by how long the Fund owned the investments that generated the gains, rather than how long a shareholder has owned his or her Shares. Distributions of net capital gain (that is, the excess of net long-term capital gain from the sale of investments that the Fund owned for more than one year over net short-term capital loss), if any, that are properly designated by the Fund as capital-gain dividends (“Capital Gain Dividends”), will be taxable as long-term capital gain regardless of how long a shareholder has held Fund Shares. Distributions of gains from the sale of investments that a Fund owned for one year or less will be taxable as ordinary income. Distributions of long-term capital gain generally will be subject to a 20% tax rate in the hands of shareholders who are individuals, with lower rates applying to taxpayers in tax rate brackets lower than the highest rate bracket, and will not be eligible for the dividends-received deduction. Distributions from capital gain are generally made after applying any capital loss carryover. Distributions are taxable to Fund shareholders whether received in cash or reinvested in additional Fund Shares.
Dividends and distributions on a Fund’s Shares are generally subject to federal income taxation as described herein to the extent they do not exceed the Fund’s realized income and gains, even though such dividends and distributions may represent economically a return of a particular shareholder’s investment. Such distributions are likely to occur in respect of Shares purchased at a time when the Fund’s NAV reflects gains that are either unrealized, or realized but not yet distributed. Such realized gains may be required to be distributed even when the Fund’s NAV also reflects unrealized losses.
If a Fund makes a distribution in excess of its net investment income and net realized capital gains, if any, in any taxable year, the excess distribution will be treated as ordinary dividend income (not eligible for tax-exempt treatment) to the extent of the Fund’s current and accumulated “earnings and profits” (including earnings and profits arising from tax-exempt income, and also specifically including the amount of any non-deductible expenses arising in connection with such tax-exempt income). For Funds with taxable years other than the calendar year, if post-December 31 distributions exceed the amount of the excess distribution for the taxable year, the entire excess distribution will be allocated to post-December 31 distributions and will be treated as ordinary income. Distributions in excess of earnings and profits will be treated as a return of capital to the extent of a shareholder’s basis for tax purposes in Fund Shares, and thereafter as capital gain. A return of capital is not taxable, but it does reduce the shareholder’s basis in the Shares, which increases the gain (or reduces the loss) on a subsequent taxable disposition by the shareholder of those Shares.
A dividend paid to shareholders by a Fund in January generally is deemed to have been paid by the Fund on December 31 of the preceding year, if the dividend was declared and payable to shareholders of record on a date in October, November or December of that preceding year. The Funds will provide federal tax information to its shareholders annually, including information about dividends and distributions paid during the preceding year.
25
In general, distributions of investment income reported by a Fund as derived from “qualified dividend income” will be treated as qualified dividend income by a non-corporate shareholder provided the shareholder meets the holding period and other requirements. In order for some portion of the dividends received by a Fund shareholder to be qualified dividend income, the Fund must meet holding period and other requirements with respect to some portion of the dividend-paying stocks in its portfolio and the shareholder must meet holding period and other requirements with respect to the Fund’s Shares. A dividend will not be treated as qualified dividend income (at either the Fund or shareholder level) (1) if the dividend is received with respect to any share of stock held for fewer than 61 days during the 121-day period beginning on the date which is 60 days before the date on which such share becomes ex-dividend with respect to such dividend (or, in the case of certain preferred stock, 91 days during the 181-day period beginning 90 days before such date), (2) to the extent that the recipient is under an obligation (whether pursuant to a short sale or otherwise) to make related payments with respect to positions in substantially similar or related property, (3) if the recipient elects to have the dividend income treated as investment income for purposes of the limitation on deductibility of investment interest, or (4) if the dividend is received from a foreign corporation that is (a) not eligible for the benefits of a comprehensive income tax treaty with the United States (with the exception of dividends paid on stock of such a foreign corporation readily tradable on an established securities market in the United States) or (b) treated as a passive foreign investment company. The Funds do not expect a significant portion of their distributions to be derived from qualified dividend income.
In any event, if the aggregate qualified dividends received by a Fund during any taxable year are 95% or more of its gross income, then 100% of the Fund’s dividends (other than Capital Gain Dividends) will be eligible to be treated as qualified dividend income. For this purpose, the only gain included in the term “gross income” is the excess of net short-term capital gain over net long-term capital loss.
Dividends of net investment income received by corporate shareholders of a Fund will qualify for the dividends-received deduction generally available to corporations to the extent of the amount of qualifying dividends received by the Fund from domestic corporations for the taxable year. A dividend received by a Fund will not be treated as a qualifying dividend (1) if the stock on which the dividend is paid is considered to be “debt-financed” (generally, acquired with borrowed funds), (2) if it has been received with respect to any share of stock that the Fund has held for less than 46 days (91 days in the case of certain preferred stock) during the 91-day period beginning on the date which is 45 days before the date on which such share becomes ex-dividend with respect to such dividend (during the 181-day period beginning 90 days before such date in the case of certain preferred stock) or (3) to the extent that the Fund is under an obligation (pursuant to a short sale or otherwise) to make related payments with respect to positions in substantially similar or related property. Moreover, the dividends-received deduction may be disallowed or reduced (1) if the corporate shareholder fails to satisfy the foregoing requirements with respect to its Shares of the Fund or (2) by application of the Code.
The tax-exempt portion of dividends paid will be reported to shareholders based upon the ratio of net tax-exempt income to total net investment income earned during the year. The percentage is applied uniformly to all distributions made during the year. Thus, the percentage of income designated as tax-exempt for any particular distribution may be substantially different from the percentage of the Fund’s income that was tax-exempt during the period covered by the distribution. Accordingly, a shareholder who holds Shares for only part of the year may be allocated more or less tax-exempt interest dividends than would be the case if the allocation were based on the ratio of net tax-exempt income to total net investment income actually earned while a shareholder.
26
Generally, distributions that a Fund properly reports as exempt-interest dividends will be excluded from gross income for federal income tax purposes, but may be taxable for federal alternative minimum tax purposes (for individual and shareholders) and for state and local tax purposes. Interest on certain tax-exempt bonds that are “private activity bonds” (as defined in the Code) is treated as a tax preference item for purposes of the alternative minimum tax. Any such interest received by a Fund and distributed to shareholders will be treated as a tax preference item for purposes of any alternative minimum tax liability of shareholders. Additionally, exempt-interest dividends, if any, attributable to interest received on certain private-activity obligations and certain industrial-development bonds will not be tax-exempt to any shareholders who are “substantial users” of the facilities financed by such obligations or bonds or who are “related persons” of such substantial users. A “substantial user” is defined under U.S. Treasury Regulations to include any non-exempt person who regularly uses a part of such facilities in his or her trade or business and (a)(i) whose gross revenues derived with respect to the facilities financed by the issuance of bonds are more than 5% of the total revenues derived by all users of such facilities or (ii) who occupies more than 5% of the usable area of the facility or (b) for whom such facilities or a part thereof were specifically constructed, reconstructed or acquired. A lessee or sublessee of all or any portion of such facilities might also be a substantial user. “Related persons” include certain related natural persons, affiliated corporations, a partnership and its partners, and an S corporation and its shareholders.
Interest on indebtedness, if any, incurred or continued by a shareholder to purchase or carry Shares of a Fund paying exempt-interest dividends is not deductible to the extent it relates to exempt-interest dividends received by the shareholder from that Fund. Under rules used by the IRS to determine when borrowed funds are considered used for the purpose of purchasing or carrying particular assets, the purchase of Shares might be considered to have been made with borrowed funds even though the funds are not directly traceable to the purchase of Shares.
A Fund might acquire rights regarding specified portfolio securities under puts. The policy of each Fund is to limit its acquisition of puts to those under which such Fund will be treated for federal income tax purposes as the owner of the Municipal Securities acquired subject to the put and the interest on the Municipal Securities will be tax-exempt to such Fund. The IRS has issued a published ruling that provides some guidance regarding the tax consequences of the purchase of puts, but there is currently no definitive rule that establishes the tax consequences of many of the types of puts that the Fund is permitted to acquire under the 1940 Act. Therefore, a Fund will only acquire a put after concluding that it will have the tax consequences described above, but the IRS might reach a different conclusion from that of the Fund.
In certain instances, the portion of Social Security or Railroad Retirement benefits that may be subject to federal income taxation might be affected by the amount of tax-exempt interest income, including exempt-interest dividends, received by a shareholder. Shareholders who receive Social Security or Railroad Retirement benefits should consult their tax advisors to determine what effect, if any, an investment in a Fund might have on the federal income taxation of their benefits. The exemption from federal income taxation for exempt-interest dividends does not necessarily result in exemption for such dividends under the income or other tax laws of any state or local authority. You are advised to consult with your tax advisor about state and local tax matters.
Opinions relating to the validity of Municipal Securities and to the exemption of interest thereon from federal income tax are rendered by bond counsel to the respective issuers at the time of issuance. Neither the Fund nor its Adviser will review the proceedings relating to the issuance of Municipal Securities or the basis for such opinions.
Shareholders who sell, exchange or redeem Fund Shares generally will recognize gain or loss in an amount equal to the difference between their adjusted tax bases in the Fund Shares and the amount received. If Fund shareholders hold their Fund Shares as capital assets, the gain or loss arising from (or treated as arising from) any sale, exchange or redemption will be a capital gain or loss. In general, any gain or loss realized upon a taxable disposition of Fund Shares will be treated as long-term capital gain or loss if the Shares have been held for more than 12 months, and as short-term capital gain or loss if the Shares have not been held for more than 12 months. The tax rate generally applicable to net capital gain recognized by individuals and other noncorporate taxpayers is (i) the same as the ordinary income tax rate for short-term capital gain or (ii) 20% for long-term capital gain (including Capital Gain Dividends) in the hands of shareholders who are individuals, with lower rates applicable to shareholders in tax rate brackets lower than the highest rated bracket.
If a shareholder receives an exempt-interest dividend with respect to any Share and such Share is held by the shareholder for six months or less, any loss on the sale or exchange of such Share will be disallowed to the extent of the amount of such exempt-interest dividend, unless the Share was acquired from a Fund which declares exempt-interest dividends on a daily basis in an amount equal to at least 90 percent of its net tax-exempt interest and distributes such dividends on a monthly or more frequent basis. In addition, any loss upon a taxable disposition of Fund Shares held for six months or less will be treated as a long-term capital loss to the extent of any long-term capital gain distributions (including Capital Gain Dividends) received (or deemed received) with respect to those Fund Shares. For purposes of determining whether Fund Shares have been held for six months or less, the holding period is suspended for any periods during which your risk of loss is diminished as a result of holding one or more other positions in substantially similar or related property, or through certain options or short sales.
27
All or a portion of any loss realized on a sale or exchange of Shares will be disallowed to the extent that a shareholder replaces the disposed-of Shares with other Shares of the same Fund within a period of 61 days beginning 30 days before and ending 30 days after the date of disposition, which could, for example, occur as a result of automatic dividend reinvestment. In such an event, a shareholder’s basis in the replacement Shares will be adjusted to reflect the disallowed loss.
REPURCHASE AGREEMENTS AND SECURITIES LENDING
Each Fund’s participation in repurchase agreements and loans of securities may affect the amount, timing, and character of distributions to shareholders. If a Fund participates in a securities lending transaction, to the extent that a Fund makes a distribution of income received by the Fund in lieu of dividends (a “substitute payment”) with respect to securities on loan pursuant to such a securities lending transaction, such income will not constitute qualified dividend income and thus will not be eligible for taxation at the rates applicable to long-term capital gain. Withholding taxes accrued on dividends during the period that any security was not directly held by a Fund will not qualify as a foreign tax paid by the Fund and therefore cannot be passed through to shareholders. As noted above, the Funds do not expect a significant portion of their distributions to be derived from qualified dividend income.
Certain debt securities purchased by the Funds are acquired at a discount and periodic cash interest payments are not made on such securities. Similarly, zero-coupon bonds do not make periodic interest payments. A Fund will be required to include as part of its current income for tax purposes the imputed interest on such obligations even though the Fund has not received any interest payments on such obligations during that period. Because each Fund distributes annually substantially all of its net investment income to its shareholders (including such imputed interest), a Fund may have to sell portfolio securities in order to generate the cash necessary for the required distributions. Such sales might occur at a time when the Adviser would not otherwise have chosen to sell such securities and might result in a taxable gain or loss. Some of the Funds may invest in inflation-linked debt securities. Any increase in the principal amount of an inflation-linked debt security will be original issue discount, which is taxable as ordinary income and is required to be distributed, even though the Fund will not receive the principal, including any increase thereto, until maturity. A Fund investing in such securities may be required to liquidate other investments, including at times when it is not advantageous to do so, in order to satisfy its distribution requirements and eliminate any taxation at the Fund level.
Subject to their investment policies described in the Prospectus and this SAI, some of the Bond and Equity Funds may invest to a significant extent in debt obligations that are in the lowest-rated categories (or are unrated), including debt obligations of issuers that are not currently paying interest or that are in default. Investments in debt obligations that are at risk of being in default (or are presently in default) present special tax issues for a Fund. Tax rules are not entirely clear about issues such as when a Fund may cease to accrue interest, original issue discount or market discount, when and to what extent deductions may be taken for bad debts or worthless securities and how payments received on obligations in default should be allocated between principal and income. These and other related issues will be addressed by each Fund when, and if it invests in such securities, in order to seek to ensure that it distributes sufficient income to preserve its status as a RIC and does not become subject to U.S. federal income taxation or any excise tax.
Special tax considerations apply if a Fund invests in investment companies that are taxable for federal income tax purposes as partnerships. In general, the Fund will not recognize income earned by such an investment company until the close of the investment company’s taxable year. The Fund will, however, recognize such income as it is earned by the investment company for purposes of determining whether it is subject to the 4% excise tax. Therefore, if the Fund and such an investment company have different taxable years, the Fund may be compelled to make distributions in excess of the income recognized from such an investment company in order to avoid the imposition of the 4% excise tax. A Fund’s receipt of a non-liquidating cash distribution from an investment company taxable as a partnership generally will result in recognized gain (but not loss) only to the extent that the amount of the distribution exceeds the Fund’s adjusted basis in shares of such investment company before the distribution. A Fund that receives a liquidating cash distribution from an investment company taxable as a partnership will recognize capital gain or loss to the extent of the difference between the proceeds received by the Fund and the Fund’s adjusted tax basis in shares of such investment company; however, the Fund will recognize ordinary income, rather than capital gain, to the extent that the Fund’s allocable share of “unrealized receivables” (including any accrued but untaxed market discount) exceeds the shareholder’s share of the basis in those unrealized receivables.
28
Some of the Bond and Equity Funds may invest in real estate investment trusts (“REITs”). Investments in REIT equity securities may require a Fund to accrue and distribute income not yet received. In order to generate sufficient cash to make the requisite distributions, the Fund may be required to sell securities in its portfolio (including when it is not advantageous to do so) that it otherwise would have continued to hold. A Fund’s investments in REIT equity securities may at other times result in the Fund’s receipt of cash in excess of the REIT’s earnings; if the Fund distributes such amounts, such distribution could constitute a return of capital to Fund shareholders for federal income tax purposes. Dividends received by a Fund from a REIT generally will not constitute qualified dividend income. “Qualified REIT dividends” (i.e., ordinary REIT dividends other than capital gain dividends and portions of REIT dividends designated as qualified dividend income eligible for capital gain tax rates) are eligible for a 20% deduction by non-corporate taxpayers. This deduction, if allowed in full, equates to a maximum effective tax rate of 29.6% (37% top rate applied to income after 20% deduction). Distributions by a Fund to its shareholders that are attributable to qualified REIT dividends received by the Fund and which the Fund properly reports as “section 199A dividends,” are treated as “qualified REIT dividends” in the hands of non-corporate shareholders. A section 199A dividend is treated as a qualified REIT dividend only if the shareholder receiving such dividend holds the dividend-paying RIC shares for at least 46 days of the 91-day period beginning 45 days before the shares become ex-dividend, and is not under an obligation to make related payments with respect to a position in substantially similar or related property. A Fund is permitted to report such part of its dividends as section 199A dividends as are eligible, but is not required to do so.
Some of the REITs in which some of the Funds may invest are permitted to hold residual interests in real estate mortgage investment conduits (“REMICs”). Under Treasury Regulations that have not yet been issued, but may apply with retroactive effect, a portion of a Fund’s income from a REIT that is attributable to the REIT’s residual interest in a REMIC (referred to in the Code as an “excess inclusion”) will be subject to federal income taxation in all events.
These regulations are also expected to provide that excess inclusion income of a RIC, such as each of the Funds, will be allocated to shareholders of the RIC in proportion to the dividends received by such shareholders, with the same consequences as if the shareholders held the related REMIC residual interest directly.
In general, excess inclusion income allocated to shareholders cannot be offset by net operating losses (subject to a limited exception for certain thrift institutions). Any investment in residual interests of a CMO that has elected to be treated as a REMIC can create complex tax problems, especially if the Fund has state or local governments or other tax-exempt organizations as shareholders.
Under current law, the Fund serves to block unrelated business taxable income (“UBTI”) from being realized by its tax-exempt shareholders. Notwithstanding the foregoing, a tax-exempt shareholder will recognize UBTI by virtue of its investment in the Fund if shares in the Fund constitute debt-financed property in the hands of the tax-exempt shareholder within the meaning of Code Section 514(b). Furthermore, a tax-exempt shareholder may recognize UBTI if the Fund recognizes “excess inclusion income” derived from direct or indirect investments in REMIC residual interests or taxable mortgage pools if the amount of such income recognized by the Fund exceeds the Fund’s investment company taxable income (after taking into account deductions for dividends paid by the Fund).
A charitable remainder trust (“CRT”), as defined in section 664 of the Code, that realizes UBTI for a taxable year must pay an excise tax annually of an amount equal to such UBTI. Under IRS guidance, a CRT will not recognize UBTI solely as a result of investing in a Fund that recognizes “excess inclusion income.” Rather, if at any time during any taxable year a CRT (or one of certain other tax-exempt shareholders, such as the United States, a state or political subdivision, or an agency or instrumentality thereof, and certain energy cooperatives) is a record holder of a share in a Fund that recognizes “excess inclusion income,” then the Fund will be subject to a tax on that portion of its “excess inclusion income” for the taxable year that is allocable to such shareholders at the highest federal corporate income tax rate. To the extent permitted under the 1940 Act, each Fund may elect to specially allocate any such tax to the applicable CRT, or other shareholder, and thus reduce such shareholder’s distributions for the year by the amount of the tax that relates to such shareholder’s interest in the Fund. The Funds have not yet determined whether such an election will be made. CRTs are urged to consult their tax advisors concerning the consequences of investing in each Fund.
29
If a Fund invests in shares of other mutual funds, ETFs or other companies that are taxable as RICs (collectively, “underlying funds”), its distributable income and gains will normally consist, in part, of distributions from the underlying funds and gains and losses on the disposition of shares of the underlying funds. To the extent that an underlying fund realizes net losses on its investments for a given taxable year, the Fund will not be able to recognize its share of those losses (so as to offset distributions of net income or capital gains from other underlying funds) until it disposes of shares of the underlying fund. Moreover, even when the Fund does make such a disposition, a portion of its loss may be recognized as a long-term capital loss, which will not be treated as favorably for federal income tax purposes as a short-term capital loss or an ordinary deduction. In particular, the Fund will not be able to offset any capital losses from its dispositions of underlying fund shares against its ordinary income (including distributions of any net short-term capital gain realized by an underlying fund). In addition, in certain circumstances, the “wash sales” rule under section 1091 of the Code might apply to a Fund’s sale of underlying fund shares that have generated losses. A wash sale occurs if shares of an underlying fund are sold by the Fund at a loss and the Fund acquires additional shares of that same underlying fund 30 days before or after the date of the sale. The wash-sales rule could defer losses in the Fund’s hands on sales of underlying fund shares (to the extent such sales are wash sales) for extended (and, in certain cases, potentially indefinite) periods of time.
As a result of the foregoing rules, and certain other special rules, the amounts of net investment income and net capital gain that each Fund will be required to distribute to shareholders may be greater than such amounts would have been had the Fund directly invested in the securities held by the underlying funds, rather than investing in shares of the underlying funds. For similar reasons, the character of distributions from the Fund (e.g., long-term capital gain, exempt interest, eligibility for dividends-received deduction, etc.) will not necessarily be the same as it would have been had the Fund invested directly in the securities held by the underlying funds.
A Fund’s transactions, if any, in options, futures contracts, foreign-currency-denominated securities, and certain other investment and hedging activities, will be subject to special tax rules (including “mark-to-market,” “straddle,” “wash sale,” “constructive sale” and “short sale” rules), the effect of which may be to accelerate income to the Fund, defer losses to the Fund, cause adjustments in the holding periods of the Fund’s assets, and otherwise affect the character of the Fund’s income. These rules could therefore affect the amount, timing, and character of distributions to shareholders and cause differences between a Fund’s book income and its taxable income.
Each Fund is required for federal income tax purposes to mark to market and recognize as income for each taxable year its net unrealized gains and losses on certain futures and options contracts as of the end of the year as well as those actually realized during the year. Gain or loss from futures and options contracts on broad-based indexes required to be marked to market will be 60% long-term and 40% short-term capital gain or loss. Application of this rule may alter the timing and character of distributions to shareholders. A Fund may be required to defer the recognition of losses on futures contracts, options contracts and swaps to the extent of any unrecognized gains on offsetting positions held by the Fund. These provisions may also require a Fund to mark-to-market certain types of positions in its portfolio (i.e., treat them as if they were closed out), which may cause the Fund to recognize income without receiving cash with which to make distributions in amounts necessary to satisfy the distribution requirement and for avoiding the excise tax discussed above. Accordingly, to avoid certain income and excise taxes, a Fund may be required to liquidate its investments at a time when the investment adviser might not otherwise have chosen to do so.
Offsetting positions held by a Fund involving certain derivative instruments, such as options, forwards, and futures, as well as its long and short positions in portfolio securities, may be considered to constitute “straddles” for federal income tax purposes. In general, straddles are subject to certain rules that may affect the amount, character and timing of a Fund’s gains and losses with respect to the straddle positions by requiring, among other things, that: (1) any loss realized on disposition of one position of a straddle may not be recognized to the extent that the Fund has unrealized gains with respect to the other positions in straddle; (2) the Fund’s holding period in straddle positions be suspended while the straddle exists (possibly resulting in a gain being treated as short-term rather than long-term capital gain); (3) the losses recognized with respect to certain straddle positions that are part of a mixed straddle and are non-section 1256 contracts be treated as 60% long-term and 40% short-term capital loss; (4) losses recognized with respect to certain straddle positions that would otherwise constitute short-term capital losses be treated as long-term capital losses; and (5) the deduction of interest and carrying charges attributable to certain straddle positions may be deferred. Various elections are available to a Fund, which may mitigate the effects of the straddle rules, particularly with respect to mixed straddles.
30
In general, the straddle rules described above do not apply to any straddles held by a Fund if all of the offsetting positions consist of contracts governed by section 1256 of the Code. The straddle rules described above also do not apply if all the offsetting positions making up a straddle consist of one or more “qualified covered call options” and the stock to be purchased under the options and the straddle is not part of a larger straddle. A qualified covered call option is generally any option granted by a Fund to purchase stock it holds (or stock it acquires in connection with granting the option) if, among other things, (1) the option is traded on a national securities exchange that is registered with the SEC or other market the IRS determined has rules adequate to carry out the purposes of the applicable Code provision, (2) the option is granted more than 30 days before it expires, (3) the option is not a “deep-in-the-money option,” (4) such option is not granted by an options dealer in connection with his activity of dealing in options, and (5) gain or loss with respect to the option is not ordinary income or loss. In addition, the straddle rules could cause distributions from a Fund that would otherwise constitute “qualified dividend income” or qualify for the dividends-received deduction to fail to satisfy the applicable holding period requirements.
To the extent a Fund writes options that are not subject to the rules of section 1256 of the Code, the amount of the premium received by the Fund for writing such options is likely to be entirely short-term capital gain to the Fund. In addition, if such an option is closed by the Fund, any gain or loss realized by the Fund as a result of closing the transaction will also generally be short-term capital gain or loss. If such an option is exercised any gain or loss realized by the Fund upon the sale of the underlying security pursuant to such exercise will generally be short-term or long-term capital gain or loss to the Fund depending on the Fund’s holding period for the underlying security.
If a Fund enters into a “constructive sale” of any appreciated financial position in its portfolio, such Fund will be treated as if it had sold and immediately repurchased the property and must recognize gain (but not loss) with respect to that position. A constructive sale of an appreciated financial position occurs when a Fund enters into certain offsetting transactions with respect to the same or substantially identical property, including, but not limited to: (i) a short sale; (ii) an offsetting notional principal contract; (iii) a futures or forward contract; or (iv) other transactions identified in future Treasury Regulations. The character of the gain from constructive sales will depend upon a Fund’s holding period in the appreciated financial position. Losses realized from a sale of a position that was previously the subject of a constructive sale will be recognized when the position is subsequently disposed of. The character of such losses will depend upon a Fund’s holding period in the position beginning with the date the constructive sale was deemed to have occurred and the application of various loss deferral provisions in the Code. Constructive sale treatment does not apply to certain closed transactions, including if such a transaction is closed on or before the 30th day after the close of a Fund’s taxable year and such Fund holds the appreciated financial position unhedged throughout the 60-day period beginning with the day such transaction was closed.
A Fund’s investment in a master limited partnership (“MLP”) may qualify as an investment in a (1) QPTP, (2) a “regular” partnership, (3) a “passive foreign investment company” (a “PFIC”, as defined below), or (4) a corporation for U.S. federal income tax purposes. The treatment of particular MLPs for U.S. federal income tax purposes will affect the extent to which a Fund can invest in MLPs. Some amounts received by each Fund with respect to its investments in MLPs will likely be treated as a return of capital because of accelerated deductions available with respect to the activities of such MLPs. On the disposition of an investment in such an MLP, a Fund will likely realize taxable income in excess of economic gain with respect to that asset (or if the Fund does not dispose of the MLP, the Fund will likely realize taxable income in excess of cash flow with respect to the MLP in a later period), and the Fund must take such income into account in determining whether the Fund has satisfied its distribution requirements. A Fund may have to borrow or liquidate securities to satisfy its distribution requirements and to meet its redemption requests, even though investment considerations might otherwise make it undesirable for the Fund to sell securities or borrow money at such time. “Qualified publicly traded partnership income” within the meaning of Section 199A(e)(5) of the Code is eligible for a 20% deduction by non-corporate taxpayers. Qualified publicly traded partnership income is generally income of a “publicly traded partnership” that is not treated as a corporation for U.S. federal income tax purposes that is effectively connected with such entity’s trade or business, but does not include certain investment income. A “publicly traded partnership” for purposes of this deduction is not necessarily the same as a QPTP (as described above in the section entitled “Qualification as a Regulated Investment Company”). This deduction, if allowed in full, equates to a maximum effective tax rate of 29.6% (37% top rate applied to income after 20% deduction). A RIC, such as the Funds, is not permitted to pass the special character of this income through to its shareholders. Currently, direct investors in entities that generate “qualified publicly traded partnership income” will enjoy the lower rate, but investors in RICs that invest in such entities will not. It is uncertain whether future technical corrections or administrative guidance will address this issue to enable the Funds to pass through the special character of “qualified publicly traded partnership income” to their shareholders.
31
FOREIGN INVESTMENT, FOREIGN CURRENCY-DENOMINATED SECURITIES AND RELATED HEDGING TRANSACTIONS
If a Fund invests in foreign securities, dividends and interest received by the Fund, if any, might be subject to income, withholding or other taxes imposed by foreign countries and U.S. possessions that would reduce the yield on the Fund’s securities. Tax conventions between certain countries and the U.S. may reduce or eliminate these taxes. Foreign countries generally do not impose taxes on capital gains with respect to investments by foreign investors. Shareholders generally will not be entitled to claim a credit or deduction with respect to such foreign taxes imposed on the Fund. If, however, at the end of a Fund’s taxable year more than 50% of the value of its total assets represents securities of foreign corporations, the Fund will be eligible to make an election permitted by the Code to treat any foreign taxes paid by it on securities it has held for at least the minimum period specified in the Code as having been paid directly by the Fund’s shareholders in connection with the Fund’s dividends received by them. In such a case, shareholders generally will be required to include in U.S. taxable income their pro rata share of such taxes.
A shareholder’s ability to claim a foreign tax credit or deduction in respect of foreign taxes paid by a Fund may be subject to certain limitations imposed by the Code, as a result of which a shareholder may not get a full credit or deduction for the amount of such taxes. In particular, shareholders who hold Fund Shares (without protection from risk of loss) on the ex-dividend date and for at least 15 other days during the 30-day period surrounding the ex-dividend date may be entitled to claim a foreign tax credit for their share of these taxes. Shareholders who do not itemize deductions on their federal income tax returns may claim a credit (but no deduction) for such foreign taxes.
Foreign tax credits, if any, received by a Fund as a result of an investment in another RIC (including an ETF which is taxable as a RIC) will not be passed through to you unless the Fund qualifies as a “qualified fund-of-funds” under the Code. If a Fund is a “qualified fund-of-funds” it will be eligible to file an election with the IRS that will enable the Fund to pass along these foreign tax credits to its shareholders. A Fund will be treated as a “qualified fund-of-funds” under the Code if at least 50% of the value of the Fund’s total assets (at the close of each quarter of the Fund’s taxable year) is represented by interests in other RICs.
A Fund’s transactions in foreign currencies, foreign currency-denominated debt securities and certain foreign currency options, futures contracts and forward contracts (and similar instruments) may give rise to ordinary income or loss to the extent such income or loss results from fluctuations in the value of the foreign currency concerned.
A Fund’s investment in a PFIC is subject to special federal income tax rules. A PFIC is generally any foreign corporation if (i) 75% or more of the foreign corporation’s gross income for a taxable year is passive income, or (ii) 50% or more of the average percentage of the foreign corporation’s total assets (generally by value, but by adjusted tax basis in certain cases) produce or are held for the production of passive income. Generally, passive income for this purpose means dividends, interest (including income equivalent to interest), royalties, rents, annuities, the excess of gain over loss from certain property transactions and commodities transactions, and foreign currency gain. Passive income for this purpose does not include rents and royalties received by a foreign corporation from an active business and certain income received from related persons. Dividends paid by PFICs will not be eligible to be treated as “qualified dividend income.”
Investment by a Fund in PFICs could subject the Fund to a U.S. federal income tax or other charges on distributions received from such a company or on the proceeds from the sale of its investment in such a company, which tax cannot be eliminated by making distributions to Fund shareholders; however, this tax can be avoided by making an election to mark such investments to market annually or to treat the passive foreign investment company as a “qualified electing fund.” If a Fund is in a position to treat a PFIC as a “qualified electing fund” (“QEF”), the Fund will be required to include in its income annually its share of the company’s income and net capital gain, regardless of whether it receives any distributions from the company. Alternately, a Fund may make an election to mark the gains (and to a limited extent losses) in such holdings “to the market” as though it had sold and repurchased its holdings in those PFICs on the last day of the Fund’s taxable year. Such gain and loss is treated as ordinary income and loss. The QEF and mark-to-market elections may have the effect of accelerating the recognition of income without the receipt of cash and increasing the amount required to be distributed by the Fund to avoid taxation. Making either of these elections, therefore, may require the Fund to liquidate other investments, including at times when it is not advantageous to do so, to meet its distribution requirement, which also may accelerate the recognition of gain and affect the Fund’s total return. A Fund that invests in PFICs by virtue of the Fund’s investments, if any, in other investment companies that qualify as “U.S. Persons” within the meaning of the Code may not make such elections; rather, the underlying investment companies directly investing in the PFICs would decide whether to make such elections. Amounts included in income each year by a Fund arising from a QEF election will be “qualifying income” under the annual 90% gross income test described in (a) above in the section titled “Qualification as a Regulated Investment Company” even if not distributed to the Fund, if the Fund derives such income from its business of investing in stock, securities or currencies.
32
A Fund generally is required to back-up withhold and remit to the U.S. Treasury a percentage of the taxable dividends and other distributions paid to, and proceeds of Share sales, exchanges or redemptions made by, any individual shareholder who fails to properly furnish the Fund with a correct taxpayer identification number, who has under-reported dividend or interest income, or who fails to certify to the Fund that he or she is not a United States person and is not subject to back-up withholding. The back-up withholding tax rate is 24%. Back-up withholding is not an additional tax. Any amounts withheld may be credited against the shareholder’s U.S. federal income tax liability, provided the appropriate information is furnished to the IRS. In order for a foreign investor to qualify for an exemption from back-up withholding, the foreign investor must comply with special certification and filing requirements. Foreign investors in the Funds should consult their tax advisors in this regard.
TAX SHELTER REPORTING REGULATIONS
Under Treasury Regulations, if a shareholder realizes a loss on disposition of the Fund’s Shares of $2 million or more for an individual shareholder or $10 million or more for a corporate shareholder, the shareholder must file with the IRS a disclosure statement on Form 8886. Direct shareholders of portfolio securities are in many cases excepted from this reporting requirement, but under current guidance, shareholders of a RIC are not excepted. Future guidance may extend the current exception from this reporting requirement to shareholders of most or all regulated investment companies. The fact that a loss is reportable under these regulations does not affect the legal determination of whether the taxpayer’s treatment of the loss is proper. Shareholders should consult their tax advisers to determine the applicability of these regulations in light of their individual circumstances.
SHARES PURCHASED THROUGH TAX-QUALIFIED PLANS
Special tax rules apply to investments made through defined contribution plans and other tax-qualified plans. Shareholders should consult their tax adviser to determine the suitability of Shares of a Fund as an investment through such plans and the precise effect of an investment on their particular tax situation.
The foregoing is only a summary of some of the important federal tax considerations generally affecting purchasers of Shares of each Fund. This summary is based on tax laws and regulations which are in effect on January 1, 2025; such laws and regulations may be changed by legislative, judicial or administrative action, and such changes may have a retroactive effect.
No attempt is made to present a detailed explanation of the federal income tax treatment of each Fund or its shareholders, and this discussion is not intended as a substitute for careful tax planning. Accordingly, potential purchasers of Shares of a Fund are urged to consult their tax advisors with specific reference to their own tax situations, including the potential application of foreign, federal, state and local taxes.
Securities for which market quotations are readily available will be valued on the basis of quotations provided by dealers in such securities or furnished through an independent pricing service approved by the Board of Trustees. The following is an overview of how securities will be valued in the Funds:
| • | Domestic Equity Securities. Domestic equity securities are valued at the closing price on the exchange or system where the security is principally traded (including the NASDAQ official Closing Price for securities traded on NASDAQ). If there have been no sales for that day on any exchange or market, the security is valued at the latest available bid price on the exchange or system where the security is principally traded. |
33
| • | Foreign Equity Securities. Foreign equity securities will be priced at the closing price reported on the foreign exchange on which they are principally traded. If there have been no sales for that day, a security will be valued at the latest available bid price on the exchange where the security is principally traded. Prices of foreign securities denominated in foreign currency shall be converted into U.S. dollar equivalents using the daily rate of exchange. |
| • | Domestic and Foreign Fixed Income Securities. Fixed income securities will be valued using Board approved policies and procedures, including the use of pricing services. Short term fixed income securities (maturing in less than sixty-one days) of sufficient credit quality are valued at market value. Prices of foreign securities denominated in foreign currency shall be converted into U.S. dollar equivalents using the daily rate of exchange. Special valuation procedures (see below) apply with respect to “odd-lot” securities. |
| • | Mutual Funds. Open ended mutual fund investments will be valued at the most recently calculated NAV. Closed end mutual funds are valued at their market values based upon the latest available sale price. |
| • | Options on Securities, Indices and Futures Contracts. Options on securities, indices and futures contracts purchased by the Fund generally are valued at their last sale price prior to the time as of which the Fund determines its NAV or, if there was no sale on that day, at the last bid quote. |
| • | Repurchase Agreements. Repurchase agreements will be valued at original cost. |
Other securities and assets for which market quotations are not readily available will be valued at fair value using methods determined in good faith by the Fund’s Pricing Committee under the general supervision of the Board of Trustees and may include yield equivalents or a price produced through use of a pricing matrix provided by a national pricing service approved by the Board of Trustees.
Notwithstanding the above, securities transferred in transactions subject to Rule 17a-7 under the 1940 Act shall be priced on the day transferred pursuant to Rule 17a-7 and any currently effective procedures adopted by the Board of Trustees under that Rule.
Odd Lot Securities. The following methodology will be used for fixed income positions which, due to their small size, may receive prices by automated pricing services which reflect a large block trade and not what actually could be obtained for the small bond position:
| • | For each position at or below $25,000 par value, Citi Fund Services will compare the actual purchase price of that position with the next day’s price received from the pricing service. |
| • | Positions for which the next day’s price is 2% or greater than the purchase price (a “next day price jump”) will be subject to the application of an ongoing discount equal to that next day price jump. |
| • | Within 10 business days of each fiscal quarter end, broker quotes will be ascertained for each position currently subject to the above described pricing methodology. |
| • | The broker quotes will be used to calculate a revised discount which will then be applied to each position from that point forward. If by virtue of a broker quote, a position’s discount is revised below 2% then that position will no longer be subject to discount and will be valued in the same manner as other fixed income securities. |
The Pricing Committee conducts its pricing activities in the manner established by the Security Valuation Procedures. The Security Valuation Procedures are reviewed and approved by the Trust’s Board of Trustees at least annually.
The Money Market Funds have elected to use the amortized cost method of valuation pursuant to Rule 2a-7 under the 1940 Act. This involves valuing an instrument at its cost initially and thereafter assuming a constant amortization to maturity of any discounts or premium, regardless of the impact of fluctuating interest rates on the market value of the instrument. This method may result in periods during which value, as determined by amortized cost, is higher or lower than the price each Money Market Fund would receive if it sold the instrument. The value of securities in the Money Market Funds can be expected to vary inversely with changes in prevailing interest rates.
34
Pursuant to Rule 2a-7, the Money Market Funds will maintain a dollar-weighted average portfolio maturity appropriate to their objective of maintaining a stable net asset value per Share, provided that no Fund will purchase any security with a remaining maturity of more than 397 days (securities subject to maturity dates) nor maintain a dollar-weighted, average portfolio maturity which exceeds 60 days. The Board of Trustees has also undertaken to establish procedures reasonably designed, taking into account current market conditions and a Fund’s investment objective, to stabilize the net asset value per share of the Money Market Funds for purposes of sales and redemptions at $1.00. These procedures include review by the Board of Trustees, at such intervals as they deem appropriate, to determine the extent, if any, to which the net asset value per Share of each Fund calculated by using available market quotations deviates from $1.00 per Share (the “Mark to Market”). In performing the Mark to Market, securities for which market quotations are not readily available and other assets will be valued at fair value and may include yield equivalents or a price produced through use of a pricing matrix provided by a national pricing service approved by the Board of Trustees.
In the event such deviations exceed one half of one percent, Rule 2a-7 requires that the Board of Trustees promptly consider what action, if any, should be initiated. If the Board of Trustees believes that the extent of any deviation from a Money Market Fund’s $1.00 amortized cost price per Share may result in material dilution or other unfair results to new or existing investors, they will take such steps as they consider appropriate to eliminate or reduce to the extent reasonably practicable any such dilution or unfair results. These steps may include selling portfolio instruments prior to maturity, shortening the average portfolio maturity, withholding or reducing dividends, reducing the number of a Money Market Fund’s outstanding shares without monetary consideration, or utilizing a net asset value per share determined by using available market quotations.
The Pricing Committee conducts its pricing activities in the manner established by the Security Valuation Procedures. The Security Valuation Procedures are reviewed and approved by the Trust’s Board of Trustees at least annually.
ADDITIONAL PURCHASE AND REDEMPTION INFORMATION
Shares in each Fund are sold on a continuous basis by Cavanal Hill Distributors, Inc. (“CHD” or the “Distributor”), and the Distributor has agreed to use appropriate efforts to solicit all purchase orders. In addition to purchasing Shares directly from the Distributor, shares may be purchased through financial institutions and intermediaries, broker-dealers, or similar entities, including affiliates or subsidiaries of the Distributor (“Participating Organizations”) pursuant to contractual arrangements with the Distributor under the Funds’ Amended and Restated Distribution and Shareholder Services Plan (the “Distribution Plan”). Customers purchasing Shares of the Funds may include officers, directors, or employees of the Adviser and its affiliates.
The Funds may suspend the right of redemption or postpone the date of payment for Shares during any period when (a) trading on the NYSE is restricted by applicable rules and regulations of the SEC or of the NYSE, (b) the NYSE is closed for other than customary weekend and holiday closings, (c) the SEC has by order permitted such suspension, or (d) an emergency exists as determined by the SEC.
Regarding Shares purchased through a Participating Organization, the entity through which you are purchasing, selling or exchanging your Shares is responsible for transmitting orders to the Funds, and it may have an earlier cutoff time and different trading and exchanging policies. Consult that entity for specific information. Some policy differences may include minimum investment requirements, exchange policies, cutoff time for investments, and redemption fees.
The Funds may redeem shares involuntarily if redemption appears appropriate in light of the Funds’ responsibilities under the 1940 Act. (See “Your Account” — Involuntary Sale of Your Shares” in the Funds’ prospectus for further information.)
Each Fund will only accept new account applications and additional purchases of Fund shares from an established shareholder account that
| (1) | reflects a residential address for an individual (or the principal place of business for an entity) located within the U.S. or its territories; or |
| (2) | reflects a U.S. military address; and (3) in every case, is associated with a valid U.S. taxpayer identification number. |
IMPORTANT NOTICE REGARDING DELIVERY OF SHAREHOLDER DOCUMENTS
To reduce expenses, we may only mail one copy of each of the Fund’s prospectus, annual report or semi-annual report to those addresses shared by two or more accounts, unless we receive contrary instruction from you. If you are a direct shareholder and wish to receive individual copies of these documents, please call us at 1-800-762-7085. If you are not a direct shareholder, please contact your financial institution to opt out of householding. We will begin sending you individual copies thirty days after receiving your request.
35
INITIAL SALES CHARGE
The Class A Shares of the Bond and Equity Funds are subject to an initial sales charge. The sales charge is used to compensate participating dealers for their expenses incurred in connection with the distribution of the Class A Shares. The amount of the initial sales charge is based upon the amount purchased:
Shareholder Fees
For Bond and Equity Funds
(fees paid directly from your investment)
| Purchase Amount | Sales Charge (Load) imposed on Purchases (as a percentage of offering price) | Sales Charge (Load) imposed on Purchases (as a percentage of net amount invested) | Reallowance | Maximum Contingent Deferred Sales Charge (Load) (as a percentage of the lesser of the amount redeemed or the total original cost, for shares held less than 12 months) | ||||||||||||
| Less than $200,000 | 2.00 | % | 2.04 | % | 2.00 | % | None | |||||||||
| Over $200,000 | None | 0.00 | % | — | 1.00 | % | ||||||||||
You may qualify for reduced sales charges or sales charge exceptions. To qualify for these reductions or exceptions, you or your financial adviser must notify the transfer agent, FIS Investor Services, LLC (“FIS”), and provide the necessary documentation at the time of purchase that your purchase qualifies for such treatment.
No person or entity may distribute shares of the Funds without payment of the applicable sales charge other than to purchasers that qualify for the reductions or exceptions described below.
Purchases of the Money Market Funds will not be taken into account in determining whether a purchase qualifies for a reduction in initial sales charge.
| • | Rights of Accumulation. |
| • | You may combine your new purchases of Class A Shares of a Fund with other Bond or Equity Fund shares currently owned for the purpose of qualifying for the lower initial sales charge rates that apply to purchasers of more than $200,000. The applicable initial sales charge for the new purchase is based on the total of your current purchase and the value of other Bond or Equity Fund shares owned based on their current public offering price. |
| • | If a purchaser qualifies for a reduced sales charge, the reduced sales charge applies to the total amount of money being invested, even if only a portion of that amount exceeds the breakpoint for the reduced sales charge. |
36
| • | No credit is available for prior investments made at a lower breakpoint subject to a higher fee. |
| • | Accumulated purchases of $200,000 or more are subject to the CDSC described below. |
| • | Letters of Intent. |
| • | Under a Letter of Intent (LOI), you commit to purchase a specified dollar amount of Class A Shares of one or more Bond or Equity Funds during a 13-month period. If you agree to purchase over $200,000, you will not pay an initial sales charge. All subsequent purchases during the 13-month period count toward the completion of the LOI. |
| • | By signing an LOI, a purchaser is not making a binding commitment to purchase additional shares. However, if the full amount committed to in the LOI is not invested by the end of the 13-month period, your account will be assessed the higher initial sales charge that would normally be applicable to the amount actually invested. |
| • | To assure compliance with the provisions of the 1940 Act, FIS will reserve, in escrow or similar arrangement, in the form of shares, an appropriate dollar amount to pay the sales charge that would normally be applicable to the amount actually invested. If the total investment is completed within the 13-month period, the reserve will be promptly released. |
| • | If at any time before completing the LOI the purchaser requests that the Transfer Agent liquidate or transfer his shares, the LOI will be automatically cancelled and the Transfer Agent will redeem an appropriate number of reserved shares equal to the difference between the sales charge actually paid and the sales charge that would have been paid if the total purchases would have been made on a single occasion. |
| • | LOIs to purchase $200,000 or more of Class A Shares are subject to the CDSC described below. |
| • | Persons and Entities |
| • | Class A Series of the Funds may be purchased without an initial sales charge by the following persons (and their spouses and children under 21 years of age): (i) registered representatives and other employees of intermediaries that have selling agreements with the Distributor to sell Class A Shares; (ii) directors, officers, and employees of the Adviser and its affiliates; |
(iii) Trustees and officers of the Trust and (iv) investors that purchase directly from the Fund. In addition, the initial sales charge may be waived on purchases of Class A Shares through financial intermediaries that have entered into an agreement with the Distributor that allows the waiver of the sales charge. The Funds do not currently have any such sales waiver agreements in place with financial intermediaries.
| • | Purchases of $200,000 or more by the persons or entities identified are subject to the CDSC described below. |
| • | Shareholders purchasing Fund shares through a Morgan Stanley Wealth Management brokerage account will be eligible only for the following front-end sales charge exceptions and the initial sales charge exceptions available to other investors listed immediately above are not available to investors investing through a Morgan Stanley Wealth Management brokerage account. |
| • | Employer-sponsored retirement plans (e.g., 401(k) plans, 457 plans, employer-sponsored 403(b) plans, profit sharing and money purchase pension plans and defined benefit plans). For purposes of this provision, employer-sponsored retirement plans do not include SEP IRAs, Simple IRAs, SAR-SEPs or Keogh plans |
| • | Morgan Stanley employee and employee-related accounts according to MSSB’s account linking rules |
| • | Shares purchased through reinvestment of dividends and capital gains distributions when purchasing shares of the same fund |
| • | Shares purchased through a Morgan Stanley self-directed brokerage account |
37
| • | Class C (i.e., level-load) shares that are no longer subject to a contingent deferred sales charge and are converted to Class A shares of the same fund pursuant to Morgan Stanley Wealth Management’s share class conversion program |
| • | Shares purchased from the proceeds of redemptions within the same fund family, provided (i) the repurchase occurs within 90 days’ following the redemption, (ii) the redemption and purchase occur in the same account, and (iii) redeemed shares were subject to a front-end or deferred sales charge. |
| • | Contingent Deferred Sales Charges (CDSC — Class A and C only). |
| • | Class A Shares. |
Investors who purchase or own $200,000 or more of Bond or Equity Fund Class A Shares do not pay an initial sales charge. If, however, you redeem Class A Shares purchased without paying sales charge prior to 12 months after the date of purchase, the redemption will be subject to a CDSC of 1%. The CDSC on redemptions of shares is computed based on the lower of their original purchase price or current net asset value, net of reinvested dividends and capital gains distributions. In determining whether to charge a CDSC, shares are accounted for on a first-in, first-out basis, which means that you will redeem shares on which there is no CDSC first and, then, shares in the order of their purchase.
The Distributor will pay dealer commissions on Class A Share trades of $200,000 or more, up to a maximum amount of $100,000. The amount available for such payments is:
Up to 1% of the first $4 million;
plus 0.50% on the next $6 million
plus 0.25% on purchases more than $10 million
By way of illustration, the Distributor would pay up to the following on purchases of $20 million:
| • | 1% of the first $4 million = $40,000; plus |
| • | 0.5% on the next $6 million = $30,000; plus |
| • | 0.25% on the next $10 million = $25,000 |
For a total payment of up to $95,000 ($40,000 + $30,000 + $25,000)
| • | Class C Shares. |
Class C Shares are not subject to an initial sales charge so you will invest the full amount of your purchase price. However, Class C Shares pay an annual 12b-1 Distribution/Service Fee of 1.00% (0.75% in asset-based sales charge and 0.25% in 12b-1 service fee) and a Shareholder Servicing Fee of 0.25% of average net assets. Because these fees are paid out of the Fund’s assets over time, they will increase the cost of your investment and may cost you more than if you had purchased Class A Shares. Class C Shares of each Fund will automatically convert into Class A Shares of the same Fund after they have been held for ten years. This automatic conversion will be executed without any sales charge, fee or other charge. The IRS currently takes the position that such automatic conversions are not taxable. Should its position change, the automatic conversion feature may be replaced with a conversion option. If you sell your Class C Shares within 12 months after purchase, you may pay a 1.00% CDSC, which will be applied to the lesser of amount invested or redemption value of the shares redeemed.
Shareholders who are investing $200,000 or more through a sales charge reduction feature, including a shareholder eligible to purchase Class A Shares at no sales charge on a purchase of $200,000 or more of Class A Shares, or through Rights of Accumulation, a LOI or grouping purchases by certain related persons may not purchase Class C Shares. In such case, requests to purchase Class C Shares will automatically be treated as a request to purchase Class A Shares. The Fund will not apply the limitation to Class C Share purchases made by shareholders whose Shares are held in an omnibus account on any of the Funds’ records, and it will be the selling broker-dealer’s responsibility to apply the limitation for such purchases.
38
MANAGEMENT AND SERVICE PROVIDERS OF THE FUNDS
Board Leadership Structure
The Funds are managed under the direction of the Board of Trustees (the “Board”). The Board consists of three Trustees who supervise the business affairs of the Trust. The Board is responsible for the general oversight of the Funds’ business and for assuring that the Funds are managed in the best interest of the Fund’s shareholders. The Board periodically reviews the Funds’ investment performance as well as the quality of other services provided to the Funds by each of the Funds’ service providers. Subject to the provisions of the Funds’ Declaration of Trust and By-laws, and applicable provisions of Massachusetts law, the Trustees have all powers necessary and convenient to carry out this responsibility, including the election and removal of the Funds’ officers.
The Board is comprised of two-thirds of Trustees who are not “interested persons” (as defined under the 1940 Act) of the Funds (the “Independent Trustees”). In addition, the Chairman of the Board is an Independent Trustee. The Board holds regular quarterly meetings. The Chairman presides at meetings of the Trustees, and may call special meetings of the Board and any Board committee whenever he deems it necessary. The Board is involved in identifying information to be presented to the Board and matters to be acted upon by the Board. The Board engages in communication with each other, the Funds’ management, and service providers, as necessary, between meetings. The Board has designated a number of standing committees as further described below, each of which has a Chairman. The designation of a Trustee as Chairman does not generally impose on that Trustee any obligations or liability that is greater than any other Trustee.
The Board believes that the current Fund leadership structure is appropriate because it allows the Board to exercise informed and independent judgment over matters under its purview, and it allocates areas of responsibility among committees with the effect of enhancing Fund oversight. The Board considers the facts that a majority of its members, and its Chairman, are Independent Trustees to be integral to promoting effective and independent oversight of the Funds’ operations, as well as meaningful representation of the shareholders’ interests. The Board also believes that having an interested person serve on the Board brings corporate and financial viewpoints that are important elements in its decision-making process. The Board size and leadership structure may be changed at any time at the discretion of the Board.
Risk Oversight
The Trustees play an active role, as a full Board and at the committee level, in overseeing risk management for the Funds. The Trustees delegate the day-to-day risk management of the Funds to various groups, including but not limited to, portfolio management, compliance, legal and fund accounting. These groups provide the Trustees with regular reports regarding investment, valuation, liquidity, and compliance, as well as the risks associated with each. The Trustees also oversee risk management for the Funds through interactions with the Funds’ external auditors. The Board recognizes that it is not possible to identify all of the risks that may affect the Funds or to develop processes and controls to eliminate or mitigate their occurrence or effects.
The Funds’ compliance program covers the following broad areas of compliance: portfolio management, trading practices, code of ethics and protection of non-public information, accuracy of disclosures, safeguarding of fund assets, recordkeeping, marketing, selection and retention of service providers, fees, privacy, anti-money laundering, business continuity, valuation and pricing of funds shares, processing of fund shares, affiliated transactions, fund governance and market timing. The program seeks to identify and assess risk through various methods, including through regular interdisciplinary communications between compliance professionals, operational risk management and business personnel who participate on a daily basis in risk management on behalf of the Funds. The Funds’ chief compliance officer provides quarterly and annual compliance reports and other compliance related briefings to the Board in writing and in person.
39
Trustee Qualifications
The Board has not established specific qualifications that must be met by a member of the Board. The Board believes that all of the Trustees bring to the Board a wealth of executive leadership experience derived from their service as executives, board members, and leaders of companies, community and other organizations. The Board also believes that the different perspectives, viewpoints, professional experience, education, and individual qualities of each Trustee represent a diversity of experiences and a variety of complementary skills. In evaluating nominees, the Nominations Committee considers, among other things, an individual’s background, skills, education and experience; whether the individual is an “interested person;” and whether the individual could be deemed a “financial expert” within the meaning of applicable SEC rules. The Nominations Committee also considers whether the individual’s background, skills, and experience will complement, and add to the diversity of, the background, skills, and experience of other Trustees, and will contribute to the Board’s deliberations.
In addition to the information provided in the table that follows, below is certain additional information concerning each individual Trustee. The information provided below and in the table is not all-inclusive. Many of the Trustees’ qualifications to serve on the Board involve intangible elements, such as intelligence, integrity, work ethic, the ability to work together, the ability to communicate effectively, the ability to exercise judgment, the ability to ask incisive questions, and commitment to shareholder interests.
William H. Wilson Jr. Mr. Wilson has served as an Independent Trustee since May 2008. Mr. Wilson has ownership interests and holds executive level positions at a variety of organizations with diverse interests. Mr. Wilson is a Certified Public Accountant with a Master in Business Administration degree from Harvard Graduate School of Business Administration and a Bachelor of Science in Economics from the Wharton School University of Pennsylvania. Through his employment, education and experience, Mr. Wilson brings financial, accounting, regulatory and investment skills to the Board.
Jennifer Wheeler Ms. Wheeler has served as an Independent Trustee since November 2016. Ms. Wheeler is a consultant to the American Fidelity Insurance Company. Ms. Wheeler earned a J.D., with honors, from the University of Oklahoma. Ms. Wheeler previously provided legal representation to the Trust’s Independent Trustees as a partner at McAfee and Taft. Ms. Wheeler brings legal, financial, regulatory and investment skills to the Board.
Scott Grauer Mr. Grauer has served as an Interested Trustee since January 2010. Mr. Grauer currently serves as Executive Vice President, Wealth Management Division, BOK Financial Corporation (“BOK Financial”) and Chief Executive Officer of BOK Financial Securities, Inc. (“BOKFS”). Mr. Grauer is also Chairman of the Board of BOKFS, Cavanal Hill Investment Management and affiliated advisers and BOK Financial Private Wealth, Inc., and serves as an officer or as a member of the board for other BOK Financial subsidiaries. Mr. Grauer earned a Bachelor’s degree in Business Administration from Baker University. Mr. Grauer is involved in community service organizations including Junior Achievement’s Investor Challenge. Through his employment, education and experience, Mr. Grauer brings financial, accounting, regulatory and investment skills to the Board.
The Trustees and officers of the Funds, their year of birth, the position they hold with the Funds, their term of office and length of time served, a description of their principal occupations during the past five years, the number of portfolios in the fund complex that the Trustee oversees and any other directorships held by the Trustee are listed in the two tables immediately following. The business address of the persons listed below is One Williams Center, BOKF Tower — 10 SW, Tulsa, Oklahoma 74172.
INDEPENDENT TRUSTEES
| NAME AND AGE | POSITION(S) HELD WITH THE FUNDS |
TERM
OF OFFICE AND LENGTH OF TIME SERVED |
PRINCIPAL OCCUPATION(S) DURING THE PAST 5 YEARS |
NUMBER
OF PORTFOLIOS IN FUND COMPLEX OVERSEEN BY TRUSTEE |
OTHER DIRECTORSHIPS HELD BY TRUSTEE DURING THE PAST 5 YEARS* | |||||
| William H. Wilson Jr. (1958) | Trustee, Chairman | Indefinite, 5/08 – Present | Ownership interest and/or executive positions with Sage Partners | 8 | N/A | |||||
| Jennifer Wheeler (1972) | Trustee | Indefinite, 11/16 – Present | From March 2025 to present, Consultant to the American Fidelity Insurance Company. From October 2016 to March 2025, Counsel to the American Fidelity Insurance Company | 8 | N/A |
40
INTERESTED TRUSTEE
| NAME AND AGE | POSITION(S) HELD WITH THE FUNDS |
TERM
OF OFFICE AND LENGTH OF TIME SERVED |
PRINCIPAL OCCUPATION(S) DURING THE PAST 5 YEARS |
NUMBER
OF PORTFOLIOS IN FUND COMPLEX OVERSEEN BY TRUSTEE |
OTHER DIRECTORSHIPS HELD BY TRUSTEE DURING THE PAST 5 YEARS* | |||||
| Scott Grauer** (1964) | Trustee | Indefinite, 1/10 – Present | From July 2008 to present, Executive Vice President, Wealth Management Division, BOKF; from 1991 to present, CEO, BOK
Financial Securities, Inc. |
8 | N/A |
| * | Directorships held in (1) any other investment companies registered under the 1940 Act, (2) any company with a class of securities registered pursuant to Section 12 of the Securities Exchange Act of 1934, as amended (the “Exchange Act”) or (3) any company subject to the requirements of Section 15(d) of the Exchange Act. |
| ** | Mr. Grauer is treated by the Funds as an “interested person” (as defined in Section 2(a)(19) of the 1940 Act) of the Funds. Mr. Grauer is an “interested person” because he is an Executive Vice President of BOK Financial, the parent of CHD and the indirect parent of Cavanal Hill Investment Management. Mr. Grauer is also Chairman of the Board of BOKFS, CHD, Cavanal Hill Investment Management and affiliated advisers, BOK Financial Asset Management, Inc. and BOK Financial Private Wealth, Inc., and serves as an officer or as a member of the board for other BOK Financial subsidiaries. |
OFFICERS
| NAME AND AGE | POSITION(S) HELD WITH THE FUNDS |
TERM OF OFFICE AND LENGTH OF TIME SERVED | PRINCIPAL
OCCUPATION(S) DURING THE PAST 5 YEARS |
NUMBER OF PORTFOLIOS IN FUND COMPLEX | OTHER DIRECTORSHIPS HELD BY TRUSTEE | |||||
| Catherine Dunn (1971) | President | Indefinite, 10/24 – Present |
From October 2022 to present, Senior Vice President, Cavanal Hill Funds Administration Manager. From April 2021 to September 2022, Manager, Global Fund Services at U.S. Bank. | N/A | N/A | |||||
| Assistant Secretary | Indefinite 07/23 – Present |
From October 2016 to April 2022, Vice President, Financial Reporting at State Street Bank & Trust. |
||||||||
| Jerica Newbill (1985) | Treasurer and Principal Financial and Accounting Officer | Indefinite, 7/24 – Present |
From May 2024 to present, Director of Principal Financial Officer Services of PINE Advisors LLC. From April 2022 to May 2024, Member of Accounting and Financial Reporting Team at Fundrise. From 2019 to 2022, Officer of Fund Administration for State Street Bank. | N/A | N/A | |||||
| Amy Siefer (1977) | Chief Compliance Officer, Anti-Money Laundering Officer and Disaster Recovery Plan Business Operations Manager | Indefinite 7/24 – Present |
From June 2024 to present, Director at PINE Advisors LLC. From 2012 to May 2024, Vice President at Citi Fund Services Ohio, Inc. From 2018 to September 2023, Chief Compliance Officer and AML Officer for Boston Trust Walden Funds. | N/A | N/A | |||||
| Cheryl Briggs (1960) | Vice President and Secretary | Indefinite,
4/15 – Present |
From March 2015 to present, Officer, Cavanal Hill Funds Administrator. | N/A | N/A |
41
For interested officers, Ms. Briggs and Ms. Dunn, positions held with affiliated persons or principal underwriters of the Trust are provided above. For interested Trustees, the information is listed in the following table:
| NAME | POSITIONS HELD
WITH AFFILIATED PERSONS OR PRINCIPAL UNDERWRITERS OF THE FUNDS |
|
| Scott Grauer (1964) | BOK Financial, Executive Vice President,
Wealth Management Division; BOKFS, Chief Executive Officer.
Mr. Grauer is also Chairman of the Board of BOKFS, CHD, Cavanal Hill Investment Management and affiliated advisers, BOK Financial Asset Management and BOK Financial Private Wealth, Inc., and serves as an officer or as a member of the board for other BOK Financial subsidiaries. |
42
COMMITTEES OF THE BOARD OF TRUSTEES
The purposes of the Audit Committee are to oversee the Trust’s accounting and financial reporting policies and practices; to oversee the quality and objectivity of the Trust’s financial statements and the independent audit thereof; to consider the selection of independent registered public accountants for the Trust and the scope of the audit; and to act as a liaison between the Trust’s independent registered public accountants and the full Board. Mr. Wilson and Ms. Wheeler serve on this Committee. Mr. Wilson joined this Committee on June 23, 2008. Ms. Wheeler joined this Committee on November 1, 2016. For the fiscal year ended August 31, 2026, there were [four] meetings of the Audit Committee.
The purpose of the Nominations Committee is to recommend qualified candidates to the Board in the event that a position is vacated or created. Mr. Wilson and Ms. Wheeler serve on this Committee; Mr. Wilson became a Committee member on May 1, 2008 and Ms. Wheeler joined the Committee on November 1, 2016. The Committee will consider nominees recommended by shareholders. Recommendations should be submitted to the Nominations Committee in care of the Cavanal Hill Funds. For the fiscal year ended August 31, 2026, there were no meetings of the Nominations Committee.
For each Trustee, the following table discloses the dollar range of equity securities beneficially owned by the Trustee in the Fund indicated and, on an aggregate basis, in any RIC overseen by the Trustee within the Fund’s family of investment companies as of December 31, 2025:
| NAME OF TRUSTEE | DOLLAR RANGE OF
EQUITY SECURITIES IN THE FUNDS |
AGGREGATE DOLLAR
RANGE OF EQUITY SECURITIES IN ALL REGISTERED INVESTMENT COMPANIES OVERSEEN BY TRUSTEE IN FAMILY OF INVESTMENT COMPANIES |
||
| William H. Wilson Jr. | World Energy
& Power Fund: $10,001 – $50,000 Hedged Equity Income Fund: $100,001 – 500,000 |
$100,001 – $500,000 |
The following table shows information for Trustees who are “interested persons” of the Funds as defined in the 1940 Act:
| NAME OF TRUSTEE | DOLLAR RANGE OF
EQUITY SECURITIES IN THE FUNDS |
AGGREGATE DOLLAR
RANGE OF EQUITY SECURITIES IN ALL REGISTERED INVESTMENT COMPANIES OVERSEEN BY TRUSTEE IN FAMILY OF INVESTMENT COMPANIES |
||
| Scott Grauer | Limited Duration Fund: $1 – $10,000 Government Securities MMF: $100,001 – $500,000 Bond Fund: $1 – $10,000 World Energy & Power Fund: $50,001 – $100,000 |
$100,001 – $500,000* |
| * | Under the definition of “beneficial ownership” used for purposes of the foregoing table, Mr. Grauer, who is an executive officer of BOK Financial, is not considered the beneficial owner of any Fund securities with respect to which BOK Financial or its affiliates has investment or voting discretion. Affiliates of BOK Financial have investment and voting discretion over a substantial majority of each Fund’s securities. |
43
For independent Trustees and their immediate family members, the following table provides information regarding each class of securities owned beneficially in an investment adviser or principal underwriter of the Trust, or a person (other than a RIC) directly or indirectly controlling, controlled by, or under common control with an investment adviser or principal underwriter of the Trust as of December 31, 2025:
| NAME OF TRUSTEE | NAME
OF OWNERS AND RELATIONSHIPS TO TRUSTEE |
COMPANY | TITLE
OF CLASS |
VALUE
OF SECURITIES | PERCENT
OF CLASS |
|||||
| William H. Wilson Jr. | N/A | N/A | N/A | N/A | N/A | |||||
| Jennifer Wheeler | N/A | N/A | N/A | N/A | N/A |
Cavanal Hill Investment Management provides advisory services to separately managed accounts, which may have the same or similar strategies as Cavanal Hill Funds. From time to time, Trustees, Officers and other individuals involved in the operation of the Funds may hold interests in such separately managed accounts.
The Trustees receive fees and are reimbursed for their expenses in connection with each meeting of the Board they attend. However, no officer or employee of an Adviser or the Administrator (as defined herein) of the Funds receives any compensation from the Funds for acting as a Trustee. The officers of the Funds (other than Ms. Siefer and Ms. Newbill) receive no compensation directly from the Funds for performing the duties of their offices. PINE Advisors LLC (“PINE”) receives fees from the Funds for providing Chief Compliance Officer and Principal Financial and Accounting Officer services. Ms. Siefer, the Chief Compliance Officer, Anti-Money Laundering Compliance Officer, Identity Theft Officer and Disaster Recovery Plan Business Operations Manager, and Ms. Newbill, the Treasurer and Principal Financial and Accounting Officer, are employees of PINE and receive compensation from PINE derived from fees paid by the Funds to PINE under a Services Agreement (the “PINE Agreement”). The PINE Agreement is described under the “PINE Advisors LLC” section.
INDEPENDENT TRUSTEES’ COMPENSATION
| NAME OF PERSON, POSITION | AGGREGATE
COMPENSATION FROM THE FUNDS FOR THE FISCAL YEAR ENDED AUGUST 31, 2026 | PENSION
OR RETIREMENT BENEFITS ACCRUED AS PART OF FUND EXPENSES | ESTIMATED
ANNUAL BENEFITS UPON RETIREMENT | TOTAL
COMPENSATION FROM FUNDS AND FUND COMPLEX PAID TO TRUSTEES FOR THE FISCAL YEAR ENDED AUGUST 31, 2026 | ||||||||||||
| William H. Wilson Jr., Chairman of the Board | $ | 84,996 | N/A | N/A | $ | 84,996 | ||||||||||
| Jennifer Wheeler | $ | 75,000 | N/A | N/A | $ | 75,000 | ||||||||||
Each Fund, Cavanal Hill Investment Management and CHD have adopted codes of ethics (“Codes”) under Rule 17j-1 of the 1940 Act, and these Codes permit personnel subject to the Codes to invest in securities, including securities that may be purchased or held by each Fund.
The Bond and Equity Funds do not authorize, and use reasonable methods to discourage, short-term or excessive trading, often referred to as “market timing.” Market timing is an investment strategy using frequent purchases, redemptions and/or exchanges in an attempt to profit from short-term market movements. Market timing or excessive trading may result in dilution of the value of fund shares held by long-term shareholders, disrupt portfolio management, and increase fund expenses for all shareholders. The Funds will take reasonable steps to discourage excessive short-term trading and the Board has adopted the following policies and procedures with respect to market timing. The Funds will monitor selected trades in an effort to detect excessive short-term trading. If a Fund has reason to believe that a shareholder has engaged in excessive short-term trading, the Fund may ask the shareholder to stop such activities or refuse to process purchases or exchanges in the shareholder’s accounts. In addition to rejecting purchase orders in connection with suspected market timing activities, The Funds can reject a purchase order for any reason. While the Funds cannot assure the prevention of all excessive trading and market timing, by making these judgments the Funds believe they are acting in a manner that is in the best interests of shareholders.
44
Market timers may disrupt portfolio management and harm fund performance. To the extent that the Funds are unable to identify market timers effectively, long-term investors may be adversely affected. Although the Funds use a variety of methods to detect and deter market timing, due to the complexity involved in identifying excessive trading there is no assurance that the Funds efforts will identify and eliminate all trades or trading practices that may be considered abusive. In accordance with Rule 22c-2 under the 1940 Act, the Trust has entered into information sharing agreements with certain financial intermediaries. Under these agreements, a financial intermediary is obligated to: (1) adopt and enforce during the term of the agreement, a market timing policy, the terms of which are acceptable to the Trust; (2) furnish the Trust, upon its request, with information regarding customer trading activities in shares of the Trust; and (3) enforce its market-timing policy with respect to customers identified by the Trust as having engaged in market timing. When information regarding transactions in the Trust’s shares is requested by the Trust and such information is in the possession of a person that is itself a financial intermediary to a financial intermediary (an “indirect intermediary”), any financial intermediary with whom the Trust has an information sharing agreement is obligated to obtain transaction information from the indirect intermediary or, if directed by the Trust, to restrict or prohibit the indirect intermediary from purchasing shares of the Trust on behalf of other persons. The Funds apply these policies and procedures to all shareholders believed to be engaged in market timing or excessive trading. The Funds have no arrangements to permit any investor to trade frequently in shares of the funds, nor will it enter into any such arrangements in the future. Because the Money Market Funds are designed to offer investors a liquid cash option that they may sell as often as they wish, they are not subject to the same policies and procedures. We reserve the right to modify our policies and procedures related to market timing at any time without prior notice as we deem in our sole discretion to be in the best interests of Fund shareholders, or to comply with state or Federal legal requirements.
DISCLOSURE OF PORTFOLIO HOLDINGS
Information regarding portfolio holdings may be made available to third parties in the following circumstances:
| • | Through disclosure in the Trust’s monthly reporting on Form N-PORT; |
| • | In marketing materials, provided that the information regarding portfolio holdings contained therein is at least fifteen days old; or |
| • | When a Fund has a legitimate business purpose for doing so and the recipients are subject to a confidentiality agreement which prohibits both disclosure of portfolio holdings to third parties and trading based on such information. Such disclosure shall be authorized by the Trust’s President or Treasurer and shall be reported annually to the Board. |
In addition, the Adviser will post portfolio holdings information for the Cavanal Hill Funds on the Funds’ website at www.cavanalhillfunds.com. The website will contain each Fund’s complete schedule of portfolio holdings as of the last day of the most recent month end (except the Money Market Funds, which holdings are posted daily). Although the Adviser will typically post this information approximately 16 days after a month’s end, and such information will remain accessible on the website until the information is filed with the SEC as part of the Trust’s Form N-MFP, N-CSR or Form N-PORT, as applicable, it may (but is not required to) post more current information regarding the holdings of one or more of the Funds on the Trust’s website. Such posted information may include all of a Fund’s holdings, or may be limited to more current information about select issuers or types of issuers, as determined by Trust management.
Except as disclosed above, it is the policy of the Funds not to disclose material information about their portfolio holdings, trading strategies implemented or to be implemented or pending transactions to other third parties. The Funds’ service providers are prohibited from disclosing to other third parties’ material information about the Funds’ portfolio holdings, trading strategies implemented or to be implemented or pending transactions. The Funds may, however, provide information regarding their portfolio holdings to their service providers where relevant to duties to be performed for the Funds. Such service providers include fund accountants, administrators, investment advisers, custodians, independent public accountants, and attorneys. The Funds’ fund accountants, administrators, investment advisers and custodians are provided with portfolio holdings information on a daily basis. The Fund’s independent public accountants and attorneys are provided with portfolio holdings information as issues may arise. In addition, portfolio holding information may be disclosed to facilitate the review of a Fund by certain mutual fund analysts and ratings agencies (such as Morningstar and Lipper Analytical Services) on an as-needed basis.
45
Other than the service provider arrangements discussed above, the Funds do not have in place any ongoing arrangements to provide information regarding portfolio holdings to any person. The Fund’s policies prohibit the receipt of compensation for the disclosure of portfolio holdings. Any violation of the Funds’ policies with respect to the disclosure of portfolio holdings is reported to the Board on a quarterly basis.
PROXY VOTING POLICIES AND PROCEDURES
The following proxy voting policies and procedures apply to the Bond and Equity Funds and the Adviser:
Cavanal Hill Funds Proxy Voting Policy
It is the policy of the Board to delegate the responsibility for voting proxies relating to portfolio securities to each investment adviser as a part of the adviser’s general management of the portfolio, subject to the Board’s continuing oversight. The following are the guidelines adopted by the Board for the administration of this policy:
Fiduciary Duty
The right to vote a proxy with respect to portfolio securities held in portfolios of the Funds is an asset of the Funds. Each adviser to whom authority to vote on behalf of the Funds is delegated acts as a fiduciary of the Funds and must vote proxies in a manner consistent with the best interest of the Funds and its shareholders.
Review of Policies & Procedures
Consistent with the delegation of proxy voting responsibilities, the Adviser is responsible for the following:
| • | implementing written policies and procedures, in compliance with Rule 206(4)-6 under the Advisers Act, reasonably designed to ensure that the Adviser votes portfolio securities in the best interest of shareholders of the Funds; |
| • | presenting to the Board its policies, procedures and other guidelines for voting proxies at least annually; |
| • | providing a summary of the material changes to a proxy policy and a redlined copy of such Proxy Policy as applicable to the Board; and |
| • | reviewing its Proxy Policy at least annually to ensure compliance with Rule 206(4)-6 under the Advisers Act and confirm the Policy is reasonably designed to ensure that the Adviser votes portfolio securities in the best interest of shareholders of the Fund. |
On a quarterly basis, the Fund’s chief compliance officer shall request confirmation from the Adviser that any proxy votes for the Funds were handled in compliance with the Proxy Policies. The Board shall review the policies, procedures and other guidelines presented by the Adviser to determine that they meet the requirements of this policy.
Proxy Voting Services
The Adviser may retain a proxy-voting service to coordinate, collect, and maintain all proxy-related information.
If the Adviser retains a proxy-voting service, the Adviser will be responsible for overseeing the service provider and performing such review as is necessary to determine the accuracy of the votes and alignment with the Adviser’s policies.
Voting Record Keeping
The Adviser must include in its Board presentation materials once each year a record of each proxy voted with respect to portfolio securities of the Funds during the year. Proxy solicitations that might involve a conflict of interest between the Adviser and the Fund will be considered by the Adviser’s Investment Policy Committee (“IPC”), which will determine, based on a review of the issues raised by the solicitation, the nature of the potential conflict and, most importantly, the Adviser’s commitment to vote proxies in the best interest of the Fund, how the proxy will be handled.
The Trust will file complete proxy voting record with the SEC on Form N-PX annually by August 31 of each year. The Funds’ Administrator will be responsible for the oversight and completion of the filing of Form N-PX with the SEC and will file Form N-PX for each twelve-month period ended June 30 on or before August 31 of that year.
46
Sub-advisers
The Adviser may but is not required to further delegate the responsibility for voting proxies relating to portfolio securities to a Sub-Adviser retained to provide investment advisory services to portfolios of the Funds. If such responsibility is delegated to a Sub-Adviser, the Sub-Adviser shall assume the reporting responsibilities of the adviser under these policy guidelines.
Revocation
The delegation of authority by the Board to vote proxies relating to portfolio securities of the Funds is entirely voluntary and may be revoked by the Board, in whole or in part, at any time.
Recordkeeping
Documentation of all votes for the Funds will be maintained by the Adviser and through a third-party proxy voting service, as applicable.
Shareholder Disclosure
The Trust Shall:
| • | file its complete proxy voting record with the SEC on an annual basis on Form N-PX. |
| • | disclose in its statement of additional information the policies and procedures that it uses to vote proxies relating to portfolio securities held by the Trust. |
| • | make available to shareholders, on its website and upon request, the record of how the Trust voted proxies relating to portfolio securities held by the Trust. |
You may obtain information about how a Fund voted proxies related to its portfolio securities during the 12 month period ended June 30 by visiting the SEC’s Web site at www.sec.gov or without charge, upon request, by contacting us by telephone at 1-800-762-7085 or in writing at Cavanal Hill Funds, 4400 Easton Commons, Suite 200, Columbus, Ohio 43219-3035.
Cavanal Hill Investment Management (referred to as “CHIM” or the “Firm” in the following Policy and Procedures)
Policy
CHIM, as a matter of policy and as a fiduciary to our clients, has responsibility for voting proxies for portfolio securities consistent with the best interests of the clients. The firm maintains written policies and procedures as to the handling, research, voting and reporting of proxy voting and makes appropriate disclosures about the firm’s proxy policies and practices. The firm’s policy and practice include the responsibility to receive and vote client proxies and disclose any potential conflicts of interest as well as making information available to clients about the voting of proxies for their portfolio securities and maintaining relevant and required records.
It is the policy of the Firm that, absent compelling reasons why a proxy should not be voted, all proxies relating to client securities should be voted. Proxies are voted in the best interests of the client accounts. The determination of the interest of a client account in a proposal presented by proxy is the anticipated effect the proposal could have on the current or future value of the investment. Subject to the adoption of procedures or guidelines by the Firm’s Board of Directors or specific written direction from a client, proxy voting shall be the responsibility of the President and the Investment Policy Committee (IPC), both of whom may delegate such aspects of this responsibility as it may consider appropriate to designated officers or employees of the Firm. If it is appropriate to do so, an outside service provider may be employed to vote client proxies or to provide advice in the voting of a proxy.
Proxy solicitations that might involve a conflict of interest between the Firm and its client accounts will be considered by the IPC, which will determine, based on a review of the issues raised by the solicitation, the nature of the potential conflict and, most importantly, the Firm’s commitment to vote proxies in the best economic interest of client accounts, how the proxy will be handled.
47
Procedure
The Firm may utilize one or more outside service providers to facilitate the execution of and recordkeeping related to the execution of client proxy voting. Such service provider must adhere to the proxy voting policies, procedures, and guidelines adopted by the Firm.
The Firm will maintain a list of those companies, which issue publicly traded securities and with which the Firm or its affiliates have such a relationship that proxies presented with respect to those companies may give rise to a conflict of interest between the Firm and its clients.
Proxy Voting Guidelines
The key element underlying any evaluation of the interest of an advisory account in an issue presented to the shareholders of the company is the anticipated effect a proposal could have on the current or future value of the investment.
It is the practice of the Firm to vote with Management Proposals, unless it appears to conflicts with other Guidelines.
To the extent that management’s proposals do not appear to infringe on stockholder rights, the firm will support their position. Management sponsored resolutions can be grouped into five primary categories:
Standard Proposals (for example):
| • | Elect or re-elect members of the board of directors |
| • | Select outside auditors |
| • | Set the annual meeting date and location |
| • | Eliminate preemptive rights or dual classes of stock |
| • | Establish dividend reinvestment plans |
| • | Provide cumulative voting for directors |
| • | Indemnify directors, officers and employees |
| • | Change the corporate name |
Capitalization Proposals (for example):
| • | Increase the authorized number common shares |
| • | Adjust of par value |
| • | Establish flexible schedules of preferred dividends |
| • | Repurchase shares |
| • | Authorize stock splits or stock dividends |
| • | Establish anti-greenmail measures |
Non-Salary Compensation Programs (for example):
The Firm will support stock or other non-salary compensation plans that afford incentives based on performance, as opposed to risk-free rewards, including:
| • | Performance incentives |
| • | Stock option plans |
| • | Stock purchase or stock ownership plans |
| • | Thrift/Profit Sharing plans |
48
Miscellaneous Corporate Governance Matters (for example):
| • | Limit directors’ liability |
| • | Authorize indemnification agreements |
| • | Meet SEC/NASD quorum requirements |
| • | Reorganize as a holding company |
Shareholder Proposals:
The Firm recognizes that shareholders regularly make various proposals which they perceive as offering social (and, at times, economic) benefits to both the corporation and its shareholders. While the Firm acknowledges that economic and social considerations are often closely intertwined, the management group and elected directors are best positioned to make corporate decisions on these proposals. The Firm will generally support management’s position on shareholder proposals presented by proxy.
The Firm will not sup p ort Anti-Takeover Measures:
The Firm believes that charter and by-law amendments designed to thwart takeover attempts sometimes undermine the prospects for realizing maximum appreciation, and thus, are not in the best interest of shareholders. The Firm will oppose the following anti-takeover measures (for example):
| • | Fair pricing procedures |
| • | Super majority rules |
| • | Board classification |
| • | Bars to written consent |
| • | Incumbent-entrenchment measures |
| • | Re-incorporation measures |
| • | Control share measures |
The Firm will retain records relating to the voting of proxies, including:
| • | A copy of policies, procedures or guidelines relating to the voting of proxies. |
| • | A copy of each proxy statement, written or electronic, that the Firm receives regarding client securities. The Firm may rely on a third party to make and retain, on its behalf, a copy of a proxy statement, which may be electronic, provided that the Firm has obtained an undertaking from the third party to provide a copy of the proxy statement promptly upon request or may rely on obtaining a copy of a proxy statement from the Electronic Data Gathering, Analysis, and Retrieval (EDGAR) system. |
| • | A record of each vote cast by the Firm in the aggregate on behalf of all clients. The Firm may rely on a third party to make and retain, on its behalf, a record of the vote cast, provided that the adviser has obtained an undertaking from the third party to provide a copy of the record promptly upon request. |
| • | A copy of any document created by the Firm that was material to making a decision regarding how to vote proxies or that memorializes the basis for that decision. |
| • | A copy of each written client request for information on how the Firm voted proxies on behalf of the client, and a copy of any written response by the Firm to any client request for information on how the adviser voted proxies in the aggregate and within the time frame requested by the client. |
These records will be retained for five years from the end of the fiscal year during which the last entry was made on such record, with at least the first two years in an appropriate office of the Firm.
49
The Firm shall disclose, via website, how each client may obtain information about how the Firm voted with respect to their securities; and shall provide each client a description of the Firm’s proxy voting policies and procedures and, upon request, shall furnish a copy of the policies and procedures to the requesting client.
Background
Proxy voting is an important right of shareholders and reasonable care and diligence must be undertaken to ensure that such rights are properly and timely exercised.
Investment advisers registered with the SEC, and which exercise voting authority with respect to client securities, are required by Rule 206(4)-6 of the Advisers Act (17 CFR § 275.206(4)-6) to (a) adopt and implement written policies and procedures that are reasonably designed to ensure that client securities are voted in the best interests of clients, which must include how an adviser addresses material conflicts that may arise between an adviser’s interests and those of its clients; (b) to disclose to clients how they may obtain information from the adviser with respect to the voting of proxies for their securities; (c) to describe to clients a summary of its proxy voting policies and procedures and, upon request, furnish a copy to its clients; and (d) maintain certain records relating to the adviser’s proxy voting activities when the adviser does have proxy voting authority.
Staff Legal Bulletin No. 20 was jointly published by the SEC’s Division of Investment Management and Division of Corporation Finance on June 30, 2014. The Division of Investment Management provided guidance about investment advisers’ responsibilities in voting client proxies and retaining proxy advisory firms, while the Division of Corporation Finance addressed the availability and requirements of two exemptions to the federal proxy rules that are often relied upon by proxy advisory firms.
CURRENT PROXY VOTING ARRANGEMENTS
In accordance with its proxy voting procedures, Cavanal Hill Investment Management has retained Institutional Shareholder Services, Inc. (“ISS”), an unaffiliated third party, as its agent to vote proxies relating to portfolio securities of Cavanal Hill Funds on behalf of Cavanal Hill Investment Management. ISS is providing three basic services to Cavanal Hill Investment Management:
| • | ISS has received Cavanal Hill Investment Management’s proxy voting guidelines (a copy of the current guidelines are attached); |
| • | ISS will vote the proxies relating to portfolio securities in accordance with the proxy voting guidelines; and |
| • | ISS will maintain records relating to the voting of proxies which will be used both to monitor proxy voting activity and to meet the reporting requirements of Cavanal Hill Investment Management’s proxy voting procedures and SEC rules and regulations. |
Cavanal Hill Investment Management believes that this arrangement is reasonably designed to ensure that proxies relating to client securities will be voted in the best interest of the clients and, because the process is handled by a third party not affiliated with Cavanal Hill Investment Management, will avoid material conflicts between Cavanal Hill Investment Management and its clients.
Investment advisory services are provided to each of the Funds by Cavanal Hill Investment Management pursuant to an Investment Advisory Agreement. Cavanal Hill Investment Management is a separate, wholly-owned subsidiary of BOKF, NA. It began serving as Investment Adviser to the Funds on May 12, 2001. Cavanal Hill Investment Management, subject to the general supervision of the Board, is responsible for providing research, investment decision making, strategizing and risk management, and day-to-day portfolio management. Cavanal Hill Investment Management is located at One Williams Center, 15th Floor, Tulsa, OK 74172-0172. As of September 30, 2026, Cavanal Hill Investment Management had approximately $[•] billion in assets under management.
50
BOKF is a subsidiary of BOK Financial. BOK Financial is controlled by its principal shareholder, George B. Kaiser. Subsidiaries of BOK Financial provide an array of wealth management, trust, custody and administration, and commercial and retail banking services, as well as non-banking financial services. Non-banking subsidiaries provide various financial services, including mortgage banking, broker-dealer and investment advisory services, private equity and alternative investing, and credit life, accident, and health insurance on certain loans originated by its subsidiaries.
BOKF Financial subsidiaries maintain offices in Oklahoma, Arizona, Arkansas, Colorado, Kansas, Missouri, New Mexico and Texas, and offer a variety of services for both corporate and individual customers. Individual financial trust services include personal trust management, administration of estates, and management of individual investments and custodial accounts. For corporate clients, the array of services includes management, administration and recordkeeping of pension plans, thrift plans, 401(k) plans and master trust plans. BOK Financial subsidiaries also provide investment banking services, serve as transfer agent and registrar for corporate securities, broker/dealer, paying agent for dividends and interest, and indenture trustee of bond issues. As of September 30, 2026, BOK Financial and its subsidiaries had approximately $[•] billion in assets under management or in custody.
Subject to the general supervision of the Board and in accordance with the investment objective and restrictions of each of the Funds, Cavanal Hill Investment Management reviews, supervises, and provides general investment advice regarding each of the Funds’ investment programs. Subject to the general supervision of the Board and in accordance with the investment objective and restrictions of each of the Funds, Cavanal Hill Investment Management makes all final decisions with respect to portfolio securities of each of the Funds, places orders for all purchases and sales of the portfolio securities of each of the Funds, and maintains each Fund’s records directly relating to such purchases and sales.
For the services provided and expenses assumed pursuant to the Investment Advisory Agreement with the Funds, the Adviser is entitled to receive a fee from each of the Funds, computed daily and paid monthly, based on the lower of (1) such fee as may, from time to time, be agreed upon in writing by the Funds and the Adviser or (2) the average daily net assets of each such Fund as follows: the Money Market Funds — five one-hundredths of one percent (0.05%) annually; the Bond Fund — twenty one-hundredths of one percent (0.20%) annually; the Limited Duration Fund— fifteen one-hundredths of one percent (0.15%) annually; the Strategic Enhanced Yield Fund — fifty one-hundredths of one percent (0.50%) annually; the World Energy & Power Fund — sixty one-hundredths of one percent (0.60%) annually, the Hedged Equity Income Fund — eighty one-hundredths of one percent (0.80%) annually; and the Industrial Frontier Fund — sixty one-hundredths of one percent (0.60%) annually. Cavanal Hill Investment Management may periodically waive all or a portion of its fee with respect to any Fund to increase the net income of such Fund available for distribution as dividends. The Funds paid Cavanal Hill Investment Management the following aggregate fees for investment advisory services for the following fiscal years ended:*
| AUGUST 31, 2026 | AUGUST 31, 2025 | AUGUST 31, 2024 | ||||||||||||||||||||||
| GROSS FEES | AMOUNT WAIVED/ REIMBURSED | GROSS FEES | AMOUNT WAIVED/ REIMBURSED | GROSS FEES | AMOUNT WAIVED/ REIMBURSED | |||||||||||||||||||
| U.S. Treasury Fund | [•] | [•] | $ | 883,013 | $ | — | $ | 895,445 | $ | — | ||||||||||||||
| Government Securities Money Market Fund | [•] | [•] | $ | 1,501,084 | $ | — | $ | 1,321,857 | $ | — | ||||||||||||||
| Limited Duration Fund | [•] | [•] | $ | 47,127 | $ | 146,823 | $ | 48,128 | $ | 1,427 | ||||||||||||||
| Bond Fund | [•] | [•] | $ | 233,846 | $ | 978 | $ | 240,009 | $ | 1,074 | ||||||||||||||
| Strategic Enhanced Yield Fund | [•] | [•] | $ | 100,003 | $ | 143,019 | $ | 34,769 | $ | 98,280 | ||||||||||||||
| World Energy & Power Fund | [•] | [•] | $ | 659,328 | $ | 105,919 | $ | 535,363 | $ | 92,151 | ||||||||||||||
| Hedged Equity Income Fund | [•] | [•] | $ | 218,530 | $ | 122,082 | $ | 232,682 | $ | 59,805 | ||||||||||||||
| * | The Industrial Frontier Fund had not commenced operations as of August 31, 2026. |
The Investment Advisory Agreement will continue in effect as to a particular Fund for successive one-year terms, if such continuance is approved at least annually by the Board or by vote of a majority of the outstanding voting Shares of such Fund and a majority of the Trustees who are not parties to the Investment Advisory Agreement, or interested persons (as defined in the 1940 Act) of any party to the Investment Advisory Agreement by votes cast in person at a meeting called for such purpose.
51
The Investment Advisory Agreement is terminable as to a particular Fund at any time on 60 days’ written notice without penalty by the Trustees, by vote of a majority of the outstanding voting Shares of that Fund, or by the Adviser. The Investment Advisory Agreement also terminates automatically in the event of any assignment, as defined in the 1940 Act.
The Investment Advisory Agreement provides that the Adviser shall not be liable for any error of judgment or mistake of law or for any loss suffered by the Funds in connection with the performance of the Investment Advisory Agreement, except a loss resulting from a breach of fiduciary duty with respect to the receipt of compensation for services or a loss resulting from willful misfeasance, bad faith, or gross negligence on the part of the respective provider of services to the Funds in the performance of its duties, or from reckless disregard by it of its duties and obligations thereunder.
A discussion of the basis for the Board’s approval of the Funds’ investment advisory contracts is included in the Funds’ reports on Form N-CSR for the period during which the Board approved such contracts.
From time to time, advertisements, supplemental sales literature and information furnished to present or prospective Shareholders of the Funds may include descriptions of the Adviser including, but not limited to, (i) a description of the Adviser’s operations; (ii) descriptions of certain personnel and their functions; and (iii) statistics and rankings related to the Adviser’s operations.
INVESTMENT SUB-ADVISERS
Investment sub-advisory services are provided to the Hedged Equity Income Fund by Lavaca Capital, LLC (“Lavaca”) pursuant to an investment sub-advisory agreement between Cavanal Hill Investment Management and Lavaca, as approved by the Board (the “Lavaca Investment Sub-Advisory Agreement”).
The Hedged Equity Income Fund’s principal investment strategy involves purchasing dividend paying equity securities and hedging the fund’s stock holdings, including buying/selling puts and writing/buying back covered calls against the securities owned in the fund. Lavaca will provide the hedging portion of the strategy, utilizing its options and volatility-based hedging strategies, specializing in the use of U.S. listed equity options, seeking to (i) reduce risk, (ii) enhance income and (iii) provide an alternative source of absolute return for client portfolios.
Subject to the general supervision of the Board and in accordance with the investment objective and restrictions of the Hedged Equity Income Fund, Lavaca will formulate and implement a continuous hedging investment program as agreed between Lavaca and Cavanal Hill Investment Management. Lavaca will provide execution services in association with the buying/selling of protective puts and writing/buying back covered calls against securities owned in the Hedged Equity Income Fund. For the services provided and expenses assumed pursuant to the Lavaca Investment Sub-Advisory Agreement, Lavaca will receive a monthly fee equal to 50% of the monthly management fee payable to Cavanal Hill Investment Management by the Hedged Equity Income Fund under the Investment Advisory Agreement for the applicable month.
The Lavaca Investment Sub-Advisory Agreement will continue in effect as to the Hedged Equity Income Fund for successive one-year terms, if such continuance is approved at least annually by the Board or by vote of a majority of the outstanding voting Shares of such Fund and a majority of the Trustees who are not parties to the Lavaca Investment Sub-Advisory Agreement, or interested persons (as defined in the 1940 Act) of any party to the Lavaca Investment Sub-Advisory Agreement by votes cast in person at a meeting called for such purpose.
The Lavaca Investment Sub-Advisory Agreement is terminable as to the Hedged Equity Income Fund at any time on 60 days’ written notice without penalty by the Trustees, by vote of a majority of the outstanding voting Shares of that Fund, or by the Adviser or Lavaca. The Lavaca Investment Sub-Advisory Agreement also terminates automatically in the event of any assignment, as defined in the 1940 Act.
The Lavaca Investment Sub-Advisory Agreement provides that Lavaca shall not be liable for any error of judgment or mistake of law or for any loss suffered by the Funds in connection with the performance of the Lavaca Investment Sub-Advisory Agreement, except a loss resulting from a breach of fiduciary duty with respect to the receipt of compensation for services or a loss resulting from willful misfeasance, bad faith, or gross negligence on the part of the respective provider of services to the Funds in the performance of its duties, or from reckless disregard by it of its duties and obligations thereunder.
As of September 30, 2026, Lavaca had approximately $[•] million in assets under management.
52
Investment sub-advisory services are provided to the Strategic Enhanced Yield Fund by LM Capital Group, LLC (“LM Capital”) pursuant to an investment sub-advisory agreement between Cavanal Hill Investment Management and LM Capital, as approved by the Board (the “LM Capital Investment Sub-Advisory Agreement”).
The Strategic Enhanced Yield Fund’s principal investment strategy involves investing in a diversified portfolio of fixed income instruments of varying maturities, engaging in opportunistic trading among various sectors based on the perceived market anomalies and inefficiencies in an effort to actively enhance total return and minimize risk. LM Capital, subject to the general supervision of the Board, is responsible for the day-to-day management of the Strategic Enhanced Yield Fund.
The LM Capital Investment Sub-Advisory Agreement will continue in effect as to the Strategic Enhanced Yield Fund for successive one-year terms, if such continuance is approved at least annually by the Board or by vote of a majority of the outstanding voting Shares of such Fund and a majority of the Trustees who are not parties to the LM Capital Investment Sub-Advisory Agreement, or interested persons (as defined in the 1940 Act) of any party to the LM Capital Investment Sub-Advisory Agreement by votes cast in person at a meeting called for such purpose.
The LM Capital Investment Sub-Advisory Agreement is terminable as to the Strategic Enhanced Yield Fund at any time on 60 days’ written notice without penalty by the Trustees, by vote of a majority of the outstanding voting Shares of that Fund, or by the Adviser or LM Capital. The LM Capital Investment Sub-Advisory Agreement also terminates automatically in the event of any assignment, as defined in the 1940 Act.
The LM Capital Investment Sub-Advisory Agreement provides that LM Capital shall not be liable for any error of judgment or mistake of law or for any loss suffered by the Funds in connection with the performance of the LM Capital Investment Sub-Advisory Agreement, except a loss resulting from a breach of fiduciary duty with respect to the receipt of compensation for services or a loss resulting from willful misfeasance, bad faith, or gross negligence on the part of the respective provider of services to the Funds in the performance of its duties, or from reckless disregard by it of its duties and obligations thereunder.
As of September 30, 2026, LM Capital had approximately $[•] billion in assets under management.
The portfolio managers identified under “Investment Management” in the Prospectus are jointly and primarily responsible for the day-to-day
management of the Funds. Each portfolio manager also has responsibility for the day-to-day management of accounts other than the Fund(s) for which he or she serves as portfolio manager. Information regarding these accounts is set forth below.
Number of Other Accounts Managed and Assets by Account Type as of August 31, 2026:
| PORTFOLIO MANAGER | OTHER
REGISTERED INVESTMENT COMPANIES |
OTHER
POOLED INVESTMENT VEHICLES |
OTHER ACCOUNTS | |||
| Brandon R. Barnes | Number: None | Number: None | Number: [•]Assets: | |||
| N/A | Assets: N/A | Assets: $[•] | ||||
| Michael P. Maurer | Number: None | Number: [•] | Number: [•] | |||
| Assets: N/A | Assets: $[•] million | Assets: $[•] million | ||||
| Michael Schloss | Number: None | Number: None | Number: [•] | |||
| Assets: N/A | Assets: N/A | Assets: $[•] million | ||||
| Matthew C. Stephani | Number: None | Number: None | Number: None | |||
| Assets: N/A | Assets: N/A | Assets: N/A | ||||
| Thomas W. Verdel | Number: None | Number: None | Number: [•] | |||
| Assets: N/A | Assets: N/A | Assets: $[•] billion | ||||
| Keaton Hoppe | Number: None | Number: None | Number: [•] | |||
| Assets: N/A | Assets: N/A | Assets: $[•] billion | ||||
| Chase McLean | Number: -- | Number: -- | Number: -- | |||
| Assets: -- | Assets: -- | Assets: -- |
53
| PORTFOLIO MANAGER | OTHER
REGISTERED INVESTMENT COMPANIES |
OTHER
POOLED INVESTMENT VEHICLES |
OTHER ACCOUNTS | |||
| Leslie Martin | Number: -- | Number: -- | Number: -- | |||
| Assets: -- | Assets: -- | Assets: -- | ||||
| Benjamin C. Wolthuizen | Number: -- | Number: -- | Number: -- | |||
| Assets: -- | Assets: -- | Assets: -- | ||||
| Scott Phillips | Number: None | Number: [•] | Number: [•] | |||
| Assets: N/A | Assets: $[•] million | Assets: $[•] million | ||||
| Jacob Johnson | Number: None | Number: None | Number: [•] | |||
| Assets: N/A | Assets: N/A | Assets: $[•] million | ||||
| Luis Maizel | Number: None | Number: None | Number: [•] | |||
| Assets: N/A | Assets: N/A | Assets: $[•] million | ||||
| Michael Chalker | Number: None | Number: None | Number: [•] | |||
| Assets: N/A | Assets: N/A | Assets: $[•] billion | ||||
| Mario Modiano* | Number: -- | Number: -- | Number: -- | |||
| Assets: -- | Assets: -- | Assets: -- | ||||
| Vincent H. Nguyen** | Number: -- | Number: -- | Number: -- | |||
| Assets: -- | Assets: -- | Assets: -- |
| * | No information to be reported as of August 31, 2026, because the portfolio manager joined the portfolio management team on September 1, 2026. |
| ** | No information to be reported as of August 31, 2026, because the portfolio manager joined the portfolio management team on December 28, 2026. |
As of August 31, 2025, the following portfolio managers managed the following numbers of accounts in each of the indicated categories, having the indicated total assets, with respect to which the advisory fee is based on the performance of the account.
Performance Based Advisory Fees Number of Other Accounts Managed and Assets by Account Type as of August 31, 2026:
| PORTFOLIO MANAGER | OTHER
REGISTERED INVESTMENT COMPANIES |
OTHER
POOLED INVESTMENT VEHICLES |
OTHER ACCOUNTS | |||
| Brandon R. Barnes | Number: None | Number: None | Number: None | |||
| Assets: $0 | Assets: $0 | Assets: $0 | ||||
| Michael P. Maurer | Number: None | Number: None | Number: None | |||
| Assets: $0 | Assets: $0 | Assets: $0 | ||||
| Michael Schloss | Number: None | Number: None | Number: None | |||
| Assets: $0 | Assets: $0 | Assets: $0 | ||||
| Matthew C. Stephani | Number: None | Number: None | Number: None | |||
| Assets: $0 | Assets: $0 | Assets: $0 | ||||
| Thomas W. Verdel | Number: None | Number: None | Number: None | |||
| Assets: $0 | Assets: $0 | Assets: $0 | ||||
| Keaton Hoppe | Number: None | Number: None | Number: None | |||
| Assets: $0 | Assets: $0 | Assets: $0 | ||||
| Chase McLean | Number: -- | Number: -- | Number: -- | |||
| Assets: -- | Assets: -- | Assets: -- | ||||
| Leslie Martin | Number: -- | Number: -- | Number: -- | |||
| Assets: -- | Assets: -- | Assets: -- | ||||
| Benjamin C. Wolthuizen | Number: -- | Number: -- | Number: -- | |||
| Assets: -- | Assets: -- | Assets: -- | ||||
| Scott Phillips | Number: None | Number: 3 | Number: 35 | |||
| Assets: $0 | Assets: $70.6 million | Assets: $92.5 million | ||||
| Jacob Johnson | Number: None | Number: None | Number: 39 | |||
| Assets: $0 | Assets: $0 | Assets: $109.6 million |
54
| PORTFOLIO MANAGER | OTHER REGISTERED INVESTMENT COMPANIES |
OTHER POOLED INVESTMENT VEHICLES |
OTHER ACCOUNTS | |||
| Luis Maizel | Number: None | Number: None | Number: None | |||
| Assets: $0 | Assets: $0 | Assets: $0 | ||||
| Michael Chalker | Number: None | Number: None | Number: None | |||
| Assets: $0 | Assets: $0 | Assets: $0 | ||||
| Mario Modiano* | Number: None | Number: None | Number: None | |||
| Assets: $0 | Assets: $0 | Assets: $0 | ||||
| Vincent H. Nguyen** | Number: None | Number: None | Number: None | |||
| Assets: $0 | Assets: $0 | Assets: $0 |
| * | No information to be reported as of August 31, 2026, because the portfolio manager joined the portfolio management team on September 1, 2026. |
| ** | No information to be reported as of August 31, 2026, because the portfolio manager joined the portfolio management team on December 28, 2026. |
Conflicts of Interest
From time to time, potential conflicts of interest may arise between a portfolio manager’s management of the investments of a Fund and the management of other RICs, pooled investment vehicles and other accounts (collectively, the “Managed Accounts”). The Managed Accounts might have similar investment objectives or strategies as a Fund, track the same indexes a Fund tracks or otherwise hold, purchase, or sell securities that are eligible to be held, purchased or sold by a Fund. The Managed Accounts might also have different investment objectives or strategies than a Fund.
A potential conflict of interest may arise as a result of the portfolio manager’s management of a number of accounts with varying investment guidelines. Often, an investment opportunity may be suitable for both a Fund and the Managed Accounts, but may not be available in sufficient quantities for both a Fund and the Managed Accounts to participate fully. Similarly, there may be limited opportunity to sell an investment held by a Fund and another Managed Account. Cavanal Hill Investment Management has adopted policies and procedures designed to allocate investment opportunities on a fair and equitable basis over time.
Portfolio Manager Compensation
Cavanal Hill Investment Management offers investment professionals a compensation plan which has two components: (i) base compensation, which is linked to job function, responsibilities and experience, and (ii) incentive compensation, which is a percentage of the base that varies based on investment performance. The majority of the total cash compensation is derived by the incentive compensation, which could ultimately make up more than half of the investment professional’s compensation. The incentive compensation is based on the pre-tax investment performance of investments on a calendar year basis in comparison to their respective Lipper peer group. Certain portfolio managers may receive non-cash incentives from BOKF, the parent company of Cavanal Hill Investment Management, in the form of stock options or restricted stock in connection with management responsibilities of such portfolio managers. These long-term non-cash incentives, which are used as a retention tool, facilitate long-term commitments from key investment professionals.
55
Securities Ownership
The following table discloses the dollar range of equity securities of each of the Funds beneficially owned by the portfolio managers as of August 31, 2026:
| NAME OF PORTFOLIO MANAGER | DOLLAR RANGE OF EQUITY SECURITIES IN EACH FUND | |
| Brandon R. Barnes | None | |
| Michael P. Maurer | World Energy & Power Fund: $100,001 – $500,000 | |
| Michael Schloss | None | |
| Matthew C. Stephani | World Energy & Power Fund: $50,001 – 100,000 | |
| Thomas W. Verdel | None | |
| Keaton Hoppe | None | |
| Chase McLean | -- | |
| Leslie Martin | -- | |
| Benjamin Wolthuizen | -- |
56
| NAME OF PORTFOLIO MANAGER | DOLLAR RANGE OF EQUITY SECURITIES IN EACH FUND | |
| Scott Phillips | Hedged Equity Income Fund: $100,001 – 500,000 | |
| Jacob Johnson | None | |
| Luis Maizel | None | |
| Michael Chalker | None | |
| Mario Modiano* | -- | |
| Vincent H. Nguyen** | -- |
| * | No information to be reported as of August 31, 2026, because the portfolio manager joined the portfolio management team on September 1, 2026. |
| ** | No information to be reported as of August 31, 2026, because the portfolio manager joined the portfolio management team on December 28, 2026. |
Shares of the Funds are sold on a continuous basis by the Distributor for the Funds. Under the Distribution Plan, the Class A, Investor Class and Administrative Class of Shares of each of the Funds will pay a monthly distribution fee to the Distributor as compensation for its services in connection with the Distribution Plan at an annual rate equal to 0.25% of its average daily net assets. Under the Distribution Plan, the Premier Class and the Class C Shares of each of the Funds will pay a monthly distribution fee to the Distributor as compensation for its services in connection with the Distribution Plan. The annual rate for Premier Class Shares is equal to 0.50% of its average daily net assets and the annual rate for C Class Shares is equal to 1.00% of its average daily net assets (0.75% in asset-based sales charge and 0.25% in 12b-1 service fee). The Distributor may use the distribution fee to provide distribution assistance with respect to the Funds’ Shares or to provide Shareholder services to the holders of the Funds’ Shares. The Distributor may also use the distribution fee (i) to pay financial institutions and intermediaries (such as insurance companies and investment counselors, but not including banks), broker-dealers, and the Distributor’s affiliates and subsidiaries compensation for services or reimbursement of expenses incurred in connection with distribution assistance or (ii) to compensate banks, other financial institutions and intermediaries, broker-dealers, and the Distributor’s affiliates and subsidiaries for services or reimbursement of expenses incurred in connection with the provision of Shareholder services. All payments by the Distributor for distribution assistance or Shareholder services under the Distribution Plan will be made pursuant to an agreement between the Distributor and such bank, other financial institution or intermediary, broker-dealer, or affiliate or subsidiary of the Distributor (a “Servicing Agreement”). A Servicing Agreement will relate to the provision of distribution assistance in connection with the distribution of the Funds’ Shares to the Participating Organization’s customers on whose behalf the investment in such Shares is made and/or to the provision of Shareholder services rendered to the Participating Organization’s customers owning the Funds’ Shares. Under the Distribution Plan, a Participating Organization may include the Adviser or its affiliates. A Servicing Agreement entered into with a bank (or any of its subsidiaries or affiliates) will contain a representation that the bank (or subsidiary or affiliate) believes that it possesses the legal authority to perform the services contemplated by the Servicing Agreement without violation of applicable banking laws.
The distribution fee will be payable without regard to whether the amount of the fee is more or less than the actual expenses incurred in a particular year by the Distributor in connection with distribution assistance or Shareholder services rendered by the Distributor itself or incurred by the Distributor pursuant to the Servicing Agreements entered into under the Distribution Plan. If the amount of the distribution fee is less than the Distributor’s actual expenses incurred in a particular year, the Distributor will realize a loss in that year under the Distribution Plan and will not recover from the Funds the excess of expenses for the year over the distribution fee, unless actual expenses incurred in a later year in which the Distribution Plan remains in effect were less than the distribution fee paid in that later year. The Distributor may periodically waive all or a portion of the distribution fee to increase the net income attributable to a Fund available for distribution as dividends to the Fund’s Shareholders. To lower operating expenses, the Distributor may voluntarily reduce its fees under the Distribution Plan.
57
The Distributor has contractually agreed to the fee waivers shown in the table below. Contractual waivers are in place for the period through December 31, 2027, and may only be terminated or modified with the approval of the Board.
| Distribution Fee | Distribution Fee Waivers | |
| Bond and Equity Funds | ||
| Class A Shares | 0.25% | No Waiver |
| Class C Shares | 1.00% | No Waiver |
| Investor Shares | 0.25% | No Waiver |
| Institutional Shares | 0.00% | N/A – No 12b-1 Fee |
| Money Market Funds | ||
| Administrative | 0.25% | No Waiver |
| Institutional | 0.00% | N/A – No 12b-1 Fee |
| Select | 0.00% | N/A – No 12b-1 Fee |
| Premier | 0.50% | No Waiver |
The Adviser and the Distributor (and their affiliates) may finance, from their own resources, certain activities intended to result in the distribution and servicing of a Fund’s shares. These amounts may be in addition to amounts paid by the Funds under the Distribution and Shareholder Servicing Plan and may include payments to the Funds’ Adviser and its affiliates for such activities.
CHD became the Distributor of the Funds on January 1, 2017 and received the following amounts for the fiscal years ended:*
| AUGUST 31, 2026 | AUGUST 31, 2025 | AUGUST 31, 2024 | ||||||||||||||||||||||
| GROSS FEES | AMOUNT WAIVED/ REIMBURSED | GROSS
FEES | AMOUNT WAIVED/ REIMBURSED | GROSS FEES | AMOUNT WAIVED/ REIMBURSED | |||||||||||||||||||
| U.S. Treasury Fund | $ | [•] | $ | — | $ | 3,791,488 | $ | — | $ | 3,985,431 | $ | — | ||||||||||||
| Government Securities Money Market Fund | $ | [•] | $ | — | $ | 4,462,636 | $ | — | $ | 4,072,694 | $ | — | ||||||||||||
| Limited Duration Fund | $ | [•] | $ | — | $ | 13,119 | $ | — | $ | 9,314 | $ | — | ||||||||||||
| Bond Fund | $ | [•] | $ | — | $ | 1,915 | $ | — | $ | 2,456 | $ | — | ||||||||||||
| Strategic Enhanced Yield Fund | $ | [•] | $ | — | $ | 3,053 | $ | — | $ | 726 | $ | — | ||||||||||||
| World Energy & Power Fund | $ | [•] | $ | — | $ | 136,056 | $ | — | $ | 124,846 | $ | — | ||||||||||||
| Hedged Equity Income Fund | $ | [•] | $ | — | $ | 3,339 | $ | — | $ | 2,371 | $ | — | ||||||||||||
* The Industrial Frontier Fund had not commenced operations as of August 31, 2026.
The entire amount received by CHD under the Distribution Plan during the period from September 1, 2025, until August 31, 2026, was spent on compensation to dealers.
The Trust on behalf of each of the Funds has approved a Shareholder Servicing Plan that enables the Funds to obtain the services of one or more shareholder servicing agents (“Shareholder Servicing Agents”) under shareholder servicing agreements. Under the agreements, the Shareholder Servicing Agents will be responsible for performing shareholder account, administrative and servicing functions, which may include but are not limited to, establishing and maintaining records of shareholders accounts; processing purchase and redemption transactions; confirming shareholder transactions; answering routine shareholder inquiries regarding the Funds; providing assistance to shareholders in effecting changes to their dividend options, account designations and addresses; withholding taxes on non-resident alien accounts; disbursing income dividends and capital gains distributions; reinvesting dividends and distributions; arranging for bank wires; preparing and delivering to shareholders, and state and federal authorities including the IRS, such information respecting dividends and distributions paid by the Funds as may be required by law, rule or regulation; withholding on dividends and distributions as may be required by state or federal authorities from time to time; and such other services as the Funds may reasonably request. The Funds have entered into agreements under the Shareholder Servicing Plan with BOKF, the owner of the Adviser, BOKFS, a broker-dealer affiliate, and may enter into agreements with other banks that are affiliates of BOKF, to provide shareholder services to the Funds’ shareholders in exchange for payments by the Fund for such services under the Shareholder Servicing Plan.
58
Each of the Funds may pay the Shareholder Servicing Agents an annual fee of up to 0.25% of the average daily net assets of the shares of each of the Funds, other than the A Shares of the Bond and Equity Funds, for which a fee of 0.10% of the daily net assets is available. BOKF and BOKFS have agreed to the contractual fee waivers shown in the table below for Shareholder Servicing Fees to which they are entitled. The BOKF and BOKFS waivers result in a reduction of the Shareholder Servicing fee paid by all purchasers of a class to the extent shown in the Annual Fund Operating Expense table. Contractual waivers are in place for the period through December 31, 2027, and may only be modified with the approval of the Board.
| Shareholder Servicing Fee | Shareholder
Servicing Fee Waivers | |
| Bond and Equity Funds | ||
| Class A Shares | 0.10% | Waived in Full |
| Class C Shares | 0.25% | Waived in Full |
| Investor Shares | 0.25% | Waived in Full |
| Institutional Shares | 0.25% | Waived in Full |
| Money Market Funds | ||
| Administrative | 0.25% | No Waiver |
| Institutional | 0.25% | 0.17% Waived |
| Select | 0.25% | Waived in Full |
| Premier | 0.25% | Waived in Full |
The table below sets forth the total Shareholder Servicing Fees paid by the shares of each Fund for fiscal years ended:*
| AUGUST 31, 2026 | AUGUST 31, 2025 | AUGUST 31, 2024 | |||||||||||||||||||||
| GROSS FEES | AMOUNT WAIVED/ REIMBURSED | GROSS
FEES | AMOUNT WAIVED/ REIMBURSED | GROSS
FEES | AMOUNT WAIVED/ REIMBURSED | ||||||||||||||||||
| U.S. Treasury Fund | [•] | [•] | $ | 4,415,066 | $ | 441,741 | $ | 4,477,195 | $ | 339,702 | |||||||||||||
| Government Securities Money Market Fund | [•] | [•] | $ | 7,505,422 | $ | 5,551,365 | $ | 6,609,236 | $ | 4,917,468 | |||||||||||||
| Limited Duration Fund | [•] | [•] | $ | 76,139 | $ | 74,228 | $ | 76,881 | $ | 70,388 | |||||||||||||
| Bond Fund | [•] | [•] | $ | 292,225 | $ | 290,942 | $ | 299,926 | $ | 299,417 | |||||||||||||
| Strategic Enhanced Yield Fund | [•] | [•] | $ | 49,822 | $ | 47,178 | $ | 17,199 | $ | 15,732 | |||||||||||||
| World Energy & Power Fund | [•] | [•] | $ | 267,579 | $ | 190,464 | $ | 219,129 | $ | 155,117 | |||||||||||||
| Hedged Equity Income Fund | [•] | [•] | $ | 66,657 | $ | 56,898 | $ | 71,456 | $ | 71,358 | |||||||||||||
* The Industrial Frontier Fund had not commenced operations as of August 31, 2026.
Should further legislative, judicial or administrative action prohibit or restrict the activities of the Adviser, BOKF, their affiliates, or BOKF’s correspondent banks in connection with customer purchases of Shares of the Trust, any or all such entities might be required to alter materially or discontinue the services offered by them. It is not anticipated, however, that any change in the Trust’s method of operations would affect its NAV per Share or result in financial losses to any customer.
Pursuant to the Investment Advisory Agreement, subject to the general supervision of the Board and in accordance with each Fund’s investment objective, policies and restrictions, the Adviser determines which securities are to be purchased and sold by each such Fund and which brokers are to be eligible to execute its portfolio transactions. Purchases and sales of portfolio securities with respect to the Bond Funds and Money Market Funds usually are principal transactions in which portfolio securities are purchased directly from the issuer or from an underwriter or market maker for the securities. Purchases from underwriters of portfolio securities include a commission or concession paid by the issuer to the underwriter and purchases from dealers serving as market makers may include the spread between the bid and asked price. Transactions with respect to the Equity Funds on stock exchanges (other than certain foreign stock exchanges) involve the payment of negotiated brokerage commissions. Transactions in the over-the-counter market are generally principal transactions with dealers. With respect to the over-the-counter market, the Funds, where possible, will deal directly with the dealers who make a market in the securities involved except in those circumstances where better price and execution are available elsewhere. While the Adviser generally seeks competitive spreads or commissions, the Funds may not necessarily pay the lowest spread or commission available on each transaction, for reasons discussed below.
59
During the fiscal year ended August 31, 2026, the Funds paid aggregate brokerage commissions as follows:
| World Energy & Power Fund | $ | [•] | ||
| Hedged Equity Income Fund | $ | [•] |
During the fiscal year ended August 31, 2025, the Funds paid aggregate brokerage commissions as follows:
| World Energy & Power Fund | $ | 306,689 | ||
| Hedged Equity Income Fund | $ | 16,563 |
During the fiscal year ended August 31, 2024, the Funds paid aggregate brokerage commissions as follows:
| World Energy & Power Fund | $ | 287,430 | ||
| Hedged Equity Income Fund | $ | 26,537 |
The following table sets forth the value of securities owned by each of the Funds that were issued by a “regular” broker or dealer (or the parent company of a regular broker or dealer), as of August 31, 2026.*
| Fund | Regular Broker or Dealer (or Parent) Issuer | Value of Securities | |
| U.S. Treasury Fund | Bank of Montreal | $ | [•] |
| Bank of New York Mellon | $ | [•] | |
| Credit Agricole CIB | $ | [•] | |
| Federal Reserve Bank NY | $ | [•] | |
| First American Treasury Obligations Fund | $ | [•] | |
| Goldman Sachs & Co. | $ | [•] | |
| Nomura Holdings, Inc. | $ | [•] | |
| Northern Trust Corp. | $ | [•] | |
| RBC Dominion Securities, Inc. | $ | [•] | |
| State Street Bank & Trust Co. | $ | [•] | |
| Government Securities Money Market Fund | Bank of Montreal | $ | [•] |
| Bank of New York Mellon | $ | [•] | |
| Credit Agricole CIB | $ | [•] | |
| Federal Reserve Bank NY | $ | [•] | |
| First American Treasury Obligations Fund | $ | [•] | |
| Goldman Sachs & Co. | $ | [•] | |
| Nomura Holdings, Inc. | $ | [•] | |
| Northern Trust Corp. | $ | [•] | |
| RBC Dominion Securities, Inc. | $ | [•] | |
| State Street Bank & Trust Co. | $ | [•] | |
| Limited Duration Fund | Bank of America | $ | [•] |
| JPMorgan Mortgage Trust | $ | [•] | |
| Wells Fargo Securities, LLC | $ | [•] | |
| Bond Fund | Bank of America | $ | [•] |
| JPMorgan Chase & Co. | $ | [•] | |
| Morgan Stanley & Co, LLC | $ | [•] | |
| Nomura Holdings, Inc. | $ | [•] | |
| Strategic Enhanced Yield Fund | Goldman Sachs & Co. | $ | [•] |
| Morgan Stanley & Co, LLC. | $ | [•] | |
| Wells Fargo Securities, LLC | $ | [•] | |
| Hedged Equity Income Fund | JPMorgan Chase & Co. | $ | [•] |
* The Industrial Frontier Fund had not commenced operations as of August 31, 2026.
60
Allocation of transactions, including their frequency, to various dealers is determined by the Adviser with respect to the Funds it serves based on its best judgment and in a manner deemed fair and reasonable to Shareholders. The primary consideration is prompt execution of orders in an effective manner at the most favorable price. Subject to this consideration, dealers who provide supplemental investment research to the Adviser may receive orders for transactions by the Funds. Information so received is in addition to and not in lieu of services required to be performed by the Adviser and does not reduce the advisory fees payable to the Adviser. Such information may be useful to the Adviser in serving both the Funds and other clients and, conversely, supplemental information obtained by the placement of business of other clients may be useful to such adviser in carrying out its obligations to the Funds.
The Funds will not execute portfolio transactions through, acquire portfolio securities issued by, make savings deposits in, or enter into repurchase or reverse repurchase agreements with the Adviser, the Distributor, or their affiliates except as may be permitted under the 1940 Act, and will not give preference to correspondents of an Adviser with respect to such transactions, securities, savings deposits, repurchase agreements, and reverse repurchase agreements.
Investment decisions for each Fund are made independently from those for the other Funds or any other investment company, trust fund or account managed by the Adviser. Any such other investment company or account may also invest in the same securities as the Funds. When a purchase or sale of the same security is made at substantially the same time on behalf of a given Fund and another Fund, investment company, trust fund or account, the transaction will be averaged as to price, and available investments allocated as to amount, in a manner which the Adviser believes to be equitable to the Fund(s) and such other investment company or account. In some instances, this investment procedure may adversely affect the price paid or received by a Fund or the size of the position obtained by a Fund. To the extent permitted by law, the Adviser may aggregate the securities to be sold or purchased by it for a Fund with those to be sold or purchased by it for other Funds or for other investment companies, trust funds or accounts in order to obtain best execution. As provided by the Investment Advisory Agreement, in making investment recommendations for the Funds, the Adviser will not inquire or take into consideration whether an issuer of securities proposed for purchase or sale by the Funds is a customer of the Adviser or their respective parents or subsidiaries or affiliates unless legally required to do so and, in dealing with its commercial customers, the Adviser and their respective parents, subsidiaries, and affiliates will not inquire or take into consideration whether securities of such customers are held by the Funds.
ALLOCATION OF INITIAL PUBLIC OFFERINGS
Opportunities to invest in initial public offerings (“IPOs”) will be allocated to the Bond and Equity Funds in a fair and equitable manner pursuant to the following procedures. It is the policy of the Funds to participate in IPOs when deemed appropriate by the Adviser. The Adviser considers the suitability of the new holding for a particular strategy and the eligibility of the particular Fund. When an opportunity to participate in an IPO has been identified, the investment personnel of Cavanal Hill Investment Management will conduct an analysis to determine which strategies Cavanal Hill Investment Management manages, including which Funds, would benefit from the addition of the IPO to their portfolios. This analysis will take into account each Fund’s investment objective, policies and limitations. Also considered will be each Fund’s liquidity and present portfolio, including risk/reward characteristics. When Cavanal Hill Investment Management investment personnel determine that an IPO opportunity is suitable for more than one strategy, the initial allocation among strategies, including the Funds, is determined by the Adviser based on a number of factors such as investment goals, current holdings, available cash, portfolio restrictions and the judgment of portfolio managers. Because the initial allocation is based on various factors, rather than strict mathematical formulas, allocation of any specific IPO offering may not result in proportional allocation across all strategies. Where the opportunity is determined to be suitable and desirable for only one Fund, the opportunity will be allocated solely to that Fund. The availability of opportunities to invest in IPOs is highly dependent on market conditions. Investing in IPOs may significantly affect the performance of a Fund.
Because an IPO is an equity security that is new to the public market, the value of IPOs may fluctuate dramatically. Therefore, IPOs have greater risks than other equity investments. Because of the cyclical nature of the IPO market, from time to time there may be limited or no IPOs in which a Fund can participate. Even when a Fund requests to participate in an IPO, there is no guarantee that a Fund will receive an allotment of shares in an IPO sufficient to satisfy a Fund’s desired participation. Due to the volatility of IPOs, these investments can have a significant impact on performance, which may be positive or negative.
61
Cavanal Hill Investment Management serves as administrator (the “Administrator”) of each Fund pursuant to the Administration Agreement (the “Administration Agreement”), between the Trust and the Administrator. The Administrator assists in supervising all operations of each Fund.
Under the Administration Agreement, the Administrator, directly or with the assistance of other service providers, has agreed to provide the Trust with regulatory reporting, to maintain office facilities for the Funds, to calculate contractual Trust expenses and control disbursements, to maintain the Funds’ financial accounts and records, and to furnish the Funds statistical and research data, data processing, clerical, accounting, and bookkeeping services, and certain other services required by the Funds. The Administrator supervises the preparation of annual and semi-annual reports to the SEC, coordinates and supervises the preparation and filing of federal and state tax returns, prepares filings with state securities commissions, and generally assists in all aspects of the Funds’ operations other than those performed under the Investment Advisory, Custodian, Fund Accounting, and Transfer Agency Agreements. Under the Administration Agreement, the Administrator may delegate all or any part of its responsibilities thereunder.
The Administrator receives a fee from each Fund for its services provided and expenses assumed pursuant to the Administration Agreement, calculated daily and paid monthly. Effective September 1, 2015, the fee was reduced from the annual rate of twenty one hundredths of one percent (0.20%) to eight one hundredths of one percent (0.08%) of each Bond and Equity Fund’s average daily net assets and from twelve one hundredths of one percent (0.12%) to five one hundredths of one percent (0.05%) of each Money Market Fund’s average daily net assets. The Administrator may periodically set its fees at less than the maximum allowable amount with respect to any Fund in order to increase the net income of one or more of the Funds available for distribution as dividends.
The following fees were paid to the Administrator by the Funds for management and administrative services for the fiscal years ended:*
| AUGUST 31, 2026 | AUGUST 31, 2025 | AUGUST 31, 2024 | ||||||||||||||||||||||
| GROSS FEES | AMOUNT WAIVED/ REIMBURSED | GROSS FEES | AMOUNT WAIVED/ REIMBURSED | GROSS FEES | AMOUNT WAIVED/ REIMBURSED | |||||||||||||||||||
| U.S. Treasury Fund | [•] | $ | [•] | $ | 883,013 | $ | — | $ | 895,445 | $ | — | |||||||||||||
| Government Securities Money Market Fund | [•] | [•] | $ | 1,501,084 | $ | — | $ | 1,321,857 | $ | — | ||||||||||||||
| Limited Duration Fund | [•] | [•] | $ | 25,134 | $ | 737 | $ | 25,669 | $ | 507 | ||||||||||||||
| Bond Fund | [•] | [•] | $ | 93,539 | $ | 978 | $ | 96,004 | $ | 1,073 | ||||||||||||||
| Strategic Enhanced Yield Fund | [•] | [•] | $ | 16,000 | $ | 219 | $ | 5,563 | $ | 96 | ||||||||||||||
| World Energy & Power Fund | [•] | [•] | $ | 87,911 | $ | 783 | $ | 71,382 | $ | 463 | ||||||||||||||
| Hedged Equity Income Fund | $ | 21,853 | $ | 218 | $ | 23,268 | $ | 359 | $ | 23,268 | $ | 359 | ||||||||||||
* The Industrial Frontier Fund had not commenced operations as of August 31, 2026.
The Administration Agreement provides that the Administrator shall not be liable for any error of judgment or mistake of law or any loss suffered by the Funds in connection with the matters to which the Agreement relates, except a loss resulting from willful misfeasance, bad faith, or gross negligence in the performance of its duties, or from the reckless disregard by it of its obligations and duties thereunder.
Citi Fund Services Ohio, Inc. (“Citi Fund Services”) serves as Sub-Administrator to the Funds pursuant to an agreement between Cavanal Hill Investment Management and Citi Fund Services and performs certain administrative duties for the Trust. The fees paid to Citi Fund Services by the Adviser for such services come out of the Adviser’s administration fees and are not an additional charge to the Funds.
62
The Adviser pays Citi Fund Services the following annual fees:
| Regulatory Administration Fee | $100,000 in the aggregate for all Funds |
| Financial Statements | $15,000 per Fund |
| Expense Payments | $7,500 per Fund |
| Tax Services | $7,500 per Fund |
| Portfolio Compliance (no manual processes) | |
| First 5 Funds | $3,000 per Fund |
| Each Additional Fund | $2,500 per Fund |
| Form N-PORT | $14,000 per Fund |
| Sleeve Fee | $1,000 per sleeve |
| Liquidity Risk Management | $3,000 per Fund |
| Tailored Shareholder Reporting (“TSR”) | $1,500 per TSR produced |
| Rule 18f-4 Support | |
| Standard Service | $5,000 per Fund |
| Life Service | $1,500 per Fund |
| Money Market Fund Reporting | $5,000 per Money Market Fund |
| Typesetting Fees | $1,500 per Fund |
Under the Sub-Administration Agreement, the Adviser also pays out-of-pocket expenses and has the option to obtain optional services, including corporate tax and performance reporting services for specified fees.
The following fees were paid, after waivers, to the Sub-Administrator for the fiscal years ended:*
| AUGUST 31, 2026 | AUGUST 31, 2025 | AUGUST 31, 2024 | ||||||||||
| U.S. Treasury Fund | $ | [•] | $ | 167,442 | $ | 248,657 | ||||||
| Government Securities Money Market Fund | $ | [•] | $ | 285,325 | $ | 367,172 | ||||||
| Limited Duration Fund | $ | [•] | $ | 2,977 | $ | 4,459 | ||||||
| Bond Fund | $ | [•] | $ | 11,096 | $ | 16,680 | ||||||
| Strategic Enhanced Yield Fund | $ | [•] | $ | 1,908 | $ | 953 | ||||||
| World Energy & Power Fund | $ | [•] | $ | 10,449 | $ | 12,395 | ||||||
| Hedged Equity Income Fund | $ | [•] | $ | 2,590 | $ | 4,049 | ||||||
* The Industrial Frontier Fund had not commenced operations as of August 31, 2026.
PINE ADVISORS LLC
Pursuant to the PINE Agreement, which became effective July 31, 2024, the Funds pay PINE, located at 501 S Cherry Street, Ste 610, Denver, CO 80246, to perform certain services including making employees available to serve as the Funds’ Chief Compliance Officer and Anti-Money Laundering Compliance Officer (“CCO/AMLCO”) and the Principal Financial and Accounting Officer (“PFAO”). The Funds also pay out-of-pocket expenses and have the option to obtain optional services from PINE. For the period September 1, 2025, through August 31, 2026, the Funds paid PINE $[•] for CCO/AMLCO and PFAO services under the PINE Agreement.
CHD serves as Distributor of each of the Funds pursuant to a Distribution Agreement with the Funds effective January 1, 2017, replacing BOKFS in such capacity. CHD is a subsidiary of BOK Financial and an affiliate of Cavanal Hill Investment Management, the Funds’ Adviser and Administrator, and BOKF, the Funds’ Custodian. CHD is located at One Williams Center, 15th Floor, Bank of Oklahoma Tower, Tulsa, Oklahoma, 74172. Information regarding distribution services and compensation is provided in the section titled, “Distribution.”
63
CUSTODIAN, TRANSFER AGENT, FUND ACCOUNTANT AND COMPLIANCE SERVICES
Cash and securities owned by each of the Funds are held by BOKF as Custodian. BOKF’s principal business address is One Williams Center, Plaza SE, Bank of Oklahoma Tower, Tulsa, Oklahoma, 74172. Under the Custodian Agreement, BOKF (i) maintains a separate account or accounts in the name of each Fund; (ii) makes receipts and disbursements of money on behalf of each Fund; (iii) collects and receives all income and other payments and distributions on account of the Funds’ portfolio securities; (iv) responds to correspondence from security brokers and others relating to its duties; and (v) makes periodic reports to the Board concerning the Funds’ operations. BOKF may, at its own expense, open and maintain a sub-custody account or accounts on behalf of the Funds, provided that it shall remain liable for the performance of all of its duties under the Custodian Agreement.
Under the Custodian Agreement, the Funds have agreed to pay BOKF a custodian fee with respect to each Fund at an annual rate of one one-hundredths of one percent (0.01%) of such Fund’s average daily net assets. BOKF is also entitled to be reimbursed by the Funds for its reasonable out-of-pocket expenses incurred in the performance of its duties under the Custodian Agreement. BOKF may periodically set its custodian fees at less than the maximum allowable amount with respect to a Fund to increase the Fund’s net income available for distribution as dividends. BOKF is a subsidiary of BOK Financial and an affiliate of Cavanal Hill Investment Management, the Funds’ Adviser and Administrator, and CHD, the Funds’ Distributor.
Effective March 15, 2016, FIS began serving as transfer agent to each of the Funds pursuant to a Transfer Agency Agreement with the Funds that was assigned to FIS’s predecessor by Citi Fund Services, with the Administrator’s consent. Under the Transfer Agency Agreement, FIS has agreed: (i) to issue and redeem Shares of the Funds; (ii) to address and mail all communications by the Funds to its Shareholders, including reports to Shareholders, dividend and distribution notices, and proxy material for its meetings of Shareholders; (iii) to respond to correspondence or inquiries by Shareholders and others relating to its duties; (iv) to maintain Shareholder accounts and certain sub-accounts; and (v) to make periodic reports to the Board concerning the Funds’ operations. FIS Investor Services LLC is located at 4249 Easton Way, Suite 400, Columbus, OH 43219.
Under its Transfer Agency Agreement with the Trust, FIS receives an annual fee of $15,000 for each Class of the Funds (by CUSIP) and annual fees per account, including: $18 for Non-NSCC accounts, $11 for NSCC accounts, and $2 for closed accounts. FIS charges a monthly Profile II Services fee of $72 for each Class of the Funds (by CUSIP). FIS is also entitled to receive an annual per account fee of $15 for each IRA account. FIS is entitled to be reimbursed for out-of-pocket expenses in providing services under the Transfer Agency Agreement.
Citi Fund Services serves as fund accountant for each Fund pursuant to a Fund Accounting and Compliance Services Agreement with the Trust.
As fund accountant for the Funds, Citi Fund Services prices the Funds’ Shares, calculates the Funds’ NAV, and maintains the general ledger accounting records for each Fund.
For accounting services, the Funds pay Citi Fund Services an annual fee based on the average daily net assets of the Trust as follows:
| Assets | Rate | |||
| $0 to $2 Billion | 0.0225 | % | ||
| $2 to $4 Billion | 0.0150 | % | ||
| Over $4 Billion | 0.0100 | % | ||
In addition, there is a $60,909.86 annual minimum fee applicable to each of the Funds and those Funds that are subject to fair value determinations pay an additional $6,090.99-$9,136.48 annually. There are also certain fees relating to security pricing and System and Organization Controls (SOC) reporting services.
Citi Fund Services is also entitled to be reimbursed for out-of-pocket expenses in providing services under the Fund Accounting and Compliance Services Agreement. Citi Fund Services may periodically set its fund accounting fees at less than the maximum allowable amount with respect to a Fund in order to increase the Fund’s net income available for distribution as dividends.
64
PAYMENTS TO BOKF (AND ITS AFFILIATES)
The following is a summary of payments made to BOKF (and its affiliates) for the Cavanal Hill Funds for the fiscal year ended August 31, 2026:
Payments to BOKF (and its affiliates)
| Investment Adviser | Administrator | Custodian | Shareholder Servicing Fees | 12b-1 Fees | ||||||||||||||||
| Payments | $ | [•] | $ | [•] | $ | [•] | $ | [•] | $ | [•] | ||||||||||
| Waivers | $ | [•] | $ | [•] | $ | [•] | $ | [•] | $ | [•] | ||||||||||
| Net Payments (Reimbursements) | $ | [•] | $ | [•] | $ | [•] | $ | [•] | $ | [•] | ||||||||||
None.
INDEPENDENT REGISTERED PUBLIC ACCOUNTING FIRM
KPMG LLP, 191 W. Nationwide Blvd., Suite 500, Columbus, Ohio 43215, serves as independent registered public accountants for the Trust. KPMG LLP provides financial auditing services as well as certain tax return preparation services for the Trust.
Frederic Dorwart, Lawyers, PLLC 124 E. Fourth Street, Tulsa, Oklahoma 74103 are counsel to the Trust.
65
Each Fund is a separate series of a Massachusetts business trust which was organized on October 1, 1987, and began active operations in August of 1990. The Declaration of Trust was filed with the Secretary of State of the Commonwealth of Massachusetts on October 2, 1987 and authorizes the Board to issue an unlimited number of Shares, which are units of beneficial interest, with par value of $0.00001. The Trust currently comprises eight series of Shares, each Series represents interests in a Fund. The Trust offers Class A, Investor Class and Institutional Class Shares for the Limited Duration Fund, the Bond Fund, the Strategic Enhanced Yield Fund, the World Energy & Power Fund, the Industrial Frontier Fund, and the Hedged Equity Income Fund. The Trust offers Administrative Class, Institutional Class, Select and Premier Class Shares for the U.S. Treasury Fund and the Government Securities Money Market Fund. The Trust also offers Class C Shares for the Equity Funds. The Declaration of Trust authorizes the Board to divide or redivide any unissued Shares of the Trust into one or more additional series by setting or changing in any one or more respects their respective preferences, conversion or other rights, voting power, restrictions, limitations as to dividends, qualifications, and terms and conditions of redemption.
Shares have no subscription or preemptive rights and only such conversion or exchange rights as the Board may grant in its discretion. When issued for payment as described in the Prospectus and this SAI, the Trust’s Shares will be fully paid and non-assessable. In the event of a liquidation or dissolution of the Trust, Shareholders of a Fund are entitled to receive the assets available for distribution belonging to the Fund, and a proportionate distribution, based upon the relative asset values of the respective series of the Trust, of any general assets not belonging to any particular Fund which are available for distribution.
Rule 18f-2 under the 1940 Act provides that any matter required to be submitted to the holders of the outstanding voting securities of an investment company such as the Trust shall not be deemed to have been effectively acted upon unless approved by the holders of a majority of the outstanding Shares of each Fund affected by the matter. For purposes of determining whether the approval of a majority of the outstanding Shares of a Fund will be required in connection with a matter, a Fund will be deemed to be affected by a matter unless it is clear that the interests of each Fund in the matter are identical (in which case the Shareholders of the Funds will vote in the aggregate), or that the matter does not affect any interest of the Fund (in which case no vote by the Shareholders of the Fund in question will be required). Under Rule 18f-2, the approval of an investment advisory agreement or any change in investment policy would be effectively acted upon with respect to a Fund only if approved by a majority of the outstanding Shares of such Fund. Rule 18f-2, however, also provides that the ratification of independent public accountants, the approval of principal underwriting contracts, and the election of Trustees may be effectively acted upon by Shareholders of the Trust voting without regard to series.
SHAREHOLDER AND TRUSTEE LIABILITY
Under Massachusetts law, holders of units of beneficial interest in a business trust may, under certain circumstances, be held personally liable as partners for the obligations of the Trust. The Declaration of Trust provides, however, that Shareholders shall not be subject to any personal liability for the obligations of the Funds, and that every written agreement, obligation, instrument, or undertaking made by the Funds shall contain a provision to the effect that the Shareholders are not personally liable thereunder. The Declaration of Trust provides for indemnification out of the trust property of any Shareholder held personally liable solely by reason of his being or having been a Shareholder. The Declaration of Trust also provides that the Funds shall, upon request, assume the defense of any claim made against any Shareholder for any act or obligation of the Funds, and shall satisfy any judgment thereon. Thus, the risk of a Shareholder incurring financial loss on account of Shareholder liability is limited to circumstances in which the Funds themselves would be unable to meet their obligations.
The Declaration of Trust states further that no Trustee, officer, or agent of the Funds shall be personally liable in connection with the administration or preservation of the assets of the Trust or the conduct of the Funds’ business; nor shall any Trustee, officer, or agent be personally liable to any person for any action or failure to act except for his own bad faith, willful misfeasance, gross negligence, or reckless disregard of his duties. The Declaration of Trust also provides that all persons having any claim against the Trustees or the Funds shall look solely to the assets of the Trust for payment.
66
The Funds are not required to hold a meeting of Shareholders for the purpose of electing Trustees, except in circumstances where less than a majority of the Trustees holding office have been elected by Shareholders. Trustees may not, without Shareholder approval, appoint one or more Trustees if, following such appointment, less than two-thirds of the Trustees holding office have been elected by the Shareholders. In addition, the Funds have undertaken to hold a meeting of Shareholders for the purpose of voting upon the question of removal of any Trustee or Trustees when requested by the holders of Shares representing not less than 10% of the outstanding Shares of the Trust. A removal proposal at such a meeting would succeed if supported by the vote of the holders of (i) 67% or more of the Shares present at the meeting, if the holders of more than 50% of the outstanding Shares of the Trust are present or represented by proxy; or (ii) 50% of the outstanding Shares of the Trust, whichever is less. The Trust’s Declaration of Trust provides that any action to be taken at a shareholder meeting may also be effected by a written consent. All actions with respect to the election and removal of Trustees are subject to the requirements of the 1940 Act and rules and regulations thereunder. Except as set forth above, the Trustees may continue to hold office and may appoint successor Trustees.
The Trust is registered with the SEC as a management investment company. Such registration does not involve supervision by the SEC of the management or policies of the Trust.
The Prospectus and this SAI omit certain of the information contained in the Registration Statement filed with the SEC. Copies of such information may be obtained from the SEC’s website at http://www.sec.gov or from the SEC upon payment of the prescribed fee.
The Prospectus and this SAI are not an offering of the securities herein described in any state or other jurisdiction in which such offering may not lawfully be made. No salesman, dealer, or other person is authorized to give any information or make any representation other than those contained in the Prospectus and SAI.
A principal shareholder is any person who owns of record or beneficially 5% or more of the outstanding shares of a Fund. A control person is one who owns beneficially or through controlled companies more than 25% of the voting securities of a company or acknowledges the existence of control. Shareholders with a controlling interest could affect the outcome of voting or the direction of management of the Funds. Further, a withdrawal of the investment of a control person could adversely affect the Funds.
67
As of December 1, 2026, BOKF, NA (Bank of Oklahoma Tower, One Williams Center, Tulsa, Oklahoma 74102-2300) and its bank affiliates were the Shareholder of record of:
[To Be Added by Amendment]
| Premier Shares | 0.00 | |||
| Select Shares | 91.93 |
68
As of December 1, 2026, BOKF, NA and its bank affiliates possessed, on behalf of its underlying accounts, voting or investment power with respect to:
[To Be Added by Amendment]
69
As of December 1, 2026, the Trustees and Officers of the Funds, as a group, owned less than one percent of the Shares of each of the Funds.
The following table indicates each person known by the Funds to own beneficially five percent (5%) or more of the Shares of the Funds as of December 1, 2026:
[To Be Added by Amendment]
70
The Report of the Independent Registered Public Accounting Firm, Financial Highlights, and Financial Statements included in the Cavanal Hill Funds’ Annual Report filed as part of the Form N-CSR for the fiscal year ended August 31, 2026, are incorporated by reference into this SAI. A copy of Form N-CSR, including the Annual Report for the fiscal year ended as of August 31, 2026, may be obtained without charge by contacting the Distributor, Cavanal Hill Distributors, Inc. at One Williams Center, 15th Floor, Bank of Oklahoma Tower, Tulsa, Oklahoma, 74172, or by telephoning toll-free at 1-800-762-7085.
71
The nationally recognized statistical rating organizations (individually, an “NRSRO”) that may be utilized by the Funds with regard to portfolio investments for the Funds include Moody’s Investors Service, Inc. (“Moody’s”), Standard & Poor’s Corporation Rating Services (“S&P”), Fitch, Inc. (“Fitch”), Morningstar, Kroll, and Dominion Bond Rating Service. Set forth below is a description of the relevant ratings of each NRSRO. The NRSROs that may be utilized by the Funds and the description of each NRSRO’s ratings is as of the date of this SAI, and may subsequently change.
LONG-TERM DEBT RATINGS (may be assigned, for example, to corporate and municipal bonds)
Description of the Moody’s long-term debt ratings (Moody’s applies numerical modifiers (1, 2, and 3) to each rating classification to indicate the security’s ranking within the category. The modifier “1” indicates that the obligation ranks in the higher end of its generic rating category; the modifier “2” indicates a mid-range ranking; and the modifier “3” indicates a ranking in the lower end of that generic rating category.):
| Aaa | Obligations rated “Aaa” are judged to be of the highest quality, subject to the lowest level of credit risk. |
| Aa | Obligations rated “Aa” are judged to be of high quality and are subject to very low credit risk. |
| A | Obligations rated “A” are judged upper-medium grade and are subject to low credit risk. |
| Baa | Obligations rated “Baa” are judged to be medium-grade and subject to moderate credit risk and as such may possess certain speculative characteristics. |
| Ba | Obligations rated “Ba” are judged to be speculative and are subject to substantial credit risk. |
| B | Obligations rated “B” are considered speculative and are subject to high credit risk. |
| Caa | Obligations rated Caa are judged to be speculative of poor standing and are subject to very high credit risk. |
| Ca | Obligations rated Ca are highly speculative and are likely in, or very near, default, with some prospect of recovery of principal and interest. |
| C | Obligations rated C are the lowest rated and are typically in default, with little prospect for recovery of principal or interest. |
Description of the S&P long-term debt ratings (S&P may apply a plus (+) or minus (-) to a particular rating classification to show relative standing within that classification):
| AAA | An obligation rated “AAA” has the highest rating assigned by S&P. The obligor’s capacity to meet its financial commitment on the obligation is extremely strong. |
| AA | An obligation rated “AA” differs from the highest rated obligations only to a small degree. The obligor’s capacity to meet its financial commitment on the obligation is very strong. |
| A | An obligation rated “A” is somewhat more susceptible to the adverse effects of changes in circumstances and economic conditions than obligations in higher rated categories. However, the obligor’s capacity to meet its financial commitment on the obligation is still strong. |
| BBB | An obligation rated “BBB” exhibits adequate protection parameters. However, adverse economic conditions or changing circumstances are more likely to lead to a weakened capacity of the obligor to meet its financial commitment on the obligation. |
| BB | An obligation rated ‘BB’ is less vulnerable to nonpayment than other speculative issues. However, it faces major ongoing uncertainties or exposure to adverse business, financial, or economic conditions which could lead to the obligor’s inadequate capacity to meet its financial commitment on the obligation. |
| B | An obligation rated “B” is more vulnerable to adverse business, financial and economic conditions but currently has the capacity to meet financial commitments. |
72
| CCC | An obligation rated “CCC” is currently vulnerable and dependent on favorable business, financial and economic conditions to meet financial commitments. |
| CC | An obligation rated “CC” is currently highly vulnerable. |
| C | An obligation rated “C” is subject to currently highly vulnerable obligations and other defined circumstances. |
| D | An obligation rated “D” is subject to payment default on financial commitments. |
Description of the Fitch international long-term credit ratings (Fitch may apply a plus (+) or minus (-) sign to a rating to denote relative status within major rating categories. Such suffixes are not added to the “AAA” rating category.):
| AAA | Highest credit quality. “AAA” ratings denote the lowest expectation of credit risk. They are assigned only in case of exceptionally strong capacity for payment of financial commitments. This capacity is highly unlikely to be adversely affected by foreseeable events. |
| AA | Very high credit quality. “AA” ratings denote expectation of very low credit risk. They indicate very strong capacity for payment of financial commitments. This capacity is not significantly vulnerable to foreseeable events. |
| A | High credit quality. “A” ratings denote a low expectation of credit risk. The capacity for payment of financial commitments is considered strong. This capacity may, nevertheless, be more vulnerable to changes in circumstances or in economic conditions than is the case for higher ratings. |
| BBB | Good credit quality. ‘BBB’ ratings indicate that expectations of default risk are currently low. The capacity for payment of financial commitments is considered adequate but adverse business or economic conditions are more likely to impair this capacity. |
| BB | Speculative. ‘BB’ ratings indicate an elevated vulnerability to default risk, particularly in the event of adverse changes in business or economic conditions over time; however, business or financial flexibility exists which supports the servicing of financial commitments. |
| B | Highly speculative. ‘B’ ratings indicate that material default risk is present, but a limited margin of safety remains. Financial commitments are currently being met; however, capacity for continued payment is vulnerable to deterioration in the business and economic environment. |
| CCC | Substantial credit risk. Default is a real possibility. |
| CC | Very high levels of credit risk. Default of some kind appears probable. |
| C | Exceptionally high levels of credit risk. Default is imminent or inevitable, or the issuer is in standstill. |
| RD | Restricted default. ‘RD’ ratings indicate an issuer that in Fitch Ratings’ opinion has experienced an uncured payment default on a bond, loan or other material financial obligation but which has not entered into bankruptcy filings, administration, receivership, liquidation or other formal winding-up procedure, and which has not otherwise ceased operating. |
| D | Default. ‘D’ ratings indicate an issuer that in Fitch Ratings’ opinion has entered into bankruptcy filings, administration, receivership, liquidation or other formal winding-up procedure, or which has otherwise ceased business. |
Description of the Morningstar corporate credit ratings (Morningstar may apply a plus (+) or minus (-) sign to a rating to denote relative strength within rating categories. Such suffixes are not added to the “AAA” rating category.):
| AAA | A rating of AAA is the highest letter-grade rating assigned by Morningstar. A rating of AAA indicates an extremely strong ability to make timely interest and principal payments. |
| AA | A rating of AA indicates a very strong ability to make timely interest and principal payments. |
| A | A rating of A indicates a strong ability to make timely interest and principal payments, but adverse changes in circumstances or conditions, such as adverse business or economic conditions, could influence that ability. |
73
| BBB | A rating of BBB indicates the ability to make timely payments of interest and principal on or prior to a rated final distribution date, but adverse changes in circumstances or conditions, such as adverse business or economic conditions, could affect that ability. |
| BB | A rating of BB indicates the ability to make timely payments of interest and principal in the absence of various adverse circumstances or conditions such as adverse business or economic conditions. The vulnerability of securities rated BB to the previously mentioned conditions is greater than that of higher-rated issuers or securities. |
| B | A rating of B indicates a default has not yet occurred but the issuer or securities are vulnerable to challenging changes in environment, conditions, or circumstances. Issuers or securities rated B are more vulnerable to nonpayment of timely interest and principal than higher-rated issuers or securities. |
| CCC | A rating of CCC indicates a material likelihood of default and significant dependence on favorable business conditions to avoid default or capital restructuring. Forecast or actual losses may erode but have not yet eliminated available credit support. |
| CC | A rating of CC indicates a default has not yet occurred but the issuer or security is extremely dependent on favorable business conditions to avoid default or significant capital restructuring. |
| C | A rating of C indicates a default is expected in the very near term. Corporate issuers or securities will be rated C and placed on Watch Negative during a cure period for payments of interest and principal. |
| SD | A rating of SD indicates a selective default when an issuer has defaulted on one or more but not all of its debt obligations without entering bankruptcy. |
| D | A rating of D indicates that a default has occurred. |
Description of the Kroll long-term credit ratings (Kroll may apply a plus (+) or minus (-) sign to a rating to denote relative status within major rating categories. Such suffixes are not added to the “AAA” rating category.):
| AAA | Determined to have almost no risk of loss due to credit-related events. Assigned only to the very highest quality obligors and obligations able to survive extremely challenging economic events. |
| AA | Determined to have minimal risk of loss due to credit-related events. Such obligors and obligations are deemed very high quality. |
| A | Determined to be of high quality with a small risk of loss due to credit-related events. Issuers and obligations in this category are expected to weather difficult times with low credit losses. |
| BB | Determined to be of medium quality with some risk of loss due to credit-related events. Such issuers and obligations may experience credit losses during stress environments. |
| BB | Determined to be of low quality with moderate risk of loss due to credit-related events. Such issuers and obligations have fundamental weaknesses that create moderate credit risk. |
| B | Determined to be of very low quality with high risk of loss due to credit-related events. These issuers and obligations contain many fundamental shortcomings that create significant credit risk. |
| CC | Determined to be at substantial risk of loss due to credit-related events, or currently in default with high recovery expectations. CC Determined to be near default or in default with average recovery expectations. |
| C | Determined to be near default or in default with low recovery expectations. |
| D | KBRA defines default as occurring if: |
| 1. | There is a missed interest or principal payment on a rated obligation which is unlikely to be recovered. | |
| 2. | The rated entity files for protection from creditors, is placed into receivership or is closed by regulators such that a missed payment is likely to result. |
The rated entity seeks and completes a distressed exchange, where existing rated obligations are replaced by new obligations with a diminished economic value.
74
Description of the Dominion Bond Rating Service long-term credit ratings (Dominion may apply a plus (+) or minus (-) sign to a rating to denote relative status within major rating categories. Such suffixes are not added to the “AAA” rating category.):
| AAA | Highest credit quality. The capacity for the payment of financial obligations is exceptionally high and unlikely to be adversely affected by future events. |
| AA | Superior credit quality. The capacity for the payment of financial obligations is considered high. Credit quality differs from AAA only to a small degree. Unlikely to be significantly vulnerable to future events. |
| A | Good credit quality. The capacity for the payment of financial obligations is substantial, but of lesser credit quality than AA. May be vulnerable to future events, but qualifying negative factors are considered manageable. |
| BBB | Adequate credit quality. The capacity for the payment of financial obligations is considered acceptable. May be vulnerable to future events. |
| BB | Speculative, non-investment grade credit quality. The capacity for the payment of financial obligations is uncertain. Vulnerable to future events. |
| B | Highly speculative credit quality. There is a high level of uncertainty as to the capacity to meet financial obligations. |
| CCC/CC/C | Very highly speculative credit quality. In danger of defaulting on financial obligations. There is little difference between these three categories, although CC and C ratings are normally applied to obligations that are seen as highly likely to default, or subordinated to obligations rated in the CCC to B range. Obligations in respect of which default has not technically taken place but is considered inevitable may be rated in the C category. |
| D | When the issuer has filed under any applicable bankruptcy, insolvency or winding up statute or there is a failure to satisfy an obligation after the exhaustion of grace periods, a downgrade to D may occur. DBRS may also use SD (Selective Default) in cases where only some securities are impacted, such as the case of a “distressed exchange”. See Default Definition for more information. |
SHORT-TERM DEBT RATINGS (may be assigned, for example, to commercial paper, master demand notes, bank instruments, and letters of credit)
Moody’s description of its short-term debt ratings:
P-1 Issuers (or supporting institutions) rated Prime-1 have a superior ability to repay short-term debt obligations.
P-2 Issuers (or supporting institutions) rated Prime-2 have a strong ability to repay short-term debt obligations.
P-3 Issuers (or supporting institutions) rated Prime-3 have an acceptable ability to repay of short-term obligations.
NP Issuers (or supporting institutions) rated Not Prime do not fall within any of the Prime rating categories.
S&P’s description of its short-term issue credit ratings:
| A-1 | A short-term obligation rated “A-1” is rated in the highest category by S&P. The obligor’s capacity to meet its financial commitment on the obligation is strong. Within this category, certain obligations are designated with a plus sign (+). This indicates that the obligor’s capacity to meet its financial commitment on these obligations is extremely strong. |
| A-2 | A short-term obligation rated “A-2” is somewhat more susceptible to the adverse effects of changes in circumstances and economic conditions than obligations in higher rating categories. However, the obligor’s capacity to meet its financial commitment on the obligation is satisfactory. |
| A-3 | A short-term obligation rated “A-3” exhibits adequate protection parameters. However, adverse economic conditions or changing circumstances are more likely to lead to a weakened capacity of the obligor to meet its financial commitment on the obligation. |
75
| B | A short-term obligation rated “B” is regarded as having significant speculative characteristics. Ratings of “B-1”, “B-2”, and “B-3” may be assigned to indicate finer distinctions within the “B” category. The obligor currently has the capacity to meet its financial commitment on the obligation; however, it faces major ongoing uncertainties which could lead to the obligor’s inadequate capacity to meet its financial commitment on the obligation. |
| C | A short-term obligation rated “C” is currently vulnerable to nonpayment and is dependent upon favorable business, financial, and economic conditions for the obligor to meet its financial commitment on the obligation. |
| D | A short-term obligation rated “D” is in payment default. |
Description of the four highest international short-term credit ratings by Fitch (Fitch may apply a plus (+), or minus (-) sign to a rating to denote relative status within major rating categories. Such suffixes are not added to short-term ratings other than “F1”.):
| F1 | Highest credit quality. Indicates the strongest capacity for timely payment of financial commitments; may have an added “+” to denote any exceptionally strong credit feature. |
| F2 | Good credit quality. A satisfactory capacity for timely payment of financial commitments, but the margin of safety is not as great as in the case of the higher ratings. |
| F3 | Fair credit quality. The capacity for timely payment of financial commitments is adequate; however, near-term adverse changes could result in a reduction to non-investment grade. |
| B | Speculative. Minimal capacity for timely payment of financial commitments, plus vulnerability to near term adverse changes in financial and economic conditions. |
Description of the four highest short-term credit ratings by Kroll (Kroll may apply a plus (+), or minus (-) sign to a rating to denote relative status within major rating categories. Such suffixes are not added to short-term ratings other than “F1”.):
| K1 | Very strong ability to meet short-term obligations. |
| K2 | Strong ability to meet short-term obligations. |
| K3 | Adequate ability to meet short-term obligations. |
| B | Questionable ability to meet short-term obligations. |
| C | Little ability to meet short-term obligations. |
| D | KBRA defines default as occurring if: |
| 1. | There is a missed interest or principal payment on a rated obligation which is unlikely to be recovered. | |
| 2. | The rated entity files for protection from creditors, is placed into receivership or is closed by regulators such that a missed payment is likely to result. | |
| 3. | The rated entity seeks and completes a distressed exchange, where existing rated obligations are replaced by new obligations with a diminished economic value. |
76
Description of the four highest short-term credit ratings by Dominion Bond Rating Service (Dominion may apply a plus (+), or minus (-) sign to a rating to denote relative status within major rating categories. Such suffixes are not added to short-term ratings other than “F1”.):
| R-1 (high) | Highest credit quality. The capacity for the payment of short-term financial obligations as they fall due is exceptionally high. Unlikely to be adversely affected by future events. |
| R-1 (mid) | Superior credit quality. The capacity for the payment of short-term financial obligations as they fall due is very high. Differs from R-1 (high) by a relatively modest degree. Unlikely to be significantly vulnerable to future events. |
| R-1 (low) | Good credit quality. The capacity for the payment of short-term financial obligations as they fall due is substantial. Overall strength is not as favorable as higher rating categories. May be vulnerable to future events, but qualifying negative factors are considered manageable. |
| R-2 (high) | Upper end of adequate credit quality. The capacity for the payment of short-term financial obligations as they fall due is acceptable. May be vulnerable to future events. |
| R-2 (mid) | Adequate credit quality. The capacity for the payment of short-term financial obligations as they fall due is acceptable. May be vulnerable to future events or may be exposed to other factors that could reduce credit quality. |
| R-2 (low) | Lower end of adequate credit quality. The capacity for the payment of short-term financial obligations as they fall due is acceptable. May be vulnerable to future events. A number of challenges are present that could affect the issuer’s ability to meet such obligations. |
| R-3 | Lowest end of adequate credit quality. There is a capacity for the payment of short-term financial obligations as they fall due. May be vulnerable to future events and the certainty of meeting such obligations could be impacted by a variety of developments. |
| R-4 | Speculative credit quality. The capacity for the payment of short-term financial obligations as they fall due is uncertain. |
| R-5 | Highly speculative credit quality. There is a high level of uncertainty as to the capacity to meet short-term financial obligations as they fall due. |
| D | When the issuer has filed under any applicable bankruptcy, insolvency or winding up statute or there is a failure to satisfy an obligation after the exhaustion of grace periods, a downgrade to D may occur. DBRS may also use SD (Selective Default) in cases where only some securities are impacted, such as the case of a “distressed exchange”. See Default Definition for more information. |
SHORT-TERM LOAN/MUNICIPAL NOTE RATINGS
Moody’s description of its two highest US Municipal short-term debt and demand obligations ratings:
MIG 1 This designation denotes superior credit quality. Excellent protection is afforded by established cash flows, highly reliable liquidity support, or demonstrated broad-based access to the market for refinancing.
MIG 2 This designation denotes strong credit quality. Margins of protection are ample, though not as large as in the preceding group.
VMIG 1 This designation denotes superior credit quality. Excellent protection is afforded by the superior short-term credit strength of the liquidity provider and structural and legal protections that ensure the timely payment of purchase price upon demand.
VMIG 2 This designation denotes strong credit quality. Good protection is afforded by the strong short-term credit strength of the liquidity provider and structural and legal protections that ensure the timely payment of purchase price upon demand.
77
PART C. OTHER INFORMATION
Item 28. Exhibits
C-1
C-2
| * | Incorporated by Reference |
Item 29. Persons Controlled by or under Common Control with Registrant
There are no persons controlled or under common control with the Registrant.
Item 30. Indemnification
Article VIII of Registrant’s Agreement and Declaration of Trust, filed or incorporated by reference as an Exhibit hereto, provides for the indemnification of Registrant’s trustees and officers. Indemnification of Registrant’s principal underwriter is provided for in the Agreement between Registrant and that service provider as filed or incorporated by reference as an Exhibit hereto. As of the effective date of this Registration Statement, Registrant has obtained from a major insurance carrier a trustees and officers’ liability policy covering certain types of errors and omissions. In no event will Registrant indemnify any of its trustees, officers, employees, or agents against any liability to which such person would otherwise be subject by reason of his willful misfeasance, bad faith, or gross negligence in the performance of his duties, or by reason of his reckless disregard of the duties involved in the conduct of his office or under his agreement with Registrant. Registrant will comply with Rule 484 under the Securities Act of 1933 and Release 11330 under the Investment Company Act of 1940 in connection with any indemnification.
C-3
Insofar as indemnification for liability arising under the Securities Act of 1933 may be permitted to trustees, officers, and controlling persons of Registrant pursuant to the foregoing provisions, or otherwise, Registrant has been advised that in the opinion of the Securities and Exchange Commission such indemnification is against public policy as expressed in the Act and is, therefore, unenforceable. In the event that a claim for indemnification against such liabilities (other than the payment by Registrant of expenses incurred or paid by a trustee, officer or controlling person of Registrant in the successful defense of any action, suit or proceeding) is asserted by such trustee, officer, or controlling person in connection with the securities being registered, Registrant will, unless in the opinion of its counsel the matter has been settled by controlling precedent, submit to a court of appropriate jurisdiction the question of whether such indemnification by it is against public policy as expressed in the Act and will be governed by the final adjudication of such issue.
Item 31. Business and Other Connections of Investment Adviser
Cavanal Hill Investment Management, Inc. (“Cavanal Hill Investment Management”) serves as Registrant’s investment adviser. Lavaca Capital, LLC serves as investment sub-adviser for the Hedged Equity Income Fund. LM Capital Group, LLC serves as investment sub-adviser for the Strategic Enhanced Yield Fund.
To the knowledge of Registrant, none of the directors or officers of Cavanal Hill Investment Management, Lavaca Capital, LLC, nor LM Capital Group, LLC is or has been, at any time during the past two calendar years, engaged in any other business, profession, vocation or employment of a substantial nature.
The address of Cavanal Hill Investment Management is One Williams Center, Bank of Oklahoma Tower, Tulsa, Oklahoma 74172.
The address of Lavaca Capital, LLC is 2700 Post Oak Blvd., Suite 1250, Houston, TX 77056.
The address of LM Capital Group, LLC is 750 B Street, Suite 3010, San Diego, CA 92101.
The address of Cavanal Hill Distributors, Inc. is One Williams Center, Plaza SE Bank of Oklahoma Tower, Tulsa, Oklahoma 74172.
The address of BOKF, N.A. is P.O. Box 2300, Tulsa, Oklahoma 74172.
The address of BOK Financial Corporation is One Williams Center, Bank of Oklahoma Tower, Tulsa, Oklahoma 74172.
Item 32. Principal Underwriters.
Item 32(a) Cavanal Hill Distributors, Inc., (“CHD” or the “Distributor”) acts as principal underwriter for the following investment companies: Cavanal Hill Funds.
CHD is registered with the Securities and Exchange Commission (“SEC”) as a broker-dealer and is a member of the Financial Industry Regulatory Authority. SEC registration does not imply a certain level of skill or training. CHD’s main address is One Williams Center, Plaza SE Bank of Oklahoma Tower Tulsa, OK 74172. Principal Office of Supervisory Jurisdiction (OSJ) Branch is at One Williams Center, Plaza SE Bank of Oklahoma Tower Tulsa, OK 74172. CHD is a direct wholly-owned subsidiary of BOK Financial Corporation.
Item 32(b) Information about Directors and Officers of CHD is as follows:
| Names and Address | Position with Underwriter | |
| Scott Grauer | Director | |
| Brian Henderson | Director | |
| Matthew Stephani | Director | |
| Mindy Mahaney | Director | |
| Bill King | Director, Chief Executive Officer and President | |
| Brian Quill | Chief Compliance Officer | |
| Cheryl Briggs | Secretary | |
| Craig Swanson | Financial and Operations Principal |
The address for the Directors and Officers of CHD is:
One Williams Center, 15th Floor
Bank of Oklahoma Tower
Tulsa, OK 74172
C-4
Item 32(c) Not applicable.
Item 33. Location of Accounts and Records
| (1) | Cavanal Hill Investment Management, Inc., Bank of Oklahoma Tower, Tulsa, Oklahoma 74172 (records relating to its functions as Investment Adviser and Administrator). |
| (2) | Cavanal Hill Distributors, Inc., One Williams Center, 15th Floor, Bank of Oklahoma Tower, Tulsa, OK 74172 (records relating to its functions as Distributor). |
| (3) | Citi Fund Services Ohio, Inc., 4400 Easton Commons, Suite 200, Columbus, OH 43219 (records relating to its functions as Sub-Administrator and Fund Accountant. |
| (4) | FIS Investor Services LLC, 4249 Easton Way, Suite 400, Columbus, OH 43219 (records relating to its functions as Transfer Agent). |
| (5) | BOKF, N.A., Bank of Oklahoma Tower, Tulsa, Oklahoma 74103 (records relating to its functions as Custodian). |
| (6) | Frederic Dorwart, Lawyers PLLC, 124 E. Fourth Street, Tulsa, OK 74103 (Agreement and Declaration of Trust, Bylaws and Minute Books). |
| (7) | Pine Advisors LLC, 501 S Cherry Street, Ste 610, Denver, CO 80246 (records related to CCO/AMLCO and PFAO services) |
Item 34. Management Services
N/A.
Item 35. Undertakings.
| (a) | Registrant undertakes to call a meeting of shareholders, at the request of holders of 10% of the Registrant’s outstanding shares, for the purpose of voting upon the question of removal of a trustee or trustees and undertakes to assist in communications with other shareholders as required by Section 16(c) of the Investment Company Act of 1940. |
| (b) | The Registrant undertakes to furnish to each person to whom a prospectus is delivered a copy of the Registrant’s latest annual report to shareholders upon request and without charge. |
C-5
SIGNATURES
Pursuant to the requirements of the Securities Act of 1933 (the “Securities Act”) and the Investment Company Act of 1940, the Registrant certifies that it meets all the requirements for effectiveness of this Registration Statement under Rule 485(b) under the Securities Act and has duly caused this registration statement to be signed on its behalf by the undersigned, duly authorized, in the City of Tulsa, Oklahoma on October 6, 2026.
| Cavanal Hill Funds | ||
| By: | */s/ Catherine Dunn | |
| Catherine Dunn | ||
| President | ||
Pursuant to the requirements of the Securities Act and the Investment Company Act of 1940, this Post-Effective Amendment No. 91 to the registration statement has been signed below by the following persons in the capacities and on the date(s) indicated.
| Signature | Title | Date | ||
| */s/ Catherine Dunn | President, Chief Executive Officer | October 6, 2026 | ||
| Catherine Dunn | ||||
| */s/ Jerica Newbill | Treasurer, Principal Financial & Accounting Officer | October 6, 2026 | ||
| Jerica Newbill | ||||
| */s/ William H. Wilson Jr. | Trustee | October 6, 2026 | ||
| William H. Wilson Jr. | ||||
| */s/ Jennifer Wheeler | Trustee | October 6, 2026 | ||
| Jennifer Wheeler | ||||
| */s/ Scott Grauer | Trustee | October 6, 2026 | ||
| Scott Grauer |
* By Power of Attorney
| /s/ Amy Newsome | |
| Amy Newsome | |
| Attorney in Fact, Fund Counsel |
C-6
CERTIFIED RESOLUTIONS OF BOARD OF TRUSTEES
I, Cheryl Briggs, secretary of the Cavanal Hill Funds, an open-end management investment company established in 1987 as a Massachusetts business trust, do hereby certify that the following is a true copy of resolutions adopted on July 30, 2026, at meetings of the Trustees of such investment company held in the City of Tulsa, Oklahoma, duly called in accordance with the provisions of the By-Laws of such investment company, and at which a quorum of Trustees was present:
RESOLVED, that the appropriate officers of the Trust be, and they hereby are, authorized, empowered and directed to:
| (1) | Prepare and, upon execution by a majority of the members of this Board (either directly or pursuant to powers of attorney, if any, that the members of this Board may provide the Trust’s officers or agents), file when they shall deem it timely in light of the objective set forth in (5) below one or more post-effective amendments to the Registration Statement (including the Summary Prospectuses, the Statutory Prospectus and Statements of Additional Information that form a part of such Registration Statement) to provide appropriate or required financial information with respect to the Trust and their performance for either the fiscal year that shall end August 31, 2026, and such other periods or as of such dates as may be required by applicable laws or regulations, and to make such other changes to such documents as are required by law or which such officers may determine to be necessary or appropriate to reflect any changes to the Trust since the date the Registration Statement was last declared or became effective under the Securities Act of 1933 and the Investment Company Act or as they may otherwise determine to be necessary or appropriate to provide current and prospective investors in the Trust’s securities relevant information regarding the Trust and its securities; |
| (2) | Make such further filings or provide such further reports, notices and certificates to the SEC, state securities regulators, representatives of FINRA and any other governmental or self-regulatory body as such officers may determine to be necessary or appropriate to cause the Trust to comply with any applicable legal requirements; |
| (3) | Respond to any inquiries from the SEC or any other regulator or self-regulatory organization with respect to the matters hereinbefore authorized; |
| (4) | Prepare and cause to be filed or provided to the SEC and such appropriate persons or entities such other or related reports, certificates and documents, that shall be required of the Trust under applicable legal requirements or which such officers determine to be necessary or in the best interest of the Trust to so file or provide; |
| (5) | Cause, to the extent they may do so consistent with the foregoing directives and applicable laws and regulations, the Registration Statement, as so amended pursuant to this resolution, to be declared or to become effective as of no later than December 31, 2026; and |
| (6) | Take such other actions as such officers shall determine to be necessary or appropriate to implement the purposes and intentions of this resolution, each such determination to be conclusively evidenced by the taking of any such action. |
IN WITNESS WHEREOF, I have hereto subscribed my signature this 6 day of October, 2026.
| /s/ Cheryl Briggs | |
| Cheryl Briggs | |
| Secretary |
C-7
POWER OF ATTORNEY
Catherine Dunn, whose signature appears below, does hereby constitute and appoint Tamara Sloan, Amy E. Newsome and Jacob F. Calvani, each individually, her true and lawful attorneys and agents, with power of substitution or resubstitution, to do any and all acts and things and to execute any and all instruments which said attorneys and agents, each individually, may deem necessary or advisable or which may be required to enable the Cavanal Hill Funds (the “Trust”), to comply with the Investment Company Act of 1940, as amended, and the Securities Act of 1933, as amended (“Acts”), and any rules, regulations or requirements of the Securities and Exchange Commission in respect thereof, in connection with the filing and effectiveness of any and all amendments or supplements to the Trust’s Registration Statement on Form N-1A filed with the Securities and Exchange Commission (including the Prospectuses and Statements of Additional Information that form a part of such Registration Statement) pursuant to said Acts or the filing of any periodic or current reports concerning the performance of the Trust or any portion of the Trust, including specifically, but without limiting the generality of the foregoing, the power and authority to sign in the name and on behalf of the undersigned as a trustee and/or officer of the Trust any and all such amendments, supplements or reports filed with the Securities and Exchange Commission under said Acts, and any other instruments or documents related thereto, and the undersigned does hereby ratify and confirm all that said attorneys and agents, or either of them, shall do or cause to be done by virtue thereof.
| Dated: December 4, 2025 | /s/ Catherine Dunn |
| Catherine Dunn |
C-8
POWER OF ATTORNEY
William H. Wilson Jr., whose signature appears below, does hereby constitute and appoint Tamara Sloan, Jacob F. Calvani and Amy E. Newsome, each individually, his true and lawful attorneys and agents, with power of substitution or resubstitution, to do any and all acts and things and to execute any and all instruments which said attorneys and agents, each individually, may deem necessary or advisable or which may be required to enable the Cavanal Hill Funds (the “Trust”), to comply with the Investment Company Act of 1940, as amended, and the Securities Act of 1933, as amended (“Acts”), and any rules, regulations or requirements of the Securities and Exchange Commission in respect thereof, in connection with the filing and effectiveness of any and all amendments or supplements to the Trust’s Registration Statement on Form N-1A filed with the Securities and Exchange Commission (including the Prospectuses and Statements of Additional Information that form a part of such Registration Statement) pursuant to said Acts or the filing of any periodic or current reports concerning the performance of the Trust or any portion of the Trust, including specifically, but without limiting the generality of the foregoing, the power and authority to sign in the name and on behalf of the undersigned as a trustee and/or officer of the Trust any and all such amendments, supplements or reports filed with the Securities and Exchange Commission under said Acts, and any other instruments or documents related thereto, and the undersigned does hereby ratify and confirm all that said attorneys and agents, or either of them, shall do or cause to be done by virtue thereof.
| Dated: December 5, 2025 | /s/ William H. Wilson Jr. |
| William H. Wilson Jr. |
C-9
POWER OF ATTORNEY
Jennifer Wheeler, whose signature appears below, does hereby constitute and appoint Tamara Sloan, Jacob F. Calvani and Amy E. Newsome, each individually, her true and lawful attorneys and agents, with power of substitution or resubstitution, to do any and all acts and things and to execute any and all instruments which said attorneys and agents, each individually, may deem necessary or advisable or which may be required to enable the Cavanal Hill Funds (the “Trust”), to comply with the Investment Company Act of 1940, as amended, and the Securities Act of 1933, as amended (“Acts”), and any rules, regulations or requirements of the Securities and Exchange Commission in respect thereof, in connection with the filing and effectiveness of any and all amendments or supplements to the Trust’s Registration Statement on Form N-1A filed with the Securities and Exchange Commission (including the Prospectuses and Statements of Additional Information that form a part of such Registration Statement) pursuant to said Acts or the filing of any periodic or current reports concerning the performance of the Trust or any portion of the Trust, including specifically, but without limiting the generality of the foregoing, the power and authority to sign in the name and on behalf of the undersigned as a trustee and/or officer of the Trust any and all such amendments, supplements or reports filed with the Securities and Exchange Commission under said Acts, and any other instruments or documents related thereto, and the undersigned does hereby ratify and confirm all that said attorneys and agents, or either of them, shall do or cause to be done by virtue thereof.
| Dated: December 15, 2025 | /s/ Jennifer Wheeler |
| Jennifer Wheeler |
C-10
POWER OF ATTORNEY
Scott Grauer, whose signature appears below, does hereby constitute and appoint Tamara Sloan, Jacob F. Calvani and Amy E. Newsome, each individually, his true and lawful attorneys and agents, with power of substitution or resubstitution, to do any and all acts and things and to execute any and all instruments which said attorneys and agents, each individually, may deem necessary or advisable or which may be required to enable the Cavanal Hill Funds (the “Trust”), to comply with the Investment Company Act of 1940, as amended, and the Securities Act of 1933, as amended (“Acts”), and any rules, regulations or requirements of the Securities and Exchange Commission in respect thereof, in connection with the filing and effectiveness of any and all amendments or supplements to the Trust’s Registration Statement on Form N-1A filed with the Securities and Exchange Commission (including the Prospectuses and Statements of Additional Information that form a part of such Registration Statement) pursuant to said Acts or the filing of any periodic or current reports concerning the performance of the Trust or any portion of the Trust, including specifically, but without limiting the generality of the foregoing, the power and authority to sign in the name and on behalf of the undersigned as a trustee and/or officer of the Trust any and all such amendments, supplements or reports filed with the Securities and Exchange Commission under said Acts, and any other instruments or documents related thereto, and the undersigned does hereby ratify and confirm all that said attorneys and agents, or either of them, shall do or cause to be done by virtue thereof.
| Dated: December 4, 2025 | /s/ Scott Grauer |
| Scott Grauer |
C-11
POWER OF ATTORNEY
Jerica Newbill, whose signature appears below, does hereby constitute and appoint Tamara Sloan, Jacob F. Calvani and Amy E. Newsome, each individually, her true and lawful attorneys and agents, with power of substitution or resubstitution, to do any and all acts and things and to execute any and all instruments which said attorneys and agents, each individually, may deem necessary or advisable or which may be required to enable the Cavanal Hill Funds (the “Trust”), to comply with the Investment Company Act of 1940, as amended, and the Securities Act of 1933, as amended (“Acts”), and any rules, regulations or requirements of the Securities and Exchange Commission in respect thereof, in connection with the filing and effectiveness of any and all amendments or supplements to the Trust’s Registration Statement on Form N-1A filed with the Securities and Exchange Commission (including the Prospectuses and Statements of Additional Information that form a part of such Registration Statement) pursuant to said Acts or the filing of any periodic or current reports concerning the performance of the Trust or any portion of the Trust, including specifically, but without limiting the generality of the foregoing, the power and authority to sign in the name and on behalf of the undersigned as a trustee and/or officer of the Trust any and all such amendments, supplements or reports filed with the Securities and Exchange Commission under said Acts, and any other instruments or documents related thereto, and the undersigned does hereby ratify and confirm all that said attorneys and agents, or either of them, shall do or cause to be done by virtue thereof.
| Dated: December 8, 2025 | /s/ Jerica Newbill |
| Jerica Newbill |
C-12

FREE Breaking News Alerts from StreetInsider.com!
StreetInsider.com Top Tickers, 10/6/2026
- S&P 500, Nasdaq reach record closing highs as focus pivots to earnings
- Oil prices fall nearly 2% as Middle East supply concerns ease
- U.S. 10-year yield climb revives dotcom-era parallels: UBS weighs in
- Goldman flags 2 key market risks if a climb in yields persists
- Shell CEO says Middle East oil flows reach 80% of prewar levels
Serious News for Serious Traders! Try StreetInsider.com Premium Free!
You May Also Be Interested In
- Atlantic Petroleum - Convertible Loan
- SEC Seeks Final Judgment Against Former Western Asset Co-CIO Ken Leech in Cherry Picking Case
- Bake3D Inc. Introduces AI-Powered 3D Character and Motion Engine for Games, Film and Digital Content
Create E-mail Alert Related Categories
SEC FilingsSign up for StreetInsider Free!
Receive full access to all new and archived articles, unlimited portfolio tracking, e-mail alerts, custom newswires and RSS feeds - and more!
