



Form 424B2 MORGAN STANLEY
 Tweet
 Share
 E-mail
October 2026
Preliminary Pricing Supplement No. 19,658
Registration Statement Nos. 333-293641; 333-293641-01
Dated October 26, 2026
Filed pursuant to Rule 424(b)(2)
Morgan Stanley Finance LLC
Structured Investments
Opportunities in U.S. Equities
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
Fully and Unconditionally Guaranteed by Morgan Stanley
|
■Linked to the lowest performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index (each referred to as an “underlying”) ■The securities offered are unsecured obligations of Morgan Stanley Finance LLC (“MSFL”) and are fully and unconditionally guaranteed by Morgan Stanley. The securities will pay no interest, provide for a maturity payment amount that may be significantly less than the face amount, and may be zero, and have the terms described in the accompanying product supplement for principal at risk securities, index supplement, tax supplement and prospectus, as supplemented or modified by this document. At maturity: ■If the level of the lowest performing underlying has increased, investors will receive the face amount plus a positive return equal to at least 126.50% (to be determined on the pricing date) of the percentage increase in the level of the lowest performing underlying from its starting level of the face amount ■If the level of the lowest performing underlying has decreased, but the lowest performing underlying has not decreased by more than 20%, investors will receive the face amount ■If the level of the lowest performing underlying has decreased by more than the buffer amount, investors will have 1-to-1 downside exposure to the decrease in the level of the lowest performing underlying from its starting level in excess of the buffer amount ■Investors may lose up to 80% of the face amount of the securities ■The securities are for investors who seek an equity-based return and who are willing to risk their investment, risk exposure to the lowest performing underlying and forgo current income in exchange for the participation rate and buffer features that in each case apply to a limited range of performance of the lowest performing underlying ■The securities are notes issued as part of MSFL’s Series A Global Medium-Term Notes program ■All payments are subject to our credit risk. If we default on our obligations, you could lose some or all of your investment ■These securities are not secured obligations and you will not have any security interest in, or otherwise have any access to, any securities included in any of the underlyings |
The current estimated value of the securities is approximately $948.00 per security, or within $25.00 of that estimate. The estimated value of the securities is determined using our own pricing and valuation models, market inputs and assumptions relating to the underlyings, instruments based on the underlyings, volatility and other factors including current and expected interest rates, as well as an interest rate related to our secondary market credit spread, which is the implied interest rate at which our conventional fixed rate debt trades in the secondary market. See “Estimated Value of the Securities” on page 4.
The securities have complex features and investing in the securities involves risks not associated with an investment in ordinary debt securities. See “Risk Factors” beginning on page 11. All payments on the securities are subject to our credit risk.
The Securities and Exchange Commission and state securities regulators have not approved or disapproved these securities, or determined if this document or the accompanying product supplement, index supplement, tax supplement and prospectus is truthful or complete. Any representation to the contrary is a criminal offense.
The securities are not deposits or savings accounts and are not insured by the Federal Deposit Insurance Corporation or any other governmental agency or instrumentality, nor are they obligations of, or guaranteed by, a bank.
You should read this document together with the related product supplement for principal at risk securities, index supplement, tax supplement and prospectus, each of which can be accessed via the hyperlinks below. Please also see “Additional Information About the Securities” at the end of this document.
As used in this document, “we,” “us” and “our” refer to Morgan Stanley or MSFL, or Morgan Stanley and MSFL collectively, as the context requires.
|
Commissions and offering price: |
Price to public |
Agent’s commissions(1)(2) |
Proceeds to us(3) |
|
Per security |
$1,000 |
$25.75 |
$974.25 |
|
Total |
$ |
$ |
$ |
(1) Wells Fargo Securities, LLC, an agent for this offering, will receive a commission of up to $25.75 for each security it sells. Dealers, including Wells Fargo Advisors (“WFA”), may receive a selling concession of up to $20.00 per security, and WFA will receive a distribution expense fee of $0.75 for each security sold by WFA. See “Supplemental information concerning plan of distribution; conflicts of interest.”
(2) In respect of certain securities sold in this offering, we may pay a fee of up to $3.00 per security to selected securities dealers in consideration for marketing and other services in connection with the distribution of the securities to other securities dealers.
(3) See “Use of Proceeds and Hedging” in the accompanying product supplement.
Product Supplement for Principal at Risk Securities dated April 8, 2026 Index Supplement dated April 8, 2026 Tax Supplement dated April 8, 2026 Prospectus dated April 8, 2026
Morgan Stanley Wells Fargo Securities
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
|
Terms |
||
|
Issuer: |
Morgan Stanley Finance LLC |
|
|
Guarantor: |
Morgan Stanley |
|
|
Maturity date: |
February 1, 2029†, subject to postponement if the calculation day is postponed* |
|
|
Underlyings: |
Dow Jones Industrial AverageSM (the “INDU Index”), State Street® Technology Select Sector SPDR® ETF (the “XLK Shares”) and S&P 500® Index (the “SPX Index”) The Dow Jones Industrial AverageSM and the S&P 500® Index are sometimes collectively referred to herein as the “Indices” and individually as an “Index,” and the State Street® Technology Select Sector SPDR® ETF is sometimes individually referred to herein as a “Fund.” |
|
|
Fund underlying index: |
Technology Select Sector Index |
|
|
Fund underlying index sponsor: |
S&P® Dow Jones Indices LLC, or any successor thereof |
|
|
Maturity payment amount: |
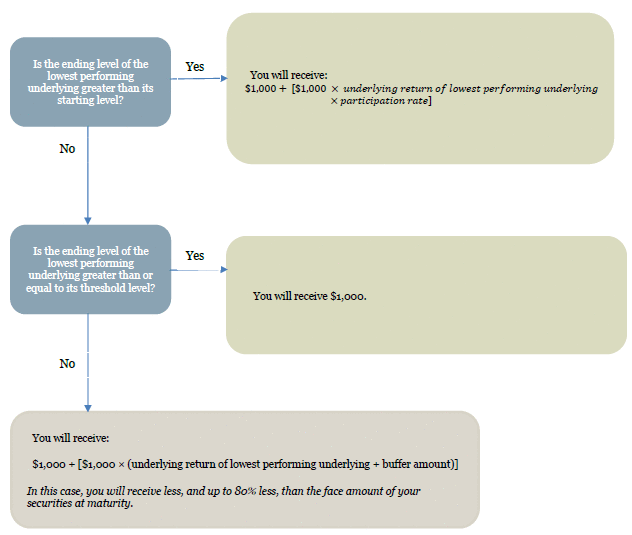
At maturity, the maturity payment amount per $1,000 face amount of securities will be determined as follows: ●If the ending level of the lowest performing underlying is greater than its starting level: ●If the ending level of the lowest performing underlying is less than or equal to its starting level, but greater than or equal to its threshold level: $1,000 If the ending level of the lowest performing underlying is less than its threshold level: $1,000 + [$1,000 × (underlying return of lowest performing underlying + buffer amount)] If the ending level of the lowest performing underlying is less than its threshold level, you will receive less, and up to 80% less, than the face amount of your securities at maturity. |
|
|
Participation rate: |
At least 126.50%, to be determined on the pricing date |
|
|
Lowest performing underlying: |
The underlying with the lowest underlying return |
|
|
Underlying return: |
With respect to each underlying, the percentage change from its starting level to its ending level, measured as follows: ending level – starting level starting level |
|
|
Starting level: |
With respect to the INDU Index: , its closing level on the pricing date. With respect to the XLK Shares: $ , its closing price on the pricing date. With respect to the SPX Index: , its closing level on the pricing date. |
|
|
Ending level: |
With respect to each of the INDU Index and the SPX Index, the closing level on the calculation day. With respect to the XLK Shares, the closing price of one XLK Share on the calculation day multiplied by the adjustment factor on such day. |
|
|
Calculation day: |
January 29, 2029**† |
|
|
Threshold level: |
With respect to the INDU Index: , which is equal to 80% of its starting level. With respect to the XLK Shares: $ , which is equal to 80% of its starting level. With respect to the SPX Index: , which is equal to 80% of its starting level. |
|
|
Buffer amount: |
20% |
|
|
Face amount: |
$1,000 per security. References in this document to a “security” are to a security with a face amount of $1,000. |
|
|
Pricing date: |
October 29, 2026† |
|
|
Original issue date: |
November 3, 2026† (3 business days after the pricing date) |
|
|
Adjustment factor: |
The “adjustment factor” means, 1.0, subject to adjustment in the event of certain events affecting the Fund. See “General Terms of the Securities—Anti-dilution Adjustments Relating to a Fund; Alternate Calculation” in the accompanying product supplement for principal at risk securities. |
|
|
CUSIP / ISIN: |
61781TKU6 / US61781TKU69 |
|
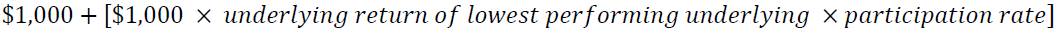
October 2026 Page 2
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
|
Listing: |
The securities will not be listed on any securities exchange. |
|
|
Agents: |
Morgan Stanley & Co. LLC (“MS & Co.”), an affiliate of MSFL and a wholly owned subsidiary of Morgan Stanley, and Wells Fargo Securities, LLC (“WFS”). See “Additional Information About the Securities—Supplemental information regarding plan of distribution; conflicts of interest.” |
|
|
† To the extent we make any change to the pricing date or original issue date, the calculation day and maturity date may also be changed in our discretion to ensure that the term of the securities remains the same. * Subject to postponement pursuant to “General Terms of the Securities—Payment Dates” in the accompanying product supplement for principal at risk securities. ** Subject to postponement pursuant to “General Terms of the Securities—Consequences of a Market Disruption Event; Postponement of a Calculation Day” in the accompanying product supplement for principal at risk securities. |
||
October 2026 Page 3
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
|
Estimated Value of the Securities |
|
The face amount of each security is $1,000. This price includes costs associated with issuing, selling, structuring and hedging the securities, which are borne by you, and, consequently, the estimated value of the securities on the pricing date will be less than $1,000 per security. We estimate that the value of each security on the pricing date will be approximately $948.00, or within $25.00 of that estimate. Our estimate of the value of the securities as determined on the pricing date will be set forth in the final pricing supplement. What goes into the estimated value on the pricing date? In valuing the securities on the pricing date, we take into account that the securities comprise both a debt component and a performance-based component linked to the underlyings. The estimated value of the securities is determined using our own pricing and valuation models, market inputs and assumptions relating to the underlyings, instruments based on the underlyings, volatility and other factors including current and expected interest rates, as well as an interest rate related to our secondary market credit spread, which is the implied interest rate at which our conventional fixed rate debt trades in the secondary market. What determines the economic terms of the securities? In determining the economic terms of the securities, including the participation rate and the threshold levels, we use an internal funding rate which is likely to be lower than our secondary market credit spreads and therefore advantageous to us. If the issuing, selling, structuring and hedging costs borne by you were lower or if the internal funding rate were higher, one or more of the economic terms of the securities would be more favorable to you. What is the relationship between the estimated value on the pricing date and the secondary market price of the securities? The price at which MS & Co. purchases the securities in the secondary market, absent changes in market conditions, including those related to the underlyings, may vary from, and be lower than, the estimated value on the pricing date, because the secondary market price takes into account our secondary market credit spread as well as the bid-offer spread that MS & Co. would charge in a secondary market transaction of this type and other factors. However, because the costs associated with issuing, selling, structuring and hedging the securities are not fully deducted upon issuance, for a period of up to 3 months following the issue date, to the extent that MS & Co. may buy or sell the securities in the secondary market, absent changes in market conditions, including those related to the underlyings, and to our secondary market credit spreads, it would do so based on values higher than the estimated value. We expect that those higher values will also be reflected in your brokerage account statements. MS & Co. may, but is not obligated to, make a market in the securities and, if it once chooses to make a market, may cease doing so at any time. |
October 2026 Page 4
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
|
Investor Considerations |
|
The Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029 (the “securities”) may be appropriate for investors who: ■Seek an alternative to direct exposure to the underlyings that enhances returns for any positive performance of the lowest performing underlying ■Seek to enhance returns and potentially outperform the lowest performing underlying by taking advantage of the participation rate with no limitation on the appreciation potential ■Understand that the ending level of the lowest performing underlying may decrease by more than the buffer amount from its starting level, resulting in a loss of some or a significant portion of the initial investment ■Desire to obtain a buffer against a specified level of negative performance in the lowest performing underlying ■Understand that the return on the securities will depend solely on the performance of the lowest performing underlying and that they will not benefit in any way from the performance of any better performing underlying ■Understand that the securities are riskier than alternative investments linked to only one of the underlyings or linked to a basket composed of each underlying ■Understand and are willing to accept the full downside risks of each underlying ■Are willing to forgo interest payments on the securities and dividends on securities included in the underlyings ■Are willing to hold the securities to maturity The securities are not designed for, and may not be an appropriate investment for, investors who: ■Seek a liquid investment or are unable or unwilling to hold the securities to maturity ■Are unwilling to accept the risk that the ending level of the lowest performing underlying may decrease by more than the buffer amount from its starting level, resulting in a loss of some or a significant portion of the initial investment ■Seek full return of the face amount of the securities at maturity ■Seek current income from their investments ■Are unwilling to accept the risk of exposure to each of the underlyings ■Seek exposure to the lowest performing underlying but are unwilling to accept the risk/return trade-offs inherent in the maturity payment amount for the securities ■Seek exposure to a basket composed of each underlying or a similar investment in which the overall return is based on a blend of the performances of the underlyings, rather than solely on the lowest performing underlying ■Are unwilling to accept our credit risk ■Prefer the lower risk of fixed income investments with comparable maturities issued by companies with comparable credit ratings |
The considerations identified above are not exhaustive. Whether or not the securities are an appropriate investment for you will depend on your individual circumstances, and you should reach an investment decision only after you and your investment, legal, tax, accounting and other advisors have carefully considered the appropriateness of an investment in the securities in light of your particular circumstances. You should also review carefully the “Risk Factors” herein and in the accompanying product supplement for risks related to an investment in the securities. For more information about the underlyings, please see the sections titled “Dow Jones Industrial AverageSM Overview,” “State Street® Technology Select Sector SPDR® ETF Overview” and “S&P 500® Index Overview” below.
October 2026 Page 5
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
|
Determining Maturity Payment Amount |
At maturity, the maturity payment amount per $1,000 face amount of securities will be determined as follows:
October 2026 Page 6
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
|
How the Securities Work |
Payoff Diagram
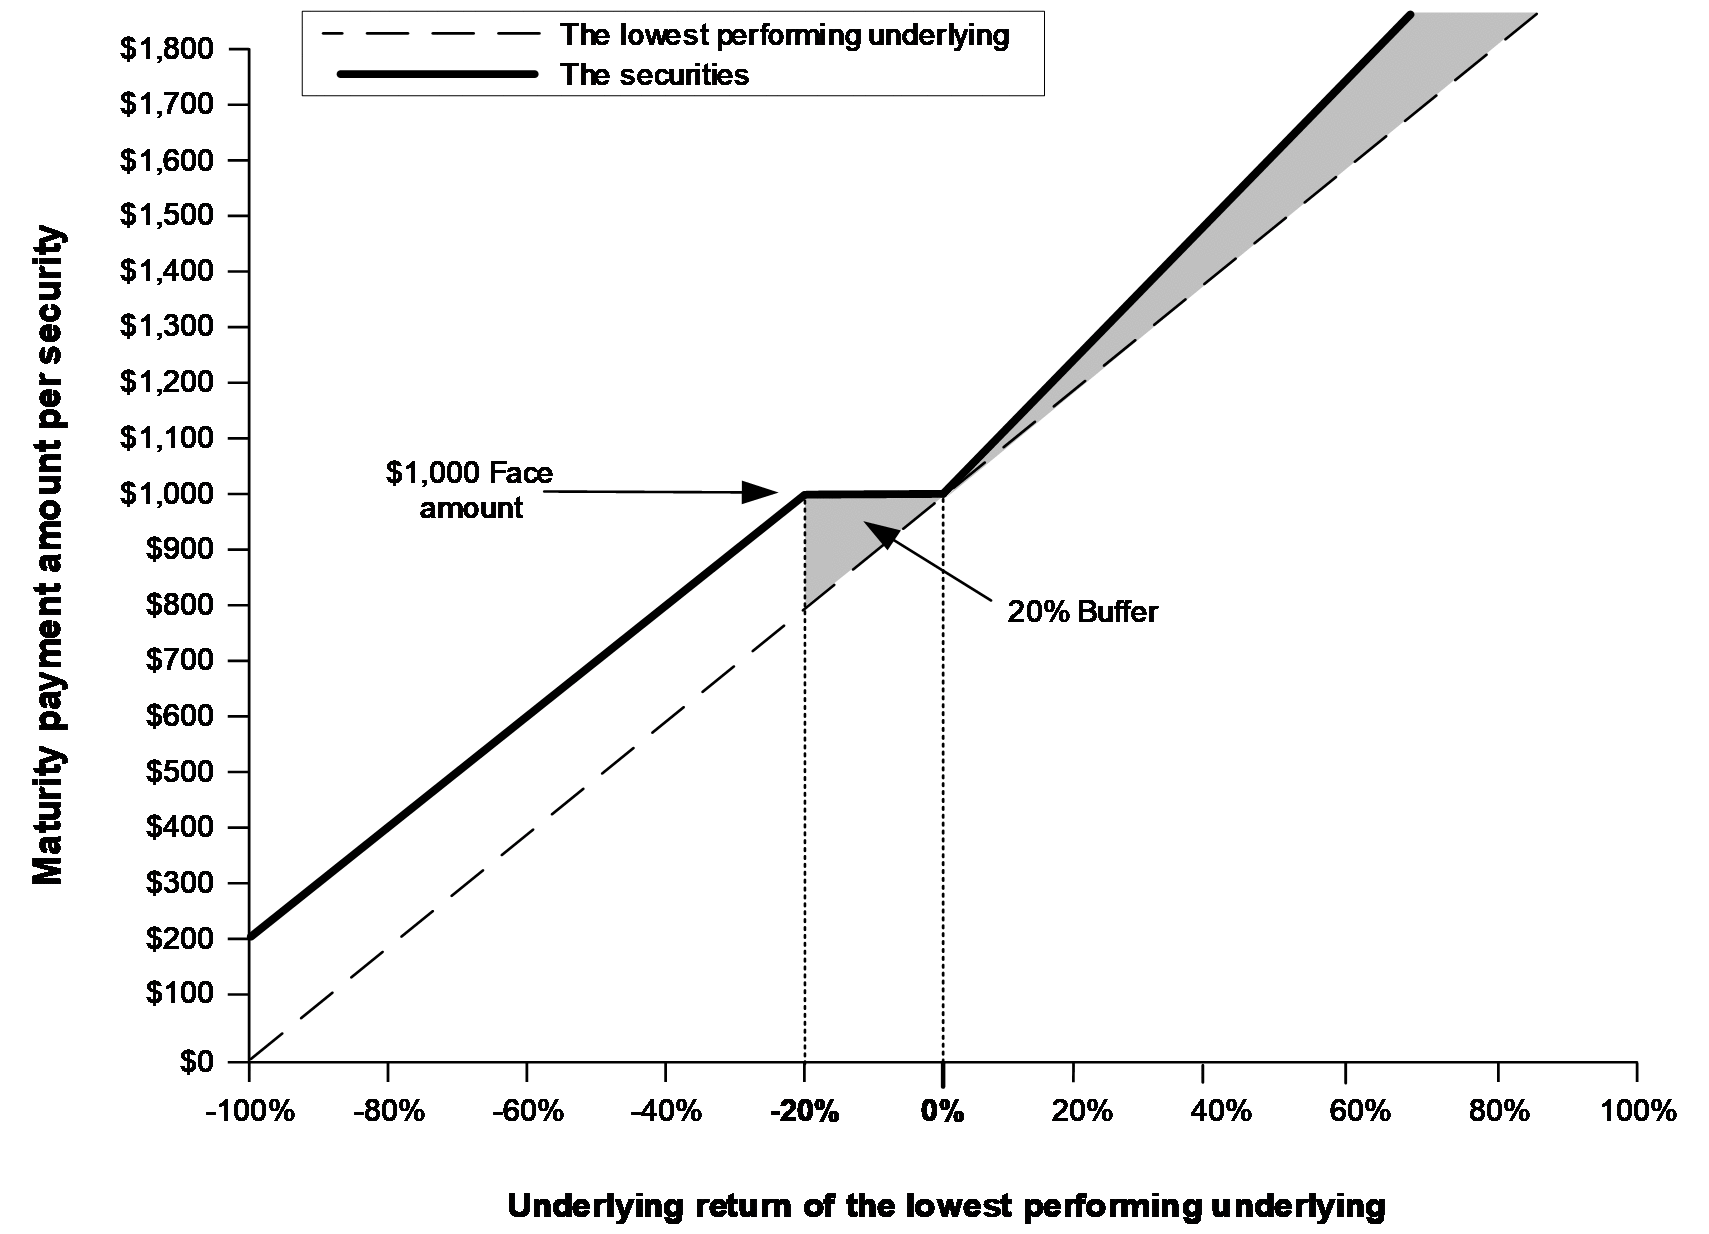
The payoff diagram below illustrates the maturity payment amount on the securities based on a range of hypothetical underlying returns of the lowest performing underlying and the following terms:
|
Face amount: |
$1,000 per security |
|
Hypothetical participation rate: |
126.50%. The actual participation rate will be determined on the pricing date. |
|
Threshold level: |
80% of its starting level |
|
Buffer amount: |
20% |
|
Securities Payoff Diagram |
|
|
October 2026 Page 7
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
|
Scenario Analysis and Examples of Maturity Payment Amount at Maturity |
The following scenario analysis and examples are provided for illustrative purposes only and are hypothetical. They do not purport to be representative of every possible scenario concerning increases or decreases in the levels of the underlyings relative to their respective starting levels. We cannot predict the ending levels of the underlyings on the calculation day. You should not take the scenario analysis and these examples as an indication or assurance of the expected performance of the underlyings. The numbers appearing in the examples below may have been rounded for ease of analysis. Notwithstanding anything to the contrary in the accompanying product supplement for principal at risk securities, the amount you will receive per $1,000 face amount of securities at maturity will be the maturity payment amount, defined and calculated as provided in this document. The following scenario analysis and examples illustrate the maturity payment amount on a hypothetical offering of the securities, based on the following terms*:
|
Investment term: |
Approximately 2.25 years |
|
Hypothetical starting level: |
With respect to the INDU Index: 100 |
|
|
With respect to the XLK Shares: $100 |
|
|
With respect to the SPX Index: 100 |
|
Hypothetical threshold level: |
With respect to the INDU Index, 80, which is 80% of its respective hypothetical starting level |
|
|
With respect to the XLK Shares, $80, which is 80% of its respective hypothetical starting level |
|
|
With respect to the SPX Index, 80, which is 80% of its respective hypothetical starting level |
|
Buffer amount: |
20% |
|
Hypothetical participation rate: |
126.50%. The actual participation rate will be determined on the pricing date. |
* The hypothetical starting level of 100 for the underlyings has been chosen for illustrative purposes only and does not represent the actual starting level of any underlying. The actual starting levels, threshold levels and participation rate will be determined on the pricing date and will be set forth under “Terms” above. For historical data regarding the actual closing levels of the underlyings, see the historical information set forth herein.
Example 1 — Each underlying appreciates over the term of the securities, and investors receive a positive return, calculated based on the underlying return of the lowest performing underlying.
|
Ending level |
|
INDU Index: 110 |
|
|
|
XLK Shares: $140 |
|
|
|
SPX Index: 150 |
|
Underlying return |
|
INDU Index: (110 – 100) / 100 = 10% XLK Shares: ($140 – $100) / $100 = 40% SPX Index: (150 – 100) / 100 = 50% |
|
Maturity payment amount |
= |
$1,000 + [$1,000 × underlying return of lowest performing underlying ×participation rate] |
|
|
= |
$1,000 + [$1,000 × 10% × 126.50%] |
|
|
= |
$1,126.50 |
In example 1, the ending level of each of the INDU Index, the XLK Shares and the SPX Index is greater than its starting level. Therefore, investors receive at maturity the face amount plus a positive return equal to 126.50% of the appreciation of the lowest performing underlying, which is the INDU Index in this example. Investors receive $1,126.50 per security at maturity (assuming a hypothetical participation rate of 126.50%). The actual participation rate will be determined on the pricing date.
October 2026 Page 8
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
Example 2 — One underlying appreciates, while the other two underlyings decline over the term of the securities but no underlying declines below the hypothetical starting level by more than the buffer amount, and investors receive the face amount.
|
Ending level |
|
INDU Index: 130 |
|
|
|
XLK Shares: $90 |
|
|
|
SPX Index: 80 |
|
Underlying return |
|
INDU Index: (130 – 100) / 100 = 30% XLK Shares: ($90 – $100) / $100 = -10% SPX Index: (80 – 100) / 100 = -20% |
|
Maturity payment amount |
= |
$1,000 |
In example 2, the ending level of the INDU Index is greater than its starting level, while the ending levels of the XLK Shares and the SPX Index are less than their respective starting levels, but are greater than or equal to their respective threshold levels. Therefore, investors receive at maturity the face amount of $1,000.
Example 3 — Two underlyings appreciate while one underlying declines over the term of the securities, and the ending level of the lowest performing underlying is less than the hypothetical starting level by more than the buffer amount. Investors are therefore exposed to the decline in the level of the lowest performing underlying in excess of the buffer amount.
|
Ending level |
|
INDU Index: 130 |
|
|
|
XLK Shares: $105 |
|
|
|
SPX Index: 30 |
|
Underlying return |
|
INDU Index: (130 – 100) / 100 = 30% XLK Shares: ($105 – $100) / $100 = 5% SPX Index: (30 – 100) / 100 = -70% |
|
Maturity payment amount |
= |
$1,000 + [$1,000 × underlying return of lowest performing underlying + buffer amount] |
|
|
= |
$1,000 + [$1,000 ×-70% + 20%] |
|
|
= |
$500 |
In example 3, the ending levels of the INDU Index and the XLK Shares are greater than their respective starting levels, while the ending level of the SPX Index has declined below its threshold level. Because the ending level of the SPX Index has declined by more than the buffer amount, investors are exposed to the negative performance of the SPX Index, which is the lowest performing underlying in this example, in excess of the buffer amount. Investors receive a maturity payment amount of $500.
Example 4 — Each underlying declines below its respective threshold level, and investors are therefore exposed to the decline in the level of the lowest performing underlying in excess of the buffer amount.
|
Ending level |
|
INDU Index: 30 |
|
|
|
XLK Shares: $45 |
|
|
|
SPX Index: 40 |
|
Underlying return |
|
INDU Index: (30 – 100) / 100 = -70% XLK Shares: ($45 – $100) / $100 = -55% SPX Index: (40 – 100) / 100 = -60% |
|
Maturity payment amount |
= |
$1,000 + [$1,000 × underlying return of lowest performing underlying + buffer amount] |
|
|
= |
$1,000 + [$1,000 ×-70% + 20%] |
|
|
= |
$500 |
In example 4, the ending level of each of the INDU Index, the XLK Shares and the SPX Index is less than its respective threshold level. Therefore, investors are exposed to the negative performance of the INDU Index, which is the lowest performing underlying in this example, in excess of the buffer amount. Investors receive a maturity payment amount of $500.
Because the maturity payment amount of the securities is based on the lowest performing underlying, a decline in any underlying below its respective threshold level will result in a loss of up to 80% of the face amount of your securities at maturity, even if the other underlyings have appreciated or have not declined as much.
October 2026 Page 9
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
Scenario Analysis – Hypothetical Maturity Payment Amount for each $1,000 Face Amount of Securities.
|
Performance of the Lowest Performing Underlying* |
Performance of the Securities(1)
|
|||
|
Ending Level |
Underlying Return |
Maturity Payment Amount |
Return on Securities(2) |
|
|
200 |
100.00% |
$2,265.00 |
126.500% |
|
|
190 |
90.00% |
$2,138.50 |
113.850% |
|
|
180 |
80.00% |
$2,012.00 |
101.200% |
|
|
170 |
70.00% |
$1,885.50 |
88.550% |
|
|
160 |
60.00% |
$1,759.00 |
75.900% |
|
|
150 |
50.00% |
$1,632.50 |
63.250% |
|
|
140 |
40.00% |
$1,506.00 |
50.600% |
|
|
130 |
30.00% |
$1,379.50 |
37.950% |
|
|
120 |
20.00% |
$1,253.00 |
25.300% |
|
|
110 |
10.00% |
$1,126.50 |
12.650% |
|
|
105 |
5.00% |
$1,063.25 |
6.325% |
|
|
100(3) |
0.00% |
$1,000.00 |
0.00% |
|
|
95 |
-5.00% |
$1,000.00 |
0.00% |
|
|
90 |
-10.00% |
$1,000.00 |
0.00% |
|
|
80 |
-20.00% |
$1,000.00 |
0.00% |
|
|
79 |
-21.00% |
$990.00 |
-1.00% |
|
|
70 |
-30.00% |
$900.00 |
-10.00% |
|
|
60 |
-40.00% |
$800.00 |
-20.00% |
|
|
50 |
-50.00% |
$700.00 |
-30.00% |
|
|
40 |
-60.00% |
$600.00 |
-40.00% |
|
|
30 |
-70.00% |
$500.00 |
-50.00% |
|
|
20 |
-80.00% |
$400.00 |
-60.00% |
|
|
10 |
-90.00% |
$300.00 |
-70.00% |
|
|
0 |
-100.00% |
$200.00 |
-80.00% |
|
*The underlyings exclude cash dividend payments on stocks included in the Indices or the fund underlying index.
(1) Assumes a participation rate of 126.50%. The actual participation rate will be determined on the pricing date.
(2) The “Return on Securities” is the number, expressed as a percentage, which results from comparing the maturity payment amount per $1,000 face amount of securities to the purchase price of $1,000 per security.
(3) The hypothetical starting level of each underlying.
October 2026 Page 10
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
|
Risk Factors |
This section describes the material risks relating to the securities. For further discussion of these and other risks, you should read the section entitled “Risk Factors” in the accompanying product supplement for principal at risk securities, index supplement, tax supplement and prospectus. We also urge you to consult your investment, legal, tax, accounting and other advisers in connection with your investment in the securities.
Risks Relating to an Investment in the Securities
■The securities do not pay interest, and you will receive less, and up to 80% less, than the face amount of your securities at maturity if the ending level of the lowest performing underlying is less than its respective threshold level. The terms of the securities differ from those of ordinary debt securities in that the securities do not pay interest or repay a fixed amount of the face amount of the securities. If the ending level of the lowest performing underlying is less than its threshold level, which is 80% of the starting level, you will receive less, and up to 80% less, than the face amount of your securities at maturity. Investors may lose some or a significant portion of their investment in the securities.
■The market price will be influenced by many unpredictable factors. Several factors, many of which are beyond our control, will influence the value of the securities in the secondary market and the price at which MS & Co. or any other dealer may be willing to purchase or sell the securities in the secondary market, including the level, volatility (frequency and magnitude of changes in level) and dividend yield of the underlyings, interest and yield rates in the market, time remaining to maturity, geopolitical conditions and economic, financial, political, regulatory or judicial events that affect the underlyings or equities markets generally and which may affect the ending levels of the underlyings, the occurrence of certain events affecting the Fund that may or may not require an adjustment to the adjustment factor and any actual or anticipated changes in our credit ratings or credit spreads. Generally, the longer the time remaining to maturity, the more the market price of the securities will be affected by the other factors described above. The levels of the underlyings may be, and have recently been, volatile, and we can give you no assurance that the volatility will lessen. See “Dow Jones Industrial AverageSM Overview,” “State Street® Technology Select Sector SPDR® ETF Overview” and “S&P 500® Index Overview” below. You may receive less, and possibly significantly less, than the face amount per security if you try to sell your securities prior to maturity.
■The securities are subject to our credit risk, and any actual or anticipated changes to our credit ratings or credit spreads may adversely affect the market value of the securities. You are dependent on our ability to pay all amounts due on the securities at maturity, and therefore you are subject to our credit risk. If we default on our obligations under the securities, your investment would be at risk and you could lose some or all of your investment. As a result, the market value of the securities prior to maturity will be affected by changes in the market’s view of our creditworthiness. Any actual or anticipated decline in our credit ratings or increase in the credit spreads charged by the market for taking our credit risk is likely to adversely affect the market value of the securities.
■As a finance subsidiary, MSFL has no independent operations and will have no independent assets. As a finance subsidiary, MSFL has no independent operations beyond the issuance and administration of its securities and will have no independent assets available for distributions to holders of MSFL securities if they make claims in respect of such securities in a bankruptcy, resolution or similar proceeding. Accordingly, any recoveries by such holders will be limited to those available under the related guarantee by Morgan Stanley and that guarantee will rank pari passu with all other unsecured, unsubordinated obligations of Morgan Stanley. Holders will have recourse only to a single claim against Morgan Stanley and its assets under the guarantee. Holders of securities issued by MSFL should accordingly assume that in any such proceedings they would not have any priority over and should be treated pari passu with the claims of other unsecured, unsubordinated creditors of Morgan Stanley, including holders of Morgan Stanley-issued securities.
■The amount payable on the securities is not linked to the values of the underlyings at any time other than the calculation day. The ending level of each underlying will be based on the closing level of such underlying on the calculation day, subject to postponement for non-trading days and certain market disruption events. Even if each
October 2026 Page 11
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
underlying appreciates prior to the calculation day but the level of any underlying decreases by the calculation day, the maturity payment amount may be less, and may be significantly less, than it would have been had the maturity payment amount been linked to the levels of the underlyings prior to such decrease. Although the actual levels of the underlyings on the maturity date or at other times during the term of the securities may be higher than their respective ending levels, the maturity payment amount will be based solely on the closing levels on the calculation day.
■Investing in the securities is not equivalent to investing in the underlyings or the stocks composing the Indices or the fund underlying index. Investing in the securities is not equivalent to investing in the underlyings or the stocks that constitute the Indices or the fund underlying index. Investors in the securities will not have voting rights or rights to receive dividends or other distributions or any other rights with respect to the stocks that constitute the Indices or the fund underlying index.
■The rate we are willing to pay for securities of this type, maturity and issuance size is likely to be lower than the rate implied by our secondary market credit spreads and advantageous to us. Both the lower rate and the inclusion of costs associated with issuing, selling, structuring and hedging the securities in the face amount reduce the economic terms of the securities, cause the estimated value of the securities to be less than the face amount and will adversely affect secondary market prices. Assuming no change in market conditions or any other relevant factors, the prices, if any, at which dealers, including MS & Co., may be willing to purchase the securities in secondary market transactions will likely be significantly lower than the face amount, because secondary market prices will exclude the issuing, selling, structuring and hedging-related costs that are included in the face amount and borne by you and because the secondary market prices will reflect our secondary market credit spreads and the bid-offer spread that any dealer would charge in a secondary market transaction of this type as well as other factors.
The inclusion of the costs of issuing, selling, structuring and hedging the securities in the face amount and the lower rate we are willing to pay as issuer make the economic terms of the securities less favorable to you than they otherwise would be.
However, because the costs associated with issuing, selling, structuring and hedging the securities are not fully deducted upon issuance, for a period of up to 3 months following the issue date, to the extent that MS & Co. may buy or sell the securities in the secondary market, absent changes in market conditions, including those related to the underlyings, and to our secondary market credit spreads, it would do so based on values higher than the estimated value, and we expect that those higher values will also be reflected in your brokerage account statements.
■The estimated value of the securities is determined by reference to our pricing and valuation models, which may differ from those of other dealers and is not a maximum or minimum secondary market price. These pricing and valuation models are proprietary and rely in part on subjective views of certain market inputs and certain assumptions about future events, which may prove to be incorrect. As a result, because there is no market-standard way to value these types of securities, our models may yield a higher estimated value of the securities than those generated by others, including other dealers in the market, if they attempted to value the securities. In addition, the estimated value on the pricing date does not represent a minimum or maximum price at which dealers, including MS & Co., would be willing to purchase your securities in the secondary market (if any exists) at any time. The value of your securities at any time after the date of this document will vary based on many factors that cannot be predicted with accuracy, including our creditworthiness and changes in market conditions. See also “The market price will be influenced by many unpredictable factors” above.
■The securities will not be listed on any securities exchange and secondary trading may be limited. The securities will not be listed on any securities exchange. Therefore, there may be little or no secondary market for the securities. MS & Co. and WFS may, but are not obligated to, make a market in the securities and, if either of them once chooses to make a market, may cease doing so at any time. When they do make a market, they will generally do so for transactions of routine secondary market size at prices based on their respective estimates of the current value of the securities, taking into account their respective bid/offer spreads, our credit spreads, market volatility, the notional size of the proposed sale, the cost of unwinding any related hedging positions, the time remaining to maturity and the
October 2026 Page 12
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
likelihood that they will be able to resell the securities. Even if there is a secondary market, it may not provide enough liquidity to allow you to trade or sell the securities easily. Since other broker-dealers may not participate significantly in the secondary market for the securities, the price at which you may be able to trade your securities is likely to depend on the price, if any, at which MS & Co. or WFS is willing to transact. If, at any time, MS & Co. and WFS were to cease making a market in the securities, it is likely that there would be no secondary market for the securities. Accordingly, you should be willing to hold your securities to maturity.
■The calculation agent, which is a subsidiary of Morgan Stanley and an affiliate of MSFL, will make determinations with respect to the securities. As calculation agent, MS & Co. will determine the starting levels, the threshold levels and the ending levels and will calculate the amount of cash you receive at maturity. Moreover, certain determinations made by MS & Co., in its capacity as calculation agent, may require it to exercise discretion and make subjective judgments, such as with respect to the occurrence or non-occurrence of market disruption events and the selection of a successor index or calculation of an ending level in the event of a market disruption event, discontinuance of any of the underlyings or certain adjustments to the adjustment factor. These potentially subjective determinations may adversely affect the payout to you at maturity. For further information regarding these types of determinations, see “General Terms of the Securities—Market Disruption Events,” “—Adjustments to an Index,” “—Discontinuance of an Index,” “—Anti-dilution Adjustments Relating to a Fund; Alternate Calculation,” “—Consequences of a Market Disruption Event; Postponement of a Calculation Day” and “Alternate Exchange Calculation in Case of an Event of Default” in the accompanying product supplement for principal at risk securities. In addition, MS & Co. has determined the estimated value of the securities on the pricing date.
■Hedging and trading activity by our affiliates could potentially adversely affect the value of the securities. One or more of our affiliates and/or third-party dealers expect to carry out hedging activities related to the securities (and possibly to other instruments linked to the underlyings or the component stocks of the Indices or fund underlying index), including trading in the shares of the Fund or the stocks that constitute the Indices or the fund underlying index as well as in other instruments related to the underlyings. As a result, these entities may be unwinding or adjusting hedge positions during the term of the securities, and the hedging strategy may involve greater and more frequent dynamic adjustments to the hedge as the calculation day approaches. Some of our affiliates also trade the shares of the Fund or the stocks that constitute the Indices or fund underlying index and other financial instruments related to the underlyings on a regular basis as part of their general broker-dealer and other businesses. Any of these hedging or trading activities on or prior to the pricing date could potentially affect the starting level of an underlying, and, therefore, could increase the level at or above which such underlying must close on the calculation day so that investors do not suffer a loss on their initial investment in the securities (depending also on the performance of the other underlyings). Additionally, such hedging or trading activities during the term of the securities, including on the calculation day, could adversely affect the level of an underlying on the calculation day, and, accordingly, the amount of cash an investor will receive at maturity (depending also on the performance of the other underlyings).
■The maturity date may be postponed if the calculation day is postponed. If the scheduled calculation day is not a trading day or if a market disruption event occurs on that day so that the calculation day is postponed and falls less than three business days prior to the maturity date, the maturity date of the securities will be postponed to the third business day following that calculation day as postponed.
■Potentially inconsistent research, opinions or recommendations by Morgan Stanley, MSFL, WFS or our or their respective affiliates. Morgan Stanley, MSFL, WFS and our or their respective affiliates may publish research from time to time on financial markets and other matters that may influence the value of the securities, or express opinions or provide recommendations that are inconsistent with purchasing or holding the securities. Any research, opinions or recommendations expressed by Morgan Stanley, MSFL, WFS or our or their respective affiliates may not be consistent with each other and may be modified from time to time without notice. Investors should make their own independent investigation of the merits of investing in the securities and the underlyings to which the securities are linked.
■The U.S. federal income tax consequences of an investment in the securities offered by this pricing supplement are uncertain. There is no direct legal authority regarding the proper U.S. federal income tax treatment
October 2026 Page 13
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
of the securities, and significant aspects of the tax treatment of the securities are uncertain. Moreover, the securities may be subject to the “constructive ownership” regime, in which case certain adverse tax consequences may apply upon your disposition of a security. You should review carefully the section entitled “United States Federal Income Tax Considerations” herein, in combination with the section entitled “United States Federal Taxation” in the accompanying tax supplement, and consult your tax adviser regarding the U.S. federal income tax consequences of an investment in the securities.
Risks Relating to the Underlyings
■You are exposed to the price risk of each underlying. Your return on the securities is not linked to a basket consisting of each underlying. Rather, it will be based upon the independent performance of each underlying. Unlike an instrument with a return linked to a basket of underlying assets, in which risk is mitigated and diversified among all the components of the basket, you will be exposed to the risks related to each underlying. Poor performance by any underlying over the term of the securities will negatively affect your return and will not be offset or mitigated by any positive performance by the other underlyings. If any underlying has declined to below its respective threshold level as of the calculation day, you will be exposed to the negative performance of the lowest performing underlying at maturity, even if the other underlyings have appreciated or have not declined as much, and you will lose some or significant portion of your investment. Accordingly, your investment is subject to the price risk of each underlying.
■Because the securities are linked to the performance of the lowest performing underlying, you are exposed to greater risk of sustaining a significant loss on your investment than if the securities were linked to just one underlying. The risk that you will suffer a significant loss on your investment is greater if you invest in the securities as opposed to substantially similar securities that are linked to the performance of just one underlying. With three underlyings, it is more likely that any underlying will decline to below its threshold level as of the calculation day, than if the securities were linked to only one underlying. Therefore it is more likely that you will suffer a significant loss on your investment.
■Investing in the securities exposes investors to risks associated with investments with a concentration in the technology sector. The stocks included in the Technology Select Sector Index and that are generally tracked by the State Street® Technology Select Sector SPDR® ETF are stocks of companies whose primary business is directly associated with the technology sector, including the following sub-sectors: computers and peripherals, software, diversified telecommunication services, communications equipment, semiconductors and semiconductor equipment, internet software and services, IT services, electronic equipment, instruments and components, wireless telecommunication services and office electronics. Because the value of the securities is linked to the performance of the underlying shares, an investment in the securities exposes investors to risks associated with investments in securities with a concentration in the technology sector.
The values of stocks of technology companies and companies that rely heavily on technology are particularly vulnerable to rapid changes in technology product cycles, rapid product obsolescence, government regulation and competition, both domestically and internationally, including competition from foreign competitors with lower production costs. Technology companies and companies that rely heavily on technology, especially those of smaller, less-seasoned companies, tend to be more volatile than the overall market. Additionally, companies in the technology sector may face
dramatic and often unpredictable changes in growth rates and competition for the services of qualified personnel. All of these factors could have an effect on the price of the underlying shares and, therefore, on the value of the securities.
■The performance and market price of the Fund, particularly during periods of market volatility, may not correlate with the performance of the fund underlying index, the performance of the component securities of the fund underlying index or the net asset value per share of the Fund. The Fund does not fully replicate the fund underlying index and may hold securities that are different than those included in the fund underlying index. In addition, the performance of the Fund will reflect additional transaction costs and fees that are not included in the calculation of the fund underlying index. All of these factors may lead to a lack of correlation between the performance of the Fund and the fund underlying index. In addition, corporate actions (such as mergers and spin-offs) with respect to the equity securities constituting the Fund may impact the variance between the performances of Fund and the fund underlying index. Finally, because the shares of the Fund are traded on an exchange and are subject to
October 2026 Page 14
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
market supply and investor demand, the market price of one share of the Fund may differ from the net asset value per share of the Fund.
In particular, during periods of market volatility, or unusual trading activity, trading in the securities constituting the Fund may be disrupted or limited, or such securities may be unavailable in the secondary market. Under these circumstances, the liquidity of the Fund may be adversely affected, market participants may be unable to calculate accurately the net asset value per share of the Fund, and their ability to create and redeem shares of the Fund may be disrupted. Under these circumstances, the market price of shares of the Fund may vary substantially from the net asset value per share of the Fund or the level of the fund underlying index.
For all of the foregoing reasons, the performance of the Fund may not correlate with the performance of the fund underlying index, the performance of the component securities of the fund underlying index or the net asset value per share of the Fund. Any of these events could materially and adversely affect the price of the shares of the Fund and, therefore, the value of the securities. Additionally, if market volatility or these events were to occur on the calculation day, the calculation agent would maintain discretion to determine whether such market volatility or events have caused a market disruption event to occur, and such determination may affect the payment at maturity of the securities. If the calculation agent determines that no market disruption event has taken place, the payment at maturity would be based on the published fund closing price per share of the Fund on the calculation day, even if the Fund’s shares are underperforming the fund underlying index or the component securities of the fund underlying index and/or trading below the net asset value per share of the Fund.
■Adjustments to the Indices could adversely affect the value of the securities. The publisher of any Index may add, delete or substitute the stocks constituting such Index or make other methodological changes that could change the value of such Index. The publisher of such Index may discontinue or suspend calculation or publication of such Index at any time. In these circumstances, the calculation agent will have the sole discretion to substitute a successor index that is comparable to the discontinued Index and is permitted to consider indices that are calculated and published by the calculation agent or any of its affiliates. If the calculation agent determines that there is no appropriate successor Index, the maturity payment amount on the securities will be an amount based on the closing prices at maturity of the securities composing such Index at the time of such discontinuance, without rebalancing or substitution, computed by the calculation agent in accordance with the formula for calculating such Index last in effect prior to discontinuance of the Index.
■Adjustments to the Fund or to the fund underlying index could adversely affect the value of the securities. The investment adviser to the XLK Shares, SSGA Funds Management, Inc. (the “Investment Adviser”), seeks investment results that correspond generally to the price and yield performance, before fees and expenses, of the fund underlying index. Pursuant to its investment strategy or otherwise, the Investment Adviser may add, delete or substitute the components securities of the Fund. Any of these actions could adversely affect the price of the shares of the Fund and, consequently, the value of the securities. In addition, the fund underlying index sponsor of the Fund is responsible for calculating and maintaining the fund underlying index. The fund underlying index sponsor may add, delete or substitute the stocks constituting the fund underlying index or make other methodological changes that could change the value of the shares of the Fund. The fund underlying index sponsor may also discontinue or suspend calculation or publication of a fund underlying index at any time. If this discontinuance or suspension occurs following the termination of the Fund, the calculation agent will have the sole discretion to substitute a successor index that is comparable to the discontinued fund underlying index, and is permitted to consider indices that are calculated and published by the calculation agent or any of its affiliates. Any of these actions could adversely affect the values of the shares of the Fund and, consequently, the value of the securities.
■Historical levels of the underlyings should not be taken as an indication of the future performance of the underlyings during the term of the securities. No assurance can be given as to the level of the underlyings at any time, including on the calculation day, because historical levels of the underlyings do not provide an indication of future performance of the underlyings.
October 2026 Page 15
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
■The antidilution adjustments the calculation agent is required to make do not cover every event that could affect the Fund. MS & Co., as calculation agent, will adjust the adjustment factor for certain events affecting the Fund. However, the calculation agent will not make an adjustment for every event that could affect the Fund. If an event occurs that does not require the calculation agent to adjust the adjustment factor, the market price of the securities may be materially and adversely affected.
October 2026 Page 16
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
|
Dow Jones Industrial AverageSM Overview |
The Dow Jones Industrial AverageSM is a price-weighted index composed of 30 common stocks that is published by S&P® Dow Jones Indices LLC, the marketing name and a licensed trademark of CME Group Inc., as representative of the broad market of U.S. industry. For additional information about the Dow Jones Industrial AverageSM, see the information set forth under “Dow Jones Industrial AverageSM” in the accompanying index supplement.
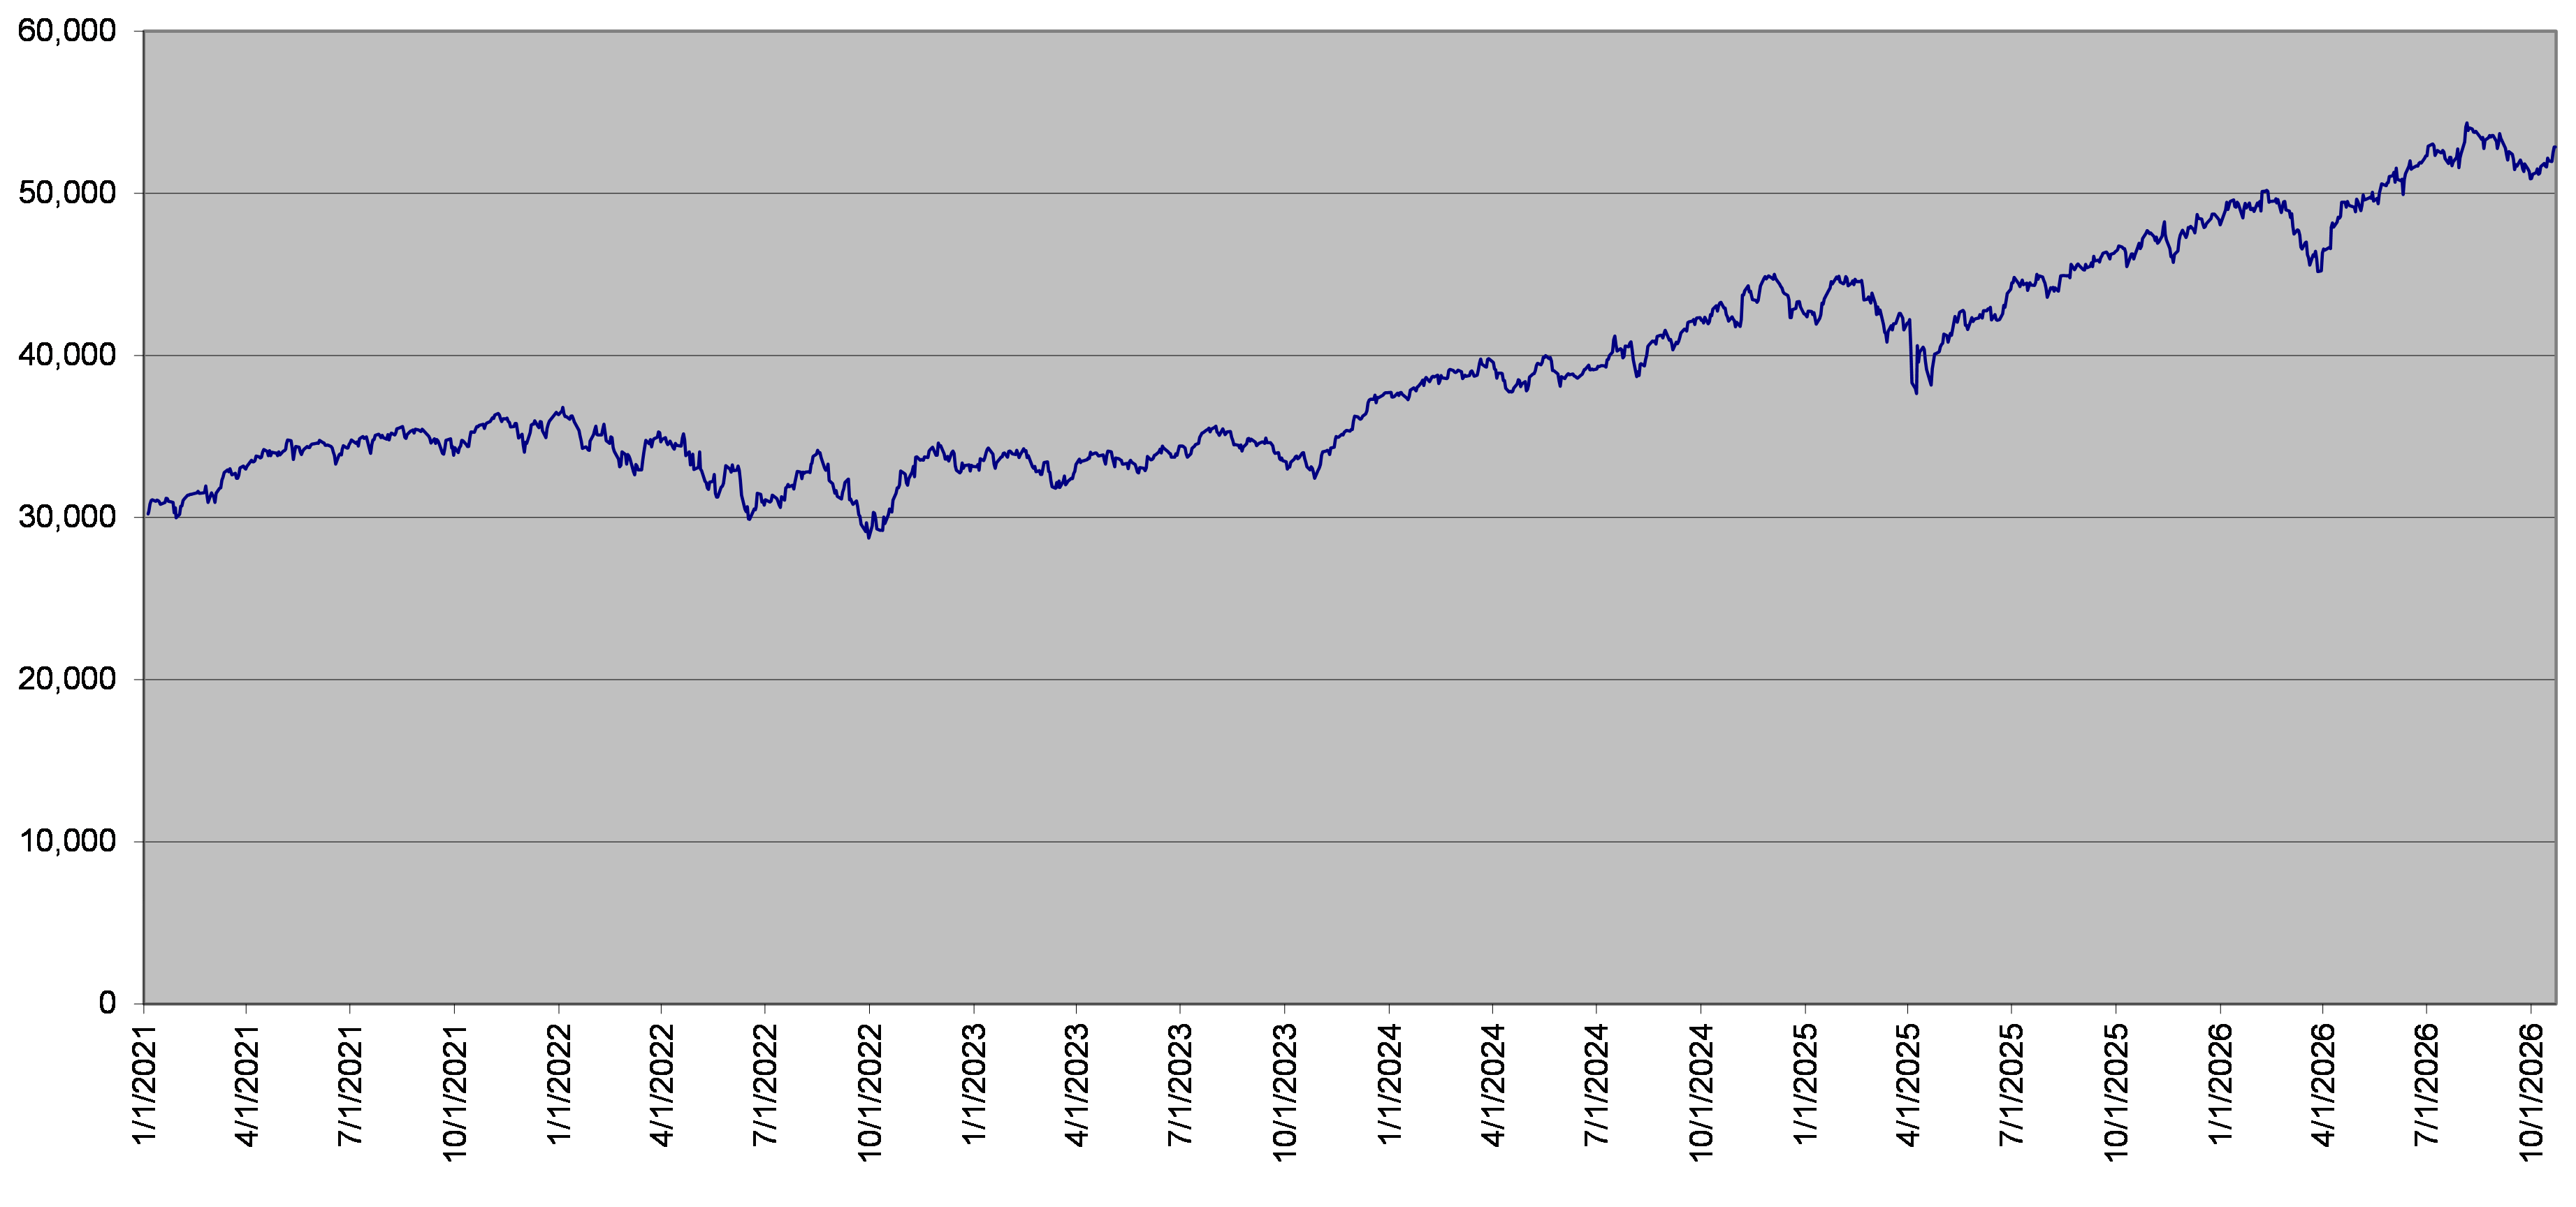
The following graph sets forth the daily closing levels of the INDU Index for the period from January 1, 2021 through October 22, 2026. The closing level of the INDU Index on October 22, 2026 was 52,867.98. We obtained the information in the graph below from Bloomberg Financial Markets without independent verification. The INDU Index has at times experienced periods of high volatility. You should not take the historical levels of the INDU Index as an indication of its future performance, and no assurance can be given as to the closing level of the INDU Index on the calculation day.
|
Dow Jones Industrial AverageSM – Daily Closing Levels January 1, 2021 to October 22, 2026 |
|
|
“Dow Jones,” “Dow Jones Industrial Average,” “Dow Jones Indexes” and “DJIA” are service marks of Dow Jones Trademark Holdings LLC. For more information, see “Dow Jones Industrial AverageSM” in the accompanying index supplement.
October 2026 Page 17
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
|
State Street® Technology Select Sector SPDR® ETF Overview |
The State Street® Technology Select Sector SPDR® ETF is an exchange-traded fund managed by Select Sector SPDR Trust (the “Trust”), which is a registered investment company. The Trust consists of numerous separate investment portfolios, including the State Street® Technology Select Sector SPDR® ETF. The State Street® Technology Select Sector SPDR® ETF seeks investment results that correspond generally to the price and yield performance, before fees and expenses, of the Technology Select Sector Index. Effective December 1, 2025, the underlier changed its name from Technology Select Sector SPDR® Fund to State Street® Technology Select Sector SPDR® ETF. It is possible that this fund may not fully replicate the performance of the Technology Select Sector Index due to the temporary unavailability of certain securities in the secondary market or due to other extraordinary circumstances. Information provided to or filed with the Securities and Exchange Commission (the “Commission”) by the Trust pursuant to the Securities Act of 1933 and the Investment Company Act of 1940 can be located by reference to Commission file numbers 333-57791 and 811-08837, respectively, through the Commission’s website at www.sec.gov. In addition, information may be obtained from other publicly available sources. Neither the issuer nor the agent makes any representation that any such publicly available information regarding the State Street® Technology Select Sector SPDR® ETF is accurate or complete.
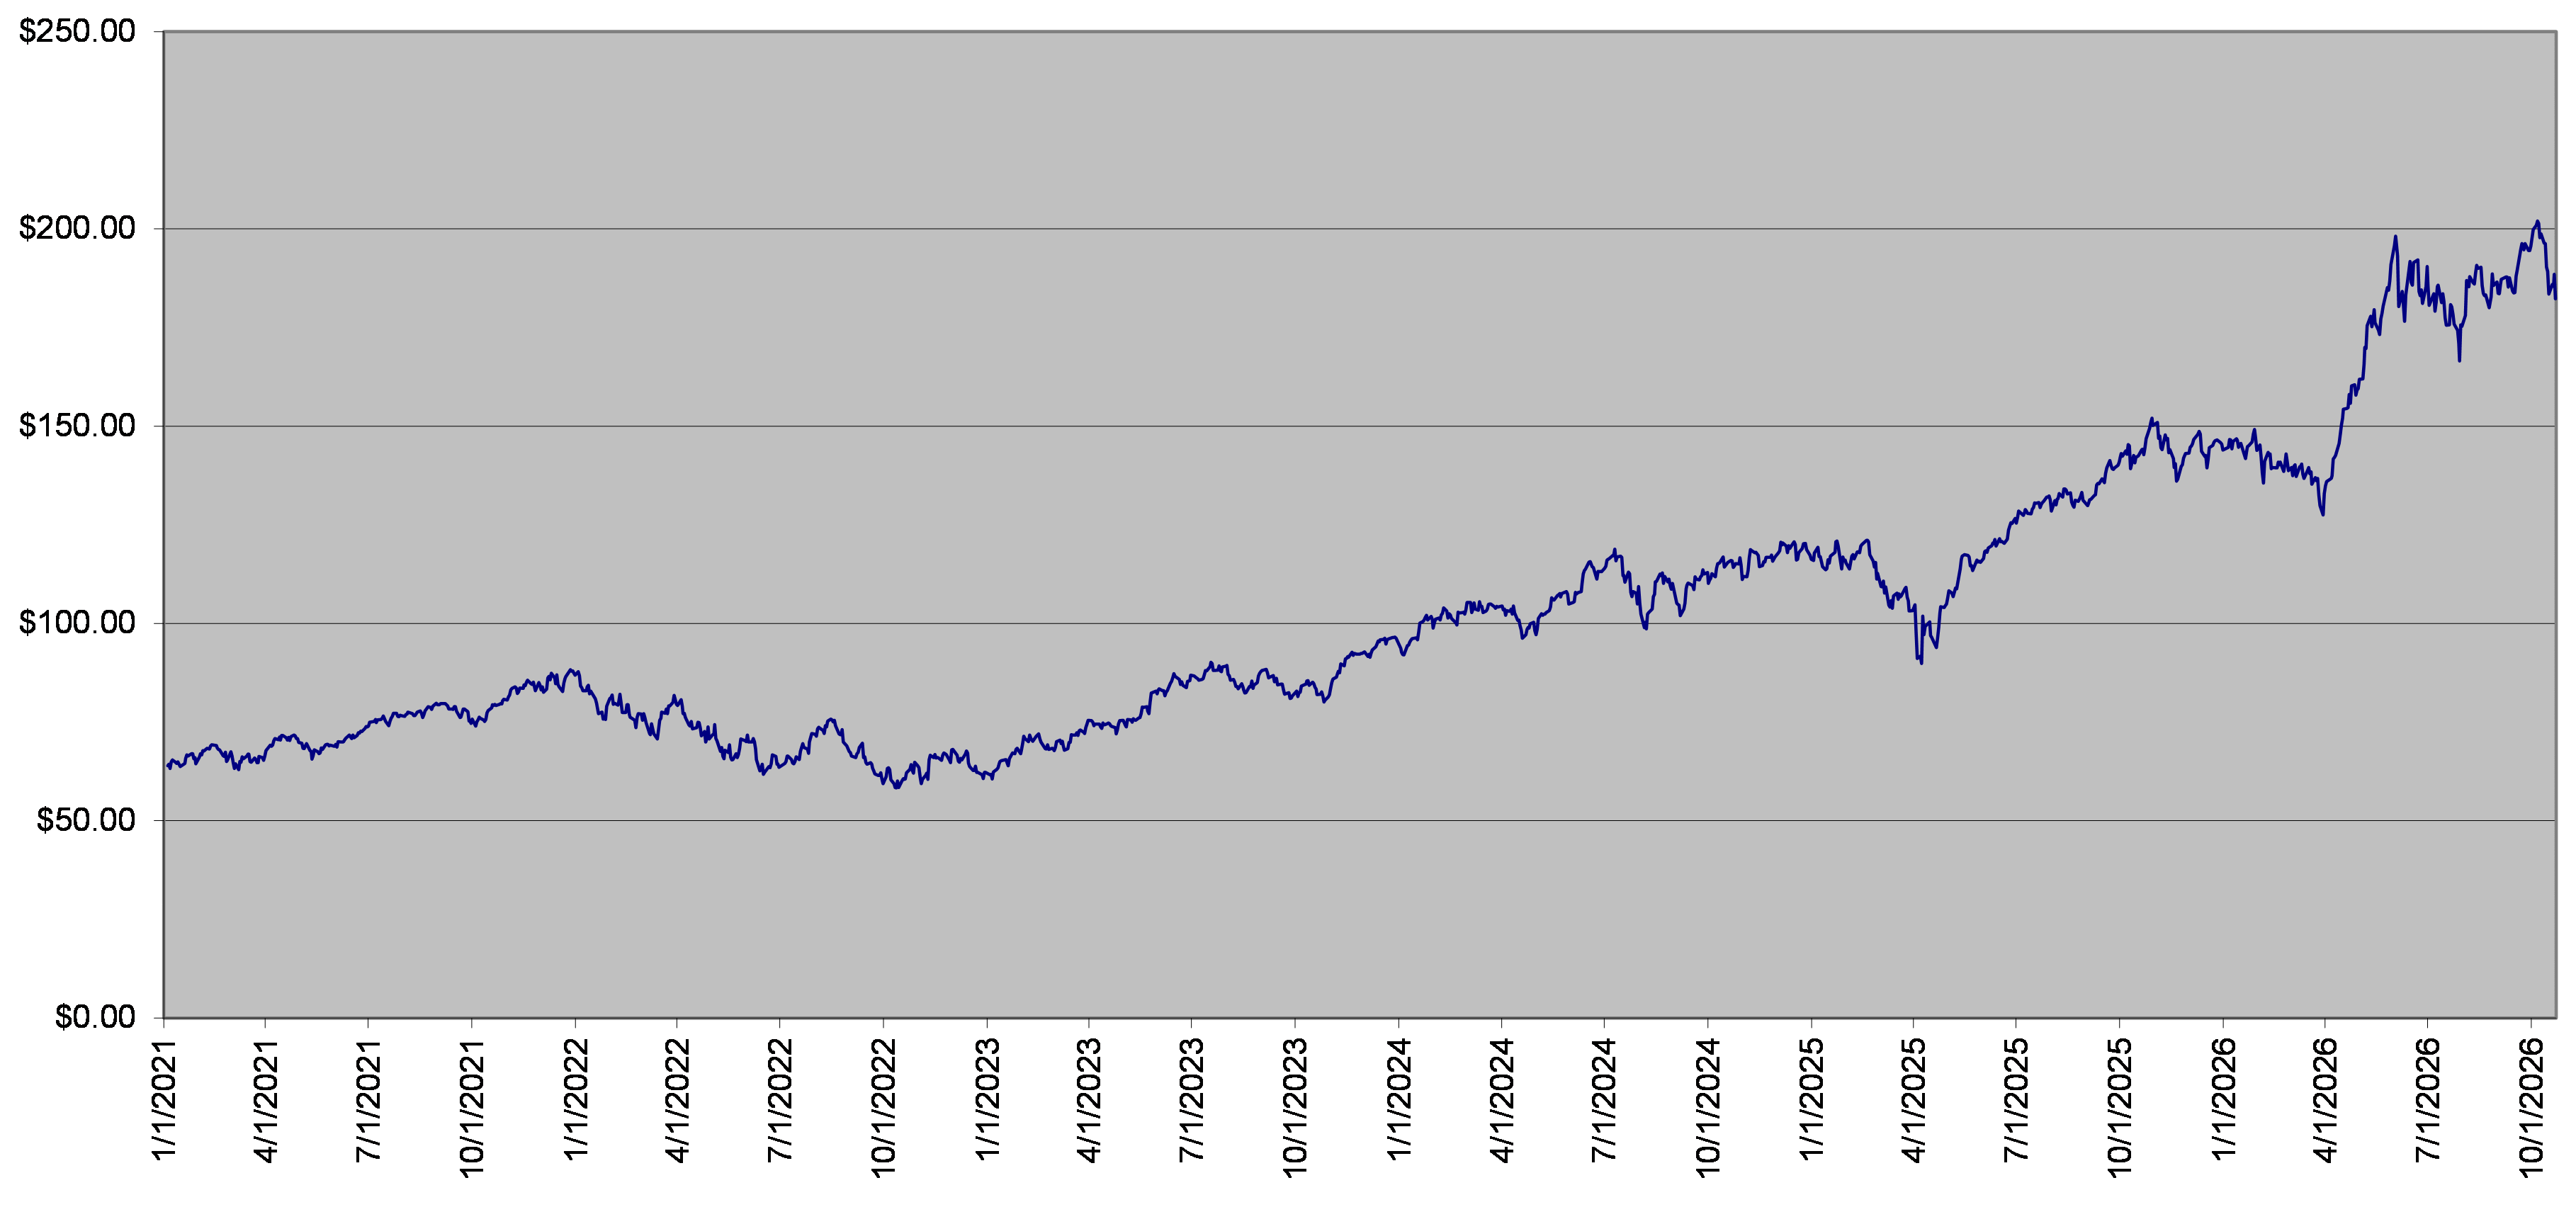
The following graph sets forth the daily closing prices of the XLK Shares for the period from January 1, 2021 through October 22, 2026. The closing price of the XLK Shares on October 22, 2026 was $182.34. We obtained the information in the graph below from Bloomberg Financial Markets without independent verification. The XLK Shares have at times experienced periods of high volatility. You should not take the historical prices of the XLK Shares as an indication of its future performance, and no assurance can be given as to the closing price of the XLK Shares on the calculation day.
|
Shares of the State Street® Technology Select Sector SPDR® ETF – Daily Closing Prices January 1, 2021 to October 22, 2026 |
|
|
This document relates only to the securities offered hereby and does not relate to the XLK Shares. We have derived all disclosures contained in this document regarding the Trust from the publicly available documents described above. In connection with the offering of the securities, neither we nor the agent has participated in the preparation of such documents or made any due diligence inquiry with respect to the Trust. Neither we nor the agent makes any representation that such publicly available documents or any other publicly available information regarding the Trust is accurate or complete. Furthermore, we cannot give any assurance that all events occurring prior to the date hereof (including events that would affect the accuracy or completeness of the publicly available documents described above) that would affect the trading price of the XLK Shares (and therefore the price of the XLK Shares at the time we price the securities) have been publicly disclosed. Subsequent disclosure of any such events or the disclosure of or failure to disclose material future events concerning the Trust could affect the value received with respect to the securities and therefore the value of the securities.
October 2026 Page 18
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
Neither we nor any of our affiliates makes any representation to you as to the performance of the XLK Shares.
We and/or our affiliates may presently or from time to time engage in business with the Trust. In the course of such business, we and/or our affiliates may acquire non-public information with respect to the Trust, and neither we nor any of our affiliates undertakes to disclose any such information to you. In addition, one or more of our affiliates may publish research reports with respect to the XLK Shares. The statements in the preceding two sentences are not intended to affect the rights of investors in the securities under the securities laws. As a prospective purchaser of the securities, you should undertake an independent investigation of the Trust as in your judgment is appropriate to make an informed decision with respect to an investment linked to the XLK Shares.
“Standard & Poor’s®”, “S&P®”, “S&P 500®”, “SPDR®”, “Select Sector SPDR®” and “Select Sector SPDRs” are trademarks of Standard & Poor’s Financial Services LLC (“S&P®”), an affiliate of S&P® Global Inc. The securities are not sponsored, endorsed, sold, or promoted by S&P®, S&P® Global Inc. or the Trust. S&P®, S&P® Global Inc. and the Trust make no representations or warranties to the owners of the securities or any member of the public regarding the advisability of investing in the securities. S&P®, S&P® Global Inc. and the Trust have no obligation or liability in connection with the operation, marketing, trading or sale of the securities.
Technology Select Sector Index. The Technology Select Sector Index, which is one of the Select Sector sub-indices of the S&P 500® Index, is intended to give investors an efficient, modified market capitalization-based way to track the movements of certain public companies that represent the technology sector of the S&P 500® Index. The Technology Select Sector Index includes component stocks in industries such as technology hardware, storage and peripherals; software; diversified telecommunication services; communications equipment; semiconductor and semiconductor equipment; internet software and services; IT services; wireless telecommunication services; and electronic equipment and instruments. For more information, see “S&P® Select Sector Indices—Technology Select Sector Index” in the accompanying index supplement.
October 2026 Page 19
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
|
S&P 500® Index Overview |
The S&P 500® Index, which is calculated, maintained and published by S&P® Dow Jones Indices LLC (“S&P®”), is intended to provide a benchmark for performance measurement of the large capitalization segment of the U.S. equity markets by tracking the stock price movement of 500 companies with large market capitalizations. Component stocks of the S&P 500® Index are required to have a total company level market capitalization that reflects approximately the 85th percentile of the S&P® Total Market Index. The S&P 500® Index measures the relative performance of the common stocks of 500 companies as of a particular time as compared to the performance of the common stocks of 500 similar companies during the base period of the years 1941 through 1943. For additional information about the S&P 500® Index, see the information set forth under “S&P® U.S. Indices—S&P 500® Index” in the accompanying index supplement.
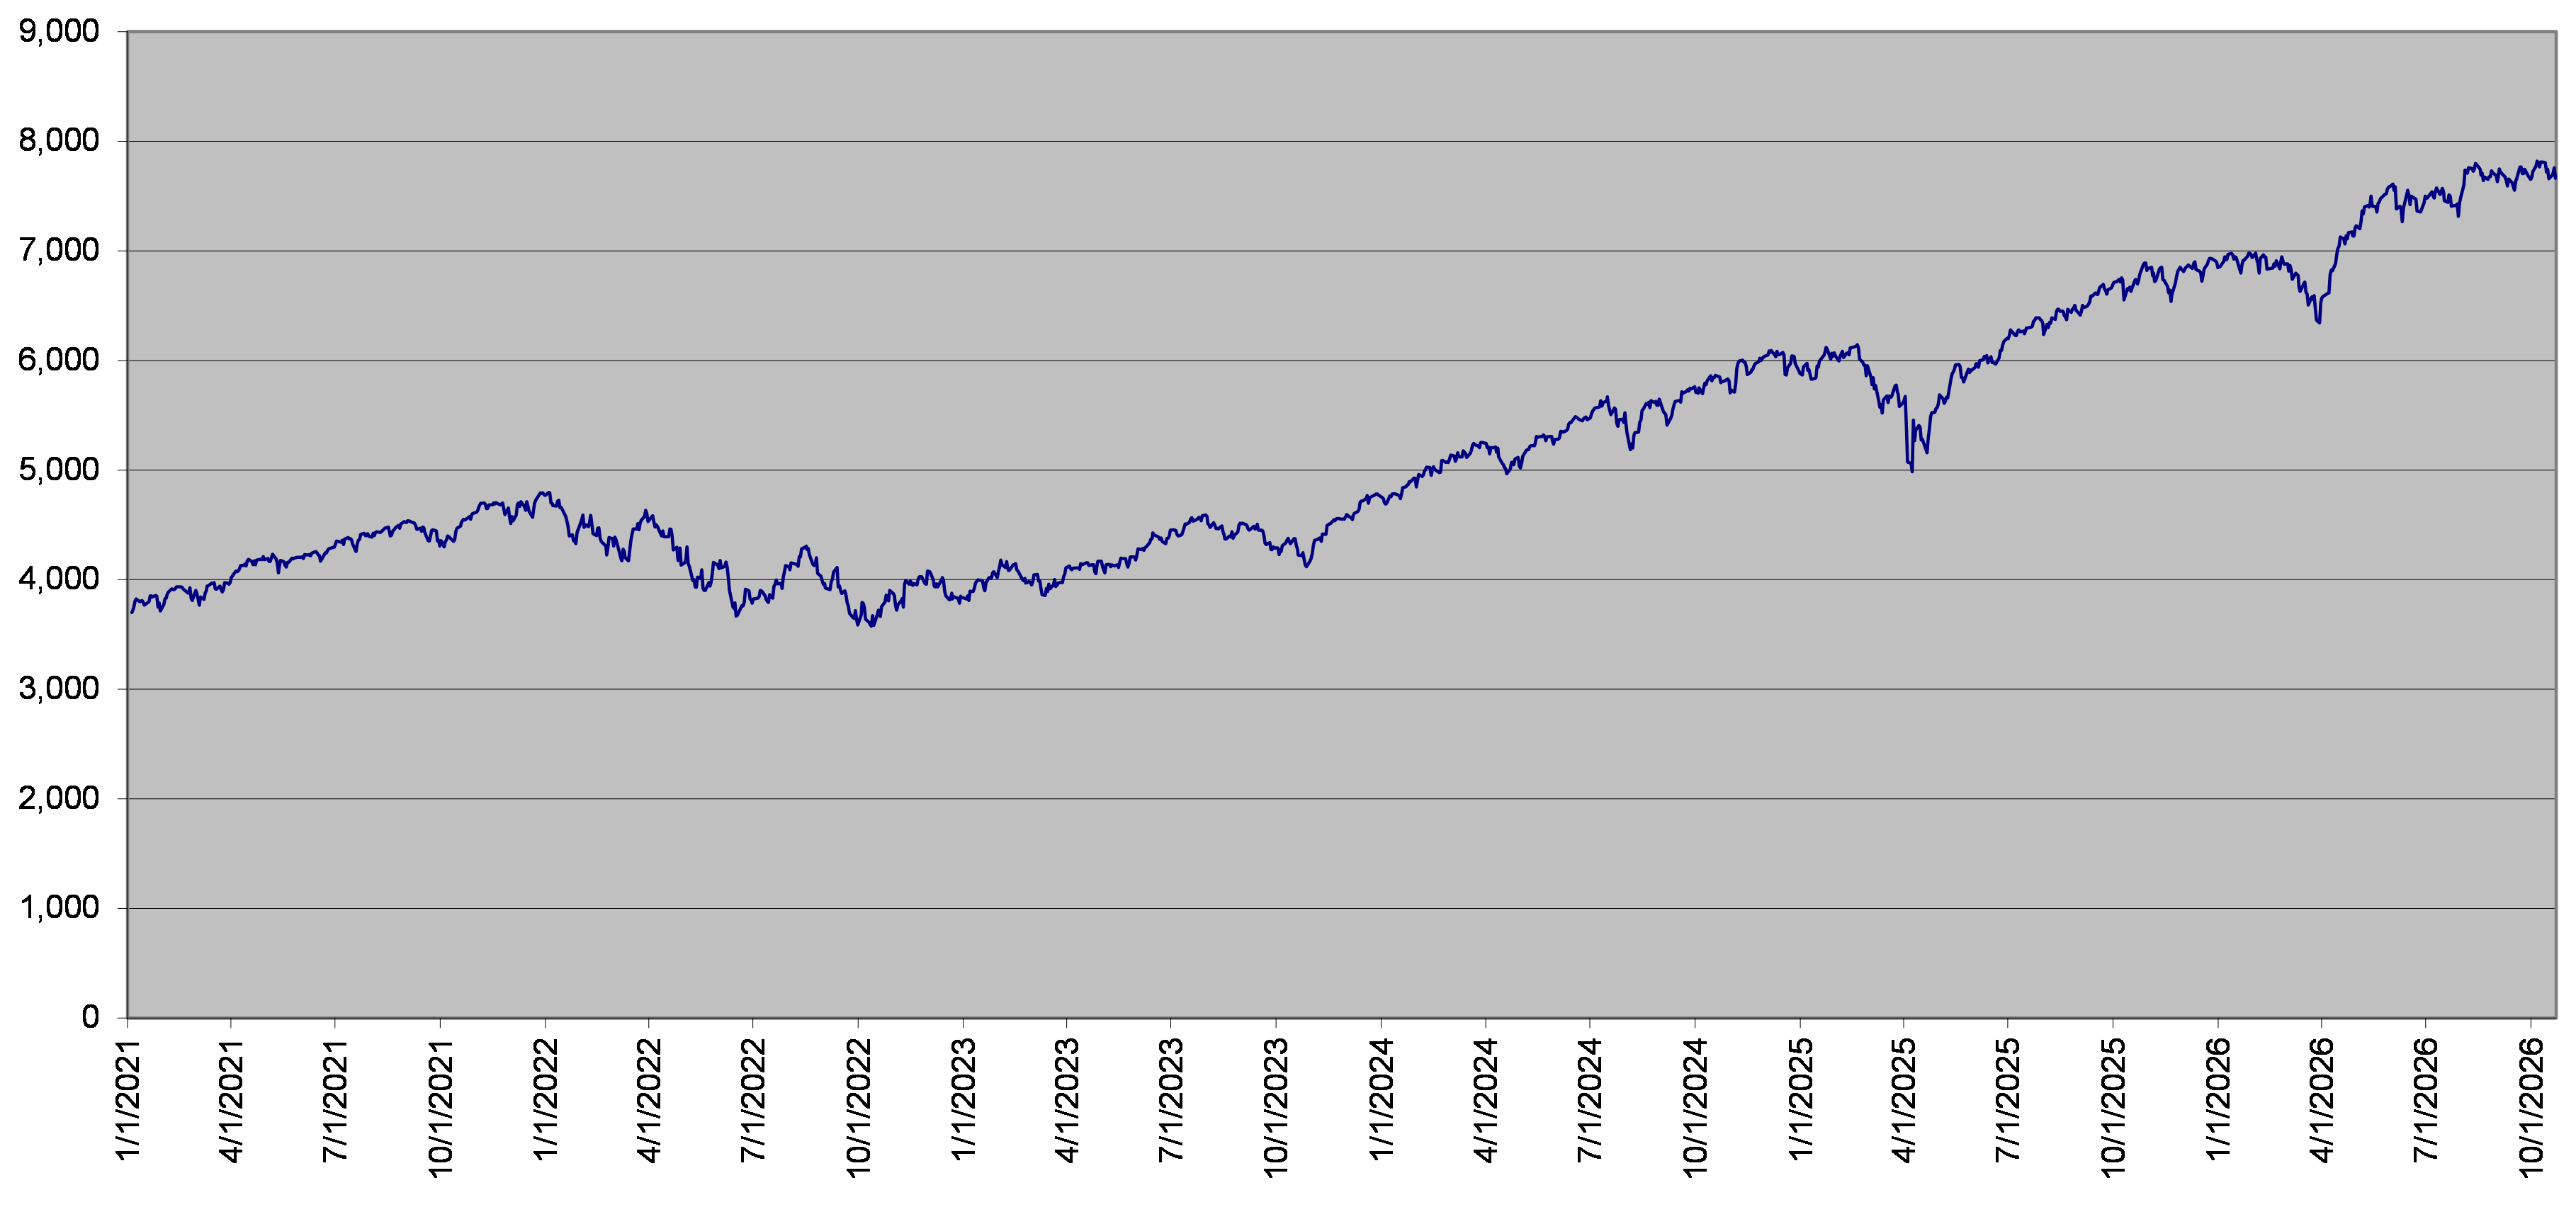
The following graph sets forth the daily closing values of the SPX Index for the period from January 1, 2021 through October 22, 2026. The closing value of the SPX Index on October 22, 2026 was 7,663.43. We obtained the information in the graph below from Bloomberg Financial Markets without independent verification. The SPX Index has at times experienced periods of high volatility. You should not take the historical closing values of the SPX Index as an indication of future performance, and no assurance can be given as to the closing value of the SPX Index at any time, including on the calculation day.
|
S&P 500® Index – Daily Closing Levels January 1, 2021 to October 22, 2026 |
|
|
October 2026 Page 20
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
|
Additional Information About the Securities |
Minimum ticketing size
$1,000 / 1 security
Tax considerations
You should review carefully the section in the accompanying tax supplement entitled “United States Federal Taxation.” The following discussion, when read in combination with that section, constitutes the full opinion of our counsel, Davis Polk & Wardwell LLP, regarding the material U.S. federal income tax consequences of owning and disposing of the securities offered by this pricing supplement.
Generally, this discussion assumes that you purchased a security for cash in the original issuance at the stated issue price and does not address other circumstances specific to you, including consequences that may arise due to any other investments relating to an underlier. Moreover, as discussed in the section entitled “United States Federal Taxation” in the accompanying tax supplement, we have not attempted to ascertain whether any issuer of any underlier to which the securities relate is a U.S. real property holding corporation or a passive foreign investment company. You should consult your tax adviser regarding these issues, including the effect any circumstances specific to you may have on the U.S. federal income tax consequences of your ownership of a security.
In the opinion of our counsel, which is based on current market conditions, it is reasonable to treat the securities for U.S. federal income tax purposes as prepaid financial contracts that are “open transactions,” as described in the section entitled “United States Federal Taxation—Tax Consequences to U.S. Holders—Program Securities Treated as Prepaid Financial Contracts that are Open Transactions” in the accompanying tax supplement. There is uncertainty regarding this treatment, and the Internal Revenue Service (the “IRS”) or a court might not agree with it. Moreover, because this treatment of the securities and our counsel’s opinion are based on market conditions as of the date of this preliminary pricing supplement, each is subject to confirmation on the pricing date. A different tax treatment could be adverse to you. Generally, if this treatment is respected, subject to the potential application of the “constructive ownership” regime discussed below, (i) you should not recognize taxable income or loss prior to the taxable disposition of your securities (including upon maturity or an earlier redemption, if applicable) and (ii) the gain or loss on your securities generally should be treated as capital gain or loss.
Even if the treatment of the securities as prepaid financial contracts is respected, purchasing a security could be treated as entering into a “constructive ownership transaction” within the meaning of Section 1260 of the Internal Revenue Code (“Section 1260”), as described in the sections entitled “United States Federal Taxation—Tax Consequences to U.S. Holders—Program Securities Treated as Prepaid Financial Contracts that are Open Transactions—Possible Application of Section 1260 of the Code” in the accompanying tax supplement. Due to the lack of direct legal authority, our counsel is unable to opine as to whether or how Section 1260 applies to the securities.
We do not plan to request a ruling from the IRS regarding the treatment of the securities. An alternative characterization of the securities could materially and adversely affect the tax consequences of ownership and disposition of the securities, including the timing and character of income recognized. In addition, the U.S. Treasury Department and the IRS have requested comments on various issues regarding the U.S. federal income tax treatment of “prepaid forward contracts” and similar financial instruments and have indicated that such transactions may be the subject of future regulations or other guidance. Furthermore, members of Congress have proposed legislative changes to the tax treatment of derivative contracts. Any legislation, Treasury regulations or other guidance promulgated after consideration of these issues could materially and adversely affect the tax consequences of an investment in the securities, possibly with retroactive effect.
Non-U.S. Holders. If you are a Non-U.S. Holder (as defined in the accompanying tax supplement), please also read the section entitled “United States Federal Taxation—Tax Consequences to Non-U.S. Holders—Program Securities Not Treated as Debt Instruments” in the accompanying tax supplement.
As discussed under “United States Federal Taxation—Tax Consequences to Non-U.S. Holders—Dividend Equivalents under Section 871(m) of the Code” in the accompanying tax supplement, Section 871(m) of the Internal Revenue Code and Treasury regulations promulgated thereunder (“Section 871(m)”) generally impose a 30% withholding tax on dividend equivalents paid or deemed paid to Non-U.S. Holders with respect to certain financial instruments linked to U.S. equities or indices that include U.S. equities. The Treasury regulations, as modified by an IRS notice, exempt financial instruments issued prior to January 1, 2029 that do not have a “delta” of one. Based on certain determinations made by us, we expect that Section 871(m) will not apply to the securities with regard to Non-U.S. Holders. Our determination is not binding on the
October 2026 Page 21
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
IRS, and the IRS may disagree with this determination. If necessary, further information regarding the potential application of Section 871(m) will be provided in the final pricing supplement for the securities.
We will not be required to pay any additional amounts with respect to U.S. federal withholding taxes.
You should consult your tax adviser regarding the U.S. federal income tax consequences of an investment in the securities, including possible alternative treatments and the potential application of the “constructive ownership” regime, as well as tax consequences arising under the laws of any state, local or non-U.S. taxing jurisdiction.
Additional considerations
Client accounts over which Morgan Stanley, Morgan Stanley Wealth Management or any of their respective subsidiaries have investment discretion are not permitted to purchase the securities, either directly or indirectly.
Supplemental information regarding plan of distribution; conflicts of interest
MS & Co. and WFS will act as the agents for this offering. WFS will receive a commission of up to $25.75 for each security it sells. WFS proposes to offer the securities in part directly to the public at the price to public set forth on the cover page of this document and in part to Wells Fargo Advisors (“WFA”) (the trade name of the retail brokerage business of WFS’s affiliates, Wells Fargo Clearing Services, LLC and Wells Fargo Advisors Financial Network, LLC), an affiliate of WFS, or other securities dealers at such price less a selling concession of up to $20.00 per security. In addition to the selling concession allowed to WFA, WFS will pay $0.75 per security of the commission to WFA as a distribution expense fee for each security sold by WFA.
In addition, in respect of certain securities sold in this offering, we may pay a fee of up to $3.00 per security to selected securities dealers in consideration for marketing and other services in connection with the distribution of the securities to other securities dealers.
See "Plan of Distribution, Conflicts of Interest" in the accompanying product supplement for principal at risk securities for information about the distribution arrangements for the securities. References therein to "agent" refer to each of MS & Co. and WFS, as agents for this offering, except that references to "agent" in the context of offers to certain Morgan Stanley dealers and compliance with FINRA Rule 5121 do not apply to WFS. MS & Co., WFS or their affiliates may enter into hedging transactions with us in connection with this offering.
MS & Co. is an affiliate of MSFL and a wholly owned subsidiary of Morgan Stanley, and it and other affiliates of ours expect to make a profit by selling, structuring and, when applicable, hedging the securities. When MS & Co. prices this offering of securities, it will determine the economic terms of the securities, including the participation rate, such that for each security the estimated value on the pricing date will be no lower than the minimum level described in “Estimated Value of the Securities” beginning on page 4.
MS & Co. will conduct this offering in compliance with the requirements of FINRA Rule 5121 of the Financial Industry Regulatory Authority, Inc., which is commonly referred to as FINRA, regarding a FINRA member firm’s distribution of the securities of an affiliate and related conflicts of interest. MS & Co. or any of our other affiliates may not make sales in this offering to any discretionary account. See “Plan of Distribution (Conflicts of Interest)” and “Use of Proceeds and Hedging” in the accompanying product supplement for principal at risk securities.
Where you can find more information
Morgan Stanley and MSFL have filed a registration statement (including a prospectus, as supplemented by the product supplement for principal at risk securities, the index supplement, and the tax supplement) with the Securities and Exchange Commission, or SEC, for the offering to which this communication relates. You should read the prospectus in that registration statement, the product supplement for principal at risk securities, the index supplement, the tax supplement and any other documents relating to this offering that Morgan Stanley and MSFL have filed with the SEC for more complete information about Morgan Stanley, MSFL and this offering. You may get these documents without cost by visiting EDGAR on the SEC web site at.www.sec.gov. Alternatively, Morgan Stanley, MSFL, any underwriter or any dealer participating in the offering will arrange to send you the product supplement for principal at risk securities, index supplement, tax supplement and prospectus if you so request by calling toll-free 1-(800)-584-6837.
You may access these documents on the SEC web site at www.sec.gov as follows:
Product Supplement for Principal at Risk Securities dated April 8, 2026
October 2026 Page 22
Morgan Stanley Finance LLC
Market Linked Securities—Leveraged Upside Participation with Fixed Percentage Buffered Downside
Principal at Risk Securities Linked to the Lowest Performing of the Dow Jones Industrial AverageSM, the State Street® Technology Select Sector SPDR® ETF and the S&P 500® Index due February 1, 2029
Tax Supplement dated April 8, 2026
Prospectus dated April 8, 2026
Terms used but not defined in this document are defined in the product supplement for principal at risk securities, in the index supplement, in the tax supplement or in the prospectus.
October 2026 Page 23
FREE Breaking News Alerts from StreetInsider.com!
StreetInsider.com Top Tickers, 10/26/2026
- Equities end higher as Anthropic's IPO filing buoys AI stocks
- Anthropic files for Nasdaq IPO as revenue jumps to $16.3 billion
- Meta reverses losses to rise as investors weigh $35 billion AI funding plan
- Post-election relief ahead for markets, says Morgan Stanley
- Musk says SpaceX raised $40 billion in debt, warns of neocloud collapse
Serious News for Serious Traders! Try StreetInsider.com Premium Free!
You May Also Be Interested In
- Broadcom secures $63 billion from banks to finance AI compute sales to Anthropic
- Four banks form $63B financing vehicle for Broadcom AI chips leased to Anthropic
- Bank of America, Blackstone, Citi and Morgan Stanley Announce Landmark $63 Billion Financing Structure to Enable AI Compute Capacity in Partnership with Broadcom
Create E-mail Alert Related Categories
SEC FilingsRelated Entities
Morgan StanleySign up for StreetInsider Free!
Receive full access to all new and archived articles, unlimited portfolio tracking, e-mail alerts, custom newswires and RSS feeds - and more!
