


Form 424B2 MORGAN STANLEY
 Tweet
 Share
 E-mail
|
Preliminary Pricing Supplement No. 18,769 Registration Statement Nos. 333-293641; 333-293641-01 Dated September 15, 2026 Filed Pursuant to Rule 424(b)(2) |
|
Morgan Stanley Finance LLC Trigger Autocallable Notes Linked to the Invesco S&P 500® Equal Weight ETF due September 21, 2028
Fully and Unconditionally Guaranteed by Morgan Stanley
Principal at Risk Securities
|
Investment Description |
These Trigger Autocallable Notes (the “Securities”) are unsecured and unsubordinated debt obligations of Morgan Stanley Finance LLC (“MSFL”) and are fully and unconditionally guaranteed by Morgan Stanley. The Securities provide returns based on the performance of the Invesco S&P 500® Equal Weight ETF (the “Underlying Shares”). Beginning after one year, if the Observation Date Closing Price of the Underlying Shares on any quarterly Observation Date beginning September 27, 2027 (including the Final Observation Date) is equal to or greater than the Initial Price, MSFL will automatically call the Securities and pay the principal amount of the Securities plus a Call Return that will vary depending on the Observation Date and will reflect a fixed Call Return Rate on a per-annum basis. If the Securities are not automatically called and the Final Price is less than the Initial Price but greater than or equal to the Downside Threshold, MSFL will pay you the principal amount at maturity. However, if the Final Price is less than the Downside Threshold, MSFL will pay you significantly less than the full principal amount, if anything, at maturity, resulting in a loss on your principal amount that is proportionate to the full decline in the price of the Underlying Shares from the Trade Date to the Final Observation Date. Investors will not participate in any appreciation of the Underlying Shares. The Securities may be appropriate for investors who are willing to risk their entire principal at maturity and are willing to forgo current income in exchange for the possibility of receiving the Call Return prior to or at maturity, if the Observation Date Closing Price of the Underlying Shares is at or above the Initial Price as of one of the quarterly Observation Dates (beginning after one year), and, if the Securities have not been called, in exchange for a contingent repayment of principal, but only if the Final Price has not declined below the Downside Threshold. Investing in the Securities involves significant risks. You may lose a significant portion or all of your principal amount. Generally, the higher the Call Return Rate for the Securities, the greater the risk of loss on those Securities. The Downside Threshold is observed only on the Final Observation Date and the contingent downside market exposure applies at maturity; if you are able to sell the Securities prior to maturity, you may receive substantially less than the principal amount even if the price of the Underlying Shares is greater than the Downside Threshold at the time of sale.
All payments are subject to our credit risk. If we default on our obligations, you could lose some or all of your investment. These Securities are not secured obligations and you will not have any security interest in, or otherwise have any access to, any underlying reference asset or assets.
|
Features |
|
Key Dates* |
|
❑Automatically Callable: Beginning after one year, MSFL will automatically call the Securities and pay you the principal amount plus a Call Return if the Observation Date Closing Price on any quarterly Observation Date beginning September 27, 2027 (including the Final Observation Date) is equal to or greater than the Initial Price, and no further payments will be made on the Securities. The Call Return will vary depending on the Observation Date and will reflect a fixed Call Return Rate on a per-annum basis. If the Securities are not called, investors will have the potential for downside equity market risk at maturity. ❑Contingent Downside Market Exposure: If the Securities have not been called and the Final Price is less than the Initial Price but equal to or greater than the Downside Threshold, MSFL will pay you the principal amount per Security at maturity. However, if the Final Price is less than the Downside Threshold, MSFL will repay significantly less than the principal amount, if anything, at maturity, resulting in a loss on your principal amount that is proportionate to the full decline in the price of the Underlying Shares from the Trade Date to the Final Observation Date. The Downside Threshold is observed only on the Final Observation Date and the contingent downside market exposure applies at maturity; if you are able to sell the Securities prior to maturity, you may receive substantially less than the principal amount even if the price of the Underlying Shares is greater than the Downside Threshold at the time of sale. Any payment on the Securities is subject to our creditworthiness. |
|
Trade Date |
September 18, 2026 |
|
|
Settlement Date |
September 23, 2026 |
|
|
|
Observation Dates |
Quarterly, beginning September 27, 2027 |
|
|
|
See “Call Returns and Observation Dates” on page 6 for details. |
||
|
|
Final Observation Date** |
September 18, 2028 |
|
|
|
Maturity Date** |
September 21, 2028 |
|
|
|
* Expected. In the event that we make any change to the expected Trade Date and Settlement Date, we may change the Observation Dates, the Final Observation Date and/or the Maturity Date so that the stated term of the Securities remains the same. ** Subject to postponement in the event of a market disruption event or for non-trading days. See “Postponement of Determination Dates” in the accompanying product supplement. |
||
NOTICE TO INVESTORS: THE SECURITIES ARE SIGNIFICANTLY RISKIER THAN CONVENTIONAL DEBT INSTRUMENTS. THE SECURITIES DO NOT GUARANTEE THE REPAYMENT OF THE FULL PRINCIPAL AMOUNT AT MATURITY, AND THE SECURITIES CAN HAVE DOWNSIDE MARKET RISK SIMILAR TO THE UNDERLYING SHARES. THIS MARKET RISK IS IN ADDITION TO THE CREDIT RISK INHERENT IN PURCHASING OUR DEBT OBLIGATIONS. YOU SHOULD NOT PURCHASE THE SECURITIES IF YOU DO NOT UNDERSTAND OR ARE NOT COMFORTABLE WITH THE SIGNIFICANT RISKS INVOLVED IN INVESTING IN THE SECURITIES. THE SECURITIES WILL NOT BE LISTED ON ANY SECURITIES EXCHANGE.
YOU SHOULD CAREFULLY CONSIDER THE RISKS DESCRIBED UNDER “KEY RISKS” BEGINNING ON PAGE 8 BEFORE PURCHASING ANY SECURITIES. EVENTS RELATING TO ANY OF THOSE RISKS, OR OTHER RISKS AND UNCERTAINTIES, COULD ADVERSELY AFFECT THE MARKET VALUE OF, AND THE RETURN ON, YOUR SECURITIES. YOU MAY LOSE A SIGNIFICANT PORTION OR ALL OF YOUR PRINCIPAL AMOUNT.
|
Security Offering |
We are offering the Trigger Autocallable Notes linked to the Invesco S&P 500® Equal Weight ETF. The actual Initial Level, Downside Threshold and Call Return Rate will be determined on the Trade Date. The Securities are offered at a minimum investment of $1,000 in denominations of $10 and integral multiples thereof.
|
Underlying Shares |
Call Return Rate* |
Initial Price |
Downside Threshold |
CUSIP |
ISIN |
|
|
Invesco S&P 500® Equal Weight ETF |
8.00% to 8.50% per annum |
$ |
75% of the Initial Price |
61780K533 |
US61780K5332 |
|
* If the Securities are called, the Call Price will be a fixed amount based on the Call Return with respect to each Observation Date. See “Call Returns and Observation Dates” on page 6. The actual Call Return Rate will be set on the Trade Date.
See “Additional Information about Morgan Stanley, MSFL and the Securities” on page 2. The Securities will have the terms set forth in the accompanying prospectus and product supplement and tax supplement and this preliminary pricing supplement.
Neither the Securities and Exchange Commission nor any other regulatory body has approved or disapproved of these Securities or passed upon the adequacy or accuracy of this preliminary pricing supplement or the accompanying product supplement, tax supplement or prospectus. Any representation to the contrary is a criminal offense. The Securities are not deposits or savings accounts and are not insured by the Federal Deposit Insurance Corporation or any other governmental agency or instrumentality, nor are they obligations of, or guaranteed by, a bank.
|
Estimated value on the Trade Date |
Approximately $9.724 per Security, or within $0.25 of that estimate. See “Additional Information about Morgan Stanley, MSFL and the Securities” on page 2. |
||
|
|
Price to Public |
Underwriting Discount(1) |
Proceeds to Us(2) |
|
Per Security |
$10 |
$0.175 |
$9.825 |
|
Total |
$ |
$ |
$ |
(1) UBS Financial Services Inc., acting as dealer, will receive from Morgan Stanley & Co. LLC, the agent, a fixed sales commission of $0.175 for each Security it sells. For more information, please see “Supplemental Plan of Distribution; Conflicts of Interest” beginning on page 19 of this preliminary pricing supplement.
(2) See “Use of Proceeds and Hedging” on page 19.
The agent for this offering, Morgan Stanley & Co. LLC (“MS & Co.”), is our affiliate and a wholly owned subsidiary of Morgan Stanley. See “Supplemental Plan of Distribution; Conflicts of Interest” beginning on page 19 of this preliminary pricing supplement.
Morgan Stanley UBS Financial Services Inc.
1
|
Additional Information about Morgan Stanley, MSFL and the Securities |
Morgan Stanley and MSFL have filed a registration statement (including a prospectus, as supplemented by a product supplement, an index supplement and a tax supplement) with the SEC for the offering to which this communication relates. Before you invest, you should read the prospectus in that registration statement, the product supplement, the index supplement, the tax supplement and any other documents relating to this offering that Morgan Stanley and MSFL have filed with the SEC for more complete information about Morgan Stanley, MSFL and this offering. You may get these documents for free by visiting EDGAR on the SEC website at.www.sec.gov. Alternatively, Morgan Stanley, MSFL, any underwriter or any dealer participating in this offering will arrange to send you the prospectus, the index supplement, the product supplement and the tax supplement if you so request by calling toll-free 1-(800)-584-6837.
You may access the accompanying product supplement, index supplement, tax supplement and prospectus on the SEC website at.www.sec.gov as follows:
♦ Product supplement for auto-callable securities dated April 8, 2026:
https://www.sec.gov/Archives/edgar/data/895421/000095010326005464/dp244203_424b2-psautocallsec.htm
♦ Index supplement dated April 8, 2026:
https://www.sec.gov/Archives/edgar/data/895421/000095010326005457/dp244875_424b2-indexsupp.htm
♦ Tax supplement dated April 8, 2026:
https://www.sec.gov/Archives/edgar/data/895421/000095010326005451/dp244874_424b2-sats.htm
♦ Prospectus dated April 8, 2026:
https://www.sec.gov/Archives/edgar/data/895421/000095010326005450/dp244347_424b2-basepro.htm
References to “MSFL” refer only to MSFL, references to “Morgan Stanley” refer only to Morgan Stanley and references to “we,” “our” and “us” refer to MSFL and Morgan Stanley collectively. In this document, the “Securities” refers to the Trigger Autocallable Notes that are offered hereby. Also, references to the accompanying “prospectus,” “index supplement,” “product supplement” and “tax supplement” mean the prospectus filed by MSFL and Morgan Stanley dated April 8, 2026, the index supplement filed by MSFL and Morgan Stanley dated April 8, 2026, the product supplement for auto-callable securities filed by MSFL and Morgan Stanley dated April 8, 2026 and the tax supplement filed by MSFL and Morgan Stanley dated April 8, 2026, respectively.
You should rely only on the information incorporated by reference or provided in this preliminary pricing supplement or the accompanying product supplement, index supplement, tax supplement and prospectus. We have not authorized anyone to provide you with different information. We are not making an offer of these Securities in any state where the offer is not permitted. You should not assume that the information in this preliminary pricing supplement or the accompanying product supplement, index supplement, tax supplement and prospectus is accurate as of any date other than the date on the front of this document.
The Issue Price of each Security is $10. This price includes costs associated with issuing, selling, structuring and hedging the Securities, which are borne by you, and, consequently, the estimated value of the Securities on the Trade Date will be less than $10. We estimate that the value of each Security on the Trade Date will be approximately $9.724, or within $0.25 of that estimate. Our estimate of the value of the Securities as determined on the Trade Date will be set forth in the final pricing supplement.
What goes into the estimated value on the Trade Date?
In valuing the Securities on the Trade Date, we take into account that the Securities comprise both a debt component and a performance-based component linked to the Underlying Shares. The estimated value of the Securities is determined using our own pricing and valuation models, market inputs and assumptions relating to the Underlying Shares, instruments based on the Underlying Shares, volatility and other factors including current and expected interest rates, as well as an interest rate related to our secondary market credit spread, which is the implied interest rate at which our conventional fixed rate debt trades in the secondary market.
What determines the economic terms of the Securities?
In determining the economic terms of the Securities, including the Call Return Rate and the Downside Threshold, we use an internal funding rate, which is likely to be lower than our secondary market credit spreads and therefore advantageous to us. If the issuing, selling, structuring and hedging costs borne by you were lower or if the internal funding rate were higher, one or more of the economic terms of the Securities would be more favorable to you.
What is the relationship between the estimated value on the Trade Date and the secondary market price of the Securities?
The price at which MS & Co. purchases the Securities in the secondary market, absent changes in market conditions, including those related to the Underlying Shares, may vary from, and be lower than, the estimated value on the Trade Date, because the secondary market price takes into account our secondary market credit spread as well as the bid-offer spread that MS & Co. would charge in a secondary market transaction of this type and other factors. However, because the costs associated with issuing, selling, structuring and hedging the Securities are not fully deducted upon issuance, for a period of up to 6 months following the Settlement Date, to the extent that MS & Co. may buy or sell the Securities in the secondary market, absent changes in market conditions, including those related to the Underlying Shares, and to our secondary market credit spreads, it would do so based on values higher than the estimated value. We expect that those higher values will also be reflected in your brokerage account statements.
MS & Co. currently intends, but is not obligated, to make a market in the Securities, and, if it once chooses to make a market, may cease doing so at any time.
2
|
Investor Suitability |
|
|
The Securities may be suitable for you if: |
The Securities may not be suitable for you if: |
|
♦You fully understand the risks inherent in an investment in the Securities, including the risk of loss of your entire initial investment in the Securities. ♦You can tolerate a loss of all or a substantial portion of your investment and are willing to make an investment that may have the same downside market risk as the Underlying Shares. ♦You understand and accept the risks associated with the Underlying Shares. ♦You believe the Underlying Shares will close at or above the Initial Price on one of the Observation Dates (beginning after one year) or will close at or above the Downside Threshold on the Final Observation Date. ♦You understand and accept that you will not participate in any appreciation in the price of the Underlying Shares and that your potential return is limited to the applicable Call Return. ♦You can tolerate fluctuations in the price of the Securities prior to maturity that may be similar to or exceed the downside fluctuations of the Underlying Shares. ♦You are willing to invest in the Securities based on the Downside Threshold specified on the cover hereof. ♦You would be willing to invest in the Securities if the Call Return Rate were set equal to the bottom of the range specified on the cover hereof (the actual Call Return Rate will be set on the Trade Date). ♦You do not seek current income from this investment and are willing to forgo dividends paid on the constituent stocks of the Underlying Shares. ♦You are willing to invest in securities that may be called early and you are otherwise willing to hold such securities to maturity, as set forth on the cover page of this preliminary pricing supplement. ♦You accept that there may be little or no secondary market for the Securities and that any secondary market will depend in large part on the price, if any, at which MS & Co. is willing to trade the Securities. ♦You are willing to assume our credit risk for all payments under the Securities, and understand that we default on our obligations you may not receive any amounts due to you and could lose your entire investment. |
♦You do not fully understand the risks inherent in an investment in the Securities, including the risk of loss of your entire initial investment in the Securities. ♦You cannot tolerate a loss of all or a substantial portion of your investment, and are unwilling to make an investment that may have the same downside market risk as the Underlying Shares. ♦You require an investment designed to provide a full return of principal at maturity. ♦You do not understand and accept the risks associated with the Underlying Shares. ♦You believe that the price of the Underlying Shares will decline during the term of the Securities and is likely to close below the Downside Threshold on the Final Observation Date, exposing you to the full decline in the Underlying Shares. ♦You seek an investment that participates in the full appreciation in the price of the Underlying Shares or that has unlimited return potential. ♦You cannot tolerate fluctuations in the price of the Securities prior to maturity that may be similar to or exceed the downside fluctuations of the Underlying Shares. ♦You are unwilling to invest in the Securities based on the Downside Threshold specified on the cover hereof. ♦You would be unwilling to invest in the Securities if the Call Return Rate were set equal to the bottom of the range specified on the cover hereof (the actual Call Return Rate will be set on the Trade Date). ♦You prefer the lower risk, and therefore accept the potentially lower returns, of fixed income investments with comparable maturities and credit ratings. ♦You seek current income from this investment or prefer to receive the dividends paid on the constituent stocks of the Underlying Shares, if any. ♦You are unable or unwilling to hold securities that may be called early, or you are otherwise unable or unwilling to hold such securities to maturity, as set forth on the cover page of this preliminary pricing supplement, or you seek an investment for which there will be an active secondary market. ♦You are not willing to assume our credit risk for all payments under the Securities. |
The investor suitability considerations identified above are not exhaustive. Whether or not the Securities are a suitable investment for you will depend on your individual circumstances, and you should reach an investment decision only after you and your investment, legal, tax, accounting and other advisors have carefully considered the suitability of an investment in the Securities in light of your particular circumstances. You should also review carefully the sections entitled “Key Risks” beginning on page 8 of this preliminary pricing supplement and “Risk Factors” beginning on page 7 of the accompanying prospectus and page S-15 of the accompanying product supplement and “Risk Factors” beginning on page TS-4 of the accompanying tax supplement for risks related to an investment in the Securities. For additional information about the Underlying Shares, see the information set forth under “The Invesco S&P 500® Equal Weight ETF” on page 15.
3
|
Terms |
|
|
Issuer |
Morgan Stanley Finance LLC |
|
Guarantor |
Morgan Stanley |
|
Issue Price |
$10.00 per Security. The Securities are offered at a minimum investment of 100 Securities. |
|
Underlying Shares |
Invesco S&P 500® Equal Weight ETF (the “Fund”)
|
|
Principal Amount |
$10.00 per Security |
|
Term |
Approximately 2 years, unless called earlier |
|
Automatic Call Feature |
The Securities will be called automatically if the Observation Date Closing Price on any Observation Date (beginning after one year), including the Final Observation Date, is equal to or greater than the Initial Price.
If the Securities are called, MSFL will pay you on the related Call Settlement Date a Call Price per Security calculated as follows (see “Call Returns and Observation Dates” on page 6):
$10 + ($10 x Call Return)
After the Securities have been called, no further payments will be made on the Securities. |
|
Call Return and Call Return Rate |
The Call Return varies depending on the Observation Date and increases the longer the Securities are outstanding. The Call Return is based on a Call Return Rate of 8.00% to 8.50% per annum. The actual Call Return Rate will be set on the Trade Date. See “Call Returns and Observation Dates” on page 6. |
|
Trade Date |
September 18, 2026 |
|
Settlement Date |
September 23, 2026 |
|
Observation Dates |
Quarterly, beginning September 27, 2027. See “Call Returns and Observation Dates” on page 6. |
|
Final Observation Date |
September 18, 2028* |
|
Maturity Date |
September 21, 2028* |
|
Call Settlement Dates |
See “Call Returns and Observation Dates” on page 6. The Call Settlement Date with respect to the Final Observation Date will be the Maturity Date. |
|
* Subject to postponement in the event of a Market Disruption Event or for non-trading days. See “Postponement of Determination Dates” in the accompanying product supplement. |
|
|
Payment at Maturity (per Security) |
If the Securities are not automatically called prior to or on the Maturity Date, MSFL will pay you a cash payment on the Maturity Date based on the Final Price, as follows:
If the Securities are not called prior to or on the Maturity Date, and the Final Price is less than the Initial Price but equal to or greater than the Downside Threshold, MSFL will pay you the $10 principal amount.
If the Securities are not called prior to or on the Maturity Date, and the Final Price is less than the Downside Threshold, MSFL will pay you an amount per Security calculated as follows:
$10 × (1 + Underlying Return)
In this case, you will lose a significant portion and could lose all of the principal amount in an amount proportionate to the full decline of the Underlying Shares from the Trade Date to the Final Observation Date. |
|
Observation Date Closing Price |
The Closing Price of the Underlying Shares on any Observation Date times the Adjustment Factor on such date. |
|
Underlying Return |
Final Price – Initial Price |
4
|
Initial Price |
, which is the Closing Price of the Underlying Shares on the Trade Date. |
|
Final Price |
The Closing Price of the Underlying Shares on the Final Observation Date times the Adjustment Factor on such date. |
|
Downside Threshold |
75% of the Initial Price |
|
Adjustment Factor |
1.0, subject to adjustment in the event of certain corporate events affecting the Underlying Shares. |
|
Trustee |
The Bank of New York Mellon |
|
Calculation Agent |
MS & Co. |
Investing in the Securities involves significant risks. You may lose YOUR ENTIRE principal amount. Any payment on the Securities is subject to OUR creditworthiness. If WE were to default on OUR payment obligations, you may not receive any amounts owed to you under the Securities and you could lose your entire investment.
5
|
Call Returns and Observation Dates |
|
Observation Date |
Call Settlement Date / Maturity Date** |
Call Return (Assuming a Call Return Rate of 8.00% to 8.50% per annum)*** |
Call Price (per $10 of Securities) |
|
9/27/2027 |
9/30/2027 |
8.000% to 8.500% |
$10.800 to $10.850 |
|
12/20/2027 |
12/22/2027 |
10.000% to 10.625% |
$11.000 to $11.0625 |
|
3/20/2028 |
3/22/2028 |
12.000% to 12.750% |
$11.200 to $11.275 |
|
6/20/2028 |
6/22/2028 |
14.000% to 14.875% |
$11.400 to $11.4875 |
|
9/18/2028 (the Final Observation Date)* |
9/21/2028 (the Maturity Date)* |
16.000% to 17.000% |
$11.600 to $11.700 |
* Subject to postponement in the event of a market disruption event or for non-trading days. See “Postponement of Determination Dates” in the accompanying product supplement.
** If, due to a market disruption event or otherwise, any Observation Date (including the Final Observation Date) is postponed so that it falls less than two business days prior to the scheduled Call Settlement Date, the Call Settlement Date or Maturity Date, as applicable, will be postponed to the second business day following that Observation Date as postponed.
*** If the Securities are called following any Observation Date, the Call Price will be a fixed amount based on the Call Return with respect to each Observation Date, as specified above, regardless of the actual number of days during such period. The actual Call Return Rate will be set on the Trade Date.
6
|
Investment Timeline |
|
|
|
|
|
|
The Initial Price and Downside Threshold are determined, and the Call Return Rate is set. |
|
|
|
|
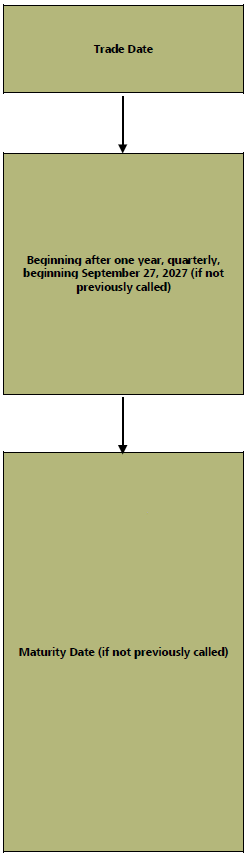
Beginning after one year, the Securities will be called automatically if the Observation Date Closing Price on any Observation Date (including the Final Observation Date) is equal to or greater than the Initial Price.
If the Securities are called, MSFL will pay you a Call Price per Security calculated as follows:
$10 + ($10 x Call Return)
After the Securities are called, no further payments will be made on the Securities. |
|
|
|
|
|
The Final Price is determined as of the Final Observation Date.
If the Securities are not automatically called prior to or on the Maturity Date and the Final Price is equal to or greater than the Downside Threshold but below the Initial Price, MSFL will pay you the $10 principal amount.
If the Securities are not automatically called prior to or on the Maturity Date and the Final Price is less than the Downside Threshold, MSFL will pay you an amount calculated as follows:
$10 × (1+ Underlying Return) This will be less than the $10 principal amount by an amount proportionate to the full negative Underlying Return, and you could lose your entire investment. |
|
7
|
Key Risks |
An investment in the Securities involves significant risks. The material risks that apply to the Securities are summarized here, but we urge you to also read the “Risk Factors” section of the accompanying prospectus, product supplement and tax supplement. You should also consult your investment, legal, tax, accounting and other advisers before you invest in the Securities.
Risks Relating to an Investment in the Securities
♦The Securities do not pay interest or guarantee the return of any principal. The terms of the Securities differ from those of ordinary debt securities in that the Securities do not pay interest or guarantee the return of any of the principal amount at maturity. In addition, while the Securities will generally offer the possibility of a higher return if the Securities are automatically called than the potential return payable on our ordinary debt securities with a similar maturity, this higher return potential reflects the risk that you may not receive a positive return on the Securities and may lose a significant portion or all of your investment if the Securities have not been called prior to maturity and if the Final Price is less than the Downside Threshold. In this case, you will be exposed to the full negative Underlying Return, and MSFL will pay you an amount at maturity that is significantly less than the $10 principal amount, resulting in a loss proportionate to the full decline of the Underlying Shares over the term of the Securities. You could lose your entire principal amount.
♦The appreciation potential of the Securities is limited by the fixed Call Returns specified for each Observation Date. The appreciation potential of the Securities is limited to the fixed Call Returns specified for each Observation Date if the Underlying Shares closes at or above the Initial Price on any Observation Date (beginning after one year), including the Final Observation Date, and you will not participate in any appreciation of the Underlying Shares, which could be significant. If the Securities are not previously called and the Final Price is less than the Downside Threshold, you will be fully exposed to the decline in the price of the Underlying Shares from the Trade Date to the Final Observation Date, and you will lose a significant portion or all of your investment.
♦You may incur a loss on your investment if you sell your Securities prior to maturity. The Downside Threshold is observed only on the Final Observation Date and the contingent downside market exposure applies at maturity. If you are able to sell your Securities in the secondary market prior to maturity, you may have to sell them at a loss relative to your initial investment even if the price of the Underlying Shares is above the Downside Threshold at that time.
♦Early redemption risk. The term of your investment in the Securities may be limited to as short as approximately one year by the automatic call feature of the Securities. If the Securities are called prior to maturity, you will not receive any further payments on the Securities and you may be forced to invest in a lower interest rate environment and may not be able to reinvest at comparable terms or for similar returns. Generally, the longer the Securities have been outstanding, the less likely it is that they will be automatically called, because the price of the Underlying Shares will necessarily have declined from the Initial Price if the Securities were not called following an Observation Date, and there will be less time remaining until maturity in which the price of the Underlying Shares can recover.
♦No interest payments. You will not receive any interest payments during the term of the Securities.
♦The Securities are subject to our credit risk, and any actual or anticipated changes to our credit ratings or our credit spreads may adversely affect the market value of the Securities. You are dependent on our ability to pay all amounts due on the Securities, if any, and any payments upon an automatic call or at maturity, and therefore you are subject to our credit risk. If we default on our obligations under the Securities, your investment would be at risk and you could lose some or all of your investment. As a result, the market value of the Securities prior to maturity will be affected by changes in the market’s view of our creditworthiness. Any actual or anticipated decline in our credit ratings or increase in our credit spreads charged by the market for taking our credit risk is likely to adversely affect the market value of the Securities.
♦As a finance subsidiary, MSFL has no independent operations and will have no independent assets. As a finance subsidiary, MSFL has no independent operations beyond the issuance and administration of its securities and will have no independent assets available for distributions to holders of MSFL securities if they make claims in respect of such securities in a bankruptcy, resolution or similar proceeding. Accordingly, any recoveries by such holders will be limited to those available under the related guarantee by Morgan Stanley and that guarantee will rank pari passu with all other unsecured, unsubordinated obligations of Morgan Stanley. Holders will have recourse only to a single claim against Morgan Stanley and its assets under the guarantee. Holders of securities issued by MSFL should accordingly assume that in any such proceedings they would not have any priority over and should be treated pari passu with the claims of other unsecured, unsubordinated creditors of Morgan Stanley, including holders of Morgan Stanley-issued securities.
♦The market price of the Securities may be influenced by many unpredictable factors. Several factors, many of which are beyond our control, will influence the value of the Securities in the secondary market and the price at which MS & Co. may be willing to purchase or sell the Securities in the secondary market. Although we expect that generally the closing price of the Underlying Shares on any day will affect the value of the Securities more than any other single factor, other factors that may influence the value of the Securities include:
othe volatility (frequency and magnitude of changes in value) of the Underlying Shares,
odividend rates on the securities included in the Share Underlying Index,
ointerest and yield rates in the market,
otime remaining until the Securities mature,
ogeopolitical conditions and economic, financial, political, regulatory or judicial events that affect the Underlying Shares or equities markets generally and which may affect the Observation Date Closing Prices or Final Price,
8
othe occurrence of certain events affecting the Underlying Shares that may or may not require an adjustment to the Adjustment Factor, and
oany actual or anticipated changes in our credit ratings or credit spreads.
Some or all of these factors will influence the terms of the Securities at the time of issuance and the price that you will receive if you are able to sell your Securities prior to maturity, as the Securities are comprised of both a debt component and a performance-based component linked to the Underlying Shares, and these are the types of factors that also generally affect the values of debt securities and derivatives linked to the Underlying Shares. The price of the Underlying Shares may be, and has recently been, volatile, and we can give you no assurance that the volatility will lessen. See “The Invesco S&P 500® Equal Weight ETF” below. You may receive less, and possibly significantly less, than the principal amount per Security if you try to sell your Securities prior to maturity.
♦Investing in the Securities is not equivalent to investing in the Underlying Shares or the stocks composing the Underlying Shares. Investing in the Securities is not equivalent to investing in the Underlying Shares or the stocks that constitute the Underlying Shares. Investors in the Securities will not participate in any appreciation of the Underlying Shares, and will not have voting rights or rights to receive dividends or other distributions or any other rights with respect to the stocks that constitute the Underlying Shares.
♦No dividend payments or voting rights. Owning the Securities is not the same as owning the Underlying Shares or the stocks comprising the Share Underlying Index. As a holder of the Securities, you will not have voting rights or rights to receive dividends or other distributions or other rights that holders of shares of the Underlying Shares or stocks held by the Fund would have.
♦The Securities will not be listed on any securities exchange and secondary trading may be limited. The Securities will not be listed on any securities exchange. Therefore, there may be little or no secondary market for the Securities. MS & Co. currently intends, but is not obligated, to make a market in the Securities. Even if there is a secondary market, it may not provide enough liquidity to allow you to trade or sell the Securities easily. Because we do not expect that other broker-dealers will participate significantly in the secondary market for the Securities, the price at which you may be able to trade your Securities is likely to depend on the price, if any, at which MS & Co. is willing to transact. If, at any time, MS & Co. were to cease making a market in the Securities, it is likely that there would be no secondary market for the Securities. Accordingly, you should be willing to hold your Securities to maturity.
♦The rate we are willing to pay for securities of this type, maturity and issuance size is likely to be lower than the rate implied by our secondary market credit spreads and advantageous to us. Both the lower rate and the inclusion of costs associated with issuing, selling, structuring and hedging the Securities in the Issue Price reduce the economic terms of the Securities, cause the estimated value of the Securities to be less than the Issue Price and will adversely affect secondary market prices. Assuming no change in market conditions or any other relevant factors, the prices, if any, at which dealers, including MS & Co., may be willing to purchase the Securities in secondary market transactions will likely be significantly lower than the Issue Price, because secondary market prices will exclude the issuing, selling, structuring and hedging-related costs that are included in the Issue Price and borne by you and because the secondary market prices will reflect our secondary market credit spreads and the bid-offer spread that any dealer would charge in a secondary market transaction of this type as well as other factors.
The inclusion of the costs of issuing, selling, structuring and hedging the Securities in the Issue Price and the lower rate we are willing to pay as issuer make the economic terms of the Securities less favorable to you than they otherwise would be.
However, because the costs associated with issuing, selling, structuring and hedging the Securities are not fully deducted upon issuance, for a period of up to 6 months following the Settlement Date, to the extent that MS & Co. may buy or sell the Securities in the secondary market, absent changes in market conditions, including those related to the Underlying Shares, and to our secondary market credit spreads, it would do so based on values higher than the estimated value, and we expect that those higher values will also be reflected in your brokerage account statements.
♦The estimated value of the Securities is determined by reference to our pricing and valuation models, which may differ from those of other dealers and is not a maximum or minimum secondary market price. These pricing and valuation models are proprietary and rely in part on subjective views of certain market inputs and certain assumptions about future events, which may prove to be incorrect. As a result, because there is no market-standard way to value these types of securities, our models may yield a higher estimated value of the Securities than those generated by others, including other dealers in the market, if they attempted to value the Securities. In addition, the estimated value on the Trade Date does not represent a minimum or maximum price at which dealers, including MS & Co., would be willing to purchase your Securities in the secondary market (if any exists) at any time. The value of your Securities at any time after the date of this preliminary pricing supplement will vary based on many factors that cannot be predicted with accuracy, including our creditworthiness and changes in market conditions. See also “The market price of the Securities may be influenced by many unpredictable factors” above.
♦Hedging and trading activity by our affiliates could potentially adversely affect the value of the Securities. One or more of our affiliates and/or third-party dealers expect to carry out hedging activities related to the Securities (and to other instruments linked to the Underlying Shares), including trading in the Underlying Shares. As a result, these entities may be unwinding or adjusting hedge positions during the term of the Securities, and the hedging strategy may involve greater and more frequent dynamic adjustments to the hedge as the Final Observation Date approaches. Some of our affiliates also trade the Underlying Shares and other financial instruments related to the Underlying Shares on a regular basis as part of their general broker-dealer and other businesses. Any of these hedging or trading activities on or prior to the Trade Date could potentially increase the Initial Price, and, as a result, the price at or above which the Underlying Shares must close on any of the Observation Dates (beginning after one year) for the Securities to be called, or the Downside Threshold, which, if the Securities are not called, is the price at or above which the Underlying Shares must close on the Final Observation Date so that you do not suffer a significant loss on your initial investment in the Securities. Additionally, such hedging or trading activities during the term of the
9
Securities could potentially affect the price of the Underlying Shares on the Observation Dates, and, accordingly, whether the Securities are automatically called, and, if the Securities are not called, the payout to you at maturity, if any.
♦The Calculation Agent, which is an affiliate of the Issuer, will make determinations with respect to the Securities. As Calculation Agent, MS & Co. will determine the Initial Price, the Downside Threshold, the Observation Date Closing Price, the Final Price, whether the Securities will be called following any Observation Date, whether a market disruption event has occurred and the payment that you will receive upon a call or at maturity, if any. Moreover, certain determinations made by MS & Co., in its capacity as Calculation Agent, may require it to exercise discretion and make subjective judgments, such as with respect to the occurrence or nonoccurrence of market disruption events. These potentially subjective determinations may affect the payout to you upon a call or at maturity, if any. For further information regarding these types of determinations, see “Description of Auto-Callable Securities—Postponement of Determination Dates,” “—Discontinuance of the Underlying Shares of an Exchange-Traded Fund and/or Share Underlying Index; Alteration of Method of Calculation” and “—Calculation Agent and Calculations” in the accompanying product supplement. In addition, MS & Co. has determined the estimated value of the Securities on the Trade Date.
♦The U.S. federal income tax consequences of an investment in the securities offered by this pricing supplement are uncertain. There is no direct legal authority regarding the proper U.S. federal income tax treatment of the securities, and significant aspects of the tax treatment of the securities are uncertain. In particular, due to the terms of the securities and current market conditions, there is a substantial risk that the securities could be characterized as debt instruments for U.S. federal income tax purposes, in which case the timing and character of income recognized in respect of the securities could be different from those described herein and possibly adverse to certain investors. Moreover, the securities may be subject to the “constructive ownership” regime, in which case certain adverse tax consequences may apply upon your disposition of a security. You should review carefully the section entitled “United States Federal Income Tax Considerations” herein, in combination with the section entitled “United States Federal Taxation” in the accompanying tax supplement, and consult your tax adviser regarding the U.S. federal income tax consequences of an investment in the securities.
Risks Relating to the Underlying
♦A higher Call Return Rate and/or a lower Downside Threshold may reflect greater expected volatility of the Underlying Shares, and greater expected volatility generally indicates an increased risk of declines in the price of the Underlying Shares and, potentially, a significant loss at maturity. The economic terms for the Securities, including the Call Return Rate and the Downside Threshold, are based, in part, on the expected volatility of the Underlying Shares at the time the terms of the Securities are set. “Volatility” refers to the frequency and magnitude of changes in the price of the Underlying Shares. Higher expected volatility with respect to the Underlying Shares as of the Trade Date generally indicates a greater expectation as of that date that the Final Price of the Underlying Shares could ultimately be less than the Downside Threshold on the Final Observation Date, which would result in a loss of a significant portion or all of the Principal Amount. At the time the terms of the Securities are set, higher expected volatility will generally be reflected in a higher Call Return Rate and/or a lower Downside Threshold, as compared to otherwise comparable securities. Therefore, a relatively higher Call Return Rate, which would increase the upside return if the Securities are automatically called, may indicate an increased risk that the price of the Underlying Shares will decrease substantially, which would result in a significant loss at maturity. In addition, and as described above in "The Securities do not pay interest or guarantee the return of any principal," in general, the higher potential return on the Securities than the return payable on our ordinary debt securities with a comparable maturity indicates the risk that you may not receive a positive return on the Securities and may lose a significant portion or all of your investment. Further, a relatively lower Downside Threshold may not indicate that the Securities have a greater likelihood of a return of principal at maturity. You should be willing to accept the downside market risk of the Underlying Shares and the potential to lose a significant portion or all of your Principal Amount at maturity.
♦Governmental regulatory actions could result in material changes to the composition of the Underlying and could negatively affect your return on the Securities. Governmental regulatory actions, including but not limited to sanctions-related actions by the U.S. or foreign governments, could make it necessary or advisable for there to be material changes to the composition of the Underlying, depending on the nature of such governmental regulatory actions and the Underlying constituent stocks that are affected. If any governmental regulatory action results in the removal of Underlying constituent stocks that have (or historically have had) significant weights within the Underlying, such removal, or even any uncertainty relating to a possible removal, could have a material and negative effect on the level of the Underlying and, therefore, your return on the Securities.
♦Adjustments to the Underlying Shares or the Share Underlying Index could adversely affect the value of the Securities. As the investment adviser to the S&P 500® Equal Weight ETF, Invesco Capital Management LLC (the “Investment Adviser”), seeks investment results that correspond generally to the price and yield performance, before fees and expenses, of the Share Underlying Index. Pursuant to its investment strategy or otherwise, the Investment Adviser may add, delete or substitute the stocks composing the S&P 500® Equal Weight ETF. Any of these actions could adversely affect the price of the Underlying Shares and, consequently, the value of the Securities. S&P® Dow Jones Indices LLC (“S&P®”) is responsible for calculating and maintaining the Share Underlying Index. S&P® may add, delete or substitute the stocks constituting the Share Underlying Index or make other methodological changes that could change the value of the Share Underlying Index. S&P® may discontinue or suspend calculation or publication of the Share Underlying Index at any time. If trading in the Underlying Shares is permanently discontinued and/or the S&P 500® Equal Weight ETF is liquidated or otherwise terminated, and S&P® subsequently discontinues publication of the Share Underlying Index, the Calculation Agent will have the sole discretion to substitute a successor index that is comparable to the discontinued Share Underlying Index and is permitted to consider indices that are calculated and published by the Calculation Agent or any of its affiliates. Any of these actions could adversely affect the price of the Underlying Shares, and consequently, the value of the Securities.
♦The performance and market price of the Fund, particularly during periods of market volatility, may not correlate with the performance of the Share Underlying Index, the performance of the component securities of the Share Underlying Index or the net asset value per share of the Fund. The Fund does not fully replicate the Share Underlying Index and may hold securities that are different than those included in the Share Underlying Index. In addition, the performance of the Fund will reflect additional transaction costs and fees that are not included in the calculation of the Share Underlying Index. All of these factors may lead to a lack of correlation between the performance of the Fund and the Share Underlying Index. In addition, corporate actions (such as mergers and spin-offs) with
10
respect to the equity securities underlying the Fund may impact the variance between the performances of the Fund and the Share Underlying Index. Finally, because the shares of the Fund are traded on an exchange and are subject to market supply and investor demand, the market price of one share of the Fund may differ from the net asset value per share of the Fund.
In particular, during periods of market volatility, or unusual trading activity, trading in the securities underlying the Fund may be disrupted or limited, or such securities may be unavailable in the secondary market. Under these circumstances, the liquidity of the Fund may be adversely affected, market participants may be unable to calculate accurately the net asset value per share of the Fund, and their ability to create and redeem shares of the Fund may be disrupted. Under these circumstances, the market price of shares of the Fund may vary substantially from the net asset value per share of the Fund or the level of the Share Underlying Index.
For all of the foregoing reasons, the performance of the Fund may not correlate with the performance of the Share Underlying Index, the performance of the component securities of the Share Underlying Index or the net asset value per share of the Fund. Any of these events could materially and adversely affect the price of the shares of the Fund and, therefore, the value of the Securities. Additionally, if market volatility or these events were to occur on the Final Observation Date, the Calculation Agent would maintain discretion to determine whether such market volatility or events have caused a Market Disruption Event to occur, and such determination would affect the Payment at Maturity of the Securities. If the Calculation Agent determines that no Market Disruption Event has taken place, the payment at maturity would be based solely on the published closing price per share of the Fund on the Final Observation Date, even if the Fund’s shares are underperforming the Share Underlying Index or the component securities of the Share Underlying Index and/or trading below the net asset value per share of the Fund.
♦The adjustments to the Adjustment Factor the Calculation Agent is required to make do not cover every corporate event that can affect the shares of the Underlying Shares. MS & Co., as Calculation Agent, will adjust the Adjustment Factor for certain events affecting the Underlying Shares, including stock splits and reverse stock splits. However, the Calculation Agent will not make an adjustment for every event that can affect the Underlying Shares. If an event occurs that does not require the Calculation Agent to adjust the Adjustment Factor, the market price of the Securities may be materially and adversely affected. The determination by the Calculation Agent to adjust, or not to adjust, the Adjustment Factor may materially and adversely affect the market price of the Securities.
11
|
Hypothetical Payments on the Securities at Maturity |
The examples below illustrate the payment upon a call or at maturity for a $10 Security on a hypothetical offering of the Securities, with the following assumptions (the actual terms for the Securities are listed on the cover hereof or will be determined on the Trade Date; amounts may have been rounded for ease of reference):
♦Principal Amount: $10
♦Term: Approximately 2 years
♦Hypothetical Initial Price: $150
♦Hypothetical Call Return Rate: 8.00% per annum.
♦Call Returns:
|
Observation Date |
Call Return |
|
First Observation Date |
8.000% |
|
Second Observation Date |
10.000% |
|
Third Observation Date |
12.000% |
|
Fourth Observation Date |
14.000% |
|
Final Observation Date |
16.000% |
♦Observation Dates: Quarterly, beginning on September 27, 2027
♦Hypothetical Downside Threshold: $112.50, which is 75% of the Hypothetical Initial Price
Early Call — Securities are Called following the Second Observation Date
|
Date |
Closing Price |
Payment (per Security) |
|
First Observation Date |
$75 (below Initial Price; Securities NOT called) |
-- |
|
Second Observation Date |
$315 (at or above Initial Price; Securities are called) |
$10 + ($10 x Call Return) = $10 + ($10 x 10.000%) = $11.000 |
The Observation Date Closing Price is below the Initial Price on the first Observation Date (beginning after one year) but above the Initial Price on the second Observation Date and therefore the Securities are called on the second Call Settlement Date. MSFL will pay you on the Call Settlement Date the principal amount of $10.00 plus a Call Return of 10.000% per Security, reflecting the hypothetical Call Return Rate of 8.00% on a per-annum basis. No further amount will be owed to you under the Securities, and you do not participate in the appreciation of the Underlying.
Payment at Maturity
Example 1 — The Final Price is ABOVE the Initial Price; Securities are Called on the Maturity Date
|
Date |
Closing Price |
Payment (per Security) |
|
First Observation Date |
$50 (below Initial Price; Securities Not Called) |
-- |
|
Second Observation Date |
$65 (below Initial Price; Securities Not Called) |
-- |
|
Third through Fourth Observation Dates |
Various (all below the Initial Price; Securities Not Called) |
-- |
|
Final Observation Date |
$350 (at or above Initial Price) |
$10 + ($10 x Call Return) = $10 + ($10 x 16.000%) = $11.600 (Payment at Maturity) |
The Observation Date Closing Price is below the Initial Price on each of the Observation Dates prior to the Final Observation Date and therefore the Securities are not called prior to maturity. On the Final Observation Date, the Final Price is greater than the Initial Price and therefore MSFL will call the Securities on the Maturity Date and pay you at maturity the principal amount plus the hypothetical Call Return of 16.000% per Security. Investors do not participate in the appreciation of the Underlying Shares.
Example 2 — The Final Price is BELOW the Initial Price but AT OR ABOVE the Downside Threshold
|
Date |
Closing Price |
Payment (per Security) |
|
First Observation Date |
$65 (below Initial Price; Securities Not Called) |
-- |
|
Second Observation Date |
$70 (below Initial Price; Securities Not Called) |
-- |
|
Third through Fourth Observation Dates |
Various (all below the Initial Price; Securities Not Called) |
-- |
|
Final Observation Date |
$125 (below Initial Price, at or above Downside Threshold) |
$10 |
12
Because the Securities are not called prior to maturity and the Final Price of the Underlying Shares is below the Initial Price but at or above the Downside Threshold, at maturity MSFL will pay you the $10 principal amount per Security.
Example 3 —The Final Price is BELOW the Downside Threshold
|
Date |
Closing Price |
Payment (per Security) |
|
First Observation Date |
$55 (below Initial Price; Securities Not Called) |
-- |
|
Second Observation Date |
$60 (below Initial Price; Securities Not Called) |
-- |
|
Third through Fourth Observation Dates |
Various (all below the Initial Price; Securities Not Called) |
-- |
|
Final Observation Date |
$45 (below Downside Threshold) |
$10 + ($10 x Underlying Return) = |
Since the Securities are not called prior to maturity and the Final Price of the Underlying Shares is below the Downside Threshold, at maturity MSFL will pay you $3.00 per Security, reflecting a loss of principal proportionate to the full decline in the Final Price from the Initial Price.
The Securities differ from ordinary debt securities in that, among other features, MSFL is not necessarily obligated to repay the full amount of your initial investment. If the Securities are not called, you may lose a significant portion or all of your initial investment. Specifically, if the Securities are not called and the Final Price is less than the Downside Threshold, you will lose 1% (or a fraction thereof) of your principal amount for each 1% (or a fraction thereof) that the Underlying Return is negative. Any payment on the Securities, including any payment upon an automatic call or the Payment at Maturity, is dependent on our ability to satisfy our obligations when they come due. If we are unable to meet our obligations, you may not receive any amounts due to you under the Securities.
13
|
United States Federal Income Tax Considerations |
You should review carefully the section in the accompanying tax supplement entitled “United States Federal Taxation.” The following discussion, when read in combination with that section, constitutes the full opinion of our counsel, Davis Polk & Wardwell LLP, regarding the material U.S. federal income tax consequences of owning and disposing of the securities offered by this pricing supplement.
Generally, this discussion assumes that you purchased a security for cash in the original issuance at the stated issue price and does not address other circumstances specific to you, including consequences that may arise due to any other investments relating to an underlier. Moreover, as discussed in the section entitled “United States Federal Taxation” in the accompanying tax supplement, we have not attempted to ascertain whether any issuer of any underlier to which the securities relate is a U.S. real property holding corporation or a passive foreign investment company. You should consult your tax adviser regarding these issues, including the effect any circumstances specific to you may have on the U.S. federal income tax consequences of your ownership of a security.
In the opinion of our counsel, which is based on current market conditions, it is reasonable to treat the securities for U.S. federal income tax purposes as prepaid financial contracts that are “open transactions,” as described in the section entitled “United States Federal Taxation—Tax Consequences to U.S. Holders—Program Securities Treated as Prepaid Financial Contracts that are Open Transactions” in the accompanying tax supplement. There is uncertainty regarding this treatment, and the Internal Revenue Service (the “IRS”) or a court might not agree with it. Moreover, because this treatment of the securities and our counsel’s opinion are based on market conditions as of the date of this preliminary pricing supplement, each is subject to confirmation on the pricing date. A different tax treatment could be adverse to you. Generally, if this treatment is respected, subject to the potential application of the “constructive ownership” regime discussed below, (i) you should not recognize taxable income or loss prior to the taxable disposition of your securities (including upon maturity or an earlier redemption, if applicable) and (ii) the gain or loss on your securities generally should be treated as capital gain or loss.
Even if the treatment of the securities as prepaid financial contracts is respected, purchasing a security could be treated as entering into a “constructive ownership transaction” within the meaning of Section 1260 of the Internal Revenue Code (“Section 1260”), as described in the sections entitled “United States Federal Taxation—Tax Consequences to U.S. Holders—Program Securities Treated as Prepaid Financial Contracts that are Open Transactions—Possible Application of Section 1260 of the Code” in the accompanying tax supplement. Due to the lack of direct legal authority, our counsel is unable to opine as to whether or how Section 1260 applies to the securities.
We do not plan to request a ruling from the IRS regarding the treatment of the securities. An alternative characterization of the securities could materially and adversely affect the tax consequences of ownership and disposition of the securities, including the timing and character of income recognized. In particular, due to the terms of the securities and current market conditions, there is a substantial risk that the securities could be characterized as debt instruments for U.S. federal income tax purposes, in which case the timing and character of income recognized in respect of the securities could be different from those described herein and possibly adverse to certain investors. In addition, the U.S. Treasury Department and the IRS have requested comments on various issues regarding the U.S. federal income tax treatment of “prepaid forward contracts” and similar financial instruments and have indicated that such transactions may be the subject of future regulations or other guidance. Furthermore, members of Congress have proposed legislative changes to the tax treatment of derivative contracts. Any legislation, Treasury regulations or other guidance promulgated after consideration of these issues could materially and adversely affect the tax consequences of an investment in the securities, possibly with retroactive effect.
Non-U.S. Holders. If you are a Non-U.S. Holder (as defined in the accompanying tax supplement), please also read the section entitled “United States Federal Taxation—Tax Consequences to Non-U.S. Holders—Program Securities Not Treated as Debt Instruments” in the accompanying tax supplement.
As discussed under “United States Federal Taxation—Tax Consequences to Non-U.S. Holders—Dividend Equivalents under Section 871(m) of the Code” in the accompanying tax supplement, Section 871(m) of the Internal Revenue Code and Treasury regulations promulgated thereunder (“Section 871(m)”) generally impose a 30% withholding tax on dividend equivalents paid or deemed paid to Non-U.S. Holders with respect to certain financial instruments linked to U.S. equities or indices that include U.S. equities. The Treasury regulations, as modified by an IRS notice, exempt financial instruments issued prior to January 1, 2027 that do not have a “delta” of one. Based on certain determinations made by us, we expect that Section 871(m) will not apply to the securities with regard to Non-U.S. Holders. Our determination is not binding on the IRS, and the IRS may disagree with this determination. If necessary, further information regarding the potential application of Section 871(m) will be provided in the final pricing supplement for the securities.
We will not be required to pay any additional amounts with respect to U.S. federal withholding taxes.
You should consult your tax adviser regarding the U.S. federal income tax consequences of an investment in the securities, including possible alternative treatments and the potential application of the “constructive ownership” regime, as well as tax consequences arising under the laws of any state, local or non-U.S. taxing jurisdiction.
14
|
The Invesco S&P 500® Equal Weight ETF |
|
The Invesco S&P 500® Equal Weight ETF, or RSP, is an exchange-traded fund that seeks investment results that correspond generally to the price and yield performance, before fees and expenses, of the S&P 500® Equal Weight Index. The Invesco S&P 500® Equal Weight ETF is managed by Invesco Exchange-Traded Fund Trust (the “Trust”), a registered investment company that consists of numerous separate investment portfolios, including the Invesco S&P 500® Equal Weight ETF. Information provided to or filed with the Securities and Exchange Commission (the “Commission”) by Invesco Exchange-Traded Fund Trust pursuant to the Securities Act of 1933 and the Investment Company Act of 1940 can be located by reference to Commission file numbers 333-102228 and 811-21265, respectively, through the Commission’s website at www.sec.gov. In addition, information may be obtained from other publicly available sources. Neither the issuer nor the agent makes any representation that any such publicly available information regarding the Invesco S&P 500® Equal Weight ETF is accurate or complete. The Underlying Shares are listed on The NYSE Arca Exchange under the ticker symbol “RSP UP.” The S&P 500® Equal Weight Index is the equal-weight version of the S&P 500® Index. The index includes the same constituents as the capitalization-weighted S&P 500® Index, but each company in the S&P 500® Equal Weight Index is allocated a fixed weight of 0.2% of the index total at each quarterly rebalancing. Therefore, the performances of the S&P 500® Equal Weight Index and the Underlying Shares will differ, perhaps materially, from the performance of the S&P 500® Index, which is weighted unevenly based on market capitalization. The S&P 500® Index, which is calculated, maintained and published by S&P® Dow Jones Indices LLC (“S&P®”), is intended to provide a benchmark for performance measurement of the large capitalization segment of the U.S. equity markets by tracking the stock price movement of 500 companies with large market capitalizations. Component stocks of the S&P 500® Index are required to have a total company level market capitalization that reflects approximately the 85th percentile of the S&P® Total Market Index. The S&P 500® Index measures the relative performance of the common stocks of 500 companies as of a particular time as compared to the performance of the common stocks of 500 similar companies during the base period of the years 1941 through 1943. For additional information about the S&P 500® Index, see the information set forth under “S&P® U.S. Indices—S&P 500® Index” in the accompanying index supplement. We and/or our affiliates may presently or from time to time engage in business with the Trust. In the course of such business, we and/or our affiliates may acquire non-public information with respect to the Trust, and neither we nor any of our affiliates undertakes to disclose any such information to you. In addition, one or more of our affiliates may publish research reports with respect to the Underlying Shares. The statements in the preceding two sentences are not intended to affect the rights of investors in the Securities under the securities laws. As a prospective purchaser of the Securities, you should undertake an independent investigation of Trust as in your judgment is appropriate to make an informed decision with respect to an investment linked to the Underlying Shares. “Standard & Poor’s®”, “S&P®”, “S&P 500®” are trademarks of Standard & Poor’s Financial Services LLC (“S&P®”), an affiliate of S&P® Global Inc. The Securities are not sponsored, endorsed, sold, or promoted by S&P, S&P Global Inc. or the Trust. S&P®, S&P® Global Inc. and the Trust make no representations or warranties to the owners of the Securities or any member of the public regarding the advisability of investing in the Securities. S&P®, S&P® Global Inc. and the Trust have no obligation or liability in connection with the operation, marketing, trading or sale of the Securities. |
|
Historical Information |
The following table sets forth the published high and low Closing Price, as well as the end-of-quarter Closing Price, of the Invesco S&P 500® Equal Weight ETF for each quarter in the period from January 1, 2021 through September 14, 2026. The Closing Price of the Invesco S&P 500® Equal Weight ETF on September 14, 2026 was $215.01. We obtained the information in the table below from Bloomberg Financial Markets, without independent verification. The historical Closing Price of the Invesco S&P 500® Equal Weight ETF should not be taken as an indication of future performance, and no assurance can be given as to the price of the Invesco S&P 500® Equal Weight ETF on any Observation Date, including the Final Observation Date.
|
Quarter Begin |
Quarter End |
Quarterly High ($) |
Quarterly Low ($) |
Quarterly Close ($) |
|
1/1/2021 |
3/31/2021 |
142.80 |
125.70 |
141.66 |
|
4/1/2021 |
6/30/2021 |
152.26 |
143.08 |
150.73 |
|
7/1/2021 |
9/30/2021 |
157.39 |
146.61 |
149.82 |
|
10/1/2021 |
12/31/2021 |
163.01 |
150.88 |
162.75 |
|
1/1/2022 |
3/31/2022 |
164.20 |
148.26 |
157.71 |
|
4/1/2022 |
6/30/2022 |
158.96 |
130.84 |
134.23 |
|
7/1/2022 |
9/30/2022 |
152.39 |
127.28 |
127.28 |
|
10/1/2022 |
12/31/2022 |
149.03 |
128.02 |
141.25 |
|
1/1/2023 |
3/31/2023 |
154.96 |
137.35 |
144.62 |
|
4/1/2023 |
6/30/2023 |
149.64 |
139.61 |
149.64 |
|
7/1/2023 |
9/30/2023 |
155.00 |
141.04 |
141.69 |
|
10/1/2023 |
12/31/2023 |
158.41 |
133.66 |
157.80 |
|
1/1/2024 |
3/31/2024 |
169.37 |
153.84 |
169.37 |
|
4/1/2024 |
6/30/2024 |
168.37 |
159.21 |
164.28 |
|
7/1/2024 |
9/30/2024 |
179.16 |
162.83 |
179.16 |
|
10/1/2024 |
12/31/2024 |
187.62 |
174.22 |
175.23 |
|
1/1/2025 |
3/31/2025 |
182.84 |
169.43 |
173.23 |
|
4/1/2025 |
6/30/2025 |
181.74 |
152.93 |
181.74 |
|
7/1/2025 |
9/30/2025 |
190.33 |
181.56 |
189.70 |
|
10/1/2025 |
12/31/2025 |
194.73 |
182.18 |
191.56 |
|
1/1/2026 |
3/31/2026 |
204.97 |
188.07 |
191.92 |
|
4/1/2026 |
6/30/2026 |
213.05 |
192.54 |
212.77 |
|
7/1/2026 |
9/14/2026* |
222.77 |
211.92 |
215.01 |
15
* Available information for the indicated period includes data for less than the entire calendar quarter, and, accordingly, the “Quarterly High,” “Quarterly Low” and “Quarterly Close” data indicated are for this shortened period only.
16
The graph below illustrates the performance of the Invesco S&P 500® Equal Weight ETF from January 1, 2008 through September 14, 2026, based on information from Bloomberg.
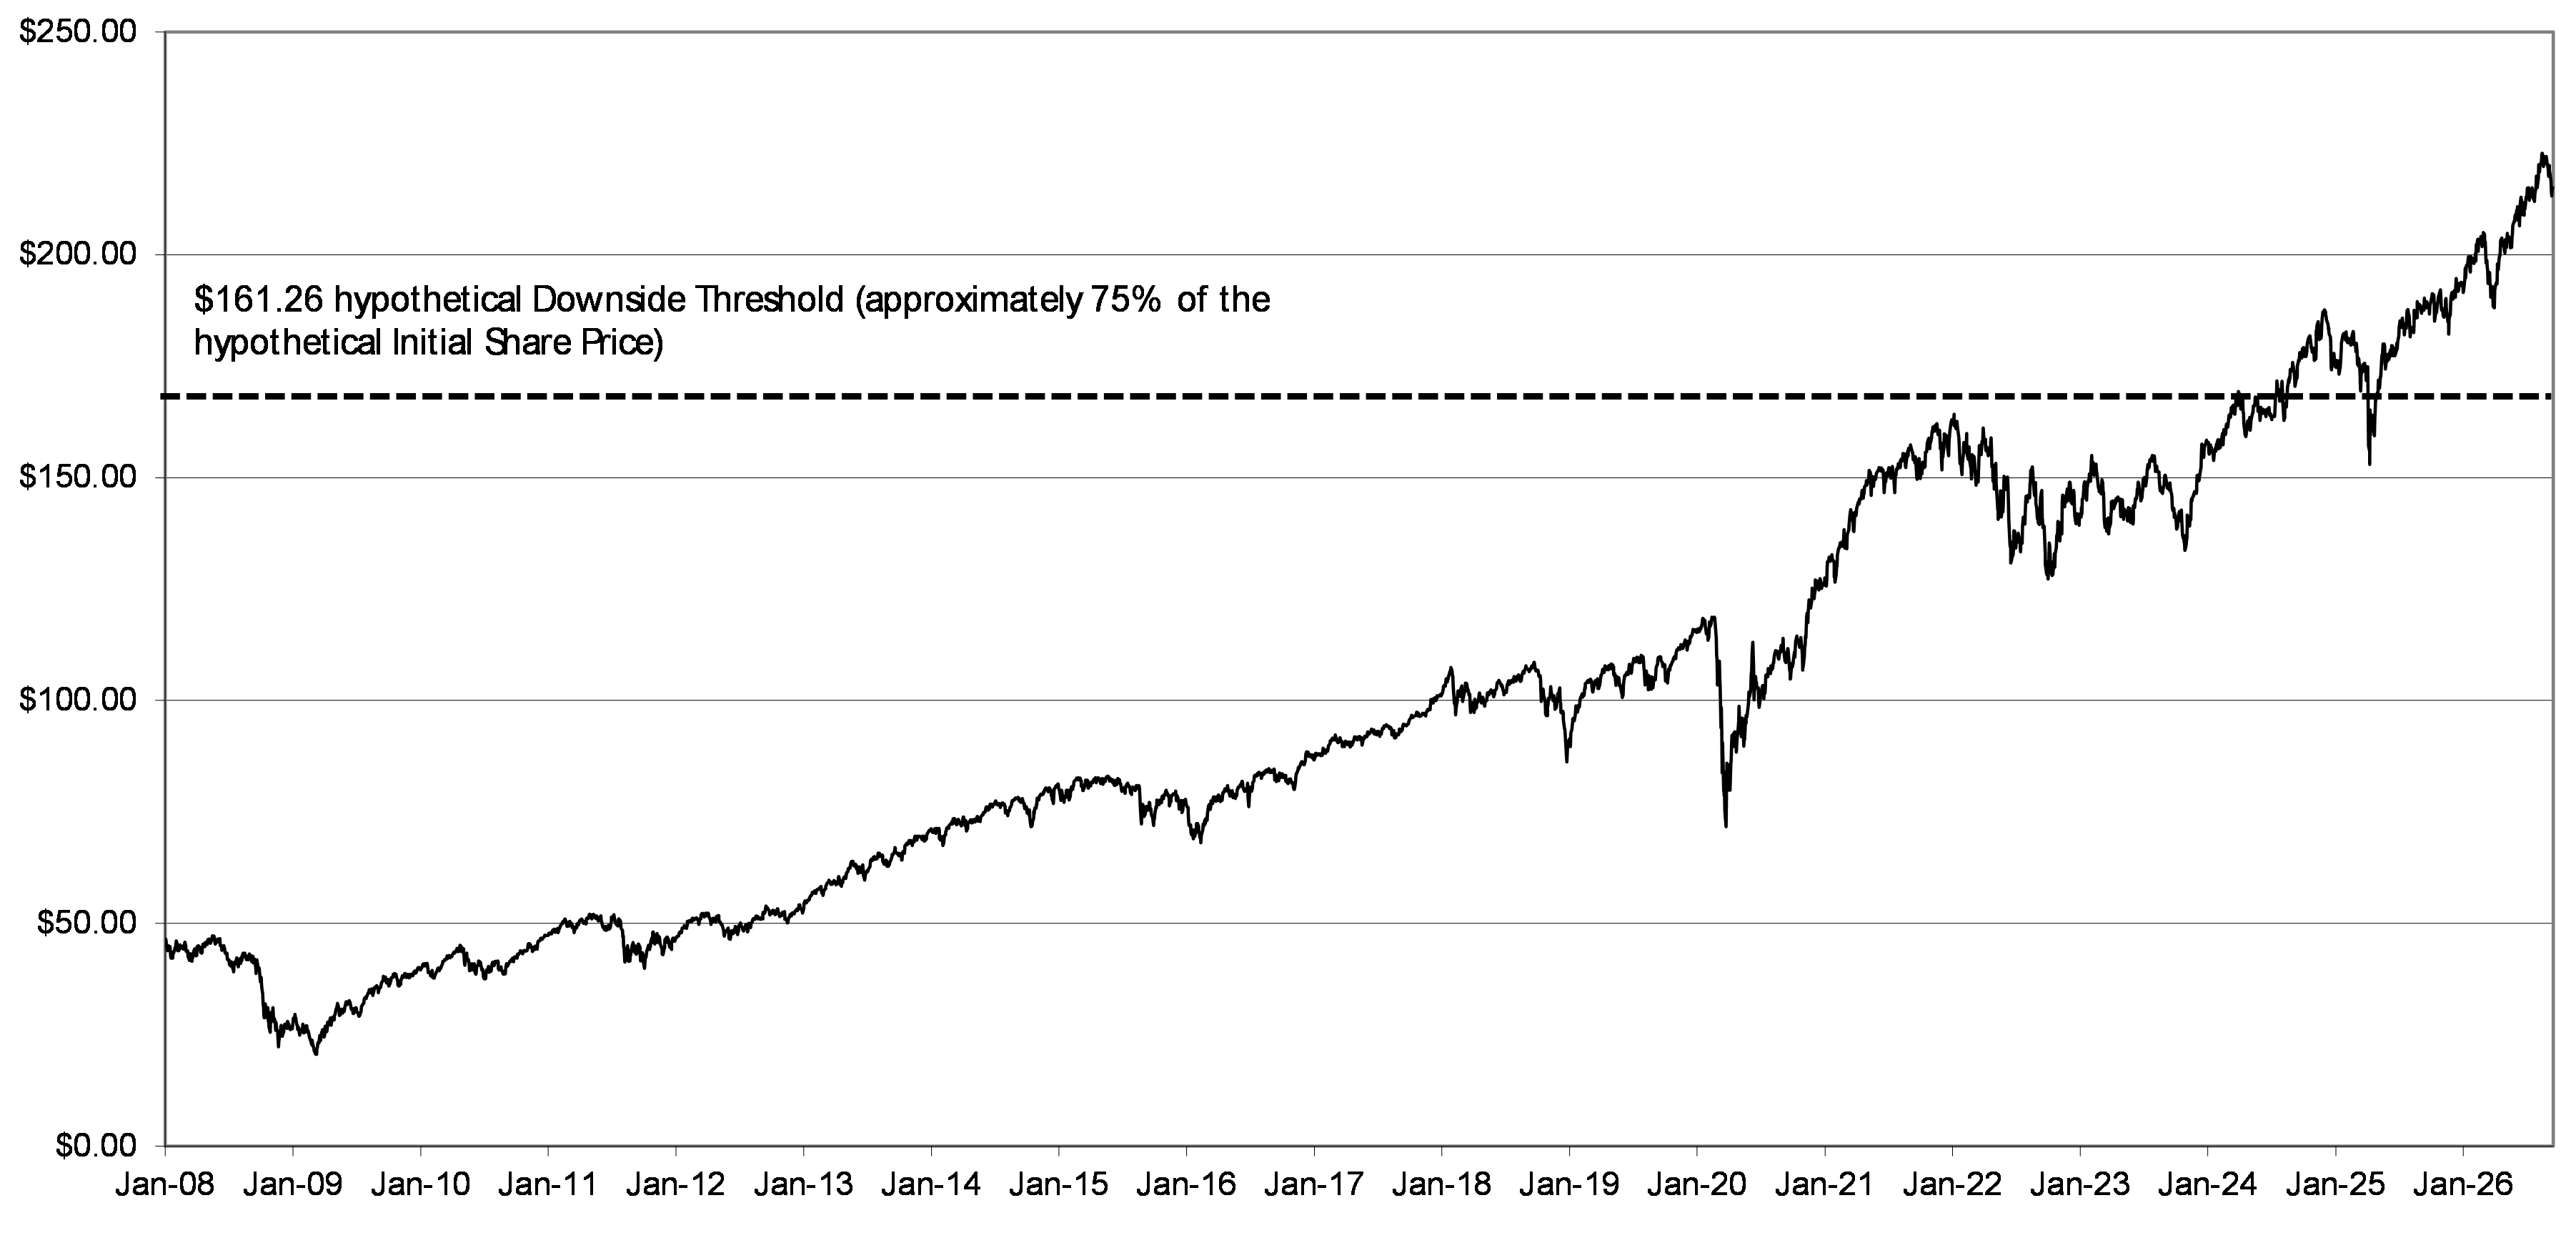
* The dashed line indicates the hypothetical Downside Threshold, assuming the Closing Price of the Invesco S&P 500® Equal Weight ETF on September 14, 2026 were its Initial Underlying Price.
Past performance is not indicative of future results.
17
|
Additional Terms of the Securities |
If the terms described in this preliminary pricing supplement are inconsistent with those described in the accompanying product supplement, index supplement, tax supplement or prospectus, the terms described in this preliminary pricing supplement will prevail.
The accompanying product supplement for autocallable securities refers to the Initial Price as the “initial share price,” the Trade Date as the “pricing date,” the Observation Dates as “determination dates,” the Final Observation Date as the “final determination date,” the Downside Threshold as the “downside threshold price” and the Call Settlement Dates as the “Early Redemption Dates.”
Share Underlying Index
S&P 500® Equal Weight Index
Share Underlying Index Publisher
S&P® Dow Jones Indices LLC or any successor thereto.
“Closing Price” means, on any Trading Day for the Underlying Shares, the closing price of one Underlying Share times the Adjustment Factor on such Trading Day. In certain circumstances, the Closing Price will be based on the alternate calculation of the Underlying Shares or the Share Underlying Index as described under “—Discontinuance of the Underlying Shares of an Exchange-Traded Fund and/or Share Underlying Index; Alteration of Method of Calculation” in the accompanying product supplement.
Issuer Notice to Registered Security Holders, the Trustee and the Depositary
In the event that the Maturity Date of the Securities is postponed due to a postponement of the Final Observation Date, the Issuer shall give notice of such postponement and, once it has been determined, of the date to which the Maturity Date has been rescheduled (i) to each registered holder of the Securities by mailing notice of such postponement by first class mail, postage prepaid, to such registered holder’s last address as it shall appear upon the registry books, (ii) to the Trustee by facsimile confirmed by mailing such notice to the Trustee by first class mail, postage prepaid, at its New York office and (iii) to The Depository Trust Company (the “Depositary”) by telephone or facsimile confirmed by mailing such notice to the Depositary by first class mail, postage prepaid. Any notice that is mailed to a registered holder of the Securities in the manner herein provided shall be conclusively presumed to have been duly given to such registered holder, whether or not such registered holder receives the notice. The Issuer shall give such notice as promptly as possible, and in no case later than (i) with respect to notice of postponement of the Maturity Date, the business day immediately preceding the scheduled Maturity Date and (ii) with respect to notice of the date to which the Maturity Date has been rescheduled, the business day immediately following the Final Observation Date as postponed.
In the event that the Securities are subject to Automatic Call, the Issuer shall, (i) on the business day following the applicable Observation Date, give notice of the Automatic Call and the applicable automatic call payment, including specifying the payment date of the applicable amount due upon the Automatic Call, (x) to each registered holder of the Securities by mailing notice of such Automatic Call by first class mail, postage prepaid, to such registered holder’s last address as it shall appear upon the registry books, (y) to the Trustee by facsimile confirmed by mailing such notice to the Trustee by first class mail, postage prepaid, at its New York office and (z) to the Depositary by telephone or facsimile confirmed by mailing such notice to the Depositary by first class mail, postage prepaid and (ii) on or prior to the Automatic Call Date, deliver the aggregate cash amount due with respect to the Securities to the Trustee for delivery to the Depositary, as holder of the securities. Any notice that is mailed to a registered holder of the Securities in the manner herein provided shall be conclusively presumed to have been duly given to such registered holder, whether or not such registered holder receives the notice. This notice shall be given by the Issuer or, at the Issuer’s request, by the Trustee in the name and at the expense of the Issuer, with any such request to be accompanied by a copy of the notice to be given.
The Issuer shall, or shall cause the Calculation Agent to, (i) provide written notice to the Trustee and to the Depositary of the amount of cash, if any, to be delivered with respect to the Securities, on or prior to 10:30 a.m. (New York City time) on the business day preceding the Maturity Date, and (ii) deliver the aggregate cash amount due with respect to the Securities, if any, to the Trustee for delivery to the Depositary, as holder of the Securities, on or prior to the Maturity Date.
18
|
Additional Information About the Securities |
Use of Proceeds and Hedging
The proceeds from the sale of the Securities will be used by us for general corporate purposes. We will receive, in aggregate, $10 per Security issued, because, when we enter into hedging transactions in order to meet our obligations under the Securities, our hedging counterparty will reimburse the cost of the Agent’s commissions. The costs of the Securities borne by you and described on page 2 above comprise the Agent’s commissions and the cost of issuing, structuring and hedging the Securities. See also “Use of Proceeds” in the accompanying prospectus.
On or prior to the Trade Date, we will hedge our anticipated exposure in connection with the Securities, by entering into hedging transactions with our affiliates and/or third party dealers. We expect our hedging counterparties to take positions in the constituent stocks of the Share Underlying Index, in futures or options contracts on the Share Underlying Index or the constituent stocks of the Share Underlying Index, as well as in other instruments related to the Share Underlying Index that they may wish to use in connection with such hedging. Such purchase activity could potentially increase the Initial Price, and, as a result, the price at or above which the Underlying Shares must close on any Observation Date for the Securities to be called, or the Downside Threshold, which, if the Securities are not called, is the price at or above which the Underlying Shares must close on the Final Observation Date so that you do not suffer a significant loss on your initial investment in the Securities. In addition, through our affiliates, we are likely to modify our hedge position throughout the life of the Securities, including on the Final Observation Date, by purchasing and selling the Underlying Shares, futures or options contracts on the Underlying Shares, or any other securities or instruments that we may wish to use in connection with such hedging activities, including by purchasing or selling any such securities or instruments on the Final Observation Date. As a result, these entities may be unwinding or adjusting hedge positions during the term of the Securities, and the hedging strategy may involve greater and more frequent dynamic adjustments to the hedge as the Final Observation Date approaches. We cannot give any assurance that our hedging activities will not affect the value of the Underlying Shares, and, therefore, affect the value of the Securities, whether the Securities are called, or the payment you will receive at maturity, if any, if the Securities are not called.
Supplemental Plan of Distribution; Conflicts of Interest
MS & Co. will act as the agent for this offering. We will agree to sell to MS & Co., and MS & Co. will agree to purchase, all of the Securities at the issue price less the underwriting discount indicated on the cover of this document. UBS Financial Services Inc., acting as dealer, will receive from MS & Co. a fixed sales commission of $0.175 for each Security it sells.
MS & Co. is our affiliate and a wholly owned subsidiary of Morgan Stanley, and it and other affiliates of ours expect to make a profit by selling, structuring and, when applicable, hedging the Securities. When MS & Co. prices this offering of Securities, it will determine the economic terms of the Securities, including the Call Return Rate, such that for each Security the estimated value on the Trade Date will be no lower than the minimum level described in “Additional Information about Morgan Stanley, MSFL and the Securities” on page 2.
MS & Co. will conduct this offering in compliance with the requirements of Rule 5121 of the Financial Industry Regulatory Authority, Inc. (“FINRA”), regarding a FINRA member firm’s distribution of the securities of an affiliate and related conflicts of interest. MS & Co. or any of our other affiliates may not make sales in this offering to any discretionary account.
In order to facilitate the offering of the Securities, the agent may engage in transactions that stabilize, maintain or otherwise affect the price of the Securities. Specifically, the agent may sell more Securities than it is obligated to purchase in connection with the offering, creating a naked short position in the Securities, for its own account. The agent must close out any naked short position by purchasing the Securities in the open market. A naked short position is more likely to be created if the agent is concerned that there may be downward pressure on the price of the Securities in the open market after pricing that could adversely affect investors who purchase in the offering. As an additional means of facilitating the offering, the agent may bid for, and purchase, the Securities or the constituent stocks of the Underlying Shares in the open market to stabilize the price of the Securities. Any of these activities may raise or maintain the market price of the Securities above independent market levels or prevent or retard a decline in the market price of the Securities. The agent is not required to engage in these activities, and may end any of these activities at any time. An affiliate of the agent has entered into a hedging transaction with us in connection with this offering of Securities. See “—Use of Proceeds and Hedging” above.
19
Serious News for Serious Traders! Try StreetInsider.com Premium Free!
You May Also Be Interested In
- SGF Capital sells $1.9 billion stake in Diamondback Energy
- Morgan Stanley Downgrades Peloton Interactive (PTON) to Underweight
- Egan-Jones backs Garg Group's board removal bid at Better
Create E-mail Alert Related Categories
SEC FilingsRelated Entities
Morgan StanleySign up for StreetInsider Free!
Receive full access to all new and archived articles, unlimited portfolio tracking, e-mail alerts, custom newswires and RSS feeds - and more!
