




Form 424B2 MORGAN STANLEY
 Tweet
 Share
 E-mail
|
Pricing Supplement No. 7,104 Registration Statement Nos. 333-275587; 333-275587-01 Dated March 26, 2025 Filed Pursuant to Rule 424(b)(2) |
Morgan Stanley Finance LLC $4,890,160 Trigger GEARS
Linked to the Least Performing Underlying between the SPDR® Dow Jones® Industrial Average℠ ETF Trust and the Invesco S&P 500® Equal Weight ETF due March 29, 2030
Fully and Unconditionally Guaranteed by Morgan Stanley
Principal at Risk Securities
|
Investment Description |
||||||||||
|
These Trigger GEARS (the “Securities”) are unsecured and unsubordinated debt securities issued by Morgan Stanley Finance LLC (“MSFL”) and fully and unconditionally guaranteed by Morgan Stanley with returns linked to the performance of the Least Performing Underlying Shares between the SPDR® Dow Jones® Industrial Average℠ ETF Trust (the “DIA Shares”) and the Invesco S&P 500® Equal Weight ETF (the “RSP Shares,” and together with the DIA Shares, the “Underlying Shares”). If the Underlying Share Return of each of the DIA Shares and the RSP Shares (each, an “Underlying Shares”) is greater than zero, MSFL will pay the Principal Amount at maturity plus a return equal to the product of (i) the Principal Amount multiplied by (ii) the Underlying Share Return of the Least Performing Underlying Shares multiplied by (iii) the Upside Gearing of 1.293. If the Underlying Share Return of either Underlying Shares is less than or equal to zero, MSFL will either pay the full Principal Amount at maturity, or, if the Final Price of either Underlying Shares is less than its respective Downside Threshold, MSFL will pay significantly less than the full Principal Amount at maturity, if anything, resulting in a loss of principal that is proportionate to the negative Underlying Share Return of the Least Performing Underlying. Because the Payment at Maturity of the Securities is based on the Least Performing Underlying Shares between the DIA Shares and the RSP Shares, the fact that the Securities are linked to two Underlying Shares does not provide any asset diversification benefits and instead means that a decline beyond the relevant Downside Threshold of either the DIA Shares or the RSP Shares will result in a significant loss on your investment, even if the other Underlying Shares appreciates or does not decline as much. These long-dated Securities are for investors who seek an equity fund-based return and who are willing to risk a loss on their principal, risk exposure to the least performing of two Underlying Shares and forgo current income in exchange for the Upside Gearing feature and the contingent repayment of principal, which applies only if the Final Price of each Underlying Shares is not less than its respective Downside Threshold, each as applicable at maturity. Investing in the Securities involves significant risks. You will not receive interest or dividend payments during the term of the Securities. You may lose a significant portion or all of your Principal Amount. The contingent repayment of principal applies only if you hold the Securities to maturity. All payments are subject to our credit risk. If we default on our obligations, you could lose some or all of your investment. These Securities are not secured obligations and you will not have any security interest in, or otherwise have any access to, any underlying reference asset or assets. |
||||||||||
|
Features |
|
Key Dates |
||||||||
|
❑Enhanced Growth Potential: If the Underlying Share Return of each Underlying Shares is greater than zero, the Upside Gearing feature will provide leveraged exposure to the positive performance of the Least Performing Underlying Shares, and MSFL will pay the Principal Amount at maturity plus pay a return equal to the Underlying Share Return of the Least Performing Underlying Shares multiplied by the Upside Gearing. If the Underlying Share Return of either Underlying Shares is less than zero, investors may be exposed to the negative Underlying Share Return of the Least Performing Underlying Shares at maturity. ❑Contingent Repayment of Principal at Maturity: If the Underlying Share Return of either Underlying Shares is equal to or less than zero and the Final Price of each Underlying Shares is not less than its respective Downside Threshold, MSFL will pay the Principal Amount at maturity. However, if the Final Price of either Underlying Shares is less than its respective Downside Threshold, MSFL will pay less than the full Principal Amount, if anything, resulting in a significant loss of principal that is proportionate to the negative Underlying Share Return of the Least Performing Underlying. The contingent repayment of principal applies only if you hold the Securities to maturity. Any payment on the Securities, including any repayment of principal, is subject to our creditworthiness. |
|
Trade Date |
March 26, 2025 |
|||||||
|
|
Settlement Date |
March 31, 2025 |
||||||||
|
|
Final Valuation Date* |
March 26, 2030 |
||||||||
|
|
Maturity Date* |
March 29, 2030 |
||||||||
|
|
*Subject to postponement in the event of a Market Disruption Event or for non-Trading Days. See “Postponement of Final Valuation Date and Maturity Date” under “Additional Terms of the Securities.” |
|||||||||
|
The Securities are significantly riskier than conventional debt INSTRUMENTS. the terms of the securities may not obligate us TO REPAY THE FULL PRINCIPAL AMOUNT OF THE SECURITIES. the Securities CAN have downside MARKET risk SIMILAR TO THE LEAST PERFORMING OF THE TWO UNDERLYING SHARES, WHICH CAN RESULT IN A LOSS OF A SIGNIFICANT PORTION OR ALL OF YOUR INVESTMENT at maturity. This MARKET risk is in addition to the CREDIT risk INHERENT IN PURCHASING our DEBT OBLIGATIONS. You should not PURCHASE the Securities if you do not understand or are not comfortable with the significant risks INVOLVED in INVESTING IN the Securities. THE SECURITIES WILL NOT BE LISTED ON ANY SECURITIES EXCHANGE. YOU SHOULD CAREFULLY CONSIDER THE RISKS DESCRIBED UNDER ‘‘KEY RISKS’’ BEGINNING ON PAGE 5 OF THIS PRICING SUPPLEMENT IN CONNECTION WITH YOUR PURCHASE OF THE SECURITIES. EVENTS RELATING TO ANY OF THOSE RISKS, OR OTHER RISKS AND UNCERTAINTIES, COULD ADVERSELY AFFECT THE MARKET VALUE OF, AND THE RETURN ON, YOUR SECURITIES. |
||||||||||
|
Security Offering |
||||||||||
|
We are offering Trigger GEARS linked to the Least Performing Underlying Shares between the SPDR® Dow Jones® Industrial Average℠ ETF Trust and the Invesco S&P 500® Equal Weight ETF. The Securities are not subject to a predetermined maximum gain and, accordingly, any return at maturity will be determined by the performance of the Least Performing Underlying Shares. The Securities are offered at a minimum investment of 100 Securities at the Price to Public listed below. |
||||||||||
|
Underlying Shares |
Initial Price |
Downside Threshold |
Upside Gearing |
CUSIP |
ISIN |
|||||
|
SPDR® Dow Jones® Industrial Average℠ ETF Trust |
$424.23 |
$318.17, which is approximately 75% of the Initial Price |
1.293 |
61777V856 |
US61777V8569 |
|||||
|
Invesco S&P 500® Equal Weight ETF |
$174.94 |
$131.21, which is approximately 75% of the Initial Price |
|
|||||||
See “Additional Information about Morgan Stanley, MSFL and the Securities” on page 2. The Securities will have the terms set forth in the accompanying prospectus, prospectus supplement and index supplement and this pricing supplement.
Neither the Securities and Exchange Commission nor any other regulatory body has approved or disapproved of these Securities or passed upon the adequacy or accuracy of this pricing supplement or the accompanying prospectus supplement, index supplement and prospectus. Any representation to the contrary is a criminal offense. The Securities are not deposits or savings accounts and are not insured by the Federal Deposit Insurance Corporation or any other governmental agency or instrumentality, nor are they obligations of, or guaranteed by, a bank.
|
Estimated value on the Trade Date |
$9.439 per Security. See “Additional Information about Morgan Stanley, MSFL and the Securities” on page 2. |
|||
|
|
Price to Public |
Underwriting Discount(1) |
Proceeds to Us(2) |
|
|
Per Security |
$10.00 |
$0.35 |
$9.65 |
|
|
Total |
$4,890,160 |
$171,155.60 |
$4,719,004.40 |
|
(1) UBS Financial Services Inc., acting as dealer, will receive from Morgan Stanley & Co. LLC, the agent, a fixed sales commission of $0.35 for each Security it sells. For more information, please see “Supplemental Plan of Distribution; Conflicts of Interest” on page 27 of this pricing supplement.
(2) See “Use of Proceeds and Hedging” on page 27.
The agent for this offering, Morgan Stanley & Co. LLC, is our affiliate and a wholly owned subsidiary of Morgan Stanley. See “Supplemental Plan of Distribution; Conflicts of Interest” on page 27 of this pricing supplement.
Morgan Stanley UBS Financial Services Inc.
|
Additional Information about Morgan Stanley, MSFL and the Securities |
Morgan Stanley and MSFL have filed a registration statement (including a prospectus, as supplemented by a prospectus supplement and an index supplement) with the SEC for the offering to which this communication relates. In connection with your investment, you should read the prospectus in that registration statement, the prospectus supplement, the index supplement and any other documents relating to this offering that Morgan Stanley and MSFL have filed with the SEC for more complete information about Morgan Stanley, MSFL and this offering. When you read the accompanying prospectus supplement and index supplement, please note that all references in such supplements to the prospectus dated November 16, 2023, or to any sections therein, should refer instead to the accompanying prospectus dated April 12, 2024 or to the corresponding sections of such prospectus, as applicable. You may get these documents for free by visiting EDGAR on the SEC website at.www.sec.gov. Alternatively, Morgan Stanley, MSFL, any underwriter or any dealer participating in this offering will arrange to send you the prospectus, the prospectus supplement and the index supplement if you so request by calling toll-free 1-(800)-584-6837.
You may access the accompanying prospectus supplement, index supplement and prospectus on the SEC website at.www.sec.gov as follows:
♦Prospectus supplement dated November 16, 2023:
https://www.sec.gov/Archives/edgar/data/895421/000095010323016325/dp202714_4242-seriesa.htm
♦Index supplement dated November 16, 2023:
https://www.sec.gov/Archives/edgar/data/895421/000095010323016332/dp202718_424b2-isn2023.htm
♦Prospectus dated April 12, 2024:
https://www.sec.gov/Archives/edgar/data/895421/000095010324005205/dp209505_424b2-base.htm
References to “MSFL” refer only to MSFL, references to “Morgan Stanley” refer only to Morgan Stanley and references to “we,” “our” and “us” refer to MSFL and Morgan Stanley collectively. In this document, the “Securities” refers to the Trigger GEARS that are offered hereby. Also, references to the accompanying “prospectus,” “prospectus supplement” and “index supplement” mean the prospectus filed by MSFL and Morgan Stanley dated April 12, 2024, the prospectus supplement filed by MSFL and Morgan Stanley dated November 16, 2023 and the index supplement filed by MSFL and Morgan Stanley dated November 16, 2023, respectively.
You should rely only on the information incorporated by reference or provided in this pricing supplement or the accompanying prospectus supplement, index supplement and prospectus. We have not authorized anyone to provide you with different information. We are not making an offer of these Securities in any state where the offer is not permitted. You should not assume that the information in this pricing supplement or the accompanying prospectus supplement, index supplement and prospectus is accurate as of any date other than the date on the front of this document.
The Issue Price of each Security is $10. This price includes costs associated with issuing, selling, structuring and hedging the Securities, which are borne by you, and, consequently, the estimated value of the Securities on the Trade Date is less than $10. We estimate that the value of each Security on the Trade Date is $9.439.
What goes into the estimated value on the Trade Date?
In valuing the Securities on the Trade Date, we take into account that the Securities comprise both a debt component and a performance-based component linked to the Underlying Shares. The estimated value of the Securities is determined using our own pricing and valuation models, market inputs and assumptions relating to the Underlying Shares, instruments based on the Underlying Shares, volatility and other factors including current and expected interest rates, as well as an interest rate related to our secondary market credit spread, which is the implied interest rate at which our conventional fixed rate debt trades in the secondary market.
What determines the economic terms of the Securities?
In determining the economic terms of the Securities, including the Upside Gearing and the Downside Thresholds, we use an internal funding rate, which is likely to be lower than our secondary market credit spreads and therefore advantageous to us. If the issuing, selling, structuring and hedging costs borne by you were lower or if the internal funding rate were higher, one or more of the economic terms of the Securities would be more favorable to you.
What is the relationship between the estimated value on the Trade Date and the secondary market price of the Securities?
The price at which MS & Co. purchases the Securities in the secondary market, absent changes in market conditions, including those related to the Underlying Shares, may vary from, and be lower than, the estimated value on the Trade Date, because the secondary market price takes into account our secondary market credit spread as well as the bid-offer spread that MS & Co. would charge in a secondary market transaction of this type and other factors. However, because the costs associated with issuing, selling, structuring and hedging the Securities are not fully deducted upon issuance, for a period of up to 12 months following the Settlement Date, to the extent that MS & Co. may buy or sell the Securities in the secondary market, absent changes in market conditions, including those related to the Underlying Shares, and to our secondary market credit spreads, it would do so based on values higher than the estimated value. We expect that those higher values will also be reflected in your brokerage account statements.
MS & Co. currently intends, but is not obligated, to make a market in the Securities, and, if it once chooses to make a market, may cease doing so at any time.
2
|
Investor Suitability |
|
|
The Securities may be suitable for you if: ♦You fully understand the risks inherent in an investment in the Securities, including the risk of loss of your entire initial investment. ♦You can tolerate a loss of all or a substantial portion of your Principal Amount and are willing to make an investment that may have the same downside market risk as an investment in the Least Performing Underlying Shares. ♦You understand and accept the risks associated with the Underlying Shares. ♦You understand that the linkage to two Underlying Shares does not provide any portfolio diversification benefits and instead means that a decline beyond the relevant Downside Threshold of either Underlying Shares will result in a significant loss on your investment, even if the other Underlying Shares appreciates. ♦You are willing to hold the Securities to maturity, as set forth on the cover of this pricing supplement, and accept that there may be little or no secondary market for the Securities. ♦You believe the Underlying Shares will appreciate over the term of the Securities, and you are willing to invest in the Securities based on the Upside Gearing of 1.293. ♦You can tolerate fluctuations of the price of the Securities prior to maturity that may be similar to or exceed the downside fluctuations in the prices of the Underlying Shares. ♦You do not seek current income from your investment and are willing to forgo dividends paid on the Underlying Shares. ♦You are willing to assume our credit risk, and understand that if we default on our obligations you may not receive any amounts due to you including any repayment of principal.
|
The Securities may not be suitable for you if: ♦You do not fully understand the risks inherent in an investment in the Securities, including the risk of loss of your entire initial investment. ♦You cannot tolerate a loss of all or a substantial portion of your Principal Amount, and you are not willing to make an investment that may have the same downside market risk as an investment in the Least Performing Underlying Shares. ♦You require an investment designed to provide a full return of principal at maturity. ♦You do not understand and accept the risks associated with the Underlying Shares. ♦You are not comfortable with an investment linked to two Underlying Shares such that a decline beyond the relevant Downside Threshold of either Underlying Shares will result in a significant loss on your investment, even if the other Underlying Shares appreciates. ♦You are unable or unwilling to hold the Securities to maturity, as set forth on the cover of this pricing supplement, or you seek an investment for which there will be an active secondary market. ♦You believe that the prices of the Underlying Shares will decline during the term of the Securities and that the Final Price of either Underlying Shares is likely to close below its respective Downside Threshold on the Final Valuation Date. ♦You are not willing to invest in the Securities based on the Upside Gearing of 1.293. ♦You prefer the lower risk, and, therefore, accept the potentially lower returns, of conventional debt securities with comparable maturities issued by us or another issuer with a similar credit rating. ♦You seek current income from your investment or prefer to receive the dividends paid on the Underlying Shares. ♦You are not willing or are unable to assume the credit risk associated with us for any payment on the Securities, including any repayment of principal.
|
The investor suitability considerations identified above are not exhaustive. Whether or not the Securities are a suitable investment for you will depend on your individual circumstances, and you should reach an investment decision only after you and your investment, legal, tax, accounting and other advisors have carefully considered the suitability of an investment in the Securities in light of your particular circumstances. You should also review “Key Risks” on page 5 of this pricing supplement and “Risk Factors” beginning on page 7 of the accompanying prospectus for risks related to an investment in the Securities. For additional information about the Underlying Shares, see the information set forth under “SPDR® Dow Jones® Industrial Average℠ ETF Trust” on page 17 and “Invesco S&P 500® Equal Weight ETF” on page 19.
3
|
Final Terms |
|
Investment Timeline |
||
|
Issuer |
Morgan Stanley Finance LLC |
|
|
The Closing Price of each Underlying Shares (the respective Initial Price) was observed, the Downside Thresholds were determined and the Upside Gearing was set. |
|
Guarantor |
Morgan Stanley |
|
||
|
Issue Price (per Security) |
$10.00 per Security |
|
||
|
Principal Amount |
$10.00 per Security |
|
||
|
Term |
Approximately 5 years |
|
||
|
Underlying Shares |
SPDR® Dow Jones® Industrial Average℠ ETF Trust and Invesco S&P 500® Equal Weight ETF |
|
|
|
|
Downside Threshold |
With respect to the DIA Shares, $318.17, which is approximately 75% of the Initial Price of such Underlying Shares With respect to the RSP Shares, $131.21, which is approximately 75% of the Initial Price of such Underlying Shares |
|
|
|
|
Upside Gearing |
1.293 |
|
The Final Price and Underlying Share Return of each Underlying Shares are determined on the Final Valuation Date.
If the Underlying Share Return of each Underlying Shares is greater than zero, MSFL will pay you a cash payment per Security equal to:
$10 + [$10 × (Underlying Share Return of the Least Performing Underlying Shares × Upside Gearing)]
If the Underlying Share Return of either Underlying Shares is less than or equal to zero and the Final Price of each Underlying Shares is greater than or equal to its respective Downside Threshold on the Final Valuation Date, MSFL will pay you a cash payment of $10 per $10 Security.
If the Final Price of either Underlying Shares is less than its respective Downside Threshold on the Final Valuation Date, MSFL will pay you a cash payment at maturity equal to:
$10 + ($10 × Underlying Share Return of the Least Performing Underlying Shares)
Under these circumstances, you will lose a significant portion, and could lose all, of your Principal Amount. |
|
|
Payment at Maturity (per Security) |
If the Underlying Share Return of each Underlying Shares is greater than zero, MSFL will pay you an amount calculated as follows: $10 + [$10 × (Underlying Share Return of the Least Performing Underlying Shares × Upside Gearing)] If the Underlying Share Return of either Underlying Shares is less than or equal to zero and the Final Price of each Underlying Shares is greater than or equal to its respective Downside Threshold, MSFL will pay you a cash payment of: $10 per Security If the Final Price of either Underlying Shares is less than its respective Downside Threshold, MSFL will pay you an amount calculated as follows: $10 + ($10 × Underlying Share Return of the Least Performing Underlying Shares) In this case, you could lose up to all of your Principal Amount in an amount proportionate to the negative Underlying Share Return of the Least Performing Underlying. |
|
||
|
Underlying Share Return
|
Final Price – Initial Price Initial Price |
|
||
|
Least Performing Underlying Shares |
The Underlying Shares with the lesser Underlying Share Return. |
|
||
|
Initial Price |
With respect to the DIA Shares, $424.23 With respect to the RSP Shares, $174.94 |
|
||
|
Final Price |
With respect to each Underlying Shares, the Closing Price of such Underlying Shares on the Final Valuation Date. |
|
||
|
Trade Date |
March 26, 2025 |
|
||
|
Settlement Date |
March 31, 2025 |
|
||
|
Final Valuation Date |
March 26, 2030* |
|
||
|
Maturity Date |
March 29, 2030* |
|
||
|
Adjustment Factor |
For each of the Underlying Shares, 1.0, subject to adjustment in the event of certain corporate events affecting such Underlying Shares. |
|
||
|
CUSIP / ISIN |
61777V856 / US61777V8569 |
|
||
|
Calculation Agent |
Morgan Stanley & Co. LLC |
|
||
|
*Subject to postponement in the event of a Market Disruption Event or for non-Trading Days. See “Postponement of Final Valuation Date and Maturity Date” under “Additional Terms of the Securities,” below. |
|
|||
INVESTING IN THE SECURITIES INVOLVES SIGNIFICANT RISKS. YOU MAY LOSE YOUR ENTIRE PRINCIPAL AMOUNT. ANY PAYMENT ON THE SECURITIES IS SUBJECT TO OUR CREDITWORTHINESS. IF WE WERE TO DEFAULT ON OUR PAYMENT OBLIGATIONS, YOU MAY NOT RECEIVE ANY AMOUNTS OWED TO YOU UNDER THE SECURITIES AND YOU COULD LOSE YOUR ENTIRE INVESTMENT.
4
|
Key Risks |
An investment in the Securities involves significant risks. The material risks that apply to the Securities are summarized here, but we urge you to also read the “Risk Factors” section of the accompanying prospectus. You should also consult your investment, legal, tax, accounting and other advisers in connection with your investment in the Securities.
Risks Relating to an Investment in the Securities
♦The Securities do not guarantee any return of principal – The terms of the Securities differ from those of ordinary debt securities in that MSFL is not necessarily obligated to repay any of the Principal Amount at maturity. If the Final Price of either Underlying Shares is less than its respective Downside Threshold (which is 75% of the respective Initial Price), you will be exposed to the full negative Underlying Share Return of the Least Performing Underlying Shares and the payout owed at maturity by MSFL will be an amount in cash that is at least 25% less than the $10 Principal Amount of each Security, resulting in a loss proportionate to the decrease in the value of the Least Performing Underlying Shares from the Initial Price to the Final Price. There is no minimum payment at maturity on the Securities, and, accordingly, you could lose all of your Principal Amount in the Securities.
♦You may incur a loss on your investment if you sell your Securities prior to maturity – The Downside Thresholds are observed on the Final Valuation Date, and the contingent repayment of principal applies only at maturity. If you are able to sell your Securities in the secondary market prior to maturity, you may have to sell them at a loss relative to your initial investment even if the Closing Prices of the Underlying Shares are above their respective Downside Thresholds at that time.
♦The Upside Gearing applies only if you hold the Securities to maturity – You should be willing to hold your Securities to maturity. If you are able to sell your Securities prior to maturity in the secondary market, the price you receive will likely not reflect the full economic value of the Upside Gearing or the Securities themselves, and the return you realize may be less than the Least Performing Underlying Shares’ return even if such return is positive. You can receive the full benefit of the Upside Gearing from MSFL only if you hold your Securities to maturity.
♦The Securities are subject to our credit risk, and any actual or anticipated changes to our credit ratings or our credit spreads may adversely affect the market value of the Securities – You are dependent on our ability to pay all amounts due on the Securities at maturity, if any, and therefore you are subject to our credit risk. If we default on our obligations under the Securities, your investment would be at risk and you could lose some or all of your investment. As a result, the market value of the Securities prior to maturity will be affected by changes in the market’s view of our creditworthiness. Any actual or anticipated decline in our credit ratings or increase in our credit spreads charged by the market for taking our credit risk is likely to adversely affect the market value of the Securities.
♦As a finance subsidiary, MSFL has no independent operations and will have no independent assets – As a finance subsidiary, MSFL has no independent operations beyond the issuance and administration of its securities and will have no independent assets available for distributions to holders of MSFL securities if they make claims in respect of such securities in a bankruptcy, resolution or similar proceeding. Accordingly, any recoveries by such holders will be limited to those available under the related guarantee by Morgan Stanley and that guarantee will rank pari passu with all other unsecured, unsubordinated obligations of Morgan Stanley. Holders will have recourse only to a single claim against Morgan Stanley and its assets under the guarantee. Holders of securities issued by MSFL should accordingly assume that in any such proceedings they would not have any priority over and should be treated pari passu with the claims of other unsecured, unsubordinated creditors of Morgan Stanley, including holders of Morgan Stanley-issued securities.
♦The Securities do not pay interest – MSFL will not pay any interest with respect to the Securities over the term of the Securities.
♦The market price of the Securities may be influenced by many unpredictable factors – Several factors, many of which are beyond our control, will influence the value of the Securities in the secondary market and the price at which MS & Co. may be willing to purchase or sell the Securities in the secondary market (if at all), including:
othe prices of the Underlying Shares at any time,
othe volatility (frequency and magnitude of changes in price) of the Underlying Shares,
ointerest and yield rates in the market,
ogeopolitical conditions and economic, financial, political, regulatory or judicial events that affect the Underlying Shares or stock markets generally and which may affect the Initial Prices and/or the Final Prices,
othe time remaining until the Securities mature, and
oany actual or anticipated changes in our credit ratings or credit spreads.
Some or all of these factors will influence the terms of the Securities at the time of issuance and the price that you will receive if you are able to sell your Securities prior to maturity, as the Securities are comprised of both a debt component and a performance-based component linked to the Underlying Shares, and these are the types of factors that also generally affect the values of debt securities and derivatives linked to the Underlying Shares. Generally, the longer the time remaining to maturity, the more the market price of the Securities will be affected by the other factors described above. For example, you may have to sell your Securities at a substantial discount from the principal amount of $10 per Security if the value of
5
either Underlying Shares at the time of sale is at, below or moderately above its respective Initial Price, and especially if it is near or below its respective Downside Threshold, or if market interest rates rise. The value of each of the Underlying Shares may be, and each has recently been, volatile, and we can give you no assurance that the volatility will lessen. See “Historical Information” below. You cannot predict the future performance of the Underlying Shares based on their historical performance.
♦The amount payable on the Securities is not linked to the prices of the Underlying Shares at any time other than the Final Valuation Date – The Final Price of each Underlying Shares will be based on the Closing Price of such Underlying Shares on the Final Valuation Date, subject to postponement for non-Trading Business Days and certain Market Disruption Events. Even if both Underlying Shares appreciate prior to the Final Valuation Date but the price of either Underlying Shares drops by the Final Valuation Date, the Payment at Maturity may be significantly less than it would have been had the Payment at Maturity been linked to the prices of the Underlying Shares prior to such drop. Although the actual prices of the Underlying Shares on the stated Maturity Date or at other times during the term of the Securities may be higher than their respective Final Prices, the Payment at Maturity will be based solely on the Closing Prices of the Underlying Shares on the Final Valuation Date as compared to their Initial Prices.
♦Investing in the Securities is not equivalent to investing in the Underlying Shares or the stocks composing the Share Underlying Indices – Investing in the Securities is not equivalent to investing in the Underlying Shares, the Share Underlying Indices or the stocks that constitute the Share Underlying Indices. Investors in the Securities will not have voting rights or rights to receive dividends or other distributions or any other rights with respect to the Underlying Shares or the stocks that constitute the Share Underlying Indices.
♦The rate we are willing to pay for securities of this type, maturity and issuance size is likely to be lower than the rate implied by our secondary market credit spreads and advantageous to us. Both the lower rate and the inclusion of costs associated with issuing, selling, structuring and hedging the Securities in the Issue Price reduce the economic terms of the Securities, cause the estimated value of the Securities to be less than the Issue Price and will adversely affect secondary market prices – Assuming no change in market conditions or any other relevant factors, the prices, if any, at which dealers, including MS & Co., may be willing to purchase the Securities in secondary market transactions will likely be significantly lower than the Issue Price, because secondary market prices will exclude the issuing, selling, structuring and hedging-related costs that are included in the Issue Price and borne by you and because the secondary market prices will reflect our secondary market credit spreads and the bid-offer spread that any dealer would charge in a secondary market transaction of this type as well as other factors.
The inclusion of the costs of issuing, selling, structuring and hedging the Securities in the Issue Price and the lower rate we are willing to pay as issuer make the economic terms of the Securities less favorable to you than they otherwise would be.
However, because the costs associated with issuing, selling, structuring and hedging the Securities are not fully deducted upon issuance, for a period of up to 12 months following the Settlement Date, to the extent that MS & Co. may buy or sell the Securities in the secondary market, absent changes in market conditions, including those related to the Underlying Shares, and to our secondary market credit spreads, it would do so based on values higher than the estimated value, and we expect that those higher values will also be reflected in your brokerage account statements.
♦The estimated value of the Securities is determined by reference to our pricing and valuation models, which may differ from those of other dealers and is not a maximum or minimum secondary market price – These pricing and valuation models are proprietary and rely in part on subjective views of certain market inputs and certain assumptions about future events, which may prove to be incorrect. As a result, because there is no market-standard way to value these types of securities, our models may yield a higher estimated value of the Securities than those generated by others, including other dealers in the market, if they attempted to value the Securities. In addition, the estimated value on the Trade Date does not represent a minimum or maximum price at which dealers, including MS & Co., would be willing to purchase your Securities in the secondary market (if any exists) at any time. The value of your Securities at any time after the date of this pricing supplement will vary based on many factors that cannot be predicted with accuracy, including our creditworthiness and changes in market conditions. See also “The market price of the Securities may be influenced by many unpredictable factors” above.
♦The Securities will not be listed on any securities exchange and secondary trading may be limited – The Securities will not be listed on any securities exchange. Therefore, there may be little or no secondary market for the Securities. MS & Co. currently intends, but is not obligated, to make a market in the Securities and, if it once chooses to make a market, may cease doing so at any time. When it does make a market, it will generally do so for transactions of routine secondary market size at prices based on its estimate of the current value of the Securities, taking into account its bid/offer spread, our credit spreads, market volatility, the notional size of the proposed sale, the cost of unwinding any related hedging positions, the time remaining to maturity and the likelihood that it will be able to resell the Securities. Even if there is a secondary market, it may not provide enough liquidity to allow you to trade or sell the Securities easily. Since other broker-dealers may not participate significantly in the secondary market for the Securities, the price at which you may be able to trade your Securities is likely to depend on the price, if any, at which MS & Co. is willing to transact. If, at any time, MS & Co. were to cease making a market in the Securities, it is likely that there would be no secondary market for the Securities. Accordingly, you should be willing to hold your Securities to maturity.
6
♦Hedging and trading activity by our affiliates could potentially adversely affect the value of the Securities – One or more of our affiliates and/or third-party dealers expect to carry out hedging activities related to the Securities, including trading in the Underlying Shares or the stocks that constitute the Share Underlying Indices, in futures or options contracts on the Underlying Shares, the Share Underlying Indices or the constituent stocks of the Underlying Shares or the Share Underlying Indices, as well as in other instruments related to the Underlying Shares or the Share Underlying Indices. As a result, these entities may be unwinding or adjusting hedge positions during the term of the Securities, and the hedging strategy may involve greater and more frequent dynamic adjustments to the hedge as the Final Valuation Date approaches. MS & Co. and some of our other affiliates also trade the Underlying Shares or the stocks that constitute the Share Underlying Indices, in futures or options contracts on the Underlying Shares, the Share Underlying Indices or the constituent stocks of the Share Underlying Indices, as well as in other instruments related to the Underlying Shares or the Share Underlying Indices, on a regular basis as part of their general broker-dealer and other businesses. Any of these hedging or trading activities on or prior to the Trade Date could potentially increase the Initial Prices of either of the Underlying Shares, and, therefore, could increase the Downside Threshold of such Underlying Shares, which is the price at or above which such Underlying Shares must close on the Final Valuation Date so that investors do not suffer a significant loss on their initial investment in the Securities (depending also on the performance of the other Underlying Shares). Additionally, such hedging or trading activities during the term of the Securities, including on the Final Valuation Date, could adversely affect the Closing Prices of either of the Underlying Shares on the Final Valuation Date, and, accordingly, the amount of cash payable at maturity, if any (depending also on the performance of the other Underlying Shares).
♦Potential conflict of interest – As Calculation Agent, MS & Co. will determine the Initial Prices, the Downside Threshold, the Upside Gearing, the Final Prices and whether any Market Disruption Event has occurred, and will calculate the amount payable at maturity, if any. Moreover, certain determinations made by MS & Co., in its capacity as Calculation Agent, may require it to exercise discretion and make subjective judgments, such as with respect to the occurrence or non-occurrence of Market Disruption Events, any adjustment to an Adjustment Factor and the selection of a Successor Index or calculation of the Final Prices in the event of a discontinuance of a Share Underlying Index or a Market Disruption Event. These potentially subjective determinations may adversely affect the payout to you at maturity, if any. For further information regarding these types of determinations, see “Additional Terms of the Securities—Postponement of Final Valuation Date and Maturity Date,” “—Discontinuance of the Underlying Shares and/or Share Underlying Index; Alteration of Method of Calculation,”“—Calculation Agent and Calculations” and related definitions below. In addition, MS & Co. has determined the estimated value of the Securities on the Trade Date.
♦Potentially inconsistent research, opinions or recommendations by Morgan Stanley, UBS or our or their respective affiliates – Morgan Stanley, UBS and our or their respective affiliates may publish research from time to time on financial markets and other matters that may influence the value of the Securities, or express opinions or provide recommendations that are inconsistent with purchasing or holding the Securities. Any research, opinions or recommendations expressed by Morgan Stanley, UBS or our or their respective affiliates may not be consistent with each other and may be modified from time to time without notice. Investors should make their own independent investigation of the merits of investing in the Securities and the Underlying Shares to which the Securities are linked.
♦The U.S. federal income tax consequences of an investment in the Securities are uncertain – Please note that the discussions in this pricing supplement concerning the U.S. federal income tax consequences of an investment in the Securities supersede the discussions contained in the accompanying prospectus supplement.
Subject to the discussion under “What Are the Tax Consequences of the Securities” in this pricing supplement, although there is uncertainty regarding the U.S. federal income tax consequences of an investment in the Securities due to the lack of governing authority, in the opinion of our counsel, Davis Polk & Wardwell LLP (“our counsel”), under current law, and based on current market conditions, each Security should be treated as a single financial contract that is an “open transaction” for U.S. federal income tax purposes.
Because the Securities are linked to shares of exchange-traded funds, although the matter is not clear, there is a substantial risk that an investment in the Securities will be treated as a “constructive ownership transaction.” If this treatment applies, all or a portion of any long-term capital gain of a U.S. Holder (as defined below) in respect of the Securities could be recharacterized as ordinary income (in which case an interest charge would be imposed). As a result of certain features of the Securities, it is unclear how to calculate the amount of gain that would be recharacterized if an investment in the Securities were treated as a constructive ownership transaction. U.S. Holders should read the section entitled “United States Federal Taxation — Tax Consequences to U.S. Holders — Tax Treatment of the Securities — Potential Application of the Constructive Ownership Rule” in this pricing supplement.
If the Internal Revenue Service (the “IRS”) were successful in asserting an alternative treatment for the Securities, the timing and character of income on the Securities might differ significantly from the tax treatment described herein. For example, under one possible treatment, the IRS could seek to recharacterize the Securities as debt instruments. In that event, U.S. Holders (as defined below) would be required to accrue into income original issue discount on the Securities every year at a “comparable yield” determined at the time of issuance and recognize all income and gain in respect of the Securities as ordinary income. The risk that financial instruments providing for buffers, triggers or similar downside protection features, such as the Securities, would be recharacterized as debt is greater than the risk of recharacterization for comparable financial
7
instruments that do not have such features. We do not plan to request a ruling from the IRS regarding the tax treatment of the Securities, and the IRS or a court may not agree with the tax treatment described in this pricing supplement.
In 2007, the U.S. Treasury Department and the IRS released a notice requesting comments on the U.S. federal income tax treatment of “prepaid forward contracts” and similar instruments. The notice focuses in particular on whether to require holders of these instruments to accrue income over the term of their investment. It also asks for comments on a number of related topics, including the character of income or loss with respect to these instruments; whether short-term instruments should be subject to any such accrual regime; the relevance of factors such as the exchange-traded status of the instruments and the nature of the underlying property to which the instruments are linked; the degree, if any, to which income (including any mandated accruals) realized by Non-U.S. Holders (as defined below) should be subject to withholding tax; and whether these instruments are or should be subject to the “constructive ownership” rule, as discussed above. While the notice requests comments on appropriate transition rules and effective dates, any Treasury regulations or other guidance promulgated after consideration of these issues could materially and adversely affect the tax consequences of an investment in the Securities, possibly with retroactive effect.
Both U.S. and Non-U.S. Holders should read carefully the discussion under “What Are the Tax Consequences of the Securities” in this pricing supplement and consult their tax advisers regarding all aspects of the U.S. federal tax consequences of an investment in the Securities as well as any tax consequences arising under the laws of any state, local or non-U.S. taxing jurisdiction.
Risks Relating to the Underlying Shares
♦You are exposed to the price risk of both Underlying Shares – Your return on the Securities it not linked to a basket consisting of both Underlying Shares. Rather, it will be based upon the independent performance of each Underlying. Unlike an instrument with a return linked to a basket of underlying assets, in which risk is mitigated and diversified among all the components of the basket, you will be exposed to the risks related to both Underlying Shares. Poor performance by either Underlying Shares over the term of the Securities will negatively affect your return and will not be offset or mitigated by any positive performance by the other Underlying Shares. If either Underlying Shares declines to below its respective Downside Threshold as of the Final Valuation Date, you will be exposed to the negative performance of the Least Performing Underlying Shares at maturity, even if the other Underlying Shares has appreciated or has not declined as much, and you will lose a significant portion or all of your investment. Accordingly, your investment is subject to the price risk of both Underlying Shares. Additionally, movements in the values of the Underlying Shares may be correlated or uncorrelated at different times during the term of the Securities, and such correlation (or lack thereof) could have an adverse effect on your return on the Securities. For example, the likelihood that one of the Underlying Shares will close below its Downside Threshold on the Final Valuation Date will increase when the movements in the values of the Underlying Shares are uncorrelated. This results in a greater potential for a significant loss of principal at maturity. If the performance of the Underlying Shares is not correlated or is negatively correlated, the risk of incurring a significant loss of principal at maturity is greater. In addition, correlation generally decreases for each additional Underlying Shares to which the Securities are linked, resulting in a greater potential for a significant loss of principal at maturity.
♦Because the Securities are linked to the performance of the least performing between the DIA Shares and the RSP Shares, you are exposed to greater risk of sustaining a significant loss on your investment than if the Securities were linked to just the DIA Shares or just the RSP Shares – The risk that you will suffer a significant loss on your investment is greater if you invest in the Securities as opposed to substantially similar securities that are linked to just the performance of one Underlying Shares. With two Underlying Shares, it is more likely that either Underlying Shares will decline to below its Downside Threshold as of the Final Valuation Date than if the Securities were linked to only one Underlying. Therefore it is more likely that you will suffer a significant loss on your investment.
♦The probability that the Final Price of either Underlying Shares will be less than its respective Downside Threshold will depend on the volatility of such Underlying Shares – “Volatility” refers to the frequency and magnitude of changes in the prices of the Underlying Shares. Higher expected volatility with respect to the Underlying Shares as of the Trade Date generally indicates a greater chance as of that date that the Final Price of one or both of the Underlying Shares will be less than the respective Downside Thresholds, which would result in a loss of a significant portion or all of your investment at maturity. However, the volatility of the Underlying Shares can change significantly over the term of the Securities. The price of either Underlying Shares could fall sharply, resulting in a significant loss of principal. You should be willing to accept the downside market risk of both Underlying Shares and the potential loss of a significant portion or all of your investment at maturity.
♦The performance and market price of each of the Underlying Shares, particularly during periods of market volatility, may not correlate with the performance of its respective Share Underlying Index, the performance of the component securities of such Share Underlying Index or the net asset value per share of such Underlying Shares – The Underlying Shares do not fully replicate their respective Share Underlying Indices, and each may hold securities that are different than those included in its respective Share Underlying Index. In addition, the performance of each of the Underlying Shares will reflect additional transaction costs and fees that are not included in the calculation of the Share Underlying Indices. All of these factors may lead to a lack of correlation between the performance of each of the Underlying Shares and its respective Share Underlying Index. In addition, corporate actions (such as mergers and spin-offs) with respect to the equity securities underlying each of the Underlying Shares may impact the variance between the performance of each of the Underlying Shares and its respective Share Underlying Index. Finally, because the shares of each of the Underlying
8
Shares is traded on an exchange and are subject to market supply and investor demand, the market price of one share of each of the Underlying Shares may differ from the net asset value per share of such Underlying Shares.
In particular, during periods of market volatility, or unusual trading activity, trading in the securities underlying each of the Underlying Shares may be disrupted or limited, or such securities may be unavailable in the secondary market. Under these circumstances, the liquidity of each Underlying Shares may be adversely affected, market participants may be unable to calculate accurately the net asset value per share of each of the Underlying Shares, and their ability to create and redeem shares of each of the Underlying Shares may be disrupted. Under these circumstances, the market price of shares of each of the Underlying Shares may vary substantially from the net asset value per share of each underlying share or the price of its respective Share Underlying Index.
For all of the foregoing reasons, the performance of each of the Underlying Shares may not correlate with the performance of its respective Share Underlying Index, the performance of the component securities of such Share Underlying Index or the net asset value per share of such Underlying Shares. Any of these events could materially and adversely affect the prices of each of the Underlying Shares and, therefore, the value of the securities. Additionally, if market volatility or these events were to occur on the valuation date, the calculation agent would maintain discretion to determine whether such market volatility or events have caused a market disruption event to occur, and such determination would affect the payment at maturity of the securities. If the calculation agent determines that no market disruption event has taken place, the payment at maturity would be based solely on the published closing price per share of each of the Underlying Shares on the Final Observation Date, even if any of the Underlying Shares is underperforming its respective Share Underlying Index or the component securities of such Share Underlying Index and/or trading below the net asset value per share of such Underlying Shares.
♦Governmental regulatory actions could result in material changes to the composition of the Underlying Shares and could negatively affect your return on the Securities – Governmental regulatory actions, including but not limited to sanctions-related actions by the U.S. or foreign governments, could make it necessary or advisable for there to be material changes to the composition of the Underlying Shares, depending on the nature of such governmental regulatory actions and the Underlying Shares or the constituent stocks of the Share Underlying Indices that are affected. If any governmental regulatory action results in the removal of Underlying Shares or the constituent stocks of the Share Underlying Indices that have (or historically have had) significant weights within the applicable Underlying Shares, such removal, or even any uncertainty relating to a possible removal, could have a material and negative effect on the price of the applicable Underlying Shares and, therefore, your return on the Securities.
♦Adjustments to the SPDR® Dow Jones® Industrial Average℠ ETF Trust or the Invesco S&P 500® Equal Weight ETF could adversely affect the value of the Securities – The investment advisor to each of the SPDR® Dow Jones® Industrial Average℠ ETF Trust and the Invesco S&P 500® Equal Weight ETF (State Street Global Advisors Trust Company for the DIA Shares and Invesco Capital Management LLC for the RSP Shares) seeks investment results that correspond generally to the price and yield performance, before fees and expenses, of the relevant Share Underlying Index. Pursuant to its investment strategy or otherwise, the investment advisor may add, delete or substitute the stocks composing the respective Underlying Shares. Any of these actions could adversely affect the price of the respective Underlying Shares and, consequently, the value of the securities. The Share Underlying Index Publisher is responsible for calculating and maintaining the Share Underlying Indices. The Share Underlying Index Publisher may add, delete or substitute the securities constituting the Share Underlying Indices or make other methodological changes that could change the value of the Share Underlying Indices, and, consequently, the price of the Underlying Shares and the value of the securities. The Share Underlying Index Publisher may discontinue or suspend calculation or publication of a Share Underlying Index at any time. In these circumstances, the calculation agent will have the sole discretion to substitute a Successor Index that is comparable to the discontinued Share Underlying Index, and will be permitted to consider indices that are calculated and published by the calculation agent or any of its affiliates. Any of these actions could adversely affect the price of either Underlying Shares and, consequently, the value of the securities.
♦The adjustments to an Adjustment Factor the Calculation Agent is required to make do not cover every corporate event that can affect the shares of the Underlying Shares – MS & Co., as Calculation Agent, will adjust an Adjustment Factor for certain events affecting the relevant Underlying Shares, including stock splits and reverse stock splits. However, the Calculation Agent will not make an adjustment for every event that can affect the Underlying Shares. If an event occurs that does not require the Calculation Agent to adjust the Adjustment Factor, the market price of the Securities may be materially and adversely affected. The determination by the Calculation Agent to adjust, or not to adjust, an Adjustment Factor may materially and adversely affect the market price of the Securities.
9
|
Scenario Analysis and Examples at Maturity |
These examples are based on hypothetical terms. The actual terms are set forth on the cover of this pricing supplement.
The below scenario analysis and examples are provided for illustrative purposes only and are hypothetical. They do not purport to be representative of every possible scenario concerning increases or decreases in the prices of the Underlying Shares relative to their respective Initial Prices. We cannot predict the Final Price of either Underlying Shares on the Final Valuation Date. You should not take the scenario analysis and these examples as an indication or assurance of the expected performance of the Underlying Shares. The numbers appearing in the examples below have been rounded for ease of analysis. The following scenario analysis and examples illustrate the payment at maturity for a $10.00 security on a hypothetical offering of the Securities, and assume a hypothetical Initial Price for the Least Performing Underlying Shares of $100 and a hypothetical Downside Threshold of $75, based on the following terms*:
|
Investment term: |
Approximately 5 years |
|
Upside Gearing: |
1.293 |
* The hypothetical Initial Price for the Least Performing Underlying Shares of $100 has been chosen for illustrative purposes only and is not the actual Initial Price for either Underlying Shares. The actual Initial Prices and Downside Thresholds for the Underlying Shares are specified on the cover of this pricing supplement.
Example 1— Both Underlying Shares appreciate over the term of the Securities, and the price of the Least Performing Underlying Shares increases from an Initial Price of $100 to a Final Price of $110. The Underlying Share Return of the Least Performing Underlying Shares is greater than zero and expressed as a formula:
Underlying Share Return of the Least Performing Underlying Shares = ($110 - $100) / $100 = 10.00%
Payment at Maturity = $10 + [$10 × (10.00% × 1.293)] = $11.293
Because the Underlying Share Return of the Least Performing Underlying Shares is equal to 10.00%, the Payment at Maturity is equal to $11.293 per $10.00 Principal Amount of Securities, resulting in a total return on the Securities of 12.93%.
Example 2— The Final Price of the Least Performing Underlying Shares is equal to the Initial Price of $100. The Underlying Share Return of the Least Performing Underlying Shares is zero and expressed as a formula:
Underlying Share Return of the Least Performing Underlying Shares = ($100 – $100) / $100 = 0.00%
Payment at Maturity = $10.00
Because the Underlying Share Return of the Least Performing Underlying Shares is zero, the Payment at Maturity per Security is equal to the original $10.00 Principal Amount per Security, resulting in a zero percent return on the Securities, even though the other Underlying Shares has appreciated.
Example 3— The price of the Least Performing Underlying Shares decreases from an Initial Price of $100 to a Final Price of $90. The Underlying Share Return of the Least Performing Underlying Shares is negative and expressed as a formula:
Underlying Share Return of the Least Performing Underlying Shares = ($90 - $100) / $100 = -10.00%
Payment at Maturity = $10.00
Because the Underlying Share Return of the Least Performing Underlying Shares is less than zero, but the Final Price of the Least Performing Underlying Shares is greater than or equal to its Downside Threshold on the Final Valuation Date, MSFL will pay you a Payment at Maturity equal to $10.00 per $10.00 Principal Amount of Securities, resulting in a zero percent return on the Securities, even if the other Underlying Shares has appreciated.
Example 4— The price of the Least Performing Underlying Shares decreases from an Initial Price of $100 to a Final Price of $40. The Underlying Share Return of the Least Performing Underlying Shares is negative and expressed as a formula:
Underlying Share Return of the Least Performing Underlying Shares = ($40 - $100) / $100 = -60.00%
Payment at Maturity = $10 + ($10 × -60.00%) = $4.00
Because the Underlying Share Return of the Least Performing Underlying Shares is less than zero and the Final Price of the Least Performing Underlying Shares is below its Downside Threshold on the Final Valuation Date, the Securities will be fully exposed to any decline in the price of the Least Performing Underlying Shares on the Final Valuation Date. Therefore, the Payment at Maturity is equal to $4.00 per $10.00 Principal Amount of Securities, resulting in a total loss on the Securities of 60.00%.
If the Final Price of either Underlying Shares is below its Downside Threshold on the Final Valuation Date, the Securities will be fully exposed to any decline in the Least Performing Underlying Shares, and you will lose a significant portion or all of your Principal Amount at maturity.
10
Scenario Analysis – Hypothetical Payment at Maturity for each $10.00 Principal Amount of Securities.
|
Performance of the Least Performing Underlying Shares* |
Performance of the Securities |
||||
|
Final Price of the Least Performing Underlying Shares |
Underlying Share Return of the Least Performing Underlying Shares |
Upside Gearing |
Payment at Maturity |
Return on Securities Purchased at $10.00(1) |
|
|
$200.00 |
100.00% |
1.293 |
$22.93 |
129.30% |
|
|
$190.00 |
90.00% |
1.293 |
$21.637 |
116.37% |
|
|
$180.00 |
80.00% |
1.293 |
$20.344 |
103.44% |
|
|
$170.00 |
70.00% |
1.293 |
$19.051 |
90.51% |
|
|
$160.00 |
60.00% |
1.293 |
$17.758 |
77.58% |
|
|
$150.00 |
50.00% |
1.293 |
$16.465 |
64.65% |
|
|
$140.00 |
40.00% |
1.293 |
$15.172 |
51.72% |
|
|
$130.00 |
30.00% |
1.293 |
$13.879 |
38.79% |
|
|
$120.00 |
20.00% |
1.293 |
$12.586 |
25.86% |
|
|
$110.00 |
10.00% |
1.293 |
$11.293 |
12.93% |
|
|
$100.00 |
0.00% |
N/A |
$10.00 |
0.00% |
|
|
$90.00 |
-10.00% |
N/A |
$10.00 |
0.00% |
|
|
$80.00 |
-20.00% |
N/A |
$10.00 |
0.00% |
|
|
$75.00 |
-25.00% |
N/A |
$10.00 |
0.00% |
|
|
$74.00 |
-26.00% |
N/A |
$7.40 |
-26.00% |
|
|
$70.00 |
-30.00% |
N/A |
$7.00 |
-30.00% |
|
|
$60.00 |
-40.00% |
N/A |
$6.00 |
-40.00% |
|
|
$50.00 |
-50.00% |
N/A |
$5.00 |
-50.00% |
|
|
$40.00 |
-60.00% |
N/A |
$4.00 |
-60.00% |
|
|
$30.00 |
-70.00% |
N/A |
$3.00 |
-70.00% |
|
|
$20.00 |
-80.00% |
N/A |
$2.00 |
-80.00% |
|
|
$10.00 |
-90.00% |
N/A |
$1.00 |
-90.00% |
|
|
$0.00 |
-100.00% |
N/A |
$0.00 |
-100.00% |
|
*. The columns above reflect only the performance of the Least Performing Underlying Shares.
(1) This “Return on Securities” is the number, expressed as a percentage, that results from comparing the Payment at Maturity per $10 Principal Amount Security to the purchase price of $10 per Security.
11
|
What are the tax consequences of the Securities? |
Prospective investors should note that the discussion under the section called “United States Federal Taxation” in the accompanying prospectus supplement does not apply to the Securities issued under this pricing supplement and is superseded by the following discussion.
The following summary is a general discussion of the principal U.S. federal income tax consequences and certain estate tax consequences of the ownership and disposition of the Securities. This discussion applies only to investors in the Securities who:
♦purchase the Securities in the original offering; and
♦hold the Securities as capital assets within the meaning of Section 1221 of the Internal Revenue Code of 1986, as amended (the “Code”).
This discussion does not describe all of the tax consequences that may be relevant to a holder in light of the holder’s particular circumstances or to holders subject to special rules, such as:
♦certain financial institutions;
♦insurance companies;
♦dealers and certain traders in securities or commodities;
♦investors holding the Securities as part of a “straddle,” wash sale, conversion transaction, integrated transaction or constructive sale transaction;
♦U.S. Holders (as defined below) whose functional currency is not the U.S. dollar;
♦partnerships or other entities classified as partnerships for U.S. federal income tax purposes;
♦regulated investment companies;
♦real estate investment trusts; or
♦tax-exempt entities, including “individual retirement accounts” or “Roth IRAs” as defined in Section 408 or 408A of the Code, respectively.
If an entity that is classified as a partnership for U.S. federal income tax purposes holds the Securities, the U.S. federal income tax treatment of a partner will generally depend on the status of the partner and the activities of the partnership. If you are a partnership holding the Securities or a partner in such a partnership, you should consult your tax adviser as to the particular U.S. federal tax consequences of holding and disposing of the Securities to you.
In addition, we will not attempt to ascertain whether any issuer of any shares to which a Security relates (such shares hereafter referred to as “Underlying Shares”) is treated as a “passive foreign investment company” (“PFIC”) within the meaning of Section 1297 of the Code or as a “U.S. real property holding corporation” (“USRPHC”) within the meaning of Section 897 of the Code. If any issuer of Underlying Shares were so treated, certain adverse U.S. federal income tax consequences might apply, to a U.S. Holder in the case of a PFIC and to a Non-U.S. Holder (as defined below) in the case of a USRPHC, upon the sale, exchange or settlement of the Securities. You should refer to information filed with the Securities and Exchange Commission or other governmental authorities by the issuers of the Underlying Shares and consult your tax adviser regarding the possible consequences to you if any issuer is or becomes a PFIC or USRPHC.
As the law applicable to the U.S. federal income taxation of instruments such as the Securities is technical and complex, the discussion below necessarily represents only a general summary. Moreover, the effect of any applicable state, local or non-U.S. tax laws is not discussed, nor are any alternative minimum tax consequences or consequences resulting from the Medicare tax on investment income.
This discussion is based on the Code, administrative pronouncements, judicial decisions and final, temporary and proposed Treasury regulations, all as of the date of this pricing supplement, changes to any of which subsequent to the date hereof may affect the tax consequences described herein. Persons considering the purchase of the Securities should consult their tax advisers with regard to the application of the U.S. federal income tax laws to their particular situations as well as any tax consequences arising under the laws of any state, local or non-U.S. taxing jurisdiction.
General
Although there is uncertainty regarding the U.S. federal income tax consequences of an investment in the Securities due to the lack of governing authority, in the opinion of our counsel, under current law, and based on current market conditions, each Security should be treated as a single financial contract that is an “open transaction” for U.S. federal income tax purposes.
Due to the absence of statutory, judicial or administrative authorities that directly address the treatment of the Securities or instruments that are similar to the Securities for U.S. federal income tax purposes, no assurance can be given that the Internal Revenue Service (the “IRS”) or a court will agree with the tax treatment described herein. Accordingly, you should consult your tax adviser regarding all aspects of the U.S. federal tax consequences of an
12
investment in the Securities (including possible alternative treatments of the Securities). Unless otherwise stated, the following discussion is based on the treatment of the Securities as described in the previous paragraph.
Tax Consequences to U.S. Holders
This section applies to you only if you are a U.S. Holder. As used herein, the term “U.S. Holder” means a beneficial owner of a Security that is, for U.S. federal income tax purposes:
♦a citizen or individual resident of the United States;
♦a corporation, or other entity taxable as a corporation, created or organized in or under the laws of the United States, any state thereof or the District of Columbia; or
♦an estate or trust the income of which is subject to U.S. federal income taxation regardless of its source.
Tax Treatment of the Securities
Assuming the treatment of the Securities as set forth above is respected, the following U.S. federal income tax consequences should result.
Tax Treatment Prior to Settlement. A U.S. Holder should not be required to recognize taxable income over the term of the Securities prior to settlement, other than pursuant to a sale or exchange as described below.
Tax Basis. A U.S. Holder’s tax basis in the Securities should equal the amount paid by the U.S. Holder to acquire the Securities.
Sale, Exchange or Settlement of the Securities. Upon a sale, exchange or settlement of the Securities, a U.S. Holder should recognize gain or loss equal to the difference between the amount realized on the sale, exchange or settlement and the U.S. Holder’s tax basis in the Securities sold, exchanged or settled. Subject to the discussion above regarding the possible application of Section 1297 of the Code, any gain or loss recognized upon the sale, exchange or settlement of the Securities should be long-term capital gain or loss if the U.S. Holder has held the Securities for more than one year at such time, and short-term capital gain or loss otherwise.
Potential Application of the Constructive Ownership Rule. Because the Securities are linked to shares of exchange-traded funds, although the matter is not clear, there is a substantial risk that an investment in the Securities will be treated as a “constructive ownership transaction” under Section 1260 of the Code. If this treatment applies, all or a portion of any long-term capital gain of the U.S. Holder in respect of the Securities could be recharacterized as ordinary income (the “Recharacterized Gain”), in which case an interest charge will be imposed. The amount of Recharacterized Gain (if any) that would be treated as ordinary income in respect of a Security will equal the excess of (i) any long-term capital gain recognized by the U.S. Holder in respect of a Security over (ii) the “net underlying long-term capital gain” (as defined in Section 1260 of the Code). Under Section 1260 of the Code, the amount of net underlying long-term capital gain will be treated as zero unless otherwise “established by clear and convincing evidence.” As a result of the terms of the Securities, it is unclear how to calculate the amount of Recharacterized Gain if an investment in the Securities were treated as a constructive ownership transaction. Due to the lack of governing authority, our counsel is unable to opine as to whether or how Section 1260 of the Code applies to the Securities. U.S. Holders should consult their tax advisers regarding the potential application of the “constructive ownership” rule.
Possible Alternative Tax Treatments of an Investment in the Securities
Due to the absence of authorities that directly address the proper tax treatment of the Securities, no assurance can be given that the IRS will accept, or that a court will uphold, the treatment described above. In particular, the IRS could seek to analyze the U.S. federal income tax consequences of owning the Securities under Treasury regulations governing contingent payment debt instruments (the “Contingent Debt Regulations”). If the IRS were successful in asserting that the Contingent Debt Regulations applied to the Securities, the timing and character of income thereon would be significantly affected. Among other things, a U.S. Holder would be required to accrue into income original issue discount on the Securities every year at a “comparable yield” determined at the time of their issuance, adjusted upward or downward to reflect the difference, if any, between the actual and the projected amount of the contingent payment on the Securities. Furthermore, any gain realized by a U.S. Holder at maturity or upon a sale, exchange or other disposition of the Securities would generally be treated as ordinary income, and any loss realized would be treated as ordinary loss to the extent of the U.S. Holder’s prior accruals of original issue discount and as capital loss thereafter. The risk that financial instruments providing for buffers, triggers or similar downside protection features, such as the Securities, would be recharacterized as debt is greater than the risk of recharacterization for comparable financial instruments that do not have such features.
Other alternative federal income tax treatments of the Securities are also possible, which, if applied, could significantly affect the timing and character of the income or loss with respect to the Securities. In 2007, the U.S. Treasury Department and the IRS released a notice requesting comments on the U.S. federal income tax treatment of “prepaid forward contracts” and similar instruments. The notice focuses in particular on whether to require holders of these instruments to accrue income over the term
13
of their investment. It also asks for comments on a number of related topics, including the character of income or loss with respect to these instruments; whether short-term instruments should be subject to any such accrual regime; the relevance of factors such as the exchange-traded status of the instruments and the nature of the underlying property to which the instruments are linked; and whether these instruments are or should be subject to the “constructive ownership” rule, which very generally can operate to recharacterize certain long-term capital gain as ordinary income and impose an interest charge. While the notice requests comments on appropriate transition rules and effective dates, any Treasury regulations or other guidance promulgated after consideration of these issues could materially and adversely affect the tax consequences of an investment in the Securities, possibly with retroactive effect. U.S. Holders should consult their tax advisers regarding the U.S. federal income tax consequences of an investment in the Securities, including possible alternative treatments and the issues presented by this notice.
Backup Withholding and Information Reporting
Backup withholding may apply in respect of the payment on the Securities at maturity and the payment of proceeds from a sale, exchange or other disposition of the Securities, unless a U.S. Holder provides proof of an applicable exemption or a correct taxpayer identification number and otherwise complies with applicable requirements of the backup withholding rules. The amounts withheld under the backup withholding rules are not an additional tax and may be refunded, or credited against the U.S. Holder’s U.S. federal income tax liability, provided that the required information is timely furnished to the IRS. In addition, information returns may be filed with the IRS in connection with the payment on the Securities and the payment of proceeds from a sale, exchange or other disposition of the Securities, unless the U.S. Holder provides proof of an applicable exemption from the information reporting rules.
Tax Consequences to Non-U.S. Holders
This section applies to you only if you are a Non-U.S. Holder. As used herein, the term “Non-U.S. Holder” means a beneficial owner of a Security that is, for U.S. federal income tax purposes:
♦an individual who is classified as a nonresident alien;
♦a foreign corporation; or
♦a foreign estate or trust.
The term “Non-U.S. Holder” does not include any of the following holders:
♦a holder who is an individual present in the United States for 183 days or more in the taxable year of disposition and who is not otherwise a resident of the United States for U.S. federal income tax purposes;
♦certain former citizens or residents of the United States; or
♦a holder for whom income or gain in respect of the Securities is effectively connected with the conduct of a trade or business in the United States.
Such holders should consult their tax advisers regarding the U.S. federal income tax consequences of an investment in the Securities.
Tax Treatment upon Sale, Exchange or Settlement of the Securities
In general. Assuming the treatment of the Securities as set forth above is respected, and subject to the discussions below concerning backup withholding and the possible application of Section 871(m) of the Code and the discussion above concerning the possible application of Section 897 of the Code, a Non-U.S. Holder of the Securities generally will not be subject to U.S. federal income or withholding tax in respect of amounts paid to the Non-U.S. Holder.
Subject to the discussions regarding the possible application of Sections 871(m) and 897 of the Code and FATCA, if all or any portion of a Security were recharacterized as a debt instrument, any payment made to a Non-U.S. Holder with respect to the Securities would not be subject to U.S. federal withholding tax, provided that:
♦the Non-U.S. Holder does not own, directly or by attribution, ten percent or more of the total combined voting power of all classes of Morgan Stanley stock entitled to vote;
♦the Non-U.S. Holder is not a controlled foreign corporation related, directly or indirectly, to Morgan Stanley through stock ownership;
♦the Non-U.S. Holder is not a bank receiving interest under Section 881(c)(3)(A) of the Code, and
♦the certification requirement described below has been fulfilled with respect to the beneficial owner.
14
Certification Requirement. The certification requirement referred to in the preceding paragraph will be fulfilled if the beneficial owner of a Security (or a financial institution holding a Security on behalf of the beneficial owner) furnishes to the applicable withholding agent an IRS Form W-8BEN (or other appropriate form) on which the beneficial owner certifies under penalties of perjury that it is not a U.S. person.
In 2007, the U.S. Treasury Department and the IRS released a notice requesting comments on the U.S. federal income tax treatment of “prepaid forward contracts” and similar instruments. Among the issues addressed in the notice is the degree, if any, to which any income with respect to instruments such as the Securities should be subject to U.S. withholding tax. It is possible that any Treasury regulations or other guidance promulgated after consideration of this issue could materially and adversely affect the withholding tax consequences of ownership and disposition of the Securities, possibly on a retroactive basis. Non-U.S. Holders should note that we currently do not intend to withhold on any payment made with respect to the Securities to Non-U.S. Holders (subject to compliance by such holders with the certification requirement described above and to the discussions regarding Sections 871(m) and 897 of the Code and FATCA). However, in the event of a change of law or any formal or informal guidance by the IRS, the U.S. Treasury Department or Congress, we may decide to withhold on payments made with respect to the Securities to Non-U.S. Holders, and we will not be required to pay any additional amounts with respect to amounts withheld. Accordingly, Non-U.S. Holders should consult their tax advisers regarding all aspects of the U.S. federal income tax consequences of an investment in the Securities, including the possible implications of the notice referred to above.
Section 871(m) Withholding Tax on Dividend Equivalents
Section 871(m) of the Code and Treasury regulations promulgated thereunder (“Section 871(m)”) generally impose a 30% (or a lower applicable treaty rate) withholding tax on dividend equivalents paid or deemed paid to Non-U.S. Holders with respect to certain financial instruments linked to U.S. equities or indices that include U.S. equities (each, an “Underlying Security”). Subject to certain exceptions, Section 871(m) generally applies to securities that substantially replicate the economic performance of one or more Underlying Securities, as determined based on tests set forth in the applicable Treasury regulations (a “Specified Security”). However, pursuant to an IRS notice, Section 871(m) will not apply to securities issued before January 1, 2027 that do not have a delta of one with respect to any Underlying Security. Based on our determination that the Securities do not have a delta of one with respect to any Underlying Security, our counsel is of the opinion that the Securities should not be Specified Securities and, therefore, should not be subject to Section 871(m).
Our determination is not binding on the IRS, and the IRS may disagree with this determination. Section 871(m) is complex and its application may depend on your particular circumstances, including whether you enter into other transactions with respect to an Underlying Security. If withholding is required, we will not be required to pay any additional amounts with respect to the amounts so withheld. You should consult your tax adviser regarding the potential application of Section 871(m) to the Securities.
U.S. Federal Estate Tax
Individual Non-U.S. Holders and entities the property of which is potentially includible in such an individual’s gross estate for U.S. federal estate tax purposes (for example, a trust funded by such an individual and with respect to which the individual has retained certain interests or powers), should note that, absent an applicable treaty exemption, the Securities may be treated as U.S. situs property subject to U.S. federal estate tax. Prospective investors that are non-U.S. individuals, or are entities of the type described above, should consult their tax advisers regarding the U.S. federal estate tax consequences of an investment in the Securities.
Backup Withholding and Information Reporting
Information returns may be filed with the IRS in connection with the payment on the Securities at maturity as well as in connection with the payment of proceeds from a sale, exchange or other disposition of the Securities. A Non-U.S. Holder may be subject to backup withholding in respect of amounts paid to the Non-U.S. Holder, unless such Non-U.S. Holder complies with certification procedures to establish that it is not a U.S. person for U.S. federal income tax purposes or otherwise establishes an exemption. Compliance with the certification procedures described above under “―Tax Treatment upon Sale, Exchange or Settlement of the Securities – Certification Requirement” will satisfy the certification requirements necessary to avoid backup withholding as well. The amount of any backup withholding from a payment to a Non-U.S. Holder will be allowed as a credit against the Non-U.S. Holder’s U.S. federal income tax liability and may entitle the Non-U.S. Holder to a refund, provided that the required information is timely furnished to the IRS.
FATCA
Legislation commonly referred to as “FATCA” generally imposes a withholding tax of 30% on payments to certain non-U.S. entities (including financial intermediaries) with respect to certain financial instruments, unless various U.S. information reporting and due diligence requirements have been satisfied. An intergovernmental agreement between the United States and the non-U.S. entity’s jurisdiction may modify these requirements. FATCA generally applies to certain financial instruments that are treated as paying U.S.-source interest or other U.S.-source “fixed or determinable annual or periodical” income (“FDAP income”). If the Securities were recharacterized as debt instruments, FATCA would apply to any payment of amounts treated as interest and to payments of gross proceeds of the disposition (including upon retirement) of the Securities. However, under proposed regulations (the preamble to which specifies that taxpayers are permitted to rely on them pending finalization), no withholding
15
will apply on payments of gross proceeds (other than amounts treated as FDAP income). If withholding were to apply to the Securities, we would not be required to pay any additional amounts with respect to amounts withheld. Both U.S. and Non-U.S. Holders should consult their tax advisers regarding the potential application of FATCA to the Securities.
The discussion in the preceding paragraphs under “What Are the Tax Consequences of the Securities,” insofar as it purports to describe provisions of U.S. federal income tax laws or legal conclusions with respect thereto, constitutes the full opinion of Davis Polk & Wardwell LLP regarding the material U.S. federal income tax consequences of an investment in the Securities.
16
|
SPDR® Dow Jones® Industrial Average℠ ETF Trust |
|
The SPDR® Dow Jones® Industrial AverageSM ETF Trust is an exchange-traded fund that seeks to provide investment results that correspond generally to the price and yield performance, before fees and expenses, of the Dow Jones Industrial AverageSM. The SPDR® Dow Jones® Industrial AverageSM ETF Trust, a registered investment company, is managed by State Street Global Advisors Trust Company (“SSGA”), as trustee, and PDR Services LLC (“PDRS”), as sponsor. Information provided to or filed with the Securities and Exchange Commission (the “Commission”) by SPDR® Dow Jones® Industrial AverageSM ETF Trust pursuant to the Securities Act of 1933 and the Investment Company Act of 1940 can be located by reference to Commission file numbers 333-31247 and 811-09170, respectively, through the Commission’s website at www.sec.gov. In addition, information may be obtained from other publicly available sources. Neither the issuer nor the agent makes any representation that such publicly available documents or any other publicly available information regarding the SPDR® Dow Jones® Industrial Average℠ ETF Trust is accurate or complete. The DIA Shares are listed on The NYSE Arca Exchange under the ticker symbol “DIA UP.” The Dow Jones Industrial AverageSM is a price-weighted index composed of 30 common stocks that is published by S&P® Dow Jones Indices LLC, the marketing name and a licensed trademark of CME Group Inc., as representative of the broad market of U.S. industry. For additional information about the Dow Jones Industrial AverageSM, see the information set forth under “Dow Jones Industrial AverageSM” in the accompanying index supplement. We and/or our affiliates may presently or from time to time engage in business with SPDR® Dow Jones® Industrial AverageSM ETF Trust. In the course of such business, we and/or our affiliates may acquire non-public information with respect to SPDR® Dow Jones® Industrial AverageSM ETF Trust, and neither we nor any of our affiliates undertakes to disclose any such information to you. In addition, one or more of our affiliates may publish research reports with respect to the DIA Shares. The statements in the preceding two sentences are not intended to affect the rights of investors in the Securities under the securities laws. As a prospective purchaser of the Securities, you should undertake an independent investigation of SPDR® Dow Jones® Industrial AverageSM ETF Trust as in your judgment is appropriate to make an informed decision with respect to an investment linked to the DIA Shares. “S&P®®,” “SPDR®” and “Dow Jones Industrial AverageSM” are trademarks of Standard & Poor’s Financial Services LLC (“S&P®”), an affiliate of S&P® Global Inc. The Securities are not sponsored, endorsed, sold, or promoted by S&P®, S&P® Global Inc., SSGA or PDRS. S&P®, S&P® Global Inc., SSGA and PDRS make no representations or warranties to the owners of the Securities or any member of the public regarding the advisability of investing in the Securities. S&P®, S&P® Global Inc., SSGA and PDRS have no obligation or liability in connection with the operation, marketing, trading or sale of the Securities.
|
|
Historical Information |
The following table sets forth the published high and low Closing Prices, as well as the end-of-quarter Closing Prices, of the SPDR® Dow Jones® Industrial Average℠ ETF Trust for each quarter in the period from January 1, 2020 through March 26, 2025. The Closing Price of the SPDR® Dow Jones® Industrial Average℠ ETF Trust on March 26, 2025 was $424.23. We obtained the information in the table below from Bloomberg Financial Markets, without independent verification. The historical Closing Prices of the SPDR® Dow Jones® Industrial Average℠ ETF Trust should not be taken as an indication of future performance, and no assurance can be given as to the Closing Price of the SPDR® Dow Jones® Industrial Average℠ ETF Trust on the Final Valuation Date.
|
Quarter Begin |
Quarter End |
Quarterly High |
Quarterly Low |
Quarterly Close |
|
1/1/2020 |
3/31/2020 |
295.72 |
186.13 |
219.23 |
|
4/1/2020 |
6/30/2020 |
276.28 |
209.38 |
257.87 |
|
7/1/2020 |
9/30/2020 |
291.21 |
257.24 |
277.50 |
|
10/1/2020 |
12/31/2020 |
305.79 |
265.06 |
305.79 |
|
1/1/2021 |
3/31/2021 |
331.66 |
299.81 |
330.18 |
|
4/1/2021 |
6/30/2021 |
347.90 |
331.45 |
344.95 |
|
7/1/2021 |
9/30/2021 |
356.57 |
338.29 |
338.29 |
|
10/1/2021 |
12/31/2021 |
364.84 |
340.01 |
363.32 |
|
1/1/2022 |
3/31/2022 |
367.87 |
326.53 |
346.83 |
|
4/1/2022 |
6/30/2022 |
351.53 |
298.72 |
307.82 |
|
7/1/2022 |
9/30/2022 |
341.74 |
287.30 |
287.30 |
|
10/1/2022 |
12/31/2022 |
346.15 |
291.96 |
331.33 |
|
1/1/2023 |
3/31/2023 |
343.04 |
318.50 |
332.62 |
|
4/1/2023 |
6/30/2023 |
344.77 |
327.75 |
343.85 |
|
7/1/2023 |
9/30/2023 |
356.20 |
334.95 |
334.95 |
|
10/1/2023 |
12/31/2023 |
377.03 |
324.19 |
376.87 |
|
1/1/2024 |
3/31/2024 |
397.76 |
372.72 |
397.76 |
|
4/1/2024 |
6/30/2024 |
399.95 |
377.31 |
391.13 |
|
7/1/2024 |
9/30/2024 |
423.12 |
386.81 |
423.12 |
|
10/1/2024 |
12/31/2024 |
450.94 |
417.67 |
425.50 |
|
1/1/2025 |
3/26/2025* |
448.82 |
408.78 |
424.23 |
* Available information for the indicated period includes data for less than the entire calendar quarter, and, accordingly, the “Quarterly High,” “Quarterly Low” and “Quarterly Close” data indicated are for this shortened period only.
17
The graph below illustrates the performance of the SPDR® Dow Jones® Industrial Average℠ ETF Trust from January 1, 2008 through March 26, 2025, based on information from Bloomberg. Past performance of the SPDR® Dow Jones® Industrial Average℠ ETF Trust is not indicative of the future performance of the SPDR® Dow Jones® Industrial Average℠ ETF Trust.
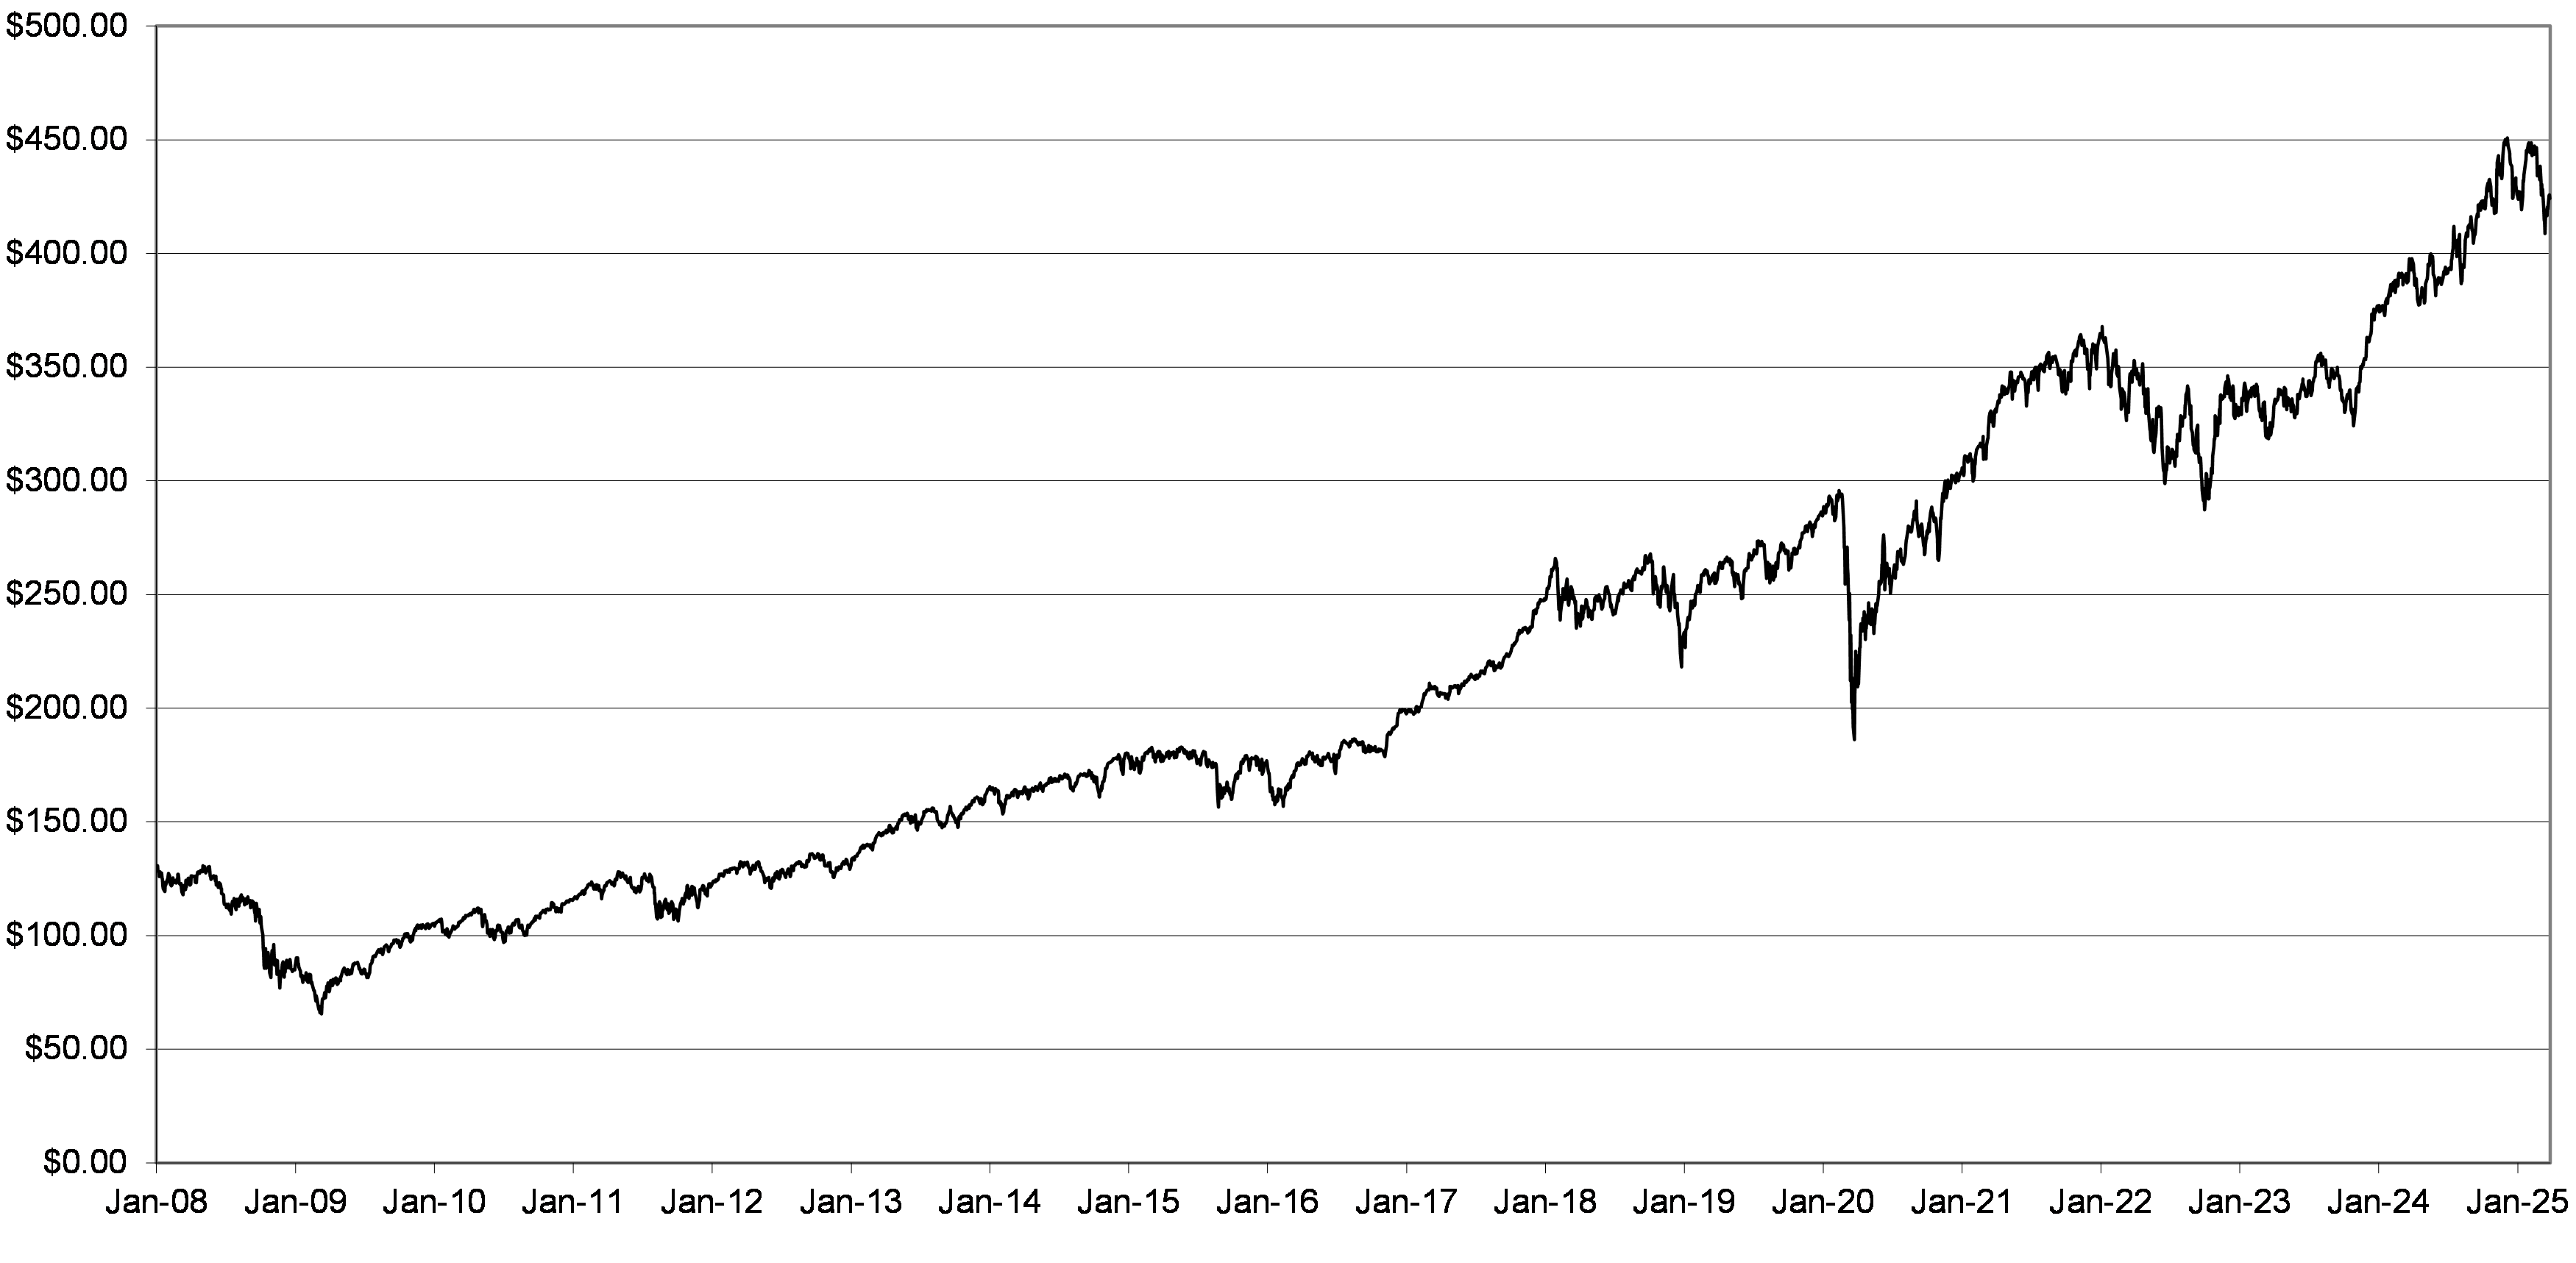
18
|
Invesco S&P 500® Equal Weight ETF |
|
The Invesco S&P 500® Equal Weight ETF, or RSP, is an exchange-traded fund that seeks investment results that correspond generally to the price and yield performance, before fees and expenses, of the S&P 500® Equal Weight Index. The Invesco S&P 500® Equal Weight ETF is managed by Invesco Exchange-Traded Fund Trust (the “Trust”), a registered investment company that consists of numerous separate investment portfolios, including the Invesco S&P 500® Equal Weight ETF. Information provided to or filed with the Securities and Exchange Commission (the “Commission”) by Invesco Exchange-Traded Fund Trust pursuant to the Securities Act of 1933 and the Investment Company Act of 1940 can be located by reference to Commission file numbers 333-102228 and 811-21265, respectively, through the Commission’s website at www.sec.gov. In addition, information may be obtained from other publicly available sources. Neither the issuer nor the agent makes any representation that any such publicly available information regarding the Invesco S&P 500® Equal Weight ETF is accurate or complete. The Underlying Shares are listed on The NYSE Arca Exchange under the ticker symbol “RSP UP.” The S&P 500® Equal Weight Index is the equal-weight version of the S&P 500® Index. The index includes the same constituents as the capitalization-weighted S&P 500® Index, but each company in the S&P 500® Equal Weight Index is allocated a fixed weight of 0.2% of the index total at each quarterly rebalancing. Therefore, the performances of the S&P 500® Equal Weight Index and the Underlying Shares will differ, perhaps materially, from the performance of the S&P 500® Index, which is weighted unevenly based on market capitalization. The S&P 500® Index, which is calculated, maintained and published by S&P® Dow Jones Indices LLC (“S&P®”), is intended to provide a benchmark for performance measurement of the large capitalization segment of the U.S. equity markets by tracking the stock price movement of 500 companies with large market capitalizations. Component stocks of the S&P 500® Index are required to have a total company level market capitalization that reflects approximately the 85th percentile of the S&P® Total Market Index. The S&P 500® Index measures the relative performance of the common stocks of 500 companies as of a particular time as compared to the performance of the common stocks of 500 similar companies during the base period of the years 1941 through 1943. For additional information about the S&P 500® Index, see the information set forth under “S&P® U.S. Indices—S&P 500® Index” in the accompanying index supplement. We and/or our affiliates may presently or from time to time engage in business with the Trust. In the course of such business, we and/or our affiliates may acquire non-public information with respect to the Trust, and neither we nor any of our affiliates undertakes to disclose any such information to you. In addition, one or more of our affiliates may publish research reports with respect to the RSP Shares. The statements in the preceding two sentences are not intended to affect the rights of investors in the Securities under the securities laws. As a prospective purchaser of the Securities, you should undertake an independent investigation of the Trust as in your judgment is appropriate to make an informed decision with respect to an investment linked to the RSP Shares. “Standard & Poor’s®,” “S&P®,” “S&P 500®” are trademarks of Standard & Poor’s Financial Services LLC (“S&P®”), an affiliate of S&P® Global Inc. The Securities are not sponsored, endorsed, sold, or promoted by S&P®, S&P® Global Inc. or the Trust. S&P®, S&P® Global Inc. and the Trust make no representations or warranties to the owners of the Securities or any member of the public regarding the advisability of investing in the Securities. S&P®, S&P® Global Inc. and the Trust have no obligation or liability in connection with the operation, marketing, trading or sale of the Securities. |
|
Historical Information |
The following table sets forth the published high and low Closing Prices, as well as the end-of-quarter Closing Prices, of the Invesco S&P 500® Equal Weight ETF for each quarter in the period from January 1, 2020 through March 26, 2025. The Closing Price of the Invesco S&P 500® Equal Weight ETF on March 26, 2025 was $174.94. We obtained the information in the table below from Bloomberg Financial Markets, without independent verification. The historical Closing Prices of the Invesco S&P 500® Equal Weight ETF should not be taken as an indication of future performance, and no assurance can be given as to the Closing Price of the Invesco S&P 500® Equal Weight ETF on the Final Valuation Date.
|
Quarter Begin |
Quarter End |
Quarterly High |
Quarterly Low |
Quarterly Close |
|
1/1/2020 |
3/31/2020 |
118.71 |
71.66 |
84.02 |
|
4/1/2020 |
6/30/2020 |
113.09 |
79.83 |
101.76 |
|
7/1/2020 |
9/30/2020 |
113.96 |
100.38 |
108.11 |
|
10/1/2020 |
12/31/2020 |
127.54 |
106.78 |
127.54 |
|
1/1/2021 |
3/31/2021 |
142.80 |
125.70 |
141.66 |
|
4/1/2021 |
6/30/2021 |
152.26 |
143.08 |
150.73 |
|
7/1/2021 |
9/30/2021 |
157.39 |
146.61 |
149.82 |
|
10/1/2021 |
12/31/2021 |
163.01 |
150.88 |
162.75 |
|
1/1/2022 |
3/31/2022 |
164.20 |
148.26 |
157.71 |
|
4/1/2022 |
6/30/2022 |
158.96 |
130.84 |
134.23 |
|
7/1/2022 |
9/30/2022 |
152.39 |
127.28 |
127.28 |
|
10/1/2022 |
12/31/2022 |
149.03 |
128.02 |
141.25 |
|
1/1/2023 |
3/31/2023 |
154.96 |
137.35 |
144.62 |
|
4/1/2023 |
6/30/2023 |
149.64 |
139.61 |
149.64 |
|
7/1/2023 |
9/30/2023 |
155.00 |
141.04 |
141.69 |
|
10/1/2023 |
12/31/2023 |
158.41 |
133.66 |
157.80 |
|
1/1/2024 |
3/31/2024 |
169.37 |
153.84 |
169.37 |
|
4/1/2024 |
6/30/2024 |
168.37 |
159.21 |
164.28 |
|
7/1/2024 |
9/30/2024 |
179.16 |
162.83 |
179.16 |
|
10/1/2024 |
12/31/2024 |
187.62 |
174.22 |
175.23 |
|
1/1/2025 |
3/26/2025* |
182.84 |
169.43 |
174.94 |
* Available information for the indicated period includes data for less than the entire calendar quarter, and, accordingly, the “Quarterly High,” “Quarterly Low” and “Quarterly Close” data indicated are for this shortened period only.
19
The graph below illustrates the performance of the Invesco S&P 500® Equal Weight ETF from January 1, 2008 through March 26, 2025, based on information from Bloomberg. Past performance of the Invesco S&P 500® Equal Weight ETF is not indicative of the future performance of the Invesco S&P 500® Equal Weight ETF.
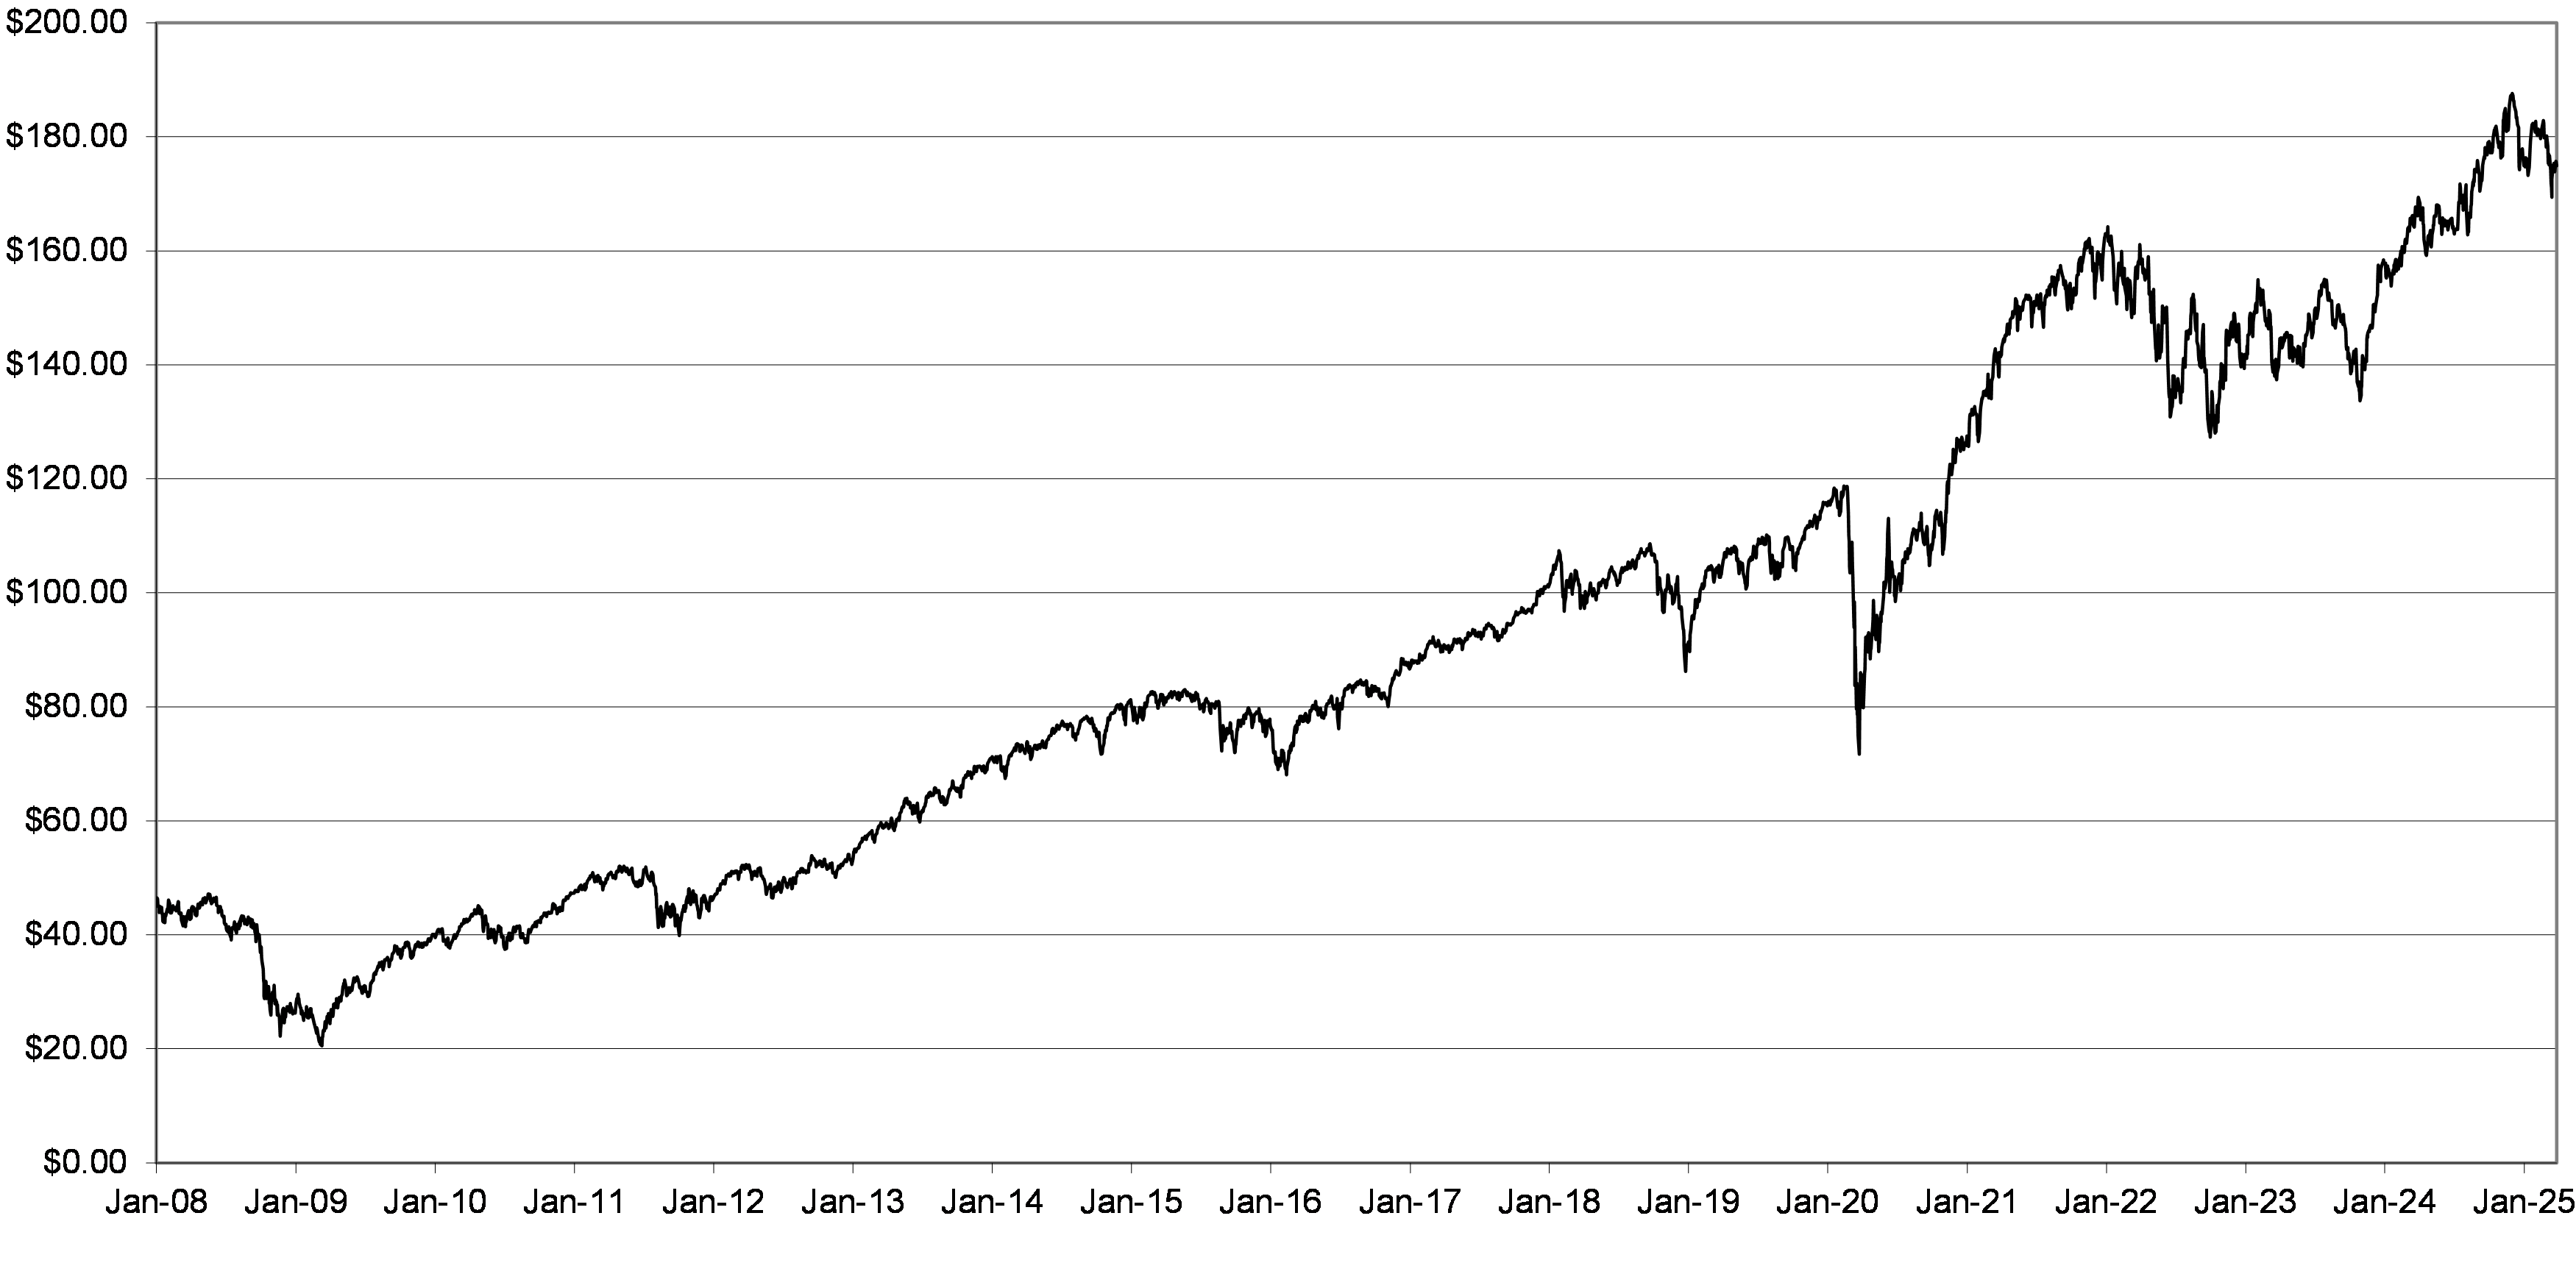
20
|
Correlation of the Underlying Shares |
The graph below illustrates the daily performance of the SPDR® Dow Jones® Industrial Average℠ ETF Trust and the Invesco S&P 500® Equal Weight ETF from January 1, 2008 through March 10, 2025. For comparison purposes, each Underlying Shares has been “normalized” to have a closing value of 100 on January 1, 2008 by dividing the closing value of that Underlying on each Index Business Day by the closing value of that Underlying on January 1, 2008 and multiplying by 100. We obtained the closing values used to determine the normalized closing values set forth below from Bloomberg, without independent verification.
A closer relationship between the daily returns of two or more underlying assets over a given period indicates that such underlying assets have been more positively correlated. Lower (or more-negative) correlation among two or more underlying assets over a given period may indicate that it is less likely that those underlying assets will subsequently move in the same direction. Therefore, lower correlation among the Underlying Shares may indicate a greater potential for one of the Underlying Shares to close below its respective Downside Threshold on the Final Valuation Date because there may be a greater likelihood that at least one of the Underlying Shares will decrease in value significantly. However, even if the Underlying Shares have a higher positive correlation, one or both of the Underlying Shares may close below their respective Downside Threshold(s) on the Final Valuation Date, as the Underlying Shares may both decrease in value. Moreover, the actual correlation among the Underlying Shares may differ, perhaps significantly, from their historical correlation. A higher Upside Gearing is generally associated with lower correlation among the Underlying Shares, which may indicate a greater potential for a significant loss on your investment at maturity. See “Key Risks — You are exposed to the price risk of both Underlying Shares,” “—Because the Securities are linked to the performance of the least performing between the DIA Shares and the RSP Shares, you are exposed to greater risk of sustaining a significant loss on your investment than if the Securities were linked to just the DIA Shares or just the RSP Shares” and “—The probability that the Final Price of either Underlying Shares will be less than its respective Downside Threshold will depend on the volatility of such Underlying Shares” herein.
Past performance and correlation of the Underlying Shares are not indicative of the future performance or correlation of the Underlying Shares.
21
|
Additional Terms of the Securities |
If the terms contained in this pricing supplement differ from those contained in the prospectus supplement, index supplement or prospectus, the terms contained in this pricing supplement will control.
Some Definitions
We have defined some of the terms that we use frequently in this pricing supplement below:
♦“Share Underlying Index” means, with respect to the DIA Shares, the Dow Jones Industrial Average℠; and with respect to the RSP Shares, the S&P 500® Equal Weight Index.
♦“Share Underlying Index Publisher” means, with respect to each of the DIA Shares and the RSP Shares, S&P® Dow Jones Indices LLC or any successor thereto.
♦“Closing Price” means, subject to the provisions set out under “Discontinuance of any Underlying Shares and/or Share Underlying Indices; Alteration of Method of Calculation” below, for one share of any Underlying Shares (or one unit of any other security for which a Closing Price must be determined) on any Trading Day means:
oif such Underlying Shares (or any such other security) are listed on a national securities exchange (other than The Nasdaq Stock Market LLC (“Nasdaq”)), the last reported sale price, regular way, of the principal trading session on such day on the principal national securities exchange registered under the Securities Exchange Act of 1934, as amended (the “Exchange Act”), on which the Underlying Shares (or any such other security) are listed,
oif such Underlying Shares (or any such other security) are securities of Nasdaq, the official closing price published by Nasdaq on such day, or
oif such Underlying Shares (or any such other security) are not listed on any national securities exchange but are included in the OTC Bulletin Board Service (the “OTC Bulletin Board”) operated by the Financial Industry Regulatory Authority, Inc. (“FINRA”), the last reported sale price of the principal trading session on the OTC Bulletin Board on such day.
If such Underlying Shares (or any such other security) are listed on any national securities exchange but the last reported sale price or the official closing price published by such exchange, or by Nasdaq, as applicable, is not available pursuant to the preceding sentence, then the Closing Price for one share of such Underlying Shares (or one unit of any such other security) on any Trading Day will mean the last reported sale price of the principal trading session on the over-the-counter market as reported on Nasdaq or the OTC Bulletin Board on such day. If a Market Disruption Event (as defined below) occurs with respect to such Underlying Shares (or any such other security) or the last reported sale price or the official closing price published by Nasdaq, as applicable, for such Underlying Shares (or any such other security) is not available pursuant to either of the two preceding sentences, then the Closing Price for any Trading Day will be the mean, as determined by the Calculation Agent, of the bid prices for the Underlying Shares (or any such other security) for such Trading Day obtained from as many recognized dealers in such security, but not exceeding three, as will make such bid prices available to the Calculation Agent. Bids of Morgan Stanley & Co. LLC (“MS & Co.”) and its successors or any of its affiliates may be included in the calculation of such mean, but only to the extent that any such bid is the highest of the bids obtained. If no bid prices are provided from any third-party dealers, the Closing Price will be determined by the Calculation Agent in its sole and absolute discretion (acting in good faith) taking into account any information that it deems relevant. The term “OTC Bulletin Board Service” will include any successor service thereto, or, if applicable, the OTC Reporting Facility operated by FINRA. This definition of “Closing Price” is subject to the provisions under “—Discontinuance of any Underlying Shares and/or Share Underlying Indices; Alteration of Method of Calculation” below.
♦“Trading Day” means a day, as determined by the Calculation Agent, on which trading is generally conducted on each of the Relevant Exchange(s) for either of the Underlying Shares , other than a day on which trading on such exchange(s) is scheduled to close prior to the time of the posting of its regular final weekday closing price.
♦“Market Disruption Event” means, with respect to each of the Underlying Shares:
(i)the occurrence or existence of any of:
(a) a suspension, absence or material limitation of trading of such Underlying Shares on the primary market for such Underlying Shares for more than two hours of trading or during the one-half hour period preceding the close of the principal trading session in such market; or a breakdown or failure in the price and trade reporting systems of the primary market for such Underlying Shares as a result of which the reported trading prices for such Underlying Shares during the last one-half hour preceding the close of the principal trading session in such market are materially inaccurate; or the suspension, absence or material limitation of trading on the primary market for trading in futures or options contracts related to such Underlying Shares, if available, during the one-half hour period preceding the close of the principal trading session in the applicable market, or
22
(b) the occurrence or existence of a suspension, absence or material limitation of trading of securities then constituting 20 percent or more of the value of the relevant Share Underlying Index on the Relevant Exchanges for such securities for more than two hours of trading or during the one-half hour period preceding the close of the principal trading session on such Relevant Exchanges, or
(c) the suspension, material limitation or absence of trading on any major U.S. securities market for trading in futures or options contracts related to the relevant Share Underlying Index or such Underlying Shares for more than two hours of trading or during the one-half hour period preceding the close of the principal trading session on such market,
in each case, as determined by the Calculation Agent in its sole discretion; and
(ii)a determination by the Calculation Agent in its sole discretion that any event described in clause (i) above materially interfered with our ability or the ability of any of our affiliates to unwind or adjust all or a material portion of the hedge position with respect to the Securities.
For the purpose of determining whether a Market Disruption Event exists at any time, if trading in a security included in a Share Underlying Index is materially suspended or materially limited at that time, then the relevant percentage contribution of that security to the level of the Share Underlying Index shall be based on a comparison of (x) the portion of the level of such Share Underlying Index attributable to that security relative to (y) the overall level of such Share Underlying Index, in each case immediately before that suspension or limitation.
For the purpose of determining whether a Market Disruption Event has occurred: (1) a limitation on the hours or number of days of trading will not constitute a Market Disruption Event if it results from an announced change in the regular business hours of the Relevant Exchange or market, (2) a decision to permanently discontinue trading in either of the Underlying Shares or in the futures or options contract related to a Share Underlying Index or such Underlying Shares will not constitute a Market Disruption Event, (3) a suspension of trading in futures or options contracts on such Share Underlying Index or the Underlying Shares by the primary securities market trading in such contracts by reason of (a) a price change exceeding limits set by such securities exchange or market, (b) an imbalance of orders relating to such contracts or (c) a disparity in bid and ask quotes relating to such contracts will constitute a suspension, absence or material limitation of trading in futures or options contracts related to a Share Underlying Index or such Underlying Shares and (4) a “suspension, absence or material limitation of trading” on any Relevant Exchange or on the primary market on which futures or options contracts related to a Share Underlying Index or such Underlying Shares are traded will not include any time when such securities market is itself closed for trading under ordinary circumstances.
♦“Relevant Exchange” means the primary exchange(s) or market(s) of trading for any security (or any combination thereof) then included in the relevant Share Underlying Index or any Successor Index.
Postponement of Final Valuation Date and Maturity Date
If the scheduled Final Valuation Date is not a Trading Day or if a Market Disruption Event with respect to an Underlying Shares occurs on such date, the Closing Price solely for such Underlying Shares for such date will be determined on the immediately succeeding Trading Day on which no Market Disruption Event shall have occurred with respect to such affected Underlying Shares; provided that the Closing Price with respect to the Final Valuation Date will not be determined on a date later than the fifth scheduled Trading Day after the scheduled Final Valuation Date, and if such date is not a Trading Day or if there is a Market Disruption Event on such date, the Calculation Agent will determine the Closing Price of the affected Underlying Shares on such date as the mean of the bid prices for such Underlying Shares for such date obtained from as many recognized dealers in such security, but not exceeding three, as will make such bid prices available to the Calculation Agent. Bids of MS & Co. or any of its affiliates may be included in the calculation of such mean, but only to the extent that any such bid is the highest of the bids obtained. If no bid prices are provided from any third-party dealers, the Closing Price will be determined by the Calculation Agent in its sole and absolute discretion (acting in good faith) taking into account any information that it deems relevant.
If the Final Valuation Date is postponed so that it falls less than two business days prior to the scheduled Maturity Date, the Maturity Date will be the second business day following the Final Valuation Date, as postponed.
Antidilution Adjustments for Securities linked to Exchange-Traded Funds
If the shares of either of the Underlying Shares are subject to a stock split or reverse stock split, then once such split has become effective, the Adjustment Factor will be adjusted to equal the product of the prior Adjustment Factor and the number of shares issued in such stock split or reverse stock split with respect to one Underlying Share of such Underlying Shares. No such adjustment to an Adjustment Factor will be required unless such adjustment would require a change of at least 0.1% in the amount being adjusted as then in effect. Any number so adjusted will be rounded to the nearest one hundred-thousandth with five one-millionths being rounded upward.
Alternate Exchange Calculation in case of an Event of Default
If an event of default with respect to the Securities shall have occurred and be continuing, the amount declared due and payable upon any acceleration of the Securities (the “Acceleration Amount”) will be an amount, determined by the Calculation Agent in its sole discretion, that is equal to the cost of having a Qualified Financial Institution, of the kind and selected as described below, expressly assume all our payment and other obligations with respect to the Securities as of that day and as if no default or
23
acceleration had occurred, or to undertake other obligations providing substantially equivalent economic value to you with respect to the Securities. That cost will equal:
othe lowest amount that a Qualified Financial Institution would charge to effect this assumption or undertaking, plus
othe reasonable expenses, including reasonable attorneys’ fees, incurred by the holders of the Securities in preparing any documentation necessary for this assumption or undertaking.
During the Default Quotation Period for the Securities, which we describe below, the holders of the Securities and/or we may request a Qualified Financial Institution to provide a quotation of the amount it would charge to effect this assumption or undertaking. If either party obtains a quotation, it must notify the other party in writing of the quotation. The amount referred to in the first bullet point above will equal the lowest—or, if there is only one, the only—quotation obtained, and as to which notice is so given, during the Default Quotation Period. With respect to any quotation, however, the party not obtaining the quotation may object, on reasonable and significant grounds, to the assumption or undertaking by the Qualified Financial Institution providing the quotation and notify the other party in writing of those grounds within two business days after the last day of the Default Quotation Period, in which case that quotation will be disregarded in determining the Acceleration Amount.
Notwithstanding the foregoing, if a voluntary or involuntary liquidation, bankruptcy or insolvency of, or any analogous proceeding is filed with respect to MSFL or Morgan Stanley, then depending on applicable bankruptcy law, your claim may be limited to an amount that could be less than the Acceleration Amount.
If the maturity of the Securities is accelerated because of an event of default as described above, we shall, or shall cause the Calculation Agent to, provide written notice to the Trustee at its New York office, on which notice the Trustee may conclusively rely, and to the Depositary of the Acceleration Amount and the aggregate cash amount due, if any, with respect to the Securities as promptly as possible and in no event later than two business days after the date of such acceleration.
Default Quotation Period
The Default Quotation Period is the period beginning on the day the Acceleration Amount first becomes due and ending on the third business day after that day, unless:
ono quotation of the kind referred to above is obtained, or
oevery quotation of that kind obtained is objected to within five business days after the due date as described above.
If either of these two events occurs, the Default Quotation Period will continue until the third business day after the first business day on which prompt notice of a quotation is given as described above. If that quotation is objected to as described above within five business days after that first business day, however, the Default Quotation Period will continue as described in the prior sentence and this sentence.
In any event, if the Default Quotation Period and the subsequent two business day objection period have not ended before the Final Valuation Date, then the Acceleration Amount will equal the principal amount of the Securities.
Qualified Financial Institutions
For the purpose of determining the Acceleration Amount at any time, a Qualified Financial Institution must be a financial institution organized under the laws of any jurisdiction in the United States or Europe, which at that time has outstanding debt obligations with a stated maturity of one year or less from the date of issue and rated either:
oA-2 or higher by Standard & Poor’s Ratings Services or any successor, or any other comparable rating then used by that rating agency, or
oP-2 or higher by Moody’s Investors Service or any successor, or any other comparable rating then used by that rating agency.
Discontinuance of any Underlying Shares and/or Share Underlying Indices; Alteration of Method of Calculation
If trading in either of the Underlying Shares on every applicable national securities exchange, on the OTC Bulletin Board and in the over-the-counter market is permanently discontinued or either of the Underlying Shares are liquidated or otherwise terminated (a “Discontinuance or Liquidation Event”), the Closing Price of an Underlying Shares on the Final Valuation Date or the date of acceleration following the Discontinuance or Liquidation Event will be determined by the Calculation Agent and will be deemed to equal the product of (i) the closing value of the relevant Share Underlying Index for such Underlying Shares (or any Successor Index, as described below) on such date (taking into account any material changes in the method of calculating the Share Underlying Index following such Discontinuance or Liquidation Event) and (ii) a fraction, the numerator of which is the Closing Price of such Underlying Shares and the denominator of which is the closing value of the Share Underlying Index (or any Successor Index, as described below), each determined as of the last day prior to the occurrence of the Discontinuance or Liquidation Event on which a Closing Price of such Underlying Shares was available.
If, subsequent to a Discontinuance or Liquidation Event, the relevant Share Underlying Index Publisher discontinues publication of the relevant Share Underlying Index and the Share Underlying Index Publisher or another entity (including MS & Co.) publishes a successor or substitute index that the Calculation Agent, determines, in its sole discretion, to be comparable to the discontinued Share Underlying Index (such index being referred to herein as a “Successor Index”), then any subsequent Closing Price for such
24
Underlying Shares on any Trading Day following a Discontinuance or Liquidation Event will be determined by reference to the published value of such Successor Index at the regular weekday close of trading on such Trading Day, and, to the extent the value of the Successor Index differs from the value of the relevant Share Underlying Index at the time of such substitution, proportionate adjustments will be made by the Calculation Agent to the Initial Price and Downside Threshold.
Upon any selection by the Calculation Agent of a Successor Index, the Calculation Agent will cause written notice thereof to be furnished to the Trustee, to us and to the Depositary, as holder of the Securities, within three business days of such selection. We expect that such notice will be made available to you, as a beneficial owner of such Securities, in accordance with the standard rules and procedures of the Depositary and its direct and indirect participants.
If, subsequent to a Discontinuance or Liquidation Event, the Share Underlying Index Publisher discontinues publication of the relevant Share Underlying Index prior to, and such discontinuance is continuing on, the Final Valuation Date, and the Calculation Agent determines, in its sole discretion, that no Successor Index is available at such time, then the Calculation Agent will determine the Closing Price for such Underlying Shares for such date. Such Closing Price will be computed by the Calculation Agent in accordance with the formula for and method of calculating such Share Underlying Index last in effect prior to such discontinuance, using the Closing Price (or, if trading in the relevant securities has been materially suspended or materially limited, its good faith estimate of the Closing Price that would have prevailed but for such suspension or limitation) at the close of the principal trading session of the Relevant Exchange on the Final Valuation Date of each security most recently constituting the relevant Share Underlying Index without any rebalancing or substitution of such securities following such discontinuance. Notwithstanding these alternative arrangements, discontinuance of the publication of a Share Underlying Index may adversely affect the value of the Securities.
Trustee
The “Trustee” for each offering of notes issued under our Senior Debt Indenture, including the Securities, will be The Bank of New York Mellon, a New York banking corporation.
Agent
The “agent” is MS & Co.
Calculation Agent and Calculations
The “Calculation Agent” for the Securities will be MS & Co. As Calculation Agent, MS & Co. will determine, among other things, the Initial Prices, the Final Prices, the Underlying Share Returns and the Payment at Maturity.
All determinations made by the Calculation Agent will be at the sole discretion of the Calculation Agent and will, in the absence of manifest error, be conclusive for all purposes and binding on you, the Trustee and us.
All calculations with respect to the Payment at Maturity, if any, will be rounded to the nearest one hundred-thousandth, with five one-millionths rounded upward (e.g., .876545 would be rounded to .87655); all dollar amounts related to determination of the amount of cash payable per Security will be rounded to the nearest ten-thousandth, with five one hundred-thousandths rounded upward (e.g., .76545 would be rounded up to .7655); and all dollar amounts paid on the aggregate number of Securities will be rounded to the nearest cent, with one-half cent rounded upward.
Because the Calculation Agent is our affiliate, the economic interests of the Calculation Agent and its affiliates may be adverse to your interests, as an owner of the Securities, including with respect to certain determinations and judgments that the Calculation Agent must make in determining the Final Price or whether a Market Disruption Event has occurred. See “—Discontinuance of the Underlying Shares and/or Share Underlying Index; Alteration of Method of Calculation,” and the definition of Market Disruption Event. MS & Co. is obligated to carry out its duties and functions as Calculation Agent in good faith and using its reasonable judgment.
Issuer Notice to Registered Security Holders, the Trustee and the Depositary
In the event that the Maturity Date of the Securities is postponed due to a postponement of the Final Valuation Date, the Issuer shall give notice of such postponement and, once it has been determined, of the date to which the Maturity Date has been rescheduled (i) to each registered holder of the Securities by mailing notice of such postponement by first class mail, postage prepaid, to such registered holder’s last address as it shall appear upon the registry books, (ii) to the Trustee by facsimile confirmed by mailing such notice to the Trustee by first class mail, postage prepaid, at its New York office and (iii) to The Depository Trust Company (the “Depositary”) by telephone or facsimile confirmed by mailing such notice to the Depositary by first class mail, postage prepaid. Any notice that is mailed to a registered holder of the Securities in the manner herein provided shall be conclusively presumed to have been duly given to such registered holder, whether or not such registered holder receives the notice. The Issuer shall give such notice as promptly as possible, and in no case later than (i) with respect to notice of postponement of the Maturity Date, the Business Day immediately preceding the scheduled Maturity Date and (ii) with respect to notice of the date to which the Maturity Date has been rescheduled, the Business Day immediately following the Final Valuation Date as postponed.
The Issuer shall, or shall cause the Calculation Agent to, (i) provide written notice to the Trustee and to the Depositary of the amount of cash, if any, to be delivered with respect to each stated principal amount of the Securities, on or prior to 10:30 a.m.
25
(New York City time) on the Business Day preceding the Maturity Date, and (ii) deliver the aggregate cash amount due with respect to the Securities, if any, to the Trustee for delivery to the Depositary, as holder of the Securities, on the Maturity Date.
26
|
Additional Information About the Securities |
Use of Proceeds and Hedging
The proceeds from the sale of the Securities will be used by us for general corporate purposes. We will receive, in aggregate, $10 per Security issued, because, when we enter into hedging transactions in order to meet our obligations under the Securities, our hedging counterparty will reimburse the cost of the Agent’s commissions. The costs of the Securities borne by you and described on page 2 above comprise the Agent’s commissions and the cost of issuing, structuring and hedging the Securities. See also “Use of Proceeds” in the accompanying prospectus.
On or prior to the Trade Date, we will hedge our anticipated exposure in connection with the Securities, by entering into hedging transactions with our affiliates and/or third-party dealers. We expect our hedging counterparties to take positions in the Underlying Shares or the constituent stocks of the Share Underlying Indices, in futures or options contracts on the Underlying Shares, the Share Underlying Indices or the constituent stocks of the Share Underlying Indices, as well as in other instruments related to the Underlying Shares or the Share Underlying Indices that they may wish to use in connection with such hedging. Such purchase activity could increase the Initial Price of either Underlying, and, therefore, could increase the Downside Threshold of either Underlying Shares, which is the price at or above which such Underlying Shares must close on the Final Valuation Date so that you do not suffer a significant loss on your initial investment in the Securities (depending also on the performance of the other Underlying Shares). In addition, through our affiliates, we are likely to modify our hedge position throughout the term of the Securities, including on the Final Valuation Date, by purchasing and selling the Underlying Shares or the constituent stocks of the Shares Underlying Indices, futures or options contracts on the Underlying Shares, the Share Underlying Indices or the component stocks listed on major securities markets or positions in any other available securities or instruments that we may wish to use in connection with such hedging activities, including by purchasing or selling any such securities or instruments on the Final Valuation Date. As a result, these entities may be unwinding or adjusting hedge positions during the term of the Securities, and the hedging strategy may involve greater and more frequent dynamic adjustments to the hedge as the Final Valuation Date approaches. We cannot give any assurance that our hedging activities will not affect the prices of either of the Underlying Shares and, therefore, adversely affect the value of the Securities or the amount payable at maturity, if any (depending also on the performance of the other Underlying Shares).
Supplemental Plan of Distribution; Conflicts of Interest
MS & Co. is the agent for this offering. We have agreed to sell to MS & Co., and MS & Co. has agreed to purchase, all of the Securities at the issue price less the underwriting discount indicated on the cover of this document. UBS Financial Services Inc., acting as dealer, will receive from MS & Co. a fixed sales commission of $0.35 for each Security it sells.
MS & Co. is our affiliate and a wholly owned subsidiary of Morgan Stanley, and it and other affiliates of ours expect to make a profit by selling, structuring and, when applicable, hedging the Securities.
MS & Co. will conduct this offering in compliance with the requirements of Rule 5121 of the Financial Industry Regulatory Authority, Inc. (“FINRA”), regarding a FINRA member firm’s distribution of the securities of an affiliate and related conflicts of interest. MS & Co. or any of our other affiliates may not make sales in this offering to any discretionary account.
In order to facilitate the offering of the Securities, the agent may engage in transactions that stabilize, maintain or otherwise affect the price of the Securities. Specifically, the agent may sell more Securities than it is obligated to purchase in connection with the offering, creating a naked short position in the Securities, for its own account. The agent must close out any naked short position by purchasing the Securities in the open market. A naked short position is more likely to be created if the agent is concerned that there may be downward pressure on the price of the Securities in the open market after pricing that could adversely affect investors who purchase in the offering. As an additional means of facilitating the offering, the agent may bid for, and purchase, the Securities, the Underlying Shares or the stocks constituting the Share Underlying Indices in the open market to stabilize the price of the Securities. Any of these activities may raise or maintain the market price of the Securities above independent market levels or prevent or retard a decline in the market price of the Securities. The agent is not required to engage in these activities, and may end any of these activities at any time. An affiliate of the agent has entered into a hedging transaction with us in connection with this offering of Securities. See “—Use of Proceeds and Hedging” above.
Form of Securities
The Securities will be issued in the form of one or more fully registered global securities which will be deposited with, or on behalf of, the Depositary and will be registered in the name of a nominee of the Depositary. The Depositary’s nominee will be the only registered holder of the Securities. Your beneficial interest in the Securities will be evidenced solely by entries on the books of the securities intermediary acting on your behalf as a direct or indirect participant in the Depositary. In this pricing supplement, all references to payments or notices to you will mean payments or notices to the Depositary, as the registered holder of the Securities, for distribution to participants in accordance with the Depositary’s procedures. For more information regarding the Depositary and book entry notes, please read “Form of Securities—The Depositary” and “Securities Offered on a Global Basis Through the Depositary” in the accompanying prospectus.
27
Validity of the Securities
In the opinion of Davis Polk & Wardwell LLP, as special counsel to MSFL and Morgan Stanley, when the Securities offered by this pricing supplement have been executed and issued by MSFL, authenticated by the trustee pursuant to the MSFL Senior Debt Indenture (as defined in the accompanying prospectus) and delivered against payment as contemplated herein, such Securities will be valid and binding obligations of MSFL and the related guarantee will be a valid and binding obligation of Morgan Stanley, enforceable in accordance with their terms, subject to applicable bankruptcy, insolvency and similar laws affecting creditors’ rights generally, concepts of reasonableness and equitable principles of general applicability (including, without limitation, concepts of good faith, fair dealing and the lack of bad faith), provided that such counsel expresses no opinion as to (i) the effect of fraudulent conveyance, fraudulent transfer or similar provision of applicable law on the conclusions expressed above and (ii) any provision of the MSFL Senior Debt Indenture that purports to avoid the effect of fraudulent conveyance, fraudulent transfer or similar provision of applicable law by limiting the amount of Morgan Stanley’s obligation under the related guarantee. This opinion is given as of the date hereof and is limited to the laws of the State of New York, the General Corporation Law of the State of Delaware and the Delaware Limited Liability Company Act. In addition, this opinion is subject to customary assumptions about the trustee’s authorization, execution and delivery of the MSFL Senior Debt Indenture and its authentication of the Securities and the validity, binding nature and enforceability of the MSFL Senior Debt Indenture with respect to the trustee, all as stated in the letter of such counsel dated February 26, 2024, which is Exhibit 5-a to Post-Effective Amendment No. 2 to the Registration Statement on Form S-3 filed by Morgan Stanley on February 26, 2024.
28
ATTACHMENTS / EXHIBITS

FREE Breaking News Alerts from StreetInsider.com!
StreetInsider.com Top Tickers, 10/10/2026
- Wall Street posts weekly gains with earnings, inflation data on tap
- Oil prices settle higher as more production shut ahead of hurricane
- Apple cuts iPhone 18 Pro orders due to soft demand, Nikkei Asia reports
- UBS flags level in gold prices where dip buyers will likely emerge
- Telecom stocks tumble on SpaceX spectrum acquisition news
Create E-mail Alert Related Categories
SEC FilingsRelated Entities
Morgan StanleySign up for StreetInsider Free!
Receive full access to all new and archived articles, unlimited portfolio tracking, e-mail alerts, custom newswires and RSS feeds - and more!
