Form FWP ROYAL BANK OF CANADA Filed by: ROYAL BANK OF CANADA
Royal Bank of Canada Market Linked Securities |
Filed Pursuant to Rule 433 Registration Statement No. 333-275898
|

|
Market Linked Securities—Auto-Callable with Contingent Coupon and Contingent Downside Principal at Risk Securities Linked to the Lowest Performing of the Nasdaq-100 Index®, the Russell 2000® Index and the S&P 500® Index due November 1, 2029 Term Sheet dated October 21, 2026 |
|
Summary of Terms |
Summary of Terms (continued) |
| Issuer: | Royal Bank of Canada |
| Market Measures: | The Nasdaq-100 Index® (the “NDX Index”), the Russell 2000® Index (the “RTY Index”) and the S&P 500® Index (the “SPX Index”) (each an “Index” and collectively the “Indices”) |
| Pricing Date: | October 29, 2026 |
| Issue Date: | November 3, 2026 |
| Final Calculation Day: | October 29, 2029 |
| Stated Maturity Date: | November 1, 2029 |
| Face Amount: | $1,000 per security |
| Contingent Coupon Payment: | On each contingent coupon payment date, you will receive a contingent coupon payment at a per annum rate equal to the contingent coupon rate if the closing value of the lowest performing Index on the related calculation day is greater than or equal to its coupon threshold value. Each “contingent coupon payment,” if any, will be calculated per security as follows: ($1,000 × contingent coupon rate)/4. |
| Contingent Coupon Payment Dates: | Quarterly, on the third business day following each calculation day, provided that the contingent coupon payment date with respect to the final calculation day will be the stated maturity date |
| Contingent Coupon Rate: | At least 8.75% per annum, to be determined on the pricing date |
| Automatic Call: | If the closing value of the lowest performing Index on any of the quarterly calculation days scheduled to occur from January 2027 to July 2029, inclusive, is greater than or equal to its starting value, the securities will be automatically called, and on the related call settlement date you will be entitled to receive a cash payment per security in U.S. dollars equal to the face amount plus a final contingent coupon payment. |
| Calculation Days: | Quarterly, on the 29th day of each January, April, July and October, commencing January 2027 and ending October 2029, provided that the October 2029 calculation day will be the final calculation day |
| Call Settlement Date: | The contingent coupon payment date immediately following the applicable calculation day |
| Maturity Payment Amount, if the Securities Are Not Automatically Called (per Security): |
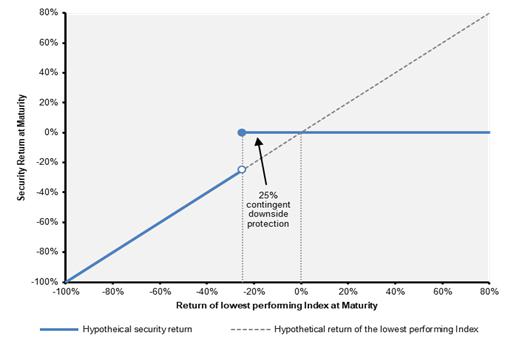
· if the ending value of the lowest performing Index on the final calculation day is greater than or equal to its downside threshold value: $1,000; or · if the ending value of the lowest performing Index on the final calculation day is less than its downside threshold value: $1,000 × performance factor of the lowest performing Index on the final calculation day |
| Lowest Performing Index: | For any calculation day, the Index with the lowest performance factor on that calculation day |
| Performance Factor: | With respect to an Index on any calculation day, its closing value on that calculation day divided by its starting value (expressed as a percentage) |
| Starting Value: | For each Index, its closing value on the pricing date |
| Ending Value: | For each Index, its closing value on the final calculation day |