


Form 8-K MACERICH CO For: Feb 04
QuickLinks -- Click here to rapidly navigate through this document
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, DC 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section�13 or 15(d) of the
Securities Exchange Act of 1934
Date of report (Date of earliest event reported) February�4, 2015
THE MACERICH COMPANY
(Exact Name of Registrant as Specified in Charter)
| MARYLAND (State or Other Jurisdiction of Incorporation) |
� | 1-12504 (Commission File Number) |
� | 95-4448705 (IRS Employer Identification No.) |
401 Wilshire Boulevard, Suite�700, Santa Monica, California 90401
(Address of Principal Executive Offices)������������������������(Zip Code)
Registrant's telephone number, including area code (310)�394-6000
N/A
(Former Name or Former Address, if Changed Since Last report)
Check the appropriate box below if the Form�8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction�A.2. below):
- o
- Written
communications pursuant to Rule�425 under the Securities Act (17�CFR�230.425)
- o
- Soliciting
material pursuant to Rule�14a-12 under the Exchange Act (17�CFR�240.14a-12)
- o
- Pre-commencement
communications pursuant to Rule�14d-2(b) under the Exchange Act
(17�CFR�240.14d-2(b))
- o
- Pre-commencement communications pursuant to Rule�13e-4(c) under the Exchange Act (17�CFR�240.13e-4(c))
���
ITEM 2.02����RESULTS OF OPERATIONS AND FINANCIAL CONDITION.
��������The Company issued a press release on February�4, 2015 announcing results of operations for the Company for the quarter ended December�31, 2014 and such press release is furnished as Exhibit�99.1 hereto.
��������The press release included as an exhibit with this report is being furnished pursuant to Item�2.02 and Item�7.01 of Form�8-K and shall not be deemed to be "filed" with the SEC or incorporated by reference into any other filing with the SEC.
ITEM 7.01����REGULATION FD DISCLOSURE.
��������On February�4, 2015, the Company made available on its website a financial supplement containing financial and operating information of the Company ("Supplemental Financial Information") for the three and twelve months ended December�31, 2014 and such Supplemental Financial Information is furnished as Exhibit�99.2 hereto.
��������The Supplemental Financial Information included as an exhibit with this report is being furnished pursuant to Item�7.01 of Form�8-K and shall not be deemed to be "filed" with the SEC or incorporated by reference into any other filing with the SEC.
ITEM 9.01����FINANCIAL STATEMENTS AND EXHIBITS.
��������Listed below are the financial statements, pro forma financial information and exhibits furnished as part of this report:
��������(a), (b)�and (c)�Not applicable.
��������(d) Exhibits.
��������Exhibit Index attached hereto and incorporated herein by reference.
2
��������Pursuant to the requirements of the Securities Exchange Act of 1934, The Macerich Company has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| � | � | THE MACERICH COMPANY |
� |
� |
By: THOMAS E. O'HERN |
February�4, 2015 Date |
� |
/s/�THOMAS E. O'HERN Senior Executive Vice President, Chief Financial Officer and Treasurer |
3
| EXHIBIT NUMBER |
� | NAME
|
|
|---|---|---|---|
| � | 99.1 | � | Press Release dated February�4, 2015 |
� |
99.2 |
� |
Supplemental Financial Information for the three and twelve months ended December�31, 2014 |
4
-
ITEM 2.02 RESULTS OF OPERATIONS AND FINANCIAL CONDITION.
ITEM 7.01 REGULATION FD DISCLOSURE.
ITEM 9.01 FINANCIAL STATEMENTS AND EXHIBITS.
EXHIBIT INDEX
QuickLinks -- Click here to rapidly navigate through this document
PRESS RELEASE
| For: | � | THE MACERICH COMPANY |
MACERICH ANNOUNCES QUARTERLY RESULTS AND 2015 EARNINGS GUIDANCE
��������Santa Monica, CA (2/04/15)�The Macerich Company (NYSE Symbol: MAC) today announced results of operations for the quarter ended December�31, 2014 which included funds from operations ("FFO") diluted of $158.8�million or $.99 per share-diluted compared to $140.6�million or $.94 per share-diluted for the quarter ended December�31, 2013. Included in the 2014 fourth quarter results is a loss on early extinguishment of debt of $9.1�million or $.06 per share related to the payoff of two high coupon mortgage loans. Net income attributable to the Company was $1.4�billion or $9.51 per share-diluted for the quarter ended December�31, 2014 compared to net income attributable to the Company for the quarter ended December�31, 2013 of $144.9�million or $1.03 per share-diluted. Included in net income in the 2014 fourth quarter and year to date results is a $1.4�billion or $8.88 per share gain on remeasurement resulting from the buyout of partner interests in five malls during the quarter. A description and reconciliation of FFO per share-diluted to EPS-diluted is included in the financial tables accompanying this press release.
Recent Highlights:
- �
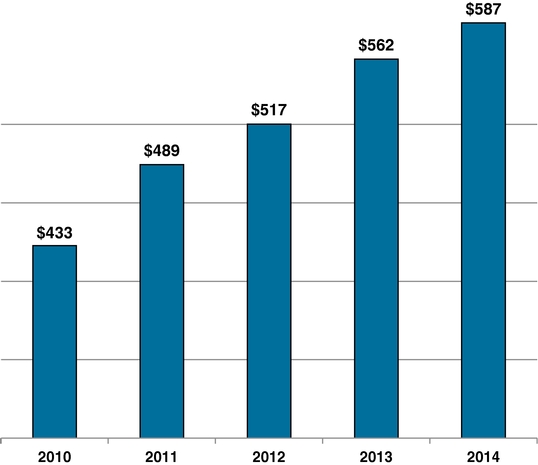
- Mall tenant annual sales per square foot for the portfolio increased 4.4% for the year ended December�31, 2014 to $587 compared
to $562 for the year ended December�31, 2013.������������On a same center basis, annual sales per square foot have increased to $587 for 2014, up from $574 for 2013.
- �
- The releasing spreads for the year ended December�31, 2014 were up 22%.
- �
- Mall portfolio occupancy was 95.8% at December�31, 2014 compared to 94.6% at December�31, 2013.
- �
- During the quarter the Company increased its' interest in Fashion Outlets of Chicago to 100%.
- �
- During the quarter the Company increased its ownership in five top super regional malls to 100% through a $1.8�billion acquisition of its partners' 49% interest in exchange for common stock and assumption of debt.
��������Commenting on the quarter, Arthur Coppola chairman and chief executive officer of Macerich stated, "Our solid leasing momentum continued into year-end, with additional occupancy gains and accelerating releasing spreads. In addition, we continued to execute on our deep pipeline of value-add redevelopment and expansion projects while also completing a number of significant transactions which further improved the quality and growth prospects of our portfolio. In particular, we are very pleased to have increased our ownership of five top super regional malls through a common stock for asset exchange with our long-time joint venture partner the Ontario Teachers' Pension Plan Board."
Developments:
��������At Tysons Corner Center, the Company's 2.1�million square foot super regional mall, construction continues on the multifamily and hotel components of this mixed use project which will add 1.4�million square feet to one of the country's premier retail centers. The Tysons expansion includes a 527,000 square foot office tower with major tenants Intelsat and Deloitte which opened in August. The office building is currently over 80% leased. A 30-story, 430-unit luxury residential tower; and a 300-room Hyatt Regency hotel are under construction with completion slated in early 2015.
��������At Broadway Plaza, in Walnut Creek, California, a major redevelopment, including a 235,000 square foot expansion, is underway. This 774,000 square foot mall (pre-expansion) is anchored by Macy's, Nordstrom and Neiman Marcus. The expansion will open in phases starting in fall 2015.
��������At both Los Cerritos Center and Scottsdale Fashion Square, expansions are underway to add a Dick's Sporting Goods store and a Harkins Theatre. Both projects are planned for completion in the second half of 2015.
Financing:
��������In December, the Company paid off a $156.2�million, 6.76% interest rate loan on Fresno Fashion Fair and a $98�million, 5.8% interest rate loan on Vintage Faire Mall. The Company incurred prepayment penalties totaling $9.1�million related to these early debt extinguishments. The Company has arranged a $280�million, eleven year fixed rate loan on Vintage Faire Mall. The interest rate is 3.49% and the transaction is expected to close in March, 2015.
Acquisitions:
��������In November, 2014 the Company closed on the acquisition of its joint venture partner's 49% interest in Queens Center, Washington Square, Los Cerritos Center, Stonewood Center and Lakewood Center from a wholly-owned subsidiary of the Ontario Teachers' Pension Plan Board. Total consideration was approximately $1.8�billion (USD), including the assumption of $672�million of property-level debt. The balance was funded through the direct issuance to a wholly-owned subsidiary of the Ontario Teachers' Pension Plan Board of approximately 17.1�million shares of Macerich common stock, representing a 10.9% common ownership stake in the Company.
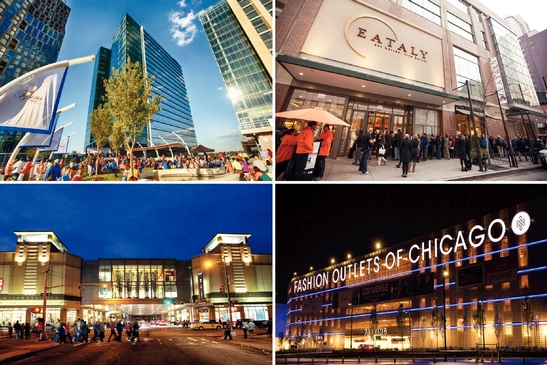
��������Also in November, the Company closed on the acquisition of joint venture partner AWE Talisman's 40% interest in Fashion Outlets of Chicago for $70�million. With this purchase, Macerich now owns 100% of the recently-developed, 529,000 square foot center which was completed in August 2013 and, as of December�31, 2014, was 94.4% occupied with annual tenant sales of $651 per square foot.
Dispositions:
��������In October, the Company sold South Towne Center in Sandy, Utah for $205�million. This 1.2�million square foot mall had annual tenant sales of $344 per square foot.
��������Also, during the quarter, the Company sold its 67.5% interest in Camelback Colonnade, a community center in Phoenix, Arizona. The Company's proceeds from this transaction totaled $61.2�million. These transactions increased the Company's 2014 dispositions of non-core assets to $360�million.
2015 Earnings Guidance:
��������Management is providing diluted EPS and FFO per share guidance for 2015.
��������A reconciliation of estimated EPS to FFO per share-diluted follows:
| � |
� |
� |
� | |
|---|---|---|---|---|
| � |
� | 2015 range | � | |
Diluted EPS |
� | � | $1.28�-�$1.38 | � |
Plus: real estate depreciation and amortization |
� | � | ��2.52�-���2.52 | � |
Less: gain on sale of dispositions |
� | � | ����.00�����.00 | � |
Diluted FFO per share |
� | � | $3.80�$3.90 | � |
��������Details of the guidance assumptions are included in the Company's Form�8-K supplemental financial information.
��������Macerich, an S&P�500 company, currently celebrating 20�years of trading on the NYSE, is a fully integrated self-managed and self-administered real estate investment trust, which focuses on the acquisition, leasing, management, development and redevelopment of regional malls throughout the United States.
��������Macerich currently owns 54�million square feet of real estate consisting primarily of interests in 51 regional shopping centers. Macerich specializes in successful retail properties in many of the country's most attractive, densely populated markets with significant presence in California, Arizona, Chicago, and the Greater New York Metro area. Additional information about Macerich can be obtained from the Company's website at www.macerich.com.
Investor Conference Call
��������The Company will provide an online Web simulcast and rebroadcast of its quarterly earnings conference call. The call will be available on The Macerich Company's website at www.macerich.com (Investing Section). The call begins Thursday, February�5, 2015 at 10:30 AM Pacific Time. To listen to the call, please go to the website at least 15 minutes prior to the call in order to register and download audio software if needed. An online replay at www.macerich.com (Investing Section) will be available for one year after the call.
��������The Company will publish a supplemental financial information package which will be available at www.macerich.com in the Investing Section. It will also be furnished to the SEC as part of a Current Report on Form�8-K.
��������Note: This release contains statements that constitute forward-looking statements which can be identified by the use of words, such as "expects," "anticipates," "assumes," "projects," "estimated" and "scheduled" and similar expressions that do not relate to historical matters. Stockholders are cautioned that any such forward-looking statements are not guarantees of future performance and involve risks, uncertainties and other factors that may cause actual results, performance or achievements of the Company to vary materially from those anticipated, expected or projected. Such factors include, among others, general industry, as well as national, regional and local economic and business conditions, which will, among other things, affect demand for retail space or retail goods, availability and creditworthiness of current and prospective tenants, anchor or tenant bankruptcies, closures, mergers or consolidations, lease rates, terms and payments, interest rate fluctuations, availability, terms and cost of financing and operating expenses; adverse changes in the real estate markets including, among other things, competition from other companies, retail formats and technology, risks of real estate development and redevelopment, acquisitions and dispositions; the liquidity of real estate investments, governmental actions and initiatives (including legislative and regulatory changes); environmental and safety requirements; and terrorist activities or other acts of violence which could adversely affect all of the above factors. The reader is directed to the Company's various filings with the Securities and Exchange Commission, including the Annual Report on Form�10-K for the year ended December�31, 2013, for a discussion of such risks and uncertainties, which discussion is incorporated herein by reference. The Company does not intend, and undertakes no obligation, to update any forward-looking information to reflect events or circumstances after the date of this release or to reflect the occurrence of unanticipated events unless required by law to do so.
��������(See attached tables)
THE MACERICH COMPANY
FINANCIAL HIGHLIGHTS
(IN THOUSANDS, EXCEPT PER SHARE AMOUNTS)
Results of Operations:
| � |
� |
� |
� | ||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | Results before Discontinued Operations(a) |
� | Impact of Discontinued Operations(a) |
� | Results after Discontinued Operations(a) |
� | ||||||||||||
| � |
� | For the Three Months Ended December�31, |
� | For the Three Months Ended December�31, |
� | For the Three Months Ended December�31, |
� | ||||||||||||
| � |
� | Unaudited | � | Unaudited | � | Unaudited | � | ||||||||||||
| � |
� | 2014 | � | 2013 | � | 2014 | � | 2013 | � | 2014 | � | 2013 | � | ||||||
Minimum rents |
� | $ | 182,323 | � | $ | 159,967 | � | $ | 0 | � | $ | (4,349 | ) | $ | 182,323 | � | $ | 155,618 | � |
Percentage rents |
� | � | 15,055 | � | � | 13,107 | � | � | � | � | � | (561 | ) | � | 15,055 | � | � | 12,546 | � |
Tenant recoveries |
� | � | 96,210 | � | � | 92,138 | � | � | � | � | � | (2,223 | ) | � | 96,210 | � | � | 89,915 | � |
Management Companies' revenues |
� | � | 8,733 | � | � | 9,001 | � | � | � | � | � | � | � | � | 8,733 | � | � | 9,001 | � |
Other income |
� | � | 20,588 | � | � | 15,249 | � | � | � | � | � | (192 | ) | � | 20,588 | � | � | 15,057 | � |
Total revenues |
� | � | 322,909 | � | � | 289,462 | � | � | 0 | � | � | (7,325 | ) | � | 322,909 | � | � | 282,137 | � |
Shopping center and operating expenses |
� | � | 95,922 | � | � | 91,643 | � | � | � | � | � | (2,482 | ) | � | 95,922 | � | � | 89,161 | � |
Management Companies' operating expenses |
� | � | 23,239 | � | � | 24,459 | � | � | � | � | � | � | � | � | 23,239 | � | � | 24,459 | � |
REIT general and administrative expenses |
� | � | 12,073 | � | � | 9,099 | � | � | � | � | � | � | � | � | 12,073 | � | � | 9,099 | � |
Depreciation and amortization |
� | � | 112,517 | � | � | 95,061 | � | � | � | � | � | (1,929 | ) | � | 112,517 | � | � | 93,132 | � |
Interest expense |
� | � | 50,748 | � | � | 49,941 | � | � | � | � | � | (2,353 | ) | � | 50,748 | � | � | 47,588 | � |
Loss on early extinguishment of debt, net |
� | � | 9,146 | � | � | 655 | � | � | � | � | � | (149 | ) | � | 9,146 | � | � | 506 | � |
Total expenses |
� | � | 303,645 | � | � | 270,858 | � | � | � | � | � | (6,913 | ) | � | 303,645 | � | � | 263,945 | � |
Equity in income of unconsolidated joint ventures |
� | � | 16,019 | � | � | 22,103 | � | � | � | � | � | � | � | � | 16,019 | � | � | 22,103 | � |
Co-venture expense(b) |
� | � | (3,315 | ) | � | (2,633 | ) | � | � | � | � | � | � | � | (3,315 | ) | � | (2,633 | ) |
Income tax benefit (expense) |
� | � | 510 | � | � | (572 | ) | � | � | � | � | � | � | � | 510 | � | � | (572 | ) |
Gain (loss) on sale or write down of assets, net |
� | � | 74,944 | � | � | 98,423 | � | � | � | � | � | (152,418 | ) | � | 74,944 | � | � | (53,995 | ) |
Gain on remeasurement of assets |
� | � | 1,423,136 | � | � | 14,864 | � | � | � | � | � | � | � | � | 1,423,136 | � | � | 14,864 | � |
Income from continuing operations |
� | � | 1,530,558 | � | � | 150,789 | � | � | 0 | � | � | (152,830 | ) | � | 1,530,558 | � | � | (2,041 | ) |
Discontinued operations: |
� | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Gain on sale, disposition or write down of assets, net |
� | � | � | � | � | � | � | � | � | � | � | 152,269 | � | � | � | � | � | 152,269 | � |
Income from discontinued operations |
� | � | � | � | � | � | � | � | � | � | � | 561 | � | � | � | � | � | 561 | � |
Total income from discontinued operations |
� | � | � | � | � | � | � | � | � | � | � | 152,830 | � | � | � | � | � | 152,830 | � |
Net income |
� | � | 1,530,558 | � | � | 150,789 | � | � | � | � | � | � | � | � | 1,530,558 | � | � | 150,789 | � |
Less net income attributable to noncontrolling interests |
� | � | 101,337 | � | � | 5,911 | � | � | � | � | � | � | � | � | 101,337 | � | � | 5,911 | � |
Net income attributable to the Company |
� | $ | 1,429,221 | � | $ | 144,878 | � | $ | 0 | � | $ | 0 | � | $ | 1,429,221 | � | $ | 144,878 | � |
Average number of shares outstanding�basic |
� | � | 149,924 | � | � | 140,724 | � | � | � | � | � | � | � | � | 149,924 | � | � | 140,724 | � |
Average shares outstanding, assuming full conversion of OP Units(c) |
� | � | 160,026 | � | � | 150,348 | � | � | � | � | � | � | � | � | 160,026 | � | � | 150,348 | � |
Average shares outstanding�Funds From Operations ("FFO")�diluted(c) |
� | � | 160,241 | � | � | 150,375 | � | � | � | � | � | � | � | � | 160,241 | � | � | 150,375 | � |
Per share income�diluted before discontinued operations |
� | � | � | � | � | � | � | � | � | � | � | � | � | $ | 9.51 | � | $ | 0.01 | � |
Net income per share�basic |
� | $ | 9.52 | � | $ | 1.03 | � | � | � | � | � | � | � | $ | 9.52 | � | $ | 1.03 | � |
Net income per share�diluted |
� | $ | 9.51 | � | $ | 1.03 | � | � | � | � | � | � | � | $ | 9.51 | � | $ | 1.03 | � |
Dividend declared per share |
� | $ | 0.65 | � | $ | 0.62 | � | � | � | � | � | � | � | $ | 0.65 | � | $ | 0.62 | � |
FFO�basic(c)(d) |
� | $ | 158,848 | � | $ | 140,624 | � | � | � | � | � | � | � | $ | 158,848 | � | $ | 140,624 | � |
FFO�diluted(c)(d) |
� | $ | 158,848 | � | $ | 140,624 | � | � | � | � | � | � | � | $ | 158,848 | � | $ | 140,624 | � |
FFO�excluding early extinguishment of debt�diluted(c)(d) |
� | $ | 167,994 | � | $ | 141,279 | � | � | � | � | � | � | � | $ | 167,994 | � | $ | 141,279 | � |
FFO per share�basic(c)(d) |
� | $ | 0.99 | � | $ | 0.94 | � | � | � | � | � | � | � | $ | 0.99 | � | $ | 0.94 | � |
FFO per share�diluted(c)(d) |
� | $ | 0.99 | � | $ | 0.94 | � | � | � | � | � | � | � | $ | 0.99 | � | $ | 0.94 | � |
FFO per share excluding early extinguishment of debt�diluted(c)(d) |
� | $ | 1.05 | � | $ | 0.94 | � | � | � | � | � | � | � | $ | 1.05 | � | $ | 0.94 | � |
THE MACERICH COMPANY
FINANCIAL HIGHLIGHTS
(IN THOUSANDS, EXCEPT PER SHARE AMOUNTS)
Results of Operations:
| � |
� |
� |
� | ||||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | Results before Discontinued Operations(a) |
� | Impact of Discontinued Operations(a) |
� | Results after Discontinued Operations(a) |
� | ||||||||||||
| � |
� | For the Twelve Months Ended December�31, |
� | For the Twelve Months Ended December�31, |
� | For the Twelve Months Ended December�31, |
� | ||||||||||||
| � |
� | Unaudited | � | Unaudited | � | Unaudited | � | ||||||||||||
| � |
� | 2014 | � | 2013 | � | 2014 | � | 2013 | � | 2014 | � | 2013 | � | ||||||
Minimum rents |
� | $ | 633,571 | � | $ | 611,888 | � | $ | 0 | � | $ | (33,775 | ) | $ | 633,571 | � | $ | 578,113 | � |
Percentage rents |
� | � | 24,350 | � | � | 24,594 | � | � | � | � | � | (1,438 | ) | � | 24,350 | � | � | 23,156 | � |
Tenant recoveries |
� | � | 361,119 | � | � | 355,625 | � | � | � | � | � | (17,853 | ) | � | 361,119 | � | � | 337,772 | � |
Management Companies' revenues |
� | � | 33,981 | � | � | 40,192 | � | � | � | � | � | � | � | � | 33,981 | � | � | 40,192 | � |
Other income |
� | � | 52,226 | � | � | 51,928 | � | � | � | � | � | (1,686 | ) | � | 52,226 | � | � | 50,242 | � |
Total revenues |
� | � | 1,105,247 | � | � | 1,084,227 | � | � | 0 | � | � | (54,752 | ) | � | 1,105,247 | � | � | 1,029,475 | � |
Shopping center and operating expenses |
� | � | 353,505 | � | � | 349,225 | � | � | � | � | � | (19,430 | ) | � | 353,505 | � | � | 329,795 | � |
Management Companies' operating expenses |
� | � | 88,424 | � | � | 93,461 | � | � | � | � | � | � | � | � | 88,424 | � | � | 93,461 | � |
REIT general and administrative expenses |
� | � | 29,412 | � | � | 27,772 | � | � | � | � | � | � | � | � | 29,412 | � | � | 27,772 | � |
Depreciation and amortization |
� | � | 378,716 | � | � | 374,425 | � | � | � | � | � | (17,260 | ) | � | 378,716 | � | � | 357,165 | � |
Interest expense |
� | � | 190,689 | � | � | 211,787 | � | � | � | � | � | (14,540 | ) | � | 190,689 | � | � | 197,247 | � |
Loss (gain) on early extinguishment of debt, net |
� | � | 9,551 | � | � | (2,684 | ) | � | � | � | � | 1,252 | � | � | 9,551 | � | � | (1,432 | ) |
Total expenses |
� | � | 1,050,297 | � | � | 1,053,986 | � | � | � | � | � | (49,978 | ) | � | 1,050,297 | � | � | 1,004,008 | � |
Equity in income of unconsolidated joint ventures |
� | � | 60,626 | � | � | 167,580 | � | � | � | � | � | � | � | � | 60,626 | � | � | 167,580 | � |
Co-venture expense(b) |
� | � | (9,490 | ) | � | (8,864 | ) | � | � | � | � | � | � | � | (9,490 | ) | � | (8,864 | ) |
Income tax benefit |
� | � | 4,269 | � | � | 1,692 | � | � | � | � | � | � | � | � | 4,269 | � | � | 1,692 | � |
Gain (loss) on sale or write down of assets, net |
� | � | 73,440 | � | � | 207,105 | � | � | � | � | � | (285,162 | ) | � | 73,440 | � | � | (78,057 | ) |
Gain on remeasurement of assets |
� | � | 1,423,136 | � | � | 51,205 | � | � | � | � | � | � | � | � | 1,423,136 | � | � | 51,205 | � |
Income from continuing operations |
� | � | 1,606,931 | � | � | 448,959 | � | � | 0 | � | � | (289,936 | ) | � | 1,606,931 | � | � | 159,023 | � |
Discontinued operations: |
� | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Gain on sale, disposition or write down of assets, net |
� | � | � | � | � | � | � | � | � | � | � | 286,414 | � | � | � | � | � | 286,414 | � |
Income from discontinued operations������������������ |
� | � | � | � | � | � | � | � | � | � | � | 3,522 | � | � | � | � | � | 3,522 | � |
Total income from discontinued operations |
� | � | � | � | � | � | � | � | � | � | � | 289,936 | � | � | � | � | � | 289,936 | � |
Net income |
� | � | 1,606,931 | � | � | 448,959 | � | � | � | � | � | � | � | � | 1,606,931 | � | � | 448,959 | � |
Less net income attributable to noncontrolling interests |
� | � | 107,889 | � | � | 28,869 | � | � | � | � | � | � | � | � | 107,889 | � | � | 28,869 | � |
Net income attributable to the Company |
� | $ | 1,499,042 | � | $ | 420,090 | � | $ | 0 | � | $ | 0 | � | $ | 1,499,042 | � | $ | 420,090 | � |
Average number of shares outstanding�basic |
� | � | 143,144 | � | � | 139,598 | � | � | � | � | � | � | � | � | 143,144 | � | � | 139,598 | � |
Average shares outstanding, assuming full conversion of OP Units(c) |
� | � | 153,224 | � | � | 149,444 | � | � | � | � | � | � | � | � | 153,224 | � | � | 149,444 | � |
Average shares outstanding�Funds From Operations ("FFO")�diluted(c) |
� | � | 153,371 | � | � | 149,526 | � | � | � | � | � | � | � | � | 153,371 | � | � | 149,526 | � |
Per share income�diluted before discontinued operations |
� | � | � | � | � | � | � | � | � | � | � | � | � | $ | 10.45 | � | $ | 1.06 | � |
Net income per share-basic |
� | $ | 10.46 | � | $ | 3.01 | � | � | � | � | � | � | � | $ | 10.46 | � | $ | 3.01 | � |
Net income per share�diluted |
� | $ | 10.45 | � | $ | 3.00 | � | � | � | � | � | � | � | $ | 10.45 | � | $ | 3.00 | � |
Dividend declared per share |
� | $ | 2.51 | � | $ | 2.36 | � | � | � | � | � | � | � | $ | 2.51 | � | $ | 2.36 | � |
FFO�basic(c)(d) |
� | $ | 542,754 | � | $ | 527,574 | � | � | � | � | � | � | � | $ | 542,754 | � | $ | 527,574 | � |
FFO�diluted(c)(d) |
� | $ | 542,754 | � | $ | 527,574 | � | � | � | � | � | � | � | $ | 542,754 | � | $ | 527,574 | � |
FFO�excluding early extinguishment of debt�diluted(c)(d) |
� | $ | 552,305 | � | $ | 524,538 | � | � | � | � | � | � | � | $ | 552,305 | � | $ | 524,538 | � |
FFO per share�basic(c)(d) |
� | $ | 3.54 | � | $ | 3.53 | � | � | � | � | � | � | � | $ | 3.54 | � | $ | 3.53 | � |
FFO per share�diluted(c)(d) |
� | $ | 3.54 | � | $ | 3.53 | � | � | � | � | � | � | � | $ | 3.54 | � | $ | 3.53 | � |
FFO per share excluding early extinguishment of debt�diluted(c)(d) |
� | $ | 3.60 | � | $ | 3.51 | � | � | � | � | � | � | � | $ | 3.60 | � | $ | 3.51 | � |
THE MACERICH COMPANY
FINANCIAL HIGHLIGHTS
(IN THOUSANDS, EXCEPT PER SHARE AMOUNTS)
- (a)
- In April 2014, the Financial Accounting Standards Board issued guidance that amends the definition of discontinued
operations by limiting discontinued operations reporting to disposals that represent strategic shifts that have, or will have, a major effect on an entity's operations and financial results.
Previously, the Company had reported all disposed properties that qualified as discontinued operations. The Company early adopted this accounting pronouncement in the first quarter of 2014. As a
result, the Company's results of operations for all 2014 property disposals are presented within income from continuing operations in the consolidated statements of operations.
- (b)
- This
represents the outside partners' allocation of net income in the Chandler Fashion Center/Freehold Raceway Mall joint venture.
- (c)
- The
Macerich Partnership,�L.P. (the "Operating Partnership" or the "OP") has operating partnership units ("OP units"). OP units can be converted into
shares of Company common stock. Conversion of the OP units not owned by the Company has been assumed for purposes of calculating FFO per share and the weighted average number of shares outstanding.
The computation of average shares for FFO�diluted includes the effect of share and unit-based compensation plans, stock warrants and convertible senior notes using the treasury stock
method. It also assumes conversion of MACWH,�LP preferred and common units to the extent they are dilutive to the calculation.
- (d)
- The
Company uses FFO in addition to net income to report its operating and financial results and considers FFO and FFO-diluted as supplemental measures for
the real estate industry and a supplement to Generally Accepted Accounting Principles ("GAAP") measures. The National Association of Real Estate Investment Trusts ("NAREIT") defines FFO as net income
(loss) (computed in accordance with GAAP), excluding gains (or losses) from extraordinary items and sales of depreciated operating properties, plus real estate related depreciation and amortization,
impairment write-downs of real estate and write-downs of investments in an affiliate where the write-downs have been driven by a decrease in the value of real estate held by the affiliate and after
adjustments for unconsolidated joint ventures. Adjustments for unconsolidated joint ventures are calculated to reflect FFO on the same basis.
FFO and FFO on a diluted basis are useful to investors in comparing operating and financial results between periods. This is especially true since FFO excludes real estate depreciation and amortization, as the Company believes real estate values fluctuate based on market conditions rather than depreciating in value ratably on a straight-line basis over time. The Company believes that such a presentation also provides investors with a more meaningful measure of its operating results in comparison to the operating results of other real estate investment trusts ("REITs"). The Company believes that FFO on a diluted basis is a measure investors find most useful in measuring the dilutive impact of outstanding convertible securities. The Company further believes that FFO does not represent cash flow from operations as defined by GAAP, should not be considered as an alternative to net income (loss) as defined by GAAP, and is not indicative of cash available to fund all cash flow needs. The Company also cautions that FFO as presented, may not be comparable to similarly titled measures reported by other REITs.
THE MACERICH COMPANY
FINANCIAL HIGHLIGHTS
(IN THOUSANDS, EXCEPT PER SHARE AMOUNTS)
Reconciliation of Net income attributable to the Company to FFO (d):
| � |
� |
� |
� | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | For the Three Months Ended December�31, |
� | For the Twelve Months Ended December�31, |
� | ||||||||
| � |
� | Unaudited | � | Unaudited | � | ||||||||
| � |
� | 2014 | � | 2013 | � | 2014 | � | 2013 | � | ||||
Net income attributable to the Company |
� | $ | 1,429,221 | � | $ | 144,878 | � | $ | 1,499,042 | � | $ | 420,090 | � |
Adjustments to reconcile net income attributable to the Company to FFO�basic and diluted: |
� | � | � | � | � | � | � | � | � | � | � | � | � |
Noncontrolling interests in OP |
� | � | 100,594 | � | � | 10,033 | � | � | 105,584 | � | � | 29,637 | � |
Gain on sale or write down of consolidated assets, net |
� | � | (74,944 | ) | � | (98,423 | ) | � | (73,440 | ) | � | (207,105 | ) |
Gain on remeasurement of consolidated assets |
� | � | (1,423,136 | ) | � | (14,864 | ) | � | (1,423,136 | ) | � | (51,205 | ) |
plus gain on undepreciated asset sales�consolidated assets |
� | � | 477 | � | � | 308 | � | � | 1,396 | � | � | 2,546 | � |
plus non-controlling interests share of gain (loss) on sale or write down of consolidated joint ventures, net |
� | � | 185 | � | � | (5,245 | ) | � | 146 | � | � | (2,082 | ) |
(Gain) loss on sale or write down of assets from unconsolidated entities (pro rata), net |
� | � | (2,528 | ) | � | (3,295 | ) | � | 1,237 | � | � | (94,372 | ) |
plus gain on undepreciated asset sales�unconsolidated entities (pro rata) |
� | � | 2,621 | � | � | 169 | � | � | 2,621 | � | � | 602 | � |
Depreciation and amortization on consolidated assets |
� | � | 112,517 | � | � | 95,061 | � | � | 378,716 | � | � | 374,425 | � |
Less depreciation and amortization allocable to noncontrolling interests on consolidated joint ventures |
� | � | (4,419 | ) | � | (5,514 | ) | � | (20,700 | ) | � | (19,928 | ) |
Depreciation and amortization on joint ventures (pro rata) |
� | � | 21,244 | � | � | 20,396 | � | � | 82,570 | � | � | 86,866 | � |
Less: depreciation on personal property |
� | � | (2,984 | ) | � | (2,880 | ) | � | (11,282 | ) | � | (11,900 | ) |
Total FFO�basic and diluted |
� | $ | 158,848 | � | $ | 140,624 | � | $ | 542,754 | � | $ | 527,574 | � |
Loss (gain) on early extinguishment of debt, net�consolidated assets |
� | � | 9,146 | � | � | 655 | � | � | 9,551 | � | � | (2,684 | ) |
Gain on early extinguishment of debt, net�unconsolidated entities (pro rata) |
� | � | � | � | � | � | � | � | � | � | � | (352 | ) |
Total FFO excluding early extinguishment of debt�diluted |
� | $ | 167,994 | � | $ | 141,279 | � | $ | 552,305 | � | $ | 524,538 | � |
Reconciliation of EPS to FFO per diluted share (d):
| � |
� |
� |
� | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | For the Three Months Ended December�31, |
� | For the Twelve Months Ended December�31, |
� | ||||||||
| � |
� | Unaudited | � | Unaudited | � | ||||||||
| � |
� | 2014 | � | 2013 | � | 2014 | � | 2013 | � | ||||
Earnings per share�diluted |
� | $ | 9.51 | � | $ | 1.03 | � | $ | 10.45 | � | $ | 3.00 | � |
Per share impact of depreciation and amortization of real estate |
� | � | 0.79 | � | � | 0.72 | � | � | 2.81 | � | � | 2.88 | � |
Per share impact of gain on remeasurement, sale or write down of assets, net |
� | � | (9.31 | ) | � | (0.81 | ) | � | (9.72 | ) | � | (2.35 | ) |
FFO per share�diluted |
� | $ | 0.99 | � | $ | 0.94 | � | $ | 3.54 | � | $ | 3.53 | � |
Per share impact of loss (gain) on early extinguishment of debt, net |
� | � | 0.06 | � | � | 0.00 | � | � | 0.06 | � | � | (0.02 | ) |
FFO per share excluding early extinguishment of debt�diluted |
� | $ | 1.05 | � | $ | 0.94 | � | $ | 3.60 | � | $ | 3.51 | � |
THE MACERICH COMPANY
FINANCIAL HIGHLIGHTS
(IN THOUSANDS, EXCEPT PER SHARE AMOUNTS)
Reconciliation of Net income attributable to the Company to EBITDA:
| � |
� |
� |
� | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | For the Three Months Ended December�31, |
� | For the Twelve Months Ended December�31, |
� | ||||||||
| � |
� | Unaudited | � | Unaudited | � | ||||||||
| � |
� | 2014 | � | 2013 | � | 2014 | � | 2013 | � | ||||
Net income attributable to the Company |
� | $ | 1,429,221 | � | $ | 144,878 | � | $ | 1,499,042 | � | $ | 420,090 | � |
Interest expense�consolidated assets |
� | � | 50,748 | � | � | 49,941 | � | � | 190,689 | � | � | 211,787 | � |
Interest expense�unconsolidated entities (pro rata) |
� | � | 12,165 | � | � | 17,330 | � | � | 61,971 | � | � | 69,224 | � |
Depreciation and amortization�consolidated assets |
� | � | 112,517 | � | � | 95,061 | � | � | 378,716 | � | � | 374,425 | � |
Depreciation and amortization�unconsolidated entities (pro rata) |
� | � | 21,244 | � | � | 20,396 | � | � | 82,570 | � | � | 86,866 | � |
Noncontrolling interests in OP |
� | � | 100,594 | � | � | 10,033 | � | � | 105,584 | � | � | 29,637 | � |
Less: Interest expense and depreciation and amortization allocable to noncontrolling interests on consolidated joint ventures |
� | � | (6,871 | ) | � | (8,387 | ) | � | (31,960 | ) | � | (31,397 | ) |
Loss (gain) on early extinguishment of debt�consolidated entities |
� | � | 9,146 | � | � | 655 | � | � | 9,551 | � | � | (2,684 | ) |
Gain on early extinguishment of debt�unconsolidated entities (pro rata) |
� | � | � | � | � | � | � | � | � | � | � | (352 | ) |
Gain on sale or write down of assets�consolidated assets, net |
� | � | (74,944 | ) | � | (98,423 | ) | � | (73,440 | ) | � | (207,105 | ) |
Gain on remeasurement of assets�consolidated assets |
� | � | (1,423,136 | ) | � | (14,864 | ) | � | (1,423,136 | ) | � | (51,205 | ) |
(Gain) loss on sale or write down of assets�unconsolidated entities (pro rata), net |
� | � | (2,528 | ) | � | (3,295 | ) | � | 1,237 | � | � | (94,372 | ) |
Add: Non-controlling interests share of gain (loss) on sale of consolidated assets, net |
� | � | 185 | � | � | (5,245 | ) | � | 146 | � | � | (2,082 | ) |
Income tax (benefit) expense |
� | � | (510 | ) | � | 572 | � | � | (4,269 | ) | � | (1,692 | ) |
Distributions on preferred units |
� | � | 159 | � | � | 184 | � | � | 710 | � | � | 735 | � |
EBITDA(e) |
� | $ | 227,990 | � | $ | 208,836 | � | $ | 797,411 | � | $ | 801,875 | � |
Reconciliation of EBITDA to Same Centers�Net Operating Income ("NOI"):
| � |
� |
� |
� | ||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | For the Three Months Ended December�31, |
� | For the Twelve Months Ended December�31, |
� | ||||||||
| � |
� | Unaudited | � | Unaudited | � | ||||||||
| � |
� | 2014 | � | 2013 | � | 2014 | � | 2013 | � | ||||
EBITDA(e) |
� | $ | 227,990 | � | $ | 208,836 | � | $ | 797,411 | � | $ | 801,875 | � |
Add: REIT general and administrative expenses |
� | � | 12,073 | � | � | 9,099 | � | � | 29,412 | � | � | 27,772 | � |
Management Companies' revenues |
� | � | (8,733 | ) | � | (9,001 | ) | � | (33,981 | ) | � | (40,192 | ) |
Management Companies' operating expenses |
� | � | 23,239 | � | � | 24,459 | � | � | 88,424 | � | � | 93,461 | � |
Straight-line and above/below market adjustments to minimum rents of comparable centers |
� | � | (3,709 | ) | � | (4,109 | ) | � | (9,722 | ) | � | (12,961 | ) |
EBITDA of non-comparable centers |
� | � | (40,230 | ) | � | (30,184 | ) | � | (102,461 | ) | � | (132,172 | ) |
Same Centers�NOI(f) |
� | $ | 210,630 | � | $ | 199,100 | � | $ | 769,083 | � | $ | 737,783 | � |
- (e)
- EBITDA represents earnings before interest, income taxes, depreciation, amortization, noncontrolling interests, extraordinary items, gain (loss) on remeasurement, sale or write down of assets and preferred dividends and includes joint ventures at their pro rata share. Management considers EBITDA to be an appropriate supplemental measure to net income because it helps investors understand the ability of the Company to incur and service debt and make capital expenditures. The Company believes that EBITDA should not be construed as an alternative to operating income as an indicator of the Company's operating performance, or to cash flows from operating activities (as determined in accordance with GAAP) or as a measure of liquidity. The Company also cautions that EBITDA, as presented, may not be comparable to similarly titled measurements reported by other companies.
- (f)
- The Company presents same center NOI because the Company believes it is useful for investors to evaluate the operating performance of comparable centers. Same center NOI is calculated using total EBITDA and subtracting out EBITDA from non-comparable centers and eliminating the management companies and the Company's general and administrative expenses. Same center NOI excludes the impact of straight-line and above/below market adjustments to minimum rents.
MACERICH ANNOUNCES QUARTERLY RESULTS AND 2015 EARNINGS GUIDANCE
THE MACERICH COMPANY FINANCIAL HIGHLIGHTS (IN THOUSANDS, EXCEPT PER SHARE AMOUNTS)
THE MACERICH COMPANY FINANCIAL HIGHLIGHTS (IN THOUSANDS, EXCEPT PER SHARE AMOUNTS)
THE MACERICH COMPANY FINANCIAL HIGHLIGHTS (IN THOUSANDS, EXCEPT PER SHARE AMOUNTS)
THE MACERICH COMPANY FINANCIAL HIGHLIGHTS (IN THOUSANDS, EXCEPT PER SHARE AMOUNTS)
THE MACERICH COMPANY FINANCIAL HIGHLIGHTS (IN THOUSANDS, EXCEPT PER SHARE AMOUNTS)
QuickLinks -- Click here to rapidly navigate through this document
Supplemental Financial Information
For the three and twelve months ended December�31, 2014
The Macerich Company
Supplemental Financial and Operating Information
Table of Contents
��������All information included in this supplemental financial package is unaudited, unless otherwise indicated.
| � |
� | Page No. |
|---|---|---|
|
� |
� | � |
Corporate Overview |
� | 1-3 |
Overview |
� | 1 |
Capital Information and Market Capitalization |
� | 2 |
Changes in Total Common and Equivalent Shares/Units |
� | 3 |
Financial Data |
� | 4-9 |
Unaudited Pro Rata Statement of Operations |
� | 5-6 |
Notes to Unaudited Pro Rata Statement of Operations |
� | 7 |
Unaudited Pro Rata Balance Sheet |
� | 8 |
2015 Guidance Range |
� | 9 |
Supplemental FFO Information |
� | 10 |
Capital Expenditures |
� | 11 |
Operational Data |
� | 12-27 |
Sales Per Square Foot |
� | 12 |
Sales Per Square Foot by Property Ranking |
� | 13-17 |
Occupancy |
� | 18 |
Average Base Rent Per Square Foot |
� | 19 |
Cost of Occupancy |
� | 20 |
Percentage of Net Operating Income by State |
� | 21 |
Property Listing |
� | 22-25 |
Joint Venture List |
� | 26-27 |
Debt Tables |
� | 28-30 |
Debt Summary |
� | 28 |
Outstanding Debt by Maturity Date |
� | 29-30 |
Development Pipeline |
� | 31-33 |
Corporate Information |
� | 34 |
��������This Supplemental Financial Information should be read in connection with the Company's fourth quarter 2014 earnings announcement (included as Exhibit�99.1 of the Company's Current Report on 8-K, event date February�4, 2015) as certain disclosures, definitions and reconciliations in such announcement have not been included in this Supplemental Financial Information.
The Macerich Company
Supplemental Financial and Operating Information
Overview
��������The Macerich Company (the "Company") is involved in the acquisition, ownership, development, redevelopment, management and leasing of regional and community/power shopping centers located throughout the United States. The Company is the sole general partner of, and owns a majority of the ownership interests in, The Macerich Partnership,�L.P., a Delaware limited partnership (the "Operating Partnership").
��������As of December�31, 2014, the Operating Partnership owned or had an ownership interest in 51�regional shopping centers and eight community/power shopping centers aggregating approximately 54�million square feet of gross leasable area ("GLA"). These 59 centers are referred to hereinafter as the "Centers", unless the context requires otherwise.
��������The Company is working with the loan servicer for Great Northern Mall, which is expected to result in a transition of the asset to the loan servicer or a receiver. Consequently, Great Northern Mall has been excluded from all Non-GAAP Operating Data in 2014, including Sales per square foot, Occupancy, Average Base Rent per square foot and Cost of Occupancy as well as the Property Listing.
��������The Company is a self-administered and self-managed real estate investment trust ("REIT") and conducts all of its operations through the Operating Partnership and the Company's management companies (collectively, the "Management Companies").
��������All references to the Company in this Exhibit include the Company, those entities owned or controlled by the Company and predecessors of the Company, unless the context indicates otherwise.
��������This document contains information constituting forward-looking statements and includes expectations regarding the Company's future operational results as well as development, redevelopment and expansion activities. Stockholders are cautioned that any such forward-looking statements are not guarantees of future performance and involve risks, uncertainties and other factors that may cause actual results, performance or achievements of the Company to vary materially from those anticipated, expected or projected. Such factors include, among others, general industry, economic and business conditions, which will, among other things, affect demand for retail space or retail goods, availability and creditworthiness of current and prospective tenants, anchor or tenant bankruptcies, closures, mergers or consolidations, lease rates, terms and payments, interest rate fluctuations, availability, terms and cost of financing, operating expenses, and competition; adverse changes in the real estate markets, including the liquidity of real estate investments; and risks of real estate development, redevelopment, and expansion, including availability, terms and cost of financing, construction delays, environmental and safety requirements, budget overruns, sunk costs and lease-up; the inability to obtain, or delays in obtaining, all necessary zoning, land-use, building, and occupancy and other required governmental permits and authorizations; and governmental actions and initiatives (including legislative and regulatory changes) as well as terrorist activities or other acts of violence which could adversely affect all of the above factors. Furthermore, occupancy rates and rents at a newly completed property may not be sufficient to make the property profitable. The reader is directed to the Company's various filings with the Securities and Exchange Commission, including the Annual Report on Form�10-K for the year ended December�31, 2013, for a discussion of such risks and uncertainties, which discussion is incorporated herein by reference. The Company does not intend, and undertakes no obligation, to update any forward-looking information to reflect events or circumstances after the date of this document or to reflect the occurrence of unanticipated events unless required by law to do so.
1
The Macerich Company
Supplemental Financial and Operating Information (unaudited)
Capital Information and Market Capitalization
| � | � | � | � | � | � | � | � | � | � | � |
| � |
� | Period Ended | � | |||||||
|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | 12/31/2014 | � | 12/31/2013 | � | 12/31/2012 | � | |||
| � |
� | dollars in thousands, except per share data |
� | |||||||
Closing common stock price per share |
� | $ | 83.41 | � | $ | 58.89 | � | $ | 58.30 | � |
52�week high |
� | $ | 85.55 | � | $ | 72.19 | � | $ | 62.83 | � |
52�week low |
� | $ | 55.21 | � | $ | 55.13 | � | $ | 49.67 | � |
Shares outstanding at end of period |
� | � | � | � | � | � | � | � | � | � |
Class�A non-participating convertible preferred units |
� | � | 145,839 | � | � | 184,304 | � | � | 184,304 | � |
Common shares and partnership units |
� | � | 168,721,053 | � | � | 150,673,110 | � | � | 147,601,848 | � |
Total common and equivalent shares/units outstanding |
� | � | 168,866,892 | � | � | 150,857,414 | � | � | 147,786,152 | � |
Portfolio capitalization data |
� | � | � |
� | � | � |
� | � | � |
� |
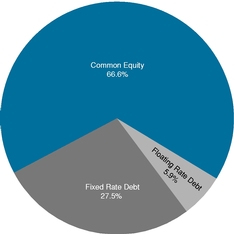
Total portfolio debt, including joint ventures at pro rata |
� | $ | 7,050,437 | � | $ | 6,037,219 | � | $ | 6,620,507 | � |
Equity market capitalization |
� | � | 14,085,187 | � | � | 8,883,993 | � | � | 8,615,933 | � |
Total market capitalization |
� | $ | 21,135,624 | � | $ | 14,921,212 | � | $ | 15,236,440 | � |
Leverage ratio(a) |
� | � | 33.4 | % | � | 40.5 | % | � | 43.5 | % |
- (a)
- Debt as a percentage of total market capitalization.
Portfolio Capitalization at December�31, 2014
2
The Macerich Company
Supplemental Financial and Operating Information (unaudited)
Changes in Total Common and Equivalent Shares/Units
|
� |
� | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | Partnership Units |
� | Company Common Shares |
� | Class�A Non-Participating Convertible Preferred Units |
� | Total Common and Equivalent Shares/ Units |
� | ||||
Balance as of December 31, 2013 |
� | � | 9,939,427 | � | � | 140,733,683 | � | � | 184,304 | � | � | 150,857,414 | � |
Conversion of partnership units to cash |
� | � | (3,445 | ) | � | � | � | � | � | � | � | (3,445 | ) |
Conversion of partnership units to common shares |
� | � | (63,000 | ) | � | 63,000 | � | � | � | � | � | � | � |
Issuance of stock/partnership units from restricted stock issuance or other share- or unit-based plans |
� | � | 246,471 | � | � | 82,701 | � | � | � | � | � | 329,172 | � |
Balance as of March�31, 2014 |
� | � | 10,119,453 | � | � | 140,879,384 | � | � | 184,304 | � | � | 151,183,141 | � |
Conversion of partnership units to cash |
� | � | (285 | ) | � | � | � | � | � | � | � | (285 | ) |
Conversion of partnership units to common shares |
� | � | (8,333 | ) | � | 8,333 | � | � | � | � | � | � | � |
Issuance of stock/partnership units from restricted stock issuance or other share- or unit-based plans |
� | � | � | � | � | 19,703 | � | � | � | � | � | 19,703 | � |
Balance as of June�30, 2014 |
� | � | 10,110,835 | � | � | 140,907,420 | � | � | 184,304 | � | � | 151,202,559 | � |
Conversion of partnership units to cash |
� | � | (234 | ) | � | � | � | � | � | � | � | (234 | ) |
Issuance of stock/partnership units from restricted stock issuance or other share- or unit-based plans |
� | � | � | � | � | 13,064 | � | � | � | � | � | 13,064 | � |
Balance as of September�30, 2014 |
� | � | 10,110,601 | � | � | 140,920,484 | � | � | 184,304 | � | � | 151,215,389 | � |
Conversion of partnership units to common shares |
� | � | (24,286 | ) | � | 62,751 | � | � | (38,465 | ) | � | � | � |
Issuance of common shares�Acquisition of partnership interest |
� | � | � | � | � | 17,140,845 | � | � | � | � | � | 17,140,845 | � |
Issuance of stock/partnership units from restricted stock issuance or other share- or unit-based plans |
� | � | 432,742 | � | � | 77,916 | � | � | � | � | � | 510,658 | � |
Balance as of December 31, 2014 |
� | � | 10,519,057 | � | � | 158,201,996 | � | � | 145,839 | � | � | 168,866,892 | � |
3
��������On the following pages, the Company presents its unaudited pro�rata statement of operations and unaudited pro�rata balance sheet reflecting the Company's proportionate ownership of each asset in its portfolio. The Company also reconciles net income attributable to the Company to funds from operations ("FFO") and FFO-diluted for the three and twelve months ended December�31, 2014.
4
THE MACERICH COMPANY
UNAUDITED PRO RATA STATEMENT OF OPERATIONS
(Dollars in thousands)
| � |
� |
� |
� | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | For the Three Months Ended December�31, 2014 | � | |||||||||||||
| � |
� | Consolidated | � | Non- Controlling Interests(1) |
� | Company's Consolidated Share |
� | Company's Share of Joint Ventures(2) |
� | Company's Total Share |
� | |||||
Revenues: |
� | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Minimum rents |
� | $ | 182,323 | � | $ | (9,124 | ) | $ | 173,199 | � | $ | 44,325 | � | $ | 217,524 | � |
Percentage rents |
� | � | 15,055 | � | � | (741 | ) | � | 14,314 | � | � | 3,296 | � | � | 17,610 | � |
Tenant recoveries |
� | � | 96,210 | � | � | (5,031 | ) | � | 91,179 | � | � | 20,423 | � | � | 111,602 | � |
Management Companies' revenues |
� | � | 8,733 | � | � | � | � | � | 8,733 | � | � | � | � | � | 8,733 | � |
Other income |
� | � | 20,588 | � | � | (997 | ) | � | 19,591 | � | � | 4,437 | � | � | 24,028 | � |
Total revenues |
� | � | 322,909 | � | � | (15,893 | ) | � | 307,016 | � | � | 72,481 | � | � | 379,497 | � |
Expenses: |
� | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Shopping center and operating expenses |
� | � | 95,922 | � | � | (5,149 | ) | � | 90,773 | � | � | 25,581 | � | � | 116,354 | � |
Management Companies' operating expenses |
� | � | 23,239 | � | � | � | � | � | 23,239 | � | � | � | � | � | 23,239 | � |
REIT general and administrative expenses |
� | � | 12,073 | � | � | � | � | � | 12,073 | � | � | � | � | � | 12,073 | � |
Depreciation and amortization |
� | � | 112,517 | � | � | (4,419 | ) | � | 108,098 | � | � | 21,244 | � | � | 129,342 | � |
Interest expense |
� | � | 50,748 | � | � | (2,452 | ) | � | 48,296 | � | � | 12,165 | � | � | 60,461 | � |
Loss on early extinguishment of debt, net |
� | � | 9,146 | � | � | � | � | � | 9,146 | � | � | � | � | � | 9,146 | � |
Total expenses |
� | � | 303,645 | � | � | (12,020 | ) | � | 291,625 | � | � | 58,990 | � | � | 350,615 | � |
Equity in income of unconsolidated joint ventures |
� | � | 16,019 | � | � | � | � | � | 16,019 | � | � | (16,019 | ) | � | � | � |
Co-venture expense |
� | � | (3,315 | ) | � | 3,315 | � | � | � | � | � | � | � | � | � | � |
Income tax benefit |
� | � | 510 | � | � | � | � | � | 510 | � | � | � | � | � | 510 | � |
Gain on sale or write down of assets, net |
� | � | 74,944 | � | � | (185 | ) | � | 74,759 | � | � | 2,528 | � | � | 77,287 | � |
Gain on remeasurement of assets |
� | � | 1,423,136 | � | � | � | � | � | 1,423,136 | � | � | � | � | � | 1,423,136 | � |
Net income |
� | � | 1,530,558 | � | � | (743 | ) | � | 1,529,815 | � | � | � | � | � | 1,529,815 | � |
Less net income attributable to noncontrolling interests |
� | � | 101,337 | � | � | (743 | ) | � | 100,594 | � | � | � | � | � | 100,594 | � |
Net income attributable to the Company |
� | $ | 1,429,221 | � | $ | � | � | $ | 1,429,221 | � | $ | � | � | $ | 1,429,221 | � |
Reconciliation of net income attributable to the Company to FFO(3): |
� | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Net income attributable to the Company |
� | � | � | � | � | � | � | $ | 1,429,221 | � | $ | � | � | $ | 1,429,221 | � |
Equity in income of unconsolidated joint ventures |
� | � | � | � | � | � | � | � | (16,019 | ) | � | 16,019 | � | � | � | � |
Adjustments to reconcile net income to FFO�basic and diluted: |
� | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Noncontrolling interests in the Operating Partnership |
� | � | � | � | � | � | � | � | 100,594 | � | � | � | � | � | 100,594 | � |
Gain on sale or write down of assets, net |
� | � | � | � | � | � | � | � | (74,759 | ) | � | (2,528 | ) | � | (77,287 | ) |
Gain on remeasurement of assets |
� | � | � | � | � | � | � | � | (1,423,136 | ) | � | � | � | � | (1,423,136 | ) |
Gain on sale of undepreciated assets, net |
� | � | � | � | � | � | � | � | 477 | � | � | 2,621 | � | � | 3,098 | � |
Depreciation and amortization of all property |
� | � | � | � | � | � | � | � | 108,098 | � | � | 21,244 | � | � | 129,342 | � |
Depreciation on personal property |
� | � | � | � | � | � | � | � | (2,746 | ) | � | (238 | ) | � | (2,984 | ) |
Total FFO�Basic and diluted |
� | � | � | � | � | � | � | � | 121,730 | � | � | 37,118 | � | � | 158,848 | � |
Loss on early extinguishment of debt, net |
� | � | � | � | � | � | � | � | 9,146 | � | � | � | � | � | 9,146 | � |
Total FFO excluding early extinguishment of debt�diluted |
� | � | � | � | � | � | � | $ | 130,876 | � | $ | 37,118 | � | $ | 167,994 | � |
- (1)
- This
represents the non-owned portion of the consolidated entities not wholly-owned by the Company.
- (2)
- This represents the Company's pro rata share of unconsolidated joint ventures.
5
THE MACERICH COMPANY
UNAUDITED PRO RATA STATEMENT OF OPERATIONS
(Dollars in thousands)
| � |
� |
� |
� | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | For the Year Ended December�31, 2014 | � | |||||||||||||
| � |
� | Consolidated | � | Non- Controlling Interests(1) |
� | Company's Consolidated Share |
� | Company's Share of Joint Ventures(2) |
� | Company's Total Share |
� | |||||
Revenues: |
� | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Minimum rents |
� | $ | 633,571 | � | $ | (38,764 | ) | $ | 594,807 | � | $ | 191,255 | � | $ | 786,062 | � |
Percentage rents |
� | � | 24,350 | � | � | (1,562 | ) | � | 22,788 | � | � | 8,399 | � | � | 31,187 | � |
Tenant recoveries |
� | � | 361,119 | � | � | (23,193 | ) | � | 337,926 | � | � | 92,567 | � | � | 430,493 | � |
Management Companies' revenues������������ |
� | � | 33,981 | � | � | � | � | � | 33,981 | � | � | � | � | � | 33,981 | � |
Other income |
� | � | 52,226 | � | � | (2,842 | ) | � | 49,384 | � | � | 20,203 | � | � | 69,587 | � |
Total revenues |
� | � | 1,105,247 | � | � | (66,361 | ) | � | 1,038,886 | � | � | 312,424 | � | � | 1,351,310 | � |
Expenses: |
� | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Shopping center and operating expenses |
� | � | 353,505 | � | � | (22,752 | ) | � | 330,753 | � | � | 106,020 | � | � | 436,773 | � |
Management Companies' operating expenses |
� | � | 88,424 | � | � | � | � | � | 88,424 | � | � | � | � | � | 88,424 | � |
REIT general and administrative expenses |
� | � | 29,412 | � | � | � | � | � | 29,412 | � | � | � | � | � | 29,412 | � |
Depreciation and amortization |
� | � | 378,716 | � | � | (20,700 | ) | � | 358,016 | � | � | 82,570 | � | � | 440,586 | � |
Interest expense |
� | � | 190,689 | � | � | (11,260 | ) | � | 179,429 | � | � | 61,971 | � | � | 241,400 | � |
Loss on early extinguishment of debt, net |
� | � | 9,551 | � | � | � | � | � | 9,551 | � | � | � | � | � | 9,551 | � |
Total expenses |
� | � | 1,050,297 | � | � | (54,712 | ) | � | 995,585 | � | � | 250,561 | � | � | 1,246,146 | � |
Equity in income of unconsolidated joint ventures |
� | � | 60,626 | � | � | � | � | � | 60,626 | � | � | (60,626 | ) | � | � | � |
Co-venture expense |
� | � | (9,490 | ) | � | 9,490 | � | � | � | � | � | � | � | � | � | � |
Income tax benefit |
� | � | 4,269 | � | � | � | � | � | 4,269 | � | � | � | � | � | 4,269 | � |
Gain (loss) on sale or write down of assets, net |
� | � | 73,440 | � | � | (146 | ) | � | 73,294 | � | � | (1,237 | ) | � | 72,057 | � |
Gain on remeasurement of assets |
� | � | 1,423,136 | � | � | � | � | � | 1,423,136 | � | � | � | � | � | 1,423,136 | � |
Net income |
� | � | 1,606,931 | � | � | (2,305 | ) | � | 1,604,626 | � | � | � | � | � | 1,604,626 | � |
Less net income attributable to noncontrolling interests |
� | � | 107,889 | � | � | (2,305 | ) | � | 105,584 | � | � | � | � | � | 105,584 | � |
Net income attributable to the Company |
� | $ | 1,499,042 | � | $ | � | � | $ | 1,499,042 | � | $ | � | � | $ | 1,499,042 | � |
Reconciliation of net income attributable to the Company to FFO(3): |
� | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Net income attributable to the Company |
� | � | � | � | � | � | � | $ | 1,499,042 | � | $ | � | � | $ | 1,499,042 | � |
Equity in income of unconsolidated joint ventures |
� | � | � | � | � | � | � | � | (60,626 | ) | � | 60,626 | � | � | � | � |
Adjustments to reconcile net income to FFO�basic and diluted: |
� | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Noncontrolling interests in the Operating Partnership |
� | � | � | � | � | � | � | � | 105,584 | � | � | � | � | � | 105,584 | � |
(Gain) loss on sale or write down of assets, net |
� | � | � | � | � | � | � | � | (73,294 | ) | � | 1,237 | � | � | (72,057 | ) |
Gain on remeasurement of assets |
� | � | � | � | � | � | � | � | (1,423,136 | ) | � | � | � | � | (1,423,136 | ) |
Gain on sale of undepreciated assets, net |
� | � | � | � | � | � | � | � | 1,396 | � | � | 2,621 | � | � | 4,017 | � |
Depreciation and amortization of all property |
� | � | � | � | � | � | � | � | 358,016 | � | � | 82,570 | � | � | 440,586 | � |
Depreciation on personal property |
� | � | � | � | � | � | � | � | (10,321 | ) | � | (961 | ) | � | (11,282 | ) |
Total FFO�Basic and diluted |
� | � | � | � | � | � | � | � | 396,661 | � | � | 146,093 | � | � | 542,754 | � |
Loss on early extinguishment of debt, net |
� | � | � | � | � | � | � | � | 9,551 | � | � | � | � | � | 9,551 | � |
Total FFO excluding early extinguishment of debt�diluted |
� | � | � | � | � | � | � | $ | 406,212 | � | $ | 146,093 | � | $ | 552,305 | � |
- (1)
- This
represents the non-owned portion of the consolidated entities not wholly-owned by the Company.
- (2)
- This represents the Company's pro rata share of unconsolidated joint ventures.
6
The Macerich Company
Notes to Unaudited Pro Rata Statement of Operations
- (1)
- This
represents the non-owned portion of consolidated joint ventures.
- (2)
- This
represents the Company's pro rata share of unconsolidated joint ventures.
- (3)
- The Company uses FFO in addition to net income to report its operating and financial results and considers FFO and FFO-diluted as supplemental measures for the real estate industry and a supplement to Generally Accepted Accounting Principles ("GAAP") measures. The National Association of Real Estate Investment Trusts ("NAREIT") defines FFO as net income (loss) (computed in accordance with GAAP), excluding gains (or losses) from extraordinary items and sales of depreciated operating properties, plus real estate related depreciation and amortization, impairment write-downs of real estate and write-downs of investments in an affiliate where the write-downs have been driven by a decrease in the value of real estate held by the affiliate and after adjustments for unconsolidated joint ventures. Adjustments for unconsolidated joint ventures are calculated to reflect FFO on the same basis.
FFO and FFO on a diluted basis are useful to investors in comparing operating and financial results between periods. This is especially true since FFO excludes real estate depreciation and amortization, as the Company believes real estate values fluctuate based on market conditions rather than depreciating in value ratably on a straight-line basis over time. The Company believes that such a presentation also provides investors with a more meaningful measure of its operating results in comparison to the operating results of other REITs. The Company believes that FFO on a diluted basis is a measure investors find most useful in measuring the dilutive impact of outstanding convertible securities. The Company further believes that FFO does not represent cash flow from operations as defined by GAAP, should not be considered as an alternative to net income (loss) as defined by GAAP, and is not indicative of cash available to fund all cash flow needs. The Company also cautions that FFO, as presented, may not be comparable to similarly titled measures reported by other REITs.
Management compensates for the limitations of FFO by providing investors with financial statements prepared according to GAAP, along with a detailed discussion of FFO and a reconciliation of FFO and FFO-diluted to net income attributable to the Company. Management believes that to further understand the Company's performance, FFO should be compared with the Company's reported net income and considered in addition to cash flows in accordance with GAAP, as presented in the Company's consolidated financial statements.
7
THE MACERICH COMPANY
UNAUDITED PRO RATA BALANCE SHEET
(All Dollars in thousands)
| � |
� |
� |
� | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | As of December�31, 2014 | � | |||||||||||||
| � |
� | Consolidated | � | Non- Controlling Interests(1) |
� | Company's Consolidated Share |
� | Company's Share of Joint Ventures(2) |
� | Company's Total Share |
� | |||||
ASSETS: |
� | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Property, net(3) |
� | $ | 11,067,890 | � | $ | (329,922 | ) | $ | 10,737,968 | � | $ | 1,944,366 | � | $ | 12,682,334 | � |
Cash and cash equivalents |
� | � | 84,907 | � | � | (9,139 | ) | � | 75,768 | � | � | 26,317 | � | � | 102,085 | � |
Restricted cash |
� | � | 13,530 | � | � | � | � | � | 13,530 | � | � | 2,523 | � | � | 16,053 | � |
Tenant and other receivables, net |
� | � | 132,026 | � | � | (20,186 | ) | � | 111,840 | � | � | 26,136 | � | � | 137,976 | � |
Deferred charges and other assets, net |
� | � | 759,061 | � | � | (6,959 | ) | � | 752,102 | � | � | 47,482 | � | � | 799,584 | � |
Due from affiliates |
� | � | 80,232 | � | � | 217 | � | � | 80,449 | � | � | (1,830 | ) | � | 78,619 | � |
Investments in unconsolidated joint ventures |
� | � | 984,132 | � | � | � | � | � | 984,132 | � | � | (984,132 | ) | � | � | � |
Total assets |
� | $ | 13,121,778 | � | $ | (365,989 | ) | $ | 12,755,789 | � | $ | 1,060,862 | � | $ | 13,816,651 | � |
LIABILITIES AND EQUITY: |
� | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Mortgage notes payable |
� | $ | 5,404,521 | � | $ | (234,409 | ) | $ | 5,170,112 | � | $ | 997,886 | � | $ | 6,167,998 | � |
Bank and other notes payable |
� | � | 887,879 | � | � | (5,440 | ) | � | 882,439 | � | � | � | � | � | 882,439 | � |
Accounts payable and accrued expenses |
� | � | 115,406 | � | � | (2,197 | ) | � | 113,209 | � | � | 32,946 | � | � | 146,155 | � |
Other accrued liabilities |
� | � | 568,716 | � | � | (23,489 | ) | � | 545,227 | � | � | 59,987 | � | � | 605,214 | � |
Distributions in excess of investment in unconsolidated joint ventures |
� | � | 29,957 | � | � | � | � | � | 29,957 | � | � | (29,957 | ) | � | � | � |
Co-venture obligation |
� | � | 75,450 | � | � | (75,450 | ) | � | � | � | � | � | � | � | � | � |
Total liabilities |
� | � | 7,081,929 | � | � | (340,985 | ) | � | 6,740,944 | � | � | 1,060,862 | � | � | 7,801,806 | � |
Commitments and contingencies |
� | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Equity: |
� | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Stockholders' equity: |
� | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Common stock |
� | � | 1,581 | � | � | � | � | � | 1,581 | � | � | � | � | � | 1,581 | � |
Additional paid-in capital |
� | � | 5,041,798 | � | � | � | � | � | 5,041,798 | � | � | � | � | � | 5,041,798 | � |
Retained earnings |
� | � | 596,741 | � | � | � | � | � | 596,741 | � | � | � | � | � | 596,741 | � |
Total stockholders' equity |
� | � | 5,640,120 | � | � | � | � | � | 5,640,120 | � | � | � | � | � | 5,640,120 | � |
Noncontrolling interests |
� | � | 399,729 | � | � | (25,004 | ) | � | 374,725 | � | � | � | � | � | 374,725 | � |
Total equity |
� | � | 6,039,849 | � | � | (25,004 | ) | � | 6,014,845 | � | � | � | � | � | 6,014,845 | � |
Total liabilities and equity |
� | $ | 13,121,778 | � | $ | (365,989 | ) | $ | 12,755,789 | � | $ | 1,060,862 | � | $ | 13,816,651 | � |
- (1)
- This
represents the non-owned portion of the consolidated joint ventures.
- (2)
- This
represents the Company's pro rata share of the unconsolidated joint ventures.
- (3)
- Includes construction in progress of $290,369 from the Company's consolidated share and $212,179 from its pro rata share of the unconsolidated joint ventures.
8
The Macerich Company
2015 Guidance Range (Unaudited)
| � |
� |
� |
||
|---|---|---|---|---|
| � |
� | Year 2015 Guidance |
� | � |
Earnings Expectations: |
� | � | � | � |
Earnings per share�diluted |
� | $1.28�-�$1.38 |
� | � |
Plus: real estate depreciation and amortization |
� | $2.52 | � | � |
Less: gain on sale of dispositions |
� | $0.00 | � | � |
FFO per share�diluted |
� | $3.80�-�$3.90 | � | � |
Underlying Assumptions to 2015 Guidance |
� | � |
� | � |
Cash Same Center NOI Growth(a) |
� | 4.25% to 4.75% |
� | � |
Assumed acquisitions |
� | $0 | � | � |
Assumed dispositions |
� | $0 | � | � |
�
| � |
� |
� |
||
|---|---|---|---|---|
| � |
� | � |
� | Year 2015 FFO / Share Impact |
Lease termination income |
� | $10�million | � | $0.06 |
Capitalized interest |
� | $14�million | � | $0.084 |
Bad debt expense |
� | ($4�million) | � | $(0.024) |
Dilutive impact on 2015 of assets sold in 2014 |
� | ($17�million) | � | $(0.10) |
- (a)
- Excludes non cash items of straight-line and above/below market adjustments to minimum rents. Includes lease termination income.
9

The Macerich Company
Supplemental Financial and Operating Information (unaudited)
Supplemental FFO Information(a)
|
� |
||||
|---|---|---|---|---|
| � |
� | As of December�31, | ||
| � |
� | 2014 | � | 2013 |
| � |
� | dollars in millions |
||
Straight-line rent receivable |
� | $75.2 | � | $69.9 |
�
|
� |
� | ||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | For the Three Months Ended December�31, |
� | For the Twelve Months Ended December�31, |
� | ||||||||
| � |
� | 2014 | � | 2013 | � | 2014 | � | 2013 | � | ||||
| � |
� | dollars in millions |
� | ||||||||||
Lease termination fees |
� | $ | 6.8 | � | $ | 0.6 | � | $ | 11.8 | � | $ | 5.0 | � |
Straight-line rental income |
� | $ | 3.8 | � | $ | 2.2 | � | $ | 9.3 | � | $ | 8.1 | � |
Gain on sales of undepreciated assets |
� | $ | 3.1 | � | $ | 0.5 | � | $ | 4.0 | � | $ | 3.2 | � |
Amortization of acquired above- and below-market leases |
� | $ | 3.5 | � | $ | 2.3 | � | $ | 10.2 | � | $ | 8.7 | � |
Amortization of debt premiums |
� | $ | 4.7 | � | $ | 1.2 | � | $ | 8.5 | � | $ | 6.9 | � |
Interest capitalized |
� | $ | 5.5 | � | $ | 4.7 | � | $ | 23.2 | � | $ | 19.3 | � |
- (a)
- All joint venture amounts included at pro rata.
10
The Macerich Company
Supplemental Financial and Operating Information (unaudited)
Capital Expenditures
|
� |
� | � |
� | |||||||
|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | Year Ended 12/31/14 |
� | Year Ended 12/31/13 |
� | Year Ended 12/31/12 |
� | |||
| � |
� | dollars in millions |
� | |||||||
Consolidated Centers |
� | � | � | � | � | � | � | � | � | � |
Acquisitions of property and equipment(a) |
� | $ | 97.9 | � | $ | 591.6 | � | $ | 1,313.1 | � |
Development, redevelopment, expansions and renovations of Centers |
� | � | 197.9 | � | � | 164.4 | � | � | 158.5 | � |
Tenant allowances |
� | � | 30.5 | � | � | 20.9 | � | � | 18.1 | � |
Deferred leasing charges |
� | � | 26.6 | � | � | 23.9 | � | � | 23.5 | � |
Total |
� | $ | 352.9 | � | $ | 800.8 | � | $ | 1,513.2 | � |
Unconsolidated Joint Venture Centers(b) |
� | � | � |
� | � | � |
� | � | � |
� |
Acquisitions of property and equipment |
� | $ | 158.8 | � | $ | 8.2 | � | $ | 5.1 | � |
Development, redevelopment, expansions and renovations of Centers |
� | � | 201.8 | � | � | 118.8 | � | � | 79.6 | � |
Tenant allowances |
� | � | 4.8 | � | � | 8.1 | � | � | 6.4 | � |
Deferred leasing charges |
� | � | 3.0 | � | � | 3.3 | � | � | 4.2 | � |
Total |
� | $ | 368.4 | � | $ | 138.4 | � | $ | 95.3 | � |
- (a)
- Excludes
non cash acquisition of partner's interests in five Centers on November�14, 2014.
- (b)
- All joint venture amounts at pro rata.
11
The Macerich Company
Supplemental Financial and Operating Information (unaudited)
Regional Shopping Center Portfolio
Sales Per Square Foot(a)
|
� |
||||||
|---|---|---|---|---|---|---|
| � |
� | Consolidated Centers |
� | Unconsolidated Joint Venture Centers |
� | Total Centers |
12/31/2014(b) |
� | $556 | � | $724 | � | $587 |
12/31/2013(c) |
� | $488 | � | $717 | � | $562 |
12/31/2012 |
� | $463 | � | $629 | � | $517 |
12/31/2011 |
� | $417 | � | $597 | � | $489 |
12/31/2010 |
� | $392 | � | $468 | � | $433 |
- (a)
- Sales
are based on reports by retailers leasing mall and freestanding stores for the trailing 12�months for tenants which have occupied such stores
for a minimum of 12�months. Sales per square foot are based on tenants 10,000 square feet and under for regional shopping centers. Sales per square foot exclude Centers under development and
redevelopment.
- (b)
- Great
Northern Mall is excluded at December 31, 2014 because the Center is being transitioned to the loan servicer.
- (c)
- Rotterdam Square, sold January�15, 2014, is excluded at December�31, 2013.
12
The Macerich Company
Sales Per Square Foot by Property Ranking (Unaudited)
| � |
� | � |
� | � |
� | Sales Per Square Foot | � | Occupancy | � | � |
� | � |
� | � |
� | � |
� | Cost of Occupancy for the Trailing 12�Months Ended 12/31/14 (d) |
� | � |
� | |||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | � |
� | � |
� | Same Center NOI Growth(c) | � | % of Portfolio 2015 Forecast Pro Rata NOI (e) |
� | |||||||||||||||||||||||||||
| � |
� | � |
� | � |
� | 12/31/2014 (a) |
� | 12/31/2013 (a) |
� | 12/31/2014 (b) |
� | 12/31/2013 (b) |
� | |||||||||||||||||||||||
Count
|
� | Properties | � | 2014 | � | 2013 | � | 2012 | � | 2011 | � | |||||||||||||||||||||||||
| � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
| � | � | � | Group 1: Top 10 | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | ||
� |
1 |
� |
� |
� |
Queens Center |
� |
$ |
1,088 |
� |
$ |
1,038 |
� |
� |
99.1 |
% |
� |
98.8 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 2 | � | � | � | Washington Square | � | $ | 1,012 | � | $ | 1,090 | � | � | 94.8 | % | � | 92.2 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
3 |
� |
� |
� |
Corte Madera, Village at |
� |
$ |
957 |
� |
$ |
902 |
� |
� |
96.3 |
% |
� |
97.8 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 4 | � | � | � | North Bridge, The Shops at | � | $ | 870 | � | $ | 906 | � | � | 98.9 | % | � | 97.3 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
5 |
� |
� |
� |
Biltmore Fashion Park |
� |
$ |
865 |
� |
$ |
927 |
� |
� |
97.9 |
% |
� |
90.0 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 6 | � | � | � | Tysons Corner Center | � | $ | 821 | � | $ | 824 | � | � | 98.4 | % | � | 98.2 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
7 |
� |
� |
� |
Santa Monica Place |
� |
$ |
754 |
� |
$ |
734 |
� |
� |
92.7 |
% |
� |
90.5 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 8 | � | � | � | Tucson La Encantada | � | $ | 733 | � | $ | 694 | � | � | 94.5 | % | � | 92.2 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
9 |
� |
� |
� |
Scottsdale Fashion Square |
� |
$ |
732 |
� |
$ |
694 |
� |
� |
95.9 |
% |
� |
94.5 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 10 | � | � | � | Broadway Plaza(f) | � | � | n/a | � | $ | 726 | � | � | n/a | � | � | 87.1 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
| � | � | � | Total Top 10: | � | $ | 864 | � | $ | 855 | � | � | 96.9 | % | � | 95.0 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | 14.0 | % | � | 26.7 | % | ||
| � | � | � | Group 2: Top 11-20 | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | ||
� |
11 |
� |
� |
� |
Los Cerritos Center |
� |
$ |
720 |
� |
$ |
674 |
� |
� |
98.5 |
% |
� |
97.3 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 12 | � | � | � | Kings Plaza Shopping Center | � | $ | 673 | � | $ | 675 | � | � | 91.9 | % | � | 95.9 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
13 |
� |
� |
� |
Arrowhead Towne Center |
� |
$ |
673 |
� |
$ |
649 |
� |
� |
94.9 |
% |
� |
96.8 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 14 | � | � | � | Kierland Commons | � | $ | 671 | � | $ | 637 | � | � | 97.4 | % | � | 97.2 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
15 |
� |
� |
� |
Fashion Outlets of Chicago(g) |
� |
$ |
651 |
� |
� |
n/a |
� |
� |
94.4 |
% |
� |
95.4 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 16 | � | � | � | Danbury Fair Mall | � | $ | 643 | � | $ | 636 | � | � | 97.6 | % | � | 96.6 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
17 |
� |
� |
� |
Vintage Faire Mall |
� |
$ |
633 |
� |
$ |
594 |
� |
� |
96.6 |
% |
� |
99.3 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 18 | � | � | � | Chandler Fashion Center | � | $ | 606 | � | $ | 567 | � | � | 93.6 | % | � | 97.5 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
19 |
� |
� |
� |
Twenty Ninth Street |
� |
$ |
605 |
� |
$ |
613 |
� |
� |
97.8 |
% |
� |
95.7 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 20 | � | � | � | Fresno Fashion Fair | � | $ | 601 | � | $ | 609 | � | � | 98.4 | % | � | 96.8 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
� |
� |
Total Top 11-20: |
� |
$ |
647 |
� |
$ |
625 |
� |
� |
96.0 |
% |
� |
96.8 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
12.7 |
% |
� |
26.8 |
% |
||
13
The Macerich Company
Sales Per Square Foot by Property Ranking (Unaudited)
| � |
� | � |
� | � |
� | Sales Per Square Foot | � | Occupancy | � | � |
� | � |
� | � |
� | � |
� | Cost of Occupancy for the Trailing 12�Months Ended 12/31/14 (d) |
� | � |
� | |||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | � |
� | � |
� | Same Center NOI Growth(c) | � | % of Portfolio 2015 Forecast Pro Rata NOI (e) |
� | |||||||||||||||||||||||||||
| � |
� | � |
� | � |
� | 12/31/2014 (a) |
� | 12/31/2013 (a) |
� | 12/31/2014 (b) |
� | 12/31/2013 (b) |
� | |||||||||||||||||||||||
Count
|
� | Properties | � | 2014 | � | 2013 | � | 2012 | � | 2011 | � | |||||||||||||||||||||||||
| � | � | � | Group 3: Top 21-30 | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | ||
� |
21 |
� |
� |
� |
Freehold Raceway Mall |
� |
$ |
590 |
� |
$ |
619 |
� |
� |
98.6 |
% |
� |
98.5 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 22 | � | � | � | Green Acres Mall | � | $ | 577 | � | $ | 541 | � | � | 93.0 | % | � | 93.4 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
23 |
� |
� |
� |
Stonewood Center |
� |
$ |
544 |
� |
$ |
522 |
� |
� |
99.5 |
% |
� |
96.1 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 24 | � | � | � | Fashion Outlets of Niagara Falls USA(f) | � | � | n/a | � | $ | 532 | � | � | n/a | � | � | 94.6 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
25 |
� |
� |
� |
FlatIron Crossing |
� |
$ |
532 |
� |
$ |
525 |
� |
� |
93.9 |
% |
� |
93.7 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 26 | � | � | � | Deptford Mall | � | $ | 526 | � | $ | 505 | � | � | 98.5 | % | � | 96.7 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
27 |
� |
� |
� |
Oaks, The |
� |
$ |
512 |
� |
$ |
502 |
� |
� |
97.9 |
% |
� |
97.2 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 28 | � | � | � | West Acres | � | $ | 512 | � | $ | 527 | � | � | 99.8 | % | � | 99.8 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
29 |
� |
� |
� |
SanTan Village Regional Center |
� |
$ |
497 |
� |
$ |
495 |
� |
� |
99.1 |
% |
� |
96.7 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 30 | � | � | � | Victor Valley, Mall of | � | $ | 492 | � | $ | 509 | � | � | 98.6 | % | � | 97.0 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
� |
� |
Total Top 21-30: |
� |
$ |
535 |
� |
$ |
532 |
� |
� |
97.2 |
% |
� |
96.2 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
13.4 |
% |
� |
21.4 |
% |
||
| � | � | � | Group 4: Top 31-40 | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | ||
� |
31 |
� |
� |
� |
Valley River Center |
� |
$ |
461 |
� |
$ |
478 |
� |
� |
98.3 |
% |
� |
98.2 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 32 | � | � | � | South Plains Mall | � | $ | 455 | � | $ | 468 | � | � | 95.2 | % | � | 88.3 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
33 |
� |
� |
� |
Lakewood Center |
� |
$ |
431 |
� |
$ |
430 |
� |
� |
97.3 |
% |
� |
97.5 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 34 | � | � | � | La Cumbre Plaza | � | $ | 417 | � | $ | 396 | � | � | 85.6 | % | � | 86.4 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
35 |
� |
� |
� |
Inland Center |
� |
$ |
409 |
� |
$ |
417 |
� |
� |
98.6 |
% |
� |
97.9 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 36 | � | � | � | Pacific View | � | $ | 405 | � | $ | 405 | � | � | 95.0 | % | � | 98.7 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
37 |
� |
� |
� |
Northgate Mall |
� |
$ |
392 |
� |
$ |
396 |
� |
� |
96.0 |
% |
� |
97.9 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 38 | � | � | � | Eastland Mall | � | $ | 371 | � | $ | 395 | � | � | 94.8 | % | � | 98.8 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
| � | 39 | � | � | � | Westside Pavilion(f) | � | � | n/a | � | $ | 348 | � | � | n/a | � | � | 94.7 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
| � | 40 | � | � | � | Superstition Springs Center | � | $ | 350 | � | $ | 345 | � | � | 92.8 | % | � | 96.9 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
� |
� |
Total Top 31-40: |
� |
$ |
412 |
� |
$ |
412 |
� |
� |
95.5 |
% |
� |
96.0 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
14.9 |
% |
� |
15.3 |
% |
||
| � | � | � | Total Top 40: | � | $ | 618 | � | $ | 609 | � | � | 96.4 | % | � | 96.1 | % | � | 4.7 | % | � | 4.6 | % | � | 3.7 | % | � | 4.2 | % | � | 13.6 | % | � | 90.2 | % | ||
14
The Macerich Company
Sales Per Square Foot by Property Ranking (Unaudited)
| � |
� | � |
� | � |
� | Sales Per Square Foot | � | Occupancy | � | � |
� | � |
� | � |
� | � |
� | Cost of Occupancy for the Trailing 12�Months Ended 12/31/14 (d) |
� | � |
� | |||||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | � |
� | � |
� | Same Center NOI Growth(c) | � | % of Portfolio 2015 Forecast Pro Rata NOI (e) |
� | |||||||||||||||||||||||||||
| � |
� | � |
� | � |
� | 12/31/2014 (a) |
� | 12/31/2013 (a) |
� | 12/31/2014 (b) |
� | 12/31/2013 (b) |
� | |||||||||||||||||||||||
Count
|
� | Properties | � | 2014 | � | 2013 | � | 2012 | � | 2011 | � | |||||||||||||||||||||||||
| � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
| � | � | � | Group 5: 41-50 | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | ||
| � | 41 | � | � | � | Flagstaff Mall | � | $ | 340 | � | $ | 310 | � | � | 71.8 | % | � | 78.8 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
42 |
� |
� |
� |
Capitola Mall |
� |
$ |
334 |
� |
$ |
326 |
� |
� |
89.9 |
% |
� |
85.3 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 43 | � | � | � | Towne Mall | � | $ | 323 | � | $ | 331 | � | � | 89.8 | % | � | 86.4 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
44 |
� |
� |
� |
Cascade Mall |
� |
$ |
317 |
� |
$ |
298 |
� |
� |
91.4 |
% |
� |
91.5 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 45 | � | � | � | NorthPark Mall | � | $ | 307 | � | $ | 313 | � | � | 90.6 | % | � | 91.6 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
46 |
� |
� |
� |
Desert Sky Mall |
� |
$ |
302 |
� |
$ |
270 |
� |
� |
92.8 |
% |
� |
89.2 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 47 | � | � | � | Wilton Mall | � | $ | 276 | � | $ | 296 | � | � | 94.0 | % | � | 90.7 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
48 |
� |
� |
� |
Valley Mall |
� |
$ |
271 |
� |
$ |
286 |
� |
� |
92.6 |
% |
� |
95.4 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 49 | � | � | � | SouthPark Mall(f) | � | � | n/a | � | $ | 228 | � | � | n/a | � | � | 79.4 | % | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
� |
50 |
� |
� |
� |
Paradise Valley Mall(f) |
� |
� |
n/a |
� |
� |
n/a |
� |
� |
n/a |
� |
� |
n/a |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | � | � | Total 41-50: | � | $ | 307 | � | $ | 292 | � | � | 90.6 | % | � | 88.0 | % | � | (3.0 | )% | � | 2.5 | % | � | 1.0 | % | � | 0.5 | % | � | 12.3 | % | � | 6.1 | % | ||
� |
� |
� |
Subtotal�Regional Shopping Centers(h) |
� |
$ |
587 |
� |
$ |
574 |
� |
� |
95.8 |
% |
� |
95.1 |
% |
� |
4.2 |
% |
� |
4.4 |
% |
� |
3.3 |
% |
� |
3.8 |
% |
� |
13.5 |
% |
� |
96.3 |
% |
||
| � | � | � | Other Properties: | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | ||
� |
51 |
� |
� |
� |
Gallery, The(f)(i) |
� |
� |
n/a |
� |
� |
n/a |
� |
� |
n/a |
� |
� |
n/a |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | � | � | Community / Power Centers | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | ||
� |
� |
� |
Other Non-mall Assets |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
||
| � | � | � | Subtotal�Other Properties | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | 3.7 | % | ||
� |
� |
� |
TOTAL ALL PROPERTIES |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
13.4 |
% |
� |
100.0 |
% |
||
15
The Macerich Company
Sales Per Square Foot by Property Ranking (unaudited)
| � |
� | � |
� | � |
� | � |
� | � |
� | Same Center NOI Growth(c) |
� | � |
� | ||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | � |
� | � |
� | Sales Per Square Foot 12/31/2012 (a) |
� | � |
� | % of Portfolio 2012 Pro Rata NOI (j) |
� | ||||||||||
| � |
� | � |
� | � |
� | Occupancy 12/31/2012 (b) |
� | ||||||||||||||
Count
|
� | Properties | � | 2012 | � | 2011 | � | ||||||||||||||
| � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
| � | � | � | 2013 Disposition Centers | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | ||
� |
1 |
� |
� |
� |
Chesterfield Towne Center |
� |
$ |
361 |
� |
� |
91.9 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 2 | � | � | � | Fiesta Mall | � | $ | 235 | � | � | 86.1 | % | � | � | � | � | � | � | � | � | � |
� |
3 |
� |
� |
� |
Green Tree Mall |
� |
$ |
400 |
� |
� |
91.2 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 4 | � | � | � | Kitsap Mall | � | $ | 383 | � | � | 92.4 | % | � | � | � | � | � | � | � | � | � |
� |
5 |
� |
� |
� |
Northridge Mall |
� |
$ |
342 |
� |
� |
97.2 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 6 | � | � | � | Redmond Town Center | � | $ | 361 | � | � | 89.2 | % | � | � | � | � | � | � | � | � | � |
� |
7 |
� |
� |
� |
Redmond Town Center-Office |
� |
� |
n/a |
� |
� |
99.1 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 8 | � | � | � | Ridgmar Mall | � | $ | 332 | � | � | 84.6 | % | � | � | � | � | � | � | � | � | � |
� |
9 |
� |
� |
� |
Rimrock Mall |
� |
$ |
424 |
� |
� |
92.0 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 10 | � | � | � | Salisbury, Centre at | � | $ | 311 | � | � | 96.3 | % | � | � | � | � | � | � | � | � | � |
� |
10 |
� |
Total 2013 Disposition Centers: |
� |
$ |
348 |
� |
� |
92.1 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
||
| � | � | � | 2014 Disposition Centers | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | ||
� |
1 |
� |
� |
� |
Lake Square Mall |
� |
$ |
232 |
� |
� |
86.4 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
2 |
� |
� |
� |
Rotterdam Square |
� |
$ |
232 |
� |
� |
86.1 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
3 |
� |
� |
� |
Somersville Towne Center |
� |
$ |
287 |
� |
� |
84.7 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
� |
4 |
� |
� |
� |
South Towne Center |
� |
$ |
374 |
� |
� |
88.7 |
% |
� |
� |
� |
� |
� |
� |
� |
� |
� |
| � | 4 | � | Total 2014 Disposition Centers: | � | $ | 309 | � | � | 87.0 | % | � | � | � | � | � | � | � | � | � | ||
� |
14 |
� |
TOTAL DISPOSITION CENTERS |
� |
$ |
338 |
� |
� |
90.9 |
% |
� |
(0.1 |
)% |
� |
(5.7 |
)% |
� |
11.6 |
% |
||
16
The Macerich Company
Notes to Sales Per Square Foot by Property Ranking (unaudited)
| Footnotes | ||
| (a) | � | Sales are based on reports by retailers leasing mall and freestanding stores for the trailing 12�months for tenants which have occupied such stores for a minimum of 12�months. Sales per square foot are based on tenants 10,000 square feet and under. Properties are ranked by Sales per square foot as of December�31, 2014. Sales per square foot are excluded for Great Northern Mall which is being transitioned to the loan servicer. |
| (b) | � | Occupancy is the percentage of mall and freestanding GLA leased as of the last day of the reporting period. Occupancy excludes Centers under development and redevelopment. Occupancy excludes Great Northern Mall which is being transitioned to the loan servicer. |
| (c) | � | The Company presents Same Center Net Operating Income ("NOI") Growth because the Company believes it is useful for investors to evaluate the operating performance of comparable Centers. Same Center NOI is calculated using total EBITDA and subtracting out EBITDA from non-comparable centers and eliminating the management companies and the Company's general and administrative expenses. Same Center NOI excludes the impact of straight-line and above/below market adjustments to minimum rents. |
| � | � | EBITDA represents earnings before interest, income taxes, depreciation, amortization, noncontrolling interests, extraordinary items, gain (loss) on remeasurement, sale or write down of assets and preferred dividends and includes joint ventures at their pro rata share. Management considers EBITDA to be an appropriate supplemental measure to net income because it helps investors understand the ability of the Company to incur and service debt and make capital expenditures. The Company believes that EBITDA should not be construed as an alternative to operating income as an indicator of the Company's operating performance, or to cash flows from operating activities (as determined in accordance with GAAP) or as a measure of liquidity. The Company also cautions that EBITDA, as presented, may not be comparable to similarly titled measurements reported by other companies. |
| (d) | � | Cost of Occupancy represents "Tenant Occupancy Costs" divided by "Tenant Sales". Tenant Occupancy Costs in this calculation are the amounts paid to the Company, including minimum rents, percentage rents and recoverable expenditures, which consist primarily of property operating expenses, real estate taxes and repair and maintenance expenditures. |
| (e) | � | The percentage of Portfolio 2015 Forecast Pro Rata NOI is based on guidance provided on February�4, 2015. NOI excludes straight-line and above/below market adjustments to minimum rents. It does not reflect REIT expenses and net Management Company expenses. See the Company's forward-looking statements disclosure on page�1 for factors that may affect the information provided in this column. |
| (f) | � | These assets are under redevelopment including demolition and reconfiguration of the Centers and tenant spaces, accordingly the Sales per square foot and Occupancy during the periods of redevelopment are not included. |
| (g) | � | Fashion Outlets of Chicago opened August�1, 2013. |
| (h) | � | Properties sold prior to December�31, 2014 are excluded in prior years above. |
| (i) | � | On July�30, 2014, the Company formed a joint venture to redevelop The Gallery, a 1,474,000 square foot regional shopping center in Philadelphia, Pennsylvania. |
| (j) | � | The percentage of Portfolio 2012 Pro Rata NOI excludes the following items: straight-line rent, above/below market adjustments to minimum rents and termination fee income. It does not reflect REIT expenses and net Management Company expenses. |
17
The Macerich Company
Supplemental Financial and Operating Information (unaudited)
Occupancy(a)
|
� |
� | |||||||||
|---|---|---|---|---|---|---|---|---|---|---|
Regional Shopping Centers: Period Ended |
� | Consolidated Centers |
� | Unconsolidated Joint Venture Centers |
� | Total Centers |
� | |||
12/31/2014(b) |
� | � | 95.3% | � | � | 97.9% | � | � | 95.8% | � |
12/31/2013(c) |
� | � | 93.9% | � | � | 96.2% | � | � | 94.6% | � |
12/31/2012 |
� | � | 93.4% | � | � | 94.5% | � | � | 93.8% | � |
- (a)
- Occupancy
is the percentage of mall and freestanding GLA leased as of the last day of the reporting period. Occupancy excludes Centers under development and
redevelopment.
- (b)
- Great
Northern Mall is excluded at December�31, 2014 because the Center is being transitioned to the loan servicer.
- (c)
- Rotterdam Square, sold January�15, 2014, is excluded at December�31, 2013.
18
The Macerich Company
Supplemental Financial and Operating Information (unaudited)
Average Base Rent Per Square Foot(a)
| � |
� |
� |
� | |||||||
|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | Average Base Rent PSF(b) |
� | Average Base Rent PSF on Leases Executed during the trailing twelve months ended(c) |
� | Average Base Rent PSF on Leases Expiring(d) |
� | |||
Consolidated Centers |
� | � | � | � | � | � | � | � | � | � |
12/31/2014(e) |
� | $ | 49.68 | � | $ | 49.55 | � | $ | 41.20 | � |
12/31/2013(f) |
� | $ | 44.51 | � | $ | 45.06 | � | $ | 40.00 | � |
12/31/2012 |
� | $ | 40.98 | � | $ | 44.01 | � | $ | 38.00 | � |
Unconsolidated Joint Venture Centers |
� | � | � |
� | � | � |
� | � | � |
� |
12/31/2014 |
� | $ | 63.78 | � | $ | 82.47 | � | $ | 64.59 | � |
12/31/2013 |
� | $ | 62.47 | � | $ | 63.44 | � | $ | 48.43 | � |
12/31/2012 |
� | $ | 55.64 | � | $ | 55.72 | � | $ | 48.74 | � |
All Regional Shopping Centers |
� | � | � |
� | � | � |
� | � | � |
� |
12/31/2014(e) |
� | $ | 51.15 | � | $ | 54.48 | � | $ | 44.66 | � |
12/31/2013(f) |
� | $ | 48.16 | � | $ | 49.09 | � | $ | 41.88 | � |
12/31/2012 |
� | $ | 44.29 | � | $ | 46.78 | � | $ | 40.54 | � |
- (a)
- Average
base rent per square foot is based on spaces 10,000 square feet and under. All joint venture amounts are included at pro rata. Centers under
development and redevelopment are excluded.
- (b)
- Average
base rent per square foot gives effect to the terms of each lease in effect, as of the applicable date, including any concessions, abatements and
other adjustments or allowances that have been granted to the tenants.
- (c)
- The
average base rent per square foot on leases executed during the period represents the actual rent to be paid during the first twelve months.
- (d)
- The
average base rent per square foot on leases expiring during the period represents the final year minimum rent on a cash basis.
- (e)
- Great
Northern Mall is excluded at December�31, 2014 because the Center is being transitioned to the loan servicer.
- (f)
- Rotterdam Square, sold January�15, 2014, is excluded at December�31, 2013.
19
The Macerich Company
Supplemental Financial and Operating Information (unaudited)
Cost of Occupancy
| � |
� |
� |
� | |||||||
|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | For Years Ended December�31, | � | |||||||
| � |
� | 2014(a) | � | 2013(b) | � | 2012 | � | |||
Consolidated Centers |
� | � | � | � | � | � | � | � | � | � |
Minimum rents |
� | � | 8.7 | % | � | 8.4 | % | � | 8.1 | % |
Percentage rents |
� | � | 0.4 | % | � | 0.4 | % | � | 0.4 | % |
Expense recoveries(c) |
� | � | 4.3 | % | � | 4.5 | % | � | 4.2 | % |
Total |
� | � | 13.4 | % | � | 13.3 | % | � | 12.7 | % |
�
| � |
� |
� |
� | |||||||
|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | For Years Ended December�31, | � | |||||||
| � |
� | 2014 | � | 2013(a) | � | 2012 | � | |||
Unconsolidated Joint Venture Centers |
� | � | � | � | � | � | � | � | � | � |
Minimum rents |
� | � | 8.7 | % | � | 8.8 | % | � | 8.9 | % |
Percentage rents |
� | � | 0.4 | % | � | 0.4 | % | � | 0.4 | % |
Expense recoveries(c) |
� | � | 4.5 | % | � | 4.0 | % | � | 3.9 | % |
Total |
� | � | 13.6 | % | � | 13.2 | % | � | 13.2 | % |
�
| � |
� |
� |
� | |||||||
|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | For Years Ended December�31, | � | |||||||
| � |
� | 2014 | � | 2013(a) | � | 2012 | � | |||
All Centers |
� | � | � | � | � | � | � | � | � | � |
Minimum rents |
� | � | 8.7 | % | � | 8.6 | % | � | 8.4 | % |
Percentage rents |
� | � | 0.4 | % | � | 0.4 | % | � | 0.4 | % |
Expense recoveries(c) |
� | � | 4.3 | % | � | 4.3 | % | � | 4.0 | % |
Total |
� | � | 13.4 | % | � | 13.3 | % | � | 12.8 | % |
- (a)
- Great
Northern Mall is excluded for the year ended December�31, 2014 because the Center is being transitioned to the loan servicer.
- (b)
- Rotterdam
Square, sold January�15, 2014, is excluded for the year ended December�31, 2013.
- (c)
- Represents real estate tax and common area maintenance charges.
20
The Macerich Company
Percentage of Net Operating Income by State
��������Great Northern Mall is excluded from the table below because the Center is being transitioned to the loan servicer.
| � |
� |
� |
� | |
|---|---|---|---|---|
State
|
� | % of Portfolio 2015 Forecast Pro Rata NOI(a) |
� | |
California |
� | � | 29.0 | % |
New York |
� | � | 18.3 | % |
Arizona |
� | � | 17.0 | % |
New Jersey�& Connecticut |
� | � | 8.1 | % |
Illinois, Indiana�& Iowa |
� | � | 7.6 | % |
Pennsylvania�& Virginia |
� | � | 6.6 | % |
Oregon�& Washington |
� | � | 5.8 | % |
Colorado |
� | � | 4.9 | % |
Other(b) |
� | � | 2.7 | % |
Total |
� | � | 100.0 | % |
- (a)
- The
percentage of Portfolio 2015 Forecast Pro Rata NOI is based on guidance provided on February�4, 2015. NOI excludes straight-line and above/below
market adjustments to minimum rents. NOI also does not reflect REIT expenses and net Management Company expenses. See the Company's forward-looking statements disclosure on page�1 for factors
that may affect the information provided in this column.
- (b)
- "Other" includes Kentucky, North Dakota and Texas.
21
The Macerich Company
Property Listing
December�31, 2014
The following table sets forth certain information regarding the Centers and other locations that are wholly owned or partly owned by the Company. Great Northern Mall is excluded from the table below because the Center is being transitioned to the loan servicer.
Count
|
� | Company's Ownership(a) |
� | Name of Center/Location |
� | Year of Original Construction/ Acquisition |
� | Year of Most Recent Expansion/ Renovation |
� | Total GLA(b) |
� | ||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
|
� | CONSOLIDATED CENTERS: |
� | � | � | � | � | � | � | |||||
| � | 1 |
� | 100% |
� | Arrowhead Towne Center |
� | � | 1993/2002 | � | � | 2004 | � | � | 1,198,000 | � |
| � | 2 |
� | 100% |
� | Capitola Mall(c) |
� | � | 1977/1995 | � | � | 1988 | � | � | 577,000 | � |
| � | 3 |
� | 100% |
� | Cascade Mall |
� | � | 1989/1999 | � | � | 1998 | � | � | 589,000 | � |
| � | 4 |
� | 50.1% |
� | Chandler Fashion Center |
� | � | 2001/2002 | � | � | � | � | � | 1,320,000 | � |
| � | 5 |
� | 100% |
� | Danbury Fair Mall |
� | � | 1986/2005 | � | � | 2010 | � | � | 1,271,000 | � |
| � | 6 |
� | 100% |
� | Deptford Mall |
� | � | 1975/2006 | � | � | 1990 | � | � | 1,040,000 | � |
| � | 7 |
� | 100% |
� | Desert Sky Mall |
� | � | 1981/2002 | � | � | 2007 | � | � | 892,000 | � |
| � | 8 |
� | 100% |
� | Eastland Mall(c) |
� | � | 1978/1998 | � | � | 1996 | � | � | 1,044,000 | � |
| � | 9 |
� | 100% |
� | Fashion Outlets of Chicago |
� | � | 2013/� | � | � | � | � | � | 529,000 | � |
| � | 10 |
� | 100% |
� | Flagstaff Mall |
� | � | 1979/2002 | � | � | 2007 | � | � | 347,000 | � |
| � | 11 |
� | 100% |
� | FlatIron Crossing |
� | � | 2000/2002 | � | � | 2009 | � | � | 1,434,000 | � |
| � | 12 |
� | 50.1% |
� | Freehold Raceway Mall |
� | � | 1990/2005 | � | � | 2007 | � | � | 1,668,000 | � |
| � | 13 |
� | 100% |
� | Fresno Fashion Fair |
� | � | 1970/1996 | � | � | 2006 | � | � | 963,000 | � |
| � | 14 |
� | 100% |
� | Green Acres Mall(c) |
� | � | 1956/2013 | � | � | 2007 | � | � | 1,790,000 | � |
| � | 15 |
� | 100% |
� | Kings Plaza Shopping Center(c) |
� | � | 1971/2012 | � | � | 2002 | � | � | 1,191,000 | � |
| � | 16 |
� | 100% |
� | La Cumbre Plaza(c) |
� | � | 1967/2004 | � | � | 1989 | � | � | 491,000 | � |
| � | 17 |
� | 100% |
� | Lakewood Center |
� | � | 1953/1975 | � | � | 2008 | � | � | 2,066,000 | � |
| � | 18 |
� | 100% |
� | Los Cerritos Center |
� | � | 1971/1999 | � | � | 2010 | � | � | 1,113,000 | � |
| � | 19 |
� | 100% |
� | Northgate Mall |
� | � | 1964/1986 | � | � | 2010 | � | � | 753,000 | � |
| � | 20 |
� | 100% |
� | NorthPark Mall |
� | � | 1973/1998 | � | � | 2001 | � | � | 1,050,000 | � |
| � | 21 |
� | 100% |
� | Oaks, The |
� | � | 1978/2002 | � | � | 2009 | � | � | 1,137,000 | � |
| � | 22 |
� | 100% |
� | Pacific View |
� | � | 1965/1996 | � | � | 2001 | � | � | 1,021,000 | � |
| � | 23 |
� | 100% |
� | Queens Center(c) |
� | � | 1973/1995 | � | � | 2004 | � | � | 967,000 | � |
| � | 24 |
� | 100% |
� | Santa Monica Place |
� | � | 1980/1999 | � | � | 2010 | � | � | 466,000 | � |
22
The Macerich Company
Property Listing
December�31, 2014
Count
|
� | Company's Ownership(a) |
� | Name of Center/Location |
� | Year of Original Construction/ Acquisition |
� | Year of Most Recent Expansion/ Renovation |
� | Total GLA(b) |
� | ||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � | 25 |
� | 84.9% |
� | SanTan Village Regional Center |
� | � | 2007/� | � | � | 2009 | � | � | 1,028,000 | � |
| � | 26 |
� | 100% |
� | South Plains Mall |
� | � | 1972/1998 | � | � | 1995 | � | � | 1,127,000 | � |
| � | 27 |
� | 100% |
� | Stonewood Center(c) |
� | � | 1953/1997 | � | � | 1991 | � | � | 932,000 | � |
| � | 28 |
� | 100% |
� | Superstition Springs Center |
� | � | 1990/2002 | � | � | 2002 | � | � | 1,082,000 | � |
| � | 29 |
� | 100% |
� | Towne Mall |
� | � | 1985/2005 | � | � | 1989 | � | � | 350,000 | � |
| � | 30 |
� | 100% |
� | Tucson La�Encantada |
� | � | 2002/2002 | � | � | 2005 | � | � | 242,000 | � |
| � | 31 |
� | 100% |
� | Twenty Ninth Street(c) |
� | � | 1963/1979 | � | � | 2007 | � | � | 847,000 | � |
| � | 32 |
� | 100% |
� | Valley Mall |
� | � | 1978/1998 | � | � | 1992 | � | � | 507,000 | � |
| � | 33 |
� | 100% |
� | Valley River Center |
� | � | 1969/2006 | � | � | 2007 | � | � | 920,000 | � |
| � | 34 |
� | 100% |
� | Victor Valley, Mall of |
� | � | 1986/2004 | � | � | 2012 | � | � | 576,000 | � |
| � | 35 |
� | 100% |
� | Vintage Faire Mall |
� | � | 1977/1996 | � | � | 2008 | � | � | 1,129,000 | � |
| � | 36 |
� | 100% |
� | Washington Square |
� | � | 1974/1999 | � | � | 2005 | � | � | 1,441,000 | � |
| � | 37 |
� | 100% |
� | Wilton Mall |
� | � | 1990/2005 | � | � | 1998 | � | � | 736,000 | � |
| � |
|
� | � |
� | Total Consolidated Centers |
� | � | � | � | � | 35,834,000 | � | |||
| � | UNCONSOLIDATED JOINT VENTURE CENTERS: |
� | � | � | � | ||||||||||
| � | 38 |
� | 50% |
� | Biltmore Fashion Park |
� | � | 1963/2003 | � | � | 2006 | � | � | 516,000 | � |
| � | 39 |
� | 50.1% |
� | Corte Madera, Village at |
� | � | 1985/1998 | � | � | 2005 | � | � | 460,000 | � |
| � | 40 |
� | 50% |
� | Inland Center(c) |
� | � | 1966/2004 | � | � | 2004 | � | � | 933,000 | � |
| � | 41 |
� | 50% |
� | Kierland Commons |
� | � | 1999/2005 | � | � | 2003 | � | � | 434,000 | � |
| � | 42 |
� | 50% |
� | North Bridge, The Shops at(c) |
� | � | 1998/2008 | � | � | � | � | � | 660,000 | � |
| � | 43 |
� | 50% |
� | Scottsdale Fashion Square |
� | � | 1961/2002 | � | � | 2009 | � | � | 1,724,000 | � |
| � | 44 |
� | 50% |
� | Tysons Corner Center |
� | � | 1968/2005 | � | � | 2005 | � | � | 1,968,000 | � |
| � | 45 |
� | 19% |
� | West Acres |
� | � | 1972/1986 | � | � | 2001 | � | � | 971,000 | � |
| � |
|
� | � |
� | Total Unconsolidated Joint Venture Centers |
� | � | 7,666,000 | � | ||||||
23
The Macerich Company
Property Listing
December�31, 2014
Count
|
� | Company's Ownership(a) |
� | Name of Center/Location |
� | Year of Original Construction/ Acquisition |
� | Year of Most Recent Expansion/ Renovation |
� | Total GLA(b) |
� | ||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � | REGIONAL SHOPPING CENTERS UNDER REDEVELOPMENT: |
� | � | � | � | ||||||||||
| � | 46 |
� | 50% |
� | Broadway Plaza(c)(d) |
� | � | 1951/1985 | � | � | 1994 | � | � | 774,000 | � |
| � | 47 |
� | 100% |
� | Fashion Outlets of Niagara Falls USA(e) |
� | � | 1982/2011 | � | � | 2014 | � | � | 686,000 | � |
| � | 48 |
� | 50% |
� | Gallery, The�(c)(d) |
� | � | 1977/2014 | � | � | 1990 | � | � | 948,000 | � |
| � | 49 |
� | 100% |
� | Paradise Valley Mall(e) |
� | � | 1979/2002 | � | � | 2009 | � | � | 1,151,000 | � |
| � | 50 |
� | 100% |
� | SouthPark Mall(e) |
� | � | 1974/1998 | � | � | 1990 | � | � | 855,000 | � |
| � | 51 |
� | 100% |
� | Westside Pavilion |
� | � | 1985/1998 | � | � | 2007 | � | � | 755,000 | � |
| � |
|
� | � |
� | Total Regional Shopping Centers |
� | � | � | � | � | 48,669,000 | � | |||
| � | COMMUNITY / POWER CENTERS: |
� | � | � | � | � | � | � | |||||||
| � | 1 |
� | 50% |
� | Atlas Park, The Shops at(d) |
� | � | 2006/2011 | � | � | 2013 | � | � | 377,000 | � |
| � | 2 |
� | 50% |
� | Boulevard Shops(d) |
� | � | 2001/2002 | � | � | 2004 | � | � | 185,000 | � |
| � | 3 |
� | 39.7% |
� | Estrella Falls, The Market at(d) |
� | � | 2009/� | � | � | 2009 | � | � | 242,000 | � |
| � | 4 |
� | 100% |
� | Panorama Mall(e) |
� | � | 1955/1979 | � | � | 2005 | � | � | 312,000 | � |
| � | 5 |
� | 89.4% |
� | Promenade at Casa Grande(e) |
� | � | 2007/� | � | � | 2009 | � | � | 909,000 | � |
| � | 6 |
� | 100% |
� | Southridge Center(e) |
� | � | 1975/1998 | � | � | 2013 | � | � | 823,000 | � |
| � | 7 |
� | 100% |
� | Superstition Springs Power Center(e) |
� | � | 1990/2002 | � | � | � | � | � | 206,000 | � |
| � | 8 |
� | 100% |
� | The Marketplace at Flagstaff Mall(c)(e) |
� | � | 2007/� | � | � | � | � | � | 268,000 | � |
| � |
|
� | � |
� | Total Community / Power Centers |
� | � | 3,322,000 | � | ||||||
| � | OTHER ASSETS: |
� | � | � | � | � | � | � | � | � | � | ||||
| � |
|
� | 100% |
� | Various(e)(f) |
� | � | � | � | � | � | � | � | 572,000 | � |
| � |
|
� | 100% |
� | 500 North Michigan Avenue(e) |
� | � | � | � | � | � | � | � | 326,000 | � |
| � |
|
� | 50% |
� | Gallery, The-Offices(c)(d) |
� | � | � | � | � | � | � | � | 526,000 | � |
| � |
|
� | 100% |
� | Paradise Village Ground Leases(e) |
� | � | � | � | � | � | � | � | 58,000 | � |
| � |
|
� | 100% |
� | Paradise Village Office Park II(e) |
� | � | � | � | � | � | � | � | 46,000 | � |
| � |
|
� | 50% |
� | Scottsdale Fashion Square-Office(d) |
� | � | � | � | � | � | � | � | 123,000 | � |
| � |
|
� | 50% |
� | Tysons Corner Center-Office(d) |
� | � | � | � | � | � | � | � | 173,000 | � |
| � |
|
� | 50% |
� | Tysons Tower(d) |
� | � | � | � | � | � | � | � | 527,000 | � |
| � |
|
� | � |
� | Total Other Assets |
� | � | � | � | � | 2,351,000 | � | |||
| � |
|
� | � |
� | Grand Total at December�31, 2014 |
� | � | � | � | � | 54,342,000 | � | |||
24
The Macerich Company
Property Listing
December�31, 2014
- (a)
- The
Company's ownership interest in this table reflects its legal ownership interest. See footnotes�(a) and (b) on page�26 regarding the legal
versus economic ownership of joint venture entities.
- (b)
- Includes
GLA attributable to anchors (whether owned or non-owned) and mall and freestanding stores as of December�31, 2014.
- (c)
- Portions
of the land on which the Center is situated are subject to one or more long-term ground leases. With respect to 46 Centers, the underlying land
controlled by the Company is owned in fee entirely by the Company, or, in the case of jointly-owned Centers, by the joint venture property partnership or limited liability company.
- (d)
- Included
in Unconsolidated Joint Venture Centers.
- (e)
- Included
in Consolidated Centers.
- (f)
- The Company owns a portfolio of nine stores located at shopping centers not owned by the Company. Of these nine�stores, two have been leased to Forever 21, one has been leased to Kohl's, and six have been leased for non-Anchor usage. With respect to six of the nine�stores, the underlying land is owned in fee entirely by the Company. With respect to the remaining three stores, the underlying land is owned by third parties and leased to the Company pursuant to long-term building or ground leases.
25
��������The following table sets forth certain information regarding the Centers and other operating properties that are not wholly-owned by the Company. This list of properties includes unconsolidated joint ventures, consolidated joint ventures, and co-venture arrangements. The percentages shown are the effective legal ownership and economic ownership interests of the Company as of December�31, 2014.
|
� |
� | |||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|
Properties
|
� | 12/31/2014 Legal Ownership(a) |
� | 12/31/2014 Economic Ownership(b) |
� | Joint�Venture | � | 12/31/2014 Total�GLA(c) |
� | |||
Atlas Park, The Shops at |
� | � | 50% | � | � | 50% | � | WMAP, L.L.C. | � | � | 377,000 | � |
Biltmore Fashion Park |
� | � | 50% | � | � | 50% | � | Biltmore Shopping Center Partners�LLC | � | � | 516,000 | � |
Boulevard Shops |
� | � | 50% | � | � | 50% | � | Propcor II Associates,�LLC | � | � | 185,000 | � |
Broadway Plaza |
� | � | 50% | � | � | 50% | � | Macerich Northwestern Associates | � | � | 774,000 | � |
Chandler Fashion Center(d) |
� | � | 50.1% | � | � | 50.1% | � | Freehold Chandler Holdings�LP | � | � | 1,320,000 | � |
Corte Madera, Village at |
� | � | 50.1% | � | � | 50.1% | � | Corte Madera Village,�LLC | � | � | 460,000 | � |
Estrella Falls, The Market at(e) |
� | � | 39.7% | � | � | 39.7% | � | The Market at Estrella Falls�LLC | � | � | 242,000 | � |
Freehold Raceway Mall(d) |
� | � | 50.1% | � | � | 50.1% | � | Freehold Chandler Holdings�LP | � | � | 1,668,000 | � |
Gallery, The |
� | � | 50% | � | � | 50% | � | Various Entities | � | � | 948,000 | � |
Gallery, The-Office |
� | � | 50% | � | � | 50% | � | Various Entities | � | � | 526,000 | � |
Inland Center |
� | � | 50% | � | � | 50% | � | WM Inland�LP | � | � | 933,000 | � |
Kierland Commons |
� | � | 50% | � | � | 50% | � | Kierland Commons Investment�LLC | � | � | 434,000 | � |
North Bridge, The Shops at |
� | � | 50% | � | � | 50% | � | North Bridge Chicago�LLC | � | � | 660,000 | � |
Promenade at Casa Grande(f) |
� | � | 89.4% | � | � | 89.4% | � | WP Casa Grande Retail�LLC | � | � | 909,000 | � |
SanTan Village Regional Center |
� | � | 84.9% | � | � | 84.9% | � | Westcor SanTan Village�LLC | � | � | 1,012,000 | � |
Scottsdale Fashion Square |
� | � | 50% | � | � | 50% | � | Scottsdale Fashion Square Partnership | � | � | 1,724,000 | � |
Scottsdale Fashion Square-Office |
� | � | 50% | � | � | 50% | � | Scottsdale Fashion Square Partnership | � | � | 123,000 | � |
Tysons Corner Center |
� | � | 50% | � | � | 50% | � | Tysons Corner�LLC | � | � | 1,968,000 | � |
Tysons Corner Center-Office |
� | � | 50% | � | � | 50% | � | Tysons Corner Property�LLC | � | � | 173,000 | � |
Tysons Tower |
� | � | 50% | � | � | 50% | � | Tysons Corner Property�LLC | � | � | 527,000 | � |
West Acres |
� | � | 19% | � | � | 19% | � | West Acres Development,�LLP | � | � | 971,000 | � |
- (a)
- This
column reflects the Company's legal ownership in the listed properties as of December�31, 2014.
Legal ownership may, at times, not equal the Company's economic interest in the listed properties because of various provisions in certain joint venture agreements regarding distributions of cash flow based on capital account balances, allocations of profits and losses and payments of preferred returns. As a result, the Company's actual economic interest (as distinct from its legal ownership interest) in certain of the properties could fluctuate from time to time and may not wholly align with its legal ownership interests. Substantially all of the Company's joint venture agreements contain rights of first refusal, buy-sell provisions, exit rights, default dilution remedies and/or other break up provisions or remedies which are customary in real estate joint venture agreements and which may, positively or negatively, affect the ultimate realization of cash flow and/or capital or liquidation proceeds. - (b)
- Economic
ownership represents the allocation of cash flow to the Company as of December�31, 2014, except as noted below. In cases where the Company
receives a current cash distribution greater than its legal ownership percentage due to a capital account greater than its legal ownership percentage, only the legal ownership percentage is shown in
this column. The Company's economic ownership of these properties may fluctuate based on a number of factors, including mortgage refinancings, partnership capital contributions and distributions, and
proceeds and gains or losses from asset sales, and the matters set forth in the preceding paragraph.
- (c)
- Includes
GLA attributable to anchors (whether owned or non-owned) and mall and freestanding stores as of December�31, 2014.
- (d)
- The
joint venture entity was formed in September 2009. Upon liquidation of the partnership, distributions are made in the following order: to the
third-party partner until it receives a 13% internal rate of return on its aggregate unreturned capital contributions; to the Company until it receives a 13% internal rate of return on its aggregate
unreturned capital contributions; and, thereafter, 35% to the third-party partner and 65% to the Company.
- (e)
- Columns 1 and 2 reflect the Company's indirect ownership interest in the property owner. The Company and a third-party partner are each members of a joint venture (the "MW�Joint Venture") which, in turn, is a member in
26
the joint venture that owns the property. Cash flow distributions for the MW Joint Venture are made in accordance with the members' relative capital accounts until the members have received distributions equal to their capital accounts, and thereafter in accordance with the members' relative legal ownership percentages. In addition, the Company has executed a joint and several guaranty of the mortgage for the property with its third-party partner. The Company may incur liabilities under such guaranty greater than its legal ownership percentage.
- (f)
- Columns 1 and 2 reflect the Company's total direct and indirect ownership interest in the property owner. The Company and a third-party partner are each members of a joint venture (the "MW�Joint Venture") which, in turn, is a member in the joint venture that owns the property. Cash flow distributions for the MW Joint Venture are made in accordance with the members' relative capital accounts until the members have received distributions equal to their capital accounts, and thereafter in accordance with the members' relative legal ownership percentages.
27
The Macerich Company
Supplemental Financial and Operating Information (unaudited)
Debt Summary (at Company's pro rata share)
| � |
� |
� |
� | |||||||
|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | As of December�31, 2014 | � | |||||||
| � |
� | Fixed Rate | � | Floating Rate | � | Total | � | |||
| � |
� | dollars in thousands |
� | |||||||
Consolidated debt |
� | $ | 4,924,143 | � | $ | 1,128,408 | � | $ | 6,052,551 | � |
Unconsolidated debt |
� | � | 882,527 | � | � | 115,359 | � | � | 997,886 | � |
Total debt |
� | $ | 5,806,670 | � | $ | 1,243,767 | � | $ | 7,050,437 | � |
Weighted average interest rate |
� | � | 3.77 |
% |
� | 2.16 |
% |
� | 3.48 |
% |
Weighted average maturity (years) |
� | � | � | � | � | � | � | � | 5.16 | � |
28
The Macerich Company
Supplemental Financial and Operating Information (Unaudited)
Outstanding Debt by Maturity Date
| � |
� |
� |
� | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | As of December�31, 2014 | � | |||||||||||||
Center/Entity (dollars in thousands)
|
� | Maturity Date | � | Effective Interest Rate(a) |
� | Fixed | � | Floating | � | Total Debt Balance(a) |
� | |||||
I. Consolidated Assets: |
� | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Great Northern Mall(b) |
� | � | 01/01/15 | � | � | 6.54 | % | $ | 34,494 | � | $ | � | � | $ | 34,494 | � |
Lakewood Center |
� | � | 06/01/15 | � | � | 1.80 | % | � | 253,708 | � | � | � | � | � | 253,708 | � |
Flagstaff Mall |
� | � | 11/01/15 | � | � | 5.03 | % | � | 37,000 | � | � | � | � | � | 37,000 | � |
Washington Square |
� | � | 01/01/16 | � | � | 1.65 | % | � | 238,696 | � | � | � | � | � | 238,696 | � |
Valley River Center |
� | � | 02/01/16 | � | � | 5.59 | % | � | 120,000 | � | � | � | � | � | 120,000 | � |
Prasada(c) |
� | � | 03/29/16 | � | � | 5.25 | % | � | 5,440 | � | � | � | � | � | 5,440 | � |
Eastland Mall |
� | � | 06/01/16 | � | � | 5.79 | % | � | 168,000 | � | � | � | � | � | 168,000 | � |
Valley Mall |
� | � | 06/01/16 | � | � | 5.85 | % | � | 41,368 | � | � | � | � | � | 41,368 | � |
Deptford Mall |
� | � | 06/01/16 | � | � | 6.46 | % | � | 14,285 | � | � | � | � | � | 14,285 | � |
Stonewood Center |
� | � | 11/01/17 | � | � | 1.80 | % | � | 111,297 | � | � | � | � | � | 111,297 | � |
Freehold Raceway Mall(d) |
� | � | 01/01/18 | � | � | 4.20 | % | � | 114,851 | � | � | � | � | � | 114,851 | � |
Santa Monica Place |
� | � | 01/03/18 | � | � | 2.99 | % | � | 230,344 | � | � | � | � | � | 230,344 | � |
Los Cerritos Center |
� | � | 07/01/18 | � | � | 1.65 | % | � | 206,548 | � | � | � | � | � | 206,548 | � |
Arrowhead Towne Center |
� | � | 10/05/18 | � | � | 2.76 | % | � | 228,703 | � | � | � | � | � | 228,703 | � |
SanTan Village Regional Center(e) |
� | � | 06/01/19 | � | � | 3.14 | % | � | 113,590 | � | � | � | � | � | 113,590 | � |
Chandler Fashion Center(d) |
� | � | 07/01/19 | � | � | 3.77 | % | � | 100,200 | � | � | � | � | � | 100,200 | � |
Kings Plaza Shopping Center |
� | � | 12/03/19 | � | � | 3.67 | % | � | 480,761 | � | � | � | � | � | 480,761 | � |
Danbury Fair Mall |
� | � | 10/01/20 | � | � | 5.53 | % | � | 228,529 | � | � | � | � | � | 228,529 | � |
Fashion Outlets of Niagara Falls USA |
� | � | 10/06/20 | � | � | 4.89 | % | � | 121,376 | � | � | � | � | � | 121,376 | � |
FlatIron Crossing |
� | � | 01/05/21 | � | � | 3.90 | % | � | 261,494 | � | � | � | � | � | 261,494 | � |
Green Acres Mall |
� | � | 02/03/21 | � | � | 3.61 | % | � | 313,514 | � | � | � | � | � | 313,514 | � |
Tucson La Encantada |
� | � | 03/01/22 | � | � | 4.23 | % | � | 71,500 | � | � | � | � | � | 71,500 | � |
Pacific View |
� | � | 04/01/22 | � | � | 4.08 | % | � | 133,200 | � | � | � | � | � | 133,200 | � |
Oaks, The |
� | � | 06/05/22 | � | � | 4.14 | % | � | 210,197 | � | � | � | � | � | 210,197 | � |
Westside Pavilion |
� | � | 10/01/22 | � | � | 4.49 | % | � | 149,626 | � | � | � | � | � | 149,626 | � |
Towne Mall |
� | � | 11/01/22 | � | � | 4.48 | % | � | 22,607 | � | � | � | � | � | 22,607 | � |
Deptford Mall |
� | � | 04/03/23 | � | � | 3.76 | % | � | 197,815 | � | � | � | � | � | 197,815 | � |
Victor Valley, Mall of |
� | � | 09/01/24 | � | � | 4.00 | % | � | 115,000 | � | � | � | � | � | 115,000 | � |
Queens Center |
� | � | 01/01/25 | � | � | 3.49 | % | � | 600,000 | � | � | � | � | � | 600,000 | � |
Total Fixed Rate Debt for Consolidated Assets |
� | � | � | � | � | 3.64 | % | $ | 4,924,143 | � | $ | � | � | $ | 4,924,143 | � |
Superstition Springs Center |
� | � | 10/28/16 | � | � | 1.98 | % | $ | � | � | $ | 68,079 | � | $ | 68,079 | � |
Northgate Mall |
� | � | 03/01/17 | � | � | 3.05 | % | � | � | � | � | 64,000 | � | � | 64,000 | � |
Fashion Outlets of Chicago(f) |
� | � | 03/05/17 | � | � | 2.97 | % | � | � | � | � | 119,329 | � | � | 119,329 | � |
The Macerich Partnership,�L.P.�Line of Credit |
� | � | 08/06/18 | � | � | 1.89 | % | � | � | � | � | 752,000 | � | � | 752,000 | � |
The Macerich Partnership,�L.P.�Term Loan |
� | � | 12/08/18 | � | � | 2.25 | % | � | � | � | � | 125,000 | � | � | 125,000 | � |
Total Floating Rate Debt for Consolidated Assets |
� | � | � | � | � | 2.12 | % | $ | � | � | $ | 1,128,408 | � | $ | 1,128,408 | � |
Total Debt for Consolidated Assets |
� | � | � | � | � | 3.35 | % | $ | 4,924,143 | � | $ | 1,128,408 | � | $ | 6,052,551 | � |
29
The Macerich Company
Supplemental Financial and Operating Information (Unaudited)
Outstanding Debt by Maturity Date
| � |
� |
� |
� | |||||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | As of December�31, 2014 | � | |||||||||||||
Center/Entity (dollars in thousands)
|
� | Maturity Date | � | Effective Interest Rate(a) |
� | Fixed | � | Floating | � | Total Debt Balance(a) |
� | |||||
II. Unconsolidated Assets (At Company's pro rata share): |
� | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Broadway Plaza (50%) |
� | � | 08/15/15 | � | � | 6.12 | % | � | 68,237 | � | � | � | � | � | 68,237 | � |
North Bridge, The Shops at (50%) |
� | � | 06/15/16 | � | � | 7.52 | % | � | 96,309 | � | � | � | � | � | 96,309 | � |
West Acres (19%) |
� | � | 10/01/16 | � | � | 6.41 | % | � | 10,988 | � | � | � | � | � | 10,988 | � |
Corte Madera, The Village at (50.1%) |
� | � | 11/01/16 | � | � | 7.27 | % | � | 37,762 | � | � | � | � | � | 37,762 | � |
Scottsdale Fashion Square (50%) |
� | � | 04/03/23 | � | � | 3.02 | % | � | 253,472 | � | � | � | � | � | 253,472 | � |
Tysons Corner Center (50%) |
� | � | 01/01/24 | � | � | 4.13 | % | � | 415,759 | � | � | � | � | � | 415,759 | � |
Total Fixed Rate Debt for Unconsolidated Assets |
� | � | � | � | � | 4.50 | % | $ | 882,527 | � | $ | � | � | $ | 882,527 | � |
Estrella Falls, The Market at (39.71%)(g) |
� | � | 06/01/15 | � | � | 3.13 | % | $ | � | � | $ | 13,319 | � | $ | 13,319 | � |
Inland Center (50%) |
� | � | 04/01/16 | � | � | 3.41 | % | � | � | � | � | 25,000 | � | � | 25,000 | � |
Kierland Commons (50%)(f) |
� | � | 01/02/18 | � | � | 2.25 | % | � | � | � | � | 67,082 | � | � | 67,082 | � |
Boulevard Shops (50%)(f) |
� | � | 12/16/18 | � | � | 2.05 | % | � | � | � | � | 9,958 | � | � | 9,958 | � |
Total Floating Rate Debt for Unconsolidated Assets |
� | � | � | � | � | 2.59 | % | $ | � | � | $ | 115,359 | � | $ | 115,359 | � |
Total Debt for Unconsolidated Assets |
� | � | � | � | � | 4.28 | % | $ | 882,527 | � | $ | 115,359 | � | $ | 997,886 | � |
Total Debt |
� | � | � | � | � | 3.48 | % | $ | 5,806,670 | � | $ | 1,243,767 | � | $ | 7,050,437 | � |
Percentage to Total |
� | � | � | � | � | � | � | � | 82.36 | % | � | 17.64 | % | � | 100.00 | % |
- (a)
- The debt balances include the unamortized debt premiums/discounts. Debt premiums/discounts represent the excess of the fair value of debt over the principal value of debt assumed in various acquisitions and are amortized into interest expense over the remaining term of the related debt in a manner that approximates the effective interest method. The annual interest rate in the above table represents the effective interest rate, including the debt premiums/discounts and loan financing costs.
- (b)
- This non-recourse loan is in maturity default. The Company is working with the loan servicer, which is expected to result in a transition of the asset to the loan servicer or a receiver.
- (c)
- This property is owned by a consolidated joint venture. The above debt balance represents the Company's pro rata share of 50.0%.
- (d)
- This property is owned by a consolidated joint venture. The above debt balance represents the Company's pro rata share of 50.1%.
- (e)
- This property is owned by a consolidated joint venture. The above debt balance represents the Company's pro rata share of 84.9%.
- (f)
- The maturity date assumes that all such extension options are fully exercised and that the Company and/or its affiliates do not opt to refinance the debt prior to these dates.
- (g)
- On 02/03/15, the Company's joint venture replaced the existing loan on the property with a new $10,500 loan, at the Company's pro rata share, that bears interest at LIBOR plus 1.7% and matures on 02/05/20, including a one-year extension option.
30
The Macerich Company
Supplemental Financial and Operating Information (Unaudited)
Development Pipeline Forecast
(Dollars in millions)
as of December�31, 2014
In-Process Developments and Redevelopments:
Property
|
� | Project Type | � | Total Cost(a)(b) at 100% |
� | Ownership % |
� | Total Cost(a)(b) Pro Rata |
� | Pro Rata Capitalized Costs(b) 12/31/2014 |
� | Expected Delivery(a) |
� | Stabilized Yield(a)(b)(c) |
|
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Broadway Plaza |
� | Expansion of existing open air center adding 235,000 sf (net) of new shop space to existing 774,000 sf center which is currently anchored by Nordstrom, Neiman Marcus and Macy's. New space created by construction of a more efficient parking structure and the consolidation of stand-alone Macy's Men's Store into a single larger Macy's box. Phase�I encompasses demolition of 80,000 sf of existing retail space and construction of 240,000 sf of new retail space for a net increase of 160,000 sf. Phase�2 involves demolition of the existing Macy's Men's building and construction of 75,000 sf of new retail space for a total increase of 235,000 sf of small stores. | � | * Phase�1 : $240 * Phase�2 : $30 |
� | � | 50 | % | * Phase�1 : $120 * Phase�2 : $15 |
� | * Phase�1 : $45 * Phase�2 : $0 |
� | * 25% 4Q15 * 50% 2Q16 * 25% 2Q17 |
� | 9% |
| � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
|
� | � | � | Total: $270 | � | � | � | � | Total: $135 | � | Total: $45 | � | � | � | � |
Los Cerritos Center |
� | 200,000 square foot redevelopment, including a Dick's Sporting Goods and a Harkins Theatre | � | $45 | � | � | 100 | % | $45 | � | $6 | � | 4Q15 | � | 8% |
Santa Monica Place |
� | Movie theater addition�Adding a 48,000 square foot state-of-art, 12-screen Arclight Cinema to the third level/Dining Deck | � | $33 | � | � | 100 | % | $33 | � | $12 | � | 4Q15 | � | 8% |
Scottsdale Fashion Square |
� | 135,000 square foot addition to an existing 1.8�million square foot center, including a Dick's Sporting Goods and a Harkins Theatre | � | $30 | � | � | 50 | % | $15 | � | $5 | � | 3Q15 | � | 10% |
31
The Macerich Company
Supplemental Financial and Operating Information (Unaudited)
Development Pipeline Forecast
(Dollars in millions)
as of December�31, 2014
In-Process Developments and Redevelopments: (continued)
Property
|
� | Project Type | � | Total Cost(a)(b) at 100% |
� | Ownership % |
� | Total Cost(a)(b) Pro Rata |
� | Pro Rata Capitalized Costs(b) 12/31/2014 |
� | Expected Delivery(a) |
� | Stabilized Yield(a)(b)(c) |
|
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
Tysons Corner |
� | Mixed-use expansion/densification�Constructing office (527,000 square feet), multifamily (430 units) and hotel (300-room Hyatt Regency) components immediately adjacent to Tysons Corner Center, all of which will be served by the expanded METRO line (opened July 2014) and tied together by a 1.5-acre plaza | � | * Office: $228 * Hotel: $136 * Multifamily: $160 |
� | � | 50 | % | * Office: $114 * Hotel: $68 * Multifamily: $80 |
� | * Office: $104 * Hotel: $61 * Multifamily: $70 |
� | * Office: 3Q14 * Hotel: 1Q15 * Multifamily: 1Q15 |
� | 8% |
| � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
|
� | � | � | Total: $524 | � | � | � | � | Total: $262 | � | Total: $235 | � | � | � | � |
Green Acres Commons |
� | 335,000 square foot, Big Box development | � | $105�- $110 | � | � | 100 | % | $105�- $110 | � | $24 | � | Fall 2016 | � | 10% |
Total In-Process |
� | � | � | $1,007�- $1,012 | � | � | � | � | $595�- $600 | � | $327 | � | � | � | � |
32
The Macerich Company
Supplemental Financial and Operating Information (Unaudited)
Development Pipeline Forecast
(Dollars in millions)
as of December�31, 2014
Shadow Pipeline of Developments and Redevelopments(d):
Property
|
� | Project Type | � | Total Cost(a)(b) at 100% |
� | Ownership % |
� | Total Cost(a)(b) Pro Rata |
� | Pro Rata Capitalized Costs(b) 12/31/2014 |
� | Expected Delivery(a) |
� | Stabilized Yield(a)(b)(c) |
|||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � | � |
500 N. Michigan Ave (contiguous to The Shops at North Bridge) |
� | 25,000 square foot redevelopment/street retail | � | $20�- $25 | � | � | 100 | % | $20 -$25 | � | $ | 5 | � | � | 2016�-�2017 | � | 10%�-�12% |
Gallery, The |
� | Redevelopment of The Gallery in downtown Philadelphia | � | TBD | � | � | 50 | % | TBD | � | $ | 0 | � | � | TBD | � | TBD |
Fashion Outlets of San Francisco |
� | A 500,000 square foot outlet center on the historic site of Candlestick Park | � | TBD | � | � | 50.1 | % | TBD | � | $ | 0 | � | � | TBD | � | TBD |
Kings Plaza Shopping Center |
� | Major remerchandising and redemising of Sears | � | $65�- $75 | � | � | 100 | % | $65�- $75 | � | $ | 0 | � | � | 2017�-�2018 | � | 7%�- 8% |
Paradise Valley Mall |
� | Redevelopment (size TBD) including a theater | � | TBD | � | � | 100 | % | TBD | � | $ | 0 | � | � | TBD | � | TBD |
Scottsdale Fashion Square |
� | Office / Residential / Retail Mixed Use development on 7.5 Acres (former Days Inn) | � | $250 | � | � | 50 | % | $125 | � | $ | 0 | � | � | 2017�-�2018 | � | 8% |
Tysons Corner |
� | Mixed Use Development. Residential Tower with Retail Ground Floor. | � | $165 | � | � | 50 | % | $83 | � | $ | 0 | � | � | 2018�-�2019 | � | 7%�- 8% |
Westside Pavilion |
� | Redevelopment of an existing 755,000 square foot Regional Shopping Center | � | TBD | � | � | 100 | % | TBD | � | $ | 0 | � | � | TBD | � | TBD |
Total Shadow Pipeline |
� | � | � | $500�- $515 | � | � | � | � | $293�- $308 | � | $ | 5 | � | � | � | � | � |
- (a)
- Much of this information is estimated and may change from time to time. See the Company's forward-looking disclosure on page�1
for factors that may affect the information provided in this table.
- (b)
- This excludes GAAP allocations of non cash and indirect costs.
- (c)
- Stabilized Yield is calculated based on stabilized income after development divided by project direct costs excluding GAAP
allocations of non cash and indirect costs.
- (d)
- This section includes potential developments or redevelopments that the Company is considering. The scope of these projects may change. Average returns are expected to be 7% to 12%. There is no certainty that the Company will develop any or all of these potential projects.
33
The Macerich Company
Corporate Information
Stock Exchange Listing
New
York Stock Exchange
Symbol: MAC
��������The following table shows high and low sales prices per share of common stock during each quarter in 2014, 2013 and 2012 and dividends per share of common stock declared and paid by quarter:
|
� |
� | |||||||||
|---|---|---|---|---|---|---|---|---|---|---|
| � |
� | Market Quotation per Share |
� | Dividends | � | |||||
Quarter Ended:
|
� | High | � | Low | � | Declared and Paid |
� | |||
March�31, 2012 |
� | $ | 58.08 | � | $ | 49.67 | � | $ | 0.55 | � |
June�30, 2012 |
� | $ | 62.83 | � | $ | 54.37 | � | $ | 0.55 | � |
September�30, 2012 |
� | $ | 61.80 | � | $ | 56.02 | � | $ | 0.55 | � |
December�31, 2012 |
� | $ | 60.03 | � | $ | 54.32 | � | $ | 0.58 | � |
March�31, 2013 |
� | $ |
64.47 |
� | $ |
57.66 |
� | $ |
0.58 |
� |
June�30, 2013 |
� | $ | 72.19 | � | $ | 56.68 | � | $ | 0.58 | � |
September�30, 2013 |
� | $ | 66.12 | � | $ | 55.19 | � | $ | 0.58 | � |
December�31, 2013 |
� | $ | 60.76 | � | $ | 55.13 | � | $ | 0.62 | � |
March�31, 2014 |
� | $ |
62.41 |
� | $ |
55.21 |
� | $ |
0.62 |
� |
June�30, 2014 |
� | $ | 68.28 | � | $ | 61.66 | � | $ | 0.62 | � |
September�30, 2014 |
� | $ | 68.81 | � | $ | 62.62 | � | $ | 0.62 | � |
December�31, 2014 |
� | $ | 85.55 | � | $ | 63.25 | � | $ | 0.65 | � |
Dividend Reinvestment Plan
��������Stockholders may automatically reinvest their dividends in additional common stock of the Company through the Direct Investment Program, which also provides for purchase by voluntary cash contributions. For additional information, please contact Computershare Trust Company, N.A. at 800-567-0169.
| � |
� | � |
� | � |
|---|---|---|---|---|
| Corporate Headquarters The Macerich Company 401 Wilshire Boulevard, Suite�700 Santa Monica, California 90401 310-394-6000 www.macerich.com |
� | Transfer Agent Computershare P.O.�Box�30170 College Station, TX 77842-3170 800-567-0169 www.computershare.com |
� | � |
Macerich Website
��������For an electronic version of our annual report, our SEC filings and documents relating to Corporate Governance, please visit www.macerich.com.
Investor Relations
| Jean Wood Vice President, Investor Relations Phone: 424-229-3366 [email protected] |
� | John Perry Senior Vice President, Investor Relations Phone: 424-229-3345 [email protected] |
34
The Macerich Company Supplemental Financial and Operating Information Table of Contents
The Macerich Company Supplemental Financial and Operating Information Overview
The Macerich Company Supplemental Financial and Operating Information (unaudited) Capital Information and Market Capitalization
The Macerich Company Supplemental Financial and Operating Information (unaudited) Changes in Total Common and Equivalent Shares/Units
THE MACERICH COMPANY UNAUDITED PRO RATA STATEMENT OF OPERATIONS (Dollars in thousands)
THE MACERICH COMPANY UNAUDITED PRO RATA STATEMENT OF OPERATIONS (Dollars in thousands)
The Macerich Company Notes to Unaudited Pro Rata Statement of Operations
THE MACERICH COMPANY UNAUDITED PRO RATA BALANCE SHEET (All Dollars in thousands)
The Macerich Company 2015 Guidance Range (Unaudited)
The Macerich Company Supplemental Financial and Operating Information (unaudited) Supplemental FFO Information(a)
The Macerich Company Supplemental Financial and Operating Information (unaudited) Capital Expenditures
The Macerich Company Supplemental Financial and Operating Information (unaudited) Regional Shopping Center Portfolio Sales Per Square Foot(a)
Sales Per Square Foot
The Macerich Company Notes to Sales Per Square Foot by Property Ranking (unaudited)
The Macerich Company Supplemental Financial and Operating Information (unaudited) Occupancy(a)
The Macerich Company Supplemental Financial and Operating Information (unaudited) Average Base Rent Per Square Foot(a)
The Macerich Company Supplemental Financial and Operating Information (unaudited) Cost of Occupancy
The Macerich Company Percentage of Net Operating Income by State
The Macerich Company Property Listing December 31, 2014
Joint Venture List
The Macerich Company Supplemental Financial and Operating Information (unaudited) Debt Summary (at Company's pro rata share)
The Macerich Company Supplemental Financial and Operating Information (Unaudited) Outstanding Debt by Maturity Date
The Macerich Company Supplemental Financial and Operating Information (Unaudited) Outstanding Debt by Maturity Date
The Macerich Company Corporate Information